

- Market Size (2026)
- USD 574.2 Bn
- Forecast (2036)
- USD 891.8 Bn
- CAGR (2026 to 2036)
- 4.5%
How big is the MedTech market in 2026?
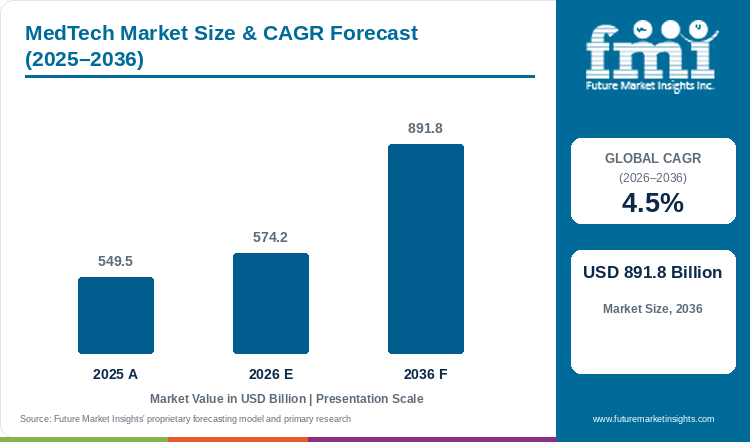
Demand is projected to expand at 4.5% CAGR from 2026 to 2036. Market value rises from USD 549.5 billion in 2025 to USD 574.24 billion in 2026 and USD 891.78 billion by 2036. [1]
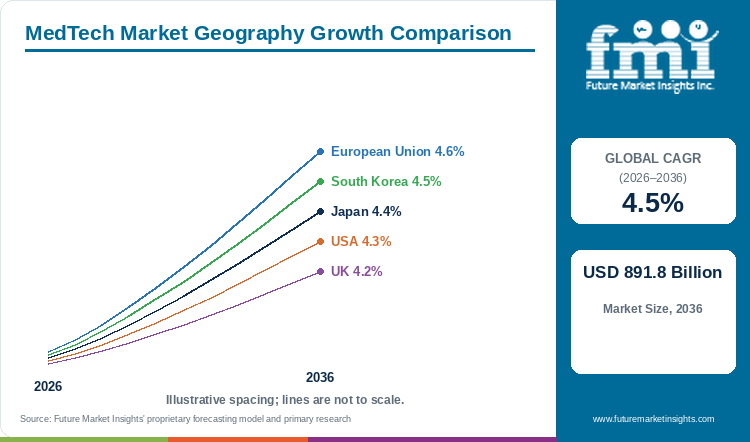
FMI values the MedTech market at USD 574.24 billion in 2026, compared with USD 549.5 billion in 2025, and projects USD 891.78 billion by 2036 at a 4.5% CAGR. [1] Medical devices account for 38.6% by product type, cardiology represents 26.9% by application and hospitals and clinics account for 57.3% by end user in 2026. [1] These categories bring together technologies with distinct clinical functions, so procurement depends on the intended care pathway and the support required for each product. FDA's QMSR became effective in February 2026 and incorporates ISO 13485:2016 by reference, establishing manufacturing quality-system requirements relevant to suppliers of covered devices. [2] Product-specific clinical evidence and authorization remain separate purchasing considerations, with a quality-system record describing manufacturing controls within its own defined regulatory purpose and scope. EUDAMED's first four modules became mandatory in May 2026, adding a concrete product and manufacturer-record requirement to the European operating context. [3] Capital equipment, consumable devices and diagnostic products create different purchasing cycles, making training, maintenance and repeat supply relevant alongside the price of acquisition. The European Union has the highest profiled rate at 4.6% CAGR from 2026 to 2036, a regional forecast distinct from individual country rates. [1] Suppliers can make procurement easier to assess through clear intended-use records, clearly defined training requirements and dependable service arrangements, helping healthcare organizations match each technology to the setting where it will be used.
Key Market Trends and Insights
- Medical devices represent 38.6% within the commercial product classification. [1]
- Cardiology holds 26.9%. Clinical functions require different purchasing assessments. [1]
- Hospitals and clinics account for 57.3% by end user. [1]
Regional Highlights
- Fastest-growing profiled market: European Union at 4.6% CAGR from 2026 to 2036. [1]
- Product and manufacturer records help healthcare organizations assess available technologies and their regulatory obligations. Digital transformation in healthcare also connects these records with clinical and administrative workflows.
Market Size and Forecast
Table 1: Market size and forecast for the MedTech market in USD billion and percentage
| Metric | Value |
|---|---|
| 2025 market size | USD 549.5 billion |
| Estimated market size in 2026 | USD 574.24 billion |
| Projected market size by 2036 | USD 891.78 billion |
| CAGR 2026 to 2036 | 4.5% |
| Added revenue 2026 to 2036 | USD 317.54 billion |
| Market expansion multiple | 1.6x |
Capital equipment and consumable devices create different purchasing cycles. Hospitals consider training and maintenance alongside acquisition, while senior care products require support suited to continuing care and everyday use.
Manufacturing Quality and Device-Record Evidence
Manufacturing quality systems and device registries organize product and manufacturer information. Product-specific authorization, intended use and clinical evidence remain relevant to each purchase. [2][3]
Table 2: Evidence and adoption indicators for the MedTech market
| Indicator | Data point or finding | Commercial relevance | Source |
|---|---|---|---|
| US quality rule | QMSR effective 2 February 2026 | Changes manufacturer quality requirements | [2] |
| Quality framework | ISO 13485:2016 incorporated by reference | Defines the cited quality-system basis | [2] |
| EU database | First four EUDAMED modules mandatory from 28 May 2026 | Adds defined registration and record obligations | [3] |
Analyst Perspective
"Healthcare procurement starts with the clinical function that a product must perform and the setting in which staff will use it. Quality records, the relevant authorization and practical training then help buyers assess whether the offer fits that care pathway. Digital health tracking apps introduce a separate software interface for following health information, with their own operating requirements. Suppliers give purchasing teams a clearer choice when the product, consumables and service responsibilities are described together for the intended use."
- Sudip Saha, Principal Consultant, FMI
How is the MedTech market segmented?
The market covers 5 commercial axes and region: product type; application; end user; distribution; pricing.
By product type: Medical devices; Medical equipment; In-vitro diagnostics; Telemedicine platforms. By application: Cardiology; Orthopedics; Oncology; Neurology; Respiratory; Other applications. By end user: Hospitals and clinics; Ambulatory surgical centers; Home healthcare; Diagnostic laboratories. By distribution: Direct; Indirect. By pricing: Premium; Mid-range; Low-cost; Subscription and pay-per-use.
Why do medical devices lead demand within the product type category?
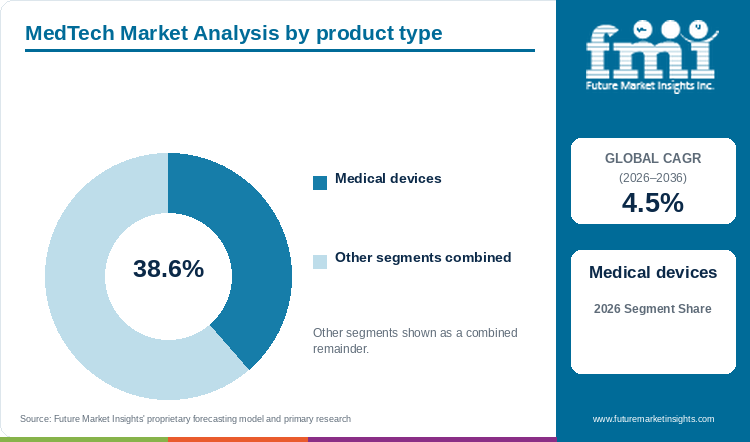
The medical devices segment accounts for 38.6% of product type demand in 2026. [1]
Medical devices serve defined clinical functions across hospitals, clinics and other care settings, giving the product category a broad role within everyday healthcare procurement. Selection brings together the intended use, relevant authorization and manufacturing quality records, while staff training and maintenance determine how the device fits the actual care pathway. Consumable demand follows the product's use and differs from capital-equipment replacement. Medical billing outsourcing supports a separate administrative part of the provider workflow, whereas device purchasing remains tied to the required clinical task and care setting.
- Medical devices represent 38.6% of product type demand in 2026, leading the commercial classification that also covers medical equipment, in-vitro diagnostics and telemedicine platforms across healthcare purchasing settings. [1]
- A healthcare buyer needs to assess the device's intended clinical function alongside relevant authorization, product records and training requirements, because those factors determine how the offer fits an actual care pathway.
Table 3: Leading product type share for the MedTech market
| Product type | Share in 2026 |
|---|---|
| Medical devices | 38.6% |
| Other segments combined | 61.4% |
| Total | 100.0% |
Table 4: Segment leadership and market growth for the MedTech market
| Metric | Value |
|---|---|
| Global CAGR 2026 to 2036 | 4.5% |
| Leading segment | Medical devices |
Why does cardiology lead demand within the application category?
The cardiology segment accounts for 26.9% of application demand in 2026. [1]
Cardiology includes monitoring and intervention technologies that perform different tasks within a care pathway, creating a range of product and support requirements within one application category. Buyers need to match each offering to the clinical function and intended setting, with staff training, consumables and maintenance assessed alongside acquisition. A monitoring product and an intervention device can therefore generate different procurement and replacement needs even within the same application. This breadth of clinical functions helps explain cardiology's leading place in the application outlook.
- Cardiology accounts for 26.9% of application demand in 2026, giving it the leading share within a classification that also includes orthopedics, oncology, neurology, respiratory care and other applications. [1]
- Monitoring and intervention products need separate purchasing assessments covering training, consumables and maintenance, so procurement teams can connect the supplied technology with its particular clinical task and intended care setting.
What are the drivers restraints and opportunities in the MedTech market?
- Driver: Hospitals purchase devices and equipment for defined tasks within a care pathway, supporting demand for products and consumables whose intended use, training needs and service arrangements fit the clinical setting and purchasing cycle.
- Restraint: Manufacturers must maintain controlled quality and product-record processes as FDA's QMSR and EUDAMED requirements apply, creating implementation work while product-specific authorization and clinical suitability continue to require their own assessment. [2][3]
- Opportunity: Suppliers can organize intended-use information, manufacturer records and service commitments into a coherent purchasing offer, helping healthcare organizations compare relevant technologies and support needs across the actual clinical functions they intend to procure.
Defined clinical functions support product procurement
Hospitals need equipment and devices for specific tasks within the care pathway, with product and consumable demand following that use and procurement schedules reflecting the clinical function required alongside the number of patients receiving care.
Quality and registry requirements add supplier work
FDA's QMSR and EU database requirements affect manufacturer records, creating a need for controlled implementation while the completed record serves its stated regulatory purpose alongside the product-level qualification relevant to the actual clinical technology supplied. [2][3]
Clear records can improve procurement comparison
EUDAMED's first four modules became mandatory in May 2026, establishing product and manufacturer records that support market oversight and that suppliers can organize alongside the service arrangements offered for the relevant healthcare technology. [3]
Which country CAGRs are profiled in the MedTech market?
Table 5: Country CAGR comparison for the MedTech market
| Country or regional market | CAGR 2026 to 2036 |
|---|---|
| European Union | 4.6% |
| South Korea | 4.5% |
| Japan | 4.4% |
| USA | 4.3% |
| UK | 4.2% |
Country and Regional Analysis
European Union
Device suppliers serving the European Union face a defined change in product administration as the first four EUDAMED modules became mandatory from 28 May 2026, covering actor registration, device identification, notified bodies and certificates, and market surveillance. [3] Keeping the relevant records current creates a practical task alongside commercial distribution, because a broad portfolio contains products with different classifications and supporting documents. The regional MedTech outlook projects 4.6% CAGR from 2026 to 2036 across the combined European Union market, alongside demand for device-specific clinical and service support. [1] For a hospital, those records sit alongside questions about clinical fit, training and maintenance of the particular device. A distributor coordinating several countries also needs an orderly route for updated product information, allowing the purchasing team to identify which equipment and service commitment its contract actually covers before installation or replacement.
South Korea
A South Korean hospital buying an imaging system makes a different operating commitment from a surgical department selecting implants, even when both purchases fall within the same supplier’s MedTech portfolio. Imaging equipment needs installation, staff training and continued maintenance, while an implant purchase connects product selection with the procedure and the clinician’s requirements. FMI projects 4.5% CAGR for South Korea from 2026 to 2036, as hospitals compare the operating commitments of different clinical products. [1] Procurement teams can therefore compare the full support arrangement for each product rather than apply one qualification checklist across every category. Where equipment is expected to serve several departments, scheduling and access to technical support become part of the purchasing decision. A supplier that specifies service responsibilities, compatible consumables and the scope of training gives the hospital a clearer basis for planning the device’s use after the initial order.
Japan
Replacing a clinical system in Japan can involve changes to an established workflow, so the hospital’s decision extends from the equipment specification to the way staff will use it during daily care. A new diagnostic platform may require revised training, compatible consumables and a maintenance schedule that fits the department’s workload, making the transition important alongside the capital price. The Japan MedTech outlook records 4.4% CAGR from 2026 to 2036, with replacement purchases needing to fit an established departmental workflow. [1] Buyers can examine whether a proposed replacement addresses the actual operating need and how the supplier will support installation and subsequent service. For equipment used repeatedly, the availability of consumables and technical assistance influences the continuing commitment. A clear account of those responsibilities allows purchasing and clinical teams to assess the same offer, reducing ambiguity when the selected system moves from evaluation into routine use.
USA
The FDA’s Quality Management System Regulation became effective in the USA on 2 February 2026, incorporating ISO 13485:2016 into the quality-system framework for relevant finished-device manufacturers. [2] Manufacturers have to connect that framework with the records and controls applicable to their products, while a hospital still needs separate evidence of clinical suitability for the intended use. The USA MedTech forecast projects 4.3% CAGR from 2026 to 2036, while supplier qualification still depends on the selected device and support offer. [1] For suppliers, quality documentation and the operational offer are closely connected when a buyer asks about installation, training and post-sale support. An imaging platform, a diagnostic product and an implant present different continuing requirements, so procurement teams can evaluate the specific device and service package rather than infer suitability from a supplier’s overall scale. Clear responsibilities help the buyer plan use and maintenance after the purchase.
UK
Procurement in the UK needs to connect the clinical purpose of a MedTech product with the people who will install, use and maintain it, since those responsibilities can cross several departments. A diagnostic platform may commit the buyer to consumables and technical support, whereas a surgical device also needs a clear relationship with the procedure and training offered to clinical staff. Against those purchasing conditions, FMI projects 4.2% CAGR from 2026 to 2036 for the UK market. [1] A broad supplier portfolio does not make every product interchangeable, and the contract needs to identify the selected equipment and the support included. Buyers comparing replacement options can consider the effect on existing workflows and the time required to bring the new system into use, giving the service arrangement a concrete role in the purchasing decision.
Who are the notable companies in the MedTech market?
Medtronic; Siemens Healthineers; Abbott; GE HealthCare; Stryker
Competitive Benchmarking
Table 6: Competitive positioning for the MedTech market
| Company or institution | Positioning | Evidence or purchasing distinction |
|---|---|---|
| Medtronic | Therapeutic device portfolio | Clinical function guides product selection [1] |
| Siemens Healthineers | Diagnostic and medical equipment | Capital and service requirements [1] |
| Abbott | Devices and diagnostics | Devices and diagnostics within a broader portfolio [1] |
| GE HealthCare | Medical imaging and patient-care equipment | Official portfolio lists imaging, ultrasound and patient monitoring products. [4] |
| Stryker | MedSurg, neurotechnology and orthopaedics | Official portfolio identifies these clinical product and service areas. [5] |
Key Developments in the MedTech Market
- FDA's QMSR became effective in February 2026 and incorporates ISO 13485:2016 by reference, establishing manufacturing quality-system requirements that healthcare suppliers need to address alongside the clinical and authorization evidence for individual products. [2]
- The first four EUDAMED modules became mandatory in May 2026, introducing defined product and manufacturer-record obligations within the European framework while the relevant regulatory requirements still depend on the specific product and category. [3]
Key Players in the MedTech Market
Medtronic; Siemens Healthineers; GE HealthCare; Stryker; Philips; Boston Scientific; Zimmer Biomet; Abbott; BD.
MedTech Market Report Scope
The commercial product categories comprise medical devices, medical equipment, in-vitro diagnostics and telemedicine platforms. Clinical applications and buyer groups define their use; regional figures for the European Union describe that combined market.
Table 7: Report coverage for the MedTech market
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; Application; End user; Distribution; Pricing; region |
| Quantitative units | USD billion |
| Market definition | Commercial medtech products and attributable platforms by the defined categories. Care-service revenue and pharmaceuticals are excluded. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries profiled | European Union; South Korea; Japan; USA; UK |
| Key companies profiled | Medtronic; Siemens Healthineers; GE HealthCare; Stryker; Philips; Boston Scientific; Zimmer Biomet; Abbott; BD |
| Forecast period | 2026 to 2036 |
MedTech Market Research Methodology
Table 8: Research methods for the MedTech market
| Method | Approach |
|---|---|
| Market definition | The study examines the MedTech market through product type, application, end user, distribution and pricing, identifying the products or services and purchasing transactions covered. |
| Public documentary research | FMI market research, FDA quality-system guidance, European Commission device-record information and official company portfolios inform the analysis of product characteristics, operating conditions and market context. |
| Company portfolio research | Official product pages and company disclosures describe relevant offerings, intended customers and participation within wider business portfolios. |
| Segment assessment | The product type, application, end user, distribution and pricing categories are examined through product or service characteristics, practical use and purchase conditions. |
| Country research | Local distribution, purchasing arrangements and applicable public requirements inform country analysis alongside the reported market outlook. |
| Regulatory and technical assessment | Intended clinical functions, authorization, manufacturing quality requirements and device records are considered alongside the training and service needed in each care setting. |
| Forecast coverage | The forecast considers the demand drivers, purchasing constraints and supplier opportunities affecting the market across the study period. |
MedTech Market by Segments
By product type
- Medical devices
- Medical equipment
- In-vitro diagnostics
- Telemedicine platforms
By application
- Cardiology
- Orthopedics
- Oncology
- Neurology
- Respiratory
- Other applications
By end user
- Hospitals and clinics
- Ambulatory surgical centers
- Home healthcare
- Diagnostic laboratories
By distribution
- Direct
- Indirect
By pricing
- Premium
- Mid-range
- Low-cost
- Subscription and pay-per-use
MedTech Market by Region
- North America
- USA
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- UK
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Future Market Insights. Published outlook accessed 12 October 2026. MedTech Market.
- [2] US Food and Drug Administration. 2 February 2026. Quality Management System Regulation.
- [3] European Commission. 27 November 2025 announcement; May 2026 application. First four EUDAMED modules mandatory from 28 May 2026.
- [4] GE HealthCare. Accessed October 2026. Products.
- [5] Stryker. Accessed October 2026. About Stryker.
This Report Answers
- How big is the MedTech market in 2026?
- What market value is projected by 2036?
- Which product type segment leads demand?
- Which other commercial categories shape the market?
- Which countries have the fastest profiled growth?
- Which companies and institutions participate in the market?
Frequently Asked Questions
How large is the MedTech market in 2026?
FMI estimates market value at USD 574.24 billion in 2026. The estimated 2025 value is USD 549.5 billion. [1]
What value and CAGR are projected through 2036?
Market value is projected to reach USD 891.78 billion by 2036 at a 4.5% CAGR from 2026 to 2036. [1]
Which product type segment leads in 2026?
Medical devices account for 38.6% of this category. [1]
What is the report segmentation?
Product type; Application; End user; Distribution; Pricing, and region.
Which profiled market records the highest CAGR?
European Union has the highest profiled rate at 4.6% from 2026 to 2036. [1]
Who are the key participants?
Medtronic; Siemens Healthineers; GE HealthCare; Stryker; Philips; Boston Scientific; Zimmer Biomet; Abbott; BD.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By product type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By product type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By product type, 2026 to 2036
- Medical devices
- Medical equipment
- In-vitro diagnostics
- Telemedicine platforms
- Y-o-Y Growth Trend Analysis By product type, 2021 to 2025
- Absolute $ Opportunity Analysis By product type, 2026 to 2036
- Global Market Analysis and Forecast, By application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By application, 2026 to 2036
- Cardiology
- Orthopedics
- Oncology
- Neurology
- Respiratory
- Other applications
- Y-o-Y Growth Trend Analysis By application, 2021 to 2025
- Absolute $ Opportunity Analysis By application, 2026 to 2036
- Global Market Analysis and Forecast, By end user, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By end user, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By end user, 2026 to 2036
- Hospitals and clinics
- Ambulatory surgical centers
- Home healthcare
- Diagnostic laboratories
- Y-o-Y Growth Trend Analysis By end user, 2021 to 2025
- Absolute $ Opportunity Analysis By end user, 2026 to 2036
- Global Market Analysis and Forecast, By distribution, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By distribution, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By distribution, 2026 to 2036
- Direct
- Indirect
- Y-o-Y Growth Trend Analysis By distribution, 2021 to 2025
- Absolute $ Opportunity Analysis By distribution, 2026 to 2036
- Global Market Analysis and Forecast, By pricing, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By pricing, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By pricing, 2026 to 2036
- Premium
- Mid-range
- Low-cost
- Subscription and pay-per-use
- Y-o-Y Growth Trend Analysis By pricing, 2021 to 2025
- Absolute $ Opportunity Analysis By pricing, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By product type
- By application
- By end user
- By distribution
- By pricing
- By Country
- Market Attractiveness Analysis
- By Country
- By product type
- By application
- By end user
- By distribution
- By pricing
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By product type
- By application
- By end user
- By distribution
- By pricing
- By Country
- Market Attractiveness Analysis
- By Country
- By product type
- By application
- By end user
- By distribution
- By pricing
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- UK
- Italy
- Spain
- Benelux
- Nordics
- By product type
- By application
- By end user
- By distribution
- By pricing
- By Country
- Market Attractiveness Analysis
- By Country
- By product type
- By application
- By end user
- By distribution
- By pricing
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By product type
- By application
- By end user
- By distribution
- By pricing
- By Country
- Market Attractiveness Analysis
- By Country
- By product type
- By application
- By end user
- By distribution
- By pricing
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By product type
- By application
- By end user
- By distribution
- By pricing
- By Country
- Market Attractiveness Analysis
- By Country
- By product type
- By application
- By end user
- By distribution
- By pricing
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By product type
- By application
- By end user
- By distribution
- By pricing
- By Country
- Market Attractiveness Analysis
- By Country
- By product type
- By application
- By end user
- By distribution
- By pricing
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC countries
- South Africa
- Türkiye
- Israel
- By product type
- By application
- By end user
- By distribution
- By pricing
- By Country
- Market Attractiveness Analysis
- By Country
- By product type
- By application
- By end user
- By distribution
- By pricing
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By application
- By end user
- By distribution
- By pricing
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By application
- By end user
- By distribution
- By pricing
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By application
- By end user
- By distribution
- By pricing
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By application
- By end user
- By distribution
- By pricing
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By application
- By end user
- By distribution
- By pricing
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By application
- By end user
- By distribution
- By pricing
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By application
- By end user
- By distribution
- By pricing
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By application
- By end user
- By distribution
- By pricing
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By application
- By end user
- By distribution
- By pricing
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By application
- By end user
- By distribution
- By pricing
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By application
- By end user
- By distribution
- By pricing
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By application
- By end user
- By distribution
- By pricing
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By application
- By end user
- By distribution
- By pricing
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By application
- By end user
- By distribution
- By pricing
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By application
- By end user
- By distribution
- By pricing
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By application
- By end user
- By distribution
- By pricing
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By application
- By end user
- By distribution
- By pricing
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By application
- By end user
- By distribution
- By pricing
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By application
- By end user
- By distribution
- By pricing
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By application
- By end user
- By distribution
- By pricing
- European Union
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By application
- By end user
- By distribution
- By pricing
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By product type
- By application
- By end user
- By distribution
- By pricing
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Medtronic
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Siemens Healthineers
- Abbott
- GE HealthCare
- Stryker
- Medtronic
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


