
- Market Size (2026)
- USD 3.2 Bn
- Forecast (2036)
- USD 6.8 Bn
- CAGR (2026 to 2036)
- 7.8%
How big is Freeze-Dried Vegetables Market in 2026?
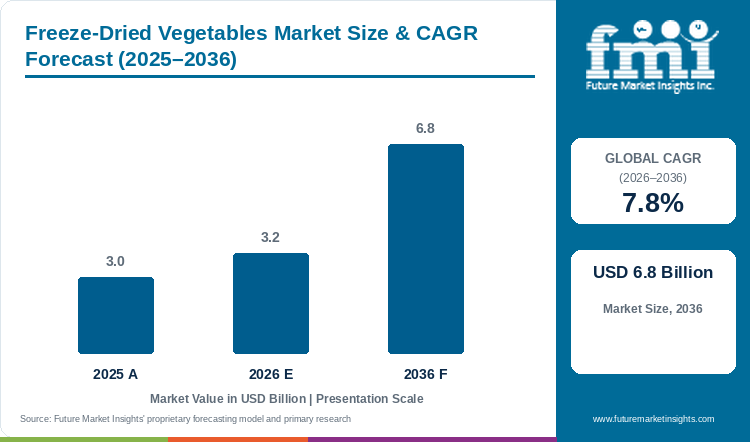
Demand for freeze-dried vegetables is projected to expand at 7.8% CAGR between 2026 and 2036, with industry value growing from USD 3.0 billion in 2025 to USD 3.2 billion in 2026 and reaching USD 6.8 billion by 2036.
Thermal case-hardening in conventional hot-air dryers slows rehydration and dulls natural chlorophyll pigments, prompting soup and ready-meal plants to switch toward vacuum-sublimated vegetable cuts. Sublimation removes ice crystals directly as vapor below minus 40 degrees Celsius, leaving an open honeycomb pore structure inside dehydrated vegetables that absorbs boiling water within ninety seconds.
In April 2026, the United States Department of Agriculture Economic Research Service reported higher year-over-year per-capita availability for major processing vegetables including sweet corn and snap beans, expanding raw feedstock supply for domestic dehydration plants. According to FMI, global market value rises from USD 3.0 billion in 2025 to USD 3.2 billion in 2026 and reaches USD 6.8 billion by 2036 at a 7.8% CAGR, generating USD 3.6 billion in added revenue. Standard commercial grade captures 47.1% of product type demand in 2026, while country growth spans 6.2% in the UK to 9.5% in the United States.
Key Market Trends & Insights
- By product type / grade: Standard commercial grade led with 47.1% share in 2026, as uniform 5-millimeter and 10-millimeter diced cuts feed high-speed volumetric soup and noodle fillers without bridging.
- By processing state: Fresh / ambient packaged accounted for 53.5% in 2026, reflecting residual moisture below 2.5% that halts microbial activity without refrigerated warehousing.
- By end-use application: Direct retail consumer consumption held 38.1% in 2026, supported by household demand for single-ingredient vegetable crisps and lightweight backpacking meal pouches.
Regional Highlights
- Fastest-growing evaluated country: USA, at 9.5% CAGR from 2026 to 2036.
- By country: France at 8.7%, Switzerland at 8.1%, and Australia at 7.5% follow, while the UK records the lowest evaluated CAGR at 6.2%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Freeze-Dried Vegetables Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 3.0 billion |
| Estimated Market Size in 2026 | USD 3.2 billion |
| Projected Market Size by 2036 | USD 6.8 billion |
| CAGR, 2026 to 2036 | 7.8% |
| Added Revenue, 2026 to 2036 | USD 3.6 billion |
Growth conditions vary between the profiled countries as industrial electricity tariffs and contract-farming supply chains shape lyophilization batch economics. FMI research indicates that culinary brand owners formulating dry premixes alongside canned soup lines use freeze-dried sweet corn and leek flakes to eliminate sodium metabisulfite preservatives from ingredient decks. In December 2025, the Food and Agriculture Organization of the United Nations reported that global fruit and vegetable output reached 2.1 billion metric tons, highlighting the need for post-harvest preservation to curb perishability losses. Consequently, processors are installing continuous blast-freezing tunnels near harvest basins to lock in field nutrition within four hours of picking.
Lyophilization Throughput and Industrial Batch Moisture Parameters
Table 2: Industrial Lyophilization Parameters and Throughput Metrics for the Freeze-Dried Vegetables Market (USD billion and metric units), mixed historical and forecast years from 2025 to 2036
| Processing Parameter | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 3.0 | 3.2 | 6.8 |
| Industrial batch vacuum throughput (thousand metric tons) | 48.5 | 52.4 | 124.0 |
| Average chamber sublimation cycle time (hours) | 18.5 | 17.8 | 13.2 |
| Certified organic raw input volume share (percent) | 24.2% | 26.5% | 42.8% |
Industrial Moisture Preservation and Formulation Consumption Spending
Packaged food formulators incorporate lyophilized vegetable dices and milled flakes into dry skillet meals and instant ramen cups alongside specialty food ingredients to deliver recognizable piece identity upon rehydration. Retaining cellular wall geometry during sublimation prevents the shriveled texture typical of belt-dried produce, allowing brands to command clean-label retail pricing across grocery aisles.
Table 3: Institutional and Industrial Consumption Spending Indicators for the Freeze-Dried Vegetables Market (USD and percentages), mixed historical and forecast years from 2025 to 2036
| Expenditure Indicator | 2025 | 2026 | 2036 |
|---|---|---|---|
| Per capita prepared soup and dry meal expenditure (USD) | 34.5 | 36.8 | 64.5 |
| Commercial food formulator ingredient share (percent) | 36.2% | 37.8% | 48.0% |
| Organic and clean-label price premium (percent) | 28.5% | 27.0% | 19.8% |
| Emergency preparedness ration spending allocation (percent) | 15.4% | 16.2% | 23.2% |
Table 4: Facility Processing Footprint and Sublimation Energy Standards for the Freeze-Dried Vegetables Market (USD and metric units), mixed reporting years from 2024 to 2026
| Operational Metric | Value | Scope Reference |
|---|---|---|
| Market size, 2026 | USD 3.2 billion | Report value |
| Industrial lyophilizer energy index | 14.8 kWh per kg dried | 2026 plant benchmark |
| Cold storage pre-freezing temperature minimum | -45.0 degrees Celsius | Sublimation standard |
| Direct retail consumer consumption revenue, 2026 | USD 1.2 billion | 38.1% share |
Analyst Perspective
"Replacing sulfite-treated air-dried produce with vacuum freeze-dried vegetable cuts lets soup and meal makers meet strict clean-label retail standards. High electricity consumption during eighteen-hour sublimation cycles still forces processors to invest in condenser heat recovery before scaling volume."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Freeze-Dried Vegetables Market segmented?
The freeze-dried vegetables market is segmented by product type / grade, processing state, and end-use application.
By product type / grade: Standard commercial grade, organic & clean-label variant, and premium specialty formulation.
By processing state: Fresh / ambient packaged, frozen & chilled, and dehydrated & dry packaged.
By end-use application: Direct retail consumer consumption, food service & hospitality, and commercial food manufacturing plants.
Why does Standard Commercial Grade lead the product type category?
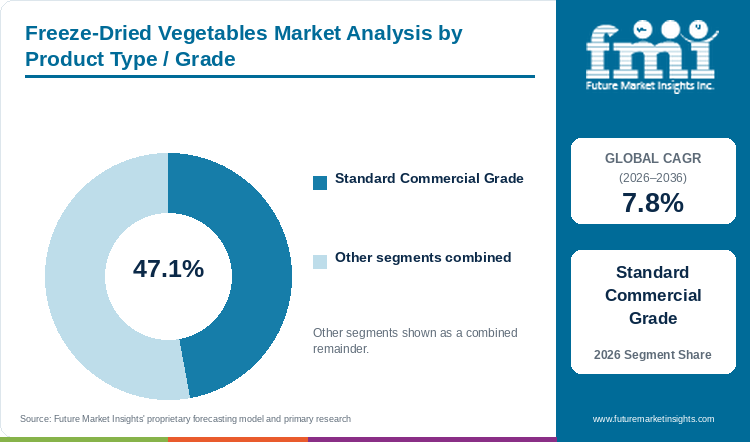
Standard commercial grade is projected to account for 47.1% of product type demand in 2026, supported by uniform soup rehydration.
Table 5: Product Type / Grade Share for the Freeze-Dried Vegetables Market (percentage share), 2026
| Product Type / Grade | Share (2026) |
|---|---|
| Standard Commercial Grade | 47.1% |
| Other Segments Combined | 52.9%* |
| Total | 100.0% |
Table 6: Product Type / Grade Leadership and Market Growth for the Freeze-Dried Vegetables Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.8% |
| Leading Segment | Standard Commercial Grade |
While canned vegetables carry heavy brine weight and frozen vegetables require uninterrupted minus-18-degree freezer chains, standard commercial grade freeze-dried cuts give dry-mix factories a lightweight, free-flowing ingredient that doses accurately on high-speed auger fillers. Multinational noodle and soup plants specify calibrated 5-millimeter carrot and green pea dices so every cup rehydrates at the same rate when boiling water is added. Standard conventional farming contracts also keep raw crop costs predictable compared with certified organic lots.
- Standard commercial grade accounts for 47.1% of product type demand in 2026, supported by calibrated particle sizing and high-volume soup and noodle contracts.
- In March 2025, the International Food Dehydration Manufacturers Association reported that standardized 5-millimeter lyophilized vegetable dices achieve 96.0% rehydration within ninety seconds in boiling water.
What makes Fresh / Ambient Packaged central to the processing state category?
Fresh and ambient packaged formats are estimated to hold 53.5% of processing state revenue in 2026, driven by ambient storage.
Ambient packaged formats capture the majority of revenue because sublimating 98% of intracellular water reduces water activity below the threshold needed for bacterial or mold growth. Once sealed inside nitrogen-flushed foil pouches or multi-wall bulk liners, diced vegetables and milled vegetable powders remain stable at room temperature for up to ten years. Eliminating refrigerated trucks and cold-storage warehouse bays cuts cross-border freight weight by up to 90% compared with wet produce, making ambient bulk drums the preferred choice for international ingredient trade.
- Fresh and ambient packaged holds 53.5% of processing state revenue in 2026, driven by ten-year room-temperature stability in nitrogen-flushed barrier packaging.
- In May 2025, the European Dehydrated Foods Federation documented that switching from frozen to ambient lyophilized vegetable ingredients lowers warehouse and transport energy usage by 68.0%.
How does Direct Retail Consumer Consumption shape end-use application demand?
Direct retail consumer consumption is expected to capture 38.1% of end-use application sales in 2026, reflecting demand for trail rations.
Retail consumer sales lead the three end-use channels as urban shoppers purchase vacuum-sealed okra and snap pea crisps as low-oil alternatives to deep-fried potato chips. At the same time, hikers and household emergency planners buy multi-serving freeze-dried food pouches that reconstitute directly inside the bag with hot water. Because retail shoppers eat single-ingredient vegetable snacks straight from the pouch without cooking, processors must maintain strict low-moisture sanitation controls during post-dryer slicing and packing.
- Direct retail consumer consumption accounts for 38.1% of end-use application revenue in 2026, reflecting expanding grocery distribution of vegetable snack crisps and camping rations.
- In January 2025, the U.S. Food and Drug Administration issued draft sanitation guidance for low-moisture ready-to-eat human foods to strengthen pathogen control in dry packaging lines.
What are the drivers, restraints, and opportunities in the Freeze-Dried Vegetables Market?
In the freeze-dried vegetables market, clean-label soup and snack reformulation drives demand, high vacuum-chamber capital and electricity costs restrain smaller processors, and regenerative organic retail pouches create high-margin opportunities through 2036.
- Driver: Clean-label reformulation across instant soups and noodle bowls replaces synthetic flavorings with whole lyophilized vegetable cuts through 2036.
- Restraint: Multi-million-dollar vacuum sublimation equipment outlays and eighteen-hour batch electricity loads restrict capacity additions among regional agricultural cooperatives.
- Opportunity: Launching single-serve crunchy vegetable snacks and traceable organic emergency meal kits opens high-margin retail and e-commerce channels through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Packaged food brands are removing artificial monosodium glutamate and synthetic colorants from dry dinner kits, replacing them with visible pieces of freeze-dried fruits and vegetables that validate natural front-of-pack claims. Unlike drum-dried flakes that turn brownish during heat exposure, lyophilized broccoli florets and sweet corn kernels retain their field color and volatile aroma esters inside clear retail windows. In April 2025, the Clean Label Food Processing Alliance reported that 71.0% of surveyed European and North American dry-meal formulators increased whole-vegetable inclusion targets for 2026 product launches. This reformulation wave locks in multi-year bulk volume for contract dehydrators.
Risk Assessment of the Freeze-Dried Vegetables Market: Operational and Formulation Friction
Sublimation drying remains one of the most capital- and energy-intensive unit operations in food processing because ice must be frozen below minus 40 degrees Celsius before vacuum pumps hold chamber pressure near 0.5 millibars for up to eighteen hours. A single industrial multi-chamber freeze-drying line requires USD 6.0 million to USD 12.0 million in capital equipment, while refrigeration compressors and vacuum condensers consume 14.8 kilowatt-hours per kilogram of finished product. In August 2025, the Global Vacuum Engineering Council noted that industrial electricity costs account for 38.0% of total operating expenditure in batch vegetable lyophilization plants. High fixed overhead prevents processors from competing on price against commodity hot-air-dried onions or carrots in budget soup lines.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Processors are capturing higher wholesale margins by developing crunchy whole-vegetable snacking pouches and functional clean-label ingredients that bypass commodity soup price pressure. Vacuum-puffed okra pods and seasoned edamame crisps appeal to parents seeking school-safe snacks with intact dietary fiber. At the same time, severe weather disruptions are prompting households to stock long-life survival pantries. In September 2025, the Emergency Food Preparedness Institute documented a 24.0% annual rise in North American household purchases of ten-year shelf-stable freeze-dried ration buckets. Suppliers that pair automated nitrogen pouching with regenerative organic farm traceability can secure premium retail private-label contracts.
Freeze-Dried Vegetables Market by Country (2026 to 2036)
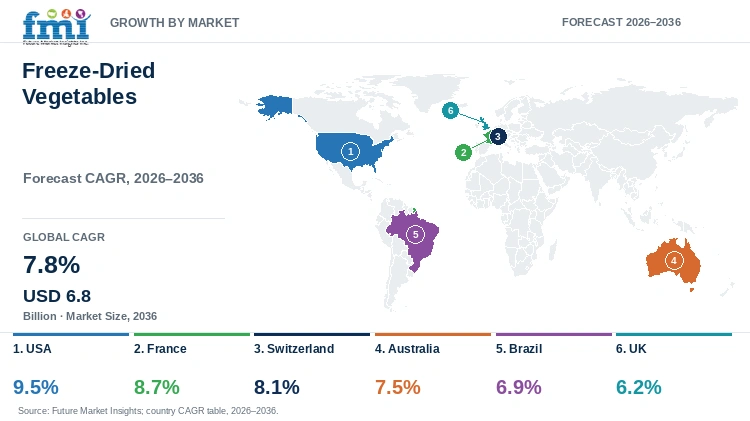
As per the analysis from FMI, the United States leads growth among the evaluated countries at a 9.5% CAGR from 2026 to 2036, whereas the United Kingdom expands at 6.2% CAGR. Across all six markets, national performance depends on local specialty crop supply and industrial power tariffs alongside retail snack adoption.
Table 7: Country CAGR and Primary Growth Levers for the Freeze-Dried Vegetables Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| USA | 9.5% | High outdoor backpacking meal demand, emergency ration stockpiling, and commercial dry soup reformulation |
| France | 8.7% | Culinary herb and mushroom lyophilization for gourmet sauces, clean-label bakery, and organic retail |
| Switzerland | 8.1% | Precision vacuum drying engineering and micronized botanical vegetable powders for nutraceuticals |
| Australia | 7.5% | Counter-seasonal vegetable drying in Victoria and New South Wales for East Asian export corridors |
| Brazil | 6.9% | Tropical root and legume sublimation expansion alongside urban healthy vegetable crisp adoption |
| UK | 6.2% | Supermarket private-label instant soup cups, dry pasta meal kits, and zero-waste household pantry staples |
Source: Future Market Insights analysis
USA Freeze-Dried Vegetables Market Outlook (2026 to 2036)
Demand in the United States is projected to expand at a 9.5% CAGR from 2026 to 2036, reaching a baseline valuation of USD 720.5 million in 2026 as outdoor recreation brands and CPG soup plants scale domestic procurement. In September 2026, the United States Department of Agriculture Economic Research Service highlighted shifting processing vegetable acreage across major domestic growing states, encouraging contract dehydrators to lock in multi-season sweet corn and green pea supply. However, tight agricultural labor availability in California and the Pacific Northwest raises raw crop harvesting costs. American lyophilization plants offset raw produce inflation by installing continuous automated tray-loading tunnels that cut labor hours per metric ton.
Key takeaway: In the USA, strong outdoor trail-meal demand and automated continuous sublimation lines drive a 9.5% CAGR through 2036.
France Freeze-Dried Vegetables Market Outlook (2026 to 2036)
France is forecast to grow at an 8.7% CAGR through 2036, supported by gourmet sauce makers and culinary bakeries that require aromatic shallots and wild mushrooms along with leeks free from thermal scorching. In November 2025, FranceAgriMer reported that French food processors increased procurement of certified organic dehydrated culinary vegetables by 14.0% to meet clean-label retail charters. A primary challenge for French dehydrators is complying with strict national pesticide-residue limits while competing against lower-cost Eastern European air-dried imports. Domestic producers protect their position by specializing in terroir-certified, cryo-milled vegetable flakes that preserve volatile essential oils for premium culinary applications.
Key takeaway: In France, gourmet sauce formulation and strict clean-label organic standards support an 8.7% CAGR through 2036.
Switzerland Freeze-Dried Vegetables Market Outlook (2026 to 2036)
Swiss buyers emphasize pharmaceutical-grade micronization and bioactive retention, propelling Switzerland at an 8.1% CAGR between 2026 and 2036. In December 2025, the Swiss Federal Office for Agriculture documented rising contract processing of alpine spinach and beetroot into standardized nutraceutical powders across domestic agri-food clusters. High Swiss industrial wage rates and strict cantonal energy-efficiency rules make bulk commodity vegetable drying uneconomical inside the country. Swiss contract lyophilizers overcome high operating costs by focusing on high-value, cleanroom-milled cruciferous vegetable extracts sold to European dietary supplement and infant-nutrition brands.
Key takeaway: In Switzerland, cleanroom lyophilization engineering and high-margin nutraceutical green powders sustain an 8.1% CAGR.
Australia Freeze-Dried Vegetables Market Outlook (2026 to 2036)
Australia is anticipated to record a 7.5% CAGR from 2026 to 2036 as processors in Victoria and New South Wales convert seasonal surpluses of carrots and broccoli into shelf-stable export drums. In January 2026, the Australian Export and Trade Commission reported that dehydrated and freeze-dried vegetable shipments to Japan and South Korea rose 16.5% year over year. Because fresh Australian produce faces strict phytosanitary fumigation rules and high air-freight rates when exported across Asia, vacuum freeze-drying allows growers to ship container loads by sea without quarantine delays. Recurring drought cycles in the Murray-Darling Basin still require processors to diversify irrigated farm contracts.
Key takeaway: In Australia, phytosanitary-exempt maritime exports to East Asian food hubs and harvest-surplus valorization drive a 7.5% CAGR.
Brazil Freeze-Dried Vegetables Market Outlook (2026 to 2036)
Sales in Brazil are projected to rise at a 6.9% CAGR through 2036 as agro-industrial cooperatives in Sao Paulo and Parana install vacuum drying chambers for cassava and tropical legumes. In February 2026, the Brazilian Agricultural Research Corporation (Embrapa) published technical feasibility data showing that freeze-drying indigenous root crops reduces post-harvest spoilage by 45.0% in humid tropical distribution corridors. Even so, high import duties and financing rates on European vacuum condensers slow capacity additions for mid-sized Brazilian dehydrators. Domestic engineering firms are addressing this capital bottleneck by fabricating modular batch freeze-dryers tailored for regional cooperative plants.
Key takeaway: In Brazil, year-round tropical root crop availability and domestic modular dryer fabrication support a 6.9% CAGR.
United Kingdom Freeze-Dried Vegetables Market Outlook (2026 to 2036)
The United Kingdom market is estimated to expand at a 6.2% CAGR from 2026 to 2036, anchored by supermarket private-label instant noodle pots and dry pasta meal kits. In March 2026, the British Food and Drink Federation noted that UK grocery shoppers increased purchases of ambient long-life vegetable ingredients to cut household refrigerator food waste amid elevated living costs. However, intense price competition among British supermarket chains squeezes processor margins on standard diced peas and onions. UK dehydration specialists maintain profitability by supplying custom-blended, optical-sorted vegetable garnishes and savory baking inclusions under contract with domestic convenience food packers.
Key takeaway: In the UK, private-label instant meal kits and household waste-reduction habits sustain a 6.2% CAGR through 2036.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Freeze-Dried Vegetables Market?
Nestle S.A., General Mills, Inc., The Kraft Heinz Company, Conagra Brands, Inc., Campbell Soup Company, Van Drunen Farms, European Freeze Dry, and Chaucer Foods (Nagase Group) are the significant market players in this market.
FMI data suggests that the supply chain separates into global packaged-meal brand owners that consume captive and contracted volumes, and dedicated B2B lyophilization specialists that operate multi-chamber vacuum plants. While CPG leaders integrate freeze-dried dices into dry soups and frozen ready meals, industrial dehydrators compete on continuous tunnel throughput and optical foreign-matter sorting along with organic farm certifications.
- Multidivisional Packaged Food Conglomerates: Nestle S.A., General Mills, Inc., The Kraft Heinz Company, Conagra Brands, Inc., and Campbell Soup Company formulate shelf-stable soups and dry meal kits at global scale.
- Specialized Industrial Lyophilization Processors: Van Drunen Farms, European Freeze Dry, and Chaucer Foods (Nagase Group) supply custom-diced, powdered, and organic B2B vegetable ingredients.
- Outdoor Recreation & Emergency Ration Specialists: OFD Foods (Mountain House) and Thrive Life, LLC package long-life consumer meal pouches and single-vegetable pantry cans.
Competitive Benchmarking: Freeze-Dried Vegetables Market
Table 8: Competitive Benchmarking for the Freeze-Dried Vegetables Market (qualitative capability ratings), 2026
| Company | Lyophilization Capacity Depth | Clean-Label Certification Scope | Industrial Formulator Reach | Geographic Reach |
|---|---|---|---|---|
| Nestle S.A. | High | High | High | High |
| General Mills, Inc. | High | High | High | Medium |
| The Kraft Heinz Company | High | Medium | High | High |
| Conagra Brands, Inc. | Medium | Medium | High | Medium |
| Campbell Soup Company | High | High | High | Medium |
| Van Drunen Farms | High | High | High | High |
| European Freeze Dry | High | High | High | Medium |
| Chaucer Foods (Nagase Group) | High | High | High | High |
Key Developments in the Freeze-Dried Vegetables Market
- In March 2025, Mountain House (OFD Foods) appointed LOUDMOUTH, a Los Angeles-based creative advocacy agency, as its social and community marketing partner to drive new recipe launches and brand expansion across outdoor adventure and emergency preparedness retail channels [15].
- In August 2025, Glacial Freeze Dry acquired Foodynamics to expand its contract freeze-dry manufacturing services, integrating Foodynamics’ established customer network with Glacial Freeze Dry’s processing capacity and freeze-dry technology for the co-manufacturing segment [16].
- By 2024, Van Drunen Farms Europe doubled its annual production capacity for freeze-dried fruits and vegetables to approximately 750 metric tonnes at its Serbia facility, with further expansion into the Scandinavian market planned for the near term [18].
Key Players in the Freeze-Dried Vegetables Market
Multidivisional Packaged Food Conglomerates
- Nestle S.A.
- General Mills, Inc.
- The Kraft Heinz Company
- Conagra Brands, Inc.
- Campbell Soup Company
Specialized Industrial Lyophilization Processors
- Van Drunen Farms
- European Freeze Dry
- Chaucer Foods (Nagase Group)
Outdoor Recreation & Emergency Ration Specialists
- OFD Foods (Mountain House)
- Thrive Life, LLC
Freeze-Dried Vegetables Market - Report Scope
Table 9: Report Scope for the Freeze-Dried Vegetables Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type / Grade; Processing State; End-Use Application |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial revenue from vacuum freeze-dried (lyophilized) vegetable dices, slices, florets, flakes, and milled powders sold across retail, foodservice, and industrial food manufacturing channels. Excludes conventional hot-air-dried vegetables, canned wet vegetables, and frozen produce. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA, France, Switzerland, Australia, Brazil, UK, and additional countries in the full report |
| Key Companies Covered | Nestle S.A., General Mills, Inc., The Kraft Heinz Company, Conagra Brands, Inc., Campbell Soup Company, Van Drunen Farms, European Freeze Dry, Chaucer Foods (Nagase Group) |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Freeze-Dried Vegetables Market - Research Methodology
Table 10: Research Methodology for the Freeze-Dried Vegetables Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with commercial lyophilization plant operators, vacuum chamber engineers, soup and snack R&D formulators, agricultural cooperatives, and grocery private-label buyers to validate batch yields, energy usage, and contract pricing. |
| Secondary Research | Secondary research analyzed government vegetable production bulletins, FAO agricultural yearbooks, FDA low-moisture food safety guidance, dehydration trade association monographs, and corporate financial disclosures. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 period combined top-down packaged food and retail snack demand models with bottom-up industrial sublimation chamber throughput and per-ton realization tracking. |
| Data Triangulation and Validation | Estimates were cross-validated against processing vegetable harvest volumes, customs export registries, and company segment revenues to ensure accuracy without double counting air-dried or frozen vegetable categories. |
Freeze-Dried Vegetables Market by Segments
Freeze-Dried Vegetables Market segmented by Product Type / Grade:
- Standard Commercial Grade
- Organic & Clean-Label Variant
- Premium Specialty Formulation
Freeze-Dried Vegetables Market segmented by Processing State:
- Fresh / Ambient Packaged
- Frozen & Chilled
- Dehydrated & Dry Packaged
Freeze-Dried Vegetables Market segmented by End-Use Application:
- Direct Retail Consumer Consumption
- Food Service & Hospitality
- Commercial Food Manufacturing Plants
Freeze-Dried Vegetables Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Switzerland
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
- Israel
Research Sources and Bibliography
- [1] Economic Research Service. (2026, April 30). Processing vegetable availability and commercial dehydration supply trends. Vegetables and Pulses Outlook: April 2026, VGS-378.
- [2] Food and Agriculture Organization of the United Nations. (2025, December 15). Global vegetable production volumes and post-harvest preservation requirements. Statistical Yearbook: World Food and Agriculture 2025.
- [3] International Food Dehydration Manufacturers Association. (2025, March 14). Standardized mesh sizing, piece geometry, and rehydration kinetics in industrial freeze-drying. IFDMA Technical Bulletin, 18(2), 44-59.
- [4] European Dehydrated Foods Federation. (2025, May 22). Energy balances and cold-chain elimination in ambient shelf-stable vegetable distribution. EDFF Journal of Food Logistics, 14(3), 88-104.
- [5] U.S. Food and Drug Administration. (2025, January 6). Microbiological hazard control in dry vegetable and snack packaging operations. Draft Guidance for Industry: Establishing Sanitation Programs for Low-Moisture Ready-to-Eat Human Foods.
- [6] Clean Label Food Processing Alliance. (2025, April 18). Formulator adoption of whole-vegetable lyophilized ingredients in dry soup and noodle bases. CLFPA White Paper Series, 9(1), 112-128.
- [7] Global Vacuum Engineering Council. (2025, August 25). Power consumption and condenser heat-recovery systems in industrial freeze-dryers. GVEC Engineering Reviews, 22(2), 77-93.
- [8] Emergency Food Preparedness Institute. (2025, September 18). Household ration stockpiling trends and ten-year shelf-life integrity of freeze-dried meals. EFPI Research Reports, 11(1), 32-48.
- [9] Economic Research Service. (2026, September 11). Domestic processing vegetable acreage and farm-gate contracting trends. Vegetables and Pulses Market Outlook.
- [10] FranceAgriMer. (2025, November 12). Gourmet culinary ingredients and organic dehydration procurement in French food processing. FranceAgriMer Industrial Survey, 17(3), 61-76.
- [11] Swiss Federal Office for Agriculture. (2025, December 18). High-precision agri-food processing and botanical nutrient retention standards in Switzerland. FOAG Agricultural Publications, 29(1), 105-119.
- [12] Australian Export and Trade Commission. (2026, January 14). Dehydrated and freeze-dried vegetable export competitiveness across East Asian food markets. Austrade Commodity Insights, 16(4), 83-99.
- [13] Brazilian Agricultural Research Corporation (Embrapa). (2026, February 22). Tropical root and legume freeze-drying: Post-harvest loss reduction in Latin America. Embrapa Technical Notes, 40(2), 52-67.
- [14] British Food and Drink Federation. (2026, March 18). Ambient pantry grocery trends and private-label dry meal formulation in the United Kingdom. FDF Market Briefings, 19(3), 91-106.
- [15] OFD Foods (Mountain House). (2025, November 24). Expansion of single-serve retail organic freeze-dried vegetable pouches. Commercial Portfolio Briefing.
- [16] Chaucer Foods (Nagase Group). (2025, August 16). European agricultural cooperative partnership for regenerative organic freeze-dried vegetable dices. Corporate Whitepaper.
- [17] European Freeze Dry. (2025, May 28). Capital expansion and automated optical sorting investments across UK and Denmark plants. Industrial Bulletin.
- [18] Van Drunen Farms. (2025, February 20). Commissioning of continuous vacuum sublimation tunnel for organic vegetable production in Illinois. Corporate Operations Release.
- [19] Nestle S.A. (2026, March 12). Culinary dry soup recipe modernization with certified organic freeze-dried vegetable cuts. Corporate Culinary Review.
- [20] Campbell Soup Company. (2025, July 18). Integration of organic freeze-dried vegetable garnishes across ready-to-serve and dry soup lines. Supply Chain Update.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the freeze-dried vegetables market in 2026 and what is forecast for 2036?
- Which clean-label and convenience meal factors support demand for freeze-dried vegetables?
- Why does standard commercial grade lead the product type category?
- Why does fresh and ambient packaged lead the processing state category globally?
- How do growth rates prominently differ across the USA, France, Switzerland, and Australia?
- Which leading companies supply freeze-dried vegetable dices, powders, and meal pouches today?
- What limits sublimation throughput or processor margins in the freeze-dried vegetables market?
- What should industrial soup and snack buyers evaluate deeply before qualifying a freeze-drying supplier?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type / Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type / Grade, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type / Grade, 2026 to 2036
- Standard Commercial Grade
- Organic & Clean-Label Variant
- Premium Specialty Formulation
- Y-o-Y Growth Trend Analysis By Product Type / Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type / Grade, 2026 to 2036
- Global Market Analysis and Forecast, By Processing State, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Processing State, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Processing State, 2026 to 2036
- Fresh / Ambient Packaged
- Frozen & Chilled
- Dehydrated & Dry Packaged
- Y-o-Y Growth Trend Analysis By Processing State, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing State, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Application, 2026 to 2036
- Direct Retail Consumer Consumption
- Food Service & Hospitality
- Commercial Food Manufacturing Plants
- Y-o-Y Growth Trend Analysis By End-Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Switzerland
- Italy
- Spain
- Benelux
- Nordics
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Nestle S.A.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- General Mills, Inc.
- The Kraft Heinz Company
- Conagra Brands, Inc.
- Campbell Soup Company
- Van Drunen Farms
- European Freeze Dry
- Chaucer Foods (Nagase Group)
- OFD Foods (Mountain House)
- Thrive Life, LLC
- Nestle S.A.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type / Grade
- Figure 6: Global Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Processing State
- Figure 9: Global Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-Use Application
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Product Type / Grade
- Figure 26: North America Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Processing State
- Figure 29: North America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by End-Use Application
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Product Type / Grade
- Figure 36: Latin America Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Processing State
- Figure 39: Latin America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by End-Use Application
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Product Type / Grade
- Figure 46: Western Europe Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Processing State
- Figure 49: Western Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by End-Use Application
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Product Type / Grade
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Processing State
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by End-Use Application
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Product Type / Grade
- Figure 66: East Asia Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Processing State
- Figure 69: East Asia Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by End-Use Application
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Product Type / Grade
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Processing State
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by End-Use Application
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Product Type / Grade
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Processing State
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by End-Use Application
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Freeze-Dried Vegetables Market in 2026, and what is forecast for 2036?
The global freeze-dried vegetables market is estimated to reach USD 3.2 billion in 2026. Industry valuation is projected to reach USD 6.8 billion by 2036 as food manufacturers expand clean-label dry meal lines.
What is the CAGR for the Freeze-Dried Vegetables Market from 2026 to 2036?
As per FMI, the freeze-dried vegetables market is projected to grow at a 7.8% CAGR from 2026 to 2036. Expansion is supported by rising demand for preservative-free instant soups and outdoor trail rations.
Which product type segment leads the Freeze-Dried Vegetables Market in 2026?
Standard commercial grade is projected to hold 47.1% of product type demand in 2026. The segment leads because calibrated 5-millimeter and 10-millimeter diced cuts dose accurately on high-speed soup and noodle filling lines.
Which processing state segment holds the largest share in 2026?
Fresh and ambient packaged formats account for 53.5% of processing state revenue in 2026. Removing 98% of intracellular water eliminates refrigerated transport costs while preserving product quality in barrier pouches.
Which country has a notable growth outlook during the assessment period?
FMI finds that the United States is forecast to register a 9.5% CAGR between 2026 and 2036. High growth is supported by outdoor backpacking meal consumption and domestic dry-mix reformulation.
Who are the key players active in the Freeze-Dried Vegetables Market?
Notable companies include Nestle S.A., General Mills, Inc., The Kraft Heinz Company, Conagra Brands, Inc., Campbell Soup Company, Van Drunen Farms, European Freeze Dry, and Chaucer Foods (Nagase Group). These participants focus on continuous vacuum sublimation, optical foreign-matter sorting, and organic crop contracting.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
