

- Market Size (2026)
- USD 948.7 Mn
- Forecast (2036)
- USD 1723.6 Mn
- CAGR (2026 to 2036)
- 6.2%
How big is Beta Glucan Market in 2026?
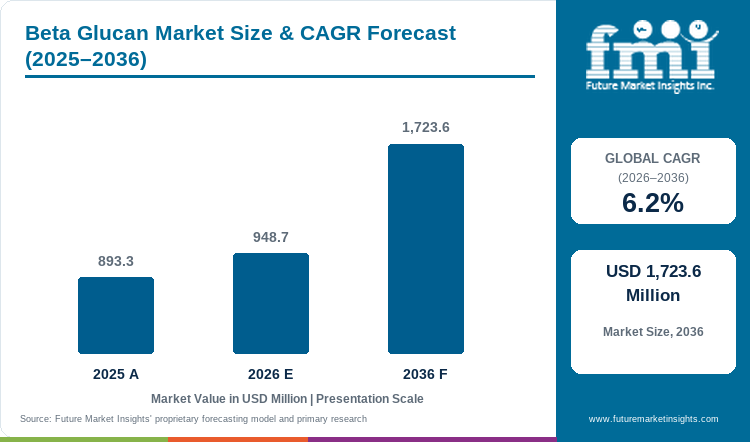
USD 948.7 million in 2026 and USD 1 723.6 million by 2036, expanding at 6.2% CAGR.
Sales in the beta glucan market are projected to grow at 6.2% CAGR through 2036, climbing from USD 893.3 million in 2025 to USD 948.7 million in 2026 before driving valuation to USD 1723.6 million by 2036. Food and supplement formulators are specifying beta glucan by source because molecular structure changes physiological positioning and processing behavior. FDA rules maintain a heart-health pathway for qualifying oat and barley soluble fiber products. Cereal beta glucan therefore enters formulation with a measurable dose and claim condition instead of a generic fiber specification.
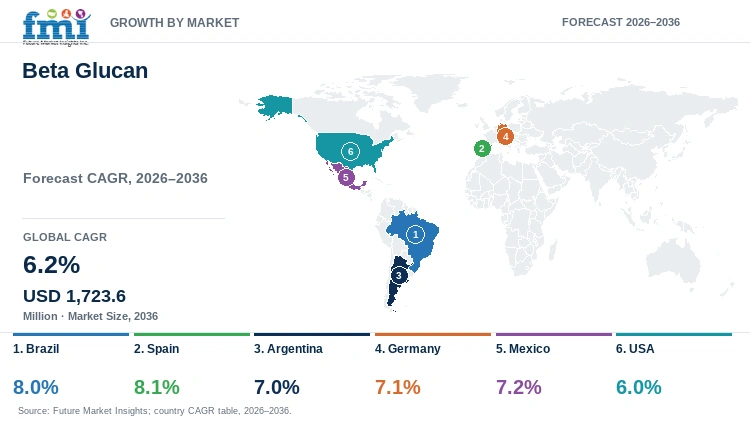
Country growth diverges because national notification and claim systems add different commercialization steps to technically similar ingredients. Spain is projected at 8.1% CAGR through 2036, while Brazil is projected at 8.0% for the defined beta glucan market. Argentina, Germany and Mexico are projected at 7.0%, 7.1% and 7.2%, respectively. Filing requirements and claim screening change how quickly source-qualified beta glucan moves from formulation into commercial launch.
Key Takeaways of Beta Glucan Market
- Cardiovascular and metabolic claims are sustaining cereal beta glucan demand while immune-health positioning supports source-defined yeast and algae ingredients.
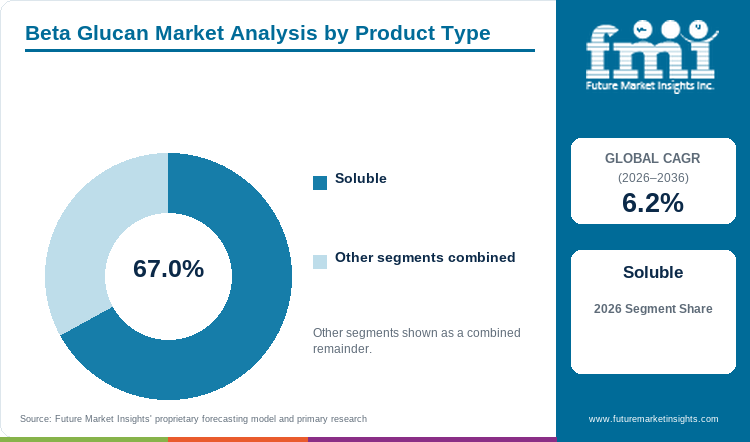
- By product type, soluble beta glucan is estimated to hold 67.0% in 2026. Hydration and viscosity support its established role in cereal-fiber formulations and recognized health-claim routes.
- In 2026, nutraceutical - dietary supplements are expected to lead end user application with 32.0% share. Defined-dose formats give formulators tighter control over active levels during commercial formulation and launch planning.
- Yeast beta glucan is projected to hold 32.0% of source demand in 2026. Its beta-1,3/1,6 structure supports differentiated immune-health formulations that require source-specific substantiation before commercial use.
- Molecular-weight loss, incomplete dispersion and jurisdiction-specific claim rules delay qualification even when beta glucan assay content meets the purchase specification.
- Some of the key players in this market include Kemin Industries Inc., Kerry Group plc, Angel Yeast Co., Ltd., Givaudan SA, Lantmännen Biorefineries, Biorigin, part of Phileo by Lesaffre, COSCIENS Biopharma Inc. (Ceapro Inc.), and Leiber GmbH.
Analyst Perspective
"Commercial beta glucan decisions start with source identity because structure determines both claim options and formulation behavior. Suppliers that document dose retention during processing can shorten qualification without asking formulators to accept weaker sensory performance."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Beta Glucan Market segmented?
The beta glucan market is segmented by Product Type, End User Application, Source, Form, and Region.
Product type covers soluble and insoluble grades while form separates powder and liquid supply for commercial processing. End user application includes nutraceutical - dietary supplements, bakery - breakfast cereals - bars, beverages, confectionery, baby food - infant nutrition, plant-based meat - meat alternatives, milk alternatives - functional foods and beverages, dairy products, pharmaceuticals, animal feed, pet food and others. Source covers yeast, barley, oats, mushroom, algae and other commercial origins used in beta glucan production.
How does soluble beta glucan shape product type selection?
Soluble beta glucan is selected when formulators need viscosity and fermentable dietary fiber behavior alongside a defined physiological route. Molecular weight and solubilization remain qualification variables because processing can preserve total assay content while changing the functional response expected from cereal beta glucan.
- By product type, soluble beta glucan is estimated to hold 67.0% in 2026. Water-dispersible functionality and recognized cereal-health mechanisms support its position in formulated foods and supplements.
- Qualification centers on molecular weight, dissolution behavior and dose retention in the finished product because those properties influence final performance.
What supports nutraceutical - dietary supplements within end user application?
Measured-dose dietary supplements let formulators control beta glucan intake without forcing the complete active level into a conventional food serving. Powder, capsule and tablet formats simplify combinations with other actives, but ingredient identity and claim wording still require source-specific review before commercial launch.
- In 2026, nutraceutical - dietary supplements are expected to lead end user application with 32.0% share. Measured formats give manufacturers repeatable dosing and clearer control over active levels in commercial formulations.
- Manufacturers reduce reformulation work when ingredient identity and recommended dose are documented before flavor systems and excipients are locked.
Why does yeast hold a central position within the source category?
Commercial yeast beta glucan uses a beta-1,3/1,6 architecture that supports immune-health positioning distinct from cereal fiber claims. Kerry and other yeast specialists document applications in supplements, foods and beverages, so qualification centers on branching structure, purity and source-specific substantiation.
- Yeast beta glucan is projected to hold 32.0% of source demand in 2026. Differentiated beta-1,3/1,6 structures support immune-health applications that require source-specific technical evidence.
- Commercial selection depends on documented purity and source-specific evidence because physiological claims cannot be transferred automatically between cereal and yeast structures.
What makes powder the preferred form for commercial beta glucan?
Powder formats support dry blending, lower transport weight and controlled dosing before the ingredient enters final processing. Concentrated oat beta-glucan powders also let food and supplement manufacturers standardize active content, while liquid formats remain useful when post-blending convenience outweighs shipping and solids-management constraints.
- Powder is set to lead the form category with 65.0% share in 2026. Standardized dry formats support commercial blending and defined-dose manufacturing with controlled active-content specifications for repeat production.
- Liquid formats remain relevant for selected beverage workflows, but dry supply reduces transport weight and gives processors more control over final solids.
What are the drivers, restraints and opportunities in the Beta Glucan Market?
Claim-supported nutrition expands beta glucan use, processing sensitivity raises qualification work and better-dispersing validated grades open additional formulation routes.
- Driver: Authorized health-claim pathways give formulators defined reasons to specify source-qualified beta glucan instead of generic fiber.
- Restraint: Processing can lower molecular weight or solubility and weaken the performance expected from an otherwise compliant ingredient.
- Opportunity: Better-dispersing grades can extend beta glucan into beverages and compact nutrition formats without forcing unacceptable texture or serving size.
Health-claim pathways turn ingredient identity into a measurable formulation requirement
Food manufacturers use authorized claim conditions to set source, dose and serving design before commercial scale-up. FDA and EU frameworks define accepted cereal beta-glucan routes, giving functional food ingredients a clear qualification basis. Suppliers shorten review when assay data and processing guidance show that the finished product still meets the intended claim conditions.
Processing sensitivity can preserve assay content while weakening the intended physiological performance
Molecular weight and solubilization can fall during extraction or thermal processing even when total beta glucan remains measurable. The risk affects nutraceutical ingredients because a conforming assay does not guarantee the same physiological response in the finished formulation. Buyers therefore require processing data that links the supplied grade with the final formulation and dose.
Dispersibility and validated new sources can broaden the formats that carry a meaningful beta glucan dose
Beverage developers need enough active beta glucan to meet a nutritional proposition without excessive viscosity, settling or flavor disruption. Better-dispersing grades can extend functional beverages into daily-use formats while preserving practical serving size. Suppliers gain access when they document active-content stability and sensory performance at the actual serving dose.
Which country CAGRs are included in the Beta Glucan Market?
| Country | CAGR |
|---|---|
| Brazil | 8.0% |
| Spain | 8.1% |
| Argentina | 7.0% |
| Germany | 7.1% |
| Mexico | 7.2% |
| USA | 6.0% |
How do country-level CAGRs compare in the Beta Glucan Market?
The forecasts range from 6.0% to 8.1%. Spain carries the upper displayed rate at 8.1%, followed by Brazil at 8.0%, while Argentina, Germany and Mexico carry distinct 7.0%, 7.1% and 7.2% rates. The rates describe forecast speed instead of present market size because national commercialization requirements differ.
- Brazil: National supplement notification makes dossier completeness and claim-ready labeling central to beta glucan commercial launches.
- Spain: EU claim eligibility and mandatory supplement communication require both ingredient compliance and national filing readiness.
- Argentina: Updated food rules expand recognized functional ingredients while preserving authorization controls for health-related supplement claims.
- Germany: First-marketing notification does not certify marketability, so finished supplements still require separate legal compliance review.
- Mexico: National rules permit defined-dose supplement formats while excluding therapeutic claims from ordinary food-supplement commercialization.
- USA: FDA cereal-fiber claim rules tie source identity and serving composition directly to qualifying beta glucan foods.
Comparable CAGRs can produce different commercial conditions because ingredient qualification and legal claim routes remain separate decisions. The full report provides country-level CAGR analysis across North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa.
Country-wise Analysis
- Brazilian supplement manufacturers work within ANVISA notification rules that require finished products to be regularized before routine commercialization. By 2036, Brazil is projected to grow at 8.0% CAGR within the defined national beta glucan market. Formal notification routes for supplements and permitted functional claims support the national commercialization path. Suppliers that prepare composition and claim files early can reduce rework during national review.
- Spanish food-supplement launches require a national communication step even when beta glucan claims follow the common European framework. Spain's beta glucan outlook is anticipated to advance at 8.1% CAGR over the assessment period. The combined EU and domestic compliance route shapes commercial preparation for finished supplement launches in Spain. Ingredient suppliers can shorten customer preparation by providing source identity and label-ready claim conditions before national communication.
- Argentina is widening the functional-ingredient options available to supplement formulators under its national food code. Beta glucan demand in Argentina is forecast to rise at 7.0% CAGR over the forecast period. Rules covering health-property declarations and dried Euglena gracilis shape the local commercial formulation route for supplements. Suppliers need documented identity and permitted-use conditions before non-cereal beta glucan enters repeat commercial work.
- German supplement companies combine European claim rules with a national notification procedure at first marketing. Adoption of beta glucan in Germany is estimated to expand at 7.1% CAGR through 2036. The filing process constrains finished-supplement commercialization because notification does not itself certify legal marketability. Suppliers reduce launch friction when source and claim documentation are resolved before customers submit the final German label.
- Mexican food-supplement rules recognize powders and tablets as defined oral formats while excluding therapeutic positioning from the ordinary supplement route. The Mexico beta glucan sector is projected to record 7.2% CAGR during the assessment period. A defined national import and supplement process governs compliant commercial entry for finished products. COFEPRIS received 3,617 import-permit applications for supplements during 2023 under that authorization system.
- US formulators can use a defined FDA pathway for soluble fiber from qualifying oat and barley foods. In the USA, beta glucan demand is predicted to advance at 6.0% CAGR through 2036. Claim conditions tie source identity and serving composition to finished-food product qualification in the national market. Suppliers of prebiotic ingredients retain repeat business when processing data confirms that active fiber remains within the finished-food specification.
Who are the notable companies in the Beta Glucan Market?
Kemin Industries Inc., Kerry Group plc, Angel Yeast Co., Ltd., Givaudan SA, Lantmännen Biorefineries, Biorigin, part of Phileo by Lesaffre, COSCIENS Biopharma Inc. (Ceapro Inc.), and Leiber GmbH are active within the defined beta glucan supply boundary.
Competition separates cereal processors, yeast specialists and functional-ingredient groups supplying standardized beta glucan for nutrition applications. Entry depends on source control and reproducible active content that customers can verify during qualification. Corporate scale carries less value when a supplier cannot connect ingredient specifications with the intended dose and processing route.
- Kemin Industries and Givaudan focus on specialized human-nutrition ingredients, while Lantmännen Biorefineries supplies oat-derived material for food and supplement formulation.
- Kerry Group and Leiber document yeast beta glucan for immune-health applications, and Angel Yeast extends yeast-derived solutions into both human nutrition and animal feed additives.
- Biorigin supplies MacroGard for animal and pet nutrition, while COSCIENS Biopharma retains Ceapro oat beta glucan and related active-ingredient technology relevant to pet food ingredients and personal-care formulations.
Competitive Benchmarking: Beta Glucan Market
| Company | Beta Glucan Source Breadth | Application Breadth | Quality or Evidence Depth | Geographic Reach |
|---|---|---|---|---|
| Kemin Industries Inc. | Low | High | High | Global |
| Kerry Group plc | Low | High | High | Global |
| Angel Yeast Co., Ltd. | Low | High | High | Global |
| Givaudan SA | Low | High | High | Global |
| Lantmännen Biorefineries | Low | Medium | High | Europe with international ingredient sales |
| Biorigin, part of Phileo by Lesaffre | Low | High | High | Global animal-nutrition reach |
| COSCIENS Biopharma Inc. (Ceapro Inc.) | High | Medium | High | North America with international distribution |
| Leiber GmbH | Low | High | High | Europe with international ingredient sales |
Scoring basis: High source breadth requires evidence for at least two documented beta glucan sources in commercial supply. Medium requires one source plus a second documented route and Low requires one verified commercial source. High application breadth requires evidence covering at least three distinct commercial application classes for the named company. Quality or evidence depth requires regulatory status or recognized clinical substantiation for the supplied beta glucan platform. Geographic reach describes documented operating regions and is not scored against the three capability criteria.
Key Developments in the Beta Glucan Market
- In July 2026, Biorigin announced that it had become part of Phileo by Lesaffre and brought MacroGard activity into a larger animal-health organization.
- In April 2026, Lantmännen published its base prospectus confirming ongoing beta-glucan processing at the Kimstad oat biorefinery and continued commercial production.
- In March 2026, COSCIENS Biopharma filed its annual report identifying Ceapro beta glucan within its continuing natural active-ingredient business and development portfolio.
Key Players in the Beta Glucan Market
Human nutrition and functional-food ingredient companies
- Kemin Industries Inc.
- Kerry Group plc
- Givaudan SA
- Lantmännen Biorefineries
Yeast and animal-nutrition beta glucan specialists
- Angel Yeast Co., Ltd.
- Biorigin, part of Phileo by Lesaffre
- Leiber GmbH
Oat active-ingredient technology
- COSCIENS Biopharma Inc. (Ceapro Inc.)
Beta Glucan Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By product type, end user application, source, form and region. |
| Quantitative Units | Revenue in USD million and CAGR in %. |
| Market Definition | Commercial beta glucan ingredients sold as cereal, yeast, algae, mushroom or other source-defined materials for food, supplement, pharmaceutical, animal-nutrition and personal-care applications are included. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | Brazil, Spain, Argentina, Germany, Mexico, USA, and 20+ countries included in the full report. |
| Key Companies Profiled | Kemin Industries Inc., Kerry Group plc, Angel Yeast Co., Ltd., Givaudan SA, Lantmännen Biorefineries, Biorigin, part of Phileo by Lesaffre, COSCIENS Biopharma Inc. (Ceapro Inc.), Leiber GmbH. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Beta Glucan Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Beta Glucan Market by Segments
Beta Glucan Market segmented by Product Type:
- Soluble
- Insoluble
Beta Glucan Market segmented by End User Application:
- Nutraceutical - Dietary Supplements
- Bakery - Breakfast Cereals - Bars
- Beverage
- Confectionery
- Baby Food - Infant Nutrition
- Plant-based Meat - Meat Alternatives
- Milk Alternatives - Functional Foods and Beverages
- Others
- Dairy Products
- Pharmaceutical
- Animal Feed
- Pet Food
Beta Glucan Market segmented by Source:
- Yeast
- Barley
- Others
- Oats
- Mushroom
- Algae
Beta Glucan Market segmented by Form:
- Powder
- Liquid
Beta Glucan Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- Middle East and Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
Research Sources and Bibliography
- U.S. Food and Drug Administration. (2024). Questions and Answers on Dietary Fiber.
- European Commission. (n.d.). Nutrition and Health Claims - EU register of health claims.
- Health Canada. (2010). Oat Products and Blood Cholesterol Lowering.
- Agência Nacional de Vigilância Sanitária. (2024, September 2). Fique atento! Novas regras para regularização de alimentos entram em vigor.
- Agencia Española de Seguridad Alimentaria y Nutrición. (n.d.). Complementos alimenticios.
- Administración Nacional de Medicamentos, Alimentos y Tecnología Médica & Secretaría de Agricultura, Ganadería y Pesca. (2025, November 3). Resolución Conjunta 3/2025: Código Alimentario Argentino.
- Bundesamt für Verbraucherschutz und Lebensmittelsicherheit. (n.d.). Anzeigeformular § 5 NemV (Nahrungsergänzungsmittel-Verordnung).
- Comisión Federal para la Protección contra Riesgos Sanitarios. (2024, February 1). Se ha atendido 100% de permisos de importación para suplementos alimenticios.
- Ministère de l’Agriculture, de l’Agro-alimentaire et de la Souveraineté alimentaire. (2026, January 21). Qu'est ce qu'un complément alimentaire ?
- Ministero della Salute. (2025, March 26). Nuova notifica di integratore alimentare.
- Department of Health and Social Care. (2020, December 31; updated 2026, May 19). Great Britain nutrition and health claims (NHC) register.
- Biorigin. (2026, July 13). Biorigin is now part of Phileo by Lesaffre.
- Angel Yeast Co., Ltd. (2026, April 22). Angel Yeast Highlights Yeast-Based Bio-Feed Advantages at VIV Select India 2026.
- Kemin Industries. (2024, January 2; updated 2026, February 10). Unlocking the Power of Beta Glucans for Immune Support [BetaVia™ product blog]
- Kerry Group plc. (2026, March 12). Immune Health: The Flavours, Formats and Functional Science Shaping the Next Wave of Wellness.
- COSCIENS Biopharma Inc. (2026, March 25). Form 6-K: Fourth Quarter and Full Year 2025 Financial Results and Corporate Update (covering Ceapro beta glucan active ingredients). Filed with the U.S. Securities and Exchange Commission.
- Lantmännen. (2026, April 17). Base Prospectus: Lantmännen Biorefineries operations and oat beta-glucan processing.
- Givaudan. (2026, January 29). 2025 Integrated Report on economic and ESG performance.
- Leiber GmbH. (2026, August 31). Completion of the Agsira S.R.L. production-site acquisition in Romania.
- Biorigin. (2026). MacroGard: Purified yeast beta-1,3/1,6-glucans.
- Garuda International. (2026). B-CAN soluble oat fiber application and quality specifications.
- Ceapro Inc. (2026). CP Oat Beta Glucan technical documentation.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations
This Report Answers
- How large is the beta glucan market from 2026 through 2036?
- Which source and formulation conditions determine commercial beta glucan qualification decisions?
- Which product type holds the largest parent-category share during the 2026 base year?
- Which end user application holds the largest parent-category share during the 2026 base year?
- Why does yeast beta glucan require separate substantiation from established cereal health claims?
- Which processing conditions can weaken beta glucan performance during commercial food formulation and manufacturing?
- How do national supplement rules change commercialization timing among the countries included in this analysis?
- Which companies supply source-defined beta glucan ingredients for current commercial nutrition applications?
Frequently Asked Questions
How big is the Beta Glucan Market in 2026?
The beta glucan market is valued at USD 948.7 million in 2026 and is projected to reach USD 1723.6 million by 2036. Source-defined health positioning and process stability support repeat qualification in commercial foods, beverages and dietary supplements.
What is the CAGR of the Beta Glucan Market from 2026 to 2036?
The beta glucan market is projected to grow at 6.2% CAGR between 2026 and 2036. Formulators are qualifying source identity and process-stable functionality before approving ingredients for recurring commercial production programs.
Which product type leads the Beta Glucan Market in 2026?
The soluble segment is estimated to hold 67.0% of product type demand in the beta glucan market in 2026. Its hydration and viscosity support cereal-health functions that manufacturers need to preserve during commercial processing.
Which end user application leads the Beta Glucan Market in 2026?
The nutraceutical - dietary supplements segment is projected to hold 32.0% of end user application demand in the beta glucan market in 2026. Defined-dose formats simplify intake control and source-specific substantiation before commercial formulation and launch decisions.
Which companies are active in the Beta Glucan Market?
Key companies operating in the beta glucan market include Kemin Industries, Kerry Group, Angel Yeast, Givaudan, Lantmännen Biorefineries, Biorigin, COSCIENS Biopharma and Leiber. These companies compete on source control, substantiation and application support used during technical qualification.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Soluble
- Insoluble
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By End User Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End User Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End User Application, 2026 to 2036
- Nutraceutical - Dietary Supplements
- Bakery - Breakfast Cereals - Bars
- Beverage
- Confectionery
- Baby Food - Infant Nutrition
- Plant-based Meat - Meat Alternatives
- Milk Alternatives - Functional Foods and Beverages
- Others
- Dairy Products
- Pharmaceutical
- Animal Feed
- Pet Food
- Y-o-Y Growth Trend Analysis By End User Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End User Application, 2026 to 2036
- Global Market Analysis and Forecast, By Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Source, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Source, 2026 to 2036
- Yeast
- Barley
- Others
- Oats
- Mushroom
- Algae
- Y-o-Y Growth Trend Analysis By Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Source, 2026 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Form, 2026 to 2036
- Powder
- Liquid
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By End User Application
- By Source
- By Form
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End User Application
- By Source
- By Form
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By End User Application
- By Source
- By Form
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End User Application
- By Source
- By Form
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- By Product Type
- By End User Application
- By Source
- By Form
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End User Application
- By Source
- By Form
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- By Product Type
- By End User Application
- By Source
- By Form
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End User Application
- By Source
- By Form
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By End User Application
- By Source
- By Form
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End User Application
- By Source
- By Form
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- By Product Type
- By End User Application
- By Source
- By Form
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End User Application
- By Source
- By Form
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
- By Product Type
- By End User Application
- By Source
- By Form
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End User Application
- By Source
- By Form
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User Application
- By Source
- By Form
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User Application
- By Source
- By Form
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User Application
- By Source
- By Form
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User Application
- By Source
- By Form
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User Application
- By Source
- By Form
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User Application
- By Source
- By Form
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User Application
- By Source
- By Form
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User Application
- By Source
- By Form
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User Application
- By Source
- By Form
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User Application
- By Source
- By Form
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User Application
- By Source
- By Form
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User Application
- By Source
- By Form
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User Application
- By Source
- By Form
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User Application
- By Source
- By Form
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User Application
- By Source
- By Form
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User Application
- By Source
- By Form
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User Application
- By Source
- By Form
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User Application
- By Source
- By Form
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User Application
- By Source
- By Form
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User Application
- By Source
- By Form
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User Application
- By Source
- By Form
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User Application
- By Source
- By Form
- Argentina
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User Application
- By Source
- By Form
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By End User Application
- By Source
- By Form
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Kemin Industries Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Kerry Group plc
- Angel Yeast Co., Ltd.
- Givaudan SA
- Lantmännen Biorefineries
- Biorigin, part of Phileo by Lesaffre
- COSCIENS Biopharma Inc. (Ceapro Inc.)
- Leiber GmbH
- Kemin Industries Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


