
- Market Size (2026)
- USD 10.1 Bn
- Forecast (2036)
- USD 18.0 Bn
- CAGR (2026 to 2036)
- 6.0%
How big is Ceiling Tiles Market in 2026?
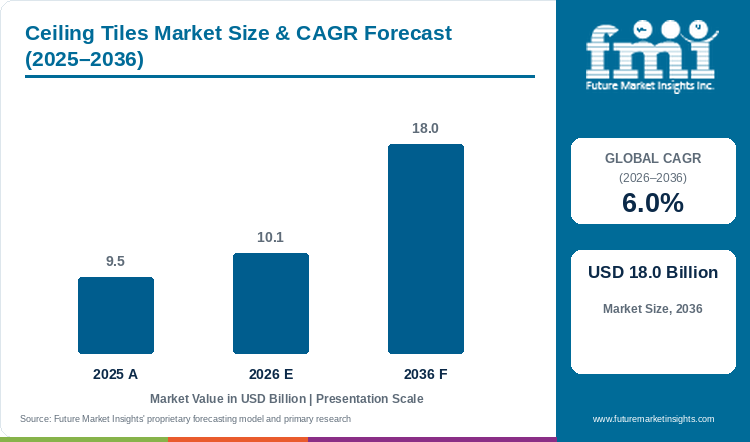
Ceiling tiles market size stood at USD 9.5 billion in 2025, reaches USD 10.1 billion in 2026 and is projected at USD 18.0 billion by 2036. Demand for ceiling tiles is set to expand at a 6% CAGR from 2026 to 2036, as commercial builders and renovation contractors replace ageing suspended grids with certified tiles.
Sales of ceiling tiles are tracking a wider rebound in commercial fit-out activity. Armstrong World Industries reported second-quarter 2025 sales of USD 424.6 million, up 16.3% from a year earlier, with Architectural Specialties ceiling and wall sales up 37.2%. Due to this, suppliers are funding capacity for higher-grade acoustic and specialty tiles, and plants serving acoustic ceiling tiles demand keep adding certified product lines. U.S. private nonresidential construction stood at USD 746.0 billion in April 2025, a seasonally adjusted annual rate, after easing 0.5% from the revised March estimate. FMI puts mineral fiber tiles in the lead with a 42% product share in 2026, as fire-rated and acoustic-rated boards remain the default choice for office and institutional ceilings. Green-building compliance is adding a second growth channel on top of base construction demand.
The recast EU Energy Performance of Buildings Directive, published in the Official Journal on 8 May 2024, sets minimum energy performance standards that require renovation of the worst-performing non-residential buildings, with national renovation plans due under a two-year transposition window. Due to this, European renovation contractors are specifying sustainability-compliant ceiling systems ahead of national transposition deadlines running through 2026. In the UK, the Building Safety Act 2022, which received royal assent on 28 April 2022, created a National Regulator for Construction Products and tightened fire-safety record-keeping for higher-risk buildings. Apart from that, South Korea's SK hynix approved a USD 38.3 billion investment in two new memory fabs in August 2026, with construction on the Yongin Y2 facility due to start in July 2027. Cleanroom floors in fabs of this kind rely on fan-filter grid systems rather than standard ceiling tiles, but the office and administrative space built alongside each fab campus is expected to add incremental orders for certified ceiling tiles through 2036.
Key Market Trends & Insights
- By product, mineral fiber tiles lead with 42% of 2026 sales, as fire rating and acoustic performance remain the baseline specification for commercial ceilings.
- By installation, suspended systems take 63% of 2026 sales. Armstrong World Industries' core ceiling systems business serves this suspended-systems segment; its separate Architectural Specialties division, which covers mainly metal and wood ceiling and wall products rather than suspended mineral-fibre grids, grew net sales 37.2% in the second quarter of 2025.
- By end use, commercial buildings hold 54% of 2026 sales, owing to office, healthcare and institutional fit-outs that specify certified acoustic and fire-rated tiles.
- By sales channel, direct sales account for 49% of 2026 sales, and long-run commercial contracts will keep direct sales as the main channel through 2036. U.S. private nonresidential construction was valued at USD 746.0 billion in April 2025.
- By application, acoustic control leads with an estimated 44% of 2026 sales, as open-plan offices and healthcare facilities specify sound-rated tiles ahead of thermal or aesthetic grades.
Regional Highlights
- Among the profiled countries, USA posts the quickest pace at 5.7% CAGR over 2026 to 2036.
- Germany (5.6%) and South Korea (5.6%) rank just behind, with Japan closing the profiled set at 5.3% through 2036.
- South Korean fab construction is adding office-support ceiling tile demand, as SK hynix approved a USD 38.3 billion investment in two new memory fabs in August 2026; the cleanroom floors themselves use fan-filter grid systems rather than ceiling tiles.
Market Size & Forecast
Table 1: Market Size and Forecast for the Ceiling Tiles Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 9.5 billion |
| Estimated Market Size in 2026 | USD 10.1 billion |
| Projected Market Size by 2036 | USD 18.0 billion |
| CAGR, 2026 to 2036 | 6% |
| Added Sales, 2026 to 2036 | USD 8.0 billion |
| Market Expansion Multiple | 1.8x |
Most ceiling tile orders now come from commercial builders and renovation contractors upgrading older suspended grids. Certified fire rating and acoustic performance are the main reasons buyers approve a purchase. U.S. private nonresidential construction eased 0.5% to USD 746.0 billion in April 2025, a seasonally adjusted annual rate. At the top end, acoustic ceiling tiles brands still gain specification approvals on sound-rated boards, which keeps premium mineral fiber tiles on order books. High-grade specialty tiles and long project approval cycles can still delay orders at smaller contractors. Replacement of older suspended grids and growth in certified commercial fit-outs is anticipated to drive most orders through 2036.
Green-Building Compliance and Construction Cycle Readiness
Sales of ceiling tiles are rising as commercial construction activity stabilizes after a soft start to 2025. U.S. private nonresidential construction eased 0.5% to USD 746.0 billion in April 2025. Armstrong World Industries reported second-quarter 2025 sales of USD 424.6 million, up 16.3% year over year, with Architectural Specialties operating income up 80.3% to USD 25.6 million. FMI expects certified acoustic and fire-rated tiles to take most new orders in the early forecast years, as building owners specify compliant products ahead of renovation deadlines. South Korea's growth is tied more to fab investment than to general commercial construction. SK hynix approved a USD 38.3 billion investment covering a 279-acre DRAM and HBM facility at the Yongin Semiconductor Cluster (Y2 fab, construction from July 2027) and a NAND flash facility at Cheongju (M17 fab), with the first Yongin cleanroom due to open in June 2029. The cleanrooms themselves use fan-filter grid systems rather than ceiling tiles, but office and support space built alongside campuses of this scale is expected to add incremental suspended-ceiling demand within the forecast.
Regulation is giving commercial builders a second reason to specify certified ceiling systems. The recast EU Energy Performance of Buildings Directive, published on 8 May 2024, sets minimum energy performance standards for the worst-performing non-residential buildings and requires national renovation plans under a two-year transposition window. Due to this, European renovation contractors are specifying sustainability-compliant tiles and grid systems ahead of national transposition deadlines. In the UK, the Building Safety Act 2022, in force since royal assent on 28 April 2022, created a National Regulator for Construction Products and tightened fire-safety documentation duties for higher-risk buildings. Apart from that, Armstrong World Industries' Architectural Specialties division grew net sales 37.2% in the second quarter of 2025, with roughly USD 28 million of that growth tied to the 2024 acquisitions of 3form and Zahner. Builders of certified, sustainability-compliant ceiling systems stand to gain from both renovation mandates and new commercial construction through 2036.
Table 2: Construction Cycle and Compliance Indicators for the Ceiling Tiles Market (percentage changes, units, USD values), mixed reporting years from 2022 to 2026
| Indicator | Data Point | Market Relevance | Source |
|---|---|---|---|
| Armstrong World Industries Q2 2025 results | Sales USD 424.6 million, up 16.3% | Commercial ceiling demand is tracking a construction recovery. | |
| Armstrong Architectural Specialties, Q2 2025 | Net sales up 37.2%; operating income up 80.3% | Certified acoustic and specialty tiles are gaining share. | |
| U.S. nonresidential construction, April 2025 | USD 746.0 billion, down 0.5% from March | Commercial construction activity sets the pace of new ceiling orders. | |
| EU EPBD recast | Published 8 May 2024; two-year transposition window | Renovation mandates will shape future ceiling specification. | |
| SK hynix fab investment | USD 38.3 billion; construction from July 2027 | Cleanrooms use fan-filter grids, not ceiling tiles; office-support space in new fab campuses adds modest ceiling tile demand. | — |
| UK Building Safety Act 2022 | Royal assent 28 April 2022 | Fire-safety documentation duties favour certified ceiling systems. | — |
Table 3: Commercial Construction and Fab Investment Benchmarks for the Ceiling Tiles Market (mixed units and currencies), mixed reporting years from 2024 to 2026
| Indicator | Reported value | Related figure | |
|---|---|---|---|
| Ceiling tiles market, 2025 to 2026 | USD 9.5 billion to USD 10.1 billion | 6% CAGR, 2026 to 2036 | |
| Armstrong World Industries Q2 2025 | Sales USD 424.6 million | Up 16.3% year over year | |
| Armstrong Architectural Specialties, Q2 2025 | Net sales up 37.2% | Operating income up 80.3% to USD 25.6 million | |
| U.S. nonresidential construction, April 2025 | USD 746.0 billion | Down 0.5% from revised March estimate | |
| EU EPBD recast | Published 8 May 2024 | Two-year transposition window | |
| SK hynix fab investment | USD 38.3 billion | 279-acre Yongin DRAM facility | |
| UK Building Safety Act 2022 | Royal assent 28 April 2022 | National Regulator for Construction Products created |
Analyst Perspective
“Building owners will favour ceiling systems that pair certified fire and acoustic ratings with faster installation on renovation projects. Suppliers offering sustainability-compliant tiles and strong grid-system service will take most replacement orders through 2036.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the Ceiling Tiles Market segmented?
The ceiling tiles market is studied across five commercial segments plus region, namely product, installation, end use, sales channel and application.
By product: mineral fiber tiles, metal tiles, wood tiles, gypsum tiles, and others.
By installation: suspended ceilings and surface-mounted ceilings.
By end use: commercial, residential, and industrial.
By sales channel: direct sales, distributors, and online sales.
By application: acoustic control, thermal insulation, and aesthetic enhancement.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do mineral fiber tiles lead product sales?
Mineral fiber tiles will hold 42% of product sales in 2026, as fire rating and acoustic performance remain the baseline commercial specification.
Table 4: Product Share for the Ceiling Tiles Market (percentage share), 2026
| Product | Share (2026) |
|---|---|
| Mineral Fiber Tiles | 42% |
| Other Segments Combined | 58% |
| Total | 100% |
Table 5: Product Leadership and Market Growth for the Ceiling Tiles Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6% |
| Leading Segment | Mineral Fiber Tiles |
Demand for mineral fiber ceiling tiles leads any commercial fit-out, as fire rating and acoustic performance remain the baseline specification. FMI finds that mineral fiber accounts for 42% of product sales in 2026. Metal and wood tiles serve design-led fit-outs, and gypsum tiles serve a smaller group of budget projects. Armstrong World Industries' Architectural Specialties division, aided by the 2024 acquisitions of 3form and Zahner, grew net sales 37.2% in the second quarter of 2025, though that division covers mainly metal and wood ceiling and wall products rather than mineral fiber; the mineral fiber share instead rests on its continued role as the default fire-rated, acoustic specification for office and institutional ceilings. Fire-rated, acoustic mineral fiber tiles with shorter lead times are anticipated to keep this segment ahead through 2036.
- Mineral fiber tiles hold 42% of product sales in 2026, since fire rating and acoustic performance remain the default specification for commercial ceilings.
- Buyers comparing mineral fiber tiles should check fire rating, sound absorption and lead time, as these factors set approval speed on commercial projects.
Why does suspended installation dominate the ceiling tiles market?
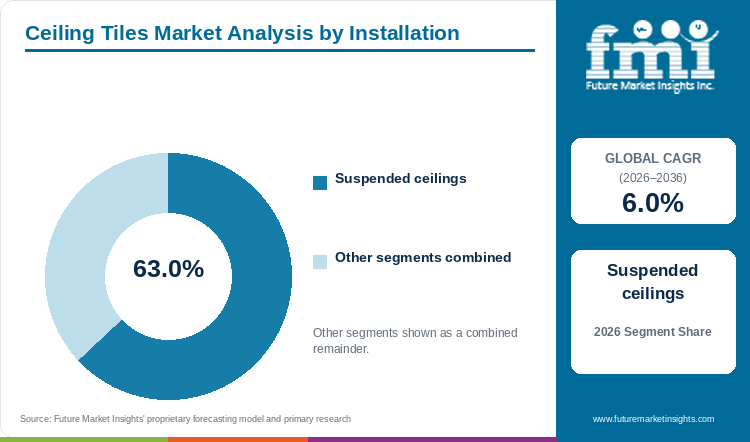
Suspended systems take 63% of installation sales in 2026, as commercial projects need accessible grids above building services.
Sales of suspended ceiling systems follow commercial construction activity, as every new office or institutional fit-out needs an accessible grid above services. As per FMI estimates, suspended systems hold 63% of installation sales in 2026. Surface-mounted ceilings suit smaller renovation budgets and tighter floor-to-floor heights. U.S. private nonresidential construction stood at USD 746.0 billion in April 2025. Wider commercial construction activity is expected to keep suspended systems ahead of surface-mounted installations.
- Suspended systems hold 63% of installation sales in 2026, as commercial projects need accessible grids above mechanical and electrical services.
- A stalled commercial project delays suspended-grid orders, so contractors weigh lead time and local stock heavily when choosing a supplier.
Why does commercial end use lead ceiling tiles demand?
Commercial buildings make up 54% of end use sales in 2026, owing to office and healthcare renovation activity.
Demand for ceiling tiles in commercial buildings is rising, as offices, healthcare facilities and institutions specify certified fire and acoustic ratings. FMI data shows commercial end use making up 54% of sales in 2026. Residential projects remain price-led, and industrial facilities specify tiles mainly for noise control around processing areas. Armstrong World Industries reported second-quarter 2025 revenue of USD 424.6 million, up 16.3% year over year, with commercial fit-out and renovation work, including projects served by its Architectural Specialties division, contributing to that growth. Office, healthcare and institutional renovation activity is expected to keep commercial buildings as the main buyers of ceiling tiles.
- Commercial end use makes up 54% of sales in 2026, and office and healthcare renovation will keep this segment in front through 2036.
- Buyers specifying tiles for healthcare or education projects should confirm fire rating and acoustic class before placing an order.
Why do direct sales lead the ceiling tiles sales channel?
Direct sales capture 49% of channel sales in 2026, owing to large commercial projects needing matched tile batches.
Commercial contractors buy most ceiling tiles straight from manufacturers, as large projects need matched batches and consistent fire ratings. FMI estimates that direct sales capture 49% of channel sales in 2026. Distributors and online sales cover smaller renovation jobs and regions with fewer manufacturer sales offices. U.S. private nonresidential construction eased 0.5% to USD 746.0 billion in April 2025, a seasonally adjusted annual rate. Large commercial construction projects will keep direct sales as the leading channel through 2036.
- Direct sales capture 49% of channel sales in 2026, supported by large commercial projects that need matched tile batches.
- Distributors and online buyers often prefer standard sizes, as renovation orders in these channels are smaller and change more often.
What gives acoustic control the lead in application demand?
Acoustic control holds an estimated 44% of application sales in 2026, as open-plan offices and healthcare facilities specify sound-rated tiles.
Building owners prefer ceiling tiles rated for sound absorption, as open-plan offices and healthcare facilities need lower ambient noise. Acoustic control holds an estimated 44% of application sales in 2026, as per FMI. Thermal insulation and aesthetic enhancement applications cover energy-focused retrofits and design-led fit-outs. Armstrong World Industries reported overall second-quarter 2025 net sales growth of 16.3%; its separate Architectural Specialties unit, which focuses mainly on metal and wood ceiling and wall products rather than mineral-fibre acoustic tiles, posted 37.2% net sales growth in the same quarter. Revenue from acoustic-rated tiles is anticipated to grow with office and healthcare renovation, and acoustic control is set to keep most new specification gains.
- Open-plan offices and healthcare facilities push acoustic control to 44% of application sales in 2026.
- Sound absorption ratings and installation support deserve a check before choosing a supplier, as acoustic performance drives most commercial specifications.
What are the drivers, restraints, and opportunities in the Ceiling Tiles Market?
Commercial construction recovery pushes plants toward certified mineral fiber tiles, input cost volatility slows approvals at smaller producers, and EU green-building renovation rules open the main opportunity for sustainability-compliant ceiling systems.
- Driver: Key drivers of the ceiling tiles market include commercial builders replacing ageing suspended grids with certified fire-rated and acoustic tiles.
- Restraint: Input cost volatility and supply chain complexity compress margins for smaller ceiling tile producers. Compliance costs for certified products also slow approvals at smaller contractors.
- Opportunity: Green-building renovation mandates in the European Union open growth for sustainability-compliant ceiling systems.
Commercial Construction Recovery Speeds Up Orders
Commercial construction activity is stabilizing after a soft start to 2025, lifting approvals for new ceiling fit-outs. Armstrong World Industries reported second-quarter 2025 revenue of USD 424.6 million, up 16.3% from a year earlier. Due to this, suppliers are adding capacity for certified acoustic and fire-rated tiles. Sales of ceiling tiles tied to commercial renovation are anticipated to grow fastest in markets with active office and healthcare construction through 2036.
Soft Construction Spending Delays Some Orders
Uneven nonresidential construction spending makes some building owners slower to approve new ceiling projects. U.S. private nonresidential construction eased 0.5% to USD 746.0 billion in April 2025, a seasonally adjusted annual rate, from a revised USD 750.1 billion in March. Every new ceiling project also needs matched fire ratings and grid compatibility, adding time before installation. High compliance costs and these approval steps may slow orders from smaller contractors in the early forecast years.
Green-Building Rules Favour Certified Tiles
European rules are moving commercial renovation toward certified, energy-efficient building components. The recast EU Energy Performance of Buildings Directive, published on 8 May 2024, sets minimum energy performance standards for the worst-performing non-residential buildings. Due to this, renovation contractors are specifying sustainability-compliant ceiling tiles ahead of national transposition deadlines. Builders of certified, sustainability-compliant ceiling systems stand to gain new European orders through 2036.
Which country CAGRs are profiled in the Ceiling Tiles Market?
Sales of ceiling tiles in the USA grow fastest among the five FMI-profiled countries, at a 5.7% CAGR between 2026 and 2036. Japan posts the slowest rate, a 5.3% CAGR over the same period. Across all five, commercial builders buy certified tiles mainly to meet fire and acoustic codes and to replace ageing suspended grids.
Table 6: Country CAGRs and Primary Growth Levers for the Ceiling Tiles Market (CAGR percentage), 2026 to 2036
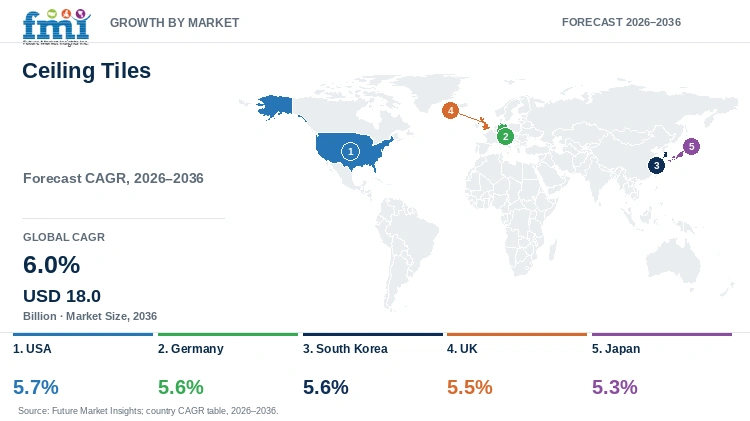
| Country | CAGR (2026–2036) | Primary Growth Lever |
|---|---|---|
| USA | 5.7% | Commercial construction recovery and Architectural Specialties growth |
| Germany | 5.6% | Renovation plans under Germany's EPBD transposition |
| South Korea | 5.6% | Semiconductor fab office-support construction and broader commercial fit-outs |
| UK | 5.5% | Fire-safety documentation under the Building Safety Act 2022 |
| Japan | 5.3% | Replacement of ceiling systems in ageing commercial buildings |
Source: Future Market Insights
USA Ceiling Tiles Market Outlook (2026–2036)
U.S. private nonresidential construction stood at USD 746.0 billion in April 2025, a seasonally adjusted annual rate, after easing 0.5% from the revised March estimate. Due to this, contractors are pacing new ceiling fit-out orders to project financing cycles. Armstrong World Industries, a leading U.S. ceiling systems maker, reported second-quarter 2025 revenue of USD 424.6 million, up 16.3% year over year, placing the USA first with a 5.7% CAGR for 2026 to 2036. Architectural Specialties, the company's custom and specialty ceiling division, grew net sales 37.2% in the same quarter, aided by the 2024 acquisitions of 3form and Zahner. This growth is creating room for suppliers of certified acoustic and specialty ceiling systems.
Key takeaway: Certified acoustic and specialty tiles tied to commercial renovation will draw most U.S. orders.
Germany Ceiling Tiles Market Outlook (2026–2036)
The recast EU Energy Performance of Buildings Directive was published in the Official Journal on 8 May 2024 and gave Member States a two-year transposition window into national law, with the renovation obligations for the worst-performing non-residential buildings phasing in on a longer timeline through 2030 and beyond. Germany's national transposition sets minimum energy performance standards for non-residential buildings, and its renovation plan sets out a 2050 vision for the building stock. Plants need certified, sustainability-compliant tile ranges to meet these renovation plans, which favours suppliers with energy-performance documentation over commodity producers. Germany is set for a 5.6% CAGR through 2036, as its national transposition measures take effect.
Key takeaway: Energy-performance documentation on tile ranges will draw EU renovation spending.
South Korea Ceiling Tiles Market Outlook (2026–2036)
SK hynix approved a USD 38.3 billion investment in two new memory fabs in August 2026, including a 279-acre DRAM facility at the Yongin Semiconductor Cluster with construction due to start in July 2027. Cleanroom floors in these fabs are built on fan-filter grid systems rather than ceiling tiles, so the direct ceiling tile opportunity sits in the office, administrative and support space built alongside each fab, together with South Korea's broader commercial construction activity. Due to this, South Korea is set for a 5.6% CAGR over 2026 to 2036, led by fab-linked office-support construction and commercial fit-outs.
Key takeaway: Office-support ceiling systems tied to new fab construction, alongside broader commercial fit-outs, form the main South Korean opening.
UK Ceiling Tiles Market Outlook (2026–2036)
The UK is projected to add ceiling tiles sales at a 5.5% CAGR through 2036. The Building Safety Act 2022, which received royal assent on 28 April 2022, created a National Regulator for Construction Products and tightened fire-safety record-keeping for higher-risk buildings. Demand for documented, fire-rated ceiling systems is growing as a result. Buyers, however, want shorter approval cycles once the Act's secondary legislation on construction products takes effect.
Key takeaway: Fire-safety documentation requirements will set the timing of UK ceiling tile purchases.
Japan Ceiling Tiles Market Outlook (2026–2036)
Japan's commercial building stock is ageing, and replacement of ceiling systems in older offices and institutional buildings is a steady source of orders. Japanese ceiling tile sales are set for a 5.3% CAGR from 2026 to 2036, the lowest among the five profiled countries. Replacement orders will favour certified fire-rated and acoustic tiles suited to renovation of existing commercial buildings over new construction.
Key takeaway: Japanese buyers will prioritize certified replacement tiles for existing commercial buildings over new-build specification.
Who are the notable companies in the Ceiling Tiles Market?
Saint-Gobain, Armstrong World Industries, Knauf Gips KG (including USG Corporation), SAS International, Zentia, Rockfon, Hunter Douglas Architectural, Techstyle Ceilings, Odenwald Faserplattenwerk, BNBM, and Daiken are the leading companies profiled in this market.
Ceiling tile manufacturers come from France, the USA, Germany, Belgium, the UK and Asia and differ in material range, grid-system integration and service reach. Saint-Gobain, Armstrong World Industries, Knauf Gips KG (whose ceiling systems business includes USG Corporation, a subsidiary since 2019) and Rockfon, part of the ROCKWOOL Group, concentrate on mineral fiber and acoustic ceiling tiles. SAS International supplies suspension grid and system hardware, and Zentia is a mineral-fibre ceiling tile maker in its own right. Hunter Douglas Architectural, Techstyle Ceilings and Odenwald Faserplattenwerk supply specialized and regional ceiling products, while BNBM and Daiken lead mineral fiber and acoustic ceiling tile supply across Asia. Leading manufacturers are widening certified product ranges and service networks to gain replacement orders from commercial builders.
- Mineral fiber and acoustic ceiling specialists: Saint-Gobain, Armstrong World Industries, Knauf Gips KG (including USG Corporation), Rockfon, BNBM, and Daiken supply fire-rated and acoustic mineral fiber tiles.
- Suspension grid and system suppliers: SAS International covers grid hardware and suspended-system integration, and Zentia supplies mineral-fibre ceiling tiles alongside grid-compatible systems.
- Specialized and regional ceiling manufacturers: Hunter Douglas Architectural, Techstyle Ceilings, and Odenwald Faserplattenwerk supply specialized and regional ceiling products.
Competitive Benchmarking: Ceiling Tiles Market
Table 7: Competitive Benchmarking for the Ceiling Tiles Market (qualitative capability ratings), 2026
| Company | Material Range | Certification | Service | Reach |
|---|---|---|---|---|
| Saint-Gobain | High | High | High | High |
| Armstrong World Industries | High | High | High | High |
| Knauf Gips KG (incl. USG Corporation) | High | Medium | Medium | High |
| BNBM | Medium | Low | Low | Medium |
| SAS International | Medium | Medium | Medium | Medium |
| Zentia Group | Medium | Medium | Medium | Medium |
| Rockfon | Medium | Medium | Medium | High |
| Hunter Douglas Architectural | Low | Low | Low | Medium |
| Techstyle Ceilings | Low | Low | Low | Low |
| Odenwald Faserplattenwerk | Low | Low | Low | Low |
| Daiken | Medium | Low | Low | Medium |
Key Developments in the Ceiling Tiles Market
- In the second quarter of 2025, Armstrong World Industries reported revenue of USD 424.6 million, up 16.3% year over year, with Architectural Specialties net sales up 37.2%.
- In May 2024, the recast EU Energy Performance of Buildings Directive (Directive 2024/1275) was published in the Official Journal, opening a two-year transposition window requiring Member States to set renovation plans for the worst-performing non-residential buildings [3].
- In August 2026, SK hynix approved a USD 38.3 billion investment in two new memory fabs, with construction on the Yongin Y2 facility due to start in July 2027.
- In April 2025, U.S. private nonresidential construction eased 0.5% to USD 746.0 billion, a seasonally adjusted annual rate.
Key Players in the Ceiling Tiles Market
Mineral Fiber and Acoustic Ceiling Specialists
- Saint-Gobain
- Armstrong World Industries, Inc.
- Knauf Gips KG (including USG Corporation)
- USG Corporation
Suspension Grid and Mineral-Fibre Suppliers
- SAS International
- Zentia
Specialized and Regional Ceiling Manufacturers
- Rockfon
- Hunter Douglas Architectural
- Techstyle Ceilings, Odenwald Faserplattenwerk, BNBM, and Daiken
Ceiling Tiles Market - Report Scope
Table 8: Report Scope for the Ceiling Tiles Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product; installation; end use; sales channel; application; region |
| Quantitative units | USD billion |
| Market definition | Revenue from first sale of mineral fiber, metal, wood and gypsum ceiling tiles, suspended and surface-mounted ceiling systems, and related grid hardware and installation service. Finished buildings, structural ceiling framing and non-ceiling interior panels are excluded. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | USA; Germany; South Korea; UK; Japan |
| Key companies profiled | Saint-Gobain, Armstrong World Industries, Knauf Gips KG (including USG Corporation), SAS International, Zentia, Rockfon, Hunter Douglas Architectural, Techstyle Ceilings, Odenwald Faserplattenwerk, BNBM, Daiken |
| Forecast period | 2026 to 2036 |
| Approach | The estimate blends bottom-up and top-down inputs, reconciling commercial construction activity, renovation cycles, certification requirements and manufacturer disclosures, checked against company filings and primary interviews. |
Ceiling Tiles Market - Research Methodology
Table 9: Research Methodology for the Ceiling Tiles Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary research includes interviews with ceiling tile manufacturers, distributors, commercial contractors and procurement teams. Interviews cover certification requirements, lead times, service needs and pricing. |
| Desk Research | Desk research draws on manufacturer filings, construction spending data, green-building regulation records and fab and infrastructure investment announcements. |
| Market Sizing and Forecasting | Sizing starts from the 2025 market value and adds commercial construction activity, renovation cycles, average tile pricing, segment splits and country-level construction conditions. |
| Data Validation | Each estimate is tested against manufacturer disclosures, construction spending data and primary interviews. Finished buildings and non-ceiling panels stay outside market value, so no revenue is counted twice. |
Ceiling Tiles Market by Segments
Ceiling Tiles Market segmented by Product:
- Mineral fiber tiles
- Metal tiles
- Wood tiles
- Gypsum tiles
- Others
Ceiling Tiles Market segmented by Installation:
- Suspended ceilings
- Surface-mounted ceilings
Ceiling Tiles Market segmented by End Use:
- Commercial
- Residential
- Industrial
Ceiling Tiles Market segmented by Sales Channel:
- Direct sales
- Distributors
- Online sales
Ceiling Tiles Market segmented by Application:
- Acoustic control
- Thermal insulation
- Aesthetic enhancement
Ceiling Tiles Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- Japan
- South Korea
- South Asia and Pacific
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Armstrong World Industries, Inc. (via The Motley Fool). (2025, July 29). Armstrong Q2 Revenue Jumps 16%.https://www.fool.com/data-news/2025/07/29/armstrong-q2-revenue-jumps-16-percent
- [2] U.S. Census Bureau, via Data Center Dynamics. (2025, April). April 2025 Construction Statistics from the U.S. Census Bureau.https://dcd.com/articles/april-2025-construction-statistics-from-the-u-s-census-bureau/
- [3] Buildings Performance Institute Europe (BPIE). (2024). The EPBD decrypted: a treasure chest of opportunities to accelerate building decarbonisation.https://www.bpie.eu/?p=7181
This Report Answers
- What value will ceiling tiles sales reach in 2026?
- By 2036, what market value will ceiling tiles reach?
- Which product type takes the largest share of orders?
- What installation type and end use do commercial buyers favour?
- Which profiled countries show the fastest growth in ceiling tiles sales?
- Which manufacturers lead the supply of ceiling tiles to commercial builders?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product, 2026 to 2036
- Mineral fiber tiles
- Metal tiles
- Wood tiles
- Gypsum tiles
- Others
- Y-o-Y Growth Trend Analysis By Product, 2021 to 2025
- Absolute $ Opportunity Analysis By Product, 2026 to 2036
- Global Market Analysis and Forecast, By Installation, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Installation, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Installation, 2026 to 2036
- Suspended ceilings
- Surface-mounted ceilings
- Y-o-Y Growth Trend Analysis By Installation, 2021 to 2025
- Absolute $ Opportunity Analysis By Installation, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Commercial
- Residential
- Industrial
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Direct sales
- Distributors
- Online sales
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Acoustic control
- Thermal insulation
- Aesthetic enhancement
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- South Korea
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- ASEAN
- Australia and New Zealand
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product
- By Installation
- By End Use
- By Sales Channel
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Saint-Gobain
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Armstrong World Industries
- Knauf Gips KG (incl. USG Corporation)
- BNBM
- SAS International
- Zentia Group
- Rockfon
- Hunter Douglas Architectural
- Techstyle Ceilings
- Odenwald Faserplattenwerk
- Daiken
- Knauf Gips KG (including USG Corporation)
- USG Corporation
- Zentia
- Techstyle Ceilings, Odenwald Faserplattenwerk, BNBM, and Daiken
- Saint-Gobain
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Installation, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Installation, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Installation, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Installation, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Installation, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Installation, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Installation, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Installation, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product
- Figure 6: Global Market Value Share and BPS Analysis by Installation, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Installation, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Installation
- Figure 9: Global Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End Use
- Figure 12: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Sales Channel
- Figure 15: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Application
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Product
- Figure 32: North America Market Value Share and BPS Analysis by Installation, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Installation, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Installation
- Figure 35: North America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by End Use
- Figure 38: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Sales Channel
- Figure 41: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Application
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Product
- Figure 48: Latin America Market Value Share and BPS Analysis by Installation, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Installation, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Installation
- Figure 51: Latin America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by End Use
- Figure 54: Latin America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Sales Channel
- Figure 57: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Application
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Product
- Figure 64: Western Europe Market Value Share and BPS Analysis by Installation, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Installation, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Installation
- Figure 67: Western Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by End Use
- Figure 70: Western Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Sales Channel
- Figure 73: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Application
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Product
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Installation, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Installation, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Installation
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by End Use
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Sales Channel
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Application
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Product
- Figure 96: East Asia Market Value Share and BPS Analysis by Installation, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Installation, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Installation
- Figure 99: East Asia Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by End Use
- Figure 102: East Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Sales Channel
- Figure 105: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Application
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Product
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Installation, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Installation, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Installation
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by End Use
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Sales Channel
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Product
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Installation, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Installation, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Installation
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by End Use
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Sales Channel
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
What is the ceiling tiles market worth in 2026?
Ceiling tiles sales are valued at USD 10.1 billion in 2026, according to FMI. The market will reach USD 18.0 billion by 2036 as commercial builders replace older suspended grids and tiles.
What CAGR is projected for the ceiling tiles market through 2036?
FMI projects a 6% CAGR for the ceiling tiles market from 2026 to 2036. Commercial construction recovery and green-building renovation rules will support much of this growth.
Which product leads ceiling tiles sales in 2026?
Mineral fiber tiles will hold 42% of product sales in 2026. Builders specify this material first for fire rating and acoustic performance.
Which installation type leads ceiling tiles sales in 2026?
Suspended systems will account for 63% of installation sales in 2026. Builders select this type to keep services above the ceiling accessible.
Which country has a leading growth outlook through 2036?
The USA leads the profiled countries with a 5.7% CAGR for ceiling tiles sales over 2026 to 2036. Recovering commercial construction and Architectural Specialties growth favour certified acoustic tiles.
Who are the key companies in the ceiling tiles market?
Key companies include Saint-Gobain, Armstrong World Industries, Knauf Gips KG (including USG Corporation), SAS International, Zentia, Rockfon, Hunter Douglas Architectural, Techstyle Ceilings, Odenwald Faserplattenwerk, BNBM, and Daiken. These manufacturers compete on material range, grid-system integration and service reach.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
