

- Market Size (2026)
- USD 120.0 Bn
- Forecast (2036)
- USD 240.4 Bn
- CAGR (2026 to 2036)
- 7.2%
How big is Ceramic Tiles Market in 2026?
The ceramic tiles market is estimated at USD 111.9 billion in 2025 and is forecast to reach USD 120.0 billion in 2026. Demand for ceramic tiles is expected to grow at a 7.2% CAGR and reach USD 240.4 billion by 2036.
Adoption of ceramic tiles is spreading from bathrooms and kitchens to whole floors and facades. Demand for ceramic tiles is set to reach USD 120.0 billion in 2026, from an estimated USD 111.9 billion in 2025, and a 7.2% CAGR over 2026 to 2036 points to USD 240.4 billion by 2036. In particular, large-format porcelain is replacing vinyl and carpet in living rooms, and North American distributors are buying more large-format stock from plants close to home. For instance, the Tile Council of North America reported first-quarter 2026 imports down 20.4% to 379.6 million sq. ft., and domestic shipments up 5.6% to 184.1 million sq. ft.[1] As a result, distributors are shortening supply lines and holding less imported stock.
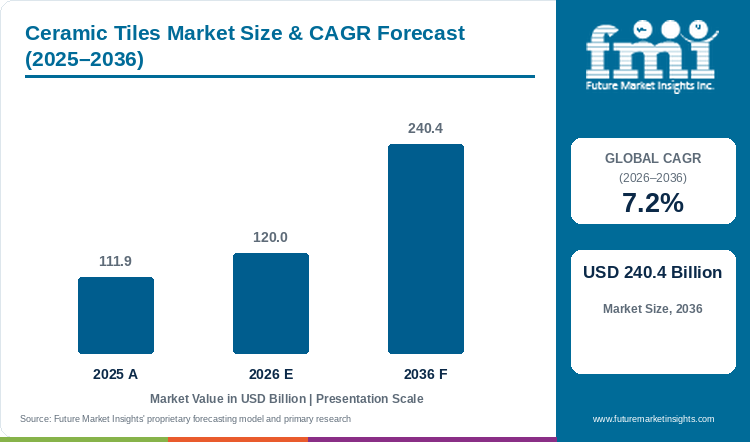
For contractors and retailers, prices are firming. On price, US-made tile averaged USD 1.86 per sq. ft. at the factory, up from USD 1.83, and arrivals from Spain fell 35.2% and from Brazil 59.8%.[1] Buyers therefore have fewer low-price import lots to pick from and less room to bargain on large orders. On that basis, FMI analysis suggests that distributors who sign 12-month supply agreements with domestic and nearshore plants will receive better allocation of large-format porcelain.
Key Market Trends & Insights
- Floor tiles hold the largest product type share, 57.6% in 2026, as homeowners carry one tile through living areas, and wall tiles follow near 34.1%.
- Porcelain is projected to hold 45% of material type sales in 2026, and premium European porcelain output is still rising. For example, Italian producers made 390.9 million sqm of tiles and slabs in 2025, up 5.7%.[2] Higher output from Italian slab and porcelain lines keeps premium supply ample for export buyers.
- Within end use, households are likely to account for 51.7%, with commercial projects at an estimated 36.5%. Even so, Mohawk Industries said commercial sales were outperforming residential in the June 2026 quarter.[3] Stronger commercial orders suggest fit-outs will narrow the gap with homes over the next few years.
Regional Highlights
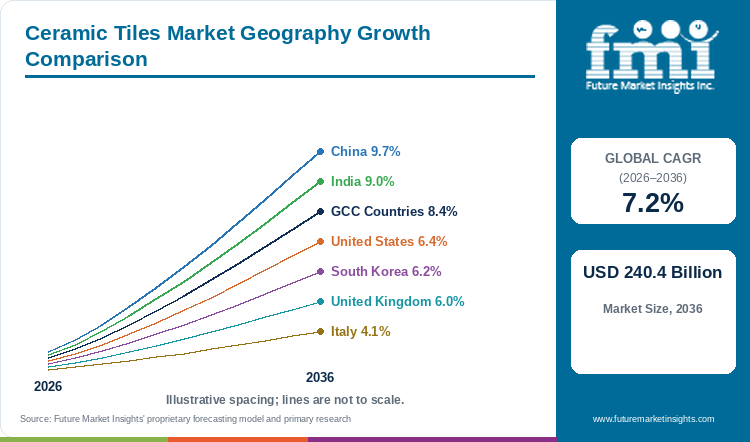
- China leads on FMI's forecast at 9.7%, as tile makers turn from new homes to refits.
- Indian demand advances 9% a year as branded makers replace unbranded tiles, and Gulf demand 8.4% as new plants open in the GCC Countries. Below the global figure, the United States reaches 6.4% and South Korea 6.2%. Italy, with 4.1%, brings up the rear, behind retail-led growth of 6% in the United Kingdom.
- Gulf producers are gaining from disrupted import flows. RAK Ceramics reported UAE revenue up 22.7% to AED 298.2 million in the June 2026 quarter and said disrupted imports opened room to gain local share.[4] Local plants that fill orders during import delays are likely to keep many of those accounts once trade normalises.
Market Size & Forecast
Table 1: Market Size and Forecast for the Ceramic Tiles Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 111.9 billion |
| Estimated Market Size in 2026 | USD 120.0 billion |
| Projected Market Size by 2036 | USD 240.4 billion |
| CAGR, 2026 to 2036 | 7.2% |
| Added Revenue, 2026 to 2036 | USD 120.4 billion |
| Market Expansion Multiple | 2.0x |
Distributors in the Americas bought ahead of price increases in mid-2026, which raised producer sales. For the June 2026 quarter, Global Ceramic net sales at Mohawk Industries were USD 1,209.7 million, up 7.9% as reported, and the company said some customers bought ahead of announced price increases.[3] Part of that gain is pulled forward from later quarters, so US volume may ease once the new price lists apply. Underlying US consumption has been falling for several years. By comparison, US consumption fell 4.9% to 238.6 million m² in 2025, the fourth straight decline, Ceramic World Web reported from TCNA data.[5] A fourth year of decline leaves room for recovery once home sales and remodelling pick up. Adhesives and grouts are used on every square metre laid, though the construction adhesives market rises more slowly, at a projected 4.6% CAGR. Even so, FMI expects the ceramic tiles market to double between 2026 and 2036, with about USD 120.4 billion of new sales. Against this, kiln fuel prices and carbon charges in Europe are the main risks to producer margins.
Import Shifts, Kiln Costs and Slab Lines
Trade flows into North America are shifting. For instance, Spain shipped 37.0 million m² of tile to the United States in 2025, up 17.5%, and Italy shipped 30.6 million m², up 6.9%, at an average of USD 25.08 per m².[5] European tile is gaining US share at higher average prices. Lower-priced suppliers are losing ground at the same time. By contrast, Indian volume fell 21.2% and Mexican volume 16% over the same year.[5] In short, European exporters are gaining in the premium tier as lower-priced suppliers lose ground.
Energy and carbon costs weigh on European makers. For example, Italian tile and slab sales were EUR 6.04 billion in 2025, 0.4% lower, average prices fell 2.5%, and direct ETS charges cost the sector an estimated EUR 70 million.[2] Carbon charges of that size cut into margins already hit by lower prices. Chinese producers are answering weak home demand by building abroad. Meanwhile, Chinese output fell 17.8% to 4.86 billion m² in 2025, and Chinese groups now run about 136 production lines abroad.[6] Lines abroad add local competition for producers in importing countries across Asia, Africa and Latin America.
Table 2: Trade, Output and Producer Indicators for the Ceramic Tiles Market (volumes, prices and sales), 2025 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| US tile consumption, Q1 2026 | 563.7 million sq. ft.; down 13.4% | US demand | [1] |
| US domestic shipments, Q1 2026 | 184.1 million sq. ft.; up 5.6% | Shift to domestic supply | [1] |
| Mohawk Industries Global Ceramic net sales, Q2 2026 | USD 1,209.7 million; up 7.9% | Producer sales in the Americas and Europe | [3] |
| Italian tile and slab production, 2025 | 390.9 million sqm; up 5.7% | European premium supply | [2] |
| China tile production, 2025 | 4.86 billion m²; down 17.8% | Global capacity | [6] |
| RAK Ceramics tiles sales, Q2 2026 | AED 482.5 million; up 1.7% | Gulf and export demand | [4] |
Analyst Perspective
“Large-format porcelain will, in my view, decide which tile makers grow through 2036, as slabs carry tile onto worktops, facades and open-plan floors. I expect plants close to the buyer in the United States, the Gulf and India to gain share from long-haul exporters as freight and carbon costs rise. Producers that pair digital printing with slab presses are turning tile showrooms into surface studios for kitchens and facades.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the ceramic tiles market segmented?
The market is segmented into product type, material type, end use, and region. Floor tiles are expected to lead product type with 57.6% share in 2026, and porcelain tiles lead material type with 45%.
By product type: floor tiles, wall tiles, and other tiles.
By material type: porcelain tiles, glazed ceramic tiles, unglazed ceramic tiles, and others.
By end use: residential, commercial, and industrial.
By region: tile plants, distributors and installers in North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do floor tiles lead ceramic tiles sales by product type?
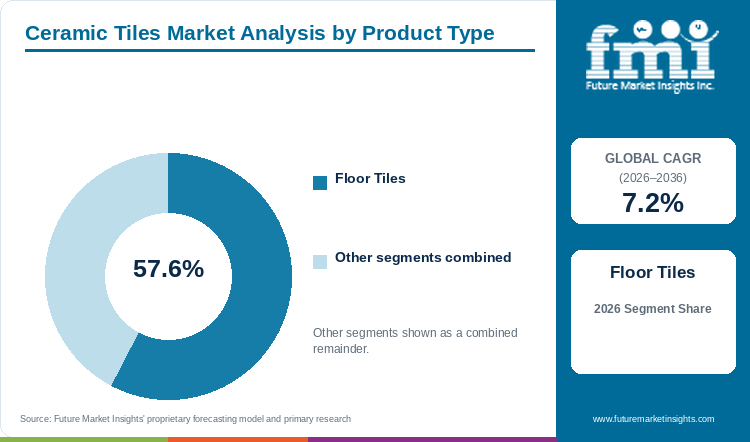
Floor tiles are expected to lead product type sales with 57.6% share in 2026, ahead of wall tiles at about 34.1% and other tiles at an estimated 8.3%.
Table 3: Product Type Share for the Ceramic Tiles Market (percentage share), 2026
| Product Type | Estimated Share (2026) |
|---|---|
| Floor Tiles | 57.6% |
| Wall Tiles | 34.1% |
| Other Tiles | 8.3% |
| Total | 100.0% |
Table 4: Product Type Leadership and Market Growth for the Ceramic Tiles Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.2% |
| Leading Segment | Floor Tiles |
Floor tiles will lead product type sales at 57.6% in 2026, since a floor needs more square metres per room than a wall and porcelain floors resist wear from shoes, chairs and carts. Wall tiles, about 34.1%, stay in bathrooms, kitchens and facades, and many homes paint the other walls. Other tiles, an estimated 8.3%, cover mosaics, trims, pool tiles and outdoor pavers. On the other hand, vinyl competes on price and laying speed, and growth of the vinyl flooring market sets the pace at which budget homes move floor area away from tile. Floor tile prices vary widely by origin and finish. At the premium end, Italian tile shipped to the United States averaged USD 25.08 per m² in 2025, against USD 6.67 for Indian tile.[5] That spread lets distributors offer floor tiles at both budget and premium price points. In practice, buyers choose floor tiles for durability and keep wall tiles for wet rooms and feature walls.
- The floor line spans porcelain floor tiles, outdoor pavers and large-format slabs for open-plan living.
- Large-format floor ranges are helping producers hold margins. Mohawk Industries reported a 7.8% operating margin for Global Ceramic in the June 2026 quarter.[3] A margin at that level gives room to keep investing in slab presses despite higher energy costs.
Why do porcelain tiles lead ceramic tiles sales by material type?
Porcelain tiles are projected to lead material type sales with 45% share in 2026, ahead of glazed ceramic tiles at about 31.4% and unglazed ceramic tiles at an estimated 14.2%.
Table 5: Material Type Share for the Ceramic Tiles Market (percentage share), 2026
| Material Type | Estimated Share (2026) |
|---|---|
| Porcelain Tiles | 45% |
| Glazed Ceramic Tiles | 31.4% |
| Unglazed Ceramic Tiles | 14.2% |
| Others | 9.4% |
| Total | 100.0% |
With water absorption below 0.5% and high breaking strength, porcelain tiles are projected to lead material type sales with 45% in 2026. By comparison, glazed ceramic tiles, about 31.4%, fire at lower cost and remain the usual choice for walls. Unglazed ceramic tiles, near 14.2%, serve quarry, terracotta and factory floors that need slip resistance above all. Others, at 9.4%, include mosaics and cotto. Gulf buyers are trading up to porcelain. For instance, RAK Ceramics said Saudi tile sales rose 11.6% in the June 2026 quarter on a shift from ceramic to gres porcelain.[4] Trading up of that kind raises value per square metre for producers with porcelain lines. In addition, glaze and body frits go into every firing, and growth of the ceramic frit market follows porcelain and glazed output. On balance, buyers pay more for porcelain in heavy-traffic rooms and stay with glazed ceramic for walls.
- Glazed porcelain, full-body porcelain and thin large-format slabs form the porcelain range.
- Porcelain now dominates export trade as well. Porcelain accounted for 52.7% of Chinese tile exports in 2025.[6] Exporters without porcelain capacity are losing ground in overseas tenders.
Why does residential lead ceramic tiles sales by end use?
Residential is likely to lead end-use sales with 51.7% share in 2026, with commercial at about 36.5% and industrial at roughly 11.8%.
Table 6: End Use Share for the Ceramic Tiles Market (percentage share), 2026
| End Use | Estimated Share (2026) |
|---|---|
| Residential | 51.7% |
| Commercial | 36.5% |
| Industrial | 11.8% |
| Total | 100.0% |
Households refit bathrooms and kitchens every 10 to 20 years and often relay floors after a home sale, so residential is likely to lead end-use sales with 51.7% in 2026. Commercial buyers, about 36.5%, specify tile for shops, hotels, hospitals and offices, and orders arrive project by project through architects. Industrial users, near 11.8%, need acid- and slip-resistant floors for food plants and workshops. Home renovation is soft in some mature markets, however. Even so, Topps Tiles said the wider market declined about 1.7% over the year to September 2026.[7] A shrinking UK market pushes retailers to take share from rivals through trade and online channels. Offices and hospitals that tile floors also fit suspended ceilings, so the ceiling tiles market, projected at a 6% CAGR, grows alongside commercial fit-outs. By 2036, homeowners will keep the largest share, and commercial demand will grow with hotel and retail fit-outs.
- Bathroom, kitchen, living-area and terrace projects form residential demand.
- Trade tilers are the growing part of UK residential demand. Topps Tiles grew Pro Tiler Tools sales 18.2% to about £42 million in the year to September 2026.[7] Growth that strong in trade supply shows professional fitters handling a larger part of home refits.
What are the drivers, restraints, and opportunities in the ceramic tiles market?
Home renovation and commercial fit-outs keep demand for ceramic tiles growing. Kiln energy and carbon costs squeeze producers, and large-format porcelain and digital decoration open higher-value sales.
- Driver: Homeowners refitting kitchens and bathrooms choose tile for water resistance and easy cleaning, so each renovation cycle brings repeat orders.
- Restraint: Tile kilns burn gas at high temperature, so swings in fuel and carbon prices cut producer margins before list prices can follow.
- Opportunity: Large-format slabs and digitally printed surfaces move tile onto worktops, facades and furniture, which raises value per square metre.
Renovation Keeps Tile Orders Coming
Repeat orders come from bathrooms and kitchens. In the United Kingdom, Topps Tiles grew group sales excluding CTD 0.7% to about £267 million in the year to 26 September 2026, and online orders reached 22.7% of group sales.[7] An online share at that level shows buyers ordering refit tiles from home. Store networks are shrinking at the same time. In addition, Topps had earlier planned to close 23 underperforming stores during the financial year.[8] Consequently, UK tile retailers will lean on trade customers and online orders to hold volume.
Kiln Energy and Carbon Charges Squeeze Producers
Producers of ceramic tiles face rising kiln costs. For example, RAK Ceramics said industry-wide gas shortages in Morbi halted output temporarily in the June 2026 quarter, and tile sales in India fell 8%.[4] Fuel interruptions of that kind hit smaller Indian kilns hardest. European makers face carbon costs on top of gas prices. In Europe, Confindustria Ceramica warned that direct ETS costs could rise to EUR 120 million without revised benchmarks for 2026 to 2030.[2] Therefore, in FMI's view, European plants without long-term gas contracts carry the highest margin risk.
Large-Format Porcelain Opens Higher-Value Sales
The ceramic tiles market will add most value through slabs and digitally printed surfaces. In China, Newpearl opened two high-performance lines on 28 March 2026 able to cut gas use by 15%, and a first electric roller kiln is planned for the second half of 2026.[6] Lower-gas slab lines cut the cost of large formats and make them more competitive with vinyl and stone. At the installation stage, heavy slabs need deformable adhesives, so growth of the tile adhesive market will track slab installations.
Which country CAGRs are profiled in the ceramic tiles market?
Table 7: Country CAGR Comparison for the Ceramic Tiles Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| China | 9.7% |
| India | 9% |
| GCC Countries | 8.4% |
| United States | 6.4% |
| South Korea | 6.2% |
| United Kingdom | 6% |
| Italy | 4.1% |
How do country-level CAGRs compare in the ceramic tiles market?
Chinese demand is resetting after the property slump. Chinese tile output fell 17.8% to 4.86 billion m² in 2025, and producers are moving from new-build orders to renovation and exports.[6] FMI therefore expects demand in China to recover fastest, at 9.7%, as refits of ageing apartments gather pace. Close behind, India, at 9%, gains from branded tiles replacing unbranded products, and the GCC Countries, at 8.4%, add local capacity. The United States, at 6.4%, gains from nearshoring, and South Korea, at 6.2%, from apartment refits, both below the 7.2% global rate. The United Kingdom grows at 6% with retail chains steadying volume, and Italy, with flat home sales, is slowest at 4.1%.
- Apartments built in the 1990s and 2000s across Chinese cities are being refitted with large-format porcelain. Refit demand favours consolidated groups with design ranges, and smaller plants built for new-build volume keep closing.
- Urban Indian buyers are moving from unbranded Morbi tiles to branded ranges with warranties, so branded makers with secure gas supply gain the most share.
- Disrupted imports have opened Gulf orders to local plants. RAK Ceramics and other producers with new capacity in Saudi Arabia can hold those accounts once trade recovers.
- Tariffs and freight costs are moving US orders to domestic and nearshore plants. Distributors gain shorter lead times, and long-haul exporters from Asia and Brazil lose volume.
- In Seoul and Busan, apartments from the 1990s are entering remodelling cycles. Large-format tiles gain from those refits, raising value per job for suppliers.
- With the wider UK market declining, retailers are shifting toward trade tilers and online orders. Chains with trade apps and next-day stock take volume from smaller independents.
- Flat home sales leave Italian domestic tile demand almost unchanged. Makers there rely on exports of premium porcelain, as design and slab capacity protect price abroad.
Full report country CAGRs cover: China, India, the GCC Countries, the United States, South Korea, the United Kingdom and Italy as profiled rates, and each other standard country inside the matching region.
Country-wise Analysis
China Ceramic Tiles Market Outlook (2026 to 2036)
Renovation is replacing new-build orders in China, and sales of ceramic tiles in China are expected to rise at a 9.7% CAGR through 2036. Abroad, Chinese exports fell 5.5% to 567 million m² in 2025, and porcelain accounted for 52.7% of that volume.[6] Weaker exports keep more porcelain at home, which raises competition for domestic refit orders. Over the forecast period, consolidation into larger, more efficient groups will continue, and those groups will sell more large-format and printed tiles at home.
Key takeaway: Renovation and consolidation shape growth in China.
India Ceramic Tiles Market Outlook (2026 to 2036)
Fuel supply has become the deciding factor for Indian tile makers. RAK Ceramics reported Indian sales of AED 73.7 million in the June 2026 quarter, 8% lower after gas shortages in Morbi stopped kilns, and said the industry restarted by June.[4] As a result, branded makers with secure gas supply will gain share from smaller Morbi plants as India grows at a forecast 9%.
Key takeaway: Secure fuel and brands decide winners in India.
GCC Countries Ceramic Tiles Market Outlook (2026 to 2036)
FMI sees Gulf demand rising 8.4% a year, 1.2 points faster than the global 7.2%, as the GCC Countries add tile capacity. In particular, RAK Ceramics grew UAE revenue 22.7% in the June 2026 quarter and expects the Yanbu greenfield tile project in Saudi Arabia to finish by Q2 2027.[4] Meanwhile, local plants are filling orders left open by delayed imports during the conflict, and many of those buyers are likely to stay with local supply.
Key takeaway: Local capacity in the Gulf replaces disrupted imports.
United States Ceramic Tiles Market Outlook (2026 to 2036)
US supply is still dominated by imports, which leaves domestic plants room to grow. US domestic shipments fell 8.1% to 65.7 million m² in 2025, the lowest since 2012, and imports supplied 72.4% of consumption.[5] An import share that high gives domestic plants room to gain as freight and tariff costs rise. Producers are also raising prices. On pricing, Mohawk Industries said additional price increases may be required in 2026.[3] Higher list prices raise the value of each square metre sold, even with flat volume. Over time, domestic and nearshore supply will rebuild share, and the United States is likely to hold a 6.4% CAGR.
Key takeaway: Domestic plants recover share in the United States.
South Korea Ceramic Tiles Market Outlook (2026 to 2036)
FMI analysis points to a 6.2% CAGR for South Korea, supported by remodelling of apartments built in the 1990s. Alongside this, builders in Seoul and Busan specify large-format tiles for new towers and refits.
Key takeaway: Korean apartment refits set the growth rate.
United Kingdom Ceramic Tiles Market Outlook (2026 to 2036)
UK tile retail is moving to trade and online channels. Topps Tiles reported Q4 FY26 online sales at about 25.6% of group sales and over 46,000 downloads of the Trade App.[7] This means digital channels now carry a growing part of UK tile sales, and UK demand for ceramic tiles is projected to rise about 6% a year through 2036.
Key takeaway: UK tile sales are moving to trade and online channels.
Italy Ceramic Tiles Market Outlook (2026 to 2036)
Export orders keep Italian plants running, as home demand barely moves. Italian domestic tile sales rose 0.6% to 85.2 million sqm in 2025, and exports reached 301.7 million sqm.[2] Exports at more than three times domestic volume leave Italian makers exposed to US and European demand. Italian demand, flat at home, advances only 4.1% a year, the slowest of the major countries.
Key takeaway: Italian makers rely on exports as home demand stays flat.
Who are the notable companies in the ceramic tiles market?
Mohawk Industries, Crossville, Florida Tile, Atlas Concorde, Porcelanosa, Gruppo Ceramiche Ricchetti, Saloni Ceramica, RAK Ceramics, Kajaria Ceramics and Monalisa Group are the profiled companies.
FMI analysis shows the tile supply base spanning North American producers, European design houses and Asian and Gulf makers. In North America, six-month Global Ceramic sales at Mohawk Industries grew to USD 2,307.1 million, against USD 2,114.7 million a year earlier.[3] Sales growth of that size keeps Mohawk the largest producer in the Americas. Gulf producers are improving margins. In the Gulf, RAK Ceramics raised the June 2026 quarter gross margin to 41% from 40.6%.[4] Better margins help fund the Yanbu plant and other capacity additions. Crossville, Florida Tile, Atlas Concorde, Porcelanosa, Gruppo Ceramiche Ricchetti, Saloni Ceramica, Kajaria Ceramics and Monalisa Group complete the group.
- North American producers: Mohawk Industries, Crossville and Florida Tile.
- European producers: Atlas Concorde, Porcelanosa, Gruppo Ceramiche Ricchetti and Saloni Ceramica.
- Asian and Gulf producers: RAK Ceramics, Kajaria Ceramics and Monalisa Group.
Competitive Benchmarking: Ceramic Tiles Market
Table 8: Competitive Benchmarking for the Ceramic Tiles Market (qualitative ratings), 2026
| Company | Sales Scale | Large-Format Range | Regional Reach | Recent Activity |
|---|---|---|---|---|
| Mohawk Industries | High | High | High | High |
| RAK Ceramics | High | Medium | Medium | High |
| Porcelanosa | Low | High | High | Low |
| Atlas Concorde | Low | High | Medium | Low |
| Kajaria Ceramics | Medium | Medium | Low | Low |
Ratings compare the companies on sales scale, large-format range and regional reach.
Key Developments in the Ceramic Tiles Market
- Topps Tiles put full-year sales at about £292 million including CTD in a 7 October 2026 trading update, which shows the UK specialist holding sales in a declining market.[7]
- RAK Ceramics grew Q2 2026 net profit 2.9% to AED 68.3 million in results of August 2026, a sign that Gulf demand is offsetting weaker Indian sales.[4]
- In Q2 results of 30 July 2026, Mohawk Industries reported Global Ceramic sales up 7.9% as reported; for US buyers, this points to firmer tile prices.[3]
- Confindustria Ceramica data from June 2026 showed Italian tile and slab investment down 16.1% to EUR 320.6 million for 2025, which signals slower capacity additions in Europe.[2]
- On 28 March 2026, Newpearl opened two high-performance kiln lines in China able to cut gas use by 15%, lowering the fuel cost of large-format tile.[6]
- The Tile Council of North America released first-quarter data on 29 May 2026 showing US consumption down 13.4%, which leaves distributors cautious on import orders.[1]
- Topps Tiles said in April 2026 that 23 underperforming stores would close during the financial year, a move that shifts more UK tile sales to trade and online channels.[8]
- TCNA figures for 2025, released in April 2026, put the fall in US tile consumption at 4.9%, the base from which a housing recovery would start.[5]
Key Players in the Ceramic Tiles Market
North American Producers
- Mohawk Industries
- Crossville
- Florida Tile
European Producers
- Atlas Concorde
- Porcelanosa
- Gruppo Ceramiche Ricchetti
- Saloni Ceramica
Asian and Gulf Producers
- RAK Ceramics
- Kajaria Ceramics
- Monalisa Group
Ceramic Tiles Market - Report Scope
Table 9: Report Scope for the Ceramic Tiles Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; material type; end use; region |
| Quantitative units | USD billion |
| Market definition | Kiln-fired clay tiles and slabs for floors, walls and other surfaces, including porcelain, glazed and unglazed ceramic tiles, mosaics and large-format slabs. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | Mohawk Industries, Crossville, Florida Tile, Atlas Concorde, Porcelanosa, Gruppo Ceramiche Ricchetti, Saloni Ceramica, RAK Ceramics, Kajaria Ceramics, Monalisa Group |
| Forecast period | 2026 to 2036 |
Ceramic Tiles Market - Research Methodology
Table 10: Research Methodology for the Ceramic Tiles Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Company results, industry associations, government statistics and trade publications. |
| Desk Research | Desk research covers tile consumption and trade, producer sales, kiln energy and carbon costs and large-format capacity. |
| Market Sizing and Forecasting | Sizing starts from the 2026 base of USD 120.0 billion and the 7.2% CAGR for 2026 to 2036. |
| Data Validation | Figures are cross-checked across company, industry and government sources. |
Ceramic Tiles Market by Segments
Ceramic Tiles Market segmented by Product Type:
- Floor Tiles
- Wall Tiles
- Other Tiles
Ceramic Tiles Market segmented by Material Type:
- Porcelain Tiles
- Glazed Ceramic Tiles
- Unglazed Ceramic Tiles
- Others
Ceramic Tiles Market segmented by End Use:
- Residential
- Commercial
- Industrial
Ceramic Tiles Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Tile Council of North America. (2026, May 29). 1Q 2026 U.S. Ceramic Tile Market Update. https://tcnatile.com/wp-content/uploads/2026/06/1Q-2026-U.S.-Ceramic-Tile-Market-Update.pdf
- [2] Ceramic World Web. (2026, June 16). Italian ceramic industry: energy and ETS charges squeeze margins. https://ceramicworldweb.com/index.php/en/economics-and-markets/italian-ceramic-industry-energy-and-ets-charges-squeeze-margins
- [3] Mohawk Industries, Inc. (2026, July 30). Mohawk Industries Reports Q2 2026 Results. https://ir.mohawkind.com/node/19026/html
- [4] RAK Ceramics PJSC. (2026, August 6). RAK Ceramics delivers resilient Q2 2026 performance amid regional disruptions. https://corporate.rakceramics.com/fin_news/rak-ceramics-delivers-resilient-q2-2026-performance-amid-regional-disruptions/
- [5] Ceramic World Web. (2026, April 1). The U.S. Ceramic Tile Market decreased by 4.9% in 2025. https://ceramicworldweb.com/index.php/en/economics-and-markets/us-ceramic-tile-market-decreased-49-2025
- [6] Ceramic World Web. (2026, June 10). China: tile production declines domestically but grows abroad. https://ceramicworldweb.com/index.php/en/economics-and-markets/china-tile-production-declines-domestically-grows-abroad
- [7] The Tile Association. (2026, October 7). Topps Tiles highlights its digital and data strategy in year-end trading report. https://tilezine.tiles.org.uk/topps-tiles-highlights-its-digital-and-data-strategy-in-year-end-trading-report/
- [8] The Tile Association. (2026, April 8). Topps Group shares trading update and future plans. https://tilezine.tiles.org.uk/topps-tiles-to-close-23-of-311-branches/
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the ceramic tiles market during 2026?
- What market size is projected by 2036?
- Which product type holds notable share?
- Which material type holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the ceramic tiles market expected in 2026?
At USD 120.0 billion, FMI's 2026 estimate for the ceramic tiles market is up from USD 111.9 billion in 2025. Sales of ceramic tiles are projected to reach USD 240.4 billion by 2036.
What CAGR is projected for the ceramic tiles market through 2036?
The ceramic tiles market is projected to grow at a 7.2% CAGR through 2036. Home renovation, commercial fit-outs and large-format porcelain carry that growth.
Which product type holds a notable market share in 2026?
Floor tiles are expected to lead with 57.6% share in 2026. Wall tiles follow at an estimated 34.1%.
Which material type holds a notable market share in 2026?
Porcelain tiles are projected to lead with 45% share. Glazed ceramic tiles follow at an estimated 31.4%.
Which country has a notable expansion outlook through 2036?
With a 9.7% CAGR, China heads the country outlook from FMI. India follows at 9%.
Who are the key companies in the ceramic tiles market?
Mohawk Industries, Crossville and Florida Tile lead the North American group, and Atlas Concorde, Porcelanosa, Gruppo Ceramiche Ricchetti and Saloni Ceramica lead the European group. RAK Ceramics, Kajaria Ceramics and Monalisa Group complete the profiled companies.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Floor Tiles
- Wall Tiles
- Other Tiles
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Material Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material Type, 2026 to 2036
- Porcelain Tiles
- Glazed Ceramic Tiles
- Unglazed Ceramic Tiles
- Others
- Y-o-Y Growth Trend Analysis By Material Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Type, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Residential
- Commercial
- Industrial
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Material Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By End Use
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Material Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By End Use
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Material Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By End Use
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Material Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By End Use
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Material Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By End Use
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Material Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By End Use
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Material Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By End Use
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End Use
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End Use
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End Use
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End Use
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End Use
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End Use
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End Use
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End Use
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End Use
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End Use
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End Use
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End Use
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End Use
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End Use
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End Use
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End Use
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End Use
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End Use
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End Use
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End Use
- GCC Countries
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End Use
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Material Type
- By End Use
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Mohawk Industries
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- RAK Ceramics
- Porcelanosa
- Atlas Concorde
- Kajaria Ceramics
- Crossville
- Florida Tile
- Gruppo Ceramiche Ricchetti
- Saloni Ceramica
- Monalisa Group
- Mohawk Industries
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


