

- Market Size (2026)
- USD 20.0 Bn
- Forecast (2036)
- USD 49.7 Bn
- CAGR (2026 to 2036)
- 9.5%
How big is Geosynthetics Market in 2026?
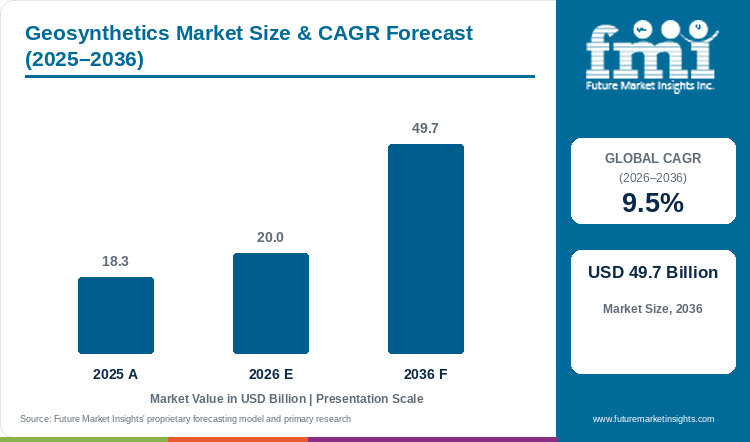
The geosynthetics market is estimated at USD 18.3 billion in 2025 and is expected to reach USD 20.0 billion in 2026. Demand for geosynthetics is projected to grow at a 9.5% CAGR and reach USD 49.7 billion by 2036.
Sales of geosynthetics are highest in road and highway work, so road budgets steer the geosynthetics market, which is estimated at USD 18.3 billion in 2025. For 2026, USD 20.0 billion is expected, and FMI's model shows the geosynthetics market reaching USD 49.7 billion by 2036, a 9.5% CAGR. Storm repair now adds to planned road programmes. The U.S. Department of Transportation released over USD 1.6 billion of emergency relief on 19 October 2026 for roads and bridges damaged in 34 states, the District of Columbia and four territories.[1] Washed-out embankments are usually rebuilt with geotextile separators and geogrid-reinforced fill, so each disaster season brings a fresh round of orders.
A buyer heat map places road builders in the hottest band, at roughly 34.6% of 2026 sales by end use and with repeat orders on every widening and resurfacing contract. Landfill and erosion control, near 21.4%, runs warm, as each new cell, cap and riverbank job needs a full liner or mat system. Railways, about 11.2%, and retaining walls, about 9.5%, stay cool, since work there arrives in fewer and larger awards.
Suppliers with geotextile and geogrid stock near state highway depots are first in line for short-notice repair work. Membrane producers will chase fewer, larger containment tenders, and price per square metre decides most of those bids.
Key Market Trends & Insights
- Across product type, geomembranes are expected to lead with 31% of 2026 sales, followed by geotextiles at about 28.4% and geogrids near 15.2%, as liner jobs use the widest rolls per project.
- Polypropylene (PP) is projected to supply 47% of material type sales in 2026, ahead of polyethylene (HDPE/LLDPE) at an estimated 33.5%, since nonwoven and woven PP fabrics serve separation, filtration and reinforcement alike.
- Within primary application, containment holds an estimated 32.5% in 2026 and separation about 24.8%. In the June 2026 quarter, the geosynthetics business at Garware Technical Fibres sustained strong growth momentum, the company said in August.[2]
- Roads (paved and unpaved) are likely to account for 34.6% of end use sales in 2026, with landfill and erosion control near 21.4%. Profitability at Tensar rose about 50% in fiscal 2026 on data center, energy and infrastructure work, Commercial Metals Company reported.[3]
Regional Highlights
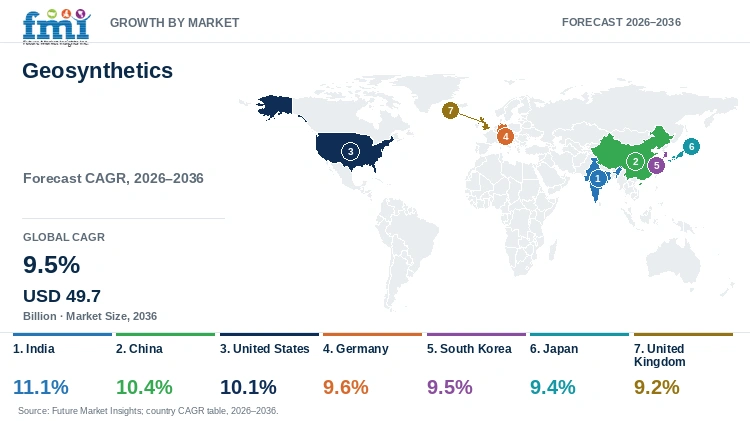
- Highway, canal and urban rail building gives India 11.1% in the FMI outlook, ahead of the 9.5% global CAGR, and China follows on 10.4% as water conservancy projects line reservoirs and channels.
- The United States, at 10.1%, is the fastest of the mature markets, with storm repair added to federal highway work. Rail renewal holds Germany at 9.6%, a tenth above the global figure, and soft-ground building keeps South Korea level at 9.5%. Repair-led Japan (9.4%) and the United Kingdom (9.2%) grow a little slower than the 9.5% global rate.
- Over GBP 1.4 billion of flood defence investment for 2026/27 will fund over 600 schemes in England, Water Magazine reported in March 2026.[4]
Market Size & Forecast
Table 1: Market Size and Forecast for the Geosynthetics Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 18.3 billion |
| Estimated Market Size in 2026 | USD 20.0 billion |
| Projected Market Size by 2036 | USD 49.7 billion |
| CAGR, 2026 to 2036 | 9.5% |
| Added Revenue, 2026 to 2036 | USD 29.7 billion |
| Market Expansion Multiple | 2.5x |
Geosynthetics are bought by the square metre against a project drawing, so orders follow the tender calendar of road agencies, landfill operators and water authorities. Roll goods reach site in large lots during the building season, and liner installers weld membranes on site under third-party quality checks. Geosynthetics form part of the wider technical textiles market, forecast at a 6.2% CAGR, and the faster pace for geosynthetics reflects heavy public works budgets for roads, water and flood defence. About USD 29.7 billion is projected to be added between 2026 and 2036, and FMI's model shows the geosynthetics market in 2036 near 2.5 times the 2026 level. Resin prices are the main near-term risk, as polypropylene and polyethylene make up most of the cost of a roll.
Road Repair, Containment and Water Works
Road repair is the steadiest source of volume. North Carolina alone is due USD 873 million of the October 2026 federal relief for damage from Hurricane Helene, across over 9,000 damage sites.[1] Each rebuilt slope or culvert crossing needs separation fabric and, on steep ground, a reinforced soil face. Contractors will draw on distributor stock for this work, so suppliers with regional warehouses gain the first call.
Containment and water works form the second track. China completed RMB 515.1 billion of water construction investment in the first half of 2026 and started 25 major projects, the Ministry of Water Resources said in July 2026.[5] Reservoir, canal and pond linings on that scale use geomembrane and clay liner by the hectare. Regulation can cut the other way, and the EPA in July 2026 let Salt River Project keep a clay liner on a coal ash pond at Coronado Generating Station, a decision SRP said avoids over USD 90 million of plastic liner cost.[6]
Table 2: Infrastructure, Water and Supplier Indicators for the Geosynthetics Market (funding, investment and company results), 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| U.S. emergency relief for roads and bridges, October 2026 | Over USD 1.6 billion across 34 states, D.C. and four territories | Repair work using separation and reinforcement products | [1] |
| China water construction investment, H1 2026 | RMB 515.1 billion; 25 major projects started | Reservoir and canal liner volume | [5] |
| England flood defence investment, 2026/27 | Over GBP 1.4 billion; over 600 schemes | Embankment, revetment and erosion control orders | [4] |
| Deutsche Bahn network investment, 2026 | Over EUR 23 billion planned | Track bed and formation renewal | [7] |
| Tensar profitability, fiscal 2026 | Up about 50% | Geogrid demand from data center, energy and infrastructure sites | [3] |
| Garware Technical Fibres net sales, Q1 FY27 | INR 482.4 crore; up 31.4% | Geosynthetics growth in India | [2] |
| SRP Coronado coal ash pond, July 2026 | Clay liner retained; over USD 90 million liner cost avoided | Regulatory risk to membrane volume | [6] |
Analyst Perspective
“Most geosynthetics are still specified one road or one landfill cell at a time, and that keeps buying fragmented. I expect the decade to reward suppliers who stock close to highway and water authority projects and who can certify a full system of fabric, grid and liner, as emergency repair and flood work leave little time for long qualification. The faster growth will come from Asian water projects and American road repair, and resin cost will decide margins more than volume.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the geosynthetics market segmented?
The market is segmented into product type, material type, primary application, end use, and region. Geomembranes are expected to lead product type with 31% share in 2026, and polypropylene (PP) leads material type with 47%.
By product type: geotextile, geomembrane, geogrid, geonet, geocomposite, geosynthetics clay liner, and others.
By material type: polyethylene (HDPE/LLDPE), polypropylene (PP), polyester, natural fibers, and others.
By primary application: separation, drainage and filtration, reinforcement, and containment.
By end use: roads (paved and unpaved), railways, retaining walls, waterworks and waste treatment, landfill and erosion control, and others.
By region: highway agencies, landfill operators, water authorities and rail owners in North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do geomembranes lead geosynthetics sales by product type?
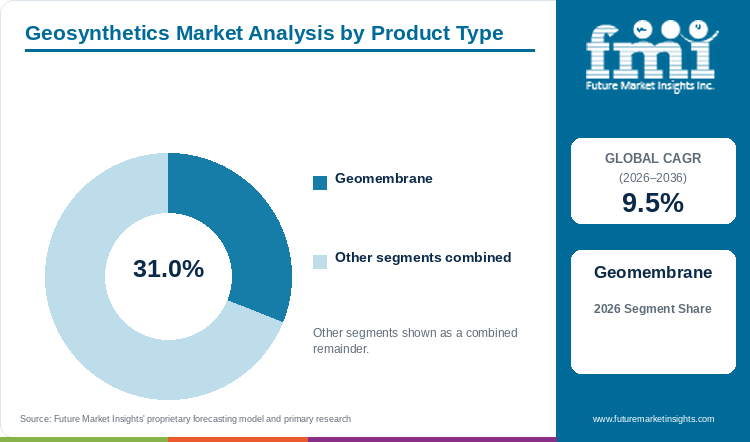
Geomembranes are expected to lead product type sales with 31% share in 2026, ahead of geotextiles at about 28.4% and geogrids at an estimated 15.2%.
Table 3: Product Type Share for the Geosynthetics Market (percentage share), 2026
| Product Type | Estimated Share (2026) |
|---|---|
| Geomembrane | 31% |
| Geotextile | 28.4% |
| Geogrid | 15.2% |
| Geocomposite | 9.6% |
| Geosynthetics Clay Liner | 6.3% |
| Geonet | 4.8% |
| Others | 4.7% |
| Total | 100.0% |
Table 4: Product Type Leadership and Market Growth for the Geosynthetics Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 9.5% |
| Leading Segment | Geomembrane |
A landfill cell or mine pond is lined wall to wall, so geomembranes are expected to lead with 31% of 2026 product type sales. Each square metre of membrane is thick, welded and tested, and the per-metre price is higher than for a fabric. Almost every road, wall and drain uses geotextiles as separators and filters, which gives the product about 28.4%. Geogrids, an estimated 15.2%, reinforce base courses and steep slopes. Drainage layers and secondary barriers account for the rest, split among geocomposites at 9.6%, geosynthetics clay liners at 6.3%, geonets at 4.8% and other products at 4.7%. Solmax began building a European geosynthetics center at Les Mureaux, France, in May 2026, bringing European nonwoven production onto one site.[8] Owners of new waste and water sites will keep membranes in the lead, and road agencies will keep fabric volume growing in step.
- Landfill, mining and water storage jobs use the bulk of HDPE and LLDPE geomembrane sheet.
- Officine Maccaferri bought nonwoven geotextile maker Ovattificio Alpino of Cittadella, Italy, in September 2026.[9]
Why does polypropylene lead geosynthetics sales by material type?
Polypropylene (PP) is projected to lead material type sales with 47% share in 2026, against an estimated 33.5% for polyethylene (HDPE/LLDPE) and about 13.2% for polyester.
Table 5: Material Type Share for the Geosynthetics Market (percentage share), 2026
| Material Type | Estimated Share (2026) |
|---|---|
| Polypropylene (PP) | 47% |
| Polyethylene (HDPE/LLDPE) | 33.5% |
| Polyester | 13.2% |
| Natural Fibers | 3.1% |
| Others | 3.2% |
| Total | 100.0% |
Nonwoven needle-punched fabrics, woven tapes and extruded grids all run on polypropylene, so PP is projected to supply 47% of material type sales in 2026. Polyethylene, an estimated 33.5%, is the resin of choice for liners, as HDPE resists chemicals and LLDPE bends over uneven ground. High-strength grids and woven reinforcement for walls and embankments run on polyester, near 13.2%. Jute and coir slope mats make up most of the 3.1% natural fiber share, and other materials hold 3.2%. Resin supply ties the two leading materials to the petrochemical cycle, and the polypropylene market grows at a projected 4.5% CAGR, half the geosynthetics pace. Converters will lock in resin contracts early to protect margin on long tenders.
- Nonwoven separators, woven tapes and extruded grids form the polypropylene core.
- Higher raw material costs weighed on Garware Technical Fibres in the June 2026 quarter, and the company passed them on to customers with some time lag.[2]
Why does containment lead geosynthetics sales by primary application?
Containment is estimated to lead primary application sales with 32.5% share in 2026, ahead of separation at about 24.8% and drainage and filtration at 22.6%.
Table 6: Primary Application Share for the Geosynthetics Market (percentage share), 2026
| Primary Application | Estimated Share (2026) |
|---|---|
| Containment | 32.5% |
| Separation | 24.8% |
| Drainage and Filtration | 22.6% |
| Reinforcement | 20.1% |
| Total | 100.0% |
Sealing waste, brine and water inside a lined cell gives containment an estimated 32.5% lead in 2026, and that share follows geomembrane and clay liner orders. Keeping road base stone apart from soft subgrade is the job of separation fabrics, about 24.8% of the split. Drainage and filtration, 22.6%, covers filter fabrics behind walls and drainage composites in landfills and tunnels. Geogrids and high-strength fabrics in embankments and walls make up reinforcement, an estimated 20.1%. Water and waste plants are the main containment buyers, and the water and wastewater treatment chemicals market is expected at a 4.6% CAGR, a reminder that new treatment lagoons add liner demand ahead of chemical dosing. Landfill and water owners will keep containment first.
- Landfill base and cap liners, mine ponds and reservoir linings make up most containment volume.
- The EPA allowed SRP to keep a clay-lined coal ash evaporation pond in July 2026, with a final demonstration report due in mid-2027.[6]
Why do roads lead geosynthetics sales by end use?
Roads (paved and unpaved) are likely to lead end use sales with 34.6% share in 2026, ahead of landfill and erosion control at an estimated 21.4% and waterworks and waste treatment at about 16.8%.
Table 7: End Use Share for the Geosynthetics Market (percentage share), 2026
| End Use | Estimated Share (2026) |
|---|---|
| Roads (Paved and Unpaved) | 34.6% |
| Landfill and Erosion Control | 21.4% |
| Waterworks and Waste Treatment | 16.8% |
| Railways | 11.2% |
| Retaining Walls | 9.5% |
| Others | 6.5% |
| Total | 100.0% |
Highway agencies specify fabric and grid on new lanes, haul roads and repairs, so roads (paved and unpaved) are likely to lead with 34.6% in 2026. An estimated 21.4% goes to landfill and erosion control, for liners, caps and slope mats. Waterworks and waste treatment, about 16.8%, lines reservoirs, canals and lagoons. Railways, 11.2%, use separators and grids under ballast, and the railway system market is forecast at a 4.4% CAGR, which keeps track renewal steady. Sports fields, tunnels and other uses hold 6.5%, just behind retaining walls at 9.5%. Road agencies will stay the largest single buyer group.
- Base stabilisation, pavement interlayers and haul road reinforcement make up most road volume.
- Deutsche Bahn plans over EUR 23 billion of network investment in 2026, with over half for the existing network, dpa reported.[7]
What are the drivers, restraints, and opportunities in the geosynthetics market?
Road, rail and water programmes keep demand for geosynthetics growing with public works budgets. Resin costs and regulatory flexibility on liners squeeze producers, and flood defence and disaster repair open new buyers.
- Driver: Each kilometre of new or rebuilt road, track or canal needs separation, filtration and reinforcement layers, so public works budgets turn directly into roll orders.
- Restraint: Polypropylene and polyethylene costs follow the oil cycle, and regulators sometimes accept natural clay in place of a plastic liner.
- Opportunity: Flood agencies and disaster repair teams need fast-installing mats, grids and barriers, which favours suppliers with stock near the work.
Public Works Budgets Turn Into Roll Orders
Demand for geosynthetics rises with the length of road, rail and canal under construction. Deutsche Bahn renewed nearly 2,300 km of track in 2025 and plans over EUR 23 billion of network investment in 2026.[7] China started 25 major water projects in the first half of 2026.[5] Every renewed formation and lined channel adds fabric, grid and liner orders.
Resin Costs and Liner Rules Squeeze Producers
Producers of geosynthetics carry resin as the largest cost line. Inflation from higher raw material costs weighed on the June 2026 quarter at Garware Technical Fibres, which passed the increase to customers with a delay.[2] Liner rules also flex, and SRP kept a clay liner at Coronado after showing 200 to 250 feet of natural clay beneath the pond.[6] FMI's model has membrane makers most exposed, since a single waiver can remove a multi-hectare order.
Flood Defence and Disaster Repair Open New Buyers
Climate repair adds a further source of growth for the geosynthetics market. England plans GBP 830 million for flood schemes within the 2026/27 programme.[4] Hawaii is due USD 81 million of the October 2026 federal relief for Kona Low storm damage.[1] Erosion mats, gabion fabrics and reinforced slopes are unlocking storm-season orders for liner and grid makers in flood and repair work.
Which country CAGRs are profiled in the geosynthetics market?
Table 8: Country CAGR Comparison for the Geosynthetics Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| India | 11.1% |
| China | 10.4% |
| United States | 10.1% |
| Germany | 9.6% |
| South Korea | 9.5% |
| Japan | 9.4% |
| United Kingdom | 9.2% |
How do country-level CAGRs compare in the geosynthetics market?
Road and canal builders in India are adding new expressways and irrigation channels every season. India leads FMI's country table at 11.1%, 1.6 points ahead of the 9.5% global CAGR, with China next on 10.4% as reservoirs and canals are lined. The United States, on 10.1%, is the largest single market, and storm repair now adds to the federal highway programme. German and South Korean rates of 9.6% and 9.5% mirror the global pace. Flood work and slope repair, in place of new roads, hold Japan to 9.4% and the United Kingdom to 9.2%, the two lowest rates.
- Expressway, irrigation and urban rail projects raise orders in India.
- Reservoir and canal lining under national water projects drives China.
- Federal highway funds and storm repair carry the United States.
- Track bed renewal by Deutsche Bahn supports Germany.
- Coastal land and road projects keep South Korea level with the global pace.
- River embankment and slope repair after heavy rain shape Japan.
- Flood defence schemes lead buying in the United Kingdom.
Full report country CAGRs cover: Two Asian markets above 10%, India and China, followed by the United States just above 10%, then Germany and South Korea within a tenth of the 9.5% global figure, with Japan and the United Kingdom completing the list, and other standard countries estimated by region.
Country-wise Analysis
India Geosynthetics Market Outlook (2026 to 2036)
Garware Technical Fibres, based in Pune, grew net sales 31.4% to INR 482.4 crore in the June 2026 quarter and said geosynthetics sustained strong growth.[2] Highway, irrigation and metro builders in India specify fabric and grid on more contracts each year, and an 11.1% CAGR is expected for India.
Key takeaway: Expressway and irrigation work keeps India first.
China Geosynthetics Market Outlook (2026 to 2036)
The Ministry of Water Resources reported RMB 515.1 billion of water construction investment over January to June 2026, with 25 major projects started, close to the number started in all of 2025.[5] Reservoir, canal and diversion projects on that scale need membrane and clay liner, which supports a 10.4% CAGR for China.
Key takeaway: Water conservancy projects drive China.
United States Geosynthetics Market Outlook (2026 to 2036)
Data center, energy and infrastructure construction raised Tensar profitability about 50% in fiscal 2026, Commercial Metals Company said.[3] Federal emergency relief of over USD 1.6 billion, announced in October 2026, adds repair work across 34 states.[1] Those orders support a 10.1% CAGR for the United States, just ahead of the global rate.
Key takeaway: Highway repair and site work for data centers carry the United States.
Germany Geosynthetics Market Outlook (2026 to 2036)
Deutsche Bahn is renewing heavily used corridors by the mid-2030s, starting with Frankfurt to Mannheim and Hamburg to Berlin, and plans over EUR 23 billion of network investment in 2026.[7] Each renewed formation uses separators and grids under ballast, giving Germany a 9.6% CAGR.
Key takeaway: Track renewal gives Germany steady orders.
South Korea Geosynthetics Market Outlook (2026 to 2036)
Road builders and reclamation contractors on the west coast use geotextile tubes, separators and drains to build on soft marine clay. On FMI's numbers, South Korea is projected to grow at 9.5%, level with the geosynthetics market, as port, road and industrial land projects continue.
Key takeaway: Soft-ground construction keeps South Korea at the global pace.
Japan Geosynthetics Market Outlook (2026 to 2036)
River authorities and road operators in Japan repair embankments and slopes after typhoons and heavy rain, using reinforced soil and drainage composites. The FMI outlook gives Japan a 9.4% CAGR, as repair work replaces most new road building.
Key takeaway: Disaster repair shapes Japan.
United Kingdom Geosynthetics Market Outlook (2026 to 2036)
The Environment Agency plans over GBP 1.4 billion of flood defence investment in 2026/27, including GBP 260 million for repair and maintenance of existing defences.[4] Embankments, revetments and erosion control on those schemes support a 9.2% CAGR for the United Kingdom, a little below the 9.5% global CAGR.
Key takeaway: Flood defence leads the United Kingdom.
Who are the notable companies in the geosynthetics market?
Solmax, Tensar, HUESKER, NAUE, AGRU, Officine Maccaferri, Garware Technical Fibres, Geofabrics Australasia, Global Synthetics, Polyfabrics Australasia and Enviro Geosynthetics are the profiled companies.
FMI profiles membrane makers, reinforcement specialists and regional fabric suppliers. Tensar closed fiscal 2026 with profitability up about 50%, Commercial Metals Company reported in October 2026.[3] Officine Maccaferri added in-house nonwoven capacity with Ovattificio Alpino and plans a US expansion by mid-2027.[9] At Les Mureaux, France, Solmax is building one European center for manufacturing, laboratory and sales.[8] HUESKER, NAUE, AGRU, Garware Technical Fibres, Geofabrics Australasia, Global Synthetics, Polyfabrics Australasia and Enviro Geosynthetics complete the group.
- Geomembrane and liner makers: Solmax, AGRU and NAUE.
- Reinforcement and geogrid specialists: Tensar, HUESKER and Officine Maccaferri.
- Regional fabric suppliers: Garware Technical Fibres, Geofabrics Australasia, Global Synthetics, Polyfabrics Australasia and Enviro Geosynthetics.
Competitive Benchmarking: Geosynthetics Market
Table 9: Competitive Benchmarking for the Geosynthetics Market (qualitative documentation ratings), 2026
| Company | Containment Liners | Reinforcement Products | Regional Plant Footprint | Recency |
|---|---|---|---|---|
| Solmax | High | Medium | High | High |
| Tensar | Low | High | Medium | High |
| Officine Maccaferri | Low | High | High | High |
| Garware Technical Fibres | Medium | Medium | Low | High |
| HUESKER | Medium | High | Medium | Low |
The grades reflect how fully each company reported on each column during 2025 and 2026 and say nothing about share.
Key Developments in the Geosynthetics Market
- On 19 October 2026, the U.S. Department of Transportation announced over USD 1.6 billion of emergency relief for disaster-damaged roads and bridges.[1]
- On 15 October 2026, Commercial Metals Company reported fiscal 2026 results, with Tensar profitability up about 50%.[3]
- On 3 September 2026, Officine Maccaferri acquired 100% of Ovattificio Alpino, a maker of nonwoven geotextiles and technical felts.[9]
- On 5 August 2026, Garware Technical Fibres put Q1 FY27 net sales at INR 482.4 crore.[2]
- On 24 July 2026, KJZZ reported that the EPA let SRP keep a clay liner on the Coronado coal ash pond.[6]
- On 24 July 2026, the Ministry of Water Resources in China said 25 major water projects started in the first half.[5]
- On 5 May 2026, building work started on the Solmax geosynthetics center at Les Mureaux, France.[8]
- In March 2026, the Environment Agency confirmed over GBP 1.4 billion for flood defences in 2026/27.[4]
- In December 2025, Deutsche Bahn set network investment for 2026 at over EUR 23 billion.[7]
Key Players in the Geosynthetics Market
Geomembrane and Liner Makers
- Solmax
- AGRU
- NAUE
Reinforcement and Geogrid Specialists
- Tensar
- HUESKER
- Officine Maccaferri
Regional Fabric Suppliers
- Garware Technical Fibres
- Geofabrics Australasia
- Global Synthetics
- Polyfabrics Australasia
- Enviro Geosynthetics
Geosynthetics Market - Report Scope
Table 10: Report Scope for the Geosynthetics Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; material type; primary application; end use; region |
| Quantitative units | USD billion |
| Market definition | Polymer and natural fiber sheets, fabrics, grids, nets, composites and clay liners placed in soil, rock or water to separate, filter, drain, reinforce or contain in roads, railways, walls, water works, landfills and erosion control. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | Solmax, Tensar, HUESKER, NAUE, AGRU, Officine Maccaferri, Garware Technical Fibres, Geofabrics Australasia, Global Synthetics, Polyfabrics Australasia, Enviro Geosynthetics |
| Forecast period | 2026 to 2036 |
Geosynthetics Market - Research Methodology
Table 11: Research Methodology for the Geosynthetics Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Transport and water ministry releases, company results and filings, regulator decisions and trade press from May 2025 onward. |
| Desk Research | Desk research covers road and rail renewal, water conservancy, flood defence, landfill liner rules and resin costs. |
| Market Sizing and Forecasting | Sizing starts from the 2026 base of USD 20.0 billion and the 9.5% CAGR for 2026 to 2036. |
| Data Validation | Funding, investment and company figures were checked against the release, filing or article that first carried them. |
Geosynthetics Market by Segments
Geosynthetics Market segmented by Product Type:
- Geotextile
- Geomembrane
- Geogrid
- Geonet
- Geocomposite
- Geosynthetics Clay Liner
- Others
Geosynthetics Market segmented by Material Type:
- Polyethylene (HDPE/LLDPE)
- Polypropylene (PP)
- Polyester
- Natural Fibers
- Others
Geosynthetics Market segmented by Primary Application:
- Separation
- Drainage and Filtration
- Reinforcement
- Containment
Geosynthetics Market segmented by End Use:
- Roads (Paved and Unpaved)
- Railways
- Retaining Walls
- Waterworks and Waste Treatment
- Landfill and Erosion Control
- Others
Geosynthetics Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Department of Transportation. (2026, October 19). Trump's Department of Transportation Secretary Sean P. Duffy Announces Over $1.6 Billion in Emergency Rescue Funds to Repair State Roads and Bridges Damaged by Natural Disasters Across U.S. https://www.transportation.gov/briefing-room/trumps-department-transportation-secretary-sean-p-duffy-announces-over-16-billion
- [2] Garware Technical Fibres Ltd. (2026, August 5). Garware Technical Fibres declares consolidated net profit before tax to Rs. 86.4 Cr in Q1FY27 (press release, NSE filing). https://nsearchives.nseindia.com/corporate/GARFIBRES_05082026161742_PressRelease05082026.pdf
- [3] Commercial Metals Company (PR Newswire). (2026, October 15). CMC Reports Fourth Quarter and Full Year Fiscal 2026 Results. https://www.prnewswire.com/news-releases/cmc-reports-fourth-quarter-and-full-year-fiscal-2026-results-302909411.html
- [4] Water Magazine. (2026, March 20). £1.4bn flood investment unleashed to protect homes and businesses. https://www.watermagazine.co.uk/2026/03/20/1-4bn-flood-investment-unleashed-to-protect-homes-and-businesses/
- [5] Science and Technology Daily. (2026, July 24). Ministry of Water Resources: 25 major water projects newly started nationwide in the first half, investment completed above RMB 500 billion (in Chinese). https://www.stdaily.com/web/gdxw/2026-07/24/content_553204.html
- [6] KJZZ. (2026, July 24). EPA reverses course on coal ash pond requirement at SRP's Coronado Generating Station. https://www.kjzz.org/business/2026-07-24/epa-reverses-course-on-coal-ash-pond-requirement-at-srps-coronado-generating-station
- [7] Schwäbische (dpa). (2025, December 28). Bahn will 2026 mehr als 23 Milliarden Euro ins Netz stecken. https://www.schwaebische.de/wirtschaft/bahn-will-2026-mehr-als-23-milliarden-euro-ins-netz-stecken-4224922
- [8] Solmax. (2026, May 5). Solmax begins construction of flagship European geosynthetics center in Les Mureaux. https://www.solmax.com/us/en/news/solmax-begins-construction-of-flagship-european-geosynthetics-center-in-les
- [9] Ambienta SGR. (2026, September 3). Officine Maccaferri expands geosynthetics offering with acquisition of Ovattificio Alpino. https://ambientasgr.com/news/officine-maccaferri-expands-geosynthetics-offering-with-acquisition-of-ovattificio-alpino
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the geosynthetics market during 2026?
- What market size is projected by 2036?
- Which product type holds notable share?
- Which material type holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the geosynthetics market expected in 2026?
The geosynthetics market is expected to reach USD 20.0 billion in 2026 in FMI's numbers, up from USD 18.3 billion in 2025, and sales of geosynthetics are projected at USD 49.7 billion by 2036.
What CAGR is projected for the geosynthetics market through 2036?
Sales of geosynthetics are projected to grow at a 9.5% CAGR between 2026 and 2036. Road repair, water projects and flood defence carry that growth.
Which product type holds a notable market share in 2026?
Geomembranes are expected to lead with 31% share in 2026. Geotextiles follow at about 28.4%.
Which material type holds a notable market share in 2026?
Polypropylene (PP) is projected to lead with 47% share. Polyethylene (HDPE/LLDPE) follows at an estimated 33.5%.
Which country has a notable expansion outlook through 2036?
India, at 11.1%, is first in FMI's country table. China follows at 10.4%.
Who are the key companies in the geosynthetics market?
Solmax, AGRU and NAUE lead the liner group, and Tensar, HUESKER and Officine Maccaferri lead reinforcement. Garware Technical Fibres, Geofabrics Australasia, Global Synthetics, Polyfabrics Australasia and Enviro Geosynthetics complete the profiled companies.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Geotextile
- Geomembrane
- Geogrid
- Geonet
- Geocomposite
- Geosynthetics Clay Liner
- Others
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Material Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material Type, 2026 to 2036
- Polyethylene (HDPE/LLDPE)
- Polypropylene (PP)
- Polyester
- Natural Fibers
- Others
- Y-o-Y Growth Trend Analysis By Material Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Type, 2026 to 2036
- Global Market Analysis and Forecast, By Primary Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Primary Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Primary Application, 2026 to 2036
- Separation
- Drainage and Filtration
- Reinforcement
- Containment
- Y-o-Y Growth Trend Analysis By Primary Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Primary Application, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Roads (Paved and Unpaved)
- Railways
- Retaining Walls
- Waterworks and Waste Treatment
- Landfill and Erosion Control
- Others
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Material Type
- By Primary Application
- By End Use
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Solmax
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Tensar
- Officine Maccaferri
- Garware Technical Fibres
- HUESKER
- AGRU
- NAUE
- Geofabrics Australasia
- Global Synthetics
- Polyfabrics Australasia
- Enviro Geosynthetics
- Solmax
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


