
- Market Size (2026)
- USD 5,192.4 Mn
- Forecast (2036)
- USD 8,953.7 Mn
- CAGR (2026 to 2036)
- 5.6%
How big is Rail Wheel and Axle Market in 2026?
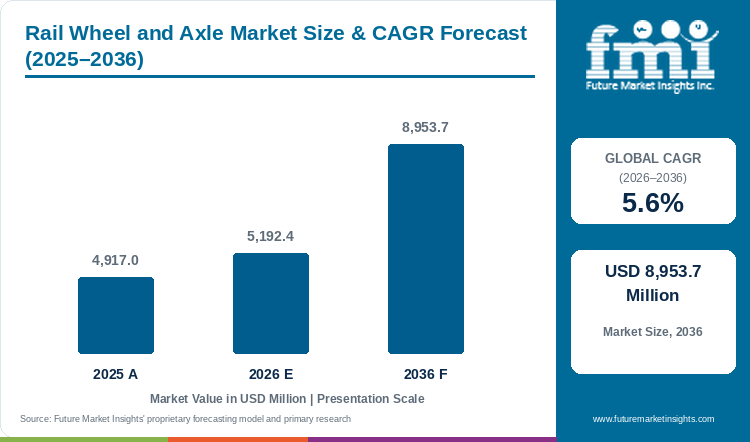
Sales of rail wheels and axles will grow at a CAGR of 5.6% from 2026 to 2036. The 2025 base stood at USD 4,917.0 million. Market size for 2026 is estimated at USD 5,192.4 million, and the 2036 figure is projected to reach USD 8,953.7 million.
Demand for rail wheels and axles is estimated at USD 5,192.4 million in 2026, up from USD 4,917.0 million in 2025. FMI's report projects USD 8,953.7 million by 2036, a 5.6% CAGR between 2026 and 2036.
Every new car from the rolling stocks market, on a 3.9% CAGR from 2026 to 2036, leaves the plant on new wheelsets. Wheelsets grow faster as fleets reorder worn wheels long after delivery, so aftermarket work fills presses between car programmes. Bogie overhauls renew sliding bearings next to wheelsets, and the railway sliding bearing market posts a 5.1% CAGR over the same years, so wheel makers will quote both parts as one bogie package.
Alstom ended fiscal 2025/26 with a backlog of €104.4 billion, yet car output fell 2% to 4,284 cars. Alstom guided 2026/27 production to 4,400 to 4,500 cars, so wheelset call-offs will rise. OEM channels, an estimated 61.4% of 2026 sales, will feel higher Alstom output first.
Wheel makers will face long forge and machining queues in peak build years. The segment mix is changing, since heavy-haul freight wheels for North America and India will share presses with passenger programmes. Operators will therefore weigh refurbished sets against new monoblock wheels, which hold an estimated 46.2% of wheel type sales.
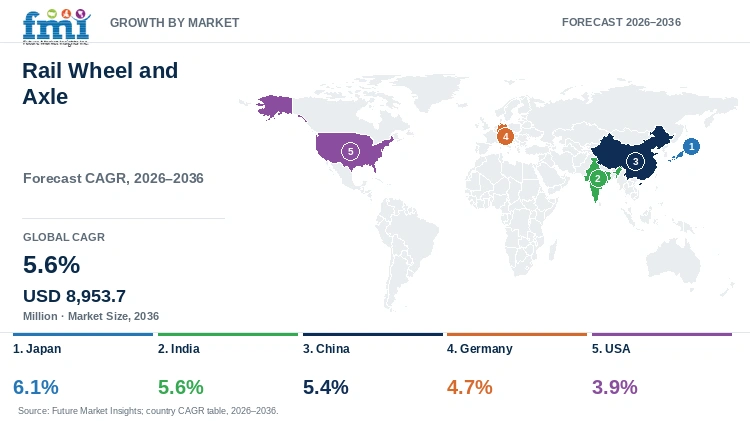
Japan leads profiled countries at 6.1%, India keeps pace with the global 5.6%, and the USA has the slowest CAGR at 3.9%.
Key Market Trends & Insights
- Monoblock designs headed wheel type sales in 2026 with an estimated 46.2%, and steel tyred wheels followed at about 18.7%.
- Roller axles carried an estimated 52.8% of axle type sales in 2026, with solid axles near 31.6% and hollow axles near 15.6% (both estimated). The roller axle segment posts a 5.4% CAGR. Nippon Steel says hollow axles save about 50 kg each.
- High-speed railway was the biggest end use in 2026 at 43.5%, with subway use next at an estimated 24.8%.
- OEM channels supplied an estimated 61.4% in 2026, and the aftermarket took about 38.6%. Greenbrier reported a backlog of 13,800 new railcars with an estimated value of $2.0 billion at 31 May 2026.
Regional Highlights
- Fastest-growing profiled country: Japan (6.1% CAGR, 2026 to 2036).
- By country: India comes second at 5.6% and China third at 5.4%, Germany posts 4.7%, and the USA closes the table at 3.9%.
- China put 363.2 billion yuan into railway fixed assets in January to June 2026, a rise of 2.1%, and opened 355.2 km of new line.
Market Size & Forecast
Table 1: Market Size and Forecast for the Rail Wheel and Axle Market (USD million and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 4,917.0 million |
| Estimated Market Size in 2026 | USD 5,192.4 million |
| Projected Market Size by 2036 | USD 8,953.7 million |
| CAGR, 2026 to 2036 | 5.6% |
| Added Revenue, 2026 to 2036 | USD 3,761.3 million |
| Market Expansion Multiple | 1.7x |
Rail wheels and railway sliding bearings grow at two different rates. FMI places the rail wheel and axle CAGR at 5.6%, and the railway sliding bearing market moves at a 5.1% CAGR for 2026 to 2036. Makers in the railway bearing market gain from smart monitoring and from the roller axle designs that lead axle type sales. Wheel and axle makers gain from the sheer count of new cars, metro sets and freight wagons now on order books.
Forge Capacity and Order Books Behind Wheelset Supply
Train and wagon order books at Siemens, Greenbrier and Jupiter stretch years ahead of forge output. Siemens reported Mobility orders of €7.6 billion in the third quarter of fiscal 2026, including €2.2 billion for double-deck trains in Switzerland. Greenbrier held 13,800 railcars in backlog at 31 May 2026 after taking orders for 2,200 units in the quarter. Jupiter Wagons closed fiscal 2026 with a consolidated order book of ₹4,675 crore, and the wheel subsidiary took orders spanning freight wagons, LHB coaches, metro applications and Vande Bharat trains. Each railcar and train car on order at those three builders needs a full set of wheels and axles before delivery. Metro and Vande Bharat orders at the Jupiter wheel subsidiary build the commercial case for emerging applications beyond freight wagons.
New wheel capacity comes from two named projects, the GHH-BONATRANS plant in New York and the Jupiter plant in Odisha. GHH-BONATRANS plans to invest up to $93 million in a wheelset and axle plant in Wayland, New York, with operations planned for late 2028. Jupiter expects production at the Odisha wheel facility to start in phases over the coming years. Nippon Steel makes about 1,000 wheels a day at the Kansai Works Osaka District, the only plant in Japan that makes railway wheels and axles. Indian Railways will supply 152,800 metric tonnes of wheel, tyre and axle scrap to the Rail Wheel Factory in Yelahanka and the Rail Wheel Plant in Bela in fiscal 2026-27. The Wayland plant opens in late 2028, so Nippon Steel and other incumbents with running presses will hold pricing power until 2028.
Table 2: Production Capacity and Rolling-Stock Backlog Indicators for the Rail Wheel and Axle Market (units, currency and tonnes), 2025 to 2028
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Alstom backlog, 31 March 2026 | €104.4 billion; 4,284 cars produced in fiscal 2025/26 | Car output sets OEM wheelset call-offs. | |
| Alstom production guidance, fiscal 2026/27 | 4,400 to 4,500 cars | A higher build rate raises wheelset needs. | |
| Siemens Mobility orders, third quarter of fiscal 2026 | €7.6 billion | Large train contracts add future wheelset demand. | |
| Greenbrier new railcar backlog, 31 May 2026 | 13,800 units; estimated $2.0 billion | Freight car builds draw on heavy-haul wheels and axles. | |
| Jupiter Wagons order book, fiscal 2026 | ₹4,675 crore | Wheel subsidiary orders span wagons, coaches, metro and Vande Bharat. | |
| GHH-BONATRANS Wayland plant | Up to $93 million; operations planned for late 2028 | First North American plant for the group. | |
| Nippon Steel Kansai Works Osaka District | About 1,000 wheels a day; over 300 wheel types | Sole domestic wheel and axle source in Japan. | |
| Indian Railways WTA scrap supply, fiscal 2026-27 | 152,800 metric tonnes | Scrap feeds in-house wheel factories. |
Analyst Perspective
“My view is that forge capacity will decide market share through 2036, since rolling-stock backlogs already run years ahead of wheelset output. Makers that add press lines close to train builders in India, the USA and Europe will secure the long-term OEM contracts first.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the rail wheel and axle market segmented?
The rail wheel and axle market divides into wheel type, axle type, end use and sales channel, and region. Monoblock wheels hold an estimated 46.2% of wheel type sales in 2026. High-speed railway leads end use at 43.5%, and roller axles and OEM supply head the other splits at estimated shares of 52.8% and 61.4%.
By wheel type: monoblock wheels, resilient wheels, rubber tyred wheels, steel tyred wheels, and other special wheels.
By axle type: hollow axles, solid axles, and roller axles.
By end use: high-speed railway, fast speed railway, subway, and other end use.
By sales channel: OEM and aftermarket.
By region: rail demand is tracked in seven regions, from North America and Latin America to Western Europe and Eastern Europe, with East Asia, South Asia, and Middle East and Africa completing the set.
Why do monoblock wheels lead wheel type sales?
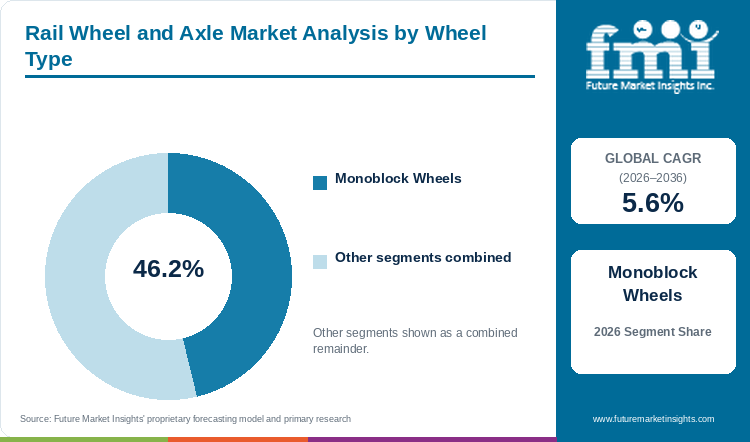
Monoblock wheels make up an estimated 46.2% of wheel type sales in 2026, with steel tyred wheels second at about 18.7%.
Table 3: Wheel Type Share for the Rail Wheel and Axle Market (percentage share), 2026
| Wheel Type | Estimated Share (2026) |
|---|---|
| Monoblock Wheels | 46.2% |
| Steel Tyred Wheels | 18.7% |
| Resilient Wheels | 15.4% |
| Rubber Tyred Wheels | 11.3% |
| Other Special Wheels | 8.4% |
| Total | 100.0% |
Table 4: Wheel Type Leadership and Market Growth for the Rail Wheel and Axle Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.6% |
| Leading Segment | Monoblock Wheels |
Nippon Steel forges wheels on a 10,000-ton hydraulic press after heating steel to about 1,200°C, Mynavi News reported in December 2025. Single-piece forging on the 10,000-ton press suits high-speed and freight duty. Steel tyred wheels add a separate tyre to replace at overhaul. Monoblock wheels hold an estimated 46.2%, steel tyred wheels about 18.7% and resilient wheels about 15.4%. Rubber tyred wheels, estimated at 11.3%, and resilient wheels serve trams and metro lines that need noise damping. Other special wheels make up an estimated 8.4%. Operators will keep one monoblock design across fleets to simplify inspection.
- Steel tyred and resilient wheels form the second tier of wheel types.
- Nippon Steel produces over 300 wheel types at the Osaka plant.
Why do roller axles lead axle type sales?
Roller axles take an estimated 52.8% of 2026 axle type sales, ahead of solid axles at about 31.6% and hollow axles at about 15.6%.
Table 5: Axle Type Share for the Rail Wheel and Axle Market (percentage share), 2026
| Axle Type | Estimated Share (2026) |
|---|---|
| Roller Axles | 52.8% |
| Solid Axles | 31.6% |
| Hollow Axles | 15.6% |
| Total | 100.0% |
Rail car fleets use roller axles widely, and approval from the Association of American Railroads (AAR) keeps the design on freight specifications. FMI data show a 5.4% CAGR for roller axles. Roller axles hold an estimated 52.8%, ahead of solid axles at about 31.6%. Sealing systems and simple handling give roller designs the edge over solid axles on freight duty. Hollow axles, estimated at 15.6%, save about 50 kg per axle and suit high-speed sets. Bearing upgrades in the locomotive drive shaft market and related running gear will keep roller axles ahead of solid and hollow axles.
- Solid and hollow axles form the second and third tiers behind roller designs.
- Hollow axles save about 50 kg each at Nippon Steel.
Why does high-speed railway lead end use sales?
High-speed railway carries a 43.5% end use share in 2026, and subway use follows at an estimated 24.8%.
Table 6: End Use Share for the Rail Wheel and Axle Market (percentage share), 2026
| End Use | Estimated Share (2026) |
|---|---|
| High-Speed Railway | 43.5% |
| Subway | 24.8% |
| Fast Speed Railway | 19.6% |
| Other End Use | 12.1% |
| Total | 100.0% |
Operators of high-speed lines buy wheelsets on tight tolerance and short reprofiling cycles, and that tight-tolerance buying keeps high-speed railway ahead of subway use. On FMI figures, high-speed railway holds 43.5% in 2026. Subway takes an estimated 24.8% and fast speed railway about 19.6%. China runs a high-speed network above 40,000 km, and European corridors add cross-border routes. Subway demand comes from metro growth in Asian cities. Siemens booked €0.6 billion for long-term service of battery-powered trains in Germany in the third quarter of fiscal 2026. Other end uses make up an estimated 12.1%.
- Subway and fast speed railway rank behind high-speed use.
- Siemens booked €2.2 billion for double-deck trains in Switzerland.
Why does OEM supply lead sales channel sales?
OEM buyers absorb an estimated 61.4% of channel sales in 2026, leaving about 38.6% to the aftermarket.
Table 7: Sales Channel Share for the Rail Wheel and Axle Market (percentage share), 2026
| Sales Channel | Estimated Share (2026) |
|---|---|
| OEM | 61.4% |
| Aftermarket | 38.6% |
| Total | 100.0% |
Limited forge time goes first to new-build contracts, which carry volume and long terms. OEM supply therefore holds an estimated 61.4% of the channel split, and the aftermarket covers about 38.6%. Greenbrier delivered 3,600 railcars in the third quarter of fiscal 2026 and calls itself a leading provider of freight railcar wheel services in North America. Aftermarket buyers want reprofiling, wheelset overhaul and spare sets near the depot. Work in the railway maintenance machinery market supports aftermarket reprofiling and overhaul.
- Aftermarket sales come from replacement, reprofiling and overhaul.
- Greenbrier delivered 3,600 units in the quarter to 31 May 2026.
What are the drivers, restraints, and opportunities in the rail wheel and axle market?
Key trends in the rail wheel and axle market include lightweight alloys, smart monitoring and localized production hubs. Sales potential is expected to emerge from metro programmes, freight modernization and after-sales service contracts.
- Driver: High-speed and metro construction, freight fleet renewal and replacement of ageing wheelsets raise order volumes.
- Restraint: High manufacturing cost, precision engineering needs and budget limits in developing regions slow purchases.
- Opportunity: Local plants near train builders, lightweight designs and wheelset service contracts widen margins.
Network Building in Asia Expands Wheelset Volume
Railway fixed-asset investment in China totalled 363.2 billion yuan in the first half of 2026, China State Railway Group said. New lines covering 355.2 km entered service in the same period. FMI cites metro and long-distance rail budgets in India, China and Indonesia among the main drivers. Each of the 355.2 new km needs trains, and each train adds wheelsets to OEM orders.
Cost of Precision Manufacturing Holds Back Smaller Buyers
GHH-BONATRANS plans up to $93 million for one new plant in New York, with up to 85 jobs. A $93 million budget for one plant shows the cost of entering wheelset production. Precision engineering, specialized steel and quality control raise unit costs for every maker. Budget limits in developing regions will delay some purchases and push buyers toward cheaper imports.
Localized Plants Near Builders Open Supply Contracts
Jupiter Wagons signed a supply agreement with Tatravagonka covering substantial wheelset requirements from the Odisha facility. Captive offtake from Tatravagonka lowers risk for the new Odisha plant. Seat, interior and running gear suppliers in the train seat market follow the same train build schedules as wheel makers. Wheel makers that co-locate with car builders will lock in multi-year volume.
Which country CAGRs are profiled in the rail wheel and axle market?
Table 8: Country CAGR Comparison for the Rail Wheel and Axle Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| Japan | 6.1% |
| India | 5.6% |
| China | 5.4% |
| Germany | 4.7% |
| USA | 3.9% |
How do country-level CAGRs compare in the rail wheel and axle market?
Japan is the only profiled country above the global rate. FMI ranks Japan first at 6.1% from 2026 to 2036, with India level with the global 5.6% and China at 5.4%. Germany is next on 4.7%, with the USA last on 3.9%. Among the countries setting the growth agenda, quality-led replacement in Japan and network building in India and China outpace mature freight demand in the USA.
- Japan joins strict rail quality standards with a single domestic wheel maker.
- India pairs in-house wheel factories with private forged wheel plants.
- China links a 40,000 km high-speed network with continued line openings.
- Germany combines rail engineering exports with service contracts for battery trains.
- The USA ties the largest freight rail system to railcar backlogs.
Full report country CAGRs cover: South Asia; North America; East Asia; Eastern Europe; Western Europe; Middle East and Africa; Latin America.
Country-wise Analysis
Japan Rail Wheel and Axle Market Outlook (2026 to 2036)
Strict rail quality standards give Japan the highest profiled growth, a 6.1% CAGR over the decade. Nippon Steel calls itself the only domestic maker of railway wheels, including those for the Shinkansen. The Osaka plant also exports wheels to North America and Europe. A single domestic source gives JR operators stable specifications, and export lines add volume to the same presses.
Key takeaway: Japanese growth runs through one supplier, so capacity at Osaka sets the ceiling for domestic and export orders.
India Rail Wheel and Axle Market Outlook (2026 to 2036)
Indian Railways will route 152,800 metric tonnes of wheel, tyre and axle scrap to the Yelahanka and Bela wheel plants in fiscal 2026-27, ThePrint reported in June 2026. Eastern, South Central and Northern Railway carry the largest zone quotas. Private capacity is rising alongside, with Jupiter building a wheel facility in Odisha. India's 5.6% CAGR for 2026 to 2036 equals the global figure.
Key takeaway: India mixes state factories and new private plants, and scrap supply will set the output ceiling for the state factories.
China Rail Wheel and Axle Market Outlook (2026 to 2036)
Domestic producers such as Taiyuan Heavy Industry serve a high-speed network above 40,000 km, and policy favours local manufacturing. Chinese sales grow at 5.4% CAGR through 2036. Investment in railway fixed assets rose 2.1% to 363.2 billion yuan over January to June 2026. The Belt and Road Initiative adds export routes for Chinese rolling stock and for the wheelsets fitted under those trains.
Key takeaway: Chinese demand stays inside a domestic supply chain, which limits access for foreign wheel makers.
Germany Rail Wheel and Axle Market Outlook (2026 to 2036)
GHH-BONATRANS and Lucchini RS lead the German supplier base, backed by rail engineering skills and an export-oriented industry. GHH-BONATRANS runs operations in the Czech Republic and Germany. Siemens secured a €0.6 billion contract for long-term service of battery-powered trains in Germany in the third quarter of fiscal 2026. Germany posts 4.7% CAGR from 2026 to 2036, with high-speed and urban transit investment as the main levers.
Key takeaway: German makers grow through exports and service work, and the new US plant extends that reach across the Atlantic.
USA Rail Wheel and Axle Market Outlook (2026 to 2036)
Growth in the USA is the weakest of the five profiled countries at 3.9% CAGR, FMI finds. Greenbrier reported new railcar orders for 2,200 units and a 13,800-unit backlog for the quarter to 31 May 2026. Amsted Rail leads domestic manufacturing for a freight network above 140,000 miles. GHH-BONATRANS will add a wheelset and axle plant in Steuben County, with operations planned for late 2028.
Key takeaway: US sales follow freight car builds, and a second domestic wheelset plant from 2028 will give railcar builders more sourcing choice.
Who are the notable companies in the rail wheel and axle market?
Key companies in this market are Nippon Steel Corporation, GHH-BONATRANS, Amsted Rail, Lucchini RS Group, Vyksa Steel Works (OMK Group), EVRAZ NTMK, CAF USA, Kolowag, Taiyuan Heavy Industry and Interpipe.
Tier 1 producers with revenue above USD 100 million hold 50% to 60% of global sales, and FMI groups Nippon Steel, GHH-BONATRANS, Amsted Rail, Lucchini RS, Vyksa Steel Works and EVRAZ NTMK in that tier. Small, local and largely unorganized players make up Tier 2.
Product work at Nippon Steel and GHH-BONATRANS centres on lighter and quieter wheelsets. Nippon Steel partnered with a European rail operator in May 2024 on lightweight, high-strength wheels and axles, and GHH-BONATRANS launched noise-reducing urban transit wheels in April 2024. GHH-BONATRANS announced a Wayland, New York plant in April 2026, the first for the group in North America.
- Tier 1 wheel and axle producers: Nippon Steel Corporation, GHH-BONATRANS, Amsted Rail, Lucchini RS Group, Vyksa Steel Works (OMK Group), and EVRAZ NTMK.
- Regional and rolling-stock linked suppliers: CAF USA, Kolowag, and Interpipe.
- China-focused producer: Taiyuan Heavy Industry Co., Ltd.
- Builders and buyers with large 2025 to 2026 backlogs: Alstom, Siemens Mobility, Greenbrier, and Jupiter Wagons.
Competitive Benchmarking: Rail Wheel and Axle Market
Table 9: Competitive Benchmarking for the Rail Wheel and Axle Market (qualitative documentation ratings), 2026
| Company | Capacity Data | Order Visibility | New Plant Activity | Disclosure |
|---|---|---|---|---|
| Nippon Steel Corporation | High | Low | Low | Medium |
| GHH-BONATRANS | Low | Low | High | Medium |
| Jupiter Wagons | Medium | High | High | High |
| Greenbrier | Low | High | Low | High |
| Alstom | Medium | High | Low | High |
Ratings grade dated capacity, order and plant activity and imply no ranking by share or quality.
Key Developments in the Rail Wheel and Axle Market
- In August 2026, Siemens reported Mobility orders of €7.6 billion for the third quarter of fiscal 2026.
- In July 2026, China State Railway Group put January to June investment in railway fixed assets at 363.2 billion yuan.
- In July 2026, Greenbrier reported a new railcar backlog of 13,800 units.
- In June 2026, the Railway Board set 152,800 metric tonnes of wheel, tyre and axle scrap supply for fiscal 2026-27.
- In June 2026, Jupiter Wagons reported a consolidated order book of ₹4,675 crore for fiscal 2026.
- In May 2026, Alstom reported a backlog of €104.4 billion and guided to 4,400 to 4,500 cars for fiscal 2026/27.
- In April 2026, GHH-BONATRANS announced a wheelset plant in Wayland, New York, with investment of up to $93 million.
- In December 2025, Mynavi News reported that the Nippon Steel Osaka plant makes about 1,000 wheels a day.
Key Players in the Rail Wheel and Axle Market
Tier 1 Wheel and Axle Producers
- Nippon Steel Corporation
- GHH-BONATRANS
- Amsted Rail
- Lucchini RS Group
- Vyksa Steel Works (OMK Group)
- EVRAZ NTMK
Regional and Rolling-Stock Linked Suppliers
- CAF USA
- Kolowag
- Interpipe
China-Focused Producer
- Taiyuan Heavy Industry Co., Ltd.
Builders and Buyers with Large 2025 to 2026 Backlogs
- Alstom
- Siemens Mobility
- Greenbrier
- Jupiter Wagons
Rail Wheel and Axle Market - Report Scope
Table 10: Report Scope for the Rail Wheel and Axle Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Wheel type; axle type; end use; sales channel; region |
| Quantitative units | USD million |
| Market definition | Railway wheels and axles, covering monoblock, resilient, rubber tyred, steel tyred and special wheels and hollow, solid and roller axles for high-speed, fast speed, subway and other rail use, sold to OEMs and the aftermarket. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia; Middle East and Africa |
| Countries covered | Japan; India; China; Germany; USA |
| Key companies profiled | Nippon Steel Corporation, GHH-BONATRANS, Amsted Rail, CAF USA, Lucchini RS Group, Kolowag, Vyksa Steel Works (OMK Group), EVRAZ NTMK, Taiyuan Heavy Industry, Interpipe |
| Forecast period | 2026 to 2036 |
Rail Wheel and Axle Market - Research Methodology
Table 11: Research Methodology for the Rail Wheel and Axle Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Capacity and backlog facts come from company results, government releases and trade press dated May 2025 or later. |
| Desk Research | Desk research covers train builder backlogs, railcar orders, wheel plant announcements, railway investment and wheel factory inputs. |
| Market Sizing and Forecasting | Sizing starts from the 2025 base of USD 4,917.0 million and the 5.6% CAGR. |
| Data Validation | Backlog and plant figures come from builder results and plant announcements, set against railway ministry data for China and India. |
Rail Wheel and Axle Market by Segments
Rail Wheel and Axle Market segmented by Wheel Type:
- Monoblock Wheels
- Resilient Wheels
- Rubber Tyred Wheels
- Steel Tyred Wheels
- Other Special Wheels
Rail Wheel and Axle Market segmented by Axle Type:
- Hollow Axles
- Solid Axles
- Roller Axles
Rail Wheel and Axle Market segmented by End Use:
- High-Speed Railway
- Fast Speed Railway
- Subway
- Other End Use
Rail Wheel and Axle Market segmented by Sales Channel:
- OEM
- Aftermarket
Rail Wheel and Axle Market by Region
- North America
- USA
- Latin America
- Western Europe
- Germany
- Eastern Europe
- East Asia
- China
- Japan
- South Asia
- India
- Middle East and Africa
Research Sources and Bibliography
- [1] Alstom. (2026, May 13). Alstom's Fiscal Year 2025/26 Results. https://www.alstom.com/press-releases-news/2026/5/alstoms-fiscal-year-202526-results
- [2] Mynavi News (Nippon Steel PR). (2025, December 8). https://news.mynavi.jp/kikaku/20251208-3430742/
- [3] The Greenbrier Companies. (2026, July 1). Greenbrier Reports Third Quarter Results. https://pressroom.gbrx.com/2026-07-01-Greenbrier-Reports-Third-Quarter-Results
- [4] Xinhua via english.gov.cn. (2026, July 17). China's railway fixed-asset investment up 2.1 pct in first half. https://english.www.gov.cn/archive/statistics/202607/17/content_WS6a5a0875c6d00ca5f9a0c45e.html
- [5] Siemens AG. (2026, August 6). Siemens Q3 fiscal 2026 earnings release. https://assets.new.siemens.com/siemens/assets/api/uuid:84d1a90b-542e-4775-a907-06f29940eb71/HQCOPR202608037434EN.pdf
- [6] The Machine Maker. (2026, June 6). Jupiter Wagons Strengthens Growth with Mobility Expansion. https://themachinemaker.com/news/jupiter-wagons-strengthens-growth-with-mobility-expansion/
- [7] Office of the Governor of New York. (2026, April 30). Governor Hochul Announces Railway Industry Manufacturer GHH-BONATRANS to Establish First North American Facility. https://www.governor.ny.gov/news/governor-hochul-announces-railway-industry-manufacturer-ghh-bonatrans-establish-first-north
- [8] ThePrint (PTI). (2026, June 23). Railway Board directs zones to send scrapped wheels to factories for 2026-27 production targets. https://theprint.in/india/railway-board-directs-zones-to-send-scrapped-wheels-to-factories-for-2026-27-production-targets/2967892/
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- What will rail wheel and axle market size be in 2026?
- What size will the market reach by 2036?
- Which wheel type will hold the largest share?
- Which end use will lead sales?
- Which countries will grow fastest?
- Which companies will supply rail wheels and axles?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Wheel Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Wheel Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Wheel Type, 2026 to 2036
- Monoblock Wheels
- Resilient Wheels
- Rubber Tyred Wheels
- Steel Tyred Wheels
- Other Special Wheels
- Y-o-Y Growth Trend Analysis By Wheel Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Wheel Type, 2026 to 2036
- Global Market Analysis and Forecast, By Axle Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Axle Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Axle Type, 2026 to 2036
- Hollow Axles
- Solid Axles
- Roller Axles
- Y-o-Y Growth Trend Analysis By Axle Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Axle Type, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End Use, 2026 to 2036
- High-Speed Railway
- Fast Speed Railway
- Subway
- Other End Use
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- OEM
- Aftermarket
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- By Wheel Type
- By Axle Type
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Wheel Type
- By Axle Type
- By End Use
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Wheel Type
- By Axle Type
- By End Use
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Wheel Type
- By Axle Type
- By End Use
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- By Wheel Type
- By Axle Type
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Wheel Type
- By Axle Type
- By End Use
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Wheel Type
- By Axle Type
- By End Use
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Wheel Type
- By Axle Type
- By End Use
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- By Wheel Type
- By Axle Type
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Wheel Type
- By Axle Type
- By End Use
- By Sales Channel
- Key Takeaways
- South Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- By Wheel Type
- By Axle Type
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Wheel Type
- By Axle Type
- By End Use
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Wheel Type
- By Axle Type
- By End Use
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Wheel Type
- By Axle Type
- By End Use
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Wheel Type
- By Axle Type
- By End Use
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Wheel Type
- By Axle Type
- By End Use
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Wheel Type
- By Axle Type
- By End Use
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Wheel Type
- By Axle Type
- By End Use
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Wheel Type
- By Axle Type
- By End Use
- By Sales Channel
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Wheel Type
- By Axle Type
- By End Use
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Nippon Steel Corporation
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- GHH-BONATRANS
- Jupiter Wagons
- Greenbrier
- Alstom
- Amsted Rail
- Lucchini RS Group
- Vyksa Steel Works (OMK Group)
- EVRAZ NTMK
- CAF USA
- Kolowag
- Interpipe
- Taiyuan Heavy Industry Co., Ltd.
- Siemens Mobility
- Nippon Steel Corporation
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Wheel Type, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Axle Type, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 5: Global Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 6: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Wheel Type, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by Axle Type, 2021 to 2036
- Table 9: North America Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 10: North America Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 11: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Million) Forecast by Wheel Type, 2021 to 2036
- Table 13: Latin America Market Value (USD Million) Forecast by Axle Type, 2021 to 2036
- Table 14: Latin America Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 15: Latin America Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 16: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Million) Forecast by Wheel Type, 2021 to 2036
- Table 18: Western Europe Market Value (USD Million) Forecast by Axle Type, 2021 to 2036
- Table 19: Western Europe Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 20: Western Europe Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Million) Forecast by Wheel Type, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Million) Forecast by Axle Type, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 26: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Million) Forecast by Wheel Type, 2021 to 2036
- Table 28: East Asia Market Value (USD Million) Forecast by Axle Type, 2021 to 2036
- Table 29: East Asia Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 30: East Asia Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 31: South Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 32: South Asia Market Value (USD Million) Forecast by Wheel Type, 2021 to 2036
- Table 33: South Asia Market Value (USD Million) Forecast by Axle Type, 2021 to 2036
- Table 34: South Asia Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 35: South Asia Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Million) Forecast by Wheel Type, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Million) Forecast by Axle Type, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Wheel Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Wheel Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Wheel Type
- Figure 6: Global Market Value Share and BPS Analysis by Axle Type, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Axle Type, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Axle Type
- Figure 9: Global Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End Use
- Figure 12: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Sales Channel
- Figure 15: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Wheel Type, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Wheel Type, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Wheel Type
- Figure 29: North America Market Value Share and BPS Analysis by Axle Type, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Axle Type, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Axle Type
- Figure 32: North America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by End Use
- Figure 35: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Sales Channel
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Wheel Type, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Wheel Type, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Wheel Type
- Figure 42: Latin America Market Value Share and BPS Analysis by Axle Type, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Axle Type, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Axle Type
- Figure 45: Latin America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by End Use
- Figure 48: Latin America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Sales Channel
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Wheel Type, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Wheel Type, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Wheel Type
- Figure 55: Western Europe Market Value Share and BPS Analysis by Axle Type, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by Axle Type, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by Axle Type
- Figure 58: Western Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by End Use
- Figure 61: Western Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Sales Channel
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Wheel Type, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Wheel Type, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Wheel Type
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by Axle Type, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by Axle Type, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by Axle Type
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by End Use
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by Sales Channel
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Wheel Type, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Wheel Type, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Wheel Type
- Figure 81: East Asia Market Value Share and BPS Analysis by Axle Type, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by Axle Type, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by Axle Type
- Figure 84: East Asia Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by End Use
- Figure 87: East Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by Sales Channel
- Figure 90: South Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia Market Value Share and BPS Analysis by Wheel Type, 2026 and 2036
- Figure 92: South Asia Market Y-o-Y Growth Comparison by Wheel Type, 2026-2036
- Figure 93: South Asia Market Attractiveness Analysis by Wheel Type
- Figure 94: South Asia Market Value Share and BPS Analysis by Axle Type, 2026 and 2036
- Figure 95: South Asia Market Y-o-Y Growth Comparison by Axle Type, 2026-2036
- Figure 96: South Asia Market Attractiveness Analysis by Axle Type
- Figure 97: South Asia Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 98: South Asia Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 99: South Asia Market Attractiveness Analysis by End Use
- Figure 100: South Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 101: South Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 102: South Asia Market Attractiveness Analysis by Sales Channel
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by Wheel Type, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by Wheel Type, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by Wheel Type
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by Axle Type, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by Axle Type, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by Axle Type
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by End Use
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by Sales Channel
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the rail wheel and axle market expected in 2026?
FMI expects market size of USD 5,192.4 million in 2026. The projection for 2036 will be USD 8,953.7 million.
What CAGR is projected for the rail wheel and axle market through 2036?
Sales growth will average a 5.6% CAGR through 2036. The €104.4 billion backlog at Alstom and new Chinese rail lines will drive the 5.6% CAGR.
Which wheel type holds a notable market share in 2026?
Monoblock wheels will hold an estimated 46.2% of wheel type sales in 2026, ahead of steel tyred wheels at about 18.7%.
Which end use holds a notable market share in 2026?
High-speed railway will remain the top end use with 43.5% in 2026. Subway use will rank second at an estimated 24.8%.
Which country has a notable expansion outlook through 2036?
Japan will post the top profiled CAGR of 6.1% over 2026 to 2036, per FMI. India will follow with a 5.6% CAGR.
Who are the key companies in the rail wheel and axle market?
Tier 1 suppliers will include Nippon Steel, GHH-BONATRANS, Amsted Rail, Lucchini RS, Vyksa Steel Works and EVRAZ NTMK. CAF USA, Kolowag, Taiyuan Heavy Industry and Interpipe will also compete.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
