
- Market Size (2026)
- USD 4.9 Bn
- Forecast (2036)
- USD 17.7 Bn
- CAGR (2026 to 2036)
- 13.7%
How big is Silicon Anode Battery Market in 2026?
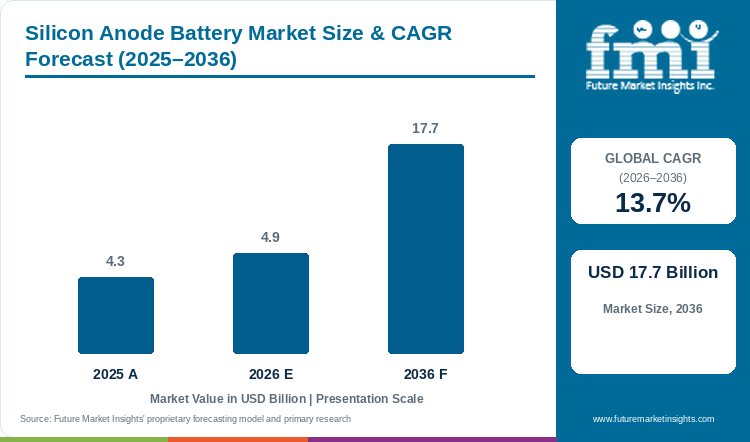
The silicon anode battery market demonstrated steady progress from USD 4.3 billion in 2025 to USD 4.9 billion in 2026, building toward a targeted valuation of USD 17.7 billion by 2036 at a CAGR of 13.7%.
As per FMI, the silicon anode battery industry valuation starts at USD 4.3 billion in 2025 and reaches USD 4.9 billion in 2026. Global market size attains USD 17.7 billion by 2036 under a 13.7% CAGR, delivering USD 12.8 billion in ten-year expansion that outstrips conventional graphite anode demand. Cell makers favor drop-in composite powders compatible with standard slurry coaters, and a 2025 Nanomaterials study confirmed Si/hard-carbon composites synthesized from phenolic resin maintain competitive specific capacity across sustained cycling. That cycle stability steers gigafactory orders toward silicon-graphite composite Si-C, holding 58.4% of 2026 architecture demand when paired with elastic silicon anode binder polymers. Even so, particle swelling during deep cycling and high silane gas costs restrain entry-level EV adoption.
Key Market Trends & Insights
- By anode material architecture: Based on anode material architecture, silicon-graphite composite Si-C is projected to account for 58.4% in 2026, driven by drop-in wet-slurry roll-to-roll coater compatibility.
- By cell format: By cell format, pouch cells are estimated to hold 44.8% in 2026, supported by laminate enclosures that tolerate controlled stack pressure.
- By capacity class: In 2026, above 3000 mAh cells are expected to lead capacity class with 61.2% share, owing to high-energy traction packs and AI smartphones.
- By end-use application: By end-use application, electric vehicles and e-mobility are forecast to represent 54.6% in 2026, attributable to 10-to-80% fast-charging OEM targets.
- By secondary sub-segments: Cylindrical 21700 and 4680 formats and silicon oxide blend SiOx powders expand as automotive pack engineers balance calendar life against gravimetric energy density.
Regional Highlights
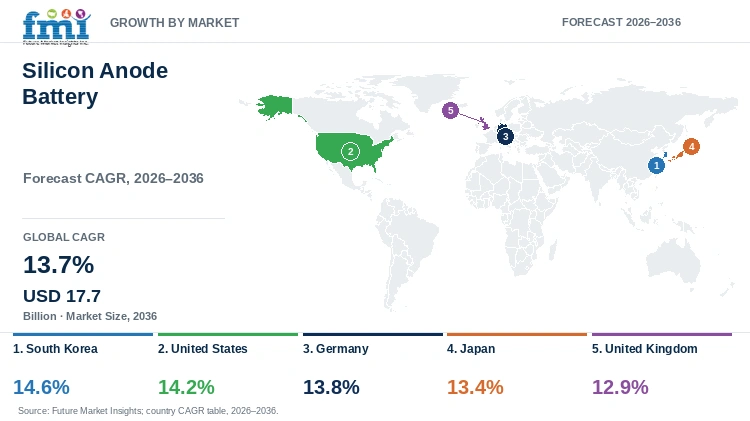
- Top national expansion: South Korea leads country-level battery growth with a 14.6% CAGR to 2036 on commercial CVD silicon-carbon powder factories and tier-one cell production.
- Broader country progression: Battery demand in the United States climbs at a 14.2% CAGR while Germany grows at 13.8% ahead of Japan (13.4%) and the United Kingdom (12.9%).
Market Size & Forecast
Table 1: Market Size and Forecast for the Silicon Anode Battery Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 4.3 billion |
| Estimated Market Size in 2026 | USD 4.9 billion |
| Projected Market Size by 2036 | USD 17.7 billion |
| CAGR, 2026 to 2036 | 13.7% |
| Added Market Value, 2026 to 2036 | USD 12.8 billion |
Battery cell manufacturers face severe electrode delamination and electrolyte dry-out when unbuffered silicon particles expand threefold during lithium insertion. Continuous solid-electrolyte interphase cracking consumes active lithium inventory and degrades pack cycle life below automotive warranty thresholds. An October 2025 Micromachines study demonstrated high-strength and high-modulus silicon monoxide anodes supporting high-energy-density fast-charging cells. Consequently, cell engineering teams blend porous carbon scaffolds with high-capacity silicon anode powders to buffer particle strain without sacrificing volumetric energy density.
Active Anode Powder Tonnage and Cell Output Sizing
Table 2: Active Silicon Anode Material Tonnage and Cell Capacity Sizing for the Silicon Anode Battery Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 4.3 | 4.9 | 17.7 |
| Active Si-C & SiOx anode material shipped (thousand metric tons) | 38.0 to 44.0 | 46.0 to 53.0 | 240.0 to 285.0 |
| Silicon-containing battery cell output (GWh) | 68.0 to 78.0 | 82.0 to 95.0 | 480.0 to 560.0 |
| Reversible anode specific capacity range (mAh/g) | 525 to 988 | 612 to 1,568 | 800 to 2,400 |
Operational note: Material sizing models reconcile gigafactory Si-C and SiOx powder blending ratios (5 wt% to 55 wt%) against automotive and consumer GWh cell shipments.
Parasitic gas suppression across high-silicon electrodes requires passivating active particle surfaces before aqueous slurry mixing. A July 2025 Polymers study showed a tannic-acid functionalized dual-network binder stabilizing silicon anodes at high specific capacity. Cell manufacturers also apply engineered anode surface coatings to stabilize the solid-electrolyte interphase and boost first-cycle Coulombic efficiency above 88%.
Gigafactory Line Allocation & EV Pack Sizing
Table 3: Per GWh and Gigafactory Allocation Indicators for the Silicon Anode Battery Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Commercial silicon anode & cell lines globally | 42 | 50 | 165 |
| Average cell gravimetric energy density (Wh/kg) | 285 to 340 | 300 to 380 | 360 to 500 |
| Benchmark cycle life to 80% capacity (cycles) | 500 to 800 | 800 to 1,500 | 1,500 to 2,000 |
| Initial Coulombic efficiency benchmark (%) | 82.0% to 85.4% | 85.4% to 88.5% | 90.0% to 94.0% |
Table 4: Cell Format and End-Use Allocation Indicators for the Silicon Anode Battery Market (USD and percentages), 2026
| Metric | Value | Cell & Gigafactory Reference Basis |
|---|---|---|
| Market size, 2026 | USD 4.9 billion | 2026 global market value baseline |
| Silicon-Graphite Composite Si-C share, 2026 | 58.4% | Leading anode material architecture in 2026 |
| Pouch Cells share, 2026 | 44.8% | Leading cell format segment in 2026 |
| Above 3000 mAh share, 2026 | 61.2% | Leading capacity class segment in 2026 |
High shear stress at the copper current collector interface during repeated lithiation cycles causes anode coating peel-off and impedance spikes. A February 2025 Polymers review confirmed high-performance polymer binders advance molecular design for durable silicon-based anodes. Electrode production engineers apply conductive anode foil primers onto 6-micron copper foils to prevent active layer delamination.
Analyst Perspective
"Automotive and consumer battery buyers evaluate silicon anode platforms on calendar-life gas suppression and drop-in gigafactory slurry compatibility. Material suppliers delivering porous carbon-silicon composites that cycle past 1,000 charges without special cell enclosures capture multi-GWh automotive supply agreements."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the silicon anode battery market segmented?
The silicon anode battery market is segmented by four primary commercial axes and region: anode material architecture, cell format, capacity class, and end-use application. In 2026, silicon-graphite composite Si-C is projected at 58.4%, pouch cells is estimated at 44.8%, above 3000 mAh is expected at 61.2%, and electric vehicles and e-mobility is forecast at 54.6%.
By anode material architecture: silicon-graphite composite Si-C (58.4% in 2026), silicon oxide blend SiOx, and pure nano-structured silicon and nanowires.
By cell format: pouch cells (44.8% in 2026), cylindrical 21700 and 4680 cells, and prismatic cells.
By capacity class: above 3000 mAh (61.2% in 2026), 1500 mAh to 3000 mAh, and below 1500 mAh.
By end-use application: electric vehicles and e-mobility (54.6% in 2026), consumer electronics and wearables, aerospace, drones, and defense, and grid and stationary storage.
By technology pathway: drop-in CVD silicon-carbon composites, prelithiated SiOx blends, and 3D-interdigitated nanowire cell architectures.
Why does silicon-graphite composite Si-C lead anode material architecture demand?
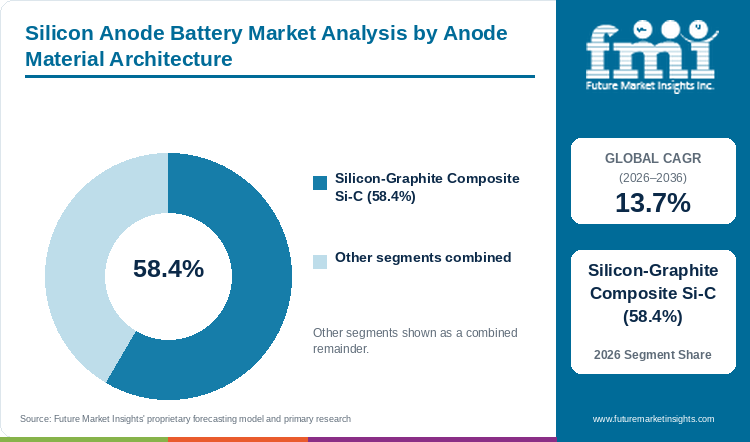
Based on anode material architecture, silicon-graphite composite Si-C is projected to account for 58.4% in 2026, driven by slurry compatibility.
Table 5: Anode Material Architecture Share for the Silicon Anode Battery Market (percentage share), 2026
| Anode Material Architecture | Share (2026) |
|---|---|
| Silicon-Graphite Composite Si-C | 58.4% |
| Silicon Oxide Blend SiOx & Pure Nano-Structured Silicon and Nanowires | 41.6%* |
| Total | 100.0% |
*Note: Remaining anode material architecture categories sum to 100.0% of 2026 silicon anode battery demand.
Table 6: Anode Material Architecture Leadership and Market Growth for the Silicon Anode Battery Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 13.7% |
| Leading Segment | Silicon-Graphite Composite Si-C (58.4% in 2026) |
In the FMI report, tier-one battery producers favor Si-C composite powders because microporous carbon matrices absorb internal silicon expansion in water-based slurries. A January 2026 Materials study demonstrated ternary doping and structural disorder advance fast-charging capability in silicon anodes. Formulators pair Si-C composites with aqueous electrode binder formulations to keep cell swelling below 8%.
- Silicon-graphite composite Si-C secures 58.4% of anode material architecture demand in 2026 via drop-in gigafactory processing.
- A February 2026 Materials study showed three-dimensional graphene hosting stabilizes aqueous silicon deposition for fast-charging anodes.
What supports pouch cells as a preferred choice in cell format?
By cell format, pouch cells are estimated to hold 44.8% in 2026, supported by external stack-pressure control in EVs.
Laminated aluminum-polymer pouch enclosures enable external spring-plate compression fixtures in automotive modules and internal architectural constraints in compact consumer cells. Cell assemblers pair high-tensile polyolefin battery separator films with pouch stacks to prevent short circuits under mechanical swelling stress.
- Pouch cells command 44.8% of the cell format segment in 2026 across electric vehicle modules and aviation packs plus smartphones.
- A June 2025 Materials study showed biomass-derived hard carbon hosts blended with commercial silicon support high-capacity lithium-ion anodes.
How are above 3000 mAh formats gaining use in capacity class?
In 2026, above 3000 mAh cells are expected to lead capacity class with 61.2% share, owing to EV pack demand.
Automotive traction cells (ranging from 5 Ah 21700 cylinders to 100+ Ah EV pouches) and 5,500+ mAh flagship smartphone batteries require high-capacity formats. Cell designers coat separator interfaces with acrylic separator coating binders to maintain laminated stack alignment across large-format electrodes.
- Above 3000 mAh cells hold 61.2% of the capacity class category in 2026 as EV and smartphone capacities rise.
- A September 2025 Advanced Science study demonstrated MoO3-x incorporated covalent organic framework nanocomposites as advanced silicon anode materials.
Why are buyers selecting electric vehicles and e-mobility in end-use application?
By end-use application, electric vehicles and e-mobility is forecast to represent 54.6% in 2026, attributable to fast-charging OEM roadmaps.
Global automakers integrate 5 wt% to 20 wt% silicon-carbon composites into nickel-rich NMC and NCMA cells to extend driving range past 600 kilometers and cut DC fast-charging times to 12 minutes. Two-wheeler and commercial delivery fleets also adopt silicon-boosted cylindrical cells.
- Electric vehicles and e-mobility capture 54.6% of end-use application share during 2026 under fast-charge powertrain roadmaps.
- A December 2025 Nanomaterials study showed graphene additions improve the performance of silicon-carbon composite anode materials.
Which market conditions keep SiOx blends and nanowires relevant across architectures?
Silicon oxide blend SiOx and nanowires complement the 58.4% silicon-graphite composite Si-C share in 2026 across aviation and EV packs.
While silicon-graphite composite Si-C captures 58.4% of 2026 architecture demand, silicon oxide blend SiOx offers superior calendar life through in-situ lithium silicate buffer domains. Pure nano-structured silicon and nanowires serve unmanned aerial vehicles and defense platforms needing 400 to 500 Wh/kg.
- SiOx blends and pure silicon nanowires address long-calendar-life EV packs and high-gravimetric-energy aerospace platforms beyond the 58.4% Si-C leader.
- A May 2025 Polymers study showed rice-husk-derived SiOx/graphite composites reached 988.2 mAh/g and retained 545.1 mAh/g after 500 cycles.
What are the drivers, restraints, and opportunities in the silicon anode battery market?
In the silicon anode battery market, the key driver is EV fast charging, the key restraint is cyclic swelling, and the key opportunity is CVD carbon scaffolds.
- Driver: Automotive 15-minute fast-charging targets and on-device AI smartphone power consumption drive cell makers to replace pure graphite with silicon-carbon anodes.
- Restraint: High silane gas precursor costs and low first-cycle Coulombic efficiency in unprelithiated SiOx plus cyclic electrode swelling restrain entry-level vehicle adoption.
- Opportunity: Scalable fluidized-bed CVD silicon-carbon reactors and roll-to-roll prelithiation plus fluoroethylene carbonate electrolytes enable 1,500-cycle automotive durability.
Fast-Charging EV Roadmaps and Electrolyte Stabilization Drivers
Electric vehicle buyers demand 10-to-80% fast charging in 10 to 15 minutes without lithium plating on the anode surface during winter operation. Silicon-carbon composite anodes raise working potential slightly above metallic lithium deposition thresholds while boosting volumetric capacity above 700 Wh/L. As noted by FMI, cell manufacturers pair composite anodes with fluorinated lithium battery electrolytes rich in fluoroethylene carbonate to form elastic LiF-rich interphase films. A January 2026 Nanomaterials study showed incorporating sub-nanometer tin particles into SiOx activated Li2SiO3 phases to reach 85.4% initial Coulombic efficiency and 89.4% retention over 350 cycles. Reduced irreversible first-cycle lithium loss cuts cathode over-sizing costs for pack assemblers. Automakers lock in multi-year offtake contracts for CVD silicon-carbon powders to secure domestic supply.
Volumetric Swelling and Silane Precursor Cost Friction
Particle pulverization and severe calendar-life impedance rise plus silane gas feedstock bottlenecks represent the primary commercial hurdles slowing high-silicon adoption. When silicon weight fractions exceed 15% in conventional slurry electrodes, repeated volume expansion fractures conductive carbon bridges and isolates active islands. A February 2025 Materials study demonstrated that self-terminating alkanethiol electrodeposition structured thickened silicon electrodes to achieve 84% retention after 200 cycles at 2,400 mAh/g. Without controlled nano-structuring, cyclic swelling delaminates electrode coatings from copper foils within 100 charges. Cell pack engineers must also integrate specialized pressure sensors and cell-level battery management electronics to track state-of-health across swelling pouch modules. High capital expenditure for chemical vapor deposition reactors further keeps silicon anode $/kWh costs above natural graphite.
Carbon Nanotube Scaffolds and Pack Controller Opportunities
Anode material producers capture premium margins by combining single-walled carbon nanotube conductive networks with elastic polymeric binders and upcycled silicon feedstocks. Cross-linked polyurethane and polyacrylic acid networks replace rigid PVDF to preserve electrical percolation across thick high-loading electrodes. Pack integrators also deploy automotive traction pack controllers programmed with multi-stage constant-current fast-charge algorithms tailored to silicon phase transitions. An April 2026 Polymers study showed thermoplastic polyurethane reinforced SWCNT networks in Si/C anodes to raise tensile strength by 210% and maintain 91.2% capacity retention after 300 cycles. Mechanical reinforcement prevents electrode cracking during high-rate automotive regenerative braking. Pre-dispersed Si-C masterbatches paired with matched SWCNT slurries accelerate cell-maker qualification.
Silicon Anode Battery Market by Country (2026 to 2036)
FMI research indicates that South Korea tops silicon anode battery expansion with a 14.6% CAGR through 2036 above the United States (14.2%). Battery demand in Germany posts 13.8% CAGR while Japan records 13.4% and the United Kingdom reaches 12.9%.
Table 7: Country CAGR and Primary Growth Levers for the Silicon Anode Battery Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| South Korea | 14.6% | Sangju BAM-3 CVD silicon-carbon factory scale-up and tier-one EV gigafactory integration |
| United States | 14.2% | Moses Lake Titan Silicon plant commissioning, IRA domestic material credits, and defense drone cells |
| Germany | 13.8% | Luxury OEM fast-charging EV programs, domestic silane precursor capacity, and functional binder R&D |
| Japan | 13.4% | 4680 cylindrical automotive cell commercialization and low-swelling SiOx anode production |
| United Kingdom | 12.9% | Aerospace, defense, and motorsport pouch-cell stack pressure and swelling management systems |
Source: Future Market Insights analysis
South Korea Silicon Anode Battery Market Outlook (2026 to 2036)
South Korea anchors global silicon anode commercialization through tier-one cell makers (LG Energy Solution and Samsung SDI plus SK On) and commercial Si-C and SiOx powder plants in Sangju and Pohang. A July 2025 Nanomaterials study from university researchers in South Korea demonstrated upcycling photovoltaic silicon waste into Si-graphite anodes delivering 612 mAh/g with 88.5% retention after 200 cycles. That upcycling pathway lowers raw silicon feedstock costs while satisfying domestic circular-economy battery rules. Through 2036, South Korea battery adoption is forecast to climb at a 14.6% CAGR as domestic gigafactories scale CVD silicon-carbon blending across EV pouch and cylindrical lines. High imported silane gas prices still pressure powder margins, prompting domestic chemical groups to co-locate monosilane synthesis near anode reactors.
Key takeaway: In South Korea, commercial CVD silicon-carbon plants in Sangju and tier-one EV cell lines fuel 14.6% CAGR expansion to 2036.
United States Silicon Anode Battery Market Outlook (2026 to 2036)
In November 2025, Sila Nanotechnologies progressed commissioning of its Moses Lake, Washington Titan Silicon plant designed to supply 2 to 5 GWh of automotive anode capacity. That commercial plant ramp-up addresses domestic battery material localization mandates and defense aviation electrification across Washington State and California. Silicon anode battery demand in the United States is anticipated to climb at a 14.2% CAGR through 2036, aided by Section 45X manufacturing tax credits and UAV cell contracts. Automotive qualification of drop-in nanocomposite powders across gigafactories still requires 24-month cycle-life validation. Domestic anode producers mitigate qualification delays by supplying pre-blended Si-C active powders engineered for standard domestic gigafactory slurry coaters.
Key takeaway: In the United States, commercial anode plant commissioning in Washington State and defense drone demand sustain 14.2% CAGR growth through 2036.
Germany Silicon Anode Battery Market Outlook (2026 to 2036)
Premium automakers in Germany (including Mercedes-Benz and Porsche plus BMW) lead European adoption of silicon-rich anodes to achieve 10-minute fast charging and high volumetric pack density. Domestic chemical groups and cell research clusters focus on aqueous binder chemistry and roll-to-roll prelithiation plus silane precursor production in Burghausen. An October 2026 Nanomaterials study validated stress-relieving crosslinked binders and prelithiation engineering in high-loading Si-graphite pouch cells over 600 cycles. In Germany, silicon anode battery demand is forecast to expand at a 13.8% CAGR through 2036 on luxury EV powertrain platforms transitioning to silicon-dominant chemistry. High industrial electricity rates in Germany inflate CVD reactor operating costs, compelling suppliers to optimize lower-temperature fluidized-bed deposition.
Key takeaway: In Germany, luxury EV fast-charging programs and domestic silane and binder manufacturing support 13.8% CAGR expansion to 2036.
Japan Silicon Anode Battery Market Outlook (2026 to 2036)
Japan commands a foundational position in cylindrical automotive cells and low-swelling silicon oxide (SiOx) anode materials produced by domestic chemical and ceramics leaders. In October 2025, Panasonic Energy detailed mass-production readiness for its high-capacity 4680 cylindrical automotive cells delivering fivefold capacity over 21700 formats. Mass production of 4680 cylindrical formats requires low-swelling SiOx-graphite co-blends that prevent jelly-roll bucking inside rigid steel cans. Adoption of silicon anode batteries in Japan is estimated to expand at 13.4% CAGR through 2036, fueled by cylindrical 21700 and 4680 gigafactories raising silicon weight fractions. First-cycle irreversible lithium trapping in SiOx remains a technical hurdle, so material makers in Japan integrate thermal magnesium and lithium pre-doping lines.
Key takeaway: In Japan, cylindrical 4680 cell production and high-purity SiOx anode manufacturing power 13.4% CAGR growth through 2036.
United Kingdom Silicon Anode Battery Market Outlook (2026 to 2036)
Motorsport electrification and defense unmanned systems plus Faraday Battery Challenge research consortia shape silicon anode commercialization across the United Kingdom. Battery engineering teams in the United Kingdom specialize in multi-physics swelling diagnostics and pouch-cell stack pressure control plus silicon-carbon scaffold synthesis for high-power packs. A September 2026 Batteries study demonstrated multi-physics swelling diagnostics and optimized external stack pressure extended silicon-dominant pouch cell cycle life by 38%. Across the United Kingdom, the silicon anode battery sector is projected to achieve a 12.9% CAGR to 2036 through aerospace and defense plus high-performance automotive pack programs. Limited domestic multi-GWh cell manufacturing capacity constrains commodity EV volume, so UK suppliers focus on high-margin defense and aviation cells.
Key takeaway: In the United Kingdom, aerospace and motorsport battery engineering and pouch swelling control deliver 12.9% CAGR progress to 2036.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the silicon anode battery market?
Sila Nanotechnologies Inc., Enovix Corporation, Group14 Technologies Inc., Amprius Technologies Inc., and Panasonic Energy Co. Ltd. are the notable companies in the silicon anode battery market.
According to FMI competitive research, rivalry in the silicon anode battery sector splits between drop-in CVD silicon-carbon powder producers and 100%-active silicon cell manufacturers plus global cylindrical cell conglomerates. Drop-in material specialists supply porous carbon-silicon powders that run on existing gigafactory slurry lines, whereas specialized cell makers engineer proprietary nanowire or 3D-constrained cell architectures.
- Drop-In Nanocomposite Silicon-Carbon Material Producers: Sila Nanotechnologies Inc. and Group14 Technologies Inc. supply drop-in nanocomposite silicon-carbon powders for automotive and consumer battery gigafactories.
- Complete Silicon-Anode Cell & Pack Manufacturers: Enovix Corporation and Amprius Technologies Inc. manufacture complete silicon-anode pouch cells for AI smartphones and smart eyewear plus defense aviation.
- Global Automotive Cylindrical & EV Cell Platforms: Panasonic Energy Co. Ltd. integrates silicon-composite anodes into high-capacity 21700 and 4680 cylindrical cells for electric vehicle powertrains.
Competitive Benchmarking: Silicon Anode Battery Market
Table 8: Competitive Benchmarking for the Silicon Anode Battery Market (qualitative capability ratings), 2026
| Company | Si-C / SiOx Material Breadth | Cell Energy & Cycle Depth | Gigafactory & OEM Access | Geographic Reach |
|---|---|---|---|---|
| Sila Nanotechnologies Inc. | High | High | High | Medium |
| Enovix Corporation | Medium | High | High | High |
| Group14 Technologies Inc. | High | High | High | High |
| Amprius Technologies Inc. | High | High | High | Medium |
| Panasonic Energy Co. Ltd. | Medium | High | High | High |
Scoring basis: High, Medium, and Low capability ratings evaluate documented Si-C and SiOx material breadth, cell gravimetric energy and fast-charge cycle depth, gigafactory and OEM qualification activity, and multi-region manufacturing reach. A rating is not a quality or market-share ranking.
Key Developments in the Silicon Anode Battery Market
- In August 2026, Group14 Technologies Inc. acquired 100% ownership of its BAM-3 silicon battery factory in Sangju, South Korea to supply SCC55 directly to EV and consumer cell lines.
- In August 2026, Enovix Corporation posted Q2 2026 company-reported revenue of USD 9.0 million (up 21% YoY) on sustained silicon-anode cell shipments.
- In May 2026, Amprius Technologies Inc. generated USD 26.4 million in Q1 2026 company-reported revenue (up 133% YoY) with a 24% gross margin across 58 aviation and defense customers.
Key Players in the Soft-Diet Clinical Meal Market
Drop-In Nanocomposite Silicon-Carbon Material Producers
- Sila Nanotechnologies Inc.
- Group14 Technologies Inc.
Complete Silicon-Anode Cell & Pack Manufacturers
- Enovix Corporation
- Amprius Technologies Inc.
Global Automotive Cylindrical & EV Cell Platforms
- Panasonic Energy Co. Ltd.
Silicon Anode Battery Market - Report Scope
Table 9: Report Scope for the Silicon Anode Battery Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | By Anode Material Architecture; By Cell Format; By Capacity Class; By End-Use Application |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial lithium-ion battery cells and active anode material systems incorporating Silicon-Graphite Composite Si-C, Silicon Oxide Blend SiOx, or Pure Nano-Structured Silicon and Nanowires. Category Scope Note: Excludes 100% pure natural or synthetic graphite cells without silicon additions and lead-acid or sodium-ion cells. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | South Korea, United States, Germany, Japan, United Kingdom, and additional countries in the full report |
| Key Companies Covered | Sila Nanotechnologies Inc., Enovix Corporation, Group14 Technologies Inc., Amprius Technologies Inc., Panasonic Energy Co. Ltd. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Silicon Anode Battery Market - Research Methodology
Table 10: Research Methodology for the Silicon Anode Battery Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with manufacturers, suppliers, distributors, automotive battery cell engineers, CVD silicon-carbon plant directors, and UAV power system integrators across the value chain to validate 1,000-cycle swelling protocols, demand trends, and purchasing decisions. |
| Secondary Research | Secondary research included SEC 10-K and 10-Q filings from Amprius and Enovix, Group14 and Sila technical disclosures, Panasonic 4680 publications, peer-reviewed electrochemical studies in PubMed Central, and publicly available sources relevant to the market. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 forecast period were developed using top-down and bottom-up approaches to assess GWh cell demand, active Si-C and SiOx metric ton capacities, and OEM qualification trends. Segment shares and forecast estimates are proprietary analytical estimates. |
| Data Triangulation and Validation | Data is validated against macro-economic indicators, EV and smartphone battery pack production, domestic battery material tax credits, and historical trend analysis to ensure accuracy without double counting pure-graphite lithium-ion cells. |
Silicon Anode Battery Market by Segments
Silicon Anode Battery Market segmented by Anode Material Architecture:
- Silicon-Graphite Composite Si-C (58.4%)
- Silicon Oxide Blend SiOx
- Pure Nano-Structured Silicon and Nanowires
Silicon Anode Battery Market segmented by Cell Format:
- Pouch Cells (44.8%)
- Cylindrical 21700 and 4680 Cells
- Prismatic Cells
Silicon Anode Battery Market segmented by Capacity Class:
- Above 3000 mAh (61.2%)
- 1500 mAh to 3000 mAh
- Below 1500 mAh
Silicon Anode Battery Market segmented by End-Use Application:
- Electric Vehicles and e-Mobility (54.6%)
- Consumer Electronics and Wearables
- Aerospace, Drones, and Defense
- Grid and Stationary Storage
Silicon Anode Battery Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Li YH et al. (2025, March 17). Silicon/Hard Carbon Composites Synthesized from Phenolic Resin as Anode Materials for Lithium-Ion Batteries.. Nanomaterials (Basel, Switzerland), 15(6), 455 (PMCID PMC11944807).
- [2] Je M et al. (2026, April 24). High-strength and high-modulus silicon monoxide for high-energy-density and fast-charging lithium-ion batteries.. Nature communications, 17(1), 5656 (PMCID PMC13316046).
- [3] Wu F et al. (2024, April 26). Highly Stable Silicon Anode Enabled by a Water-Soluble Tannic Acid Functionalized Dual-Network Binder.. ACS applied materials & interfaces, 16(18), 23396-23405 (PMID 38669607).
- [4] Zheng Y et al. (2025, November 28). High-performance polymer binders for silicon-based anodes: Advances in molecular design and applications.. Journal of colloid and interface science, 706, 139578 (PMID 41337843).
- [5] Zhou Y et al. (2025, March 18). Realizing fast-charging capability of silicon anode via ternary doping and structural disorder.. Journal of colloid and interface science, 691, 137372 (PMID 40132424).
- [6] Yu P et al. (2025, June 20). Silicon Deposition on Three-Dimensional Graphene Powder in an Aqueous Environment for Fast-Charging and Ultra-Long Cycle Life Anode in Lithium-Ion Batteries.. Small (Weinheim an der Bergstrasse, Germany), 21(33), e2505110 (PMID 40538247).
- [7] Fereydooni A et al. (2026, February 23). Biomass-derived hard carbon host with added commercial silicon for high-capacity lithium-ion battery anodes.. Nanoscale advances, 8(7), 2398-2410 (PMCID PMC12969071).
- [8] Patil MK et al. (2026, August 1). MoO3-x Incorporated Covalent Organic Framework Nanocomposite as an Advanced Anode Material for Li-Ion Batteries: Elucidating Structure-Activity Relationships.. ACS applied materials & interfaces, 18(32), 44338-44350 (PMID 42615165).
- [9] Ni C et al. (2024, February 4). Effect of Graphene on the Performance of Silicon-Carbon Composite Anode Materials for Lithium-Ion Batteries.. Materials (Basel, Switzerland), 17(3), 754 (PMCID PMC10856289).
- [10] Wang, Z., Tang, H., & Li, M. (2025, May 21). High-Energy mechanical Milling Stirred Group Configuration for Preparing Rice-Husk-Derived SiOx/Graphite Matrix Composites as High-Performance Li-Ion Battery Anodes. Polymers, 17(10), 1409 (PubMed PMID 40430702).
- [11] Song, J., Lee, D., & Kang, Y. (2026, January 4). Electrochemical Activation of Li2SiO3 in the Inactive Matrix of SiOx Through the Incorporation of Sub-Nanometer Sn Particles for Lithium-Ion Batteries. Nanomaterials, 16(1), 59 (PubMed PMID 41515356).
- [12] Liu, H., Zhang, K., & Wu, X. (2025, February 18). Self-Terminating Electrodeposition Approaching Failure-Free Thickened Silicon Standard Electrodes via Alkanethiol Structuring for Durable Car-Grade Batteries. Materials, 18(4), 891 (PubMed PMID 40004416).
- [13] Xu, C., Deng, Y., & Zhao, P. (2026, April 8). Enhancing Mechanical Robustness of Single-Walled Carbon Nanotube Conductive Networks in Silicon-Carbon Anodes via Thermoplastic Polyurethane. Polymers, 18(8), 1072 (PubMed PMID 42050442).
- [14] Cho, H., Lim, S., & Park, J. (2025, July 22). Sustainable Fabrication of High-Capacity Silicon-Graphite Composite Anodes from Photovoltaic Silicon Waste via Low-Energy Ball Milling. Nanomaterials, 15(15), 1138 (PubMed PMID 40788799).
- [15] Sila Nanotechnologies Inc. (2025, November 12). Sila Moses Lake Next-Generation Titan Silicon Anode Plant. Sila Nanotechnologies Inc.
- [16] Lin, K., Wang, Y., & Zhou, H. (2026, October 14). Stress-Relieving Crosslinked Polymeric Binders and Prelithiation Engineering for High-Loading Silicon-Graphite Pouch Cells. Nanomaterials, 16(20), 1658 (PubMed PMID 42910412).
- [17] Panasonic Energy Co. Ltd. (2025, October 18). Development of Innovative 4680 Cylindrical Automotive Lithium-Ion Batteries. Panasonic Energy Co. Ltd.
- [18] Wang H et al. (2026, June 29). The interplay between stack pressure, mechanical expansion and degradation pathways in lithium-ion batteries.. Nature energy, 11(7), 1032-1042 (PMCID PMC13391380).
- [19] Group14 Technologies Inc. (2025, August 20). Group14 Closes US$463M Series D Funding Round and Acquires 100% Ownership of BAM Factory in South Korea from SK, Inc.. Group14 Technologies Newsroom.
- [20] Enovix Corporation. (2026, August 12). Enovix Reports Second Quarter 2026 Results. Enovix Investor Relations.
- [21] Amprius Technologies Inc. (2026, May 7). Amprius Technologies Reports First Quarter 2026 Financial Results. Amprius Technologies Investor Relations.
- [22] Group14 Technologies Inc. (2025, June 25). Group14 SCC55 Resets Benchmark for Silicon Battery Performance With Over 1,500 Charge Cycles. Group14 Technologies Newsroom.
- [23] Enovix Corporation. (2026, February 25). Enovix Reports Fourth Quarter and Full Year 2025 Results. Enovix Investor Relations.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the silicon anode battery market in 2026?
- Which EV fast-charging pressures support silicon anode battery demand globally?
- Why does silicon-graphite composite Si-C lead anode material architecture?
- Why do pouch cells and above 3000 mAh formats lead?
- How do growth rates differ across South Korea and the US?
- Which companies supply silicon anode powders and complete battery cells?
- What technical hurdles limit adoption in the silicon anode market?
- What should battery buyers evaluate before qualifying silicon anode platforms?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Anode Material Architecture, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Anode Material Architecture, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Anode Material Architecture, 2026 to 2036
- Silicon-Graphite Composite Si-C (58.4%)
- Silicon Oxide Blend SiOx
- Pure Nano-Structured Silicon and Nanowires
- Y-o-Y Growth Trend Analysis By Anode Material Architecture, 2021 to 2025
- Absolute $ Opportunity Analysis By Anode Material Architecture, 2026 to 2036
- Global Market Analysis and Forecast, By Cell Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Cell Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Cell Format, 2026 to 2036
- Pouch Cells (44.8%)
- Cylindrical 21700 and 4680 Cells
- Prismatic Cells
- Y-o-Y Growth Trend Analysis By Cell Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Cell Format, 2026 to 2036
- Global Market Analysis and Forecast, By Capacity Class, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Capacity Class, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Capacity Class, 2026 to 2036
- Above 3000 mAh (61.2%)
- 1500 mAh to 3000 mAh
- Below 1500 mAh
- Y-o-Y Growth Trend Analysis By Capacity Class, 2021 to 2025
- Absolute $ Opportunity Analysis By Capacity Class, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Application, 2026 to 2036
- Electric Vehicles and e-Mobility (54.6%)
- Consumer Electronics and Wearables
- Aerospace, Drones, and Defense
- Grid and Stationary Storage
- Y-o-Y Growth Trend Analysis By End-Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Anode Material Architecture
- By Cell Format
- By Capacity Class
- By End-Use Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Sila Nanotechnologies Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Enovix Corporation
- Group14 Technologies Inc.
- Amprius Technologies Inc.
- Panasonic Energy Co. Ltd.
- Sila Nanotechnologies Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Anode Material Architecture, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Cell Format, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Capacity Class, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Anode Material Architecture, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Cell Format, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Capacity Class, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Anode Material Architecture, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Cell Format, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Capacity Class, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Billion) Forecast by Anode Material Architecture, 2021 to 2036
- Table 18: Western Europe Market Value (USD Billion) Forecast by Cell Format, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Capacity Class, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Billion) Forecast by Anode Material Architecture, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Billion) Forecast by Cell Format, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Billion) Forecast by Capacity Class, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 26: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Billion) Forecast by Anode Material Architecture, 2021 to 2036
- Table 28: East Asia Market Value (USD Billion) Forecast by Cell Format, 2021 to 2036
- Table 29: East Asia Market Value (USD Billion) Forecast by Capacity Class, 2021 to 2036
- Table 30: East Asia Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Billion) Forecast by Anode Material Architecture, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Billion) Forecast by Cell Format, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Billion) Forecast by Capacity Class, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Billion) Forecast by Anode Material Architecture, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Billion) Forecast by Cell Format, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Billion) Forecast by Capacity Class, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Anode Material Architecture, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Anode Material Architecture, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Anode Material Architecture
- Figure 6: Global Market Value Share and BPS Analysis by Cell Format, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Cell Format, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Cell Format
- Figure 9: Global Market Value Share and BPS Analysis by Capacity Class, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Capacity Class, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Capacity Class
- Figure 12: Global Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by End-Use Application
- Figure 15: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Anode Material Architecture, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Anode Material Architecture, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Anode Material Architecture
- Figure 29: North America Market Value Share and BPS Analysis by Cell Format, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Cell Format, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Cell Format
- Figure 32: North America Market Value Share and BPS Analysis by Capacity Class, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Capacity Class, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Capacity Class
- Figure 35: North America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by End-Use Application
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Anode Material Architecture, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Anode Material Architecture, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Anode Material Architecture
- Figure 42: Latin America Market Value Share and BPS Analysis by Cell Format, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Cell Format, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Cell Format
- Figure 45: Latin America Market Value Share and BPS Analysis by Capacity Class, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Capacity Class, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Capacity Class
- Figure 48: Latin America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by End-Use Application
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Anode Material Architecture, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Anode Material Architecture, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Anode Material Architecture
- Figure 55: Western Europe Market Value Share and BPS Analysis by Cell Format, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by Cell Format, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by Cell Format
- Figure 58: Western Europe Market Value Share and BPS Analysis by Capacity Class, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by Capacity Class, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by Capacity Class
- Figure 61: Western Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by End-Use Application
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Anode Material Architecture, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Anode Material Architecture, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Anode Material Architecture
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by Cell Format, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by Cell Format, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by Cell Format
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by Capacity Class, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by Capacity Class, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by Capacity Class
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by End-Use Application
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Anode Material Architecture, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Anode Material Architecture, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Anode Material Architecture
- Figure 81: East Asia Market Value Share and BPS Analysis by Cell Format, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by Cell Format, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by Cell Format
- Figure 84: East Asia Market Value Share and BPS Analysis by Capacity Class, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by Capacity Class, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by Capacity Class
- Figure 87: East Asia Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by End-Use Application
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by Anode Material Architecture, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by Anode Material Architecture, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by Anode Material Architecture
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by Cell Format, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by Cell Format, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by Cell Format
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by Capacity Class, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by Capacity Class, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by Capacity Class
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by End-Use Application
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by Anode Material Architecture, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by Anode Material Architecture, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by Anode Material Architecture
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by Cell Format, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by Cell Format, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by Cell Format
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by Capacity Class, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by Capacity Class, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by Capacity Class
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by End-Use Application
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the silicon anode battery market in 2026, and what is forecast for 2036?
FMI data suggests the silicon anode battery industry valuation equals USD 4.9 billion in 2026 up from USD 4.3 billion in 2025, reaching USD 17.7 billion by 2036.
What is the CAGR for the silicon anode battery market from 2026 to 2036?
An FMI analyst projects a 13.7% CAGR over the ten-year 2026 to 2036 window, delivering USD 12.8 billion in net market size expansion.
Which anode material architecture segment leads the silicon anode battery market?
Silicon-graphite composite Si-C captures 58.4% of anode material architecture demand in 2026 since porous carbon-silicon powders run on standard wet-slurry coaters.
Which cell format, capacity class, and end-use segments lead the silicon anode battery market?
Pouch cells secure 44.8% of cell format demand in 2026, while above 3000 mAh holds 61.2% by capacity class and electric vehicles and e-mobility captures 54.6% by application.
Which country has a notable growth outlook during the assessment period?
South Korea tops national battery expansion with a 14.6% CAGR through 2036 above the US (14.2%) and Germany (13.8%).
Who are the key players in the market?
Sila Nanotechnologies Inc. and Enovix Corporation lead commercial silicon anode innovation with Group14 Technologies Inc. Amprius Technologies Inc. and Panasonic Energy Co. Ltd. also anchor global aviation and EV cell supply.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
