

- Market Size (2026)
- USD 48.4 Bn
- Forecast (2036)
- USD 152.0 Bn
- CAGR (2026 to 2036)
- 12.1%
How big is Wi-Fi Market in 2026?
The global Wi-Fi market is estimated at USD 43.2 billion in 2025 and is expected to reach USD 48.4 billion in 2026. Demand for Wi-Fi equipment, software and services is forecast to grow at a CAGR of 12.1% between 2026 and 2036, taking the market to USD 152.0 billion by 2036. Solutions are expected to hold the largest share, at 46% of 2026 component sales, according to FMI analysis.
Sales of access points are rising as regulators open more of the 6 GHz band to unlicensed devices. A case in point is the FCC decision of January 2026, which created a geofenced variable power class that lets 6 GHz devices run indoors and outdoors at higher power [1]. In turn, stadiums, campuses and yards can now be covered with fewer, stronger access points. Demand for Wi-Fi among households also has a large base to draw on, as the ITU counted an estimated 6 billion internet users in 2025, with 2.2 billion people still offline [2]. This is visible in chip roadmaps, as Broadcom launched a unified Wi-Fi 8 platform for homes in January 2026, led by the BCM4918 APU with a built-in neural engine [3]. Adoption of Wi-Fi 8 routers is therefore likely to follow later in the decade. FMI analysis points to early silicon of this kind as the trigger for the next router replacement cycle.
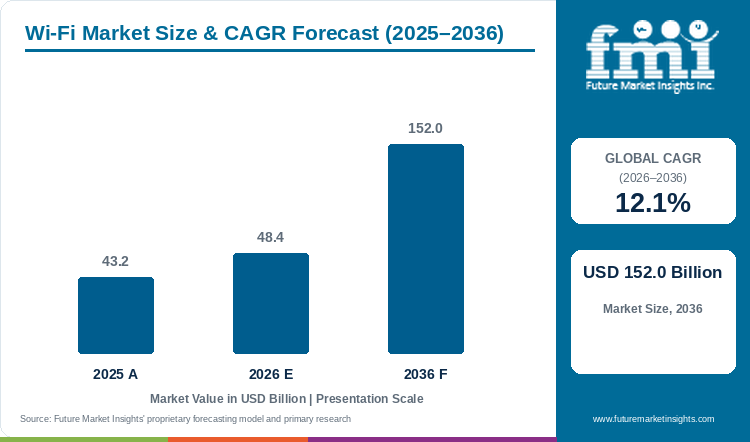
Table 1: Wi-Fi Market Size and Forecast (USD billion), 2025 to 2036
| Market size and forecast | Value |
|---|---|
| 2025 market size | USD 43.2 billion |
| Estimated market size in 2026 | USD 48.4 billion |
| Projected market size by 2036 | USD 152.0 billion |
| CAGR (2026 to 2036) | 12.1% |
| Added sales, 2026 to 2036 | USD 103.6 billion |
Key Market Trends & Insights
- By component: Solutions, at an estimated 46% of 2026 component sales, lead hardware and services, as buyers purchase access points together with controller and management software.
- By density: Offices, hospitals and schools need managed coverage across many floors, so enterprise-class deployments will hold about 63% of 2026 density sales.
- By location type: Indoor networks are expected to account for 71% of location sales in 2026; most phone and laptop traffic starts inside homes and buildings.
Regional Highlights
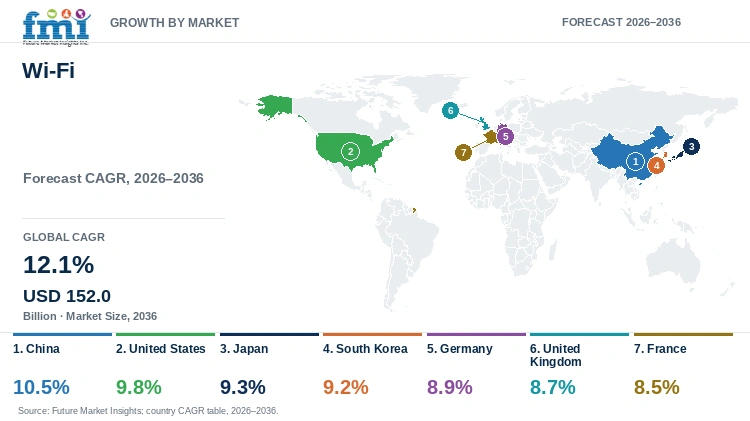
- Fastest-growing country: China is projected to grow at a CAGR of 10.5% between 2026 and 2036, the highest among profiled countries, as factories and offices move to newer standards.
- Growth across other countries: The United States (9.8%), Japan (9.3%) and South Korea (9.2%) grow more slowly, as most homes and offices there already have dense networks. Germany is projected at 8.9% on factory projects, and the United Kingdom at 8.7% after the new spectrum decision. France grows slowest at 8.5%.
Growth of the Wi-Fi market depends on spectrum supply, and regulators are adding room in the 6 GHz band. The FCC allowed geofenced variable power devices to use the U-NII-5 and U-NII-7 portions of the 6 GHz band [1]. Outdoor access at higher power lets operators cover parks, ports and campuses with fewer units, which brings more sites within reach. Europe is moving in a similar direction, though with sharing rules. Ofcom adopted a hybrid sharing model for the upper 6 GHz band in July 2026, with 160 MHz at 6425 to 6585 MHz prioritised for Wi-Fi [4]. Consequently, British vendors can plan tri-band products around a fixed block, and mobile use of the rest is expected only in the 2030s.
Campus refresh cycles keep commercial momentum strong in enterprise networking. Cisco reported fourth-quarter fiscal 2026 networking sales of USD 9,791 million, up 28%, with total product orders up 35% [5]. With orders growing faster than sales, Cisco has a full delivery pipeline going into fiscal 2027. Similarly, HPE reported third-quarter Campus and Branch sales of USD 1.4 billion, up 31% [6]. Fast growth in campus equipment shows that offices and schools are replacing older access points with Wi-Fi 6E and Wi-Fi 7 units. Moreover, larger vendors are bundling wireless with switching and security, so smaller suppliers face harder price competition in enterprise tenders.
New silicon and supplier results show newer standards spreading quickly. Broadcom said third-generation digital pre-distortion in the Wi-Fi 8 platform reduces peak power by 25% [3]. Lower power draw makes multi-radio routers cheaper to run, which supports faster replacement of home gateways. Results at prosumer and SMB suppliers point the same way. Ubiquiti grew fourth-quarter fiscal 2026 sales 23.5% year on year to USD 937.3 million [7]. On the consumer side, NETGEAR consumer sales fell 9.4% in the second quarter of 2026, although enterprise sales rose 7.7% [8]. The contrast shows that business buyers, more than households, now drive most of the growth.
Table 2: Supporting Industry Indicators for the Wi-Fi Market, 2025 to 2026
| Indicator | Data point | Why it matters | Source |
|---|---|---|---|
| US 6 GHz rules | Geofenced variable power class adopted, January 2026 | Higher-power indoor and outdoor devices widen use cases | [1] |
| UK upper 6 GHz band | 160 MHz at 6425 to 6585 MHz prioritised for Wi-Fi, July 2026 | A fixed Wi-Fi block supports tri-band product planning | [4] |
| People online | About 6 billion in 2025 | Sets the size of the connected user base | [2] |
| People offline | 2.2 billion in 2025 | Leaves room for public and rural hotspots | [2] |
| Urban and rural internet use | 85% urban against 58% rural, 2025 | Rural gaps point to coverage projects | [2] |
| Cisco networking sales | USD 9,791 million in fourth-quarter fiscal 2026, up 28% | Enterprise network refresh is strong | [5] |
| Cisco product orders | Up 35% in fourth-quarter fiscal 2026 | Order growth signals deliveries ahead | [5] |
| HPE Campus and Branch sales | USD 1.4 billion in third-quarter fiscal 2026, up 31% | Campus wireless upgrades are accelerating | [6] |
| Ubiquiti annual sales | USD 3.3 billion in fiscal 2026 | SMB and prosumer networks keep growing | [7] |
| NETGEAR enterprise sales | USD 89 million in the second quarter of 2026, up 7.7% | Business buyers offset weaker households | [8] |
| Wi-Fi 8 silicon | Broadcom tri-band Wi-Fi 8 platform, January 2026 | Early chips set the next router cycle | [3] |
Demand Intensity Analysis
Large vendor sales give a direct outside check on the size of the Wi-Fi opportunity. Cisco reported fiscal 2026 networking sales of USD 34,668 million, up 22% [5]. The Wi-Fi market, estimated at USD 43.2 billion for 2025, comes to about 1.25 times that networking line. Scope differs, since Cisco networking includes switching, routing and data centre products, and the market estimate covers consumer routers, chipsets and services across all vendors. A multiple only slightly above one shows that Wi-Fi purchases are spread well beyond the largest enterprise vendor.
A second check comes from Ubiquiti, a fast-growing mid-sized supplier of SMB and prosumer gear. Ubiquiti reported fiscal 2026 sales of USD 3.3 billion [7]. Against this figure, the 2025 market estimate equals about 13 times the annual sales of one supplier serving SMB and prosumer networks. Ubiquiti sales also include switching, cameras and service provider gear, so the Wi-Fi share of that figure is smaller. The ratio shows a fragmented field, so mid-sized vendors can still add share in segments in which large vendors charge high prices.
Today's upgrade cycle is running above the long-run pace, judging by vendor growth rates. Cisco networking grew 22% in fiscal 2026, and Ubiquiti sales rose 23.5% in the fourth quarter [5] [7]. Against those rates, the 12.1% market CAGR for 2026 to 2036 implies that vendor growth will slow by about half as refresh demand settles. Average prices per access point are likely to ease as Wi-Fi 7 volumes rise. The forecast therefore leans on more endpoints and wider coverage, more than on sustained double-digit pricing.
Measured per user, the market still has plenty of room to grow as more people come online. ITU data puts the online population at about 6 billion in 2025 [2]. On that basis, the 2025 market estimate equals about USD 7.2 per online person, rising to about USD 8.1 on the 2026 value. Many users share one home router, and enterprises serve thousands of users per network, so spend per user stays low in absolute terms. A low figure per user implies that coverage of the 2.2 billion people still offline can add volume without large price increases.
Table 3: Demand Intensity Metrics for the Wi-Fi Market, 2025 to 2026 Data Against 2025 and 2026 Market Values
| Demand intensity metric | Value | Basis |
|---|---|---|
| Cisco networking sales, fiscal 2026 | USD 34,668 million | Cisco, fiscal 2026 results |
| 2025 market value as a multiple of Cisco networking sales | 1.25 times | Calculated from Cisco fiscal 2026 networking sales and the 2025 market value |
| Ubiquiti sales, fiscal 2026 | USD 3.3 billion | Ubiquiti, fiscal 2026 results |
| 2025 market value as a multiple of Ubiquiti sales | About 13 times | Calculated from Ubiquiti fiscal 2026 sales and the 2025 market value |
| Cisco networking growth, fiscal 2026 | 22% | Cisco, fiscal 2026 results |
| Ubiquiti sales growth, fourth-quarter fiscal 2026 | 23.5% | Ubiquiti, fourth-quarter fiscal 2026 results |
| People online, 2025 | About 6 billion | International Telecommunication Union, 2025 |
| Market value per online person | About USD 7.2 (2025) and USD 8.1 (2026) | Calculated from International Telecommunication Union users and the 2025 and 2026 market values |
| People offline, 2025 | 2.2 billion | International Telecommunication Union, 2025 |
Analyst Perspective
“Wi-Fi spend is shifting from coverage to capacity, and spectrum rules in the 6 GHz band now decide product roadmaps. Enterprise campuses are carrying growth today, and Wi-Fi 8 will restart the home cycle later in the decade. Vendors that sell management software with the hardware will hold customers longer.”
- Sudip saha, Principal Consultant, Future Market Insights.
How is the wi-fi market segmented?
The market is segmented into component, density, location type, organization size, vertical, and region. Solutions are expected to lead component with 46% share in 2026, and enterprise-class deployments lead density with an estimated 63%.
By component: hardware, solutions, and services.
By density: hi-density and enterprise-class.
By location type: indoor and outdoor.
By organization size: large enterprises and SMEs.
By vertical: education, healthcare and life sciences, transportation and logistics, retail and e-commerce, government, manufacturing, hospitality, and others.
By region: homes, campuses and public venues across North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do solutions lead Wi-Fi sales by component?
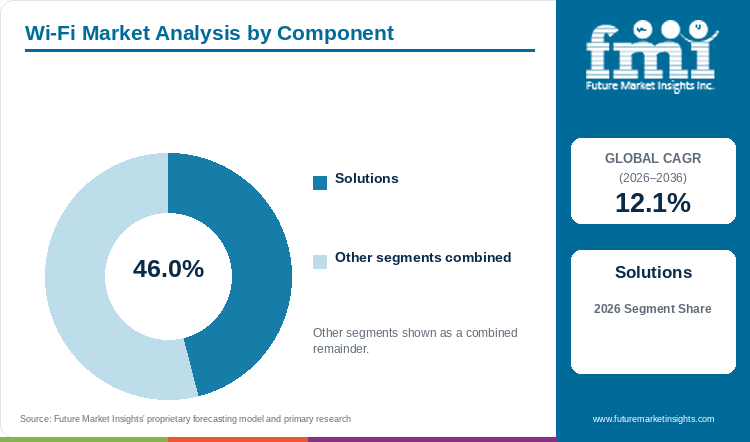
With an estimated 46% of 2026 component sales, solutions lead hardware at 34% and services at 20%.
Table 4: Component Share for the Wi-Fi Market (percentage share), 2026
| Component | Estimated Share (2026) |
|---|---|
| Solutions | 46% |
| Hardware | 34% |
| Services | 20% |
| Total | 100.0% |
Table 5: Component Leadership and Market Growth for the Wi-Fi Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 12.1% |
| Leading Segment | Solutions |
Buyers increasingly purchase Wi-Fi as a managed system, so solutions combining access points, controllers and software lead the component mix. FMI estimates solutions at 46% of 2026 component sales, 12 points ahead of stand-alone hardware at 34%. Services hold the remaining 20%, covering network design, installation and managed operations. Campus refresh projects are the clearest sign that buyers now purchase complete systems. HPE reported Campus and Branch sales of USD 1.4 billion in the third quarter of fiscal 2026 [6]. Campus deals bundle wireless, switching and cloud management, which keeps solutions ahead of loose hardware through 2036.
- Managed access point systems, wireless controllers, cloud management platforms and location analytics make up solutions.
- Service providers also drive solution sales, and the carrier Wi-Fi equipment market is projected to reach USD 12.8 billion by 2035. Operator networks add managed Wi-Fi to broadband plans, which extends solution sales into homes.
Why do enterprise-class deployments lead Wi-Fi sales by density?
Enterprise-class deployments are expected to lead density sales with 63% share in 2026, ahead of hi-density networks at an estimated 37%.
Table 6: Density Share for the Wi-Fi Market (percentage share), 2026
| Density | Estimated Share (2026) |
|---|---|
| Enterprise-class | 63% |
| Hi-density | 37% |
| Total | 100.0% |
Most organisations need reliable coverage across offices and floors, so enterprise-class networks lead density sales. FMI places enterprise-class deployments at 63% of 2026 density sales, against 37% for hi-density networks in stadiums, airports and lecture halls. Hi-density sites buy more radios per square metre but are fewer in number. Enterprise refresh is running at a strong pace at the largest networking vendor. Cisco total product orders rose 35% in the fourth quarter of fiscal 2026 [5]. Strong order intake points to continued enterprise upgrades, which keeps enterprise-class networks ahead in the density mix.
- Office floors, hospital wards, school buildings and warehouse aisles make up enterprise-class deployments.
- Hi-density venues benefit from wider channels, and Ofcom kept 160 MHz of the upper 6 GHz band as a Wi-Fi priority block in July 2026 [4]. Wider channels raise capacity per access point, which improves the economics of crowded venues.
Why do indoor networks lead Wi-Fi sales by location type?
Indoor networks are expected to lead location type sales with 71% share in 2026, ahead of outdoor networks at an estimated 29%.
Table 7: Location Type Share for the Wi-Fi Market (percentage share), 2026
| Location Type | Estimated Share (2026) |
|---|---|
| Indoor | 71% |
| Outdoor | 29% |
| Total | 100.0% |
Consumption of Wi-Fi traffic happens mostly in homes, offices and shops, so indoor networks dominate location sales. In FMI estimates, indoor networks account for 71% of 2026 location sales, against 29% for outdoor networks. Outdoor use has been limited by power rules, which kept coverage short. That power limit is now easing in the United States after a new FCC decision. The FCC adopted a geofenced variable power class for 6 GHz devices operating indoors and outdoors in January 2026 [1]. Higher outdoor power is likely to raise the outdoor share gradually, although indoor networks will keep the lead through 2036.
- Homes, offices, retail stores, hospitals and classrooms make up indoor networks.
- Home networks are adding services on top of coverage, and the smart home service market is projected to grow at a 15.4% CAGR through 2035. Service bundles such as security and parental controls raise the value of each indoor router.
Why do large enterprises lead Wi-Fi sales by organization size?
Large enterprises account for an estimated 58% of 2026 organization size sales, and SMEs make up the other 42%.
Table 8: Organization Size Share for the Wi-Fi Market (percentage share), 2026
| Organization Size | Estimated Share (2026) |
|---|---|
| Large Enterprises | 58% |
| SMEs | 42% |
| Total | 100.0% |
Large organisations run many sites and buy whole networks at once, so large enterprises hold the bigger share of organization size sales. Large enterprises are estimated at 58% of 2026 sales, with SMEs at 42%. SMEs buy simpler cloud-managed kits, which suppliers sell through distributors and online. That online and distributor channel is growing quickly at SMB-focused vendors such as Ubiquiti. Enterprise Technology products brought Ubiquiti USD 2,972.3 million in fiscal 2026 sales [7]. Strong growth in low-cost managed equipment suggests that SMEs are gaining share, though large enterprises keep the lead.
- Corporate campuses, hospital groups, universities and retail chains make up the large enterprise group.
- Business buyers are steadier than households, and NETGEAR enterprise sales rose 7.7% to USD 89 million in the second quarter of 2026 [8]. Steady business orders help small vendors offset weaker consumer sales.
Why do healthcare and life sciences lead Wi-Fi sales by vertical?
Healthcare and life sciences are expected to lead vertical sales with 18% share in 2026, ahead of education at an estimated 16%.
Table 9: Vertical Share for the Wi-Fi Market (percentage share), 2026
| Vertical | Estimated Share (2026) |
|---|---|
| Healthcare and Life Sciences | 18% |
| Education | 16% |
| Retail and E-commerce | 15% |
| Transportation and Logistics | 12% |
| Hospitality | 11% |
| Government | 10% |
| Manufacturing | 9% |
| Others | 9% |
| Total | 100.0% |
Hospitals connect monitors, pumps and staff devices across large buildings, so healthcare and life sciences lead vertical sales. Healthcare and life sciences are estimated at 18% of 2026 sales, ahead of education at 16% and retail and e-commerce at 15%. Transportation and logistics hold 12% and hospitality 11%, driven by warehouse and guest networks, and government, manufacturing and others make up the rest. Industrial sites are a growing buyer group, and the industrial IoT market is projected to reach USD 1,744.2 billion by 2035. Connected machines need reliable wireless links, so manufacturing is expected to gain share over the decade.
- Hospitals, clinics, laboratories and pharmaceutical plants make up healthcare and life sciences.
- Rural coverage remains a gap for public services, as 85% of urban residents were online in 2025 against 58% in rural areas [2]. Closing that gap will require more government and education networks in smaller towns.
What are the drivers, restraints, and opportunities in the wi-fi market?
New spectrum and enterprise refresh cycles push organisations to upgrade Wi-Fi networks. Weak household budgets for routers slow consumer sales, and the next standard opens a new replacement wave.
- Driver: Regulators are opening more spectrum for unlicensed use, which lets vendors sell faster access points and pushes buyers to replace older networks.
- Restraint: Households keep routers for many years and buy on price, which slows consumer sales and pressures margins at retail-focused vendors.
- Opportunity: The next Wi-Fi standard and on-device intelligence in home gateways give vendors a new reason for customers to upgrade.
New Spectrum and Enterprise Refresh Drive Upgrades
Spectrum policy and enterprise budgets drive most Wi-Fi upgrades. The FCC allowed geofenced variable power devices in the U-NII-5 and U-NII-7 bands in January 2026 [1]. More usable spectrum lets each new access point carry more users, which shortens the replacement cycle. Enterprise budgets are following that spectrum opening with larger network orders. HPE reported third-quarter fiscal 2026 Networking sales of USD 2.9 billion, up 74.9% [6]. Strong vendor growth confirms that enterprises are funding network refresh, a trend likely to continue as Wi-Fi 7 matures.
Weak Household Budgets Restrain Consumer Sales
Consumer preference for long router lifetimes keeps household sales behind business sales, as households replace routers only when service fails or speeds fall short. Consumer sales at NETGEAR dropped 9.4% to USD 79.6 million in the second quarter of 2026 [8]. Weaker household orders hold back retail-focused vendors and keep price competition intense. Even so, NETGEAR said recurring home networking revenue performed well, driving 15% year-over-year growth in annual recurring revenue [8]. Subscription services are therefore cushioning weaker router sales, which favours vendors with paid security and support plans.
Wi-Fi 8 and Edge Intelligence Open a New Cycle
Later in the decade, the next standard will restart the home router cycle. Broadcom launched the BCM4918 Wi-Fi 8 APU with an integrated neural engine for on-device AI inference in January 2026 [3]. On-device intelligence lets gateways manage traffic and security locally, which gives service providers a reason to replace equipment. Faster gigabit access points support the same shift, and the gigabit Wi-Fi access point market is projected to grow at a 32.3% CAGR through 2034. Vendors that launch Wi-Fi 8 early are likely to gain operator contracts in the second half of the forecast period.
Which country CAGRs are profiled in the wi-fi market?
Table 10: Country CAGR Comparison for the Wi-Fi Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| China | 10.5% |
| United States | 9.8% |
| Japan | 9.3% |
| South Korea | 9.2% |
| Germany | 8.9% |
| United Kingdom | 8.7% |
| France | 8.5% |
How do country-level CAGRs compare in the wi-fi market?
Every profiled country runs below the 12.1% global CAGR, and FMI places China highest at 10.5% as factories and offices adopt newer standards. Faster growth comes from countries in the regional tables, mainly in South Asia and Pacific, Latin America and the Middle East and Africa, as first-time coverage is still spreading there. In the United States (9.8%), Japan (9.3%) and South Korea (9.2%), most sales come from replacing dense home and office networks. Germany at 8.9%, the United Kingdom at 8.7% and France at 8.5% close the table, as mature broadband bases leave less room for new coverage.
- Demand for industrial wireless links in China rises with factory automation, which shifts sales toward higher-value enterprise systems.
- Use of outdoor and venue Wi-Fi in the United States benefits from new 6 GHz power rules, which raises system value per site.
- Key trends in Japan point to replacement of advanced home and office networks on a regular cycle, giving suppliers steady renewal orders.
- Popularity of new standards in South Korea helps premium access points sell well soon after launch.
- Sales of enterprise Wi-Fi in Germany stay steady with factory and hospital modernisation, despite a mature home base.
- In the United Kingdom, the upper 6 GHz decision gives vendors a clear block for tri-band products.
- Consumer preference for faster routers is growing in France as fibre roll-out spreads, though the installed base is already large.
Full report country CAGRs cover: seven page-level rates from France at 8.5% to China at 10.5%, with faster-growing standard countries shown in regional tables.
Country-wise Analysis
China Wi-Fi Market Outlook (2026 to 2036)
With a large installed base of home and office networks, China depends on upgrades to newer standards for new sales. Factory automation adds industrial wireless projects, which carry higher value per site. FMI places China first among profiled countries, with a 10.5% CAGR to 2036.
Key takeaway: Chinese factories and offices will keep upgrading to newer Wi-Fi standards, which makes China the fastest-growing of the profiled countries.
United States Wi-Fi Market Outlook (2026 to 2036)
The United States is opening more of the 6 GHz band to higher-power use. The FCC voted in January 2026 to let geofenced variable power devices operate indoors and outdoors at higher power than earlier devices [1]. Rules of this kind open stadiums, campuses and logistics yards to new outdoor projects. With venue and campus projects adding demand, Wi-Fi in the United States is projected to grow at 9.8% a year.
Key takeaway: Stadium, campus and logistics yard owners in the United States can now buy higher-power outdoor Wi-Fi, thanks to the new 6 GHz rules.
Japan Wi-Fi Market Outlook (2026 to 2036)
Japanese homes and offices replace advanced networks with each new standard. An ageing workforce also raises interest in connected tools in hospitals and factories. Japan is projected to grow at 9.3% a year from 2026 to 2036 on regular replacement cycles.
Key takeaway: Japanese households and offices replace Wi-Fi equipment with each new standard, which gives vendors steady but moderate sales growth.
South Korea Wi-Fi Market Outlook (2026 to 2036)
South Korea adopts new wireless standards early, and premium routers sell soon after launch. Fast broadband lines push homes toward multi-gigabit Wi-Fi, so home networks keep up with the line speed. With premium upgrades and early adoption, South Korea is projected to grow at a 9.2% CAGR through 2036.
Key takeaway: South Korean buyers pick up new Wi-Fi standards early, so vendors can sell premium routers and access points there soon after launch.
Germany Wi-Fi Market Outlook (2026 to 2036)
Germany modernises factories and hospitals steadily, and each project includes wireless upgrades. A mature home base limits consumer growth, so enterprise projects account for most new sales. Germany is projected to grow at an 8.9% CAGR over the forecast period, supported by steady enterprise refresh.
Key takeaway: In Germany, factories and hospitals will account for most new Wi-Fi purchases, since most homes already have modern routers.
United Kingdom Wi-Fi Market Outlook (2026 to 2036)
The United Kingdom now has clear rules for the upper 6 GHz band. Ofcom set 6425 to 6585 MHz as a Wi-Fi priority block under a hybrid sharing model in July 2026 [4]. A defined block lets vendors launch tri-band products with confidence. The United Kingdom is projected to grow at an 8.7% CAGR to 2036 as vendors launch tri-band products.
Key takeaway: British vendors can launch tri-band products with confidence under the new 6 GHz rules, although most homes and offices already own recent equipment.
France Wi-Fi Market Outlook (2026 to 2036)
France has a wide fibre footprint, and faster lines push households toward newer routers. Offices and public buildings add managed networks, though the installed base is already large. France ranks last among profiled countries in FMI projections, with an 8.5% CAGR.
Key takeaway: French households moving to faster fibre lines will buy newer routers, but a large installed base keeps France at the bottom of the growth table.
Who are the notable companies in the wi-fi market?
Enterprise networking vendors, chipset suppliers and consumer and SMB equipment makers make up the profiled field, including Cisco Systems, Broadcom, Qualcomm Technologies, NETGEAR, TP-Link Technologies, Hewlett Packard Enterprise (Aruba Networks), D-Link, Samsung Electronics, Ubiquiti and Zyxel Communications.
In the Wi-Fi market, the leading companies divide into enterprise vendors that sell managed systems and consumer brands that sell routers through retail. The profiled companies split into three groups by role, since chipset suppliers shape product timing for every equipment brand. Enterprise vendors are growing fastest in the current cycle, helped by campus upgrades. Full-year fiscal 2026 sales at Cisco reached USD 63.3 billion, a 12% gain [5]. Scale of this size lets large vendors bundle wireless with switching and security, so consumer brands compete mainly on price and retail reach.
- Enterprise networking vendors: Cisco Systems, Hewlett Packard Enterprise (Aruba Networks) and Ubiquiti, which sell managed campus and branch networks.
- Chipset suppliers: Broadcom, Qualcomm Technologies and Samsung Electronics, whose radio silicon sets launch timing for equipment brands.
- Consumer and SMB equipment makers: NETGEAR, TP-Link Technologies, D-Link and Zyxel Communications, selling mainly through retail stores and distributors.
Competitive Benchmarking: Wi-Fi Market
Table 11: Competitive Benchmarking for the Wi-Fi Market (qualitative ratings), 2026
| Company | Enterprise Systems | Chipsets and Standards | Consumer Reach | Recent Activity |
|---|---|---|---|---|
| Cisco Systems | High | Low | Low | High |
| Hewlett Packard Enterprise (Aruba Networks) | High | Low | Low | High |
| Ubiquiti | Medium | Low | Medium | High |
| Broadcom | Low | High | Medium | High |
| Qualcomm Technologies | Low | High | Medium | Low |
| NETGEAR | Medium | Low | High | Medium |
| TP-Link Technologies | Medium | Low | High | Low |
Ratings compare the companies on enterprise systems, chipsets and standards, consumer reach and recent activity.
Key Developments in the Wi-Fi Market
- HPE reported third-quarter fiscal 2026 Networking sales of USD 2.9 billion on September 2, 2026, up 74.9%, showing how quickly campus buyers are refreshing [6].
- Ubiquiti closed fiscal 2026 with sales of USD 3.3 billion, reported on August 21, 2026, which confirms strong demand for low-cost managed networks [7].
- On August 12, 2026, Cisco reported fourth-quarter networking sales up 28% and product orders up 35%, pointing to a full pipeline for campus upgrades [5].
- NETGEAR enterprise sales rose 7.7% to USD 89 million in the second quarter of 2026, offsetting a 9.4% fall in consumer sales [8].
- In July 2026, Ofcom adopted hybrid sharing of the upper 6 GHz band with a 160 MHz Wi-Fi priority block, giving vendors spectrum certainty in the United Kingdom [4].
- The FCC voted on January 29, 2026 to create geofenced variable power devices for 6 GHz, opening higher-power outdoor use in the United States [1].
- Broadcom introduced the BCM4918 Wi-Fi 8 APU and two Wi-Fi 8 radios at CES in January 2026, setting the timing for the next router cycle [3].
Key Players in the Wi-Fi Market
Enterprise Networking Vendors
- Cisco Systems
- Hewlett Packard Enterprise (Aruba Networks)
- Ubiquiti
Chipset Suppliers
- Broadcom
- Qualcomm Technologies
- Samsung Electronics
Consumer and SMB Equipment Makers
- NETGEAR
- TP-Link Technologies
- D-Link
- Zyxel Communications
Wi-Fi Market - Report Scope
Table 12: Report Scope for the Wi-Fi Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Component; density; location type; organization size; vertical; region |
| Quantitative units | USD billion |
| Market definition | Wireless local area network hardware, solutions and services for homes, enterprises and public venues, including access points, routers, controllers, management software and related services. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | China; United States; Japan; South Korea; Germany; United Kingdom; France |
| Key companies profiled | Cisco Systems, Broadcom, Qualcomm Technologies, NETGEAR, TP-Link Technologies, Hewlett Packard Enterprise (Aruba Networks), D-Link, Samsung Electronics, Ubiquiti, Zyxel Communications |
| Forecast period | 2026 to 2036 |
Wi-Fi Market - Research Methodology
Table 13: Research Methodology for the Wi-Fi Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Company results, industry associations, government statistics and trade publications. |
| Desk Research | Desk research covers spectrum policy, Wi-Fi standards, enterprise networking, consumer routers and managed services. |
| Market Sizing | Market size is built from component, density, location, organization size and vertical sales across regions. |
| Data Validation | Figures are cross-checked across company, industry and government sources. |
Wi-Fi Market by Segments
Wi-Fi Market segmented by Component:
- Hardware
- Solutions
- Services
Wi-Fi Market segmented by Density:
- Hi-density
- Enterprise-class
Wi-Fi Market segmented by Location Type:
- Indoor
- Outdoor
Wi-Fi Market segmented by Organization Size:
- Large Enterprises
- SMEs
Wi-Fi Market segmented by Vertical:
- Education
- Healthcare and Life Sciences
- Transportation and Logistics
- Retail and E-commerce
- Government
- Manufacturing
- Hospitality
- Others
Wi-Fi Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Federal Communications Commission. (2026, January 29). FCC Votes to Enable Better, Faster Wi-Fi and Next-Gen Connectivity. https://docs.fcc.gov/public/attachments/DOC-418324A1.pdf
- [2] International Telecommunication Union. (2025, November 17). Global number of Internet users increases, but disparities deepen key digital divides. https://www.itu.int/en/mediacentre/Pages/PR-2025-11-17-Facts-and-Figures.aspx
- [3] Broadcom Inc. (2026, January 6). Broadcom Launches Unified Wi-Fi 8 Platform for Seamless AI Experiences in Homes. https://investors.broadcom.com/news-releases/news-release-details/broadcom-launches-unified-wi-fi-8-platform-seamless-ai
- [4] ISPreview. (2026, July 20). Ofcom Adopt Shared Upper 6GHz Band for UK Mobile and Wi-Fi Networks. https://www.ispreview.co.uk/index.php/2026/07/ofcom-adopt-shared-upper-6ghz-band-for-uk-mobile-and-wi-fi-networks.html
- [5] Cisco Systems, Inc. (2026, August 12). Cisco Reports Fourth Quarter Earnings. https://newsroom.cisco.com/c/r/newsroom/en/us/a/y2026/m08/cisco-reports-fourth-quarter-earnings.html
- [6] Hewlett Packard Enterprise. (2026, September 2). Hewlett Packard Enterprise reports 3Q results. https://www.fierce-network.com/newswire/hewlett-packard-enterprise-reports-3q-results
- [7] Ubiquiti Inc. (2026, August 21). Ubiquiti Inc. Reports Fourth Quarter Fiscal 2026 Financial Results. https://www.sec.gov/Archives/edgar/data/0001511737/000151173726000057/exhibit991-063026.htm
- [8] NETGEAR, Inc. (2026, August 6). NETGEAR Reports Second Quarter 2026 Results. https://investors.netgear.com/releases/news-details/2026/NETGEAR-Reports-Second-Quarter-2026-Results/default.aspx
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the wi-fi market during 2026?
- What market size is projected by 2036?
- Which component holds notable share?
- Which density holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the wi-fi market expected in 2026?
With campus networks moving to newer standards, the Wi-Fi market is expected to reach USD 48.4 billion in 2026, FMI estimates, from USD 43.2 billion in 2025.
What CAGR is projected for the wi-fi market through 2036?
Demand for Wi-Fi equipment, software and services is projected to grow at a 12.1% CAGR from 2026 to 2036 and reach USD 152.0 billion, since new spectrum keeps upgrade cycles going.
Which component holds a notable market share in 2026?
Solutions are expected to hold 46% of component sales in 2026, as buyers prefer managed systems over loose hardware.
Which density holds a notable market share in 2026?
Enterprise-class deployments are likely to account for 63% of density sales in 2026, given that most organisations need reliable coverage across floors.
Which country has a notable expansion outlook through 2036?
China leads the profiled countries in the FMI outlook at a 10.5% CAGR, as factories and offices move to newer Wi-Fi standards.
Who are the key companies in the wi-fi market?
Cisco Systems, Hewlett Packard Enterprise (Aruba Networks) and Ubiquiti lead enterprise systems, Broadcom and Qualcomm Technologies lead chipsets, and NETGEAR and TP-Link Technologies lead consumer equipment, since each controls a different layer of the network.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Component, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Component, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Component, 2026 to 2036
- Hardware
- Solutions
- Services
- Y-o-Y Growth Trend Analysis By Component, 2021 to 2025
- Absolute $ Opportunity Analysis By Component, 2026 to 2036
- Global Market Analysis and Forecast, By Density, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Density, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Density, 2026 to 2036
- Hi-density
- Enterprise-class
- Y-o-Y Growth Trend Analysis By Density, 2021 to 2025
- Absolute $ Opportunity Analysis By Density, 2026 to 2036
- Global Market Analysis and Forecast, By Location Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Location Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Location Type, 2026 to 2036
- Indoor
- Outdoor
- Y-o-Y Growth Trend Analysis By Location Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Location Type, 2026 to 2036
- Global Market Analysis and Forecast, By Organization Size, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Organization Size, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Organization Size, 2026 to 2036
- Large Enterprises
- SMEs
- Y-o-Y Growth Trend Analysis By Organization Size, 2021 to 2025
- Absolute $ Opportunity Analysis By Organization Size, 2026 to 2036
- Global Market Analysis and Forecast, By Vertical, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Vertical, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Vertical, 2026 to 2036
- Education
- Healthcare and Life Sciences
- Transportation and Logistics
- Retail and E-commerce
- Government
- Manufacturing
- Hospitality
- Others
- Y-o-Y Growth Trend Analysis By Vertical, 2021 to 2025
- Absolute $ Opportunity Analysis By Vertical, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Component
- By Density
- By Location Type
- By Organization Size
- By Vertical
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Cisco Systems
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Hewlett Packard Enterprise (Aruba Networks)
- Ubiquiti
- Broadcom
- Qualcomm Technologies
- NETGEAR
- TP-Link Technologies
- Samsung Electronics
- D-Link
- Zyxel Communications
- Cisco Systems
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


