

- Market Size (2026)
- USD 4.2 Bn
- Forecast (2036)
- USD 5.8 Bn
- CAGR (2026 to 2036)
- 3.3%
How big is Herbal Tea Market in 2026?
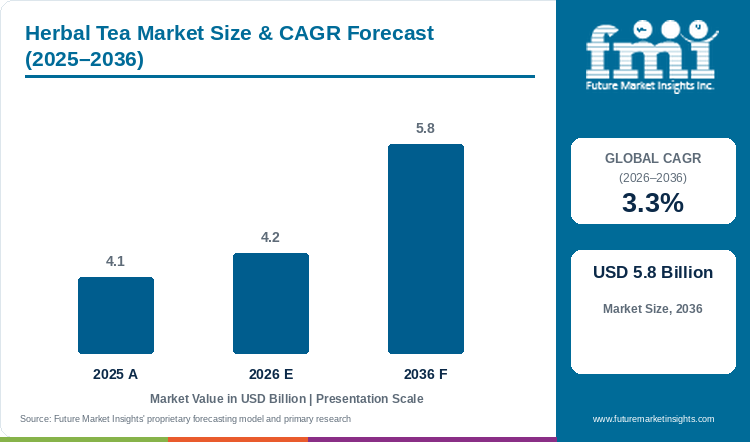
Sales in the herbal tea market are projected to grow at 3.3% CAGR, with the market size rising from USD 4.1 billion in 2025 to USD 4.2 billion in 2026 and reaching USD 5.8 billion by 2036.
Rising consumer fatigue with synthetic wellness supplements and high-caffeine beverages has surged the requirement for gentle, caffeine-free botanical infusions that support restorative sleep, digestive comfort, and daily stress mitigation without disrupting established household habits. Managing routine hydration and preventative health is a critical task, as consumers increasingly seek functional ingredients that deliver tangible physiological relief while remaining suitable for repeated daily consumption. This generates an expanding need for standardized herbal tea formulations that combine certified botanical purity with recognizable flavor profiles and convenient portion packaging. According to Future Market Insights analysis, the global herbal tea market stands at USD 4.1 billion in 2025 and rises to USD 4.2 billion in 2026. Industry valuation is projected to reach USD 5.8 billion by 2036, expanding at a 3.3% CAGR and generating USD 1.6 billion in added revenue over the forecast period. Chamomile accounts for 32.0% of ingredient demand in 2026, tea bags hold 58.0% of packaging volume owing to standardized dosing and mess-free preparation, and supermarkets represent 40.0% of distribution channel revenue. In January 2026, official export data from the Indian Tea Association confirmed that national tea shipments reached a record 285.5 million kilograms in 2025, providing regional blenders with an extensive processing foundation to scale value-added botanical infusions [1]. However, agricultural harvest volatility, pesticide residue enforcement across export corridors, and rapid moisture degradation during maritime storage continue to constrain supplier operating margins. Related context is also visible in botanical infusion demand.
Key Market Trends & Insights
- By ingredient: Chamomile is projected to account for 32.0% in 2026, supported by established use in relaxation-focused blends.
- By packaging: Tea bags are estimated to hold 58.0% in 2026, owing to measured portions and convenient daily preparation.
- By distribution channel: Supermarkets and hypermarkets are forecast to represent 40.0% in 2026, driven by high shopper traffic and broad assortment visibility.
Regional Highlights
- Fastest-growing evaluated country: India, at 5.2% CAGR from 2026 to 2036.
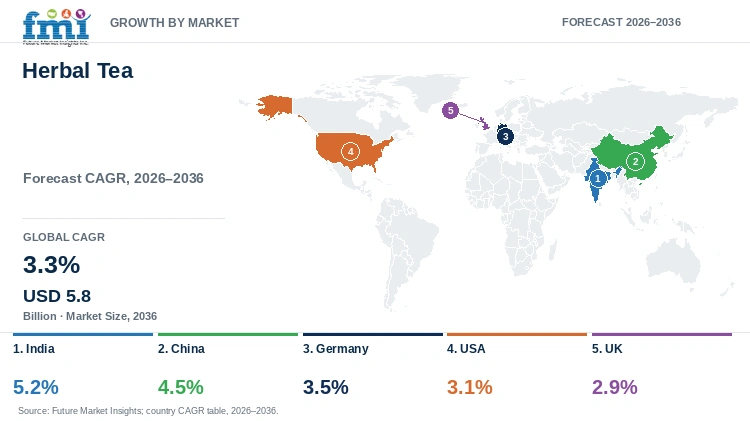
- China follows at 4.5%, while Germany reaches 3.5%, the USA 3.1%, and the UK records 2.9%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Herbal Tea Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 4.1 billion |
| Estimated Market Size in 2026 | USD 4.2 billion |
| Projected Market Size by 2036 | USD 5.8 billion |
| CAGR, 2026 to 2036 | 3.3% |
| Added Revenue, 2026 to 2036 | USD 1.6 billion |
Commercial conditions differ across the profiled countries owing to regional infusion traditions and supermarket shelf allocation practices. Retailers are giving more space to blends that explain their use in simple words, but this does not mean every functional claim will travel easily. A product still has to taste familiar, remain affordable and carry enough ingredient support for the claim printed on the pack. In July 2025, Celestial Seasonings expanded its core wellness portfolio with targeted herbal blends addressing mood balance, sleep hygiene, digestion, and daily vitality, illustrating how mainstream retail fixtures are shifting from simple botanical names toward occasion-based functional sets [2]. For suppliers, the commercial opportunity will remain stronger where wellness intent is immediately evident without forcing the tea to resemble an intimidating clinical supplement.
Household Consumption and Pack Requirement Sizing
Table 2: Consumption and Pack Requirement Sizing for the Herbal Tea Market (USD billion and scenario indicators), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 4.1 | 4.2 | 5.8 |
| Estimated retail packs sold (million) | 430 to 485 | 445 to 500 | 560 to 650 |
| Average cups per pack | 18 to 22 | 18 to 22 | 19 to 24 |
| Implied cups consumed (billion) | 7.7 to 10.7 | 8.0 to 11.0 | 10.6 to 15.6 |
Per Capita and Retail Channel Sizing
Herbal infusions are moving from occasional purchase towards repeated household use, although the route to scale remains different by channel. Supermarkets build reach because the buyer can compare a chamomile, ginger or peppermint blend during the normal grocery trip. Online retail works better for narrow botanicals, mixed packs and subscriptions, but repeat orders can fall if the first cup does not justify the premium. This is why ingredient clarity, freshness protection and an easy preparation format are likely to matter more than adding a longer list of herbs.
Table 3: Per Capita Spending Indicators for the Herbal Tea Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD) | 0.49 | 0.51 | 0.65 |
| Spend per 1,000 people (USD) | 494 | 506 | 648 |
| Estimated annual household spend (USD) | 3.80 to 5.60 | 3.90 to 5.80 | 4.90 to 7.60 |
Table 4: Retail Channel Spending Indicators for the Herbal Tea Market (USD billion and percentages), 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 4.2 billion | Report value |
| Supermarket and hypermarket revenue | USD 1.7 billion | 40.0% share |
| Tea bag packaging revenue | USD 2.4 billion | 58.0% share |
| Chamomile ingredient revenue | USD 1.3 billion | 32.0% share |
Analyst Perspective
“Herbal tea is moving from flavor-led purchase toward defined wellness occasions. Brands combining trusted botanicals with credible sourcing will strengthen repeat retail demand.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the herbal tea market segmented?
The herbal tea market is segmented by ingredient, packaging, and distribution channel. In 2026, chamomile is projected at 32.0%, tea bags at 58.0%, and supermarkets and hypermarkets at 40.0%.
By ingredient: Chamomile, Peppermint, Ginger, Hibiscus, and Others.
By packaging: Tea Bags, Loose Leaf, Ready-to-Drink, and Others.
By distribution channel: Supermarkets/Hypermarkets, Specialty Stores, Online Retail, and Convenience Stores.
Why does Chamomile lead the ingredient category?
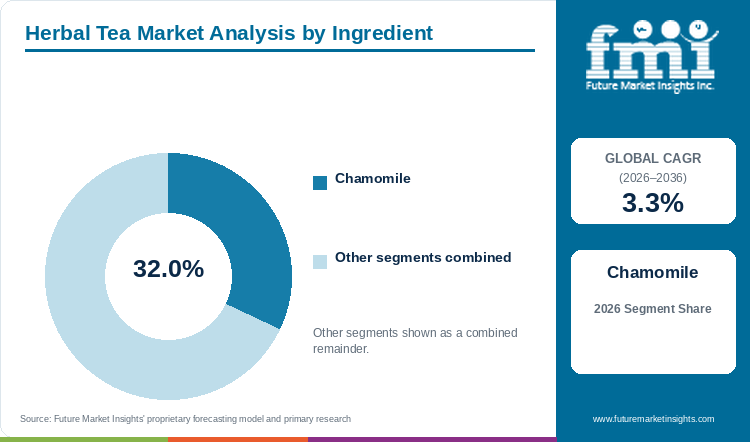
Chamomile represents 32.0% of ingredient demand in 2026, supported by familiar relaxation positioning and broad blend compatibility.
Table 5: Ingredient Share for the Herbal Tea Market (percentage share), 2026
| Ingredient | Share (2026) |
|---|---|
| Chamomile | 32.0% |
| Other Segments Combined | 68.0%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment share from 100.0%.
Table 6: Ingredient Leadership and Market Growth for the Herbal Tea Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 3.3% |
| Leading Segment | Chamomile |
Chamomile leads because the ingredient does not need a long explanation before purchase. Buyers already connect it with evening use, while overlap with organic tea gives certified blends another value cue. Its 32.0% share in 2026 therefore reflects familiarity along with formulation flexibility, although weak harvest quality or an over-priced claim can still move buyers towards alternatives.
- Chamomile is projected to hold 32.0% of ingredient demand in 2026, reinforced by established household familiarity.
- A current product and market review confirms chamomile as the leading ingredient within the 2026 segment structure.
What keeps Tea Bags ahead by packaging?
Tea bags account for 58.0% of packaging in 2026, pairing measured preparation with convenient storage and retail handling.
Tea bags stay ahead because the format fixes quantity and shortens preparation. Development in tea and coffee bags also gives suppliers room to improve barrier and material choice without changing the single-serve habit. The 58.0% share will remain easier to defend if these changes do not push a familiar drink too far into premium pricing.
- By packaging, tea bags are estimated to hold 58.0% in 2026, driven by portion control and convenience.
- Product innovation increasingly focuses on biodegradable materials and structures that protect volatile botanical oils.
What gives Supermarkets and Hypermarkets the leading channel position?
Supermarkets and hypermarkets hold 40.0% of sales in 2026, driven by broad choice and frequent household shopping.
Supermarkets and hypermarkets hold 40.0% share because herbal tea is still purchased more often with routine groceries. Wider work in tea packaging matters here because shelf life and freshness protection have to survive high-volume handling. Slow-moving claims or stock variation can shorten a listing, whereas clear ingredients and dependable supply can turn trial into repeat purchase.
- Supermarkets and hypermarkets are forecast to represent 40.0% in 2026, underpinned by dependable shopper traffic.
- Retail listing increasingly depends on traceability, packaging compliance, and credible wellness communication.
What are the drivers, restraints, and opportunities in the herbal tea market?
Wellness routines lift repeat demand, botanical volatility restrains margin stability, and credible functional blends create premium retail value.
- Driver: Consumers are integrating caffeine-free infusions into sleep, digestion, hydration, and stress-management routines.
- Restraint: Botanical harvest variability and claim substantiation raise sourcing, formulation, and compliance costs.
- Opportunity: Functional blends and sustainable packaging can widen value per pack across grocery and digital channels.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Daily wellness routines are widening the use of herbal tea beyond an occasional evening cup. Sleep, digestion and caffeine reduction are understandable needs, which helps a blend enter regular use without the buyer treating it as medicine. India produced 1,395.5 million kilograms of tea and exported 285.5 million kilograms in 2025, showing that a major sourcing country has both material availability and a stronger route towards value-added exports. This can favour packaged herbal formats, although growth will depend on whether processors control botanical quality and keep the final pack within a price that mass retail can carry.
Risk Assessment of the Herbal Tea Market: Sourcing and Claims Friction
Botanical sourcing can disturb the market even when consumer demand remains present. Heat, uneven rainfall and storage conditions can change aroma, moisture and the strength of one production lot against another. A brand may then face higher testing cost or reformulation before the product reaches retail. The risk becomes larger when benefit language is stronger than the evidence behind it, as one rejected label can delay a complete launch. Multi-origin buying and tighter incoming checks can reduce this variation, but smaller suppliers may find the added inventory and qualification cost difficult to absorb. [3].
Commercial Opportunity Analysis: Functional Blends and Value-Add Formats
Functional blends create value when the use occasion is easy to recognise. Demand around fruit tea can also make botanical blends easier to trial through familiar taste. Celestial Seasonings and Bigelow show how known ingredients are being tied to daily needs, although unclear claims or unstable flavour will limit repeat sales after the first purchase [4].
Herbal Tea Market by Country (2026 to 2036)
Country growth will not move through one common reason. India reaches 5.2% CAGR as processing and packaged exports improve, China follows at 4.5% where loose-leaf habits can support premium value, while Germany at 3.5% depends more on documented quality. The USA reaches 3.1% through benefit-led retail, whereas the UK records 2.9% as herbal formats gain buyers but remain exposed to promotion and private labels. The difference shows that botanical availability may open supply in one country, while retail access, local taste or compliance decides whether the same blend can scale in another.
Table 7: Country CAGR and Primary Growth Levers for the Herbal Tea Market (CAGR percentage and commercial drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| India | 5.2% | Value-added processing and export momentum |
| China | 4.5% | Large domestic tea demand and premium loose-leaf traditions |
| Germany | 3.5% | Established herbal infusion culture and quality standards |
| USA | 3.1% | Functional wellness positioning and specialty retail breadth |
| UK | 2.9% | Younger consumers shifting from black tea toward herbal formats |
Source: Future Market Insights analysis
India Herbal Tea Market Outlook (2026 to 2036)
India is likely to grow faster because the market has a large tea-processing base, familiar botanicals such as tulsi and ginger, and a stronger reason to move exports beyond bulk leaf. Tea production reached 1,395.5 million kilograms in 2025 and exports touched 285.5 million kilograms, but auction prices did not rise with labour, energy and compliance cost. This creates two directions at the same time. Packaged herbal blends can improve value per kilogram, while climate pressure and weak producer margins can disturb raw material consistency. The 5.2% CAGR will therefore depend on how quickly suppliers convert available processing capacity into repeatable, shelf-ready products rather than only adding more blends.
Key takeaway: In India, export momentum and familiar botanicals are moving suppliers toward shelf-ready value-added formats.
China Herbal Tea Market Outlook (2026 to 2036)
China is different from the global market because herbal infusion knowledge sits beside a deep loose-leaf culture. Interest in tea polyphenols supports ingredient-led communication, but local taste remains decisive. The 4.5% CAGR can be supported by origin and gifting, while a transferred western blend may struggle if flavour strength and pack size do not match local buying habits.
Key takeaway: In China, premium loose-leaf habits support value while competition for top-grade botanicals tightens sourcing.
Germany Herbal Tea Market Outlook (2026 to 2036)
Germany does not need the herbal infusion category to be introduced, which changes the basis of growth. The 3.5% CAGR is more likely to come from certified ingredients, organic ranges and blends for digestion or evening use than from broad flavour novelty. Buyers across grocery, pharmacy and specialist channels expect residue control, documented origin and stable sensory quality. These conditions favour suppliers that can repeat the same cup across batches, while a cheaper blend with weak paperwork may find entry difficult even when the ingredients are familiar.
Key takeaway: In Germany, strict quality expectations favor certified suppliers with consistent flavor and documented origin.
USA Herbal Tea Market Outlook (2026 to 2036)
The USA market places herbal tea inside a crowded wellness space. Expansion of ready-to-drink tea can open colder and on-the-go occasions, but it also puts herbal products against functional waters and energy drinks. Grocery distribution can build scale, while a costly blend with no clear taste reason may disappear inside the wider beverage aisle.
Key takeaway: In USA, defined wellness benefits and grocery access shape repeat purchase across a crowded beverage aisle.
UK Herbal Tea Market Outlook (2026 to 2036)
The UK carries a strong tea habit, but herbal growth is coming from consumers adding or replacing a black-tea occasion. Product learning from pyramid tea bags can improve infusion and premium presentation, although packaging still has to protect aroma at an accessible price. Private labels and promotions will continue to limit how far brands can raise value per pack.
Key takeaway: In UK, channel shifts and younger demand support herbal formats despite promotional pressure in mainstream retail.
Full report country CAGRs cover: North America; Latin America; Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the herbal tea market?
Twinings, Celestial Seasonings, Tielka, Traditional Medicinals, Bigelow Tea, Tata Consumer Products, Pukka Herbs, VAHDAM India, Rishi Tea & Botanicals, and Bird & Blend Tea Co. are the significant market players in this market.
Competition is divided by the route used to win repeat purchase. Large platforms can use grocery scale, while specialists use botanical authority and brands active in matcha products show how provenance can support premium positioning. A broad range without clear use can still slow on shelf, and a strong story can fail where supply varies between batches.
- Global Tea Platforms: Twinings, Tata Consumer Products, and Pukka Herbs combine established sourcing with broad retail networks.
- Wellness and Herbal Specialists: Celestial Seasonings, Traditional Medicinals, and Bigelow Tea emphasize recognizable benefit-led blends.
- Premium and Digital Specialists: Tielka, VAHDAM India, Rishi Tea & Botanicals, and Bird & Blend Tea Co. focus on premium provenance and direct engagement.
Competitive Benchmarking: Herbal Tea Market
Table 8: Competitive Benchmarking for the Herbal Tea Market (qualitative capability ratings), 2026
| Company | Herbal Blend Breadth | Functional Positioning | Retail / Digital Access | Geographic Reach |
|---|---|---|---|---|
| Twinings | High | High | High | High |
| Celestial Seasonings | High | High | High | Medium |
| Tielka | Medium | Medium | Medium | Low |
| Traditional Medicinals | High | High | High | Medium |
| Bigelow Tea | High | High | High | Medium |
| Tata Consumer Products | High | Medium | High | High |
| Pukka Herbs | High | High | High | High |
| VAHDAM India | High | Medium | High | High |
| Rishi Tea & Botanicals | High | High | Medium | Medium |
| Bird & Blend Tea Co. | High | Medium | High | Low |
Scoring basis: High indicates broad public evidence across the capability. Medium indicates a narrower or regionally concentrated offering. Low indicates limited documented reach relative to the evaluated group.
Key Developments in the Herbal Tea Market
- In August 2025, Bigelow Tea introduced Golden Turmeric Honey Herbal Tea plus Adaptogens with turmeric, tulsi leaf, and dandelion root.
- In July 2025, Celestial Seasonings expanded its wellness tea platform with new functional blends for defined daily need states.
Key Players in the Herbal Tea Market
Global Tea Platforms
- Twinings
- Tata Consumer Products
- Pukka Herbs
Herbal Wellness Specialists
- Celestial Seasonings
- Traditional Medicinals
- Bigelow Tea
Premium and Digital Brands
- Tielka
- VAHDAM India
- Rishi Tea & Botanicals
- Bird & Blend Tea Co.
Herbal Tea Market - Report Scope
Table 9: Report Scope for the Herbal Tea Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Ingredient; Packaging; Distribution Channel |
| Quantitative Units | USD Billion |
| Market Definition | Commercial infusions made from fruits, herbs, spices, flowers, and other plant materials excluding conventional Camellia sinensis tea as the primary base. |
| Regions Covered | North America; Latin America; Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | India, China, Germany, USA, UK, and additional countries in the full report |
| Key Companies Covered | Twinings, Celestial Seasonings, Tielka, Traditional Medicinals, Bigelow Tea, Tata Consumer Products, Pukka Herbs, VAHDAM India, Rishi Tea & Botanicals, Bird & Blend Tea Co. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Herbal Tea Market - Research Methodology
Table 10: Research Methodology for the Herbal Tea Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with manufacturers, suppliers, distributors, retailers, industry experts, and key opinion leaders across the value chain to validate demand patterns, sourcing conditions, channel dynamics, and purchasing decisions. |
| Secondary Research | Secondary research included company annual reports, investor presentations, regulatory publications, industry associations, technical papers, trade journals, company websites, product literature, and other public sources relevant to herbal beverages. |
| Market Sizing and Forecasting | Market sizing and forecasting for 2026 to 2036 used top-down and bottom-up approaches to assess revenue, channel mix, ingredient demand, and packaging adoption. |
| Data Triangulation and Validation | Data was validated against macro-economic indicators, consumption patterns, regulatory conditions, official trade statistics, and historical trend analysis to support accuracy without double counting adjacent tea categories. |
Herbal Tea Market by Segments
Herbal Tea Market segmented by Ingredient:
- Chamomile
- Peppermint
- Ginger
- Hibiscus
- Others
Herbal Tea Market segmented by Packaging:
- Tea Bags
- Loose Leaf
- Ready-to-Drink
- Others
Herbal Tea Market segmented by Distribution Channel:
- Supermarkets/Hypermarkets
- Specialty Stores
- Online Retail
- Convenience Stores
Herbal Tea Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Indian Tea Association. (2026). ITA Tea India Publication 2026: Official export statistics and production review..
- [2] The Hain Celestial Group. (2025, July 29). Celestial Seasonings Tea Expands Category-Leading Wellness Platform with New Line of Benefit Teas..
- [3] Indian Tea Association. (2026). White Paper on Darjeeling Tea Industry: Agricultural harvest economics and climate impact..
- [4] Bigelow Tea. (2025, August 19). Bigelow Tea Launches New Golden Turmeric Honey Herbal Tea plus Adaptogens..
The bibliography lists the authoritative sources used for external statistics and company developments in this report.
This Report Answers
- How large is the herbal tea market in 2026 and what is forecast for 2036?
- Which wellness and sourcing pressures support demand for herbal tea?
- Why does chamomile lead ingredient demand?
- Why do tea bags remain the leading packaging format?
- How do growth rates differ across India, China, Germany, the USA, and the UK?
- Which companies supply significant herbal tea ranges today?
- What limits functional blend adoption and supplier switching?
- What should retail buyers evaluate before selecting an herbal tea supplier?
Frequently Asked Questions
How big is the herbal tea market in 2026, and what is forecast for 2036?
Future Market Insights estimates that the global herbal tea market will reach USD 4.2 billion in 2026. The market is projected to reach USD 5.8 billion by 2036.
What is the CAGR for the herbal tea market from 2026 to 2036?
Future Market Insights projects a 3.3% CAGR over the assessment period. Growth is supported by caffeine-free wellness routines and wider functional positioning.
Which ingredient segment leads the herbal tea market?
Chamomile is projected to account for 32.0% share in 2026 due to strong household recognition and relaxation-led use.
Which packaging segment leads the herbal tea market?
Tea bags are projected to hold 58.0% share in 2026 as measured portions and easy preparation sustain mass-market use.
Which country has a notable growth outlook?
India is projected to register a 5.2% CAGR from 2026 to 2036, supported by value-added processing and export momentum.
Who are the key players in the market?
Key participants include Twinings, Celestial Seasonings, Traditional Medicinals, Bigelow Tea, Tata Consumer Products, Pukka Herbs, VAHDAM India, and other established specialists.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Ingredient, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Ingredient, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Ingredient, 2026 to 2036
- Chamomile
- Peppermint
- Ginger
- Hibiscus
- Others
- Y-o-Y Growth Trend Analysis By Ingredient, 2021 to 2025
- Absolute $ Opportunity Analysis By Ingredient, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging, 2026 to 2036
- Tea Bags
- Loose Leaf
- Ready-to-Drink
- Others
- Y-o-Y Growth Trend Analysis By Packaging, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Supermarkets/Hypermarkets
- Specialty Stores
- Online Retail
- Convenience Stores
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Ingredient
- By Packaging
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Ingredient
- By Packaging
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Ingredient
- By Packaging
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Ingredient
- By Packaging
- By Distribution Channel
- Key Takeaways
- Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Ingredient
- By Packaging
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Ingredient
- By Packaging
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Ingredient
- By Packaging
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Ingredient
- By Packaging
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Ingredient
- By Packaging
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Ingredient
- By Packaging
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Ingredient
- By Packaging
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Ingredient
- By Packaging
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient
- By Packaging
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient
- By Packaging
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient
- By Packaging
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient
- By Packaging
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient
- By Packaging
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient
- By Packaging
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient
- By Packaging
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient
- By Packaging
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient
- By Packaging
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient
- By Packaging
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient
- By Packaging
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient
- By Packaging
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient
- By Packaging
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient
- By Packaging
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient
- By Packaging
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient
- By Packaging
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient
- By Packaging
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient
- By Packaging
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Ingredient
- By Packaging
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Twinings
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Celestial Seasonings
- Tielka
- Traditional Medicinals
- Bigelow Tea
- Tata Consumer Products
- Pukka Herbs
- VAHDAM India
- Rishi Tea & Botanicals
- Bird & Blend Tea Co.
- Twinings
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


