

- Market Size (2026)
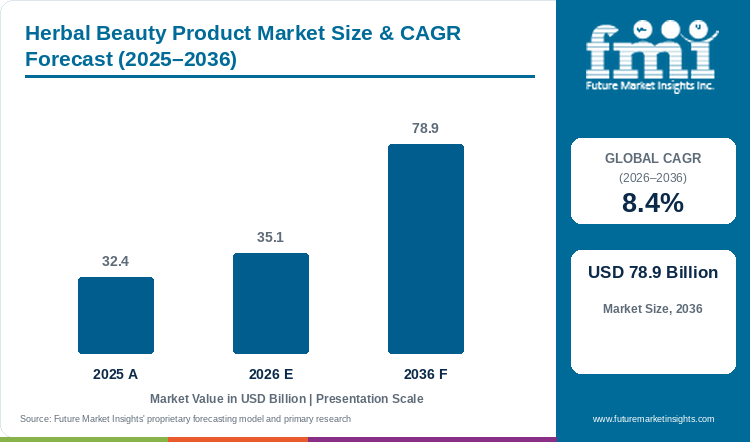
- USD 35.1 Bn
- Forecast (2036)
- USD 78.9 Bn
- CAGR (2026 to 2036)
- 8.4%
How big is the herbal beauty product market in 2026?
Demand is projected to expand at 8.4% CAGR from 2026 to 2036. Market value rises from USD 32.38 billion in 2025 to USD 35.1 billion in 2026 and USD 78.9 billion by 2036. [1]
FMI values the herbal beauty product market at USD 35.1 billion in 2026, compared with USD 32.38 billion in 2025, and projects USD 78.9 billion by 2036 at an 8.4% CAGR. [1] Skincare accounts for 52.0% by product and specialty stores represent approximately 31.2% by distribution channel in 2026, leading the respective classifications of finished herbal beauty products. [1] Botanical ingredients contribute to the formulation alongside other materials, with species identity, extract specifications and intended cosmetic use helping explain the actual product offered to the customer. Kew's Medicinal Plant Names Services links scientific, common and pharmaceutical names, with its version 15 resource published in 2025 explaining that one name can refer to different species. [2] Scientific identity consequently provides a useful basis for specifying botanical materials, while the complete formula determines texture and use rather than a broad plant-origin description alone. EU fragrance-allergen requirements address specified substances and thresholds, with the 2026 transition creating a concrete labelling consideration for relevant products at the applicable supply stage. [3] FDA distinguishes cosmetic claims from claims to treat disease or affect body structure or function, making the intended description relevant when a supplier explains the purpose of a herbal beauty formulation. [4] The USA has the fastest profiled growth rate at 9.1% CAGR from 2026 to 2036, within an outlook covering skincare, hair care, colour cosmetics, fragrance and bath products. [1] Suppliers can improve range clarity through consistent sourcing records and formulation-specific information, helping retailers connect the botanical material with the actual cosmetic use described for each finished product.
Key Market Trends and Insights
- Skincare carries 52.0% of the forecast product mix. [1]
- Specialty stores account for approximately 31.2% of the channel mix. [1]
- Botanical naming and applicable allergen labels require specific records. [2][3]
Regional Highlights
- Fastest-growing profiled market: USA at 9.1% CAGR from 2026 to 2036. [1]
- EU Regulation 2023/1545 sets 31 July 2026 as the placing-on-market transition and 31 July 2028 as the making-available transition for qualifying products. The dates concern different supply stages for relevant fragrance-allergen labelling. [3]
Market Size and Forecast
Table 1: Market size and forecast for the herbal beauty product market in USD billion and percentage
| Metric | Value |
|---|---|
| 2025 market size | USD 32.38 billion |
| Estimated market size in 2026 | USD 35.1 billion |
| Projected market size by 2036 | USD 78.9 billion |
| CAGR 2026 to 2036 | 8.4% |
| Added revenue 2026 to 2036 | USD 43.8 billion |
| Market expansion multiple | 2.2x |
Repeatable sourcing supports consistent finished formulations. Organic cosmetics add a separate sourcing preference, while vegan cosmetics address ingredient origin. Botanical species and extract specifications remain relevant to the herbal formulation itself.
Botanical Identity and 2026 Labelling Conditions
Kew provides botanical nomenclature and reference information. EU fragrance-allergen rules address specified substances and thresholds, linking ingredient records with applicable finished-product labelling. [2][3]
Table 2: Evidence and adoption indicators for the herbal beauty product market
| Indicator | Data point or finding | Commercial relevance | Source |
|---|---|---|---|
| Kew name resource | MPNS version 15 published in 2025 | Common and scientific names need reconciliation | [2] |
| EU placing-on-market transition | 31 July 2026 for qualifying products | New supply requires the applicable labelling assessment | [3] |
| EU making-available transition | 31 July 2028 for qualifying earlier products | Distinguishes later distribution from new placement | [3] |
| US claim boundary | Disease and body-function claims can change product classification | Herbal wording does not settle a product's intended use | [4] |
Analyst Perspective
"A botanical ingredient needs a clear scientific identity and material specification before it can support a consistent finished-product description. The formula then determines the intended cosmetic use and texture, with relevant label requirements assessed for the substances actually present. Facial oils offer another product format where the ingredient and use description need to work together. Suppliers make herbal beauty products easier to compare when botanical records stay connected with the complete formula and the claim presented to the customer."
- Rahul Pandita, Principal Analyst at Future Market Insights
How is the herbal beauty product market segmented?
The market covers 3 commercial axes and region: product type; botanical source; distribution channel.
By product type: Skincare; Hair care; Colour cosmetics; Fragrances; Bath and body. By botanical source: Botanical extracts; Essential oils; Plant-based actives; Herbal formulations. By distribution channel: Specialty stores; Online retail; Supermarkets and hypermarkets; Direct sales.
Why does skincare lead demand within the product type category?
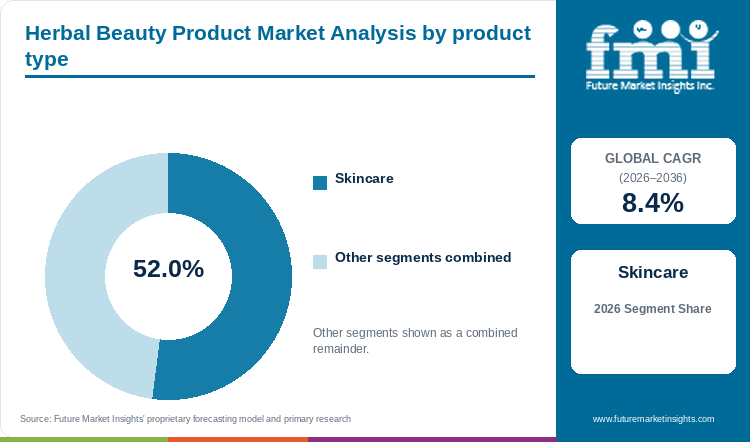
The skincare segment accounts for 52.0% of product type demand in 2026. [1]
Herbal skincare brings botanical materials into finished formulations intended for different textures and cosmetic uses, giving the product category a range of practical applications within the beauty offer. The complete formula determines how those ingredients contribute to the product, making species identity and material specifications relevant alongside the label's plant-origin wording. Cold-pressed soap illustrates another format where botanical content and processing form part of the description. Skincare's leading share therefore needs to be understood through the actual formulations and intended uses included in the product mix.
- Skincare accounts for 52.0% of product demand in 2026, leading the herbal beauty classification that also includes hair care, colour cosmetics, fragrances, and bath and body formulations across distribution channels. [1]
- Scientific botanical identity and material specifications help describe the ingredients in a skincare formula, while the completed product determines the texture and cosmetic use presented to the customer at purchase.
Table 3: Leading product type share for the herbal beauty product market
| Product type | Share in 2026 |
|---|---|
| Skincare | 52.0% |
| Other segments combined | 48.0% |
| Total | 100.0% |
Table 4: Segment leadership and market growth for the herbal beauty product market
| Metric | Value |
|---|---|
| Global CAGR 2026 to 2036 | 8.4% |
| Leading segment | Skincare |
Why do specialty stores lead demand within the distribution channel category?
The specialty stores segment accounts for approximately 31.2% of distribution channel demand in 2026. [1]
Specialty stores provide a setting in which customers can compare ingredient and use differences across herbal beauty products, making understandable formula information relevant to the retail offer. A clear description connects the botanical identity with the material used and the purpose of the finished cosmetic, helping buyers assess nearby alternatives within a range. The product still needs its own formulation and label record because a store format does not establish ingredient quality or eligibility. These information needs help explain the leading role of specialty stores within the channel outlook.
- Specialty stores account for approximately 31.2% of channel demand in 2026, leading the distribution mix that also includes online retail, supermarkets and hypermarkets, and direct sales of herbal beauty products. [1]
- Retail product information can connect botanical identity with the complete formula and intended use, helping customers compare products through specific ingredient descriptions while the relevant cosmetic claims and labelling requirements remain clear.
What are the drivers restraints and opportunities in the herbal beauty product market?
- Driver: Finished formulas can differentiate through their actual botanical materials and intended cosmetic use, supporting repeated purchasing when consistent sourcing and product descriptions allow customers to identify the formulation they selected across the available beauty categories and sales channels.
- Restraint: Common plant names can refer to different species, requiring specific botanical records and material specifications, while the product description needs to retain the distinction between an intended cosmetic use and a claim to treat disease or affect body function. [2][4]
- Opportunity: Botanical-name reconciliation helps maintain clear sourcing records, while relevant EU fragrance-allergen transitions give suppliers a concrete opportunity to review formula-specific labels and the supply stage affected by the applicable requirements during the product's distribution. [2][3]
Defined botanical formulations support differentiated products
A finished formula can differentiate through its actual botanical materials and intended cosmetic use, with consistent sourcing and product descriptions supporting repeat purchases by helping customers recognize the formulation beyond the broad wording of a plant-origin label.
Ambiguous plant names and overextended claims complicate qualification
Kew documents ambiguity in common plant names, making scientific species identity and material specifications relevant to the supplied extract while FDA distinguishes ordinary cosmetic purposes from claims to treat disease or affect body structure or function. [2][4]
Identity records and label updates can improve range consistency
Botanical-name reconciliation helps maintain clear sourcing records, while the 2026 EU fragrance-allergen transition gives suppliers a specific reason to review the formula's labels and the supply stage affected by the relevant requirements for its actual substances. [2][3]
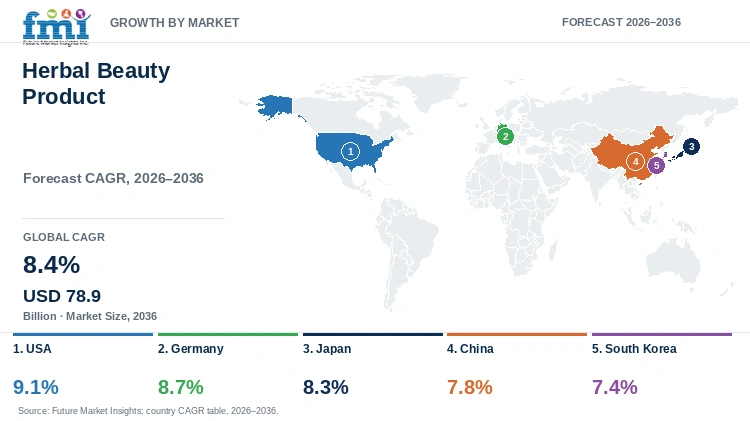
Which country CAGRs are profiled in the herbal beauty product market?
Table 5: Country CAGR comparison for the herbal beauty product market
| Country | CAGR 2026 to 2036 |
|---|---|
| USA | 9.1% |
| Germany | 8.7% |
| Japan | 8.3% |
| China | 7.8% |
| South Korea | 7.4% |
Country-wise Analysis
USA
How a herbal beauty product is described matters in the USA, because FDA distinguishes cosmetic purposes from claims to treat disease or affect the body's structure or function. [4] A botanical skincare range can explain its texture, intended cosmetic use and ingredients while keeping that description tied to the formula supplied. This claim setting accompanies the fastest profiled forecast, with USA demand projected to expand at 9.1% CAGR from 2026 to 2036. [1] Ingredient identity also affects sourcing: Kew's plant-name resource helps connect common names with scientific names, giving formulators a basis for specifying the botanical material. [2] Retailers can bring those details into product selection alongside ordinary questions about application and routine, allowing the plant-origin description to support a comparison of finished cosmetics rather than stand in for it.
Germany
Germany's established natural-beauty retail offer gives botanical ranges access to customers who compare ingredient information and certified-organic positioning alongside product performance. [1] For relevant fragranced formulations, the EU's revised allergen-labelling rules introduce a separate, substance-specific requirement, with the 31 July 2026 placing-on-the-market deadline and the later transition for eligible existing products needing to be distinguished. [3] Suppliers therefore need to relate the label to the complete formula and its supply stage, including when botanical oils contribute fragrance substances. Germany's 8.7% CAGR from 2026 to 2036 sits within this combination of consumer interest and formulation requirements. [1] Retail buyers can assess the range through accurate ingredient records and clear use information, while an organic or herbal description continues to identify particular product attributes without establishing every aspect of the cosmetic's performance.
Japan
Japanese customers selecting a botanical skincare product still compare how it feels and fits their routine, giving formulation texture and use information a practical role alongside the ingredient story. The country outlook links herbal extracts with established cosmetic development, within projected growth of 8.3% CAGR from 2026 to 2036. [1] Formulators maintaining such a range need a reproducible material specification, because common plant names can refer to different species and extracts can differ in the material supplied. Kew's Medicinal Plant Names Services provides a resource for connecting those identities. [2] That sourcing detail supports consistency between product batches, while the retailer's description explains what the finished cleanser, moisturiser or other cosmetic is intended to do. A useful range therefore brings the botanical record and the ordinary experience of using the formulation together.
China
China's botanical resources and established herbal knowledge provide a sourcing and development context for finished beauty formulations. [1] The material's identity remains important when a manufacturer turns that background into a reproducible cosmetic, since a marketing name may not describe the species or extract actually purchased. Kew's naming resource helps explain this distinction between familiar plant terminology and a scientific material record. [2] Within the market outlook, China is projected to record 7.8% CAGR from 2026 to 2036 as botanical ingredients are used across several beauty categories. [1] Suppliers can relate sourcing information to the texture and cosmetic purpose of the finished item, allowing retailers to compare skincare, haircare and other products through their intended use. The commercial offer depends on that delivered formulation and its continuing availability, rather than the reputation of a plant considered in isolation.
South Korea
Formulation development within South Korea's beauty industry gives herbal products a setting in which botanical ingredients are presented alongside texture, application and the finished product's place in a routine. [1] A supplier introducing a plant extract needs to keep the ingredient specification connected with the item delivered to a retailer, particularly when new variants extend an existing range. Kew's plant-name resource provides a useful basis for checking botanical identity across scientific and familiar names. [2] South Korea's 7.4% CAGR from 2026 to 2036 accompanies demand for the finished beauty products covered by the outlook. [1] Retail descriptions can explain the cosmetic use and ordinary differences between formulations, helping customers choose among products without treating a broad herbal label as a complete account of texture, application or the ingredients present in the formula.
Who are the notable companies in the herbal beauty product market?
Weleda; Burt's Bees; Aveda; Origins; Shiseido
Competitive Benchmarking
Table 6: Competitive positioning for the herbal beauty product market
| Company or institution | Positioning | Evidence or purchasing distinction |
|---|---|---|
| Weleda | Botanical personal-care ranges | Assess the actual finished formula and use claim [1] |
| Burt's Bees | Personal-care products | Identify relevant botanical lines within the range [1] |
| Aveda | Hair and personal-care range | Separate product categories and botanical records [1] |
| Origins | Botanical-themed skincare range | Official catalog includes Mega-Mushroom skincare products. [5] |
| Shiseido | Botanical-ingredient skincare within a wider portfolio | Official WASO cleanser page identifies Shikuwasa Japanese lime. [6] |
Key Developments in the Herbal Beauty Product Market
- Kew's Medicinal Plant Names Services version 15, published in 2025, links scientific, common and pharmaceutical names and explains naming ambiguity, giving botanical-material specifications a basis in scientific identity for the plant actually used. [2]
- EU fragrance-allergen labelling requirements include transitions in 2026 and 2028 for the relevant product supply stages, creating a formula-specific need to assess specified substances and thresholds when suppliers review finished-product labels for the market. [3]
Key Players in the Herbal Beauty Product Market
Weleda; Burt's Bees; Aveda; Origins; Shiseido; L'Oréal; Unilever; Estée Lauder Companies.
Herbal Beauty Product Market Report Scope
The market comprises finished beauty products using botanical ingredients across skincare, hair care, colour cosmetics, fragrances, bath and body. Species identity, extract specification and intended cosmetic use describe the formulation; allergen requirements apply to relevant substances and jurisdictions.
Table 7: Report coverage for the herbal beauty product market
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; Botanical source; Distribution channel; region |
| Quantitative units | USD billion |
| Market definition | Finished cosmetic products using botanical extracts, essential oils or plant-based actives within the reported scope. Herbal medicines, teas and food supplements are excluded. Botanical origin does not imply that every ingredient in the formula is plant-derived. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries profiled | USA; Germany; Japan; China; South Korea |
| Key companies profiled | Weleda; Burt's Bees; Aveda; Origins; Shiseido; L'Oréal; Unilever; Estée Lauder Companies |
| Forecast period | 2026 to 2036 |
Herbal Beauty Product Market Research Methodology
Table 8: Research methods for the herbal beauty product market
| Method | Approach |
|---|---|
| Market definition | The study examines the herbal beauty product market through product type, botanical source and distribution channel, identifying the products or services and purchasing transactions covered. |
| Public documentary research | FMI research, Kew botanical references, EU allergen regulations, FDA claims guidance and official product descriptions inform the analysis of product characteristics, operating conditions and market context. |
| Company portfolio research | Official product pages and company disclosures describe relevant offerings, intended customers and participation within wider business portfolios. |
| Segment assessment | The product type, botanical source and distribution channel categories are examined through product or service characteristics, practical use and purchase conditions. |
| Country research | Local distribution, purchasing arrangements and applicable public requirements inform country analysis alongside the reported market outlook. |
| Regulatory and technical assessment | Scientific plant identity, extract specifications and intended cosmetic use inform formulation assessment, alongside substance-specific allergen requirements and the relevant product supply stage. |
| Forecast coverage | The forecast considers the demand drivers, purchasing constraints and supplier opportunities affecting the market across the study period. |
Herbal Beauty Product Market by Segments
By product type
- Skincare
- Hair care
- Colour cosmetics
- Fragrances
- Bath and body
By botanical source
- Botanical extracts
- Essential oils
- Plant-based actives
- Herbal formulations
By distribution channel
- Specialty stores
- Online retail
- Supermarkets and hypermarkets
- Direct sales
Herbal Beauty Product Market by Region
- North America
- USA
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- UK
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Future Market Insights. Published outlook accessed 12 October 2026. Herbal Beauty Product Market.
- [2] Royal Botanic Gardens Kew. Version 15 published 2025; accessed October 2026. Medicinal Plant Names Services: Resource version.
- [3] European Union. 26 July 2023; transitions in 2026 and 2028. Commission Regulation EU 2023/1545 on labelling of fragrance allergens.
- [4] US Food and Drug Administration. Accessed October 2026. Cosmetics Labeling Claims.
- [5] Origins. Accessed October 2026. Origins Skincare.
- [6] Shiseido. Accessed October 2026. WASO SHIKULIME Gel-to-Oil Cleanser.
This Report Answers
- How big is the herbal beauty product market in 2026?
- What market value is projected by 2036?
- Which product type segment leads demand?
- Which other commercial categories shape the market?
- Which countries have the fastest profiled growth?
- Which companies and institutions participate in the market?
Frequently Asked Questions
How large is the herbal beauty product market in 2026?
FMI estimates market value at USD 35.1 billion in 2026. The estimated 2025 value is USD 32.38 billion. [1]
What value and CAGR are projected through 2036?
Market value is projected to reach USD 78.9 billion by 2036 at a 8.4% CAGR from 2026 to 2036. [1]
Which product type segment leads in 2026?
Skincare accounts for 52.0% of this category. [1]
What is the report segmentation?
Product type; Botanical source; Distribution channel, and region.
Which profiled market records the highest CAGR?
USA has the highest profiled rate at 9.1% from 2026 to 2036. [1]
Who are the key participants?
Weleda; Burt's Bees; Aveda; Origins; Shiseido; L'Oréal; Unilever; Estée Lauder Companies.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By product type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By product type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By product type, 2026 to 2036
- Skincare
- Hair care
- Colour cosmetics
- Fragrances
- Bath and body
- Y-o-Y Growth Trend Analysis By product type, 2021 to 2025
- Absolute $ Opportunity Analysis By product type, 2026 to 2036
- Global Market Analysis and Forecast, By botanical source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By botanical source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By botanical source, 2026 to 2036
- Botanical extracts
- Essential oils
- Plant-based actives
- Herbal formulations
- Y-o-Y Growth Trend Analysis By botanical source, 2021 to 2025
- Absolute $ Opportunity Analysis By botanical source, 2026 to 2036
- Global Market Analysis and Forecast, By distribution channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By distribution channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By distribution channel, 2026 to 2036
- Specialty stores
- Online retail
- Supermarkets and hypermarkets
- Direct sales
- Y-o-Y Growth Trend Analysis By distribution channel, 2021 to 2025
- Absolute $ Opportunity Analysis By distribution channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By product type
- By botanical source
- By distribution channel
- By Country
- Market Attractiveness Analysis
- By Country
- By product type
- By botanical source
- By distribution channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By product type
- By botanical source
- By distribution channel
- By Country
- Market Attractiveness Analysis
- By Country
- By product type
- By botanical source
- By distribution channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- UK
- Italy
- Spain
- Benelux
- Nordics
- By product type
- By botanical source
- By distribution channel
- By Country
- Market Attractiveness Analysis
- By Country
- By product type
- By botanical source
- By distribution channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By product type
- By botanical source
- By distribution channel
- By Country
- Market Attractiveness Analysis
- By Country
- By product type
- By botanical source
- By distribution channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By product type
- By botanical source
- By distribution channel
- By Country
- Market Attractiveness Analysis
- By Country
- By product type
- By botanical source
- By distribution channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By product type
- By botanical source
- By distribution channel
- By Country
- Market Attractiveness Analysis
- By Country
- By product type
- By botanical source
- By distribution channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC countries
- South Africa
- Türkiye
- Israel
- By product type
- By botanical source
- By distribution channel
- By Country
- Market Attractiveness Analysis
- By Country
- By product type
- By botanical source
- By distribution channel
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By botanical source
- By distribution channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By botanical source
- By distribution channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By botanical source
- By distribution channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By botanical source
- By distribution channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By botanical source
- By distribution channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By botanical source
- By distribution channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By botanical source
- By distribution channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By botanical source
- By distribution channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By botanical source
- By distribution channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By botanical source
- By distribution channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By botanical source
- By distribution channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By botanical source
- By distribution channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By botanical source
- By distribution channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By botanical source
- By distribution channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By botanical source
- By distribution channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By botanical source
- By distribution channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By botanical source
- By distribution channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By botanical source
- By distribution channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By botanical source
- By distribution channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By botanical source
- By distribution channel
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By product type
- By botanical source
- By distribution channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Weleda
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Burt's Bees
- Aveda
- Origins
- Shiseido
- Weleda
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


