
- Market Size (2026)
- USD 610.0 Bn
- Forecast (2036)
- USD 1092.4 Bn
- CAGR (2026 to 2036)
- 6.0%
How big is Beauty And Personal Care Product Market in 2026?
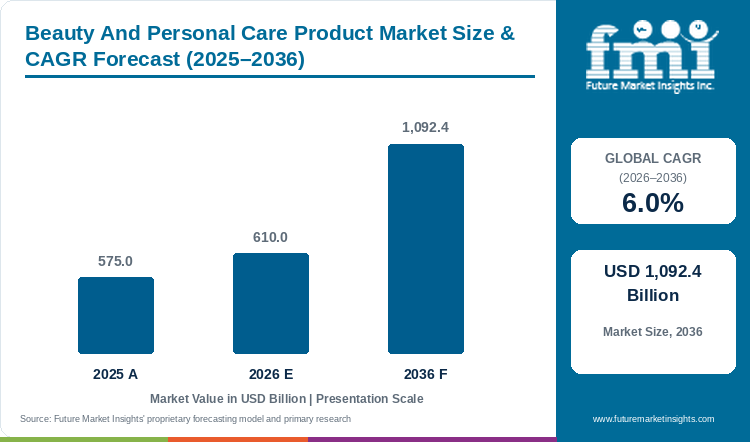
Assessed at USD 575.0 billion in 2025 and progressing to USD 610.0 billion in 2026, the beauty and personal care product market valuation is on course to reach USD 1,092.4 billion by 2036, supported by a forecast-period CAGR of 6.0%.
Table 1: Market Size and Forecast for the Beauty And Personal Care Product Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 575.0 billion |
| Estimated Market Size in 2026 | USD 610.0 billion |
| Projected Market Size by 2036 | USD 1,092.4 billion |
| CAGR, 2026 to 2036 | 6.0% |
| Added Revenue, 2026 to 2036 | USD 482.4 billion |
The global beauty and personal care product market was valued at USD 575.0 billion in 2025 and is estimated to reach USD 610.0 billion in 2026. The market is projected to reach USD 1,092.4 billion by 2036, expanding at a compound annual growth rate (CAGR) of 6.0% between 2026 and 2036. Skincare holds a projected 44.0% share of 2026 category demand, given that shoppers treat facial cleansers and sunscreens as daily health regimens. FMI demand analysis indicates that household spending is shifting toward multi-active clinical serums and concentrated eau de parfum sprays, where higher active dosing lifts average basket values across pharmacy and specialty aisles. That broad multi-category base separates overall industry growth from specialized skincare formulations projected at an 8.1% CAGR, since mature bath soap volumes moderate faster dermocosmetic gains. The demand for personal care essentials is supported by European consumption, with Cosmetics Europe reporting in October 2025 that the continental cosmetics sector reached EUR 104 billion across 500 million daily consumers. Manufacturers are also expanding digital-first regional portfolios and selective divisions, evidenced when L'Oreal SA reported EUR 23.77 billion in first-half 2026 sales in July 2026 following its agreement to acquire a majority stake in Indian personal care player Innovist. Retailers allocate shelf space to clinically tested routines, and brands that pair active potency with accessible pricing hold repeat accounts through 2036.
Key Market Trends & Insights
- By product sector: Skincare is projected to hold an estimated 44.0% share in 2026, driven by daily consumer use of facial cleansers, clinical serums and sunscreens.
- By price and positioning: Mass Market and Drugstore Formats are expected to represent 58.0% in 2026 as supermarket and pharmacy chains expand dermatologist-backed everyday lines.
- By distribution channel: Specialty Multi-Brand Beauty Retailers are anticipated to account for 48.0% in 2026 through guided in-store shade matching and omnichannel loyalty programs.
- By formulation claim: Conventional Formulations are estimated to secure 54.0% in 2026 owing to proven preservative stability and cost-effective surfactant systems in high-volume wash lines.
- By packaging format: Bottles and Jars are forecast to command 46.0% in 2026 through automated high-speed filling compatibility across lotions, shampoos and glass perfume flacons.
Regional Highlights
- Top national expansion: The UAE leads national growth projections at a 7.4% CAGR through 2036 under luxury fragrance tourism and climate-adapted sun care demand.
- Broader country progression: South Korea tracks at a 7.1% CAGR ahead of the USA at 6.8% and Saudi Arabia at 6.7%, while Japan advances at a 5.3% CAGR.
Market Size & Forecast
Multinational personal care formulators face strict ingredient safety disclosures and facility registration rules that reshape how new skincare and cosmetic lines reach retail shelves. When brands launch across North American and European pharmacy chains, compliance teams must verify adverse-event tracking and toxicological dossiers for every active compound. This regulatory baseline is confirmed by U.S. Food and Drug Administration records updated in September 2026, which govern mandatory cosmetic facility registrations and product ingredient listings under the Modernization of Cosmetics Regulation Act. Consequently, retail category buyers favor established manufacturers that maintain audited GMP manufacturing plants and clinical safety documentation across fragranced personal care products.
Active Formulation Volume and Retail Unit Sizing
Table 2: Active Formulation Volume and Retail Unit Sizing for the Beauty And Personal Care Product Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 575.0 | 610.0 | 1,092.4 |
| Finished personal care & cosmetic units shipped (billion units) | 142.0 to 154.0 | 148.5 to 161.0 | 238.0 to 258.0 |
| Formulated active & functional ingredient volume (million metric tons) | 18.4 to 20.2 | 19.3 to 21.2 | 31.5 to 34.8 |
| Average manufacturer realization per retail unit (USD) | 3.85 to 4.15 | 3.92 to 4.24 | 4.35 to 4.72 |
Operational note: Retail unit and active ingredient tonnage ranges reflect finished consumer units shipped across skincare, haircare and daily hygiene lines.
Cosmetic chemists formulating daily UV protection and pigment-correcting facial creams combine UV filters with anti-inflammatory actives to prevent visible-light skin darkening. Rather than selling single-purpose moisturizers, mass and masstige brands bundle barrier repair and photoprotection into single morning serums to raise unit realizations. Clinical trial findings published in Photodermatology, Photoimmunology and Photomedicine in November 2025 substantiate this formulation shift, demonstrating that a broad-spectrum sunscreen containing sclareolide and niacinamide improved protected skin pigmentation by 11.76 delta ITA degrees with 48% to 87% secondary endpoint gains. Brand owners therefore specify multifunctional actives across sunscreen filter boosters to justify premium retail price tiers.
Per Capita & Omnichannel Retail Spending Indicators
Table 3: Per Capita and Omnichannel Retail Spending Indicators for the Beauty And Personal Care Product Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Annual beauty & personal care spend per capita (USD) | 70.1 | 73.5 | 121.4 |
| Specialty retail & e-commerce channel share (%) | 45.5% to 48.0% | 47.0% to 49.5% | 56.0% to 59.5% |
| Clinical & dermocosmetic skincare share of total market (%) | 16.5% to 18.2% | 17.4% to 19.1% | 24.5% to 27.0% |
Table 4: Retail Pharmacy & Corporate Division Benchmarks for the Beauty And Personal Care Product Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 610.0 billion | 2026 global beauty & personal care baseline |
| European cosmetics & personal care retail baseline | EUR 104.0 billion | Cosmetics Europe sector valuation across 500M consumers |
| U.S. Health & Personal Care Stores employment (Aug 2026) | 1,052.1 thousand | U.S. Bureau of Labor Statistics NAICS 446 payroll registry |
| Specialty Multi-Brand Beauty Retailers revenue, 2026 | USD 292.8 billion | 48.0% distribution channel allocation |
Global personal care conglomerates are restructuring their brand portfolios around high-margin dermatological skincare and prestige beauty to protect operating profitability when mass grocery inflation slows unit volume. Financial disclosures from L'Oreal SA in February 2026 confirm this revenue distribution, documenting EUR 44.05 billion in 2025 group sales led by EUR 16.09 billion in Consumer Products and EUR 7.20 billion in Dermatological Beauty growing at 11.5% in the fourth quarter. Retail pharmacy chains consequently expand dedicated dermocosmetic consultation bays near radiance-boosting skin care displays to capture higher-margin basket trade-ups.
Analyst Perspective
"Shoppers no longer divide their beauty budget strictly between luxury department store counters and basic drugstore soaps. Brands that bring clinical active concentrations such as ceramides, peptides and niacinamide into accessible drugstore and specialty retail formats are capturing the fastest repeat-purchase velocity across both developed and emerging markets."
- Rahul Pandita, Principal Consultant, Future Market Insights.
How is the beauty and personal care product market segmented?
The beauty and personal care product market is segmented by product sector, price and positioning, distribution channel, formulation claim, and packaging format. In 2026, Skincare is projected at 44.0%, Mass Market and Drugstore Formats at 58.0%, Specialty Multi-Brand Beauty Retailers at 48.0%, Conventional Formulations at 54.0%, and Bottles and Jars at 46.0%.
By product sector: Skincare, Haircare, Color Cosmetics, and Fragrances and Personal Hygiene.
By price and positioning: Mass Market and Drugstore Formats, Masstige Premium Formats, Prestige and Luxury Department Store Formats, and Clinical and Dermocosmetic Formats.
By distribution channel: Specialty Multi-Brand Beauty Retailers, Supermarkets and Hypermarkets, Pharmacies and Drugstores, Direct-to-Consumer Brand Websites and Social Commerce, and Department Store Beauty Counters.
By formulation claim: Conventional Formulations, Clean and Botanical Formulations, Dermatologist-Tested Clinical Formulations, and Certified Organic and Vegan Formulations.
By packaging format: Bottles and Jars, Tubes and Squeeze Dispensers, Airless Pumps and Dropper Vials, and Refill Pouches and Solid Bars.
Why does Skincare lead the product sector category?
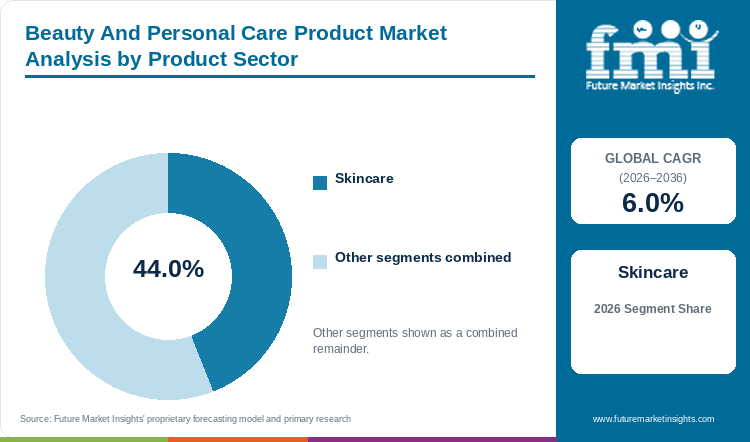
Skincare formulations hold an estimated 44.0% of product sector demand in 2026, anchored by daily consumer replenishment of cleansers, clinical serums, moisturizers, and sunscreens.
Table 5: Product Sector Share for the Beauty And Personal Care Product Market (percentage share), 2026
| Product Sector | Share (2026) |
|---|---|
| Skincare | 44.0% |
| Other Segments Combined | 56.0%* |
| Total | 100.0% |
*Note: Remaining product sector categories account for the balance of 2026 global beauty and personal care product demand.
Table 6: Product Sector Leadership and Market Growth for the Beauty And Personal Care Product Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.0% |
| Leading Segment | Skincare |
Skincare formulations encompassing facial cleansers, concentrated serums and daily sunscreens anchor industry demand as consumers apply multi-step regimens twice daily across all age cohorts. In contrast to color cosmetics that fluctuate with seasonal fashion cycles, facial and body care products generate steady 30-to-60-day replenishment cycles across anti-aging creams and serums. Clinical dermatology reviews published in October 2025 confirm this buyer preference, showing that topical 0.2% Thiamidol and 3% to 5% niacinamide formulations significantly reduce visible-light hyperpigmentation and melanosome transfer over 12-week treatment windows. High formulation costs for encapsulated retinoids and peptide complexes nevertheless challenge mass-market margin structures.
- Within the product sector category, Skincare is projected to account for a leading 44.0% share in 2026, supported by year-round consumer replenishment of facial moisturizers and UV protectants.
- Segment growth through 2036 is anticipated to accelerate across clinical barrier-repair serums and scalp-to-face hybrid treatments as aging urban demographics prioritize preventive dermatological care.
What sustains Mass Market and Drugstore Formats leadership in the price and positioning segment?
Mass Market and Drugstore Formats represent an estimated 58.0% of the price and positioning category in 2026, supported by high-frequency household purchasing across pharmacies and supermarkets.
Mass Market and Drugstore Formats dominate global unit movement and category value since households rely on accessible supermarket and pharmacy aisles for daily shampoos, body washes and facial moisturizers. Global personal care manufacturers defend mass-tier volume by cascading active ingredients such as hyaluronic acid, ceramides and vitamin C from prestige lines into affordable daily formats across nourishing hair and skin care. Private-label supermarket competition and retail promotional pressure still compress gross margins for mid-tier brands that lack patented delivery systems.
- In 2026, Mass Market and Drugstore Formats are anticipated to capture 58.0% of the price and positioning segment, reflecting broad household penetration across emerging and developed retail markets.
- Unilever plc confirmed the resilience of accessible power brands in July 2026, reporting 5.9% underlying sales growth in Beauty and Wellbeing and 4.8% growth in Personal Care led by Dove and Vaseline volume gains.
How do Specialty Multi-Brand Beauty Retailers lead the distribution channel category?
Specialty Multi-Brand Beauty Retailers account for an anticipated 48.0% of distribution channel demand in 2026, driven by in-store shade testing and omnichannel loyalty replenishment.
Specialty Multi-Brand Beauty Retailers lead category distribution by combining open-sell tester gondolas, licensed in-store estheticians and tiered loyalty apps that bridge mass and prestige brands under one roof. Shoppers purchasing foundation shades, clinical acid peels or niche premium cosmetics prefer physical test bars where staff verify skin-tone compatibility before checkout while integrated mobile apps capture repeat replenishment orders. Annual Form 10-K filings submitted to the U.S. Securities and Exchange Commission by Kenvue Inc. in February 2026 document this category scale, noting that global skin health and beauty sales across pharmacy, specialty beauty and digital retail channels drive recurring brand retention. Elevated shelf placement costs and active ingredient research budgets require disciplined brand portfolio management.
- By distribution channel, Specialty Multi-Brand Beauty Retailers are estimated to reach 48.0% of total category share in 2026 as omnichannel loyalty programs convert in-store trial into digital reorders.
- Direct-to-consumer brand websites and social commerce livestreams are projected to gain incremental share through 2036 among Gen Z shoppers, though specialty chains retain leadership through curated multi-brand discovery.
Why does Conventional Formulations lead the formulation claim category?
Conventional Formulations secure a projected 54.0% of formulation claim value in 2026, supported by long shelf-life stability and proven sensory performance across global climates.
Conventional Formulations retain the largest share of global personal care demand given that synthetic preservatives, silicones and approved UV filters provide long ambient shelf life and consistent sensory slip across tropical and temperate supply chains. High-speed haircare and color cosmetic plants rely on conventional polymers and chelators to prevent emulsion separation and microbial spoilage during multi-month container shipping, including across whole-body deodorants. Stricter European Union microplastic and wastewater rules however compel formulators to phase out cyclic silicones and persistent synthetic polymers.
- Conventional Formulations are predicted to secure 54.0% of formulation claim demand in 2026, supported by proven emulsion stability and lower raw material costs across high-volume wash and styling lines.
- The Procter and Gamble Company reported in its July 2026 full-year earnings release that organic sales in its Beauty segment rose 4% on 3% volume growth through core Pantene, Olay and Head and Shoulders formulation upgrades.
What gives Bottles and Jars the leading position in packaging format?
Bottles and Jars command an estimated 46.0% of packaging format share in 2026, anchored by high-speed filling line compatibility and recyclable glass and PET formats.
Bottles and Jars represent the primary container architecture across liquid shampoos, body lotions and fine fragrance sprays since rigid PET, HDPE and glass containers run at high speeds on automated rotary filling and capping lines. Cosmetic brand owners pair recycled-content bottles and heavy-wall glass jars with precision lotion pumps and atomizers across beauty and personal care packaging to protect volatile fragrances and active serums from oxidation. U.S. Bureau of Labor Statistics sector tracking for Health and Personal Care Stores (NAICS 446) in September 2026 recorded a preliminary Producer Price Index of 151.106 with 1,052.1 thousand retail employees handling packaged personal care inventory. Rigid container weight and resin cost volatility still motivate brands to test lightweight refill pouches.
- Strong repeat ordering across liquid haircare, body care and facial creams places Bottles and Jars on course to hold an estimated 46.0% share of the packaging format category in 2026.
- Airless pumps and mono-material refill cartridges are forecast to expand steadily through 2036 as prestige skincare houses reduce preservative loads to comply with packaging recyclability mandates.
What are the drivers, restraints, and opportunities in the beauty and personal care product market?
In the beauty and personal care product market, clinical active skincare adoption and prestige fragrance layering are projected to drive growth whereas European wastewater fees and ingredient restrictions restrain margins and biomimetic ceramides with refillable packaging create new demand avenues.
- Driver: Widespread consumer adoption of dermatologist-validated skincare actives and prestige fragrance layering routines lifts per-capita spending and repeat replenishment frequency.
- Restraint: Stringent environmental wastewater regulations and cosmetic ingredient restrictions across Europe and North America increase compliance and reformulation costs.
- Opportunity: Deployment of biomimetic ceramide skincare, refillable packaging and localized emerging-market beauty incubation programs creates new high-margin revenue streams.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Consumer migration toward clinically substantiated dermocosmetics and daily photoprotection is driving sustained revenue expansion across both pharmacy and specialty beauty channels. Shoppers managing acne, melasma and photoaging bypass generic moisturizers in favor of targeted serums containing patented tyrosinase inhibitors, ceramides and broad-spectrum UV filters. Full-year financial disclosures from Beiersdorf AG in March 2026 confirm this demand growth, showing that its Derma division housing Eucerin and Aquaphor achieved double-digit organic growth and outperformed the broader skincare sector through Epigenetic Serum and Thiamidol rollouts. Dermatologist endorsements and pharmacy tester bars continue driving multi-unit regimen purchases across global urban markets.
Risk Assessment of the Beauty And Personal Care Product Market: Operational and Formulation Friction
Stricter environmental extended-producer-responsibility fees and ingredient restriction dockets across the European Union and Latin America represent a primary operational restraint for personal care manufacturers. Under the recast European Urban Wastewater Treatment Directive (EU 2024/3019), cosmetic producers face mandatory quaternary wastewater treatment cost allocations and stricter safety bans on cyclic silicones and certain UV filters. Industry position filings published by Cosmetics Europe in December 2025 document this regulatory friction, noting that misallocated substance classifications overstated the cosmetics sector's toxic wastewater load at 26% compared with independent hydrological assessments of 1.54%. Compliance re-testing and preservative reformulation consequently lengthen product launch timelines and restrain near-term operating margins.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Personal care groups create new demand avenues by developing biomimetic barrier-repair chemistry and investing in digital-native founders in fast-growing Asian and European markets. Water-light ceramide lotions and sweat-resistant deodorants tailored to regional humidity and sensitive-skin profiles allow global houses to capture underserved consumer segments across restructuring hair care products and facial care. Corporate expansion announcements from Kao Corporation in August 2026 illustrate this commercial pathway, as the company launched its biomimetic ceramide skincare brand Curel across Sweden, Norway and Denmark to accelerate European cosmetics growth . Localized accelerator partnerships and refillable prestige flacons further expand long-term customer lifetime value.
Beauty And Personal Care Product Market by Country (2026 to 2036)
FMI country modeling indicates that the UAE leads beauty and personal care expansion at a 7.4% CAGR through 2036, while Japan advances at a 5.3% CAGR. National growth patterns across Gulf luxury retail hubs, East Asian dermocosmetic centers and Western pharmacy networks depend on local regulatory registration speed and omnichannel store density.
Table 7: Country CAGR and Primary Growth Levers for the Beauty And Personal Care Product Market (CAGR percentage and operational drivers), 2026 to 2036
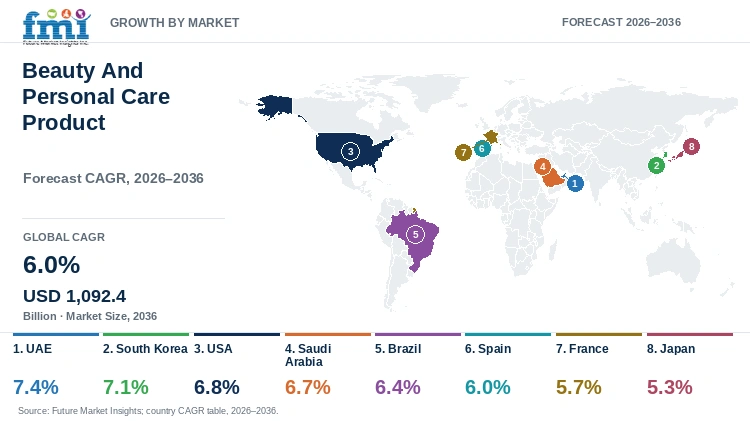
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| UAE | 7.4% | Luxury mall travel retail, oud-EDP fragrance layering, and high-SPF desert sun care |
| South Korea | 7.1% | ODM functional K-beauty serum innovation and MFDS GCORAS regulatory export alignment |
| USA | 6.8% | Specialty multi-brand retail expansion, MoCRA-compliant clinical skincare, and social commerce |
| Saudi Arabia | 6.7% | Rising female workforce participation, prestige amber-oud perfumery, and modern beauty retail |
| Brazil | 6.4% | High-frequency tropical deodorant and haircare routines plus pharmacy SPF 50+ sun care |
| Spain | 6.0% | Mediterranean photoprotection demand, pharmacy dermo-counseling, and fragrance export plants |
| France | 5.7% | Para-pharmacy thermal dermocosmetics, selective luxury perfumery, and AGEC eco-refill formats |
| Japan | 5.3% | MHLW quasi-drug brightening and anti-wrinkle lotions across 4,038 licensed marketing holders |
Source: Future Market Insights analysis
UAE Beauty And Personal Care Product Market Outlook (2026 to 2036)
Demand for personal care and beauty products in the UAE is projected to expand at a leading 7.4% CAGR between 2026 and 2036 as luxury mall flagships and travel-retail concourses in Dubai and Abu Dhabi capture high-spending residents and international tourists. Domestic commercial demand is driven by the intense consumer practice of layering concentrated oud perfume oils with alcohol-based eau de parfum sprays and high-SPF desert sun care. In October 2026, the USDA Foreign Agricultural Service reported in its United Arab Emirates Retail Foods and Consumer Products annual assessment that modern hypermarkets and rapid quick-commerce apps serve an urban population exceeding 9.5 million with over 85% expatriate diversity. Extreme summer heat and indoor air conditioning further compel shoppers to purchase intensive hyaluronic hydration serums and thermal-stable cosmetics.
Key takeaway: In the UAE, luxury travel retail, concentrated fragrance layering and climate-adapted hydration routines are projected to drive a leading 7.4% CAGR through 2036.
South Korea Beauty And Personal Care Product Market Outlook (2026 to 2036)
South Korea's cosmetics and personal care sector is projected to advance at a 7.1% CAGR from 2026 to 2036, acting as the global R&D and contract-manufacturing hub for functional K-beauty serums, cushion foundations and hybrid sunscreens. South Korean demand thrives on rapid indie-brand incubation through health-and-beauty chains and ODM formulation labs. Comparative regulatory analysis published in Stem Cells Translational Medicine in March 2026 confirms this compliance framework, documenting how the South Korean Ministry of Food and Drug Safety enforces the Cosmetics Act to prohibit live human cells in cosmetics while regulating topical conditioned media and exosomes under strict safety standards . Domestic demographic aging also shifts local formulation toward exosome, PDRN and peptide anti-wrinkle ampoules.
Key takeaway: In South Korea, rapid ODM formulation cycles and regulatory export harmonization are anticipated to sustain a 7.1% CAGR across functional skincare and hybrid makeup.
USA Beauty And Personal Care Product Market Outlook (2026 to 2036)
Commercial personal care and beauty demand in the USA is anticipated to advance at a 6.8% CAGR through 2036, anchored by nationwide specialty beauty chains, pharmacy dermocosmetic walls and TikTok Shop social commerce. American shoppers cross-shop clinical skincare, prestige fragrances and mass body care across suburban strip-center specialty stores and algorithmic video feeds. Corporate leadership updates from Coty Inc. in October 2026 reflect this domestic market focus, as the company appointed dedicated U.S. Consumer Beauty and mass color cosmetics executives to accelerate omnichannel execution across CoverGirl, Sally Hansen and Rimmel. Mandatory FDA facility registration and allergen tracking under MoCRA however raise compliance hurdles for smaller contract fillers.
Key takeaway: In the USA, specialty multi-brand retail expansion and prestige fragrance adoption are expected to support a 6.8% CAGR through 2036.
Saudi Arabia Beauty And Personal Care Product Market Outlook (2026 to 2036)
In Saudi Arabia, personal care and cosmetics sales are forecast to grow at a 6.7% CAGR between 2026 and 2036 as female workforce participation, youth demographics and modern lifestyle malls reshape retail consumption across Riyadh and Jeddah. Saudi consumers exhibit exceptionally high per-capita usage of amber, musk and oud fine fragrances paired with clinical skin-brightening and hair-repair masks. Product launch records from Coty Inc. in September 2025 illustrate how global houses target this demand, detailing strategic investments in prestige fragrance artistry and consumer beauty portfolio optimization across key regional markets. All imported and locally filled cosmetics must complete electronic notification and ingredient safety clearance under Saudi Food and Drug Authority rules before customs release.
Key takeaway: In Saudi Arabia, rising female employment and high-concentration prestige perfumery demand are forecast to drive a 6.7% CAGR through 2036.
Brazil Beauty And Personal Care Product Market Outlook (2026 to 2036)
Brazil's cosmetics and personal hygiene sector is estimated to progress at a 6.4% CAGR over the 2026 to 2036 forecast period, supported by tropical grooming habits that make the country one of the largest consumers of deodorants, hair conditioners and body splashes. What sets Brazil apart from North American and European markets is the integration of multi-million-consultant social selling networks with pharmacy chains and native Amazonian botanical ingredients. Clinical photoprotection trials published in early 2026 on ultra-high SPF 50+ sunscreens containing Polypodium leucotomos extract confirm the strong dermatological focus on preventing solar hyperpigmentation in high-UV tropical climates. Strict ANVISA registration enforcement against unverified sunscreens and complex state tax structures nevertheless challenge imported brands.
Key takeaway: In Brazil, high-frequency tropical personal hygiene routines and pharmacy dermatological sun care are estimated to sustain a 6.4% CAGR.
Spain Beauty And Personal Care Product Market Outlook (2026 to 2036)
Sales of cosmetics and personal care items in Spain are slated to expand at a 6.0% CAGR from 2026 to 2036, driven by thriving Mediterranean tourism, pharmacy dermo-cosmetic counseling and export-scale perfume manufacturing across Catalonia and Madrid. Spanish consumers and visiting tourists generate high seasonal spikes in photoprotective sunscreens, after-sun emulsions and prestige eau de toilette sprays. Peer-reviewed cosmetic formulation studies published by Spanish university researchers in Cosmetics in 2026 validate this regional specialization, demonstrating how antioxidant botanical extracts stabilize broad-spectrum photoprotective topical emulsions under intense UV radiation. European packaging waste directives and pharmacy price competition require Spanish producers to invest in automated refillable bottle lines.
Key takeaway: In Spain, pharmacy photoprotection counseling and export-oriented fragrance and skincare manufacturing are slated to support a 6.0% CAGR.
France Beauty And Personal Care Product Market Outlook (2026 to 2036)
National demand for cosmetics and personal care in France is predicted to advance at a 5.7% CAGR between 2026 and 2036, anchored by the country's global leadership in luxury perfumery, thermal-spring dermocosmetics and selective perfumery retail. French buyers rely heavily on para-pharmacy pharmacists for clinical skincare prescriptions and selective retailers for prestige fragrances. Corporate artisan initiatives announced by LVMH Moet Hennessy Louis Vuitton in October 2026 reflect this domestic craftsmanship base, celebrating 69 Virtuosos across Perfumes and Cosmetics and Selective Retailing Houses including Parfums Christian Dior and Guerlain. Mature domestic population growth and strict French AGEC anti-waste plastic reduction laws nonetheless restrain unit volume expansion in basic toiletries.
Key takeaway: In France, para-pharmacy dermocosmetic authority and luxury fragrance craftsmanship are predicted to maintain a 5.7% CAGR through 2036.
Japan Beauty And Personal Care Product Market Outlook (2026 to 2036)
In Japan, domestic personal care and skincare demand is likely to progress at a 5.3% CAGR across the 2026 to 2036 horizon as aging consumers prioritize quasi-drug brightening lotions, UV-essence gels and scalp-care treatments. What differentiates Japan from Western beauty markets is the regulatory quasi-drug classification under the Ministry of Health, Labour and Welfare, which requires verified active efficacy for wrinkle improvement and melanin suppression. Official industry survey data compiled by the Ministry of Economy, Trade and Industry (METI) documents that Japan supports 4,038 licensed cosmetics marketing authorization holders and 3,968 manufacturing facilities nationwide. Population contraction in rural prefectures limits volume growth, pushing Japanese brands to rely on inbound duty-free shoppers and high-value quasi-drug refills.
Key takeaway: In Japan, quasi-drug anti-aging skincare standards and inbound travel retail recovery are likely to sustain a 5.3% CAGR through 2036.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the beauty and personal care product market?
L'Oreal SA, The Estee Lauder Companies Inc., Unilever plc, The Procter and Gamble Company, Shiseido Company Limited, Beiersdorf AG, Coty Inc., Kao Corporation, LVMH Moet Hennessy Louis Vuitton, and Kenvue Inc. are the notable companies in the beauty and personal care product market.
Competitive positioning across the personal care and cosmetics industry divides global multi-category conglomerates, dermatological and Asian skincare innovators and prestige fragrance and specialty retail leaders. L'Oreal SA, Unilever plc, The Procter and Gamble Company and Beiersdorf AG command massive scale across mass drugstore and clinical pharmacy channels. The Estee Lauder Companies Inc., Shiseido Company Limited, Kao Corporation and LVMH Moet Hennessy Louis Vuitton anchor luxury skincare and makeup while Coty Inc. and Kenvue Inc. drive fragrance licensing and clinical skin health formulations.
- Global Multi-Category and Dermocosmetic Leaders: L'Oreal SA, Unilever plc, The Procter and Gamble Company and Beiersdorf AG scale dermatologist-endorsed skincare and personal hygiene power brands globally.
- Prestige Skincare and Asian Beauty Innovators: The Estee Lauder Companies Inc., Shiseido Company Limited, Kao Corporation and LVMH Moet Hennessy Louis Vuitton formulate luxury serums and couture cosmetics.
- Fragrance Licensing and Clinical Skin Health Platforms: Coty Inc. and Kenvue Inc. expand licensed designer eau de parfum collections, mass color cosmetics and clinically backed dermocosmetic skin health brands.
Competitive Benchmarking: Beauty And Personal Care Product Market
Table 8: Competitive Benchmarking for the Beauty And Personal Care Product Market (qualitative capability ratings), 2026
| Company | Clinical Active & R&D Depth | Omnichannel & Specialty Reach | Sustainability & Refill Readiness | Geographic Reach |
|---|---|---|---|---|
| L'Oreal SA | High | High | High | Global presence across 150+ countries; EUR 44.05B 2025 sales across 4 divisions |
| The Estee Lauder Companies Inc. | High | High | High | Global prestige skincare, makeup, and fragrance network; BEAUTY&YOU India hub |
| Unilever plc | High | High | High | Global mass and prestige personal care network; strong Asia and Americas volume |
| The Procter and Gamble Company | High | High | Medium | North America, Europe, and Asia pharmacy and grocery haircare and skin grooming |
| Shiseido Company Limited | High | High | High | Japan, China, Asia-Pacific, Europe, and Americas prestige skincare and fragrance |
| Beiersdorf AG | High | High | High | Global pharmacy and mass skincare network anchored by NIVEA, Eucerin, and La Prairie |
| Coty Inc. | Medium | High | Medium | Global prestige fragrance and mass color cosmetics across Americas, EMEA, and APAC |
| Kao Corporation | High | Medium | High | Japan, East Asia, and expanding European biomimetic skincare and KATE cosmetics |
| LVMH Moet Hennessy Louis Vuitton | High | High | High | Global luxury Perfumes & Cosmetics houses (Dior, Guerlain, Givenchy) and Sephora |
| Kenvue Inc. | High | High | High | 160+ countries; global skin health and beauty leader via Neutrogena, Aveeno, and Clean & Clear |
Evaluation basis: Clinical Active & R&D Depth evaluates patented molecules and dermatological clinical trials, while Omnichannel & Specialty Reach measures distribution across specialty beauty chains, pharmacies and e-commerce. Sustainability & Refill Readiness rates documented eco-refill packaging, biodegradable surfactant systems and regulatory compliance infrastructure.
Key Developments in the Beauty And Personal Care Product Market
- Coty Inc. announced a long-term extension of its fragrance license agreement with Marc Jacobs on November 4, 2026, securing a 40-year partnership across prestige fragrances and beauty collections.
- The Estee Lauder Companies Inc. announced the 2026 winners of its BEAUTY&YOU India entrepreneurship program on October 15, 2026, awarding funding and R&D mentorship to climate-adapted deodorant and green-chemistry fragrance innovators.
- Shiseido Company Limited launched Max Mara Le Parfum on August 31, 2026, expanding its European luxury fragrance licensing portfolio across global prestige department stores and specialty beauty retailers.
Key Players in the Beauty And Personal Care Product Market
Global Multi-Category and Dermocosmetic Leaders
- L'Oreal SA
- Unilever plc
- The Procter and Gamble Company
- Beiersdorf AG
Prestige Skincare and Asian Beauty Innovators
- The Estee Lauder Companies Inc.
- Shiseido Company Limited
- Kao Corporation
- LVMH Moet Hennessy Louis Vuitton
Fragrance Licensing and Specialty Retail Platforms
- Coty Inc.
- Kenvue Inc.
Beauty And Personal Care Product Market - Report Scope
Table 9: Report Scope for the Beauty And Personal Care Product Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Sector; Price and Positioning; Distribution Channel; Formulation Claim; Packaging Format |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial manufacturer and brand revenue from finished consumer beauty and personal care products across skincare (cleansers, toners, serums, moisturizers, sunscreens), haircare, color cosmetics, fragrances and eau de parfum, and daily personal hygiene (bath soaps, body washes, deodorants). Category Scope Note: Excludes upstream commodity chemical feedstocks, oral dental prosthetics, and invasive prescription aesthetic injectables. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | UAE, South Korea, USA, Saudi Arabia, Brazil, Spain, France, Japan, and additional countries in the full report |
| Key Companies Covered | L'Oreal SA, The Estee Lauder Companies Inc., Unilever plc, The Procter and Gamble Company, Shiseido Company Limited, Beiersdorf AG, Coty Inc., Kao Corporation, LVMH Moet Hennessy Louis Vuitton, Kenvue Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down corporate division and bottom-up retail category triangulation. |
Beauty And Personal Care Product Market - Research Methodology
Table 10: Research Methodology for the Beauty And Personal Care Product Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with retail pharmacy category buyers, cosmetic R&D formulation directors, prestige fragrance license managers, and specialty beauty store merchandisers. |
| Secondary Research | Analysis of U.S. FDA MoCRA registration registries, U.S. Bureau of Labor Statistics NAICS 446 series, Cosmetics Europe socio-economic assessments, MFDS Korea and METI Japan statistical reports, and corporate Form 10-K and annual filings. |
| Market Sizing and Forecasting | Top-down multinational beauty conglomerate division baselines reconciled against bottom-up finished unit shipments (148.5B to 161.0B units in 2026) and average manufacturer realizations from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight specialty beauty store density, per-capita disposable grooming expenditure, UV photoprotection intensity, and national regulatory registration frameworks across eight countries. |
| Operational Benchmark Traceability | Formulation volume, retail employment, and division revenue indicators in Tables 2, 3, and 4 trace to Cosmetics Europe market performance reports, BLS NAICS 446 data, and audited corporate financial disclosures. |
| Data Triangulation and Validation | Revenue estimates isolate finished consumer beauty and personal care formulations while excluding upstream bulk surfactants, salon furniture, and medical dermatology lasers. |
Beauty And Personal Care Product Market by Segments
Beauty And Personal Care Product Market segmented by Product Sector:
- Skincare
- Haircare
- Color Cosmetics
- Fragrances and Personal Hygiene
Beauty And Personal Care Product Market segmented by Price and Positioning:
- Mass Market and Drugstore Formats
- Masstige Premium Formats
- Prestige and Luxury Department Store Formats
- Clinical and Dermocosmetic Formats
Beauty And Personal Care Product Market segmented by Distribution Channel:
- Specialty Multi-Brand Beauty Retailers
- Supermarkets and Hypermarkets
- Pharmacies and Drugstores
- Direct-to-Consumer Brand Websites and Social Commerce
- Department Store Beauty Counters
Beauty And Personal Care Product Market segmented by Formulation Claim:
- Conventional Formulations
- Clean and Botanical Formulations
- Dermatologist-Tested Clinical Formulations
- Certified Organic and Vegan Formulations
Beauty And Personal Care Product Market segmented by Packaging Format:
- Bottles and Jars
- Tubes and Squeeze Dispensers
- Airless Pumps and Dropper Vials
- Refill Pouches and Solid Bars
Beauty And Personal Care Product Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- Beiersdorf AG. (2026, March 2). Full year results 2025: Beiersdorf grows in a slowing market, Derma outperforms. Beiersdorf Corporate Newsroom.
- Clinical Pigmentation Review Group. (2025, October 20). Beyond Tint: Active Ingredient Strategies for Post-Inflammatory Hyperpigmentation and Visible Light Protection. Journal of Cosmetic Dermatology (PMC13401449).
- Cosmetics Europe. (2025, October 2). EU policymakers tour the L'Oreal facility in Libramont, Belgium. Cosmetics Europe News & Events.
- Cosmetics Europe. (2025, December 9). Stop the clock: Cosmetics industry urges the European Commission to correct flawed data and apply Polluter Pays Principle in the UWWTD. Cosmetics Europe News & Events.
- Coty Inc. (2025, September 29). Coty Announces Plans to Strengthen Its Leading Position in Fragrance and Consumer Beauty Review. Coty Corporate Newsroom.
- Coty Inc. (2026, October 1). Coty Strengthens U.S. Consumer Beauty Leadership with Key Appointments. Coty Corporate Newsroom.
- Coty Inc. (2026, November 4). Coty Extends Marc Jacobs License, Securing 40-Year License Partnership. Coty Corporate Newsroom.
- Formulation Science Group. (2026, May 10). A Photoprotective Cosmetic Formulation Assessment Containing Botanical Antioxidant Extracts. Cosmetics (MDPI).
- Kao Corporation. (2026, August 25). Kao Steps Up EMEA Skincare Growth with Curel Launch in the Nordics. Kao Global Newsroom.
- Kenvue Inc. (2026, February 26). Annual Report on Form 10-K for the Fiscal Year Ended December 31, 2025. U.S. Securities and Exchange Commission EDGAR.
- L'Oreal SA. (2026, February 12). 2025 Annual Results: Solid Growth and Record Operating Profitability. L'Oreal Groupe Finance Releases.
- L'Oreal SA. (2026, July 29). 2026 Half-Year Results: Strong Momentum Confirmed and Majority Stake Agreement in Innovist. L'Oreal Groupe Finance Releases.
- LVMH Moet Hennessy Louis Vuitton. (2026, October 30). LVMH reveals and celebrates the 2026 promotion of Virtuosos across Perfumes & Cosmetics and Selective Retailing. LVMH Newsroom.
- Ministry of Economy, Trade and Industry (METI). (2025, March 31). Survey on Future Directions for the Sustainable Development of the Cosmetics Industry in Japan. Government of Japan METI Research Reports.
- on behalf of Investigator-Blinded Photoprotection Study Group. (2025, November 15). An Investigator-Blinded, Randomized Trial of a Broad-Spectrum Sunscreen Containing Sclareolide and Niacinamide. Photodermatology, Photoimmunology & Photomedicine (PMC12872947).
- Photoprotection Clinical Group. (2026, January 15). A 50+ Sunscreen Containing Polypodium Leucotomos Extract Prevents Solar Pigmentation. National Library of Medicine (PMC12883900).
- Shiseido Company, Limited. (2026, August 31). Shiseido Launches Max Mara Le Parfum, Strengthening Its Global Fragrance Business. Shiseido Corporate News Releases.
- The Estee Lauder Companies Inc. (2026, October 15). The Estee Lauder Companies Announces BEAUTY&YOU India 2026 Award Winners. The Estee Lauder Companies Newsroom.
- The Procter & Gamble Company. (2026, July 29). P&G Announces Fourth Quarter and Fiscal Year 2026 Results. P&G Corporate Newsroom.
- Unilever plc. (2026, July 28). Desire at Scale powering strong H1 2026 performance across Beauty & Wellbeing and Personal Care. Unilever Press Releases.
- U.S. Bureau of Labor Statistics. (2026, September 4). Industries at a Glance: Health and Personal Care Stores (NAICS 446). U.S. Department of Labor.
- U.S. Food and Drug Administration. (2026, September 9). Registration & Listing of Cosmetic Product Facilities and Products under MoCRA. U.S. Department of Health and Human Services.
- USDA Foreign Agricultural Service. (2026, October 19). United Arab Emirates: Retail Foods and Consumer Products Annual. U.S. Department of Agriculture GAIN Report.
- Xiao, Y., Liao, Z., Zhang, H., & Guan, T. (2026, March 26). The global regulatory landscape of stem cell medical aesthetics: challenges, comparisons, and pathways to coordination. Stem Cells Translational Medicine (PMC13064846).
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the beauty and personal care product market in 2026 and what is forecast for 2036?
- Which clinical skincare actives and fragrance layering trends support demand for personal care products?
- Why does Skincare lead the product sector category?
- Why do Mass Market and Drugstore Formats lead the price and positioning category globally?
- How do growth rates differ across the UAE, South Korea, the USA and Saudi Arabia?
- Which leading companies supply multi-category personal care lines versus prestige skincare and fragrances today?
- What regulatory ingredient rules and wastewater directives restrain margin expansion in the personal care sector?
- What should beauty brands evaluate before scaling biomimetic skincare and refillable packaging formats?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Sector, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Sector, 2026 to 2036
- Skincare
- Haircare
- Color Cosmetics
- Fragrances and Personal Hygiene
- Y-o-Y Growth Trend Analysis By Product Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Price and Positioning, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Price and Positioning, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Price and Positioning, 2026 to 2036
- Mass Market and Drugstore Formats
- Masstige Premium Formats
- Prestige and Luxury Department Store Formats
- Clinical and Dermocosmetic Formats
- Y-o-Y Growth Trend Analysis By Price and Positioning, 2021 to 2025
- Absolute $ Opportunity Analysis By Price and Positioning, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Specialty Multi-Brand Beauty Retailers
- Supermarkets and Hypermarkets
- Pharmacies and Drugstores
- Direct-to-Consumer Brand Websites and Social Commerce
- Department Store Beauty Counters
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Formulation Claim, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Formulation Claim, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Formulation Claim, 2026 to 2036
- Conventional Formulations
- Clean and Botanical Formulations
- Dermatologist-Tested Clinical Formulations
- Certified Organic and Vegan Formulations
- Y-o-Y Growth Trend Analysis By Formulation Claim, 2021 to 2025
- Absolute $ Opportunity Analysis By Formulation Claim, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Bottles and Jars
- Tubes and Squeeze Dispensers
- Airless Pumps and Dropper Vials
- Refill Pouches and Solid Bars
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- UAE
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Sector
- By Price and Positioning
- By Distribution Channel
- By Formulation Claim
- By Packaging Format
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- L'Oreal SA
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- The Estee Lauder Companies Inc.
- Unilever plc
- The Procter and Gamble Company
- Shiseido Company Limited
- Beiersdorf AG
- Coty Inc.
- Kao Corporation
- LVMH Moet Hennessy Louis Vuitton
- Kenvue Inc.
- L'Oreal SA
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Sector, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Price and Positioning, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Formulation Claim, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Product Sector, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Price and Positioning, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Formulation Claim, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Product Sector, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Price and Positioning, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Formulation Claim, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Product Sector, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Price and Positioning, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Formulation Claim, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Product Sector, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Price and Positioning, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Formulation Claim, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Product Sector, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Price and Positioning, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Formulation Claim, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Product Sector, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Price and Positioning, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Formulation Claim, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Product Sector, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Price and Positioning, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Formulation Claim, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Sector, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Sector, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Sector
- Figure 6: Global Market Value Share and BPS Analysis by Price and Positioning, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Price and Positioning, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Price and Positioning
- Figure 9: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Distribution Channel
- Figure 12: Global Market Value Share and BPS Analysis by Formulation Claim, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Formulation Claim, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Formulation Claim
- Figure 15: Global Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Packaging Format
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Product Sector, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Product Sector, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Product Sector
- Figure 32: North America Market Value Share and BPS Analysis by Price and Positioning, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Price and Positioning, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Price and Positioning
- Figure 35: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Distribution Channel
- Figure 38: North America Market Value Share and BPS Analysis by Formulation Claim, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Formulation Claim, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Formulation Claim
- Figure 41: North America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Packaging Format
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Product Sector, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Product Sector, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Product Sector
- Figure 48: Latin America Market Value Share and BPS Analysis by Price and Positioning, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Price and Positioning, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Price and Positioning
- Figure 51: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 54: Latin America Market Value Share and BPS Analysis by Formulation Claim, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Formulation Claim, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Formulation Claim
- Figure 57: Latin America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Packaging Format
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Product Sector, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Product Sector, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Product Sector
- Figure 64: Western Europe Market Value Share and BPS Analysis by Price and Positioning, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Price and Positioning, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Price and Positioning
- Figure 67: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 70: Western Europe Market Value Share and BPS Analysis by Formulation Claim, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Formulation Claim, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Formulation Claim
- Figure 73: Western Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Packaging Format
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Product Sector, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Product Sector, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Product Sector
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Price and Positioning, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Price and Positioning, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Price and Positioning
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Formulation Claim, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Formulation Claim, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Formulation Claim
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Packaging Format
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Product Sector, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Product Sector, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Product Sector
- Figure 96: East Asia Market Value Share and BPS Analysis by Price and Positioning, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Price and Positioning, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Price and Positioning
- Figure 99: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 102: East Asia Market Value Share and BPS Analysis by Formulation Claim, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Formulation Claim, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Formulation Claim
- Figure 105: East Asia Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Packaging Format
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Product Sector, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Sector, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Product Sector
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Price and Positioning, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Price and Positioning, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Price and Positioning
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Formulation Claim, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Formulation Claim, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Formulation Claim
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Packaging Format
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Product Sector, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Product Sector, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Product Sector
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Price and Positioning, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Price and Positioning, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Price and Positioning
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Formulation Claim, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Formulation Claim, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Formulation Claim
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Packaging Format
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the beauty and personal care product market in 2026, and what is forecast for 2036?
FMI estimates that global personal care and beauty valuation stood at USD 575.0 billion in 2025 and reached USD 610.0 billion in 2026. Category revenue is forecast to hit USD 1,092.4 billion by 2036.
What is the CAGR for the beauty and personal care product market from 2026 to 2036?
The beauty and personal care product sector is projected to expand at a 6.0% CAGR over the 2026 to 2036 window, generating USD 482.4 billion in incremental revenue across global retail channels.
Which product sector segment leads the beauty and personal care product market?
Skincare formulations are anticipated to hold 44.0% of product sector demand in 2026, supported by daily consumer replenishment of cleansers, serums and sunscreens.
Which price and positioning segment leads the beauty and personal care product market?
Mass Market and Drugstore Formats are expected to represent 58.0% of the price and positioning category in 2026 as pharmacy and grocery chains expand accessible clinical skincare and daily hygiene lines.
Which country has a notable growth outlook during the assessment period?
The UAE leads national expansion projections at a 7.4% CAGR through 2036, driven by luxury travel retail, oud and eau de parfum layering and climate-adapted sun care demand.
Who are the key players in the market?
L'Oreal SA, The Estee Lauder Companies Inc., Unilever plc and The Procter and Gamble Company lead global supply. Shiseido Company Limited, Beiersdorf AG and Coty Inc. hold strong positions. Kao Corporation, LVMH and Kenvue Inc. also compete.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
