

- Market Size (2026)
- USD 271.1 Bn
- Forecast (2036)
- USD 607.3 Bn
- CAGR (2026 to 2036)
- 8.4%
How big is the Herbal Medicinal Products Market in 2026?
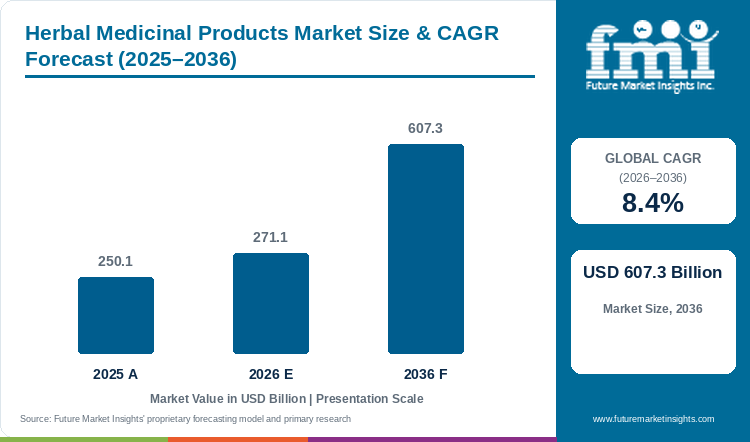
The Herbal Medicinal Products Market is projected to expand at a CAGR of 8.4% between 2026 and 2036. Market value rises from USD 250.1 billion in 2025 to USD 271.1 billion in 2026 and USD 607.3 billion by 2036. [1]
The herbal medicinal products market was estimated at USD 250.1 billion in 2025. It reaches USD 271.1 billion in 2026 and is forecast at USD 607.3 billion by 2036. Tablets and capsules hold 38.0% of product demand, digestive health accounts for 18.0% of market value, and pharmacies represent 45.0% of channel demand. Commercial opportunities depend on the formulation, its permitted claims and the distribution route used in each country. The outlook places growth at 8.4% CAGR over 2026 to 2036. The market brings together finished herbal formulations sold through pharmacy and consumer channels.
A botanical ingredient can enter different regulatory categories depending on its intended use and jurisdiction. The supplier therefore needs to connect the plant material, extraction process and finished presentation with a suitable route to market. Brand recognition and availability influence the sale, while product documentation determines which claims and channels the company can pursue. [1, 2, 3] Registered herbal medicines, traditional-use products and herbal supplements may use related plant materials under different requirements. Evidence needs to support the particular preparation and intended use. Pharmacy access also depends on supplying the registered or listed presentation consistently. Product classification guides sourcing, formulation, quality control and distribution decisions. [2, 3, 4]
Key Market Trends & Insights
- Tablets and capsules hold 38.0% of product demand in 2026. [1]
- Digestive health accounts for 18.0% of market value. [1]
- Pharmacies lead distribution with 45.0% of channel demand. [1]
- Product category, botanical consistency and channel requirements shape market entry. [1]
Regional Highlights
- Fastest-growing profiled country: China (9.5% CAGR, 2026 to 2036). [1]
- By country: India (9.0%) follows, while Germany records 7.2%. [1]
- Regulatory classification and documentation affect which herbal preparations suppliers can place in each market.
Market Size & Forecast
Table 1: Market Size and Forecast for the Herbal Medicinal Products Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 250.1 billion |
| Estimated Market Size in 2026 | USD 271.1 billion |
| Projected Market Size by 2036 | USD 607.3 billion |
| CAGR, 2026 to 2036 | 8.4% |
| Added Revenue, 2026 to 2036 | USD 336.2 billion |
| Market Expansion Multiple | 2.2x |
Herbal Medicinal Products Market Industry and Operating Indicators
Published product and operating developments describe the choices and requirements suppliers face.
Table 2: Industry Indicators for the Herbal Medicinal Products Market, 2025 to 2026
| Indicator | Data Point | Why It Matters | Source |
|---|---|---|---|
| Natural-health acquisition | Apotex announced the CanPrev acquisition on February 3, 2025. | Adds natural-health brands and distribution relationships to the purchaser’s business. | [7] |
| Product standards | The 2025 Chinese Pharmacopoeia came into force on October 1, 2025. | Establishes relevant standards and dossier requirements for covered products. | [13] |
| Product-quality support | India’s Ministry of Ayush described drug-development, standardization and quality-support programs in December 2025. | Provides a policy and technical context for formulation and documentation. | [14] |
Analyst Perspective
The commercial value of a herbal formulation rests on a repeatable product. Buyers need to know which botanical material is present, how it is processed and what the finished product is permitted to claim. Distribution becomes more dependable when that information travels with the formulation through production and into the sales channel.
- Anurag Sharma, Principal Consultant, Future Market Insights.
How is the Herbal Medicinal Products Market segmented?
The market is segmented by Product, Indication and Distribution Channel. [1]
By Product: Tablets and Capsules, Powders, Extracts, Syrups.
By Indication: Digestive Health, Respiratory Care, Pain Management, Skin Care.
By Distribution Channel: Pharmacies, Hospital Pharmacies, Online Stores, Retail Stores.
By Region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa.
Product coverage includes tablets and capsules, powders, extracts and syrups. Indication groups cover digestive health, respiratory care, pain management and skin care. These describe product positioning; permitted uses remain specific to the formulation and market. Channels comprise pharmacies, hospital pharmacies, online stores and retail stores. Classification determines documentation, labelling and placement. Ingredient supply is a separate step from the finished-product sale. [1, 2, 3, 4]
Why do tablets and capsules lead product demand?
Tablets and capsules account for 38.0% of product demand in 2026. The presentation supports pharmacy and retail replenishment, while botanical consistency and permitted claims remain specific to the formulation. [1, 5, 6]
Table 3: Product Share for the Herbal Medicinal Products Market (percentage share), 2026
| Product | Share (2026) |
|---|---|
| Tablets and Capsules | 38.0% |
| Other Segments Combined | 62.0% |
| Total | 100.0% |
Table 4: Product Focus and Market Growth for the Herbal Medicinal Products Market, 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 8.4% |
| Leading Segment | Tablets and Capsules |
Tablets and capsules provide a defined presentation for pharmacy and retail replenishment. Himalaya describes botanical selection and phytochemical profiling during formulation, while Bionorica develops herbal medicinal products. Manufacturers need to establish the composition and consistency of the preparation, with a label suited to the intended market. The dosage form alone does not establish therapeutic performance. [5, 6]
- Tablets and capsules hold 38.0% of product demand in 2026. [1]
- Himalaya documents geographic and seasonal marker-profile assessment during herbal formulation. [5]
What supports digestive-health positioning?
Digestive health accounts for 18.0% of market value in 2026. Product selection depends on the preparation and permitted use, with registration and monographs relevant to medicinal products. [1, 3]
Digestive health is the largest profiled indication group. Suppliers can offer a range of herbal preparations within this positioning, but product selection depends on the specific formulation and permitted use. Pharmacy teams and retailers need clear distinctions among these presentations, especially where products share familiar plant names. A manufacturer can support assortment decisions through consistent pack information, availability and documentation for the relevant preparation. European herbal monographs and national registration requirements provide a framework for medicinal products sold in those markets. [1, 3]
- Digestive health accounts for 18.0% of market value in 2026. [1]
- The indication taxonomy also includes respiratory care, pain management and skin care. [1]
Why do pharmacies lead distribution?
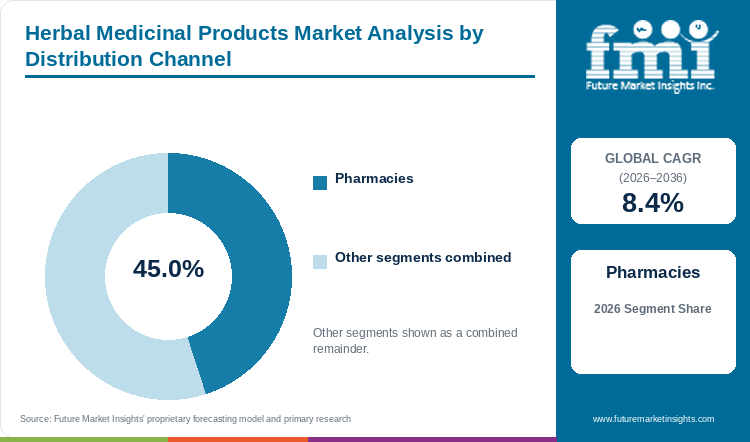
Pharmacies connect herbal products with an established channel for medicines and health products. Apotex’s acquisition of CanPrev in February 2025 specifically referred to its existing pharmacy presence as well as wider natural-health distribution. For a supplier, pharmacy access involves an appropriate assortment, product information and reliable replenishment. Pack design and classification need to support the product’s position on the shelf. Hospital pharmacies form a separate channel in the taxonomy and have purchasing requirements tied to their institutions. [1, 7]
- Pharmacies represent 45.0% of channel demand in 2026. [1]
- Apotex retained CanPrev’s existing brands and distribution channels after the acquisition. [7]
What drives and constrains demand?
Established herbal brands and channel access support demand; formulation consistency and market-specific requirements constrain expansion; documented products and dependable supply create opportunities.
- Driver: Established botanical portfolios can serve pharmacy and consumer-health channels.
- Restraint: Formulation, evidence and permitted claims vary by product category and market.
- Opportunity: Traceable sourcing and clear documentation can support distribution and product development.
Driver. Established portfolios give companies existing retail relationships for herbal preparations. Dabur’s annual report describes its Ayurveda-based business and distribution network, while Apotex’s CanPrev acquisition adds natural-health brands and channel relationships. Expansion requires a product that the intended channel can supply consistently, with formulation and destination-market requirements addressed even where consumers already recognize the brand. [7, 10]
Restraint. Herbal material can vary with species, plant part, growing conditions and processing. A company needs specifications and controls that make its chosen preparation repeatable. FDA’s botanical-drug guidance identifies raw-material, manufacturing and analytical controls as parts of therapeutic-consistency assessment for botanical drugs. EMA’s quality guidance addresses herbal preparations within medicinal-product dossiers. These requirements make botanical identity and the production process commercially relevant when a business plans a new product or transfers supply to another source. [2, 11]
Opportunity. Sourcing records connect botanical suppliers with finished formulations. Gaia Herbs describes oversight from its farm through laboratory and manufacturing, while Himalaya assesses herbs across seasons and locations. Records of origin, processing and consistency support purchasing and quality systems, and give distributors clear information about the product they receive. [5, 12]
Which country CAGRs are profiled?
The country outlook covers 2026 to 2036. [1]
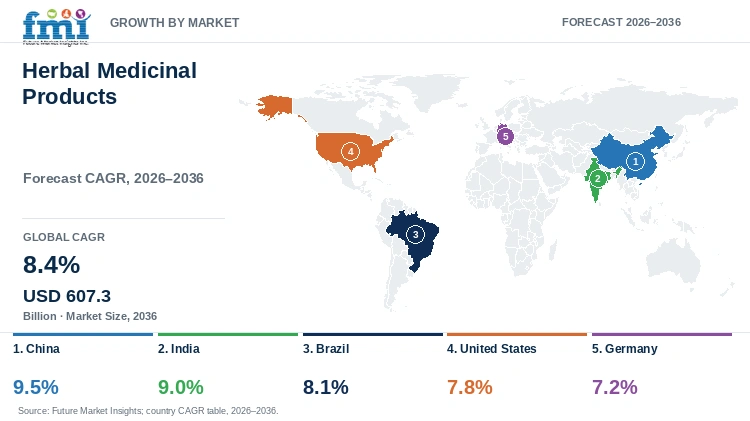
| Country | CAGR 2026 to 2036 |
|---|---|
| China | 9.5% |
| India | 9.0% |
| Brazil | 8.1% |
| United States | 7.8% |
| Germany | 7.2% |
How do geographic opportunities compare?
The five profiles have different registration and distribution routes. China and India lead the growth outlook. Brazil distinguishes herbal medicines from traditional herbal products, the United States separates botanical drugs from supplements, and Germany follows the European medicinal-product framework. Product classification determines the claims, packaging and supporting information needed for market entry. [1, 2, 3, 4, 13, 14, 15]
China: Pharmacopoeial standards shape medicinal-product quality and documentation. India: Ayurveda portfolios and standards programs support product development and distribution. Brazil: Registration and notification pathways distinguish herbal-product categories. United States: Botanical-drug and dietary-supplement routes carry different requirements. Germany: The European herbal-medicine framework supports medicinal-product assessment.
Country-wise Analysis
China
China is forecast at 9.5% CAGR through 2036, the fastest rate among the five profiles. The 2025 Chinese Pharmacopoeia took effect on October 1, 2025. NMPA identifies it as a national technical standard covering relevant medicinal products and requires assessment of registration standards against the new edition. For manufacturers, this creates a need to keep specifications, testing and dossiers aligned with the preparation they supply. Commercial growth therefore connects product demand with the ability to maintain a documented medicinal formulation across production and distribution. [1, 13]
Brazil
Brazil is forecast at 8.1% CAGR through 2036. Anvisa’s framework distinguishes herbal medicines from traditional herbal products and provides registration or notification routes for the applicable category. This makes classification an early part of product planning. A supplier must connect the formulation, intended positioning and supporting information with the correct route before approaching a distributor. Pharmacy and retail expansion then require a presentation and supply arrangement that fit the approved or notified product. Local regulatory documentation is therefore part of the commercial launch sequence. [1, 15]
United States
The U.S. outlook is 7.8% CAGR over 2026 to 2036. FDA distinguishes botanical drugs from dietary supplements and other botanical products. Botanical-drug development follows the relevant investigational and marketing-application pathways, with consistency of complex preparations a central issue. Consumer-health brands need to establish intended use and classification for their U.S. presentation; medicinal claims from another jurisdiction require the appropriate U.S. basis. [1, 2, 4]
Germany
Germany’s forecast is 7.2% CAGR through 2036. The European framework provides routes for herbal medicinal products based on the applicable evidence and use history, while retaining requirements for quality documentation. Bionorica provides a local example of a company focused on herbal medicines and related research. A new entrant needs to assess its preparation against the relevant framework and support the finished presentation through production and distribution. Pharmacy access depends on the product available in that market, with the brand’s wider international portfolio offering context rather than replacing the local dossier. [1, 3, 6, 11]
Who participates in the market?
Notable participants include Himalaya Wellness, Dabur, Bionorica, Blackmores, Gaia Herbs and CanPrev; botanical-ingredient suppliers support their wider value chain.
Finished-product brands compete through formulation portfolios and distribution. Himalaya and Dabur draw on Ayurveda; Bionorica develops herbal medicines; Blackmores, now a subsidiary of Japan's Kirin Holdings, has a broader natural-health portfolio. Adjacent nutraceutical products require their own classification and positioning. Gaia Herbs combines herbal supplements with sourcing and production oversight. Bio-Botanica and Ayana Bio supply ingredients for finished formulations, with their sales distinguished from the subsequent branded-product sale. [5, 6, 8, 9, 10, 12, 16]
- Finished herbal and natural-health portfolios: Himalaya Wellness, Dabur, Bionorica, Blackmores, Gaia Herbs and CanPrev.
- Other profiled brands: Patanjali Ayurved, Swisse, and Ricola. [1]
- Botanical ingredient capabilities: Bio-Botanica and Ayana Bio. [8, 9]
Competitive Benchmarking: Herbal Medicinal Products Market
| Participant | Documented Role | Portfolio or Capability | Value-chain Position | Commercial Context |
|---|---|---|---|---|
| Himalaya Wellness | Herbal formulation | Botanical profiling and formulation | Finished products | Ayurveda-based portfolio |
| Dabur India | Ayurveda and consumer products | Brands and distribution | Finished products | Domestic and international channels |
| Bionorica | Herbal medicinal products | Phytopharmaceutical development | Finished medicines | Medicinal-product markets |
| Blackmores | Natural-health products | Formulation and quality approach | Finished products | Broader supplement portfolio |
| Gaia Herbs | Herbal supplements | Farm, laboratory and manufacturing oversight | Finished products | Sourcing-linked brand positioning |
| CanPrev / Apotex | Natural-health portfolio | CanPrev, Cyto-Matrix and Orange Naturals | Finished products | Pharmacy and wider retail channels |
| Bio-Botanica | Botanical extraction | Liquid and powder ingredients | Ingredient supply | Several formulation industries |
| Ayana Bio | Plant-cell-derived botanicals | Botanical ingredient platform | Ingredient supply | Consumer-product formulation |
Key Developments in Herbal Medicinal Products
- Apotex announced its acquisition of CanPrev on February 3, 2025. The transaction adds natural-health brands and distribution relationships to its business. [7]
- The 2025 Chinese Pharmacopoeia came into force on October 1, 2025, with requirements for relevant product standards and dossiers. [13]
- India’s Ministry of Ayush described its drug-development, standardization and product-quality support programs in December 2025. [14]
Key Players in Herbal Medicinal Products
Finished-product Portfolios
- Himalaya Wellness
- Dabur India
- Patanjali Ayurved
- Swisse
- Bionorica
- Blackmores
- Ricola
- Gaia Herbs
- CanPrev / Apotex
Botanical Ingredient Supply
- Bio-Botanica
- Ayana Bio
Herbal Medicinal Products Market - Report Scope
| Coverage Field | Report Scope |
|---|---|
| Market Breakdown | Product; Indication; Distribution Channel |
| Quantitative Units | Revenue in USD billion |
| Market Definition | Finished herbal formulations across medicinal and relevant consumer-health categories, organized by product format, indication positioning and distribution channel. Local classification determines the applicable medicinal or supplement route. |
| Exclusions | Conventional non-botanical drugs; ordinary foods and beverages; cosmetics without the covered herbal-health positioning; separately counted bulk ingredient revenue. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Country Profiles | China; India; Brazil; United States; Germany |
| Competitive Coverage | Finished-product brands, formulation capabilities and supporting botanical-ingredient suppliers |
| 2025 Market Value | Estimated at USD 250.1 billion |
| 2026 Market Value | USD 271.1 billion |
| 2036 Forecast Value | USD 607.3 billion |
| CAGR | 8.4% |
| Forecast Period | 2026 to 2036 |
Herbal Medicinal Products Market - Research Framework
| Research Area | Coverage |
|---|---|
| Market Coverage | Finished herbal formulations and their sales channels |
| Industry Evidence | Regulatory frameworks, company formulation documentation and distribution announcements |
| Geographic Analysis | Product categories, medicinal standards and route-to-market requirements |
| Competitive Analysis | Portfolio, botanical processing, documentation and distribution capabilities |
Herbal Medicinal Products Market by Segments
Herbal Medicinal Products Market segmented by Product:
- Tablets and Capsules
- Powders
- Extracts
- Syrups
Herbal Medicinal Products Market segmented by Indication:
- Digestive Health
- Respiratory Care
- Pain Management
- Skin Care
Herbal Medicinal Products Market segmented by Distribution Channel:
- Pharmacies
- Hospital Pharmacies
- Online Stores
- Retail Stores
Herbal Medicinal Products Market by Region
- North America
- United States
- Canada
- Mexico
- Latin America
- Brazil
- Chile
- Rest of Latin America
- Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan and Baltic Countries
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- Middle East and Africa
- Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
Research Sources and Bibliography
- [1] U.S. FDA (2016, December). Botanical drug development guidance.
- [2] European Medicines Agency. Herbal medicinal product pathways.
- [3] U.S. FDA. What Is a Botanical Drug?
- [4] Himalaya Wellness. Formulating a Herbal Drug.
- [5] Bionorica. Research and Development.
- [6] Apotex (2025, February 3). CanPrev acquisition announcement.
- [7] Bio-Botanica. Company and Botanical Extraction Capabilities.
- [8] Ayana Bio. Plant-cell-derived Botanical Ingredients.
- [9] Dabur. Digital Annual Report 2025–2026: About Dabur.
- [10] European Medicines Agency. Quality of Herbal Medicinal Products: Questions and Answers.
- [11] Gaia Herbs. Company, Farm and Manufacturing Overview.
- [12] National Medical Products Administration (2025). 2025 Chinese Pharmacopoeia implementation.
- [13] Press Information Bureau (2025, December 9). Standardisation and Validation of Ayush Drugs.
- [14] Anvisa. Registration of Herbal Products.
- [15] Blackmores. Innovation and Quality Approach.
This Report Answers
- What was the estimated herbal medicinal products market value in 2025?
- How large is the market in 2026 and what is forecast for 2036?
- Why do tablets and capsules lead product demand?
- Which indication group holds the largest profiled share?
- How do pharmacies and online stores serve herbal-product brands?
- Which countries have the fastest profiled growth rates?
- How do finished-product brands and ingredient suppliers differ?
- What connects botanical consistency with commercial market access?
Frequently Asked Questions
How big is the herbal medicinal products market in 2026?
The market reaches USD 271.1 billion in 2026, following an estimated USD 250.1 billion in 2025. [1]
What is the market forecast for 2036?
The market is forecast at USD 607.3 billion by 2036 at 8.4% CAGR over 2026 to 2036. [1]
Which product format leads?
Tablets and capsules hold 38.0% of product demand in 2026. [1]
Which indication group leads?
Digestive health accounts for 18.0% of market value. [1]
Which distribution channel leads?
Pharmacies represent 45.0% of channel demand. [1]
Which profiled country grows fastest?
China leads at 9.5% CAGR, followed by India at 9.0%, over 2026 to 2036. [1]
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product, 2026 to 2036
- Tablets and Capsules
- Powders
- Extracts
- Syrups
- Y-o-Y Growth Trend Analysis By Product, 2021 to 2025
- Absolute $ Opportunity Analysis By Product, 2026 to 2036
- Global Market Analysis and Forecast, By Indication, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Indication, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Indication, 2026 to 2036
- Digestive Health
- Respiratory Care
- Pain Management
- Skin Care
- Y-o-Y Growth Trend Analysis By Indication, 2021 to 2025
- Absolute $ Opportunity Analysis By Indication, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Pharmacies
- Hospital Pharmacies
- Online Stores
- Retail Stores
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- Mexico
- By Product
- By Indication
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Indication
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Chile
- Rest of Latin America
- By Product
- By Indication
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Indication
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- By Product
- By Indication
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Indication
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan and Baltic Countries
- Rest of Eastern Europe
- By Product
- By Indication
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Indication
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product
- By Indication
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Indication
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- By Product
- By Indication
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Indication
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
- By Product
- By Indication
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Indication
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Indication
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Indication
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Indication
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Indication
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Indication
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Indication
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Indication
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Indication
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Indication
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Indication
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Indication
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Indication
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Indication
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Indication
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Indication
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Indication
- By Distribution Channel
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Indication
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Indication
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Indication
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Indication
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Indication
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product
- By Indication
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Himalaya Wellness
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Dabur India
- Bionorica
- Blackmores
- Gaia Herbs
- CanPrev / Apotex
- Bio-Botanica
- Ayana Bio
- Patanjali Ayurved
- Swisse
- Ricola
- Himalaya Wellness
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


