

- Market Size (2026)
- USD 74900.0 Mn
- Forecast (2036)
- USD 140400.0 Mn
- CAGR (2026 to 2036)
- 6.5%
How big is Folding Boxboard Market in 2026?
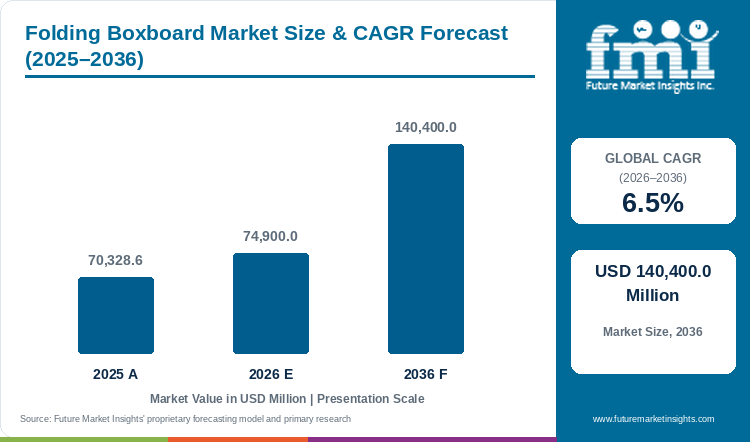
Sales in the folding boxboard market are projected to grow at 6.5% CAGR, with the market size rising from USD 70,328.6 million in 2025 to USD 74,900.0 million in 2026 and reaching USD 140,400.0 million by 2036.
Increasing demand for sustainable retail packaging and the urgent transition away from plastic trays and multi-layer laminates has surged adoption of folding boxboard across consumer goods. As per Future Market Insights analysis, the global folding boxboard market is valued at USD 70,328.6 million in 2025 and reaches USD 74,900.0 million in 2026. Sales are projected to touch USD 140,400.0 million by 2036, advancing at a steady 6.5% CAGR and generating USD 65,500.0 million in added revenue over the forecast decade. Packaging converters and brand owners are shifting toward renewable paperboard packaging solutions to satisfy strict supermarket recyclability standards and material-reduction mandates.
In February 2026, preliminary data from Cepi indicated that European packaging paper and board output remained comparatively stable in 2025 despite a 1.5% drop in total paper production, underscoring strong commercial resilience in cartonboard compared to graphic paper grades [1]. Pulp-based material accounts for 70.0% of material demand in 2026, as food and healthcare cartons require high brightness, taint-free barrier coatings, and smooth converting surfaces. Across evaluated countries, China expands at a leading 8.3% CAGR, followed by the USA at 6.0%, although rising thermal drying costs and coating-line capital expenditures restrain smaller regional mills.
Key Market Trends & Insights
- By material type: Pulp-based materials are projected to account for 70.0% in 2026, supported by high brightness and food-contact suitability.
- By structure: Single-layer structures are estimated to hold 30.0% in 2026, owing to economical converting for dry and cost-sensitive cartons.
- By application: Food and beverages are forecast to represent 50.0% in 2026, driven by frequent pack turnover and plastic-to-paper substitution.
- By end user: FMCG manufacturers lead demand as branded retail products require printable, lightweight, and tamper-evident cartons.
Regional Highlights
- Fastest-growing evaluated country: China, at 8.3% CAGR from 2026 to 2036.
- By country: Indonesia at 7.2%, India at 7.1%, and Brazil at 6.5% follow, while the USA records 6.0% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Folding Boxboard Market (USD million and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 70,328.6 million |
| Estimated Market Size in 2026 | USD 74,900.0 million |
| Projected Market Size by 2036 | USD 140,400.0 million |
| CAGR, 2026 to 2036 | 6.5% |
| Added Revenue, 2026 to 2036 | USD 65,500.0 million |
Country commercial conditions differ as mills navigate uneven regional demand alongside stricter packaging design rules. The European Union Packaging and Packaging Waste Regulation entered into force in February 2025 and begins applying from August 2026 [2]. Buyers are therefore accelerating the qualification of lighter boards and water-based dispersion barriers within paper and paperboard packaging lines that preserve carton stiffness, creasing accuracy, and high-speed line performance without disrupting existing repulping streams.
Fiber and Carton Conversion Sizing
Table 2: Fiber and Carton Conversion Sizing for the Folding Boxboard Market (USD million and scenario indicators), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD million) | 70,328.6 | 74,900.0 | 140,400.0 |
| Indicative shipped volume (million tonnes) | 47-51 | 49-53 | 78-86 |
| Average value per tonne (USD) | 1,380-1,500 | 1,410-1,530 | 1,630-1,800 |
| Barrier-coated share of premium demand | 18-22% | 20-24% | 31-38% |
Per Capita & Converter Spending Indicators
Folding boxboard demand follows packaged food volume, branded retail penetration, and converter investment. Higher-value growth comes from specialized boxboard packaging formats that combine lightweight grades retaining stiffness after scoring with dispersion coatings that add grease or moisture resistance without blocking fiber recovery.
Table 3: Per Capita Spending Indicators for the Folding Boxboard Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD) | 8.55 | 9.02 | 15.69 |
| Spend per 1,000 people (USD) | 8,545 | 9,024 | 15,687 |
| Food and beverage revenue (USD million) | 35,164.3 | 37,450.0 | 70,200.0 |
Table 4: Converter and Application Spending Indicators for the Folding Boxboard Market (USD million and percentages), 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 74,900.0 million | Report value |
| Pulp-based material revenue | USD 52,430.0 million | 70.0% share |
| Food and beverage revenue | USD 37,450.0 million | 50.0% share |
| Single-layer structure revenue | USD 22,470.0 million | 30.0% share |
Analyst Perspective
“Folding boxboard purchasing is shifting from simple grammage comparisons toward stiffness, coating performance, and recovery-system compatibility. Mills that combine fiber security with stable converting performance will protect premium contracts.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Folding Boxboard Market segmented?
The folding boxboard market is segmented by material type, structure, application, and end user. In 2026, pulp-based materials are projected at 70.0%, single-layer structures at 30.0%, and food and beverages at 50.0%.
By material type: Pulp-based, bleached chemical pulp, recovered paper, and others.
By structure: Single-layer and multi-layer.
By application: Food and beverages, personal care, healthcare, household products, and others.
By end user: FMCG manufacturers, pharmaceutical companies, retailers, and food service providers.
Why does Pulp-Based Material account for a notable share of material demand?
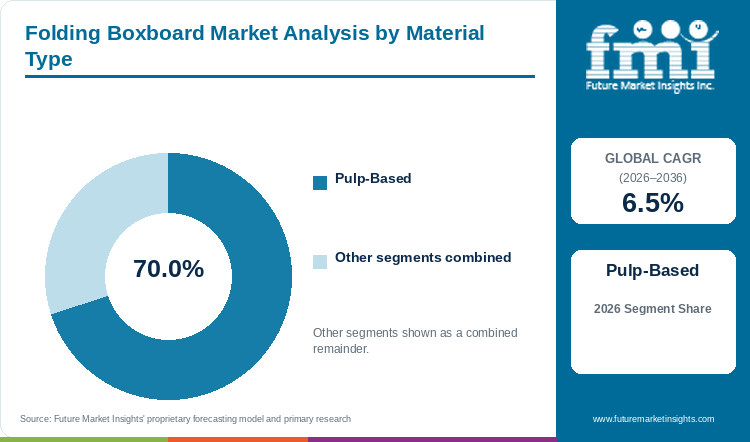
Pulp-based material represents 70.0% of material demand in 2026, balancing high brightness with reliable carton stiffness.
Table 5: Material Type Share for the Folding Boxboard Market (percentage share), 2026
| Material Type | Share (2026) |
|---|---|
| Pulp-Based Materials | 70.0% |
| Other Segments Combined | 30.0%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment share from 100.0%.
Table 6: Material Leadership and Market Growth for the Folding Boxboard Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.5% |
| Leading Segment | Pulp-Based Materials |
Fresh and bleached pulp provides uniform formation, high whiteness, and clean surfaces for precise graphics. These attributes reduce print variation and support food or healthcare cartons where odor, migration, and shelf presentation influence qualification.
- Pulp-based materials are projected to hold 70.0% share in 2026, supported by premium print and hygiene requirements.
- An FMI analyst notes that lightweight virgin-fiber grades will retain value where recovered-fiber variability affects coating and creasing.
What supports Single-Layer Structures as a preferred choice in the structure category?
Single-layer structures account for 30.0% of structure demand in 2026, meeting economical conversion and dry-pack requirements.
Single-layer board remains relevant where barrier complexity is low and converters prioritize throughput, competing directly with clay coated recycled boxboard across cost-sensitive dry-food packs. The simpler sheet construction reduces delamination risk during die cutting and supports private-label cartons where unit cost matters more than premium reverse-side appearance.
- By structure, single-layer board is estimated to hold 30.0% in 2026, owing to economical high-speed converting.
- Demand remains concentrated in dry food, household, and value-tier consumer packs with moderate protection requirements.
How is Food and Beverages gaining use across applications?
Food and beverages hold 50.0% of application demand in 2026, driven by recurring carton turnover and fiber substitution.
Food cartons combine high consumption frequency with strong pressure to replace plastic trays, sleeves, and liners, complementing emerging fiber substrates such as sugarcane packaging in commercial takeout lines. Mills are responding with direct-food-contact grades and dispersion barriers that resist grease or moisture while preserving repulpability.
- In 2026, food and beverages lead application demand with 50.0% share, reinforced by takeaway and retail carton volumes.
- Barrier performance expands addressable demand in chilled foods, confectionery, frozen foods, and quick-service packaging.
Why are buyers selecting FMCG Manufacturers within the end-user segment?
FMCG manufacturers lead end-user demand in 2026 as branded cartons combine protection, graphics, and automated line compatibility.
FMCG buyers purchase board against tightly controlled caliper, stiffness, print, and scoring tolerances, while luxury personal-care cartons incorporate aesthetics from gift packaging to drive premium shelf presentation. A stable sheet reduces stoppages across high-speed cartoning lines and gives brand teams consistent color reproduction across regional converter networks.
- FMCG demand is underpinned by frequent redesign cycles and large production runs across food and personal care.
- Approved-supplier status depends on dependable fiber sourcing, food-contact documentation, and repeatable converting behavior.
What are the drivers, restraints, and opportunities in the Folding Boxboard Market?
Plastic substitution raises demand, while energy and fiber volatility pressure margins, and recyclable barrier coatings create premium value.
- Driver: Packaging regulation and brand commitments shift retail cartons toward renewable fiber substrates.
- Restraint: High energy costs, fiber price volatility, and coating-line investment restrict smaller mill economics.
- Opportunity: Lightweight barrier-coated grades can replace plastic components without sacrificing print or food protection.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Retail packaging is moving toward board formats that can pass recyclability assessments without losing shelf performance, frequently deploying cartonboard alongside molded fiber packaging in food-service applications. Cepi data shows packaging paper and board remained broadly stable in 2025 even as total European paper and board output declined [1]. The divergence confirms that packaging demand has a different cycle from graphic paper. Future Market Insights finds that food, healthcare, and personal-care buyers now specify stiffness and coating compatibility at the same time. Mills answer with lighter multi-ply constructions that place stronger fibers where bending stress is highest. The design reduces material use per carton and protects print quality. Converters gain more saleable blanks from each tonne, which supports long-term qualification despite cautious consumer spending.
Risk Assessment of the Folding Boxboard Market: Operational and Coating Friction
Coating and drying create the main operating friction for higher-value folding boxboard. Moisture variation can distort caliper while poor coating holdout causes mottling and weak ink density. In tertiary logistics, primary cartons interface directly with secondary corrugated board cases, requiring consistent corner strength during palletization. The Packaging and Packaging Waste Regulation raises design scrutiny across European packs and begins applying in August 2026 [2]. Mills must therefore prove that barrier chemistry does not block recovery in existing paper streams. Qualification takes longer when food-contact migration and recyclability testing run in parallel. Energy-intensive drying also raises the cost of adding barrier layers. Smaller mills face a choice between capital spending and commodity exposure. Buyers respond by consolidating volumes with suppliers that can document coating composition, runnability, and fiber recovery performance.
Commercial Opportunity Analysis: Lightweighting and Functional Barrier Differentiation
The strongest value pool sits between standard cartonboard and plastic-laminated packs. Brand owners want grease, moisture, and oxygen resistance without adding structures that complicate collection, mirroring consumer preferences observed in eco friendly paper plates and circular food containers. In January 2026, Stora Enso introduced Performa Lumi as a lightweight GC1 folding boxboard for beauty, healthcare, food, and personal-care cartons [3]. The grade uses a coated reverse and covers 205 to 310 gsm. The launch shows how suppliers can combine visual quality with yield improvement. Metsä Board completed a EUR 60 million modernisation of its Simpele mill in 2025, introducing curtain and blade coating technology to raise print quality and visual uniformity for food and healthcare packaging grades. These investments move competition away from nominal grammage. Commercial advantage comes from delivering lower pack weight, stable scoring, and repeatable barrier performance on existing converter equipment.
Folding Boxboard Market by Country (2026 to 2036)
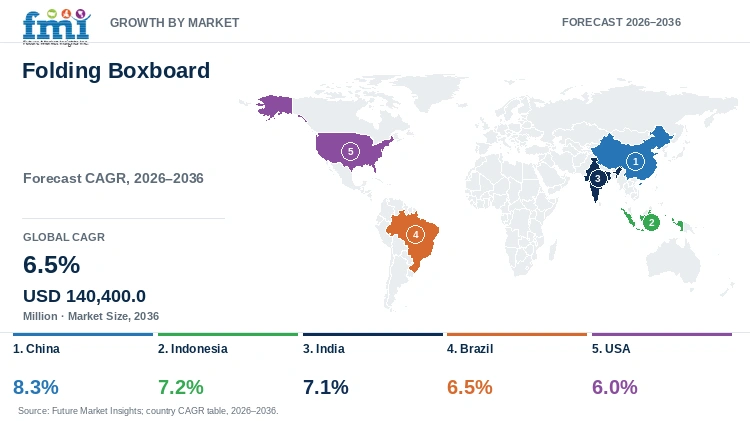
According to FMI, China represents the fastest-growing folding boxboard market among the five evaluated countries at 8.3% CAGR from 2026 to 2036, while the USA records 6.0% CAGR. Commercial outcomes differ with retail formalization, fiber economics, plastic rules, and local mill investment.
Table 7: Country CAGR and Primary Growth Levers for the Folding Boxboard Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| China | 8.3% | Bleached board capacity and plastic substitution |
| Indonesia | 7.2% | Integrated fiber base and regional exports |
| India | 7.1% | Branded FMCG and organized retail expansion |
| Brazil | 6.5% | Low-cost eucalyptus fiber and export economics |
| USA | 6.0% | Inventory normalization and domestic supply security |
Source: Future Market Insights analysis
China Folding Boxboard Market Outlook (2026 to 2036)
Large-scale paper and board capacity gives Chinese mills a direct route into food-delivery and retail substitution demand. In 2026, the National Bureau of Statistics of China confirmed that national industrial paper and board output expanded during 2025 while several mature western producers recorded declines, reinforcing China’s scale advantage [7]. Folding boxboard sales are forecast to expand at 8.3% CAGR through 2036. Yet excess capacity and aggressive pricing can weaken returns on premium coating assets. Producers are shifting new machines toward bleached grades, lighter calipers, and high-whiteness surfaces that qualify for consumer brands. The commercial response also includes integrated pulp supply and domestic coating chemistry. These measures lower unit costs while meeting the print and food-contact requirements needed for plastic-replacement cartons.
Key takeaway: In China, production scale and plastic substitution support rapid growth, while premium-grade discipline remains central to margin protection.
Indonesia Folding Boxboard Market Outlook (2026 to 2036)
Indonesia enters the market through fiber availability and export positioning rather than domestic premium consumption alone. According to Statistics Indonesia trade data, paper and paperboard exports create a resilient base for serving Southeast Asian converters with competitive standard grades [8]. The country’s folding boxboard outlook is anticipated to advance at 7.2% CAGR over the assessment period. Port logistics and sustainability scrutiny around plantation sourcing create the main friction. Integrated producers respond with chain-of-custody certification, efficient pulp links, and larger runs that spread machine costs across regional contracts. Export success depends on consistent caliper and print surfaces that reduce converter waste. Producers that document responsible fiber and dependable lead times can move beyond price-led supply.
Key takeaway: In Indonesia, integrated fiber and export access support expansion, while verified sourcing determines entry into premium regional accounts.
India Folding Boxboard Market Outlook (2026 to 2036)
Formal retail and packaged consumer goods are raising the quality threshold for cartons across India. As documented in national manufacturing accounts from the Ministry of Statistics and Programme Implementation, food, personal-care, and pharmaceutical brands increasingly need repeatable graphics and stronger protection than low-grade board provides [9]. Folding boxboard demand in India is forecast to rise at 7.1% CAGR over the forecast period. The main hurdle is converter fragmentation, which creates uneven quality expectations and price sensitivity. Domestic mills are improving coating uniformity and stiffness to displace imported premium grades. Lightweight board helps buyers control unit cost without giving up shelf impact. Suppliers also work through converter qualification programs that align die-cutting, creasing, and ink performance across regional plants.
Key takeaway: In India, packaged retail expansion raises board quality needs, while lightweight domestic grades address persistent cost sensitivity.
Brazil Folding Boxboard Market Outlook (2026 to 2036)
Brazil’s advantage begins with fast-growing eucalyptus and integrated pulp economics. The fiber base supports competitive virgin-board production and provides insulation from some imported pulp volatility. Adoption of folding boxboard in Brazil is estimated to expand at 6.5% CAGR through 2036. Currency movement and long transport distances can still disrupt delivered costs for converters. As highlighted in Klabin corporate disclosures, integrated forestry, board production, and port access support both domestic and export volumes [11]. Food and agricultural brands favor high-strength cartons that protect products through longer distribution routes. Mills that combine fiber efficiency with printable surfaces can secure contracts across Latin America and overseas markets.
Key takeaway: In Brazil, integrated eucalyptus economics support competitive board, while logistics discipline converts fiber advantage into reliable supply.
USA Folding Boxboard Market Outlook (2026 to 2036)
The United States is moving from inventory correction toward selective carton demand recovery, driving demand for domestic united states boxboard packaging grades. Buyers remain cautious after destocking, but foodservice, healthcare, and domestic sourcing priorities support stable board procurement according to U.S. Census Bureau retail indicators [10]. The USA folding boxboard sector is projected to record 6.0% CAGR during the assessment period. High operating costs and competition from imports limit broad price increases. Domestic suppliers respond through mill rationalization, grade specialization, and contracts tied to service reliability. Converter customers place more weight on short lead times and consistent machine performance after recent supply disruptions. Premium SBS and folding carton grades retain value where food contact, color control, and local supply assurance outweigh the lowest sheet price.
Key takeaway: In the USA, supply security and performance consistency support recovery, while high costs keep capacity and grade choices disciplined.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Folding Boxboard Market?
Stora Enso, Metsä Board, International Paper, Mayr-Melnhof Karton, Sappi, Nine Dragons Paper, Klabin, ITC Limited, Oji Holdings, and Nippon Paper Industries are significant market players.
FMI data suggests that competition divides between integrated fiber owners, specialist cartonboard mills, and diversified paper groups. Qualification depends on print quality, stiffness, food-contact documentation, coating performance, and dependable regional supply.
- European premium board platforms: Stora Enso, Metsä Board, Mayr-Melnhof Karton, and Sappi.
- Asian integrated producers: Nine Dragons Paper, ITC Limited, Oji Holdings, and Nippon Paper Industries.
- Americas fiber-integrated suppliers: International Paper and Klabin.
Competitive Benchmarking: Folding Boxboard Market
Table 8: Competitive Benchmarking for the Folding Boxboard Market (qualitative capability ratings), 2026
| Company | FBB Breadth | Fiber Integration | Barrier Capability | Geographic Reach |
|---|---|---|---|---|
| Stora Enso | High | High | High | High |
| Metsä Board | High | High | High | High |
| International Paper | Medium | High | Medium | High |
| Mayr-Melnhof Karton | High | Medium | High | High |
| Sappi | Medium | High | High | High |
| Nine Dragons Paper | High | High | Medium | High |
| Klabin | Medium | High | Medium | Medium |
| ITC Limited | Medium | High | Medium | Medium |
| Oji Holdings | High | High | High | High |
| Nippon Paper Industries | Medium | High | High | High |
Key Developments in the Folding Boxboard Market
- In January 2026, Stora Enso introduced Performa Lumi, a lightweight GC1 folding boxboard produced on its Oulu BM6 line [3].
- In April 2025, Metsä Board announced an improved version of MetsäBoard Classic FBB featuring curtain and blade coating technology for enhanced print quality, produced at its Simpele mill following a EUR 60 million modernisation investment [4].
- In September 2025, Metsä Board began the installation phase of its Simpele mill board machine modernisation, a five-week investment shutdown covering a full coating section upgrade and expansion of the coating kitchen [5].
Key Players in the Folding Boxboard Market
Premium European Cartonboard Producers
- Stora Enso
- Metsä Board
- Mayr-Melnhof Karton
- Sappi
Integrated Asian Paper Groups
- Nine Dragons Paper
- ITC Limited
- Oji Holdings
- Nippon Paper Industries
Americas Fiber-Integrated Producers
- International Paper
- Klabin
Folding Boxboard Market - Report Scope
Table 9: Report Scope for the Folding Boxboard Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Material Type; Structure; Application; End User |
| Quantitative Units | USD Million |
| Market Definition | Supplier revenue from folding boxboard and solid bleached cartonboard used in folding-carton applications. Liquid packaging board and containerboard are excluded. |
| Regions Covered | North America; Latin America; Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | China, Indonesia, India, Brazil, USA, and additional countries in the full report |
| Key Companies Covered | Stora Enso, Metsä Board, International Paper, Mayr-Melnhof Karton, Sappi, Nine Dragons Paper, Klabin, ITC Limited, Oji Holdings, Nippon Paper Industries |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Folding Boxboard Market - Research Methodology
Table 10: Research Methodology for the Folding Boxboard Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Interviews with paperboard producers, converters, coating suppliers, distributors, brand owners, and packaging procurement specialists validate demand and purchasing behavior. |
| Secondary Research | Company annual reports, investor presentations, regulatory publications, industry associations, technical papers, trade journals, company websites, and product literature inform the assessment. |
| Market Sizing and Forecasting | Top-down and bottom-up approaches assess shipment value, grade mix, application demand, and country growth for 2026 to 2036. |
| Data Triangulation and Validation | Results are checked against paper and board production, packaging regulation, corporate investments, trade indicators, and historical demand patterns. |
Folding Boxboard Market by Segments
Folding Boxboard Market segmented by Material Type:
- Pulp-Based
- Bleached Chemical Pulp
- Recovered Paper
- Others
Folding Boxboard Market segmented by Structure:
- Single-Layer
- Multi-Layer
Folding Boxboard Market segmented by Application:
- Food and Beverages
- Personal Care
- Healthcare
- Household Products
- Others
Folding Boxboard Market segmented by End User:
- FMCG Manufacturers
- Pharmaceutical Companies
- Retailers
- Food Service Providers
Folding Boxboard Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Nordics
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Cepi. (2026, February). Preliminary statistics 2025: European pulp and paper industry. Official source
- [2] European Commission. (2025). Packaging and packaging waste regulation: New rules for more sustainable packaging. Official source
- [3] Stora Enso. (2026, January 22). Stora Enso introduces Performa Lumi, a lightweight GC1 folding boxboard with premium visual performance.
- [4] Metsä Board. (2025, April 3). MetsäBoard Classic FBB leads the pack with better printability and a smaller CO2 footprint.
- [5] Metsä Board. (2025, August 19). Metsä Board starts installation phase of board machine modernisation at Simpele mill – MetsäBoard Classic FBB renewed to meet growing quality and sustainability demands.
- [6] Future Market Insights. (2026, February 17). Folding boxboard market: Forecast and outlook, 2026 to 2036.
- [7] National Bureau of Statistics of China. (2026). Statistical communique on national economic and social development in 2025. Official source
- [8] Statistics Indonesia. (2026). Indonesia foreign trade statistics 2025.
- [9] Government of India, Ministry of Statistics and Programme Implementation. (2026). National accounts statistics 2025-26.
- [10] U.S. Census Bureau. (2026). Annual retail trade survey and manufacturing indicators. Official source
- [11] Klabin S.A. (2026). Annual report 2025: Paperboard and packaging operations.
- [12] ITC Limited. (2026). Report and accounts 2026: Paperboards, paper and packaging.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the folding boxboard market in 2026 and what is forecast for 2036?
- Which packaging and regulatory pressures support folding boxboard demand?
- Why do pulp-based materials lead the material category?
- Why do food and beverages lead application demand?
- How do growth rates differ across China, Indonesia, India, Brazil, and the USA?
- Which companies supply significant folding boxboard grades today?
- What limits mill investment or supplier switching?
- What should converters evaluate before qualifying a folding boxboard grade?
Frequently Asked Questions
How big is the Folding Boxboard Market in 2026, and what is forecast for 2036?
Future Market Insights estimates the global market at USD 74,900.0 million in 2026 and USD 140,400.0 million by 2036.
What is the CAGR from 2026 to 2036?
As per FMI, the market is projected to expand at 6.5% CAGR over the assessment period.
Which material type leads?
Projections indicate that pulp-based material will hold 70.0% share in 2026.
Which application leads?
Food and beverages are projected to account for 50.0% of application demand in 2026.
Which country has the fastest evaluated growth?
China is projected to register 8.3% CAGR from 2026 to 2036.
Who are the key players?
Key participants include Stora Enso, Metsä Board, International Paper, Mayr-Melnhof Karton, Sappi, Nine Dragons Paper, Klabin, ITC Limited, Oji Holdings, and Nippon Paper Industries.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Material Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Material Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Material Type, 2026 to 2036
- Pulp-Based
- Bleached Chemical Pulp
- Recovered Paper
- Others
- Y-o-Y Growth Trend Analysis By Material Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Type, 2026 to 2036
- Global Market Analysis and Forecast, By Structure, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Structure, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Structure, 2026 to 2036
- Single-Layer
- Multi-Layer
- Y-o-Y Growth Trend Analysis By Structure, 2021 to 2025
- Absolute $ Opportunity Analysis By Structure, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Application, 2026 to 2036
- Food and Beverages
- Personal Care
- Healthcare
- Household Products
- Others
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By End User, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End User, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End User, 2026 to 2036
- FMCG Manufacturers
- Pharmaceutical Companies
- Retailers
- Food Service Providers
- Y-o-Y Growth Trend Analysis By End User, 2021 to 2025
- Absolute $ Opportunity Analysis By End User, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Material Type
- By Structure
- By Application
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Structure
- By Application
- By End User
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Material Type
- By Structure
- By Application
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Structure
- By Application
- By End User
- Key Takeaways
- Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Nordics
- By Material Type
- By Structure
- By Application
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Structure
- By Application
- By End User
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Material Type
- By Structure
- By Application
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Structure
- By Application
- By End User
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Material Type
- By Structure
- By Application
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Structure
- By Application
- By End User
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Material Type
- By Structure
- By Application
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Structure
- By Application
- By End User
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Structure
- By Application
- By End User
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Structure
- By Application
- By End User
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Structure
- By Application
- By End User
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Structure
- By Application
- By End User
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Structure
- By Application
- By End User
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Structure
- By Application
- By End User
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Structure
- By Application
- By End User
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Structure
- By Application
- By End User
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Structure
- By Application
- By End User
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Structure
- By Application
- By End User
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Structure
- By Application
- By End User
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Structure
- By Application
- By End User
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Structure
- By Application
- By End User
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Structure
- By Application
- By End User
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Structure
- By Application
- By End User
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Structure
- By Application
- By End User
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Structure
- By Application
- By End User
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Structure
- By Application
- By End User
- Indonesia
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Structure
- By Application
- By End User
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Material Type
- By Structure
- By Application
- By End User
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Stora Enso
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Metsä Board
- International Paper
- Mayr-Melnhof Karton
- Sappi
- Nine Dragons Paper
- Klabin
- ITC Limited
- Oji Holdings
- Nippon Paper Industries
- Stora Enso
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


