

- Market Size (2026)
- USD 1.5 Bn
- Forecast (2036)
- USD 3.0 Bn
- CAGR (2026 to 2036)
- 7.2%
How big is Lecithin Market in 2026?
USD 1.5 billion in 2026 and USD 3.0 billion by 2036, expanding at 7.2% CAGR.
Demand of the lecithin is anticipated to expand at a 7.2% CAGR over the forecast period, building from USD 1.4 billion in 2025 to USD 1.5 billion in 2026, before pushing valuation to USD 3.0 billion by 2036. Manufacturers are retaining lecithin because one ingredient can perform emulsification or dispersion without changing an established production step. The USA Food and Drug Administration updated its food-substance inventory in July 2026 and lists lecithin as an emulsifier and texturizer. Federal recognition supports routine food use and keeps qualification focused on source identity and process performance.
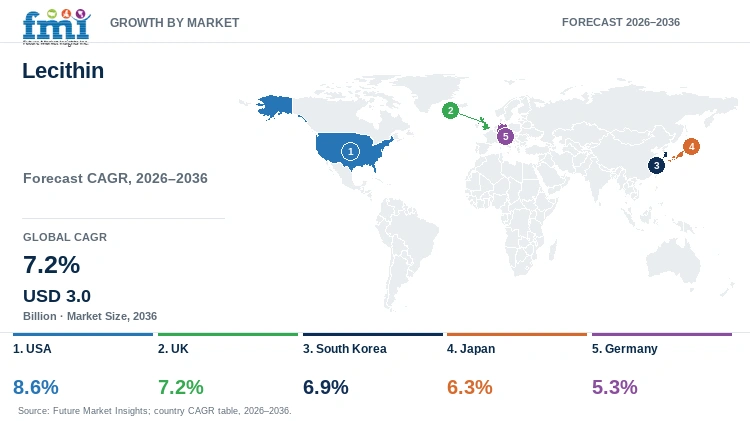
National labeling rules are shaping how the global forecast converts into qualified ingredient orders. The USA lecithin market is projected to grow at 8.6% CAGR compared with 6.3% for Japan through 2036. Japan’s Consumer Affairs Agency published an allergen-labeling handbook in April 2026 and the handbook identifies soy and egg yolk origins for lecithin. Botanical origin is part of the documentation reviewed during Japanese reformulation and supplier qualification.
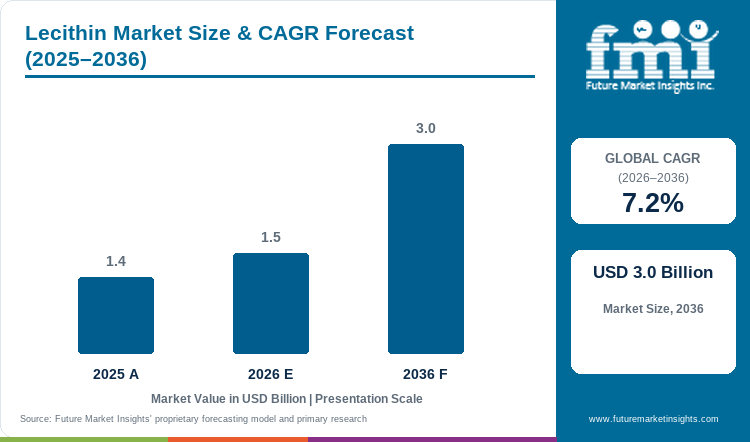
Key Takeaways of Lecithin Market
- Repeat formulation use supports lecithin demand because emulsification and dispersion remain routine requirements in several commercial applications.
- Fluid is estimated to hold 60.1% of product type revenue in 2026, attributable to installed liquid dosing systems in commercial plants.
- By source soy is forecast to represent 68.3% of revenue in 2026, supported by familiar specifications that simplify repeat qualification.
- Food is expected to lead application revenue with 30.3% share in 2026, reflecting routine use across multiple formulation functions.
- Botanical-source changes can delay adoption because labeling review and finished-process validation often precede routine purchasing approval.
- Some of the key players in this market include Cargill, Incorporated, ADM, Bunge Global SA, Lasenor Emul S.L., Sonic Biochem Extractions Pvt. Ltd., American Lecithin Company, Wilmar International Limited, Patanjali Foods Limited, and Lipoid GmbH.
Analyst Perspective
“Ingredient teams rarely switch lecithin on price alone because botanical origin can change labeling and line performance. Suppliers earn repeat business when source identity and physical form stay consistent during the customer qualification cycle.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights
How is the Lecithin Market segmented?
The lecithin market is segmented by product type, source and application.
The lecithin market is segmented by product type, source and application. Product type includes fluid, de-oiled and modified lecithin. Source covers soy, sunflower, rapeseed, egg and others. Application includes food, animal feed, nutraceuticals, others, cosmetics and pharmaceuticals.
How do high-volume dosing systems support fluid lecithin demand?
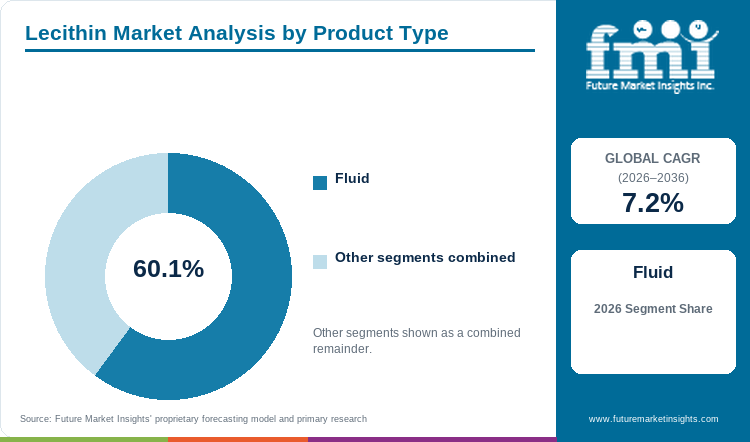
Fluid lecithin is practical for plants that meter emulsifier directly into fat or aqueous phases without a separate powder-handling stage. Controlled storage temperature and pumping conditions affect dosing because viscosity changes during routine production. ADM documents standardized fluid lecithin for mixing and release functions within commercial food formulations. Production lines built around tanks and metering equipment can qualify fluid grades without changing the core dosing route. Dry handling requirements or greater water dispersibility can shift selection toward powdered or modified grades.
- Fluid is projected to hold 60.1% of product type revenue in 2026, attributable to direct compatibility with liquid handling systems.
- Food plants are retaining fluid grades because existing pumps and mixers already meet viscosity control and repeat dosing requirements.
How do origin labels shape soy lecithin selection?
Formulators are selecting soy lecithin because familiar specifications make the ingredient straightforward to qualify in many commercial formulations. Cargill documents soy beside sunflower and canola options within its current lecithin range for several food applications. The available source range lets formulators retain the same functional category while changing botanical origin for a defined label requirement. Soy carries an allergen-label consideration in the United States and can require identity-preserved documentation for some purchasing programs.
- Soy is forecast to represent 68.3% of source revenue in 2026, reinforced by mature specifications that reduce repeat qualification changes.
- Alternative botanical sources are gaining attention as allergen positioning or non-GMO requirements justify additional qualification work for finished formulations.
How do food formulations sustain lecithin application demand?
Food manufacturers are using lecithin for emulsion control and release behavior in processes designed for functional ingredients. Lasenor documents soy and sunflower lecithin use in bakery alongside confectionery and instant-powder applications. The same ingredient can solve different production problems without pushing formulators into an unrelated additive class during reformulation. Bakery lines are testing viscosity or dough behavior during grade changes because small functional differences can alter throughput. Confectionery operations are comparing viscosity response as lecithin influences processing conditions and cocoa-butter use.
- By application food is forecast to represent 30.3% of revenue in 2026, influenced by routine formulations that use lecithin for several functions.
- Bakery and confectionery users are repeating purchases because ingredient performance remains stable in installed bread emulsifier and chocolate-processing systems.
What are the drivers, restraints and opportunities in the Lecithin Market?
Routine functional use supports demand, qualification friction slows switching and differentiated botanical formats create expansion routes.
- Driver: Multiple technical functions keep lecithin in repeat food and formulation purchasing cycles following commercial line qualification.
- Restraint: Supply variation and origin documentation can raise the cost and time required for supplier changes during production qualification.
- Opportunity: Sunflower and specialty phospholipid formats can serve applications that require different labels or handling characteristics during reformulation.
Why does multifunctional use sustain recurring lecithin orders?
Formulators are using lecithin repeatedly because one ingredient can perform several physical functions during production. FDA records for enzyme-modified lecithin identify emulsification as its technical effect within the federal food-substance inventory. Federal recognition supports repeat specification in products that depend on phase control for texture or processing consistency. Repeat orders are more durable once a grade performs reliably on the customer line under the same specification. Manufacturers are avoiding unnecessary reformulation work because an approved grade already solves the required mixing or release problem.
Why can botanical-source switching slow lecithin qualification?
Botanical origin is affecting availability and documentation during replacement-grade qualification. Lasenor reported in its first-quarter 2025 update that lecithin prices were roughly 15% to 20% above the previous quarter. The update linked pressure to lower soybean processing in India and tighter sunflower and rapeseed conditions. Purchasers cannot switch source automatically because allergen declarations or identity-preserved requirements can trigger fresh document review. Formulation teams often repeat line trials if a new botanical source changes handling or sensory performance.
How can source-specific lecithin formats expand supplier opportunities?
Suppliers are expanding source choice for customers seeking non-soy positioning without abandoning phospholipid functionality. FDA allergen guidance requires the food source of major allergens to appear on packaged-food labels and uses “lecithin (soy)” as an example. The rule makes botanical origin part of the commercial specification for products changing from soy-derived lecithin. Sunflower or rapeseed grades can address that labeling requirement once replacement performance is confirmed on the customer line. Dry or modified forms address handling and water-dispersibility limits that reduce the practicality of fluid grades. Bakery emulsions require documented processing equivalence during reformulation so successful trials can convert into routine production.
Which country CAGRs are profiled in the Lecithin Market?
| Country | CAGR |
|---|---|
| USA | 8.6% |
| UK | 7.2% |
| South Korea | 6.9% |
| Japan | 6.3% |
| Germany | 5.3% |
How do country-level CAGRs compare in the Lecithin Market?
The country forecasts span 3.3 percentage points and separate into three practical growth bands for supplier planning. USA and UK form the upper pair while South Korea and Japan occupy a narrower middle range. Germany follows at 5.3% with a more measured qualification environment instead of a declining market. The spacing compares forecast growth rates only and does not establish relative revenue size or current consumption.
- Federal ingredient rules in the USA support routine lecithin specification and reduce ambiguity during food formulation review and supplier qualification.
- UK additive authorization gives suppliers a defined E-number framework that keeps documentation central during formulation review and changes to approved ingredient sources.
- South Korea’s national additive specifications give importers a formal qualification route and require compliant documentation for commercial lecithin formulations.
- Japanese food-labeling requirements make botanical origin a practical selection factor for manufacturers qualifying soy-derived lecithin in packaged foods.
- Germany’s combination of EU additive authorization and national consumer-claim guidance rewards suppliers that can document approved use and support compliant ingredient descriptions.
Comparable CAGRs can produce different commercial conditions because each country applies its own labeling and qualification requirements. The full report provides country-level CAGR analysis across North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa.
Country-wise Analysis
- Federal allergen-labeling rules give United States formulators a national route for soy-derived ingredients in packaged foods. The USA lecithin market is projected to grow at 8.6% CAGR through 2036, led by routine food applications that preserve a qualification base. FDA issued its fifth-edition food-allergen labeling guidance in January 2025 for packaged foods under federal law. The guidance requires major allergen sources such as soybeans to be declared under applicable labeling rules. Food plants approve a new botanical source once label and process records match the intended product. Source records must accompany grade changes that can alter finished labels during commercial qualification. Suppliers serving United States food emulsifier applications need identity documentation that matches specifications during repeat qualification.
- United Kingdom food additive qualification spans separate arrangements for Great Britain and Northern Ireland. Lecithin demand in the UK is forecast to rise at 7.2% CAGR over the forecast period, aided by routine additive qualification under existing authorization rules. Food Standards Agency guidance lists lecithins as E 322 for England and Wales together with Northern Ireland. Food Standards Scotland confirms that approved E numbers apply in Great Britain including Scotland. Suppliers are maintaining grade records that meet the relevant jurisdictional requirements for commercial use. UK food plants are comparing botanical origin and physical form during qualification of new grades. European food emulsifier suppliers compete on documentation and application support that can shorten customer review cycles.
- South Korea maintains a national food-additive code that defines specifications used during ingredient control and commercial qualification. South Korea’s lecithin outlook is anticipated to advance at 6.9% CAGR over the assessment period, tied to additive specifications that formalize repeat qualification. The Ministry of Food and Drug Safety updated the Food Additives Code under Notice 2025-76 on November 26 2025. Importers use that national specification to check composition and documentation for food ingredients entering the country. Local customers may request translated records for production entry and purchasing approval. Food and nutrition manufacturers compare the approved specification with line performance during purchasing decisions. Suppliers with consistent composition and origin records can reduce avoidable review work during repeat ordering.
- Japanese labeling practice places botanical origin beside ingredient identity for soy-derived lecithin used in packaged foods. Lecithin demand in Japan is predicted to advance at 6.3% CAGR through 2036, due to labeling practices that keep botanical origin central to reformulation review. The Consumer Affairs Agency’s October 2025 Food Labeling Standards Q&A gives “lecithin (soy origin)” as an additive-labeling example. Grade changes can trigger label review even if emulsification performance stays comparable on qualified production lines. Suppliers need stable origin records and predictable technical behavior for replacement grades entering routine manufacturing. National labeling requirements keep precise documentation commercially relevant during routine food production and planned formulation changes.
- German food manufacturers operate under EU additive authorization and national guidance governing consumer-facing descriptions for food additives. Germany’s lecithin market is estimated to post 5.3% CAGR over the forecast period, shaped by mature processors that qualify functional additives within existing production systems. A joint state working group and the Federal Office of Consumer Protection and Food Safety adopted a naturalness decision tree for food additives in March 2025. The guidance covers food additives broadly and informs claim review for lecithin without measuring lecithin demand itself. Natural-positioning language can require separate review from technical qualification during approval of a new grade. Suppliers serving food additive applications need records that support performance and intended claim language during approval.
Who are the notable companies in the Lecithin Market?
Cargill, Incorporated, ADM, Bunge Global SA, Lasenor Emul S.L., Sonic Biochem Extractions Pvt. Ltd., American Lecithin Company, Wilmar International Limited, Patanjali Foods Limited, and Lipoid GmbH are the notable companies serving this market.
Competition includes integrated oilseed processors alongside specialist manufacturers and high-purity phospholipid suppliers serving narrower applications. Integrated groups manage botanical sourcing alongside conversion capacity while specialists compete on form modification and application support. Entry depends on repeatable specifications and complete customer documentation instead of corporate scale during routine qualification.
- Integrated ingredient platforms include Cargill, Incorporated, ADM, Bunge Global SA, Wilmar International Limited and Patanjali Foods Limited.
- Specialist lecithin suppliers include Lasenor Emul S.L., Sonic Biochem Extractions Pvt. Ltd. and American Lecithin Company.
- Lipoid GmbH supplies specialized phospholipid systems for pharmaceutical and nutrition applications that require tighter composition control.
Competitive Benchmarking: Lecithin Market
| Company | Botanical Source Breadth | Lecithin Form Breadth | Application/Technical Specialization | Geographic Reach |
|---|---|---|---|---|
| Cargill, Incorporated | High | High | High | North America and Europe with broader ingredient distribution |
| ADM | High | High | High | North America with international ingredient distribution |
| Bunge Global SA | High | High | High | Lecithin operations serving multiple continents |
| Lasenor Emul S.L. | High | High | High | Europe, Asia, Africa and the Americas |
| Sonic Biochem Extractions Pvt. Ltd. | Medium | High | High | India with export-oriented ingredient supply |
| American Lecithin Company | High | High | High | North America with Lipoid Group-linked specialty coverage |
| Wilmar International Limited | Low | Medium | Medium | Asia-centered processing network with international sales |
| Patanjali Foods Limited | Low | High | High | India with established export channels |
| Lipoid GmbH | Medium | Medium | High | German production sites with international distribution |
Scoring basis: High botanical-source breadth requires three documented origins while Medium requires two and Low identifies one. High form breadth requires fluid and dry or modified formats while Medium covers two classes and Low one. High technical specialization requires several documented application groups while Medium covers a narrower range and Low one primary route.
Key Developments in the Lecithin Market
- In March 2026, Bunge Global SA completed its acquisition of IFF’s soy protein concentrate and lecithin businesses together with related soy crush operations. The closing added Solec and expanded Bunge’s botanical and physical-form coverage in commercial lecithin supply.
- In July 2025, Lasenor Emul S.L. launched the RELISER SC range for continuous sliced-cheese lines. The release-agent system uses soy or sunflower lecithin with vegetable oils and extends direct lecithin use into a defined industrial processing application.
Key Players in the Lecithin Market
Integrated Oilseed and Ingredient Platforms
- Cargill, Incorporated
- ADM
- Bunge Global SA
- Wilmar International Limited
- Patanjali Foods Limited
Specialized Food Lecithin and Emulsifier Suppliers
- Lasenor Emul S.L.
- Sonic Biochem Extractions Pvt. Ltd.
- American Lecithin Company
Phospholipid and High-Purity Application Specialists
- Lipoid GmbH
Lecithin Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By product type, source, application and region. |
| Quantitative Units | Revenue in USD billion and CAGR in %. |
| Market Definition | Revenue from lecithin ingredients sold within the stated product type, source and application taxonomy; downstream finished-product revenue and unrelated emulsifier substitutes are excluded. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | USA, UK, South Korea, Japan, Germany, and 20+ countries included in the full report. |
| Key Companies Profiled | Cargill, Incorporated, ADM, Bunge Global SA, Lasenor Emul S.L., Sonic Biochem Extractions Pvt. Ltd., American Lecithin Company, Wilmar International Limited, Patanjali Foods Limited, and Lipoid GmbH. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Lecithin Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Lecithin Market by Segments
Lecithin Market segmented by Product Type:
- Fluid
- De-oiled
- Modified
Lecithin Market segmented by Source:
- Soy
- Sunflower
- Rapeseed
- Egg
- Others
Lecithin Market segmented by Application:
- Food
- Animal Feed
- Nutraceuticals
- Others
- Cosmetics
- Pharmaceuticals
Lecithin Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Chile
- Rest of Latin America
- Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- Middle East and Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
Research Sources and Bibliography
- USA Food and Drug Administration. (2026, July 28). Substances Added to Food (formerly EAFUS): Lecithin.
- ADM. (n.d.). Food & Beverage Lecithin Emulsifiers.
- Cargill, Incorporated. (n.d.). Lecithin.
- Lasenor Emul S.L. (n.d.). High quality Lecithin | Natural emulsifier by Lasenor.
- USA Food and Drug Administration. (2026, April 21). Substances Added to Food (formerly EAFUS): Lecithin, enzyme-modified.
- Lasenor Emul S.L. (2025, Q1). Lecithin News Q1 2025.
- USA Food and Drug Administration. (2026). Food Allergies.
- USA Food and Drug Administration. (2025, January). Guidance for Industry: Questions and Answers Regarding Food Allergen Labeling (Edition 5).
- Food Standards Agency. (2026, June 25). Approved additives and E numbers.
- Food Standards Scotland. (n.d.). Additives and e-numbers.
- Ministry of Food and Drug Safety, Republic of Korea. (2025, November 27).
- Consumer Affairs Agency, Japan. (2025, October 1).
- Bundesamt für Verbraucherschutz und Lebensmittelsicherheit. (2025, March 24–26). Stellungnahme Nr. 2025/01: Entscheidungsbaum „Natürlichkeit von Lebensmittelzusatzstoffen“ der VO (EG) Nr. 1333/2008.
- Bunge Global SA. (2026, March 2). Bunge Completes Acquisition of IFF’s Soy Protein Concentrate, Lecithin, and Crush Business.
- Lipoid GmbH. (2025, August 20). 2025 – New milestone reached at the Cologne site: Logistics, administration, and production areas ready for planned commissioning in 2026.
- Lasenor Emul S.L. (2025, July). Sliced Cheese: Aligning Market Forces with Lasenor’s Technological Edge.
- Bunge Global SA. (n.d.). Germany Legal Statement.
- Patanjali Foods Limited. (n.d.). Food & Speciality.
- Wilmar International Limited. (n.d.). Processing.
- Sonic Biochem Extractions Pvt. Ltd. (n.d.). Products and Applications.
- American Lecithin Company. (n.d.). Lecithins and Phospholipids: More Than Just Emulsifiers.
- Lipoid GmbH. (n.d.). About Us.
- Lasenor Emul S.L. (2025, August). Replacement of DATEM with Lecithin in Bakery Products.
- FoodChain ID Certification Ltd. (2025, March 6). FoodChain ID Non-GMO Global Standard certificate for Bunge Netherlands B.V.
- Lipoid GmbH. (2025, March 24). LIPOID Liposome Basic H: Pre-formulated High-quality Liposomes.
- KF Kosher. (2025, December 21). Kosher certificate for Bunge Iberica SA, Barcelona, Spain.
- STAR-K Kosher Certification. (2026, February 6). American Lecithin Company kosher certificate.
- Patanjali Foods - Specialty Ingredients (Food/Feed/Nutra). (2026, September). Did you know? Behind every batch of our soy lecithin is one of India’s largest integrated soybean processing infrastructures [LinkedIn post].
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the lecithin market in 2026 and 2036?
- Which functional requirements keep lecithin inside repeat commercial formulation purchasing cycles?
- Why does fluid hold 60.1% of product type revenue?
- Why does soy account for 68.3% of source revenue?
- Which requirements can delay switching between botanical lecithin sources during qualification?
- Which companies supply the principal lecithin forms and application categories globally?
- How do source identity and documentation requirements affect repeat supplier qualification?
Frequently Asked Questions
How big is the Lecithin Market in 2026?
The lecithin market is valued at USD 1.5 billion in 2026 and is projected to reach USD 3.0 billion by 2036. Repeat formulation use supports the forecast because emulsification and dispersion remain routine production requirements.
What is the CAGR of the Lecithin Market from 2026 to 2036?
The lecithin market is projected to grow at 7.2% CAGR between 2026 and 2036 during the assessment period. Growth depends on repeat technical use and consistent supplier performance during customer qualification and later reformulation work.
Which product type leads the Lecithin Market in 2026?
The fluid segment is estimated to hold 60.1% of product type revenue in 2026 during the assessment period. Installed tanks and metering systems keep liquid handling practical for high-volume commercial formulations during qualification.
Which source leads the Lecithin Market in 2026?
The soy segment is projected to account for 68.3% of source revenue in 2026 during the assessment period. Familiar specifications support repeat use while allergen declarations and identity records remain important during supplier changes.
Which countries record stronger Lecithin Market growth rates?
The USA lecithin market is projected to grow at 8.6% CAGR from 2026 to 2036. The UK follows at 7.2% with South Korea at 6.9% then Japan at 6.3% and Germany at 5.3% over the same period.
Which companies are active in the Lecithin Market?
Active lecithin companies include Cargill, Incorporated, ADM, Bunge Global SA, Lasenor Emul S.L., Sonic Biochem Extractions Pvt. Ltd., American Lecithin Company, Wilmar International Limited, Patanjali Foods Limited, and Lipoid GmbH. Their roles span oilseed processing plus specialist food lecithins and high-purity phospholipid applications worldwide.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Fluid
- De-oiled
- Modified
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source, 2026 to 2036
- Soy
- Sunflower
- Rapeseed
- Egg
- Others
- Y-o-Y Growth Trend Analysis By Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Source, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Food
- Animal Feed
- Nutraceuticals
- Others
- Cosmetics
- Pharmaceuticals
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Source
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Source
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Product Type
- By Source
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Source
- By Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- By Product Type
- By Source
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Source
- By Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- By Product Type
- By Source
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Source
- By Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Source
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Source
- By Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- By Product Type
- By Source
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Source
- By Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
- By Product Type
- By Source
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Source
- By Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Application
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Application
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Application
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source
- By Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Source
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Cargill, Incorporated
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- ADM
- Bunge Global SA
- Lasenor Emul S.L.
- Sonic Biochem Extractions Pvt. Ltd.
- American Lecithin Company
- Wilmar International Limited
- Patanjali Foods Limited
- Lipoid GmbH
- Cargill, Incorporated
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


