

- Market Size (2026)
- USD 52.6 Bn
- Forecast (2036)
- USD 165.6 Bn
- CAGR (2026 to 2036)
- 12.0%
How big is Plant-based Food Market in 2026?
The plant-based food market is valued at USD 52.6 billion in 2026 and is projected to reach USD 165.6 billion by 2036, growing at a 12.0% CAGR.
The Plant-based Food Market is valued at USD 52.6 Billion in 2026 and is forecast to reach USD 165.6 Billion by 2036 at a 12.0% CAGR. Demand is broadening beyond strict vegetarian diets because many buyers use plant-based products alongside conventional foods. GFI data show that 60% of U.S. households purchased plant-based foods in 2025. The same source found that 96% of households buying plant-based meat also bought animal meat. Suppliers therefore compete for recurring flexitarian occasions rather than a narrow dietary niche. The 2025 base is estimated at USD 47.0 Billion.
Plant-based sales differ sharply by product and channel. Recent US retail data show a large customer base, while foodservice buyers use milk and creamer in ways that do not mirror home purchases of meat alternatives. Japan is organizing food-tech commercialization and Australia is working on local protein ingredients. Awareness can earn a trial; taste, price; nutrition and dependable availability decide whether the product stays on a menu or shopping list.
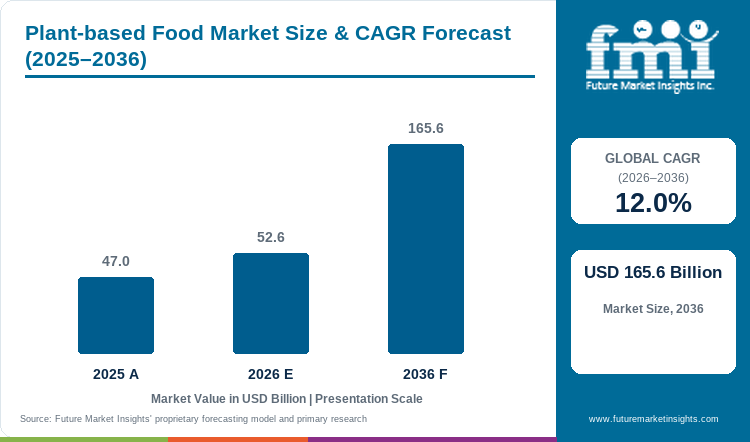
Key Takeaways of Plant-based Food Market
- Demand is anchored in flexitarian and repeat-use occasions. Commercial gains depend on converting trial into regular household and foodservice purchasing.
- Plant-based Meat leads Product Type in 2026 because familiar burgers, sausages, pieces and other meat-like formats fit established meal preparation and menu routines.
- HoReCa leads Sales Channel in 2026 because a single operator listing can create repeated menu exposure and aggregate procurement across many consumer occasions.
- Category momentum is uneven. Current U.S. evidence shows growth in areas such as creamer, yogurt, tofu; tempeh and seitan even while larger plant-based categories face softer retail demand.
- Trial can stall at the second purchase when a price premium is paired with weaker taste or an unclear nutrition benefit.
- Profiled companies include Beyond Meat, Impossible Foods Inc., Danone S.A.; Nestle S.A.; Kellanova; The Kraft Heinz Company; Tyson Foods; Conagra Brands; Amy's Kitchen Inc. and Unilever Group.
Analyst Perspective
The plant-based products most likely to stay on a menu or shelf fit ordinary meals and ordinary budgets. Operators also need predictable preparation and enough repeat orders to justify the space.
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Plant-based Food Market segmented?
The plant-based food market is segmented by Product Type and Sales Channel.
The plant-based food market uses two segment axes that separate the product format from the route to the consumer.
Product type covers plant-based meat, plant-based spreads, margarine, creams & chilled desserts, plant-based creamer, tofu, tempeh & seitan, plant-based yogurt, plant-based meals, plant-based ice-cream & frozen novelty, plant-based protein liquids & powders, plant-based butter, and plant-based cheese.
Sales channel covers HoReCa, QSRs, bakeries & patisseries, hypermarkets/supermarkets, online retail, mass grocery retailers, wholesale stores, specialty stores, convenience stores, and independent retailers.
What makes Plant-based Meat central to the Product Type category?
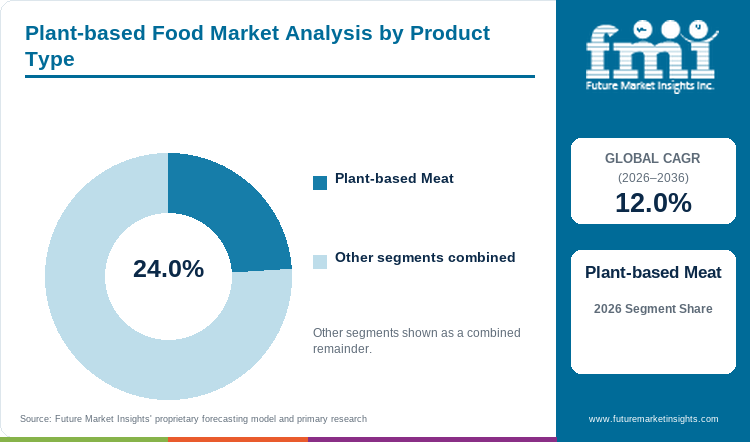
Plant-based Meat occupies a direct substitution role in familiar meals. Products are designed around established cooking cues such as browning, bite and portioning, which lowers the behavior change required from flexitarian buyers. The category also spans both retail and out-of-home menus. Current U.S. shopper data show that almost all plant-based meat-buying households still buy conventional meat so the strongest commercial proposition is an additional meal choice rather than an all-or-nothing switch.
- Plant-based Meat holds a 24.0% share in 2026. Burgers, sausages and pieces enter meal plans consumers already know; brands still need the cooking result to justify a repeat purchase.
- In 2025, GFI reported that U.S. plant-based meat buyers were overwhelmingly also conventional-meat buyers. This indicates that suppliers must win flexitarian occasions on taste, convenience and value rather than rely on dietary identity.
Why does HoReCa lead the Sales Channel category?
HoReCa concentrates purchasing through operators that can put plant-based choices in front of many diners without requiring home preparation. The channel rewards products that fit kitchen workflows, hold quality through service and work within menu economics. It also gives suppliers a route to repeat exposure through restaurants, cafés and institutional dining. These operating requirements make foodservice-specific pack size; cooking performance and distributor availability important commercial levers.
- HoReCa holds a 26.0% share in 2026. A menu listing turns one kitchen decision into repeated orders, provided the product survives service and meets the operator’s cost per serving.
- GFI recorded USD 291 million in US broadline distributor sales of plant-based protein products in 2025. Foodservice milk and creamer are separate purchasing categories. The figure shows an established route to operators; it does not measure the whole plant-based food market or predict a brand's next listing.
What are the drivers, restraints and opportunities in the Plant-based Food Market?
In the plant-based food market, the key driver is the recurring flexitarian occasion created by households and foodservice buyers who alternate plant-based and conventional foods rather than switching entirely, making familiar meat-like formats such as burgers, sausages and pieces the leading product type since they fit established meal preparation and menu routines without requiring behavior change, the key restraint is that a price premium paired with inconsistent taste or an unclear nutrition benefit can stall conversion from trial to repeat purchase, since surveyed buyers in markets like the UK have called plant-based food poor value even after trying it, and the key opportunity is matching specific products and channels to the eating occasions where affordability, localized formulation and convenient formats are already improving purchase frequency, letting suppliers grow repeat volume in categories and geographies rather than relying on one category's trial data to represent the whole market.
- Driver: Flexitarian households and foodservice buyers create recurring occasions for products that fit familiar meals and professional-kitchen workflows.
- Restraint: Price premiums and uneven taste or health perceptions can limit repeat purchase even when consumers are willing to try plant-based products.
- Opportunity: Suppliers can target categories and geographies where better affordability, localized formulations and convenient formats are already improving purchase frequency.
The demand pool includes households that alternate plant-based and conventional foods: GFI found 60% of U.S. households bought plant-based foods in 2025 and most plant-based meat buyers also purchased animal meat. In foodservice, plant-based meat buyers spend more annually at restaurant chains than the average diner according to GFI. That combination matters because suppliers are not restricted to a small vegan population. Products that work in routine breakfasts, coffee occasions; frozen meals and center-of-plate dishes can compete for high-frequency eating occasions across channels.
Trial is easy to win compared with a second purchase. In a January-to-June 2026 UK online sample, GFI Europe found plant-based meat priced 34% above animal meat per kilogram; only 30% of surveyed adults called plant-based food good value. Taste and nutrition also matter. The UK's 2025 SACN/COT assessment found wide variation in plant-drink fortification, so a dairy alternative cannot be assumed nutritionally equivalent to milk. A brand needs to show what the shopper gains for the price.
The better opening is to match product and channel to a specific eating occasion. US data for 2025 show sizeable plant-based retail sales across several categories, and foodservice buyers use milk and creamer differently from households buying meat alternatives. Japan is supporting food-tech commercialization through a public-private council. A supplier should test the price, preparation and repeat-purchase case for each format instead of assuming one category's sales signal applies to the rest.
Which country CAGRs are profiled in the Plant-based Food Market?
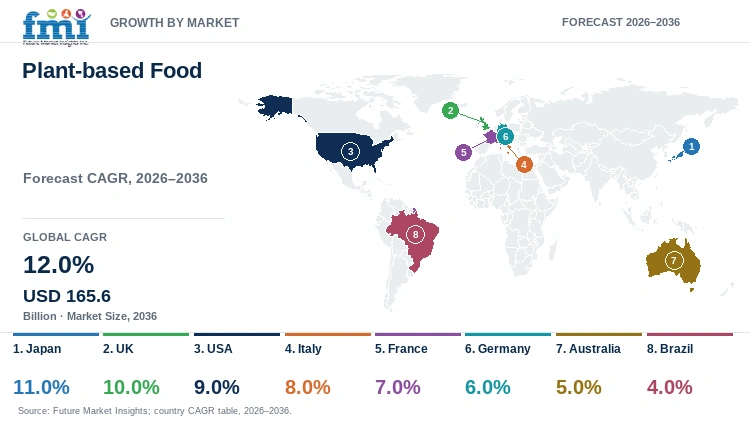
| Country | CAGR |
|---|---|
| Japan | 11.0% |
| UK | 10.0% |
| USA | 9.0% |
| Italy | 8.0% |
| France | 7.0% |
| Germany | 6.0% |
| Australia | 5.0% |
| Brazil | 4.0% |
How do country-level CAGRs compare in the plant-based food market?
The profiled rates span 11.0% in Japan to 4.0% in Brazil, a spread of 7.0 percentage points. Japan, the UK and the USA form the highest-growth band. Italy and France sit in the next tier; followed by Germany; Australia and Brazil. These figures describe forecast growth rates rather than absolute market size. A slower-growing country can still represent a larger revenue base than a faster-growing country.
- Japan: Public-private food-tech activity creates a commercialization framework for new plant-based products and alternative protein businesses.
- UK: High household trial coexists with a measurable price premium, making value improvement central to the forecast.
- USA: Broad household penetration provides a large repeat-purchase pool, but recent retail softness shifts attention toward product quality and foodservice execution.
- Italy: Rising retail volume across tracked plant-based categories shows that improving affordability can broaden demand in a mature food culture.
- France: Retail growth and vegetarian-menu requirements in collective catering create both consumer and institutional routes to plant-based choices.
- Germany: A comparatively developed retail base is still expanding in volume, which raises the importance of quality and category-specific innovation.
- Australia: Labeling work and public support for local plant-protein development can reduce information and supply barriers over time.
- Brazil: Consumer curiosity is evident, but price and product availability remain material barriers to frequent purchasing.
Country CAGRs vary with market maturity, channel mix and purchasing barriers.
Country-wise Analysis
- Japan has the fastest profiled rate at 11.0% CAGR from 2026 to 2036. The country benefits from an organized commercialization ecosystem rather than from a single demand signal. Japan's Ministry of Agriculture, Forestry and Fisheries serves as secretariat for a public-private Foodtech Council that explicitly includes a Plant-Based Food promotion working group. The council also lists plant-based food under alternative protein sources and held its first fiscal-2026 general meeting in June 2026. This infrastructure can connect food manufacturers, retailers; restaurants and researchers. Suppliers still need Japanese taste fit and dependable foodservice performance before technical novelty converts into routine purchasing.
- The UK is profiled at 10.0% CAGR from 2026 to 2036, despite a mixed near-term retail backdrop. GFI Europe reported that 31.2% of UK households bought plant-based meat at least once in 2025. However, its January-to-June 2026 online sample found plant-based meat priced 34% higher per kilogram than animal meat on average. Only 30% of surveyed adults saw plant-based foods as good value. The country therefore offers a broad installed base of trial but repeat volume remains sensitive to taste and affordability. Suppliers that improve value without weakening product quality are better placed to reactivate frequency.
- The USA carries a 9.0% CAGR from 2026 to 2036. GFI reported USD 7.9 billion of US plant-based retail sales in 2025 and said 60% of households bought a plant-based food. That broad reach does not mean every product is thriving. Milk, creamer, meat alternatives and prepared foods face different price and taste tests. A brand has to identify the occasion it can win and then show repeat purchases in that aisle or menu channel.
- Italy is profiled at 8.0% CAGR from 2026 to 2036. GFI Europe's five-category retail set reached EUR 669 million in 2025. A brand still has to earn a place in familiar Italian meals. Flavor, clear labeling and a usable pack price matter together; a low price will not rescue a product that people do not want to cook again.
- France is profiled at 7.0% CAGR from 2026 to 2036. GFI Europe recorded EUR 572 million of 2025 sales across five plant-based retail categories. Collective-catering rules also put vegetarian meals on school menus and in certain state restaurants. Retail and institutional kitchens therefore present distinct briefs: a supermarket shopper judges taste and price, while a caterer also needs repeatable preparation at scale. Suppliers need products designed for the channel they hope to enter.
- Germany carries a 6.0% CAGR from 2026 to 2036. GFI Europe recorded EUR 1.71 billion in 2025 sales across six tracked plant-based categories. Availability is broad enough that a new product must do more than claim plant-based credentials. The buyer will compare price, taste, nutrition and how the item cooks. Mature distribution gives brands reach but it also makes weak repeat sales visible quickly.
- Australia carries a 5.0% CAGR in the 2026 to 2036 profile. In January 2025, the Department of Industry announced AUD 2.2 million for Harvest B to develop a gluten-free faba-bean protein for meat alternatives. The work addresses a local ingredient and manufacturing challenge. It does not guarantee consumer demand. Producers still need recognizable meal uses, acceptable texture and a price that can survive ordinary grocery comparison.
- Brazil is profiled at 4.0% CAGR from 2026 to 2036. Recent GFI Brasil material says 61% of consumers searched for plant-based alternatives during the previous six months, yet only 8% found everything they wanted. It also identifies high prices as a barrier to frequent buying. That is a distribution and value problem as much as an awareness problem. Brands need to be visible in the stores people already use and give them a reason to return after an initial trial.
Who are the notable companies in the Plant-based Food Market?
Beyond Meat, Impossible Foods Inc., Danone S.A.; Nestle S.A.; Kellanova (Mars Snacking); The Kraft Heinz Company; Tyson Foods; Conagra Brands; Amy's Kitchen Inc. and Unilever Group are the notable companies profiled in this market.
Competitors reach the shopper through very different products. Beyond Meat and Impossible Foods concentrate on meat-like formats. Danone and Nestle cover wider plant-based portfolios, while Conagra and Amy's Kitchen use prepared meals. Kraft Heinz works with NotCo. Kellanova owns MorningStar Farms and Unilever's 2025 sale of The Vegetarian Butcher narrowed its direct role. Comparing these companies only by brand reach misses the practical differences in cooking use, merchandising and distribution.
- Plant-based meat specialists and established meat-alternative brands: Beyond Meat; Impossible Foods Inc.; Kellanova; Tyson Foods; and Conagra Brands
- Diversified plant-based food platforms and portfolio-transition participants: Danone S.A.; Nestle S.A.; The Kraft Heinz Company; and Unilever Group.
- Prepared plant-based meals and organic convenience foods: Amy's Kitchen Inc.
Competitive Benchmarking: Plant-based Food Market
| Company | Plant-based Category Breadth | Retail Route-to-Market | Foodservice Route-to-Market | Geographic Reach |
|---|---|---|---|---|
| Beyond Meat, Inc. | High | High | High | United States; additional international activity documented in company materials |
| Impossible Foods Inc. | High | High | Medium | United States and selected markets across Europe, Asia-Pacific and the Middle East |
| Danone S.A. | High | High | Medium | Europe and other international markets through Alpro; 30+ countries documented |
| Nestle S.A. | High | High | High | United States, Latin America, Europe; China and Southeast Asia |
| Kellanova (Mars Snacking) | High | High | Medium | United States; MorningStar Farms is part of its current portfolio. |
| The Kraft Heinz Company | Medium | High | Medium | United States and Canada; selected out-of-home activation documented |
| Tyson Foods, Inc. | Medium | Medium | Medium | Documented availability varies by brand and product; no consolidated footprint is stated here. |
| Conagra Brands, Inc. | High | High | Low | North America; current Gardein and Purple Carrot retail capability documented |
| Amy's Kitchen Inc. | Medium | Medium | Low | United States; current public detail on plant-based international reach is limited |
| Unilever Group | Medium | Medium | Medium | Global foods group; its direct plant-based meat role narrowed after the 2025 sale of The Vegetarian Butcher. |
Key Developments in the Plant-based Food Market
- In June 2026, Beyond Meat, Inc. launched Beyond Steak Filet at Wegmans and H-E-B; marking the product's first retail availability after a direct-to-consumer launch. The whole-cut format uses mycelium and avocado oil and provides 28 grams of plant protein per serving. The move tests whether premium whole-cut alternatives can earn incremental center-of-plate demand in mainstream grocery.
- In March 2025, Impossible Foods Inc. introduced Impossible Steak Bites, its first steak-format product. The pre-cooked product began rolling into grocery stores nationwide with restaurant availability planned. The launch broadened the company beyond burgers; chicken and other ground or formed formats; increasing the number of familiar meal occasions in which its plant-based proteins can compete.
- In June 2025, Conagra introduced new Gardein formats including plant-based steak tips, sausage crumbles and a single-serve Fried Chick'n Mac & Cheeze Bowl. The mix of cooking ingredients and a ready meal gives shoppers different ways into the category. For the retailer; the question is whether each format earns repeat freezer-space sales; rather than whether a plant-based label attracts a first purchase.
Key Players in the Plant-based Food Market
Plant-based Meat Specialists and Established Alternative-Meat Brands
- Beyond Meat, Inc.
- Impossible Foods Inc.
- Kellanova (Mars Snacking)
- Tyson Foods, Inc.
- Conagra Brands, Inc.
Diversified Plant-based Food Platforms and Portfolio-Transition Participants
- Danone S.A.
- Nestle S.A.
- The Kraft Heinz Company
- Unilever Group
Organic and Plant-forward Prepared Foods
- Amy's Kitchen Inc.
Plant-based Food Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Sales Channel |
| Quantitative Units | USD Billion |
| Market Definition | Revenue from plant-based food products sold within the listed Product Type and Sales Channel taxonomy. Included packaged plant-based meals are counted as products. Downstream restaurant or prepared-dish revenue beyond the value of the plant-based product supplied into the channel is excluded, as are adjacent substitute categories outside the listed taxonomy. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA; Germany; UK; Brazil; France; Japan; Australia; Italy |
| Key Companies Profiled | Beyond Meat, Inc.; Impossible Foods Inc.; Danone S.A.; Nestle S.A.; Kellanova; The Kraft Heinz Company; Tyson Foods, Inc.; Conagra Brands, Inc.; Amy's Kitchen Inc.; Unilever Group |
| Forecast Period | 2026 to 2036 |
| Approach | Tracked retail categories and current product evidence used to interpret FMI estimates. |
Plant-based Food Market - Research Methodology
| Method | Approach |
|---|---|
| Market Scope | The category combines meat alternatives, dairy alternatives and prepared foods. Each has a different cooking use, shelf position and route to the customer. |
| Public Evidence | The review uses 2025 retail findings, government innovation releases and current company announcements. A tracked-category retail total is identified by its coverage rather than treated as all plant-based food. |
| Forecast Interpretation | FMI market values and 2026-2036 country CAGRs remain forecast figures. Household reach and sales in a subset of products are contextual measures, not a derivation of the forecast. |
| Source Checks | Ownership, launch and distribution statements were checked against recent company material. A product available in one country is not assumed to be available across a group footprint. |
Plant-based Food Market by Segments
Plant-based Food Market segmented by Product Type
- Plant-based Meat
- Plant-based Spreads, Margarine, Creams & Chilled Desserts
- Plant-based Creamer
- Tofu, Tempeh & Seitan
- Plant-based Yogurt
- Plant-based Meals
- Plant-based Ice-cream & Frozen Novelty
- Plant-based Protein Liquids & Powders
- Plant-based Butter
- Plant-based Cheese
Plant-based Food Market segmented by Sales Channel
- HoReCa
- QSRs
- Bakeries & Patisseries
- Hypermarkets / Supermarkets
- Online Retail
- Mass Grocery Retailers
- Wholesale Stores
- Specialty Stores
- Convenience Stores
- Independent Retailers
Plant-based Food Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- The Good Food Institute (n.d.). U.S. retail market insights for the plant-based industry.
- The Good Food Institute (n.d.). U.S. foodservice market insights for plant-based foods.
- GFI Europe (2026, June 9). Europe’s plant-based food retail market grows as prices become more competitive, but good taste remains key.
- GFI Europe (2026, June 9). Germany remains Europe’s leading market for plant-based foods with 3.1 % growth in sales value.
- GFI Europe (2026, June 9). Retail sales of plant-based alternatives have risen by 21% over the past two years in France.
- GFI Europe (2026, June 9). Italy’s retail plant-based market reaches €669 million.
- GFI Europe (2026, August 26). Plant-based meat and its role in the UK’s food system.
- GFI Brasil (n.d.). Estudos de Consumidor.
- Australian Government Department of Agriculture, Fisheries and Forestry (n.d.). Plant-based alternative product labelling.
- Australian Government Department of Industry, Science and Resources (2025, January 9). Innovative crop harvester; faba bean and firefighting robot projects get IGP grants.
- Ministry of Agriculture, Forestry and Fisheries of Japan (n.d.). Council for Public-Private Partnership in Food Technology.
- Ministry of Agriculture, Forestry and Fisheries of Japan (n.d.). Affiliated Organizations of Members.
- Beyond Meat, Inc. (2026, June 29). Beyond Meat® Launches Beyond Steak® Filet at Wegmans and H-E-B.
- Impossible Foods Inc. (2025, March 5). Impossible Foods Introduces Impossible® Steak Bites - Its Meatiest Plant-Based Innovation.
- Conagra Brands, Inc. (n.d.). Offering Solutions for Individual Nutrition Goals.
- Unilever Group (2025, March 20). Unilever to sell The Vegetarian Butcher to Vivera [binding agreement announced; completion expected Q3 2025].
- Houlihan Lokey (n.d.). Vivera - JBS - The Vegetarian Butcher - Unilever | Transaction Details.
- Nestle S.A. (2025, March 10). Nestlé R&D to strengthen local capabilities in key innovation areas in Singapore.
- Nestle S.A. (n.d.). Discover our plant-based products.
- Nestle S.A. (n.d.). Discover our food service brands - Garden Gourmet.
- Danone S.A. (n.d.). The Alpro range of plant-based products.
- Amy's Kitchen Inc. (n.d.). Our Foods - Plant Based.
- UK Scientific Advisory Committee on Nutrition and Committee on Toxicity (2025, July 16). Assessment of the health benefits and risks of consuming plant-based drinks: summary.
- Conagra Brands, June 2025 frozen-food product introductions
This Report Answers
- How large is the Plant-based Food Market in 2026, and what value is forecast for 2036?
- Which industry pressures are supporting demand for plant-based food across retail and foodservice?
- Why does Plant-based Meat hold the leading position within Product Type?
- Why does HoReCa hold the leading position within Sales Channel?
- How do growth rates differ across the profiled countries from 2026 to 2036?
- Which profiled companies supply relevant plant-based product and channel categories?
- What limits adoption, repeat purchase or supplier switching in plant-based food?
- What should buyers evaluate before purchasing or listing plant-based food products?
Frequently Asked Questions
How big is the Plant-based Food Market in 2026, and what is forecast for 2036?
The market is valued at USD 52.6 Billion in 2026 and is forecast to reach USD 165.6 Billion by 2036. The expansion depends on higher repeat use across multiple plant-based categories and sales channels.
What is the CAGR for the Plant-based Food Market from 2026 to 2036?
The market is forecast to grow at a 12.0% CAGR from 2026 to 2036. This rate reflects the expected scaling of both established and emerging plant-based food categories.
Which Product Type segment leads the Plant-based Food Market?
Plant-based Meat leads Product Type in 2026. Its familiar formats let consumers and foodservice operators substitute within established meal routines.
Which Sales Channel segment leads the Plant-based Food Market?
HoReCa leads Sales Channel in 2026. Operator purchasing can create repeated menu exposure and aggregate demand across many dining occasions.
Which profiled countries have the highest growth rates in the Plant-based Food Market?
Japan has the highest profiled CAGR at 11.0%, followed by the UK at 10.0% and the USA at 9.0% from 2026 to 2036. These are growth rates and do not indicate each country's absolute market size.
Which companies are active in the Plant-based Food Market?
Profiled companies are Beyond Meat, Impossible Foods Inc., Danone S.A.; Nestle S.A.; Kellanova; The Kraft Heinz Company; Tyson Foods; Conagra Brands; Amy's Kitchen Inc. and Unilever Group. Their roles differ by product breadth; channel model and current portfolio status.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Plant-based Meat
- Plant-based Spreads, Margarine, Creams & Chilled Desserts
- Plant-based Creamer
- Tofu, Tempeh & Seitan
- Plant-based Yogurt
- Plant-based Meals
- Plant-based Ice-cream & Frozen Novelty
- Plant-based Protein Liquids & Powders
- Plant-based Butter
- Plant-based Cheese
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- HoReCa
- QSRs
- Bakeries & Patisseries
- Hypermarkets / Supermarkets
- Online Retail
- Mass Grocery Retailers
- Wholesale Stores
- Specialty Stores
- Convenience Stores
- Independent Retailers
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Beyond Meat, Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Impossible Foods Inc.
- Danone S.A.
- Nestle S.A.
- Kellanova
- The Kraft Heinz Company
- Tyson Foods, Inc.
- Conagra Brands, Inc.
- Amy's Kitchen Inc.
- Unilever Group
- Beyond Meat, Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


