

- Market Size (2026)
- USD 150.7 Mn
- Forecast (2036)
- USD 237.2 Mn
- CAGR (2026 to 2036)
- 4.6%
How big is Lentil Protein Market in 2026?
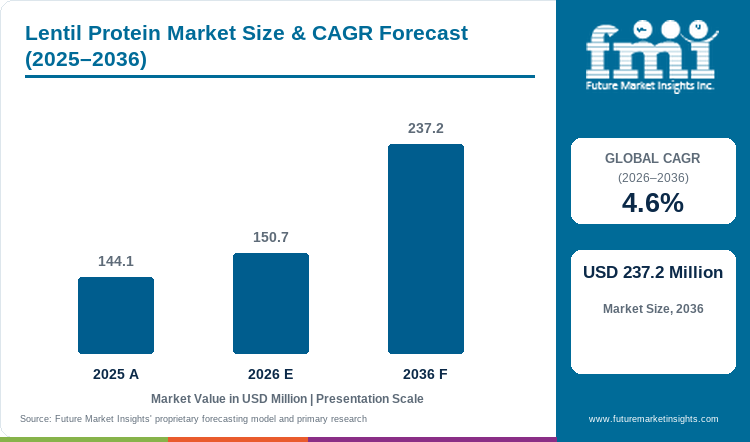
USD 150.7 Million in 2026 and USD 237.2 Million by 2036 at a 4.6% CAGR.
Sales of lentil protein are estimated to grow at 4.6% from USD 150.7 Million in 2026 to USD 237.2 Million by 2036. The market was valued at USD 144.1 Million in 2025. Food manufacturers are using lentil-derived proteins where they can raise protein content while contributing binding, emulsification or egg-replacement functionality. Commercial adoption still depends on whether the ingredient performs consistently without creating unacceptable flavor, texture or processing penalties.
The growth mechanism differs by country. Canada provides a large lentil crop base, while the United States combines North American crop access with food-ingredient processing infrastructure. The UK and South Korea show stronger commercialization signals around alternative proteins and food technology. Lentil protein also competes within the wider plant-based protein market and protein ingredients market, so suppliers need a clearer functional or sourcing advantage than plant origin alone.
Key Takeaways of Lentil Protein Market
- Food processors are the main demand engine because lentil protein can combine protein enrichment with binding, emulsification and texture-management functions.
- Protein Isolates lead Product Type with a 47.4% share in 2026 because higher protein density gives formulators more room to reach nutrition targets without adding excessive solids.
- Conventional products hold 95.3% of Nature demand in 2026, supported by broader raw-material availability and simpler large-volume sourcing.
- Food Processing represents 68.2% of End Use, with applications spanning bakery, pasta, snacks, sauces, beverages and plant-based foods.
- Flavor consistency, processing performance, food-safety requirements and delivered cost remain important barriers to supplier qualification.
- Notable market participants include AGT Food and Ingredients, Ingredion Incorporated, Roquette Frères, Vestkorn Milling, PURIS, Avena Foods, Anchor Ingredients, The Scoular Company, Parrish & Heimbecker and Diefenbaker Spice & Pulse.
Analyst Perspective
Repeat revenue depends on whether lentil protein can solve a formulation problem at the required inclusion level without adding sensory or manufacturing complexity. The strongest suppliers will combine reliable crop access with protein fractionation, application support and consistent specifications across commercial production runs.
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Lentil Protein Market segmented?
The market is segmented by Product Type, Nature, End Use and Processing Type.
By product type, it includes protein isolates, protein concentrates, flour, and other product types. By nature, it covers conventional and organic. By end use, it comprises food processing, sports nutrition, nutraceuticals, infant nutrition, and animal feed. By processing type, it includes dry processing and wet processing.
Why do protein isolates lead demand within the product type category?
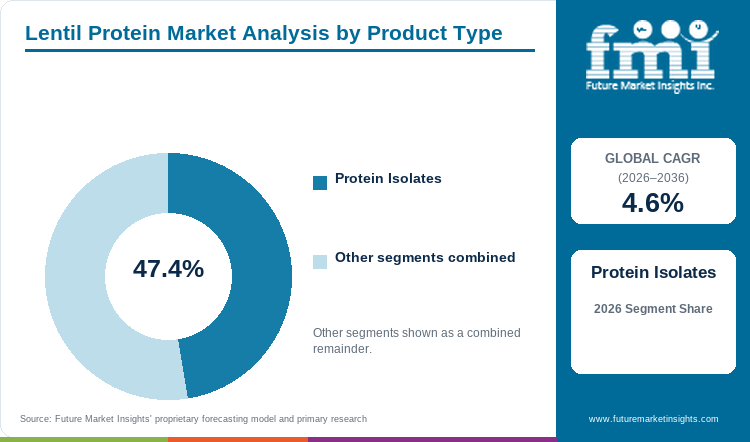
Protein Isolates lead because concentrated protein enables formulators to reach nutrition targets with less ingredient mass than lower-protein fractions. This becomes important in beverages, nutrition formats and dense food systems where extra flour or concentrate can change viscosity, flavor or carbohydrate load. AGT's current PulsePlus range includes lentil protein concentrate and isolate grades, showing how suppliers position different protein concentrations against distinct formulation needs. Similar purchasing logic is visible across the wider pea protein market.
- Protein Isolates represent 47.4% of Product Type demand in 2026, reflecting the value of higher protein density in concentrated nutrition formulations.
- Greater protein density gives formulators additional flexibility when finished products carry demanding protein targets or limited capacity for added solids.
Why does conventional lead demand within the nature category?
Conventional lentil protein draws from a wider crop pool without the additional segregation and certification steps required for organic supply. That matters for large food-processing runs where continuity and cost consistency can outweigh premium sourcing claims. Organic lentil protein remains commercially relevant for certified finished products, but each stage of sourcing and processing has to preserve organic status.
- Conventional products account for 95.3% of Nature demand in 2026, reflecting their broad availability across mainstream food-ingredient applications.
- In July 2025, Avena Foods launched a regenerative agriculture protocol covering oat and pulse ingredients, illustrating how traceability and differentiated sourcing are developing alongside the larger conventional supply base.
Why does food processing lead demand within the end use category?
Food Processing offers the widest range of commercial applications because lentil protein can contribute both nutrition and process functionality. Pasta, bakery products, snacks, sauces, dairy alternatives, meat alternatives and protein beverages can use lentil protein differently, which expands the addressable customer base beyond sports or clinical nutrition. Suppliers still need to match flavor, hydration and texture behavior to each finished product rather than sell protein concentration as a stand-alone attribute.
- Food Processing captures 68.2% of End Use demand in 2026, reflecting the broad application range for lentil protein across mainstream food categories.
- In March 2025, AGT described investment in its Minot, North Dakota food-ingredients manufacturing operations for U.S.-focused business, highlighting the connection between pulse ingredients and scalable food-processing applications.
Why does dry processing lead demand within the processing type category?
Dry Processing uses mechanical size reduction and separation to produce protein-rich fractions without the extended water-handling sequence associated with wet isolation. The route suits processors seeking useful protein concentrates alongside starch-rich and fiber-rich fractions. Wet processing reaches different purity and functional targets, though the additional separation, water management and drying requirements introduce greater process complexity.
- Dry Processing comprises 66.4% of Processing Type demand in 2026, reflecting its suitability for producing protein-rich fractions with fewer water-intensive processing stages.
- Dry fractionation produces commercially useful protein-rich streams while retaining additional lentil components that processors may direct toward starch, fiber, or other food applications.
What are the drivers, restraints and opportunities in the Lentil Protein Market?
Food manufacturers are widening demand for functional plant proteins, while flavor and processing economics restrain substitution and integrated fractionation creates an opportunity to capture more value from each lentil stream.
- Driver: Food processors need protein ingredients that raise nutritional value while contributing usable binding, emulsification or texture performance.
- Restraint: Commercial adoption slows when flavor, protein yield, process safety or co-product economics weaken the cost case against established protein systems.
- Opportunity: Integrated processors can improve economics by matching different lentil fractions to food, nutrition and ingredient applications.
Food manufacturers continue to evaluate a broader set of protein sources for meat alternatives, snacks, bakery products, nutrition formats and dairy alternatives. The UK Government Chemist reported in June 2025 that interest in the development and commercialization of alternative dietary proteins was increasing. Lentil protein benefits when it contributes functionality as well as protein content. The same buying logic shapes the wider alternative protein market, where taste, processing behavior and delivered economics determine whether a new protein source moves beyond a trial.
Processing economics remain a central restraint. Suppliers need to produce a protein fraction with suitable purity and functionality while creating viable outlets for starch, fiber and lower-protein co-products. Food-safety treatment can add another qualification step, particularly when mechanically processed pulse ingredients require additional downstream processing. A technically suitable ingredient therefore needs to work within the customer's full production economics rather than simply meet a laboratory protein specification.
The strongest opportunity is to build more value around the whole lentil. Statistics Canada reported record lentil production of 3.4 million tonnes in 2025, giving processors a large crop base close to established handling infrastructure. Protein, starch, flour and fiber streams can serve different customers and improve plant utilization when each has a dependable outlet. This creates useful overlap with the ingredients market for plant-based food and beverages, where food manufacturers increasingly buy ingredients for both nutritional and functional performance.
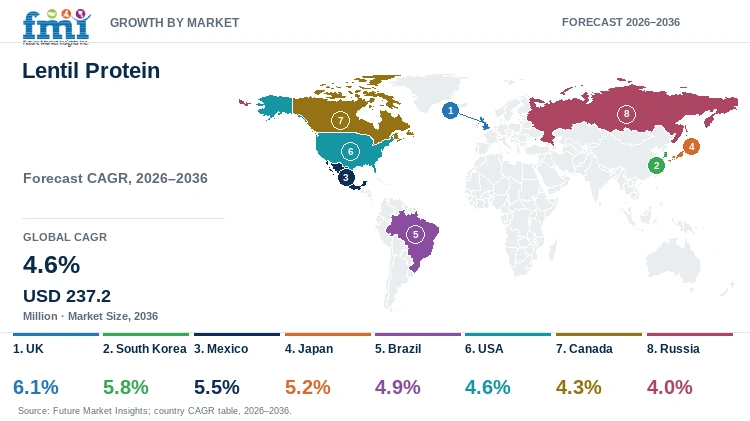
Which country CAGRs are profiled in the Lentil Protein Market?
| Country | CAGR |
|---|---|
| UK | 6.1% |
| South Korea | 5.8% |
| Mexico | 5.5% |
| Japan | 5.2% |
| Brazil | 4.9% |
| USA | 4.6% |
| Canada | 4.3% |
| Russia | 4.0% |
How do country-level CAGRs compare in the Lentil Protein Market?
The profiled growth rates form a relatively narrow range. The UK and South Korea occupy the upper end, followed by Mexico and Japan. Brazil and the USA sit close to the global forecast rate, while Canada and Russia expand more gradually. The difference between the UK at 6.1% and Russia at 4.0% is 2.1 percentage points. These rates compare growth pace and do not indicate absolute country market size.
- UK: Alternative-protein development and nutrition scrutiny keep product quality, fortification and functional performance in the buyer conversation.
- South Korea: Food-tech policy provides plant-based alternatives with a more defined innovation and commercialization framework.
- Mexico: Domestic lentil production and public food-distribution initiatives support crop familiarity and wider consideration of value-added lentil applications.
- Japan: Food-tech demonstration programs support commercial testing of emerging ingredient and alternative-protein technologies.
- Brazil: Alternative-protein research activity broadens the food-technology ecosystem and exposes formulators to a wider range of protein systems.
- USA: Access to North American lentil supply and domestic food-ingredient processing supports shorter procurement routes for some customers.
- Canada: Large lentil production provides a strong raw-material base for greater domestic value addition.
- Russia: A substantial pulse-trading system provides crop availability, while protein fractionation requires a separate value-added processing proposition.
Country-wise Analysis
- The UK is profiled at a 6.1% CAGR from 2026 to 2036. In June 2025, the Government Chemist reported increasing UK interest in the development and commercialization of alternative dietary proteins. A government assessment published in July 2025 also examined plant-based drinks and their nutritional role. For lentil protein suppliers, this creates a market where protein quality, flavor, fortification compatibility and processing performance are likely to receive close scrutiny before a new ingredient becomes part of a repeat formulation.
- South Korea carries a 5.8% CAGR over 2026 to 2036. In July 2026, the Ministry of Agriculture, Food and Rural Affairs announced the country's first statutory master plan under the Food Tech Industry Promotion Act. Plant-based meat alternatives sit within that broader food-tech framework, alongside additional research and commercialization infrastructure. Lentil protein suppliers can participate where they provide technical support suited to local food processes rather than relying on a generic plant-protein proposition.
- Mexico is forecast to grow at a 5.5% CAGR from 2026 to 2036. In November 2025, the Agriculture Ministry reported that 8,114 tonnes of lentils had been harvested in 2024 and outlined plans to purchase lentils from 2026 for distribution through Tiendas Bienestar. The commercial opportunity for lentil protein sits further downstream. Processors need food-grade conversion capacity and customers willing to pay for concentrated protein functionality instead of purchasing lentils only as whole pulses.
- Japan is profiled at a 5.2% CAGR. In April 2026, the Ministry of Agriculture, Forestry and Fisheries opened a food-tech business demonstration and implementation program for domestic food companies and research organizations. The country's food-tech framework supports experimentation with alternative protein sources and new food formats. Lentil protein suppliers still need to compete on taste, solubility, texture and processing reliability against better-established soy and pea systems.
- Brazil records a 4.9% CAGR from 2026 to 2036. In June 2025, Fundação Araucária and GFI Brasil launched a R$2 million alternative-protein research program in Paraná. The initiative broadens the country's food-technology ecosystem even though its focus extends beyond pulse proteins. Lentil protein therefore competes for formulation attention alongside several protein technologies. Commercial traction is strongest where suppliers can solve a specific processing problem at a viable delivered cost.
- The USA is profiled at a 4.6% CAGR from 2026 to 2036. USDA Economic Research Service reported in July 2025 that U.S. lentil exports from July 2024 through May 2025 were 32% above the comparable prior period. The country also has food-ingredient processing infrastructure connected to Canadian and domestic pulse supply. Regional manufacturing and inventory can reduce freight and replenishment exposure for food processors, but suppliers still need repeatable specifications and appropriate safety controls.
- Canada is projected to grow at a 4.3% CAGR from 2026 to 2036. Statistics Canada reported record lentil production of 3.4 million tonnes in 2025, with Saskatchewan accounting for most output. In June 2026, seeded lentil area was reported at 3.9 million acres, 10.9% below the previous year. The combination of large crop availability and seasonal variation makes Canada important to both raw-material sourcing and future ingredient-processing investment. Greater value capture depends on conversion capacity, co-product outlets and stable demand from food manufacturers.
- Russia has the lowest profiled CAGR at 4.0% from 2026 to 2036. In February 2025, the FAO Liaison Office reported that the Global Grain and Pulses Forum discussed Russian pulse-market development, trade corridors and export opportunities. A large commodity channel does not automatically translate into protein-ingredient revenue because milling and fractionation add another stage of capital, technical control and customer qualification. Growth therefore depends on processors finding food customers that value the functional benefits of higher-value lentil ingredients.
Who are the notable companies in the Lentil Protein Market?
AGT Food and Ingredients, Ingredion Incorporated, Roquette Frères, Vestkorn Milling, PURIS, Avena Foods, Anchor Ingredients, Parrish & Heimbecker, The Scoular Company and Diefenbaker Spice & Pulse are among the notable companies and pulse-ingredient participants profiled in the market.
AGT Food and Ingredients and Ingredion Incorporated have the strongest direct lentil-protein positioning within the profiled group. AGT markets lentil protein concentrates and isolates as part of its PulsePlus range, while Ingredion's VITESSENCE portfolio includes lentil protein for food applications. Their positioning brings protein concentration, functionality and application performance into the same customer discussion.
The wider competitive environment includes plant-protein processors and pulse specialists. Roquette Frères, Vestkorn Milling and PURIS strengthen substitution pressure through broader plant-protein portfolios. Avena Foods, Anchor Ingredients, Parrish & Heimbecker, The Scoular Company and Diefenbaker Spice & Pulse contribute pulse sourcing, milling, processing, traceability or distribution capabilities that can influence where lentils move into higher-value ingredient channels.
Competitive Benchmarking: Lentil Protein Market
| Company | Lentil Protein Portfolio | Lentil Processing Integration | Lentil Application Capability | Geographic Reach |
|---|---|---|---|---|
| AGT Food and Ingredients | High | High | High | Canada, United States and export markets |
| Ingredion Incorporated | High | High | High | North America with broader international technical channels |
| Roquette Frères | Low | Low | Low | Europe and North America with global food channels |
| Vestkorn Milling | Low | Low | Low | Norway and wider European plant-protein channels |
| PURIS | Low | Low | Low | United States and wider North American food channels |
| Avena Foods | Low | Low | Low | Canadian Prairies and international pulse customers |
| Anchor Ingredients | Low | Low | Low | United States and North American ingredient distribution |
| Parrish & Heimbecker | Low | Low | Low | Canada and North American pulse-processing channels |
| The Scoular Company | Low | Low | Low | North America with broader international ingredient channels |
| Diefenbaker Spice & Pulse | Low | Low | Low | Saskatchewan and export-oriented pulse channels |
Key Developments in the Lentil Protein Market
- In July 2024, AGT Food and Ingredients opened its new Extrusion Center of Excellence in Minot, North Dakota, a multi-million-dollar facility for producing gluten-free pasta and plant-based pulse ingredients. The center reinforces the connection between North American pulse origination, ingredient manufacturing and downstream food-processing customers.
- In June 2025, Roquette Frères launched new textured wheat and pea protein ingredients for plant-based food applications. The products broaden the substitution set available to food manufacturers and raise the performance benchmark that lentil protein suppliers face when competing for meat-alternative and formulated-food applications.
- In July 2025, Avena Foods launched its regenerative agriculture protocol for oat and pulse ingredients. The program adds traceability from agricultural production into the ingredient supply chain and shows how pulse suppliers are using sourcing information to differentiate value-added products.
Key Players in the Lentil Protein Market
Direct lentil protein and formulation specialists
- AGT Food and Ingredients
- Ingredion Incorporated
Broader plant-protein and pulse-processing platforms
- Roquette Frères
- Vestkorn Milling
- PURIS
- Parrish & Heimbecker
Pulse sourcing, milling and ingredient-channel specialists
- Avena Foods
- Anchor Ingredients
- The Scoular Company
- Diefenbaker Spice & Pulse
Lentil Protein Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Nature; End Use; Processing Type |
| Quantitative Units | Revenue in USD Million and CAGR in %. |
| Market Definition | Revenue from lentil protein sold as Protein Isolates, Protein Concentrates, Flour and Other Product Types across the stated Nature, End Use and Processing Type segmentation. Downstream finished-product revenue and substitute protein revenue are excluded. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Russia; Canada; USA; Brazil; Japan; Mexico; South Korea; UK |
| Key Companies Profiled | AGT Food and Ingredients; Ingredion Incorporated; Roquette Frères; Vestkorn Milling; PURIS; Avena Foods; Anchor Ingredients; Parrish & Heimbecker; The Scoular Company; Diefenbaker Spice & Pulse |
| Forecast Period | 2026 to 2036 |
| Base Year | 2025 |
| Approach | Primary and secondary research with market triangulation |
Lentil Protein Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gather input from ingredient manufacturers, pulse processors, distributors, food manufacturers, procurement teams and technical specialists. Interviews examine purchasing requirements, application performance, qualification barriers and commercial support needs. |
| Desk Research | Research covers government statistics, agricultural publications, trade information, technical literature, standards, company filings, product information and official corporate announcements. |
| Market Sizing and Forecasting | Market sizing combines the baseline value with segment structure, pricing and volume indicators, ingredient adoption, company activity and country-level demand conditions. Forecast assumptions incorporate processing investment, food-industry demand, supply availability and barriers to wider use. |
| Data Validation | Estimates are compared across independent demand, supply, trade and company indicators before segment and regional totals are finalized. |
Lentil Protein Market by Segments
Lentil Protein Market segmented by Product Type:
- Protein Isolates
- Protein Concentrates
- Flour
- Other Product Types
Lentil Protein Market segmented by Nature:
- Conventional
- Organic
Lentil Protein Market segmented by End Use:
- Food Processing
- Sports Nutrition
- Nutraceuticals
- Infant Nutrition
- Animal Feed
Lentil Protein Market segmented by Processing Type:
- Dry Processing
- Wet Processing
Lentil Protein Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- Statistics Canada (2026, February 4). Canada's multi-billion-dollar bean business.
- Statistics Canada (2026, June 30). Principal field crop areas, June 2026.
- U.S. Department of Agriculture, Economic Research Service (2025, July 31). Vegetables and Pulses Outlook: July 2025.
- Secretaría de Agricultura y Desarrollo Rural, Mexico (2025, November 30). Las lentejas “vienen con todo” en el Plan Michoacán.
- Ministry of Agriculture, Forestry and Fisheries, Japan (2026, April 7). Food-tech Business Demonstration and Implementation Project.
- Ministry of Agriculture, Food and Rural Affairs, Republic of Korea (2026, July 20). S. Korea Unveils Master Plan to Integrate Advanced Technologies into the Food Sector.
- Ministry of Agriculture, Food and Rural Affairs, Republic of Korea (2025, July 16). The AFPRO 2025: Innovative Technologies of Ag-tech and Food-tech Startups Grab Special Attention from the Industry.
- Fundação Araucária (2025, June 6). Programa de Pesquisa em Proteínas Alternativas terá investimentos de R$ 2 milhões.
- Government Chemist, United Kingdom (2025, June 16). Quantitative review of sustainable novel food production.
- Office for Health Improvement and Disparities, United Kingdom (2025, July 16). Plant-based drinks: health benefits and risks.
- Food and Agriculture Organization of the United Nations (2025, February 25). An oasis of global food security: from mirages to reality.
- AGT Food and Ingredients (2024, July 22). Dignitaries mark opening of new pasta extrusion center in Minot at AGT Foods open house and ribbon cutting. agtfoods.com/news/2024-07-22
- AGT Food and Ingredients (n.d.). PulsePlus Protein Concentrates and Isolates.
- Avena Foods (2025, July 21). Launching Avena Regen Ag Protocol Oat and Pulse Ingredients.
- Roquette Frères (2025, June 17). Roquette launches new textured wheat and pea proteins.
- Ingredion Incorporated (n.d.). VITESSENCE Pulse 2550 Lentil Protein application information.
"This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations."
This Report Answers
- How large is the Lentil Protein Market in 2026 and what value is forecast for 2036?
- Which industry pressures support demand for lentil protein ingredients?
- Why do Protein Isolates lead the Product Type category?
- Why does Conventional lead the Nature category?
- Why does Food Processing lead the End Use category?
- How do the profiled country growth rates differ from 2026 to 2036?
- Which companies participate in lentil protein and adjacent pulse-ingredient supply?
- What should buyers evaluate before qualifying a lentil protein grade?
Frequently Asked Questions
How big is the Lentil Protein Market in 2026, and what is forecast for 2036?
The Lentil Protein Market is valued at USD 150.7 Million in 2026 and is forecast to reach USD 237.2 Million by 2036. The market was valued at USD 144.1 Million in 2025.
What is the CAGR for the Lentil Protein Market from 2026 to 2036?
The market is forecast to expand at a 4.6% CAGR from 2026 to 2036 as food manufacturers widen their use of functional pulse proteins.
Which Product Type segment leads the Lentil Protein Market?
Protein Isolates lead Product Type with a 47.4% share in 2026. Their higher protein density supports applications where formulators need to increase protein without adding excessive ingredient mass.
Which Nature segment leads the Lentil Protein Market?
Conventional products lead Nature with a 95.3% share in 2026. Wider crop availability and simpler sourcing support large-volume procurement.
Which End Use segment leads the Lentil Protein Market?
Food Processing leads End Use with a 68.2% share in 2026. Bakery, pasta, snacks, beverages, sauces and plant-based foods provide multiple commercial applications for lentil protein.
Which countries show the highest profiled growth rates?
The UK has the highest profiled CAGR at 6.1%, followed by South Korea at 5.8% and Mexico at 5.5% from 2026 to 2036. These figures compare growth pace rather than absolute market size.
Which companies are active in the Lentil Protein Market?
The profiled competitive set includes AGT Food and Ingredients, Ingredion Incorporated, Roquette Frères, Vestkorn Milling, PURIS, Avena Foods, Anchor Ingredients, Parrish & Heimbecker, The Scoular Company and Diefenbaker Spice & Pulse.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Protein Isolates
- Protein Concentrates
- Flour
- Other Product Types
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Nature, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Nature, 2026 to 2036
- Conventional
- Organic
- Y-o-Y Growth Trend Analysis By Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Nature, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End Use, 2026 to 2036
- Food Processing
- Sports Nutrition
- Nutraceuticals
- Infant Nutrition
- Animal Feed
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Processing Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Processing Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Processing Type, 2026 to 2036
- Dry Processing
- Wet Processing
- Y-o-Y Growth Trend Analysis By Processing Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing Type, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Nature
- By End Use
- By Processing Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By End Use
- By Processing Type
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Nature
- By End Use
- By Processing Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By End Use
- By Processing Type
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Nature
- By End Use
- By Processing Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By End Use
- By Processing Type
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Nature
- By End Use
- By Processing Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By End Use
- By Processing Type
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Nature
- By End Use
- By Processing Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By End Use
- By Processing Type
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Nature
- By End Use
- By Processing Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By End Use
- By Processing Type
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Nature
- By End Use
- By Processing Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By End Use
- By Processing Type
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Processing Type
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Processing Type
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Processing Type
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Processing Type
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Processing Type
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Processing Type
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Processing Type
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Processing Type
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Processing Type
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Processing Type
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Processing Type
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Processing Type
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Processing Type
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Processing Type
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Processing Type
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Processing Type
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Processing Type
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Processing Type
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Processing Type
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Processing Type
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Processing Type
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Nature
- By End Use
- By Processing Type
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- AGT Food and Ingredients
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Ingredion Incorporated
- Roquette Frères
- Vestkorn Milling
- PURIS
- Avena Foods
- Anchor Ingredients
- Parrish & Heimbecker
- The Scoular Company
- Diefenbaker Spice & Pulse
- AGT Food and Ingredients
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


