

- Market Size (2026)
- USD 4.5 Bn
- Forecast (2036)
- USD 8.7 Bn
- CAGR (2026 to 2036)
- 6.8%
How big is Protein Ingredients Market in 2026?
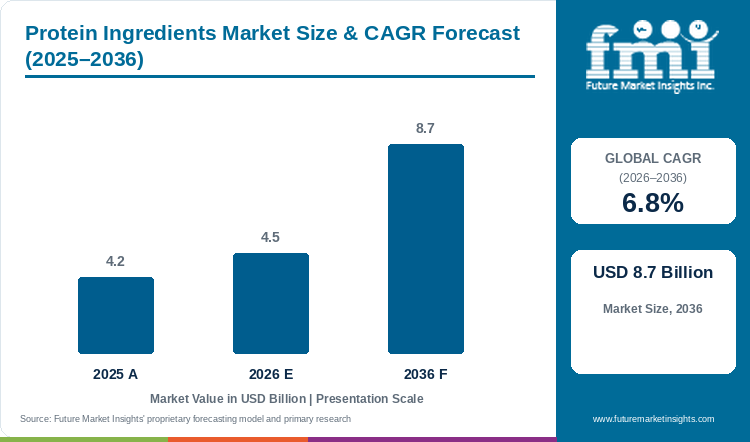
Demand for protein ingredients is projected to expand at 6.8% CAGR between 2026 and 2036, with the market size rising from USD 4.2 billion in 2025 to USD 4.5 billion in 2026 and reaching USD 8.7 billion by 2036.
Food and supplement processors formulating ready-to-mix sports powders, clinical sarcopenia shakes, and high-protein snacks require purified isolates that raise protein density without altering beverage viscosity or flavor. According to Future Market Insights analysis, the global protein ingredients market stands at USD 4.2 billion in 2025, reaches USD 4.5 billion in 2026, and is projected to attain USD 8.7 billion by 2036, advancing at a 6.8% CAGR and generating USD 4.2 billion in added revenue. In October 2025, Food and Agriculture Organization dietary data highlighted expanding global reliance on fractionated plant and dairy proteins to meet daily amino acid requirements [1]. Fine Powder & Micronized Crystals leads with 41.3% share in 2026, while country growth spans 5.4% in France to 8.3% in Canada.
Key Market Trends & Insights
- By form / physical state: With a 41.3% share in 2026, Fine Powder & Micronized Crystals led the category, as fluid-bed lecithin agglomeration enables instant cold-water dispersion inside shaker bottles [3].
- By source / nature: Conventional Farm Source held the leading share of 53.0% in 2026, because established yellow pea, soy, and sweet whey collection networks provide dependable wet-milling volume.
- By application sector: Dietary Supplements & Nutraceuticals represented 33.4% of revenue in 2026, supported by daily resistance-training powders and GLP-1 companion sports nutrition shakes.
Regional Highlights
- Fastest-growing evaluated country: Canada, at 8.3% CAGR from 2026 to 2036.
- By country: South Korea at 7.6%, the USA at 7.1%, Japan at 6.5%, and Germany at 6.0% follow, while France records the lowest evaluated CAGR at 5.4%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Protein Ingredients Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 4.2 billion |
| Estimated Market Size in 2026 | USD 4.5 billion |
| Projected Market Size by 2036 | USD 8.7 billion |
| CAGR, 2026 to 2036 | 6.8% |
| Added Revenue, 2026 to 2036 | USD 4.2 billion |
North American and Western European wet-fractionation plants process locally grown yellow peas and sweet cheese whey at farmgate scale, whereas East Asian beverage formulators rely heavily on imported isolate powders. Extracting protein isolates above 85% dry-basis purity requires balancing cross-flow membrane flux rates against natural gas spray-drying costs. In May 2025, the European Food Safety Authority issued updated nutritional and safety evaluations for novel plant and microbial protein isolates used in commercial food fortification [2]. Owing to these amino acid scoring standards, bakery and nutrition brands are blending pulse ingredients with cereal fractions to achieve complete protein digestibility across commercial production runs.
Protein Fractionation and Agglomeration Processing Metrics
Table 2: Protein Fractionation and Agglomeration Processing Metrics for the Protein Ingredients Market (USD billion and operational parameters), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 4.2 | 4.5 | 8.7 |
| Commercial protein fractionation tonnage (thousand metric tons) | 820.0 | 885.0 | 1,720.0 |
| Average protein purity in commercial isolates (percentage) | 88.0 to 92.5 | 89.0 to 93.0 | 90.0 to 95.0 |
| Cold-water dissolution time for agglomerated powder (seconds) | 18 to 28 | 16 to 25 | 12 to 20 |
Dry-basis purity figures reflect Dumas nitrogen combustion assays across licensed dairy ultrafiltration plants and industrial oilseed and pulse wet-milling complexes. Reconstitution times measure 25-gram powder charges stirred into 250 milliliters of cold water.
Facility Capital Expenditure & Fractionation Yardstick Metrics
Separating native whey and legume storage proteins without heat denaturation requires multi-stage ceramic microfiltration skids paired with tall-form spray dryers. When beverage and clinical nutrition brands specify low-astringency isolates that stay suspended in ready-to-drink bottles, wet-milling plants must add aqueous debittering columns and inline particle-size analyzers. Expanding orders for functional proteins across sports and medical nutrition lines are driving capital outlays for membrane filtration and wastewater recovery.
Table 3: Facility Capital Expenditure and Processing Yardstick Metrics for the Protein Ingredients Market (USD and units), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Operational protein fractionation plants globally (units) | 620 | 660 | 1,080 |
| Industrial spray drying tower spend per plant (USD million) | 6.5 to 9.8 | 6.8 to 10.2 | 9.5 to 14.5 |
| Cross-flow ceramic ultrafiltration skid cost (USD million) | 1.8 to 2.8 | 1.9 to 3.0 | 2.8 to 4.2 |
| Protein purity and amino acid assay cost per lot (USD) | 350 to 520 | 380 to 550 | 520 to 750 |
Table 4: Facility & Operational Cost Benchmark Indicators for the Protein Ingredients Market (USD and percentages), mixed reporting years from 2024 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 4.5 billion | Report value |
| Raw grain and milk share of conversion cost | 48.0% to 58.0% | 2026 wet-milling operating range |
| Spray drying gas and power outlay per ton | USD 155 to 205 | Industrial tower benchmark |
| Dietary supplements & nutraceuticals revenue, 2026 | USD 1.5 billion | 33.4% share |
Analyst Perspective
"Low-astringency pea isolates and cold-filtered native whey fractions give formulators wider room to fortify clear beverages and clinical nutrition shakes. Batch-to-batch hydration differences and volatile yellow pea and milk prices still require rigorous pilot-line testing before food plants approve routine supply."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the protein ingredients market segmented?
The protein ingredients market is segmented by form / physical state, source / nature, application sector, and region. In 2026, Fine Powder & Micronized Crystals is projected at 41.3%, Conventional Farm Source at 53.0%, and Dietary Supplements & Nutraceuticals at 33.4%.
By form / physical state: Fine Powder & Micronized Crystals, Liquid Extract & Tincture, and Standardized Granules & Pellets.
By source / nature: Conventional Farm Source, Certified Organic & Non-GMO, and Fermentation / Bio-Synthesized.
By application sector: Dietary Supplements & Nutraceuticals, Functional Food & Beverages, Cosmetics & Topical Personal Care, and Animal Nutrition.
Why does Fine Powder & Micronized Crystals lead the form / physical state category?
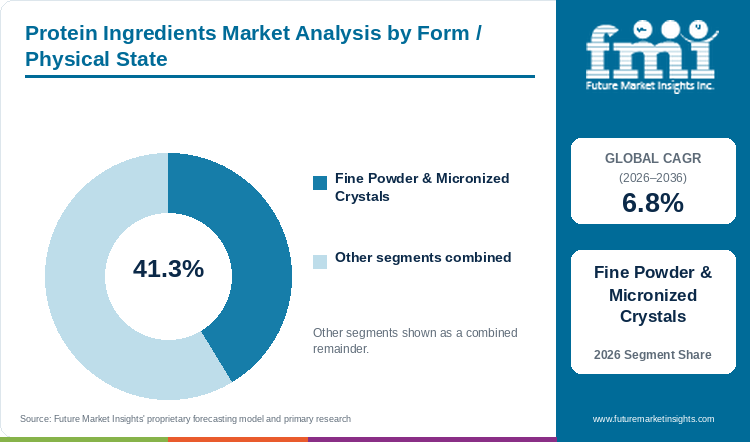
Fine Powder & Micronized Crystals is projected to capture 41.3% of form / physical state demand in 2026, driven by instant cold-water dispersibility.
Table 5: Form / Physical State Share for the Protein Ingredients Market (percentage share), 2026
| Form / Physical State | Share (2026) |
|---|---|
| Fine Powder & Micronized Crystals | 41.3% |
| Other Segments Combined | 58.7%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Form / Physical State Leadership and Market Growth for the Protein Ingredients Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.8% |
| Leading Segment | Fine Powder & Micronized Crystals |
Spray-dried particles milled below 80 microns suspend smoothly in cold water without gritty sedimentation, making fine powders the preferred physical state for dry beverage mixes and nutrition canisters. Whereas liquid protein concentrates require refrigerated tanker transport and rapid turnover, dry micronized pea protein and organic rice protein isolates ship economically in multi-wall moisture-barrier bags with 24-month ambient shelf stability. Fluid-bed agglomeration lets contract compounders meter exact amino acid ratios into canisters and stick packs. Quality teams still test tapped bulk density and wetting speed before qualifying a powder lot for high-speed auger filling.
- Fine Powder & Micronized Crystals is expected to account for 41.3% of form / physical state revenue in 2026, driven by low ambient freight cost and rapid beverage wetting.
- In February 2026, Roquette launched NUTRALYS Pea 850F, a soluble fine-powder pea protein isolate engineered to eliminate characteristic legume notes in wet and dry nutrition mixes [4].
What keeps Conventional Farm Source ahead by source / nature?
With an estimated 53.0% share in 2026, Conventional Farm Source leads source / nature, underpinned by large-scale grain and dairy supply.
Industrial wet-milling and cheese-whey filtration plants require continuous multi-thousand-ton raw intake to keep extraction costs competitive, placing conventional farm crops and milk solids at the center of global supply. Processors contract conventional whey protein and yellow pea protein feedstocks for mainstream nutrition brands that cannot absorb the 35% to 50% crop price premiums attached to certified organic harvests. Established grain elevator grading and sweet-whey collection pipelines allow refiners to blend lots for uniform nitrogen content. Formulators expanding into savory snacks and bakery mixes also incorporate chickpea protein concentrates where emulsification and light crumb color are needed.
- Conventional Farm Source is projected to hold 53.0% of source / nature demand in 2026, underpinned by multi-million-ton agricultural availability and lower raw feedstock cost.
- In September 2026, the USDA Economic Research Service reported that expanding U.S. dairy herd productivity supported higher domestic milk and whey solids availability for 2026 commercial processing [5].
Why do Dietary Supplements & Nutraceuticals define the largest application sector?
Dietary Supplements & Nutraceuticals is anticipated to contribute 33.4% of application sector sales in 2026, owing to recurring sports shake and clinical demand.
Active gym users, older adults managing age-related muscle loss, and patients using GLP-1 weight-management medications consume concentrated protein shakes on a daily schedule. Supplement formulators blend cold-filtered native whey protein and soy protein isolate into 25-gram to 30-gram servings that deliver the leucine threshold required to trigger post-exercise muscle synthesis. Enzymatic hydrolysis also allows brands to produce clear protein waters and compact 100-milliliter medical shots without heavy dairy viscosity. Clinical and sports buyers still audit heavy-metal certificates and free-amino-acid spiking assays before signing annual supply agreements.
- Dietary Supplements & Nutraceuticals accounts for 33.4% of application sector revenue in 2026, owing to daily repeat consumption across sports powders and medical nutrition drinks.
- In May 2026, Arla Foods Ingredients introduced specialized high-protein dairy concepts at Vitafoods Europe in Barcelona tailored for consumers seeking muscle preservation during GLP-1 weight-management therapy [6].
What are the drivers, restraints, and opportunities in the protein ingredients market?
Sports and GLP-1 muscle-preservation nutrition elevates isolate volume, whereas spray-drying energy costs and pulse cultivar variability restrain margins, and clear hydrolyzed protein drinks create high-margin value.
- Driver: Expanding protein fortification across sports powders, senior sarcopenia diets, and GLP-1 companion foods drives recurring isolate procurement through 2036.
- Restraint: High natural gas consumption in spray-drying towers and batch-to-batch solubility variation across pulse cultivars compress processor margins and extend qualification trials.
- Opportunity: Engineering acid-stable clear whey and debittered pulse peptide isolates unlocks premium applications in sparkling refreshments and compact clinical nutrition shots.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Food and nutrition brands are raising protein claims across everyday breakfast cereals, RTD shakes, and clinical recovery beverages as consumers prioritize lean muscle maintenance alongside calorie control. Rather than relying solely on commodity flour enrichment, formulators specify 85% to 90% protein isolates that deliver high branched-chain amino acid density without adding excess carbohydrates. Clinical guidance on age-related sarcopenia and medical weight loss is widening the buyer base well beyond traditional athletes. In April 2025, a clinical nutrition study in the American Journal of Clinical Nutrition confirmed that leucine-enriched plant and whey isolate blends stimulated postprandial muscle protein synthesis comparable to pure dairy whey [7]. Ingredient suppliers must provide verified amino-acid digestibility data before major food brands lock in multi-year contracts.
Risk Assessment of the Protein Ingredients Market: Operational and Formulation Friction
Evaporating moisture from liquid protein retentate inside tall-form spray dryers consumes substantial natural gas and electricity, exposing wet millers to industrial energy price swings. In addition to this, cultivar differences across yellow peas and faba beans alter globulin-to-albumin ratios, causing unexpected shifts in gelation and water binding on customer food lines. In July 2025, European Dairy Association technical benchmarks noted that ceramic membrane fouling and wastewater biological oxygen demand treatment add significant recurring operating costs for European whey and plant fractionators [8]. Food manufacturers delay commercial rollouts when isolate lots fail viscosity consistency checks during pilot UHT sterilization.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Traditional dairy and legume proteins coagulate and turn chalky at pH levels below 4.0, which previously barred their use in fruit juices and carbonated soft drinks. By applying targeted membrane microfiltration and enzymatic cleavage, suppliers now produce acid-stable clear whey and debittered plant-based protein peptides that dissolve transparently without isoelectric precipitation or green-beany off-notes. In November 2025, Arla Foods Ingredients unveiled a transparent high-protein yogurt concept and a carbonated milk-like protein refreshment ahead of Food ingredients Europe [9]. Processors that combine heat-stable clarity with clean sensory profiles win high-margin supply contracts with functional beverage bottlers.
Protein Ingredients Market by Country (2026 to 2036)
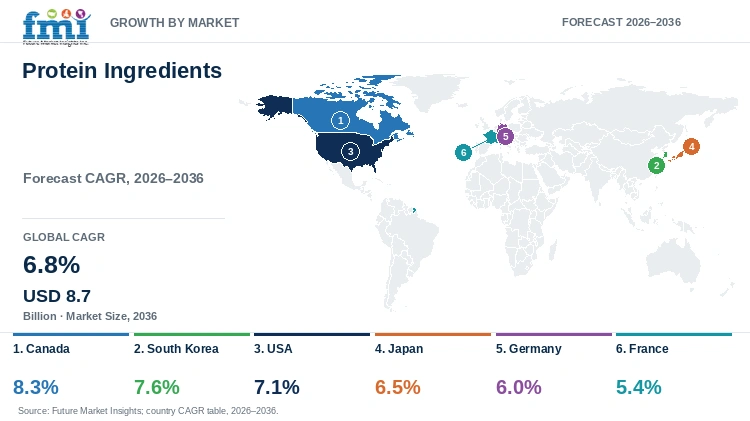
Prairie pulse fractionation capacity places Canada at the top of the country growth table with an 8.3% CAGR from 2026 to 2036. South Korea (7.6%) and the USA (7.1%) follow on strong RTD shake and sports powder turnover, while Japan (6.5%), Germany (6.0%), and France (5.4%) reflect mature dairy and clinical nutrition channels.
Table 7: Country CAGR and Primary Growth Levers for the Protein Ingredients Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Canada | 8.3% | Prairie yellow pea and lentil wet-fractionation scale and export processing |
| South Korea | 7.6% | Convenience-store RTD protein beverage boom and active-aging nutrition |
| USA | 7.1% | High sports supplement consumption and GLP-1 companion food reformulation |
| Japan | 6.5% | Geriatric sarcopenia prevention programs and low-viscosity peptide drinks |
| Germany | 6.0% | Federal plant-protein value-chain support and organic clean-label bakery demand |
| France | 5.4% | Native dairy microfiltration leadership and domestic faba and pea processing |
Source: Future Market Insights analysis
Canada Protein Ingredients Market Outlook (2026 to 2036)
Industrial wet-fractionation complexes across Saskatchewan, Manitoba, and Alberta convert domestic yellow pea, lentil, and faba bean harvests into high-purity protein isolates for North American and Asian food makers. By 2036, Canada is projected to grow at 8.3% CAGR, supported by colocation of pulse mills near prairie grain elevators and co-product starch valorization. In July 2025, Agriculture and Agri-Food Canada sector analysis highlighted how Canadian agri-food collaborations have expanded value-added pulse protein isolate exports to European and North American clean-label food manufacturers [10]. However, long rail-freight corridors to Vancouver and Montreal ports and winter sub-zero bottlenecks raise outbound container costs. Canadian processors mitigate freight friction by establishing long-term unit-train contracts and high-density bulk tote loading.
Key takeaway: In Canada, abundant prairie pulse harvests and co-located wet-fractionation plants drive the fastest growth rate among the evaluated countries.
South Korea Protein Ingredients Market Outlook (2026 to 2036)
In South Korea, demand for protein ingredients is predicted to advance at 7.6% CAGR through 2036, propelled by urban convenience-store sales of ready-to-drink protein shakes and active-aging nutritional powders. Domestic dairy and food groups have moved protein fortification from bodybuilding shops into mainstream supermarkets and neighborhood convenience chains. In September 2025, the Korea Agro-Fisheries and Food Trade Corporation reported that domestic retail turnover for protein-fortified beverages and snacks rose 18.0% as middle-aged consumers adopted daily protein supplementation [11]. Because South Korea imports nearly all of its whey and isolated soy and pea feedstocks, won volatility and import tariffs expose local blenders to margin swings. Domestic formulators manage import costs by blending imported dairy whey with enzymatically hydrolyzed soy and grain proteins.
Key takeaway: In South Korea, rapid convenience-store RTD beverage expansion and middle-aged wellness adoption fuel strong demand for imported protein isolates.
USA Protein Ingredients Market Outlook (2026 to 2036)
American food and beverage brands are reformulating snack bars, yogurts, and hydration powders with higher protein loads to serve both gym-goers and millions of adults using GLP-1 weight-management therapies. The USA protein ingredients sector is projected to record 7.1% CAGR during the assessment period, underpinned by domestic soy, corn, and dairy wet-milling infrastructure across the Midwest. In January 2026, USDA National Agricultural Statistics Service crop reports confirmed strong domestic dry edible pea and soybean harvests available for commercial crushing and protein extraction [12]. Even so, heightened consumer scrutiny over ultra-processed ingredient labels and heavy-metal testing in plant powders creates formulation hurdles. U.S. suppliers address this by deploying aqueous physical filtration and publishing batch purity certificates.
Key takeaway: In the USA, GLP-1 companion food reformulation and high sports-nutrition volume sustain robust domestic demand for whey and plant isolates.
Japan Protein Ingredients Market Outlook (2026 to 2036)
Japanese medical nutrition and functional beverage makers prioritize low-viscosity, fast-absorbing protein hydrolysates that prevent sarcopenia in older adults without causing digestive heaviness. Adoption of protein ingredients in Japan is estimated to expand at 6.5% CAGR through 2036, enabled by pharmacy and convenience-store distribution of compact protein jellies, clear pouch drinks, and fortified soups. In November 2025, Japan's Ministry of Health, Labour and Welfare noted in its national nutrition survey updates that targeted protein enrichment remains central to frailty prevention among seniors aged 65 and above [13]. However, strict Japanese sensory standards reject earthy or astringent plant isolate notes, and a shrinking youth cohort limits bulk sports tub growth. Suppliers win Japanese accounts by providing deodorized soy and clear whey peptides.
Key takeaway: In Japan, geriatric frailty prevention programs and strict sensory clarity requirements drive demand for refined whey and soy peptide isolates.
Germany Protein Ingredients Market Outlook (2026 to 2036)
Sales of protein ingredients in Germany are forecast to expand at 6.0% CAGR through 2036, supported by federal nutrition policies promoting domestic legume value chains and strong retail demand for non-GMO plant-based foods. German bakeries, meat-alternative producers, and sports nutrition brands actively substitute imported soy with European-grown pea, faba bean, and lupin protein fractions. In May 2025, Germany's Federal Ministry of Food and Agriculture updated its nutrition-strategy measures to strengthen domestic plant-based protein cultivation and regional processing infrastructure [14]. Nevertheless, high German industrial electricity tariffs and strict European Union novel-food authorization rules slow the commercialization of new fermented protein isolates. Domestic processors counter energy pressures by utilizing dry air-classification alongside targeted aqueous extraction.
Key takeaway: In Germany, federal support for regional legume value chains and strict non-GMO retail standards favor European pea and faba bean isolates.
France Protein Ingredients Market Outlook (2026 to 2036)
France combines world-class dairy membrane filtration in Brittany and Normandy with large-scale yellow pea and faba bean fractionation in northern agricultural basins. Between 2026 and 2036, the France market is expected to progress at 5.4% CAGR, backed by high-value exports of native micellar casein, native whey isolates, and clean-taste pea proteins for infant, clinical, and culinary applications. In August 2025, the French Dairy Interbranch Organization reported that specialized French whey and milk protein isolate exports rose 7.0% year-on-year on strong clinical and infant-formula demand [15]. Still, mature domestic food consumption and stiff price competition from lower-cost Eastern European and Asian concentrates cap domestic volume growth. French suppliers protect margins by focusing on patented non-denatured dairy and functional pea fractions.
Key takeaway: In France, advanced native dairy microfiltration and domestic pulse fractionation sustain high-value ingredient production for clinical and culinary markets.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the protein ingredients market?
ADM, Cargill, Incorporated, Ingredion Incorporated, Kerry Group plc, Roquette Frères, Glanbia plc, dsm-firmenich, International Flavors & Fragrances (IFF), Fonterra Co-operative Group, and Arla Foods Ingredients are the notable companies in this market.
Protein ingredient suppliers win industrial accounts through farmgate crop origination, membrane filtration purity, and pilot-scale application support. ADM, Cargill, and Ingredion run multi-crop crushing and wet-milling complexes that ship soy and pulse concentrates in bulk railcars and ocean containers. Roquette Frères, Kerry Group, IFF, and dsm-firmenich pair specialty pea, soy, canola, and yeast protein extraction with flavor-masking and high-moisture extrusion labs. Glanbia plc, Fonterra, and Arla Foods Ingredients operate cold cross-flow microfiltration towers to isolate native whey and casein fractions directly from fresh milk and sweet cheese whey. Food processors check dry-basis nitrogen purity and cold-water dispersibility before approving a vendor.
- Global Plant and Multi-Crop Protein Platforms: ADM, Cargill, Incorporated, Ingredion Incorporated, and International Flavors & Fragrances (IFF) supply soy, pea, and multi-grain isolates at global industrial scale.
- Pulse Fractionation and Taste-Optimization Specialists: Roquette Frères, Kerry Group plc, and dsm-firmenich combine specialized pea, canola, and yeast protein isolation with sensory masking and application labs.
- Dairy Membrane and Clinical Whey Refiners: Glanbia plc, Fonterra Co-operative Group, and Arla Foods Ingredients engineer native whey isolates, hydrolysates, and micellar caseins for sports and medical nutrition.
Competitive Benchmarking: Protein Ingredients Market
Table 8: Competitive Benchmarking for the Protein Ingredients Market (qualitative capability ratings), 2026
| Company | Plant & Dairy Isolate Breadth | Fractionation & Drying Scale | Sensory & Application Support | Geographic Reach |
|---|---|---|---|---|
| ADM | High | High | High | High |
| Cargill, Incorporated | High | High | High | High |
| Ingredion Incorporated | High | High | High | High |
| Kerry Group plc | High | Medium | High | High |
| Roquette Frères | High | High | High | High |
| Glanbia plc | High | High | High | High |
| dsm-firmenich | Medium | Medium | High | High |
| International Flavors & Fragrances | High | High | High | High |
| Fonterra Co-operative Group | High | High | Medium | High |
| Arla Foods Ingredients | High | High | High | High |
Scoring basis: Ratings reflect documented extraction capability and technical formulation support across plant and dairy protein streams. Plant & Dairy Isolate Breadth distinguishes suppliers offering concentrates, 90% isolates, hydrolysates, and textured extrudates from those focused on a single crop or fermentation stream. Fractionation & Drying Scale evaluates wet-milling and spray-drying tower tonnage, while Sensory & Application Support and Geographic Reach track pilot beverage and extrusion laboratories across North America, Europe, Asia-Pacific, and Latin America.
Key Developments in the Protein Ingredients Market
- In September 2026, Arla Foods Ingredients launched a dedicated portfolio of high-protein dairy concepts for GLP-1 weight-management medication users ahead of Vitafoods Europe [16].
- In February 2026, Roquette Frères commercially introduced NUTRALYS Pea 850F to provide clean taste and high solubility in plant-based beverage and powder applications [17].
- In April 2025, BENEO and pulse processing partners expanded European faba-bean protein fractionation capacity in Germany to supply regional food and feed manufacturers [18].
Key Players in the Protein Ingredients Market
Global Plant and Multi-Crop Protein Platforms
- ADM
- Cargill, Incorporated
- Ingredion Incorporated
- International Flavors & Fragrances (IFF)
Pulse Fractionation and Taste-Optimization Specialists
- Roquette Frères
- Kerry Group plc
- dsm-firmenich
Dairy Membrane and Clinical Whey Refiners
- Glanbia plc
- Fonterra Co-operative Group
- Arla Foods Ingredients
Protein Ingredients Market - Report Scope
Table 9: Report Scope for the Protein Ingredients Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Form / Physical State; Source / Nature; Application Sector; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes B2B supplier revenue from concentrated and isolated protein ingredients (powders, micronized crystals, liquid extracts, and textured granules/pellets derived from dairy, oilseeds, pulses, grains, and microbial fermentation) sold within the listed segmentation. Excludes whole unfractionated agricultural grains, fluid retail milk, and finished consumer retail supplements. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Canada, South Korea, USA, Japan, Germany, France, and additional countries in the full report |
| Key Companies Covered | ADM, Cargill, Incorporated, Ingredion Incorporated, Kerry Group plc, Roquette Frères, Glanbia plc, dsm-firmenich, International Flavors & Fragrances (IFF), Fonterra Co-operative Group, Arla Foods Ingredients |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Protein Ingredients Market - Research Methodology
Table 10: Research Methodology for the Protein Ingredients Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with grain wet-milling plant directors, dairy membrane engineers, food application scientists, and sports nutrition procurement leads across the value chain to validate isolate purity standards, agglomeration yields, and pricing dynamics. |
| Secondary Research | Secondary research included Food and Agriculture Organization databases, national agricultural statistics, regulatory novel-food filings, company annual reports, investor presentations, and technical dairy and pulse fractionation literature. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 period were developed using top-down pulse, soy, and whey fractionation tonnages paired with bottom-up ingredient procurement modeling across supplement and food categories. |
| Data Triangulation and Validation | Data is validated against commercial spray-drying capacities, agricultural crushing volumes, and international trade customs records to ensure high accuracy without double counting raw farm commodities. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's food ingredients econometric model, calibrating evaluated national growth rates against the 6.8% global baseline through verified plant-based protein fractionation capacity, whey isolate export tariffs, and sports nutrition manufacturer demand. |
| Operational Benchmark Traceability | Operational benchmarks (commercial protein fractionation tonnage, dry ultrafiltration yields, and PDCAAS amino acid scoring assay costs) represent modeled estimates synthesized from FAO agricultural outlooks, USDA ERS data, Agriculture and Agri-Food Canada reports, and commercial protein refiner disclosures. |
Protein Ingredients Market by Segments
Protein Ingredients Market segmented by Form / Physical State:
- Fine Powder & Micronized Crystals
- Liquid Extract & Tincture
- Standardized Granules & Pellets
Protein Ingredients Market segmented by Source / Nature:
- Conventional Farm Source
- Certified Organic & Non-GMO
- Fermentation / Bio-Synthesized
Protein Ingredients Market segmented by Application Sector:
- Dietary Supplements & Nutraceuticals
- Functional Food & Beverages
- Cosmetics & Topical Personal Care
- Animal Nutrition
Protein Ingredients Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Ireland
- Denmark
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Food and Agriculture Organization of the United Nations. (2025, October 28). Global protein availability and dietary diversity indicators across food systems. The State of Food Security and Nutrition in the World.
- [2] European Food Safety Authority. (2025, May 22). Scientific opinion on novel plant and microbial protein isolates and amino acid digestibility equivalence. EFSA Journal, 23(5), 8860.
- [3] International Dairy Federation. (2025, July 14). Bulletin on dairy protein membrane fractionation technologies and fluid-bed agglomeration standards. IDF Technical Series No. 531.
- [4] Roquette Frères. (2026, February 23). Roquette launches NUTRALYS Pea 850F soluble pea protein isolate for clean-taste food and nutrition formulations. Roquette Food and Nutrition Press Releases.
- [5] United States Department of Agriculture. (2026, September 25). U.S. dairy herd expansion and milk solids production outlook for 2026 processing. USDA Economic Research Service Food Outlook.
- [6] Arla Foods Ingredients Group P/S. (2026, May 05). Arla Foods Ingredients presents high-protein companion nutrition concepts for GLP-1 users at Vitafoods Europe 2026. Corporate Press Releases.
- [7] American Journal of Clinical Nutrition. (2025, April 18). Postprandial muscle protein synthesis rates following ingestion of leucine-matched plant versus dairy protein isolates. AJCN Clinical Trials, 122(2), 245-260.
- [8] European Dairy Association. (2025, July 29). Advanced ceramic microfiltration economics and spray-drying thermal energy benchmarks in European whey plants. EDA Technical Bulletin, 15, 70-88.
- [9] Arla Foods Ingredients Group P/S. (2025, November 11). Arla Foods Ingredients debuts transparent high-protein yogurt and carbonated protein drink concepts ahead of Fi Europe 2025. Corporate Innovation News.
- [10] Agriculture and Agri-Food Canada. (2025, July 02). Canadian pulse processing sector review: Fractionation capacity and international plant-protein demand. Sector Trend Analysis: Plant-Based Pulse Ingredients.
- [11] Korea Agro-Fisheries and Food Trade Corporation (aT). (2025, September 19). Market trends in protein-fortified ready-to-drink beverages and supplements in South Korea. aT Statistical Review, 19, 55-72.
- [12] USDA National Agricultural Statistics Service. (2026, January 06). Annual crop production summary: U.S. dry edible pea, lentil, and soybean harvest statistics. NASS Agricultural Publications.
- [13] Ministry of Health, Labour and Welfare of Japan (MHLW). (2025, November 14). National health and nutrition survey: Protein intake patterns and sarcopenia prevention in aging cohorts. MHLW Statistical Bulletin, 44, 90-108.
- [14] Federal Ministry of Food and Agriculture (BMEL). (2025, May 16). Updated German nutrition strategy and domestic plant-based protein value-chain initiatives. BMEL Policy Reports, 28, 42-58.
- [15] Centre National Interprofessionnel de l'Economie Laitiere (CNIEL). (2025, August 26). L'economie laitiere en chiffres: Specialized French native whey and milk protein isolate exports. CNIEL Annual Overview, 33, 62-80.
- [16] Food Engineering & Ingredients & Arla Foods Ingredients. (2026, September 16). Arla Foods Ingredients launches high-protein dairy concepts tailored for GLP-1 medication users. European Ingredient Briefings.
- [17] Roquette Corporate Communications. (2026, February 23). Commercial rollout of NUTRALYS Pea 850F isolate for high-protein beverages and nutrition mixes. Roquette Press Room.
- [18] Pulse Canada. (2025, August 12). Canadian pulse ingredient quality specifications, dry and wet fractionation yields, and sustainability metrics. Canadian Pulse Industry Impact Report.
- [19] ADM (Archer Daniels Midland Company). (2025, October 09). Expansion of Decatur soy and pulse protein isolate texturization and wet-fractionation lines. ADM Corporate Investor Releases.
- [20] Ingredion Incorporated. (2026, June 15). Introduction of VITESSENCE Pea & Rice protein solutions for clean-label food and beverage fortification. Ingredion Newsroom.
- [21] Glanbia plc. (2025, September 22). Upgrade of low-temperature ceramic microfiltration capacity for native whey protein isolate production. Glanbia Nutritionals Updates.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the protein ingredients market in 2026 and what is forecast for 2036?
- Which sports, clinical, and GLP-1 nutrition trends support demand for protein ingredients?
- Why does Fine Powder & Micronized Crystals lead the form / physical state category?
- Why does Conventional Farm Source lead the source / nature category globally?
- How do growth rates differ across Canada, South Korea, the USA, Japan, Germany, and France?
- Which leading companies supply plant and dairy protein isolates today?
- What drying energy and cultivar solubility factors restrain margin expansion in the market?
- What should food and supplement buyers evaluate before qualifying a protein isolate supplier?
Frequently Asked Questions
How large is the Protein Ingredients Market expected to be in 2026?
The global protein ingredients market is estimated to reach USD 4.5 billion in 2026. Market valuation is projected to expand further and reach USD 8.7 billion by 2036, driven by sports, clinical, and everyday food fortification.
What CAGR is forecast for the Protein Ingredients Market through 2036?
As per FMI, the protein ingredients market is projected to advance at a 6.8% CAGR from 2026 to 2036. Growth is supported by expanding wet-fractionation capacity for yellow pea and native dairy whey isolates.
Which physical form holds the largest share in the protein ingredients market in 2026?
Fine Powder & Micronized Crystals is projected to hold 41.3% of form / physical state demand in 2026. The segment benefits from fluid-bed agglomeration that delivers rapid cold-water solubility and low transport weight.
Which application sector leads demand in the protein ingredients market in 2026?
Dietary Supplements & Nutraceuticals is estimated to account for 33.4% of application sector revenue in 2026. Demand is underpinned by daily resistance-training powders, senior sarcopenia shakes, and GLP-1 companion nutrition.
Which country has the highest growth outlook during the 2026 to 2036 assessment period?
FMI finds that Canada is projected to grow at an 8.3% CAGR from 2026 to 2036. Growth is supported by abundant prairie yellow pea and lentil harvests paired with modern domestic wet-fractionation plants.
Which companies are active in the Protein Ingredients Market during 2026?
Notable companies active in the market include ADM, Cargill, Incorporated, Ingredion Incorporated, Kerry Group plc, Roquette Frères, Glanbia plc, dsm-firmenich, International Flavors & Fragrances (IFF), Fonterra Co-operative Group, and Arla Foods Ingredients. These suppliers focus on isolate purity, flavor debittering, and cold-water dispersibility.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Form / Physical State, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Form / Physical State, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Form / Physical State, 2026 to 2036
- Fine Powder & Micronized Crystals
- Liquid Extract & Tincture
- Standardized Granules & Pellets
- Y-o-Y Growth Trend Analysis By Form / Physical State, 2021 to 2025
- Absolute $ Opportunity Analysis By Form / Physical State, 2026 to 2036
- Global Market Analysis and Forecast, By Source / Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source / Nature, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source / Nature, 2026 to 2036
- Conventional Farm Source
- Certified Organic & Non-GMO
- Fermentation / Bio-Synthesized
- Y-o-Y Growth Trend Analysis By Source / Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Source / Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Application Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application Sector, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application Sector, 2026 to 2036
- Dietary Supplements & Nutraceuticals
- Functional Food & Beverages
- Cosmetics & Topical Personal Care
- Animal Nutrition
- Y-o-Y Growth Trend Analysis By Application Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By Application Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Form / Physical State
- By Source / Nature
- By Application Sector
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Form / Physical State
- By Source / Nature
- By Application Sector
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Ireland
- Denmark
- Italy
- Spain
- Benelux
- Nordics
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Form / Physical State
- By Source / Nature
- By Application Sector
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Form / Physical State
- By Source / Nature
- By Application Sector
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Form / Physical State
- By Source / Nature
- By Application Sector
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Form / Physical State
- By Source / Nature
- By Application Sector
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Form / Physical State
- By Source / Nature
- By Application Sector
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Form / Physical State
- By Source / Nature
- By Application Sector
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- ADM
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Cargill, Incorporated
- Ingredion Incorporated
- Kerry Group plc
- Roquette Frères
- Glanbia plc
- dsm-firmenich
- International Flavors & Fragrances
- Fonterra Co-operative Group
- Arla Foods Ingredients
- International Flavors & Fragrances (IFF)
- ADM
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


