

- Market Size (2026)
- USD 5.4 Bn
- Forecast (2036)
- USD 8.6 Bn
- CAGR (2026 to 2036)
- 4.8%
How big is Tapioca Market in 2026?
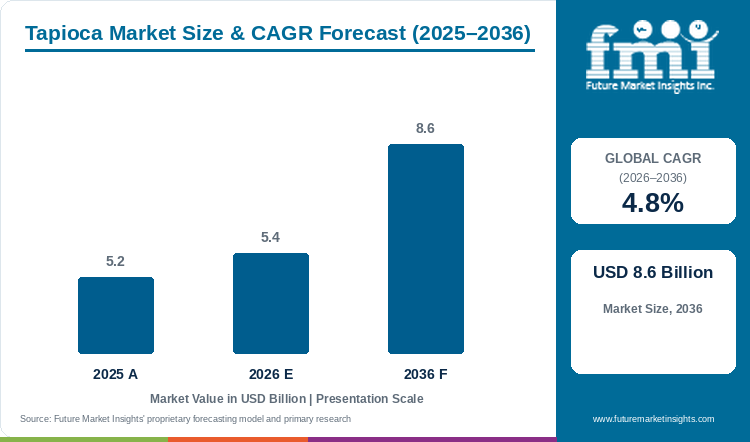
Demand for tapioca is projected to expand at 4.8% CAGR between 2026 and 2036. Industry value grows from USD 5.2 billion in 2025 to USD 5.4 billion in 2026 and is projected to reach USD 8.6 billion by 2036.
Escalating consumer preference for clean label ingredients and growing prevalence of celiac complications have burdened industrial food processors with replacing cereal starches without compromising product viscosity. Managing industrial formulation requires balancing gelatinization temperature with neutral flavor profiles. This generates an expanding requirement for tapioca solutions that deliver high paste clarity and gluten-free compliance across sauces, bakery, and dairy alternatives. According to Future Market Insights analysis, the global tapioca market advances from USD 5.2 billion in 2025 to USD 5.4 billion in 2026, and is projected to reach USD 8.6 billion by 2036, registering a 4.8% CAGR and generating USD 3.2 billion in added revenue. In December 2025, FAOSTAT updated its global crop production dataset, confirming steady cassava root harvests that provide procurement stability for industrial starch processors [1]. Standard commercial grade commands the leading position with 56.0% share in 2026, as uniform mesh size and dependable paste stability lower factory switching costs.
Key Market Trends & Insights
- By product type / grade: Standard commercial grade led with 56.0% share in 2026, because broad viscosity profiles and neutral flavor lower substitution costs across packaged foods.
- By processing state: Fresh / ambient packaged held 42.4% in 2026, as shelf-stable ambient distribution eliminates cold-chain storage expenses for retail grocery channels.
- By end-use application: Direct retail consumer consumption represented 47.0% in 2026, supported by versatile household cooking and baking applications in home kitchens.
Regional Highlights
- Fastest-growing evaluated country: France, at 5.9% CAGR from 2026 to 2036.
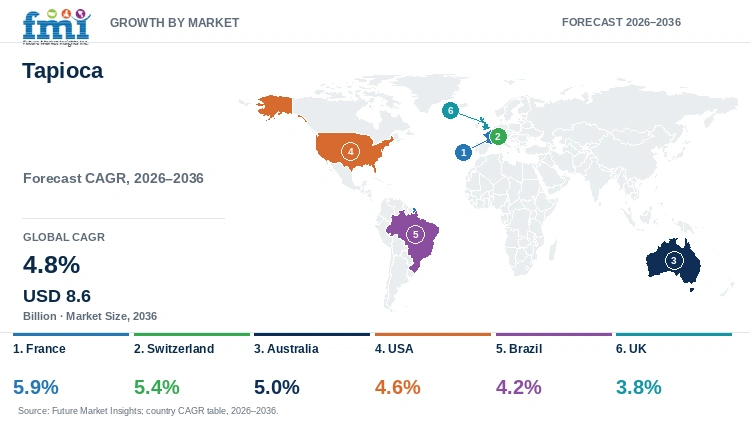
- By country: Switzerland at 5.4%, Australia at 5.0%, and the USA at 4.6% follow, while Brazil at 4.2% and the UK record lower CAGRs at 3.8%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Tapioca Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 5.2 billion |
| Estimated Market Size in 2026 | USD 5.4 billion |
| Projected Market Size by 2036 | USD 8.6 billion |
| CAGR, 2026 to 2036 | 4.8% |
| Added Revenue, 2026 to 2036 | USD 3.2 billion |
Future Market Insights research indicates that regional adoption develops unevenly across manufacturing hubs as cassava root availability and local import dependencies dictate processing economics. United States and European processors must manage ocean freight fluctuations when importing native starch from Southeast Asian mills. In 2026, Food and Agriculture Organization trade assessments indicated persistent freight variances across maritime agricultural corridors [2]. Consequently, multinational food brands are establishing long-term volume agreements with integrated starch millers, insulating downstream processing lines from raw root supply disruptions while securing consistent ingredient batches.
Ingredient and Processing Demand Sizing
Table 2: Indicative Tapioca Demand Structure, 2026
| Indicator | 2026 estimate | Commercial meaning |
|---|---|---|
| Standard commercial grade revenue | USD 3.0 billion | Broad food and industrial formulation base |
| Fresh / ambient packaged revenue | USD 2.3 billion | Retail and foodservice turnover |
| Direct retail consumer revenue | USD 2.5 billion | Household cooking and packaged formats |
Calculation basis: Revenue values apply the supplied 2026 shares to the USD 5.4 billion market estimate. Rounded figures are analytical allocations and not measured company sales.
Trade and Supply Indicators
Table 3: Supply and Demand Indicators for the Tapioca Market
| Indicator | Position | Use in assessment |
|---|---|---|
| Cassava production data | FAOSTAT updated December 2025 | Supply availability and country comparison |
| Agricultural trade data | USDA and national customs portals | Import dependence and channel movement |
| Food formulation demand | Company product and technical pages | Application fit and substitution routes |
Table 4: Market Revenue Allocation Indicators, 2026
| Metric | Value | Basis |
|---|---|---|
| Market size | USD 5.4 billion | Report estimate |
| Standard commercial grade | USD 3.0 billion | 56.0% share |
| Fresh / ambient packaged | USD 2.3 billion | 42.4% share |
| Direct retail consumption | USD 2.5 billion | 47.0% share |
Analyst Perspective
“Tapioca is moving from a substitute starch toward a planned formulation input. Buyers will reward consistent viscosity and documented root sourcing.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the tapioca market segmented?
Tapioca Market is segmented by three primary commercial axes and region: product type / grade, processing state, end-use application, and region. Standard commercial grade, fresh / ambient packaged, and direct retail consumption are projected to lead their respective axes in 2026.
By product type / grade: standard commercial grade, organic and clean-label variant, and premium specialty formulation.
By processing state: fresh / ambient packaged, frozen and chilled, and dehydrated and dry packaged.
By end-use application: direct retail consumer consumption, food service and hospitality, commercial food manufacturing plants, and industrial applications.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does standard commercial grade retain broad product demand?
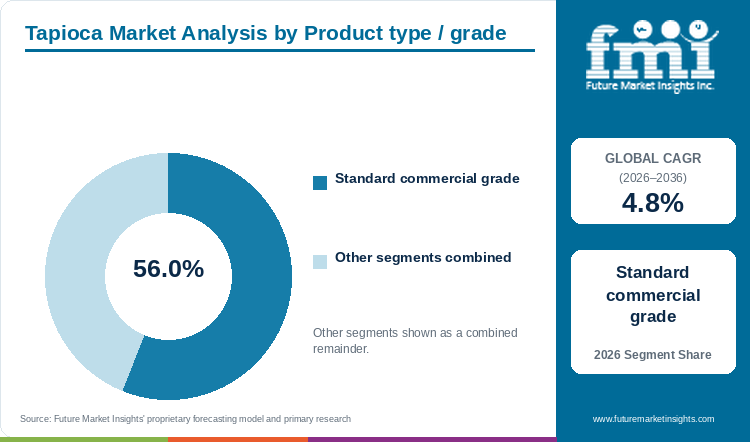
Standard commercial grade is projected to account for 56.0% of product type / grade revenue in 2026, driven by versatile thickening and binding performance across food formulations.
Table 5: Product Type / Grade Share for the Tapioca Market (percentage share), 2026
| Product type / grade | Share (2026) |
|---|---|
| Standard commercial grade | 56.0% |
| Other Segments Combined | 44.0%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Type Leadership and Market Growth for the Tapioca Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.8% |
| Leading Segment | Standard commercial grade |
Standard commercial grade fits the viscosity and binding needs of mainstream food and industrial recipes without requiring costly custom chemical modifications. Food manufacturing facilities deploy this grade across soups, sauces, and baked goods where stable paste clarity is essential. When formulating next-generation recipes, commercial buyers frequently blend tapioca with modified starch or dedicated food thickeners to balance gel strength against recipe costs.
- Standard commercial grade represents 56.0% of product type / grade revenue as broad specifications lower switching costs.
- In 2025, Thai Wah continued positioning tapioca starch for food and industrial customers through its integrated cassava platform [3].
What supports fresh packaged tapioca in the processing-state mix?
Fresh / ambient packaged is estimated to represent 42.4% of processing-state demand in 2026, supported by ambient shelf stability and simplified retail culinary preparation.
Ambient packs shorten preparation for puddings, beverages, and household desserts while avoiding costly freezer infrastructure across grocery logistics. The format integrates seamlessly into convenience foods where direct shelf presentation drives routine impulse purchases among urban consumers.
- Fresh / ambient packaged products hold 42.4% of processing-state revenue through convenient storage and familiar preparation.
- In 2025, national food-trade databases continued reporting product-level flows that help importers plan ambient inventory [4].
How does direct retail consumption lead end-use application demand?
Direct retail consumer consumption is projected to capture 47.0% of end-use application revenue in 2026, reflecting household preparation across traditional desserts and home baking.
Retail demand spans pearls, flour, and starch mixes as domestic consumers prepare home desserts and regional dishes without requiring specialized kitchen equipment. Rising household awareness regarding gluten free food alternatives has further propelled direct grocery purchases of tapioca flours for allergen-safe baking.
- Direct retail consumer consumption contributes 47.0% of end-use revenue as multiple formats fit everyday kitchens.
- The 2025 expansion of online grocery assortments widened consumer access to tapioca pearls, flour, and starch formats [5].
What are the drivers, restraints, and opportunities in the tapioca market?
In the tapioca market, gluten-free reformulation expands volume demand, cassava root price volatility constrains processor margins, and clean-label specialty starches open high-value formulation contracts through 2036.
- Driver: Food manufacturers use tapioca to replace wheat-based thickeners while retaining neutral flavor and stable texture.
- Restraint: Cassava-root price swings and variable starch recovery raise procurement risk for import-dependent processors.
- Opportunity: Organic, clean-label, resistant-starch, and application-specific grades open higher-value formulation routes.
Gluten-Free Reformulation Expands Use
Tapioca gives formulators viscosity without gluten or cereal notes, fitting bakery fillings, sauces, and plant based food formulations. In 2025, the U.S. Food and Drug Administration continued enforcing strict gluten-free labeling thresholds across packaged food products [6]. FMI research indicates that industrial processors adopt tapioca starch when they require a single ingredient to deliver high binding strength while maintaining clean label compliance.
Root Supply Creates Cost Friction
Cassava starch extraction depends directly on root harvest yields, moisture variations, and milling efficiency. When raw root supplies contract, processors face elevated raw material expenses before native starches reach export terminals. In 2026, FAOSTAT agricultural dissemination calendars confirmed periodic harvest contractions across tropical cultivation belts [7]. Procurement teams therefore diversify supply contracts between Southeast Asia and Latin America to mitigate regional shortage risks.
Specialty Grades Open New Margins
Specialty tapioca derivatives deliver freeze-thaw stability, retrogradation resistance, and tailored texture across dairy desserts and confectionery ingredients. During 2025, Ingredion expanded technical solutions targeting clean-label texture and customized food formulations [8]. FMI data suggests that suppliers investing in documented viscosity profiles can secure long-term contracts outside commodity pricing pressures.
Tapioca Market by Country (2026 to 2036)
As per Future Market Insights, the country outlook is strongest in France and Switzerland, where clean-label food formulation and premium specialty products support above-market growth. Australia remains close to the global rate, while Brazil and the UK show steadier expansion tied to domestic root supply and mature packaged-food channels.
Table 7: Country CAGR and Primary Growth Levers for the Tapioca Market, 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary growth lever |
|---|---|---|
| France | 5.9% | Clean-label formulation and gluten-free retail |
| Switzerland | 5.4% | Premium nutrition and specialty food processing |
| Australia | 5.0% | Packaged foods and broad gluten-free shelves |
| USA | 4.6% | Large food-processing base and retail variety |
| Brazil | 4.2% | Domestic cassava supply and regional food uses |
| UK | 3.8% | Mature grocery channels and imported starch use |
France Tapioca Market Outlook (2026 to 2036)
France’s tapioca market is anticipated to advance at 5.9% CAGR over the assessment period, supported by clean-label reformulation across commercial bakery, desserts, sauces, and free-from food preparations. In 2025, Agreste agricultural publications documented national expansions in food processing output that require allergen-safe starches [9]. Industrial formulators favor tapioca because it provides high paste transparency and smooth mouthfeel without altering subtle recipe aromas. However, price competition from domestic wheat and potato starches forces suppliers to supply certified clean-label lots. Importers navigating European food regulations succeed by verifying batch consistency and full origin traceability.
Key takeaway: In France, clean-label culinary standards and gluten-free retail demand compel processors to procure certified, high-viscosity native starches.
Switzerland Tapioca Market Outlook (2026 to 2036)
Premium food and clinical nutrition products shape Swiss tapioca demand more than bulk industrial starch volumes, leading to an estimated 5.4% CAGR through 2036. In 2025, the Swiss Federal Office for Customs and Border Security updated trade statistics recording recurring imports of specialty food preparations [10]. High domestic production costs prevent local processors from competing in low-margin commodity starches. Swiss ingredient distributors therefore prioritize certified organic, non-GMO, and application-tailored tapioca variants. Suppliers with extensive technical documentation capture enduring supply contracts across regional confectionery and infant food lines.
Key takeaway: In Switzerland, premium nutrition and specialty food processing establish recurring demand for certified allergen-free and organic starch grades.
Australia Tapioca Market Outlook (2026 to 2036)
Tapioca demand in Australia is forecast to rise at 5.0% CAGR over the forecast period, driven by packaged retail groceries and expanding foodservice menus. In 2025, the Australian Bureau of Statistics published retail trade data reflecting heightened consumer demand for specialized dietary products [11]. Rapid growth of bubble tea chains and Asian dessert parlors accelerates bulk pearl imports across eastern metropolitan centers. Because domestic cassava cultivation remains negligible, Australian distributors manage significant shipping lead times by stocking dry formats in regional logistics hubs.
Key takeaway: In Australia, packaged foods and expanding Asian culinary channels drive recurring demand for dry, shelf-stable tapioca formats.
USA Tapioca Market Outlook (2026 to 2036)
In the USA, tapioca sales are forecast to expand at 4.6% CAGR through 2036, underpinned by an expansive food manufacturing base and strict FDA gluten-free labeling guidelines. In 2025, U.S. Census Bureau merchandise trade databases confirmed substantial import volumes of prepared starches and root flours [12]. Industrial processors utilize tapioca where its glossy texture and freeze-thaw stability outperform domestic corn starch in refrigerated sauces and fruit fillings. Although high maritime shipping costs present periodic cost friction, large food conglomerates maintain regular purchasing orders for functional native grades.
Key takeaway: In the USA, large-scale industrial food manufacturing and strict gluten-free labeling enforce steady procurement of modified and clean-label tapioca starches.
Brazil Tapioca Market Outlook (2026 to 2036)
Brazil is estimated to post 4.2% CAGR over the forecast period, linked to vast domestic cassava farming and centuries-old culinary traditions. In 2025, the Brazilian Institute of Geography and Statistics (IBGE) reported stable nationwide cassava harvests that provide ample raw material for domestic starch mills [13]. Plentiful local root supplies insulate Brazilian manufacturers from international currency swings and ocean freight spikes. Regional demand is supported by widespread consumption of tapioca crepes, farofa, and industrial food starches, while leading processors modernize processing lines to pursue regional export opportunities.
Key takeaway: In Brazil, domestic cassava root abundance and established culinary consumption anchor recurring commercial demand for regional starch processors.
UK Tapioca Market Outlook (2026 to 2036)
The tapioca market in the UK is anticipated to grow at 3.8% CAGR between 2026 and 2036, supported by supermarket free-from aisles and diverse Asian food formats. In 2025, the UK Office for National Statistics published food retail sales figures showing consistent household spending across allergen-free grocery categories [14]. Food manufacturers utilize tapioca starch in gluten-free bakery lines to prevent crumbly textures without adding synthetic binders. Total import reliance leaves British wholesalers vulnerable to container freight inflation, which distributors mitigate by maintaining multi-month buffer inventories in central distribution warehouses.
Key takeaway: In the UK, mature grocery free-from aisles and international dessert formats sustain predictable import flows of processed tapioca products.
Who are the notable companies in the tapioca market?
Thai Wah Public Company Limited, Ingredion Incorporated, Cargill, Incorporated, ADM, PT Budi Starch & Sweetener Tbk, Roquette Frères, Tereos, and SMS Corporation are notable companies operating in the tapioca market.
An FMI analyst notes that competition in the tapioca sector is moderately fragmented between primary Southeast Asian cassava millers and multinational ingredient conglomerates. Thai and Indonesian processors leverage immediate plantation access to supply cost-competitive native starches and cassava starch derivatives. Conversely, global ingredient corporations compete through advanced technical laboratories, application centers, and multi-starch product lines. Commercial food buyers evaluate vendors based on strict viscosity consistency, microbiological controls, and reliable delivery schedules.
- Integrated cassava processors: Thai Wah, PT Budi Starch & Sweetener, and SMS Corporation connect root sourcing with starch production.
- Global ingredient suppliers: Ingredion, Cargill, ADM, Roquette, and Tereos offer broader formulation and distribution reach.
Competitive Benchmarking: Tapioca Market
Table 8: Competitive Benchmarking for the Tapioca Market, 2026
| Company | Tapioca breadth | Specialty depth | Application support | Geographic reach |
|---|---|---|---|---|
| Thai Wah Public Company Limited | High | High | High | Medium |
| Ingredion Incorporated | High | High | High | High |
| Cargill, Incorporated | High | High | High | High |
| ADM | High | High | High | High |
| PT Budi Starch & Sweetener Tbk | High | Medium | Medium | Medium |
| Roquette Frères | High | High | High | High |
| Tereos | High | High | High | High |
| SMS Corporation | High | Medium | Medium | Medium |
Scoring basis: High indicates broad documented product or regional coverage. Medium indicates a narrower verified range. Low is reserved for a documented limitation. Ratings describe public capability evidence and do not represent market share or product quality.
Key Developments in the Tapioca Market
- In September 2026, Thai Wah reported continued execution of its regional starch and food strategy with cassava-based products remaining part of the portfolio [15].
- In May 2026, Ingredion continued presenting clean-label texture systems for food manufacturers through its official product and investor channels [16].
- In February 2026, PT Budi Starch & Sweetener continued reporting tapioca-starch operations through its corporate disclosure materials [17].
Key Players in the Tapioca Market
Integrated Cassava and Tapioca Processors
- Thai Wah Public Company Limited
- PT Budi Starch & Sweetener Tbk
- SMS Corporation
Diversified Starch and Ingredient Platforms
- Ingredion Incorporated
- Cargill, Incorporated
- ADM
- Roquette Frères
- Tereos
Tapioca Market - Report Scope
Table 9: Report Scope for the Tapioca Market, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type / grade; processing state; end-use application |
| Quantitative units | USD Billion |
| Market definition | Supplier revenue from tapioca pearls, flour, starch, and in-scope processed tapioca formats. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | USA, France, Switzerland, Australia, Brazil, UK, and additional countries |
| Forecast period | 2026 to 2036 |
| Proprietary data | Segment shares and forecast estimates are FMI proprietary analytical estimates. |
In the FMI report, supplier revenue encompasses commercial tapioca derivatives and excludes farm-gate cassava roots not converted into processed starch ingredients.
Tapioca Market - Research Methodology
Table 10: Research Methodology for the Tapioca Market, 2026 edition
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product evaluation, adoption barriers, approval requirements, pricing considerations, and support expectations. |
| Desk Research | Desk research covered government statistics, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, date, geographic coverage, and consistency with the market scope. |
| Market Sizing and Forecasting | The market assessment combined the baseline value with segment structure, pricing and volume indicators, adoption levels, company participation, and country demand conditions. Forecast assumptions considered economic activity, regulation, purchasing cycles, supply availability, and barriers to wider use. |
| Data Validation | Estimates were checked against public data, company activity, trade patterns, industry developments, and primary research findings. Adjacent categories, unsupported claims, overlapping revenues, and activities outside the market boundary were excluded. |
Tapioca Market by Segments
Tapioca Market segmented by Product type / grade:
- Standard commercial grade
- Organic and clean-label variant
- Premium specialty formulation
Tapioca Market segmented by Processing state:
- Fresh / ambient packaged
- Frozen and chilled
- Dehydrated and dry packaged
Tapioca Market segmented by End-use application:
- Direct retail consumer consumption
- Food service and hospitality
- Commercial food manufacturing plants
- Industrial applications
Tapioca Market by Region
- North America
- United States
- Canada.
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Rest of Latin America.
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Switzerland
- Rest of Western Europe.
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- Rest of Eastern Europe.
- East Asia
- China
- Japan
- South Korea.
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific.
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
- Rest of Middle East and Africa.
Research Sources and Bibliography
- [1] Food and Agriculture Organization of the United Nations. (2025, December 31). Crops and livestock products production data update. FAOSTAT.
- [2] Food and Agriculture Organization of the United Nations. (2026). Market and Trade Data Portal. FAO Trade Reports.
- [3] Thai Wah Public Company Limited. (2025). Integrated annual report and tapioca product information. Corporate Disclosures.
- [4] U.S. Department of Agriculture. (2026). Import and trade research databases. USDA Foreign Agricultural Service.
- [5] United Nations Trade and Development. (2026). UNCTAD Data Hub: Merchandise trade indicators. United Nations Publications.
- [6] U.S. Food and Drug Administration. (2025). Gluten-free labeling of foods. Center for Food Safety and Applied Nutrition.
- [7] Food and Agriculture Organization of the United Nations. (2026). Data releases and dissemination calendar. FAO Statistics Division.
- [8] Ingredion Incorporated. (2025). Texture and clean-label ingredient solutions. Commercial Technical Portfolios.
- [9] Agreste. (2025). French agricultural statistics and publications. Ministère de l'Agriculture et de la Souveraineté Alimentaire.
- [10] Swiss Federal Office for Customs and Border Security. (2025). Swiss foreign trade statistics. FOCBS Economic Publications.
- [11] Australian Bureau of Statistics. (2025). Retail trade and manufacturing statistics. ABS Economic Releases.
- [12] U.S. Census Bureau. (2025). USA Trade Online: Merchandise trade records. Department of Commerce.
- [13] Brazilian Institute of Geography and Statistics. (2025). Systematic survey of agricultural production. IBGE Publications.
- [14] UK Office for National Statistics. (2025). Retail sales and food industry statistics. ONS Statistical Releases.
- [15] Thai Wah Public Company Limited. (2026). Corporate news and investor disclosures. Investor Relations.
- [16] Ingredion Incorporated. (2026). Corporate news and investor relations. Press Releases.
- [17] PT Budi Starch & Sweetener Tbk. (2026). Corporate reports and disclosures. Financial Filings.
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the tapioca market in 2026 and by 2036?
- What demand conditions support tapioca use in food processing today?
- Why does standard commercial grade lead product type / grade?
- How does fresh / ambient packaging support tapioca sales?
- Which country shows a notable tapioca growth outlook through 2036?
- Which companies participate in the global tapioca market?
Frequently Asked Questions
How big is the tapioca market in 2026?
Future Market Insights estimates the tapioca market at USD 5.4 billion in 2026, rising from USD 5.2 billion in 2025.
What is the tapioca market CAGR through 2036?
As per FMI, the market is projected to expand at 4.8% CAGR from 2026 to 2036 and reach USD 8.6 billion.
Which product grade leads the tapioca market?
Standard commercial grade is projected to hold 56.0% of product type / grade revenue in 2026, supported by versatile formulation performance.
Which processing state holds a notable 2026 share?
Fresh / ambient packaged tapioca is estimated to represent 42.4% of processing-state revenue in 2026, benefiting from ambient shelf stability.
Which country has a notable growth outlook?
France is projected to record 5.9% CAGR through 2036, supported by clean-label reformulation and gluten-free retail demand.
Who are the notable tapioca market companies?
Notable participants include Thai Wah, Ingredion, Cargill, ADM, PT Budi Starch & Sweetener, Roquette, Tereos, and SMS Corporation.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product type / grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product type / grade, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product type / grade, 2026 to 2036
- Standard commercial grade
- Organic and clean-label variant
- Premium specialty formulation
- Y-o-Y Growth Trend Analysis By Product type / grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Product type / grade, 2026 to 2036
- Global Market Analysis and Forecast, By Processing state, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Processing state, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Processing state, 2026 to 2036
- Fresh / ambient packaged
- Frozen and chilled
- Dehydrated and dry packaged
- Y-o-Y Growth Trend Analysis By Processing state, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing state, 2026 to 2036
- Global Market Analysis and Forecast, By End-use application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-use application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-use application, 2026 to 2036
- Direct retail consumer consumption
- Food service and hospitality
- Commercial food manufacturing plants
- Industrial applications
- Y-o-Y Growth Trend Analysis By End-use application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-use application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada.
- By Product type / grade
- By Processing state
- By End-use application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product type / grade
- By Processing state
- By End-use application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- Rest of Latin America.
- By Product type / grade
- By Processing state
- By End-use application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product type / grade
- By Processing state
- By End-use application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Switzerland
- Rest of Western Europe.
- By Product type / grade
- By Processing state
- By End-use application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product type / grade
- By Processing state
- By End-use application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- Rest of Eastern Europe.
- By Product type / grade
- By Processing state
- By End-use application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product type / grade
- By Processing state
- By End-use application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea.
- By Product type / grade
- By Processing state
- By End-use application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product type / grade
- By Processing state
- By End-use application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific.
- By Product type / grade
- By Processing state
- By End-use application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product type / grade
- By Processing state
- By End-use application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- Rest of Middle East and Africa.
- By Product type / grade
- By Processing state
- By End-use application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product type / grade
- By Processing state
- By End-use application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type / grade
- By Processing state
- By End-use application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type / grade
- By Processing state
- By End-use application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type / grade
- By Processing state
- By End-use application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type / grade
- By Processing state
- By End-use application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type / grade
- By Processing state
- By End-use application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type / grade
- By Processing state
- By End-use application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type / grade
- By Processing state
- By End-use application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type / grade
- By Processing state
- By End-use application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type / grade
- By Processing state
- By End-use application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type / grade
- By Processing state
- By End-use application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type / grade
- By Processing state
- By End-use application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type / grade
- By Processing state
- By End-use application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type / grade
- By Processing state
- By End-use application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type / grade
- By Processing state
- By End-use application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type / grade
- By Processing state
- By End-use application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type / grade
- By Processing state
- By End-use application
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type / grade
- By Processing state
- By End-use application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type / grade
- By Processing state
- By End-use application
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type / grade
- By Processing state
- By End-use application
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type / grade
- By Processing state
- By End-use application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product type / grade
- By Processing state
- By End-use application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Thai Wah Public Company Limited
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Ingredion Incorporated
- Cargill, Incorporated
- ADM
- PT Budi Starch & Sweetener Tbk
- Roquette Frères
- Tereos
- SMS Corporation
- Thai Wah Public Company Limited
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


