
- Market Size (2026)
- USD 596.8 Mn
- Forecast (2036)
- USD 1048.7 Mn
- CAGR (2026 to 2036)
- 5.8%
How big is Travel Intermediaries Business Market in 2026?
The global travel intermediaries business market is estimated at USD 564.1 million in 2025 and is expected to reach USD 596.8 million in 2026. Over 2026 to 2036, sales of intermediary travel services are likely to grow at a CAGR of 5.8% and reach USD 1,048.7 million. Vacation packages will hold the largest share of service type sales in 2026, at 41.6%, as per FMI analysis.
Growth of the travel intermediaries business market rests on two shifts, more people flying and more trips planned with AI tools. The first shift is visible in airline traffic, with passenger numbers, counted by flight segment, forecast to rise from 4,967 million in 2025 to 5,085 million in 2026 [1]. In turn, agents and platforms have a larger pool of trips to package and sell. Sales of agency services also benefit from the large volume of airline sales, as airlines processed USD 1.05 trillion in sales in 2025 at a payment cost of USD 24.5 billion [2]. Adoption of AI trip planning is the second shift, led by the largest platforms. For instance, Booking Holdings announced a planned USD 100 million investment in Vayo, a personal travel agent, on October 14, 2026 [3]. FMI analysis expects AI planning to move more itinerary work onto intermediary platforms and raise service value per trip.
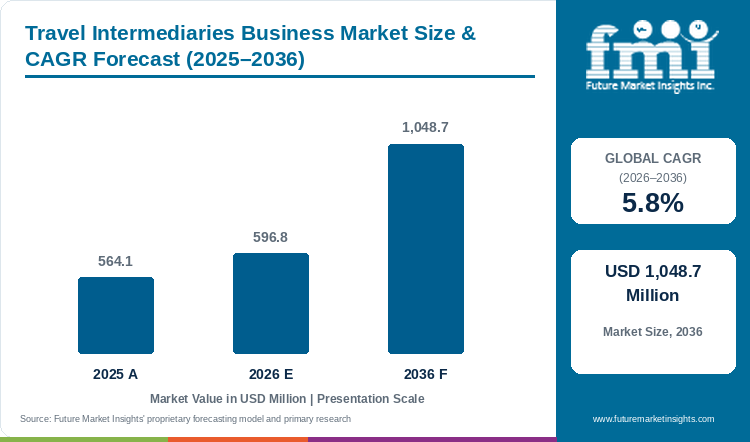
Table 1: Travel Intermediaries Business Market Size and Forecast (USD million), 2025 to 2036
| Market size and forecast | Value |
|---|---|
| 2025 market size | USD 564.1 million |
| Estimated market size in 2026 | USD 596.8 million |
| Projected market size by 2036 | USD 1,048.7 million |
| CAGR (2026 to 2036) | 5.8% |
| Added sales, 2026 to 2036 | USD 451.9 million |
Key Market Trends & Insights
- By service type: Vacation packages will hold 41.6% of 2026 sales, given that bundled flights, hotels and transfers carry the highest service margin for agents.
- By mode of transport: Air bookings account for an estimated 63.5% of 2026 sales, as flights remain the main item in most intermediated trips.
- By mode of booking: Online channels are expected to hold 58.4% of 2026 sales, since apps and booking sites now handle search, comparison and payment in one flow.
Regional Highlights
- Fastest-growing country: The United States is expected to grow fastest, at a CAGR of 6.1% between 2026 and 2036, as AI booking tools and large outbound travel volumes widen platform reach.
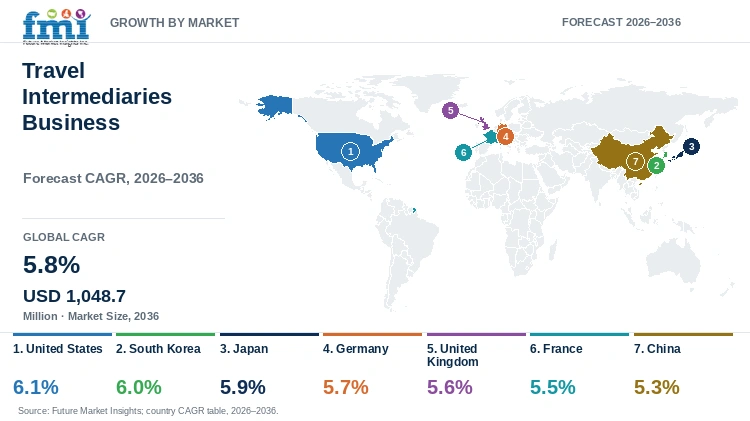
- Growth across other countries: South Korea is set to grow at 6%, as travellers book trips abroad on mobile apps, and Japan at 5.9%, with support from group tours. Germany is next at 5.7%, as travellers value the legal protection of package holidays, slightly ahead of the United Kingdom at 5.6% and France at 5.5%. China has the lowest rate at 5.3%, as tighter platform regulation slows commission growth.
Growth of the travel intermediaries business market depends on air capacity and on the distribution systems that agents use. Amadeus reported 238.0 million Air Distribution bookings in the first half of 2026, a decline of 3.7% [4]. Lower booking counts through global distribution systems show that some airline sales are moving to direct and new channels. At the same time, distribution networks are adding fares from more airlines. Wizz Air content is to become available on the Amadeus Travel Platform for the first time, through the Amadeus Ticketless Access solution [5]. Once low-cost fares appear in agency systems, intermediaries have more flights to sell, which makes agents more useful to travellers.
Trips booked through agents and platforms are growing at different speeds, depending on the type of product. Net revenue at Trip.com Group came to USD 2.3 billion in the second quarter of 2026, 6% higher than a year earlier [6]. Packaged-tour revenue rose 8% to USD 171 million, and corporate travel revenue grew 11% to USD 114 million. Consequently, packaged and business travel are outpacing ticketing, which favours intermediaries with tour and corporate desks. Advertising is a further income line, and Booking Holdings unified Booking.com, Priceline and Agoda ads under BKNG Ads in May 2026 [7]. Income from advertising helps platforms afford lower commissions, which puts pressure on smaller agents.
New airline retailing standards are changing how intermediaries sell tickets. IATA said seven airlines are using or implementing the new Orders standard for airline bookings, with more than 20 expected to follow from 2027 [8]. Under the new standard, agents receive and manage airline bookings in a different format, so agency systems will need upgrades. Meanwhile, regulators are watching dominant platforms more closely. Trip.com Group accepted an administrative penalty decision from the State Administration for Market Regulation of China in July 2026 [9]. Closer oversight of large platforms can open room for smaller agents and supplier-direct channels.
Table 2: Supporting Industry Indicators for the Travel Intermediaries Business Market, 2025 to 2026
| Indicator | Data point | Why it matters | Source |
|---|---|---|---|
| Airline passengers | 4,967 million segment passengers in 2025, rising to 5,085 million in 2026. | More passengers enlarge the trip pool for intermediaries. | [1] |
| Airline revenues | Airline industry revenues forecast at USD 1,165 billion for 2026. | Airline sales are the largest product sold through agents. | [1] |
| Payment volume | Airlines processed USD 1.05 trillion in sales in 2025, at USD 24.5 billion in payment costs. | Payment costs shape agency settlement and card policy. | [2] |
| Card fees | Average card payment fees of 2.53% for airlines in 2025. | Card costs influence how agents are paid and charged. | [2] |
| Airline retailing | Seven airlines live or implementing Orders, with more than 20 expected from 2027. | Agents need new systems to sell order-based content. | [8] |
| Distribution results | Amadeus first half 2026 revenue of EUR 3,334.9 million, up 5.1% at constant currency. | Distribution suppliers still grow despite lower bookings. | [4] |
| Agency air bookings | Amadeus Air Distribution bookings of 238.0 million in the first half of 2026, down 3.7%. | Some airline sales are moving away from agency channels. | [4] |
| New content | Wizz Air content announced for the Amadeus Travel Platform in October 2026. | Low-cost carrier content widens agency inventory. | [5] |
| Platform results | Trip.com Group second quarter 2026 net revenue of USD 2.3 billion, up 6%. | Large platforms show steady demand for intermediated travel. | [6] |
| Platform regulation | Trip.com Group accepted a SAMR administrative penalty decision in July 2026. | Oversight of dominant platforms can reshape commissions. | [9] |
| AI trip planning | Booking Holdings planned a USD 100 million investment in Vayo, announced October 2026. | AI agents may capture more trip planning value. | [3] |
Demand Intensity Analysis
Airline passenger counts give the broadest volume benchmark for intermediary demand. IATA estimated 4,967 million segment passengers in 2025 [1]. Spread over those passengers, the 2025 market estimate of USD 564.1 million works out to about USD 0.114 of intermediary income per traveller. The air segment, at 63.5% of 2026 sales or about USD 379.0 million, equals some USD 0.075 per forecast 2026 passenger. The low ratio shows that the market covers intermediary service fees only, and the gross value of tickets sold stays outside the estimate.
Airline sales give a value benchmark with a similar result. Airlines processed USD 1.05 trillion in sales in 2025 [2]. The 2025 market estimate equals about 0.054% of that sales pool. Agents earn fees on only part of airline sales, and many tickets are sold direct, so the ratio is small by design. Even modest gains in service fees per booking would therefore move the market more than passenger growth alone.
Prices of packaged and managed trips matter as much as volume, and a comparison of growth rates shows how much of the outlook depends on price. IATA forecasts passengers rising from 4,967 million in 2025 to 5,085 million in 2026, a gain of about 2.4% [1]. The 5.8% CAGR implies annual price and mix gains of about 3.3% above that passenger growth. Packages and corporate travel carry higher fees than single tickets, so the outlook assumes a steady shift toward bundled and managed trips.
Companies at the top of the travel intermediaries business market report revenues that put the estimate in context. Trip.com Group alone earned net revenue of USD 2.3 billion in a single quarter in mid-2026 [6]. One quarter at a single platform is therefore about 3.9 times the 2026 market estimate. Platform revenue includes hotel commissions, advertising and merchant margins, which fall outside the market definition of intermediary service fees. Amadeus Air Distribution revenue of EUR 1,584.7 million on 238.0 million bookings gives about EUR 6.66 per booking in the first half of 2026 [4]. Fee levels of that size per transaction indicate how thin intermediary service charges remain.
Table 3: Demand Intensity Metrics for the Travel Intermediaries Business Market, 2025 and 2026 Data Against 2025 and 2026 Market Values
| Demand intensity metric | Value | Basis |
|---|---|---|
| Airline segment passengers, 2025 | 4,967 million | International Air Transport Association, June 2026 fact sheet |
| Airline segment passengers, 2026 forecast | 5,085 million | International Air Transport Association, June 2026 fact sheet |
| Sales per airline passenger, 2025 | USD 0.114 | Calculated from IATA 2025 passengers and the 2025 market value |
| Air segment sales per passenger, 2026 | USD 0.075 | Calculated from IATA 2026 passengers and the 63.5% air share of the 2026 market value |
| Airline sales processed, 2025 | USD 1.05 trillion | International Air Transport Association, payments data |
| 2025 market value as a share of airline sales | 0.054% | Calculated from IATA airline sales and the 2025 market value |
| Implied annual price and mix growth | About 3.3% | Calculated from the 5.8% CAGR and 2.4% passenger growth |
| Trip.com Group second quarter 2026 net revenue | USD 2.3 billion | Trip.com Group, September 2026 results |
| Trip.com quarterly revenue as a multiple of the 2026 market value | 3.9 times | Calculated from Trip.com results and the 2026 market value |
| Amadeus Air Distribution revenue per booking, first half 2026 | EUR 6.66 | Calculated from Amadeus Air Distribution revenue and bookings |
Analyst Perspective
“Travel intermediaries are moving from selling tickets to running whole trips, and AI planning tools will speed that shift. Agents that package flights, stays and services and handle disruption will keep earning fees, though plain ticket resale will shrink. Airline order systems and platform regulation will decide who controls the customer relationship over the next decade.”
- Ronak Shah, Principal Consultant, Future Market Insights.
How is the travel intermediaries business market segmented?
The market is segmented into service type, mode of transport, mode of booking, and region. Vacation packages are expected to lead service type with 41.6% share in 2026, and air leads mode of transport with an estimated 63.5%.
By service type: vacation packages, travel, and accommodation.
By mode of transport: air and others.
By mode of booking: online, offline, and direct.
By region: travel bookings sold in North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa, each with a distinct agency mix.
Why do vacation packages lead the travel intermediaries business market by service type?
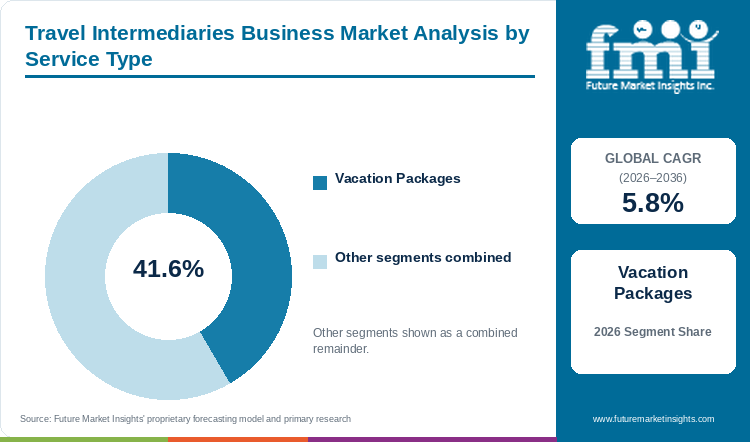
Vacation packages are expected to lead service type sales with 41.6% share in 2026, ahead of travel services at an estimated 34.2% and accommodation near 24.2%.
Table 4: Service Type Share for the Travel Intermediaries Business Market (percentage share), 2026
| Service Type | Estimated Share (2026) |
|---|---|
| Vacation Packages | 41.6% |
| Travel | 34.2% |
| Accommodation | 24.2% |
| Total | 100.0% |
Table 5: Service Type Leadership and Market Growth for the Travel Intermediaries Business Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.8% |
| Leading Segment | Vacation Packages |
Vacation packages are expected to hold 41.6% in 2026, as bundling flights, hotels and transfers gives agents a margin that single tickets rarely offer. Travel services, at an estimated 34.2%, cover air, rail and ground ticketing with lower fees per sale. Accommodation, near 24.2%, earns commissions on hotel and rental bookings but faces direct competition from hotel brands. Packages also protect travellers under package travel rules, which builds trust in agents. Packages are expected to keep the lead through 2036, with accommodation gaining as alternative stays grow.
- Beach holidays, city breaks, cruises with flights and guided tours make up the vacation package segment.
- Packaged travel is growing at large platforms, and Trip.com Group reported packaged-tour revenue of USD 171 million in the second quarter of 2026, up 8% [6]. Package revenue growing faster than ticketing confirms that travellers prefer bundled trips.
Why does air lead the travel intermediaries business market by mode of transport?
Air is estimated to lead mode of transport sales with 63.5% share in 2026, ahead of other modes at about 36.5%.
Table 6: Mode of Transport Share for the Travel Intermediaries Business Market (percentage share), 2026
| Mode of Transport | Estimated Share (2026) |
|---|---|
| Air | 63.5% |
| Others | 36.5% |
| Total | 100.0% |
Air is estimated at 63.5% of 2026 sales, as flights are the most complex and highest-value item in an intermediated trip. Supply of rail, coach, ferry and car rental add-ons makes up the other modes, at about 36.5%. Airline retailing is changing fast, though, as carriers push direct and order-based sales. Agents that update booking systems for new airline sales formats will help air keep the lead. Meanwhile, the travel agency services market is projected to grow at a 10.4% CAGR from 2026 to 2036. Air is likely to hold about two thirds of sales through the forecast period.
- Scheduled flights, low-cost carrier fares and charter seats make up the air segment.
- Airline payment costs shape how agents sell, and IATA put average card payment fees for airlines at 2.53% in 2025 [2]. Card costs at that level push airlines to steer agents toward cheaper settlement methods.
Why do online channels lead the travel intermediaries business market by mode of booking?
Online channels are expected to lead mode of booking sales with 58.4% share in 2026, ahead of offline agencies at about 27.3% and direct bookings near 14.3%.
Table 7: Mode of Booking Share for the Travel Intermediaries Business Market (percentage share), 2026
| Mode of Booking | Estimated Share (2026) |
|---|---|
| Online | 58.4% |
| Offline | 27.3% |
| Direct | 14.3% |
| Total | 100.0% |
Online channels are expected to hold 58.4% of 2026 sales, as apps and booking sites let travellers search, compare and pay in one flow. Buyer preference for human advice keeps offline agencies at about 27.3%, with a strong base in complex, group and senior travel. Direct bookings handled by intermediaries on behalf of suppliers hold near 14.3%. Online share keeps rising as AI assistants plan trips inside apps. Accordingly, FMI expects online channels to widen the lead, with offline agents focusing on high-touch trips.
- Online travel agencies, metasearch-linked booking sites and mobile travel apps make up the online channel.
- Platforms are building AI booking tools, and Booking Holdings launched Vayo in private beta in October 2026, with a planned USD 100 million investment [3]. AI agents of this kind keep more trip planning inside online channels.
What are the drivers, restraints, and opportunities in the travel intermediaries business market?
Growing passenger numbers and complex multi-product trips keep travellers using intermediaries. Direct airline and hotel sales squeeze agent fees, and AI planning tools and corporate travel open new demand.
- Driver: Travellers book more complex trips that combine flights, stays and activities, and intermediaries simplify comparison, payment and support.
- Restraint: Airlines and hotel chains push direct booking with loyalty perks, which reduces the commissions available to agents.
- Opportunity: AI trip planning and managed corporate travel let intermediaries charge for service and disruption handling.
Complex Trips Keep Travellers With Intermediaries
More complex trips are the main reason travellers keep paying for intermediary services. IATA forecasts 5,085 million airline segment passengers in 2026, up from 4,967 million in 2025 [1]. More travellers combine flights with stays and activities, which raises the value of packaged booking. As a result, intermediaries that bundle and support whole trips will keep winning volume through 2036.
Direct Booking Squeezes Agent Fees
Supply of airline seats through direct channels remains the main brake on intermediary growth. Amadeus Air Distribution bookings fell 3.7% to 238.0 million in the first half of 2026 [4]. Lower agency air bookings show that airlines are steering more sales to direct channels. Consequently, agents relying on ticket resale face fee pressure, and service-based pricing becomes necessary.
AI Planning and Corporate Travel Open New Demand
AI trip planning and managed business travel give intermediaries new services to sell. Trip.com Group reported corporate travel revenue growth of 11% in the second quarter of 2026 [6]. Managed business trips carry service fees and duty-of-care tasks that direct channels rarely offer. Agency markets in individual countries are also growing fast, with the UK travel agency services market projected to grow at a 10.9% CAGR from 2026 to 2036. Intermediaries that combine AI planning with corporate service will therefore capture the strongest growth.
Which country CAGRs are profiled in the travel intermediaries business market?
Table 8: Country CAGR Comparison for the Travel Intermediaries Business Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| United States | 6.1% |
| South Korea | 6% |
| Japan | 5.9% |
| Germany | 5.7% |
| United Kingdom | 5.6% |
| France | 5.5% |
| China | 5.3% |
How do country-level CAGRs compare in the travel intermediaries business market?
FMI places the United States at the top with a 6.1% CAGR, 0.3 points above the 5.8% global rate, as large platforms invest in AI booking tools. South Korea (6%) and Japan (5.9%) also run slightly ahead of the global pace on strong outbound travel. German package travel runs close to the average at 5.7%. The United Kingdom (5.6%), France (5.5%) and China (5.3%) grow below the global rate, as mature package markets and platform regulation slow fee growth. North American agency demand stays strong, with the USA travel agency services market projected to grow at a 7.2% CAGR from 2025 to 2035.
- In the United States, AI booking tools and many large online platforms raise the value of intermediary services on each trip.
- South Korea combines high outbound travel with mobile-first booking, so app-based agents gain volume quickly.
- In Japan, packaged tours and group travel keep offline and online agents relevant to senior travellers.
- German travellers rely on package holidays with legal protection, which supports established tour operators.
- The United Kingdom has a mature package holiday market, and low-cost carrier content in agency systems widens choice.
- France pairs strong domestic tourism with direct hotel booking, so agent fees grow slowly.
- Platform regulation in China raises compliance costs for the largest intermediaries and slows commission growth.
Full report country CAGRs cover: intermediary growth for the United States, South Korea, Japan, Germany, the United Kingdom, France and China, between 6.1% and 5.3%, with other standard countries in regional tables.
Country-wise Analysis
United States Travel Intermediaries Business Market Outlook (2026 to 2036)
The United States hosts the largest online travel platforms, and investment in AI agents is rising. Booking Holdings announced a planned USD 100 million investment in Vayo, a personal travel agent, in October 2026 [3]. AI agents can handle planning and rebooking, which raises intermediary value per trip. FMI expects American intermediary income to rise at a 6.1% CAGR, ahead of every other profiled market.
Key takeaway: In the United States, travellers will lean more on AI planning tools from large platforms, which lets intermediaries earn more from each trip arranged.
South Korea Travel Intermediaries Business Market Outlook (2026 to 2036)
South Koreans take many trips abroad for the size of the population, and most book travel on mobile phones. Popularity of concert tours and short-haul trips across Asia keeps app-based agents busy. Korean app-based agents are therefore likely to grow at a 6% CAGR.
Key takeaway: Korean travellers book short trips abroad by phone, so app-based agents will win most of the new bookings in South Korea.
Japan Travel Intermediaries Business Market Outlook (2026 to 2036)
Older Japanese travellers still book through agents, which keeps the packaged tour business large. Use of group travel arrangements is also rising as inbound and outbound travel recovers. With steady demand from group tours and senior travellers, Japanese agency income is expected to grow 5.9% a year to 2036.
Key takeaway: Older Japanese travellers still prefer group and packaged tours, so agents that sell these trips will keep steady business in Japan.
Germany Travel Intermediaries Business Market Outlook (2026 to 2036)
Consumer preference for package holidays keeps Germany among the largest package markets in Europe. Consumer preference for legally protected packages keeps tour operators and agents central to holiday sales. German tour operator and agency sales are set to rise at a 5.7% CAGR.
Key takeaway: German holidaymakers buy package trips for the legal protection those trips carry, so tour operators and travel agents remain the main sellers of holidays in Germany.
United Kingdom Travel Intermediaries Business Market Outlook (2026 to 2036)
The United Kingdom has a mature agency sector and a strong low-cost airline base. Wizz Air content is to become available on the Amadeus Travel Platform for the first time [5]. Wider low-cost content in agency systems helps agents compete with direct airline sites. FMI sees British intermediary income growing at a 5.6% CAGR.
Key takeaway: British agents can now offer more low-cost airline fares through agency booking systems, which helps agents compete with airline websites for holiday sales.
France Travel Intermediaries Business Market Outlook (2026 to 2036)
France has strong domestic tourism and many independent hotels that sell direct. Agents grow mainly through packages and outbound trips. Agency sales in France are likely to grow at a 5.5% CAGR as hotels push direct booking.
Key takeaway: Many French hotels sell rooms directly to guests, so agents in France will grow mainly by selling packages and trips abroad.
China Travel Intermediaries Business Market Outlook (2026 to 2036)
Regulators in China are reviewing large online travel platforms more closely. Trip.com Group accepted an administrative penalty decision from SAMR in July 2026 and said rectification measures would follow [9]. Tighter oversight can limit commission growth for the largest platforms. FMI expects Chinese intermediary income to rise at a 5.3% CAGR, the lowest rate in the profile.
Key takeaway: In China, closer regulation of the largest travel platforms is likely to slow commission growth, even as people keep booking trips online.
Who are the notable companies in the travel intermediaries business market?
The profiled online platforms are Booking Holdings, Expedia Group, Trip.com Group, Airbnb and Traveloka. Distribution systems Amadeus IT Group and Sabre Corporation are also covered, along with Google Travel, Hopper and Corporate Travel Management.
Online travel platforms, distribution technology providers and specialist agencies compete for traveller and supplier relationships. Scale matters most in online booking, and Booking Holdings now sells advertising across Booking.com, Priceline and Agoda under one brand [7]. Unified advertising adds income beyond commissions, which strengthens large platforms against smaller agents. Amadeus and Sabre supply the systems that agents use, and FMI views the range of airline and hotel fares on offer as the main advantage for distribution providers. Hopper, Traveloka and Corporate Travel Management compete on mobile booking, regional reach and managed travel.
- Online travel platforms: Booking Holdings, Expedia Group, Trip.com Group, Airbnb and Traveloka.
- Distribution technology providers: Amadeus IT Group and Sabre Corporation.
- Search and specialist agencies: Google Travel, Hopper and Corporate Travel Management.
Competitive Benchmarking: Travel Intermediaries Business Market
Table 9: Competitive Benchmarking for the Travel Intermediaries Business Market (qualitative ratings), 2026
| Company | Package and Stay Breadth | Air Distribution | AI and Mobile Tools | Recent Activity |
|---|---|---|---|---|
| Booking Holdings | High | Medium | High | High |
| Expedia Group | High | Medium | High | Medium |
| Trip.com Group | High | High | Medium | High |
| Amadeus IT Group | Medium | High | Medium | High |
| Sabre Corporation | Low | High | Medium | Low |
| Corporate Travel Management | Medium | Medium | Low | Low |
Ratings compare the companies on package and stay breadth, air distribution, AI and mobile tools and recent activity.
Key Developments in the Travel Intermediaries Business Market
- Booking Holdings unveiled Vayo in October 2026 with a planned USD 100 million investment, a step toward AI-run trip planning [3].
- On October 22, 2026, Amadeus announced that Wizz Air content will become available on the Amadeus Travel Platform, widening low-cost inventory for agents [5].
- Trip.com Group grew second quarter 2026 net revenue 6% to USD 2.3 billion, with the international platform up more than 50% [6].
- Amadeus posted first half 2026 revenue of EUR 3,334.9 million in July 2026 even as air bookings fell 3.7%, showing a shift toward hospitality and other solutions [4].
- IATA reported in October 2026 that seven airlines are live or implementing Orders, with more than 20 expected to follow from 2027 [8].
- In July 2026, Trip.com Group accepted a SAMR penalty decision, signalling closer oversight of dominant travel platforms [9].
- Booking.com, Priceline and Agoda advertising was brought together under BKNG Ads in May 2026, adding a non-commission income line [7].
Key Players in the Travel Intermediaries Business Market
Online Travel Platforms
- Booking Holdings
- Expedia Group
- Trip.com Group
- Airbnb
- Traveloka
Distribution Technology Providers
- Amadeus IT Group
- Sabre Corporation
Search and Specialist Agencies
- Google Travel
- Hopper
- Corporate Travel Management
Travel Intermediaries Business Market - Report Scope
Table 10: Report Scope for the Travel Intermediaries Business Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Service type; mode of transport; mode of booking; region |
| Quantitative units | USD million |
| Market definition | Service income earned by agencies, online platforms and distribution intermediaries for arranging vacation packages, travel tickets and accommodation. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | Booking Holdings, Expedia Group, Amadeus IT Group, Sabre Corporation, Trip.com Group, Google Travel, Hopper, Airbnb, Traveloka, Corporate Travel Management |
| Forecast period | 2026 to 2036 |
Travel Intermediaries Business Market - Research Methodology
Table 11: Research Methodology for the Travel Intermediaries Business Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Company results, industry associations, government statistics and trade publications. |
| Desk Research | Passenger traffic, airline retailing, booking channels, platform regulation and AI trip planning. |
| Market Sizing | Sizing combines booking volumes, service fees and channel mix across service types and regions. |
| Data Validation | Figures are cross-checked across company, industry and government sources. |
Travel Intermediaries Business Market by Segments
Travel Intermediaries Business Market segmented by Service Type:
- Vacation Packages
- Travel
- Accommodation
Travel Intermediaries Business Market segmented by Mode of Transport:
- Air
- Others
Travel Intermediaries Business Market segmented by Mode of Booking:
- Online
- Offline
- Direct
Travel Intermediaries Business Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] International Air Transport Association. (2026, June). Economics Fact Sheet - Industry Statistics. https://www.iata.org/en/iata-repository/pressroom/fact-sheets/industry-statistics/
- [2] International Air Transport Association. (2026, October 27). Payments Cost Airlines $24.5bn in 2025. https://www.iata.org/en/pressroom/2026-releases/10-27-payments-cost-airlines/
- [3] Booking Holdings Inc. (2026, October 14). Booking Holdings Launches Vayo with Planned $100M Investment. https://www.bookingholdings.com/press-releases/booking-holdings-launches-vayo-with-planned-100m-investment/
- [4] Amadeus IT Group. (2026, July 31). Amadeus delivers resilient H1 2026 performance despite challenging operating environment. https://amadeus.com/en/newsroom/press-releases/amadeus-h1-2026-resilient-performance
- [5] Amadeus IT Group. (2026, October 22). Wizz Air content to become available on the Amadeus Travel Platform for the first time. https://amadeus.com/en/newsroom/press-releases/wizz-air-become-available-amadeus-travel-platform
- [6] Trip.com Group Limited. (2026, September 15). Trip.com Group Limited Reports Unaudited Second Quarter and First Half of 2026 Financial Results. https://investors.trip.com/news-releases/news-release-details/tripcom-group-limited-reports-unaudited-second-quarter-and-4
- [7] Booking Holdings Inc. (2026, May 21). Booking Holdings Unifies Global Advertising Solutions with Introduction of BKNG Ads. https://www.bookingholdings.com/press-releases/booking-holdings-unifies-global-advertising-solutions-with-introduction-of-bkng-ads/
- [8] International Air Transport Association. (2026, October 28). IATA Highlights Priorities to Create Value from Digitalization. https://www.iata.org/en/pressroom/2026-releases/10-28-iata-highlights-priorities-create-value-digitalization/
- [9] Trip.com Group Limited. (2026, July 25). Trip.com Group Sincerely Accepts Administrative Penalty Decision Issued by the State Administration for Market Regulation of the People's Republic of China. https://investors.trip.com/news-releases/news-release-details/tripcom-group-sincerely-accepts-administrative-penalty-decision
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the travel intermediaries business market during 2026?
- What market size is projected by 2036?
- Which service type holds notable share?
- Which mode of booking holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Service Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Service Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Service Type, 2026 to 2036
- Vacation Packages
- Travel
- Accommodation
- Y-o-Y Growth Trend Analysis By Service Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Service Type, 2026 to 2036
- Global Market Analysis and Forecast, By Mode of Transport, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Mode of Transport, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Mode of Transport, 2026 to 2036
- Air
- Others
- Y-o-Y Growth Trend Analysis By Mode of Transport, 2021 to 2025
- Absolute $ Opportunity Analysis By Mode of Transport, 2026 to 2036
- Global Market Analysis and Forecast, By Mode of Booking, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Mode of Booking, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Mode of Booking, 2026 to 2036
- Online
- Offline
- Direct
- Y-o-Y Growth Trend Analysis By Mode of Booking, 2021 to 2025
- Absolute $ Opportunity Analysis By Mode of Booking, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Service Type
- By Mode of Transport
- By Mode of Booking
- By Country
- Market Attractiveness Analysis
- By Country
- By Service Type
- By Mode of Transport
- By Mode of Booking
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Service Type
- By Mode of Transport
- By Mode of Booking
- By Country
- Market Attractiveness Analysis
- By Country
- By Service Type
- By Mode of Transport
- By Mode of Booking
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Service Type
- By Mode of Transport
- By Mode of Booking
- By Country
- Market Attractiveness Analysis
- By Country
- By Service Type
- By Mode of Transport
- By Mode of Booking
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Service Type
- By Mode of Transport
- By Mode of Booking
- By Country
- Market Attractiveness Analysis
- By Country
- By Service Type
- By Mode of Transport
- By Mode of Booking
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Service Type
- By Mode of Transport
- By Mode of Booking
- By Country
- Market Attractiveness Analysis
- By Country
- By Service Type
- By Mode of Transport
- By Mode of Booking
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Service Type
- By Mode of Transport
- By Mode of Booking
- By Country
- Market Attractiveness Analysis
- By Country
- By Service Type
- By Mode of Transport
- By Mode of Booking
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Service Type
- By Mode of Transport
- By Mode of Booking
- By Country
- Market Attractiveness Analysis
- By Country
- By Service Type
- By Mode of Transport
- By Mode of Booking
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Mode of Transport
- By Mode of Booking
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Mode of Transport
- By Mode of Booking
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Mode of Transport
- By Mode of Booking
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Mode of Transport
- By Mode of Booking
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Mode of Transport
- By Mode of Booking
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Mode of Transport
- By Mode of Booking
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Mode of Transport
- By Mode of Booking
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Mode of Transport
- By Mode of Booking
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Mode of Transport
- By Mode of Booking
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Mode of Transport
- By Mode of Booking
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Mode of Transport
- By Mode of Booking
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Mode of Transport
- By Mode of Booking
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Mode of Transport
- By Mode of Booking
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Mode of Transport
- By Mode of Booking
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Mode of Transport
- By Mode of Booking
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Mode of Transport
- By Mode of Booking
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Mode of Transport
- By Mode of Booking
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Mode of Transport
- By Mode of Booking
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Mode of Transport
- By Mode of Booking
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Mode of Transport
- By Mode of Booking
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Service Type
- By Mode of Transport
- By Mode of Booking
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Booking Holdings
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Expedia Group
- Trip.com Group
- Amadeus IT Group
- Sabre Corporation
- Corporate Travel Management
- Airbnb
- Traveloka
- Google Travel
- Hopper
- Booking Holdings
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Service Type, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Mode of Transport, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by Mode of Booking, 2021 to 2036
- Table 5: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Million) Forecast by Service Type, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Mode of Transport, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by Mode of Booking, 2021 to 2036
- Table 9: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Million) Forecast by Service Type, 2021 to 2036
- Table 11: Latin America Market Value (USD Million) Forecast by Mode of Transport, 2021 to 2036
- Table 12: Latin America Market Value (USD Million) Forecast by Mode of Booking, 2021 to 2036
- Table 13: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Million) Forecast by Service Type, 2021 to 2036
- Table 15: Western Europe Market Value (USD Million) Forecast by Mode of Transport, 2021 to 2036
- Table 16: Western Europe Market Value (USD Million) Forecast by Mode of Booking, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Million) Forecast by Service Type, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Million) Forecast by Mode of Transport, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Million) Forecast by Mode of Booking, 2021 to 2036
- Table 21: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Million) Forecast by Service Type, 2021 to 2036
- Table 23: East Asia Market Value (USD Million) Forecast by Mode of Transport, 2021 to 2036
- Table 24: East Asia Market Value (USD Million) Forecast by Mode of Booking, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Million) Forecast by Service Type, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Million) Forecast by Mode of Transport, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Million) Forecast by Mode of Booking, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Million) Forecast by Service Type, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Million) Forecast by Mode of Transport, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Million) Forecast by Mode of Booking, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Service Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Service Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Service Type
- Figure 6: Global Market Value Share and BPS Analysis by Mode of Transport, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Mode of Transport, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Mode of Transport
- Figure 9: Global Market Value Share and BPS Analysis by Mode of Booking, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Mode of Booking, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Mode of Booking
- Figure 12: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Service Type, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Service Type, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Service Type
- Figure 26: North America Market Value Share and BPS Analysis by Mode of Transport, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Mode of Transport, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Mode of Transport
- Figure 29: North America Market Value Share and BPS Analysis by Mode of Booking, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Mode of Booking, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Mode of Booking
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Service Type, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Service Type, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Service Type
- Figure 36: Latin America Market Value Share and BPS Analysis by Mode of Transport, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Mode of Transport, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Mode of Transport
- Figure 39: Latin America Market Value Share and BPS Analysis by Mode of Booking, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Mode of Booking, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Mode of Booking
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Service Type, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Service Type, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Service Type
- Figure 46: Western Europe Market Value Share and BPS Analysis by Mode of Transport, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Mode of Transport, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Mode of Transport
- Figure 49: Western Europe Market Value Share and BPS Analysis by Mode of Booking, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Mode of Booking, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Mode of Booking
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Service Type, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Service Type, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Service Type
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Mode of Transport, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Mode of Transport, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Mode of Transport
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Mode of Booking, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Mode of Booking, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Mode of Booking
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Service Type, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Service Type, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Service Type
- Figure 66: East Asia Market Value Share and BPS Analysis by Mode of Transport, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Mode of Transport, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Mode of Transport
- Figure 69: East Asia Market Value Share and BPS Analysis by Mode of Booking, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Mode of Booking, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Mode of Booking
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Service Type, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Service Type, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Service Type
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Mode of Transport, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Mode of Transport, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Mode of Transport
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Mode of Booking, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Mode of Booking, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Mode of Booking
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Service Type, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Service Type, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Service Type
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Mode of Transport, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Mode of Transport, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Mode of Transport
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by Mode of Booking, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by Mode of Booking, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by Mode of Booking
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the travel intermediaries business market expected in 2026?
Intermediary service income in the travel intermediaries business market is estimated by FMI to reach USD 596.8 million in 2026, up from USD 564.1 million in 2025, as passenger numbers grow.
What CAGR is projected for the travel intermediaries business market through 2036?
Between 2026 and 2036, intermediary travel services are projected to grow at a 5.8% CAGR to USD 1,048.7 million, since packaged and managed trips carry higher service fees.
Which service type holds a notable market share in 2026?
Vacation packages are expected to hold 41.6% of 2026 sales, given that bundles carry the strongest margins, with travel services next at about 34.2%.
Which mode of booking holds a notable market share in 2026?
Online channels are likely to lead with 58.4%, as apps handle search and payment in one flow, and offline agencies hold about 27.3%.
Which country has a notable expansion outlook through 2036?
The United States has the strongest FMI outlook, a 6.1% CAGR supported by AI booking tools, with South Korea second at 6%.
Who are the key companies in the travel intermediaries business market?
Booking Holdings, Expedia Group and Trip.com Group lead online platforms, Amadeus and Sabre lead distribution technology, and Hopper, Traveloka and Corporate Travel Management compete on mobile, regional and managed travel.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
