

- Market Size (2026)
- USD 2.6 Bn
- Forecast (2036)
- USD 4.1 Bn
- CAGR (2026 to 2036)
- 4.5%
How big is Asphalt Pavers Market in 2026?
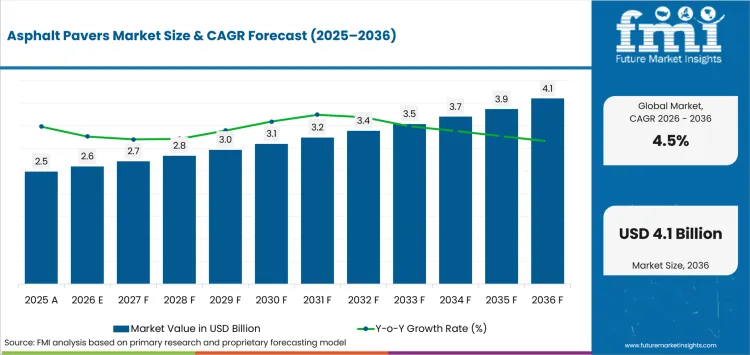
USD 2.6 billion in 2026 and USD 4.1 billion by 2036 at a 4.5% CAGR.
Demand for asphalt pavers is projected to expand at a 4.5% CAGR between 2026 and 2036, increasing from USD 2.6 billion to USD 4.1 billion. Highway contractors convert funded resurfacing into machine hours after projects reach award and site mobilization. USA Census Bureau data placed highway construction at a USD 150.9 billion annualized rate in June 2026, keeping a large workstream available for pavers equipment fleets and dealer support.
Country conditions change how quickly budgets become paver orders, as Germany’s current investment execution data demonstrate. Germany’s Federal Ministry for Transport reported in January 2026 that overall transport-investment disbursement reached 95% during 2025. That execution sustains rehabilitation work, yet contractors still weigh service response and utilization before replacing machines. The same timing affects asphalt mixing plants and paving fleets because both assets must match actual project cadence.
Key Takeaways of Asphalt Pavers Market
- Road rehabilitation and awarded construction packages raise paver utilization because contractors must protect crew productivity during tightly scheduled paving windows.
- By product type, track asphalt pavers are estimated to hold 74.0% in 2026 owing to traction and stable material delivery on sustained roadwork.
- In 2026, up to 2.6m is expected to lead working width with 52.0% share because compact tractors can pair with extensible screeds.
- The 110 - 150 HP segment is likely to capture 34.0% share in 2026 attributable to mixed commercial and medium-road workloads.
- Tender timing and weak fleet utilization can defer equipment purchases even after road authorities approve funding for construction or rehabilitation.
- Some of the key players in this market include Caterpillar Inc., Fayat Group, Wirtgen Group (Deere & Company), Ammann Group Holding AG, Astec Industries, Inc., SANY Heavy Industry Co., Ltd., XCMG Group, and Sumitomo Construction Machinery Co., Ltd.
Analyst Perspective
"Asphalt paver economics depend on productive paving hours and reliable crew output, not headline road budgets. Contractors should compare screed control, dealer response, transport burden, and operator workload against the specific contracts that will keep each machine working."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights
How is the Asphalt Pavers Market segmented?
Product Type, Working Width, Power, Fuel Type, and Application define the asphalt paver configurations assessed in this market.
Market taxonomy covers product type, working width, power, fuel type, application, and region. Product type includes track and wheel asphalt pavers. Working width covers up to 2.6m, 2.6 to 4 m, and more than 4 m. Power includes up to 75 HP, 75-110 HP, 110 - 150 HP, and more than 150 HP. Fuel type includes diesel, electric, and hybrid. Applications comprise roadways and highways, airport runways, parking and commercial areas, and industrial and other surfaces.
What drives Roadways and Highways in the Application category?
Road agencies release resurfacing packages keeping pavers working beyond isolated construction programs and short projects. Mexico placed 20 paving trains into service in January 2026 for more than 495 km of federal-road rehabilitation. Each train included a paver with support machines, linking equipment use to road marking coatings after resurfacing.
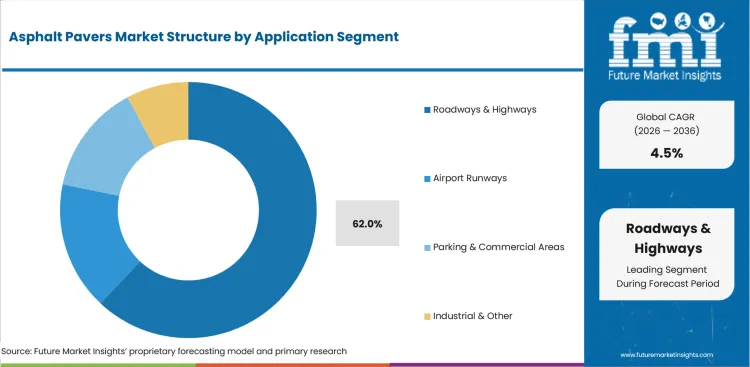
- By application, roadways and highways are forecast to represent 62.0% in 2026 driven by repeated construction and rehabilitation requirements on public networks.
- Contractors replace or expand fleets once awarded road packages expose the cost of downtime, especially where paving windows compress truck and roller schedules.
What makes Track Asphalt Pavers central to the Product Type category?
Tracked undercarriages hold traction on uneven highway bases while crews maintain steady paving speed over long pulls and resurfacing contracts. Astec Industries introduced its RP-195 Highway Class Paver in March 2025 with rubber tracks and SmartEdge joint-control technology, fitting resurfacing after road milling machines that must recover controlled mats.
- Based on product type, track asphalt pavers are projected to account for 74.0% in 2026 due to stable traction during sustained highway paving.
- Highway fleets value tracked platforms for long pulls and changing base conditions, while wheeled machines retain an advantage on short urban moves between jobs.
Why does up to 2.6m lead the Working Width category?
Compact tractors reduce transport and access burdens on municipal jobs that still require flexible screed coverage. BOMAG introduced the BF 350 C-5 and BF 350 P-5 in April 2025 with a 1.7 m basic width. Its tracked version extends to 5.0 m and suits work using bitumen emulsifiers for tack treatments.
- By working width, up to 2.6m is estimated to hold 52.0% in 2026 owing to compact transport dimensions and extensible screed coverage.
- Municipal and commercial contractors can move a smaller tractor between sites more easily, then extend the screed for lane-scale work once positioned.
What supports Diesel in the Fuel Type category?
Paving trains demand continuous tractor availability while haul trucks and rollers follow fixed production sequences during full paving shifts. Ammann stated in January 2025 that new ABG pavers arrive with HVO and need no engine changes. The familiar combustion duty cycle also fits polymer modified bitumen specifications used on demanding pavements.
- Diesel is set to lead the fuel type category with 82.0% share in 2026 due to familiar refueling and full-shift operating routines.
- Electric pavers target narrower duty cycles where charging access and low local exhaust affect project value. They do not replace diesel uniformly across fleets.
What are the drivers, restraints and opportunities in the Asphalt Pavers Market?
Awarded road programs raise machine utilization, contract release timing can delay purchases, and electric or automated pavers offer targeted gains on suitable jobs.
- Driver: Road agencies that place resurfacing packages into execution increase productive paver hours and make aging-machine downtime more expensive for contractors.
- Restraint: Public funding reaches contractors through programming and awards, so equipment orders can lag budget announcements by several procurement stages.
- Opportunity: Electric propulsion and practical automation can cut local exhaust or operator workload on projects that value those operating changes.
Executed Road Programs Raise Fleet Pressure
Mexico is expanding federal road maintenance with machinery that road crews can put directly into service. In January 2026, the Presidency said 11 additional paving trains would be acquired after the initial 2025 program. More in-house resurfacing equipment increases available paving hours and raises the service burden on machines already working in state programs. That deployment makes parts response and planned maintenance more visible during active resurfacing seasons for contractors.
Contract Release Timing Delays Equipment Orders
Approved infrastructure money does not become paver demand until agencies program and award usable work. FHWA notified states in June 2025 about anticipated fiscal-2026 federal-aid highway apportionments, while noting that final amounts could change before certification. Contractors therefore time purchases against bid visibility and fleet utilization, especially on jobs using modified bitumen mixes with specific production requirements. Confirmed letting schedules matter more to replacement timing than annual funding totals during active bidding cycles.
Electric and Automated Pavers Address Noise and Labor Constraints
Alternative power becomes commercially relevant where operating noise or local exhaust has explicit project cost. Vögele presented the battery-electric SUPER 1300-5e in April 2025 with a 126 kWh battery and Mini Class electric pavers. Contractors evaluating warm-mix agents can pair lower-temperature material strategies with lower-noise equipment, provided runtime and charging fit the paving schedule. Commercial adoption depends on charging access and service response preserving planned hourly output during paving shifts.
Which country CAGRs are profiled in the Asphalt Pavers Market?
| Country | CAGR |
|---|---|
| India | 5.9% |
| Japan | 4.1% |
| USA | 3.7% |
| Germany | 3.6% |
| China | 3.5% |
How do country-level CAGRs compare in the Asphalt Pavers Market?
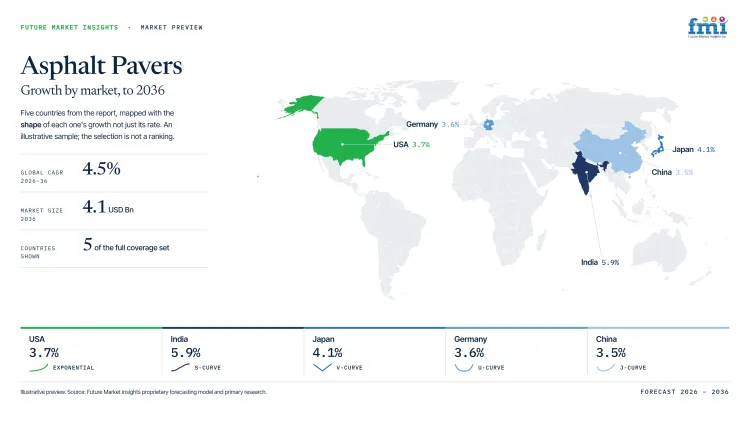
The five profiled countries span 2.4 percentage points, from India at 5.9% to China at 3.5%. India represents the fastest-growth market, followed by Japan, while the USA and Germany form a moderate-growth group. China records the lowest CAGR among the profiled countries. The differences reflect road-development intensity, rehabilitation cycles, contractor fleet maturity, and infrastructure investment patterns.
- India’s faster growth reflects continued highway construction, road-widening programs, and rehabilitation activity across expanding infrastructure networks.
- Japan’s growth is supported by mature-road rehabilitation and demand for precise paving technologies that improve productivity on constrained worksites.
- USA growth is driven mainly by highway rehabilitation and replacement demand, with established contractor fleets limiting broad-based fleet expansion.
- Germany’s growth reflects sustained road renewal requirements, although mature infrastructure and established contractor fleets constrain new equipment growth.
- China’s growth reflects its large installed equipment base and mature road-construction ecosystem, with replacement and infrastructure maintenance supporting future demand.
Installed fleet size varies separately from growth pace, so the full report evaluates procurement timing and road-program structure.
Country-wise Analysis
- Asphalt paver demand in India is forecast to expand at 5.9% CAGR through 2036, making it the fastest-growing market among the five profiled countries. Continued highway construction, road widening, expressway development, and rehabilitation projects are expected to sustain equipment demand. Contractors operating across geographically dispersed projects are likely to prioritize machine reliability, fuel efficiency, rapid service response, and availability of replacement parts. The expansion of road infrastructure also creates opportunities for manufacturers and dealers with strong regional service networks.
- Japan’s asphalt paver market is estimated to grow at 4.1% CAGR through 2036, supported primarily by rehabilitation and maintenance of mature road infrastructure. Aging pavements and constrained urban worksites increase the importance of precise paving, operator assistance, and efficient equipment utilization. Contractors are likely to favor compact, reliable machines with automation features that can improve paving consistency while maintaining straightforward setup and manual control for complex rehabilitation projects.
- The USA asphalt pavers sector is projected to record a 3.7% CAGR during the forecast period, supported by highway rehabilitation, resurfacing, and replacement demand. Established contractor fleets and mature dealer networks limit the need for rapid fleet expansion, making replacement cycles a key source of equipment sales. Manufacturers can differentiate through fuel efficiency, screed performance, operator-assistance technologies, uptime, and responsive aftermarket support as contractors seek to maximize machine utilization across scheduled paving programs.
- Germany is expected to register a 3.6% CAGR through 2036, with demand concentrated around road rehabilitation and maintenance projects. Mature infrastructure and established contractor fleets constrain broad fleet expansion, but recurring renewal requirements provide a stable replacement market. Contractors are likely to place greater emphasis on precise screed control, fast setup, reliability, and field-service responsiveness because restricted construction windows can increase the cost of equipment downtime during major rehabilitation projects.
- China’s asphalt paver market is projected to grow at 3.5% CAGR through 2036. The market benefits from its extensive road network and continuing maintenance, resurfacing, and infrastructure-upgrade requirements, although a large installed equipment base moderates new-unit growth. Replacement demand, equipment modernization, and productivity improvements are expected to remain important purchasing drivers. Manufacturers with strong domestic distribution, competitive pricing, reliable components, and advanced paving-control technologies are positioned to address evolving contractor requirements.
Who are the notable companies in the Asphalt Pavers Market?
Caterpillar Inc., Fayat Group, Wirtgen Group (Deere & Company), Ammann Group Holding AG, Astec Industries, Inc., SANY Heavy Industry Co., Ltd., XCMG Group, and Sumitomo Construction Machinery Co., Ltd. are the notable companies profiled in this market.

Competition turns on paver-class coverage, screed control, field support, and evidence from live road projects. Caterpillar, Fayat, Wirtgen, and Ammann cover broad roadbuilding portfolios, while Astec concentrates heavily on North American contractor requirements. SANY, XCMG, and Sumitomo bring Asian road-machinery depth with increasing automation in high-output paving projects. Adjacent spending on construction aggregates and bitumen modifiers also affects equipment choices because machines must match the materials and production rates specified for awarded paving work.
- Caterpillar Inc., Fayat Group, Wirtgen Group (Deere & Company), and Ammann Group Holding AG compete with broad highway and compact paving ranges backed by global roadbuilding systems.
- Astec Industries, Inc. emphasizes highway and commercial contractor platforms with rebuild support and application-specific screed options in North American channels.
- SANY Heavy Industry Co., Ltd., XCMG Group, and Sumitomo Construction Machinery Co., Ltd. use high-output road machinery and expanding automation on complex paving work.
Competitive Benchmarking: Asphalt Pavers Market
| Company | Paver-Class Coverage | Screed & Automation Depth | Service & Deployment Evidence | Geographic Reach |
|---|---|---|---|---|
| Caterpillar Inc. | High | Medium | Medium | Global |
| Fayat Group | High | High | High | Global |
| Wirtgen Group (Deere & Company) | High | High | Medium | Global |
| Ammann Group Holding AG | High | High | High | Global |
| Astec Industries, Inc. | Medium | High | Medium | North America and international |
| SANY Heavy Industry Co., Ltd. | High | High | High | China and international |
| XCMG Group | High | High | High | Global |
| Sumitomo Construction Machinery Co., Ltd. | Medium | High | Medium | Japan and selected international markets |
Scoring basis: High paver-class coverage requires recent official evidence of multiple road-paver classes or tracked and wheeled formats, while Medium identifies a narrower documented range. High screed and automation depth requires documented automated control or several digital paving functions, while Medium requires fewer verified functions. High service and deployment evidence requires named field deployments plus active support routes, while Medium requires one of those two evidence types.
Key Developments in the Asphalt Pavers Market
- In June 2026, XCMG Group deployed a seven-machine autonomous paving and compaction fleet on Oman’s Sultan Said bin Taimur Road project, where the system entered regular operation during April before a public demonstration in May.
- In May 2026, Fayat Group's Dynapac delivered Europe's first fully electric large highway asphalt pavers to three Dutch infrastructure companies for operational use in road construction.
- In June 2025, Sumitomo Construction Machinery Co., Ltd. launched ASTRA 1.0 for asphalt finishers, using stereo cameras to automate steering and screed extension without 3D survey equipment or design data.
Key Players in the Asphalt Pavers Market
Global Highway and Roadbuilding Platforms
- Caterpillar Inc.
- Fayat Group
- Wirtgen Group (Deere & Company)
- Ammann Group Holding AG
North American Contractor-Focused Platforms
- Astec Industries, Inc.
Asian Road-Machinery and Automation Specialists
- SANY Heavy Industry Co., Ltd.
- XCMG Group
- Sumitomo Construction Machinery Co., Ltd.
Asphalt Pavers Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By product type, working width, power, fuel type, application and region. |
| Quantitative Units | USD Billion. |
| Market Definition | Commercial tracked and wheeled asphalt paving machines used to place asphalt mats for roads, runways, parking areas and industrial surfaces. |
| Regions Covered | North America, Latin America, Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | India, China, Japan, USA, Germany, and 20+ countries included in the full report. |
| Key Companies Profiled | Caterpillar Inc., Fayat Group, Wirtgen Group (Deere & Company), Ammann Group Holding AG, Astec Industries, Inc., SANY Heavy Industry Co., Ltd., XCMG Group, Sumitomo Construction Machinery Co., Ltd. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Asphalt Pavers Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Asphalt Pavers Market by Segments
Asphalt Pavers Market segmented by Product Type:
- Track Asphalt Pavers
- Wheel Asphalt Pavers
Asphalt Pavers Market segmented by Working Width:
- Up to 2.6m
- 2.6 to 4 m
- More than 4 m
Asphalt Pavers Market segmented by Power:
- Up to 75 HP
- 75-110 HP
- 110 - 150 HP
- More than 150 HP
Asphalt Pavers Market segmented by Fuel Type:
- Diesel
- Electric
- Hybrid
Asphalt Pavers Market segmented by Application:
- Roadways & Highways
- Airport Runways
- Parking & Commercial Areas
- Industrial & Other
Asphalt Pavers Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- USA Census Bureau (2026, August 3). Monthly Construction Spending, June 2026.
- Federal Ministry for Transport, Germany (2026, January 23). Schnieder: Mittel für Erhalt und Sanierung in 2025 vollständig verbaut.
- Astec Industries, Inc. (2025, March 24). Rock to Road™: Astec Brings Infrastructure Solutions to World of Asphalt/AGG1.
- BOMAG GmbH (2025, April 7). Innovative Operating Concept and Powerful Performance.
- Ammann Group (2025, January 15). New ABG Pavers filled with HVO.
- Secretaría de Infraestructura, Comunicaciones y Transportes, Mexico (2026, January 26). Inician trenes de repavimentación y conservación en más de 495 km de la Red Carretera Federal: SICT.
- Presidencia de la República, Mexico (2026, January 21). En 2026, Programa Nacional de Conservación de Carreteras y Bachetón tendrán una inversión de 50 mil mdp: Presidenta Claudia Sheinbaum.
- Federal Highway Administration (2025, June 25). Advance Notification of Federal-Aid Highway Funds to be Apportioned on October 1, 2025.
- Wirtgen Group (2025, April 7). Low Noise Meets Zero Operating Emissions: The New Electric Pavers from Vögele.
- Departamento Nacional de Infraestrutura de Transportes (2026, January 6). Região Norte recebeu R$ 3,3 bilhões em obras de infraestrutura em 2025.
- Secretaría de Infraestructura, Comunicaciones y Transportes, Mexico (2026, May 18). Repara Gobierno de México 5 mil km de la Red Carretera Federal con Trenes de Pavimentación.
- Ministry of Land, Infrastructure, Transport and Tourism, Japan (2026). ROADS IN JAPAN 2026.
- Federal Highway Administration (2026, June 18). Funding.
- Die Autobahn GmbH des Bundes (2026, May 28). A63: Zweiter Bauabschnitt der Fahrbahnsanierung zwischen der AS Göllheim und der AS Sembach startet Mitte Juni.
- XCMG Group (2026, June 26). XCMG Empowers Oman’s First AI-driven Autonomous Asphalt Paving Demonstration with Digital & Intelligent Road Construction Solutions.
- Dynapac (2026, May 13). European market premiere for Dutch infrastructure sector.
- Caterpillar Inc. (2026, March 1). Caterpillar updates Cat® AP1000 and AP1055 pavers, introduces new smooth SDX plates and collision mitigation.
- Caterpillar Inc. (2025, December 15). Caterpillar CONEXPO-CON/AGG exhibits to highlight innovations that Reshape What’s Possible.
- Sumitomo Construction Machinery Co., Ltd. (2025, June 16). Launch of Asphalt Finisher Automatic Steering and Screed Extension System ASTRA 1.0.
- Dynapac (2025, July 25). Smooth Debut for First All-Electric Highway-Class Paver SD25 80C e in the Netherlands.
- Dynapac (2025, December 16). The Future Has Begun: Autonomous Paving in Real-World Road Construction.
- Ammann Group (2025, August 7). Over 40 ABG 8820 pavers deployed for the urgent overhaul of Beijing's East Fourth Ring Road.
- Wirtgen Group (2025, February 19). New pavers and technologies for automated road construction.
- Dynapac (2025, March 13). Successful Deployment of the First Fully Electric Road Paver in Germany.
- Ammann Group (2025, May 6). Electric-Drive Paver and New Technologies Grab Attention at bauma 2025.
- Astec Industries, Inc. (2026, March 1). Astec Introduces Roadtec Renew as Part of Expanded Rebuild and Repair Support for Road Construction Customers.
- SANY Group (2025, August 7). Building Smarter Equipment: SANY Is Accelerating Intelligent Transformation.
- XCMG Group (2025, April 10). XCMG Showcases Green Innovation and Intelligent Solutions at bauma 2025, Reinforcing Global Leadership.
- Sumitomo Construction Machinery Co., Ltd. (2025, December 24). Launch of New Asphalt Finishers HA60W-11 and HA60C-11.
- SANY Group (2025, December 31). A Year to Remember A Future to Build Together.
- Wirtgen Group (2026, March 10). World and Market Premieres from the Wirtgen Group Fascinate Visitors at CONEXPO 2026.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- What is the size of the Asphalt Pavers Market in 2026 and what value is forecast for 2036?
- Which road-construction and rehabilitation conditions support asphalt paver demand?
- Why do track asphalt pavers hold the leading position within product type?
- Why does up to 2.6m lead the working width category?
- What keeps diesel central to asphalt paver fleet operation?
- How do the five profiled country CAGRs compare between 2026 and 2036?
- Which companies are active in highway, compact, automated, and alternative-power asphalt paving?
- What factors can delay asphalt paver purchases even after road funding is approved?
- How are automation and electric propulsion changing paver evaluation?
Frequently Asked Questions
How big is the asphalt pavers market in 2026?
The asphalt pavers market is valued at USD 2.6 billion in 2026 and is projected to reach USD 4.1 billion by 2036. Awarded road construction and rehabilitation work keeps contractor fleets active enough to support replacement and selective expansion.
What is the CAGR of the asphalt pavers market from 2026 to 2036?
The asphalt pavers market is projected to grow at a CAGR of 4.5% between 2026 and 2036. Expansion depends on resurfacing workloads that convert public road spending into productive machine hours after contracts reach execution.
Which product type leads the asphalt pavers market?
The track asphalt pavers segment is expected to hold 74.0% of the asphalt pavers market in 2026, driven by traction and stable forward motion on sustained highway work. Wheeled units retain value on contracts that require faster movement between shorter jobs and scattered paving sites.
Which working width holds the largest current share in the asphalt pavers market?
The up to 2.6m segment is expected to hold 52.0% of the asphalt pavers market in 2026, supported by compact transport dimensions and extensible screeds. Contractors can use one tractor on municipal or commercial work without giving up broader lane coverage at the jobsite.
How much value will the asphalt pavers market add between 2026 and 2036?
The asphalt pavers market is expected to add USD 1.5 billion in value between 2026 and 2036. The increase follows continuing road rehabilitation needs and selective fleet expansion as contractors replace machines that cannot meet uptime or paving-quality requirements.
Which countries are projected to record the highest growth in the asphalt pavers market?
Brazil is projected to grow at 5.5% CAGR, followed by Mexico at 4.5% and Japan at 4.1% through 2036. Their growth paths differ because service distance, federal paving programs, and operator-assistance needs affect equipment orders in different ways.
Which companies are active in the asphalt pavers market?
Key companies in the market include Caterpillar Inc., Fayat Group, Wirtgen Group (Deere & Company), Ammann Group Holding AG, Astec Industries, Inc., SANY Heavy Industry Co., Ltd., XCMG Group, and Sumitomo Construction Machinery Co., Ltd. Competition centers on paver range, automation, screed control, and field support.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Track Asphalt Pavers
- Wheel Asphalt Pavers
- Track Asphalt Pavers
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Working Width, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Working Width, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Working Width, 2026 to 2036
- Up to 2.6m
- 2.6 to 4 m
- More than 4 m
- Up to 2.6m
- Y-o-Y Growth Trend Analysis By Working Width, 2021 to 2025
- Absolute $ Opportunity Analysis By Working Width, 2026 to 2036
- Global Market Analysis and Forecast, By Power, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Power, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Power, 2026 to 2036
- 110 - 150 HP
- 75-110 HP
- Up to 75 HP
- More than 150 HP
- 110 - 150 HP
- Y-o-Y Growth Trend Analysis By Power, 2021 to 2025
- Absolute $ Opportunity Analysis By Power, 2026 to 2036
- Global Market Analysis and Forecast, By Fuel Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Fuel Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Fuel Type, 2026 to 2036
- Diesel
- Electric
- Hybrid
- Diesel
- Y-o-Y Growth Trend Analysis By Fuel Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Fuel Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Roadways & Highways
- Airport Runways
- Parking & Commercial Areas
- Industrial & Other
- Roadways & Highways
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Working Width
- By Power
- By Fuel Type
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Caterpillar Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Volvo Construction Equipment
- Fayat Group
- Wirtgen Group (Deere & Company)
- Ammann Group Holding AG
- Astec Industries, Inc.
- SANY Heavy Industry Co., Ltd.
- XCMG Group
- Sumitomo Construction Machinery Co., Ltd.
- LeeBoy
- Caterpillar Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


