

- Market Size (2026)
- USD 2.3 Bn
- Forecast (2036)
- USD 8.9 Bn
- CAGR (2026 to 2036)
- 14.2%
How Big is the Biochar Fertilizer Market in 2026?
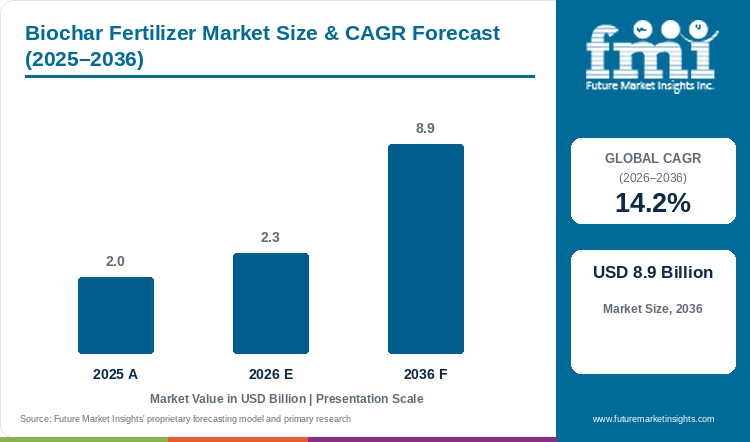
Sales of biochar fertilizer will expand at a 14.2% CAGR between 2026 and 2036. The market is estimated at USD 2.3 Billion in 2026, up from USD 2.0 Billion in 2025, and will reach USD 8.9 Billion by 2036.
The biochar fertilizer market size is estimated at USD 2.3 Billion in 2026, up from USD 2.0 Billion in 2025, and FMI projects sales of USD 8.9 Billion by 2036 at a 14.2% CAGR, a gain of USD 6.6 Billion over the decade. Set beside organic fertilizer, the nearest adjacent pool, biochar fertilizer is growing from a much smaller base at more than twice the rate, so most of the gain will come from a share shift inside soil-input budgets that growers already carry each season.
Public cost share is moving the first tonnes onto farmland, and in January 2026 the NRCS office in North Carolina extended EQIP sign-ups for Soil Carbon Amendment practice 336 across 11 western counties hit by Hurricane Helene, with four scenarios mixing biochar and compost by volume [1]. Blending with compost puts biochar suppliers in front of the same buyers who purchase organic fertilizer, a category set to rise from USD 9.8 Billion in 2026 to USD 17.9 Billion by 2036 at a 6.2% CAGR, an opportunity of USD 8.1 Billion. Demand for biofertilizers is set to expand from USD 2.9 Billion to USD 6.6 Billion at an 8.5% CAGR, and spending on soil testing will widen by USD 2.8 Billion at a 4.9% CAGR to reach USD 7.3 Billion by 2036. Biochar fertilizer will grow faster than all three adjacent categories, although organic fertilizer will still offer the larger absolute pool, so producers selling blends into organic and biological programs will reach the widest set of buyers.
In April 2026, Commission Delegated Regulation (EU) 2026/285 set certification rules for biochar carbon removal and capped cumulative application on agricultural and forest soils at 50 tonnes per hectare [2]. Analysts at FMI see producers selling one tonne into both the fertilizer channel and a certified removal registry holding a clear cost edge through 2036, since removal income will cover part of plant cost and the market value tracked in this study excludes that credit revenue. Investment in certified pyrolysis capacity close to farm buyers will give producers a second income line per tonne and give growers a lower fertilizer price as fields move toward the 50-tonne ceiling over several seasons.
Key Takeaways of Biochar Fertilizer Market
- By product type, inorganic biochar fertilizer will hold 38.8% of market share in 2026.
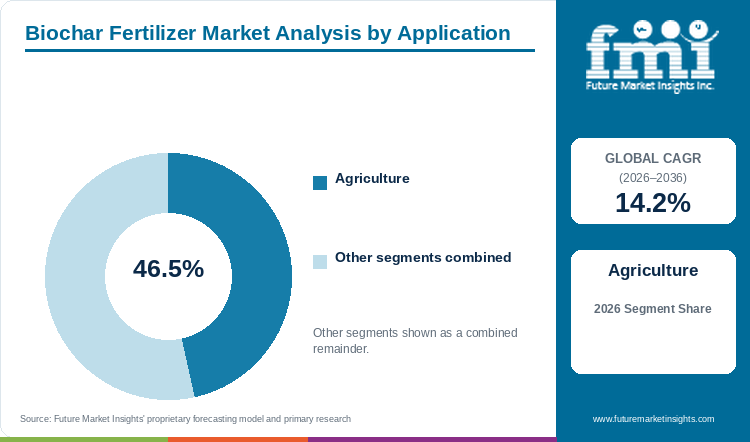
- By application, agriculture will account for 46.5% of market share in 2026.
- Key companies operating in the biochar fertilizer market include Airex Energy Inc., NetZero, Novocarbo GmbH, Pacific Biochar Benefit Corporation, ARTi, Biochar Now, LLC, Wakefield BioChar, and Carbon Gold Ltd., and the full report covers many more players.
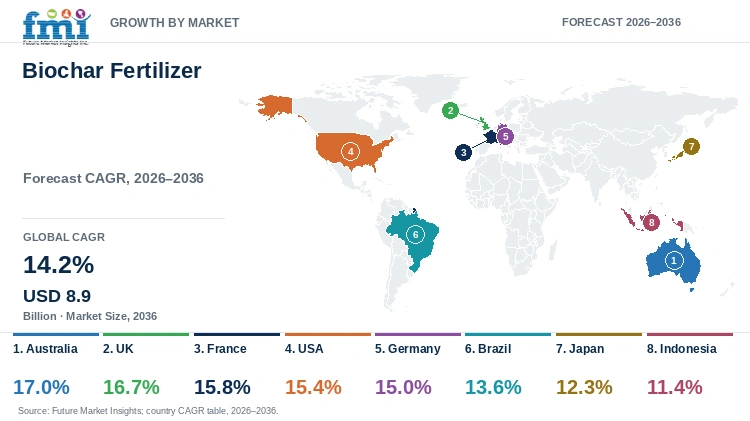
- By country, Australia will grow fastest at 17.0%, and Indonesia slowest at 11.4% through 2036.
Analyst Perspective
“In my opinion, the largest revenue opportunity in biochar fertilizer through 2036 sits with producers that blend characterized biochar into nutrient products growers already buy. Suppliers pairing a field-tested blend with certified carbon removal will bring down delivered cost per hectare and lock in multi-season farm contracts.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Biochar Fertilizer Market Segmented?
Two segment categories, product type and application, sit alongside regional coverage of more than 25 countries and country groups in this biochar fertilizer study.
Based on product type, the market is segmented into inorganic, compound, and organic biochar fertilizer. By application, the report covers agriculture, animal feed, fish farming, and other uses such as water management and animal husbandry. Upstream supply links to the granular biochar and Asia Pacific biochar categories. Regional coverage spans more than 25 countries and country groups across seven regions.
Why Does Agriculture Lead the Biochar Fertilizer Market by Application?
Farmland is giving growers a measurable baseline for soil organic matter, water holding and yield, and that baseline will shorten the path from trial plot to reorder. Feed carries a strong per-farm return case as well, with a South Australian dairy trial reporting a net profit gain of about AUD 72,000 a year per operation from feeding 150 grams of biochar per cow per day [4]. Feed use will still grow from a smaller base, since mills buying animal feed additives will ask for safety and residue data before listing a new ingredient.
- Agriculture will hold 46.5% of market share by application in 2026, with sales driven by measurable soil and crop outcomes.
- In August 2025, ARTi reported supplying biochar to the Rodale Institute Midwest Organic Center in Iowa for trials comparing conventional tillage with no-till organic systems [5].
Why Does Inorganic Biochar Fertilizer Lead Market by Product Type?
Inorganic products will hold 38.8% of product type revenue in 2026, backed by fit with established mineral nutrient programs.
Commercial farms are budgeting each season for mineral nitrogen, phosphorus and potassium, and an inorganic blend lets biochar enter that existing spend through spreaders and nutrient plans growers already use, so approval will come faster than for a stand-alone amendment. Dose control will remain the main friction, as regulators are tying spreading to a documented crop need. The Environment Agency in England allows up to one tonne of biochar per hectare in any 12-month period, and only on land with a nutrient need [3]. With so little tonnage allowed per hectare, value per tonne will rise when biochar serves as a nutrient carrier, much as silicon soil conditioners ride on existing fertilizer passes.
- Inorganic products will hold 38.8% of product type revenue in 2026, backed by fit with established mineral nutrient programs.
- In February 2026, RPS 366 let operators with a U10 or U11 waste exemption store up to 10 tonnes of biochar for up to 12 months before spreading [3].
What are the Drivers, Restraints, and Opportunities in the Biochar Fertilizer Market?
As per FMI's analysis, soil-health spending will drive sales, uneven field response and delivered cost will slow repeat orders, and certified carbon removal will open a second revenue line for producers till 2036.
- Driver: Demand will rise as growers and conservation programs are paying for soil amendments that hold nutrients and water and store carbon in the same pass.
- Restraint: Variable crop response, feedstock rules and high delivered cost are stretching the time between a first trial and a repeat order.
- Opportunity: Adoption potential of biochar is extending into certified removals, with buyers in the carbon credit market funding larger pyrolysis plants.
On the supply side, Germany ran 55 biochar plants producing about 20,000 tonnes a year as of June 2026, roughly a quarter of the 85,000 tonnes made across Europe [6]. The same German trade report put certificate income at about EUR 450 per tonne of biochar [6]. Pacific Biochar received 3,042 verified carbon removal credits from Isometric in December 2025 for biochar made from California sawmill residues and applied to farmland [7]. Once credit income covers part of plant cost, producers will have room to price the fertilizer tonne lower, and that pricing room will ease two key challenges in the market, uneven response on fertile soils and freight cost on a bulky product.
Which Country CAGRs are Profiled in the Biochar Fertilizer Market?
| Country | CAGR, 2026 to 2036 |
|---|---|
| Australia | 17.0% |
| UK | 16.7% |
| France | 15.8% |
| USA | 15.4% |
| Germany | 15.0% |
| Brazil | 13.6% |
| Japan | 12.3% |
| Indonesia | 11.4% |
How do Country-level CAGRs Compare in the Biochar Fertilizer Market?
As per FMI's analysis, the eight profiled countries will spread across a 5.6-percentage-point range through 2036, from 17.0% in Australia to 11.4% in Indonesia. Four markets, Australia, the UK, France and the USA, will grow faster than 15.0%, with Germany at 15.0% and Brazil at 13.6% close behind. Countries near the top of the table already attach carbon income, cost share or spreading rules to biochar, and the two Asian markets at the bottom are still matching the product to local soils and offset schemes.
- Australia will post the highest CAGR among profiled countries as farm trials begin to put a price on feed and soil returns.
- Demand in the USA at 15.4% is gaining from EQIP cost share under practice 336 [1].
- Japan at 12.3% will build on J-Credit demand, with Nomura targeting 10,000 tonnes of biochar a year [8].
- Indonesia will grow 5.6 points slower than Australia, and BRMP advised in July 2025 that biochar use be matched to soil type, texture and crop [9].
Regional estimates beyond the eight profiled countries cover North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa, across more than 25 countries and country groups.
Country Outlook
- Plant economics will drive the Australian outlook, with demand for biochar fertilizer rising at a 17.0% CAGR, the fastest among profiled countries. A Nuffield Australia report from April 2026 estimated that a plant making 1,000 tonnes of biochar a year could earn more than AUD 550,000 from carbon credits alone [4]. Local pyrolysis capacity near dairy and cropping regions will cut freight and move more growers past small trials.
- Feedstock traceability will set the pace in the UK, a market heading for a 16.7% CAGR till 2036. RPS 366 allows only listed untreated wood, bark and plant feedstocks, and the Environment Agency intends to review the position by March 2029 [3]. Merchants will list suppliers with traceable feedstock records first, and producers using unlisted residues will wait for the review.
- France will grow at a 15.8% CAGR through 2036 from a low starting point, as ADEME reported in March 2026 that French use of biochar remained limited and the agency is working with AFNOR on national and ISO standards [10]. ADEME also noted that Denmark had committed approximately EUR 1.3 billion to biochar for agriculture [10]. Once common grades exist, cooperatives will face lower qualification cost and producers will sell against a single specification.
- Retail shelves are opening a second route to market in the USA, and sales of biochar fertilizer there will grow at a 15.4% CAGR till 2036 alongside conservation cost share. Wakefield BioChar placed Biochar Pro Garden Mix in more than 3,700 Walmart stores in April 2026 at USD 6.97 per 4-quart bag [11]. Garden buyers will absorb output that farm channels take longer to qualify, smoothing plant utilization for producers.
- In Brazil, the 13.6% CAGR will rest on residue supply sitting next to the farms that buy the finished product. NetZero opened a fourth biochar factory in Paraguaçu, Minas Gerais, in October 2025, producing about 4,000 tonnes a year from coffee husks supplied by roughly 250 farmers [12]. Short haul distances between residue, plant and field will keep delivered cost low for coffee growers through 2036.
Who are the Notable Companies in the Biochar Fertilizer Market?
Key companies in the market include Airex Energy Inc., NetZero, Novocarbo GmbH, Pacific Biochar Benefit Corporation, ARTi, Biochar Now, LLC, Wakefield BioChar, and Carbon Gold Ltd.
Competition among biochar fertilizer suppliers is turning on plant scale, field evidence and carbon documentation, as per FMI, and entry costs are rising as farm buyers ask for all three at once. Partnerships are serving as the main route to scale, and Carbonity, the joint venture of Airex Energy, Groupe Rémabec and SUEZ, opened in Port-Cartier, Quebec, in May 2025 with 10,000 tonnes of annual capacity and plans to triple output by 2026 [13]. Heat offtake is becoming a second lever on plant economics, as In April 2026, Novocarbo signed a 15-year heat supply agreement with Stadtwerke Dessau for the Carbon Removal Park Dessau, where pyrolysis-produced biochar will be applied across agriculture, urban greening, and construction [14]. Smaller producers without feedstock contracts or credit verification will face consolidation pressure through 2036.
- Industrial-Scale Biochar Producers: Airex Energy Inc., NetZero and Novocarbo GmbH run multi-thousand-tonne pyrolysis plants serving soil and carbon removal buyers.
- Agricultural Biochar and Carbon Removal Specialists: Pacific Biochar Benefit Corporation, ARTi and Biochar Now, LLC pair farm-grade biochar with reactors, trials or verified credits. PNNL published a climate-focused life cycle assessment of an ARTi pyrolysis reactor in July 2025 [15].
- Formulated Biochar Fertilizer Brands: Wakefield BioChar and Carbon Gold Ltd. sell bagged biochar blends through retail and professional channels. Carbon Gold lists a 5-5-5 NPK biochar fertiliser approved by the Soil Association [16].
Competitive Benchmarking
| Company | Agriculture-Ready Biochar | Production Scale | Carbon Documentation | Geographic Reach |
|---|---|---|---|---|
| Airex Energy Inc. | High | High | High | Canada, with Quebec production |
| NetZero | High | High | Medium | Brazil and Cameroon |
| Novocarbo GmbH | Medium | Medium | High | Germany |
| Pacific Biochar Benefit Corporation | High | Medium | High | USA, California projects |
| ARTi | Medium | Medium | Medium | USA, Iowa base |
| Biochar Now, LLC | Medium | Medium | Low | USA, Colorado base |
| Wakefield BioChar | High | Medium | Low | USA nationwide retail |
| Carbon Gold Ltd. | High | Low | Low | UK |
Scoring basis: Agriculture-Ready Biochar scores documented soil, crop or feed products and trials. Production Scale scores documented annual plant capacity in tonnes of biochar. Carbon Documentation scores verified credits or life cycle assessment. High marks broad documented capability, Medium narrower capability, and Low limited public documentation. Geographic Reach reflects evidenced activity, as reviewed in September 2026.
Key Developments
- In May 2025, Airex Energy, Groupe Rémabec and SUEZ inaugurated the Carbonity plant in Port-Cartier, Quebec, with 10,000 tonnes of annual biochar capacity from about 58,000 tonnes of forestry residues [13].
- In October 2025, NetZero inaugurated a fourth biochar factory in Paraguaçu, Brazil, turning coffee husks from about 250 farmers into roughly 4,000 tonnes of biochar a year [12].
- In April 2026, Wakefield BioChar launched Biochar Pro Garden Mix in more than 3,700 Walmart stores across the USA [11].
Key Players
Industrial-Scale Biochar Producers
- Airex Energy Inc.
- NetZero
- Novocarbo GmbH
Agricultural Biochar and Carbon Removal Specialists
- Pacific Biochar Benefit Corporation
- ARTi
- Biochar Now, LLC
Formulated Biochar Fertilizer Brands
- Wakefield BioChar
- Carbon Gold Ltd.
Report Scope and Methodology
| Coverage field | Report scope |
|---|---|
| Market breakdown | 2 categories: Product Type (Inorganic, Compound, Organic), Application (Agriculture, Animal Feed, Fish Farming, Others (Water Management, Animal Husbandry)), and Region |
| Quantitative units | USD Billion |
| Market definition | Revenue from biochar-based fertilizer and soil amendment products sold within the stated Product Type and Application segmentation. The definition excludes carbon removal credit revenue, pyrolysis equipment sales, biochar sold for construction or metallurgy, and downstream crop or feed value. |
| Regions covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa |
| Countries covered | More than 25 countries and country groups, including Australia, the UK, France, the USA, Germany, Brazil, Japan, and Indonesia |
| Key companies profiled | A few of the notable companies out of many players covered in the study: Airex Energy Inc., NetZero, Novocarbo GmbH, Pacific Biochar Benefit Corporation, ARTi, Biochar Now, LLC, Wakefield BioChar, Carbon Gold Ltd |
| Forecast period | 2026 to 2036 |
| Approach | A hybrid bottom-up and top-down sizing framework built by FMI reconciles biochar production capacity, blend pricing and supplier revenue signals with fertilizer use, conservation program uptake and country-level soil amendment demand. |
Research Methodology
| Method | Approach |
|---|---|
| Primary research | The primary-research program engages biochar producers, pyrolysis technology suppliers, fertilizer blenders, farm distributors, agronomists and carbon project developers to test purchase drivers, dose guidance, pricing and repeat-order conditions. |
| Desk research | The analysis reviews conservation program notices, fertilizer and waste regulations, carbon removal methodologies, company announcements and product information. Sources are retained only if the material defines demand mechanisms, supplier roles, country conditions or product developments inside the market boundary. |
| Market sizing and forecasting | The sizing framework combines the baseline value with segment structure, price and volume indicators, plant capacity, company participation and country-level farm demand. Forecasts consider new plants, regulation, carbon finance and feedstock supply. |
| Data validation | Estimates are checked against public data, company activity and interview findings. Carbon credit revenue, construction uses, overlapping revenues and unsupported claims are excluded before final reconciliation. |
Biochar Fertilizer Market by Segments
Biochar Fertilizer Market Segmented by Product Type
- Inorganic
- Compound
- Organic
Biochar Fertilizer Market Segmented by Application
- Agriculture
- Animal Feed
- Fish Farming
- Others (Water Management, Animal Husbandry)
Biochar Fertilizer Market Segmented by Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
Research Sources and Bibliography
- [1] USDA Natural Resources Conservation Service, North Carolina (2026, January 21). Extended Application Deadline for Producers Interested in Soil Carbon Amendments (336).
- [2] European Union (2026, April 17). Commission Delegated Regulation (EU) 2026/285 of 3 February 2026 supplementing Regulation (EU) 2024/3012 by establishing certification methodologies for permanent carbon removals activities.
- [3] Environment Agency (2026, February 26). Storing and spreading biochar to benefit land: RPS 366.
- [4] Nuffield Australia (2026, April 15). From Paddock Waste to Carbon Credits: SA Farmer Investigates Biochar's Potential for Australian Agriculture.
- [5] ARTi (2025, August 29). From Soil to Solutions: ARTi Joins Forces with the Rodale Institute.
- [6] top agrar (2026, June 10). Neues Geschäftsfeld Pflanzenkohle.
- [7] Isometric (2025, December 16). First credits issued to Pacific Biochar under Isometric's Biochar Protocol
- [8] Nomura Holdings (2025, August 4). Biochar, carbon offset's rising star.
- [9] BRMP Tanah dan Pupuk, Ministry of Agriculture, Indonesia (2025, July 17). BRMP Sampaikan Peran Biochar sebagai Pembenah Tanah.
- [10] ADEME (2026, March). Les biochars, une ressource d'avenir encore sous-utilisée.
- [11] Wakefield BioChar (2026, April 21). Wakefield Biochar, a Professional-Preferred Soil Amendment to Help Gardens and Lawns Thrive with Less Watering, is Now Available for Gardeners and Homeowners at Walmart Stores Across the U.S.
- [12] NetZero (2025, October 31). NetZero inaugurates its fourth biochar factory.
- [13] Airex Energy (2025, May 22). Inauguration of Carbonity, Canada's Largest Biochar Plant: A Concrete Solution for Soil Regeneration and Carbon Sequestration.
- [14] Novocarbo (2026, April 22). Laying the foundation for climate-friendly heat production: Stadtwerke Dessau and Novocarbo sign long-term heat offtake agreement.
- [15] Pacific Northwest National Laboratory (2025, July 9). Climate-focused Life Cycle Assessments of Biochar Production by an ARTi Pyrolysis Reactor and an Air Burners CharBoss Air Curtain Incinerator.
- [16] Carbon Gold Ltd. (2026, September). Biochar Fertiliser product page.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- What will the Biochar Fertilizer Market size be in 2026, and what value will the market reach by 2036?
- Which conservation programs and soil-health needs will continue to support demand for biochar fertilizer?
- Why will inorganic products hold the leading position within the Product Type category in 2026?
- Why will agriculture hold the leading position within the Application category?
- How will growth rates differ across Australia, the UK, France, the USA, Germany, Brazil, Japan, and Indonesia till 2036?
- How will certified carbon removal change the cost of biochar fertilizer for growers?
- How will spreading limits, feedstock rules and delivered cost slow repeat orders?
- How should buyers assess the roles and capabilities of the profiled companies?
- What will fertilizer distributors and farm buyers need to check before selecting a biochar supplier?
Frequently Asked Questions
How Big Is the Biochar Fertilizer Market Expected to Be in 2026?
Sales of biochar fertilizer total USD 2.3 Billion in 2026, up from USD 2.0 Billion in 2025, according to FMI. Revenue will reach USD 8.9 Billion by 2036 as growers and conservation programs pay for soil amendments that hold nutrients, water and carbon.
What Is the CAGR of the Biochar Fertilizer Market from 2026 to 2036?
Sales of biochar fertilizer will grow at a 14.2% CAGR from 2026 to 2036. New pyrolysis capacity and carbon removal income will set the pace by lowering delivered cost.
Which Product Type Holds the Largest Share of the Biochar Fertilizer Market?
Inorganic products will lead with 38.8% of product type revenue in 2026. Growers will keep adding biochar to mineral nutrient programs and existing spreading equipment.
Which Application Leads the Biochar Fertilizer Market?
Agriculture will account for 46.5% of application revenue in 2026. Farmland will offer the clearest baseline for soil organic matter, water holding and yield.
Which Country Is Expected to Grow Fastest in the Biochar Fertilizer Market?
Growth of biochar fertilizer sales will be fastest in Australia, at a 17.0% CAGR till 2036, with the UK following at 16.7%. Indonesia will sit last among the eight profiled countries at 11.4%.
What Notable Restraint Affects the Biochar Fertilizer Market?
Key challenges in the biochar fertilizer market will include uneven crop response, feedstock rules and delivered cost. England will cap spreading at one tonne per hectare a year, and growers on fertile soils will need field proof before a repeat order.
Which Are the Key Companies in the Biochar Fertilizer Market?
Airex Energy Inc., NetZero, Novocarbo GmbH, Pacific Biochar Benefit Corporation, ARTi, Biochar Now, LLC, Wakefield BioChar, and Carbon Gold Ltd. rank among the notable companies covered by FMI, and the report will assign each company to one of three strategy groups.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Inorganic
- Compound
- Organic
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Agriculture
- Animal Feed
- Fish Farming
- Others (Water Management, Animal Husbandry)
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Application
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Application
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Application
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Application
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Application
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Application
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Application
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- Key Takeaways
- Key Countries Market Analysis
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Indonesia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Australia
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Airex Energy Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- NetZero
- Novocarbo GmbH
- Pacific Biochar Benefit Corporation
- ARTi
- Biochar Now, LLC
- Wakefield BioChar
- Carbon Gold Ltd.
- Airex Energy Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


