
- Market Size (2026)
- USD 6.2 Bn
- Forecast (2036)
- USD 23.6 Bn
- CAGR (2026 to 2036)
- 14.2%
How big is the Carbon Capture and Storage (CCS) Market in 2026?
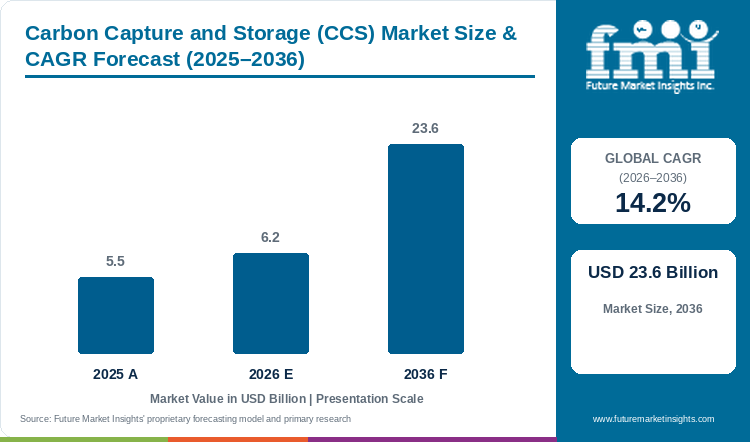
The global carbon capture and storage market is forecast to reach USD 23.57 billion by 2036, compared with USD 6.25 billion in 2026 and USD 5.5 billion in 2025, expanding at a 14.2% CAGR from 2026 to 2036. FMI's 2026 assessment places post-combustion at 48.0% by technology, oil and gas at 42.0% by end-use industry, and Carbon Capture Systems at 63.0% by product.
FMI expects industrial capture investment, shared transport networks and financed storage capacity to drive this expansion. These projects create orders for capture equipment, compression and injection infrastructure across several emitters. The International Energy Agency reported in March 2026 that operational and under-construction capture capacity had risen by over 10% between database editions, while storage capacity increased by about 25%. Permitting delays and uncertain capture volumes remain material restraints: storage networks can advance before enough customers commit, leaving infrastructure underused, according to the International Energy Agency.
Northern Lights provides a qualified example. Its first CO2 was stored in August 2025 (Equinor), while its March 2026 update described construction toward more than 5 million tonnes of annual capacity by 2028; the larger capacity remains a development target (Northern Lights JV). Direct air capture remains outside the report's three combustion-technology categories; related coverage includes solid sorbents for direct air capture.
Key Market Trends & Insights
- The IEA reported that the United Kingdom accounted for around 85% of commercial CCUS bank financing raised over the preceding two years. Financing remains concentrated where revenue and cross-chain risks are addressed, directing equipment opportunities toward a limited set of funded projects. [11]
- Northern Lights' March 2026 fleet update identified a new 12,000 m3 carrier under a long-term charter, with service due from the second half of 2028 to the first half of 2029. Shipping capacity is therefore being procured against future storage contracts rather than assumed to exist when capture plants start. [14]
- Heidelberg Materials' November 2025 selection for grant-agreement preparation covers different routes: oxyfuel capture in Belgium, a French pipeline-and-shipping connection, an Italian link to Ravenna and storage appraisal in Poland. Suppliers face distinct engineering and appraisal packages within one funding round. [7]
Regional Highlights
- Europe had 15 operating commercial CCS projects and 21 under construction as of 31 July 2026, according to the Global CCS Institute. The construction pipeline creates demand for equipment and integration work, while storage access and cross-border connections still determine which industrial capture projects can proceed. [12]
- The Americas had 63 operating projects and 18 under construction on the same date. This larger installed base creates a different mix of operating-service and expansion opportunities from Europe's construction-heavy project count; counts do not measure market revenue or actual annual capture. [12]
Table 1: Carbon Capture and Storage (CCS) Market Size and Forecast (USD billion and CAGR percentage), 2025 to 2036
| Market size and forecast | Value |
|---|---|
| Market size in 2025 | USD 5.5 billion |
| Estimated market size in 2026 | USD 6.25 billion |
| Projected market size by 2036 | USD 23.57 billion |
| CAGR from 2026 to 2036 | 14.2% |
Source: Future Market Insights, Carbon Capture and Storage (CCS) Market, 2026 to 2036.
Analyst Perspective
“A capture project needs a workable transport and storage route before its announced capacity can become a dependable service. Permits, commissioning dates and any conditions attached to financial support can therefore affect when equipment orders and storage contracts move ahead.”
- Nikhil Kaitwade, Principal Consultant, FMI
How is the Carbon Capture and Storage (CCS) Market segmented?
The report covers carbon capture, transport, storage and utilization systems and the revenue attributable to their deployment. It separates the market by technology, end-use industry, product, application and region.
- By Technology: Post-combustion; Pre-combustion; Oxy-fuel Combustion.
- By End-Use Industry: Oil and Gas; Coal and Biomass Power Plant; Iron and Steel; Chemicals; Others.
- By Product: Carbon Capture Systems (Post Combustion Capture, Pre Combustion Capture, Oxy Fuel Combustion Capture); Carbon Transport Systems (Pipeline Transport, Ship Transport); Carbon Storage Solutions (Geological Storage, Ocean Storage); Carbon Utilization Solutions (Enhanced Oil Recovery, Chemical Conversion, Mineralization).
- By Application: Power Generation; Oil and Gas; Cement Production; Iron and Steel; Chemical and Petrochemical.
- By Region: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Why does Post-combustion lead by Technology in the Carbon Capture and Storage (CCS) Market?
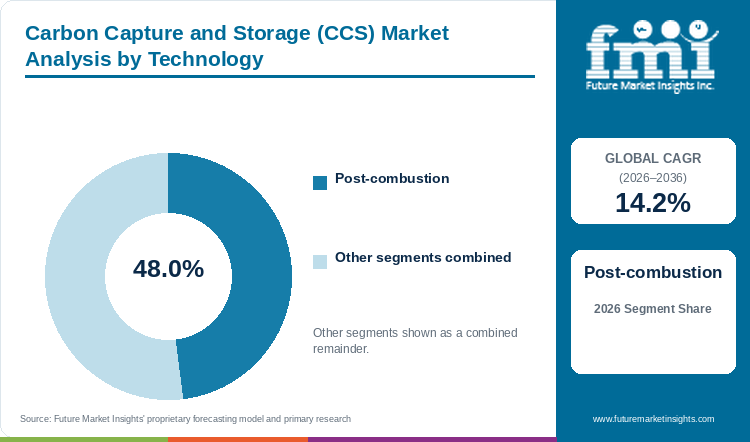
Post-combustion accounts for 48.0% of the Carbon Capture and Storage (CCS) Market by Technology in 2026, according to FMI's assessment.
Retrofit projects create demand for capture engineering and equipment at existing power and industrial plants, while heat integration and transport access affect which designs reach construction. Mitsubishi Heavy Industries reported 18 plants delivered using its KM CDR Process and Advanced KM CDR Process as of July 2025. Its delivery record supports the availability of commercial capture technology for this project pipeline. [5]
MHI's July 2025 basic-design contract at Hokkaido Electric Power's Tomato-Atsuma Power Station covers a planned 5,200-tonne-per-day capture plant. [5] A design contract creates engineering work before full plant construction; it does not demonstrate that the capture facility is already operating. FMI expects retrofit opportunities to support post-combustion demand, while site heat integration, financing and access to transport and storage constrain conversion of designs into equipment orders. Pre-combustion and oxy-fuel combustion make up the other technology categories in the report.
Table 2: Carbon Capture and Storage (CCS) Market Share by Technology, 2026 (percentage)
| Leading Share | 2026 market share |
|---|---|
| Post-combustion | 48.0% |
| All Other Segments Combined Share | 52.0% |
Source: Future Market Insights, Carbon Capture and Storage (CCS) Market, 2026 to 2036.
Why does Oil and Gas lead by End-Use Industry in the Carbon Capture and Storage (CCS) Market?
Oil and Gas accounts for 42.0% of the Carbon Capture and Storage (CCS) Market by End-Use Industry in 2026, according to FMI's assessment.
Gas-processing projects create capture demand within the industry's own operations, distinct from storage services sold to cement or other industrial customers. The IEA identifies hydrocarbon operations as a source of recent Middle Eastern CCUS progress. [11] In February 2026, ExxonMobil reported that it was transporting and storing CO2 from the NG3 project in Louisiana, where up to 1.2 million tonnes a year is expected to be removed from the natural-gas stream. [18]
FMI expects this connection between gas treatment and a receiving storage route to support equipment and service orders in the oil and gas segment. ExxonMobil describes the current NG3 storage route as enhanced oil recovery, with a planned transition to dedicated permanent storage. [18] That status matters to the applicable service and monitoring requirements. Storage ownership remains a supplier characteristic: an oil company's investment in a network does not turn its cement customers into oil and gas end users.
Coal and Biomass Power Plant, Iron and Steel, Chemicals and Others together account for the remaining 58.0% of this report's end-use assessment.
Table 3: Carbon Capture and Storage (CCS) Market Share by End-Use Industry, 2026 (percentage)
| Leading Share | 2026 market share |
|---|---|
| Oil and Gas | 42.0% |
| All Other Segments Combined Share | 58.0% |
Source: Future Market Insights, Carbon Capture and Storage (CCS) Market, 2026 to 2036.
Why do Carbon Capture Systems lead by Product in the Carbon Capture and Storage (CCS) Market?
Carbon Capture Systems account for 63.0% of the Carbon Capture and Storage (CCS) Market by Product in 2026, according to FMI's assessment.
FMI attributes this position to industrial capture packages requiring plant-specific process engineering, integration and equipment procurement, while shared transport and storage networks serve several capture sites. Gassnova's 2025 review identifies integration choices and the capture supplier market as important sources of project complexity and cost-reduction potential. [15]
SLB Capturi and Aker Solutions' January 2025 EPCIC award for Hafslund Celsio illustrates the scope of a capture-side supply package: a capture plant, liquefaction and associated handling facilities at the waste-to-energy site. The cited project targets 350,000 tonnes of annual capture when operational; the award does not establish current output. [16] Such packages create equipment and engineering revenue before commissioning. Their conversion into later orders still depends on financing, integration and a receiving storage route. FMI classifies dedicated transport and permanent-storage equipment under their own product categories, alongside Carbon Utilization Solutions.
Table 4: Carbon Capture and Storage (CCS) Market Share by Product, 2026 (percentage)
| Leading Share | 2026 market share |
|---|---|
| Carbon Capture Systems | 63.0% |
| All Other Segments Combined Share | 37.0% |
Source: Future Market Insights, Carbon Capture and Storage (CCS) Market, 2026 to 2036.
What are the key drivers restraints and opportunities?
The forecast adds USD 17.32 billion of revenue between 2026 and 2036. Government certification and funding mechanisms are maturing in several large markets at the same time that permitting timelines remain a real constraint on how fast capacity can actually come online.
Driver
Government support reduces specific revenue and infrastructure risks. Treasury and IRS guidance issued in December 2025 provided a conditional certification route for qualifying 2025 capture and geological storage if EPA's reporting tool was unavailable by the stated June 2026 checkpoint. [1] The guidance documents a defined compliance contingency rather than a general promise of future tax-credit eligibility. In the United Kingdom, the August 2025 HyNet expansion negotiations followed financial close for the shared network supporting the UK's carbon capture and storage programme. [2] FMI expects funded common infrastructure and clearer contracting arrangements to help individual capture investments proceed.
Restraint
Storage permitting and cross-chain timing constrain commissioning. The EPA describes completeness checks, technical review, a draft permit, public consultation and a final decision for Class VI wells. Review time depends on project complexity and application quality. [10] A storage permit authorises specified injection activity under its conditions; it is not proof that the associated capture plant is operating. Developers must align permitted storage, transport availability and capture construction, and the IEA reports that permitting and construction delays have pushed planned capacity toward 2035. [11]
Opportunity
Shared networks create an opportunity for suppliers of CO2 compression, plant integration and capture-process engineering as funded projects move into delivery. Baker Hughes' June 2025 announcement documents an order, booked in the first quarter, for three compressor trains for Saipem's Liverpool Bay work. [6] On the capture side, Japan's carbon capture and storage buildout included MHI's July 2025 basic-design award at Tomato-Atsuma. [5] These are defined equipment and engineering contracts at different stages. FMI expects further orders where capture projects secure a receiving route, while distinguishing a contract award from recognised revenue or commissioned capacity.
How do quality requirements and government policies affect Carbon Capture and Storage (CCS) Market purchasing?
US Class VI well construction rules directly affect the materials a storage operator can purchase. Under 40 CFR 146.86, casing, cement, tubing and packer materials must be compatible with the fluids they encounter and meet API, ASTM or comparable standards accepted by the regulator. The owner must supply information on CO2-stream corrosiveness and composition, pressures and material grades. [17] FMI finds that these requirements favour suppliers able to document material compatibility and the relevant pressure and corrosion duty. They apply to Class VI injection wells, rather than automatically prescribing every upstream capture component. Policy support addresses a different purchasing constraint. The UK's HyNet negotiations classify projects by deliverability and value for money, [2] while the EU Innovation Fund uses emissions-trading revenues to support eligible low-carbon projects. [8] Material qualification and project funding therefore determine different parts of the supplier decision.
What limits reliable Carbon Capture and Storage (CCS) Market supply and performance?
Capture capacity, transport availability and permitted storage must reach service together. A finished capture unit cannot establish that the receiving network has the required capacity, while storage constructed ahead of contracted capture volumes faces utilisation risk. The IEA's March 2026 review describes both delayed deployment and a potential widening gap between capture and storage development. [11] EPA Class VI approval concerns injection wells and their operating conditions; it does not certify the operational readiness of an entire capture-to-storage chain. [10] FMI expects these interfaces to affect commissioning schedules and the timing of equipment and service revenue.
Where can suppliers win additional business in the Carbon Capture and Storage (CCS) Market?
Suppliers can win additional business where one financed transport or storage network supports several separately procured capture packages. Compression and interface engineering form one opportunity: Baker Hughes' three-train Liverpool Bay order concerns a defined network equipment package. [6] Capture design and integration form another. Heidelberg Materials' November 2025 selection for grant-agreement preparation covers four projects with distinct capture, transport and storage-appraisal routes. [7] Selection can support project development but is not proof that engineering contractors have already been paid or that a full construction award exists. FMI expects suppliers to benefit as individual projects reach those contracting stages, with order timing shaped by the availability of the shared receiving infrastructure.
Carbon Capture and Storage (CCS) Market by Country (2026 to 2036)
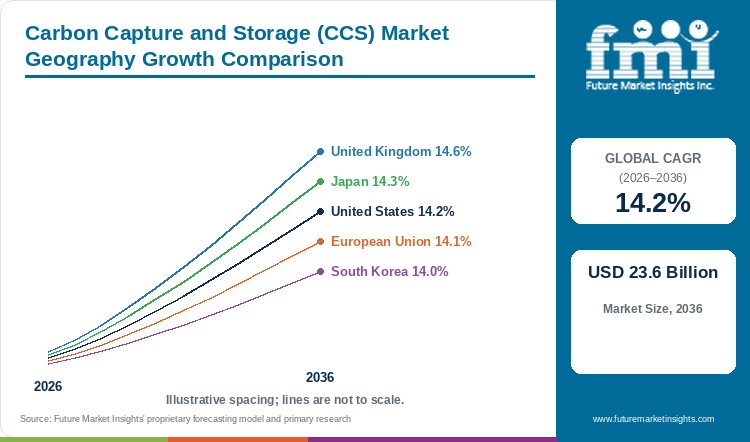
Table 5: Carbon Capture and Storage (CCS) Market Country Growth Forecast, 2026 to 2036
| Country | CAGR |
|---|---|
| United Kingdom | 14.6% |
| Japan | 14.3% |
| United States | 14.2% |
| European Union | 14.1% |
| South Korea | 14.0% |
Source: Future Market Insights, Carbon Capture and Storage (CCS) Market, 2026 to 2036.
What is driving the United Kingdom's Carbon Capture and Storage (CCS) Market?
The United Kingdom's shared transport infrastructure creates a defined route for industrial capture projects, but access remains subject to project negotiations. DESNZ's 5 August 2025 HyNet Track-1 expansion list selected six projects for negotiations after Liverpool Bay Carbon Capture and Storage Limited reached financial close on the transport-and-storage network. [2] The government assessed deliverability, value for money, affordability and departmental objectives, and retained the ability to revise Priority and Standby status. Selection therefore indicates a negotiating position rather than a construction award or operating capture capacity. For equipment suppliers, the distinction determines whether demand is still at design stage or has reached an order that can support a delivery schedule.
Baker Hughes' June 2025 announcement of three CO2 compressor trains for Saipem's Liverpool Bay work shows a specific equipment package progressing within that network. [6] FMI forecasts a 14.6% CAGR for the United Kingdom from 2026 to 2036, the highest rate in this report's comparison. The forecast rests on conversion of supported capture and infrastructure projects into deployment, rather than on every negotiated project proceeding unchanged. Suppliers serving the cluster must match compressor delivery and capture commissioning with the storage network's availability. A financed common network reduces one obstacle, while individual capture contracts, construction and operating interfaces still decide when each customer contributes revenue. This sequence makes the timing of awards as important as the nominal project queue.
How is Japan structuring its Carbon Capture and Storage (CCS) Market?
Tomakomai links Japan's capture-design programme to a specific storage area. MHI's July 2025 disclosure reports METI's selection of the sea area under the CCS Business Act and a separate JOGMEC design contract involving Hokkaido Electric Power, Idemitsu Kosan and Japan Petroleum Exploration. The planned storage volume is 1.5 to 2 million tonnes a year by 2030, with exploratory drilling under consideration in the cited disclosure. [5] These are distinct development steps: identifying an area and undertaking design work provide a route for technical appraisal, while subsurface results and later approvals determine whether it becomes a commercial receiving site. This gives capture designers an identifiable counterpart for transport and storage planning without treating an area designation as a final commissioning commitment.
Mitsubishi Heavy Industries' July 2025 basic-design contract for a planned 5,200-tonne-per-day post-combustion capture plant at Tomato-Atsuma provides a capture-side counterpart to that storage work. Its KM CDR Process and Advanced KM CDR Process had been delivered to 18 commercial plants worldwide by July 2025, while this new Japanese facility was at basic-design stage. [5] FMI forecasts Japan's market to expand at a 14.3% CAGR from 2026 to 2036. The commercial argument depends on connecting capture engineering with site appraisal and transport arrangements. A designated sea area is an important legal step, but it does not by itself prove final storage capacity, commercial construction approval or a matched commissioning date. Capture licensors have an early engineering opportunity; later equipment orders depend on the project advancing through those remaining stages.
What is shaping Carbon Capture and Storage (CCS) Market demand in the United States?
Tax-credit documentation and injection permits address separate commercial risks in the United States. Treasury and IRS guidance issued on 19 December 2025 set a safe harbour for qualifying 2025 capture and storage if EPA's electronic reporting tool was not operating by 10 June 2026. An independent engineer or geologist could provide the specified certification under that conditional route. [1] The guidance concerns the stated reporting year and conditions; it does not establish whether the contingency was needed after June or guarantee future credit treatment. FMI regards documentation certainty as relevant to project revenues, while capture construction and storage permitting remain separate decisions. Suppliers therefore need to distinguish a developer's eligibility argument from evidence that equipment has been ordered and a storage route is ready.
Occidental and 1PointFive's April 2025 Class VI approvals for STRATOS in Texas illustrate storage authorisation for a direct-air-capture project designed for up to 500,000 tonnes a year. [4] That planned capacity does not establish current output, and direct air capture remains outside this report's combustion-technology categories. The permit example informs the storage discussion without adding DAC equipment revenue to those technology categories. FMI forecasts a 14.2% CAGR for the United States from 2026 to 2036. Deployment depends on the combination of finance, permitted injection, transport access and capture commissioning. EPA's review stages make application quality and project complexity relevant to schedules. [10] A supplier assessing an order should check the status of each part of that chain rather than infer operational readiness from a tax-credit announcement or a well permit alone.
How is the European Union coordinating Carbon Capture and Storage (CCS) Market deployment?
The European Union's funding programme supports several distinct industrial capture and storage routes. Heidelberg Materials announced selection of four additional projects for Innovation Fund grant-agreement preparation on 3 November 2025: an oxyfuel project at Antoing in Belgium, a French project at Airvault with pipeline and shipping arrangements, a Rezzato-Mazzano project linked to Italy's Ravenna hub, and storage-potential appraisal in Poland. [7] These are different engineering packages rather than evidence that all four plants are already capturing CO2. The French transport route raises shipping and cross-border interfaces; the Italian hub link concerns a different local network; the Polish work addresses storage appraisal. A common funding round therefore creates opportunities across capture design, transport and subsurface evaluation without making their schedules or risks identical.
The Innovation Fund is financed by EU Emissions Trading System revenues. [8] This provides a bloc-wide funding channel, while each recipient must still arrange its own transport route, storage access and commissioning sequence. FMI forecasts the European Union market to expand at a 14.1% CAGR from 2026 to 2036. The rate reflects the commercial potential of industrial projects progressing from awards into deployment, with no assumption that a grant removes every construction or operating risk. Capture-equipment vendors can compete for plant-specific packages, whereas transport and storage providers need sufficient contracted volumes to support shared assets. The supplier opportunity consequently depends on contract scope and project maturity as well as the size of the announced funding programme.
What does South Korea's new legal framework mean for its Carbon Capture and Storage (CCS) Market?
South Korea's storage-permission requirements create separate gates for site exploration, business approval and operation. The Act on Carbon Dioxide Capture, Transport, Storage, and Utilization, as amended in 2025, requires exploration approval and storage-business permission. Its current text assigns these functions to the Minister of Climate, Energy and Environment and requires prior marine permission for offshore storage. [9] Developers therefore need a qualified storage site as well as a capture customer. A proposed industrial cluster cannot supply either approval by itself. FMI expects the quality of site evidence, the proposed operating controls and the availability of finance to influence which projects advance from preliminary plans into procurement. These are project conditions rather than proof that a national storage network is already operating.
FMI forecasts South Korea's market to expand at a 14.0% CAGR from 2026 to 2036. The commercial opportunity spans capture engineering and storage development, but each package reaches revenue at a different stage. Geological appraisal supports an early service opportunity; larger capture and compression orders depend on a credible receiving site and a coordinated construction schedule. Suppliers need to distinguish an exploration programme from a permitted storage business, and a permitted business from an operating capture-to-storage chain. The legal framework provides a process for development without guaranteeing how quickly every candidate site will qualify. FMI's outlook consequently depends on successful project conversion and matching capture demand with storage availability, while keeping commissioning and contracted volumes separate from policy ambition.
Who are the notable companies in the Carbon Capture and Storage (CCS) Market?
Occidental, the Northern Lights partners, Mitsubishi Heavy Industries and Baker Hughes represent four commercial roles in this market. Occidental and 1PointFive's cited STRATOS project combines direct-air-capture development with geological storage permits; the April 2025 approval concerns injection wells for a facility designed to capture up to 500,000 tonnes a year. [4] Northern Lights, owned by Equinor, Shell and TotalEnergies, operates a shared transport-and-storage service. Its first CO2 was stored in August 2025, while the expansion remains a separate development programme. [3][13] MHI supplies capture-process technology and engineering. Its July 2025 disclosure records 18 delivered plants and a new basic-design award at Tomato-Atsuma, rather than demonstrating that all 18 were operating at that date. [5] Baker Hughes supplies CO2 compression equipment, including the contracted Liverpool Bay package. [6] Eni's role in that network and Heidelberg Materials' industrial capture projects further distinguish infrastructure owners from emitting customers. [6][7] FMI therefore compares companies by the activity sold, the project stage and the operating responsibility they accept. Storage operators need contracted capture volumes, while equipment suppliers compete for defined packages. These roles expose participants to different development schedules and qualification requirements; they do not establish a numerical ranking of company market shares.
Key Developments in the Carbon Capture and Storage (CCS) Market
- On 17 March 2026, Northern Lights reported detailed engineering, rising onshore construction activity and major-component fabrication for Phase 2. The expansion targets more than 5 million tonnes of annual transport and storage capacity by 2028, compared with Phase 1's 1.5 million tonnes; the expanded capacity remains under development. [13]
Key Players in the Carbon Capture and Storage (CCS) Market
- Occidental Petroleum / 1PointFive
- Equinor
- Shell
- TotalEnergies
- Mitsubishi Heavy Industries
- Baker Hughes
- Heidelberg Materials
- Eni
Carbon Capture and Storage (CCS) Market Report Scope
Table 6: Carbon Capture and Storage (CCS) Market Report Scope
| Coverage field | Report scope |
|---|---|
| Market definition | Revenue from carbon capture, transport, storage and utilization systems deployed across the industries and applications listed in this report. |
| Technology | Post-combustion; Pre-combustion; Oxy-fuel Combustion |
| End-Use Industry | Oil and Gas; Coal and Biomass Power Plant; Iron and Steel; Chemicals; Others |
| Product | Carbon Capture Systems (post-combustion, pre-combustion and oxy-fuel); Carbon Transport Systems (pipeline and ship); Carbon Storage Solutions (geological and ocean); Carbon Utilization Solutions (enhanced oil recovery, chemical conversion and mineralization). |
| Application | Power Generation; Oil and Gas; Cement Production; Iron and Steel; Chemical and Petrochemical |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Profiled markets | United Kingdom, Japan, United States, European Union, South Korea |
| Companies covered | Occidental Petroleum / 1PointFive; Equinor; Shell; TotalEnergies; Mitsubishi Heavy Industries; Baker Hughes; Heidelberg Materials; Eni |
| Quantitative Units | USD billion |
Source: Future Market Insights, Carbon Capture and Storage (CCS) Market, 2026 to 2036.
Carbon Capture and Storage (CCS) Market Research Methodology
This assessment uses the report's market outlook and classifications alongside secondary review of the official and company records in the bibliography. Market figures were checked for currency, units, forecast-period arithmetic and consistency across the narrative, tables and FAQs. The technology and end-use share findings were retained within their stated classifications. The product assessment draws on value-chain investment structure and procurement evidence, with separate consideration of supplier revenue. Project announcements were reviewed for dates, contract scope and planned versus operating status.
Carbon Capture and Storage (CCS) Market by Segments
Carbon Capture and Storage (CCS) Market segmented by Technology:
- Post-combustion
- Pre-combustion
- Oxy-fuel Combustion
Carbon Capture and Storage (CCS) Market segmented by End-Use Industry:
- Oil and Gas
- Coal and Biomass Power Plant
- Iron and Steel
- Chemicals
- Others
Carbon Capture and Storage (CCS) Market segmented by Product:
- Carbon Capture Systems
- Post Combustion Capture
- Pre Combustion Capture
- Oxy Fuel Combustion Capture
- Carbon Transport Systems
- Pipeline Transport
- Ship Transport
- Carbon Storage Solutions
- Geological Storage
- Ocean Storage
- Carbon Utilization Solutions
- Enhanced Oil Recovery
- Chemical Conversion
- Mineralization
Carbon Capture and Storage (CCS) Market segmented by Application:
- Power Generation
- Oil and Gas
- Cement Production
- Iron and Steel
- Chemical and Petrochemical
Carbon Capture and Storage (CCS) Market by Region
- North America
- USA
- Canada
- Mexico
- Latin America
- Brazil
- Chile
- Rest of Latin America
- Western Europe
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- Middle East & Africa
- Saudi Arabia
- Other GCC Countries
- Turkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
Research Sources and Bibliography
- [1] Internal Revenue Service / US Department of the Treasury. Treasury, IRS provide safe harbor for taxpayers claiming the carbon capture credit. IR-2025-122, 19 December 2025.
- [2] Department for Energy Security and Net Zero (United Kingdom). Track 1 Expansion of the HyNet CCUS Cluster: project negotiation list. 5 August 2025.
- [3] Equinor ASA. Northern Lights. Project page, accessed 2 November 2026.
- [4] Occidental Petroleum Corporation / 1PointFive. Occidental and 1PointFive Secure Class VI Permits for STRATOS Direct Air Capture Facility. 7 April 2025.
- [5] Mitsubishi Heavy Industries, Ltd. MHI Awarded Contract for Basic Design of Japan's Largest CO2 Capture Plant at Hokkaido Electric Power's Tomato-Atsuma Power Station. Press release, 7 July 2025.
- [6] Baker Hughes Company. Baker Hughes to Provide CO2 Compressor Technology to Saipem for Eni's Liverpool Bay CCS Project. Press release, 30 June 2025.
- [7] Heidelberg Materials AG. Heidelberg Materials Secures Four Additional EU Innovation Fund Grants to Drive Decarbonisation Projects. Press release, 3 November 2025.
- [8] European Commission, European Climate, Infrastructure and Environment Executive Agency (CINEA). The Innovation Fund. Programme page, accessed 2 November 2026.
- [9] Korea Legislation Research Institute. Act on Carbon Dioxide Capture, Transport, Storage, and Utilization, Act No.20203 of 6 February 2024, as amended through 2 December 2025; Articles13,18,25to28. Accessed 2 November 2026. https://elaw.klri.re.kr/eng_mobile/viewer.do?hseq=72473&key=39&type=part
- [10] US Environmental Protection Agency. Class VI Wells Permitted by EPA: permit review process. Programme page, accessed 2 November 2026.
- [11] International Energy Agency. Policy and financing momentum sustain CCUS progress despite setbacks. 27 March 2026. https://www.iea.org/commentaries/policy-and-financing-momentum-sustain-ccus-progress-despite-setbacks
- [12] Global CCS Institute. Global Status of CCS 2026, global and regional overview; project data as at 31 July 2026. Accessed 2 November 2026. https://www.globalccsinstitute.com/global-status-of-ccs/
- [13] Northern Lights JV. Northern Lights Phase 2: Expanding Europe's CO2 Storage Capacity. 17 March 2026. https://norlights.com/news/northern-lights-phase-2-expanding-europes-co%E2%82%82-storage-capacity/
- [14] Northern Lights JV. Northern Lights hosts signing ceremony for expanded CO2 fleet. 5 March 2026. https://norlights.com/news/northern-lights-hosts-signing-ceremony-for-expanded-co%E2%82%82-fleet/
- [15] Gassnova SF. Potential for Cost Reductions in the CCS Value Chain. 6 June 2025; analysis based on Longship Phase 1 and work undertaken May to November 2024. https://gassnova.no/app/uploads/sites/6/2025/09/Ny080925_ENG_Endelig_Ekstern-rapport-Kostnader.pdf
- [16] SLB. SLB Capturi and Aker Solutions win contract to deliver carbon capture solution for Hafslund Celsio. 27 January 2025. https://www.slb.com/newsroom/press-release/2025/slb-capturi-and-aker-solutions-win-contract-to-deliver-carbon-capture-solution-for-hafslund-celsio
- [17] Office of the Federal Register and US Environmental Protection Agency. 40 CFR 146.86, Injection well construction requirements, paragraphs (b) and (c). eCFR text displayed current through 28 October 2026; accessed 3 November 2026. https://www.ecfr.gov/current/title-40/chapter-I/subchapter-D/part-146/subpart-H/section-146.86
- [18] ExxonMobil. Expanding our CCS operations in Louisiana with another project startup. 18 February 2026. https://corporate.exxonmobil.com/what-we-do/delivering-industrial-solutions/carbon-capture-and-storage/expanding-our-ccs-operations-in-louisiana-with-another-project-startup
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Technology, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Technology, 2026 to 2036
- Post-combustion
- Pre-combustion
- Oxy-fuel Combustion
- Y-o-Y Growth Trend Analysis By Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By Technology, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Industry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Industry, 2026 to 2036
- Oil and Gas
- Coal and Biomass Power Plant
- Iron and Steel
- Chemicals
- Others
- Y-o-Y Growth Trend Analysis By End-Use Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Product, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product, 2026 to 2036
- Carbon Capture Systems
- Post Combustion Capture
- Pre Combustion Capture
- Oxy Fuel Combustion Capture
- Carbon Transport Systems
- Pipeline Transport
- Ship Transport
- Carbon Storage Solutions
- Geological Storage
- Ocean Storage
- Carbon Utilization Solutions
- Enhanced Oil Recovery
- Chemical Conversion
- Mineralization
- Y-o-Y Growth Trend Analysis By Product, 2021 to 2025
- Absolute $ Opportunity Analysis By Product, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Power Generation
- Oil and Gas
- Cement Production
- Iron and Steel
- Chemical and Petrochemical
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- Mexico
- By Technology
- By End-Use Industry
- By Product
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By End-Use Industry
- By Product
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Chile
- Rest of Latin America
- By Technology
- By End-Use Industry
- By Product
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By End-Use Industry
- By Product
- By Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Technology
- By End-Use Industry
- By Product
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By End-Use Industry
- By Product
- By Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Technology
- By End-Use Industry
- By Product
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By End-Use Industry
- By Product
- By Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Technology
- By End-Use Industry
- By Product
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By End-Use Industry
- By Product
- By Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Technology
- By End-Use Industry
- By Product
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By End-Use Industry
- By Product
- By Application
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Saudi Arabia
- Other GCC Countries
- Turkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Technology
- By End-Use Industry
- By Product
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By End-Use Industry
- By Product
- By Application
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End-Use Industry
- By Product
- By Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End-Use Industry
- By Product
- By Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End-Use Industry
- By Product
- By Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End-Use Industry
- By Product
- By Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End-Use Industry
- By Product
- By Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End-Use Industry
- By Product
- By Application
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End-Use Industry
- By Product
- By Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End-Use Industry
- By Product
- By Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End-Use Industry
- By Product
- By Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End-Use Industry
- By Product
- By Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End-Use Industry
- By Product
- By Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End-Use Industry
- By Product
- By Application
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End-Use Industry
- By Product
- By Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End-Use Industry
- By Product
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End-Use Industry
- By Product
- By Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End-Use Industry
- By Product
- By Application
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End-Use Industry
- By Product
- By Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End-Use Industry
- By Product
- By Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End-Use Industry
- By Product
- By Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End-Use Industry
- By Product
- By Application
- European Union
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By End-Use Industry
- By Product
- By Application
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Technology
- By End-Use Industry
- By Product
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Occidental Petroleum / 1PointFive
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Equinor / Shell / TotalEnergies (Northern Lights)
- Mitsubishi Heavy Industries
- Baker Hughes
- Equinor
- Shell
- TotalEnergies
- Heidelberg Materials
- Eni
- Occidental Petroleum / 1PointFive
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 18: Western Europe Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 26: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 28: East Asia Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 29: East Asia Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 30: East Asia Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 36: Middle East & Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: Middle East & Africa Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 38: Middle East & Africa Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 39: Middle East & Africa Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 40: Middle East & Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Technology
- Figure 6: Global Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by End-Use Industry
- Figure 9: Global Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Product
- Figure 12: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Application
- Figure 15: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East & Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Technology
- Figure 29: North America Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by End-Use Industry
- Figure 32: North America Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Product
- Figure 35: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Application
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Technology
- Figure 42: Latin America Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by End-Use Industry
- Figure 45: Latin America Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Product
- Figure 48: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Application
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Technology
- Figure 55: Western Europe Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by End-Use Industry
- Figure 58: Western Europe Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by Product
- Figure 61: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Application
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Technology
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by End-Use Industry
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by Product
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by Application
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Technology
- Figure 81: East Asia Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by End-Use Industry
- Figure 84: East Asia Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by Product
- Figure 87: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by Application
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by Technology
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by End-Use Industry
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by Product
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 103: Middle East & Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East & Africa Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 105: Middle East & Africa Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 106: Middle East & Africa Market Attractiveness Analysis by Technology
- Figure 107: Middle East & Africa Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 108: Middle East & Africa Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 109: Middle East & Africa Market Attractiveness Analysis by End-Use Industry
- Figure 110: Middle East & Africa Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 111: Middle East & Africa Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 112: Middle East & Africa Market Attractiveness Analysis by Product
- Figure 113: Middle East & Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 114: Middle East & Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 115: Middle East & Africa Market Attractiveness Analysis by Application
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
What is the forecast for the Carbon Capture and Storage (CCS) Market?
FMI projects USD 23.57 billion by 2036, from USD 6.25 billion in 2026 and USD 5.5 billion in 2025, with a 14.2% CAGR from 2026 to 2036, adding USD 17.32 billion of revenue over the period.
Which technology leads the Carbon Capture and Storage (CCS) Market in 2026?
Post-combustion leads the technology breakdown with a 48.0% share in FMI's 2026 assessment.
Which end-use industry and product lead the Carbon Capture and Storage (CCS) Market in 2026?
Oil and Gas leads by end-use industry with 42.0%, and Carbon Capture Systems lead by product with 63.0%, in FMI's 2026 assessment.
Which profiled market has the highest forecast growth?
The United Kingdom has the highest forecast CAGR among the profiled markets at 14.6% from 2026 to 2036, followed by Japan at 14.3%, the United States at 14.2%, the European Union at 14.1% and South Korea at 14.0%.
Does an EPA Class VI storage permit guarantee capture-plant commissioning?
No. EPA's Class VI process concerns injection wells and their conditions; approval does not establish that a capture plant is operating or guarantee its commissioning date. Capture construction, transport availability and storage readiness require separate evidence. [10]
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
