

- Market Size (2026)
- USD 1185.8 Bn
- Forecast (2036)
- USD 1754.8 Bn
- CAGR (2026 to 2036)
- 4.0%
How big is Carbon Steel Market in 2026?
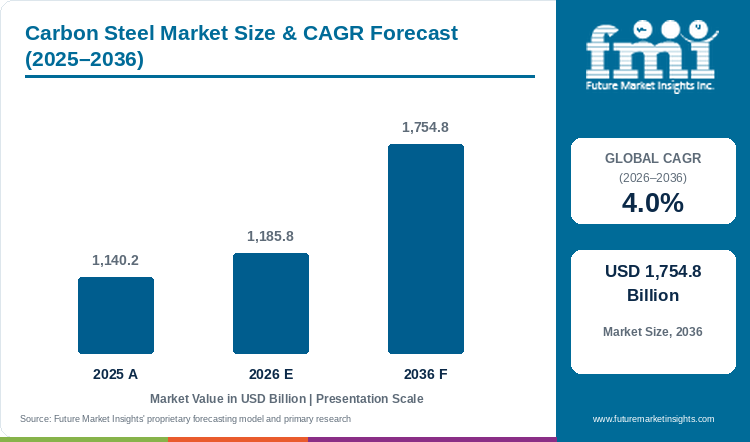
The carbon steel market is estimated at USD 1,140.2 billion in 2025 and is projected to reach USD 1,185.8 billion in 2026. Sales of carbon steel are expected to grow at a 4% CAGR and reach USD 1,754.8 billion by 2036.
Sales of carbon steel follow building frames, car bodies and machinery, and sales of carbon steel are estimated at USD 1,140.2 billion in 2025. In FMI's outlook, a rise to USD 1,185.8 billion is projected for the carbon steel market in 2026. A 4% CAGR across the forecast period is expected to take sales of carbon steel to USD 1,754.8 billion by 2036. Tonnage is flat near term, so growth leans on coated, high-strength and lower-emission grades. On 12 October 2026, worldsteel forecast global steel demand to stay essentially unchanged in 2026 at 1,722 Mt, before growth of 1.7% to 1,752 Mt in 2027.[1] With flat volume, mills price for grade and service, and buyers in developed economies will see contract volumes pick up first.
Results and trade rules are changing buying terms. ArcelorMittal reported Q2 2026 steel prices of USD 1,161 per tonne in North America and USD 967 per tonne in Europe, and said the EU tariff rate quota in force from 1 July 2026, together with CBAM, can support higher domestic capacity utilization.[2] For European fabricators and carmakers, country-specific import quotas shrink the pool of low-cost coil, so annual contracts with EU mills will carry more weight than spot imports. American buyers pay the highest regional price, so talks there turn on lead times and grade availability.
Key Market Trends & Insights
- Mild grades keep low-carbon steel in front within carbon content, with an expected 58.4% share in 2026. Medium-carbon steel is likely to hold 27.6%, and high-carbon grades for springs, wire and blades make up an estimated 14%.
- Flat products are projected to account for 72.5% of 2026 sales by product type, ahead of long products at about 27.5%. Tata Steel reported 21% year-on-year growth in hi-end automotive sales for the quarter to June 2026.[3]
- Demand for carbon steel from building and construction is likely to hold 34% of end use sales in 2026, with automotive the second largest user at an estimated 15.2%. Gerdau said civil construction in Brazil performed relatively steadily in Q2 2026.[4]
Regional Highlights
- Highway, metro and housing work keeps India first, with a 4.8% CAGR per FMI's country model, faster than the market average of 4%.
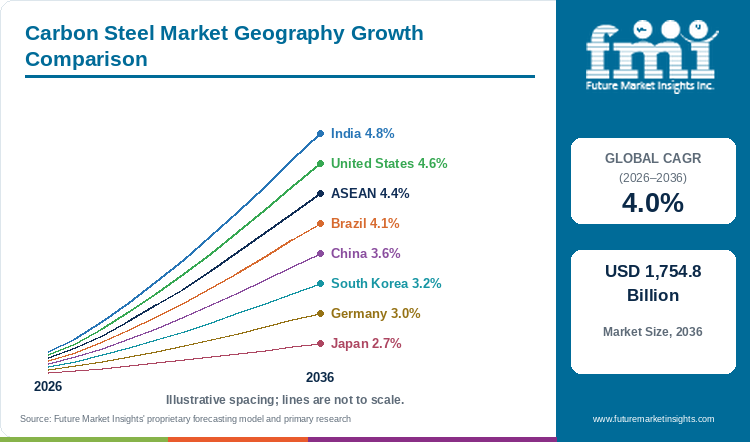
- The United States follows at 4.6% behind tariff protection, with ASEAN (4.4%) and Brazil (4.1%) next. Growth below the global rate is projected for China (3.6%) and South Korea (3.2%). Japan, at 2.7%, is last in the country ranking, one notch below Germany on 3%.
- India produced 14.8 Mt of crude steel in August 2026, up 4.6% year on year, according to worldsteel.[5]
Market Size & Forecast
Table 1: Market Size and Forecast for the Carbon Steel Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 1,140.2 billion |
| Estimated Market Size in 2026 | USD 1,185.8 billion |
| Projected Market Size by 2036 | USD 1,754.8 billion |
| CAGR, 2026 to 2036 | 4% |
| Added Revenue, 2026 to 2036 | USD 569 billion |
| Market Expansion Multiple | 1.5x |
Carbon steel is bought through quarterly or annual mill contracts by carmakers and pipe makers, and through service centers by fabricators who order by the week, so mill utilization moves before list prices do. Nucor ran steel mills at 91% utilization in the quarter to 4 July 2026, up from 86%, and shipped 7,100 thousand tons at an external average of USD 1,145 per ton.[6] Gerdau raised consolidated shipments 3% year on year to 2.9 million tonnes in Q2 2026.[4] Coil from these mills passes through slitting and storage lines, and the steel coil handling equipment market is projected at a CAGR of 4.4%, a sign that service centers keep adding processing capacity. FMI analysts expect the carbon steel market to gain USD 569 billion over the decade, so 2036 sales will be about one and a half times the 2026 estimate. Excess capacity remains the main risk, as new furnaces in several regions can push export prices down.
Trade Quotas, Mill Pricing and the Shift to Electric Furnaces
Trade rules now decide which mills supply carbon steel buyers. The United States raised Section 232 duties on steel imports from 25% to 50% from 4 June 2025, with UK steel kept at 25%.[7] The EU tariff rate quota applied from 1 July 2026 introduced country-specific import quotas, which ArcelorMittal called a meaningful improvement.[2] Brazil renewed a tariff quota system in June 2026, cutting the annual quota volume by 30% for certain product codes, and Gerdau said Brazilian steel imports fell more than 30% in Q2 2026 against the prior quarter.[4] Buyers in protected regions will pay closer to domestic mill prices and sign longer supply terms.
Grade and route are the second shift. POSCO completed a 2.5 million ton electric arc furnace at Gwangyang in June 2026, with carbon emissions up to about 75% lower than a blast furnace.[8] ArcelorMittal is studying a potential second 1.5 Mt electric arc furnace at Calvert in the United States.[2] Tata Steel said Tata Tiscon rebar and Tata Steelium cold-rolled sheet each grew more than 30% year on year in the June 2026 quarter.[3] Carmakers and builders asking for lower embedded carbon will place more orders with furnace-based mills.
Table 2: Trade, Price and Production Indicators for the Carbon Steel Market (tariffs, prices and output), 2025 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Global steel demand forecast, 2026 | 1,722 Mt, essentially unchanged; 1,752 Mt in 2027 | Flat tonnage, value from grade mix | [1] |
| US Section 232 steel duty, June 2025 | Raised from 25% to 50% | Higher domestic price floor in the United States | [7] |
| ArcelorMittal steel prices, Q2 2026 | USD 1,161/t North America; USD 967/t Europe; USD 798/t Brazil | Regional price spread for buyers | [2] |
| Nucor steel mills, Q2 2026 | 91% utilization; USD 1,145 per ton | Tight US mill capacity | [6] |
| Brazil steel imports, Q2 2026 | Down more than 30%; 22.5% import penetration in H1 2026 | Effect of the renewed tariff quota | [4] |
| POSCO Gwangyang furnace, June 2026 | 2.5 million tons of annual capacity; up to 75% lower emissions | Low-carbon flat steel supply | [8] |
| India crude steel output, August 2026 | 14.8 Mt; up 4.6% | Fastest-growing large producer | [5] |
Analyst Perspective
“Coated and high-strength flat steel made in electric arc furnaces will give mills the best margins of the next decade, as carmakers and builders now ask for lower embedded carbon alongside price. Furnace-based producers near protected markets are opening a premium lane for low-emission coil, and I expect buyers in the United States and the EU to sign multi-year contracts for that steel well before 2030.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the carbon steel market segmented?
The market is segmented into carbon content, product type, end use, and region. Low-carbon steel is expected to hold the largest carbon content share at 58.4% in 2026, and flat products the largest product type share at 72.5%.
By carbon content: low-carbon steel, medium-carbon steel, and high-carbon steel.
By product type: flat products and long products.
By end use: building and construction, automotive, oil and gas and energy, heavy machinery and equipment, shipbuilding and marine, railways, consumer appliances, and aerospace and others.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does low-carbon steel lead carbon steel sales by carbon content?
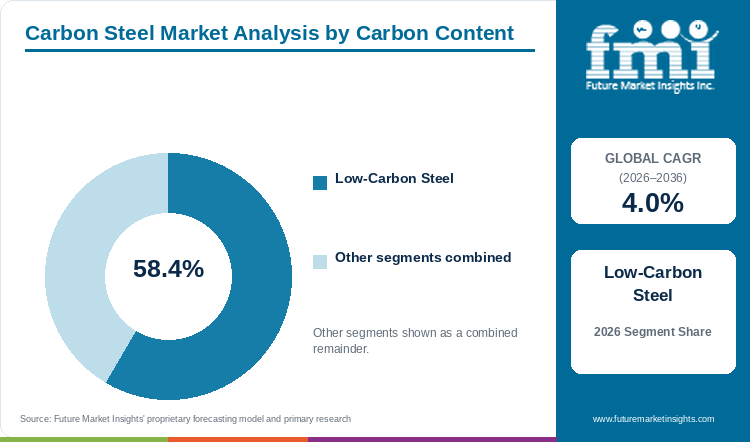
Low-carbon steel is expected to lead carbon content sales with 58.4% share in 2026, ahead of medium-carbon steel at 27.6% and high-carbon steel at an estimated 14%.
Table 3: Carbon Content Share for the Carbon Steel Market (percentage share), 2026
| Carbon Content | Estimated Share (2026) |
|---|---|
| Low-Carbon Steel | 58.4% |
| Medium-Carbon Steel | 27.6% |
| High-Carbon Steel | 14% |
| Total | 100.0% |
Table 4: Carbon Content Leadership and Market Growth for the Carbon Steel Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4% |
| Leading Segment | Low-Carbon Steel |
Rebar, beams, car body panels and appliance casings all need steel that welds and bends without cracking, so low-carbon steel is expected to lead in 2026, holding a 58.4% share. Medium-carbon steel, at 27.6%, goes into axles, crankshafts, rails and gears, and every tonne passes through forging and heat treatment, which limits volume to machine and vehicle builders. High-carbon steel, an estimated 14%, makes springs, wire rope, bearings and blades, and those buyers order in small lots at higher prices per tonne. Mild grades also come from scrap-fed furnaces with little alloy control, so new electric furnace capacity adds low-carbon supply first. Demand for corrosion-resistant grades in food plants and chemical lines goes to alloyed steel, and the stainless steel market has a projected CAGR of 5.4%, which keeps carbon steel focused on structural and body uses. Builders and carmakers will keep low-carbon steel as the default specification.
- Rebar, wire rod, structural sections and deep-drawing sheet form most low-carbon volume.
- Tata Tiscon rebar and Tata Steelium cold-rolled sheet each grew more than 30% year on year in the quarter to June 2026, Tata Steel reported.[3]
Why do flat products lead carbon steel sales by product type?
Flat products are projected to lead product type sales with 72.5% share in 2026, against an estimated 27.5% for long products.
Table 5: Product Type Share for the Carbon Steel Market (percentage share), 2026
| Product Type | Estimated Share (2026) |
|---|---|
| Flat Products | 72.5% |
| Long Products | 27.5% |
| Total | 100.0% |
Carmakers, appliance makers, pipe mills and shipyards all buy coil, sheet and plate, so flat products are projected to take the lead in 2026 at a 72.5% share. Long products, an estimated 27.5%, cover rebar, wire rod, sections and rails, and most of that tonnage goes to construction sites at lower prices per tonne than coated sheet. Construction also buys flat steel as roofing, decking, purlins and plate for bridges, so a 34% construction share is consistent with a large flat products lead. Galvanized and painted coil commands a premium over hot-rolled coil, and growth of the galvanized and coated iron and steel sheets market keeps coating lines among the busiest at integrated mills. Car body panels face pressure from aluminium in some electric vehicle programmes, and the aluminum flat products market competes for closures and battery trays. Mills will defend flat steel share with thinner high-strength grades that cut vehicle weight.
- Hot-rolled coil, cold-rolled sheet, galvanized coil and heavy plate make up the flat product range.
- POSCO aims to mass-produce automotive and electrical steel sheet from the new Gwangyang furnace by 2030.[8]
Why does building and construction lead carbon steel sales by end use?
Building and construction is likely to lead end use sales with 34% share in 2026, ahead of automotive at an estimated 15.2% and heavy machinery and equipment at about 13.5%.
Table 6: End Use Share for the Carbon Steel Market (percentage share), 2026
| End Use | Estimated Share (2026) |
|---|---|
| Building and Construction | 34% |
| Automotive | 15.2% |
| Heavy Machinery and Equipment | 13.5% |
| Oil and Gas and Energy | 11.8% |
| Consumer Appliances | 7.3% |
| Aerospace and Others | 6.7% |
| Shipbuilding and Marine | 6.4% |
| Railways | 5.1% |
| Total | 100.0% |
Every bridge, warehouse, tower and housing block uses rebar, beams and decking in large tonnages, so building and construction is likely to stay the largest user in 2026, with a 34% share. Automotive, an estimated 15.2%, buys higher-value coated and high-strength sheet, but car output in Europe and Japan is under pressure. Heavy machinery and equipment, about 13.5%, buys plate and bar for cranes, excavators and presses, and orders follow capital investment cycles. Oil and gas and energy, near 11.8%, needs line pipe, tower steel and plate, and project timing makes volumes uneven. Consumer appliances account for an estimated 7.3%, aerospace and others 6.7%, shipbuilding and marine 6.4% and railways 5.1%, each with fewer and larger orders. In India, infrastructure-led construction remains the primary driver, worldsteel said.[1] Construction will keep the lead as long as public works budgets hold.
- Rebar, structural sections, roofing coil and bridge plate form most construction tonnage.
- Gerdau said civil construction performed relatively steadily in Q2 2026 and that Miguel Burnier and Pindamonhangaba were scheduled to start operations in the third quarter.[4]
What are the drivers, restraints, and opportunities in the carbon steel market?
Public works, grid build and factory investment keep steady demand for carbon steel frames, plate and pipe. Excess capacity and trade barriers cloud prices, and lower-emission furnace steel opens premium contracts with carmakers and builders.
- Driver: Governments and utilities building roads, rail, grids and housing need structural steel and rebar in volume, which gives mills a base load of orders.
- Restraint: Surplus capacity in some exporting regions pushes low-cost steel into open markets, and importing countries answer with quotas that fragment pricing.
- Opportunity: Carmakers and builders with emission targets want certified low-carbon steel, which favours furnace-based mills able to document the carbon content of each order.
Public Works and Factory Building Keep Orders Steady
Adoption of carbon steel in new structures follows public and corporate investment, and developed economies are adding both. worldsteel expects steel demand in the developed world to grow 1% in 2026 and 2.2% in 2027.[1] Nucor linked consecutive quarters of higher mill shipments in 2026 to investment across key sectors of the U.S. economy.[6] Each new data center, plant or grid project adds a block of beam, plate and rebar orders.
Surplus Capacity and Quotas Split Prices by Region
Surplus capacity, and the trade defences raised against surplus steel, weigh on carbon steel prices. China produced 74.6 Mt of crude steel in August 2026, down 3.7% year on year, against demand that worldsteel expects to contract by 2% in 2026.[5][1] The EU tariff rate quota from 1 July 2026 joins US duties of 50% on imported steel.[2][7] Prices for the same coil grade will keep diverging between protected and open markets.
Low-Emission Furnace Steel Opens Premium Contracts
Growth of the carbon steel market will come partly from buyers paying for documented lower emissions. POSCO began producing low-carbon steel at Gwangyang in June 2026 and plans to complete HyREX hydrogen reduction technology by 2030.[8] ArcelorMittal said CBAM can support higher domestic capacity utilization in Europe.[2] Mills able to certify the carbon footprint of each coil will sign the longest automotive and building contracts.
Which country CAGRs are profiled in the carbon steel market?
Table 7: Country CAGR Comparison for the Carbon Steel Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| India | 4.8% |
| United States | 4.6% |
| ASEAN | 4.4% |
| Brazil | 4.1% |
| China | 3.6% |
| South Korea | 3.2% |
| Germany | 3% |
| Japan | 2.7% |
How do country-level CAGRs compare in the carbon steel market?
Indian builders are pouring rebar into highways, metro lines and housing, and worldsteel forecasts Indian steel demand to grow 7.9% in 2026 to 172.4 Mt.[1] FMI's country table places India first at 4.8%. The United States, on 4.6%, is protected by 50% Section 232 duties, and ASEAN, at 4.4%, gains from new mills and construction in Viet Nam and the region. Brazil follows on 4.1% after cutting import quotas. China grows at 3.6% as property building shrinks, and South Korea, at 3.2%, rebuilds after a steep fall in 2025. Weak car output and slow construction hold Germany to 3% and Japan to 2.7%.
- Highway, rail and housing programmes keep Indian rebar orders rising.
- Fifty percent import duties keep American buyers close to domestic mills.
- New mills in Viet Nam push ASEAN output and consumption up.
- A renewed tariff quota protects Brazilian producers of flat and long steel.
- Property weakness cuts construction steel use in China.
- Korean shipyards and carmakers anchor plate and sheet demand.
- German automotive and machinery buyers order cautiously.
- Capital goods and export orders keep Japanese mills busy.
Full report country CAGRs cover: India and the United States at the top, with ASEAN and Brazil close behind. China and South Korea under the 4% global rate. Germany and Japan slowest, plus every other standard country by region.
Country-wise Analysis
India Carbon Steel Market Outlook (2026 to 2036)
Per FMI's country model, India has the top rate among the eight countries, a 4.8% CAGR. Tata Steel delivered 5.17 million tons in India in the quarter to June 2026 despite maintenance shutdowns at Meramandali and Kalinganagar.[3] worldsteel said Indian automotive output is supported by domestic demand, exports and policy support.[1] Rebar for infrastructure and cold-rolled sheet for vehicles will carry Indian demand.
Key takeaway: Infrastructure and vehicle output keep India in front.
United States Carbon Steel Market Outlook (2026 to 2036)
FMI analysts expect a 4.6% CAGR for the United States, the second-highest rate in the table. A 50% duty on imported steel from June 2025 raised the price floor in the United States.[7] Nucor reported Q2 2026 net sales of USD 10.40 billion, up 23% year on year, and expects higher realized pricing across all major product categories in the third quarter.[6] Domestic mini-mills will supply most new data center, factory and grid projects.
Key takeaway: Tariff protection and factory building support American mills.
ASEAN Carbon Steel Market Outlook (2026 to 2036)
Crude steel output in Viet Nam rose 36.4% year on year to 2.7 Mt in August 2026.[5] worldsteel forecasts ASEAN-5 steel demand to grow 5.2% in 2026.[1] New flat mills and construction across the region support a CAGR of 4.4% for ASEAN, and imports of coated coil will keep falling as local mills add lines.
Key takeaway: New local mills drive ASEAN growth.
Brazil Carbon Steel Market Outlook (2026 to 2036)
Brazil renewed a tariff quota system in June 2026, and Gerdau said import penetration averaged 22.5% in the first half of 2026 before imports fell more than 30% in the second quarter.[4] Domestic mills will recover share in rebar and flat steel, supporting a 4.1% CAGR for Brazil.
Key takeaway: Import quotas return volume to Brazilian mills.
China Carbon Steel Market Outlook (2026 to 2036)
Chinese mills produced 74.6 Mt of crude steel in August 2026, 3.7% less than a year earlier.[5] worldsteel expects demand in China to contract by 2% in 2026 and by 1% in 2027.[1] Growth of 3.6% for China will come from higher grades for vehicles, machinery and grids as property building shrinks.
Key takeaway: Grade upgrading offsets weak property demand in China.
South Korea Carbon Steel Market Outlook (2026 to 2036)
POSCO completed a KRW 600 billion electric arc furnace with 2.5 million tons of annual capacity at Gwangyang in June 2026.[8] Korean shipyards and carmakers buy heavy plate and sheet, and worldsteel expects Korean demand to grow 1.8% in 2026 after a steep fall in 2025.[1] A CAGR of 3.2% is projected for South Korea.
Key takeaway: Low-carbon furnace capacity supports Korean flat steel.
Germany Carbon Steel Market Outlook (2026 to 2036)
German crude steel output rose 1.7% year on year to 2.6 Mt in August 2026.[5] The EU tariff rate quota from July 2026 limits low-cost imports into Germany and other member states.[2] Automotive and machinery buyers remain cautious, so German growth is projected at a CAGR of 3%.
Key takeaway: Quota protection helps German mills, and weak car output holds growth back.
Japan Carbon Steel Market Outlook (2026 to 2036)
worldsteel expects Japanese steel demand to grow 0.9% in 2026 and 1.7% in 2027, as corporate capital investment supports machinery and automotive output remains under pressure.[1] Japanese crude steel output was 6.7 Mt in August 2026, up 0.4%.[5] The FMI forecast for Japan is a 2.7% CAGR, with export and machinery orders carrying most demand.
Key takeaway: Machinery and export orders carry Japan.
Who are the notable companies in the carbon steel market?
China Baowu Group, ArcelorMittal, Nippon Steel, POSCO, HBIS Group, Jiangsu Shagang, Ansteel Group, JFE Steel, Nucor, Tata Steel and Gerdau are the profiled companies.
Buyers choose carbon steel suppliers by grade range, coating lines and delivery reach, and the leading producers span integrated mills and furnace-based groups. ArcelorMittal reported Q2 2026 sales of USD 16.8 billion and EBITDA of USD 2,064 million on 13.4 Mt of steel shipments.[2] Steel mill shipments at Nucor rose 10% year on year to 7,100 thousand tons in the same quarter.[6] Consolidated EBITDA at Tata Steel rose 25% year on year to Rs 9,370 crores.[3] Gerdau's Q2 2026 net sales were R$17.9 billion, 6.9% higher than in the first quarter.[4] FMI's company set also covers China Baowu Group, Nippon Steel, POSCO, HBIS Group, Jiangsu Shagang, Ansteel Group and JFE Steel.
- Asian integrated producers: China Baowu Group, Nippon Steel, POSCO, HBIS Group, Jiangsu Shagang, Ansteel Group and JFE Steel.
- Multi-region steelmakers: ArcelorMittal and Tata Steel.
- Americas furnace-based groups: Nucor and Gerdau.
Competitive Benchmarking: Carbon Steel Market
Table 8: Competitive Benchmarking for the Carbon Steel Market (qualitative documentation ratings), 2026
| Company | Flat Products | Long Products | Low-Emission Route | Recency |
|---|---|---|---|---|
| ArcelorMittal | High | Medium | High | High |
| Nucor | Medium | High | High | High |
| POSCO | High | Low | High | High |
| Tata Steel | High | High | Medium | High |
| Gerdau | Low | High | Medium | High |
Scores track the detail in 2025 and 2026 company releases for each column, and none of them signals market share.
Key Developments in the Carbon Steel Market
- On 12 October 2026, worldsteel forecast global steel demand at 1,722 Mt for 2026 and 1,752 Mt for 2027.[1]
- On 24 September 2026, worldsteel put August 2026 crude steel output at 144.2 Mt for 70 countries, down 1.2%.[5]
- On 4 August 2026, Gerdau said Midlothian was expected to begin operations in the second half of 2026.[4]
- On 30 July 2026, ArcelorMittal welcomed the new EU tariff rate quota alongside CBAM in the second quarter results.[2]
- On 30 July 2026, Tata Steel reported best-ever first-quarter automotive and special products sales.[3]
- On 27 July 2026, Nucor guided to higher consolidated earnings for the third quarter of 2026.[6]
- On 22 June 2026, POSCO marked completion of the 2.5 million ton Gwangyang electric arc furnace.[8]
- On 3 June 2025, a US proclamation raised Section 232 steel duties to 50% from 4 June 2025.[7]
Key Players in the Carbon Steel Market
Asian Integrated Producers
- China Baowu Group
- Nippon Steel
- POSCO
- HBIS Group
- Jiangsu Shagang
- Ansteel Group
- JFE Steel
Multi-Region Steelmakers
- ArcelorMittal
- Tata Steel
Americas Furnace-Based Groups
- Nucor
- Gerdau
Carbon Steel Market - Report Scope
Table 9: Report Scope for the Carbon Steel Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Carbon content; product type; end use; region |
| Quantitative units | USD billion |
| Market definition | Iron-carbon steel with carbon as the main alloying element, sold as flat products such as coil, sheet and plate and as long products such as rebar, wire rod, sections and rails, for construction, vehicles, machinery, energy, ships, rail and appliances. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | China Baowu Group, ArcelorMittal, Nippon Steel, POSCO, HBIS Group, Jiangsu Shagang, Ansteel Group, JFE Steel, Nucor, Tata Steel, Gerdau |
| Forecast period | 2026 to 2036 |
Carbon Steel Market - Research Methodology
Table 10: Research Methodology for the Carbon Steel Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Steelmaker results, trade body production and demand releases, and government trade proclamations dated May 2025 or later. |
| Desk Research | Desk research covers mill utilization, regional prices, import quotas, furnace investments and end use demand. |
| Market Sizing and Forecasting | Sizing starts from the 2026 base of USD 1,185.8 billion and the 4% CAGR for 2026 to 2036. |
| Data Validation | Output, price and tariff figures were matched to the release or proclamation that first carried them. |
Carbon Steel Market by Segments
Carbon Steel Market segmented by Carbon Content:
- Low-Carbon Steel
- Medium-Carbon Steel
- High-Carbon Steel
Carbon Steel Market segmented by Product Type:
- Flat Products
- Long Products
Carbon Steel Market segmented by End Use:
- Building and Construction
- Automotive
- Oil and Gas and Energy
- Heavy Machinery and Equipment
- Shipbuilding and Marine
- Railways
- Consumer Appliances
- Aerospace and Others
Carbon Steel Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] World Steel Association. (2026, October 12). worldsteel Short Range Outlook October 2026. https://worldsteel.org/media/press-releases/2026/worldsteel-short-range-outlook-october-2026/
- [2] ArcelorMittal S.A. (2026, July 30). ArcelorMittal reports second quarter 2026 results. https://mfn.se/all/a/arcelormittal/arcelormittal-s-a-arcelormittal-reports-second-quarter-2026-results-920cf2ce
- [3] Tata Steel. (2026, July 30). Tata Steel reports Consolidated EBITDA of Rs 9,370 crores for the quarter ended June 30, 2026. https://www.tatasteel.com/newsroom/press-releases/india/2026/tata-steel-reports-consolidated-ebitda-of-rs-9-370-crores-for-the-quarter-ended-june-30-2026/
- [4] Gerdau S.A. (2026, August 4). Quarterly Results 2Q26 (Form 6-K, Exhibit 99.1). https://www.sec.gov/Archives/edgar/data/0001073404/000110465926090494/tm2621830d2_ex99-1.htm
- [5] World Steel Association. (2026, September 24). August 2026 crude steel production. https://worldsteel.org/media/press-releases/2026/august-2026-crude-steel-production/
- [6] Nucor Corporation. (2026, July 27). Nucor Reports Results for the Second Quarter of 2026 (Form 8-K, Exhibit 99.1). https://www.sec.gov/Archives/edgar/data/0000073309/000119312526318190/d468854dex991.htm
- [7] The White House. (2025, June 3). Adjusting Imports of Aluminum and Steel. https://www.whitehouse.gov/presidential-actions/2025/06/adjusting-imports-of-aluminum-and-steel/
- [8] POSCO Newsroom. (2026, June 22). POSCO Accelerates Transition to Decarbonized Production System with Completion of Korea's Largest Electric Arc Furnace. https://newsroom.posco.com/en/posco-accelerates-transition-to-decarbonized-production-system-with-completion-of-koreas-largest-electric-arc-furnace/
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the carbon steel market during 2026?
- What market size is projected by 2036?
- Which carbon content holds notable share?
- Which product type holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the carbon steel market expected in 2026?
FMI's 2026 figure for the carbon steel market is USD 1,185.8 billion, against USD 1,140.2 billion in 2025. By 2036, the carbon steel market is projected to reach USD 1,754.8 billion.
What CAGR is projected for the carbon steel market through 2036?
The carbon steel market is expected to grow at a 4% CAGR from 2026 to 2036. Infrastructure, factory building and higher-value coated and high-strength grades carry that growth.
Which carbon content holds a notable market share in 2026?
With 58.4% share in 2026, low-carbon steel is expected to lead carbon content. Medium-carbon steel holds 27.6%.
Which product type holds a notable market share in 2026?
Flat products are projected to hold 72.5% of product type sales in 2026, the leading share. Long products account for an estimated 27.5%.
Which country has a notable expansion outlook through 2036?
India is projected to grow at a 4.8% CAGR, the top rate in FMI's country table. The United States follows at 4.6%.
Who are the key companies in the carbon steel market?
China Baowu Group, Nippon Steel, POSCO, HBIS Group, Jiangsu Shagang, Ansteel Group and JFE Steel form the Asian integrated group. ArcelorMittal, Tata Steel, Nucor and Gerdau complete the profiled companies.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Carbon Content, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Carbon Content, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Carbon Content, 2026 to 2036
- Low-Carbon Steel
- Medium-Carbon Steel
- High-Carbon Steel
- Y-o-Y Growth Trend Analysis By Carbon Content, 2021 to 2025
- Absolute $ Opportunity Analysis By Carbon Content, 2026 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Flat Products
- Long Products
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Building and Construction
- Automotive
- Oil and Gas and Energy
- Heavy Machinery and Equipment
- Shipbuilding and Marine
- Railways
- Consumer Appliances
- Aerospace and Others
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Carbon Content
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Carbon Content
- By Product Type
- By End Use
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Carbon Content
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Carbon Content
- By Product Type
- By End Use
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Carbon Content
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Carbon Content
- By Product Type
- By End Use
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Carbon Content
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Carbon Content
- By Product Type
- By End Use
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Carbon Content
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Carbon Content
- By Product Type
- By End Use
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Carbon Content
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Carbon Content
- By Product Type
- By End Use
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Carbon Content
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Carbon Content
- By Product Type
- By End Use
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbon Content
- By Product Type
- By End Use
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbon Content
- By Product Type
- By End Use
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbon Content
- By Product Type
- By End Use
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbon Content
- By Product Type
- By End Use
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbon Content
- By Product Type
- By End Use
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbon Content
- By Product Type
- By End Use
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbon Content
- By Product Type
- By End Use
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbon Content
- By Product Type
- By End Use
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbon Content
- By Product Type
- By End Use
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbon Content
- By Product Type
- By End Use
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbon Content
- By Product Type
- By End Use
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbon Content
- By Product Type
- By End Use
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbon Content
- By Product Type
- By End Use
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbon Content
- By Product Type
- By End Use
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbon Content
- By Product Type
- By End Use
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbon Content
- By Product Type
- By End Use
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbon Content
- By Product Type
- By End Use
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbon Content
- By Product Type
- By End Use
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbon Content
- By Product Type
- By End Use
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Carbon Content
- By Product Type
- By End Use
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Carbon Content
- By Product Type
- By End Use
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- ArcelorMittal
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Nucor
- POSCO
- Tata Steel
- Gerdau
- China Baowu Group
- Nippon Steel
- HBIS Group
- Jiangsu Shagang
- Ansteel Group
- JFE Steel
- ArcelorMittal
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


