
- Market Size (2026)
- USD 9.6 Bn
- Forecast (2036)
- USD 16.4 Bn
- CAGR (2026 to 2036)
- 5.5%
How big is Corrosion Inhibitors Market in 2026?
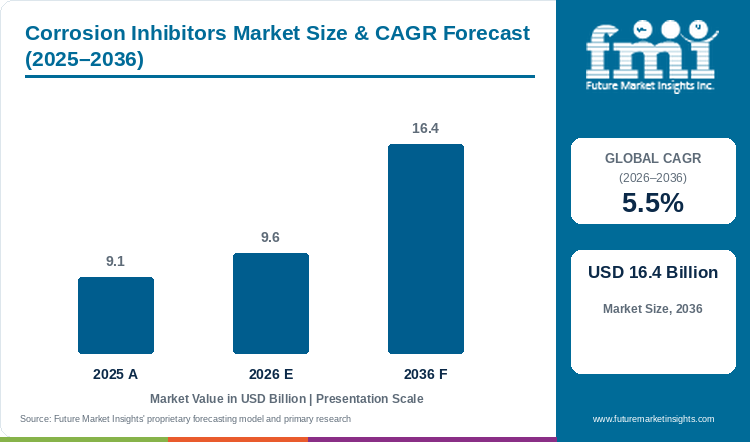
Registering a value of USD 9.1 billion in 2025, the corrosion inhibitors market expanded to USD 9.6 billion in 2026 and is anticipated to achieve USD 16.4 billion by 2036, driven by a 5.5% CAGR.
Pipeline integrity engineers managing mature high-water-cut oilfields and facility operators running 24-hour liquid-cooled data centers and refinery heat exchangers are increasing continuous chemical inhibitor dosing per barrel of fluid moved and per megawatt of heat rejected. Formulation trend analysis by FMI indicates that the global corrosion inhibitors market valuation rose from USD 9.1 billion in 2025 to an estimated market value of USD 9.6 billion in 2026, and is forecast to reach an industry valuation of USD 16.4 billion by 2036, expanding at a 5.5% CAGR between 2026 and 2036. Mixed-action organic film-forming inhibitors encompassing amines and imidazolines hold an estimated 48.0% share of 2026 demand with anodic passivating orthophosphates and molybdates, given that filming amines chemisorb onto steel pipe walls under high shear stress.
Continuous downhole and recirculating-loop chemical consumption separates this market from the additives for metalworking fluids sector at 3.3% CAGR, since batch machining sumps only dose inhibitors during fluid changeouts. Mandatory regulatory enforcement on internal pipeline integrity drives continuous inhibitor purchasing, as U.S. Pipeline and Hazardous Materials Safety Administration (PHMSA) enforcement records in September 2026 documented three crude terminal releases totaling over 3,958 barrels in Texas caused by unmitigated internal pipeline corrosion. Chemical suppliers are simultaneously expanding into high-tech electronics cooling, evidenced in July 2026, Ecolab closed its acquisition of CoolIT Systems, a leader in direct liquid cooling for high-density AI data centers. The addition brings Ecolab’s Global High-Tech business to approximately USD 1.5 billion in annualized sales and positions the company to deliver end-to-end liquid cooling and water management solutions across AI infrastructure . Environmental phase-outs of hexavalent chromium and automated real-time corrosion-rate telemetry will govern supplier qualification through 2036.
Key Market Trends & Insights
- By chemical action: Mixed-Action Organic Film-Forming Inhibitors Amines and Imidazolines hold an estimated 48.0% share in 2026 with Anodic Passivating Inhibitors since persistent chemisorbed barrier films block carbonic and hydrosulfuric acid attack.
- By formulation base: Water-Based Aqueous Corrosion Inhibitors represent 64.0% in 2026 as industrial cooling towers, steam boilers, and produced-water reinjection loops require water-soluble dosing.
- By end-use industry: Oil and Gas Downhole Pipelines and Refinery Distillation account for 52.0% in 2026 driven by rising water cuts in mature wells and sour-crude overhead condensing protection.
- By protected metal substrate: Carbon Steel and Low-Alloy Piping secures 68.0% in 2026 owing to carbon steel's low structural cost and high susceptibility to electrochemical pitting without continuous chemical inhibition.
- By delivery & dosing mode: Continuous Automated Chemical Injection and Metering commands 57.0% in 2026 through optical-fluorescence tracer pumps and downhole capillary injection strings.
Regional Highlights
- Top national expansion: Saudi Arabia leads national growth projections at a 6.5% CAGR through 2036 under sour-gas field expansions, seawater cooling networks, and downstream petrochemical complexes.
- Broader country progression: India tracks at a 6.2% CAGR ahead of Brazil at 5.9% and Canada at 5.6%, while South Korea advances at 5.4% and the USA, Germany and Japan progress between 5.1% and 4.5%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Corrosion Inhibitors Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 9.1 billion |
| Estimated Market Size in 2026 | USD 9.6 billion |
| Projected Market Size by 2036 | USD 16.4 billion |
| CAGR, 2026 to 2036 | 5.5% |
| Added Revenue, 2026 to 2036 | USD 6.8 billion |
Midstream pipeline operators, petroleum refiners and power utilities confront severe asset integrity penalties when dissolved carbon dioxide, hydrogen sulfide and chloride ions pit carbon-steel tubing and copper-nickel heat-exchanger bundles. Unplanned refinery crude-unit shutdowns or subsea flowline leaks cost operators millions of dollars per day in lost throughput, making continuous parts-per-million inhibitor injection a non-discretionary operating expense. Third-quarter 2026 financial results from Baker Hughes released in October 2026 confirm resilient oilfield chemical and equipment demand, reporting Oilfield Services and Equipment (OFSE) revenue of USD 3,660 million up 6% sequentially and OFSE orders of USD 4,047 million up 19% sequentially. Consequently, industrial plant operators bundle corrosion inhibitors with broader water treatment chemicals programs to protect multi-metal utility loops.
Global Inhibitor Tonnage and Active Dosing Volume Sizing
Table 2: Global Corrosion Inhibitor Tonnage and Active Dosing Sizing (USD billion and million metric tons), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 9.1 | 9.6 | 16.4 |
| Global formulated inhibitor volume (million metric tons) | 2.55 to 2.72 | 2.68 to 2.85 | 4.25 to 4.55 |
| Water-based aqueous inhibitor volume (million metric tons) | 1.62 to 1.74 | 1.71 to 1.82 | 2.75 to 2.95 |
| Average commercial formulation price (USD per metric ton) | 3,380 to 3,560 | 3,410 to 3,590 | 3,650 to 3,860 |
Operational note and dosing intensity analysis indicate that commercial corrosion inhibitor consumption expands from 2.68 to 2.85 million metric tons in 2026 toward 4.25 to 4.55 million metric tons by 2036 across 15 to 250 ppm continuous treatment programs. Data from the U.S. Environmental Protection Agency (EPA) in March 2026, the agency launched its RealWaterTA technical assistance initiative under the Safe Drinking Water Act and Clean Water Act to help municipal and rural water systems maintain lead-and-copper corrosion control and wastewater compliance. At the same time, upstream oil and gas producers integrate corrosion control within comprehensive oilfield chemicals tenders to prevent downhole tubing failure.
Regulatory Substitution & Automated Telemetry Economics
Table 3: Regulatory Reformulation and Telemetry Dosing Indicators for the Corrosion Inhibitors Market (USD and percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Chromate-free & low-toxicity inhibitor share of value (%) | 78.0% to 81.0% | 80.5% to 83.5% | 94.0% to 97.0% |
| Automated telemetry-metered dosing share of installations (%) | 54.0% to 56.5% | 56.0% to 58.5% | 71.0% to 75.0% |
| Annual inhibitor spend per refinery / petrochemical complex (USD M) | 2.8 to 3.4 | 3.0 to 3.6 | 4.8 to 5.7 |
| Data center & microelectronics cooling loop share of demand (%) | 6.8% to 7.6% | 7.8% to 8.8% | 15.5% to 18.0% |
Data from the European Chemicals Agency (ECHA) restriction proposal published in April 2025, EU regulators moved to restrict hexavalent chromium Cr(VI) substances including barium chromate to prevent up to 17 metric tons of environmental releases and avoid 195 cancer cases annually, with societal compliance and substitution investments estimated between EUR 314 million and EUR 3.23 billion. This regulatory clampdown accelerates industrial conversion away from legacy chromates toward organic imidazolines, molybdates, cerium salts and polyaspartate green inhibitors.
Table 4: Oilfield, Water Treatment & VCI Packaging Channel Benchmarks for the Corrosion Inhibitors Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 9.6 billion | 2026 global corrosion inhibitors revenue baseline |
| Water-Based Aqueous Inhibitor revenue, 2026 | USD 6.1 billion | 64.0% formulation base allocation |
| Oil & Gas Pipelines and Refinery revenue, 2026 | USD 5.0 billion | 52.0% end-use industry allocation |
| Continuous Automated Injection revenue, 2026 | USD 5.5 billion | 57.0% delivery and dosing mode allocation |
Closed-loop industrial cooling towers and semiconductor ultrapure water plants now specify fluorescent-traced cooling water treatment chemicals with vapor-phase packaging for exported machinery. Technical documentation released by Cortec Corporation in October 2026 demonstrates how dry Vapor phase Corrosion Inhibitor (VpCI) packaging eliminates traditional petroleum rust preventives and warm-water alkaline wash stages on metal parts, cutting factory boiler energy use and carbon emissions.
Analyst Perspective
"Refinery reliability managers and hyperscale data center operators do not buy corrosion inhibitors by the drum price; they buy verified low metal-loss rates and zero heat-exchanger fouling under automated 24-hour dosing. Chemical formulators that pair chromate-free organic filming amines or biodegradable polyaspartates with real-time linear polarization resistance telemetry will lock in long-term site service contracts through 2036."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the Corrosion Inhibitors Market segmented?
The corrosion inhibitors market is segmented by chemical action, formulation base, end-use industry, protected metal substrate, and delivery & dosing mode. In 2026, Mixed-Action Organic Film-Forming Inhibitors Amines and Imidazolines are projected at 48.0%, Water-Based Aqueous Corrosion Inhibitors at 64.0%, Oil and Gas Downhole Pipelines and Refinery Distillation at 52.0%, Carbon Steel and Low-Alloy Piping at 68.0%, and Continuous Automated Chemical Injection and Metering at 57.0%.
By chemical action: Mixed-Action Organic Film-Forming Inhibitors Amines and Imidazolines and Anodic Passivating Inhibitors, as well as Cathodic Precipitation Zinc Salts and Volatile VCI Packaging.
By formulation base: Water-Based Aqueous Corrosion Inhibitors and Oil and Solvent-Based Formulations, as well as Volatile Solid VCI Emitters and Bio-Based Green Polymeric Formulations.
By end-use industry: Oil and Gas Downhole Pipelines and Refinery Distillation and Industrial Water Treatment Boilers and Cooling Towers, as well as Chemical Processing and Automotive Coolants.
By protected metal substrate: Carbon Steel and Low-Alloy Piping and Copper Heat Exchangers, as well as Aluminum Multi-Metal Cooling Loops and Stainless Steel Alloys.
By delivery & dosing mode: Continuous Automated Chemical Injection and Metering and Batch Pipeline Pigging Slugs, as well as Closed-Loop Coolant Charges and VCI Film Emitters.
Why do Mixed-Action Organic Film-Forming Inhibitors Amines and Imidazolines lead the chemical action category?
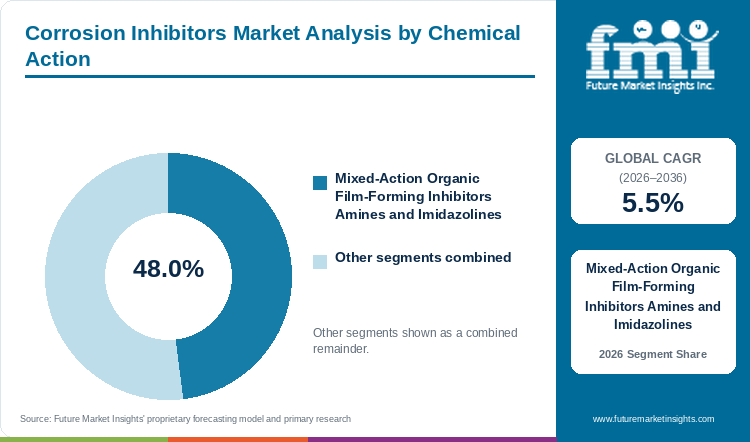
Mixed-Action Organic Film-Forming Inhibitors Amines and Imidazolines hold an estimated 48.0% of chemical action demand in 2026, anchored by hydrophobic barrier film formation in sour pipelines and refinery overheads.
Table 5: Chemical Action Share for the Corrosion Inhibitors Market (percentage share), 2026
| Chemical Action | Share (2026) |
|---|---|
| Mixed-Action Organic Film-Forming Inhibitors Amines and Imidazolines | 48.0% |
| Other Segments Combined (Anodic Passivating, Cathodic Precipitation & VCI Packaging) | 52.0%* |
| Total | 100.0% |
Table 6: Chemical Action Leadership and Market Growth for the Corrosion Inhibitors Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.5% |
| Leading Segment | Mixed-Action Organic Film-Forming Inhibitors Amines and Imidazolines |
Organic film-forming corrosion inhibitors based on amines and imidazolines dominate commercial chemical action demand since polar nitrogen headgroups chemisorb onto both anodic and cathodic metal sites while hydrophobic hydrocarbon tails repel corrosive water and acid gases in oilfield production chemicals. Whereas Anodic Passivating Inhibitors Chromates Nitrites and Orthophosphates risk severe localized pitting if under-dosed and face toxic chromate bans, organic filming amines and quaternary ammonium salts provide broad concentration tolerance across pipelines, refinery overheads and steam condensate lines. High-temperature thermal degradation above 180 degrees Celsius and foaming tendency in gas scrubbers remain practical formulation hurdles.
- Within chemical action, Mixed-Action Organic Film-Forming Inhibitors Amines and Imidazolines are projected to capture a 48.0% share in 2026 across sour oil and gas pipelines.
- Laboratory research published in the journal Coatings in November 2026 substantiated this performance advantage, demonstrating that binary Mannich bases combined with Mannich-based imidazoline quaternary ammonium salts deliver combined corrosion inhibition on carbon steel in aggressive acidic media.
What sustains Water-Based Aqueous Corrosion Inhibitors leadership in the formulation base segment?
Water-Based Aqueous Corrosion Inhibitors represent 64.0% of the formulation base category in 2026, supported by VOC-free dosing across cooling towers, steam boilers, and high-water-cut oilfields.
Water-Based Aqueous Corrosion Inhibitors serve as the standard carrier chemistry across industrial cooling towers, high-pressure steam boilers, municipal drinking-water orthophosphate networks and high-water-cut oilfield production wells where inhibitor actives must Partition into the aqueous phase. Plant engineers cross-qualifying oilfield scale inhibitors and corrosion packages favor aqueous concentrates over Oil and Solvent-Based Formulations to eliminate volatile organic compound (VOC) emissions and flammability hazards in storage. Sub-zero crystallization risk in sub-zero northern oilfields and microbial bio-fouling of dilute storage tanks nevertheless require glycol winterization and biocide co-formulation.
- In 2026, Water-Based Aqueous Corrosion Inhibitors are anticipated to capture 64.0% of global formulation base demand across cooling water and injection loops.
- A comprehensive technical review published in the journal Technologies in March 2025 confirmed that water-soluble inorganic and organic inhibitors govern industrial cooling and pipeline protection by suppressing anodic metal dissolution and cathodic oxygen reduction across aqueous interfaces.
How do Oil and Gas Downhole Pipelines and Refinery Distillation lead the end-use industry category?
Oil and Gas Downhole Pipelines and Refinery Distillation account for 52.0% of end-use industry volume in 2026, driven by rising produced-water cuts and sour CO2/H2S pipeline protection.
Upstream production wells, subsea wet-gas gathering lines and refinery atmospheric crude distillation towers operate under extreme partial pressures of carbon dioxide, hydrogen sulfide and organic naphthenic acids that rapidly corrode unprotected steel. While Industrial Water Treatment Boilers and Cooling Towers, Chemical Processing and Fertilizers and Automotive Radiator Coolants generate steady volume, oil and gas operators consume the largest tonnage of specialty inhibitors with refinery process chemicals as maturing reservoirs produce 70% to 90% water per barrel of lifted fluid. Emulsion tendency and elemental sulfur deposition inside sour-gas pipelines remain major operational challenges that require specialized non-emulsifying inhibitor blends.
- By end-use industry, Oil and Gas Downhole Pipelines and Refinery Distillation are estimated to hold 52.0% of total demand in 2026.
- Technical studies published in Corrosion and Materials Degradation in October 2026 confirmed that continuous chemical treatment in sour-gas pipelines requires maintaining active inhibitor film coverage across sulfur-deposition zones coupled with real-time corrosion monitoring.
Why does Carbon Steel and Low-Alloy Piping lead the protected metal substrate category?
Carbon Steel and Low-Alloy Piping secures 68.0% of protected metal substrate value in 2026, supported by carbon steel's universal use in pipelines, storage tanks, and utility cooling loops.
Industrial EPC contractors and pipeline operators construct more than 85% of global crude transmission lines, refinery heat-exchanger shells, cooling-water headers and district-heating pipes from carbon and low-alloy steel because stainless and titanium alloys cost four to ten times more per installed meter. Because carbon steel lacks a self-healing chromium-oxide passive layer, operators rely on continuous chemical corrosion inhibition to achieve 25-year to 40-year asset service lives at a fraction of exotic metallurgy capex. Galvanic coupling when carbon-steel piping connects to copper-alloy chillers or aluminum heat sinks inside multi-metal loops still requires blended azole-phosphate inhibitor packages.
- Carbon Steel and Low-Alloy Piping is predicted to secure 68.0% of protected metal substrate demand in 2026 across pipelines and cooling circuits.
- Materials research published by the Royal Society of Chemistry in February 2025 demonstrated that stimuli-responsive smart inhibitor systems triggered by localized pH drops at carbon-steel defect sites release targeted inhibitor ions to halt pit propagation before structural perforation occurs.
What gives Continuous Automated Chemical Injection and Metering the leading position in delivery & dosing mode?
Continuous Automated Chemical Injection and Metering commands 57.0% of delivery & dosing mode share in 2026, anchored by optical-tracer telemetry pumps and downhole capillary injection.
Continuous Automated Chemical Injection and Metering using positive-displacement diaphragm pumps, downhole capillary tubing, and inline fluorescent-tracer sensors prevents the concentration troughs that occur between manual batch slugs. In high-velocity oilfield flowlines and 24-hour hyperscale data center liquid-cooling loops, even a six-hour interruption in inhibitor feed allows chloride or acid-gas ions to strip the protective film and initiate irreversible pitting. High capital costs for explosion-proof chemical injection skids and remote satellite telemetry on unmanned wellhead platforms remain adoption hurdles for smaller operators.
- Continuous Automated Chemical Injection and Metering is forecast to command 57.0% of delivery mode share in 2026 across refineries and data centers.
- Segment growth through 2036 is expected to accelerate as water-treatment vendors bundle cloud-connected corrosion coupon probes and automated dosing skids at zero upfront capex under multi-year chemical supply contracts.
What are the drivers, restraints, and opportunities in the Corrosion Inhibitors Market?
In the corrosion inhibitors market, rising oilfield water cuts and 24-hour AI data center liquid cooling are projected to drive adoption whereas EU REACH and EPA restrictions on chromates and phosphorus restrain legacy blends and biodegradable polyaspartate and VpCI systems unlock green reformulation.
- Driver: Higher water cuts in mature oilfields and rapid expansion of closed-loop liquid cooling across AI data centers and semiconductor fabs drive continuous inhibitor dosing.
- Restraint: Strict EU REACH and EPA restrictions on hexavalent chromates, hydrazines, and high-phosphorus cooling discharges force costly reformulation and environmental toxicity testing.
- Opportunity: Scaling biodegradable polyaspartate, chitosan and volatile amine boiler/VCI inhibitors opens green compliance across offshore basins, food-grade steam plants and EV battery export packaging.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Industrial steam-boiler operators, district-energy utilities, and food-processing plants face severe condensate-line return corrosion caused by dissolved carbon dioxide and oxygen that flashes into steam headers and attacks downstream piping. When plant engineers dose volatile neutralizing and filming amines or pair liquid inhibitors with anti-corrosion coatings, boiler feedwater systems prevent iron-oxide carryover onto turbine blades and reduce fuel-wasting scale buildup. Product launches from Cortec Corporation in December 2025 confirm this commercial demand driver, as Cortec introduced a specialized boiler corrosion inhibitor solution tailored to food-industry steam boilers and seasonal layup protection.
Risk Assessment of the Corrosion Inhibitors Market: Operational and Formulation Friction
Stringent environmental discharge regulations targeting heavy metals, toxic oxygen scavengers, and nutrient eutrophication represent the primary restraint challenging traditional corrosion inhibitor formulators. Regulatory bans on hexavalent chromium with tight municipal effluent limits on zinc and orthophosphate cooling-tower blowdown compel chemical suppliers to reformulate with higher-cost sodium molybdate, tolyltriazole, and non-phosphorus organic polymers. Corporate research communications from BASF SE in August 2025 ahead of the EUROCORR 2025 congress in Stavanger emphasized that replacing legacy hazardous substances while maintaining long-term corrosion durability requires intensive cross-disciplinary electrochemistry and surface-coating R&D.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Specialty chemical manufacturers capture substantial growth avenues by developing non-toxic, biodegradable green corrosion inhibitors and recyclable volatile corrosion inhibitor films for offshore oilfields, zero-liquid-discharge cooling loops and automotive component shipping. Offshore OSPAR convention basins in the North Sea and zero-discharge industrial parks in Asia now mandate green-listed polyaspartic acid, biopolymer, and plant-extract inhibitors that degrade harmlessly after use. Peer-reviewed research published in the journal Metals in October 2026 demonstrated that a chitosan-poly(aspartic acid) microgel combined with polyepoxysuccinic acid and sodium gluconate delivers high dual scale and corrosion inhibition efficiency on carbon steel without phosphorus or toxic heavy metals.
Corrosion Inhibitors Market by Country (2026 to 2036)
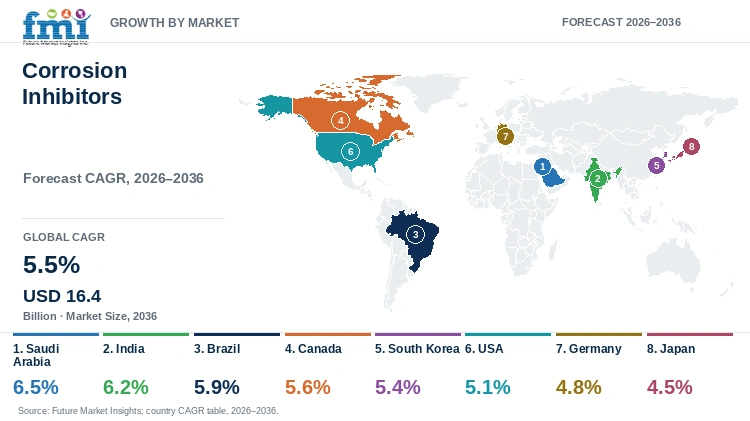
FMI country modeling indicates that Saudi Arabia leads global corrosion inhibitors expansion at a 6.5% CAGR through 2036, followed by India at 6.2%, Brazil at 5.9% and Canada at 5.6%. National growth rates reflect differences in sour-crude and offshore pre-salt production chemistry, semiconductor and data-center cooling buildouts, and European REACH chromate substitution.
Table 7: Country CAGR and Primary Growth Levers for the Corrosion Inhibitors Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Saudi Arabia | 6.5% | Unconventional sour-gas processing, seawater cooling loops, and desalination plants |
| India | 6.2% | Greenfield refinery/petrochemical complexes and semiconductor water-treatment JVs |
| Brazil | 5.9% | Deepwater pre-salt FPSO high-CO2 umbilical injection and ethanol boiler treatment |
| Canada | 5.6% | Alberta SAGD oil-sands steam generation and winterized midstream pipeline integrity |
| South Korea | 5.4% | Semiconductor fab cooling loops and chromium-free battery copper-foil passivation |
| USA | 5.1% | Record Permian crude produced-water treatment, EPA water compliance, and AI data centers |
| Germany | 4.8% | REACH chromate-free industrial reformulation, EV coolants, and VCI machinery packaging |
| Japan | 4.5% | Automated microelectronics cooling water systems and residue-free VCI export films |
Source: Future Market Insights analysis
Saudi Arabia Corrosion Inhibitors Market Outlook (2026 to 2036)
Demand for corrosion inhibitors in Saudi Arabia is projected to expand at a leading 6.5% CAGR between 2026 and 2036 across unconventional sour-gas processing plants, seawater cooling networks, and thermal desalination complexes. What distinguishes Saudi Arabia from temperate industrial markets is the extreme salinity of Arabian Gulf cooling water combined with high hydrogen sulfide concentrations in non-associated gas fields such as Jafurah that require continuous high-temperature imidazoline injection. Data from the International Energy Agency (IEA) Oil Market Report released in October 2026, Middle Eastern crude and NGL supply dynamics and refining runs remain central to global hydrocarbon balances. Domestic localization programs in Jubail and Yanbu further drive local blending of oilfield and desalination corrosion inhibitors.
Key takeaway: In Saudi Arabia, sour-gas field development and high-salinity seawater cooling and desalination plants are projected to drive the fastest national inhibitor growth through 2036.
India Corrosion Inhibitors Market Outlook (2026 to 2036)
In India, the corrosion inhibitors market is anticipated to advance at a 6.2% CAGR from 2026 to 2036 anchored by greenfield petrochemical refinery complexes, ultra-supercritical power plants and semiconductor and electronics water-treatment investments. Compared with mature Western markets where water-treatment demand is replacement-driven, Indian industrial corridors in Gujarat, Rajasthan and Tamil Nadu are commissioning new closed-loop cooling towers and zero-liquid-discharge wastewater recycling units. Corporate expansion announcements from Kurita Water Industries in September 2026 confirm this high-tech industrial pull, as Kurita Membrane India Private Limited began operations in June 2026 and debuted at SEMICON India to supply water-treatment technologies and chemicals to Indian semiconductor and industrial plants. Coastal humidity across Indian ports also accelerates VCI packaging adoption for automotive steel and machinery exports.
Key takeaway: In India, greenfield refinery and semiconductor water-treatment investments with coastal VCI export packaging are anticipated to sustain rapid corrosion inhibitor adoption.
Brazil Corrosion Inhibitors Market Outlook (2026 to 2036)
Brazilian corrosion inhibitors consumption is forecast to progress at a 5.9% CAGR over the 2026 to 2036 period, driven by deepwater pre-salt Floating Production Storage and Offloading (FPSO) vessels in the Santos and Campos basins as well as sugarcane ethanol and pulp-mill boilers. Brazil diverges from onshore shale markets because ultra-deepwater pre-salt reservoirs contain high carbon dioxide partial pressures and hypersaline brines that require umbilical-injected filming amines qualified at pressures above 500 bar. Economic and infrastructure assessments published by the World Bank in December 2025 confirm ongoing private and public-private investment across Brazilian industrial, energy, and port logistics corridors. Brazilian offshore environmental rules under IBAMA also push FPSO operators toward low-toxicity, biodegradable corrosion and scale inhibitor packages.
Key takeaway: In Brazil, high-CO2 deepwater pre-salt FPSO umbilical injection and bio-energy boiler treatment are forecast to anchor specialty corrosion inhibitor demand.
Canada Corrosion Inhibitors Market Outlook (2026 to 2036)
Sales of corrosion inhibitors in Canada are estimated to expand at a 5.6% CAGR from 2026 to 2036 across Alberta steam-assisted gravity drainage (SAGD) oil-sands facilities, midstream diluted-bitumen pipelines, and potash mining hydro-transport lines. Canadian inhibitor formulations differ markedly from standard grades since chemical packages must remain pourable at minus 40 degrees Celsius in winter while withstanding 250-degree-Celsius steam generators in SAGD bitumen extraction. Financial disclosures from Baker Hughes in April 2026 reporting resilient first-quarter 2026 North American Oilfield Services and Equipment performance reflect ongoing production-chemical and integrity services activity across North American hydrocarbon basins. Canadian pipeline integrity rules enforced by the Canada Energy Regulator further mandate continuous internal corrosion monitoring and batch pigging inhibition.
Key takeaway: In Canada, oil-sands SAGD steam generation and extreme-cold midstream pipeline integrity mandates are estimated to sustain strong demand for winterized corrosion inhibitors.
South Korea Corrosion Inhibitors Market Outlook (2026 to 2036)
Commercial demand for corrosion inhibitors in South Korea is predicted to expand at a 5.4% CAGR through 2036 across Ulsan and Yeosu petrochemical complexes, semiconductor wafer-fab ultrapure cooling loops, and copper-foil battery materials manufacturing. What sets South Korea apart from upstream oilfield markets is its high concentration of precision electronics, shipbuilding and EV battery materials plants that require ultra-clean, heavy-metal-free passivation and VCI packaging chemistries. Regional product rollouts from BASF SE's Chemetall surface-treatment division in October 2025 confirm this Asia-Pacific electronics focus, as Chemetall launched the first global chromium-free and fluoride-free Gardolene D passivation solution for copper foils used in lithium-ion batteries and printed circuit boards. Korean marine coatings and ballast-tank inhibitor demand also remains firm across major shipyards.
Key takeaway: In South Korea, semiconductor cooling loops, chromium-free battery copper-foil passivation and shipbuilding are predicted to drive high-value inhibitor adoption.
USA Corrosion Inhibitors Market Outlook (2026 to 2036)
The USA corrosion inhibitors market is slated to advance at a 5.1% CAGR during the 2026 to 2036 forecast window, representing the largest single national market across Permian Basin oilfield gathering lines, Gulf Coast refineries and municipal drinking-water orthophosphate systems and AI data center liquid cooling. American demand is uniquely driven by simultaneous record domestic crude production and massive hyperscale server-hall construction that requires 24-hour closed-loop copper and aluminum corrosion protection. Official energy statistics from the U.S. Energy Information Administration (EIA) in September 2026 confirm that the United States remains on track for record crude oil production in 2026, sustaining high produced-water treatment volumes across Texas and New Mexico. In addition, EPA Lead and Copper Rule Improvements compel U.S. municipal water utilities to upgrade orthophosphate and silicate corrosion-control dosing.
Key takeaway: In the USA, record Permian crude-water treatment, EPA municipal drinking-water compliance and AI data center liquid cooling are slated to anchor market expansion.
Germany Corrosion Inhibitors Market Outlook (2026 to 2036)
In Germany, demand for corrosion inhibitors is projected to register a 4.8% CAGR from 2026 to 2036 across integrated chemical parks along the Rhine, automotive long-life radiator coolants and metalworking fluids and district-heating water circuits. Germany diverges from hydrocarbon-extraction economies because domestic buyers prioritize REACH-compliant, nitrite-free, and chromate-free organic acid technology (OAT) coolants and biodegradable VCI films for exported machinery. Industry data from the European Chemical Industry Council (Cefic) in its Q1 2026 Chemical Trends Report published in June 2026 documents how European chemical producers are navigating high energy costs by focusing on high-margin specialty performance additives. German industrial utilities also invest heavily in closed-loop heat-pump and district-heating corrosion inhibitors to prevent magnetite sludge accumulation.
Key takeaway: In Germany, REACH chromate-free reformulation, EV thermal-management coolants and exported machinery VCI packaging are projected to drive specialty inhibitor demand.
Japan Corrosion Inhibitors Market Outlook (2026 to 2036)
Japanese corrosion inhibitors sales are forecast to grow at a 4.5% CAGR between 2026 and 2036 across semiconductor foundry cooling towers, coastal power-generation condensers, and precision automotive and robotics export packaging. Unlike high-volume oilfield chemical markets, Japan emphasizes automated sensor-driven micro-dosing of non-phosphorus cooling water inhibitors and food-safe boiler compounds developed by domestic water-treatment engineering houses. Macroeconomic assessments in the OECD Economic Outlook Volume 2026 Issue 1 for Japan released in June 2026 confirm sustained corporate capital investment in semiconductor fabs, green transformation (GX), and labor-saving automation despite demographic headwinds. Japanese electronics and auto-parts exporters also rely on ultra-pure VCI films that leave zero surface residue on optical and electrical contacts.
Key takeaway: In Japan, semiconductor fab cooling-water automation and residue-free VCI packaging for precision electronics exports are forecast to sustain steady market progression.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Corrosion Inhibitors Market?
Ecolab Inc. (Nalco Water), Baker Hughes Company, Veolia Water Technologies & Solutions / Xylem Inc., BASF SE, Lubrizol Corporation (Berkshire Hathaway), ChampionX Corporation, Cortec Corporation, Solenis LLC, Kurita Water Industries Ltd., and Clariant AG are the notable companies in the corrosion inhibitors market.
Competitive positioning across the global corrosion inhibitors industry separates integrated industrial water-treatment leaders, upstream oilfield and refinery process-chemical producers, and specialized corrosion-additive and VCI packaging formulators. Ecolab, Veolia / Xylem, Solenis and Kurita lead in automated cooling-tower and boiler and data-center water treatment. Baker Hughes, ChampionX and Clariant anchor downhole oilfield and refinery overhead corrosion control while BASF, Lubrizol and Cortec lead in metalworking and coatings and VpCI vapor-phase protection.
- Industrial Water & Boiler Treatment Leaders: Ecolab, Veolia / Xylem, Solenis and Kurita combine aqueous corrosion inhibitors with automated optical-tracer dosing skids.
- Oilfield Pipeline & Refinery Process Specialists: Baker Hughes, ChampionX and Clariant formulate high-temperature filming amines, imidazolines and sour-gas H2S/CO2 corrosion inhibitors.
- Specialty Additive, Passivation & VCI Innovators: BASF, Lubrizol and Cortec manufacture Irgacor and Gardolene surface passivators and metalworking rust preventives and VpCI packaging.
Competitive Benchmarking: Corrosion Inhibitors Market
Table 8: Competitive Benchmarking for the Corrosion Inhibitors Market (qualitative capability ratings), 2026
| Company | Oilfield & Process Inhibitor Depth | Automated Telemetry & Dosing Support | Chromate-Free & Green Fit | Geographic Reach |
|---|---|---|---|---|
| Ecolab Inc. (Nalco Water) | High | High | High | Global leader in cooling, boiler & data-center water treatment; acquiring CoolIT Systems in 2026 |
| Baker Hughes Company | High | High | Medium | Global CRONOX downhole, subsea & refinery corrosion control; USD 3,660M Q3 2026 OFSE revenue |
| Veolia Water Tech / Xylem Inc. | Medium | High | High | Global Hydrex cooling/boiler chemicals and Xylem smart industrial water treatment networks |
| BASF SE | High | Medium | High | Global Irgacor lubricant/coatings inhibitors & Chemetall Gardolene Cr-free metal passivation |
| Lubrizol Corporation | High | Medium | Medium | Global Berkshire Hathaway unit supplying Lubrizol metalworking, fuel & coolant corrosion additives |
| ChampionX Corporation | High | High | Medium | Global upstream and midstream oilfield production chemicals integrated within SLB portfolio |
| Cortec Corporation | Medium | Medium | High | Global leader in VpCI vapor-phase packaging, bio-based rust preventives & boiler layup actives |
| Solenis LLC | Medium | High | High | Global industrial cooling, boiler & direct-to-chip coolant treatment across 130 countries |
| Kurita Water Industries Ltd. | Medium | High | High | Japan, Asia & US semiconductor and industrial water treatment; opened Kurita Membrane India in 2026 |
| Clariant AG | High | Medium | High | Global Oil Services North Sea/Middle East biodegradable inhibitors and Care Chemicals additives |
Key Developments in the Corrosion Inhibitors Market
- In July 2026, Ecolab Inc. closed its acquisition of CoolIT Systems, a specialist in direct liquid cooling for high-density AI data centers, for approximately USD 4.75 billion. The addition brings Ecolab’s Global High-Tech business to approximately USD 1.5 billion in annualized sales and extends the company’s corrosion control and water chemistry capabilities across AI data center infrastructure [1].
- In May 2026, Kurita Water Industries received the Distinction Award for Water Technology Company of the Year at the Global Water Awards 2026, presented on 19 May at the Global Water Summit in Madrid. The recognition reflects Kurita’s expansion of digital water treatment and corrosion monitoring services across industrial process water accounts in Japan, Asia, and North America [2].
- In October 2025, Chemetall, the surface treatment division of BASF Coatings, launched Gardolene D, the world’s first chromium-free and fluoride-free passivation solution for copper foils used in lithium-ion battery manufacturing. The product eliminates both regulated hazardous substances from the passivation process and targets compliance with EU battery regulation standards taking effect in 2027 [3].
Key Players in the Corrosion Inhibitors Market
Industrial Water, Data Center & Boiler Treatment Leaders
- Ecolab Inc. (Nalco Water)
- Veolia Water Technologies & Solutions / Xylem Inc.
- Solenis LLC
- Kurita Water Industries Ltd.
Oilfield Downhole, Pipeline & Refinery Process Specialists
- Baker Hughes Company
- ChampionX Corporation
- Clariant AG
- Specialty Additive, Passivation & VCI Packaging Innovators
BASF SE
- Lubrizol Corporation (Berkshire Hathaway)
- Cortec Corporation
Corrosion Inhibitors Market - Report Scope
Table 9: Report Scope for the Corrosion Inhibitors Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Chemical Action; Formulation Base; End-Use Industry; Protected Metal Substrate; Delivery & Dosing Mode |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial supplier revenue from formulated chemical corrosion inhibitors (organic film-forming amines and imidazolines, anodic passivating orthophosphates, molybdates, and nitrites, cathodic zinc and polyphosphate precipitators, and volatile vapor-phase corrosion inhibitors) dosed across oilfield, refinery, utility water, coolant, and packaging applications. Category Scope Note: Excludes bulk architectural and marine barrier paints, galvanic sacrificial anodes, and impressed-current cathodic protection rectifiers. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Saudi Arabia, India, Brazil, Canada, South Korea, USA, Germany, Japan, and additional countries in the full report |
| Key Companies Covered | Ecolab Inc. (Nalco Water), Baker Hughes Company, Veolia Water Technologies & Solutions / Xylem Inc., BASF SE, Lubrizol Corporation (Berkshire Hathaway), ChampionX Corporation, Cortec Corporation, Solenis LLC, Kurita Water Industries Ltd., Clariant AG |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up dosing-volume triangulation. |
Corrosion Inhibitors Market - Research Methodology
Table 10: Research Methodology for the Corrosion Inhibitors Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with oilfield pipeline integrity engineers, industrial cooling-water formulators, refinery crude-unit metallurgists, and VCI packaging technical directors. |
| Secondary Research | Analysis of U.S. DOT PHMSA pipeline safety enforcement dockets, U.S. EPA drinking-water and effluent guidance, ECHA hexavalent chromium restriction dossiers, IEA/EIA hydrocarbon production reports, and peer-reviewed electrochemistry journals. |
| Market Sizing and Forecasting | Top-down specialty water-treatment and oilfield production-chemical baselines reconciled against bottom-up formulated inhibitor tonnage (2.68M to 2.85M MT in 2026) and active ppm dosing schedules through 2036. |
| Country Forecasting Model | Econometric national projections weight sour-crude and pre-salt water-cut ratios, refinery throughput, semiconductor/data-center cooling capacity, and REACH/EPA chromate replacement rules across eight countries. |
| Operational Benchmark Traceability | Formulated tonnage, chromate-free share, and telemetry dosing indicators in Tables 2, 3, and 4 trace to PHMSA compliance records, ECHA socio-economic restriction assessments, EPA water guidance, and audited corporate segment disclosures. |
| Data Triangulation and Validation | Revenue estimates isolate active chemical corrosion-inhibition molecules and formulated blends while strictly excluding bulk epoxy/polyurethane coatings, biocides, standalone scale dispersants, and cathodic hardware. |
Corrosion Inhibitors Market by Segments
Corrosion Inhibitors Market segmented by Chemical Action:
- Mixed-Action Organic Film-Forming Inhibitors Amines and Imidazolines
- Anodic Passivating Inhibitors Chromates Nitrites and Orthophosphates
- Cathodic Precipitation Inhibitors Zinc Salts and Polyphosphates
- Volatile Vapor Phase Corrosion Inhibitors VCI Packaging
Corrosion Inhibitors Market segmented by Formulation Base:
- Water-Based Aqueous Corrosion Inhibitors
- Oil and Solvent-Based Formulations
- Volatile Solid and Powder VCI Emitters
- Bio-Based and Green Polymeric Formulations
Corrosion Inhibitors Market segmented by End-Use Industry:
- Oil and Gas Downhole Pipelines and Refinery Distillation
- Industrial Water Treatment Boilers and Cooling Towers
- Chemical Processing and Fertilizers
- Automotive Radiator Coolants and Metalworking Fluids
- Power Generation and Data Center Liquid Cooling
Corrosion Inhibitors Market segmented by Protected Metal Substrate:
- Carbon Steel and Low-Alloy Piping
- Copper and Cupronickel Heat Exchangers
- Aluminum and Multi-Metal Cooling Loops
- Stainless Steel and High-Nickel Alloys
Corrosion Inhibitors Market segmented by Delivery & Dosing Mode:
- Continuous Automated Chemical Injection and Metering
- Batch Treatment and Pipeline Pigging Slugs
- Closed-Loop Recirculating Coolant Charges
- VCI Film Paper and Desiccant Capsules
Corrosion Inhibitors Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Pipeline and Hazardous Materials Safety Administration (PHMSA). (2026, September 2). Notice of Probable Violation CPF 4-2026-020-NOPV: Internal Pipeline Corrosion Investigation at ECHO Terminal and Sealy Station. U.S. Department of Transportation PHMSA.
- [2] Ecolab Inc. (2026, March 20). Ecolab to Acquire CoolIT Systems, a Global Leader in Advanced Liquid Cooling for Next-Gen AI Data Centers. Ecolab Investor Relations.
- [3] Baker Hughes Company. (2026, October 28). Baker Hughes Announces Third-Quarter 2026 Results: Oilfield Services and Equipment Orders and Revenue Growth. Baker Hughes Investor Relations.
- [4] U.S. Environmental Protection Agency. (2026, March 4). EPA Launches RealWaterTA Initiative to Strengthen Support for Water Systems and Safe Drinking Water Compliance. U.S. Environmental Protection Agency News Releases.
- [5] European Chemicals Agency (ECHA). (2025, April 29). ECHA Proposes EU-Wide Restrictions on Hexavalent Chromium Cr(VI) Substances to Protect Workers and Public Health. European Chemicals Agency Helsinki.
- [6] Cortec Corporation. (2026, October 16). How VpCI Vapor Phase Corrosion Inhibitor Packaging Cuts Plant Energy Use and Carbon Emissions. Cortec Corporation Official Press Releases.
- [7] Wang, Y., et al. (2026, November 3). Synergistic Corrosion Inhibition of Carbon Steel by Binary Mannich Bases and Mannich-Based Imidazoline Quaternary Ammonium Salt. Coatings, 7(4), 73, MDPI Open Access.
- [8] Al-Moubaraki, A. H., et al. (2025, March 5). Recent Development of Corrosion Inhibitors: Types, Mechanisms, Electrochemical Efficiency and Industrial Applications. Technologies, 13(3), 103, MDPI Open Access.
- [9] Chen, L., et al. (2026, October 29). Sulfur Dispersant Coverage Constraints and Continuous Chemical Corrosion Monitoring in Sour Gas Pipelines. Corrosion and Materials Degradation, 7(4), 72, MDPI Open Access.
- [10] Liu, H., et al. (2025, February 12). Smart Inhibitor Systems Towards Anti-Corrosion: Design, Stimuli-Responsive Release and Performance. RSC Sustainability / Lab on a Chip Series, Royal Society of Chemistry.
- [11] Cortec Corporation. (2025, December 31). Cortec Introduces Corrosion Solution for Food Industry Boilers and Steam Condensate Lines. Cortec Corporation Product Releases.
- [12] BASF SE. (2025, August 21). Why More Research on Corrosion Protection Leads to Lower Raw Material Consumption and Greenhouse Gas Emissions at EUROCORR 2025 (Release P-25-152). BASF Global Media Relations.
- [13] Zhang, X., et al. (2026, October 29). Chitosan-Poly(aspartic acid) Microgel with Ionic Network for Dual Scale and Corrosion Inhibition in Industrial Cooling Water. Metals, 16(11), 1199, MDPI Open Access.
- [14] International Energy Agency (IEA). (2026, October 14). Oil Market Report: October 2026: Global Crude Production and Middle East Refining Throughput. International Energy Agency Paris.
- [15] Kurita Water Industries Ltd. (2026, September 2). Kurita Membrane India Private Limited Established to Deliver Water Treatment Technologies to the Indian Semiconductor and Industrial Sector. Kurita Water Industries Newsroom.
- [16] World Bank Group. (2025, December 3). Brazil Infrastructure, Industrial Productivity, and Energy Sector Investment Assessment. World Bank Country Publications.
- [17] Baker Hughes Company. (2026, April 23). Baker Hughes Announces First-Quarter 2026 Results: North American and International Oilfield Services and Chemical Performance. Baker Hughes Investor Relations.
- [18] BASF SE. (2025, October 13). Chemetall Launches First Global Chromium-Free and Fluoride-Free Gardolene D Passivation Solution for Copper Foils in Asia-Pacific. BASF Media Releases.
- [19] U.S. Energy Information Administration (EIA). (2026, September 10). United States on Track for Record Crude Oil Production in 2026 Across Permian and Gulf Coast Basins. U.S. Department of Energy EIA Today in Energy.
- [20] European Chemical Industry Council (Cefic). (2026, June 22). Cefic Chemical Trends Report Q1 2026: European Specialty Chemical Production and Industrial Demand. Cefic Brussels Publications.
- [21] Organisation for Economic Co-operation and Development. (2026, June 3). OECD Economic Outlook, Volume 2026 Issue 1: Japan Industrial and Semiconductor Manufacturing Investment. OECD Publishing Paris.
- [22] Kurita Water Industries Ltd. (2026, May 26). Kurita Selected for Distinction Award of Water Technology Company of the Year in Global Water Awards 2026. Kurita Water Industries Newsroom.
- [23] Clariant AG. (2026, May 8). Clariant Delivers Resilient Performance in Q1 2026 with 17.5% EBITDA Margin Before Exceptional Items Across Care Chemicals and Additives. Clariant Corporate News.
- [24] Ecolab Inc. (2026, January 30). Ecolab Nalco Water and Yara Renew Strategic Partnership in Le Havre for Ultrapure and Cooling Water Management. Ecolab UK & Europe Media Center.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the corrosion inhibitors market in 2026 and what is forecast for 2036?
- Which high-water-cut pipeline and data-center cooling pressures support demand for corrosion inhibitors?
- Why do Mixed-Action Organic Film-Forming Inhibitors lead the chemical action category?
- Why do Water-Based Aqueous Corrosion Inhibitors lead the formulation base category globally?
- How do growth rates differ across Saudi Arabia, India, Brazil and Canada?
- Which leading companies supply integrated cooling-water treatment programs versus oilfield pipeline inhibitors today?
- What limits hexavalent chromate and high-phosphorus formulations in the corrosion inhibitors market?
- What should refinery and utility operators evaluate before switching to chromate-free or biodegradable inhibitors?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Chemical Action, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Chemical Action, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Chemical Action, 2026 to 2036
- Mixed-Action Organic Film-Forming Inhibitors Amines and Imidazolines
- Anodic Passivating Inhibitors Chromates Nitrites and Orthophosphates
- Cathodic Precipitation Inhibitors Zinc Salts and Polyphosphates
- Volatile Vapor Phase Corrosion Inhibitors VCI Packaging
- Y-o-Y Growth Trend Analysis By Chemical Action, 2021 to 2025
- Absolute $ Opportunity Analysis By Chemical Action, 2026 to 2036
- Global Market Analysis and Forecast, By Formulation Base, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Formulation Base, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Formulation Base, 2026 to 2036
- Water-Based Aqueous Corrosion Inhibitors
- Oil and Solvent-Based Formulations
- Volatile Solid and Powder VCI Emitters
- Bio-Based and Green Polymeric Formulations
- Y-o-Y Growth Trend Analysis By Formulation Base, 2021 to 2025
- Absolute $ Opportunity Analysis By Formulation Base, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Industry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Industry, 2026 to 2036
- Oil and Gas Downhole Pipelines and Refinery Distillation
- Industrial Water Treatment Boilers and Cooling Towers
- Chemical Processing and Fertilizers
- Automotive Radiator Coolants and Metalworking Fluids
- Power Generation and Data Center Liquid Cooling
- Y-o-Y Growth Trend Analysis By End-Use Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Protected Metal Substrate, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Protected Metal Substrate, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Protected Metal Substrate, 2026 to 2036
- Carbon Steel and Low-Alloy Piping
- Copper and Cupronickel Heat Exchangers
- Aluminum and Multi-Metal Cooling Loops
- Stainless Steel and High-Nickel Alloys
- Y-o-Y Growth Trend Analysis By Protected Metal Substrate, 2021 to 2025
- Absolute $ Opportunity Analysis By Protected Metal Substrate, 2026 to 2036
- Global Market Analysis and Forecast, By Delivery & Dosing Mode, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Delivery & Dosing Mode, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Delivery & Dosing Mode, 2026 to 2036
- Continuous Automated Chemical Injection and Metering
- Batch Treatment and Pipeline Pigging Slugs
- Closed-Loop Recirculating Coolant Charges
- VCI Film Paper and Desiccant Capsules
- Y-o-Y Growth Trend Analysis By Delivery & Dosing Mode, 2021 to 2025
- Absolute $ Opportunity Analysis By Delivery & Dosing Mode, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Chemical Action
- By Formulation Base
- By End-Use Industry
- By Protected Metal Substrate
- By Delivery & Dosing Mode
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Ecolab Inc. (Nalco Water)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Baker Hughes Company
- Veolia Water Tech / Xylem Inc.
- BASF SE
- Lubrizol Corporation
- ChampionX Corporation
- Cortec Corporation
- Solenis LLC
- Kurita Water Industries Ltd.
- Clariant AG
- Veolia Water Technologies & Solutions / Xylem Inc.
- Specialty Additive, Passivation & VCI Packaging Innovators
- Lubrizol Corporation (Berkshire Hathaway)
- Ecolab Inc. (Nalco Water)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Chemical Action, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Formulation Base, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Protected Metal Substrate, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Delivery & Dosing Mode, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Chemical Action, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Formulation Base, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Protected Metal Substrate, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Delivery & Dosing Mode, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Chemical Action, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Formulation Base, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Protected Metal Substrate, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Delivery & Dosing Mode, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Chemical Action, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Formulation Base, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Protected Metal Substrate, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Delivery & Dosing Mode, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Chemical Action, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Formulation Base, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Protected Metal Substrate, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Delivery & Dosing Mode, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Chemical Action, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Formulation Base, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Protected Metal Substrate, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Delivery & Dosing Mode, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Chemical Action, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Formulation Base, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Protected Metal Substrate, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Delivery & Dosing Mode, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Chemical Action, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Formulation Base, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Protected Metal Substrate, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Delivery & Dosing Mode, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Chemical Action, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Chemical Action, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Chemical Action
- Figure 6: Global Market Value Share and BPS Analysis by Formulation Base, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Formulation Base, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Formulation Base
- Figure 9: Global Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-Use Industry
- Figure 12: Global Market Value Share and BPS Analysis by Protected Metal Substrate, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Protected Metal Substrate, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Protected Metal Substrate
- Figure 15: Global Market Value Share and BPS Analysis by Delivery & Dosing Mode, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Delivery & Dosing Mode, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Delivery & Dosing Mode
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Chemical Action, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Chemical Action, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Chemical Action
- Figure 32: North America Market Value Share and BPS Analysis by Formulation Base, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Formulation Base, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Formulation Base
- Figure 35: North America Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by End-Use Industry
- Figure 38: North America Market Value Share and BPS Analysis by Protected Metal Substrate, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Protected Metal Substrate, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Protected Metal Substrate
- Figure 41: North America Market Value Share and BPS Analysis by Delivery & Dosing Mode, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Delivery & Dosing Mode, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Delivery & Dosing Mode
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Chemical Action, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Chemical Action, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Chemical Action
- Figure 48: Latin America Market Value Share and BPS Analysis by Formulation Base, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Formulation Base, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Formulation Base
- Figure 51: Latin America Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by End-Use Industry
- Figure 54: Latin America Market Value Share and BPS Analysis by Protected Metal Substrate, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Protected Metal Substrate, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Protected Metal Substrate
- Figure 57: Latin America Market Value Share and BPS Analysis by Delivery & Dosing Mode, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Delivery & Dosing Mode, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Delivery & Dosing Mode
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Chemical Action, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Chemical Action, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Chemical Action
- Figure 64: Western Europe Market Value Share and BPS Analysis by Formulation Base, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Formulation Base, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Formulation Base
- Figure 67: Western Europe Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by End-Use Industry
- Figure 70: Western Europe Market Value Share and BPS Analysis by Protected Metal Substrate, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Protected Metal Substrate, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Protected Metal Substrate
- Figure 73: Western Europe Market Value Share and BPS Analysis by Delivery & Dosing Mode, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Delivery & Dosing Mode, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Delivery & Dosing Mode
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Chemical Action, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Chemical Action, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Chemical Action
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Formulation Base, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Formulation Base, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Formulation Base
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by End-Use Industry
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Protected Metal Substrate, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Protected Metal Substrate, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Protected Metal Substrate
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Delivery & Dosing Mode, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Delivery & Dosing Mode, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Delivery & Dosing Mode
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Chemical Action, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Chemical Action, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Chemical Action
- Figure 96: East Asia Market Value Share and BPS Analysis by Formulation Base, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Formulation Base, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Formulation Base
- Figure 99: East Asia Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by End-Use Industry
- Figure 102: East Asia Market Value Share and BPS Analysis by Protected Metal Substrate, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Protected Metal Substrate, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Protected Metal Substrate
- Figure 105: East Asia Market Value Share and BPS Analysis by Delivery & Dosing Mode, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Delivery & Dosing Mode, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Delivery & Dosing Mode
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Chemical Action, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Chemical Action, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Chemical Action
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Formulation Base, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Formulation Base, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Formulation Base
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by End-Use Industry
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Protected Metal Substrate, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Protected Metal Substrate, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Protected Metal Substrate
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Delivery & Dosing Mode, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Delivery & Dosing Mode, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Delivery & Dosing Mode
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Chemical Action, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Chemical Action, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Chemical Action
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Formulation Base, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Formulation Base, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Formulation Base
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by End-Use Industry
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Protected Metal Substrate, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Protected Metal Substrate, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Protected Metal Substrate
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Delivery & Dosing Mode, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Delivery & Dosing Mode, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Delivery & Dosing Mode
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Corrosion Inhibitors Market in 2026, and what is forecast for 2036?
FMI estimates that global corrosion inhibitors valuation stood at USD 9.1 billion in 2025 and reached USD 9.6 billion in 2026, with projections hitting USD 16.4 billion by 2036.
What is the CAGR for the Corrosion Inhibitors Market from 2026 to 2036?
The corrosion inhibitors sector is projected to expand at a 5.5% CAGR over the 2026 to 2036 window, adding USD 6.8 billion in incremental specialty chemical revenue across global energy, water and manufacturing facilities.
Which chemical action segment leads the Corrosion Inhibitors Market?
Mixed-Action Organic Film-Forming Inhibitors Amines and Imidazolines hold an estimated 48.0% of chemical action demand in 2026 with Anodic Passivating Inhibitors since chemisorbed nitrogen barrier films protect carbon steel without toxic chromates.
Which formulation base segment leads the Corrosion Inhibitors Market?
Water-Based Aqueous Corrosion Inhibitors represent 64.0% of the formulation base category in 2026 as industrial cooling towers, steam boilers, and produced-water reinjection loops require water-soluble active dosing.
Which country has a notable growth outlook during the assessment period?
Saudi Arabia leads national expansion projections at a 6.5% CAGR through 2036, followed closely by India at 6.2% and Brazil at 5.9% driven by sour-gas processing, seawater cooling and deepwater pre-salt FPSO injection.
Who are the key players in the market?
Ecolab, Baker Hughes, and Veolia / Xylem lead global commercial supply with BASF and Lubrizol. Other key participants include ChampionX, Cortec, Solenis and Kurita and Clariant.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
