

- Market Size (2026)
- USD 141.3 Bn
- Forecast (2036)
- USD 228.0 Bn
- CAGR (2026 to 2036)
- 4.9%
How big is the Countertop Market in 2026?
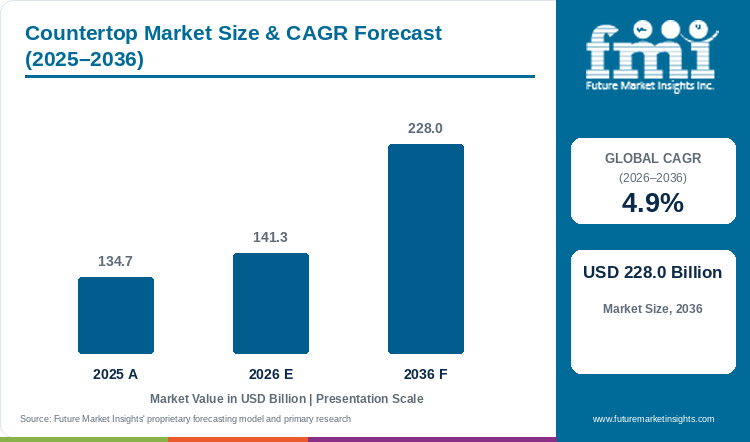
The global countertop market is estimated at USD 141.3 billion in 2026, compared with USD 134.7 billion in 2025, and is forecast to reach USD 228.0 billion by 2036, expanding at a CAGR of 4.9% from 2026 to 2036.
Demand for countertops is driven by kitchen and bathroom replacement and is expanding to permitted and low-silica materials as rules on engineered stone tighten. Renovation spending and housing programmes are supporting this demand, and the market is expected to grow at a mid-single-digit rate through 2036. For example, the US Census Bureau and HUD recorded USD 83.1 billion spent on 5.0 million kitchen remodels in the 2021 to 2023 period covered by the 2023 American Housing Survey. [1] Similarly, India's Cabinet approved PMAY-U 2.0 in August 2024 to help 10 million urban families construct, purchase or rent homes over five years. [2] Remodel spending covers the whole job and not the countertop alone, and a housing scheme creates countertop orders only when homes reach interior fitting.
Product restrictions are a second driver. Australia prohibited the manufacture, supply, processing and installation of defined engineered stone benchtops, panels and slabs from 1 July 2024, followed by an import prohibition from 1 January 2025. [3] Resin-free porcelain and sintered stone fall outside the definition. For instance, Caesarstone's June 2025 ICON disclosure states that its surfaces contain under 1% crystalline silica by XRD testing but need the same fabrication processes and safety measures as its quartz surfaces. [4] Therefore, according to analysis by FMI, restrictions redirect orders to permitted materials, while a lower silica content does not remove fabrication cost.
Market Size & Forecast
Table 1: Countertop Market Size and Forecast (USD billion and CAGR percentage), 2025 to 2036
| Market size and forecast | Value |
|---|---|
| 2025 Value | USD 134.7 billion |
| Estimated market size in 2026 | USD 141.3 billion |
| Projected market size by 2036 | USD 228.0 billion |
| CAGR (2026-2036) | 4.9% |
| Added revenue, 2026 to 2036 | USD 86.7 billion |
Key Market Trends & Insights
- Engineered quartz is estimated to account for 30.4% of countertop demand by material in 2026, which makes the range of slab designs and formats the main point of comparison for dealers.
- Residential projects are expected to hold 73.2% of demand by end use in 2026, so kitchens and bathrooms, new and renovated, set the order flow.
- Renovation spending is large. The US Census Bureau and HUD recorded USD 83.1 billion spent on 5.0 million kitchen remodels in 2021 to 2023, [1] which supports replacement orders alongside new construction.
- Product rules are redirecting orders. Australia's engineered stone import prohibition began on 1 January 2025, after its domestic prohibition in July 2024, [3] so composition records have become part of supplier selection.
- A low-silica composition does not remove workshop controls. Caesarstone's June 2025 ICON surfaces contain under 1% crystalline silica by XRD testing but keep the same fabrication processes and safety measures as its quartz surfaces. [4]
- New-home completions are falling in Germany. Destatis recorded 206,586 completed dwellings in 2025 against 251,937 in 2024, [5] which makes replacement work more important to suppliers.
Regional Highlights
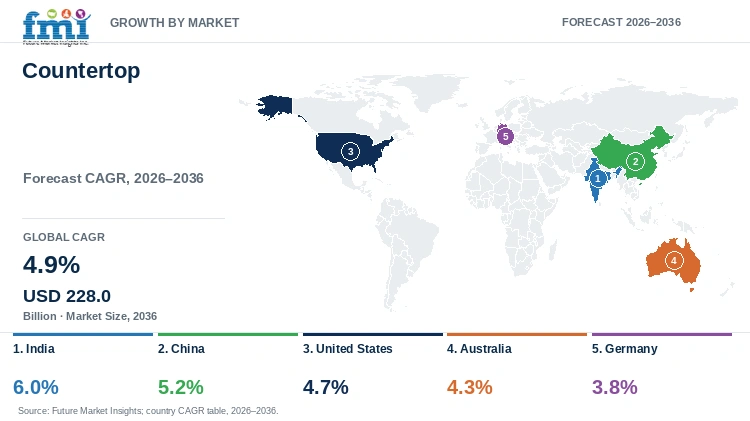
- India is likely to grow at a 6.0% CAGR during the forecast period, followed by China at 5.2%, the United States at 4.7%, Australia at 4.3% and Germany at 3.8%.
Analyst Perspective
“Renovation gives countertop suppliers a continuing source of demand as local restrictions redirect material choices. New compositions will win repeat orders when fabricators can use them reliably and customers understand the processing controls that remain necessary.”
- Nikhil Kaitwade, Principal Consultant, FMI
How is the Countertop Market segmented?
The Countertop Market is segmented by material, end use, construction activity and region.
- By Material: Granite, Solid Surfaces, Laminates, Engineered Quartz, Marble and Others.
- By End Use: Residential and Non-residential.
- By Construction Activity: New Construction and Renovation.
- By Region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why is Engineered Quartz the Leading Material in the Countertop Market?
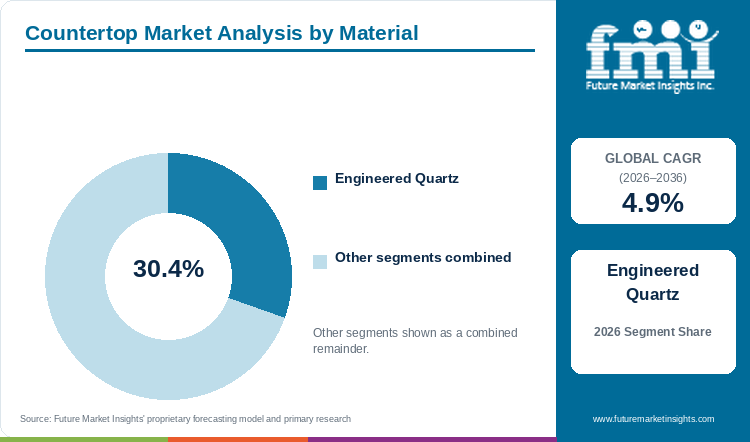
Engineered quartz accounts for an estimated 30.4% of countertop demand by material in 2026, equal to about USD 43.0 billion, as per FMI's analysis.
Table 2: Material Share for the Countertop Market (percentage share of revenue), 2026
| Segment | Share (2026) |
|---|---|
| Engineered quartz | 30.4% |
| Other segments combined | 69.6% |
Cambria sells quartz surfaces and states that the seam requirement depends on the slab and the application, and its estimating guidance asks for dimensions and fixture information. [6] A manufactured range of designs and slab formats gives dealers a clear offer, but the layout still decides how that offer becomes a finished countertop.
The material serves a wide range of projects where buyers want a defined design and a surface that can be fabricated for the room. Its leading share reflects use across markets where the product can be sold and processed under the local rules.
However, the global share does not describe the choice available in every country. Australia's prohibition applies to engineered stone products that meet its definition, with stated exclusions that include resin-free porcelain and sintered surfaces, [3] so a supplier has to establish the actual composition and product category before treating a design as available there.
Suppliers best placed to hold this share offer usable slab formats, explain how patterns will meet at the seams and give fabricators the composition and processing information for the product ordered.
Why is Residential the Leading End Use in the Countertop Market?
Residential projects are estimated to hold 73.2% of countertop demand by end use in 2026, as per FMI's analysis.
Table 3: End Use Share for the Countertop Market (percentage share of revenue), 2026
| Segment | Share (2026) |
|---|---|
| Residential | 73.2% |
| Other segments combined | 26.8% |
Cambria names cabinet dimensions and the positions of fixtures as inputs to an accurate estimate. [6] The residential lead comes from the number of rooms that need a counter and from replacement purchases as existing interiors are updated.
Renovation can require a new surface to fit cabinets that stay in place, while a new home allows more freedom in the layout, although the counter still has to accommodate the planned sink and cooking equipment. These are different orders for the dealer and the workshop even when the customer chooses the same material.
However, a higher spend on the visible surface does not remove the limits of the room. Cabinet positions, access and cutouts affect the dimensions that can be delivered and fitted, so the residential share should be read together with the work needed to complete each order.
Suppliers best placed offer samples that show the finished appearance, product information that helps the dealer establish the room requirements and fabrication support that reduces late changes to the chosen surface.
What are the Key Drivers, Restraints and Opportunities in the Countertop Market?
The countertop market is expected to grow from USD 141.3 billion in 2026 to USD 228.0 billion by 2036, which adds USD 86.7 billion over the forecast period. New construction and room renovation support demand, while fabrication work and product restrictions affect the material chosen and the cost of completing an order.
Driver: replacement and new residential construction. Existing kitchens and bathrooms create surface purchases independently of a new building project, and a renovation customer may keep the cabinets while changing the look of the room. That gives suppliers a recurring source of orders alongside counters specified for new homes.
Restraint: the work behind the finished surface. A slab price does not include every effect of the layout, because waste, difficult cutouts, joins and the route into the room change the quantity and work required. Cambria's estimating guidance makes dimensions and fixture details part of the quotation, [6] and local material restrictions can narrow the choice further. [3]
Opportunity: alternative compositions with clear product information. Caesarstone introduced ICON advanced fusion surfaces in June 2025 and states a crystalline silica content below 1.0% by XRD testing. [4] New compositions gain orders where they meet the requirements of the intended market and give the customer a useful combination of appearance and practical performance.
Suppliers that connect the selected design to a workable finished order are best placed to win a share of the USD 86.7 billion added between 2026 and 2036, because product development and fabrication support have to advance together.
How do Product Rules and Processing Guidance Influence Demand?
Product rules decide which surfaces can be sold, while processing guidance concerns the work needed to make the counter. A change in material composition does not answer every question about fabrication.
Rules that define the available product set
Australia introduced its domestic engineered stone prohibition in July 2024 and its import prohibition in January 2025. The restrictions follow a defined product boundary, with stated exclusions that include resin-free porcelain and sintered products. [3] That changes local sourcing and the range a dealer can present, and the actual composition matters more than a different commercial name.
However, Australia's rules do not set an identical product boundary in other countries. The global market includes materials sold under the requirements of their destination, so the Australian transition should be assessed within that country.
Guidance that applies during fabrication
OSHA and NIOSH issued their updated Worker Exposure to Silica during Countertop Manufacturing, Finishing, and Installation alert in February 2026. It covers the processing of natural and engineered stone, so the workshop review reaches beyond one material category. [7] The fabricator's ability to control the work affects the practical range of products a dealer can offer.
Caesarstone's ICON disclosure keeps fabrication safety measures despite a stated crystalline silica content below 1.0%. [4] A composition claim and the processing instructions have to be read together, because the claim does not show suitability for every application or remove fabrication requirements.
The rules change the mix of products available, and workshop conditions decide which of them become completed orders. A supplier that identifies the material clearly and provides the relevant technical record gives dealers a firmer basis for explaining an alternative to the customer.
What Technical and Operational Constraints Affect Countertop Supply?
Countertop supply has several separate constraints, from the selected slab to the room in which it is fitted.
The first is layout. Slab size and the proposed application affect the number of seams, and pattern placement affects how those seams look, which is why Cambria's guidance makes both the slab and the application relevant to the finished result. [6] A design chosen from a small sample may need a different cut plan when applied across a whole room.
The second is the existing room. Cabinet positions and access routes can limit the dimensions that can be delivered and installed, and sink and appliance positions set the cutouts. Keeping existing cabinets leaves less freedom than a new construction project.
The third is processing. Cutting and finishing natural or engineered stone brings the workshop controls described in the OSHA and NIOSH alert into the production plan, [7] and a changed composition may also need a review of tooling, handling and manufacturer instructions. [4]
The fourth is the quotation. Waste from the layout and the work around fixtures change the finished cost, so comparing slabs on price alone can miss these differences and lead to changes after the customer has chosen a material.
Suppliers with clear slab dimensions, representative samples and a fabrication network able to complete the proposed design have the stronger position. Resolving one constraint, such as material availability, does not resolve the cutouts, seams or access needed for the same order.
Where are the Commercial Opportunities for Countertop Suppliers?
The opportunities lie in replacement projects, a wider choice of compositions and formats that suit the sales channel.
The first is renovation. A customer keeping existing cabinets needs a replacement that fits those cabinets and the planned fixtures, and dealers can turn interest in a new appearance into an order by establishing those dimensions before the final material choice. The opportunity is an attractive surface that can be fitted with fewer late changes.
The second is the material offer. ICON is an example of a changed composition, [4] while granite, marble, laminates, solid surfaces and other permitted materials serve different project budgets and processing needs. A new surface gains commercial value when the dealer can explain what it is and the fabricator has instructions for working with it.
The third is the order format. Repeated residential layouts can support planned slab sizes and stock ranges, while individually specified renovation rooms need more detailed measurement, and a broad design catalogue has limited value when the chosen pattern is unavailable in the format the job needs. Samples that show the likely finished appearance, including pattern and joins as well as color, support a concrete decision about the room.
Countertop Market by Country (2026 to 2036)
Table 4: Country Growth Outlook for the Countertop Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026-2036) |
|---|---|
| India | 6.0% |
| China | 5.2% |
| United States | 4.7% |
| Australia | 4.3% |
| Germany | 3.8% |
What is supporting countertop demand in India?
India is likely to grow at a 6.0% CAGR during the forecast period, the highest rate among the countries analysed.
PMAY-U 2.0, approved in August 2024, provides assistance for 10 million urban families to construct, purchase or rent homes over five years. [2] Construction under the scheme is an advantage, because homes reach interior fitting in volume. The disadvantage is price sensitivity: residential buyers compare natural stone with manufactured surfaces at different price points, and the finished cost depends on the slab and the cut plan, since Cambria's guidance links slab size, application and the joins required. [6]
Suppliers serving India are likely to need a range suited to different budgets, with enough product information to complete the chosen surface in the available room.
What shapes countertop demand in China?
China is likely to grow at a 5.2% CAGR during the forecast period.
China's January 2025 policy supports purchases of materials for existing-home, kitchen and bathroom upgrades, with provinces determining the eligible categories. [8] Renovation support is an advantage for countertop dealers who can serve projects covered by local schemes. The disadvantage is that eligibility varies by province, and export supply faces destination rules, of which Australia's defined prohibition is one example. [3]
The opportunity lies in matching slab sizes and stock to the orders each channel serves, since repeated residential formats simplify planning and custom rooms need more detailed measurement.
What is driving countertop demand in the United States?
The United States is likely to grow at a 4.7% CAGR during the forecast period.
The 2023 American Housing Survey recorded 5.0 million kitchen remodels costing USD 83.1 billion in 2021 to 2023, [1] a substantial base of replacement work alongside new housing, which is an advantage. The disadvantage is the processing burden: the February 2026 OSHA and NIOSH alert addresses work on natural and engineered stone, [7] and workshops carry that cost into every order.
Suppliers gain from settling the room details before the material is final, because Cambria names cabinet dimensions and fixture locations among the inputs to an accurate estimate, [6] and from giving the workshop the product information needed to carry out that choice.
How is the material transition shaping countertop demand in Australia?
Australia is likely to grow at a 4.3% CAGR during the forecast period.
The engineered stone prohibition has changed the products available for benchtops within the regulatory definition, and resin-free porcelain and sintered products are among the stated exclusions. [3] Permitted alternatives are an advantage, because they can compete for redirected benchtop orders. The disadvantage is that a different product name does not make a surface a permitted alternative, so the actual composition and category have to be identified.
Replacement and new construction continue to create orders served by permitted materials, and suppliers with clear composition records have the stronger basis for presenting alternatives to dealers.
What is supporting specified countertop projects in Germany?
Germany is likely to grow at a 3.8% CAGR during the forecast period, the lowest rate among the countries analysed.
Destatis recorded 206,586 completed dwellings in 2025 against 251,937 in 2024, [5] 18% fewer, which reduces the flow of first-installation orders and is a disadvantage. The advantage is in kitchen and bathroom projects where the surface must fit a defined cabinet and appliance arrangement, because replacing a counter around an existing sink, or changing cooking equipment, alters the cutouts and joins required. [6]
Replacement work is therefore the more important source of orders, and suppliers create value through dimensions and finish information that designers and fabricators can read accurately, which reduces changes when the surface is fitted.
Who are the notable companies in the Countertop Market?
The companies differ by the materials and product families they offer. A corporate name can cover several compositions, so the useful comparison is the surface proposed for the customer's project.
Cosentino sells Silestone mineral surfaces, and Caesarstone sells ICON and other surface families. Caesarstone's June 2025 ICON introduction is a documented example of a composition change, with under 1.0% crystalline silica by XRD testing and fabrication safety requirements kept. [4] The offers are assessed at product level and are not interchangeable branded surfaces.
Cambria focuses on quartz surfaces and publishes information on dimensions, cutouts and seam requirements. [6] LX Hausys sells VIATERA quartz and HIMACS solid surfaces, and Wilsonart offers laminate and other countertop materials across several price positions. Silestone is a Cosentino brand and VIATERA is an LX Hausys product family, so neither is an independent company.
The selected design, the fabrication method and local availability decide which offer fits a project. The companies best placed to retain dealer business connect the design range with clear product identity and useful fabrication support.
Key Developments in the Countertop Market
- On 22 May 2026, Destatis published figures showing 206,586 completed dwellings in Germany in 2025, against 251,937 in 2024. [5]
- In February 2026, OSHA and NIOSH issued an updated countertop silica hazard alert covering the manufacturing, finishing and installation of natural and engineered stone surfaces. [7]
- In June 2025, Caesarstone introduced ICON advanced fusion surfaces, with less than 1.0% crystalline silica by XRD testing and fabrication safety measures kept in place. [4]
- On 26 January 2025, China issued a notice supporting purchases of materials for home decoration, kitchen and bathroom renewal, with provinces setting the eligible categories. [8]
- On 1 January 2025, Australia's engineered stone import prohibition began, following the domestic prohibition introduced in July 2024. [3]
- On 9 August 2024, India's Cabinet approved PMAY-U 2.0 to help 10 million urban families construct, purchase or rent homes over five years. [2]
Key Players in the Countertop Market
- Cosentino
- Caesarstone
- Cambria
- LX Hausys
- Wilsonart
Countertop Market Report Scope
Table 5: Report Scope for the Countertop Market (coverage fields and definitions), 2026 to 2036
| Coverage Field | Report Scope |
|---|---|
| Market Breakdown | Material (Granite, Solid Surfaces, Laminates, Engineered Quartz, Marble, Others); End Use (Residential, Non-residential); Construction Activity (New Construction, Renovation) |
| Quantitative Units | Revenue in USD billion and CAGR from 2026 to 2036 |
| Market Definition | Materials and fabricated surfaces sold for residential and non-residential countertop use, including granite, solid surfaces, laminates, engineered quartz, marble and other permitted countertop materials. It excludes cabinets, appliances, separately invoiced installation and surfaces sold solely for wall or floor applications. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa |
| Countries Covered | India, China, United States, Australia and Germany |
| Key Companies Covered | Cosentino, Caesarstone, Cambria, LX Hausys and Wilsonart |
| Forecast Period | 2026 to 2036 (with 2025 historical baseline) |
| Approach | Combined primary interviews, secondary literature analysis, and top-down data triangulation |
Countertop Market - Research Methodology
The market assessment combines primary interviews with industry participants and secondary research drawn from company disclosures, trade data and industry publications. Market size is built from supply-side and demand-side estimates and validated top-down, and segment shares and competitive positioning are checked through data triangulation before publication.
Countertop Market by Segments
By Material
- Granite
- Solid Surfaces
- Laminates
- Engineered Quartz
- Marble
- Others
By End Use
- Residential
- Non-residential
By Construction Activity
- New Construction
- Renovation
By Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Census Bureau and U.S. Department of Housing and Urban Development. 2023 Home Improvements Infographic: American Housing Survey. 2024.
- [2] Press Information Bureau, Government of India. Cabinet approves Pradhan Mantri Awas Yojana-Urban 2.0 Scheme. 9 August 2024.
- [3] Safe Work Australia. Silica: Engineered stone ban (guidance page). n.d.
- [4] Caesarstone. Caesarstone ICON advanced fusion surfaces. June 2025.
- [5] Federal Statistical Office of Germany (Destatis). Construction work completed in Germany. 22 May 2026.
- [6] Cambria. About Cambria FAQ (company web page). n.d.
- [7] OSHA and NIOSH. Worker Exposure to Silica during Countertop Manufacturing, Finishing, and Installation. February 2026.
- [8] Ministry of Commerce and five other departments, China. Notice on home decoration, kitchen and bathroom renewal in 2025. 26 January 2025.
Frequently Asked Questions
What is the size of the Countertop Market?
The global countertop market was valued at USD 134.7 billion in 2025 and is estimated at USD 141.3 billion in 2026. It is forecast to reach USD 228.0 billion by 2036, expanding at a CAGR of 4.9% from 2026 to 2036.
Which material and end use lead the Countertop Market?
Engineered quartz is estimated to account for 30.4% of demand by material in 2026, while residential projects are estimated at 73.2% by end use.
Which country is likely to grow fastest in the Countertop Market?
India is likely to grow at a 6.0% CAGR during the forecast period, followed by China at 5.2%, the United States at 4.7%, Australia at 4.3% and Germany at 3.8%.
Which products does the market include?
It includes materials and fabricated surfaces sold for countertop use across the listed material categories. Cabinets, appliances, separately invoiced installation and surfaces sold solely for wall or floor use are excluded.
Are Silestone and VIATERA independent companies?
No. Silestone is a Cosentino brand, and VIATERA is a product family of LX Hausys.
Does a low-silica claim remove fabrication requirements?
No. Caesarstone states that ICON contains less than 1.0% crystalline silica by XRD testing while keeping fabrication safety requirements, so the composition and the processing guidance have to be read together. [4]
Why do slab dimensions matter to the final quotation?
The layout sets the usable material, the seam requirements and the pattern transitions, and sink and appliance positions set the cutouts and fabrication work included in the quotation. [6]
How are Australian product restrictions treated?
The analysis follows the defined engineered stone boundary and its stated exclusions, including resin-free porcelain and sintered products, and does not assume that other countries apply the same rules. [3] Competitive Analysis of the Countertop Market Key Players
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Material, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material, 2026 to 2036
- Granite
- Solid Surfaces
- Laminates
- Engineered Quartz
- Marble
- Others
- Y-o-Y Growth Trend Analysis By Material, 2021 to 2025
- Absolute $ Opportunity Analysis By Material, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Residential
- Non-residential
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Construction Activity, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Construction Activity, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Construction Activity, 2026 to 2036
- New Construction
- Renovation
- Y-o-Y Growth Trend Analysis By Construction Activity, 2021 to 2025
- Absolute $ Opportunity Analysis By Construction Activity, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Material
- By End Use
- By Construction Activity
- By Country
- Market Attractiveness Analysis
- By Country
- By Material
- By End Use
- By Construction Activity
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Material
- By End Use
- By Construction Activity
- By Country
- Market Attractiveness Analysis
- By Country
- By Material
- By End Use
- By Construction Activity
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Material
- By End Use
- By Construction Activity
- By Country
- Market Attractiveness Analysis
- By Country
- By Material
- By End Use
- By Construction Activity
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Material
- By End Use
- By Construction Activity
- By Country
- Market Attractiveness Analysis
- By Country
- By Material
- By End Use
- By Construction Activity
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Material
- By End Use
- By Construction Activity
- By Country
- Market Attractiveness Analysis
- By Country
- By Material
- By End Use
- By Construction Activity
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Material
- By End Use
- By Construction Activity
- By Country
- Market Attractiveness Analysis
- By Country
- By Material
- By End Use
- By Construction Activity
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- By Material
- By End Use
- By Construction Activity
- By Country
- Market Attractiveness Analysis
- By Country
- By Material
- By End Use
- By Construction Activity
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By End Use
- By Construction Activity
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By End Use
- By Construction Activity
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By End Use
- By Construction Activity
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By End Use
- By Construction Activity
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By End Use
- By Construction Activity
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By End Use
- By Construction Activity
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By End Use
- By Construction Activity
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By End Use
- By Construction Activity
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By End Use
- By Construction Activity
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By End Use
- By Construction Activity
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By End Use
- By Construction Activity
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By End Use
- By Construction Activity
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By End Use
- By Construction Activity
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By End Use
- By Construction Activity
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By End Use
- By Construction Activity
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By End Use
- By Construction Activity
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By End Use
- By Construction Activity
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By End Use
- By Construction Activity
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By End Use
- By Construction Activity
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By End Use
- By Construction Activity
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Material
- By End Use
- By Construction Activity
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Cosentino
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Caesarstone
- Cambria
- LX Hausys
- Wilsonart
- Cosentino
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


