
- Market Size (2026)
- USD 34.0 Bn
- Forecast (2036)
- USD 103.7 Bn
- CAGR (2026 to 2036)
- 11.8%
How big is Gummy Market in 2026?
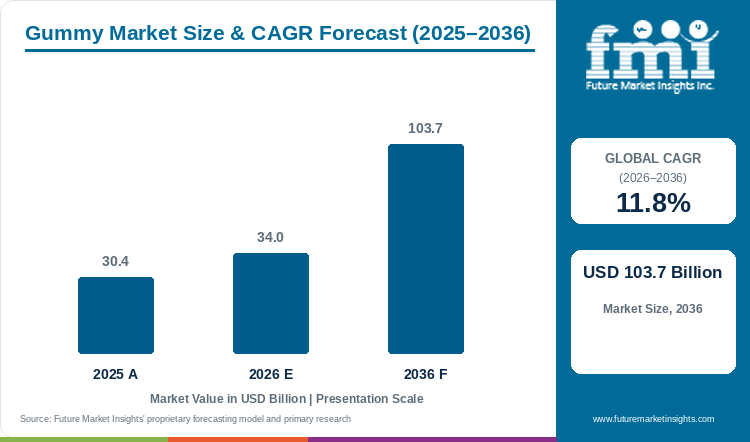
Sales in the gummy market are projected to grow at 11.8% CAGR, with market size rising from USD 30.4 billion in 2025 to USD 34.0 billion in 2026 and reaching USD 103.7 billion by 2036.
Increasing consumer fatigue toward conventional tablets and capsules, coupled with the daily requirement for measured micronutrient intake, led to the widespread adoption of chewable gummy formats. The gummy format joins measured active dosage with the familiar chew and flavor of confectionery, allowing wellness brands to transform medical supplementation into routine daily habits. On the back of this transition, the global gummy market stands at USD 30.4 billion in 2025 and rises to USD 34.0 billion in 2026. Industry valuation is forecast to reach USD 103.7 billion by 2036, expanding at an 11.8% CAGR and generating USD 69.7 billion in added revenue across the forecast period.
Vitamin gummies lead product demand with a 58.2% share in 2026, as brands prioritize shelf-stable multivitamins that eliminate bitter mineral notes. This broader consumer familiarity expands the potential user base beyond traditional supplement buyers, although technical issues such as active degradation during thermal depositing and nutrient potency loss across storage remain major hurdles for manufacturers.
Key Market Trends & Insights
- By product: Vitamin gummies are projected to account for 58.2% in 2026, supported by routine immunity, beauty, sleep, and general wellness use.
- By ingredient: Gelatin is estimated to hold 63.4% in 2026, driven by dependable elastic texture and established high-volume processing behavior.
- By end use: Adults remain the principal consumer group as wellness brands extend gummies beyond child-focused multivitamins into condition-specific routines.
- By distribution channel: Offline retail remains central for impulse confectionery and pharmacy-led supplements, while online channels widen access to specialized formulations.
Regional Highlights
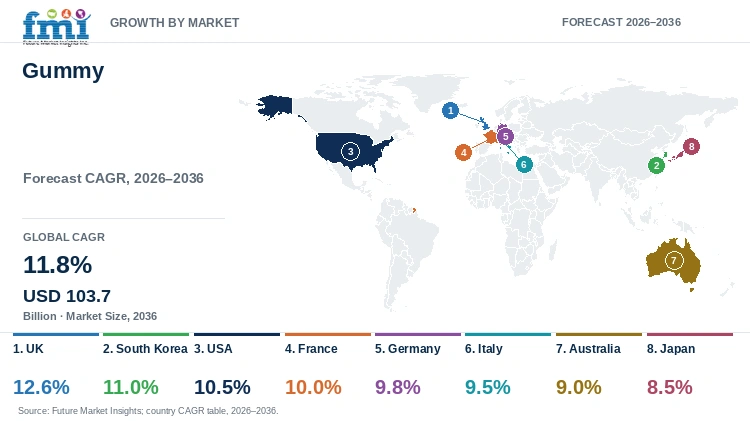
- Fastest-growing evaluated country: UK, at 12.6% CAGR from 2026 to 2036.
- By country: South Korea at 11.0%, USA at 10.5%, and France at 10.0% follow, while Japan records 8.5%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Gummy Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 30.4 billion |
| Estimated Market Size in 2026 | USD 34.0 billion |
| Projected Market Size by 2036 | USD 103.7 billion |
| CAGR, 2026 to 2036 | 11.8% |
| Added Revenue, 2026 to 2036 | USD 69.7 billion |
Formulating functional gummies presents severe chemical and mechanical processing challenges that do not exist in conventional tablet pressing. Thermal exposure during starch moghul depositing degrades heat-sensitive vitamins, while continuous moisture migration inside the hydrocolloid matrix can alter water activity and cause active degradation over time. U.S. Food and Drug Administration guidance enforces strict identity, purity, strength, and finished-product contamination standards on all dietary supplement lines. Consequently, contract manufacturers are compelled to invest in matrix-specific assay validation and stability testing across extended shelf lives, as batch testing failures can lead to mandatory product recalls, costly packaging relabeling, and lost retail distribution contracts.
Functional Gummy Revenue and Format Sizing
Table 2: Functional Gummy Revenue Indicators for the Gummy Market (USD billion and percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 30.4 | 34.0 | 103.7 |
| Vitamin gummy revenue at 58.2% share | 17.7 | 19.8 | 60.3 |
| Other product categories combined | 12.7 | 14.2 | 43.3 |
| Gelatin-based revenue at 63.4% share | 19.3 | 21.5 | 65.7 |
Per Capita and Consumer-Access Sizing
Gummies are moving from occasional purchase towards repeated wellness use, which changes the value of shelf access. A confectionery pack can win an impulse sale, while a vitamin, sleep or probiotic gummy has to bring the buyer back after the first bottle. Population growth alone does not explain the forecast; the stronger movement comes from higher spend per consumer as more functions enter one familiar format. The global value equals about USD 4.09 per person in 2026 and reaches USD 11.59 by 2036 when measured against United Nations population projections [3]. This broad comparison shows the room for adoption, although income, regulation and retail availability will keep country spending very uneven.
Table 3: Per Capita Spending Indicators for the Gummy Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD) | 3.69 | 4.09 | 11.59 |
| Spend per 1,000 people (USD) | 3,693.80 | 4,094.84 | 11,585.39 |
| Vitamin gummy spend per capita (USD) | 2.15 | 2.38 | 6.74 |
Table 4: Product and Ingredient Revenue Indicators for the Gummy Market (USD billion and percentages), 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 34.0 billion | Calculated from 2025 value at 11.8% |
| Vitamin gummy revenue | USD 19.8 billion | 58.2% product share |
| Gelatin-based revenue | USD 21.5 billion | 63.4% ingredient share |
| Plant-based gelatin substitutes | USD 12.4 billion | 36.6% balance share |
Analyst Perspective
"Gummy demand is shifting toward functional formats that must retain taste, potency, and shelf stability. Producers with validated dosing and flexible hydrocolloid systems can secure repeat retail and wellness-program demand."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Gummy Market segmented?
The gummy market is segmented by product, ingredient, end use, and distribution channel.
By product: Vitamins, minerals, carbohydrates, omega fatty acids, proteins and amino acids, probiotics and prebiotics, dietary fibers, CBD/CBN, melatonin, and others.
By ingredient: Gelatin and plant-based gelatin substitutes.
By end use: Adults, men, women, pregnant women, geriatric consumers, and kids.
By distribution channel: Offline and online.
Why do Vitamin Gummies account for a notable share of product demand?
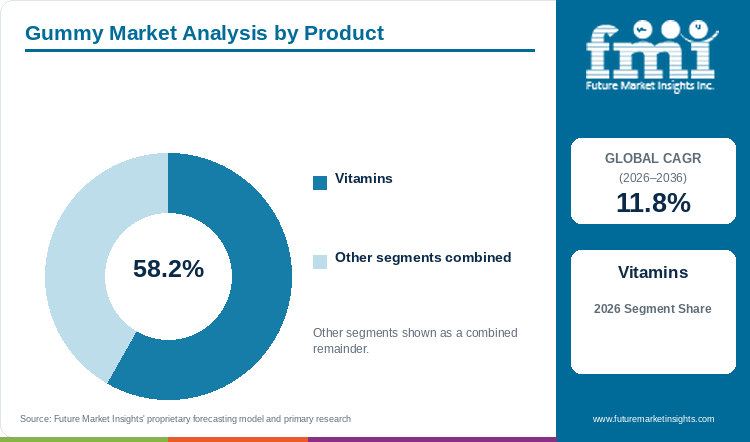
Vitamin gummies represent 58.2% of product demand in 2026, supported by familiar dosing and broad wellness positioning.
Table 5: Product Share for the Gummy Market (percentage share), 2026
| Product | Share (2026) |
|---|---|
| Vitamin Gummies | 58.2% |
| Other Product Segments Combined | 41.8%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment share from 100.0%.
Table 6: Product Leadership and Market Growth for the Gummy Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 11.8% |
| Leading Product Segment | Vitamin Gummies |
| Leading Product Share | 58.2% |
Vitamin gummies account for 58.2% of product demand in 2026 because the format has already crossed from children's multivitamins into adult routines. The segment gains when buyers can understand the benefit and serving quickly, while taste makes daily use easier than a tablet for some consumers. This leadership does not make every launch secure. Vitamins exposed to cooking and storage can fall below the declared amount, and crowded shelves make a general multivitamin difficult to separate from similar offers. Brands are therefore moving towards clearer benefit combinations and plant-based systems, but the value will remain with products which keep declared potency through shelf life rather than products that only carry a new flavour. Related demand can also be seen across vitamin gummy formulations where benefit clarity remains central.
- Based on product, vitamin gummies are projected to account for 58.2% in 2026, driven by broad usage across age groups.
- Manufacturers are extending vitamin platforms through vegan pectin systems, reduced-sugar recipes, and condition-specific nutrient combinations.
What supports Gelatin as a preferred choice in the ingredient category?
Gelatin accounts for 63.4% of ingredient demand in 2026, combining elastic texture with proven scale-up behavior.
Gelatin holds 63.4% of ingredient demand in 2026 as processors already know how it behaves during cooking, depositing, setting and drying. Its elastic chew and clear flavour release make high-volume production easier to repeat, which protects yields when manufacturers run several shapes and pack sizes. Plant-based systems are gaining attention from vegan, halal and clean-label buyers, yet they do not work as a direct one-for-one replacement. Pectin needs closer control of acid, soluble solids and setting temperature. This means gelatin can retain volume leadership even while pectin grows faster in selected products, because switching only creates value when the new texture remains stable through transport and storage. This processing choice also links the category with wider gelatin demand across food and supplement production.
- Gelatin is projected to account for 63.4% of ingredient revenue in 2026, supported by dependable elastic texture and established high-volume processing behavior.
- Pectin, agar, and related hydrocolloids expand formulation choice but require tighter control over acid balance and thermal processing.
How is Adult Demand shaping end-use applications?
Adult wellness users anchor repeat gummy purchases as brands widen benefits beyond traditional child-focused multivitamins.
Adult use is widening gummy demand because the product is now attached to sleep, beauty, digestion, minerals and general wellness rather than one family multivitamin occasion. Repeat use is possible when the serving is clear and the sensory quality remains acceptable after opening. However, more active ingredients also bring more interaction inside the matrix and a higher risk of overpromising benefits. Adult portfolios can therefore add value faster than basic children's products, but brands will need restrained claims, stable dosing and packaging that does not allow an active gummy to be mistaken for ordinary candy. This adult use sits inside broader nutraceutical adoption rather than remaining limited to candy occasions. The same movement is widening the role of gummies within functional food routines where convenience supports repeat intake.
- Adult applications remain commercially important, supported by repeat routines and broader condition-specific product portfolios.
- Beauty, sleep, digestive, and mineral formats widen adult purchase beyond the basic multivitamin occasion.
What gives Offline Retail a central role in distribution?
Offline retail remains central to gummy discovery through pharmacies, mass merchants, supermarkets, and convenience-led confectionery aisles.
Offline retail remains important because a gummy is discovered by sight and the buyer often compares flavour, benefit and pack count at the shelf. Pharmacies also add reassurance for supplement purchases, while supermarkets and convenience stores support confectionery trial. Online channels widen access to vegan, sugar-free and condition-specific products, but they place more pressure on ambient stability and inventory rotation. The stronger model is therefore not offline against online. It is a pack and supply plan that can survive both pharmacy guidance and parcel delivery without changing texture, dosage communication or product condition. Online assortment is also widening access to specialised food supplements which are not always carried by mass retail.
- Offline retail supports high visibility and pharmacy guidance, while online channels extend specialized assortment and subscription replenishment.
- Channel-specific packaging and stable ambient logistics influence margin protection across both supplement and confectionery formats.
What are the drivers, restraints, and opportunities in the Gummy Market?
Functional wellness elevates repeat consumption, while potency drift and sugar concerns restrict formulation, and plant-based low-sugar systems create value.
- Driver: Consumers increasingly prefer chewable nutrient delivery that fits established daily wellness routines.
- Restraint: Heat, moisture, acidity, and storage can reduce active stability or alter texture before shelf-life expiry.
- Opportunity: Pectin-based, reduced-sugar, and multi-benefit formulations can widen access across vegan and health-aware consumers.
Growth Analysis and Future Potential: Functional Demand Catalysts
Taste familiarity is the first reason buyers try gummies, but repeated demand is being created where the product fits a daily routine. The 58.2% share held by vitamin gummies shows that functional use is already the larger value pool. Growth can move further into probiotics, minerals, beauty and sleep, provided each product gives a clear reason for use and does not carry a sugar level that contradicts its wellness position. Retailers will favour products which explain serving and benefit quickly, while manufacturers with stable deposition and drying controls can keep the same chew across batches. This is why functional demand can lift the market, but only where formulation discipline sits behind the flavour. Digestive formats connect the market with growing probiotic supplement use among routine wellness buyers.
Risk Assessment of the Gummy Market: Formulation and Compliance Friction
A gummy matrix can hide variation that would be easier to detect in a conventional tablet. Sensitive nutrients may weaken under heat, water can move between the centre and coating and a pack can become sticky or hard before its expiry date. Finished-product testing is therefore central to the commercial risk. If the declared strength cannot be recovered and verified in the actual matrix, a larger production run only increases exposure. Sugar reduction adds another difficulty because sugar also contributes body and water control. Producers able to rebuild these functions, instead of only removing sweetness, will be in a better position to avoid returns and protect repeat orders. Sugar work also depends on the performance of naturally derived sweeteners inside a stable gel system.
Commercial Opportunity Analysis: Plant-Based and Reduced-Sugar Differentiation
Plant-based and reduced-sugar gummies offer a clear route to buyers who avoid gelatin or watch label content, but the opportunity rests on more than changing one ingredient. Pectin can support fruit-led positioning, although acid and setting conditions have to remain narrow. Reduced-sugar products face a similar trade-off because lower solids can weaken chew and shelf stability. Recent launches also show that sensory change is carrying commercial weight. Ferrara introduced a larger crunchy, chewy and juice-centred cluster in September 2025, proving that texture architecture can create premium shelf distinction even when the market is crowded. The opportunity is strongest where a cleaner formulation still gives a recognisable eating experience rather than asking the buyer to accept a weaker product. The shift creates a related opening for pectin systems where fruit-led texture is commercially suitable. Some suppliers are separating portfolios further through CBD gummy formats where serving and claim control require closer attention.
Gummy Market by Country (2026 to 2036)
Country growth is not following one global pattern. The UK leads the evaluated countries at 12.6% CAGR because plant-based formats and lower-sugar work are meeting an established wellness retail base. Japan stands at 8.5%, where slower population movement and exacting texture expectations make adoption more dependent on product precision than market breadth. Between these points, beauty-led demand supports South Korea, supplement scale supports the USA and taste or ingredient expectations shape the European markets. The rates therefore indicate different commercial routes, not the same demand story repeated across countries.
Table 7: Country CAGR and Primary Growth Levers for the Gummy Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| UK | 12.6% | Vegan formats, lower-sugar reformulation, and wellness-led retail |
| South Korea | 11.0% | Beauty nutrition and rapid adoption of functional formats |
| USA | 10.5% | Large supplement base, omnichannel retail, and flavor innovation |
| France | 10.0% | Premium taste, natural ingredients, and clean-label demand |
| Germany | 9.8% | Confectionery heritage and gelatin-free product expansion |
| Italy | 9.5% | Indulgent flavors paired with functional positioning |
| Australia | 9.0% | Natural formulations and pharmacy-led supplement demand |
| Japan | 8.5% | Texture novelty, compact packaging, and localized flavors |
Source: Market assessment
UK Gummy Market Outlook (2026 to 2036)
The UK has the fastest assessed outlook at 12.6% CAGR, but the reason is not population growth alone. Its population reached an estimated 69.5 million in mid-2025 while annual growth slowed to 0.3%, the lowest since mid-2020. Demand is more likely to come from higher penetration of vegan, functional and lower-sugar products through pharmacies, supermarkets and wellness retail. The hurdle sits in reformulation. Removing sugar can weaken body and chew, while pectin systems need controlled acidity. Suppliers which keep texture intact and support the claim with finished-product evidence can gain listings; products using only a clean-label message may struggle to hold repeat purchase.
Key takeaway: In UK, vegan formats, lower-sugar reformulation, and wellness-led retail shape supplier positioning and retail access.
South Korea Gummy Market Outlook (2026 to 2036)
South Korea carries an 11.0% CAGR outlook because beauty nutrition, probiotics and compact functional formats suit a digitally connected market with fast product discovery. The country's population remained close to 51.7 million in 2025, which gives brands a concentrated consumer base rather than a market growing through headcount. This speed can lift trial, although it also shortens the life of a trend. A collagen or vitamin gummy can move quickly through online channels, but excess variants can leave inventory behind once flavour or benefit interest changes. Brands with limited initial runs, local taste profiles and strong digital replenishment are in a better position than suppliers bringing a broad global range without adaptation. The market can grow faster than traditional supplement formats, but launch timing and stock discipline will decide how much of that growth becomes realised sales.
Key takeaway: In South Korea, beauty nutrition and rapid adoption of functional formats shape supplier positioning and retail access.
USA Gummy Market Outlook (2026 to 2036)
The USA is expected to advance at 10.5% CAGR on the back of a large supplement base and access across mass merchants, clubs, pharmacies and online channels. Population growth slowed to 0.5% between July 2024 and July 2025 as net international migration fell, so demographic expansion by itself will not carry the forecast. The stronger push comes from adults using gummies across vitamins, sleep, beauty and digestion. Scale is also the pressure point. A retailer can widen distribution quickly, but a potency failure or unstable coating can spread across a large number of packs. Manufacturers with validated assays and dependable high-volume depositing are therefore better placed to win national programmes.
Key takeaway: In USA, large supplement base, omnichannel retail, and flavor innovation shape supplier positioning and retail access.
France Gummy Market Outlook (2026 to 2036)
France is expected to record 10.0% CAGR, with a route to growth that is more taste-led than the global functional story. The population reached an estimated 69.1 million at the start of 2026, while the natural balance turned negative in 2025 for the first time since the end of the Second World War. Volume growth will therefore depend more on premiumisation and product conversion than on a rapidly expanding consumer base. Fruit authenticity, restrained sweetness and a refined chew can help gummies sit between confectionery and wellness. Products that appear too medicinal or excessively sweet may face resistance, which makes sensory quality as important as the claimed function.
Key takeaway: In France, premium taste, natural ingredients, and clean-label demand shape supplier positioning and retail access.
Germany Gummy Market Outlook (2026 to 2036)
Germany combines deep familiarity with gummy confectionery and a growing market for functional or gelatin-free formats. The country had 83.47 million residents at the end of 2025, but its population slipped 0.13% from a year earlier. This creates a large base without giving suppliers easy demographic growth. The 9.8% CAGR outlook is more likely to be earned through conversion towards vegan lines, pharmacy products and clearly differentiated benefits. Price comparison is strong and quality expectations are high, so an expensive reformulation that does not improve texture or usability can lose momentum. Efficient production and credible claims will matter more than novelty alone.
Key takeaway: In Germany, confectionery heritage and gelatin-free product expansion shape supplier positioning and retail access.
Italy Gummy Market Outlook (2026 to 2036)
Italy is projected at 9.5% CAGR, where fruit flavour and adult wellness can widen the category but affordability will remain part of the purchase. The resident population stood at 58.94 million at the start of 2026 and remained broadly stable only because positive migration offset a negative natural balance. The market therefore needs more value from each buyer rather than depending on population expansion. Smaller packs, familiar citrus or regional fruit profiles and selective fortification can support trial. If added function pushes price too far from confectionery expectations, repeat demand could soften, particularly outside premium pharmacy and specialist channels.
Key takeaway: In Italy, indulgent flavors paired with functional positioning shape supplier positioning and retail access.
Australia Gummy Market Outlook (2026 to 2036)
Australia is expected to grow at 9.0% CAGR as pharmacy-led supplements meet interest in natural and plant-based formulations. The country reached 27.61 million people in June 2025 and grew 1.5% over the year, with net overseas migration accounting for most of the increase. This gives brands a widening and internationally diverse consumer base, but long transport distances and warm conditions can expose weak moisture control. Products tested only for factory conditions may lose chew or develop surface stickiness in distribution. Climate stability, barrier packaging and clear pharmacy communication can therefore push adoption more reliably than a large flavour range.
Key takeaway: In Australia, natural formulations and pharmacy-led supplement demand shape supplier positioning and retail access.
Japan Gummy Market Outlook (2026 to 2036)
Japan records the slowest assessed rate at 8.5%, although it remains a technically demanding market rather than a weak one. The 2025 census placed the population at 123.05 million, down 2.5% from 2020, while the number of households still increased. Smaller households, ageing consumers and compact retail formats favour resealable packs and controlled serving sizes. The hurdle is that texture, sweetness and pack convenience have to feel deliberate. Local flavours and precise chew can create repeat use, but a global formulation brought without adjustment can fail even when the claimed benefit is relevant. Growth is therefore more likely to come through higher value and specialised use than broad population expansion.
Key takeaway: In Japan, texture novelty, compact packaging, and localized flavors shape supplier positioning and retail access.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Gummy Market?
Bayer AG, Church & Dwight Co., Inc., Pharmavite LLC, Nestle Health Science, Herbaland Naturals Inc., Haribo, Ferrara Candy Company, and Mondelez International are significant market players.
Competition is divided between supplement businesses which sell measured benefit and confectionery groups which sell taste, shape and familiar brands. The two sides are moving closer because buyers expect a functional gummy to eat well and a candy gummy to offer a different sensory reason for purchase. This overlap creates space for contract manufacturers with control over hydrocolloids, actives, drying and packaging. Portfolio size alone will not decide position. The stronger suppliers will be those able to repeat texture and declared composition while adjusting pack, flavour and serving for different retail channels. Confectionery companies retain an advantage in wider sugar confectionery distribution and impulse-led shelf placement.
- Supplement Platforms: Bayer, Church & Dwight, Pharmavite, Nestle Health Science, and Herbaland focus on vitamins and condition-specific wellness products.
- Confectionery Platforms: Haribo, Ferrara, and Mondelez compete through branded flavors, shapes, textures, and broad retail distribution.
- Ingredient and Process Differentiation: Gelatin, pectin, sweetener systems, coatings, and active stability programs determine manufacturing flexibility.
Competitive Benchmarking: Gummy Market
Table 8: Competitive Benchmarking for the Gummy Market (qualitative capability ratings), 2026
| Company | Gummy Portfolio Breadth | Functional Fortification | Retail Access | Geographic Reach |
|---|---|---|---|---|
| Bayer AG | High | High | High | High |
| Church & Dwight | High | High | High | Medium |
| Pharmavite | High | High | High | Medium |
| Nestle Health Science | High | High | High | High |
| Herbaland Naturals | High | High | Medium | Medium |
| Haribo | High | Low | High | High |
| Ferrara Candy Company | High | Low | High | Medium |
| Mondelez International | High | Low | High | High |
The comparison shows capability direction rather than a fixed ranking. Supplement groups carry stronger fortification systems, while confectionery groups bring wider sensory development and mass retail access. The gap can narrow where either side adds the missing capability through internal investment, acquisition or manufacturing partnerships.
Key Developments in the Gummy Market
- In September 2025, Ferrara introduced NERDS Juicy Gummy Clusters, featuring a larger size with a crunchy NERDS outer coating, a chewy gummy body, and a juicy center [5].
- In March 2025, Mondelez launched SOUR PATCH KIDS Strawberry-Watermelon Glow Ups with turmeric-derived edible confetti designed to fluoresce under blacklight.
- In March 2025, The Hershey Company positioned Shaq-A-Licious XL Gummies as the Official Gummy of March Madness within its NCAA partnership.
Key Players in the Gummy Market
Functional Supplement Platforms
- Bayer AG
- Church & Dwight Co., Inc.
- Pharmavite LLC
- Nestle Health Science
- Herbaland Naturals Inc.
Confectionery and Sensory-Innovation Platforms
- Haribo GmbH & Co. KG
- Ferrara Candy Company
- Mondelez International
- The Hershey Company
Gummy Market - Report Scope
Table 9: Report Scope for the Gummy Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product; Ingredient; End Use; Distribution Channel |
| Quantitative Units | USD Billion |
| Market Definition | Includes supplier revenue from gummy supplements and gummy confectionery formats covered by the stated taxonomy. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | UK, South Korea, USA, France, Germany, Italy, Australia, Japan, and additional countries in the full report |
| Key Companies Covered | Bayer, Church & Dwight, Pharmavite, Nestle Health Science, Herbaland, Haribo, Ferrara, Mondelez |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with data triangulation. |
Gummy Market - Research Methodology
Table 10: Research Methodology for the Gummy Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews with manufacturers, suppliers, distributors, retailers, formulators, quality professionals, industry experts, and key opinion leaders validate demand, formulation priorities, and purchasing decisions. |
| Secondary Research | Company annual reports, investor presentations, regulatory publications, industry associations, technical papers, trade journals, company websites, product literature, and public data support the assessment. |
| Market Sizing and Forecasting | Top-down and bottom-up approaches assess value demand, price points, segment mix, and channel adoption from 2026 to 2036. |
| Data Triangulation and Validation | Data is checked against macro-economic indicators, consumer demand drivers, regulatory developments, company activity, and historical category movement to support accuracy. |
Gummy Market by Segments
Gummy Market segmented by Product:
- Vitamins
- Minerals
- Carbohydrates
- Omega Fatty Acids
- Proteins and Amino Acids
- Probiotics and Prebiotics
- Dietary Fibers
- CBD/CBN
- Melatonin
- Others
Gummy Market segmented by Ingredient:
- Gelatin
- Plant-Based Gelatin Substitutes
Gummy Market segmented by End Use:
- Adults
- Men
- Women
- Pregnant Women
- Geriatric
- Kids
Gummy Market segmented by Distribution Channel:
- Offline
- Online
Gummy Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Statistics Bureau of Japan. (2026, June 25). Preliminary counts of the 2025 Population Census of Japan. Ministry of Internal Affairs and Communications
- [2] U.S. Food and Drug Administration. (2026). Dietary supplement oversight and finished-product quality expectations. U.S. Department of Health and Human Services.
- [3] United Nations, Department of Economic and Social Affairs. (2026). World Population Prospects data portal. United Nations Publications.
- [4] Mondelez International. (2025, March 4). SOUR PATCH KIDS introduces Strawberry-Watermelon Glow Ups. Mondelez Press Releases.
- [5] Ferrara Candy Company. (2025, September 30). NERDS Juicy Gummy Clusters product launch. Ferrara Corporate News.
- [6] The Hershey Company. (2025, March 24). Shaq-A-Licious XL Gummies named Official Gummy of March Madness. Hershey Newsroom.
- [7] Office for National Statistics. (2026). Population estimates for the UK: mid-2025. UK National Statistics Reports.
- [8] Statistics Korea. (2026). National population indicators and demographic statistics. Ministry of Economy and Finance.
- [9] U.S. Census Bureau. (2026, January 27). Vintage 2025 national and state population estimates. U.S. Department of Commerce.
- [10] National Institute of Statistics and Economic Studies. (2026). Demographic report 2025. INSEE Statistical Releases.
- [11] Federal Statistical Office of Germany. (2026). Population indicators and demographic reporting. Statistisches Bundesamt.
- [12] Italian National Institute of Statistics. (2026). Population and demographic indicators. ISTAT Releases.
- [13] Australian Bureau of Statistics. (2025, December 18). National, state and territory population, June 2025. Australian Government Publishing Service.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the gummy market in 2026 and what is forecast for 2036?
- Which consumer and formulation pressures support gummy demand?
- Why do vitamin gummies lead the product category?
- Why does gelatin retain the largest ingredient share?
- How do growth rates differ across the UK, South Korea, USA, and France?
- Which companies provide supplement and confectionery gummy portfolios?
- What limits adoption or supplier switching in the gummy market?
- What should buyers evaluate before sourcing gummy products?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product, 2026 to 2036
- Vitamins
- Minerals
- Carbohydrates
- Omega Fatty Acids
- Proteins and Amino Acids
- Probiotics and Prebiotics
- Dietary Fibers
- CBD/CBN
- Melatonin
- Others
- Y-o-Y Growth Trend Analysis By Product, 2021 to 2025
- Absolute $ Opportunity Analysis By Product, 2026 to 2036
- Global Market Analysis and Forecast, By Ingredient, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Ingredient, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Ingredient, 2026 to 2036
- Gelatin
- Plant-Based Gelatin Substitutes
- Y-o-Y Growth Trend Analysis By Ingredient, 2021 to 2025
- Absolute $ Opportunity Analysis By Ingredient, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Adults
- Men
- Women
- Pregnant Women
- Geriatric
- Kids
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Offline
- Online
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product
- By Ingredient
- By End Use
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Bayer AG
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Church & Dwight
- Pharmavite
- Nestle Health Science
- Herbaland Naturals
- Haribo
- Ferrara Candy Company
- Mondelez International
- Church & Dwight Co., Inc.
- Pharmavite LLC
- Haribo GmbH & Co. KG
- The Hershey Company
- Bayer AG
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Ingredient, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Ingredient, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Ingredient, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 18: Western Europe Market Value (USD Billion) Forecast by Ingredient, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Billion) Forecast by Ingredient, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 26: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 28: East Asia Market Value (USD Billion) Forecast by Ingredient, 2021 to 2036
- Table 29: East Asia Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 30: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Billion) Forecast by Ingredient, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Billion) Forecast by Ingredient, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product
- Figure 6: Global Market Value Share and BPS Analysis by Ingredient, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Ingredient, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Ingredient
- Figure 9: Global Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End Use
- Figure 12: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Distribution Channel
- Figure 15: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Product
- Figure 29: North America Market Value Share and BPS Analysis by Ingredient, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Ingredient, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Ingredient
- Figure 32: North America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by End Use
- Figure 35: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Distribution Channel
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Product
- Figure 42: Latin America Market Value Share and BPS Analysis by Ingredient, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Ingredient, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Ingredient
- Figure 45: Latin America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by End Use
- Figure 48: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Product
- Figure 55: Western Europe Market Value Share and BPS Analysis by Ingredient, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by Ingredient, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by Ingredient
- Figure 58: Western Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by End Use
- Figure 61: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Product
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by Ingredient, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by Ingredient, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by Ingredient
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by End Use
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Product
- Figure 81: East Asia Market Value Share and BPS Analysis by Ingredient, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by Ingredient, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by Ingredient
- Figure 84: East Asia Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by End Use
- Figure 87: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by Product
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by Ingredient, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by Ingredient, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by Ingredient
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by End Use
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by Product
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by Ingredient, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by Ingredient, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by Ingredient
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by End Use
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the gummy market in 2026, and what is forecast for 2036?
Future Market Insights estimates the gummy market at USD 34.0 billion in 2026, rising to USD 103.7 billion by 2036.
What is the CAGR for the gummy market from 2026 to 2036?
Future Market Insights projects 11.8% CAGR from 2026 to 2036. Functional routines support the rise, although potency control, sugar reduction and texture stability will decide how much demand converts into repeat sales.
Which product segment leads the gummy market?
Vitamin gummies are projected to hold 58.2% share in 2026, reflecting broad use across routine wellness applications.
Which ingredient segment leads the gummy market?
Gelatin is expected to account for 63.4% share in 2026 due to established texture performance and manufacturing familiarity.
Which country has a notable growth outlook?
The UK is projected to register a 12.6% CAGR from 2026 to 2036, supported by vegan formats and lower-sugar innovation.
Who are the key players in the market?
Key participants include Bayer, Church & Dwight, Pharmavite, Nestle Health Science, Herbaland, Haribo, Ferrara, and Mondelez.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
