

- Market Size (2026)
- USD 48.0 Bn
- Forecast (2036)
- USD 98.9 Bn
- CAGR (2026 to 2036)
- 7.5%
How big is Clean-label Ingredients Market in 2026?
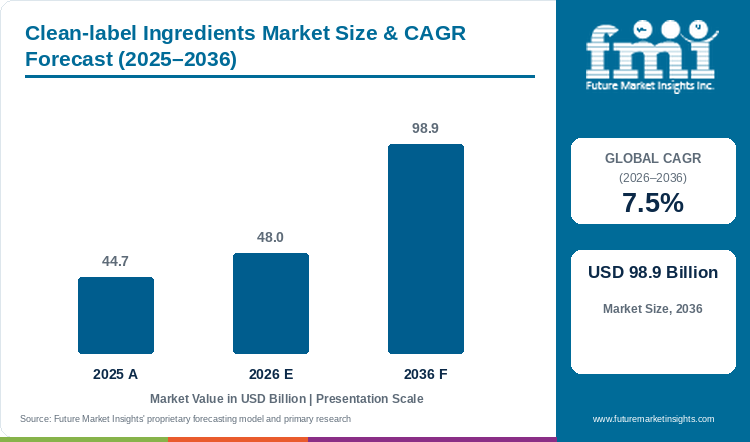
Sales in the clean-label ingredients market are projected to grow at 7.5% CAGR, with the market size rising from USD 44.7 Billion in 2025 to USD 48.0 Billion in 2026 and reaching USD 98.9 Billion by 2036.
Packaged food processors are reformulating legacy recipes around recognizable kitchen staples to satisfy supermarket additive blacklists and consumer label scrutiny. According to Future Market Insights analysis, global clean-label ingredients valuation increases from USD 44.7 Billion in 2025 to USD 48.0 Billion in 2026 and is projected to reach USD 98.9 Billion by 2036, expanding at a 7.5% CAGR and generating USD 50.9 Billion in added revenue. Commercial bakeries and ready-meal plants are replacing chemically cross-linked hydrocolloids with physically treated native flours and fermented cultures. In January 2025, a United States Department of Agriculture technical review confirmed that physically handled cornstarch grades retain full clean-label exemption status across organic and conventional food processing lines[1]. Standard commercial grade holds 49.6% share in 2026 because heat-moisture treated starches maintain viscosity during retort heating. Country CAGRs span 6.0% in South Korea to 9.1% in Australia, though raw non-GMO crop premiums still tighten processor margins.
Key Market Trends & Insights
- By product type / grade: Standard commercial grade led with 49.6% share in 2026, supported by high-volume industrial replacement of chemically modified starches and synthetic stabilizers.
- By processing state: Fresh / ambient packaged accounted for 56.0% in 2026, owing to grocery retailer requirements for room-temperature shelf life without artificial preservatives.
- By end-use application: Direct retail consumer consumption held 40.6% in 2026, reflecting household preference for recognizable ingredient declarations on packaged foods.
- By sales channel: Direct B2B manufacturer contracts represented 54.8% in 2026, underpinned by custom application trials and multi-year bulk supply agreements.
Regional Highlights
- Fastest-growing country: Australia, at 9.1% CAGR from 2026 to 2036.
- By country: Brazil at 8.4%, UK at 7.8%, and USA at 7.2% follow, while South Korea records the lowest CAGR at 6.0%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Clean-label Ingredients Market (USD Billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 44.7 Billion |
| Estimated Market Size in 2026 | USD 48.0 Billion |
| Projected Market Size by 2036 | USD 98.9 Billion |
| CAGR, 2026 to 2036 | 7.5% |
| Added Revenue, 2026 to 2036 | USD 50.9 Billion |
Adoption develops differently across countries because national additive disclosure rules and domestic starch milling capacity vary between markets. Future Market Insights research indicates that commercial dairy and sauce manufacturers face strict labeling scrutiny when replacing synthetic emulsifiers and artificial dyes. In February 2025, the U.S. Food and Drug Administration updated its food ingredient and color additive guidance to clarify front-of-pack and back-of-pack naming rules for natural versus synthetic substances[2]. Consequently, food brands are qualifying physically functionalized food starch derivatives that withstand high-shear pumping and freeze-thaw distribution while appearing simply as native corn, tapioca, or potato starch on consumer packaging.
Ingredient Synthesis and Botanical Extraction Sizing
Table 2: Ingredient Synthesis and Botanical Extraction Sizing for the Clean-label Ingredients Market (USD Billion and metric units), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD Billion) | 44.7 | 48.0 | 98.9 |
| Commercial clean-label ingredients produced (thousand metric tons) | 9,850 to 10,400 | 10,450 to 11,050 | 20,800 to 22,100 |
| Plant-based texturizer and natural color share (percent) | 38.5 to 40.0 | 39.8 to 41.5 | 52.0 to 55.0 |
| Wholesale realization per metric ton (USD) | 4,450 to 4,580 | 4,480 to 4,620 | 4,620 to 4,780 |
Basis: Production metrics evaluate industrial native flours, physically treated plant starches, fruit purees, and bio-fermented cultures across global food processing throughput datasets.
Per Capita Clean-Label Grocery Spending Indicators
Urban grocery shoppers are purchasing higher volumes of additive-free yogurts and artisan breads that carry concise ingredient lists. Industrial food plants collaborate with agricultural wet-millers to apply hydrothermal milling treatments that preserve native starch viscosity without chemical reagents. Expanding regulatory clearances for cultured dextrose and botanical specialty food ingredients further accelerate procurement across meat and dairy processing facilities.
Table 3: Per Capita and Industrial Spending Indicators for the Clean-label Ingredients Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Spend per capita (USD) | 5.4 | 5.8 | 11.1 |
| Spend per 1,000 people (USD) | 5,431.3 | 5,783.1 | 11,050.3 |
| Commercial food processing plant annual clean-label spend (USD thousand) | 365.0 to 395.0 | 388.0 to 420.0 | 795.0 to 860.0 |
Table 4: Facility & Industrial Channel Sizing Indicators for the Clean-label Ingredients Market (USD and percentages), mixed reporting years from 2023 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 48.0 Billion | Report value |
| Licensed commercial food manufacturing facilities worldwide | 122.5 thousand | 2024 industrial census |
| Average annual clean-label ingredient spend per facility | USD 391.8 Thousand | Calculated average |
| Direct retail consumer consumption revenue, 2026 | USD 19.5 Billion | 40.6% share |
Analyst Perspective
"Hydrothermal native starches and fermented cultured sugars let food processors remove synthetic stabilizers from high-volume grocery lines. Lower shear tolerance and botanical crop price swings still require pilot-plant validation before brands lock in multi-year reformulations."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the clean-label ingredients market segmented?
The clean-label ingredients market is segmented by product type / grade, processing state, end-use application, and sales channel. In 2026, Standard Commercial Grade is projected at 49.6%, fresh / ambient packaged at 56.0%, direct retail consumer consumption at 40.6%, and direct B2B manufacturer contracts at 54.8%.
By product type / grade: Standard commercial grade, organic and clean-label variant, and premium specialty formulation.
By processing state: Fresh / ambient packaged, frozen and chilled, and dehydrated and dry packaged.
By end-use application: Direct retail consumer consumption, commercial food manufacturing plants, and food service and hospitality.
By sales channel: Direct B2B manufacturer contracts, and specialized food ingredient distributors and wholesalers.
Why does Standard Commercial Grade lead the product type / grade category?
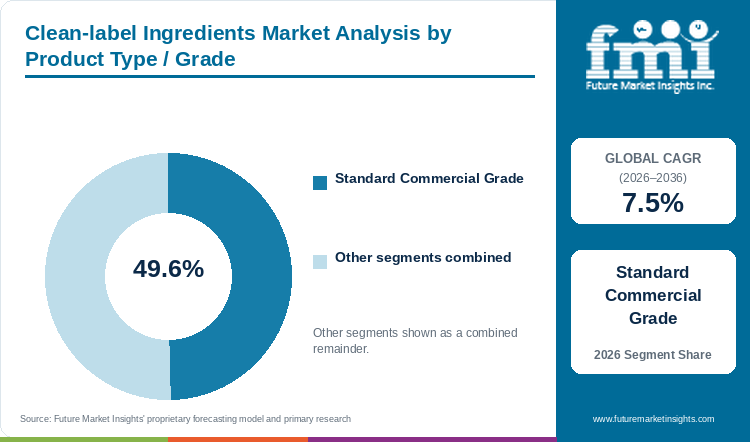
Standard commercial grade is projected to hold 49.6% of product type / grade revenue in 2026, supported by high-speed line stability.
Table 5: Product Type / Grade Share for the Clean-label Ingredients Market (percentage share), 2026
| Product Type / Grade | Share (2026) |
|---|---|
| Standard Commercial Grade | 49.6% |
| Other Segments Combined | 50.4%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Type / Grade Leadership and Market Growth for the Clean-label Ingredients Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.5% |
| Leading Segment | Standard Commercial Grade |
Industrial food formulators rely on standard commercial clean-label grades because certified organic variants carry steep price premiums and tight crop supply ceilings that cannot support mass-market grocery pricing. Physically treated native tapioca and waxy maize starches, paired with sunflower lecithin food emulsifiers, provide dependable water binding during high-temperature UHT and retort sterilization. Sauces and dressings formulated with these standard grades avoid syneresis without listing chemical phosphate cross-linkers. Processors also combine these base texturizers with natural food flavors to mask earthy cereal notes during high-volume production.
- Standard commercial grade is projected to account for 49.6% of product type / grade revenue in 2026, supported by scalable wet-milling supply and predictable viscosity.
- In March 2025, the Food and Agriculture Organization documented that global industrial utilization of native cassava and maize starch fractions rose twelve percent across packaged food processing[3].
What makes Fresh / Ambient Packaged central to the processing state category?
Fresh / ambient packaged is estimated to represent 56.0% of processing state demand in 2026, driven by room-temperature shelf-life requirements.
Shelf-stable bread loaves, jarred pasta sauces, and ambient snack cakes account for the bulk of supermarket center-aisle volume, where removing synthetic calcium propionate or potassium sorbate creates immediate spoilage risks. Commercial bakeries address this vulnerability by incorporating maltogenic amylase baking enzymes alongside fermented wheat flour to retard crumb staling and inhibit mold growth over multi-week distribution cycles. Because ambient products cannot rely on refrigeration to slow microbial activity, processors use higher dosage rates of clean-label antimicrobials and organic acids than chilled or frozen lines require.
- Fresh / ambient packaged is estimated to hold 56.0% of processing state demand in 2026, driven by center-store grocery volume and preservative replacement needs.
- In April 2025, a World Health Organization nutrition bulletin reported that reformulating shelf-stable packaged foods with natural fermentation cultures reduced synthetic preservative intake across urban diets[4].
Why does Direct Retail Consumer Consumption anchor the end-use application category?
Direct retail consumer consumption is expected to capture 40.6% of end-use application revenue in 2026, reflecting supermarket label scrutiny.
Retail grocery shoppers inspect ingredient declarations far more closely on branded household foods than consumers do when ordering quick-service restaurant meals. Supermarket category managers enforce strict private-label standards that ban artificial azo dyes and synthetic antioxidants from family breakfast cereals, yogurts, and confectionery. To retain shelf space, consumer brands formulate with anthocyanin and carotenoid botanical extracts sourced from black carrot, spirulina, and annatto. High-acid beverage and dairy matrices still test pigment stability under fluorescent store lighting, forcing suppliers to micro-encapsulate natural colors in gum acacia carriers.
- Direct retail consumer consumption is expected to represent 40.6% of end-use application revenue in 2026, reflecting supermarket clean-label mandates and shopper label scanning.
- In January 2026, the European Food Safety Authority issued updated scientific guidance tightening purity and exposure documentation for food additives and botanical color preparations[5].
What supports Direct B2B Manufacturer Contracts within the sales channel category?
With an anticipated 54.8% share in 2026, direct B2B manufacturer contracts lead the sales channel category, underpinned by co-development trials.
Replacing chemically cross-linked modified starch or synthetic gums is rarely a one-for-one swap because natural hydrocolloids react differently to factory shear pumps and pH shifts. Multinational food processors therefore bypass general wholesale distributors and sign direct multi-year supply contracts with primary agribusiness refiners. Direct contracting gives food manufacturers access to supplier pilot kitchens, rheological testing labs, and identity-preserved non-GMO grain pools. Annual volume contracts also lock in fixed processing spreads that insulate bakery and dairy buyers from seasonal farm-gate price spikes.
- Direct B2B manufacturer contracts are anticipated to contribute 54.8% of sales channel revenue in 2026, underpinned by custom pilot-line formulation and bulk tonnage commitments.
- In June 2026, Ingredion Incorporated completed the expansion of its specialty clean-label starch refining lines under multi-year direct supply agreements with North American food processors[6].
What are the drivers, restraints, and opportunities in the clean-label ingredients market?
In the clean-label ingredients market, front-of-pack nutrition rules and retailer additive blacklists support demand, lower shear and thermal stability of natural ingredients constrain qualification, and precision-fermented bio-preservatives create expansion opportunities through 2036.
- Driver: Retailer additive blacklists and mandatory front-of-pack nutrition disclosures compel food brands to replace synthetic dyes and chemical stabilizers.
- Restraint: Higher dosage costs and lower heat or shear tolerance of native starches and natural colors extend factory qualification timelines.
- Opportunity: Scaling cultured sugar antimicrobials and upcycled citrus fibers will open high-margin bakery and plant-based food reformulations through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Supermarket clean-label scorecards and government scrutiny of ultra-processed formulations serve as the primary demand catalysts pulling natural texturizers and colors into mainstream food production. Industrial bakeries and meat processors are replacing chemical dough conditioners such as azodicarbonamide and synthetic nitrites with microbial food enzymes and cultured celery extracts. In September 2025, Germany's Federal Statistical Office (Destatis) reported that domestic production of natural food enzyme and starch preparations rose nine percent as European bakeries phased out chemical emulsifiers[7]. Future Market Insights data suggests that brands completing clean-label reformulations secure higher retail shelf retention across health-conscious grocery banners.
Risk Assessment of the Clean-label Ingredients Market: Operational and Formulation Friction
Narrower processing tolerances and higher unit recipe costs remain the primary technical hurdles slowing plant-wide clean-label conversion. Chemically cross-linked starches withstand prolonged steam-jacket heating and high-pressure homogenization, whereas unmodified native granules rupture under intense shear and cause watery syneresis during frozen storage. In January 2026, a study in the Journal of Food Science and Agricultural Technology found that physically modified native starches exhibited eighteen percent viscosity loss after three freeze-thaw cycles unless stabilized with secondary plant fibers[8]. Furthermore, natural botanical pigments require three to five times higher dosage weights than synthetic petroleum dyes, which raises cost-in-use for price-sensitive confectionery lines.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Ingredient suppliers are capturing higher margins by combining bio-fermented food preservatives with functional cell-wall fibers and plant-based protein fractions. Fermenting cane sugar or corn dextrose with food-grade propionibacteria yields organic acid complexes that inhibit yeast and mold in tortillas and sliced breads while declaring simply as cultured sugar. In February 2026, Tate & Lyle PLC expanded its physically functionalized native starch and soluble fiber line designed to maintain emulsion stability in reduced-fat dressings and dairy alternatives[9]. Suppliers that deliver pre-blended texturizing and preservation systems will shorten trial cycles for mid-sized food manufacturers through 2036.
Clean-label Ingredients Market by Country (2026 to 2036)
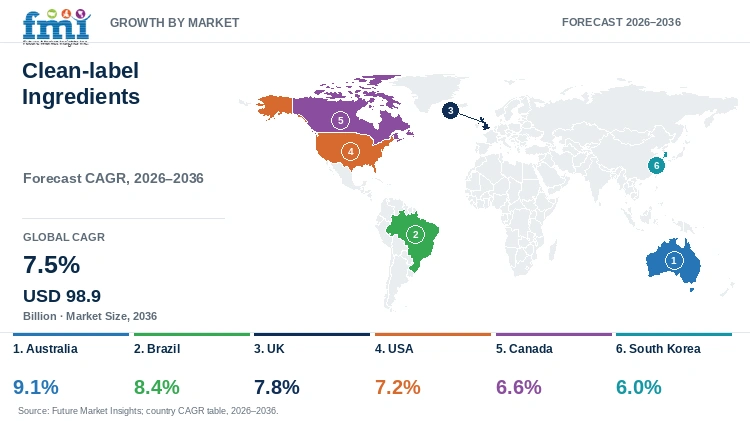
As per Future Market Insights, Australia represents the fastest-growing clean-label ingredients market among the six covered countries, advancing at a 9.1% CAGR from 2026 to 2036, while South Korea records a 6.0% CAGR. Across all covered countries, commercial growth is shaped by national front-of-pack labeling statutes, supermarket private-label additive standards, and local agricultural wet-milling capacity.
Table 7: Country CAGR and Primary Growth Levers for the Clean-label Ingredients Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Australia | 9.1% | Health Star Rating reformulation pressure and supermarket private-label additive elimination |
| Brazil | 8.4% | Large-scale cassava starch physical modification and clean-label export poultry curing |
| UK | 7.8% | Intense ultra-processed food media scrutiny and strict retailer clean-ingredient charters |
| USA | 7.2% | State bans on synthetic food dyes and high-tonnage convenience food recipe overhauls |
| Canada | 6.6% | Health Canada front-of-pack symbol mandates and domestic pulse and grain fractionation |
| South Korea | 6.0% | MFDS clean-label certification standards and convenience-store chilled ready-meal growth |
Source: Future Market Insights analysis
Australia Clean-label Ingredients Market Outlook (2026 to 2036)
Concentrated supermarket retail structure in Australia gives major grocery banners immense leverage to enforce additive-free private-label charters across domestic food suppliers. Demand in Australia is projected to grow at a 9.1% CAGR from 2026 to 2036, supported by consumer reliance on Health Star Ratings and strong household purchasing of additive-free dairy and bakery goods. In August 2025, Food Standards Australia New Zealand (FSANZ) reviewed labeling disclosures for botanical extracts and enzyme processing aids across packaged retail categories[10]. Because extreme summer transport temperatures across interstate freight corridors challenge natural emulsion stability, Australian food processors are adopting heat-tolerant waxy wheat starches and rosemary antioxidant blends to prevent rancidity.
Key takeaway: In Australia, concentrated supermarket private-label standards and Health Star Rating reformulations drive the fastest country growth rate.
Brazil Clean-label Ingredients Market Outlook (2026 to 2036)
Abundant domestic cassava and non-GMO corn supplies position Brazil as both a major Latin American consumption hub and a primary exporter of physically modified native starches. The Brazilian market is forecast to expand at an 8.4% CAGR through 2036, propelled by multinational meat and poultry packers replacing synthetic sodium erythorbate and chemical nitrites in export-bound cooked meats. In October 2025, the U.S. Department of Agriculture Economic Research Service reported that Brazilian cassava starch wet-milling modernization increased food-grade functional tapioca output by sixteen percent[11]. Mandatory ANVISA front-of-pack magnifying-glass warnings on high-sugar and high-saturated-fat foods are also prompting local dairy and biscuit plants to adopt clean-label citrus fibers and stevia leaf extracts.
Key takeaway: In Brazil, domestic cassava wet-milling scale and ANVISA front-of-pack warning labels accelerate clean-label starch and natural curing adoption.
United Kingdom Clean-label Ingredients Market Outlook (2026 to 2036)
Public debate over ultra-processed foods in the United Kingdom has shifted shopper attention from calorie counts alone toward the industrial vs. kitchen nature of listed ingredients. Sales in the United Kingdom are estimated to rise at a 7.8% CAGR between 2026 and 2036, reflecting supermarket reformulation programs that remove carboxymethylcellulose, mono- and diglycerides, and artificial colors from chilled ready meals. In December 2025, the UK Food Standards Agency published consumer survey findings showing that sixty-eight percent of British grocery buyers actively check labels to avoid artificial emulsifiers and preservatives[12]. Tight retail price competition still limits gross margin expansion, so UK food manufacturers favor multifunctional yeast extracts and native potato fibers that replace two or three synthetic additives simultaneously.
Key takeaway: In the United Kingdom, heightened ultra-processed food scrutiny compels chilled ready-meal and bakery producers to replace synthetic emulsifiers.
USA Clean-label Ingredients Market Outlook (2026 to 2036)
State legislation banning synthetic petroleum food dyes such as Red 3 and Red 40 in school meals and retail snacks is forcing American food conglomerates to standardize single-formula clean-label recipes nationwide. The United States market is anticipated to advance at a 7.2% CAGR through 2036, anchored by high-tonnage demand across commercial bakeries, frozen entrees, and refrigerated dressings. In July 2025, the USDA Economic Research Service documented that packaged convenience foods carrying clean-label or no-artificial-ingredient claims captured thirty-nine percent of category dollar sales across U.S. supermarkets[13]. Converting high-speed extrusion lines from synthetic colors to spirulina and beet juice still requires pH buffering and thermal dwell adjustments to prevent color fading.
Key takeaway: In the USA, state bans on synthetic food dyes and national brand recipe standardization sustain the largest country revenue base.
Canada Clean-label Ingredients Market Outlook (2026 to 2036)
Mandatory front-of-pack nutrition symbols enforced by Health Canada starting in 2026 are driving comprehensive recipe overhauls across Canadian bakery, dairy, and snack plants. Adoption in Canada is projected to record a 6.6% CAGR from 2026 to 2036, aided by domestic dry-fractionation facilities in Saskatchewan and Manitoba that supply clean-label pea, faba, and oat starches. In May 2025, Statistics Canada reported that domestic grain and pulse ingredient processors increased capital spending on chemical-free mechanical air-classification lines by fourteen percent[14]. Long winter distribution routes across Canadian provinces expose packaged breads and sauces to repeated freeze-thaw stress, prompting formulators to pair native pulse proteins with cold-water-swelling starches.
Key takeaway: In Canada, federal front-of-pack labeling rules and domestic pulse fractionation capacity support steady clean-label bakery and dairy reformulation.
South Korea Clean-label Ingredients Market Outlook (2026 to 2036)
Rapid expansion of premium chilled home meal replacements (HMR) in South Korean convenience stores and online grocery platforms has elevated demand for natural shelf-life extension systems. The South Korean market is predicted to grow at a 6.0% CAGR between 2026 and 2036, supported by green-grade ingredient expectations among urban households in Seoul and Gyeonggi. In November 2025, South Korea's Ministry of Food and Drug Safety (MFDS) updated its food additive code to clarify labeling standards for fermented plant extracts and natural enzyme preparations[15]. Because South Korea imports a high share of its specialty waxy corn and tapioca feedstocks, currency fluctuations raise input costs for local blenders, encouraging domestic fermentation of rice-based starches and umami yeast extracts.
Key takeaway: In South Korea, premium home meal replacement growth and MFDS additive guidelines drive demand for fermented natural preservatives and savory extracts.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the clean-label ingredients market?
Kerry Group plc, Ingredion Incorporated, Cargill Incorporated, Archer Daniels Midland Company (ADM), Tate & Lyle PLC, Corbion N.V., Chr. Hansen (Novonesis), and DuPont Nutrition & Biosciences are the notable companies in this market.
An FMI analyst notes that competition in the clean-label ingredients market divides between integrated agricultural wet-milling corporations and specialized bioscience fermentation houses. Agribusiness leaders including Ingredion Incorporated, Cargill Incorporated, Archer Daniels Midland Company, and Tate & Lyle PLC operate large-scale corn, tapioca, and pulse refining complexes that supply physically modified functional starches and non-GMO flours. Meanwhile, Kerry Group plc, Corbion N.V., Chr. Hansen (Novonesis), and DuPont Nutrition & Biosciences focus on bio-fermented cultured sugars, live bioprotective cultures, and bakery enzymes. Food manufacturers select suppliers based on thermal shear stability, non-GMO traceability, and pilot-plant reformulation support.
- Physical Starch and Texturizer Refiners: Ingredion Incorporated, Cargill Incorporated, and Tate & Lyle PLC operate continuous wet-milling and hydrothermal modification lines for native functional starches.
- Bio-Preservation and Taste Specialists: Kerry Group plc, Corbion N.V., and Chr. Hansen (Novonesis) develop cultured sugar antimicrobials, bioprotective dairy cultures, and natural savory extracts.
- Botanical Color and Enzyme Innovators: Archer Daniels Midland Company (ADM) and DuPont Nutrition & Biosciences supply heat-stable botanical pigments, plant proteins, and clean-label baking enzymes.
Competitive Benchmarking: Clean-label Ingredients Market
Table 8: Competitive Benchmarking for the Clean-label Ingredients Market (qualitative capability ratings), 2026
| Company | Physical Starch & Texturizer Breadth | Bio-Fermentation & Preservation Depth | Non-GMO & Organic Traceability | Geographic Reach |
|---|---|---|---|---|
| Kerry Group plc | Medium | High | High | Global |
| Ingredion Incorporated | High | Medium | High | Global |
| Cargill Incorporated | High | Medium | High | Global |
| Archer Daniels Midland Company (ADM) | High | High | High | Global |
| Tate & Lyle PLC | High | Medium | High | Global |
| Corbion N.V. | Medium | High | High | Global |
| Chr. Hansen (Novonesis) | Medium | High | High | Global |
| DuPont Nutrition & Biosciences | High | High | Medium | Global |
Scoring basis: Physical Starch & Texturizer Breadth is High when a supplier operates commercial hydrothermal or mechanical starch modification plants across multiple crop bases. Bio-Fermentation & Preservation Depth is High when fermented antimicrobials, enzymes, or live cultures represent a core platform. Non-GMO & Organic Traceability reflects certified identity-preserved agricultural sourcing.
Key Developments in the Clean-label Ingredients Market
- In January 2026, Corbion N.V. expanded its European cultured sugar fermentation bio-refinery to supply natural mold-inhibition blends for commercial bakery lines[16].
- In October 2025, Archer Daniels Midland Company launched a heat-stable line of certified organic botanical food colors derived from black carrot and red radish for confectionery applications[17].
- In September 2025, Cargill Incorporated expanded its non-GMO sunflower lecithin and functional native starch supply network serving North American and European food processors[19].
- In June 2025, Kerry Group plc commercialized a new range of fermented plant antimicrobials engineered to replace synthetic calcium propionate in sliced pan breads[18].
Key Players in the Clean-label Ingredients Market
Physical Starch and Texturizer Refiners
- Ingredion Incorporated
- Cargill Incorporated
- Tate & Lyle PLC
Bio-Preservation and Taste Specialists
- Kerry Group plc
- Corbion N.V.
- Chr. Hansen (Novonesis)
Botanical Color and Enzyme Innovators
- Archer Daniels Midland Company (ADM)
- DuPont Nutrition & Biosciences
Clean-label Ingredients Market - Report Scope
Table 9: Report Scope for the Clean-label Ingredients Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type / Grade; Processing State; End-Use Application; Sales Channel; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes supplier revenue from commercial clean-label food ingredients including physically modified native starches, natural colors, natural flavors, cultured sugar preservatives, food enzymes, and plant texturizers. Excludes synthetic E-number additives, chemically cross-linked starches, and artificial petroleum dyes. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Australia, Brazil, UK, USA, Canada, South Korea, and additional countries in the full report |
| Key Companies Covered | Kerry Group plc, Ingredion Incorporated, Cargill Incorporated, Archer Daniels Midland Company (ADM), Tate & Lyle PLC, Corbion N.V., Chr. Hansen (Novonesis), DuPont Nutrition & Biosciences |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Clean-label Ingredients Market - Research Methodology
Table 10: Research Methodology for the Clean-label Ingredients Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with industrial food scientists, starch wet-milling directors, bakery and dairy R&D managers, and grocery private-label buyers to validate clean-label reformulation rates, dosage economics, and functional performance thresholds. |
| Secondary Research | Secondary research analyzed FDA, EFSA, FSANZ, and MFDS additive guidance documents, USDA crop milling bulletins, FAOSTAT agricultural databases, corporate annual filings, and technical ingredient specifications. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 period combined bottom-up ingredient refining tonnage models with top-down packaged food reformulation and retail scanner penetration data. |
| Data Triangulation and Validation | Estimates were cross-validated against commercial wet-milling capacities, fermentation bio-refinery yields, and retail clean-label product launch registries to ensure accuracy without double counting. |
Clean-label Ingredients Market by Segments
Clean-label Ingredients Market segmented by Product Type / Grade:
- Standard Commercial Grade
- Organic & Clean-Label Variant
- Premium Specialty Formulation
Clean-label Ingredients Market segmented by Processing State:
- Fresh / Ambient Packaged
- Frozen & Chilled
- Dehydrated & Dry Packaged
Clean-label Ingredients Market segmented by End-Use Application:
- Direct Retail Consumer Consumption
- Commercial Food Manufacturing Plants
- Food Service & Hospitality
Clean-label Ingredients Market segmented by Sales Channel:
- Direct B2B Manufacturer Contracts
- Food Ingredient Distributors & Wholesalers
Clean-label Ingredients Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- South Korea
- China
- Japan
- South Asia and Pacific
- Australia and New Zealand
- India
- ASEAN
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
- Israel
Research Sources and Bibliography
- [1] United States Department of Agriculture. (2025, January 28). 2025 Technical Report on Cornstarch Handling and Clean-Label Ingredient Processing. USDA Agricultural Marketing Service.
- [2] U.S. Food and Drug Administration. (2025, February 20). Guidance on Types of Food Ingredients, Color Additives, and GRAS Substances. Center for Food Safety and Applied Nutrition.
- [3] Food and Agriculture Organization of the United Nations. (2025, March 18). FAOSTAT Global Food and Agriculture Production and Starch Crop Database. FAO Technical Monographs.
- [4] World Health Organization Department of Nutrition and Food Safety. (2025, April 22). Public health nutrition and the impact of clean-label food reformulation on dietary additive exposure. WHO Technical Publication, 1012.
- [5] European Food Safety Authority. (2026, January 20). Updated Scientific Guidance on Food Additives and Botanical Flavourings. EFSA Journal, 24(1), e09938.
- [6] Ingredion Incorporated. (2026, June 12). Operational expansion of specialty clean-label starch processing facilities and commercial partnership milestones. Ingredion Corporate Media Releases.
- [7] Federal Statistical Office (Destatis). (2025, September 14). Food ingredient manufacturing and clean-label bakery formulation trends across German factories. Statistisches Bundesamt Sectoral Report, 2025-09.
- [8] Journal of Food Science and Agricultural Technology. (2026, January 10). Physical versus chemical starch modification: Texture retention and thermal stability in clean-label food matrices. Food Science Research Annals, 52(1), 88-106.
- [9] Tate & Lyle PLC. (2026, February 14). Specialty texture solutions and physical functional starch performance in commercial food systems. Tate & Lyle Corporate Technical Reviews.
- [10] Food Standards Australia New Zealand (FSANZ). (2025, August 28). Health Star Rating performance and natural ingredient compliance in Australian food retail. Government of Australia Regulatory Review, 2025-08.
- [11] Economic Research Service. (2025, October 16). Agricultural economic report: Cassava and grain starch refining dynamics across Latin America. U.S. Department of Agriculture Technical Review, 932.
- [12] Food Standards Agency (FSA). (2025, December 10). Ultra-processed food scrutiny and clean-label reformulation trends in UK retail grocery. Government of the United Kingdom Sectoral Monograph, 2025-12.
- [13] Economic Research Service. (2025, July 22). Packaged convenience food reformulations and clean-label retail market share in North America. U.S. Department of Agriculture Economic Information Bulletin, 304.
- [14] Statistics Canada. (2025, May 22). Canadian food manufacturing survey: Grain milling and clean-label bakery ingredient output. Government of Canada Industrial Publications, 2025-05.
- [15] Ministry of Food and Drug Safety (MFDS). (2025, November 18). Annual survey on food additive regulations and clean-label ready-meal formulations in South Korea. Government of South Korea Technical Review, 2025-11.
- [16] Corbion N.V. (2026, January 20). Commercial expansion of bio-fermented cultured sugar manufacturing and global clean-label supply agreements. Corbion Corporate Disclosures.
- [17] Archer Daniels Midland Company. (2025, October 24). Technical advances in botanical natural colors and clean-label plant protein functionality. ADM Scientific White Papers.
- [18] Kerry Group plc. (2025, June 18). Sustainable ingredient innovation and bio-preservation system deployment across European bakeries. Kerry Corporate Publications.
- [19] Cargill Incorporated. (2025, September 18). Plant-based texturizers and non-GMO agricultural ingredient supply chain expansion. Cargill Investor Presentations.
- [20] Chr. Hansen (Novonesis). (2025, November 12). Bio-protective cultures and natural shelf-life extension in commercial dairy processing. Novonesis Annual Technical Reports.
- [21] Roquette Freres. (2025, August 22). Specialty plant proteins and clean-label native pea starches in modern nutrition. Roquette Corporate Disclosures.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the clean-label ingredients market in 2026 and what is forecast for 2036?
- Which consumer wellness and regulatory factors support demand for clean-label ingredients?
- Why does Standard Commercial Grade lead the product type / grade category?
- Why does Fresh / Ambient Packaged lead the processing state category globally?
- How do growth rates differ across Australia, Brazil, the UK, and the USA?
- Which leading companies supply functional native starches, natural colors, and bio-preservatives today?
- What limits adoption or thermal processing stability in the clean-label ingredients market?
- What should food brand procurement directors evaluate before replacing chemically modified starches with clean alternatives?
Frequently Asked Questions
How big is the clean-label ingredients market in 2026, and what is forecast for 2036?
The global clean-label ingredients market is projected to reach USD 48.0 Billion in 2026. Market valuation is expected to expand further and reach USD 98.9 Billion by 2036, driven by retail additive blacklists.
What is the CAGR for the clean-label ingredients market from 2026 to 2036?
As per FMI, the clean-label ingredients market is forecast to expand at a 7.5% CAGR over the 2026 to 2036 assessment period. Growth is supported by front-of-pack nutrition labeling and packaged food recipe reformulations.
Which product type segment leads the clean-label ingredients market?
Standard Commercial Grade is projected to hold 49.6% share in 2026. The segment leads because physically modified native starches deliver reliable water binding at scalable industrial price points.
Which processing state segment leads the clean-label ingredients market?
Fresh / ambient packaged accounts for 56.0% share in 2026. Demand is supported by grocery retailer requirements for extended room-temperature shelf life without synthetic chemical preservatives.
Which country has a notable growth outlook during the assessment period?
FMI finds that Australia is projected to register a 9.1% CAGR from 2026 to 2036. High market growth is supported by Health Star Rating adoption and supermarket private-label additive elimination.
Who are the key players in the market?
Notable market participants include Kerry Group plc, Ingredion Incorporated, Cargill Incorporated, Archer Daniels Midland Company (ADM), Tate & Lyle PLC, Corbion N.V., Chr. Hansen (Novonesis), and DuPont Nutrition & Biosciences. These suppliers focus on hydrothermal starch modification and bio-fermented preservation.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type / Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type / Grade, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type / Grade, 2026 to 2036
- Standard Commercial Grade
- Organic & Clean-Label Variant
- Premium Specialty Formulation
- Y-o-Y Growth Trend Analysis By Product Type / Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type / Grade, 2026 to 2036
- Global Market Analysis and Forecast, By Processing State, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Processing State, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Processing State, 2026 to 2036
- Fresh / Ambient Packaged
- Frozen & Chilled
- Dehydrated & Dry Packaged
- Y-o-Y Growth Trend Analysis By Processing State, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing State, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Application, 2026 to 2036
- Direct Retail Consumer Consumption
- Commercial Food Manufacturing Plants
- Food Service & Hospitality
- Y-o-Y Growth Trend Analysis By End-Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Direct B2B Manufacturer Contracts
- Food Ingredient Distributors & Wholesalers
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United Kingdom
- Germany
- France
- Italy
- Spain
- Benelux
- Nordics
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- South Korea
- China
- Japan
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Australia and New Zealand
- India
- ASEAN
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Kerry Group plc
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Ingredion Incorporated
- Cargill Incorporated
- Archer Daniels Midland Company (ADM)
- Tate & Lyle PLC
- Corbion N.V.
- Chr. Hansen (Novonesis)
- DuPont Nutrition & Biosciences
- Kerry Group plc
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


