

- Market Size (2026)
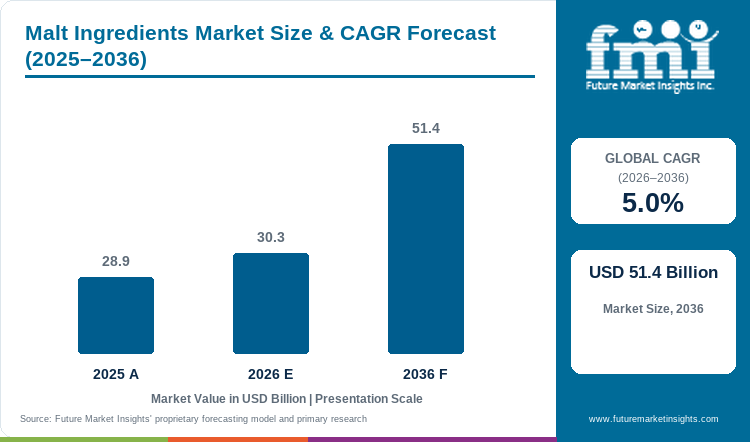
- USD 30.3 Bn
- Forecast (2036)
- USD 51.4 Bn
- CAGR (2026 to 2036)
- 5.0%
How big is Malt Ingredients Market in 2026?
USD 30.3 Billion in 2026 and USD 51.4 Billion by 2036 at a 5.0% CAGR.
The malt ingredients market is valued at USD 30.3 Billion in 2026 and is forecast to reach USD 51.4 Billion by 2036 at a 5.0% CAGR. Brewers remain a recurring customer, while distillers and food makers buy malt for different flavor, color and processing roles. Brazil's 2026 beer yearbook documents brewery activity in 2025. The breadth of possible customers matters because a brewery count alone says little about the tonnes of malt purchased. Suppliers need the right grade and delivery schedule for each use. The 2025 base is estimated at USD 28.9 Billion.
Malt buyers face two separate questions: what drink or food is being made and which barley lots can meet its specification? A brewer developing alcohol-free beer may need a different profile from a distiller. Defra reported a 6.4 million-tonne UK barley harvest in 2025 and quality problems for spring barley in several regions. Statistics Canada projected about 9.7 million tonnes of barley in 2026. Those are total crops, not ready-to-malt volumes. The supplier who can segregate suitable grain and keep extract, color and flavor consistent has an advantage when harvest quality varies.
Key Takeaways
- Demand is anchored by recurring use in brewing and food processing, but revenue capture increasingly depends on format breadth and raw-material consistency.
- Barley leads Raw Material in 2026 because its enzymatic performance and established malting infrastructure remain central to brewing and distilling.
- Malt Extract leads Product Type in 2026 because liquid and dried extracts simplify dosing, flavor delivery and formulation across beverages and foods.
- Standard Malt leads Grade in 2026 because buyers use it as the base specification for high-volume brewing and other repeat applications.
- The principal friction is the availability of barley that meets nitrogen, moisture, screening and germination requirements at an acceptable delivered cost.
- Profiled current companies include Malteurop Groupe, Boortmalt, Groupe Soufflet; Simpsons Malt Ltd.; Rahr Corporation; IREKS GmbH; Muntons PLC and Axereal.
Analyst Perspective
For a brewer, a cheaper malt lot can be expensive if extract or modification varies. Quality data, secure grain supply and consistency across batches belong in the same purchasing discussion.
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the malt ingredients market segmented?
The market is segmented by Raw Material, Product Type, Grade and End-use.
Raw Material comprises Barley, Wheat, Rye, Rice, Maize and Oat. Product Type includes Malt Extract, Dry Malt Extract, Liquid Malt Extract, Others and Malt Flour. Grade includes Standard Malt, Specialty Malt, Caramelized Malt and Roasted Malt. End-use covers Food & Beverages Industry, Beverages, Pharmaceutical Industry, Brewing, Medicines, Personal Care, Food, Distilling, Health Drinks and Nutraceuticals.
What keeps Barley central to the Raw Material category?
Barley remains the reference grain for malt because its husk structure, enzyme potential and long-established variety approval systems fit brewing and distilling workflows. Procurement is specification-led rather than purely commodity-led. The UK Malting Barley Committee evaluates varieties through micromalting and commercial trials before full approval. This process illustrates why barley sourcing is tied to end-user performance requirements rather than grain availability alone.
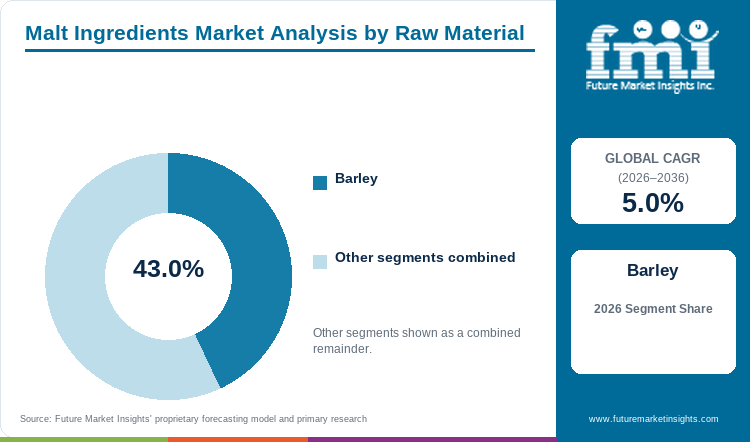
- Barley accounts for 43.0% of Raw Material in 2026. Maltsters buy grain that clears malting specifications; that qualified barley feeds recurring brewing and distilling demand.
- Defra's 2026 account of the 2025 UK crop recorded 6.4 million tonnes of barley. It also noted that spring barley in several regions missed malting-quality requirements. Barley is therefore a large input pool, but only qualifying lots can support the malt a brewer has specified.
Why does Malt Extract lead the Product Type category?
Malt extract gives formulators a concentrated route to malt flavor, color and fermentable solids without requiring an on-site malting or mashing step. That makes the format useful in beverages, bakery and other food systems. IREKS identifies in-house malt extract production as a core competence and has invested in automated evaporation capacity. Muntons also sells liquid and spray-dried formats for food and beverage applications.
- Malt Extract holds 42.0% of Product Type in 2026. Extract transfers mashing and concentration work upstream, giving food and beverage formulators a measured dose of malt solids or flavor.
- Malt extract allows a manufacturer to add malt flavor, color or fermentable material without milling whole malt on site. IREKS offers extract products for beverage and food recipes. The buyer's choice depends on concentration, flavor and how the extract behaves on its own line not simply on the supplier's installed capacity.
What sustains Standard Malt across the Grade category?
Standard malt supports the base load of brewing and other high-volume applications because it is purchased against familiar extract, moisture and modification targets. Specialty grades then adjust color or flavor around that base. Rahr’s current base-malt portfolio emphasizes common specifications across production locations. This type of consistency lowers qualification burden for repeat buyers and helps standard malt remain the default grade in large production runs.
- Standard Malt represents 51.0% of Grade in 2026. It supplies the base extract and modification targets; specialty grades can then adjust color or flavor without replacing the bulk malt input.
- In April 2025, RahrBSG described its 2-Row base malt as produced in both Shakopee and Alix to the same specification and quality-assurance standards. Multi-site consistency supports repeat procurement.
Why does Food & Beverages Industry lead the End-use category?
Malt can ferment a beer, deepen a bakery flavor or add color to a beverage. Those jobs call for different forms and specifications. Agriculture and Agri-Food Canada's 2025 application review and current ranges from Malteurop and Muntons show that food makers buy more than whole brewing malt. For a supplier, extract and specialty grades can bring in customers whose production lines were never designed to mill grain.
- Food & Beverages Industry accounts for 25.0% of End-use in 2026. Its lead reflects the combined use of malt across beverages, bakery-style foods and other formulated products.
- In July 2025, Agriculture and Agri-Food Canada updated a global analysis covering malt-based and cereal-germ ingredients across food and drink products. The breadth of applications supports supplier investment in multiple ingredient formats.
What are the drivers, restraints and opportunities in the malt ingredients market?
Demand is supported by diversified beverage and food applications, while malting-grade barley variability constrains supply and specialty low-carbon formats create a route to higher-value growth.
- Driver: Diversification across brewing, alcohol-free beverages and food formulations keeps malt relevant across multiple purchasing cycles.
- Restraint: Barley must clear tight quality specifications, so weather-driven variation can reduce usable supply and raise handling or drying costs.
- Opportunity: Suppliers can differentiate through malt extracts, specialty grades and verified lower-carbon barley-to-malt programs.
Brewers are using malt in a wider mix of products, including alcohol-free styles, while food makers use extracts for flavor and color. Brazil's 2026 beer yearbook documents product registrations and production activity for 2025. Each recipe has a different requirement for fermentability; flavor and color. A maltster that can supply both a dependable base and narrower specialty grades has more ways to serve customers than one tied to a single beer style.
The difficulty can begin in the field. Defra's 2026 crop report says the UK harvested 6.4 million tonnes of barley in 2025, but much spring barley in several regions did not meet malting quality. A large harvest therefore does not guarantee the right extract or protein profile for a brewer. Maltsters have to screen lots, segregate grain and sometimes change procurement routes. That adds cost before the malting plant can make a sale.
Muntons launched Climate Positive Malt in March 2025, putting a reported carbon figure beside familiar brewing specifications. Soufflet Malt began work on solid-state malt fermentation in 2026 for possible food ingredients. One development speaks to a brewer's sourcing target; the other is still a technical project. Both give maltsters ways to discuss value beyond base-malt price, provided the product performs in the customer's recipe.
Which country CAGRs are profiled in the malt ingredients market?
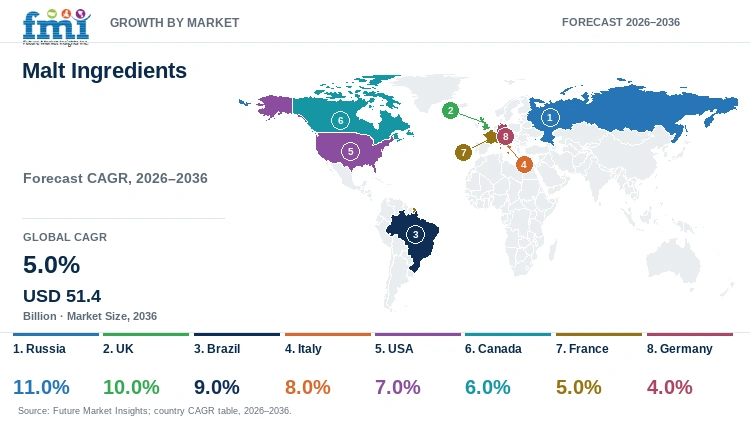
The following country CAGRs apply to the 2026 to 2036 forecast period.
| Country | CAGR |
|---|---|
| Russia | 11.0% |
| UK | 10.0% |
| Brazil | 9.0% |
| Italy | 8.0% |
| USA | 7.0% |
| Canada | 6.0% |
| France | 5.0% |
| Germany | 4.0% |
How do country-level CAGRs compare in the malt ingredients market?
The profiled rates span 4.0% to 11.0%, a 7.0 percentage-point spread. Russia and the UK form the fastest band, followed by Brazil and Italy. The USA and Canada sit in a mid-growth band while France and Germany show more measured expansion. These rates describe expected growth pace and do not establish relative market size.
- Russia: A large barley base supports domestic malting potential, but ingredient suppliers still need reliable variety selection and specification control.
- UK: A specialized malt, brewing and distilling chain creates high value per qualified tonne, while crop quality remains a recurring procurement risk.
- Brazil: Brewery registrations and rapid alcohol-free beer growth widen the customer base for base malt, specialty malt and extract formats.
- Italy: A substantial domestic brewing industry consumes barley malt directly, supporting repeat demand tied to beer output and product mix.
- USA: Thousands of craft breweries sustain a fragmented buyer base, though overall beer volume maturity increases pressure on service and differentiation.
- Canada: Barley scale and export-oriented quality programs support malt supply, while crop swings can change the premium for qualified grain.
- France: Its 2025 barley crop and established malt industry give buyers a substantial supply base, subject to malting-grade quality checks.
- Germany: The core beer market is mature, but alcohol-free production growth shifts demand toward recipe flexibility rather than simple volume expansion.
Country growth will depend on buyer mix, raw-material quality and the ability of suppliers to match local brewing or food specifications. The profiles below cover all eight profiled countries.
Country-wise Analysis
- Russia has the highest profiled rate, at 11.0% CAGR from 2026 to 2036. A large domestic barley base gives maltsters potential access to grain, but a commodity tonne is not automatically a malting tonne. Brewers need repeatable extract and flavor. For a supplier; local screening; lot segregation and dependable delivery are the route from grain availability to a usable ingredient.
- The UK is profiled at 10.0% CAGR from 2026 to 2036. Brewing and distilling both create demand for malt, but they do not buy identical specifications. Defra reported a 6.4 million-tonne barley harvest in 2025 and warned that spring-barley quality fell short in several areas. That puts value on approved varieties and careful sourcing. A maltster able to secure suitable lots and offer specialty grades can compete on more than a headline price per tonne.
- Brazil carries a 9.0% CAGR from 2026 to 2036. The agriculture ministry's 2026 beer yearbook records brewery and product activity for 2025, giving suppliers a recent view of the customer base. Small brewers may buy diverse specialty malts in shorter runs; large producers need scale and consistency. Brazil's geographic spread also makes distribution part of the offer. Registration counts describe market activity but do not, by themselves; measure malt volume.
- Italy is profiled at 8.0% CAGR from 2026 to 2036. The country has established brewers and a range of smaller producers with different recipe and lot-size needs. A malt supplier can win by matching dependable base malt with specialty flavor and color options. Logistics and technical support matter because a brewer cannot easily absorb a batch whose extract or handling differs from the approved recipe.
- The USA has a 7.0% CAGR in the 2026 to 2036 outlook. Its dispersed brewery network gives malt suppliers recurring orders, but each customer can require different styles, quantities and delivery frequency. Rahr's North American production and distribution model illustrates how manufacturing and local service can be combined. Specialty malt and recipe support offer a clearer way to grow an account than assuming every brewery will buy more base malt.
- Canada is profiled at 6.0% CAGR from 2026 to 2036. Statistics Canada projected about 9.7 million tonnes of barley for 2026. That headline includes grain that may never qualify for malting. A buyer needs variety, germination, protein and other quality information before committing to a lot. Canadian suppliers with grower relationships and segregation capacity can protect their value when the crop's usable share changes.
- France carries a 5.0% CAGR from 2026 to 2036. Agreste estimated 11.9 million tonnes of barley production in 2025. The country also has an established chain from growers through maltsters to domestic and export customers. For those buyers, the question is whether a supplier can deliver the specified grade efficiently and consistently. Energy use, grain selection and service for specialty recipes may determine where additional value is earned.
- Germany has the lowest profiled rate, at 4.0% CAGR from 2026 to 2036. Its long-established brewing sector makes base-malt demand substantial, while new beverage recipes can call for different flavor or fermentability. A malt supplier has to hold brewing specifications even as customers test alcohol-free and other styles. Growth is more likely to come through a better product mix and specialty work than through a simple increase in conventional beer volume.
Who are the notable companies in the malt ingredients market?
Malteurop Groupe, Boortmalt, Groupe Soufflet; Simpsons Malt Ltd.; Rahr Corporation; IREKS GmbH; Muntons PLC and Axereal are the notable companies profiled in this market.
Competition spans large global malt networks, integrated grain-to-malt groups and specialist ingredient suppliers. Malteurop Groupe, Boortmalt and the malt operations associated with Groupe Soufflet compete through multi-country production and barley sourcing. Axereal has a group-level grain position and owns Boortmalt. Simpsons Malt Ltd. and Muntons PLC combine UK barley relationships with differentiated sustainability programs. Rahr Corporation links North American malting with ingredients distribution while IREKS GmbH adds malt extracts and bakery-oriented application depth.
- Global integrated malt networks: Malteurop Groupe, Boortmalt, Groupe Soufflet and Axereal combine grain access or multi-site malt production with broad customer coverage.
- Specialty and application-focused suppliers: Simpsons Malt Ltd., Rahr Corporation, IREKS GmbH and Muntons PLC differentiate through specialty malt; extracts; distribution or sustainability programs.
- Adjacent grain businesses: Cargill and GrainCorp participate in cereal sourcing and distribution. Their current roles should be assessed separately from direct malt manufacturing.
Competitive Benchmarking: Malt Ingredients Market
| Company | Current Malt Manufacturing | Specialty / Ingredient Breadth | Traceability & Decarbonization | Geographic Reach |
|---|---|---|---|---|
| Malteurop Groupe | High | High | High | Europe, North America, Latin America; Asia-Pacific and other export markets |
| Boortmalt | High | Medium | High | Europe, North America, Latin America; Asia-Pacific and Africa through a global malting network |
| Groupe Soufflet | High | High | High | Global malt operations represented through Soufflet Malt across Europe, Americas, Asia-Pacific and Africa |
| Simpsons Malt Ltd. | High | Medium | High | United Kingdom production with international brewing and distilling customers |
| Rahr Corporation | High | High | Medium | United States and Canada production with broader ingredients distribution in multiple markets |
| IREKS GmbH | Medium | High | Medium | Germany and wider European network with international food and brewing ingredient operations |
| Muntons PLC | High | High | High | United Kingdom manufacturing with sales across international brewing and food ingredient markets |
| Axereal | High | Medium | High | France-based grain network with global malt reach through Boortmalt |
Scoring basis: Current Malt Manufacturing reflects documented production capacity and geographic reach. Specialty / Ingredient Breadth reflects named malt formats beyond a basic base-malt offer. Traceability & Decarbonization reflects current sourcing and plant-emissions programs. Scores are directional comparisons of public evidence, not audited capacity rankings.
Key Developments in the Malt Ingredients Market
- In February 2026, Soufflet Malt announced a EUR 100 million investment in a new AI-driven malthouse in India’s South Rajasthan. The planned facility is designed to supply beer and distilling customers as well as food and beverage manufacturers. The project extends production into a growing local demand center and adds capacity tied to broader food applications.
- In April 2025, Simpsons Malt Ltd. reported that a new germination and kilning vessel had become fully operational at Tweed Valley Maltings. The project added up to 15,000 tonnes of annual malt capacity. It also connected production to a renewable energy center; allowing the company to expand output while reducing the emissions intensity of kilning.
- In March 2025, Muntons PLC launched Climate Positive Malt at BeerX in Liverpool. Muntons reported that the product can deliver up to 30% lower carbon emissions per tonne than the UK malt average. The launch turns farm and malting decarbonization into a differentiated procurement attribute for craft brewers with formal carbon-reduction goals.
Key Players in the Malt Ingredients Market
Global Grain-to-Malt Networks
- Malteurop Groupe
- Boortmalt
- Groupe Soufflet
- Axereal
Specialty Malt and Ingredient Platforms
- Simpsons Malt Ltd.
- Rahr Corporation
- IREKS GmbH
- Muntons PLC
Adjacent Grain Businesses
- Cargill, Incorporated
- GrainCorp
Malt Ingredients Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Raw Material, Product Type, Grade and End-use |
| Quantitative Units | USD Billion |
| Market Definition | Revenue includes malt and malt-derived ingredients sold within the defined Raw Material, Product Type, Grade and End-use universe. Downstream beer, distilled spirits, finished food, medicines, personal care products and other finished goods are excluded. Bundled ingredient systems are included only to the extent that the malt ingredient is the priced market product; equipment, services and unrelated adjacent ingredients are excluded. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA, Germany, UK, France, Russia, Canada, Italy and Brazil |
| Key Companies Profiled | Malteurop Groupe; Boortmalt; Groupe Soufflet; Simpsons Malt Ltd.; Rahr Corporation; IREKS GmbH; Muntons PLC; Axereal |
| Forecast Period | 2026 to 2036 |
| Approach | Crop quality, maltster activity and beer-sector records used to interpret FMI forecasts. |
Malt Ingredients Market - Research Methodology
| Method | Approach |
|---|---|
| Market Scope | The report distinguishes barley harvests from malting-grade grain and finished malt. Brewers, distillers and food formulators have different needs for extract, color and flavor. |
| Public Evidence | Recent crop statistics, the 2025 Brazilian beer activity series and current maltster releases provide supply and downstream context. Total barley tonnes are not presented as malt output. |
| Forecast Interpretation | The 2026 and 2036 market values and country CAGRs are FMI forecasts. Grain and brewery counts help explain constraints and customer reach but do not independently size malt-ingredient sales. |
| Source Checks | Quality and capacity claims were checked for the named crop year or company. Adjacent grain businesses were kept distinct from verified malt manufacturers. |
Malt Ingredients Market by Segments
Malt Ingredients Market segmented by Raw Material:
- Barley
- Wheat
- Rye
- Rice
- Maize
- Oat
Malt Ingredients Market segmented by Product Type:
- Malt Extract
- Dry Malt Extract
- Liquid Malt Extract
- Others
- Malt Flour
Malt Ingredients Market segmented by Grade:
- Standard Malt
- Specialty Malt
- Caramelized Malt
- Roasted Malt
Malt Ingredients Market segmented by End-use:
- Food & Beverages Industry
- Beverages
- Pharmaceutical Industry
- Brewing
- Medicines
- Personal Care
- Food
- Distilling
- Health Drinks
- Nutraceuticals
Malt Ingredients Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- Statistisches Bundesamt (2025, July 29). Production of Alcohol-Free Beer Almost Doubled Over Ten Years.
- Ministério da Agricultura e Pecuária (2025, August 5). Brasil tem mais de 43 mil cervejas registradas.
- Statistics Canada (2025, January 6). How did this crop year shape up compared with previous harvests?
- Agriculture and Agri-Food Canada (2025, July 2). Customized Report Service - Global food and drink product trends containing malt-based and germ of cereal ingredients.
- Agreste, French Ministry of Agriculture (2025). GraphAgri 2025.
- Agreste, French Ministry of Agriculture (2025, December 16). Bilan conjoncturel 2025.
- U.S. Department of Agriculture, Foreign Agricultural Service (2025, January). Grain: World Markets and Trade.
- Malteurop (n.d.). MALTEUROP Homepage.
- Malteurop (n.d.). Sustainability First.
- InVivo (2025, September 10). MALTiply 2030: Soufflet Malt’s new strategy to unleash the power of malt in brewing, distilling and beyond.
- InVivo (2026, February 20). Soufflet Malt invests EUR 100 Million in India to build a new AI-driven malthouse for the food and beverage sector.
- InVivo (2026, May 27). Soufflet Malt and Ferments du Futur accelerate the development of new food applications through solid-state malt fermentation.
- Simpsons Malt Ltd. (2025, April 22). Malt production capacity increases at Simpsons Malt Limited.
- Simpsons Malt Ltd. (n.d.). Sustainability | Responsible Malting & Barley Sourcing.
- Rahr Corporation (2025, February 4). Gambrinus Malting Develops New Malt.
- Rahr Corporation (2025, April 7). What’s So Standard About Rahr 2-Row?
- IREKS GmbH (n.d.). Brewhouse: Resource-saving malt extract production.
- Muntons PLC (2025, March 19). Muntons unveil lowest-carbon Climate Positive Malt: enabling craft brewers to reach sustainability goals.
- Muntons PLC (n.d.). Sustainability.
- UK Department for Environment, Food and Rural Affairs (2026, September 3). Agriculture in the United Kingdom 2025; Chapter 7: Crops.
- Statistics Canada, September 2026 field-crop estimates
- Brazil Ministry of Agriculture, Beer Yearbook 2026
- UK Defra, September 2026 report on 2025 crops
This Report Answers
- How large is the Malt Ingredients Market in 2026, and what value is forecast for 2036?
- Which industry pressures are supporting demand for malt ingredients?
- Why does Barley hold the leading position in Raw Material?
- Why does Malt Extract hold the leading position in Product Type?
- How do profiled country growth rates differ across Russia, UK, Brazil; Italy; USA; Canada; France and Germany?
- Which companies supply or have documented roles in the relevant malt and malted-ingredient categories?
- What limits adoption, qualification or supplier switching in malt ingredients?
- What should buyers evaluate before purchasing malt ingredients?
Frequently Asked Questions
How big is the Malt Ingredients Market in 2026, and what is forecast for 2036?
The market is valued at USD 30.3 Billion in 2026 and is forecast to reach USD 51.4 Billion by 2036. The increase reflects recurring ingredient demand across brewing, food and beverage applications.
What is the CAGR of the Malt Ingredients Market from 2026 to 2036?
The market is forecast to expand at a 5.0% CAGR from 2026 to 2036. The pace depends on application diversification and the ability of suppliers to secure suitable malting raw materials.
Which Raw Material segment leads the Malt Ingredients Market?
Barley leads Raw Material in 2026. Its established malting performance and dedicated brewing and distilling supply chain support its position.
Which Product Type segment leads the Malt Ingredients Market?
Malt Extract leads Product Type in 2026. Extract formats reduce processing steps for formulators and can serve both beverage and food applications.
Which profiled countries have the highest growth rates in the Malt Ingredients Market?
Russia has the highest profiled CAGR at 11.0%, followed by the UK at 10.0% and Brazil at 9.0% from 2026 to 2036. These figures describe growth rates and not absolute country market size.
Which companies are active or profiled in the Malt Ingredients Market?
The profiled current companies are Malteurop Groupe, Boortmalt, Groupe Soufflet; Simpsons Malt Ltd.; Rahr Corporation; IREKS GmbH; Muntons PLC and Axereal. Cargill transferred its former malt business and GrainCorp demerged its former malt unit before the forecast period.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Raw Material, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Raw Material, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Raw Material, 2026 to 2036
- Barley
- Wheat
- Rye
- Rice
- Maize
- Oat
- Y-o-Y Growth Trend Analysis By Raw Material, 2021 to 2025
- Absolute $ Opportunity Analysis By Raw Material, 2026 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Malt Extract
- Dry Malt Extract
- Liquid Malt Extract
- Others
- Malt Flour
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Grade, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Grade, 2026 to 2036
- Standard Malt
- Specialty Malt
- Caramelized Malt
- Roasted Malt
- Y-o-Y Growth Trend Analysis By Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Grade, 2026 to 2036
- Global Market Analysis and Forecast, By End-use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-use, 2026 to 2036
- Food & Beverages Industry
- Beverages
- Pharmaceutical Industry
- Brewing
- Medicines
- Personal Care
- Food
- Distilling
- Health Drinks
- Nutraceuticals
- Y-o-Y Growth Trend Analysis By End-use, 2021 to 2025
- Absolute $ Opportunity Analysis By End-use, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Raw Material
- By Product Type
- By Grade
- By End-use
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Material
- By Product Type
- By Grade
- By End-use
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Raw Material
- By Product Type
- By Grade
- By End-use
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Material
- By Product Type
- By Grade
- By End-use
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Raw Material
- By Product Type
- By Grade
- By End-use
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Material
- By Product Type
- By Grade
- By End-use
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Raw Material
- By Product Type
- By Grade
- By End-use
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Material
- By Product Type
- By Grade
- By End-use
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Raw Material
- By Product Type
- By Grade
- By End-use
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Material
- By Product Type
- By Grade
- By End-use
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Raw Material
- By Product Type
- By Grade
- By End-use
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Material
- By Product Type
- By Grade
- By End-use
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Raw Material
- By Product Type
- By Grade
- By End-use
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Material
- By Product Type
- By Grade
- By End-use
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material
- By Product Type
- By Grade
- By End-use
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material
- By Product Type
- By Grade
- By End-use
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material
- By Product Type
- By Grade
- By End-use
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material
- By Product Type
- By Grade
- By End-use
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material
- By Product Type
- By Grade
- By End-use
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material
- By Product Type
- By Grade
- By End-use
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material
- By Product Type
- By Grade
- By End-use
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material
- By Product Type
- By Grade
- By End-use
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material
- By Product Type
- By Grade
- By End-use
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material
- By Product Type
- By Grade
- By End-use
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material
- By Product Type
- By Grade
- By End-use
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material
- By Product Type
- By Grade
- By End-use
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material
- By Product Type
- By Grade
- By End-use
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material
- By Product Type
- By Grade
- By End-use
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material
- By Product Type
- By Grade
- By End-use
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material
- By Product Type
- By Grade
- By End-use
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material
- By Product Type
- By Grade
- By End-use
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material
- By Product Type
- By Grade
- By End-use
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material
- By Product Type
- By Grade
- By End-use
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material
- By Product Type
- By Grade
- By End-use
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material
- By Product Type
- By Grade
- By End-use
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Raw Material
- By Product Type
- By Grade
- By End-use
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Malteurop Groupe
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Boortmalt
- Groupe Soufflet
- Simpsons Malt Ltd.
- Rahr Corporation
- IREKS GmbH
- Muntons PLC
- Axereal
- Cargill, Incorporated
- GrainCorp
- Malteurop Groupe
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


