

- Market Size (2026)
- USD 290.1 Mn
- Forecast (2036)
- USD 534.4 Mn
- CAGR (2026 to 2036)
- 6.3%
How big is Maltitol Market in 2026?
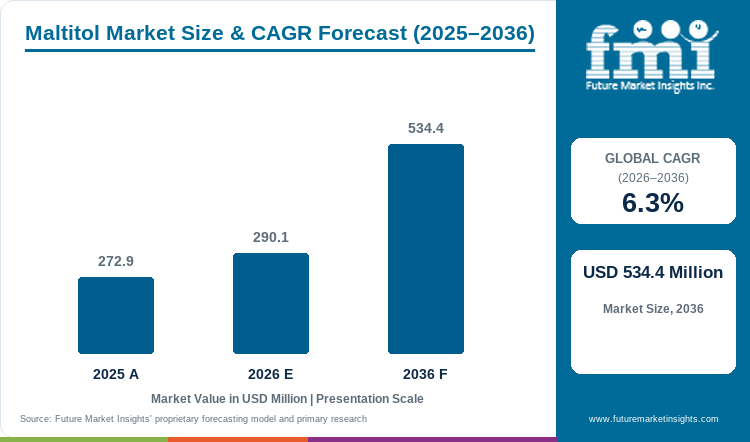
USD 290.1 million in 2026 and USD 534.4 million by 2036 at a 6.3% CAGR.
Sales of maltitol are estimated to rise at 6.3% CAGR through 2036, increasing valuation from USD 272.9 million in 2025 to USD 290.1 million in 2026, and reaching USD 534.4 million by 2036. FDA guidance identifies maltitol among sugar alcohols used in sugar-free confectionery and chewing gum. Manufacturers are using the ingredient when sugar removal also requires bulk, moisture control and stable texture during normal processing.
The expansion prospects in Japan and South Korea are illustrating how national rules can change the route from reformulation need to commercial approval. Japan requires food labels in Japanese and maintains specific nutrition-claim rules for processed foods under its national labeling system. South Korean manufacturers operate under a national sugar-reduction program that promotes lower-sugar processed foods. These conditions make technical documentation and application support part of supplier qualification before a new maltitol formulation enters regular production.
Key Takeaways of Maltitol Market
- Sugar-reduction reformulation is increasing the demand when food manufacturers need bulk sweetness together with solids and moisture control.
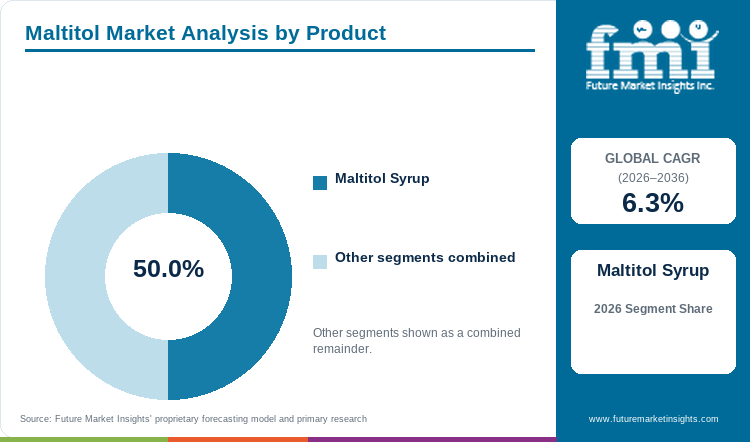
- Based on product, maltitol syrup is projected to account for 50.0% in 2026, supported by established liquid-dosing systems in industrial processing.
- By form, liquid maltitol is estimated to hold 55.0% in 2026, enabled by pumpable syrup that supports continuous mixing and controlled solids addition.
- In 2026, food and beverages are expected to lead application demand with 70.0% share, driven by recurring confectionery and bakery requirements for sugar-like bulk.
- Polyol warning requirements and application-specific additive rules can limit use rates even when a formulation needs maltitol functionality.
- Some of the key players in this market include Cargill, Incorporated, Roquette Frères, Ingredion Incorporated, Tereos Group, Mitsubishi Corporation Life Sciences Limited, Archer Daniels Midland Company, Futaste Pharmaceutical Co., Ltd., Zhejiang Huakang Pharmaceutical Co., Ltd., Shandong Bailong Chuangyuan Bio-tech Co., Ltd., and Icon Foods.
Analyst Perspective
“Maltitol wins repeat business when a supplier controls the physical work that sugar performed before reformulation. Food manufacturers then compare documentation and application support because a technically acceptable sweetener must also survive labeling review and commercial processing.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Maltitol Market segmented?
The maltitol market is segmented by Product, Form, Application, End Use, Functionality, Source, and Region.
The maltitol market is segmented by product, form, application, end use, functionality, source and region. Product and form distinguish syrup, powder, blends, liquids and solids used in commercial processing. Application covers food and beverages, pharmaceuticals and oral care while end use separates food, pharmaceutical and personal-care manufacturers. Functionality covers sweetening, bulking and humectancy while source separates corn-based, wheat-based and other carbohydrate routes.
What supports maltitol syrup within the product category?
Maltitol syrup enters sugar alcohol systems when processors need a pumpable bulk sweetener that can carry solids into continuous production. Tereos documented maltitol inside its starch and sweeteners business in January 2026 and identified food production as its primary use.
- By product, maltitol syrup is forecast to represent 50.0% in 2026, enabled by liquid handling that reduces dry-dissolution work during industrial batching.
- Commercial approval still depends on batch consistency because viscosity and solids content affect pumping behavior during repeated manufacturing runs.
How do processors evaluate liquid maltitol within the form category?
Liquid formats suit polyol sweeteners used in mixing systems that meter ingredients by flow instead of dry-weight addition. Roquette documented several solid SweetPearl maltitol grades in its February 2026 product FAQ, confirming the alternative format available for projects that require dry handling.
- By form, liquid maltitol is estimated to hold 55.0% in 2026, supported by pumpable syrup that integrates with continuous mixing and transfer equipment.
- The choice between liquid and solid formats depends on moisture balance and handling equipment instead of sweetness intensity alone.
Why do food and beverages account for most application demand?
Maltitol helps confectionery and bakery developers replace sugar without losing both sweetness and product structure. Roquette published a no-added-sugars ice cream formulation in February 2026 that paired maltitol with fiber and maltodextrin for texture. Similar work in sugar-free candy depends on controlling solids and moisture during commercial processing.
- In 2026, food and beverages are expected to lead the application category with 70.0% share, driven by repeat-volume formulations that need sugar-like bulk.
- Dairy and confectionery trials compare texture alongside sweetness because a successful recipe must remain stable during storage and normal production.
What makes food manufacturers the main end-use group?
Food manufacturers repeatedly qualify maltitol for recipes that remove added sugar without losing bulk or water control. FDA requires added sugars to remain visible on the Nutrition Facts label for packaged foods. Pharmaceutical users also buy sugar-based excipients under tighter component specifications but represent a smaller modeled end-use base.
- The end-use category is forecast to be led by food manufacturers at 65.0% share in 2026, supported by repeat production volumes across commercial food lines.
- Manufacturing teams approve a maltitol grade once the formula meets texture and labeling requirements at the intended serving size.
What are the drivers, restraints and opportunities in the Maltitol Market?
Sugar-reduction policy sustains reformulation work, polyol labeling limits some use rates, and application engineering expands higher-value maltitol uses.
- Driver: National sugar-reduction measures keep manufacturers reformulating products that still require bulk sweetness and stable physical performance.
- Restraint: Polyol warnings and category-specific additive rules can restrict inclusion levels before a formulation reaches commercial approval.
- Opportunity: Pharmaceutical and specialty food formulations reward suppliers that combine maltitol with application testing and documented quality controls.
Sugar-reduction policy keeps reformulation active even when consumer preference is not the only purchase trigger. WHO published a 2025 global assessment of sugar-sweetened beverage taxes that documented wider fiscal action on added sugar. Food developers compare low-calorie sweeteners against each recipe's required bulk and processing behavior before approving a replacement system. Maltitol becomes relevant when removing sucrose would otherwise lower solids or change texture during commercial production.
Polyol labeling creates a use-rate constraint that must be resolved before recipe approval. EU food information rules require a laxative-effects statement on foods containing more than 10% added polyols. The requirement can alter serving-size decisions and force a lower maltitol inclusion level in specific formulations. Suppliers therefore need application data that links functional performance with the intended label and use rate.
Application work expands maltitol beyond routine confectionery whenever its physical properties solve a defined processing problem. The formulation uses maltitol as a filler-binder in addition to its sweetening role. Similar expertise applies to humectant systems that must control moisture without introducing reactive sugars. Strong application evidence can shorten the move from laboratory approval into regular purchasing.
Which country CAGRs are profiled in the Maltitol Market?
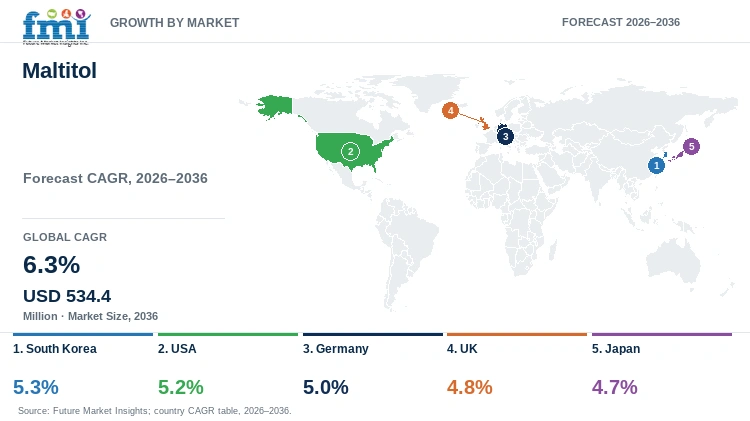
| Country | CAGR |
|---|---|
| South Korea | 5.3% |
| USA | 5.2% |
| Germany | 5.0% |
| UK | 4.8% |
| Japan | 4.7% |
How do country-level CAGRs compare in the Maltitol Market?
South Korea and the USA form a narrow upper band while Germany follows with a modestly slower forecast. The UK and Japan form the lower pair in the displayed range. The 0.6 percentage-point spread measures forecast speed instead of current revenue size because each country converts sugar-reduction policy and application demand through different approval systems.
- South Korea combines established processed-food manufacturing with national nutrition policy that keeps reduced-sugar formulation visible to product developers.
- US demand includes food and pharmaceutical applications that place component quality records alongside sweetness performance during supplier review.
- Germany gives food manufacturers a formal reduction policy that keeps recipe reformulation active inside established production portfolios.
- UK beverage policy changes the economics of added sugar while category suitability determines whether maltitol belongs in a specific recipe.
- Japan uses detailed nutrition-claim rules that make formulation evidence important before a reduced-sugar claim appears on the finished package.
Comparable CAGRs can produce different commercial conditions because local rules change which applications qualify and which documents purchasing teams require. The full report extends country-level CAGR analysis across all approved regions. Coverage includes North America and Latin America. Western Europe and Eastern Europe are included with East Asia. South Asia and Pacific plus the Middle East and Africa complete the regional structure.
Country-wise Analysis
- South Korean food manufacturers work under a national program that promotes lower sugar intake in processed foods. By 2036, South Korea is projected to grow at 5.3% CAGR, supported by continued reformulation under MFDS nutrition policy. The ministry describes sugar reduction as part of its healthy-diet work and gives manufacturers a national policy reference for product changes. Producers still need each recipe to meet category rules before claims move onto the package. Companies selling sweetener systems therefore need local documentation that connects maltitol use with the exact finished-food category.
- US maltitol demand spans food manufacturing and regulated pharmaceutical uses that place different burdens on supplier documentation. The USA is estimated to post 5.2% CAGR over the forecast period, reinforced by continued sugar-reduction work and documented excipient controls. FDA guidance identifies maltitol solution among high-risk drug components that require testing for diethylene glycol and ethylene glycol. Pharmaceutical buyers therefore require documented contaminant controls in addition to normal food-grade performance. Suppliers serving low-intensity sweeteners in both sectors must separate application support from pharmaceutical compliance evidence.
- German manufacturers continue reformulating processed foods under a national policy that sets explicit reduction goals for sugar. Maltitol demand in Germany is forecast to rise at 5.0% CAGR over the forecast period, shaped by ongoing recipe work in processed foods. The federal strategy targets lower sugar in children’s cereals and selected drinks while monitoring changes in product composition. Manufacturers still have to balance sugar reduction against texture and process behavior inside existing lines. Suppliers of food and beverage additives gain approval when technical support resolves that production trade-off without weakening label compliance.
- UK beverage manufacturers face a scheduled tax threshold change that raises the value of lowering added sugar in affected drinks. The UK maltitol sector is projected to record 4.8% CAGR during the assessment period, influenced by reformulation economics and category suitability. HM Revenue & Customs confirmed the levy threshold will fall from 5 grams to 4.5 grams of added sugar per 100 milliliters from January 2028. Maltitol still requires application-level review because polyol inclusion can affect tolerance and labeling. Suppliers must identify formulations that need maltitol for a specific technical function instead of treating every levy-exposed drink as eligible demand.
- Japanese product developers work inside detailed national rules for nutrient content claims and processed-food labeling. In Japan, maltitol demand is predicted to advance at 4.7% CAGR through 2036, linked to mature reformulation work and demanding claim review. Consumer Affairs Agency guidance requires defined conditions for free and reduced nutrient claims including specific tests for sugar reduction. Chocolate and confectionery teams using sugar-free white chocolate must therefore align recipe performance with the claim placed on the package. Suppliers that provide formulation records and grade consistency can reduce repeated review during commercial qualification.
Who are the notable companies in the Maltitol Market?
Cargill, Incorporated, Roquette Frères, Ingredion Incorporated, Tereos Group, Mitsubishi Corporation Life Sciences Limited, Archer Daniels Midland Company, Futaste Pharmaceutical Co., Ltd., Zhejiang Huakang Pharmaceutical Co., Ltd., Shandong Bailong Chuangyuan Bio-tech Co., Ltd., and Icon Foods.
Competition includes integrated starch processors and polyol specialists alongside application-focused ingredient companies that support different maltitol qualification routes. Entry depends on repeatable grade quality because food and pharmaceutical customers test processing performance before regular orders. Direct suppliers also need enough documentation to support regional labeling, purity and handling requirements.
- Cargill, Roquette Frères, Ingredion Incorporated, Tereos Group and Archer Daniels Midland Company operate broad polyol or starch-derived sweetener platforms.
- Mitsubishi Corporation Life Sciences Limited, Futaste Pharmaceutical Co., Ltd. and Zhejiang Huakang Pharmaceutical Co., Ltd. document direct maltitol products for food or pharmaceutical use.
- Shandong Bailong Chuangyuan Bio-tech Co., Ltd. and Icon Foods compete with direct maltitol formats plus application or quality documentation for commercial buyers.
Competitive Benchmarking: Maltitol Market
| Company | Maltitol Format Breadth | Application Support | Qualification Evidence | Geographic Reach |
|---|---|---|---|---|
| Cargill, Incorporated | High | High | High | Global |
| Roquette Frères | High | High | High | Global |
| Ingredion Incorporated | High | High | High | North America and multi-region channels |
| Tereos Group | Medium | High | High | Europe and international channels |
| Mitsubishi Corporation Life Sciences Limited | High | High | High | Japan and international channels |
| Archer Daniels Midland Company | Medium | High | High | North America and international channels |
| Futaste Pharmaceutical Co., Ltd. | High | Medium | Medium | China and export markets |
| Zhejiang Huakang Pharmaceutical Co., Ltd. | Medium | Medium | Medium | More than 80 countries |
| Shandong Bailong Chuangyuan Bio-tech Co., Ltd. | High | Medium | High | China and more than 60 export markets |
| Icon Foods | High | High | Medium | North America |
Scoring basis: High format breadth requires at least two documented maltitol formats while Medium requires one direct format plus a related grade route. High application support requires evidence in two or more relevant use settings while Medium requires one documented setting. High qualification evidence requires formal quality systems or regulated-use documentation while Medium requires narrower public evidence. Geographic Reach describes current public coverage without assigning a score.
Key Developments in the Maltitol Market
- In April 2026, Roquette Frères published formulation guidance for sugar-free chewing gum using SweetPearl maltitol crystals and LYCASIN maltitol syrup.
- In May 2026, Shandong Bailong Chuangyuan Bio-tech Co., Ltd. presented healthy-baking ingredient solutions at Bakery China and identified liquid and crystalline maltitol within its core portfolio.
- In March 2026, Icon Foods introduced MLT1075 NF Grade Maltitol Syrup for reduced-sugar formulations that require sugar-like bulk and processing stability.
Key Players in the Maltitol Market
Integrated polyol and starch-derived sweetener companies
- Cargill, Incorporated
- Roquette Frères
- Ingredion Incorporated
- Tereos Group
- Archer Daniels Midland Company
Asia-based direct maltitol companies
- Mitsubishi Corporation Life Sciences Limited
- Futaste Pharmaceutical Co., Ltd.
- Zhejiang Huakang Pharmaceutical Co., Ltd.
Application-focused maltitol companies
- Shandong Bailong Chuangyuan Bio-tech Co., Ltd.
- Icon Foods
Maltitol Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By product, form, application, end use, functionality, source and region. |
| Quantitative Units | USD million. |
| Market Definition | Commercial maltitol syrup, powder and blends sold for food, pharmaceutical, oral-care and related formulated applications within the stated segmentation universe. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | South Korea, USA, Germany, UK, Japan, and 20+ countries included in the full report. |
| Key Companies Profiled | Cargill, Incorporated, Roquette Frères, Ingredion Incorporated, Tereos Group, Mitsubishi Corporation Life Sciences Limited, Archer Daniels Midland Company, Futaste Pharmaceutical Co., Ltd., Zhejiang Huakang Pharmaceutical Co., Ltd., Shandong Bailong Chuangyuan Bio-tech Co., Ltd., Icon Foods. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Maltitol Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Maltitol Market by Segments
Maltitol Market segmented by Product:
- Maltitol Syrup
- Standard Syrup
- High Sweetness Syrup
- Low Viscosity Syrup
- High Purity Syrup
- Refined Grade
- Food Grade Syrup
- Maltitol Powder
- Crystalline Maltitol
- Fine Crystals
- Granular Form
- Spray Dried Powder
- Instant Soluble
- Blending Grade
- Maltitol Blends
- Maltitol with Other Polyols
- Sorbitol Blends
- Xylitol Blends
- Functional Sweetener Blends
- Low Calorie Mixes
- Sugar Reduction Formulas
Maltitol Market segmented by Form:
- Liquid
- Syrup Form
- Viscous Liquid
- Solid
- Powder
- Crystalline Form
Maltitol Market segmented by Application:
- Food and Beverages
- Confectionery
- Sugar Free Chocolates
- Candies and Chewing Gum
- Bakery Products
- Biscuits
- Cakes
- Dairy Products
- Ice Cream
- Flavored Yogurt
- Beverages
- Low Calorie Drinks
- Functional Beverages
- Pharmaceuticals
- Sugar Free Syrups
- Medicinal Formulations
- Oral Care
- Toothpaste
- Mouthwash
Maltitol Market segmented by End Use:
- Food Manufacturers
- Processed Food Companies
- Sugar Free Products
- Diet Foods
- Pharmaceutical Companies
- Drug Manufacturers
- Syrups and Tablets
- Medicinal Formulations
- Personal Care Manufacturers
- Oral Care Brands
- Toothpaste
- Dental Products
Maltitol Market segmented by Functionality:
- Sweetening Agent
- Sugar Substitute
- Low Calorie Sweetener
- Bulking Agent
- Texture Improvement
- Volume Enhancement
- Humectant
- Moisture Retention
- Shelf Life Improvement
Maltitol Market segmented by Source:
- Corn Based
- Corn Starch Hydrolysis
- Glucose Conversion
- Wheat Based
- Wheat Starch
- Alternative Grain Sources
- Other Sources
- Potato Starch
- Mixed Carbohydrate Sources
Maltitol Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Chile
- Rest of Latin America
- Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- Middle East and Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
Research Sources and Bibliography
- U.S. Food and Drug Administration. (n.d.). Aspartame and Other Sweeteners in Food.
- Consumer Affairs Agency, Government of Japan. (2026). Food Labelling.
- Tereos SCA. (2026, January 12). Information Document dated January 12, 2026.
- Roquette Frères. (2026, February 3). Troubleshooting and FAQs for SweetPearl® Maltitol.
- Roquette Frères. (2026, February 16). Permissible indulgence with a no added sugars creamy ice cream.
- U.S. Food and Drug Administration. (2026). Added Sugars on the Nutrition Facts Label.
- World Health Organization. (2026, January 13). Global report on the use of sugar-sweetened beverage taxes, 2025.
- European Union. (2026). Consolidated food information rules for foods containing added polyols.
- Roquette Frères. (2026, June 6). The Most Efficient Directly Compressible Excipient for Effervescent Tablets Formulation.
- Ministry of Food and Drug Safety, Republic of Korea. (n.d.). Promoting Healthy Diets and Safe Food Consumption.
- U.S. Food and Drug Administration. (2023, May). Testing of Glycerin, Propylene Glycol, Maltitol Solution, Hydrogenated Starch Hydrolysate, Sorbitol Solution, and Other High-Risk Drug Components for Diethylene Glycol and Ethylene Glycol.
- Federal Ministry of Food and Agriculture, Germany. (2025, March 28). The National Reduction and Innovation Strategy for Sugar, Fats and Salt in Processed Foods.
- HM Revenue & Customs. (2026, July 13). Changes to the Soft Drinks Industry Levy.
- Consumer Affairs Agency, Government of Japan. (2026). Nutrition labelling information.
- Cargill, Incorporated. (2026). Polyol Sweeteners: Sweet solutions for reduced sugar.
- Mitsubishi Corporation Life Sciences Limited. (n.d.). Food Safety & Trustworthiness.
- Archer Daniels Midland Company. (2026). Polyols.
- Futaste Group. (n.d.). Maltitol.
- Zhejiang Huakang Pharmaceutical Co., Ltd.. (n.d.). Home - Zhejiang Huakang Pharmaceutical Co., Ltd..
- Shandong Bailong Chuangyuan Bio-tech Co., Ltd.. (2026, April 27). Bailong Chuangyuan Advances with Quality-Driven Growth, Sets Sail for High-Quality Development.
- Roquette Frères. (2026, April 15). Crunch, a New Way to Extra Crunchiness.
- Shandong Bailong Chuangyuan Bio-tech Co., Ltd.. (2026, May 14). Invitation to the Baking Industry Event | Bailong Chuangyuan to Exhibit at Bakery China 2026!.
- Icon Foods. (2026, March 31). MLT1075™ NF Grade Maltitol Syrup.
- Icon Foods. (2026, August 17). Icon Foods MLT1075™ NF Grade Maltitol Syrup - The Structural Sweetener for People Who Actually Ship Product.
- Mitsubishi Corporation Life Sciences Limited. (n.d.). Sweeteners Business.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations
This Report Answers
- How large is the maltitol market in 2026 and what value is forecast for 2036?
- Which regulatory and formulation conditions are supporting maltitol demand?
- Why does maltitol syrup account for 50.0% of product demand in 2026?
- Why does liquid form represent 55.0% of form demand in 2026?
- Why do food and beverages account for 70.0% of application demand in 2026?
- How do country growth rates differ among the five profiled maltitol markets?
- Which companies have current direct maltitol evidence and application support?
- What limits wider maltitol use in food and pharmaceutical formulations?
- How does supplier documentation affect qualification and repeat purchasing?
Frequently Asked Questions
How big is the Maltitol Market in 2026?
The maltitol market is expected to be valued at USD 290.1 million in 2026 and reach USD 534.4 million by 2036. Sugar-reduction reformulation supports demand because removing sucrose leaves bulk and texture requirements unresolved.
What is the CAGR of the Maltitol Market from 2026 to 2036?
The maltitol market is projected to grow at a CAGR of 6.3% between 2026 and 2036. Expansion depends on food reformulation and documented ingredient quality across regulated commercial applications.
Which product dimension leads the Maltitol Market?
The maltitol syrup segment is expected to hold 50.0% of the maltitol market product category in 2026. Pumpable liquid handling supports repeat industrial dosing in food formulations that need bulk sweetness.
Which form dimension leads the Maltitol Market?
The liquid segment is projected to account for 55.0% of the maltitol market form category in 2026. Continuous mixing systems can meter syrup without the dissolution work required for solid grades.
How much value will the Maltitol Market add between 2026 and 2036?
The maltitol market is expected to add USD 244.3 million in value between 2026 and 2036. Growth comes from sugar-reduction work that requires sweetening together with physical functionality and qualified supply.
Which countries are projected to record notable growth in the Maltitol Market?
South Korea is projected to grow at 5.3% CAGR followed by the USA at 5.2% and Germany at 5.0% through 2036. National labeling and reformulation conditions shape each local purchase path.
Which companies are active in the Maltitol Market?
Key companies operating in the maltitol market include Cargill and Roquette Frères. Ingredion and Tereos are also active. Mitsubishi Corporation Life Sciences and ADM maintain integrated maltitol positions. Futaste and Huakang add direct product supply. Bailong Chuangyuan and Icon Foods provide additional product or formulation coverage. Their positions differ by format breadth and application support.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product, 2026 to 2036
- Maltitol Syrup
- Standard Syrup
- High Sweetness Syrup
- Low Viscosity Syrup
- High Purity Syrup
- Refined Grade
- Food Grade Syrup
- Maltitol Powder
- Crystalline Maltitol
- Fine Crystals
- Granular Form
- Spray Dried Powder
- Instant Soluble
- Maltitol Blends
- Maltitol with Other Polyols
- Sorbitol Blends
- Xylitol Blends
- Functional Sweetener Blends
- Low Calorie Mixes
- Maltitol Syrup
- Y-o-Y Growth Trend Analysis By Product, 2021 to 2025
- Absolute $ Opportunity Analysis By Product, 2026 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Form, 2026 to 2036
- Liquid
- Syrup Form
- Viscous Liquid
- Solid
- Powder
- Crystalline Form
- Liquid
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Application, 2026 to 2036
- Food and Beverages
- Confectionery
- Sugar Free Chocolates
- Candies and Chewing Gum
- Bakery Products
- Biscuits
- Cakes
- Dairy Products
- Ice Cream
- Flavored Yogurt
- Beverages
- Pharmaceuticals
- Sugar Free Syrups
- Medicinal Formulations
- Oral Care
- Toothpaste
- Mouthwash
- Food and Beverages
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End Use, 2026 to 2036
- Food Manufacturers
- Processed Food Companies
- Sugar Free Products
- Diet Foods
- Pharmaceutical Companies
- Drug Manufacturers
- Syrups and Tablets
- Medicinal Formulations
- Personal Care Manufacturers
- Oral Care Brands
- Toothpaste
- Dental Products
- Food Manufacturers
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Source, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Source, 2026 to 2036
- Corn Based
- Corn Starch Hydrolysis
- Glucose Conversion
- Wheat Based
- Wheat Starch
- Alternative Grain Sources
- Other Sources
- Potato Starch
- Mixed Carbohydrate Sources
- Corn Based
- Y-o-Y Growth Trend Analysis By Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Source, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Product
- By Form
- By Application
- By End Use
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Form
- By Application
- By End Use
- By Source
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Product
- By Form
- By Application
- By End Use
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Form
- By Application
- By End Use
- By Source
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Product
- By Form
- By Application
- By End Use
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Form
- By Application
- By End Use
- By Source
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Product
- By Form
- By Application
- By End Use
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Form
- By Application
- By End Use
- By Source
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product
- By Form
- By Application
- By End Use
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Form
- By Application
- By End Use
- By Source
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Product
- By Form
- By Application
- By End Use
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Form
- By Application
- By End Use
- By Source
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Product
- By Form
- By Application
- By End Use
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Form
- By Application
- By End Use
- By Source
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Form
- By Application
- By End Use
- By Source
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Form
- By Application
- By End Use
- By Source
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Form
- By Application
- By End Use
- By Source
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Form
- By Application
- By End Use
- By Source
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Form
- By Application
- By End Use
- By Source
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Form
- By Application
- By End Use
- By Source
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Form
- By Application
- By End Use
- By Source
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Form
- By Application
- By End Use
- By Source
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Form
- By Application
- By End Use
- By Source
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Form
- By Application
- By End Use
- By Source
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Form
- By Application
- By End Use
- By Source
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Form
- By Application
- By End Use
- By Source
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Form
- By Application
- By End Use
- By Source
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Form
- By Application
- By End Use
- By Source
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Form
- By Application
- By End Use
- By Source
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Form
- By Application
- By End Use
- By Source
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Form
- By Application
- By End Use
- By Source
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Form
- By Application
- By End Use
- By Source
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Form
- By Application
- By End Use
- By Source
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Form
- By Application
- By End Use
- By Source
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Form
- By Application
- By End Use
- By Source
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Form
- By Application
- By End Use
- By Source
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product
- By Form
- By Application
- By End Use
- By Source
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Cargill
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Incorporated
- Roquette Frères
- Ingredion Incorporated
- Tereos Group
- Mitsubishi Corporation Life Sciences Limited
- Archer Daniels Midland Company
- Futaste Pharmaceutical Co.
- Ltd.
- Zhejiang Huakang Pharmaceutical Co.
- Shandong Bailong Chuangyuan Bio-tech Co.
- Icon Foods
- Cargill Incorporated
- Futaste Pharmaceutical Co. Ltd.
- Zhejiang Huakang Pharmaceutical Co. Ltd.
- Shandong Bailong Chuangyuan Bio-tech Co. Ltd.
- Cargill
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


