
- Market Size (2026)
- USD 10.7 Bn
- Forecast (2036)
- USD 26.0 Bn
- CAGR (2026 to 2036)
- 9.3%
How big is Vitamin Gummies Market in 2026?
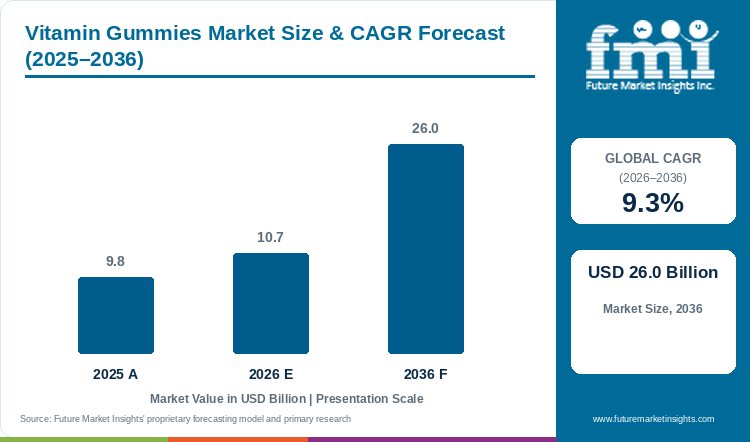
Sales in the vitamin gummies market are projected to grow at 9.3% CAGR, with the market size rising from USD 9.8 billion in 2025 to USD 10.7 billion in 2026 and reaching USD 26.0 billion by 2036.
Widespread consumer fatigue with swallowing large compressed tablets has led supplement makers to formulate chewable pectin and gelatin matrices that simplify daily micronutrient dosing for pediatric and adult users. On the market size chart, the 2025 baseline of USD 9.8 billion climbs to USD 10.7 billion for 2026 and hits USD 26.0 billion in 2036 (a 9.3% annual rate), adding USD 15.3 billion over the decade. Multivitamin formulations account for 42.0% of nutrient demand in 2026 because a single two-gummy serving consolidates essential fat-soluble and water-soluble vitamins. Consumer survey tracking from the Council for Responsible Nutrition shows that roughly three-quarters of U.S. adults take dietary supplements, with 55% qualifying as regular users and chewable formats recording consistent gains [1]. However, vitamin potency loss during hot slurry cooking still challenges contract packagers.
Key Market Trends & Insights
- By nutrient: Multivitamin formulations secure 42.0% of nutrient demand in 2026 by consolidating daily essential vitamins into a single two-gummy serving.
- By nature: Conventional formulations make up 69.0% of 2026 production owing to high-speed gelatin starch mogul lines and lower hydrocolloid costs.
- By distribution channel: Pharmacies & mass retail command 48.0% of 2026 channel sales via pharmacist guidance and seasonal immunity endcaps.
Regional Highlights
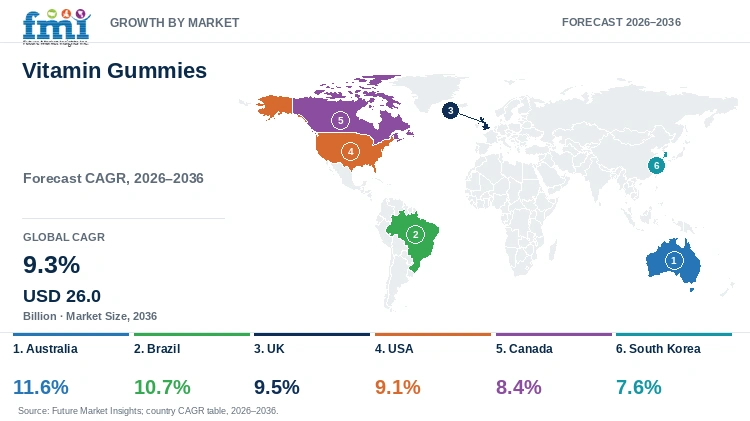
- Australia tops the profiled country growth table at an 11.6% annual clip between 2026 and 2036 thanks to TGA listed-medicine trust.
- Ten-year growth reaches 10.7% across Brazil alongside 9.5% in the UK and 9.1% in the USA, while Canada (8.4%) and South Korea (7.6%) expand more gradually.
Market Size & Forecast
Table 1: Market Size and Forecast for the Vitamin Gummies Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 9.8 billion |
| Estimated Market Size in 2026 | USD 10.7 billion |
| Projected Market Size by 2036 | USD 26.0 billion |
| CAGR, 2026 to 2036 | 9.3% |
| Added Revenue, 2026 to 2036 | USD 15.3 billion |
Australian listed-medicine auditors and North American pharmacy buyers inspect end-of-shelf-life vitamin assays rather than initial kettle inputs when qualifying chewable supplement lines. Compliance guidance updated by the U.S. Food and Drug Administration in December 2025 under the Dietary Supplement Health and Education Act reinforces strict cGMP documentation for nutrient overages and Supplement Facts panel declarations [2]. Because unencapsulated ascorbic acid and cyanocobalamin degrade when cooked in acidic fruit slurries at 85 degrees Celsius, co-packers coat active vitamins in protective lipid shells before depositing nutraceutical gummies. Starchless silicone and metal molds then cool each piece rapidly, preventing cross-batch allergen carryover and keeping water activity below 0.65.
Supplement User-Pool and Daily Regimen Sizing
Table 2: Supplement User-Pool and Regimen Sizing for the Vitamin Gummies Market (USD billion and millions), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 9.8 | 10.7 | 26.0 |
| Active daily gummy consumers worldwide (million) | 195.0 to 215.0 | 210.0 to 232.0 | 430.0 to 475.0 |
| Annual chewable dose volume (billion pieces) | 142.0 to 156.0 | 153.0 to 169.0 | 314.0 to 346.0 |
| Average annual spend per active user (USD) | 45.58 to 50.25 | 46.12 to 50.95 | 54.74 to 60.46 |
Volume ranges above translate active pediatric and adult supplement users consuming two chewable pieces per day into annual bottle demand.
Per Capita & Pharmacy Channel Sizing
Masking the metallic taste of chelated zinc and B-vitamins inside a 2.5-gram fruit gel requires precise citric and malic acid buffering alongside natural berry or citrus oils. When a chewable multivitamin tastes like confectionery without leaving a chalky film on the tongue, household refill rates climb sharply compared with hard caplets. Drugstore category managers capitalize on that repeat behavior by shelving family multivitamin jars beside dietary fiber gummies and sleep chews.
Table 3: Per Capita and Household Spending Indicators for the Vitamin Gummies Market (USD and billions), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD) | 1.19 | 1.29 | 2.91 |
| Spend per 1,000 people (USD) | 1,191 | 1,289 | 2,905 |
| Monthly outlay per active gummy user (USD) | 3.80 to 4.19 | 3.84 to 4.25 | 4.56 to 5.04 |
Table 4: Retail Pharmacy & Channel Revenue Indicators for the Vitamin Gummies Market (USD billion and percentages), mixed reporting years from 2025 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 10.7 billion | Report value |
| Pharmacies & mass retail revenue, 2026 | USD 5.1 billion | 48.0% share |
| Online direct-to-consumer revenue, 2026 | USD 3.4 billion | 32.0% share |
| Multivitamin formulations revenue, 2026 | USD 4.5 billion | 42.0% share |
Analyst Perspective
"Starchless depositing and microencapsulated vitamin premixes allow gummy manufacturers to deliver verified label potency in sugar-free pectin formats. High slurry cooking temperatures and summer transit humidity still require strict water-activity control to prevent bottle clumping."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the vitamin gummies market segmented?
The vitamin gummies market is segmented by nutrient, nature, distribution channel, and region. In 2026, multivitamin formulations are projected at 42.0%, conventional formulations at 69.0%, and pharmacies & mass retail at 48.0%.
By nutrient: Multivitamin formulations, vitamin C & immunity blends, and vitamin D & bone support.
By nature: Conventional formulations, and organic & clean-label pectin.
By distribution channel: Pharmacies & mass retail, online direct-to-consumer, and specialty health stores.
Why do Multivitamin Formulations lead the nutrient category?
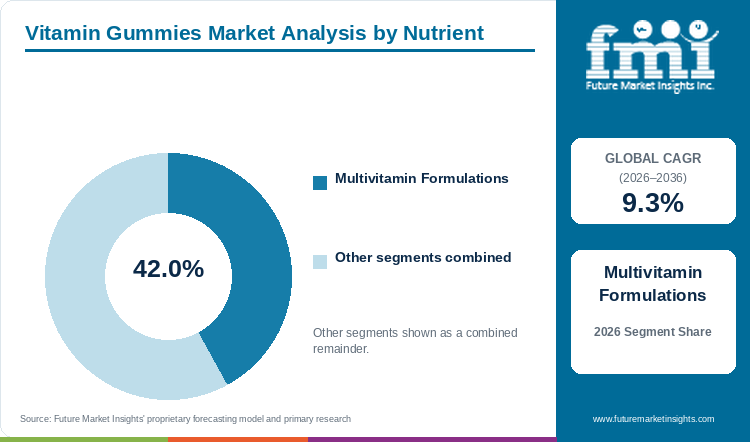
Multivitamin formulations are expected to account for 42.0% of nutrient category revenue in 2026, underpinned by broad household daily supplementation.
Table 5: Nutrient Share for the Vitamin Gummies Market (percentage share), 2026
| Nutrient | Share (2026) |
|---|---|
| Multivitamin Formulations | 42.0% |
| Other Segments Combined | 58.0%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Nutrient Leadership and Market Growth for the Vitamin Gummies Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 9.3% |
| Leading Segment | Multivitamin Formulations |
Combining 10 to 15 essential vitamins and trace minerals inside a single daily chew spares families the expense and clutter of buying separate single-nutrient bottles. That convenience places multivitamin gummies at 42.0% of nutrient category revenue in 2026, ahead of vitamin C and immunity blends at 31.0% and vitamin D and bone support at 27.0%. To prevent oil-soluble vitamins D3 and E from separating out of aqueous sugar-pectin slurries during cooking, formulators homogenize cold-water-dispersible beadlets that keep piece potency uniform across 90-count and 150-count family bottles.
- Multivitamin formulations are projected to secure 42.0% of nutrient revenue in 2026, underpinned by age-tailored pediatric and adult daily blends.
- Pharmavite LLC opened a USD 250 million, 225,000-square-foot production facility and Gummies Innovation Center of Excellence in New Albany, Ohio in May 2025 to expand Nature Made vitamin gummy output [3].
What makes Conventional Formulations central to the nature category?
Conventional formulations are anticipated to contribute 69.0% of nature category demand in 2026, owing to high-speed gelatin mogul line efficiency.
High-bloom porcine and bovine gelatin combined with standard corn glucose syrups remains the workhorse hydrocolloid system for high-volume contract packagers because it tolerates rapid starch-tray mogul depositing and delivers classic elastic chewiness at low ingredient cost. Conventional formulations capture 69.0% of nature demand in 2026, whereas organic and plant-pectin varieties hold 31.0% share. Even so, rising demand from vegetarian and warm-climate shoppers is prompting co-packers to install dual-kettle lines capable of cooking clean-label pectin slurries that resist melting up to 50 degrees Celsius.
- Conventional formulations are estimated to represent 69.0% of nature category demand in 2026, owing to established gelatin supply chains and resilient chew texture.
- United States Pharmacopeia Dietary Supplement Verification Program benchmarks updated in 2026 note that more than 75% of Americans take dietary supplements while emphasizing independent potency verification for chewable matrices [4].
What supports Pharmacies & Mass Retail leadership within distribution channel?
Pharmacies and mass retail are set to command 48.0% of distribution channel sales in 2026, reinforced by pharmacist guidance.
Brick-and-mortar drugstore chains and warehouse clubs anchor 48.0% of distribution channel sales in 2026, according to FMI, because shoppers want immediate access to USP-verified bottles and face-to-face pharmacist recommendations during cold-and-flu season. Online direct-to-consumer platforms account for 32.0% share through personalized subscription pouches, and specialty health stores represent 20.0% share. Mass retailers also allocate prominent eye-level bay space to private-label vitamin and mineral supplements in 120-count value jars that drive repeat foot traffic.
- Pharmacies & mass retail are projected to command 48.0% of distribution channel sales in 2026, reinforced by nationwide store footprints and loyalty promotions.
- Haleon plc reported in its February 2026 full-year results release that Centrum Daily Kits and Centrum Recharge expanded pharmacy market share across Asia-Pacific and global retail channels [5].
What are the drivers, restraints, and opportunities in the vitamin gummies market?
Widespread consumer tablet fatigue accelerates chewable supplement switching, whereas thermal vitamin degradation during slurry cooking restrains potency stability, and sugar-free citrus pectin systems unlock metabolic wellness segments.
- Driver: Consumer aversion to swallowing large compressed tablets and chalky capsules shifts daily household nutrition toward palatable chewable gummies.
- Restraint: Elevated cooking temperatures and residual moisture inside gummy gels accelerate degradation of sensitive vitamins C and B12 over shelf life.
- Opportunity: Buffered citrus peel pectin and non-glycemic allulose sweeteners enable heat-resilient sugar-free gummies tailored for diabetic and vegan buyers.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Large 1,000-milligram compressed tablets and two-piece hard capsules frequently cause gagging or esophageal discomfort, leading casual supplement buyers to abandon daily regimens before finishing a bottle. A systematic literature review of 13 clinical studies published in Nutrients in January 2025 demonstrated that buffered calcium ascorbate with L-threonate metabolites and liposomal vitamin C forms reduce epigastric adverse events and raise leukocyte vitamin C concentrations compared with standard ascorbic acid [6]. Because berry and citrus chews turn buffered micronutrient dosing into a pleasant habit, parents and working adults stack morning multivitamins with targeted immune health supplements throughout the year.
Risk Assessment of the Vitamin Gummies Market: Operational and Formulation Friction
National Institutes of Health Office of Dietary Supplements health-professional fact sheets note that multivitamin/mineral (MVM) formulations taken by roughly one-third of U.S. adults and one-quarter of children lack a single standardized regulatory composition and require careful protection against excess overages approaching Tolerable Upper Intake Levels [7]. Depositing gummy slurries at 80 to 95 degrees Celsius exposes heat-labile vitamins C and B12 to rapid thermal breakdown, while higher water activity inside soft gels accelerates oxidation compared with dry tablets. However, issues such as dosing 20% to 30% vitamin overages to pass 24-month stability audits raise active ingredient costs and can trigger oily surface weeping inside clear PET jars of gummy supplements.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Removing the 2 to 4 grams of refined cane sugar and glucose syrup found in first-generation vitamin gummies has become the top formulation priority for brands targeting metabolic-health and dental-conscious adults. By combining slow-set citrus pectin with rare sugars such as allulose or soluble chicory root fiber, formulators achieve a clean bite without blood-glucose spikes or sugar-alcohol laxative side effects. Pharmaceutical delivery research published in Pharmaceutics in September 2025 confirmed that encapsulating lipophilic vitamin D3 in phosphatidylcholine and TPGS nanoliposomes achieved 95.76% to 97.54% encapsulation efficiency and preserved chemical stability across gastrointestinal environments [8]. Pairing nanoliposomal fat-soluble vitamins with pectin gels allows gummies to withstand 50-degree-Celsius parcel vans without potency loss.
Vitamin Gummies Market by Country (2026 to 2036)
Among the six profiled markets, ten-year compound annual expansion ranges between a high of 11.6% for Australia (followed by Brazil at 10.7%) and 7.6% in South Korea. High-growth markets such as Australia and Brazil are propelled by expanding community pharmacy chains and heat-stable pectin reformulations, whereas mature supplement economies in North America and the United Kingdom depend on zero-sugar prebiotic fiber migration and automated starchless depositing capacity.
Table 7: Country CAGR and Primary Growth Levers for the Vitamin Gummies Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Australia | 11.6% | TGA listed-medicine quality trust and pharmacy export brand demand |
| Brazil | 10.7% | ANVISA chewable supplement approvals and expanding urban drugstore chains |
| UK | 9.5% | High vegan pectin adoption and supermarket private-label wellness lines |
| USA | 9.1% | Large-format club store placement and personalized DTC gummy subscriptions |
| Canada | 8.4% | Health Canada NPN licensing and winter vitamin D immunity demand |
| South Korea | 7.6% | Beauty-from-within nutricosmetic gummies and single-serve pouch formats |
Source: Future Market Insights analysis
Australia Vitamin Gummies Market Outlook (2026 to 2036)
Pharmaceutical-grade complementary-medicine rules govern Australian pharmacy shelves, where every commercial vitamin gummy must carry an AUST L number on the Australian Register of Therapeutic Goods. In November 2025, the Therapeutic Goods Administration introduced stronger safety and scheduling controls for complementary medicines containing vitamin B6 (pyridoxine and pyridoxal) to prevent peripheral neuropathy from overlapping daily supplements [9]. Chewable vitamin revenue in Australia is projected to advance at an 11.6% CAGR through 2036 as domestic brands reformulate multi-nutrient chews around compliant B-vitamin thresholds and export-ready cGMP dossiers. While AUST L quality trust fuels strong cross-border e-commerce sales into Southeast Asia, 40-degree-Celsius inland freight temperatures penalize unbuffered gelatin chews and push co-packers toward high-melting citrus pectin.
Key takeaway: In Australia, mandatory TGA listed-medicine oversight and heat-resistant pectin engineering propel pharmacy gummy sales at an 11.6% CAGR through 2036.
Brazil Vitamin Gummies Market Outlook (2026 to 2036)
Rapid expansion of self-service urban drugstore chains across São Paulo and Rio de Janeiro has turned chewable immunity and beauty vitamins into a high-velocity front-of-store category. Brazilian vitamin gummy demand is forecast to rise at a 10.7% CAGR between 2026 and 2036 as domestic contract packagers replace imported bovine gelatin with local fruit pectin extracted from São Paulo orange peel streams. Sanitary surveillance enforcement and authorized dietary supplement guidance from the Brazilian Health Regulatory Agency (ANVISA) in September 2026 supported an 18.0% annual rise in compliant adult and pediatric chewable vitamin registrations following recalls of unnotified brands [10]. Yet Mercosur import tariffs on microencapsulated fat-soluble vitamin beadlets create commercial friction, prompting formulators to source domestic acerola vitamin C.
Key takeaway: In Brazil, ANVISA registry enforcement and domestic citrus-pectin extraction anchor a 10.7% CAGR across urban pharmacy chains.
UK Vitamin Gummies Market Outlook (2026 to 2036)
British supermarket chains and high-street pharmacy retailers require nearly all new own-label vitamin gummies to use vegan-certified pectin and natural fruit anthocyanins so one SKU serves vegetarian and halal households. Updated Food Supplements Guidance issued by the UK Department of Health and Social Care in June 2026 reinforced statutory labeling rules and autumn-winter daily 10-microgram vitamin D advisories, helping chewable formats capture 22.4% of national vitamin unit volume [11]. However, public-health scrutiny over pediatric dental sugar intake and front-of-pack calorie disclosures restricts glucose-syrup recipes, forcing UK co-packers to sweeten chews with soluble chicory root inulin. British chewable supplement turnover is predicted to expand at a 9.5% annual pace through 2036 across high-street pharmacy and supermarket aisles.
Key takeaway: In the UK, supermarket vegan pectin mandates and chicory-inulin sugar reduction drive a 9.5% CAGR outlook through 2036.
USA Vitamin Gummies Market Outlook (2026 to 2036)
Warehouse-club twin-packs and personalized monthly subscription pouches make the United States the largest single-country market for chewable dietary supplements. National dietary-supplement tracking in the June 2026 Centers for Disease Control and Prevention Nutrition Report confirmed that 58.5% of U.S. adults use supplements regularly to bridge micronutrient gaps, anchoring more than USD 3.1 billion in domestic over-the-counter chewable vitamin sales [12]. The USA vitamin gummies market is predicted to witness 9.1% CAGR through 2036 as contract packagers replace corn-starch mogul trays with sanitary starchless silicone depositors. Nonetheless, crowded mass-retail shelves and strict USP potency audits compress baseline multivitamin margins, pushing U.S. brands toward methylated B12 and zero-sugar allulose formulations.
Key takeaway: In the USA, sanitary starchless depositing scale and warehouse-club family multi-packs power a 9.1% ten-year CAGR.
Canada Vitamin Gummies Market Outlook (2026 to 2036)
Mandatory pre-market licensing under Health Canada's Natural and Non-Prescription Health Products Directorate distinguishes Canadian supplement retail from post-market notification regimes, requiring every bottle to display an eight-digit Natural Product Number (NPN). Vitamin gummies adoption across Canada is anticipated to register 8.4% CAGR during the forecast period as long northern winters sustain demand for cholecalciferol immunity blends and chewable bone and joint health supplements. Regulatory overview benchmarks updated by Health Canada in September 2025 documented that 71.0% of Canadians use natural health products led by daily vitamins and minerals, while 12.0% report sensitivity to unverified formulations [13]. The central commercial obstacle involves sub-zero interprovincial rail transit, which causes pectin gels to turn brittle unless packagers calibrate vegetable glycerol humectants.
Key takeaway: In Canada, pre-market NPN licensing trust and winter vitamin D3 supplementation support an 8.4% CAGR through 2036.
South Korea Vitamin Gummies Market Outlook (2026 to 2036)
Health-and-beauty store merchandising across Seoul and Busan—led by Olive Young and convenience chains—favors portable 7-day and 14-day resealable gummy pouches designed for desk drawers and handbags. Nevertheless, strong preference among older Korean shoppers for traditional red-ginseng liquid sticks limits senior adoption, prompting domestic brands to launch dual-layer gummies pairing B-complex vitamins with fermented ginseng. Official production records cited in the April 2026 Ministry of Food and Drug Safety and USDA Foreign Agricultural Service Health Functional Food Market Brief (Report No. KS2026-0003) recorded an 11.2% annual expansion in domestic chewable vitamin output [14]. South Korea is estimated to post 7.6% CAGR over the forecast period as younger office workers trade bitter herbal tonics for tart fruit-pectin multivitamins.
Key takeaway: In South Korea, portable pouch merchandising across health-and-beauty chains and MFDS functional-food licensing support a 7.6% annual growth rate to 2036.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the vitamin gummies market?
Church & Dwight, Haleon plc, Bayer Consumer Health, Nestlé Health Science, Pharmavite, Herbalife Nutrition, Unilever (OLLY), and SmartyPants Vitamins are the significant market players in this market.
Securing national pharmacy and hypermarket shelf space in the vitamin gummies sector depends on whether a manufacturer can verify 100% labeled vitamin potency at 24 months while running high-speed allergen-free depositing lines. Global consumer healthcare groups including Haleon plc and Bayer Consumer Health alongside Nestlé Health Science utilize multi-country regulatory registrations (TGA and Health Canada NPN) and clinical pharmacy trust to market family multivitamin chews. North American high-capacity producers such as Pharmavite and Church & Dwight anchor club-store and mass-merchandiser supply. Meanwhile, Unilever's OLLY and SmartyPants Vitamins alongside Herbalife Nutrition focus on benefit-led pectin formulas and methylated micronutrients across direct subscription and distributor channels.
- Global Consumer Healthcare Leaders: Haleon plc and Bayer Consumer Health alongside Nestlé Health Science distribute clinically substantiated multivitamin gummies across international pharmacy networks.
- High-Volume Gummy Category Pioneers: Church & Dwight and Pharmavite operate large-scale manufacturing and mass-retail distribution across North America.
- Clean-Label and Lifestyle Wellness Brands: Unilever (OLLY) and SmartyPants Vitamins alongside Herbalife Nutrition focus on benefit-led pectin formulas and direct-to-consumer channels.
Competitive Benchmarking: Vitamin Gummies Market
Table 8: Competitive Benchmarking for the Vitamin Gummies Market (qualitative capability ratings), 2026
| Company | Formulation & Nutrient Breadth | Pectin & Sugar-Free Innovation | Pharmacy & Mass Retail Access | Geographic Reach |
|---|---|---|---|---|
| Church & Dwight | High | Medium | High | Medium |
| Haleon plc | High | High | High | High |
| Bayer Consumer Health | High | Medium | High | High |
| Nestlé Health Science | High | High | High | High |
| Pharmavite | High | Medium | High | Medium |
| Herbalife Nutrition | Medium | Medium | Medium | High |
| Unilever (OLLY) | High | High | High | High |
| SmartyPants Vitamins | High | High | Medium | Medium |
Scoring basis: Formulation & Nutrient Breadth evaluates whether a brand offers pediatric and adult blends alongside prenatal and condition-specific formulas (High) or a focused core line (Medium). Pectin & Sugar-Free Innovation reflects commercial deployment of vegan citrus pectin and prebiotic fiber sweeteners alongside microencapsulated vitamins. Pharmacy & Mass Retail Access measures shelf presence across national drugstores and warehouse clubs, while Geographic Reach distinguishes multi-region regulatory registrations from North America-focused operations.
Key Developments in the Vitamin Gummies Market
- In January 2026, Nestlé Health Science expanded pharmacy and e-commerce distribution of its Nature's Bounty and Garden of Life plant-based immunity and probiotic chewable gummies [15].
- In December 2025, Church & Dwight Co., Inc. announced a definitive agreement to sell its VitaFusion and L'il Critters gummy vitamin brands and Washington state manufacturing facilities to Piping Rock Health Products [16].
- In July 2025, Bayer Consumer Health unveiled a modernized brand identity and precision nutrition positioning across its One A Day and Supradyn multivitamin portfolios [17].
Key Players in the Vitamin Gummies Market
Global Consumer Healthcare and Pharmacy Platforms
- Haleon plc
- Bayer Consumer Health
- Nestlé Health Science
High-Volume Mass-Retail Gummy Specialists
- Church & Dwight
- Pharmavite
Clean-Label and Benefit-Led Wellness Brands
- Unilever (OLLY)
- SmartyPants Vitamins
- Herbalife Nutrition
Vitamin Gummies Market - Report Scope
Table 9: Report Scope for the Vitamin Gummies Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Nutrient; Nature; Distribution Channel; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial manufacturer revenue from chewable gelatin-based and plant-pectin-based vitamin and multivitamin gummy dietary supplements. Excludes hard compressed tablets, two-piece capsules, softgels, liquid drops, and non-fortified confectionery candies. Category Scope Note: Market valuation reflects finished retail and pharmacy chewable vitamin and multivitamin gummy formulations; upstream bulk hydrocolloid pectin, gelatin, and unformulated vitamin premix sales represent an ingredient tier outside finished supplement valuation. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Australia, Brazil, UK, USA, Canada, South Korea, and additional countries in the full report |
| Key Companies Covered | Church & Dwight, Haleon plc, Bayer Consumer Health, Nestlé Health Science, Pharmavite, Herbalife Nutrition, Unilever (OLLY), SmartyPants Vitamins |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Vitamin Gummies Market - Research Methodology
Table 10: Research Methodology for the Vitamin Gummies Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with nutraceutical formulation chemists, contract gummy manufacturers, hydrocolloid ingredient suppliers, retail pharmacy category managers, and regulatory compliance directors across the value chain to validate overage dosing, starchless depositing yields, and channel margins. |
| Secondary Research | Secondary research included regulatory databases (FDA DSHEA guidance, TGA AUST L registry, Health Canada NPN database, EFSA), industry association surveys (CRN, CHPA, HFMA), corporate annual filings, and pharmacopeial dissolution standards. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 period were developed using top-down and bottom-up models reconciling active supplement user cohorts, daily chewable piece consumption, and retail bottle pricing. |
| Data Triangulation and Validation | Estimates were validated against pharmacy scanner data, contract manufacturing line capacities, and hydrocolloid pectin and gelatin consumption volumes to ensure accuracy without double counting non-fortified sugar confectionery. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's nutraceutical dosage econometric model, calibrating evaluated national growth rates against the 9.3% global baseline through verified regulatory product registrations (TGA AUST L, ANVISA, Health Canada NPN), pharmacy shelf allocation, and sugar-free pectin reformulation rates. |
| Operational Benchmark Traceability | Operational benchmarks (active daily gummy consumer cohorts, annual chewable dose volume in pieces, and per-user annual expenditure) represent modeled estimates synthesized from FDA cGMP compliance records, NIH ODS intake surveys, USP compendial standards, and commercial contract-depositor disclosures. |
Vitamin Gummies Market by Segments
Vitamin Gummies Market segmented by Nutrient:
- Multivitamin Formulations
- Vitamin C & Immunity Blends
- Vitamin D & Bone Support
Vitamin Gummies Market segmented by Nature:
- Conventional Formulations
- Organic & Clean-Label Pectin
Vitamin Gummies Market segmented by Distribution Channel:
- Pharmacies & Mass Retail
- Online Direct-to-Consumer
- Specialty Health Stores
Vitamin Gummies Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- South Korea
- Japan
- China
- South Asia and Pacific
- Australia and New Zealand
- India
- ASEAN
- Middle East and Africa
- GCC Countries
- South Africa
- Israel
Research Sources and Bibliography
- [1] Council for Responsible Nutrition. (2025). CRN survey shows consistent supplement usage with increase of specialty product use over time. Council for Responsible Nutrition (CRN).
- [2] U.S. Food and Drug Administration. (2025, December 11). Dietary supplements guidance documents & regulatory information. U.S. Department of Health and Human Services.
- [3] Pharmavite LLC. (2025, May 8). Pharmavite, maker of Nature Made vitamins, opens $250 million production facility in New Albany, Ohio. Pharmavite LLC.
- [4] United States Pharmacopeia. (2026). USP verified mark: Dietary supplement manufacturing and verification program. USP.
- [5] Haleon plc. (2026, February 25). 2025 full year results: Consumer healthcare performance and Centrum brand expansion. Haleon plc.
- [6] Calder, P. C., Kreider, R. B., & McKay, D. L. (2025, January 14). Enhanced vitamin C delivery: A systematic literature review assessing the efficacy and safety of alternative supplement forms in healthy adults. Nutrients, 17(2), 279.
- [7] National Institutes of Health Office of Dietary Supplements. (2025). Multivitamin/mineral supplements: Fact sheet for health professionals. U.S. Department of Health and Human Services.
- [8] Landi, C., Landucci, E., Mazzantini, C., Castellacci, R., & Bergonzi, M. C. (2025, September 23). Vitamin D nanoliposomes to improve solubility, stability, and uptake across intestinal barrier. Pharmaceutics, 17(10), 1244.
- [9] Therapeutic Goods Administration. (2025, November 25). Complementary medicines: Stronger safety controls introduced for products containing vitamin B6. Australian Government Department of Health, Disability and Ageing.
- [10] Agência Nacional de Vigilância Sanitária (ANVISA). (2026, September 9). Suplementos alimentares: Como saber se um suplemento alimentar é autorizado? Portal Gov.br.
- [11] Department of Health and Social Care. (2026, June 25). Food supplements guidance. GOV.UK.
- [12] Centers for Disease Control and Prevention. (2026, June 15). 2026 CDC nutrition report: At-a-glance micronutrient and dietary supplement indicators. U.S. Department of Health and Human Services.
- [13] Health Canada. (2025, September 10). About natural health products: Natural health product regulation in Canada. Government of Canada.
- [14] Ministry of Food and Drug Safety & USDA Foreign Agricultural Service. (2026, April 6). Health functional food and supplements: Market brief for the Republic of Korea (Report No. KS2026-0003). MFDS / USDA FAS.
- [15] Nestlé Health Science. (2026, January 14). Nature's Bounty and Garden of Life chewable vitamin and probiotic gummy portfolio updates. Nestlé Health Science.
- [16] Church & Dwight Co., Inc. (2025, December 9). Church & Dwight to sell VitaFusion and L'il Critters brands. Church & Dwight Co., Inc.
- [17] Bayer Consumer Health. (2025, July 3). One A Day unveils new brand identity and Bayer launches Supradyn Naturals. Bayer AG.
- [18] OLLY PBC (Unilever). (2025, August 26). OLLY vitamins & supplements: Gut health, fiber gummy rings, and daily cellular energy collections. Unilever.
- [19] SmartyPants Vitamins. (2025, November 11). Making and testing our gummies: Multifunctional family and kids formula & fiber daily gummy vitamins. SmartyPants Vitamins.
- [20] Herbalife International. (2026, February 18). Herbalife skin, collagen beauty booster, and daily micronutrient supplement product guide. Herbalife International.
- [21] International Pharmaceutical Excipients Council. (2026, January 29). Excipient stability, water-activity control, and anti-sticking standards for chewable gel dosage forms. IPEC.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the vitamin gummies market in 2026 and what is forecast for 2036?
- Which consumer pill-fatigue and hydrocolloid formulation factors support demand for vitamin gummies?
- Why do multivitamin formulations lead the nutrient category?
- Why do conventional formulations lead the nature category globally?
- How do growth rates differ across Australia and Brazil alongside the UK and the USA?
- Which leading companies supply mass-retail multivitamin and clean-label pectin gummies today?
- What thermal potency and humidity clumping constraints limit margin expansion in the vitamin gummies market?
- What should pharmacy and retail buyers evaluate before qualifying a contract gummy manufacturer?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Nutrient, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Nutrient, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Nutrient, 2026 to 2036
- Multivitamin Formulations
- Vitamin C & Immunity Blends
- Vitamin D & Bone Support
- Y-o-Y Growth Trend Analysis By Nutrient, 2021 to 2025
- Absolute $ Opportunity Analysis By Nutrient, 2026 to 2036
- Global Market Analysis and Forecast, By Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Nature, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Nature, 2026 to 2036
- Conventional Formulations
- Organic & Clean-Label Pectin
- Y-o-Y Growth Trend Analysis By Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Pharmacies & Mass Retail
- Online Direct-to-Consumer
- Specialty Health Stores
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Nutrient
- By Nature
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nutrient
- By Nature
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Nutrient
- By Nature
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nutrient
- By Nature
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United Kingdom
- Germany
- France
- Italy
- Spain
- Benelux
- Nordics
- By Nutrient
- By Nature
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nutrient
- By Nature
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Nutrient
- By Nature
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nutrient
- By Nature
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- South Korea
- Japan
- China
- By Nutrient
- By Nature
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nutrient
- By Nature
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Australia and New Zealand
- India
- ASEAN
- By Nutrient
- By Nature
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nutrient
- By Nature
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Israel
- By Nutrient
- By Nature
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nutrient
- By Nature
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutrient
- By Nature
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutrient
- By Nature
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutrient
- By Nature
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutrient
- By Nature
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutrient
- By Nature
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutrient
- By Nature
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutrient
- By Nature
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutrient
- By Nature
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutrient
- By Nature
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutrient
- By Nature
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutrient
- By Nature
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutrient
- By Nature
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutrient
- By Nature
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutrient
- By Nature
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutrient
- By Nature
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutrient
- By Nature
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutrient
- By Nature
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutrient
- By Nature
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutrient
- By Nature
- By Distribution Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutrient
- By Nature
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Nutrient
- By Nature
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Church & Dwight
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Haleon plc
- Bayer Consumer Health
- Nestlé Health Science
- Pharmavite
- Herbalife Nutrition
- Unilever (OLLY)
- SmartyPants Vitamins
- Church & Dwight
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Nutrient, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Nutrient, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Nutrient, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Nutrient, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Nutrient, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Nutrient, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Nutrient, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Nutrient, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Nutrient, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Nutrient, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Nutrient
- Figure 6: Global Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Nature
- Figure 9: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Distribution Channel
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Nutrient, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Nutrient, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Nutrient
- Figure 26: North America Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Nature
- Figure 29: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Distribution Channel
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Nutrient, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Nutrient, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Nutrient
- Figure 36: Latin America Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Nature
- Figure 39: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Nutrient, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Nutrient, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Nutrient
- Figure 46: Western Europe Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Nature
- Figure 49: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Nutrient, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Nutrient, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Nutrient
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Nature
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Nutrient, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Nutrient, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Nutrient
- Figure 66: East Asia Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Nature
- Figure 69: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Nutrient, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Nutrient, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Nutrient
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Nature
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Nutrient, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Nutrient, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Nutrient
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Nature
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the vitamin gummies market in 2026, and what is forecast for 2036?
The global vitamin gummies market is projected to reach USD 10.7 billion in 2026 and expand further to USD 26.0 billion by 2036, driven by household switching away from hard tablets.
What is the CAGR for the vitamin gummies market from 2026 to 2036?
According to FMI, the vitamin gummies market is projected to grow at a 9.3% CAGR from 2026 to 2036. Growth is supported by starchless continuous depositing lines and sugar-free pectin formulations.
Which nutrient segment holds a notable vitamin gummies demand share in 2026?
Multivitamin formulations are projected to hold 42.0% of nutrient demand in 2026. The segment benefits from convenient all-in-one daily micronutrient dosing for pediatric, adult, and senior users.
Which nature segment holds a notable vitamin gummies share in 2026?
Conventional formulations account for 69.0% of nature category demand in 2026. Demand is supported by high-speed gelatin mogul manufacturing efficiency and resilient chew texture.
Which country has a notable vitamin gummies expansion outlook during the forecast period?
FMI finds that Australia is projected to expand at an 11.6% CAGR during the 2026 to 2036 assessment period. Growth is supported by strict TGA listed-medicine quality trust and strong pharmacy retail demand.
Which companies are active in the vitamin gummies market during 2026?
Notable companies include Church & Dwight, Haleon plc, Bayer Consumer Health, Nestlé Health Science, Pharmavite, Herbalife Nutrition, Unilever (OLLY), and SmartyPants Vitamins. These manufacturers focus on starchless depositing, microencapsulated vitamins, and sugar-free pectin systems.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
