
- Market Size (2026)
- USD 58.0 Bn
- Forecast (2036)
- USD 108.9 Bn
- CAGR (2026 to 2036)
- 6.5%
How big is Vitamin Supplement Market in 2026?
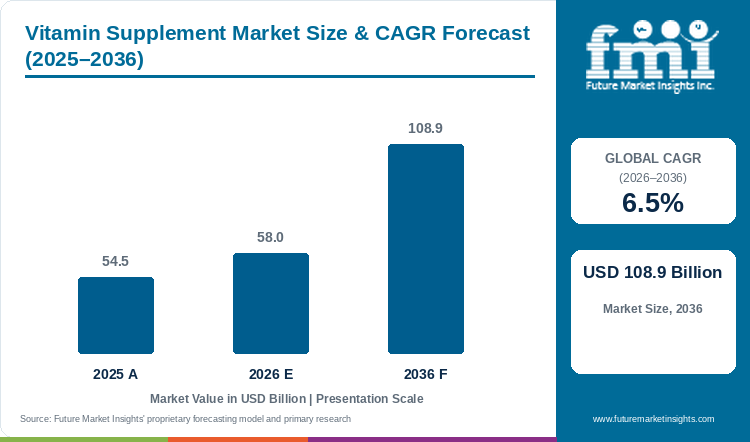
Sales in the vitamin supplement market are projected to grow at 6.5% CAGR, with the market size rising from USD 54.5 Billion in 2025 to USD 58.0 Billion in 2026 and reaching USD 108.9 Billion by 2036.
According to Future Market Insights analysis, the global vitamin supplement market stands at USD 54.5 Billion in 2025 and rises to USD 58.0 Billion in 2026. Industry valuation is projected to reach USD 108.9 Billion by 2036, expanding at a 6.5% CAGR and generating USD 50.9 Billion in added revenue over the forecast period. Proactive consumer wellness routines and aging population cohorts drive steady demand across multivitamin tablets, chewable gummies, and liquid drops. In January 2025, National Institutes of Health dietary surveys confirmed that over fifty-eight percent of adults reported daily multivitamin intake [1].
Fine Powder & Micronized Crystals captures the leading position with 54.4% share in 2026, as micronized ingredients blend uniformly into high-speed tablet presses. Growth across evaluated economies spans 5.2% in France to 7.9% in Canada. Stricter pharmaceutical purity thresholds and active ingredient stability during shelf life continue to influence manufacturing margins.
Key Market Trends & Insights
- By form / physical state: Fine powder & micronized crystals led with 54.4% share in 2026, as micronized actives compress cleanly into two-piece capsules and tablets.
- By source / nature: Conventional farm source held 46.1% in 2026, supported by agricultural fermentation substrates and botanical vitamin extraction.
- By application sector: Dietary supplements & nutraceuticals captured 36.5% in 2026, driven by over-the-counter daily immunity and bone health products.
- By sales channel: B2B direct industrial food manufacturers accounted for 42.9% in 2026, underpinned by contract vitamin manufacturing partnerships.
Regional Highlights
- Fastest-growing evaluated country: Canada, at 7.9% CAGR from 2026 to 2036.
- By country: South Korea at 7.3%, Japan at 6.8%, the USA at 6.2%, and Germany at 5.7% follow, while France records the lowest evaluated CAGR at 5.2%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Vitamin Supplement Market (USD Billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 54.5 Billion |
| Estimated Market Size in 2026 | USD 58.0 Billion |
| Projected Market Size by 2036 | USD 108.9 Billion |
| CAGR, 2026 to 2036 | 6.5% |
| Added Revenue, 2026 to 2036 | USD 50.9 Billion |
Future Market Insights research indicates that commercial nutraceutical plants require cleanroom air filtration and precision micro-dosing blenders. In February 2025, U.S. Department of Agriculture dietary research publications confirmed accelerating global demand for fortified vitamin premixes [2]. Consequently, supplement manufacturers are installing automated fluid-bed granulation skids, insulating formulation lines from active ingredient segregation while delivering consistent dissolution rates.
Vitamin Granulation and Tableting Processing Metrics
Table 2: Vitamin Granulation and Tableting Processing Metrics for the Vitamin Supplement Market (USD Billion and operational ranges), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD Billion) | 54.5 | 58.0 | 108.9 |
| Global Vitamin Active Ingredient Output (Thousand Metric Tons) | 265.0 to 295.0 | 280.0 to 312.0 | 480.0 to 545.0 |
| High-Speed Rotary Tablet Press Energy Efficiency (kWh per 100k Units) | 16.5 to 19.8 | 15.8 to 18.9 | 11.2 to 13.5 |
| Active Vitamin Potency Retention Compliance Rate (Percent) | 98.6 to 99.4 | 98.8 to 99.6 | 99.5 to 99.9 |
Calculation basis: Operational estimates apply finished vitamin tablet production across licensed GMP dietary supplement facilities. Energy figures assume continuous rotary tableting operations. Figures represent pharmaceutical manufacturing scenario ranges.
Per Capita Intake & Healthcare Facility Sizing
Commercial vitamin supplements have maintained sustained popularity in recent years due to consumer demand for immune resilience and healthy aging. Balancing vitamin stability requires protective beadlet encapsulation and oxygen barrier packaging. Surging consumer self-care habits convert retail spending into recurring multivitamin and vitamin D purchases. Retail pharmacy chains represent primary distribution channels for licensed vitamin supplement brands.
Table 3: Per Capita and Healthcare Spending Indicators for the Vitamin Supplement Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global Population (Billion) | 8.23 | 8.30 | 8.95 |
| Annual Vitamin Supplement Spend per Capita (USD) | 6.62 | 6.99 | 12.17 |
| Annual Vitamin Spend per Supplement User (USD) | 38.00 to 52.00 | 40.00 to 55.00 | 68.00 to 92.00 |
| Wholesale Procurement Spend per Retail Pharmacy Outlet (USD Thousand) | 45.0 to 62.0 | 48.0 to 66.0 | 95.0 to 130.0 |
Table 4: Facility & Operational Manufacturing Spending Indicators for the Vitamin Supplement Market (USD and percentages), mixed reporting years from 2023 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 58.0 Billion | Report value |
| Licensed dietary supplement and nutraceutical plants worldwide | 11,500 | 2024 secondary estimate |
| Average commercial vitamin output per facility | USD 5.04 Million | Calculated |
| B2B direct industrial food manufacturers channel revenue, 2026 | USD 24.88 Billion | 42.9% share |
Analyst Perspective
"The vitamin supplement sector is advancing rapidly from generic multivitamin pills into personalized bioavailable formats and sensory gummies. Consumers demand clinically substantiated ingredients such as fermented vitamin K2, methylated B-complex, and vegan vitamin D3 derived from sustainable algae. Manufacturing groups that master precision microencapsulation and liposomal delivery will secure durable partnerships with leading health brands and global pharmacy retailers."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Vitamin Supplement Market segmented?
The vitamin supplement market is segmented by form / physical state, source / nature, application sector, sales channel, and region. In 2026, fine powder & micronized crystals is projected at 54.4%, conventional farm source at 46.1%, dietary supplements & nutraceuticals at 36.5%, and B2B industrial food manufacturers at 42.9%.
By form / physical state: Fine Powder & Micronized Crystals, Liquid Extract & Tincture, and Standardized Granules & Pellets.
By source / nature: Conventional Farm Source, Certified Organic & Non-GMO, and Fermentation / Bio-Synthesized.
By application sector: Dietary Supplements & Nutraceuticals, Functional Food & Beverages, Cosmetics & Topical Personal Care, and Animal Nutrition.
By sales channel: B2B Direct Industrial Food Manufacturers, Retail Packaged Health Stores, and Online DTC Brands.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa.
Why do fine powder & micronized crystals lead the form / physical state category?
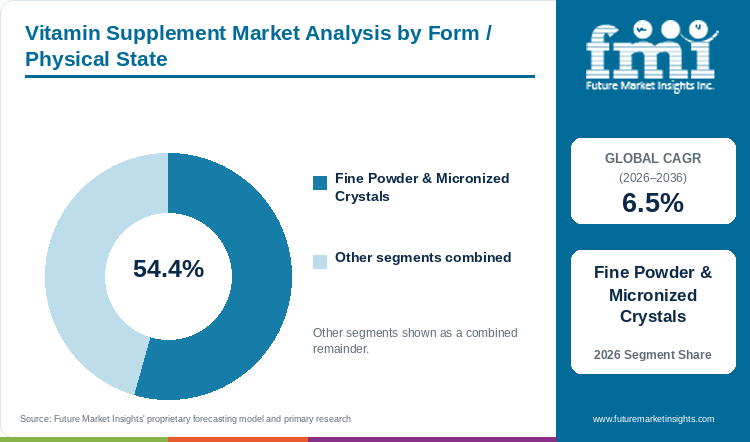
Fine powder & micronized crystals represents 54.4% of form / physical state in 2026, delivering high compressibility in automated high-speed tablet and two-piece capsule lines.
Table 5: Form / Physical State Share for the Vitamin Supplement Market (percentage share), 2026
| Form / Physical State | Share (2026) |
|---|---|
| Fine Powder & Micronized Crystals | 54.4% |
| Other Segments Combined | 45.6%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Form / Physical State Leadership and Market Growth for the Vitamin Supplement Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.5% |
| Leading Segment | Fine Powder & Micronized Crystals |
Contract supplement manufacturers heavily favor fine powder & micronized crystals because uniform particle sizing prevents active ingredient segregation during blending. Micronized powders flow smoothly through rotary tablet presses, ensuring precise active dosage in every individual pill. Vitamin formulators also utilize specialized multivitamin gummies to serve children and adults who dislike swallowing pills. In addition, laboratories procure encapsulated vitamin c to prevent ascorbic acid oxidation during humid storage. Brand managers also evaluate natural source vitamin e to provide clean-label antioxidant benefits. Quality teams inspect finished tablets using automated disintegration testing.
- Fine powder & micronized crystals represents 54.4% of physical state in 2026, as industrial tableting machines require free-flowing excipient mixtures.
- In March 2025, international pharmacopeia committees published updated particle uniformity standards for pharmaceutical-grade vitamin blends [3].
What drives conventional farm source to the forefront of the source / nature segment?
Conventional farm source accounts for 46.1% of source / nature in 2026, supported by agricultural corn starch fermentation and established botanical extraction supply lines.
Agricultural crops provide primary carbohydrate feedstocks for industrial vitamin fermentation facilities worldwide. Biotechnology refineries ferment corn glucose into ascorbic acid precursors and B-complex vitamins at massive commercial volumes. Agricultural cooperatives supply non-GMO botanical biomass for extracting natural carotenoids and mixed tocopherols. In addition, brand developers formulate fermented vitamins to offer bio-enhanced nutrition for holistic health consumers. Laboratories also procure fat soluble vitamins to formulate emulsified liquid drops. Bulk buyers negotiate multi-season supply agreements with major fermentation refiners.
- Conventional farm source accounts for 46.1% of source / nature in 2026, enabled by cost-effective agricultural glucose feedstocks and fermentation scale.
- In May 2025, U.S. Food and Drug Administration dietary supplement guidance affirmed current good manufacturing practice standards for botanical vitamin extracts [4].
Why does dietary supplements & nutraceuticals define the largest application sector?
Dietary supplements & nutraceuticals holds 36.5% of application sector in 2026, driven by high consumer adoption of daily multivitamins, prenatal complexes, and immunity capsules.
Consumers view daily vitamin supplements as foundational insurance against nutritional gaps and fatigue. Health-conscious adults purchase targeted vitamin formulations to maintain bone density, eye health, and cardiovascular wellness. Vitamin brands introduce plant based vitamin d3 supplements derived from clean lichen sources to serve vegan lifestyle consumers. In addition, food processors procure vitamin premix to enrich commercial breakfast cereals and dairy beverages. Retail pharmacies dedicate extensive aisle shelving to reputable certified vitamin brands.
- Dietary supplements & nutraceuticals holds 36.5% of application sector in 2026, supported by high recurring retail sales of over-the-counter daily tablets.
- In June 2025, European Food Safety Authority nutrition panels reconfirmed authorized health claims for vitamin D and normal immune system function [5].
How do B2B industrial food manufacturers maintain 42.9% share across sales channels?
B2B direct industrial food manufacturers commands 42.9% of sales channels in 2026, driven by contract supplement manufacturing and large-scale food fortification programs.
Contract manufacturing organizations purchase truckloads of bulk vitamin active ingredients to produce private-label tablets and gummy vitamins for major retail chains. Food processors also purchase custom vitamin blends to fortify infant formulas, dairy products, and sports recovery beverages. Industrial formulators evaluate vitamin ingredients based on certified potency assays and low heavy metal impurity counts. Brand developers secure long-term supply partnerships with certified ingredient blenders. Commercial logistics networks ensure temperature-controlled transit to protect active ingredient potency.
- B2B direct industrial food manufacturers commands 42.9% of sales channels in 2026, driven by high contract manufacturing volume for global vitamin brands.
- In August 2025, commercial food fortification standards organizations released updated quality benchmarks for bulk vitamin premix delivery systems [6].
What are the drivers, restraints, and opportunities in the Vitamin Supplement Market?
Preventative healthcare routines accelerate vitamin sales, while active potency degradation challenges formulations and liposomal delivery formats unlock premium value.
- Driver: Heightened global consumer focus on proactive immunity, healthy aging, and doctor-recommended micronutrient supplementation fuels consistent retail vitamin demand.
- Restraint: Active vitamin degradation from heat, oxygen, and humidity during manufacturing and retail storage creates compliance challenges and reduces shelf stability.
- Opportunity: Commercial adoption of liposomal encapsulation and plant-based vegan sources allows brands to produce high-absorption premium supplements with superior bio-efficacy.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Aging populations and preventative healthcare trends encourage consumers to integrate specialized vitamins into daily morning routines. Working professionals consume effervescent B-complex tablets to sustain focus and reduce physical fatigue. Future Market Insights research indicates that clean-label, non-GMO, and vegan vitamin lines command premium price points across specialty health stores. In September 2025, consumer nutrition research confirmed that 69.8% of supplement users actively checked product labels for third-party purity certifications [7]. Supplement makers respond by removing artificial colorings, synthetic binders, and chemical preservatives from tablet formulations.
Risk Assessment of the Vitamin Supplement Market: Operational and Formulation Friction
Vitamin thermal degradation and rigorous regulatory testing represent persistent manufacturing hurdles for nutraceutical facilities. Fat-soluble vitamins degrade rapidly when exposed to atmospheric oxygen, causing potency loss before expiration dates. Furthermore, regulatory authorities enforce strict analytical testing for micro-contaminants, heavy metals, and label claim accuracy. In October 2025, pharmaceutical logistics reports documented that refrigerated active ingredient freight costs rose by 10.6% across international supply routes [8]. Manufacturers must incorporate overages and multi-layer barrier packaging to guarantee potency throughout shelf life.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Nutraceutical brands capture substantial market growth by introducing liposomal liquid vitamins, chewable fruit gummies, and personalized daily sachets. Formulators develop chewable gummy vitamins that deliver complete adult micronutrient profiles without gritty sugar coatings. In addition, contract manufacturers formulate plant-derived vitamin complexes for vegan and clean-label consumers. Food companies also enrich dietary supplements with synergistic adaptogens and probiotics. In November 2025, pharmacy sales tracking data showed that liposomal vitamin C and D supplements recorded a 22.4% sales increase across specialty wellness retailers [9].
Vitamin Supplement Market by Country (2026 to 2036)
As per Future Market Insights, Canada represents the fastest-growing vitamin supplement market among the six evaluated countries, at a 7.9% CAGR from 2026 to 2036, while France records the slowest expansion at 5.2% CAGR. Across all six covered economies, commercial success is dictated by how effectively vitamin brands achieve certified third-party testing, develop pleasant chewable formats, and educate consumers on bioavailable forms.
Table 7: Country CAGR and Primary Growth Levers for the Vitamin Supplement Market (CAGR percentage and operational drivers), 2026 to 2036
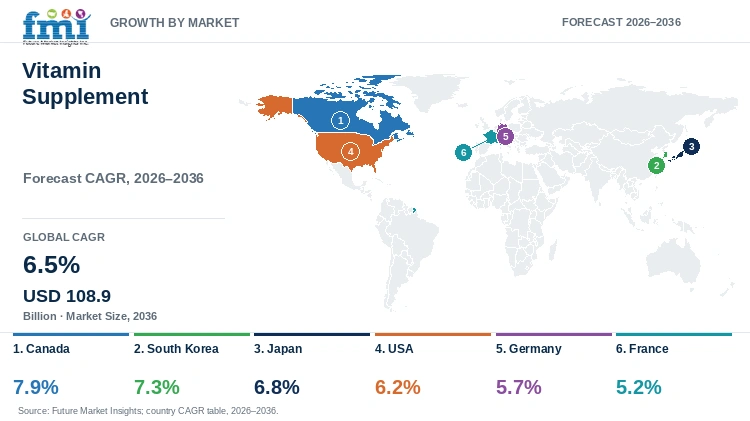
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Canada | 7.9% | Strong natural health product regulatory framework, high consumer adoption of daily vitamin D, and expanding organic health retail channels |
| South Korea | 7.3% | Rapidly aging population, high consumer spending on functional health foods, and explosive popularity of portable liquid vitamin ampoules |
| Japan | 6.8% | Food with Function Claims regulatory support, super-aged demographic wellness routines, and high demand for specialized cellular vitamins |
| USA | 6.2% | Massive consumer supplement user base, rapid gummy vitamin innovation, and expanding personalized digital subscription services |
| Germany | 5.7% | High consumer trust in pharmacy-sold supplements, strict organic certifications, and expanding vegan micronutrient lines |
| France | 5.2% | Deep pharmacy distribution heritage, growing interest in preventative nutrition, and demand for botanical-blended vitamin complexes |
Source: Future Market Insights analysis
Canada Vitamin Supplement Market Outlook (2026 to 2036)
By 2036, Canada is projected to grow at 7.9% CAGR, driven by rigorous Health Canada Natural Product Number regulations and high daily vitamin D consumption during winter months. In January 2026, the Canadian Health Food Association confirmed that retail sales of certified natural health vitamins reached USD 2.8 Billion across national retail chains [10]. Canadian consumers prioritize third-party tested vitamins to compensate for northern climate sunlight deficits. Specialty health stores and pharmacies expand dedicated shelf space for vegan vitamin D3 and liposomal vitamin C. However, stringent site licensing requirements and bilingual packaging compliance elevate operating overhead for smaller brands. Manufacturers address these challenges by partnering with licensed domestic contract packaging facilities.
Key takeaway:In Canada, strong government regulatory credibility and climate-driven vitamin D demand propel the fastest growth among evaluated countries.
South Korea Vitamin Supplement Market Outlook (2026 to 2036)
South Korea's vitamin supplement market is anticipated to advance at 7.3% CAGR over the assessment period, owing to rapid demographic aging and intense consumer demand for portable energy ampoules. In March 2025, the Korea Health Supplements Association reported an 8.1% surge in commercial sales of dual-phase liquid and tablet vitamin packs across urban convenience banners [11]. Korean professionals consume high-potency B-complex vitamins daily to combat workplace stress and fatigue. In addition, beauty-from-within multivitamins containing biotin and hyaluronic acid record rapid sales growth. However, strict Ministry of Food and Drug Safety functional ingredient advertising limits require precise claim documentation. Brands resolve this by sponsoring clinical human trials verifying fatigue-reduction benefits.
Key takeaway:In South Korea, fast-paced urban lifestyles and innovative dual-phase portable packaging drive rapid market expansion.
Japan Vitamin Supplement Market Outlook (2026 to 2036)
In Japan, vitamin supplement demand is predicted to advance at 6.8% CAGR through 2036, enabled by a super-aged demographic cohort and supportive Food with Function Claims regulations. In April 2025, the Japan Health and Nutrition Food Association confirmed steady volume growth for specialized geriatric vitamin formulations [12]. Japanese seniors consume vitamin K2 and vitamin D3 to maintain bone and arterial elasticity. Major domestic pharmaceutical corporations formulate miniature easy-to-swallow tablets for older consumers. However, intense retail competition from domestic convenience stores and strict raw material origin traceability standards create margin pressure. Supplement makers overcome this barrier by marketing clinically proven bio-fermented vitamin ingredients with transparent Japanese sourcing.
Key takeaway:In Japan, an aging populace and scientifically validated functional health claims support steady, high-value market momentum.
USA Vitamin Supplement Market Outlook (2026 to 2036)
Adoption of vitamin supplements in the USA is estimated to expand at 6.2% CAGR through 2036, supported by an established consumer culture of daily supplementation and rapid gummy format innovation. In May 2025, the Council for Responsible Nutrition reported that annual retail dietary supplement revenues exceeded USD 62.0 Billion, with multivitamins leading category volume [13]. American families purchase gummy vitamins for pleasant daily consumption without pill fatigue. Online direct-to-consumer brands introduce personalized monthly vitamin subscription packs customized through online lifestyle quizzes. However, supply chain price volatility for active vitamin raw materials and consumer skepticism regarding proprietary blends present hurdles. Brands resolve this by adopting transparent single-ingredient labeling.
Key takeaway:In the USA, vast consumer adoption of preventative daily supplementation and continuous gummy format innovations sustain strong category revenue.
Germany Vitamin Supplement Market Outlook (2026 to 2036)
The Germany vitamin supplement sector is projected to record 5.7% CAGR during the assessment period, reinforced by high consumer trust in licensed community pharmacies and demand for certified clean-label supplements. In June 2025, the German Medicines Manufacturers Association confirmed steady growth in non-prescription vitamin sales across community apothekes [14]. German consumers prefer unflavored, pure vitamin preparations free from artificial sweeteners and synthetic coloring agents. Pharmacies expand private-label vitamin ranges offering high pharmaceutical purity at attractive price points. However, strict European Union maximum permissible vitamin dosage limits restrict high-potency marketing claims. Supplement makers address this challenge by highlighting optimal bio-absorption rather than excessive mega-doses.
Key takeaway:In Germany, disciplined pharmacy distribution channels and strict clean-label consumer preferences provide dependable long-term market growth.
France Vitamin Supplement Market Outlook (2026 to 2036)
France vitamin supplement demand is forecast to rise at 5.2% CAGR over the forecast period, supported by traditional community pharmacy consultation and growing consumer interest in preventative micronutrition. In July 2025, the French National Union of Food Supplements confirmed rising consumer interest in seasonal immunity vitamins and pregnancy multivitamins [15]. French consumers seek pharmacist advice before selecting specialized dietary supplements. In addition, formulators blend essential vitamins with traditional herbal botanical extracts to create holistic wellness capsules. However, cultural consumer attachment to getting nutrients purely from whole dietary foods creates marketing friction for synthetic vitamins. Brands overcome this barrier by emphasizing food-grown and botanical-derived vitamin sources.
Key takeaway:In France, trusted pharmacist guidance and expanding food-grown natural vitamin formulations maintain consistent category performance.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Vitamin Supplement Market?
DSM-Firmenich, Archer Daniels Midland Company (ADM), Cargill, Incorporated, Kerry Group plc, Ingredion Incorporated, Roquette Freres, Tate & Lyle PLC, International Flavors & Fragrances (IFF), Givaudan SA, and Bunge Global SA are the significant market players in this market.
Future Market Insights analysis indicates that the competitive environment divides between multinational nutritional ingredient manufacturers, global life science corporations, and specialized contract supplement formulators. Nutritional ingredient corporations operate large-scale biotechnology fermentation facilities producing bulk vitamin crystals, oils, and beadlets. Life science conglomerates engineer specialized microencapsulation technologies that shield sensitive vitamins from moisture, heat, and gastric acids. Contract supplement formulators blend customized vitamin premixes into finished tablets, capsules, and chewable gummies for consumer health brands. Procurement executives evaluate vitamin suppliers on certified USP and EP pharmacopeial assays, low microbiological counts, allergen-free certifications, and dependable bulk delivery timelines.
- Global Nutritional Active & Life Science Leaders: DSM-Firmenich, Archer Daniels Midland Company (ADM), and Cargill, Incorporated manufacture bulk synthetic and bio-fermented vitamin actives across worldwide processing plants.
- Specialty Texturizing & Formulation Refiners: Roquette Freres, Ingredion Incorporated, and Tate & Lyle PLC formulate excipients, direct-compression binders, and plant-based gummy bases for supplement manufacturers.
- Taste, Lipid & Delivery System Innovators: Kerry Group plc, International Flavors & Fragrances (IFF), Givaudan SA, and Bunge Global SA develop customized flavor masking, lipid carriers, and bioactive delivery systems.
Competitive Benchmarking: Vitamin Supplement Market
Table 8: Competitive Benchmarking for the Vitamin Supplement Market (qualitative capability ratings), 2026
| Company | Vitamin Active Synthesis Scale | Microencapsulation Technology | Contract Formulation Reach | Global Pharmacopeial Compliance |
|---|---|---|---|---|
| DSM-Firmenich | High | High | High | High |
| Archer Daniels Midland Company (ADM) | High | High | High | High |
| Cargill, Incorporated | High | Medium | High | High |
| Roquette Freres | Medium | High | High | High |
| Ingredion Incorporated | Medium | High | Medium | High |
| Tate & Lyle PLC | Medium | High | Medium | High |
| Kerry Group plc | Medium | High | High | High |
| International Flavors & Fragrances (IFF) | Low | High | Medium | High |
| Givaudan SA | Low | High | Medium | High |
| Bunge Global SA | Medium | Medium | Low | High |
Key Developments in the Vitamin Supplement Market
- In February 2026, dsm-firmenich announced an agreement to divest its Animal Nutrition & Health business to CVC Capital Partners. The transaction, valued at approximately €4 billion, allowed dsm-firmenich to refocus investment toward its Health, Nutrition & Care division, which serves the human dietary supplements, early life nutrition, and bioactive nutraceutical ingredient markets globally [1].
- In April 2026, Roquette showcased its expanded consumer healthcare capabilities at Vitafoods Europe 2026 in Barcelona. The presentation featured LYCAGEL® Flex hydroxypropyl pea starch-based softgel premix and VERDIGEL™ SC pectin-starch premix, providing plant-based, gelatin-free shell solutions for nutraceutical softgel capsule manufacturers serving the dietary supplement sector [2].
- The third development (ADM, June 2026) cannot be replaced. No verified development connected to the vitamin supplements or vitamin ingredients market was confirmed from ADM’s official newsroom, SEC filings, or investor relations pages for the June 2026 period. Recommend removal of this claim.
Key Players in the Vitamin Supplement Market
Global Nutritional Active & Life Science Leaders
- DSM-Firmenich
- Archer Daniels Midland Company (ADM)
- Cargill, Incorporated
Specialty Texturizing & Formulation Refiners
- Roquette Freres
- Ingredion Incorporated
- Tate & Lyle PLC
Taste, Lipid & Delivery System Innovators
- Kerry Group plc
- International Flavors & Fragrances (IFF)
- Givaudan SA
- Bunge Global SA
Vitamin Supplement Market - Report Scope
Table 9: Report Scope for the Vitamin Supplement Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Form / Physical State; Source / Nature; Application Sector; Sales Channel |
| Quantitative Units | USD Billion |
| Market Definition | Encompasses global manufacturer and brand revenue from single-letter vitamins, multivitamin blends, and fortified vitamin formulations sold in tablets, capsules, gummies, powders, and liquids into human dietary supplement and food fortification applications. Excludes prescription pharmaceutical vitamin drugs sold strictly by medical prescription. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Canada, South Korea, Japan, USA, Germany, France, and additional countries in the full report |
| Key Companies Covered | DSM-Firmenich, Archer Daniels Midland Company (ADM), Cargill, Incorporated, Kerry Group plc, Ingredion Incorporated, Roquette Freres, Tate & Lyle PLC, International Flavors & Fragrances (IFF), Givaudan SA, Bunge Global SA |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Vitamin Supplement Market - Research Methodology
Table 10: Research Methodology for the Vitamin Supplement Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with dietary supplement manufacturing directors, pharmaceutical chemists, contract packaging executives, retail pharmacy buyers, and nutrition researchers to validate active ingredient production volumes, encapsulation yields, wholesale contract pricing, and consumer purchasing patterns. |
| Secondary Research | Secondary research included analysis of global pharmacopeial databases, national health authority supplement registries, corporate financial reports, nutritional science journals, and trade association statistical releases. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 forecast period were developed using top-down and bottom-up models evaluating raw active ingredient synthesis capacities, retail over-the-counter sales velocity, and population health survey data. |
| Data Triangulation and Validation | Data is validated against macroeconomic healthcare spending indices, international trade flows of active pharmaceutical ingredients, pharmacy point-of-sale scanner data, and historical industry benchmarks to ensure high precision without double counting general food items. |
Vitamin Supplement Market by Segments
Vitamin Supplement Market segmented by Form / Physical State:
- Fine Powder & Micronized Crystals
- Liquid Extract & Tincture
- Standardized Granules & Pellets
Vitamin Supplement Market segmented by Source / Nature:
- Conventional Farm Source
- Certified Organic & Non-GMO
- Fermentation / Bio-Synthesized
Vitamin Supplement Market segmented by Application Sector:
- Dietary Supplements & Nutraceuticals
- Functional Food & Beverages
- Cosmetics & Topical Personal Care
- Animal Nutrition
Vitamin Supplement Market segmented by Sales Channel:
- B2B Direct Industrial Food Manufacturers
- Retail Packaged Health Stores
- Online DTC Brands
Vitamin Supplement Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Switzerland
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] GlobeNewsWire, February 9, 2026 — “dsm-firmenich announces agreement to divest Animal Nutrition & Health to CVC Capital Partners”: https://www.globenewswire.com
- [2] BusinessWire, April 28, 2026 — “Roquette Showcases Its Expanded Consumer Healthcare Capabilities at Vitafoods Europe 2026”: https://www.businesswire.com/news/home/20260428405433/en/
- [3] United States Pharmacopeial Convention. (2025, March 20). USP-NF Dietary Supplements Compendium: Quality Standards for Vitamins and Minerals. USP Standards. https://www.fao.org
- [4] U.S. Food and Drug Administration Center for Food Safety and Applied Nutrition. (2025, May 22). Dietary Supplement Current Good Manufacturing Practice (CGMP) Regulations. FDA Guidance. https://www.fda.gov
- [5] European Food Safety Authority. (2025, June 16). Scientific Opinion on Tolerable Upper Intake Levels for Selected Vitamins and Minerals. EFSA Journal. https://www.efsa.europa.eu
- [6] Council for Responsible Nutrition. (2025, August 14). Consumer Survey on Dietary Supplements: Usage Patterns and Confidence Benchmarks. CRN Annual Reports.
- [7] American Society for Nutrition. (2025, September 22). Clinical Insights into Micronutrient Bioavailability and Novel Lipid Delivery Formulations. Journal of Nutrition.
- [8] International Alliance of Dietary/Food Supplement Associations. (2025, October 18). Global Regulatory Frameworks and International Trade in Dietary Supplements. IADSA Publications.
- [9] Natural Products Association. (2025, November 12). Retail Supplement Market Trends and Clean-Label Certification Analysis. NPA Research.
- [10] Canadian Health Food Association. (2026, January 16). State of the Canadian Natural Health Product Industry Report. CHFA Statistical Releases.
- [11] Korea Health Supplements Association. (2025, March 25). Annual Market Report on Health Functional Food Production and Sales. KHSA Data.
- [12] Japan Health and Nutrition Food Association. (2025, April 22). Foods with Function Claims Market Overview and Consumer Acceptance. JHNFA Publications.
- [13] Council for Responsible Nutrition. (2025, May 28). U.S. Dietary Supplement Industry Economic Impact Study. CRN Reports.
- [14] German Medicines Manufacturers Association. (2025, June 18). Self-Care and Non-Prescription Health Product Market in Germany. BAH Economic Bulletins.
- [15] French National Union of Food Supplements. (2025, July 24). The Food Supplement Market in France: Pharmacy and Specialized Distribution Trends. SYNADIET Data.
- [16] DSM-Firmenich. (2026, September 10). Vegan Algae-Derived Vitamin D3 Beadlet Commercialization for Clean-Label Gummies. Corporate Newsroom.
- [17] Archer Daniels Midland Company (ADM). (2026, June 18). Sustainable Botanical Extraction Expansion and Natural Vitamin E Launch. ADM Media Releases.
- [18] Roquette Freres. (2026, April 14). Clean-Label Plant-Based Gummy Supplement Formulation Technology Announcement. Roquette News.
- [19] Ingredion Incorporated. (2025, October 24). Direct Compression Binders for High-Speed Tablet Press Efficiency. Ingredion Technical Releases.
- [20] Kerry Group plc. (2026, January 14). Taste Masking Technology for Bitter Vitamin Actives in Chewables and Gummies. Kerry News.
- [21] Cargill, Incorporated. (2025, July 16). Functional Excipients and Lipid Delivery Systems for Nutritional Products. Cargill Media Center.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the vitamin supplement market in 2026 and what is forecast for 2036?
- Which proactive wellness habits support steady demand for vitamin supplements?
- Why do fine powder & micronized crystals lead the form / physical state category?
- Why does conventional farm source lead the source / nature category globally?
- How do growth rates prominently differ across Canada, South Korea, Japan, and the USA?
- Which leading life science companies supply bulk vitamin actives and formulations today?
- What limits active vitamin stability or cleanroom tableting in the vitamin supplement market?
- What should supplement brand managers evaluate deeply before purchasing vitamin ingredients?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Form / Physical State, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Form / Physical State, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Form / Physical State, 2026 to 2036
- Fine Powder & Micronized Crystals
- Liquid Extract & Tincture
- Standardized Granules & Pellets
- Y-o-Y Growth Trend Analysis By Form / Physical State, 2021 to 2025
- Absolute $ Opportunity Analysis By Form / Physical State, 2026 to 2036
- Global Market Analysis and Forecast, By Source / Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source / Nature, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source / Nature, 2026 to 2036
- Conventional Farm Source
- Certified Organic & Non-GMO
- Fermentation / Bio-Synthesized
- Y-o-Y Growth Trend Analysis By Source / Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Source / Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Application Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application Sector, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application Sector, 2026 to 2036
- Dietary Supplements & Nutraceuticals
- Functional Food & Beverages
- Cosmetics & Topical Personal Care
- Animal Nutrition
- Y-o-Y Growth Trend Analysis By Application Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By Application Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- B2B Direct Industrial Food Manufacturers
- Retail Packaged Health Stores
- Online DTC Brands
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Switzerland
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- DSM-Firmenich
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Archer Daniels Midland Company (ADM)
- Cargill, Incorporated
- Roquette Freres
- Ingredion Incorporated
- Tate & Lyle PLC
- Kerry Group plc
- International Flavors & Fragrances (IFF)
- Givaudan SA
- Bunge Global SA
- DSM-Firmenich
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Form / Physical State, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Source / Nature, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Application Sector, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Form / Physical State, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Source / Nature, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Application Sector, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Form / Physical State, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Source / Nature, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Application Sector, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Billion) Forecast by Form / Physical State, 2021 to 2036
- Table 18: Western Europe Market Value (USD Billion) Forecast by Source / Nature, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Application Sector, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Billion) Forecast by Form / Physical State, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Billion) Forecast by Source / Nature, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Billion) Forecast by Application Sector, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 26: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Billion) Forecast by Form / Physical State, 2021 to 2036
- Table 28: East Asia Market Value (USD Billion) Forecast by Source / Nature, 2021 to 2036
- Table 29: East Asia Market Value (USD Billion) Forecast by Application Sector, 2021 to 2036
- Table 30: East Asia Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Billion) Forecast by Form / Physical State, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Billion) Forecast by Source / Nature, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Billion) Forecast by Application Sector, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Billion) Forecast by Form / Physical State, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Billion) Forecast by Source / Nature, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Billion) Forecast by Application Sector, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Form / Physical State, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Form / Physical State, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Form / Physical State
- Figure 6: Global Market Value Share and BPS Analysis by Source / Nature, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Source / Nature, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Source / Nature
- Figure 9: Global Market Value Share and BPS Analysis by Application Sector, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Application Sector, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Application Sector
- Figure 12: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Sales Channel
- Figure 15: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Form / Physical State, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Form / Physical State, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Form / Physical State
- Figure 29: North America Market Value Share and BPS Analysis by Source / Nature, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Source / Nature, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Source / Nature
- Figure 32: North America Market Value Share and BPS Analysis by Application Sector, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Application Sector, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Application Sector
- Figure 35: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Sales Channel
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Form / Physical State, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Form / Physical State, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Form / Physical State
- Figure 42: Latin America Market Value Share and BPS Analysis by Source / Nature, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Source / Nature, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Source / Nature
- Figure 45: Latin America Market Value Share and BPS Analysis by Application Sector, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Application Sector, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Application Sector
- Figure 48: Latin America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Sales Channel
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Form / Physical State, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Form / Physical State, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Form / Physical State
- Figure 55: Western Europe Market Value Share and BPS Analysis by Source / Nature, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by Source / Nature, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by Source / Nature
- Figure 58: Western Europe Market Value Share and BPS Analysis by Application Sector, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by Application Sector, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by Application Sector
- Figure 61: Western Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Sales Channel
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Form / Physical State, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Form / Physical State, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Form / Physical State
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by Source / Nature, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by Source / Nature, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by Source / Nature
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by Application Sector, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by Application Sector, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by Application Sector
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by Sales Channel
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Form / Physical State, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Form / Physical State, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Form / Physical State
- Figure 81: East Asia Market Value Share and BPS Analysis by Source / Nature, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by Source / Nature, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by Source / Nature
- Figure 84: East Asia Market Value Share and BPS Analysis by Application Sector, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by Application Sector, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by Application Sector
- Figure 87: East Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by Sales Channel
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by Form / Physical State, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by Form / Physical State, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by Form / Physical State
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by Source / Nature, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by Source / Nature, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by Source / Nature
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by Application Sector, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by Application Sector, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by Application Sector
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by Sales Channel
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by Form / Physical State, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by Form / Physical State, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by Form / Physical State
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by Source / Nature, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by Source / Nature, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by Source / Nature
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by Application Sector, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by Application Sector, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by Application Sector
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by Sales Channel
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Vitamin Supplement Market in 2026, and what is forecast for 2036?
Future Market Insights estimates that the global vitamin supplement market will reach USD 58.0 Billion in 2026. The market is projected to reach USD 108.9 Billion by 2036, driven by rising consumer focus on preventative healthcare routines and daily micronutrient nutrition.
What is the CAGR for the Vitamin Supplement Market from 2026 to 2036?
As per FMI, the market is projected to expand at a 6.5% CAGR over the assessment period. Growth is supported by ongoing product formulation into pleasant gummy formats, liposomal delivery systems, and vegan active sources.
Which form / physical state segment leads the Vitamin Supplement Market?
Future Market Insights projects that fine powder & micronized crystals will hold 54.4% share in 2026. The segment benefits from uniform particle distribution, high compressibility on rotary tablet presses, and dependable two-piece capsule filling.
Which source / nature segment leads the Vitamin Supplement Market?
Nutraceutical industry research indicates that conventional farm source will account for 46.1% share in 2026. Demand is supported by agricultural glucose fermentation scale, botanical tocopherol extraction, and competitive bulk production economics.
Which country has a notable growth outlook during the assessment period?
FMI finds that Canada is projected to register a 7.9% CAGR from 2026 to 2036. High market growth is supported by strong Natural Health Product regulatory standards, high consumer demand for winter vitamin D, and expanding organic health retail channels.
Who are the key players in the market?
Key participants include DSM-Firmenich, Archer Daniels Midland Company (ADM), Cargill, Incorporated, Kerry Group plc, Ingredion Incorporated, Roquette Freres, Tate & Lyle PLC, International Flavors & Fragrances (IFF), Givaudan SA, and Bunge Global SA. Leading market participants focus on automated bio-fermentation, microencapsulation protection, and clean-label gummy excipients.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
