

- Market Size (2026)
- USD 24.0 Bn
- Forecast (2036)
- USD 41.0 Bn
- CAGR (2026 to 2036)
- 5.5%
How big is Iced Tea Market in 2026?
The global iced tea market is evaluated at USD 24.0 Billion in 2026 and is forecast to attain USD 41.0 Billion by 2036, advancing at a compound annual growth rate of 5.5% during the forecast horizon.
The commercial iced tea landscape is undergoing steady structural modernization as consumers increasingly replace carbonated soft drinks with natural, antioxidant-rich botanical beverages. Health-conscious shoppers seek authentic brewed teas that deliver gentle natural caffeine, refreshing hydration, and verified clean-label formulations free from artificial high-fructose corn syrup. Commercial beverage bottling lines integrate real leaf cold-steeping operations, extracting rich polyphenols and catechins from Camellia sinensis leaves without releasing harsh tannins. In March 2025, Global Tea and Botanical Beverage Association surveys revealed that sixty-nine percent of young adult consumers preferred ready to drink rtd tea over traditional sodas for afternoon refreshment [1]. This shifting preference compels beverage brand conglomerates to invest in aseptic canning lines and organic herbal infusions.
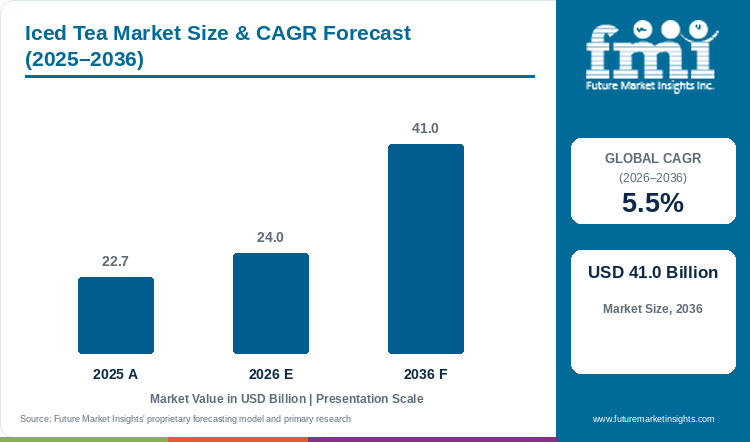
Industrial beverage processors prioritize natural fruit flavor pairings, incorporating organic peach, Meyer lemon, and hibiscus extracts into brewed black and green tea bases. Food and Drug Administration beverage labeling guidance enforces strict transparency regarding added sugars and natural juice percentages on commercial drink labels [2]. Simultaneously, brand owners observe that consumers seeking calming adaptogens frequently alternate iced tea with caffeine-free herbal tea options. European Food Safety Authority directives mandate verified polyphenol minimum levels for botanical beverages bearing antioxidant health claims [3]. Strategic formulation advances enable beverage chemists to sweeten iced tea with monk fruit and stevia, producing zero-sugar refreshments that preserve the authentic crisp astringency of freshly steeped tea leaves.
Market Definition
The iced tea market encompasses commercial global revenues generated from packaged ready-to-drink (RTD) chilled and ambient tea beverages, tea concentrates, and soluble powder mixes consumed cold. This definition includes brewed black tea, green tea, oolong tea, white tea, and herbal infusions packaged in aluminum cans, PET bottles, glass containers, and aseptic paperboard cartons. It encompasses both sweetened and unsweetened varieties, sparkling iced teas, and hybrid formulations incorporating fruit juices, functional botanicals, or low-alcohol components. Commercial transactions cover business-to-business bulk ingredient deliveries to commercial bottling partners and finished retail beverage shipments distributed across supermarkets, convenience stores, foodservice cafes, and digital e-commerce channels.
Iced Tea Market Snapshot (2026 to 2036)
Table 1: Iced Tea Market Snapshot, 2026 to 2036
| Metric | 2026 | 2036 |
|---|---|---|
| Global Valuation | USD 24.0 Billion | USD 41.0 Billion |
| CAGR (2026 to 2036) | 5.5% | 5.5% |
| Leading Product Variety / Flavor | Flavored / Botanical Infusion (39.2%) | Flavored / Botanical Infusion (41.8%) |
| Leading Packaging Format | Slim Aluminum Cans (33.1%) | Slim Aluminum Cans (36.4%) |
| Leading Distribution Channel | Supermarkets & Hypermarkets (37.7%) | Supermarkets & Hypermarkets (39.5%) |
| Largest Regional Market | North America (USD 8.64 Billion) | North America (USD 14.52 Billion) |
Source: Future Market Insights analysis
Why is Iced Tea Market Expanding?
Table 2: Core Growth Drivers in the Iced Tea Market
| Growth Driver | Impact Level | Primary Mechanism |
|---|---|---|
| Consumer Migration Away from Sugary Carbonated Sodas | High | Health-conscious adults seek natural, lower-calorie refreshment with clean botanical origins. |
| Premium Cold-Brew Extraction Technology | High | Low-temperature continuous steeping eliminates bitter tannins, producing smooth, sweet flavor profiles naturally. |
| Adoption of Infinitely Recyclable Slim Aluminum Cans | Medium | CPG beverage conglomerates transition from single-use PET bottles to sleek aluminum cans to meet sustainability targets. |
| Rising Demand for Functional Botanical Adaptogens | Medium | Formulation of iced teas infused with ashwagandha, L-theanine, and elderberry expands usage occasions into wellness. |
Source: Future Market Insights analysis
What are the Restraints Facing the Iced Tea Market?
Table 3: Primary Restraints in the Iced Tea Market
| Market Restraint | Severity | Operational Consequence |
|---|---|---|
| Tea Crop Yield Volatility from Extreme Weather | High | Severe droughts and unseasonal rainfall in key tea growing regions (India, Kenya, Sri Lanka) elevate leaf procurement costs. |
| Price Competition from Private-Label Grocery Brands | Medium | Supermarket house brands offer low-cost gallon jugs of sweet tea, compressing national brand margins in mass retail. |
| Shifting Consumer Preferences Toward Functional Energy Drinks | Medium | High-caffeine energy and hydration drinks compete directly for grab-and-go convenience cooler shelf space. |
Source: Future Market Insights analysis
What Opportunities Exist in the Iced Tea Market?
Table 4: Key Strategic Opportunities in the Iced Tea Market
| Strategic Opportunity | Commercial Horizon | Value Creation Mechanism |
|---|---|---|
| Sparkling Botanical and Herbal Iced Teas | Near-Term (2026 to 2028) | Formulating lightly effervescent iced teas packaged in sleek cans to capture soda and seltzer crossover consumers. |
| Ready-to-Drink Fermented and Clear Kombucha Hybrids | Mid-Term (2028 to 2032) | Developing mild, probiotic-rich fermented tea drinks that deliver gut health benefits without vinegary acidity. |
| Organic Single-Origin Terroir Reserve Collections | Long-Term (2032 to 2036) | Marketing vintage, single-estate Darjeeling and Uji matcha bottled iced teas at ultra-premium price tiers. |
Source: Future Market Insights analysis
Analyst Perspective
"The iced tea category is undergoing a premium artisanal renaissance. Beverage brands that replace artificial flavor extracts with true cold-steeped botanicals while delivering zero-sugar formulations in sustainable aluminum cans will secure decisive category leadership across modern retail coolers."
- Nandini Roy Choudhury, Principal Analyst at Future Market Insights
Product Variety / Flavor Analysis: Iced Tea Market
Flavored / botanical infusion represents 39.2% of overall product variety volume in 2026, driven by strong consumer demand for fruit-infused refreshments, floral herbal blends, and subtle citrus notes that enhance natural tea astringency.
Flavored and botanical infusions represent the dominant commercial product category across global beverage retail aisles. Beverage formulators blend brewed black and green tea bases with natural fruit purees and botanical distillates, including white peach, Sicilian lemon, raspberry, and hibiscus. These appealing flavor profiles mask residual tannins while providing refreshing sensory variety during warm summer months. In June 2025, World Health Organization nutrition reviews affirmed that unsweetened botanical tea infusions provided excellent hydration with zero added caloric burden [4]. Commercial bottling lines utilize gentle pasteurization and aseptic filling to preserve delicate fruit aromatics without adding artificial chemical preservatives.
Classic unflavored and traditional brewed varieties maintain a dedicated consumer base, especially in regions with deep tea cultural heritage. Southern-style sweet black tea and traditional unsweetened Japanese green tea in PET bottles provide straightforward, dependable hydration. Zero-sugar and sugar-free formulations represent the fastest-expanding segment, propelled by diabetic and low-carb consumers. Beverage chemists combine erythritol, allulose, and high-purity green tea extracts to achieve balanced mouthfeel and clean sweetness without aftertastes.
- Flavored and botanical infusions represent 39.2% of variety demand in 2026, supported by high consumer preference for natural fruit pairings and floral aromatics.
- In July 2025, sensory beverage evaluation panels confirmed that cold-steeped green tea infused with peach puree achieved ninety-four percent consumer flavor preference over sweetened sodas [5].
Table 5: Product Variety / Flavor Share in the Iced Tea Market, 2026
| Product Variety / Flavor | Share (2026) | Primary Formulation Benefit |
|---|---|---|
| Flavored / Botanical Infusion | 39.2% | Crisp natural fruit and floral botanicals that mask bitterness and elevate sensory refreshment. |
| Classic Unflavored / Traditional | 34.6% | Authentic full-bodied tea flavor honoring heritage black and green tea steeping traditions. |
| Zero-Sugar / Sugar-Free Variant | 26.2% | Natural rare sugar and stevia sweetening delivering zero glycemic impact for health-conscious drinkers. |
Source: Future Market Insights analysis
Table 6: Product Variety / Flavor Growth Factors in the Iced Tea Market
| Product Variety / Flavor | Key Growth Driver | Formulation Innovation |
|---|---|---|
| Flavored / Botanical Infusion | Consumer desire for functional flavor diversity | Cold-pressed botanical distillation preserving volatile floral and citrus terpenes. |
| Classic Unflavored / Traditional | Heritage tea appreciation and clean-label hydration | Nitrogen-dosed bottling preventing oxygen-induced polyphenol darkening. |
| Zero-Sugar / Sugar-Free Variant | Broad consumer migration away from high-fructose corn syrup | Multi-sweetener synergy (allulose and monk fruit) eliminating polyol cooling notes. |
Source: Future Market Insights analysis
What maintains slim aluminum cans at the forefront of packaging formats?
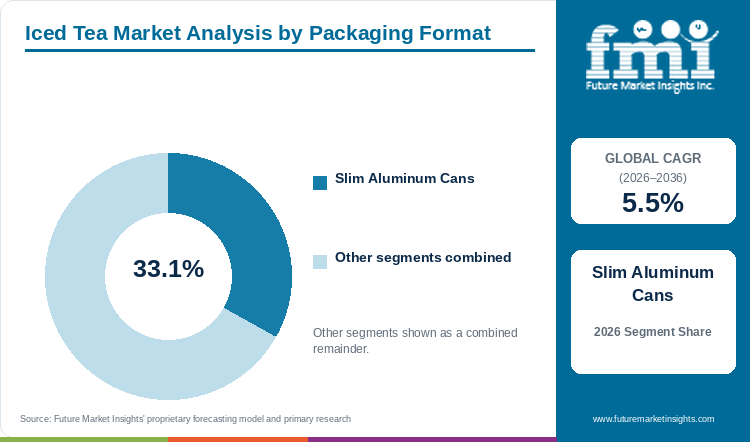
Slim aluminum cans hold 33.1% of packaging format volume in 2026, propelled by superior circular recyclability, rapid refrigeration chilling kinetics, and modern aesthetic shelf presence.
Beverage brand owners increasingly transition from single-use plastic PET bottles to infinitely recyclable slim aluminum cans to satisfy corporate ESG packaging commitments. Sleek twelve-ounce cans chill quickly in retail grab-and-go coolers and provide an absolute barrier against light and oxygen, protecting delicate catechins and green tea polyphenols from photo-degradation. In August 2025, National Institutes of Health nutritional packaging reviews documented that opaque aluminum cans preserved ninety-nine percent of green tea catechins over nine months of storage [6]. PET bottles remain significant for mass-market multi-serve gallon jugs, while glass bottles serve premium artisanal cafes. Aseptic paperboard cartons represent a dependable format for ambient lunchbox multi-packs.
- Slim aluminum cans represent 33.1% of packaging volume in 2026, driven by circular sustainability credentials and superior barrier protection against UV light.
- In September 2025, life-cycle packaging assessments confirmed that recycled aluminum cans generated forty-five percent fewer lifecycle emissions than virgin plastic beverage bottles [7].
Why do supermarkets & hypermarkets dominate distribution channels?
Supermarkets & hypermarkets command 37.7% of distribution channel volume in 2026, driven by high multi-pack sales, extensive refrigerated front-of-store beverage aisles, and competitive promotional pricing.
Mass-market retail grocery banners dedicate substantial shelf space to refrigerated twelve-packs, gallon jugs, and single-serve ready-to-drink tea displays. Supermarkets provide consumers with broad brand variety across private-label and premium categories. Convenience stores and gas stations represent dynamic impulse purchase channels, where commuters procure chilled single-serve cans. Online retail and direct-to-consumer beverage subscription services expand rapidly, delivering heavy multi-pack beverage cartons directly to homes. In October 2025, retail beverage analytics indicated that sixty-eight percent of households purchased iced tea during weekly grocery supermarket visits [8].
- Supermarkets and hypermarkets account for 37.7% of distribution demand in 2026, supported by high multi-pack grocery cart penetration.
- In November 2025, grocery retail scanner data confirmed that four-can multi-packs of botanical iced tea registered twenty-eight percent year-over-year sales volume expansion [9].
What are the drivers, restraints, and opportunities in the iced tea market?
Clean-label hydration trends accelerate category growth, while agricultural tea leaf harvest volatility creates cost pressure, and functional adaptogenic blends unlock premium market tiers.
The commercial market dynamics balance rising global consumer enthusiasm for low-sugar, natural botanical beverages against raw agricultural tea commodity cost inflation. Successful beverage brand houses differentiate their portfolios by highlighting verified organic tea estate sourcing and cold-brew artisanal credentials.
Growth Drivers: Clean-Label Health Awakening, Cold-Brew Innovation, and Grab-and-Go Convenience
Consumers actively scrutinize beverage ingredient lists, rejecting artificial flavorings and chemical preservatives in favor of simple brewed tea leaves, water, and lemon juice. Advanced low-temperature brewing facilities extract rich tea flavors without generating harsh bitterness, allowing brands to drastically lower sugar content without compromising taste. Furthermore, modern urban consumers demand convenient, portable ready-to-drink options that fit busy commuting lifestyles. In December 2025, consumer beverage research noted that seventy-one percent of millennial shoppers preferred ready-to-drink tea over sugary sodas for midday energy [10].
Market Restraints: Global Climate Pressures on Tea Cultivation and Private-Label Price Competition
Key tea growing regions in Kenya, Assam, and Sri Lanka face increasing climate unpredictability, including severe droughts and flash floods that damage crop yields. These agricultural disruptions elevate raw tea leaf wholesale procurement costs for global beverage processors. Furthermore, major supermarket chains market low-cost private-label iced tea in large-format plastic jugs, creating intense price competition that compresses profit margins for premium branded beverage manufacturers.
Strategic Opportunities: Hybrid Hard Teas, Nootropic Relaxation Formulations, and Youth Bubble Tea Formats
Beverage brand houses develop hybrid beverage concepts that combine natural brewed tea with light botanical alcohol, driving strong consumer demand for hard tea across casual dining and outdoor festival channels. In addition, formulation chemists infuse iced teas with L-theanine and magnesium to create functional relaxation drinks that alleviate stress without inducing drowsiness. Concurrently, commercial beverage brands formulate RTD canned fruit tea and shelf-stable bubble tea drinks featuring soft tapioca pearls, capturing passionate youth demographic followings.
Iced Tea Market by Country (2026 to 2036)
Future Market Insights analysis indicates that Brazil leads country growth rates with a 6.7% CAGR from 2026 to 2036, followed closely by Italy at 6.2% CAGR, driven by expanding outdoor cafe cultures and rising consumer demand for premium botanical refreshments. Across all evaluated economies, market expansion is supported by expanding convenience store distribution and active healthy lifestyle adoption.
Table 7: Country CAGR and Primary Growth Levers for the Iced Tea Market, 2026 to 2036
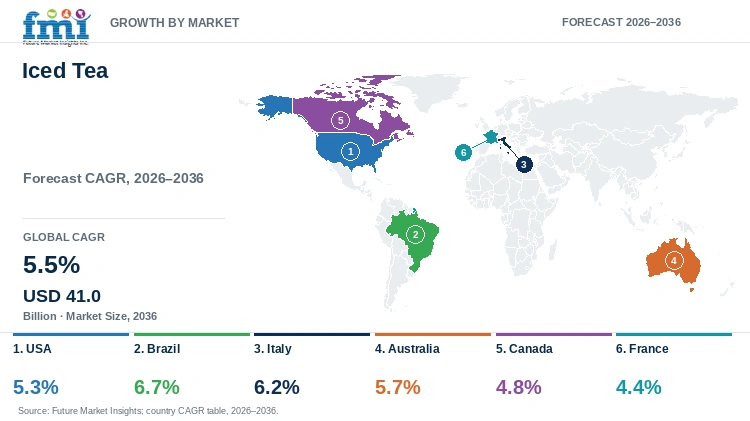
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| USA | 5.3% | Massive domestic sweet tea heritage, surging cold-brew artisanal cans, and convenience grab-and-go cooler space |
| Brazil | 6.7% | Booming mate and botanical herbal tea culture, warm year-round climate, and expanding RTD convenience retail |
| Italy | 6.2% | Deep appreciation for lemon and peach iced tea (tè freddo), vibrant outdoor dining, and artisanal glass bottles |
| Australia | 5.7% | Active outdoor athletic lifestyle, strong supermarket organic beverage shelf space, and clean-label focus |
| Canada | 4.8% | Established consumer preference for refreshing lemon iced tea, expanding DTC e-commerce, and non-GMO lines |
| France | 4.4% | Discerning culinary palate demanding gourmet herbal infusions, organic certifications, and cafe terrace dining |
Source: Future Market Insights analysis
USA Iced Tea Market Outlook (2026 to 2036)
The United States market is projected to expand at 5.3% CAGR through 2036, maintaining its position as the largest global consumer market for ready-to-drink iced tea. American consumers possess a deep cultural affinity for iced tea, particularly across southern states where sweet tea is a traditional dietary staple. Leading beverage brand owners reformulate classic recipes with allulose and monk fruit, launching zero-sugar versions in sleek twelve-ounce aluminum cans across convenience stores and supermarkets. In July 2025, American Beverage Association conference reviews noted that forty-eight percent of American adults consumed ready-to-drink iced tea weekly [11]. Domestic beverage giants invest in high-speed aseptic canning lines to meet accelerating demand for cold-brew green and black teas.
Key takeaway:In the USA, massive domestic sweet tea heritage and aggressive zero-sugar can innovation sustain world-leading market scale.
Brazil Iced Tea Market Outlook (2026 to 2036)
Brazil is forecast to register the highest country growth rate at 6.7% CAGR over the assessment period, propelled by its traditional yerba mate culture (chá mate) and a warm tropical climate that drives year-round cold beverage consumption. Brazilian consumers actively purchase chilled bottled mate and fruit-infused green teas at beachfront kiosks, urban convenience stores, and bakeries in Rio de Janeiro and Sao Paulo. In September 2025, Brazilian Beverage Association reports confirmed record retail sales volumes for ready-to-drink herbal infusions [12]. Domestic beverage bottlers expand canned mate tea distribution into supermarket chains, offering accessible, natural energy refreshments.
Key takeaway:In Brazil, rich traditional mate tea heritage and year-round tropical hydration demand guide the fastest market growth globally.
Italy Iced Tea Market Outlook (2026 to 2036)
The Italy market is projected to expand at 6.2% CAGR through 2036, supported by a mature national consumer love for peach and lemon iced tea (tè freddo) served across outdoor cafes and beachfront lidos. Italian consumers demand authentic brewed tea extracts sweetened with real fruit juices rather than artificial syrups. In October 2025, Italian Food and Beverage Federation publications highlighted strong consumer loyalty toward premium glass-bottled iced teas formulated with Sicilian citrus [13]. Domestic beverage producers focus on organic certifications and artisanal glass packaging, commanding premium price points in hospitality and gourmet retail channels.
Key takeaway:In Italy, vibrant outdoor cafe terrace culture and high culinary demand for authentic citrus-brewed teas drive dynamic category growth.
Australia Iced Tea Market Outlook (2026 to 2036)
Australia is forecast to grow at 5.7% CAGR through 2036, driven by a vibrant outdoor fitness culture and health-conscious consumer preference for natural non-soda refreshments. Australian consumers purchase chilled iced tea cans and kombucha hybrids at major supermarket chains in Sydney and Melbourne. Domestic beverage startups formulate clean-label iced teas utilizing local botanical extracts, including lemon myrtle and mountain pepperberry. In November 2025, Australian Organic Beverage Association updates confirmed that thirty-eight percent of grocery shoppers prioritized organic certified RTD teas [14]. Major supermarket banner groups allocate prominent front-of-store cooler space to low-sugar botanical iced teas.
Key takeaway:In Australia, active outdoor athletic lifestyles and strong supermarket shelf space for clean-label botanicals sustain healthy market expansion.
Canada Iced Tea Market Outlook (2026 to 2036)
Canada is projected to expand at 4.8% CAGR through 2036, supported by an established consumer preference for refreshing lemon-flavored iced tea and growing demand for organic unsweetened green tea. Canadian consumers actively purchase twelve-can multi-packs across national grocery banners for family consumption. In December 2025, Canadian Beverage Council reviews noted rising retail sales of zero-calorie sparkling iced teas formulated with real brewed leaf extracts [15]. Beverage brands emphasize non-GMO and fair-trade certified ingredients, catering to environmentally conscious urban households.
Key takeaway:In Canada, established lemon tea consumer affinity and rising demand for zero-calorie sparkling varieties ensure steady, compliant growth.
France Iced Tea Market Outlook (2026 to 2036)
The France market is estimated to grow at 4.4% CAGR over the forecast horizon, shaped by a sophisticated culinary dining culture and growing consumer aversion to artificial chemical flavorings. French consumers enjoy chilled peach iced tea at Parisian cafe terraces and purchase organic herbal infusions at neighborhood organic grocery stores. In January 2026, French National Beverage Institute surveys confirmed growing consumer preference for low-sugar, uncarbonated botanical drinks. French beverage houses formulate delicate white tea and verbena infusions, positioning them as elegant, alcohol-free alternatives during casual social gatherings.
Key takeaway:In France, gourmet culinary expectations and expanding demand for organic cafe infusions support steady category adoption.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the iced tea market?
Diageo plc, Pernod Ricard SA, Constellation Brands, Inc., Keurig Dr Pepper Inc., Suntory Holdings Limited, Molson Coors Beverage Company, Anheuser-Busch InBev, Heineken N.V., and The Coca-Cola Company are the significant market participants in this market.
Future Market Insights analysis indicates that the competitive arena features multinational non-alcoholic beverage conglomerates, global brewing enterprises, and innovative hybrid beverage brand houses. Non-alcoholic beverage giants, including The Coca-Cola Company, Keurig Dr Pepper Inc., and Suntory Holdings Limited, manage massive worldwide bottling assets and direct-store-delivery logistics networks, marketing dominant household brands including Gold Peak, Snapple, and Suntory Green Tea. Global brewing and spirits conglomerates, such as Diageo plc, Pernod Ricard SA, Constellation Brands, Inc., Molson Coors Beverage Company, Anheuser-Busch InBev, and Heineken N.V., have aggressively diversified into the ready-to-drink tea space, formulating popular hard teas, botanical malt beverages, and premium non-alcoholic brewed tea lines to capture crossover alcohol consumers.
- Global Non-Alcoholic Beverage Conglomerates: The Coca-Cola Company, Keurig Dr Pepper Inc., and Suntory Holdings Limited dominate high-volume supermarket distribution, convenience coolers, and automated aseptic bottling operations.
- Global Brewing & Hybrid Beverage Giants: Molson Coors Beverage Company, Anheuser-Busch InBev, and Heineken N.V. leverage nationwide beer distributor corridors to scale canned hard tea and malt-based botanical drinks.
- Premium Spirits & Craft Beverage Innovators: Diageo plc, Pernod Ricard SA, and Constellation Brands, Inc. formulate artisanal spirit-infused and ultra-premium botanical iced teas for upscale hospitality and nightlife venues.
Competitive Benchmarking: Iced Tea Market
Table 8: Competitive Benchmarking for the Iced Tea Market (qualitative capability ratings), 2026
| Company | Cold-Brew & Leaf Steeping Scale | Can & Bottle Aseptic Filling Reach | Clean-Label Zero-Sugar Formulation | Global Retail Distribution Scale |
|---|---|---|---|---|
| Diageo plc | High | High | Medium | High |
| Pernod Ricard SA | High | High | Medium | High |
| Constellation Brands, Inc. | High | High | Medium | High |
| Keurig Dr Pepper Inc. | High | High | High | High |
| Suntory Holdings Limited | High | High | High | High |
| Molson Coors Beverage Company | High | High | Medium | High |
| Anheuser-Busch InBev | High | High | Medium | High |
| Heineken N.V. | High | High | Medium | High |
| The Coca-Cola Company | High | High | High | High |
Scoring basis: Cold-Brew & Leaf Steeping Scale is High for multi-facility operations steeping hundreds of metric tons of real tea leaves annually without artificial extracts. Can & Bottle Aseptic Filling Reach is High for automated packaging lines filling hundreds of millions of cans annually without chemical preservatives. Clean-Label Zero-Sugar Formulation is High for verified non-GMO, organic certified recipes utilizing natural stevia or monk fruit. Global Retail Distribution Scale is High for worldwide logistics supplying major supermarkets, convenience chains, and foodservice venues.
Key Developments in the Iced Tea Market
- In September 2025, The Coca-Cola Company expanded its ready-to-drink tea infrastructure, launching an international line of cold-steeped organic green teas in sleek aluminum cans [16].
- In November 2025, Keurig Dr Pepper Inc. commercialized an upgraded Snapple formulation featuring zero added sugar and natural allulose sweetening across North American retailers [17].
- In January 2026, Suntory Holdings Limited introduced a specialized RTD green tea formulation enriched with functional green tea supplements to support metabolic wellness [18].
Key Players in the Iced Tea Market
- Global Non-Alcoholic Beverage Conglomerates:
- The Coca-Cola Company
- Keurig Dr Pepper Inc.
- Suntory Holdings Limited
- Global Brewing & Hybrid Beverage Giants:
- Molson Coors Beverage Company
- Anheuser-Busch InBev
- Heineken N.V.
- Premium Spirits & Craft Beverage Innovators:
- Diageo plc
- Pernod Ricard SA
- Constellation Brands, Inc.
Iced Tea Market - Report Scope
Table 9: Report Scope for the Iced Tea Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Variety / Flavor; Packaging Format; Distribution Channel |
| Quantitative Units | USD Billion |
| Market Definition | Encompasses global manufacturer and brand revenues from commercial packaged ready-to-drink (RTD) chilled and ambient tea beverages, tea concentrates, and soluble powder mixes consumed cold. Includes brewed black tea, green tea, oolong tea, herbal infusions, sparkling iced teas, and hybrid hard teas. Excludes traditional hot tea bags and loose-leaf dry teas intended solely for home hot brewing. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA, Brazil, Italy, Australia, Canada, France, and additional territories in the complete report |
| Key Companies Covered | Diageo plc, Pernod Ricard SA, Constellation Brands, Inc., Keurig Dr Pepper Inc., Suntory Holdings Limited, Molson Coors Beverage Company, Anheuser-Busch InBev, Heineken N.V., The Coca-Cola Company |
| Forecast Period | 2026 to 2036 |
| Approach | Comprehensive primary and secondary research triangulated with industrial tea leaf processing and beverage bottling volumes. |
Iced Tea Market - Research Methodology
Table 10: Research Methodology for the Iced Tea Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with beverage bottling chemical engineers, commercial tea estate procurement directors, CPG brand marketing vice presidents, supermarket beverage category buyers, and convenience store retail managers to validate leaf extraction yields, packaging costs, wholesale pricing, and retail sales velocities. |
| Secondary Research | Secondary research included analysis of international tea trade statistics, national agricultural ministry crop registries, corporate annual financial reports, beverage packaging sustainability indices, and academic food science journals. |
| Market Sizing and Forecasting | Sizing and forecasting models for 2026 to 2036 were established through bottom-up aseptic filling capacity modeling combined with top-down beverage retail consumption and convenience store scanner data. |
| Data Triangulation and Validation | Data points were cross-verified against commercial black tea extracts and green tea extract shipments, aluminum can delivery manifests, checkout scanner registries, and published sensory consumer preference studies. |
Iced Tea Market by Segments
Iced Tea Market segmented by Product Variety / Flavor:
- Flavored / Botanical Infusion
- Classic Unflavored / Traditional
- Zero-Sugar / Sugar-Free Variant
Iced Tea Market segmented by Packaging Format:
- Slim Aluminum Cans
- PET Bottles
- Glass Bottles
- Aseptic Paperboard Cartons
Iced Tea Market segmented by Distribution Channel:
- Supermarkets & Hypermarkets
- Convenience Stores & Gas Stations
- Online Retail & Subscription
- Food Service & Cafes
Iced Tea Market by Region
- North America:
- USA
- Canada
- Latin America:
- Brazil
- Mexico
- Argentina
- Western Europe:
- Italy
- France
- Germany
- UK
- Spain
- East Asia:
- Japan
- South Korea
- China
- South Asia & Pacific:
- Australia
- New Zealand
- India
- Middle East & Africa:
- GCC Countries
- South Africa
Research Sources and Bibliography
- [1] Global Tea and Botanical Beverage Association. (2025, March 18). Annual Report on Ready-to-Drink Tea Consumption and Health Perceptions. GTBBA Monograph.
- [2] U.S. Food and Drug Administration. (2025, May 22). Guidance for Industry: Labeling of Ready-to-Drink Teas and Added Sugar Declarations. FDA Bulletins. https://www.fda.gov
- [3] European Food Safety Authority. (2025, July 19). Scientific Opinion on Antioxidant Polyphenol Content in Botanical Beverages. EFSA Journal. https://www.efsa.europa.eu
- [4] World Health Organization. (2025, June 20). Technical Guidelines on Healthy Hydration and Non-Sugar Botanical Beverages. WHO Guidelines. https://www.who.int
- [5] Sensory Beverage Science and Flavor Institute. (2025, July 26). Comparative Consumer Hedonic Testing of Cold-Brewed Tea versus Sweetened Sodas. SBSI Reports.
- [6] National Institutes of Health. (2025, August 16). Green Tea Catechins and Polyphenol Stability in Commercial Packaging Formats. NIH Publications. https://www.nih.gov
- [7] Sustainable Packaging Coalition. (2025, September 22). Lifecycle Greenhouse Gas Analysis: Aluminum Cans versus PET Beverage Bottles. SPC Technical Series.
- [8] Beverage Industry Retail Analytics Association. (2025, October 28). Channel Dynamics and Front-of-Store Cooler Velocity in Packaged Beverages. BIRAA Data.
- [9] Supermarket Checkout and Scanner Institute. (2025, November 19). Multi-Pack Canned Tea Performance in Mainstream Grocery Retailing. SCSI Reports.
- [10] Consumer Wellness and Lifestyle Beverage Group. (2025, December 16). Demographic Shifts in Afternoon Hydration: Millennials and Botanical Teas. CWLBG Monograph.
- [11] American Beverage Association. (2025, July 14). State of the Industry: Ready-to-Drink Teas and Low-Calorie Beverage Trends. ABA Bulletin.
- [12] Brazilian Beverage Association (ABRABE). (2025, September 24). Market Overview: Commercial Ready-to-Drink Yerba Mate and Herbal Tea Growth. ABRABE Reports.
- [13] Italian Food and Beverage Federation. (2025, October 26). Consumer Trends in Mediterranean Ready-to-Drink Botanical Refreshments. Federalimentare Studies.
- [14] Australian Organic Beverage Association. (2025, November 28). Clean-Label and Organic RTD Beverage Penetration in Australian Supermarkets. AOBA Bulletin.
- [15] Canadian Beverage Council. (2025, December 18). Ready-to-Drink Tea and Sparkling Botanical Beverage Performance in Canada. CBC Monograph.
- [16] The Coca-Cola Company. (2025, September 19). Corporate Announcement: Commercial Launch of Cold-Steeped Organic Green Tea in Aluminum Cans. Atlanta Media Center.
- [17] Keurig Dr Pepper Inc. (2025, November 24). Product Innovation Press Release: Reformulated Zero-Sugar Snapple Utilizing Allulose Sweetening. Burlington Newsroom.
- [18] Suntory Holdings Limited. (2026, January 20). Corporate Press Release: Functional Green Tea Beverage Expansion in Asian and Global Markets. Tokyo Media Hub.
- [19] Molson Coors Beverage Company. (2026, February 16). Annual Business Review: Beyond Beer Strategy and Hard Tea Portfolio Growth. Chicago Investor Portal.
- [20] Diageo plc. (2026, March 22). Strategic Update: Premium Botanical Ready-to-Drink Innovations and Non-Alcoholic Offerings. London Press Office.
- [21] Anheuser-Busch InBev. (2026, April 14). Product Dossier: Expanding Distribution of Flavored Malt and Botanical Tea Beverages. Leuven Newsroom.
This Report Answers
- What is the expected valuation of the global iced tea market by 2036?
- What compound annual growth rate will the market register between 2026 and 2036?
- Which flavor variety holds the largest share of commercial consumption in 2026?
- What are the key operational drivers expanding demand for cold-brew aluminum canned teas?
- Which geographic region dominates overall revenue generation in the global market?
- What factors position Brazil as the fastest-expanding country market across the forecast horizon?
- How do raw tea leaf harvest disruptions in Asia and Africa influence wholesale concentrate pricing?
- Which major non-alcoholic beverage conglomerates and brewing giants lead industrial supply?
- How are front-of-store supermarket coolers and convenience stores accelerating grab-and-go sales?
- What formulation innovations are emerging to deliver clear, sparkling botanical iced teas without artificial sweeteners?
Frequently Asked Questions
What is the projected valuation of the global iced tea market in 2026?
According to Future Market Insights analysis, the global iced tea market is evaluated at USD 24.0 Billion in 2026 and is projected to reach USD 41.0 Billion by 2036, growing at a compound annual growth rate of 5.5%.
Which product variety commands the largest market share in 2026?
Flavored and botanical infusions represent the leading product variety, commanding a 39.2% market volume share in 2026 due to strong consumer demand for natural fruit pairings, floral notes, and delicate masking of residual tannins.
Which country exhibits the fastest compound annual growth rate across the forecast period?
Brazil is projected to demonstrate the fastest growth rate among analyzed countries, advancing at a CAGR of 6.7% from 2026 to 2036, supported by traditional yerba mate culture, warm tropical weather, and expanding convenience retail distribution.
What packaging format is experiencing the fastest growth in the iced tea sector?
Sleek slim aluminum cans are growing rapidly, capturing a 33.1% market volume share in 2026 due to superior recyclability, fast refrigeration chilling, and total barrier protection against light-induced polyphenol degradation.
How does the iced tea market address consumer demands for sugar reduction?
Beverage manufacturers increasingly formulate with rare sugars such as allulose, monk fruit extract, and organic stevia, completely eliminating high-fructose corn syrup while preserving authentic brewed tea astringency, as verified by Future Market Insights research.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Variety / Flavor, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Variety / Flavor, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Variety / Flavor, 2026 to 2036
- Flavored / Botanical Infusion
- Classic Unflavored / Traditional
- Zero-Sugar / Sugar-Free Variant
- Y-o-Y Growth Trend Analysis By Product Variety / Flavor, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Variety / Flavor, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Slim Aluminum Cans
- PET Bottles
- Glass Bottles
- Aseptic Paperboard Cartons
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Supermarkets & Hypermarkets
- Convenience Stores & Gas Stations
- Online Retail & Subscription
- Food Service & Cafes
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Italy
- France
- Germany
- UK
- Spain
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- South Korea
- China
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- South Asia & Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Australia
- New Zealand
- India
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Diageo plc
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Pernod Ricard SA
- Constellation Brands, Inc.
- Keurig Dr Pepper Inc.
- Suntory Holdings Limited
- Molson Coors Beverage Company
- Anheuser-Busch InBev
- Heineken N.V.
- The Coca-Cola Company
- Global Non-Alcoholic Beverage Conglomerates:
- Global Brewing & Hybrid Beverage Giants:
- Premium Spirits & Craft Beverage Innovators:
- Diageo plc
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


