

- Market Size (2026)
- USD 5.3 Bn
- Forecast (2036)
- USD 9.3 Bn
- CAGR (2026 to 2036)
- 6.0%
How big is Interesterified Fats Market in 2026?
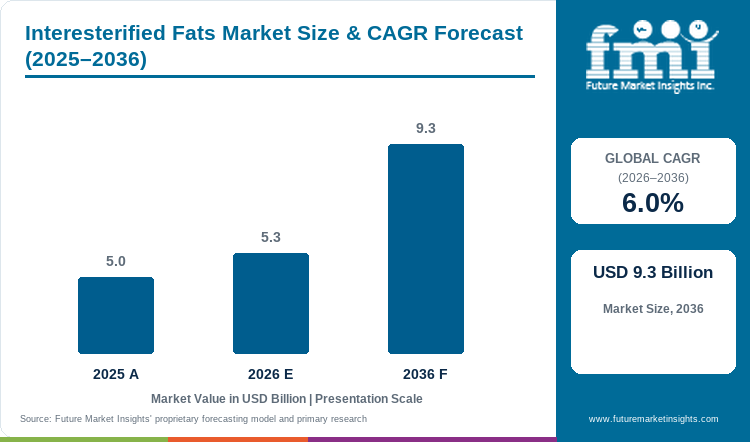
USD 5.3 Billion in 2026 and USD 9.3 Billion by 2036, expanding at 6.0% CAGR.
Demand for interesterified fats is projected to expand at 6.0% CAGR between 2026 and 2036, growing from USD 5.0 Billion in 2025 to USD 5.3 Billion in 2026 and reaching USD 9.3 Billion by 2036. Food manufacturers use interesterification to create defined melting, crystallization and plasticity profiles without depending on partially hydrogenated oils. A 2026 review of structured-lipid synthesis also highlighted enzymatic interesterification as an important route for engineering lipid structure, reinforcing its use where standard liquid oils cannot deliver the required solid-fat behavior.
The growth mechanism differs by country. Mature markets increasingly treat interesterification as an optimization tool rather than a first-generation trans-fat replacement. Bakery, confectionery and spread manufacturers are comparing fats on machinability, aeration, melting behavior and cost-in-use. That purchasing logic overlaps with the wider normal and specialty fats market, where value comes from delivering repeatable functionality under commercial processing conditions.
Key Takeaways of Interesterified Fats Market
- Food manufacturers use interesterified fats to create controlled texture, melting and crystallization profiles without relying on partially hydrogenated oil systems.
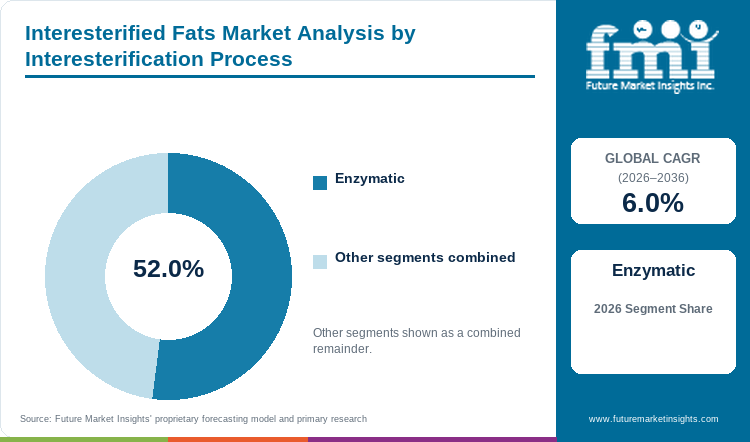
- Enzymatic leads the Interesterification Process category with a 52.0% share in 2026 as selectivity and milder processing support tightly controlled fat properties.
- Palm oil leads Source with a 28.0% share in 2026 because its semi-solid character and fractionation flexibility fit bakery, confectionery and spread formulations.
- Food Processing leads End-Use with a 71.0% share in 2026 as industrial recipes require consistent plasticity, aeration, melt and shelf-life performance.
- Qualification remains a major purchasing constraint because a replacement fat must perform consistently through mixing, cooling, storage and high-throughput production.
- Notable companies include Bunge, Cargill, ADM, Wilmar International Limited, AAK, Fuji Oil Holdings Inc. and Musim Mas Group.
Analyst Perspective
“Interesterified fats win recurring business when the supplier can reproduce a customer's target solid-fat curve under actual production conditions. Feedstock flexibility matters, but application performance and scale-up support ultimately determine whether a new fat replaces an established specification.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Interesterified Fats Market segmented?
Interesterified Fats Market is segmented by Interesterification Process, Source, End-Use, and Region.
Interesterification Process includes Enzymatic, Sodium Methoxide, Potassium Methoxide, Alkaline Catalysts, Polyethylene glycolate and Others. Source includes Palm oil, Soybean oil, Rapeseed oil, Sunflower oil, Other Vegetable oils, Groundnut oil, Cottonseed oil, Coconut oil and Walnut oil. End-Use comprises Food Processing, Pharmaceuticals and Cosmetics and Personal care.
Why does Enzymatic lead demand within the Interesterification Process category?
Enzymatic interesterification gives formulators greater control over where fatty acids are positioned within the triglyceride structure. That precision matters when a bakery or confectionery product requires a narrow melting range, controlled crystallization or a specific solid-fat curve. A 2026 structured-lipid review highlighted process control, enzyme stability and substrate selection as important to achieving high-quality structured fats at scale.
- Enzymatic accounts for 52.0% of Interesterification Process demand in 2026 because selective modification supports tighter control of functional fat properties.
- Commercial economics depend on enzyme stability, reuse and processing efficiency, making production discipline important alongside formulation performance.
Why does Palm oil lead demand within the Source category?
Palm oil starts with a naturally useful semi-solid profile and can be separated into fractions with different melting characteristics. Interesterification gives formulators another tool for adjusting plasticity and crystallization without changing the overall fatty-acid composition. This flexibility is commercially important in bakery shortening, confectionery fillings, spreads and hardstock systems. The same raw-material economics also shape purchasing across the palm oil market, where processing flexibility and traceable sourcing increasingly influence buyer decisions.
- Palm oil accounts for 28.0% of Source demand in 2026 because its hardstock characteristics and fractionation flexibility reduce the processing needed to reach many semi-solid fat specifications.
- AAK reported in April 2025 that 91% of its palm supply was verified deforestation-free and traceability to plantation had reached 97%, showing how functional-fat purchasing increasingly incorporates upstream documentation.
Why does Food Processing lead demand within the End-Use category?
Food processors purchase interesterified fats because texture must remain consistent through high-throughput manufacturing and shelf life. Bakery shortenings need plasticity and aeration. Fillings and coatings require controlled melt. Frying fats require thermal stability, while non-dairy systems need defined structure without undesirable waxiness. These requirements also support demand in the adjacent bakery fat market, where production performance is central to supplier qualification.
- Food Processing represents 71.0% of End-Use demand in 2026 because bakery, confectionery, spreads, fillings, frying and non-dairy applications consume functional fats repeatedly at industrial scale.
- Cargill's current bakery shortening range includes interesterified soybean-oil systems for cake, icing and general bakery applications, illustrating direct commercial use of interesterified fats.
What are the drivers, restraints and opportunities in the Interesterified Fats Market?
Demand is supported by low-trans functional-fat requirements, while application qualification and process economics slow switching. Feedstock-flexible structured fats create room for higher-value formulation work.
- Driver: Food manufacturers require semi-solid fat functionality without returning to partially hydrogenated oil systems.
- Restraint: Alternative fats must pass plant-scale tests for melting behavior, crystallization, aeration, shelf life and sensory neutrality.
- Opportunity: Source-flexible interesterification can support specialized bakery, confectionery, spread and structured-lipid formulations.
Functional performance keeps interesterification relevant after first-generation trans-fat reformulation
The commercial driver is no longer simply the removal of trans fat. Manufacturers still need shortening, margarine, fillings and other fat systems that hold structure during production and then melt correctly during consumption. Interest in optimized solid-fat curves therefore continues even in markets where trans-fat reformulation is mature. The same requirement is visible in the margarine market, where semi-solid performance remains fundamental to industrial use.
Cargill and ADM continue to offer interesterified soybean, palm and mixed-oil systems for bakery, icing, frying and non-dairy applications. These portfolios show why interesterification remains commercially relevant: the process allows the supplier to start with a different oil base while targeting a specific finished-fat performance.
Plant-scale qualification slows switching between functional fats
Interesterification changes triglyceride distribution, so two fats with similar fatty-acid composition can behave differently in cooling, mixing and storage. Shifts in crystal structure affect aeration and machinability; melt profile changes carry through to mouthfeel and flavor release. A 2026 review of enzymatic structured-lipid synthesis identified operational enzyme stability as an important scale-up consideration.
This makes qualification expensive enough to protect incumbent suppliers. A lower ingredient price has limited value if the replacement requires longer mixing, produces unstable crystals or changes finished-product texture. Suppliers therefore need pilot and application support that reduces the number of production trials required before routine purchasing begins.
Feedstock flexibility creates higher-value formulation opportunities
Interesterification allows suppliers to work with palm, soybean, sunflower and other vegetable-oil systems rather than rely on a single hardstock architecture. This gives manufacturers more options when they need to manage raw-material pricing, sourcing policies or application-specific melting profiles.
Confectionery creates a particularly demanding use case because snap, gloss, melt and bloom stability are sensitive to fat structure. These requirements connect interesterification with the broader confectionery fats market. Musim Mas Group's recent specialty-fat work using enzymatic interesterification illustrates how suppliers are applying the technology beyond conventional shortening into tightly engineered confectionery systems.
Which country CAGRs are profiled in the Interesterified Fats Market?
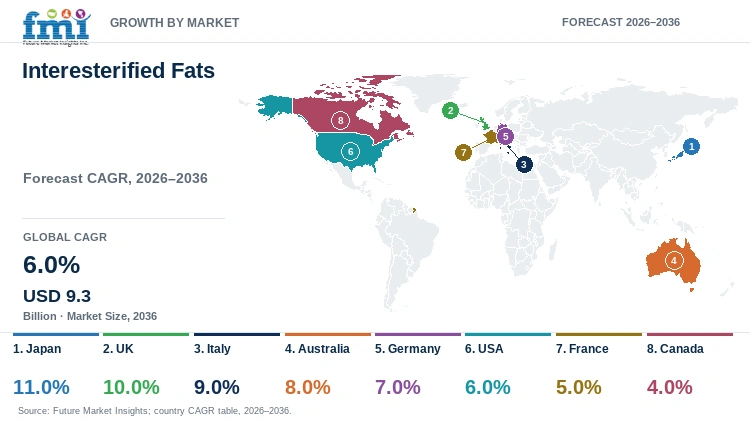
| Country | CAGR |
|---|---|
| Japan | 11.0% |
| UK | 10.0% |
| Italy | 9.0% |
| Australia | 8.0% |
| Germany | 7.0% |
| USA | 6.0% |
| France | 5.0% |
| Canada | 4.0% |
How do country-level CAGRs compare in the Interesterified Fats Market?
Japan, the UK and Italy form the fastest-growth group, followed by Australia and Germany. The USA, France and Canada show more measured expansion. The difference between Japan at 11.0% and Canada at 4.0% is 7.0 percentage points. These figures represent forecast growth pace rather than absolute country market size.
- Japan's market increasingly depends on structured-lipid functionality and technical differentiation rather than basic trans-fat replacement.
- UK demand is supported by a large food-manufacturing and bakery base where shortening and specialty-fat performance remain important to industrial production.
- Italy combines a sizable food-processing economy with bakery and confectionery applications that require controlled fat behavior.
- Australia has relatively low trans-fat intake, shifting the supplier proposition toward performance, source flexibility and plant-scale consistency.
- Germany's manufacturers operate in a cost-sensitive environment where movements in bakery, confectionery and edible-fat input prices increase scrutiny of total formulation economics.
- The USA has an established bakery manufacturing base and mature low-trans formulation environment, supporting optimization around texture and ingredient sourcing.
- With a food, beverage and tobacco manufacturing base worth EUR 207 billion in 2025, France's recurring demand for specialty fats reflects bakery, pastry and confectionery production requirements rather than a new regulatory transition.
- Canada's mature food-manufacturing sector supports incremental demand through formulation improvement and supplier switching rather than one-time regulatory conversion.
Country conditions differ because food-processing scale, input economics and customer specifications are not uniform. Suppliers therefore need application support suited to local bakery, confectionery and prepared-food production rather than one global product proposition.
Country-wise Analysis
- Japan has the highest profiled CAGR at 11.0% from 2026 to 2036. Current Japanese nutrition guidance places broader emphasis on overall fat composition, while average trans-fat exposure remains comparatively low. Growth is more closely tied to structured fats with tightly controlled melting and crystallization characteristics. Fuji Oil's strong domestic technical base in specialty fats means supplier competition centers on application precision rather than basic trans-fat removal.
- The UK is profiled at a 10.0% CAGR from 2026 to 2036. The Office for National Statistics reported in July 2026 that food remained the country's largest manufacturing division in 2025 and represented 22.9% of total manufacturers' product sales. Bakery and farinaceous product sales also remain substantial. This gives specialty-fat suppliers a large industrial customer base, but processors expect fats to maintain machinability and finished-product texture across commercial production runs.
- Italy is forecast to grow at a 9.0% CAGR from 2026 to 2036. Istat reported in 2026 that Italy's wider agri-food sector generated EUR 89 billion in value added during 2025, with food, beverage and tobacco industry volumes increasing by 1.4%. Bakery, fillings, confectionery and spread systems create recurring demand for fats that deliver controlled melting profiles. Suppliers can differentiate by balancing formulation performance with palm and seed-oil sourcing options.
- Australia is profiled at an 8.0% CAGR from 2026 to 2036. Food Standards Australia New Zealand continues to report relatively low trans-fat exposure, with Australians obtaining around 0.5% of daily energy from trans fatty acids. This makes compliance-led selling less persuasive. Commercial growth instead depends on shortening performance, temperature tolerance and fat systems that work reliably in bakery, frozen-food and plant-based formulations.
- Germany is projected to expand at a 7.0% CAGR from 2026 to 2036. Destatis reported in January 2026 that the average wholesale price of edible fats and oils increased 5.7% during 2025, while sugar, confectionery and bakery products rose 14.7%. Such movements increase attention to yield and cost-in-use. An interesterified fat must therefore protect line performance and product quality while remaining economically defensible against alternative fat systems.
- The USA carries a 6.0% CAGR profile from 2026 to 2036. U.S. Census Bureau data released in September 2026 put 2024 commercial bakery sales, shipments or revenue at approximately USD 39.8 billion. This large installed manufacturing base creates recurring demand for shortening and specialty-fat systems. Cargill and ADM already provide interesterified options, so supplier competition increasingly centers on solid-fat profile, palm alternatives and application support.
- France is profiled at a 5.0% CAGR from 2026 to 2036. Insee reported in July 2026 that French food, beverage and tobacco manufacturing production was worth EUR 207 billion in 2025. Bakery, pastry and confectionery production forms part of this established downstream base. Demand for interesterified fats therefore comes primarily from texture, shelf-life and manufacturing requirements rather than from a new regulatory transition.
- Canada has the lowest profiled CAGR at 4.0% from 2026 to 2036. Statistics Canada reported in December 2025 that food manufacturing revenue reached CAD 160.7 billion in 2024 and represented 18.4% of revenue from manufactured goods. The size of that processing sector provides a stable customer base for functional fats. Growth is likely to come through formulation optimization, second-source qualification and specialty applications rather than rapid first-time substitution.
Who are the notable companies in the Interesterified Fats Market?
Bunge, Cargill, ADM, Wilmar International Limited, AAK, Fuji Oil Holdings Inc. and Musim Mas Group are notable suppliers across integrated edible oils, interesterified fats and specialty-fat systems.
Competition separates into integrated oils businesses and specialist structured-fat platforms. Cargill and ADM document direct interesterified shortening and oil products. AAK, Fuji Oil and Musim Mas compete more directly through specialty-fat design and structured-lipid expertise. Bunge and Wilmar combine large-scale feedstock access, refining and specialty-oil capabilities.
The commercial advantage differs by customer. A multinational bakery producer may value feedstock flexibility and regional supply redundancy, while a confectionery manufacturer may place greater weight on crystallization, melt and technical co-development. Application laboratories therefore matter because specialty-fat performance is difficult to judge from composition alone.
- Integrated edible-oil and feedstock platforms include Bunge, Cargill, ADM and Wilmar International Limited.
- Specialty-fat and structured-lipid specialists include AAK, Fuji Oil Holdings Inc. and Musim Mas Group.
- Cargill and ADM offer particularly visible direct interesterified products for bakery, icing, frying and non-dairy applications.
Competitive Benchmarking: Interesterified Fats Market
| Company | Interesterification Capability | Specialty-Fat Application Breadth | Feedstock Integration | Geographic Reach |
|---|---|---|---|---|
| Bunge | Medium | High | High | Americas, Europe and Asia through a broad agribusiness and specialty-oils network |
| Cargill | High | High | High | North America, Europe, Asia Pacific, Middle East and Africa |
| ADM | High | High | High | North America with broad global edible-oils and food-ingredient reach |
| Wilmar International Limited | Medium | High | High | Asia, Africa, Europe and an international distribution network |
| AAK | High | High | Medium | Europe, the Americas and Asia through regional production and innovation sites |
| Fuji Oil Holdings Inc. | High | High | Medium | Japan, wider Asia, the Americas and Europe |
| Musim Mas Group | High | High | High | Integrated Southeast Asian production with international specialty-fat customers |
Scoring basis: Interesterification Capability reflects direct interesterified products, processes or structured-fat technology. Specialty-Fat Application Breadth considers bakery, confectionery, spreads, frying, nutrition and related applications. Feedstock Integration considers access to upstream oils, refining and specialty-fat inputs. High indicates broad capability, while Medium indicates a more concentrated position.
Key Developments in the Interesterified Fats Market
- In July 2025, Bunge completed its combination with Viterra, expanding its origination network and crop coverage. For specialty-fat customers, the broader upstream platform increases feedstock and logistics flexibility around edible-oil sourcing.
- In October 2025, AAK entered a joint venture with Kuala Lumpur Kepong Berhad to establish Nura Specialty Oils and Fats, a production plant for specialty palm fractions in Pasir Gudang, Malaysia. The facility will strengthen AAK's upstream access to high-purity feedstock for cocoa butter alternatives, with the plant expected to ramp up in 2028.
- In July 2026, Musim Mas published details of CBE CHOCO 48ES, an enzymatic interesterification solution based on high-oleic sunflower oil, positioned around crystallization performance, processing stability and resistance to fat bloom in confectionery applications.
Key Players in the Interesterified Fats Market
Integrated Global Oils and Feedstock Platforms
- Bunge
- Cargill
- ADM
- Wilmar International Limited
Specialty Fat and Structured Lipid Specialists
- AAK
- Fuji Oil Holdings Inc.
- Musim Mas Group
Interesterified Fats Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Interesterification Process, Source, End-Use |
| Quantitative Units | Revenue in USD Billion and CAGR in %. |
| Market Definition | Includes revenue from interesterified fats and oils sold as functional ingredients within the defined Interesterification Process, Source and End-Use taxonomy. Downstream finished foods, pharmaceuticals and cosmetics, unmodified oils, non-interesterified substitute fats and catalysts are outside the market scope. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa |
| Countries Covered | USA, Germany, UK, Australia, Canada, France, Italy, Japan |
| Key Companies Profiled | Bunge, Cargill, ADM, Wilmar International Limited, AAK, Fuji Oil Holdings Inc., Musim Mas Group |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation |
Interesterified Fats Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from edible-oil processors, specialty-fat manufacturers, bakery and confectionery producers, food manufacturers, distributors, procurement teams and technical specialists. Interviews examined purchasing requirements, application performance, supplier qualification, pricing and technical support. |
| Desk Research | Desk research covered government manufacturing statistics, current regulatory information, technical literature, company filings, product information and corporate announcements relevant to interesterified and specialty fats. |
| Market Sizing and Forecasting | Market sizing considered the baseline value, Interesterification Process, Source, End-Use, feedstock economics, specialty-fat demand, company participation and country-level food-processing conditions. |
| Data Validation | Estimates were compared with edible-oil activity, supplier portfolios, manufacturing indicators and findings from primary research before segment and regional values were aligned with the market total. |
Interesterified Fats Market by Segments
Interesterified Fats Market segmented by Interesterification Process:
- Enzymatic
- Sodium Methoxide
- Potassium Methoxide
- Alkaline Catalysts
- Polyethylene glycolate
- Others
Interesterified Fats Market segmented by Source:
- Palm oil
- Soybean oil
- Rapeseed oil
- Sunflower oil
- Other Vegetable oils
- Groundnut oil
- Cottonseed oil
- Coconut oil
- Walnut oil
Interesterified Fats Market segmented by End-Use:
- Food Processing
- Pharmaceuticals
- Cosmetics and Personal care
Interesterified Fats Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- Yan, H., et al. (2026, May 15). Recent Advances in Enzymatic Synthesis, Health Benefits, and Applications of Structured Lipids: A Review.
- Food Standards Australia New Zealand (2025, May 8). Trans Fatty Acids and Monitoring of Australian and New Zealand Foods.
- Ministry of Health, Labour and Welfare, Japan (2025). Dietary Reference Intakes for Japanese, 2025.
- Office for National Statistics (2026, July 24). UK Manufacturers' Sales by Product: 2025.
- Istat (2026). Economic Accounts for Agriculture: Year 2025.
- German Federal Statistical Office (2026, January). Wholesale Prices in December 2025.
- U.S. Census Bureau (2026, September 3). Annual Integrated Economic Survey: 2024 Manufacturing Summary Statistics.
- Insee (2026, July 21). Macroeconomic Indicators for Manufacturing Industry: 2025.
- Statistics Canada (2025, December 18). Annual Survey of Manufacturing Industries, 2024.
- Cargill (n.d.). Cake and Icing Shortenings.
- ADM (n.d.). Interesterified Oils and Shortenings.
- AAK (2025, April 10). Annual Report and Sustainability Report 2024.
- AAK (2025, October 24). AAK Enters Strategic Joint Venture to Strengthen Supply Chain for Cocoa Butter Equivalents.
- Bunge (2025, July 2). Bunge and Viterra Complete Merger.
- Bunge (2026, February 4). Full-Year 2025 Results.
- Musim Mas Group (2026). Cocoa Butter Equivalent Solutions for Chocolate Manufacturers.
- Wilmar International Limited (2025). Annual Report 2024.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the Interesterified Fats Market in 2026 and what value is forecast for 2036?
- Which commercial factors support demand for interesterified fats?
- Why does Enzymatic lead the Interesterification Process category?
- Why does Palm oil lead the Source category?
- Why does Food Processing lead End-Use demand?
- How do the profiled country growth rates differ from 2026 to 2036?
- Which companies supply interesterified fats and related specialty-fat systems?
- What should buyers evaluate before qualifying an interesterified-fat specification?
Frequently Asked Questions
How big is the Interesterified Fats Market in 2026, and what is forecast for 2036?
The market is valued at USD 5.3 Billion in 2026 and is forecast to reach USD 9.3 Billion by 2036. Growth is supported by food manufacturers that require tightly controlled functional-fat performance across bakery, confectionery, spreads and related applications.
What is the CAGR of the Interesterified Fats Market from 2026 to 2036?
The market is forecast to expand at a 6.0% CAGR from 2026 to 2036. Growth increasingly reflects performance optimization and structured-fat design rather than only first-generation trans-fat replacement.
Which Interesterification Process segment leads the market?
Enzymatic leads the Interesterification Process category with a 52.0% share in 2026. Its position reflects the greater control it provides over structured-fat properties.
Which Source segment leads the Interesterified Fats Market?
Palm oil leads Source with a 28.0% share in 2026. Its semi-solid profile, fractionation flexibility and existing refining infrastructure make it useful across numerous specialty-fat formulations.
Which profiled countries record the highest growth rates?
Japan has the highest profiled CAGR at 11.0%, followed by the UK at 10.0% and Italy at 9.0% from 2026 to 2036. These figures describe forecast growth pace rather than absolute country market size.
Which companies are active in the Interesterified Fats Market?
Notable companies include Bunge, Cargill, ADM, Wilmar International Limited, AAK, Fuji Oil Holdings Inc. and Musim Mas Group. Their capabilities span edible-oil origination, interesterification, structured-fat design and specialty-food applications.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Interesterification Process, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Interesterification Process, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Interesterification Process, 2026 to 2036
- Enzymatic
- Sodium Methoxide
- Potassium Methoxide
- Alkaline Catalysts
- Polyethylene glycolate
- Others
- Y-o-Y Growth Trend Analysis By Interesterification Process, 2021 to 2025
- Absolute $ Opportunity Analysis By Interesterification Process, 2026 to 2036
- Global Market Analysis and Forecast, By Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source, 2026 to 2036
- Palm oil
- Soybean oil
- Rapeseed oil
- Sunflower oil
- Other Vegetable oils
- Groundnut oil
- Cottonseed oil
- Coconut oil
- Walnut oil
- Y-o-Y Growth Trend Analysis By Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Source, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use, 2026 to 2036
- Food Processing
- Pharmaceuticals
- Cosmetics and Personal care
- Y-o-Y Growth Trend Analysis By End-Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Interesterification Process
- By Source
- By End-Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Interesterification Process
- By Source
- By End-Use
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Interesterification Process
- By Source
- By End-Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Interesterification Process
- By Source
- By End-Use
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Interesterification Process
- By Source
- By End-Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Interesterification Process
- By Source
- By End-Use
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Interesterification Process
- By Source
- By End-Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Interesterification Process
- By Source
- By End-Use
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Interesterification Process
- By Source
- By End-Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Interesterification Process
- By Source
- By End-Use
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Interesterification Process
- By Source
- By End-Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Interesterification Process
- By Source
- By End-Use
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Interesterification Process
- By Source
- By End-Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Interesterification Process
- By Source
- By End-Use
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Interesterification Process
- By Source
- By End-Use
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Interesterification Process
- By Source
- By End-Use
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Interesterification Process
- By Source
- By End-Use
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Interesterification Process
- By Source
- By End-Use
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Interesterification Process
- By Source
- By End-Use
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Interesterification Process
- By Source
- By End-Use
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Interesterification Process
- By Source
- By End-Use
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Interesterification Process
- By Source
- By End-Use
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Interesterification Process
- By Source
- By End-Use
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Interesterification Process
- By Source
- By End-Use
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Interesterification Process
- By Source
- By End-Use
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Interesterification Process
- By Source
- By End-Use
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Interesterification Process
- By Source
- By End-Use
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Interesterification Process
- By Source
- By End-Use
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Interesterification Process
- By Source
- By End-Use
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Interesterification Process
- By Source
- By End-Use
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Interesterification Process
- By Source
- By End-Use
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Interesterification Process
- By Source
- By End-Use
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Interesterification Process
- By Source
- By End-Use
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Interesterification Process
- By Source
- By End-Use
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Interesterification Process
- By Source
- By End-Use
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Interesterification Process
- By Source
- By End-Use
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Bunge
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Cargill
- ADM
- Wilmar International Limited
- AAK
- Fuji Oil Holdings Inc.
- Musim Mas Group
- Bunge
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


