
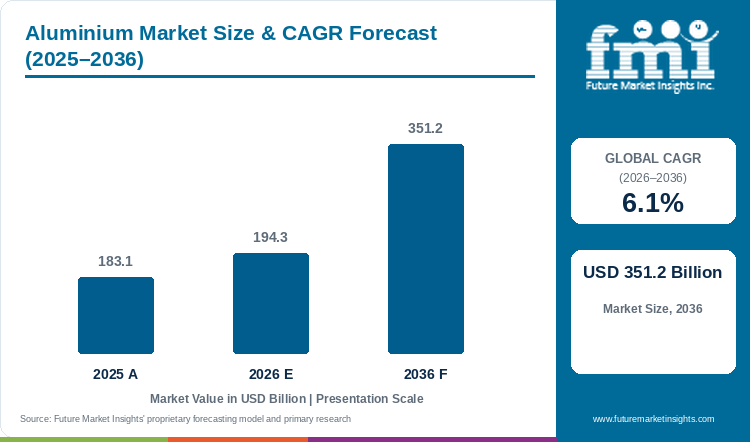
- Market Size (2026)
- USD 194.3 Bn
- Forecast (2036)
- USD 351.2 Bn
- CAGR (2026 to 2036)
- 6.1%
How big is the Aluminium Market in 2026?
Demand for aluminium in buildings, vehicles, packaging and power grids should bring the Aluminium Market to USD 351.2 billion by 2036. FMI estimates USD 194.3 billion for 2026 and a 6.1% CAGR across 2026 to 2036. The market was valued at USD 183.1 billion in 2025. Series 5 Aluminum holds 22.4% by series in 2026. Extrusions represent 29.6% by processing, with building and construction the leading end use at 27.5%.
Higher prices and firm demand shape the outlook. The World Bank expects metals prices to rise 25.0% in 2026, with aluminium among those reaching record highs [13]. The Aluminum Association reported North American demand of 13.6 billion pounds for the first half of 2026, a 3.5% rise [2]. The U.S. Geological Survey reported world primary production of about 74.0 million tonnes in 2025, of which China produced 45.0 million tonnes [1].
Energy cost and trade rules restrain supply outside China. The European Commission applies the definitive CBAM regime to aluminium imports from 1 January 2026 [3]. The United States raised its Section 232 duty on aluminium to 50.0% in June 2025 under Proclamation 10947 [18]. Rio Tinto offers a qualified example of new capacity [8]. It began commissioning a USD 1.5 billion AP60 expansion in Quebec in March 2026 and expects all 96 new pots to run by year end. The project adds about 160,000 tonnes a year and does not alter the global balance alone.
Key Market Trends & Insights
- Imports are replacing falling domestic mill output in North America. The Aluminum Association found that domestic shipments of semi-fabricated products fell 3.6% during January to June 2026 while total demand rose 3.5% [2]. Growth came largely from imported sheet. Buyers are therefore paying tariff-inclusive prices for a larger share of their coil.
- Recycled content is becoming a contract term in its own right. Hydro reached about 850,000 tonnes a year of post-consumer scrap recycling capacity at the end of 2025 and is supplying Hydro CIRCAL with at least 75.0% post-consumer scrap for Mercedes-Benz electric vehicles [5]. Suppliers that can document scrap input win qualification in automotive programmes.
- Regional premiums now matter as much as the exchange price. Rio Tinto reported that elevated regional market premiums offset the full impact of US tariffs on its aluminium business over the six months to June 2026 [8]. China Hongqiao reported an average selling price of about RMB 21,192 per tonne for aluminium alloy products in the same period. That was 18.7% higher than a year earlier [22].
Regional Highlights
- In Europe, primary output has halved since the energy crisis and imports meet more than half of demand according to European Aluminium [4]. The association reports scrap exports from the bloc of over 1.0 million tonnes a year. Producers are responding with restarts and recycling. Hydro plans to restart 75,000 tonnes at Slovalco in the second half of 2026 [6].
- In North America, net import reliance was 60.0% of apparent consumption in 2025 [1]. Primary output of 660,000 tonnes compared with imports of 4.4 million tonnes of crude and semi-fabricated products. In February 2026 Century Aluminum and Emirates Global Aluminium highlighted their partnership to build what would be the first new US primary smelter in more than 45 years at Inola, Oklahoma, although Century still described the joint venture as not yet formalised in August 2026 [20][21].
Aluminium Market Size and Forecast
Table 1: Aluminium Market Size and Forecast
| Market size and forecast | Value |
|---|---|
| Market size in 2025 | USD 183.1 billion |
| Estimated market size in 2026 | USD 194.3 billion |
| Projected market size by 2036 | USD 351.2 billion |
| CAGR from 2026 to 2036 | 6.1% |
Source: Future Market Insights analysis of the aluminium market, 2026.
Analyst Perspective
“Aluminium buyers now negotiate the metal price and the regional premium and the conversion charge as three separate items. Many also add a recycled-content clause. Suppliers differentiate on billet and coil chemistry and on their ability to document where the metal was smelted and cast. The main qualification risk is scrap quality because a contaminated melt can force a mill to downgrade a batch and miss a customer specification.”
- Nikhil Kaitwade, Principal Consultant, FMI
How is the Aluminium Market segmented?
- By series: Series 1 Aluminum, Series 2 Aluminum, Series 3 Aluminum, Series 4 Aluminum, Series 5 Aluminum, Series 6 Aluminum, Series 7 Aluminum, and Series 8 Aluminum.
- By processing: Extrusions, Castings, Flat Rolled Aluminum, Rods & Bars, Pigments & Powder, and Forgings. Press-made profiles are covered in more depth in the aluminium extrusion market that FMI tracks separately.
- By application: Transportation, Construction, Electrical and Electronics, Packaging, and Industrial Machinery.
- By end use: Automotive Industry, Aerospace Industry, Building and Construction Industry, Electrical Industry, Packaging Industry, and Industrial Machinery.
- By deployment: Primary Production and Secondary Production. Remelting economics are examined in the secondary smelting and alloying of aluminium market.
- By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does Series 5 Aluminum lead by Series in the Aluminium Market in 2026?
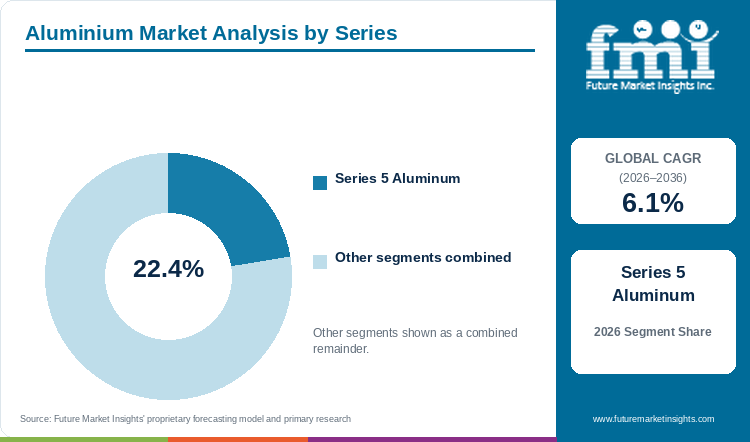
Series 5 Aluminum holds 22.4% of the Aluminium Market by series in 2026.
Magnesium-alloyed sheet and plate serve two large buyers at once: packaging mills and transport fabricators. Can ends, marine plate and commercial vehicle bodies need strength and corrosion resistance without a heat-treatment step. Constellium shipped 201,000 tonnes of packaging rolled products in the three months to September 2026 [15]. Novelis shipped 916,000 tonnes of rolled products during the quarter ended June 2026 despite a fire-related loss of about 33,000 tonnes at Oswego [9]. Packaging volumes of that size keep rolling mills committed to magnesium-bearing coil.
Packaging is also a recovery-led demand base. Packaging accounted for 24.0% of US aluminium consumption in 2025, second only to transportation [1]. Can sheet returns through deposit and kerbside schemes, so mills can run closed loops that lower metal cost. Those economics link the series to the aluminum cans market. Kaiser Aluminum reports that coated products made up about 75.0% of its packaging shipments in 2025, which shows how much value is added after rolling [31].
The other seven series together hold the remaining 77.6% by series. Series 6 Aluminum follows at 21.6% on the strength of extrusion billet for window frames and vehicle structures. Hydro serves that segment and estimated European extrusion demand to be up 0.4% in the second quarter of 2026 [6].
Table 2: Series, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Series 5 Aluminum | 22.4% |
| All Other Segments Combined Share | 77.6% |
Source: Future Market Insights analysis of the aluminium market, 2026.
Why do Extrusions lead by Processing in the Aluminium Market in 2026?
Extrusions account for 29.6% of the Aluminium Market by processing in 2026.
A press turns a heated billet into a near-finished section in one pass. Window frames and curtain wall mullions arrive with channels and fixing points already formed. The same applies to heat sinks and battery trays. That saves machining and joining for the buyer, so extruders can sell on delivered part cost instead of metal weight. Hydro runs both smelters and extrusion plants. It reported that European extrusion demand rose 0.4% and North American demand was flat year on year in the second quarter of 2026 [6]. Demand is steady and spread across many end uses.
Billet supply now comes from both primary and recycled routes. Emirates Global Aluminium began production in 2026 at its Al Taweelah recycling plant [10]. The plant can make 185,000 tonnes of billets and T-bars a year and can shred and segregate up to 150,000 tonnes of scrap. Extruders qualify each billet source for chemistry and surface finish, so a new casthouse must pass trials before it wins orders.
The five other processing routes together represent the remaining 70.4% by processing. Flat Rolled Aluminum follows at 28.9%. Rod and bar demand is rising with grid investment. Hydro has agreed to supply up to 274,000 tonnes of wire rod to NKT through 2033 [5]. A second agreement covers about 85,000 tonnes for Nexans between 2026 and 2030.
Table 3: Processing, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Extrusions | 29.6% |
| All Other Segments Combined Share | 70.4% |
Why does Building and Construction Industry lead by End Use in the Aluminium Market in 2026?
Building and Construction Industry holds 27.5% of the Aluminium Market by end use in 2026.
Buildings buy aluminium in long-lived forms such as window profiles and curtain walls and cladding. Renovation work adds a second stream of orders on top of new construction because frames and facades are replaced on energy-performance grounds. Each project specifies finish and weather resistance and fire performance. That favours suppliers with tested systems. The facade segment overlaps with the aluminium composite panels market that FMI covers separately.
National mixes differ from the global picture. Building represented 13.0% of US aluminium consumption in 2025, well behind transportation at 36.0% [1]. The global lead for construction therefore rests on markets outside the United States, where building programmes absorb more extruded and rolled metal. Bridgnorth Aluminium is a UK rolling mill serving printing and packaging and construction customers. It completed a GBP 180.0 million investment programme in July 2026 and returned to round-the-clock production [26].
The five other end-use industries together account for the remaining 72.5% by end use. Automotive Industry follows at 24.8%. Constellium shipped 61,000 tonnes of automotive rolled products and 23,000 tonnes of aerospace rolled products in the September 2026 quarter [15]. South Korean vehicle production rose 3.7% to 347,000 units in September 2026 and supports sheet and casting orders [16].
Table 4: End Use, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Building and Construction Industry | 27.5% |
| All Other Segments Combined Share | 72.5% |
What are the key drivers restraints and opportunities?
Aluminium sales grow when fabricators can source metal of the right chemistry at a price their customers will pay. The same energy and trade costs that raise prices also decide where new smelting and rolling capacity gets built.
Driver
Price and volume are rising together in 2026. The World Bank expects metals prices to climb 25.0% in 2026 as aluminium and copper and tin reach record highs [13]. It links the gains to demand from renewables and electric vehicles and data centres. Alcoa posted a quarterly revenue record of USD 3,966.0 million in the June 2026 quarter on shipments of 726,000 tonnes [7]. Rio Tinto's aluminium underlying EBITDA rose 31.0% to USD 3,093.0 million for the first six months of 2026 [8]. Higher margins give producers the cash to restart idle pots and fund casthouses.
Restraint
Smelting outside China depends on affordable power and trade access. European Aluminium reports that electricity prices in Europe are two to three times US levels and that EU primary production has halved since the energy crisis [4]. US import duties on aluminium articles rose from 25.0% to 50.0% on 4 June 2025 [18]. Alcoa still reported higher tariff costs on imported aluminium for the June 2026 quarter [7]. Fabricators that depend on imported coil therefore carry a cost that domestic rivals do not.
Opportunity
Closed-loop recycling lets a mill sell documented low-carbon metal at a premium. Hydro is investing EUR 180.0 million in a recycling plant at Torija in Spain [5]. It will produce 120,000 tonnes a year and will take in up to 70,000 tonnes of post-consumer scrap. Novelis opened a USD 65.0 million recycling centre in Ulsan in April 2025 with 100,000 tons a year of sheet ingot capacity [24]. Each plant needs sorted scrap of known chemistry, so sorting technology is the gating investment.
How do trade rules and carbon border charges affect aluminium costs?
Trade rules now set a large part of the delivered price in two major markets. In the United States, Proclamation 10947 raised the Section 232 duty on aluminium articles and derivatives to 50.0% from 4 June 2025 [18]. UK products were held at 25.0%. Proclamation 11021 then applied the duty to the full customs value of imported products from 6 April 2026 and set a 10.0% rate for derivatives made from metal smelted and cast in the United States [19]. Russian-origin metal remains subject to a 200.0% rate [19].
In the European Union, the definitive CBAM regime has applied since 1 January 2026. Importers above a 50 tonne annual threshold must hold authorised declarant status and surrender certificates each year, priced on a quarterly average in 2026 [3]. European Aluminium argues that the current design does not stop carbon leakage for aluminium and asks that the November 2025 scrap export measure be enforced [4]. Buyers must now price embedded emissions and origin into every import contract.
What limits reliable aluminium supply and metal quality?
Supply is set by potline availability and the condition of scrap. Restarts take time and money. Hydro plans to spend EUR 100.0 million to bring back 75,000 tonnes at Slovalco after securing indirect carbon cost compensation from the Slovak government [5][6]. Alcoa completed its San Ciprián restart on 7 April 2026 and is still progressing the Alumar restart in Brazil [7]. Century Aluminum completed the restart of the last 90 pots at Mt. Holly in 2026 [20]. A single incident can remove tonnage quickly. Novelis lost about 33,000 tonnes of shipments to the Oswego fires and booked USD 265.0 million of pre-tax losses before the hot mill restarted in June 2026 [9].
Scrap quality is the second limit. Coatings, paint and mixed alloys change melt chemistry and can downgrade a batch. The CLEANMAT project was launched in June 2026 with 17 partners from eight countries and runs until May 2029 [14]. It is developing sensor-based sorting and cleaner melt refining. Until such methods scale, mills blend primary units with scrap to hit specification.
Where can aluminium suppliers win additional business?
Suppliers can win on documented recycled content, grid conductor supply and battery materials. Hydro has signed close to 360,000 tonnes of wire rod agreements for European power infrastructure [5]. It is also adding 110,000 tonnes of casthouse capacity at Karmøy for NOK 1.7 billion. Hindalco commissioned a battery foil plant at Aditya and increased downstream sales to 104,000 tonnes in the April to June 2026 quarter [11]. Bridgnorth Aluminium signed a five-year supply deal with Lotte Aluminium USA for battery development material [26]. Arconic is investing USD 131.0 million in a casting complex at Davenport to recycle more metal into sheet and plate ingot [27]. Each route requires a product qualification that a commodity ingot seller does not face.
Aluminium Market by Country (2026 to 2036)
Table 5: Aluminium Market Country Growth Forecast
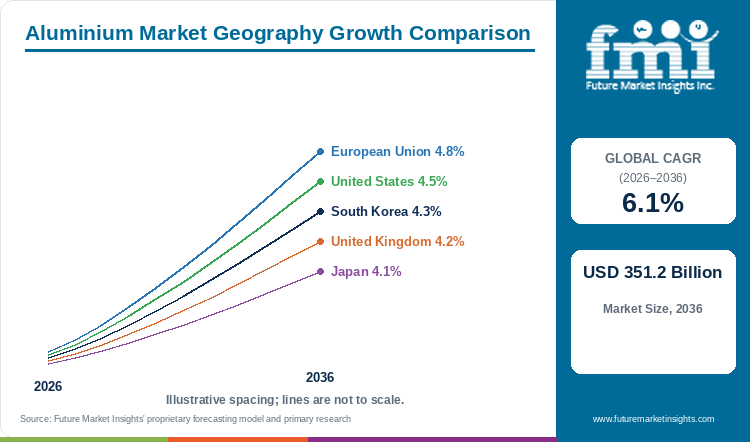
| Country | CAGR, 2026 to 2036 |
|---|---|
| European Union | 4.8% |
| United States | 4.5% |
| South Korea | 4.3% |
| United Kingdom | 4.2% |
| Japan | 4.1% |
Source: Future Market Insights analysis of the aluminium market, 2026.
European Union
The European Union buys more aluminium than it smelts, and policy is now built around that fact. European Aluminium reports that imports meet more than 50.0% of demand and that primary production is half its pre-crisis level [4]. The association expects demand to rise 30.0% by 2040 against 2022 levels as electrification proceeds. Scrap exports above 1.0 million tonnes a year still leave the bloc, and the industry wants that metal retained for local remelting.
Carbon pricing at the border changes the sourcing arithmetic. Since 1 January 2026 the definitive CBAM regime requires importers above 50 tonnes to become authorised declarants and surrender certificates each year [3]. A fabricator in Germany or Italy must now compare a CBAM-inclusive import price with regional metal from restarted or recycled sources. That comparison is why Hydro is restarting 75,000 tonnes at Slovalco with carbon cost compensation and why Alcoa finished its San Ciprián restart in April 2026 [6][7]. It is also why FMI expects a 4.8% CAGR for the bloc through the 2026 to 2036 period, ahead of the other profiled markets.
Recycling investment and secured power contracts support that view. Hydro's EUR 180.0 million Torija plant and Constellium's recycling centre in France are examples of casthouses placed next to demand [5][15]. Electricity prices of two to three times US levels remain the structural cost disadvantage for any new primary capacity [4]. Growth will therefore come from conversion value, documented recycled content and conductor rod for grid projects more than from new smelter tonnage. Suppliers that can prove origin and emissions per tonne will hold the best position with European automotive and construction customers.
United States
The United States has the widest shortfall between fabrication demand and domestic primary output of any profiled market. USGS data show 660,000 tonnes of primary production in 2025 against imports of 4.4 million tonnes of crude and semi-fabricated products [1]. Net import reliance was 60.0%. Secondary production from old and new scrap reached about 3.6 million tonnes, more than five times the primary total.
Tariff policy has raised the cost of that import dependence. The Section 232 rate on aluminium rose to 50.0% in June 2025, and from April 2026 the duty applies to the full customs value of imported goods [18][19]. Demand kept growing despite the cost, and the 4.5% CAGR for the United States across 2026 to 2036 assumes that pattern holds. The Aluminum Association recorded North American demand of 13.6 billion pounds between January and June 2026, a rise of 3.5% [2]. Domestic mill shipments fell 3.6% over the same period. Imports of sheet filled the difference.
Rolling and casting investment is the response. Novelis has begun commissioning its Bay Minette rolling and recycling plant in Alabama [9]. Arconic is adding a USD 131.0 million casting complex at Davenport [27]. Century Aluminum and EGA plan a new primary smelter at Inola in Oklahoma, subject to formalising their joint venture, and Century expects USD 500.0 million of Department of Energy funding to be available for the project [20][21]. These projects reduce import exposure only once they reach rated output and pass customer trials, so buyers should expect imported coil to remain part of the mix for several years. Transportation at 36.0% and packaging at 24.0% of consumption set the specifications that new mills must meet [1].
South Korea
South Korean aluminium demand follows the production lines of its carmakers and can makers. The Korean trade ministry reported vehicle output of 347,000 units in September 2026, a 3.7% rise on a year earlier [16]. Domestic sales fell 14.3% in the same month. Exports of eco-friendly vehicles rose 5.9% to USD 2.89 billion. Factory output decides how much sheet and extrusion and casting is ordered. Showroom sales do not.
Recycled sheet ingot is now made locally. Novelis opened its USD 65.0 million Ulsan recycling centre in April 2025 with capacity for 100,000 tons a year of low-carbon sheet ingot [24]. The ingot serves can and automotive and specialty products. Korean can makers and automotive stampers can source documented recycled metal without importing it. Novelis also operates an existing facility at Yeongju in Gyeongsangbuk-do [24].
Export access shapes the rest of the outlook. Proclamation 11021 lists Korea among the trade agreement partners eligible for duty drawback on Section 232 products, subject to conditions, which matters for vehicle parts shipped to the United States [19]. Electric vehicle subsidies in the home market were exhausted during 2026 and slowed domestic EV sales [16]. Those two forces hold Korean aluminium demand to a 4.3% CAGR for the 2026 to 2036 forecast, steady but below the European Union and United States rates. Suppliers that pass the long qualification cycles of Korean automotive and battery customers will keep the volume, because a change of supplier after tooling is complete is expensive for the buyer.
United Kingdom
British aluminium demand rests on packaging recovery and on a small number of specialist mills. Provisional government data show that 247,000 tonnes of aluminium packaging waste arose in 2025 [12]. Of that total 151,000 tonnes were recycled, a rate of 61.1%. Producer responsibility targets rise to 62.0% in 2026 and 63.0% in 2027 [17]. Each extra point requires more collection and sorting, and more domestic remelting capacity.
That capacity is being built. Novelis is doubling used beverage can recycling at Latchford by adding 85,000 tonnes a year for about USD 90.0 million [25]. Commissioning is expected to begin in December 2026. Once complete, the plant is intended to process all cans collected under the planned UK deposit return scheme. Bridgnorth Aluminium completed a GBP 180.0 million investment programme at its Shropshire mill in July 2026 and signed a five-year deal to supply Lotte Aluminium USA [26].
Trade terms favour UK exporters relative to other suppliers of the US market. Aluminium smelted or cast in the United Kingdom faces a 25.0% Section 232 rate instead of 50.0% under Proclamation 11021 [19]. Recovery-led packaging demand and specialist export orders therefore produce a 4.2% CAGR for the United Kingdom during 2026 to 2036. The absence of any announced new primary smelting capacity keeps that rate below the European Union figure. Mills that secure deposit-scheme scrap early will have the lowest metal cost in the market, while aerospace and lithographic customers will keep paying for certified plate and sheet.
Japan
Japan combines a large rolling and extrusion base with mature domestic end markets. The Japan Aluminium Association reported that 2024 demand for rolled products plus foil did not reach 2.0 million tonnes and that total aluminium product demand stayed below 4.0 million tonnes [30]. The association has set a target of 30.0% recycled ingot in wrought products by 2030. Japanese mills must therefore grow through product mix and overseas plants more than through home volume.
UACJ shows both routes. Its revenue for the year to March 2026 rose 18.3% to JPY 1,181.7 billion [28]. The company started a used beverage can melting and recycling system at Fukui Works in January 2026 for about JPY 5.2 billion and targets flat rolled sales of more than 1.4 million tons in fiscal 2027 [29]. Much of its growth capital is going to Logan in the United States and to Thailand. Those plants are being expanded to 460,000 and 340,000 tons respectively.
Slow domestic volume and a recycling push combine in a 4.1% CAGR for Japan over 2026 to 2036. That is the slowest rate of the five profiled markets. Japan is listed among the partners eligible for Section 232 duty drawback, which protects some export routes for finished parts [19]. Can stock, automotive sheet and precision foil will remain the products where Japanese mills earn their margin. Buyers in Japan pay for tolerance and surface quality, and that pricing power should hold even as construction and consumer volumes stay flat.
Who are the notable companies in the Aluminium Market?
Alcoa and Rio Tinto and Norsk Hydro and Century Aluminum and Emirates Global Aluminium show the main primary positions in this market. Alcoa produced 636,000 tonnes of aluminium in the June 2026 quarter and has completed restarts at San Ciprián and Lista and Portland [7]. Rio Tinto produced 1,676,000 tonnes over January to June 2026 and is commissioning its AP60 expansion in Quebec [8][23]. Hydro combines smelting, recycling and extrusion and is restarting Slovalco while building Torija [5][6]. Century Aluminum restarted Mt. Holly and is working with EGA on a new US smelter [20][21]. EGA runs the Al Taweelah recycling plant alongside its primary potlines [10].
China Hongqiao sold about 2.811 million tonnes of aluminium alloy products in the six months to June 2026, more than the half-year output reported by Rio Tinto [22][8]. It generated revenue of RMB 87.5 billion and expects its relocated Yunnan capacity to be fully in use by 31 December 2026 [22]. Hindalco links Indian upstream shipments of 335,000 tonnes a quarter to a growing downstream business that includes battery foil [11].
Downstream specialists compete on coil quality and recycled content. Novelis delivered 916,000 tonnes of rolled products in its April to June 2026 quarter and is commissioning Bay Minette [9]. Constellium shipped 368,000 tonnes in the third quarter of 2026 across packaging and automotive and aerospace [15]. Kaiser Aluminum earns a premium from coated packaging sheet, which made up about 75.0% of its packaging shipments in 2025 [31]. UACJ and Arconic and Bridgnorth Aluminium round out the rolling group with investments in Japan and Iowa and the United Kingdom [29][27][26]. Buyers should compare each supplier on alloy range, casthouse chemistry control and documented scrap input before awarding multi-year contracts.
Key Developments in the Aluminium Market
- On 7 April 2026, Alcoa completed the restart of its San Ciprián smelter in Spain, alongside completed capacity restarts at Lista in Norway and Portland in Australia [7].
- On 29 May 2026, Rio Tinto announced that commissioning of its USD 1.5 billion AP60 expansion at the Arvida complex in Quebec had begun in March. The 96 new pots add about 160,000 tonnes a year and are expected to be in full operation by the end of 2026 [23].
- On 6 October 2026, Hydro announced a EUR 180.0 million recycling plant at Torija in Spain that will produce 120,000 tonnes a year [5]. The plant will process up to 70,000 tonnes of post-consumer scrap.
Key Players in the Aluminium Market
- Alcoa Corporation
- Rio Tinto
- Norsk Hydro ASA
- Century Aluminum Company
- Emirates Global Aluminium (EGA)
- China Hongqiao Group Limited
- Hindalco Industries Limited
- Novelis Inc.
- Constellium SE
- Kaiser Aluminum Corporation
- Arconic Corporation
- UACJ Corporation
- Bridgnorth Aluminium Ltd
Aluminium Market Report Scope
Table 6: Aluminium Market Report Scope
| Coverage field | Report scope |
|---|---|
| Market definition | Revenue from primary and recycled aluminium and from the processed forms sold to industrial end uses, including alloy series, extrusions, castings, flat rolled products, rods and bars, powders and forgings. Bauxite and alumina sold as such are excluded. |
| Series | Series 1 Aluminum; Series 2 Aluminum; Series 3 Aluminum; Series 4 Aluminum; Series 5 Aluminum; Series 6 Aluminum; Series 7 Aluminum; Series 8 Aluminum |
| Processing | Extrusions; Castings; Flat Rolled Aluminum; Rods & Bars; Pigments & Powder; Forgings |
| Application | Transportation; Construction; Electrical and Electronics; Packaging; Industrial Machinery |
| End Use | Automotive Industry; Aerospace Industry; Building and Construction Industry; Electrical Industry; Packaging Industry; Industrial Machinery |
| Deployment | Primary Production; Secondary Production |
| Regions covered | North America, Latin America, Western and Eastern Europe, East Asia, South Asia with the Pacific, Middle East and Africa |
| Profiled markets | United States, European Union, United Kingdom, Japan, South Korea |
| Companies covered | Alcoa Corporation; Rio Tinto; Norsk Hydro ASA; Century Aluminum Company; Emirates Global Aluminium; China Hongqiao Group Limited; Hindalco Industries Limited; Novelis Inc.; Constellium SE; Kaiser Aluminum Corporation; Arconic Corporation; UACJ Corporation; Bridgnorth Aluminium Ltd |
| Quantitative Units | USD billion |
Source: Future Market Insights analysis of the aluminium market, 2026.
Aluminium Market Research Methodology
The aluminium assessment draws on government mineral statistics and trade association demand data and trade and carbon border rules and producer disclosures [1][2][3][19]. FMI measures annual revenue from primary and secondary metal and its processed forms sold to industrial customers. Segment values are classified by alloy series and processing route and application and end use and production route. Country forecasts reflect local fabrication demand and trade access and energy cost and recycling investment over the same 2026 to 2036 period. Production tonnage, shipments and revenue are reviewed as separate measures and are not added across companies.
Aluminium Market by Segments
Aluminium Market segmented by Series:
- Series 1 Aluminum
- Series 2 Aluminum
- Series 3 Aluminum
- Series 4 Aluminum
- Series 5 Aluminum
- Series 6 Aluminum
- Series 7 Aluminum
- Series 8 Aluminum
Aluminium Market segmented by Processing:
- Extrusions
- Castings
- Flat Rolled Aluminum
- Rods & Bars
- Pigments & Powder
- Forgings
Aluminium Market segmented by Application:
- Transportation
- Construction
- Electrical and Electronics
- Packaging
- Industrial Machinery
Aluminium Market segmented by End Use:
- Automotive Industry
- Aerospace Industry
- Building and Construction Industry
- Electrical Industry
- Packaging Industry
- Industrial Machinery
Aluminium Market segmented by Deployment:
- Primary Production
- Secondary Production
Aluminium Market by Region
- North America
- United States
- Canada
- Mexico
- Latin America
- Brazil
- Chile
- Rest of Latin America
- Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- BENELUX
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Geological Survey. (2026, February). Mineral Commodity Summaries 2026: Aluminum.
- [2] The Aluminum Association. (2026, October 26). North American Aluminum Demand Up 3.5% Through First Half of 2026.
- [3] European Commission. (2026). Carbon Border Adjustment Mechanism: CBAM definitive regime.
- [4] European Aluminium. (2026, January). European Aluminium Action Plan 2026. https://european-aluminium.eu/action-plan-2026/
- [5] Norsk Hydro ASA. (2026, October 6). ALUMINIUM 2026: Hydro invests to strengthen resilience across the aluminium value chain. https://www.hydro.com/en/global/media/news/2026/aluminium-2026-hydro-invests-to-strengthen-resilience-across-the-aluminium-value-chain/
- [6] Norsk Hydro ASA. (2026, July 22). Hydro's second quarter 2026: Operational strength delivering solid results. https://www.hydro.com/en/global/media/news/2026/hydros-second-quarter-2026-operational-strength-delivering-solid-results/
- [7] Alcoa Corporation. (2026, July 16). Alcoa Corporation Reports Second Quarter 2026 Results. https://investors.alcoa.com/press-releases/press-release-details/2026/Alcoa-Corporation-Reports-Second-Quarter-2026-Results/default.aspx
- [8] Rio Tinto plc. (2026, July 29). Half-year results for the six months ended 30 June 2026, Form 6-K. U.S. Securities and Exchange Commission. https://www.sec.gov/Archives/edgar/data/887028/000162828026050377/rio-20260630_d2.htm
- [9] Novelis Inc. (2026, August 5). Novelis Reports First Quarter Fiscal Year 2027 Results. https://investors.novelis.com/news-events/press-releases/detail/1425/novelis-reports-first-quarter-fiscal-year-2027-results
- [10] Emirates Global Aluminium. (2026). Al Taweelah recycling plant. https://www.ega.ae/en/about-us/operations/al-taweelah-recycling-plant
- [11] Hindalco Industries Limited. (2026, August 7). Hindalco reports Q1 FY27 financial results. https://www.hindalco.com/media/press-releases/hindalco-results-q1fy27
- [12] Department for Environment, Food and Rural Affairs. (2026, September 23). UK statistics on waste: Provisional packaging waste and recycling data, 2025.
- [13] World Bank. (2026, October 28). Commodity Markets Outlook, October 2026: press release. https://www.worldbank.org/en/news/press-release/2026/10/28/commodity-markets-outlook-october-2026
- [14] European Aluminium. (2026). CLEANMAT: Smart clean aluminium material processing. https://european-aluminium.eu/projets/cleanmat-smart-clean-aluminium-material-processing-digital-sorting-intelligent-pre-treatment-and-advanced-melt-refining/
- [15] Constellium SE. (2026, October 28). Constellium reports third quarter 2026 results, Form 6-K exhibit. U.S. Securities and Exchange Commission. https://www.sec.gov/Archives/edgar/data/1563411/000156341126000198/a2026-q3xearningspressre.htm
- [16] Ministry of Trade, Industry and Energy, Republic of Korea. (2026, October 19). September 2026 automobile industry trends. https://www.motir.go.kr/kor/article/ATCL3f49a5a8c/172302/view
- [17] UK Government. (2026, October 28). How to comply with packaging recycling obligations as a large producer. https://www.gov.uk/guidance/how-to-comply-with-packaging-recycling-obligations-as-a-large-producer
- [18] The White House. (2025, June 3). Proclamation 10947: Adjusting Imports of Aluminum and Steel Into the United States. Government Publishing Office. https://www.govinfo.gov/content/pkg/DCPD-202500655/html/DCPD-202500655.htm
- [19] The White House. (2026, April 9). Proclamation 11021: Strengthening Actions Taken To Adjust Imports of Aluminum, Steel, and Copper Into the United States. Federal Register, 91(68). https://www.govinfo.gov/content/pkg/FR-2026-04-09/html/2026-06960.htm
- [20] Century Aluminum Company. (2026, August 6). Century Aluminum Company Reports Second Quarter 2026 Results. https://s25.q4cdn.com/716080898/files/doc_news/Century-Aluminum-Company-Reports-Second-Quarter-2026-Results-2026.pdf
- [21] Century Aluminum Company. (2026, February 10). EGA and Century Celebrate Historic Smelter Project, Meet With U.S. Energy Secretary Chris Wright. https://investors.centuryaluminum.com/news-events/press-releases/press-release-details/2026/EGA-and-Century-Celebrate-Historic-Smelter-Project-Meet-With-U-S--Energy-Secretary-Chris-Wright/default.aspx
- [22] China Hongqiao Group Limited. (2026, August 21). Interim results announcement for the six months ended 30 June 2026. Hong Kong Exchanges and Clearing. https://www1.hkexnews.hk/listedco/listconews/sehk/2026/0821/2026082101077.pdf
- [23] Rio Tinto. (2026, May 29). Rio Tinto commissions US$1.5 billion AP60 smelter expansion in Quebec. https://www.riotinto.com/en/news/releases/2026/rio-tinto-commissions-1-5-billion-ap60-smelter-expansion-in-quebec
- [24] Novelis Inc. (2025, April 15). Novelis Opens Ulsan Aluminum Recycling Center. https://d1io3yog0oux5.cloudfront.net/_a4d16cc8289ebc30c1cdd3785c3cad64/novelis/news/2025-04-15_Novelis_Opens_Ulsan_Aluminum_Recycling_1390.pdf
- [25] Novelis Inc. (2024, July 17). Novelis Doubles Capacity to Recycle Used Beverage Cans in UK. https://investors.novelis.com/news-events/press-releases/detail/1353/novelis-doubles-capacity-to-recycle-used-beverage-cans-in-uk
- [26] Bridgnorth Aluminium Ltd. (2026, July 7). Viohalco celebrates 25 years of Bridgnorth Aluminium ownership with completion of £180m investment drive. https://bridgnorthaluminium.co.uk/?p=6679
- [27] Office of the Governor of Iowa. (2026, February 20). Gov. Reynolds, IEDA announce approval of first BIG incentives. https://governor.iowa.gov/press-release/2026-02-20/gov-reynolds-ieda-announce-approval-first-big-incentives
- [28] UACJ Corporation. (2026, May 14). Consolidated financial results for the fiscal year ended March 31, 2026 (IFRS). Japan Exchange Group. https://www2.jpx.co.jp/disc/57410/081220260513530366_tse-acedifsm-57410-20260514357410-ixbrl.htm
- [29] UACJ Corporation. (2026, May 29). IR-DAY 2026 presentation. https://www.uacj.co.jp/english/ir/assets/IR-DAY_2026_slide_en_r_1.pdf
- [30] Japan Aluminium Association. (2025, March 31). Aluminium Technology Strategy Roadmap 2025. https://www.aluminum.or.jp/wp-content/themes/dp-colors/img/roadmap_2025.pdf
- [31] Kaiser Aluminum Corporation. (2026). Form 10-K for the fiscal year ended December 31, 2025. U.S. Securities and Exchange Commission. https://www.sec.gov/Archives/edgar/data/811596/000119312526059575/kalu-20251231.htm
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Series, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Series, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Series, 2026 to 2036
- Series 1 Aluminum
- Series 2 Aluminum
- Series 3 Aluminum
- Series 4 Aluminum
- Series 5 Aluminum
- Series 6 Aluminum
- Series 7 Aluminum
- Series 8 Aluminum
- Y-o-Y Growth Trend Analysis By Series, 2021 to 2025
- Absolute $ Opportunity Analysis By Series, 2026 to 2036
- Global Market Analysis and Forecast, By Processing, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Processing, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Processing, 2026 to 2036
- Extrusions
- Castings
- Flat Rolled Aluminum
- Rods & Bars
- Pigments & Powder
- Forgings
- Y-o-Y Growth Trend Analysis By Processing, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Transportation
- Construction
- Electrical and Electronics
- Packaging
- Industrial Machinery
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Automotive Industry
- Aerospace Industry
- Building and Construction Industry
- Electrical Industry
- Packaging Industry
- Industrial Machinery
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Deployment, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Deployment, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Deployment, 2026 to 2036
- Primary Production
- Secondary Production
- Y-o-Y Growth Trend Analysis By Deployment, 2021 to 2025
- Absolute $ Opportunity Analysis By Deployment, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- Mexico
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- By Country
- Market Attractiveness Analysis
- By Country
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Chile
- Rest of Latin America
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- By Country
- Market Attractiveness Analysis
- By Country
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- BENELUX
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- By Country
- Market Attractiveness Analysis
- By Country
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- By Country
- Market Attractiveness Analysis
- By Country
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- By Country
- Market Attractiveness Analysis
- By Country
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- By Country
- Market Attractiveness Analysis
- By Country
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- By Country
- Market Attractiveness Analysis
- By Country
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- European Union
- Pricing Analysis
- Market Share Analysis, 2025
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Series
- By Processing
- By Application
- By End Use
- By Deployment
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Alcoa Corporation
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Rio Tinto
- Norsk Hydro ASA
- China Hongqiao Group Limited
- Novelis Inc.
- Century Aluminum Company
- Emirates Global Aluminium (EGA)
- Hindalco Industries Limited
- Constellium SE
- Kaiser Aluminum Corporation
- Arconic Corporation
- UACJ Corporation
- Bridgnorth Aluminium Ltd
- Alcoa Corporation
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Series, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Processing, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Deployment, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Series, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Processing, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Deployment, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Series, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Processing, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Deployment, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Series, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Processing, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Deployment, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Series, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Processing, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Deployment, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Series, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Processing, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Deployment, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Series, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Processing, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Deployment, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Series, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Processing, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Deployment, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Series, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Series, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Series
- Figure 6: Global Market Value Share and BPS Analysis by Processing, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Processing, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Processing
- Figure 9: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Application
- Figure 12: Global Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by End Use
- Figure 15: Global Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Deployment
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Series, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Series, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Series
- Figure 32: North America Market Value Share and BPS Analysis by Processing, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Processing, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Processing
- Figure 35: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Application
- Figure 38: North America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by End Use
- Figure 41: North America Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Deployment
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Series, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Series, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Series
- Figure 48: Latin America Market Value Share and BPS Analysis by Processing, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Processing, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Processing
- Figure 51: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Application
- Figure 54: Latin America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by End Use
- Figure 57: Latin America Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Deployment
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Series, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Series, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Series
- Figure 64: Western Europe Market Value Share and BPS Analysis by Processing, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Processing, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Processing
- Figure 67: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Application
- Figure 70: Western Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by End Use
- Figure 73: Western Europe Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Deployment
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Series, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Series, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Series
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Processing, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Processing, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Processing
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Application
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by End Use
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Deployment
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Series, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Series, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Series
- Figure 96: East Asia Market Value Share and BPS Analysis by Processing, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Processing, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Processing
- Figure 99: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Application
- Figure 102: East Asia Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by End Use
- Figure 105: East Asia Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Deployment
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Series, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Series, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Series
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Processing, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Processing, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Processing
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by End Use
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Deployment
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Series, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Series, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Series
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Processing, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Processing, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Processing
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by End Use
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Deployment
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Aluminium Market in 2026?
FMI estimates the market at USD 194.3 billion in 2026, up from USD 183.1 billion in 2025. FMI forecasts USD 351.2 billion for 2036 at a 6.1% CAGR.
Which alloy series leads the Aluminium Market in 2026?
Series 5 Aluminum leads by series with 22.4% in 2026. The other seven series together hold 77.6%.
Which processing route and end use lead in 2026?
Extrusions hold 29.6% by processing. Building and Construction Industry holds 27.5% by end use in FMI's 2026 assessment.
Which profiled market is forecast to grow fastest through 2036?
The European Union has the highest forecast CAGR at 4.8% during 2026 to 2036, followed by the United States at 4.5%. These are FMI forecasts and are not rates reported by the cited public bodies.
How do US tariffs affect aluminium buyers?
The Section 232 duty on aluminium articles rose to 50.0% on 4 June 2025, and from 6 April 2026 it applies to the full customs value of imported products [18][19]. Importers now compare duty-paid coil with domestic supply on every contract.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
