

- Market Size (2026)
- USD 13.3 Bn
- Forecast (2036)
- USD 35.7 Bn
- CAGR (2026 to 2036)
- 10.4%
How big is the computer-aided engineering market in 2026?
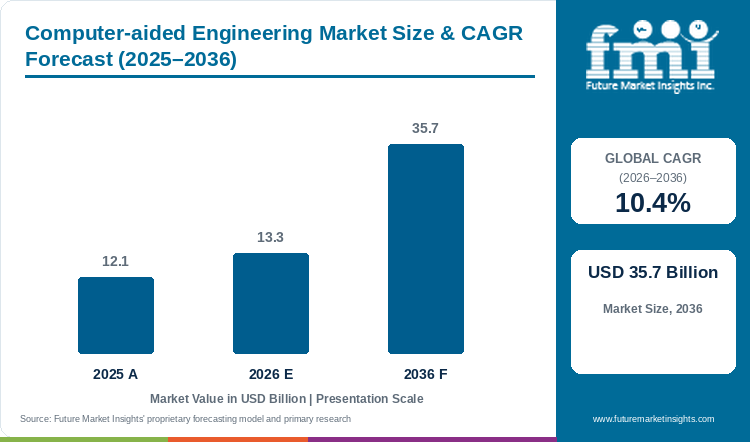
Demand is projected to expand at 10.4% CAGR from 2026 to 2036. Market value rises from USD 12.05 billion in 2025 to USD 13.3 billion in 2026 and USD 35.72 billion by 2036. [1]
Demand is estimated at USD 13.3 billion in 2026 and projected to reach USD 35.72 billion by 2036, at a CAGR of 10.4% from 2026 to 2036. [1] Computer-aided engineering supports design decisions through several simulation disciplines, allowing a team to examine behavior before a physical prototype is available. The result remains useful only when the model, operating conditions and acceptance criteria fit the question being asked, so engineering judgment and validation remain central to adoption. [2][3][4][5] Workstation systems provide one computing environment for interactive model preparation, while shared resources can support more demanding runs. Software portfolios bring several analysis disciplines together, and services help users configure methods or access expertise for a particular application. Automotive development represents a substantial demand setting because multiple performance requirements can interact within the same product, although the appropriate simulation route differs across components. [1][3][4] Deployment choices affect resource access and data management rather than removing the need to check the model against physical behavior. Over the forecast period, demand is likely to favor useful connections between design, analysis and testing, with faster computing valuable when it produces a result the engineering team can interpret and apply responsibly. [5]
Key Market Trends and Insights
- Engineering software portfolios connect several analysis disciplines, helping teams examine structural, thermal and fluid behavior within a broader product-development environment. [2][3][4]
- Cloud and local computing arrangements provide different resource options, while verification and validation remain necessary regardless of where a simulation is run. [1][5]
- Automotive design creates recurring analysis requirements across interacting components, making model consistency and the interpretation of results relevant to software and service selection. [1][3][4]
Regional Highlights
- India's engineering development and services activity supports the strongest profiled growth rate, with specialist skills and project validation influencing practical adoption. [1]
- China and Japan present substantial industrial design applications, where several analysis disciplines can contribute to the behavior of the same product. [1][2][3][4]
- US aerospace and other demanding engineering programs provide a setting in which simulation credibility and validation remain important alongside software performance. [1][5]
Market Size and Forecast
Table 1: Value outlook for the computer-aided engineering market
| Metric | Value |
|---|---|
| 2025 market value | USD 12.05 billion [1] |
| 2026 market value | USD 13.3 billion [1] |
| 2036 market value | USD 35.72 billion [1] |
| CAGR 2026 to 2036 | 10.4% [1] |
| Revenue increase 2026 to 2036 | USD 22.42 billion [1] |
| Market expansion 2026 to 2036 | 2.69 times [1] |
Growth at 10.4% CAGR from 2026 to 2036 depends on simulation that informs an actual engineering decision. Product teams need to connect the model with the expected operating condition and compare results with relevant observations, while software portfolios and services support several different analysis disciplines. Data center GPUs can provide accelerated computing for suitable workloads, although added processing capacity does not remove the need for appropriate inputs, a credible model and a defined route for evaluating the result. [1][2][3][4][5]
Why does model credibility remain central to engineering simulation?
Commercial portfolios demonstrate the breadth of structural, fluid and other simulation disciplines available to product teams. NASA's modeling and simulation standards provide a reference for credibility, verification and validation, placing numerical output within a process that also considers the intended use and acceptance criteria. These sources support a distinction between access to computing capability and the engineering evidence needed to make a dependable design decision. [2][3][4][5]
Table 2: Industry evidence relevant to the computer-aided engineering market
| Indicator | Data point or observation | Market relevance | Source |
|---|---|---|---|
| Simulation disciplines | Ansys and Siemens offer multiple engineering analysis capabilities | Software selection follows the project requirement | [2][3] |
| Connected product analysis | SIMULIA covers structural, fluid and electromagnetic simulation | Several physical effects may influence the same design | [4] |
| Model credibility | NASA standards address modeling and simulation practices | Results require verification and validation | [5] |
Analyst Perspective
"The computer-aided engineering market is likely to move toward cloud-first and AI-assisted simulation environments. Engineering teams should connect deployment choices with existing workflows and computing requirements, ensuring that simulation results can be used effectively within the design and review process for each project." [1]
— Sudip Saha, Co-founder, Future Market Insights
How is the computer-aided engineering market segmented?
The market is segmented by Solution, Deployment, End Use Industry, and Region.
By solution, coverage includes Software, Services. By deployment, coverage includes Cloud Based, On-premise. By end use industry, coverage includes Automotive, Aerospace & Defense, Electronics, Energy & Utilities, Industrial Manufacturing, Others. Regional coverage follows the report's defined geographic markets. [1]
Why does the On-premise segment lead demand within the deployment category?
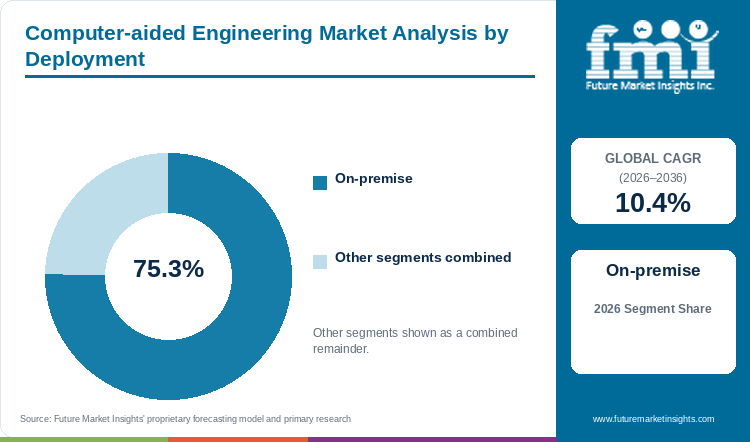
The On-premise segment accounts for 75.3% of deployment demand in 2026. [1]
On-premise deployment gives an engineering organization direct responsibility for the software and computing environment used in simulation, which can fit established project-data and infrastructure arrangements. Teams can manage their own access and configuration, although they also need to maintain enough processing and storage capacity for the intended workloads. [1] The segment's estimated position reflects that installed environment, with cloud computing providing an alternative or a complementary route for suitable tasks. The engineering requirement remains the same across both arrangements: the model must represent the intended problem and the result needs a defined review process. Buyers therefore compare deployment through resource access, support and project management rather than treating it as a substitute for verification and validation. [2][3][4][5]
- The On-premise segment is estimated to account for 75.3% of deployment demand in 2026, reflecting the continuing role of installed computing and controlled software environments within engineering simulation operations. [1]
- Resource and support responsibilities need to match the workload, while the credibility of a result depends on the model and its review process. [2][3][4][5]
Table 3: Leading deployment share in 2026
| Segment | Share of demand |
|---|---|
| On-premise | 75.3% [1] |
| Other deployment segments | 24.7% [1] |
| Total | 100.0% |
Why does the Automotive segment lead demand within the end use industry category?
The Automotive segment accounts for 28.2% of end use industry demand in 2026. [1]
Automotive development brings together many performance questions, from structural behavior and vibration to heat and airflow, giving engineering simulation a recurring role across components and systems. Software can help a team examine those interactions before physical testing, while the final interpretation still depends on appropriate material data and operating conditions. [2][3][4] The segment's share reflects this breadth of development activity, rather than suggesting that one solver or process can address every automotive task. As manufacturers consider new architectures and component designs, engineers need an analysis environment that fits the project and allows results to be checked against relevant observations, keeping simulation connected with the physical product and the decision being made. [1][5]
- The Automotive segment is estimated to account for 28.2% of end use industry demand in 2026, as vehicle development generates recurring structural, thermal, fluid and other analysis requirements across interacting components. [1]
- Engineers need consistent inputs and a clear validation route, ensuring that simulation output remains connected with the actual component and its intended operating conditions. [3][4][5]
What are the drivers, restraints, and opportunities in the computer-aided engineering market?
Driver
Product teams need to examine design choices before committing to repeated physical builds, supporting demand for software that can represent the relevant physical behavior. Simulation provides a way to compare alternatives and focus subsequent testing, while connected analysis disciplines help address interacting requirements within the same program. The demand driver is therefore a more useful design assessment, with computing performance valuable when the team can interpret the result and apply it to the actual product decision. [1][2][3][4][5]
Restraint
Simulation can require specialist knowledge of model preparation, material data and the conditions under which results are valid, making software access only one part of adoption. A detailed output may be misleading when the inputs or model do not suit the physical problem, while computing and licensing requirements add to the implementation burden. These conditions sustain demand for training and services, particularly when teams attempt to extend analysis into a new application without an established review process. [1][2][3][4][5]
Opportunity
Suppliers can connect design and analysis workflows more effectively, helping engineers carry consistent information into the model and compare results with the intended requirement. AI-assisted tools may make preparation easier, while no-code AI platforms illustrate the wider movement toward more accessible technical interfaces. The opportunity remains tied to responsible engineering use, because easier access needs to be accompanied by clear inputs, appropriate review and a dependable connection between numerical output and physical behavior. [2][3][4][5]
Which country CAGRs are profiled in the computer-aided engineering market?
Table 4: Country CAGR comparison for the computer-aided engineering market
| Country or market | CAGR 2026 to 2036 |
|---|---|
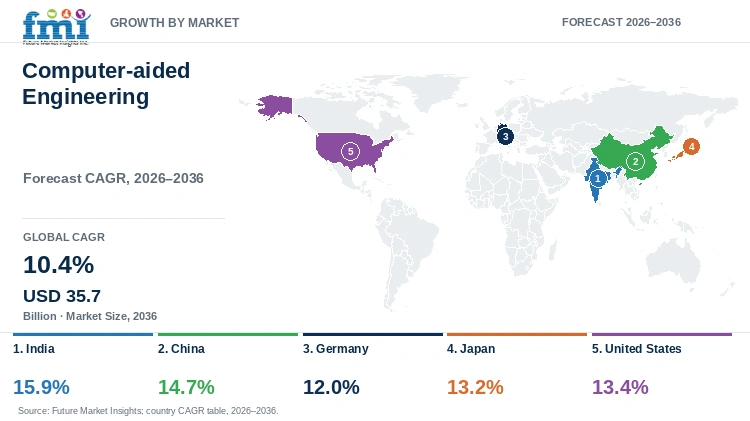
| India | 15.9% [1] |
| China | 14.7% [1] |
| Germany | 12.0% [1] |
| Japan | 13.2% [1] |
| United States | 13.4% [1] |
Country-wise Analysis
India
India's engineering services and manufacturing development activity create demand for simulation tools that can support a product decision before the team commits to repeated physical testing. The practical task is to define the model, loads and acceptance criteria clearly, because access to a solver alone does not establish a reliable prediction. [1][2][3][4] A 15.9% CAGR from 2026 to 2036 is projected for the market, with automotive and other industrial design applications supporting adoption. Buyers can compare internal capability with engineering services when specialist skills are limited, while the selected software must fit the project's data and validation requirements, giving training and review a continuing role as teams expand simulation beyond an initial development task. [5]
China
Chinese automotive and manufacturing developers face design tasks in which structural, thermal and fluid behavior may need to be considered together, creating a useful role for connected engineering simulation. The model must still represent the proposed product adequately, with material data and operating conditions informing the interpretation of results rather than letting a detailed image stand in for evidence. [1][2][3][4] The market is projected at a CAGR of 14.7% from 2026 to 2036, with demand supported by industrial product development. Suppliers can address the required analysis disciplines through software and services, while engineering teams need a defined review route that connects the simulation with physical observations and the decision the project is trying to make. [5]
Germany
Germany's automotive and industrial engineering environment places simulation within an established product-development process, where a model can inform the design but must remain connected to the intended operating condition. Teams comparing software need to consider how structural, fluid or electromagnetic results will be reviewed and used, especially when several disciplines contribute to the same component. [1][2][3][4] A 12.0% CAGR from 2026 to 2036 is projected for the market, with specialist engineering applications supporting demand. Verification and validation remain relevant to those decisions, while deployment choices influence access to computing resources and project data without changing the need for a credible model and a documented basis for accepting its results. [5]
Japan
Japanese engineering teams working on vehicles, electronics and precision products can use simulation to examine design behavior before physical hardware is available, although the value depends on an adequate model and a clear question. A team may need to compare heat, vibration and structural effects within the same program, making data consistency and the relationship between analysis disciplines important. [1][2][3][4] Demand is projected to advance at a CAGR of 13.2% from 2026 to 2036, with product-development activity supporting adoption. Software suppliers can provide a connected analysis environment, while engineers retain responsibility for checking inputs and comparing the results with relevant observations, ensuring that a faster simulation does not become detached from the physical behavior it is intended to represent. [5]
United States
US demand includes automotive, aerospace and other engineering programs in which simulation supports design assessment and the planning of physical tests. NASA's modeling and simulation references illustrate the importance of credibility and validation within demanding applications, providing a useful context for interpreting commercial software capability. [5] The market is projected at a CAGR of 13.4% from 2026 to 2036, with buyers comparing analysis disciplines and computing arrangements against the requirements of a particular project. Cloud deployment may expand access to suitable resources, but the organization still needs clear control over its model and assumptions, while software support and training help staff connect the numerical result with the product decision rather than treating solver output as sufficient evidence on its own. [1][2][3][4]
Who are the notable companies in the computer-aided engineering market?
Ansys; Siemens Digital Industries Software; Dassault Systèmes; Altair Engineering; Hexagon
Competitive Benchmarking
Ansys, Siemens and Dassault Systèmes offer broad simulation portfolios, while Altair and Hexagon bring additional engineering software and industrial-analysis relationships to the market. Buyers can compare supported disciplines, model preparation and service support against the application they need to assess, rather than selecting through a general software ranking. The organization's own engineering process remains relevant to implementation, since credible results depend on inputs and validation as well as the capabilities described in a vendor's product portfolio. [1][2][3][4][5]
Table 5: Competitive positioning for the computer-aided engineering market
| Company | Positioning | Evidence or purchasing distinction |
|---|---|---|
| Ansys | Engineering simulation software | Structural, fluid and other engineering simulation products. [2] |
| Siemens Digital Industries Software | Simcenter simulation portfolio | Engineering simulation across product-development tasks. [3] |
| Dassault Systèmes | SIMULIA simulation software | Structural, fluid, electromagnetic and multibody analysis. [4] |
| Altair Engineering | Simulation and design software | Engineering simulation and optimization offerings. [1] |
| Hexagon | Engineering analysis software | Simulation software within an industrial engineering portfolio. [1] |
Key Developments in the Computer-aided Engineering Market
- Dassault Systèmes' current SIMULIA portfolio highlights R2026x developments and connected simulation disciplines, showing how suppliers continue to broaden the engineering workflow around analysis. [4]
- Siemens' current Simcenter portfolio presents simulation across product-development tasks, maintaining a connection between engineering questions and the software capabilities used to examine them. [3]
- NASA's current modeling and simulation standard establishes practices for credibility and acceptance criteria, providing a reference for the way demanding programs evaluate simulation evidence. [5]
Key Players in the Computer-aided Engineering Market
- Ansys
- Siemens Digital Industries Software
- Dassault Systèmes
- Altair Engineering
- Hexagon
Computer-aided Engineering Market Report Scope
Table 6: Report coverage for the computer-aided engineering market
| Attribute | Coverage |
|---|---|
| Market | Computer-aided Engineering Market |
| Currency and unit | USD billion; market revenue |
| Historical reference year | 2025 |
| Base year | 2026 |
| Forecast period | 2026 to 2036 |
| Segmentation | Solution, Deployment, End Use Industry |
| Country profiles | India; China; Germany; Japan; United States |
| Competitive coverage | Ansys; Siemens Digital Industries Software; Dassault Systèmes; Altair Engineering; Hexagon |
| Geographic coverage | North America, Latin America, Europe, East Asia, South Asia and Pacific, Middle East and Africa |
Computer-aided Engineering Market Research Methodology
Table 7: Research methods for the computer-aided engineering market
| Method | Approach |
|---|---|
| Market definition | Revenue coverage is defined around computer-aided engineering offerings and their related commercial services, with adjacent markets retained as context. |
| Desk research | Public FMI outlooks, direct product documentation, institutional publications and official guidance provide the source base. |
| Segment assessment | Categories are assessed against their functional role, purchasing decisions and reported market structure, with shares kept within their own segmentation axes. |
| Country assessment | Country demand is examined through local customer requirements, industry composition and implementation conditions, with a consistent 2026 to 2036 forecast period. |
| Competitive comparison | Participants are compared through documented offerings and business roles; product features and service models are distinguished from market-share rankings. |
| Forecast assessment | The outlook considers adoption, replacement, integration effort and commercial constraints, expressing monetary forecasts and segment estimates in consistent units. |
Computer-aided Engineering Market by Segments
Computer-aided Engineering Market segmented by Solution:
- Software
- Services
Computer-aided Engineering Market segmented by Deployment:
- Cloud Based
- On-premise
Computer-aided Engineering Market segmented by End Use Industry:
- Automotive
- Aerospace & Defense
- Electronics
- Energy & Utilities
- Industrial Manufacturing
- Others
Computer-aided Engineering Market by Region
North America
- United States
- Canada
- Mexico
Latin America
- Brazil
- Chile
- Rest of Latin America
Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
Eastern Europe
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
East Asia
- China
- Japan
- South Korea
South Asia and Pacific
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
Middle East & Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Turkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
Research Sources and Bibliography
[1] Future Market Insights. Accessed 14 October 2026. Computer-aided Engineering Market
[2] Ansys, a Synopsys company. Accessed 14 October 2026. Engineering simulation products
[3] Siemens. Accessed 14 October 2026. Simcenter simulation software
[4] Dassault Systèmes. Accessed 14 October 2026. SIMULIA simulation software
[5] NASA. Accessed 14 October 2026. Standard for Models and Simulations
This Report Answers
- How big is the computer-aided engineering market in 2026?
- What is the outlook for the computer-aided engineering market through 2036?
- Which deployment segment is highlighted?
- Which markets are included in the growth comparison?
- Which participants are included in the competitive assessment?
Frequently Asked Questions
How big is the computer-aided engineering market in 2026?
The market is estimated at USD 13.3 billion in 2026, compared with USD 12.05 billion in 2025. [1]
What is the outlook for the computer-aided engineering market through 2036?
Revenue is projected to reach USD 35.72 billion by 2036, with a CAGR of 10.4% from 2026 to 2036. [1]
Which deployment segment is highlighted?
The On-premise segment accounts for an estimated 75.3% share in 2026, reflecting the purchasing conditions described in the segment analysis. [1]
Which markets are included in the growth comparison?
The comparison profiles India, China, Germany, Japan, United States and presents their demand outlooks for 2026 to 2036. [1]
Which participants are included in the competitive assessment?
The assessment includes Ansys, Siemens Digital Industries Software, Dassault Systèmes, Altair Engineering, Hexagon, with positioning based on each participant's documented business role. [1]
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Solution, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Solution, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Solution, 2026 to 2036
- Software
- Services
- Y-o-Y Growth Trend Analysis By Solution, 2021 to 2025
- Absolute $ Opportunity Analysis By Solution, 2026 to 2036
- Global Market Analysis and Forecast, By Deployment, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Deployment, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Deployment, 2026 to 2036
- Cloud Based
- On-premise
- Y-o-Y Growth Trend Analysis By Deployment, 2021 to 2025
- Absolute $ Opportunity Analysis By Deployment, 2026 to 2036
- Global Market Analysis and Forecast, By End Use Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use Industry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use Industry, 2026 to 2036
- Automotive
- Aerospace & Defense
- Electronics
- Energy & Utilities
- Industrial Manufacturing
- Others
- Y-o-Y Growth Trend Analysis By End Use Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- Mexico
- By Solution
- By Deployment
- By End Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By Deployment
- By End Use Industry
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Chile
- Rest of Latin America
- By Solution
- By Deployment
- By End Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By Deployment
- By End Use Industry
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Solution
- By Deployment
- By End Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By Deployment
- By End Use Industry
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Solution
- By Deployment
- By End Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By Deployment
- By End Use Industry
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Solution
- By Deployment
- By End Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By Deployment
- By End Use Industry
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Solution
- By Deployment
- By End Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By Deployment
- By End Use Industry
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Turkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Solution
- By Deployment
- By End Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By Deployment
- By End Use Industry
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Deployment
- By End Use Industry
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Deployment
- By End Use Industry
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Deployment
- By End Use Industry
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Deployment
- By End Use Industry
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Deployment
- By End Use Industry
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Deployment
- By End Use Industry
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Deployment
- By End Use Industry
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Deployment
- By End Use Industry
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Deployment
- By End Use Industry
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Deployment
- By End Use Industry
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Deployment
- By End Use Industry
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Deployment
- By End Use Industry
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Deployment
- By End Use Industry
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Deployment
- By End Use Industry
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Deployment
- By End Use Industry
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Deployment
- By End Use Industry
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Deployment
- By End Use Industry
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Deployment
- By End Use Industry
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Deployment
- By End Use Industry
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Deployment
- By End Use Industry
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Deployment
- By End Use Industry
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Solution
- By Deployment
- By End Use Industry
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Ansys
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Siemens Digital Industries Software
- Dassault Systèmes
- Altair Engineering
- Hexagon
- Ansys
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


