
- Market Size (2026)
- USD 178.8 Bn
- Forecast (2036)
- USD 388.3 Bn
- CAGR (2026 to 2036)
- 8.1%
How big is Engineering Plastics Market in 2026?
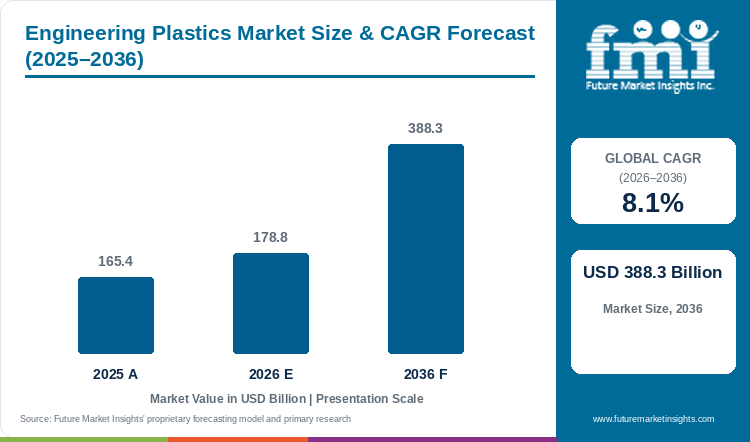
Sales of engineering plastics will grow at a CAGR of 8.1% from 2026 to 2036. Market size was USD 165.4 billion in 2025 and is projected to reach USD 178.8 billion in 2026 and USD 388.3 billion by 2036.
The engineering plastics market stood at USD 165.4 billion in 2025, is estimated at USD 178.8 billion in 2026 and is projected to reach USD 388.3 billion by 2036, growing at a CAGR of 8.1% from 2026 to 2036.
Producers are adding capacity. Polyplastics reported on 1 October 2025 that Phase 1 of the Nantong POM plant, at 90,000 tons a year, was expected to reach full capacity by March 2026, and Phase 2 adds 60,000 tons in fiscal year 2027, taking the China total to 150,000 tons a year.[1] Arkema is investing around USD 20 million in a Singapore unit that will triple Arkema's global Rilsan Clear transparent polyamide capacity, with operation expected in the first quarter of 2026.[2] Wider supply of transparent polyamide will serve eyewear, electronics and healthcare buyers.
Polyamides hold 23.5% of product type sales and automotive and transportation holds 34% of application sales in 2026, FMI finds.
Key Market Trends & Insights
- By product type, polyamides led with 23.5% of sales in 2026, ahead of polycarbonates at 15% and ABS and styrene acrylonitrile at 13%, backed by mechanical strength, thermal stability and under-the-hood automotive use. BASF reported that prices fell in engineering plastics in 2025.[3]
- By application, automotive and transportation held 34% of sales in 2026, followed by electrical and electronics at 25% and industrial and machinery at 12%, on safety, flame retardance and insulation functions.
Regional Highlights
- Fastest-growing profiled country: China (6.2% CAGR, 2026 to 2036).
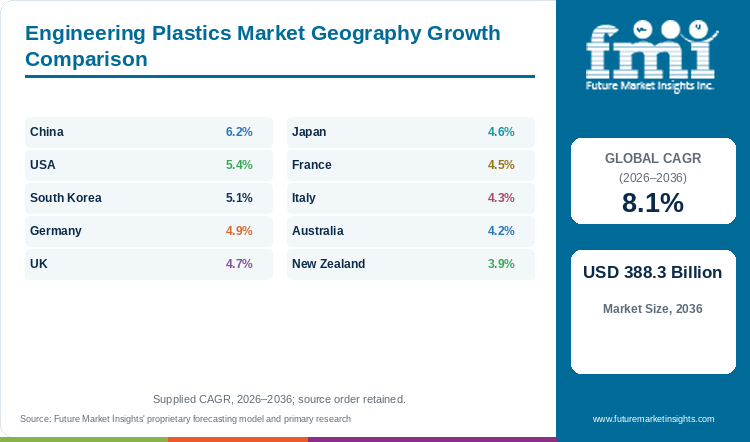
- By country: the USA (5.4%) and South Korea (5.1%) follow, then Germany at 4.9%, the UK at 4.7%, Japan at 4.6%, France at 4.5%, Italy at 4.3% and Australia at 4.2%, with New Zealand recording the lowest profiled CAGR at 3.9%.
- China set anti-dumping duties of up to 74.9% on POM copolymer imports from the United States, Reuters reported on 18 May 2025.[4]
Market Size & Forecast
Table 1: Market Size and Forecast for the Engineering Plastics Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 165.4 billion |
| Estimated Market Size in 2026 | USD 178.8 billion |
| Projected Market Size by 2036 | USD 388.3 billion |
| CAGR, 2026 to 2036 | 8.1% |
| Added Revenue, 2026 to 2036 | USD 209.5 billion |
| Market Expansion Multiple | 2.2x |
Engineering plastics market size is projected to add USD 209.5 billion between 2026 and 2036, a 2.2x expansion on the 2026 base. FMI ties the build to lightweight, durable materials in automotive and electronics, electric vehicle expansion and industrial automation. BASF reported Performance Materials sales of EUR 6,425 million for 2025, down from EUR 6,848 million, with prices lower especially in engineering plastics.[3] Raw material price volatility and trade tension, including possible export controls by major producers such as China, remain the main restraints.
Capacity Additions, Closures and Delivered Output by Producer
Capacity moves in 2025 and 2026 run in both directions. Polyplastics is adding POM in China and cyclic olefin copolymer in Germany, and Arkema is building a Singapore unit to triple global Rilsan Clear capacity.[1][2] Celanese closed the Ulsan compounding facility and completed a nylon 6,6 network optimisation ahead of schedule.[5] The additions named here are specialty grades. The subtraction is a compounding site.
Delivered capacity is a separate test. Victrex booked a GBP 60.6 million non-cash impairment on the Panjin plant in China, since the plant is not capable of the full intended nameplate capacity of 1,500 tonnes, and Victrex expects around 100 tonnes of sales from the plant in fiscal 2026.[6] Against an 8.1% market CAGR, a line that ramps slowly leaves buyers short of approved grades. LG Chem reported lower Petrochemicals sales volumes after the temporary shutdown of the Yeosu 2NCC plant.[7] Utilisation, not announced tonnage, will separate suppliers.
Table 2: Capacity and Footprint Indicators for the Engineering Plastics Market (tons, tonnes, dates and currency), mixed reporting years from 2025 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Polyplastics POM, Nantong, China, October 2025 | Phase 1 of 90,000 tons a year began November 2024 and was expected at full capacity by March 2026; Phase 2 adds 60,000 tons in fiscal year 2027 | China POM capacity reaches 150,000 tons a year after Phase 2. | [1] |
| Polyplastics COC, Leuna, Germany, October 2025 | New 25,000 ton plant that will more than double current output; commercial start-up expected in the second quarter of 2026 | Capacity additions are not limited to Asia. | [1] |
| Arkema Rilsan Clear, Singapore, July 2025 | Investment of around USD 20 million; triples global Rilsan Clear production capacity; operation expected in the first quarter of 2026 | Transparent polyamide supply widens for eyewear, electronics and healthcare buyers. | [2] |
| Celanese Ulsan, South Korea, second quarter 2026 | Compounding unit closure completed; production moved to larger assets in China and India | Korean compounding capacity leaves the Celanese network. | [5] |
| Celanese nylon 6,6 and POM, second quarter 2026 | Network optimisation completed ahead of schedule; largest POM turnaround in five years | Footprint work and a major POM outage fell in the same period. | [5] |
| Victrex Panjin, China, May 2026 | Nameplate capacity of 1,500 tonnes not deliverable; GBP 60.6 million impairment; around 100 tonnes expected in fiscal 2026 | Expected 2026 sales at the plant are well under the nameplate figure. | [6] |
| BASF Ludwigshafen, Germany, 2025 | Materials segment special charges of EUR 73 million, above all for adapting the production structure at Ludwigshafen | German production structure is being adapted. | [3] |
| LG Chem Yeosu 2NCC, South Korea, second quarter 2026 | Temporary shutdown lowered Petrochemicals sales volumes | ABS is listed among the product lines of the affected segment. | [7] |
Analyst Perspective
“Capacity is being reshaped in both directions, with specialty lines added in China, Germany and Singapore and a compounding site closed in South Korea. Buyers that qualify grades from producers with proven utilisation, not announced tonnage, will protect supply through 2036.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the engineering plastics market segmented?
The engineering plastics market is segmented into product type and application, and region. In 2026, polyamides hold 23.5% of product type sales and polycarbonates hold 15%. Automotive and transportation holds 34% of application sales, and electrical and electronics holds 25%.
By product type: polyamides, polycarbonates, polyoxymethylene, polybutylene terephthalate, ABS and styrene acrylonitrile, high-performance polymers, fluoropolymers, polymethyl methacrylate, and others.
By application: automotive and transportation, electrical and electronics, construction, medical, industrial and machinery, packaging, and others.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do polyamides lead product type sales?
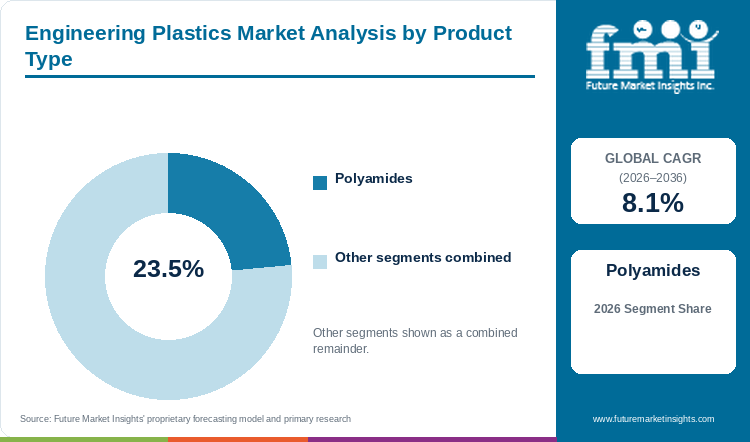
Polyamides account for 23.5% of product type sales in 2026, ahead of polycarbonates at 15%.
Table 3: Product Type Share for the Engineering Plastics Market (percentage share), 2026
| Product Type | Estimated Share (2026) |
|---|---|
| Polyamides | 23.5% |
| Polycarbonates | 15% |
| ABS and Styrene Acrylonitrile | 13% |
| Polyoxymethylene | 10% |
| Polybutylene Terephthalate | 9.5% |
| High-Performance Polymers | 9% |
| Polymethyl Methacrylate | 7.5% |
| Fluoropolymers | 6.5% |
| Others | 6% |
| Total | 100% |
Table 4: Product Type Leadership and Market Growth for the Engineering Plastics Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 8.1% |
| Leading Segment | Polyamides |
Mechanical strength, thermal stability and under-the-hood automotive use put polyamides at 23.5% of product type sales in 2026 in the FMI report. Polycarbonates follow at 15%, prized for clarity, impact and heat resistance. BASF reported Performance Materials sales of EUR 6,425 million for 2025, down from EUR 6,848 million in 2024, reflecting lower prices across engineering plastics.[3] Celanese completed the optimisation of the nylon 6,6 network ahead of schedule in the second quarter of 2026.[5] Buyers read the nylon-6 market alongside nylon 6,6 when choosing grades. Cost position in the group follows intermediates, not resin capacity alone.
- Under-the-hood automotive use anchors polyamide demand.
- BASF Performance Materials sales were EUR 6,425 million in 2025, against EUR 6,848 million in 2024.[3]
What makes automotive and transportation the largest application?
Automotive and transportation account for 34% of application sales in 2026, ahead of electrical and electronics at 25%.
Table 5: Application Share for the Engineering Plastics Market (percentage share), 2026
| Application | Estimated Share (2026) |
|---|---|
| Automotive and Transportation | 34% |
| Electrical and Electronics | 25% |
| Industrial and Machinery | 12% |
| Construction | 10% |
| Medical | 8% |
| Packaging | 6% |
| Others | 5% |
| Total | 100% |
Safety, flame retardance and insulation are the functions FMI assigns to engineering plastics, and automotive and transportation takes 34% of application sales in 2026 on the strength of them. Electrical and electronics follows at 25%. The automotive composites market tracks the lightweight side of the same vehicle programmes, and the automotive electronics market tracks the electrical side. Celanese cited continued momentum in medical and electronics in the second-quarter 2026 release.[5] Construction, medical, industrial, packaging and other uses share the remaining 41%.
- Interiors and safety, exteriors and structural parts, and engine and mechanical parts are the automotive groupings.
- DuPont reported mid-single-digit organic sales growth in Industrial Technologies in the second quarter of 2026, supported by aerospace and growth in electric vehicle applications.[8]
What are the drivers, restraints, and opportunities in the engineering plastics market?
In the engineering plastics market, demand for lightweight, durable materials in automotive and electronics drives sales, raw material price volatility and trade tension restrain supply, and circular economy innovation and growth in Asia-Pacific and Latin America open the main opportunity.
- Driver: Lightweight, durable materials for automotive and electronics, electric vehicle expansion and industrial automation drive sales.
- Restraint: Price volatility of petrochemical raw materials, regulatory attention to plastic waste, and trade tension, including possible export controls by major producers such as China.
- Opportunity: Smart technologies such as sensors and conductive materials, bio-based and recyclable plastics, and growth in Asia-Pacific and Latin America.
Electronics and Vehicle Programmes Pull Sales Forward
Celanese reported Engineered Materials net sales of USD 1.45 billion for the second quarter of 2026, up 9% on the first quarter from a 3% volume increase and a 6% price increase.[5] Celanese cited momentum in medical and electronics. Pricing added twice as much as volume to the sequential gain.
Raw Material Costs and Trade Duties Squeeze Margins
Higher raw material costs in Engineered Materials are named by Celanese as a third-quarter 2026 headwind.[5] China set POM copolymer duties of up to 74.9% on US shipments and 34.5% on EU shipments, Reuters reported on 18 May 2025.[4] Price volatility and export controls are the restraints FMI names, and both reach buyers through cost.
Specialty Grades and Asian Capacity Offer the Opening
Arkema said the Rilsan Clear unit in Singapore, an investment of around USD 20 million, would triple global Rilsan Clear production capacity, with operation expected in the first quarter of 2026.[2] Growth in Asia-Pacific and Latin America is the regional opportunity named for the market. Suppliers moving from engineering resins into higher-performance grades meet a separate buyer group, tracked in the fluoropolymer market.
Which country CAGRs are profiled in the engineering plastics market?
Table 6: Country CAGR Comparison for the Engineering Plastics Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| China | 6.2% |
| USA | 5.4% |
| South Korea | 5.1% |
| Germany | 4.9% |
| UK | 4.7% |
| Japan | 4.6% |
| France | 4.5% |
| Italy | 4.3% |
| Australia | 4.2% |
| New Zealand | 3.9% |
How do country-level CAGRs compare in the engineering plastics market?
National rates for engineering plastics span 2.3 percentage points. As per the FMI country analysis, China leads at 6.2% CAGR from 2026 to 2036, followed by the USA at 5.4% and South Korea at 5.1%. Germany is projected at 4.9%, the UK at 4.7% and Japan at 4.6%. France, Italy, Australia and New Zealand close the table at 4.5%, 4.3%, 4.2% and 3.9%.
- China pairs Asia-Pacific capacity spending with duties on imported POM copolymer.
- The USA faces the highest Chinese duty rate on POM copolymer, at 74.9%.
- South Korea combines the Celanese Ulsan closure with the LG Chem Yeosu 2NCC shutdown.
- Germany combines Covestro price gains, BASF site adaptation and a new Polyplastics plant at Leuna.
- The UK links high-performance polymer sales to the Victrex volume and price figures for the first half of fiscal 2026.
- Japan faces a 35.5% general duty on POM copolymer in China, with Asahi Kasei at 24.5%.
- France is tied to the BASF hexamethylenediamine plant at Chalampé.
- Italy is projected at 4.3% on the automotive and electronics drivers shared with Western Europe.
- Australia is projected at 4.2%, within the Asia-Pacific growth opportunity.
- New Zealand records the lowest profiled rate at 3.9%.
Full report country CAGRs cover: United States; China; South Korea; United Kingdom; Germany; France; Japan; Italy; Australia; New Zealand.
Country-wise Analysis
China Engineering Plastics Market Outlook (2026 to 2036)
Duties on imported POM copolymer reshape the supply options of buyers in China. The commerce ministry set rates of up to 74.9% on US shipments, Reuters reported on 18 May 2025.[4] Plants inside the country matter more as a result, and Polyplastics plans 150,000 tons a year of POM at Nantong once Phase 2 is complete.[1] Victrex shows the other side, since the Panjin plant cannot yet deliver the 1,500 tonne nameplate capacity.[6] The polyoxymethylene market follows POM at global level. China is projected to grow at a CAGR of 6.2% from 2026 to 2036, the highest of the ten profiled countries.
Key takeaway: In China, duties favour local POM output, and ramp-up risk at new plants stays with the buyer.
USA Engineering Plastics Market Outlook (2026 to 2036)
Portfolio changes at US producers show in second-quarter 2026 reporting. Celanese said the nylon 6,6 network optimisation finished ahead of schedule, and Engineered Materials net sales reached USD 1.45 billion in the second quarter.[5] DuPont said on 4 August 2026 that the Aramids sale to Arclin closed on 1 April 2026 for pre-tax cash proceeds of about USD 1.2 billion, and that Corporate includes the equity stake acquired in the Delrin divestiture.[8] The USA is projected to grow at a CAGR of 5.4% from 2026 to 2036. US exporters of POM copolymer meet the top Chinese duty rate of 74.9%.[4]
Key takeaway: US buyers see supplier portfolio changes ahead of new capacity, so dual-qualified grades protect supply.
South Korea Engineering Plastics Market Outlook (2026 to 2036)
South Korea is projected to grow at a CAGR of 5.1% from 2026 to 2036, behind China and the USA. Two footprint moves fell in the same quarter. Celanese completed the closure of the Ulsan compounding facility, moving production to larger assets in China and India.[5] LG Chem reported that Petrochemicals profitability improved despite lower sales volumes after the temporary shutdown of the Yeosu 2NCC plant, and ABS is among the segment product lines.[7]
Key takeaway: In South Korea, buyers of compounded grades now check the plant of origin for each approved material.
Germany Engineering Plastics Market Outlook (2026 to 2036)
Covestro raised the 2026 EBITDA outlook on 9 July 2026, citing higher prices and raw material costs that rose with a lag.[9] First-half sales were EUR 6,729 million and EBITDA was EUR 669 million.[9] BASF booked EUR 73 million of special charges in the Materials segment in 2025, above all for adapting the production structure at Ludwigshafen.[3] Polyplastics plans a 25,000 ton COC plant at Leuna, with start-up expected in the second quarter of 2026.[1] Germany is projected at 4.9% CAGR from 2026 to 2036.
Key takeaway: German buyers meet price increases from producers that are also trimming sites, so contract terms carry weight.
UK Engineering Plastics Market Outlook (2026 to 2036)
Victrex reported on 11 May 2026 that group sales volume rose 6% to 2,137 tonnes in the first half, and that average selling price fell 4% to GBP 69 per kg.[6] Headcount is being reduced by about 10%, primarily in central functions.[6] The UK is projected at a CAGR of 4.7% from 2026 to 2036, the fifth-highest of the ten profiled countries.
Key takeaway: In the UK, volume growth with falling prices tilts negotiations toward buyers of high-performance grades.
Japan Engineering Plastics Market Outlook (2026 to 2036)
Japan is projected to grow at a CAGR of 4.6% from 2026 to 2036, according to FMI. Reuters reported on 18 May 2025 a general duty of 35.5% on Japanese POM copolymer in China, with Asahi Kasei receiving a company-specific rate of 24.5%.[4] Asahi Kasei therefore ships POM copolymer into China at a lower duty than other Japanese exporters.
Key takeaway: Japanese POM exporters to China pay different duties by company, so rate gaps shape export routes.
France Engineering Plastics Market Outlook (2026 to 2036)
BASF reported that the startup of the hexamethylenediamine plant in Chalampé, France, reduced investments in the Monomers division in 2025.[3] France is projected at 4.5% CAGR from 2026 to 2036, and the polyamide chain anchors local supply.
Key takeaway: In France, polyamide buyers track BASF announcements, as Chalampé is the main local plant change.
Italy Engineering Plastics Market Outlook (2026 to 2036)
Italy ranks eighth of the ten profiled countries at a projected CAGR of 4.3% from 2026 to 2036. Automotive and electronics converters in the country face the raw material and price pressures seen across Western Europe. Supplier moves in Germany and France reach Italian buyers through contract terms and delivery schedules.
Key takeaway: In Italy, supplier decisions made elsewhere in Western Europe set the terms for converters.
Australia Engineering Plastics Market Outlook (2026 to 2036)
Australia is projected at a CAGR of 4.2% from 2026 to 2036, as part of the wider Asia-Pacific growth opportunity. Buyers of construction, medical and industrial grades draw on imports from Asian and European producers, so duty and freight changes elsewhere reach local converters.
Key takeaway: For Australia, the exposure is to import terms, not to local plant decisions.
New Zealand Engineering Plastics Market Outlook (2026 to 2036)
New Zealand records the lowest profiled CAGR at 3.9% from 2026 to 2036. A small buyer base limits the volume that suppliers allocate to the country, and converters source mostly through distributors and imports.
Key takeaway: New Zealand buyers get supply through importers, so range and lead time matter more than local production.
Who are the notable companies in the engineering plastics market?
BASF, DuPont, Covestro, LG Chem, Arkema Group, Asahi Kasei Corporation, Celanese Corporation, Envalior, Envalior, and Mitsubishi Engineering-Plastics Corporation are notable companies profiled in this market.
BASF holds 15% to 19% of the market, ahead of DuPont at 12% to 16%, Covestro at 10% to 14%, LG Chem at 8% to 12% and Arkema Group at 6% to 10%, with other companies holding 35% to 45% together. Recent moves differ sharply across the five. BASF reported lower prices in engineering plastics for 2025.[3] DuPont completed the sale of the Aramids business on 1 April 2026 and holds an equity stake from the Delrin divestiture.[8] Covestro raised the 2026 EBITDA outlook on 9 July 2026, citing higher prices.[9] Celanese closed the Ulsan compounding facility.[5] Portfolio moves, more than new tonnes, mark company position in 2026.
- Share leaders: BASF, DuPont, Covestro, LG Chem, and Arkema Group.
- Other key producers: Asahi Kasei Corporation, Celanese Corporation, Envalior, Envalior, and Mitsubishi Engineering-Plastics Corporation.
Competitive Benchmarking: Engineering Plastics Market
Table 7: Competitive Benchmarking for the Engineering Plastics Market (qualitative documentation ratings), 2026
| Company | Engineering plastics scope | Capacity or footprint action | Product detail | Disclosure |
|---|---|---|---|---|
| Celanese | High | High | Medium | High |
| Arkema | Medium | High | High | High |
| BASF | High | Medium | Low | High |
| DuPont | Low | High | Low | High |
| LG Chem | Low | Medium | Low | High |
| Covestro | Low | Low | Low | High |
High indicates wider documentation in company filings and releases, Medium indicates limited documentation, and Low indicates less direct documentation. Ratings do not indicate product quality, market share or company rank.
Key Developments in the Engineering Plastics Market
- In second-quarter 2026 results, Celanese reported the Ulsan compounding closure and the completed nylon 6,6 network optimisation.[5]
- On 4 August 2026, DuPont reported that the Aramids sale to Arclin closed on 1 April 2026.[8]
- On 31 July 2026, LG Chem reported lower Petrochemicals sales volumes after the temporary Yeosu 2NCC shutdown.[7]
- On 9 July 2026, Covestro raised the 2026 EBITDA outlook and reported preliminary first-half EBITDA of EUR 669 million.[9]
- On 11 May 2026, Victrex booked a GBP 60.6 million impairment on the Panjin plant in China.[6]
- On 27 February 2026, BASF published Performance Materials sales of EUR 6,425 million for 2025.[3]
- On 1 October 2025, Polyplastics updated the POM, COC and LCP capacity additions ahead of K 2025.[1]
- In July 2025, Arkema announced a Rilsan Clear unit in Singapore to triple global Rilsan Clear capacity.[2]
- On 18 May 2025, Reuters reported that China set anti-dumping duties of up to 74.9% on POM copolymer from the United States, the EU, Japan and Taiwan.[4]
Key Players in the Engineering Plastics Market
Market Share Leaders
- BASF SE
- DuPont
- Covestro AG
- LG Chem
- Arkema Group
Other Key Producers
- Asahi Kasei Corporation
- Celanese Corporation
- DSM N.V.
- Lanxess
- Mitsubishi Engineering-Plastics Corporation
Other Producers with Capacity Moves
- Polyplastics Co., Ltd.
- Victrex plc
Engineering Plastics Market - Report Scope
Table 8: Report Scope for the Engineering Plastics Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; application; region |
| Quantitative units | USD billion |
| Market definition | Engineering plastics market covering polyamides, polycarbonates, polyoxymethylene, polybutylene terephthalate, ABS and styrene acrylonitrile, high-performance polymers, fluoropolymers and polymethyl methacrylate, tracked by application. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | China; USA; South Korea; Germany; UK; Japan; France; Italy; Australia; New Zealand |
| Key companies profiled | BASF, DuPont, Covestro, LG Chem, Arkema Group, Asahi Kasei, Celanese, DSM N.V., Lanxess, Mitsubishi Engineering-Plastics |
| Forecast period | 2026 to 2036 |
Engineering Plastics Market - Research Methodology
Table 9: Research Methodology for the Engineering Plastics Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Capacity and trade facts come from company filings, company releases, a Chinese commerce ministry ruling as reported by a news agency and trade press dated May 2025 or later. |
| Desk Research | Desk research covers company results, capacity announcements and plant closures reported in 2025 and 2026. |
| Market Sizing and Forecasting | Sizing starts from the 2025 base market size of USD 165.4 billion and the 8.1% CAGR. |
| Data Validation | Figures are cross-checked across company results, trade rulings and trade press published from May 2025 onward. |
Engineering Plastics Market by Segments
Engineering Plastics Market segmented by Product Type:
- Polyamides
- Polycarbonates
- Polyoxymethylene
- Polybutylene Terephthalate
- ABS and Styrene Acrylonitrile
- High-Performance Polymers
- Fluoropolymers
- Polymethyl Methacrylate
- Others
Engineering Plastics Market segmented by Application:
- Automotive and Transportation
- Electrical and Electronics
- Construction
- Medical
- Industrial and Machinery
- Packaging
- Others
Engineering Plastics Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Eastern Europe
- Poland
- Russia
- Czech Republic
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- Indonesia
- Malaysia
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- Turkey
- South Africa
Research Sources and Bibliography
- [1] Polyplastics Co., Ltd. (press release carried by Polymer Update). (2025, October 1). Polyplastics to Announce Update on New Capacity Expansions for COC, POM, and LCP at K Show. https://www.polymerupdate.com/PressRelease/Details/37337
- [2] Arkema (Business Wire press release). (2025, July). Arkema Invests in a New Rilsan Clear Transparent Polyamide Unit in Singapore. https://www.businesswire.com/news/home/20250708196098/en
- [3] BASF SE. (2026, February 27). BASF Report 2025, Materials segment. https://report.basf.com/2025/en/combined-managements-report/basf-groups-business-year/segments/materials
- [4] Reuters (via Yahoo Finance). (2025, May 18). China slaps anti-dumping duties on plastics from US, EU, Japan, Taiwan. https://finance.yahoo.com/news/china-announces-anti-dumping-duties-060113340.html
- [5] Celanese Corporation (Business Wire). (2026). Celanese Corporation Reports Second Quarter Earnings. https://www.businesswire.com/news/home/20260730200927/en/
- [6] Victrex plc. (2026, May 11). Interim Results 2026 (Regulatory News Service announcement). https://data.fca.org.uk/artefacts/NSM/RNS/45f704f7-9a18-4b8f-9255-8eaea0036c1b.html
- [7] LG Chem. (2026, July 31). 2Q 2026 Earnings Release. https://www.lgchem.com/upload/file/ir-events/2Q_2026_earnings_release_ENG.pdf
- [8] DuPont de Nemours, Inc. (SEC Form 8-K, Exhibit 99.1). (2026, August 4). DuPont reports second quarter 2026 results. https://www.sec.gov/Archives/edgar/data/0001666700/000166670026000049/exhibit991enrschedules-2q26.htm
- [9] Covestro AG. (2026, July 9). Preliminary financial data for the first half year 2026 (carried by Polymer Update). https://www.polymerupdate.com/PressRelease/Details/41297
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the engineering plastics market during 2026?
- What market size is projected by 2036?
- Which product type and application hold notable share?
- Which capacity changes shape supply?
- Which countries have notable growth?
- Which companies are notable in the market?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Polyamides
- Polycarbonates
- Polyoxymethylene
- Polybutylene Terephthalate
- ABS and Styrene Acrylonitrile
- High-Performance Polymers
- Fluoropolymers
- Polymethyl Methacrylate
- Others
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Automotive and Transportation
- Electrical and Electronics
- Construction
- Medical
- Industrial and Machinery
- Packaging
- Others
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- By Product Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- By Product Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Russia
- Czech Republic
- By Product Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- Indonesia
- Malaysia
- Australia and New Zealand
- By Product Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- Turkey
- South Africa
- By Product Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Celanese
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Arkema
- BASF
- DuPont
- LG Chem
- Covestro
- BASF SE
- Covestro AG
- Arkema Group
- Asahi Kasei Corporation
- Celanese Corporation
- DSM N.V.
- Lanxess
- Mitsubishi Engineering-Plastics Corporation
- Polyplastics Co., Ltd.
- Victrex plc
- Celanese
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 4: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 7: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: Latin America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 10: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 11: Western Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 12: Western Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 13: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Eastern Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 15: Eastern Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 16: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: East Asia Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 18: East Asia Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 19: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 21: South Asia and Pacific Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 22: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 23: Middle East and Africa Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 24: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type
- Figure 6: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Application
- Figure 9: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Region
- Figure 12: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 13: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 14: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 15: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 20: North America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 21: North America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 22: North America Market Attractiveness Analysis by Product Type
- Figure 23: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Application
- Figure 26: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 27: Latin America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 28: Latin America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 29: Latin America Market Attractiveness Analysis by Product Type
- Figure 30: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 31: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 32: Latin America Market Attractiveness Analysis by Application
- Figure 33: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 34: Western Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 35: Western Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 36: Western Europe Market Attractiveness Analysis by Product Type
- Figure 37: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 38: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 39: Western Europe Market Attractiveness Analysis by Application
- Figure 40: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 41: Eastern Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 42: Eastern Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 43: Eastern Europe Market Attractiveness Analysis by Product Type
- Figure 44: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 45: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 46: Eastern Europe Market Attractiveness Analysis by Application
- Figure 47: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 48: East Asia Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 49: East Asia Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 50: East Asia Market Attractiveness Analysis by Product Type
- Figure 51: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 52: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 53: East Asia Market Attractiveness Analysis by Application
- Figure 54: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 55: South Asia and Pacific Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 56: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 57: South Asia and Pacific Market Attractiveness Analysis by Product Type
- Figure 58: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 59: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 60: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 61: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 62: Middle East and Africa Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 63: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 64: Middle East and Africa Market Attractiveness Analysis by Product Type
- Figure 65: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 66: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 67: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 68: Global Market - Tier Structure Analysis
- Figure 69: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the engineering plastics market expected in 2026?
Market size is projected to reach USD 178.8 billion in 2026 and USD 388.3 billion by 2036, as per Future Market Insights. Market size was USD 165.4 billion in 2025.
What CAGR is projected for the engineering plastics market through 2036?
As per FMI analysis, sales of engineering plastics will grow at a CAGR of 8.1% from 2026 to 2036. Demand for lightweight, durable materials in automotive and electronics supports the outlook.
Which product type and application hold notable market shares in 2026?
In 2026, polyamides hold 23.5% of product type sales, and polycarbonates hold 15%. Automotive and transportation accounts for 34% of application sales, and electrical and electronics accounts for 25%.
Which capacity changes are under way in the engineering plastics market?
Arkema plans to triple Rilsan Clear capacity in Singapore, and Polyplastics plans 150,000 tons a year of POM in China after Phase 2. Celanese has closed the Ulsan compounding facility, and Victrex reports that the Panjin plant cannot yet deliver nameplate capacity.
Which country has a notable expansion outlook through 2036?
China is projected to record the fastest growth at 6.2% CAGR from 2026 to 2036, according to FMI. The USA follows at 5.4% CAGR.
Who are the key companies in the engineering plastics market?
Notable companies include BASF, DuPont, Covestro, LG Chem, Arkema Group, Asahi Kasei Corporation, Celanese Corporation, DSM N.V., Lanxess, and Mitsubishi Engineering-Plastics Corporation.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
