

- Market Size (2026)
- USD 14.2 Bn
- Forecast (2036)
- USD 22.1 Bn
- CAGR (2026 to 2036)
- 4.5%
How big is Plastic Shrink Wrap Market in 2026?
Sales in the plastic shrink wrap market are projected to grow at 4.5% CAGR, with the market size rising from USD 13.6 billion in 2025 to USD 14.2 billion in 2026 and reaching USD 22.1 billion by 2036.
With the advancement in high-speed multipack bundling and automated warehouse palletizing, food, beverage, and consumer goods manufacturers are replacing heavy corrugated shipping boxes with biaxially oriented polymer shrink films. Plastic shrink wrap is produced by extruding polyolefin resins through circular blown-film dies or flat cast lines and orienting the polymer chains so the web contracts tightly around products when passed through a heat tunnel or hot-water bath. According to FMI, global plastic shrink wrap market valuation rises from USD 13.6 billion in 2025 to USD 14.2 billion in 2026 and is projected to reach USD 22.1 billion by 2036, expanding at a 4.5% CAGR and generating USD 7.9 billion in added revenue. In March 2026, the United States Environmental Protection Agency documented that containers and packaging accounted for over 14.5 million tons of municipal plastic generation, prompting brand owners to down-gauge flexible plastic packaging webs [1]. Polyethylene (LLDPE / HDPE) captures 31.4% of material resin / polymer sales in 2026 because metallocene-catalyzed blends resist corner tearing. Evaluated country growth spans 3.6% CAGR in Mexico to 5.5% in Japan, although virgin petrochemical price swings and plastic packaging taxes challenge converter margins.
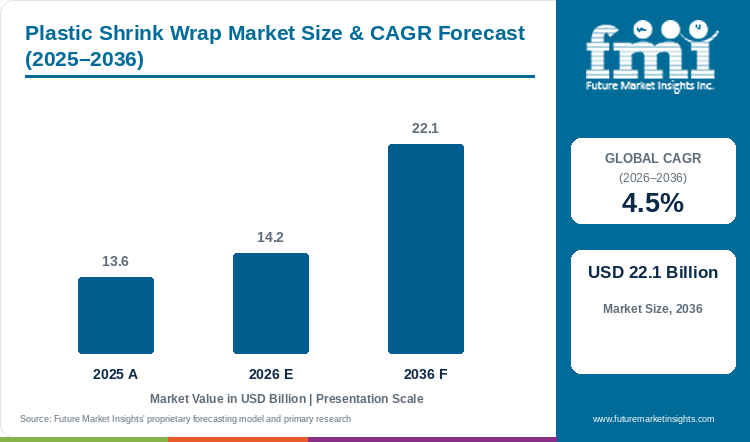
Key Market Trends & Insights
- By material resin / polymer: Polyethylene (LLDPE / HDPE) led with 31.4% share in 2026, driven by high dart-drop puncture resistance and mono-material store-drop-off recyclability.
- By product format: Pre-formed pouches & bags accounted for 37.2% in 2026, owing to hot-water dip-tank shrink performance that eliminates air pockets around chilled beef and poultry cuts.
- By barrier level: High-barrier modified atmosphere (EVOH) held 48.0% in 2026, as co-extruded ethylene-vinyl alcohol core layers block oxygen ingress and extend cold-chain meat shelf life.
- By end-use industry: Processed food & snacks represented 40.3% in 2026, underpinned by warehouse club multipack bundling and high-speed secondary tray overwrapping.
Regional Highlights
- Fastest-growing evaluated country: Japan, at 5.5% CAGR from 2026 to 2036.
- By country: The UK at 5.0%, France at 4.7%, the USA at 4.3%, and Canada at 4.0% follow, while Mexico records the lowest evaluated CAGR at 3.6%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Plastic Shrink Wrap Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 13.6 billion |
| Estimated Market Size in 2026 | USD 14.2 billion |
| Projected Market Size by 2036 | USD 22.1 billion |
| CAGR, 2026 to 2036 | 4.5% |
| Added Revenue, 2026 to 2036 | USD 7.9 billion |
Commercial conditions differ across evaluated markets owing to national recycled-content tax thresholds, extended producer responsibility fees, and automated bottling line speeds. FMI research indicates that film converters must balance 30% to 50% post-consumer recycled (PCR) resin inclusion against optical haze and heat-tunnel shrink tension when supplying beverage and retail multipack lines. In October 2025, the U.S. Environmental Protection Agency reported in its product-specific packaging data release that mechanical recovery of polyethylene bags, sacks, and wraps requires clean mono-material stream separation from multi-resin laminates [2]. Consequently, extruders are replacing chlorinated barrier layers with recycle-ready polyolefin webs and high-holding-force pallet wraps across automated distribution centers.
Blown Film Extrusion Operating Metrics and Shrink Ratio Parameters
Table 2: Blown Film Extrusion Metrics and Thermal Shrinkage Parameters for the Plastic Shrink Wrap Market (USD billion and operational metrics), mixed historical and forecast years from 2025 to 2036
| Operating Parameter | 2025 | 2026 | 2036 |
|---|---|---|---|
| Baseline Global Market Valuation (USD billion) | 13.6 | 14.2 | 22.1 |
| Global Shrink Film Production Volume (million metric tons) | 5.8 | 6.1 | 8.9 |
| Average Blown Film Extrusion Output Speed (kg/hr) | 780 | 820 | 1,120 |
| Post-Consumer Recycled (PCR) Content in Collation Shrink (%) | 22.5% | 26.0% | 58.5% |
| Multi-Layer (5+ Layer) Blown Line Market Share (%) | 48.0% | 52.5% | 84.0% |
Calculation basis: Extrusion metrics reflect commercial 5-to-9 layer co-extrusion blown film lines operating at blow-up ratios (BUR) between 2.5:1 and 4.0:1 across registered North American, European, and East Asian converting facilities.
Production Economics and Film Gauge Down-Gauging Parameters
Film converters continuously down-gauge collation and display shrink webs from forty-five microns down to twenty-five or thirty microns by blending metallocene linear low-density polyethylene into core layers. Thinner multilayer flexible packaging structures cut polymer weight per bundled case while maintaining bullseye holding force during highway transit. Lowering film thickness also reduces Extended Producer Responsibility eco-modulation fees across European and Canadian retail supply chains.
Table 3: Production Economics and Film Thickness Down-Gauging Metrics for the Plastic Shrink Wrap Market (USD and percentages), mixed historical and forecast years from 2025 to 2036
| Economic Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Average Virgin LLDPE Shrink Film Price per Metric Ton (USD) | 1,680.0 | 1,640.0 | 1,350.0 |
| Polymer Resin Share of Total Film Cost (%) | 64.0% | 62.5% | 48.0% |
| Sub-30-Micron Ultra-Thin Collation Shrink Penetration (%) | 32.0% | 36.5% | 72.5% |
| Recycled Resin Price Discount to Virgin Polymer (%) | 15.0% | 18.0% | 34.0% |
Table 4: Converting Facility Puncture Resistance and Dart Drop Standards for the Plastic Shrink Wrap Market (metric units and percentages), mixed reporting years from 2023 to 2026
| Facility Converting Parameter | Value (2026) | Basis |
|---|---|---|
| Market size, 2026 | USD 14.2 billion | Report value |
| ASTM D1709 Dart Drop Impact Resistance | 610 grams | Metallocene LLDPE benchmark |
| Machine Direction Tensile Strength at Break | 44.5 MPa | 2026 converting plant audit |
| Processed food & snacks revenue, 2026 | USD 5.72 billion | 40.3% share |
Analyst Perspective
"Multi-layer co-extrusion lets converters down-gauge polyethylene shrink films below thirty microns while incorporating 30% to 50% post-consumer recycled resin. Gel defects and inconsistent melt indices in recycled polyolefin feedstocks still require tight filtration and virgin booster layers on high-speed tunnels."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the plastic shrink wrap market segmented?
The plastic shrink wrap market is segmented by material resin / polymer, product format, barrier level, and end-use industry. In 2026, Polyethylene (LLDPE / HDPE) is projected at 31.4%, pre-formed pouches & bags at 37.2%, high-barrier modified atmosphere (EVOH) at 48.0%, and processed food & snacks at 40.3%.
By material resin / polymer: Polyethylene (LLDPE / HDPE), polypropylene (BOPP / CPP), recycled post-consumer PET, and bio-based compostable resins.
By product format: Pre-formed pouches & bags, rollstock barrier films, and thermoformed bladders & tubes.
By barrier level: High-barrier modified atmosphere (EVOH), medium-barrier standard, and breathable micro-perforated.
By end-use industry: Processed food & snacks, beverage collation & bottling, and consumer goods & logistics.
Why does Polyethylene (LLDPE / HDPE) lead the material resin / polymer category?
Polyethylene (LLDPE / HDPE) is expected to hold 31.4% of material resin / polymer demand in 2026, supported by puncture resistance.
Table 5: Material Resin / Polymer Share for the Plastic Shrink Wrap Market (percentage share), 2026
| Material Resin / Polymer | Share (2026) |
|---|---|
| Polyethylene (LLDPE / HDPE) | 31.4% |
| Other Segments Combined | 68.6%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Material Resin / Polymer Leadership and Market Growth for the Plastic Shrink Wrap Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.5% |
| Leading Segment | Polyethylene (LLDPE / HDPE) |
Beverage bottlers and industrial converters rely on polyethylene (LLDPE / HDPE) blends because co-extruding octene or hexene linear low-density polyethylene skin layers over a high-density core delivers both seal toughness and stiff dead-fold holding force. When twenty-four-can beverage trays exit heat tunnels, polyethylene collation wraps lock tightly around the load without crushing thin-wall aluminum cans, working alongside secondary stretch films on outbound warehouse skids. Unlike rigid PVC shrink films that release corrosive hydrogen chloride fumes during sealing and contaminate recycling streams, mono-material polyethylene wraps enter standard store-drop-off and commercial film baling channels. Fluctuating ethylene cracker feedstock prices still require quarterly resin indexing in supply contracts through 2036.
- Polyethylene (LLDPE / HDPE) accounts for 31.4% of material resin / polymer revenue in 2026, underpinned by high tear propagation resistance and mono-material recyclability.
- In March 2025, the Plastics Industry Association reported that biaxially oriented metallocene polyethylene shrink webs improved puncture resistance by 22.0% over conventional blown LDPE grades [3].
Why do Pre-Formed Pouches & Bags dominate the product format category?
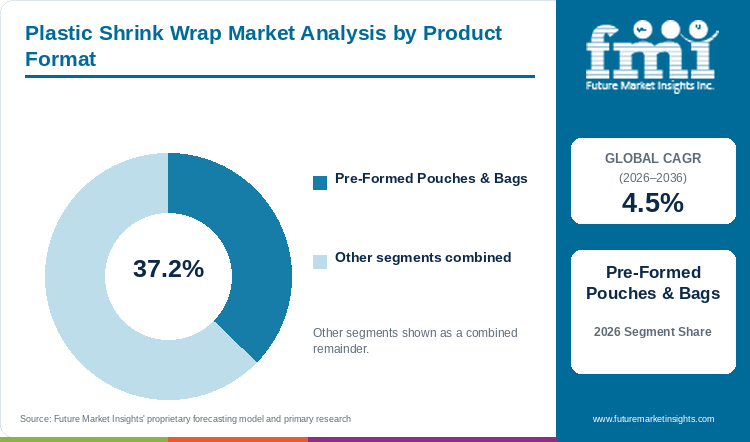
Pre-formed pouches & bags are estimated to represent 37.2% of the product format category in 2026, underpinned by vacuum meat sealing.
Slaughterhouses and cheese maturation plants purchase pre-formed pouches & bags in high volumes because curved-seal barrier shrink bags accommodate irregular bone-in beef primals, pork loins, and whole poultry carcasses without bridging. Once operators evacuate internal air inside rotary chamber vacuum packaging machines and submerge the sealed pack in an 85°C dip tank, the bag shrinks by forty percent in both directions like a second skin. That tight contraction stops blood purge pooling, prevents freezer burn, and allows wet-aging of boxed beef during transoceanic container transit. Manual bag loading on primal boning lines still requires skilled operators or automated bag-opening fingers to maintain throughput.
- Pre-formed pouches & bags hold 37.2% of product format demand in 2026, linked to hermetic curved bottom seals and zero-purge wet-aging performance.
- In July 2025, ASTM International updated its D1709-25 free-falling dart impact test protocol used to certify puncture-resistant bone-in meat shrink bags [4].
What keeps High-Barrier Modified Atmosphere (EVOH) ahead by barrier level?
Within barrier level, high-barrier modified atmosphere (EVOH) is projected to capture 48.0% share in 2026, driven by low oxygen permeability.
Fresh protein processors and specialty dairy packers specify high-barrier modified atmosphere (EVOH) shrink structures because even trace oxygen ingress triggers myoglobin discoloration and lipid rancidity in chilled meats. Co-extruding a three-to-five-micron ethylene-vinyl alcohol core sandwiched between moisture-blocking polyolefin tie layers keeps oxygen transmission rates below 1.0 cubic centimeter per square meter per day while replacing legacy polyvinylidene chloride (PVDC) coatings in heat shrink film webs. Chlorine-free EVOH structures also satisfy European supermarket recyclability scorecards that penalize halogenated plastics. Because EVOH loses gas-barrier performance when exposed to high relative humidity, converters must maintain uniform tie-layer thickness during high-ratio biaxial stretching.
- High-barrier modified atmosphere (EVOH) represents 48.0% of barrier level revenue in 2026, enabled by chlorine-free oxygen blocking that extends chilled beef shelf life up to 45 days.
- In June 2025, the European Committee for Standardization published updated EN 14615 specification benchmarks covering gas-barrier and mechanical shrink properties for co-extruded packaging films [5].
What gives Processed Food & Snacks the leading position in end-use industry?
With an estimated 40.3% share in 2026, processed food & snacks leads end-use industry sales, owing to automated multipack bundling.
Processed food & snacks manufacturers generate the largest share of shrink wrap consumption because warehouse clubs, discount grocers, and e-commerce fulfillment centers demand unitized multipacks of canned vegetables, pasta cartons, frozen pizzas, and snack boxes. High-clarity polyolefin display films and printed polyethylene bundling film hold multi-unit retail promotions together without the board weight and glue cost of secondary folding cartons. Cross-linked polyolefin shrink films also provide tamper-evident seals around boxed confectionery and frozen bakery trays without emitting smoke on L-bar sealers. Food brands still require anti-fog additive packages so refrigerated snack and prepared-meal wraps stay transparent inside humid grocery cases.
- Processed food & snacks commands 40.3% of end-use industry demand in 2026, reinforced by corrugated-case replacement and club-store multipack merchandising.
- In September 2025, the Flexible Packaging Association reported that food and snack multipack bundling accounted for over half of North American secondary shrink film shipments [6].
What are the drivers, restraints, and opportunities in the plastic shrink wrap market?
In the Plastic Shrink Wrap Market, corrugated-to-film multipack conversion and high-speed warehouse automation support demand, plastic packaging taxes and resin volatility constrain margins, and 30%-to-50% PCR mono-polyethylene shrink films unlock compliant retail contracts through 2036.
- Driver: Replacement of corrugated shipping cartons with lightweight collation shrink films across high-speed beverage and club-store lines will continue to support volume growth through 2036.
- Restraint: Statutory plastic packaging taxes, Extended Producer Responsibility fee escalations, and virgin polyolefin feedstock volatility will continue to pressure converter margins through 2036.
- Opportunity: Engineering mono-material EVOH-PE barrier bags and collation shrink wraps containing 30% to 50% certified post-consumer recycled resin is expected to capture retailer tenders through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Food, beverage, and household product plants are replacing fully enclosed corrugated RSC shipping boxes with pad-and-shrink or trayless collation shrink bundles to cut secondary packaging weight by up to 60.0% and fit more cases per outbound truckload. FMI data suggests that continuous-motion tunnel wrappers integrated with modern packaging machinery now bundle over 150 multipacks per minute without line stops. In March 2026, the Packaging Machinery Manufacturers Institute reported that 68.0% of surveyed North American food and beverage plants planned capital upgrades for secondary bundling and automated pallet unitization lines between 2026 and 2028 [7]. High-holding-force metallocene polyethylene films must still maintain consistent coefficient-of-friction ratings so bundled packs convey smoothly across robotic palletizers before plants sign multi-year film contracts.
Risk Assessment of the Plastic Shrink Wrap Market: Operational and Formulation Friction
Tightening Extended Producer Responsibility (EPR) fee modulation and restrictions on non-recyclable multi-resin laminates create compliance costs for shrink film extruders. Across the European Union under the Packaging and Packaging Waste Regulation (PPWR) and in Canadian provincial stewardship schemes, multi-layer shrink bags that combine incompatible resins such as polyamide or PVDC with polyethylene face higher eco-fees than mono-material polyolefin structures. In July 2025, the Organisation for Economic Co-operation and Development highlighted that cross-border trade in lower-grade mixed plastic film scrap declined as importing countries tightened contamination thresholds [8]. Converters producing high-barrier film packaging must therefore re-engineer tie layers usingmaleic-anhydride-grafted polyethylene compatibilizers so trimmed edge scrap and post-commercial film bales reprocess cleanly without black-speck gel defects.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Film extruders are winning long-term supermarket and beverage contracts by commercializing collation shrink webs that blend 30% to 50% mechanically recycled post-consumer polyethylene into the middle core layer while keeping virgin metallocene LLDPE on the outer sealing skins. Encapsulating PCR resin inside a 5- or 7-layer co-extruded structure isolates residual ink odors and gel particles from the sealing surface, allowing bottlers to run recycled wraps at full heat-tunnel speed. In October 2025, the Waste and Resources Action Programme published updated mechanical washing and de-inking validation guidelines showing that near-infrared sorted commercial polyethylene film bales can achieve food-adjacent secondary collation quality [9]. Scaling pcr shrink and stretch film production lets converters exempt beverage clients from plastic tax surcharges once third-party chain-of-custody audits are completed.
Plastic Shrink Wrap Market by Country (2026 to 2036)
As per FMI, Japan represents the fastest-growing plastic shrink wrap market among the evaluated economies, recording a 5.5% CAGR from 2026 to 2036, while Mexico posts the lowest evaluated CAGR at 3.6%. Across all six profiled markets, commercial growth depends on how film extruders meet national recycled-content thresholds, down-gauge micron thickness on robotic lines, and supply chlorine-free barrier bags.
Table 7: Country CAGR and Primary Growth Levers for the Plastic Shrink Wrap Market (CAGR percentage and operational drivers), 2026 to 2036
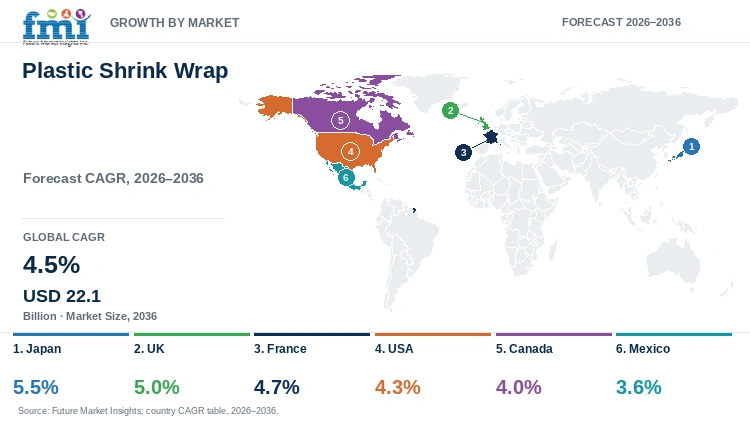
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Japan | 5.5% | Robotic retail display overwrapping and ultra-thin 11-to-15-micron cross-linked POF film adoption |
| UK | 5.0% | HMRC Plastic Packaging Tax (£228.82/tonne) accelerating 30%+ PCR collation shrink conversion |
| France | 4.7% | AGEC circular-economy mandates driving mono-material PE collation wraps and PVC phase-out |
| USA | 4.3% | Warehouse club multipack volume and high-speed e-commerce pallet unitization hubs |
| Canada | 4.0% | Provincial EPR fee modulation and cold-chain boxed beef barrier shrink bag exports |
| Mexico | 3.6% | Nearshoring appliance and automotive VCI shrink hood demand alongside domestic beverage bottling |
Source: Future Market Insights analysis
Japan Plastic Shrink Wrap Market Outlook (2026 to 2036)
Japanese convenience stores, Bento meal commissaries, and electronics makers enforce strict visual clarity and tamper-evidence standards that favor ultra-thin 11-to-15-micron cross-linked polyolefin (POF) display films. Demand for plastic shrink wrap in Japan is projected to rise at a 5.5% CAGR from 2026 to 2036, supported by high-speed robotic overwrapping lines that compensate for domestic factory labor shortages. In January 2026, the Japan Plastics Industry Federation reported that domestic shipments of down-gauged biaxially oriented polyolefin and barrier food films rose 6.1% in 2025 under the Plastic Resource Circulation Act’s weight-reduction targets [10]. High domestic naphtha feedstock and electricity costs still pressure local resin compounders. Japanese converters protect margins by exporting specialty anti-fog and low-shrink-force display films across East Asia.
Key takeaway: In Japan, robotic packaging automation and Plastic Resource Circulation Act down-gauging mandates drive the fastest evaluated country CAGR.
UK Plastic Shrink Wrap Market Outlook (2026 to 2036)
Statutory tax policy directly shapes resin selection in the United Kingdom, where HM Revenue & Customs levies the Plastic Packaging Tax on any manufactured or imported plastic packaging component containing less than 30.0% recycled plastic. The UK plastic shrink wrap market is forecast to expand at a 5.0% CAGR through 2036 as breweries, soft-drink bottlers, and supermarket chains convert secondary collation films to 30%-to-50% PCR polyethylene. In August 2026, HM Revenue & Customs reported that Plastic Packaging Tax revenue accrued in financial year 2025 to 2026 totaled GBP 250 million while the tax rate rose to GBP 228.82 per metric ton from April 2026 [11]. Limited domestic supply of clear food-grade LDPE post-consumer recyclate still creates spot price premiums. British extruders address feedstock tightness by operating back-of-store supermarket film take-back loops.
Key takeaway: In the UK, the GBP 228.82-per-tonne Plastic Packaging Tax threshold makes 30%+ PCR content mandatory for competitive beverage and grocery collation wraps.
France Plastic Shrink Wrap Market Outlook (2026 to 2036)
France’s Anti-Waste for a Circular Economy (AGEC) law and Citeo eco-modulation fee schedules penalize PVC and non-recyclable multi-material films while rewarding mono-material polyethylene shrink wraps that incorporate recycled content. Sales of plastic shrink wrap in France are anticipated to grow at a 4.7% CAGR between 2026 and 2036, underpinned by mineral-water, dairy, and wine shippers transitioning to printed PCR collation films. In February 2026, the Syndicat Français des Plastiques et Emballages documented that French industrial converters increased post-consumer recycled polyethylene integration in secondary collation shrink films to 31.8% across domestic bottling contracts [12]. Restrictions on decorative plastic overwrapping for promotional cosmetics and publishing items still trim non-food volume. French extruders offset non-food declines by supplying high-clarity cross-linked POF and chlorine-free cheese ripening bags.
Key takeaway: In France, Citeo EPR eco-modulation incentives and mineral-water multipack conversions drive rapid adoption of mono-material PCR polyethylene shrink films.
USA Plastic Shrink Wrap Market Outlook (2026 to 2036)
In the United States, warehouse club stores such as Costco, Sam’s Club, and BJ’s Wholesale Club anchor massive baseline demand for printed collation shrink film by merchandising canned goods, bottled beverages, and paper products in bundled multi-unit trays. The USA plastic shrink wrap market is estimated to progress at a 4.3% CAGR through 2036, further supported by ethane-advantaged Gulf Coast LLDPE resin supply and Midwestern boxed-beef vacuum shrink bag consumption. In May 2025, the Society of Plastics Engineers Flexible Packaging Division noted that North American 7- and 9-layer blown film installations reduced average collation shrink gauge by 18.0% while meeting How2Recycle store-drop-off criteria [13]. Divergent state-level EPR laws in California, Oregon, and Colorado complicate national film specifications. American converters standardize around recycle-ready all-PE barrier formulations to serve coast-to-coast brands.
Key takeaway: In the USA, warehouse club multipack merchandising and Gulf Coast metallocene polyethylene capacity sustain the world’s largest national revenue base.
Canada Plastic Shrink Wrap Market Outlook (2026 to 2036)
Canadian meatpacking plants in Alberta and Ontario alongside beverage bottlers in Quebec drive steady demand for bone-in barrier shrink bags and cold-resistant collation wraps, supporting a projected 4.0% CAGR from 2026 to 2036. Because winter rail and truck freight across Canadian provinces exposes unitized pallets to temperatures below minus 25°C, logistics operators require high-octene metallocene LLDPE shrink hoods that resist brittle cold-crack failure. In April 2026, the Packaging Association of Canada reported that provincial blue-box EPR harmonization in Ontario and Quebec increased commercial recovery of secondary transport shrink and stretch films by 14.5% [14]. Federal pollution-prevention reporting rules and retail pledges against problematic plastics still pressure converters to eliminate PVDC coatings. Canadian suppliers respond by qualifying EVOH-based barrier shrink bags for export beef packers.
Key takeaway: In Canada, sub-zero winter freight durability requirements and export beef vacuum packaging anchor demand for high-octene LLDPE and EVOH shrink films.
Mexico Plastic Shrink Wrap Market Outlook (2026 to 2036)
Nearshoring investments in northern Mexican automotive component, appliance, and electronics assembly plants, combined with high-volume domestic beer and soft-drink bottling, propel the Mexico plastic shrink wrap market at a projected 3.6% CAGR through 2036. Export manufacturers in Monterrey, Querétaro, and Tijuana use heavy-duty shrink hoods treated with volatile corrosion inhibitors (VCI) to protect machined engine blocks and stamped metal panels during cross-border rail transit into the United States. In May 2026, the Asociación Mexicana de Envase y Embalaje reported that industrial and beverage packaging film consumption accounted for 56.4% of Mexican flexible polymer converter output in 2025 [15]. Limited municipal post-consumer film collection infrastructure still restricts domestic PCR resin availability. Mexican extruders partner with industrial maquiladoras to recycle clean in-plant film trim and pallet wraps.
Key takeaway: In Mexico, cross-border automotive and appliance export protection alongside high-speed beer multipack bottling sustain steady industrial shrink film growth.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the plastic shrink wrap market?
Berry Global Group Inc., Sealed Air Corporation, Amcor plc, Intertape Polymer Group Inc., Coveris Management GmbH, Bolloré SE, Sigma Plastics Group, and Scientex Berhad are the significant market players in this market.
As per the analysis from FMI, the competitive structure of the plastic shrink wrap sector divides into three operational tiers based on extrusion technology and end-market specialization. Multinational flexible packaging conglomerates operate global networks of 7-to-11 layer blown and cast co-extrusion plants supplying beverage, meatpacking, and consumer goods multinationals. Specialized display and barrier shrink pioneers focus on electron-beam cross-linked polyolefin (POF) films and bone-in vacuum shrink bags. High-capacity regional extruders compete on volume collation shrink and industrial pallet hoods. Packaging buyers qualify suppliers on dart-drop impact strength, PCR resin certification, and heat-tunnel machinability.
- Global Flexible Film Conglomerates: Berry Global Group Inc., Sealed Air Corporation, and Amcor plc operate multi-region co-extrusion complexes for collation and barrier shrink packaging.
- Specialized Display and Shrink Bag Pioneers: Bolloré SE, Coveris Management GmbH, and Intertape Polymer Group Inc. engineer ultra-thin cross-linked POF display films and PCR collation wraps.
- High-Capacity Industrial Film Extruders: Sigma Plastics Group and Scientex Berhad manufacture high-volume polyethylene collation shrink, stretch hoods, and pallet unitization films.
Competitive Benchmarking: Plastic Shrink Wrap Market
Table 8: Competitive Benchmarking for the Plastic Shrink Wrap Market (qualitative capability ratings), 2026
| Company | Multi-Layer Blown Extrusion Capacity | Post-Consumer Recycled Content Scope | High-Clarity POF Display Film Engineering | Geographic Reach |
|---|---|---|---|---|
| Berry Global Group Inc. | High | High | High | High |
| Sealed Air Corporation | High | High | High | High |
| Amcor plc | High | High | High | High |
| Intertape Polymer Group Inc. | High | Medium | High | Medium |
| Coveris Management GmbH | High | High | Medium | Medium |
| Bolloré SE | High | Medium | High | High |
| Sigma Plastics Group | High | High | Medium | Medium |
| Scientex Berhad | High | Medium | Medium | Medium |
Scoring basis: Multi-Layer Blown Extrusion Capacity is High when an enterprise operates multi-layer co-extrusion lines exceeding 200,000 metric tons of annual film capacity. Post-Consumer Recycled Content Scope is High when commercial collation shrink lines routinely incorporate 30% to 50% certified PCR polyethylene. High-Clarity POF Display Film Engineering is High when producing cross-linked polyolefin films with optical haze below 3.0%, and Medium when focused on industrial polyethylene wraps. Geographic Reach is High for global operations and Medium for regional concentration.
Key Developments in the Plastic Shrink Wrap Market
- In February 2025, Berry Global Group Inc. expanded commercial production of its Sustane collation shrink film incorporating 50.0% post-consumer recycled polyethylene across European beverage bottling accounts. The co-extruded film exempts multipackers from UK and EU plastic tax penalties while maintaining 25-micron holding force [16].
- In June 2025, Sealed Air Corporation rolled out its next-generation CRYOVAC brand chlorine-free high-barrier vacuum shrink bags for fresh red meat and poultry processors. The EVOH-based structure replaces legacy PVDC layers to qualify for mechanical polyolefin recycling streams [17].
- In October 2025, Bolloré SE commissioned a new electron-beam irradiation line in France for its Bolphane ultra-thin cross-linked polyolefin display shrink films. The upgrade enables 11-micron down-gauged webs with bio-attributed and recycled resin options [18].
- In January 2026, Amcor plc commercialized a 100% recycle-ready mono-polyethylene printed collation shrink film containing 35.0% certified PCR content for multinational soft-drink and beer can multipacks [19].
Key Players in the Plastic Shrink Wrap Market
Global Flexible Film Conglomerates
- Berry Global Group Inc.
- Sealed Air Corporation
- Amcor plc
Specialized Display and Shrink Bag Pioneers
- Bolloré SE
- Coveris Management GmbH
- Intertape Polymer Group Inc.
High-Capacity Industrial Film Extruders
- Sigma Plastics Group
- Scientex Berhad
Plastic Shrink Wrap Market - Report Scope
Table 9: Report Scope for the Plastic Shrink Wrap Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Material Resin / Polymer; Product Format; Barrier Level; End-Use Industry; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes converter wholesale revenue from biaxially oriented polyethylene collation shrink films, cross-linked polyolefin display shrink webs, high-barrier vacuum shrink bags, and industrial shrink hoods sold within the listed segmentation. Excludes non-shrink ambient stretch wrap, rigid plastic containers, and paperboard cartons outside the named market. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Japan, UK, France, USA, Canada, Mexico, and additional countries in the full report |
| Key Companies Covered | Berry Global Group Inc., Sealed Air Corporation, Amcor plc, Intertape Polymer Group Inc., Coveris Management GmbH, Bolloré SE, Sigma Plastics Group, Scientex Berhad |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Plastic Shrink Wrap Market - Research Methodology
Table 10: Research Methodology for the Plastic Shrink Wrap Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with blown-film extrusion plant managers, polymer compounding engineers, meatpacking vacuum-line directors, and beverage packaging procurement leads to validate micron down-gauging, PCR resin pricing, and tunnel speeds. |
| Secondary Research | Secondary research synthesized US EPA packaging waste data, UK HMRC Plastic Packaging Tax bulletins, OECD plastic scrap trade reports, ASTM and CEN film testing standards, and corporate sustainability filings. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 period were developed using top-down and bottom-up material-balance models reconciling installed multi-layer blown film extrusion capacities against beverage collation, meatpacking, and industrial shipment volumes. |
| Data Triangulation and Validation | Data is validated against virgin and PCR polyolefin resin consumption logs, packaging tax tonnage declarations, machinery installation counts, and historical converter revenues to ensure accuracy without double counting non-shrink stretch films. |
Plastic Shrink Wrap Market by Segments
Plastic Shrink Wrap Market segmented by Material Resin / Polymer:
- Polyethylene (LLDPE / HDPE)
- Polypropylene (BOPP / CPP)
- Recycled Post-Consumer PET
- Bio-Based Compostable Resins
Plastic Shrink Wrap Market segmented by Product Format:
- Pre-Formed Pouches & Bags
- Rollstock Barrier Films
- Thermoformed Bladders & Tubes
Plastic Shrink Wrap Market segmented by Barrier Level:
- High-Barrier Modified Atmosphere (EVOH)
- Medium-Barrier Standard
- Breathable Micro-Perforated
Plastic Shrink Wrap Market segmented by End-Use Industry:
- Processed Food & Snacks
- Beverage Collation & Bottling
- Consumer Goods & Logistics
Plastic Shrink Wrap Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
- Israel
Research Sources and Bibliography
- [1] United States Environmental Protection Agency. (2026, March 13). Plastics: Material-specific data on municipal solid waste generation and packaging recovery. US EPA Facts and Figures about Materials, Waste and Recycling.
- [2] United States Environmental Protection Agency. (2025, October 23). Containers and packaging: Product-specific data on polyethylene bags, sacks, and wraps. US EPA Product-Specific Packaging Data Reports.
- [3] Plastics Industry Association (PLASTICS). (2025, March 16). Flexible packaging division technical survey: Biaxially oriented metallocene polyethylene shrink film puncture performance. PLASTICS Technical Publications, 2025-03.
- [4] American Society for Testing and Materials. (2025, July 22). Standard test method for impact resistance of plastic film by the free-falling dart method. ASTM International Standards, D1709-25.
- [5] European Committee for Standardization. (2025, June 18). Plastics: Shrink and stretch films for unitization and barrier packaging specifications and test methods. CEN European Standards, EN 14615:2025.
- [6] Flexible Packaging Association (FPA). (2025, September 18). State of the flexible packaging industry: Food and snack multipack collation shrink report. FPA Annual Sector Bulletins, 2025-09.
- [7] Packaging Machinery Manufacturers Institute (PMMI). (2026, March 20). High-speed collation shrink wrapper and automated pallet unitization equipment outlook. PMMI Business Intelligence Studies, 2026-03.
- [8] Organisation for Economic Co-operation and Development. (2025, July 22). Monitoring trade in plastic waste and scrap: Extended Producer Responsibility and film contamination thresholds. OECD Environment Data Explainers.
- [9] Waste and Resources Action Programme (WRAP). (2025, October 24). Mechanical washing, de-inking, and recyclability protocols for post-consumer polyethylene flexible films. WRAP Circular Plastics Sector Studies, 2025-10.
- [10] Japan Plastics Industry Federation (JPIF). (2026, January 16). Down-gauged polyolefin extrusion trends and robotic display packaging automation under the Plastic Resource Circulation Act. JPIF Annual Statistical Review, 2026-01.
- [11] HM Revenue & Customs. (2026, August 27). Plastic Packaging Tax (PPT) statistics commentary: Declared tonnages, recycled content compliance, and FY 2025 to 2026 revenue. GOV.UK Official Statistics.
- [12] Syndicat Francais des Plastiques et Emballages (SFPE). (2026, February 22). Integration of post-consumer recycled polyethylene in French industrial collation shrink films under AGEC mandates. SFPE Rapport Annuel, 2026-02.
- [13] Society of Plastics Engineers (SPE). (2025, May 24). Metallocene-catalyzed polyethylene morphology and biaxial shrinkage kinetics in 7- and 9-layer blown films. SPE ANTEC Conference Proceedings, 45(1), 88-101.
- [14] Packaging Association of Canada (PAC). (2026, April 16). Provincial EPR harmonization and sub-zero transport shrink film performance in Canada. PAC Technical Briefings, 2026-04.
- [15] Asociacion Mexicana de Envase y Embalaje (AMEE). (2026, May 20). Mexican industrial nearshoring packaging and volatile corrosion inhibitor shrink film assessment. AMEE Informes Tecnicos, 2026-05.
- [16] Berry Global Group Inc. (2025, February 20). Commercial rollout of Sustane 50% post-consumer recycled collation shrink film for European beverage multipacks. Berry Global Corporate Media Announcements.
- [17] Sealed Air Corporation. (2025, June 24). Expansion of CRYOVAC brand chlorine-free multi-layer EVOH barrier vacuum shrink bags for fresh protein. Sealed Air Corporate Press Releases.
- [18] Bollore SE. (2025, October 28). Commissioning of electron-beam irradiation line for ultra-thin 11-micron Bolphane POF display shrink films. Bollore Films Technical Releases.
- [19] Amcor plc. (2026, January 18). Commercialization of 100% recycle-ready mono-polyethylene printed collation shrink film with 35% PCR resin. Amcor Flexible Packaging Investor Briefings.
- [20] Intertape Polymer Group Inc. (2026, April 14). Introduction of Exlfilm down-gauged high-holding-force cross-linked polyolefin shrink film for automated tunnels. IPG Product Engineering Releases.
- [21] Coveris Management GmbH. (2025, September 12). Capacity expansion for Duralite R post-consumer recycled collation shrink films across European plants. Coveris Sustainability Updates.
- [22] Sigma Plastics Group. (2025, May 19). Commissioning of 9-layer industrial blown film extrusion line for North American collation wraps. Sigma Operations Bulletins.
- [23] Scientex Berhad. (2025, November 14). Automated multi-layer blown film capacity expansion for Asia-Pacific beverage bundling films. Scientex Corporate Filing Updates.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the plastic shrink wrap market in 2026 and what is forecast for 2036?
- Which down-gauging and PCR resin blending trends support demand for plastic shrink wrap?
- Why does Polyethylene (LLDPE / HDPE) lead the material resin / polymer category?
- Why do pre-formed pouches & bags lead the product format category globally?
- How do growth rates differ across Japan, the UK, France, the USA, Canada, and Mexico?
- Which leading companies supply collation shrink, POF display films, and barrier shrink bags today?
- What limits PCR resin inclusion or multi-layer film recycling in the plastic shrink wrap market?
- What should packaging engineers evaluate before qualifying a plastic shrink wrap supplier?
Frequently Asked Questions
How big is the plastic shrink wrap market in 2026, and what is forecast for 2036?
The global plastic shrink wrap market is estimated to reach USD 14.2 billion in 2026. Industry valuation is projected to expand further and reach USD 22.1 billion by 2036.
What is the CAGR for the plastic shrink wrap market from 2026 to 2036?
As per FMI, the plastic shrink wrap market is projected to grow at a 4.5% CAGR from 2026 to 2036. Expansion is supported by corrugated-to-film multipack conversion and automated warehouse pallet unitization.
Which material resin segment holds a notable plastic shrink wrap demand share in 2026?
Polyethylene (LLDPE / HDPE) is projected to hold 31.4% of material resin / polymer demand in 2026. The segment benefits from high metallocene dart-drop puncture resistance, low sealing energy, and mono-material recyclability.
Which product format segment holds a notable plastic shrink wrap share in 2026?
Pre-formed pouches & bags are estimated to account for 37.2% of product format demand in 2026. Demand is supported by hot-water dip-tank vacuum shrink performance that prevents blood purge loss in fresh beef and poultry.
Which country has a notable plastic shrink wrap expansion outlook during the forecast period?
FMI finds that Japan is projected to expand at a 5.5% CAGR during the 2026 to 2036 assessment period. Growth is supported by robotic retail overwrapping lines and down-gauged 11-to-15-micron cross-linked polyolefin films.
Which companies are active in the Plastic Shrink Wrap Market during 2026?
Notable companies active in the market include Berry Global Group Inc., Sealed Air Corporation, Amcor plc, Intertape Polymer Group Inc., Coveris Management GmbH, Bolloré SE, Sigma Plastics Group, and Scientex Berhad. These participants focus on 7-to-9 layer blown film co-extrusion, 30%-to-50% PCR resin integration, and chlorine-free EVOH barrier shrink bags.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Material Resin / Polymer, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material Resin / Polymer, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material Resin / Polymer, 2026 to 2036
- Polyethylene (LLDPE / HDPE)
- Polypropylene (BOPP / CPP)
- Recycled Post-Consumer PET
- Bio-Based Compostable Resins
- Y-o-Y Growth Trend Analysis By Material Resin / Polymer, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Resin / Polymer, 2026 to 2036
- Global Market Analysis and Forecast, By Product Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Format, 2026 to 2036
- Pre-Formed Pouches & Bags
- Rollstock Barrier Films
- Thermoformed Bladders & Tubes
- Y-o-Y Growth Trend Analysis By Product Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Format, 2026 to 2036
- Global Market Analysis and Forecast, By Barrier Level, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Barrier Level, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Barrier Level, 2026 to 2036
- High-Barrier Modified Atmosphere (EVOH)
- Medium-Barrier Standard
- Breathable Micro-Perforated
- Y-o-Y Growth Trend Analysis By Barrier Level, 2021 to 2025
- Absolute $ Opportunity Analysis By Barrier Level, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Industry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Industry, 2026 to 2036
- Processed Food & Snacks
- Beverage Collation & Bottling
- Consumer Goods & Logistics
- Y-o-Y Growth Trend Analysis By End-Use Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Berry Global Group Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Sealed Air Corporation
- Amcor plc
- Intertape Polymer Group Inc.
- Coveris Management GmbH
- Bolloré SE
- Sigma Plastics Group
- Scientex Berhad
- Berry Global Group Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


