
- Market Size (2026)
- USD 88.0 Bn
- Forecast (2036)
- USD 142.0 Bn
- CAGR (2026 to 2036)
- 4.9%
How big is Ice Cream and Frozen Dessert Market in 2026?
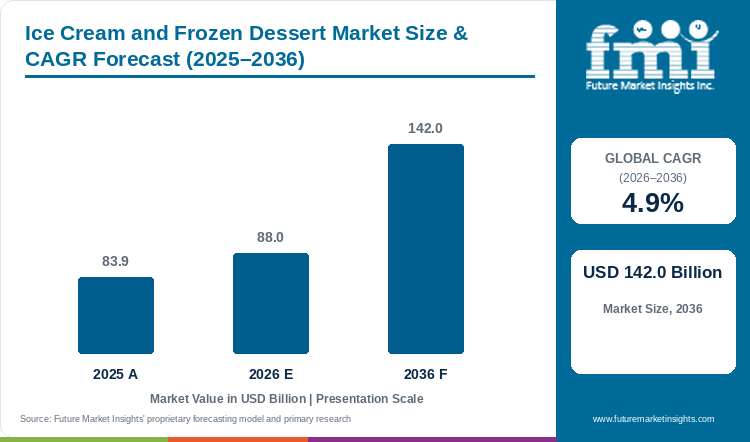
Sales in the ice cream and frozen dessert market are projected to grow at 4.9% CAGR through 2036. Market size rises from USD 83.9 billion in 2025 to USD 88.0 billion in 2026 and is expected to reach USD 142.0 billion by 2036.
Household demand for portion-controlled evening treats and high-butterfat artisanal recipes has prompted dairy creameries to reconfigure freezer lines around single-serve novelties and low-overrun pints. According to FMI, the global ice cream and frozen dessert market stands at USD 83.9 billion in 2025, rises to USD 88.0 billion in 2026, and is projected to reach USD 142.0 billion by 2036 at a 4.9% CAGR over the 2026 to 2036 period. This progression adds USD 54.0 billion in new revenue as manufacturers expand distribution of specialty frozen desserts across modern retail and quick-service chains. In April 2026, the United States
Department of Agriculture National Agricultural Statistics Service reported that U.S. regular hard ice cream production reached 60.4 million gallons in February 2026, up 2.1% year-on-year as plants built spring novelty inventories [1]. Slices, shreds & blocks lead product form / texture at 35.8% share in 2026, although rising sub-zero cold-storage electricity rates continue to pressure distributor margins.
Key Market Trends & Insights
- By product form / texture: Slices, shreds & blocks led with 35.8% share in 2026, driven by individually wrapped novelty bars, ice cream sandwiches, and pre-cut dessert blocks.
- By source base: Traditional dairy milk accounted for 40.4% of revenue in 2026, reflecting enduring consumer preference for natural bovine butterfat melt and custard creaminess.
- By distribution channel: Supermarkets & hypermarkets held 42.4% in 2026, supported by high-visibility glass-door freezer aisles and family multi-pack promotions.
- By flavor / variant: Plain & unsweetened represented 51.6% share in 2026, serving as the core sweet-cream and vanilla foundation for household desserts and foodservice plating.
Regional Highlights
- Fastest-growing evaluated country: Switzerland, at 6.0% CAGR from 2026 to 2036.
- By country: the USA at 5.5%, Australia at 5.1%, and Brazil at 4.7% follow, while Canada records the lowest evaluated CAGR at 3.9%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Ice Cream and Frozen Dessert Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 83.9 billion |
| Estimated Market Size in 2026 | USD 88.0 billion |
| Projected Market Size by 2036 | USD 142.0 billion |
| CAGR, 2026 to 2036 | 4.9% |
| Added Revenue, 2026 to 2036 | USD 54.0 billion |
Commercial conditions differ across the profiled countries owing to variations in domestic milk-fat quotas, ambient summer temperatures, and supermarket cold-chain density. FMI research indicates that commercial creameries are upgrading scraped-surface continuous freezers and spiral blast-hardening tunnels to prevent coarse ice-crystal growth during multi-stop grocery delivery. In October 2026, the USDA National Agricultural Statistics Service Dairy Products release documented that cumulative January-to-August 2026 U.S. hard ice cream output totaled 488.2 million gallons alongside steady production of low-fat and sherbet lines [2]. Installing automated ice cream equipment with precision overrun control allows processors to extrude complex novelty bars at minus 40 degrees Celsius without deforming chocolate shells.
Commercial Freezing Throughput and Butterfat Overrun Batch Parameters
Table 2: Industrial Freezing Parameters and Overrun Metrics for the Ice Cream and Frozen Dessert Market (USD billion and production units), mixed historical and forecast years from 2025 to 2036
| Manufacturing Parameter | 2025 | 2026 | 2031 | 2036 |
|---|---|---|---|---|
| Baseline Global Market Valuation (USD billion) | 83.9 | 88.0 | 112.5 | 142.0 |
| Global Production Volume (thousand metric tons) | 16,200 | 16,900 | 20,800 | 25,400 |
| Standard Industrial Overrun Rate (% air incorporated) | 75.0% | 72.0% | 65.0% | 58.0% |
| Super-Premium Butterfat Content Range (%) | 14.5% | 15.0% | 16.2% | 17.5% |
| Hardening Blast Tunnel Temperature Threshold (C) | -40.0 | -40.0 | -42.0 | -45.0 |
Household Dessert Spending and Premium Novelty Consumption Dynamics
Consumers treating frozen confections as an accessible at-home reward increasingly trade up from economy two-liter tubs to multi-textured novelty sticks and reduced-sugar pints. Formulators pairing high-protein dairy ultrafiltration with prebiotic fibers are capturing incremental freezer space in low calorie desserts, giving calorie-conscious households a creamy evening option that avoids chalky erythritol aftertastes.
Table 3: Household Consumption Spending and Channel Metrics for the Ice Cream and Frozen Dessert Market (USD and percentages), mixed historical and forecast years from 2025 to 2036
| Consumer Metric | 2025 | 2026 | 2031 | 2036 |
|---|---|---|---|---|
| Per Capita Annual Frozen Dessert Spending (USD) | 68.40 | 71.50 | 88.20 | 108.60 |
| Impulse Handheld Novelty Revenue Share (%) | 38.2% | 39.5% | 44.0% | 48.5% |
| Dairy-Free & Plant-Based Retail Penetration (%) | 12.8% | 14.2% | 19.5% | 25.0% |
| Direct-to-Consumer Frozen Home Delivery Share (%) | 6.5% | 7.4% | 11.2% | 15.8% |
Table 4: Cold-Chain Logistics and Freezing Infrastructure Standards for the Ice Cream and Frozen Dessert Market (metric units and percentages), mixed reporting years from 2023 to 2026
| Infrastructure Indicator | 2023 | 2024 | 2025 | 2026 |
|---|---|---|---|---|
| Commercial Reefer Fleet Operating Temperature (C) | -25.0 | -25.0 | -28.0 | -30.0 |
| Modern Multi-Door Display Freezers Installed (units) | 410,000 | 438,000 | 468,000 | 502,000 |
| Energy-Efficient Inverter Compressor Adoption (%) | 52.4% | 57.8% | 63.5% | 69.2% |
| Biodegradable Paper Tub Packaging Penetration (%) | 31.5% | 35.8% | 40.2% | 45.6% |
Analyst Perspective
"Low-overrun novelty bars and clean-label dairy pints allow creameries to expand unit margins even where bulk tub volumes are mature. Volatile cocoa-butter and cream costs alongside sub-zero reefer electricity bills still pressure profitability across regional distributors."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Ice Cream and Frozen Dessert Market segmented?
The ice cream and frozen dessert market is segmented by product form / texture, source base, distribution channel, flavor / variant, and region. In 2026, slices, shreds & blocks accounts for 35.8% of product form / texture, traditional dairy milk represents 40.4% of source base, supermarkets & hypermarkets commands 42.4% of distribution channel, and plain & unsweetened leads flavor / variant with 51.6%.
By product form / texture: Slices, shreds & blocks, drinkable liquid & shakes, set tubs & cups, and spreads & dips.
By source base: Traditional dairy milk, plant-based alternative (oat/almond/soy), and lactose-free & specialized.
By distribution channel: Supermarkets & hypermarkets, specialty natural food stores, and food service & quick service bakeries.
By flavor / variant: Plain & unsweetened, fruit-flavored & indulgent, and savory & herbed.
Why does Slices, Shreds & Blocks lead the product form / texture category?
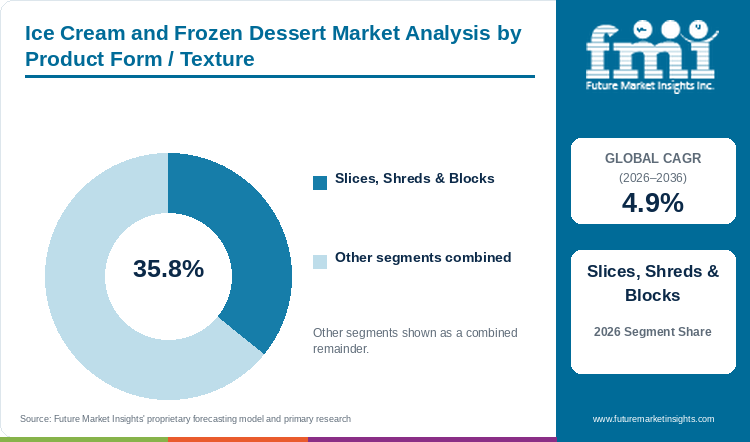
Slices, shreds and blocks are projected to capture 35.8% of product form demand in 2026, propelled by handheld portion convenience.
Table 5: Product Form / Texture Share for the Ice Cream and Frozen Dessert Market (percentage share), 2026
| Product Form / Texture | Share (2026) |
|---|---|
| Slices, Shreds & Blocks | 35.8% |
| Other Segments Combined | 64.2%* |
| Total | 100.0% |
*Balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Form / Texture Leadership and Market Growth for the Ice Cream and Frozen Dessert Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.9% |
| Leading Segment | Slices, Shreds & Blocks |
Extruded ice cream slices, wafer sandwiches, novelty bars, and cut blocks lead category revenue because consumers want pre-portioned treats that require no bowl or scoop. High-speed wire-cutting lines slice hardened ice cream logs into exact 60-to-90-milliliter portions that pass through liquid-nitrogen chillers and dip tanks using specialized ice cream coatings enriched with roasted nuts or biscuit crunch. Meanwhile, households buying take-home pints and tubs increasingly favor barrier paperboard ice cream containers that prevent freezer burn across repeated openings.
- Slices, shreds & blocks are projected to represent 35.8% of product form / texture revenue in 2026, propelled by single-serve calorie control and impulse convenience.
- In June 2025, the International Ice Cream Association reported that multipack handheld novelty bars and cut wafer sandwiches generated 44% of incremental retail dollar growth across North American grocery freezers [3].
What makes Traditional Dairy Milk central to the source base category?
In 2026, traditional dairy milk is expected to hold 40.4% of source base revenue, reinforced by rich butterfat mouthfeel.
Fresh bovine milk and sweet cream remain the benchmark source base because milk-fat globules and casein micelles stabilize microscopic air cells during whipping and melt cleanly at 35 degrees Celsius on the tongue. Super-premium brands formulate with 14% to 16% butterfat and egg-yolk solids to achieve a dense, velvety texture without relying on heavy locust-bean or guar gum stabilizers. To retain shoppers who experience mild digestive bloating from conventional milk, creameries are also rolling out digestible A2 ice cream and certified pasture-grazed organic ice cream across natural supermarket banners.
- Traditional dairy milk is expected to account for 40.4% of source base revenue in 2026, reinforced by natural butterfat emulsification and clean flavor release.
- In August 2025, a sensory tribology study in the Journal of Dairy Science demonstrated that 15% bovine butterfat mixes delivered 31% lower oral friction and superior vanilla aroma release compared with vegetable-fat blends [4].
Why do Supermarkets & Hypermarkets lead the distribution channel category?
Supermarkets and hypermarkets are estimated to account for 42.4% of distribution channel sales in 2026, enabled by multi-door freezer aisles.
Large-format supermarkets and hypermarkets anchor global volume because multi-door glass display freezers with anti-fog LED lighting let shoppers compare family tubs, novelty multipacks, and specialty pints in a single weekly trip. Automated back-room cold rooms in tier-one grocery chains transfer palletized frozen desserts from minus-28-degree delivery reefers to aisle cabinets in under 15 minutes, preventing heat-shock lactose crystallization. Alongside retail grocery aisles, high-street scoop parlors and bakery cafes drive out-of-home traffic by serving slow-churned artisanal gelato and tart probiotic frozen yogurt.
- Supermarkets & hypermarkets are estimated to capture 42.4% of distribution channel revenue in 2026, enabled by unbroken sub-zero merchandising and multi-box promotional pricing.
- In June 2025, the Food and Agriculture Organization Food Outlook noted that global milk output reached 992.7 million metric tons, supporting steady dairy cream supply into modern retail frozen aisles [5].
How does Plain & Unsweetened anchor the flavor / variant category?
With an estimated 51.6% share in 2026, plain and unsweetened leads the flavor category, associated with versatile dessert pairing.
Classic sweet-cream, fior di latte, and pure vanilla-bean bases account for over half of category demand because both households and restaurant pastry chefs use them as a neutral canvas alongside pies, brownies, fruit cobblers, and espresso affogatos. Maintaining a clean white base requires high-grade fresh cream and zero off-flavors, since there is no heavy cocoa or caramel syrup to mask oxidized milk fat. At the same time, gourmet scoop shops and hospitality lounges experiment with botanical, spiced, and savory-herbed variants such as olive-oil rosemary or mascarpone fig to elevate plated restaurant desserts.
- Plain & unsweetened is anticipated to hold 51.6% of flavor / variant demand in 2026, associated with universal culinary pairing and clean-label ingredient simplicity.
- In December 2025, the Specialty Food Association annual gastronomy report highlighted that sweet-cream and Madagascar vanilla bases remained the top-selling foundation for 54% of restaurant dessert pairings [6].
What are the drivers, restraints, and opportunities in the Ice Cream and Frozen Dessert Market?
In the ice cream and frozen dessert market, demand for portion-controlled premium novelties and clean-label dairy supports growth, cold-chain electricity and cocoa-butter inflation restrain margins, and oat-based and protein-fortified recipes open new retail segments through 2036.
- Driver: Consumers are trading up to portion-controlled chocolate-enrobed novelty bars, clean-label dairy pints, and low-overrun textures across retail and foodservice channels through 2036.
- Restraint: High industrial electricity tariffs for minus-28-degree cold storage and volatile cocoa and dairy-fat prices continue to compress processor margins through 2036.
- Opportunity: Formulating enzyme-hydrolyzed oat-milk ice creams and high-protein, prebiotic frozen treats is expected to expand flexitarian and wellness freezer sales through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Even during periods of cautious household discretionary spending, shoppers continue to buy super-premium pints and multi-textured novelty bars as an affordable home treat that replaces pricier restaurant dining. FMI data suggests that dairy processors are lowering air overrun from 80% down toward 50% in flagship lines while adding Belgian chocolate shards, roasted pistachio swirls, and fruit compotes to justify higher per-liter pricing. According to the July 2025 OECD-FAO Agricultural Outlook 2025-2034, global per-capita consumption of fresh and processed dairy products continues to rise across urbanizing economies as cold-chain retail expands [7]. Retailers still demand rapid inventory turns to justify energy-intensive freezer doors.
Risk Assessment of the Ice Cream and Frozen Dessert Market: Operational and Formulation Friction
Unlike ambient snacks or chilled yogurt, ice cream must remain below minus 18 degrees Celsius across every link of the supply chain from blast hardening to retail checkout. Even brief temperature excursions above minus 12 degrees Celsius during loading-dock transfers melt microscopic ice crystals, which then refreeze into jagged, gritty crystals that ruin mouthfeel and trigger consumer complaints. In January 2026, the European Food Safety Authority highlighted that maintaining uninterrupted sub-zero cold-chain telemetry and hygienic defrost cycles remains critical to prevent Listeria monocytogenes persistence and textural degradation in frozen dairy logistics [8]. Steep cocoa-butter prices for chocolate bar coatings further squeeze plant margins.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Early generations of dairy-free frozen desserts suffered from icy texture or overpowering coconut and bean notes, limiting repeat purchases among mainstream shoppers. Food scientists now use enzymatic amylase hydrolysis on oat bases and blend cold-pressed almond butter with pea protein to match the viscosity and freezing-point depression of dairy cream in plant-based ice creams. In February 2026, the Plant-Based Foods Institute reported that enzyme-treated oat and nut-butter frozen desserts achieved a 27% repeat-purchase lift over first-generation soy and water-based sorbet formulas [9]. Pairing dairy-free bases with probiotic cultures and reduced sugar alcohols also attracts lactose-intolerant fitness consumers.
Ice Cream and Frozen Dessert Market by Country (2026 to 2036)
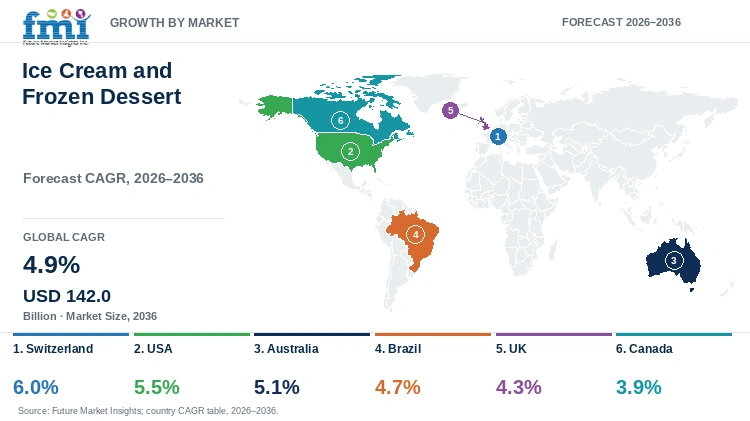
As per FMI, Switzerland represents the fastest-growing ice cream and frozen dessert market among the six profiled countries at a 6.0% CAGR from 2026 to 2036, while Canada expands at a 3.9% CAGR. Across these national markets, revenue growth depends on how creameries balance domestic milk-fat pricing, portion-controlled novelty innovation, and retail display-freezer modernization.
Table 7: Country CAGR and Primary Growth Levers for the Ice Cream and Frozen Dessert Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Switzerland | 6.0% | High disposable income, alpine double-cream and Swiss chocolate novelties, and year-round hospitality tourism |
| USA | 5.5% | Expansive supermarket freezer aisles, high-protein and keto pints, and multipack handheld novelty bars |
| Australia | 5.1% | Warm coastal climate, beachside parlor culture, macadamia and fruit inclusions, and oat-milk novelties |
| Brazil | 4.7% | Tropical year-round heat, acai and regional fruit sorbets, and expanding urban supermarket cold chains |
| UK | 4.3% | Supermarket private-label luxury pints, HFSS-compliant portion-controlled mini bars, and clotted-cream recipes |
| Canada | 3.9% | 100% Canadian Milk quality seal loyalty, year-round indoor comfort tubs, and premium maple and nut inclusions |
Source: Future Market Insights analysis
Switzerland Ice Cream and Frozen Dessert Market Outlook (2026 to 2036)
Switzerland is forecast to emerge as a high-growth market, registering 6.0% CAGR through 2036, supported by affluent household spending on super-premium alpine cream tubs and single-origin Swiss chocolate-coated sticks. Domestic creameries source Gruyere and Emmental meadow cream alongside domestic sugar-beet and chocolate couverture to craft dense, low-overrun confections sold through Migros, Coop, and alpine resort hotels. In March 2026, the Swiss Federal Statistical Office reported that specialty dairy desserts and artisanal confectionery held the highest per-kilogram basket value inside Swiss household refrigerated and frozen food expenditure [10]. High domestic wages and strict alpine milk quotas still push Swiss processors to focus on luxury exportable novelties.
Key takeaway: In Switzerland, alpine double-cream quality and domestic chocolate couverture integration sustain the highest per-liter retail realization among profiled markets.
USA Ice Cream and Frozen Dessert Market Outlook (2026 to 2036)
Revenue from ice cream and frozen dessert sales in the USA is projected to rise at 5.5% CAGR over the assessment period, driven by massive suburban supermarket freezer capacity and rapid innovation in handheld novelty multipacks and ultrafiltered high-protein pints. American grocers dedicate 20 to 30 glass freezer doors per store to frozen novelties, cookie sandwiches, and artisanal pints. In April 2026, the United States Census Bureau Monthly Retail Trade Survey recorded a 5.8% year-on-year increase in specialty food and frozen grocery sales as households shifted entertainment spending toward at-home treats [11]. Steep promotional slotting fees in national grocery chains still challenge independent regional creameries.
Key takeaway: In the USA, wide multi-door grocery freezer aisles and strong household demand for handheld novelty boxes anchor global revenue scale.
Australia Ice Cream and Frozen Dessert Market Outlook (2026 to 2036)
The outlook for ice cream and frozen desserts in Australia remains positive, with sales projected to increase at 5.1% CAGR through 2036, underpinned by warm coastal weather and one of the world's highest per-capita consumption rates at over 18 liters per person annually. Australian shoppers purchase chocolate-dipped honeycomb and macadamia novelty bars across petrol-convenience forecourts, beachside milk bars, and Woolworths and Coles freezer aisles. In May 2026, Dairy Australia reported that domestic manufactured dairy dessert and ice cream value grew 5.4% over the prior twelve months despite volatile Victorian farmgate milk prices [12]. Long refrigerated road-train hauls across hot inland states require heavy eutectic reefer insulation.
Key takeaway: In Australia, high impulse convenience-store sales and native fruit and nut inclusions support durable year-round volume across coastal cities.
Brazil Ice Cream and Frozen Dessert Market Outlook (2026 to 2036)
Ice cream and frozen dessert adoption across Brazil is anticipated to register 4.7% CAGR during the forecast period, aided by tropical temperatures across Southeast, Northeast, and Central-West urban corridors and rising modern cash-and-carry (atacarejo) freezer installations. Domestic processors blend dairy cream with regional fruit pulps including acai, cupuacu, passion fruit, and mango to serve both take-home tubs and neighborhood sorveterias. In June 2026, the Brazilian Association of Ice Cream Industries (ABIS) reported that national frozen dessert and sorbet volume surpassed 1.18 billion liters as self-service scoop parlors and retail novelty chests expanded in secondary cities [13]. Municipal power brownouts and expensive commercial freezer financing still challenge small neighborhood shops.
Key takeaway: In Brazil, tropical fruit-pulp formulations and expanding cash-and-carry supermarket freezers unlock volume growth across middle-income urban households.
United Kingdom Ice Cream and Frozen Dessert Market Outlook (2026 to 2036)
The United Kingdom market is predicted to witness 4.3% CAGR through 2036, influenced by retailer reformulation under national High in Fat, Salt and Sugar (HFSS) promotional rules and strong demand for private-label luxury pints. British supermarkets such as Tesco, Sainsbury's, and Marks & Spencer have expanded West Country clotted-cream tubs alongside sub-150-calorie mini novelty sticks that comply with checkout and endcap marketing limits. In July 2026, the British Frozen Food Federation reported that retail frozen confectionery value rose 4.6% year-on-year, led by bite-sized chocolate-coated ice cream bonbons and premium own-label gelato tubs [14]. Cool, wet summer weeks still cause sharp short-term swings in impulse kiosk sales.
Key takeaway: In the UK, HFSS-compliant mini novelty portions and supermarket own-label clotted-cream pints sustain steady retail value expansion.
Canada Ice Cream and Frozen Dessert Market Outlook (2026 to 2036)
Demand across the Canada ice cream and frozen dessert sector is expected to increase at 3.9% CAGR through 2036, sustained by strong consumer preference for tubs bearing the Dairy Farmers of Canada 100% Canadian Milk Blue Cow symbol. Under Canada's supply-management system, domestic processors must purchase quota butterfat at regulated prices unless importing under narrow tariff-rate quotas, which encourages creameries in Ontario and Quebec to focus on high-margin maple, praline, and brownie-chunk pints rather than low-price commodity tubs. In August 2026, the Canadian Dairy Commission noted that domestic ice cream and frozen dairy novelty utilization absorbed over 14.2 million kilograms of butterfat during the 2025-2026 dairy year [15]. Long winter seasons shift cold-weather buying toward family take-home tubs.
Key takeaway: In Canada, regulated domestic butterfat pricing and Blue Cow origin loyalty steer manufacturers toward higher-margin inclusion pints and novelty multipacks.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Ice Cream and Frozen Dessert Market?
Danone S.A., General Mills, Inc., The Kraft Heinz Company, Mondelez International, Inc., Conagra Brands, Inc., Campbell Soup Company are the notable companies in the ice cream and frozen dessert market.
As per the analysis from FMI, the competitive structure of the ice cream and frozen dessert market brings together multinational packaged-food corporations operating automated sub-zero distribution networks, super-premium dairy creameries, and plant-based frozen dessert innovators. Large food groups leverage national reefer fleets and supermarket category-captain agreements to secure eye-level freezer doors, while confectionery and bakery partners license recognizable biscuit and chocolate brands into handheld novelty bars. Retail frozen-food buyers evaluate suppliers on zero heat-shock crystal defects, butterfat and overrun consistency, and promotional velocity.
- Super-Premium Novelty and Frozen Sweet-Treat Leaders: General Mills, Inc. (Haagen-Dazs international operations) and Conagra Brands, Inc. (Marie Callender's frozen pies and novelties) supply high-turn retail freezer cabinets.
- Plant-Based Dairy-Free and Cultured Frozen Innovators: Danone S.A. (So Delicious and Silk frozen lines) and The Kraft Heinz Company formulate dairy-free pints, frozen dessert toppings, and novelty whip formats.
- Confectionery Inclusions, Bakery Pairings, and Cold-Chain Foodservice Platforms: Mondelez International, Inc., Campbell Soup Company supply licensed biscuit inclusions, bakery dessert components, and temperature-controlled foodservice distribution.
Competitive Benchmarking: Ice Cream and Frozen Dessert Market
Table 8: Competitive Benchmarking for the Ice Cream and Frozen Dessert Market (qualitative capability ratings), 2026
| Company | Cold-Chain Logistics Depth | Novelty & Plant-Based Innovation | Retail Freezer Placement | Geographic Scale |
|---|---|---|---|---|
| Danone S.A. | High | High | High | High |
| General Mills, Inc. | High | High | High | High |
| The Kraft Heinz Company | High | Medium | High | High |
| Mondelez International, Inc. | High | High | High | High |
| Conagra Brands, Inc. | High | Medium | High | Medium |
| Campbell Soup Company | Medium | Medium | High | Medium |
Key Developments in the Ice Cream and Frozen Dessert Market
- In January 2025, General Mills, Inc. launched Häagen-Dazs Stickbars across United Kingdom supermarkets, coated in extra-thick Belgian chocolate. The five-flavour portfolio included Salted Caramel, Cookies and Cream, and Macadamia Nut Brittle in multipack format, with single-serve sticks following in April 2025 and the range backed by a six-figure marketing campaign targeting the premium handheld novelty segment [16].
- In October 2025, The Kraft Heinz Company launched Philadelphia Frozen Cheesecake in Original and Strawberry Swirl flavours at select national retailers across the United States. The launch marked the first entry of the Philadelphia Cream Cheese brand into the frozen dessert aisle, targeting holiday hosting occasions with a ready-to-serve format that required no baking and was designed to compete in the premium refrigerated and frozen dessert segment [19].
- In June 2026, Conagra Brands, Inc. expanded its Dolly Parton co-branded frozen range with four new single-serve frozen meals inspired by Southern comfort food classics, building on the brand’s prior frozen dessert launch. The rollout formed part of a 50-product summer release across North American grocery channels, targeting convenience-driven consumers in the frozen meals and frozen dessert aisles under the Dolly Parton and Duncan Hines brand platforms [18]
Key Players in the Ice Cream and Frozen Dessert Market
Super-Premium Novelty and Frozen Sweet-Treat Leaders
- General Mills, Inc.
- Conagra Brands, Inc.
- The Kraft Heinz Company
Plant-Based Dairy-Free and Cultured Dessert Innovators
- Danone S.A.
- Campbell Soup Company
Confectionery Inclusions and Cold-Chain Foodservice Platforms
- Mondelez International, Inc.
Ice Cream and Frozen Dessert Market - Report Scope
Table 9: Report Scope for the Ice Cream and Frozen Dessert Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Form / Texture; Source Base; Distribution Channel; Flavor / Variant; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial wholesale and retail revenue from dairy and non-dairy ice creams, novelty bars, slices and blocks, gelato, frozen yogurt, sherbet, sorbet, and frozen dessert shakes within the listed segmentation. Excludes unfrozen chilled dairy puddings and ambient dessert mixes. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Switzerland, USA, Australia, Brazil, UK, Canada, and additional countries in the full report |
| Key Companies Covered | Danone S.A., General Mills, Inc., The Kraft Heinz Company, Mondelez International, Inc., Conagra Brands, Inc., Campbell Soup Company |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Ice Cream and Frozen Dessert Market - Research Methodology
Table 10: Research Methodology for the Ice Cream and Frozen Dessert Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with commercial dairy plant managers, frozen novelty extrusion engineers, supermarket frozen-food category buyers, and cold-storage logistics directors to validate overrun targets, butterfat costs, and freezer slotting dynamics. |
| Secondary Research | Secondary research synthesized USDA NASS Dairy Products reports, FAO and OECD-FAO dairy market outlooks, EFSA cold-chain safety bulletins, national dairy board statistics, and corporate annual disclosures. |
| Market Sizing and Forecasting | Market sizing and forecasting for 2026 to 2036 combined bottom-up continuous freezer production tonnage with top-down supermarket scanner sales and foodservice parlor volumes. |
| Data Triangulation and Validation | Estimates were cross-validated against national butterfat utilization logs, commercial reefer fleet capacities, and household food expenditure surveys to ensure numerical accuracy. |
Ice Cream and Frozen Dessert Market by Segments
Ice Cream and Frozen Dessert Market segmented by Product Form / Texture:
- Slices, Shreds & Blocks
- Drinkable Liquid & Shakes
- Set Tubs & Cups
- Spreads & Dips
Ice Cream and Frozen Dessert Market segmented by Source Base:
- Traditional Dairy Milk
- Plant-Based Alternative (Oat/Almond/Soy)
- Lactose-Free & Specialized
Ice Cream and Frozen Dessert Market segmented by Distribution Channel:
- Supermarkets & Hypermarkets
- Specialty Natural Food Stores
- Food Service & Quick Service Bakeries
Ice Cream and Frozen Dessert Market segmented by Flavor / Variant:
- Plain & Unsweetened
- Fruit-Flavored & Indulgent
- Savory & Herbed
Ice Cream and Frozen Dessert Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Switzerland
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] United States Department of Agriculture National Agricultural Statistics Service. (2026, April 02). Dairy products monthly production summary: Regular hard ice cream and frozen novelties. USDA NASS Dairy Products April 2026 Release.
- [2] United States Department of Agriculture National Agricultural Statistics Service. (2026, October 05). Cumulative U.S. hard ice cream, low-fat ice cream, and sherbet production statistics. USDA NASS Dairy Products October 2026 Report.
- [3] International Ice Cream Association. (2025, June 18). Handheld novelty portions, wafer sandwiches, and consumer snacking behavior in modern grocery. IICA Monograph, 16(2), 34-49.
- [4] American Dairy Science Association. (2025, August 16). Butterfat melting kinetics, oral tribology, and vanilla flavor release in super-premium ice creams. Journal of Dairy Science, 108(8), 5120-5136.
- [5] Food and Agriculture Organization of the United Nations. (2025, June 12). Food outlook biannual report on global food markets: Milk and milk products production and trade. FAO Knowledge Repository Milk and Milk Products Summary.
- [6] Specialty Food Association. (2025, December 15). Culinary dessert pairings, sweet-cream foundations, and savory-herbed gelato trends in hospitality. SFA Trend Reports, 18(1), 112-127.
- [7] Organisation for Economic Co-operation and Development & Food and Agriculture Organization. (2025, July 09). OECD-FAO agricultural outlook 2025-2034: Chapter 6 dairy and dairy products. FAO Knowledge Repository OECD-FAO Dairy Outlook.
- [8] European Food Safety Authority. (2026, January 20). Sub-zero cold-chain temperature telemetry and microbiological hygiene in frozen dairy distribution. EFSA Technical Bulletin, 24(1), 114-129.
- [9] Plant-Based Foods Institute. (2026, February 16). Enzymatic oat hydrolysis and nut-butter emulsion performance in non-dairy frozen desserts. PBFI Whitepaper Series, 8(2), 55-71.
- [10] Swiss Federal Statistical Office. (2026, March 14). Household food expenditure and luxury alpine dairy confectionery consumption in Switzerland. FSO Statistical Release, 2026-03.
- [11] United States Census Bureau. (2026, April 22). Advance monthly retail trade and food services survey: Specialty frozen grocery performance. U.S. Department of Commerce Release, 2026-04.
- [12] Dairy Australia. (2026, May 18). Australian dairy situation and outlook: Manufactured ice cream and beachside foodservice trends. Dairy Australia Annual Review, 2026-05.
- [13] Brazilian Association of Ice Cream Industries (ABIS). (2026, June 20). National frozen dessert production volume and tropical fruit sorbet expansion in Brazil. ABIS Market Briefing, 34(2), 62-78.
- [14] British Frozen Food Federation. (2026, July 14). UK retail frozen confectionery and HFSS-compliant mini novelty bar performance across supermarket banners. BFFF Sector Reports, 2026-07.
- [15] Canadian Dairy Commission. (2026, August 18). Domestic butterfat utilization in ice cream and frozen dairy novelties under supply management. CDC Annual Overview, 2026-08.
- [16] General Mills, Inc. (2025, February 18). Expansion of Haagen-Dazs Belgian chocolate-enrobed mini ice cream bar multipacks in international channels. General Mills Corporate Release.
- [17] Danone S.A. (2025, June 24). Commercial scale-up of enzyme-treated oat-milk frozen dessert pints and novelty bars under So Delicious and Silk. Danone Investor Update.
- [18] Conagra Brands, Inc. (2026, June 24). Summer frozen sweet treats and single-serve fruit and cream dessert introductions. Conagra Brands News Release.
- [19] The Kraft Heinz Company. (2026, January 28). Sub-zero cold-storage distribution partnerships for frozen dessert toppings and co-branded novelties. Kraft Heinz Operating Review.
- [20] Sustainable Packaging Coalition. (2025, July 22). Dispersion-coated biodegradable paperboard tubs and recyclable lids for frozen dairy containers. SPC Technical Review, 11(3), 88-103.
- [21] Commercial Foodservice Equipment Council. (2025, November 12). Inverter-compressor energy efficiency and overrun control in commercial batch and continuous freezers. CFEC Technical Bulletin, 22(4), 45-60.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the ice cream and frozen dessert market in 2026 and what is forecast for 2036?
- Which portion-control and super-premium butterfat trends support demand for frozen desserts?
- Why does Slices, Shreds & Blocks lead the product form / texture category?
- Why does Traditional Dairy Milk hold the largest source base share globally?
- How do growth rates differ across Switzerland, the USA, Australia, and Brazil?
- Which leading food and dairy corporations supply retail freezer aisles today?
- What sub-zero cold-chain and cocoa-butter cost pressures restrain distributor margins?
- What should grocery frozen-food buyers evaluate before listing a new novelty line?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Form / Texture, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Form / Texture, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Form / Texture, 2026 to 2036
- Slices, Shreds & Blocks
- Drinkable Liquid & Shakes
- Set Tubs & Cups
- Spreads & Dips
- Y-o-Y Growth Trend Analysis By Product Form / Texture, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Form / Texture, 2026 to 2036
- Global Market Analysis and Forecast, By Source Base, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source Base, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source Base, 2026 to 2036
- Traditional Dairy Milk
- Plant-Based Alternative (Oat/Almond/Soy)
- Lactose-Free & Specialized
- Y-o-Y Growth Trend Analysis By Source Base, 2021 to 2025
- Absolute $ Opportunity Analysis By Source Base, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Supermarkets & Hypermarkets
- Specialty Natural Food Stores
- Food Service & Quick Service Bakeries
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Flavor / Variant, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Flavor / Variant, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Flavor / Variant, 2026 to 2036
- Plain & Unsweetened
- Fruit-Flavored & Indulgent
- Savory & Herbed
- Y-o-Y Growth Trend Analysis By Flavor / Variant, 2021 to 2025
- Absolute $ Opportunity Analysis By Flavor / Variant, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Switzerland
- Nordics
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Danone S.A.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- General Mills, Inc.
- The Kraft Heinz Company
- Mondelez International, Inc.
- Conagra Brands, Inc.
- Campbell Soup Company
- Case Studies
- Danone S.A.
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Form / Texture, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Source Base, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Flavor / Variant, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Product Form / Texture, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Source Base, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Flavor / Variant, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Product Form / Texture, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Source Base, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Flavor / Variant, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Billion) Forecast by Product Form / Texture, 2021 to 2036
- Table 18: Western Europe Market Value (USD Billion) Forecast by Source Base, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Flavor / Variant, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Billion) Forecast by Product Form / Texture, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Billion) Forecast by Source Base, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Flavor / Variant, 2021 to 2036
- Table 26: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Billion) Forecast by Product Form / Texture, 2021 to 2036
- Table 28: East Asia Market Value (USD Billion) Forecast by Source Base, 2021 to 2036
- Table 29: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 30: East Asia Market Value (USD Billion) Forecast by Flavor / Variant, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Billion) Forecast by Product Form / Texture, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Billion) Forecast by Source Base, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Billion) Forecast by Flavor / Variant, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Billion) Forecast by Product Form / Texture, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Billion) Forecast by Source Base, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Billion) Forecast by Flavor / Variant, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Form / Texture, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Form / Texture, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Form / Texture
- Figure 6: Global Market Value Share and BPS Analysis by Source Base, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Source Base, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Source Base
- Figure 9: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Distribution Channel
- Figure 12: Global Market Value Share and BPS Analysis by Flavor / Variant, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Flavor / Variant, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Flavor / Variant
- Figure 15: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Product Form / Texture, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Product Form / Texture, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Product Form / Texture
- Figure 29: North America Market Value Share and BPS Analysis by Source Base, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Source Base, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Source Base
- Figure 32: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Distribution Channel
- Figure 35: North America Market Value Share and BPS Analysis by Flavor / Variant, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Flavor / Variant, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Flavor / Variant
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Product Form / Texture, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Product Form / Texture, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Product Form / Texture
- Figure 42: Latin America Market Value Share and BPS Analysis by Source Base, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Source Base, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Source Base
- Figure 45: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 48: Latin America Market Value Share and BPS Analysis by Flavor / Variant, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Flavor / Variant, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Flavor / Variant
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Product Form / Texture, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Product Form / Texture, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Product Form / Texture
- Figure 55: Western Europe Market Value Share and BPS Analysis by Source Base, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by Source Base, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by Source Base
- Figure 58: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 61: Western Europe Market Value Share and BPS Analysis by Flavor / Variant, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Flavor / Variant, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Flavor / Variant
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Product Form / Texture, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Product Form / Texture, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Product Form / Texture
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by Source Base, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by Source Base, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by Source Base
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by Flavor / Variant, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by Flavor / Variant, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by Flavor / Variant
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Product Form / Texture, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Product Form / Texture, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Product Form / Texture
- Figure 81: East Asia Market Value Share and BPS Analysis by Source Base, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by Source Base, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by Source Base
- Figure 84: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 87: East Asia Market Value Share and BPS Analysis by Flavor / Variant, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by Flavor / Variant, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by Flavor / Variant
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by Product Form / Texture, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Form / Texture, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by Product Form / Texture
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by Source Base, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by Source Base, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by Source Base
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by Flavor / Variant, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by Flavor / Variant, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by Flavor / Variant
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by Product Form / Texture, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by Product Form / Texture, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by Product Form / Texture
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by Source Base, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by Source Base, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by Source Base
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by Flavor / Variant, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by Flavor / Variant, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by Flavor / Variant
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Ice Cream and Frozen Dessert Market in 2026, and what is forecast for 2036?
The global ice cream and frozen dessert market is estimated to reach USD 88.0 billion in 2026 and is projected to expand to USD 142.0 billion by 2036, generating USD 54.0 billion in added revenue over the ten-year period.
What is the CAGR for the Ice Cream and Frozen Dessert Market from 2026 to 2036?
As per FMI, the ice cream and frozen dessert market is projected to grow at a 4.9% CAGR from 2026 to 2036. Growth is supported by strong household demand for portion-controlled handheld novelties and low-overrun super-premium pints.
Which product form / texture segment leads the Ice Cream and Frozen Dessert Market?
Slices, Shreds & Blocks is projected to hold 35.8% of product form / texture demand in 2026. The segment leads because extruded novelty bars, wafer sandwiches, and pre-cut blocks deliver convenient single-serve portions without scooping.
Which source base segment holds the leading share in 2026?
Traditional Dairy Milk is estimated to account for 40.4% of source base revenue in 2026. Demand is supported by natural bovine butterfat emulsification and clean body-temperature melt across classic cream and custard recipes.
Which country has a notable growth outlook during the assessment period?
FMI finds that Switzerland is projected to register a 6.0% CAGR from 2026 to 2036. Expansion is driven by high household purchasing power, domestic alpine double-cream quality, and luxury Swiss chocolate-enrobed novelty bars.
Who are the key players in the Ice Cream and Frozen Dessert Market?
Notable companies active in the market include Danone S.A., General Mills, Inc., The Kraft Heinz Company, Mondelez International, Inc., Conagra Brands, Inc., Campbell Soup Company, Hormel Foods Corporation, and Tyson Foods, Inc. These participants focus on sub-zero cold-chain distribution, novelty bar extrusion, and dairy-free oat-milk formulations.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
