
- Market Size (2026)
- USD 3.8 Bn
- Forecast (2036)
- USD 5.3 Bn
- CAGR (2026 to 2036)
- 3.4%
How big is Ice Cream Coating Market in 2026?
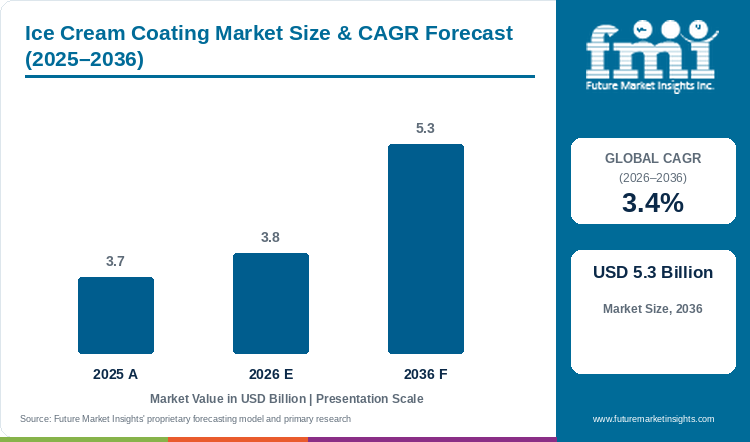
Global ice cream coating sales are estimated at USD 3.8 billion in 2026 and are projected to reach USD 5.3 billion by 2036, expanding at a 3.4% CAGR over the forecast period.
Demand in the global ice cream coating market is climbing steadily as dairy brands and frozen novelty makers roll out dipped stick bars, filled wafer cones, and bite-sized freezer treats that deliver a clean chocolate snap and keep ice cream from going icy in storage. Future Market Insights values the market at USD 3.7 billion in 2025 and USD 3.8 billion in 2026, with sales projected to reach USD 5.3 billion by 2036 at a 3.4% CAGR. Within the broader compound chocolate sector, which is growing at a faster 6.3% pace, cocoa and compound dipping coatings hold 66.1% of 2026 demand because coconut and palm kernel oil blends harden inside freezer tunnels in under twenty seconds without slow cocoa butter tempering. Lifecycle research published in Science of the Total Environment shows that raw ingredients account for over 60% of chocolate production's environmental footprint, with white chocolate reaching 4.06 kg CO2-eq per kilogram and dark chocolate at 2.32 kg CO2-eq per kilogram, giving novelty makers another strong reason to replace scarce cocoa butter with vegetable fat compounds[1]. Even so, volatile cocoa bean costs and grayish surface fat bloom when retail freezers warm up and cool down continue to squeeze profit margins for mainstream novelty producers.
Key Market Trends & Insights
- By coating base: Cocoa & Compound Coatings are projected to capture 66.1% in 2026 because fast-setting shells prevent melting on high-speed novelty lines.
- By lipid system: Lauric Vegetable Oil Compounds are estimated to command 58.3% in 2026 as coconut and palm kernel fats deliver a crisp bite without tempering.
- By inclusion texture: Smooth Gloss Enrobing is expected to concentrate 54.7% in 2026 because thin, even shells keep coating weight low on each stick bar.
- By novelty format: Extruded Stick Bars are forecast to generate 53.1% in 2026 owing to high-volume automated dipping across dairy plants.
- By price tier: Mid-Tier Mainstream Brands are anticipated to account for 52.7% in 2026 through family multipack supermarket sales.
Regional Highlights
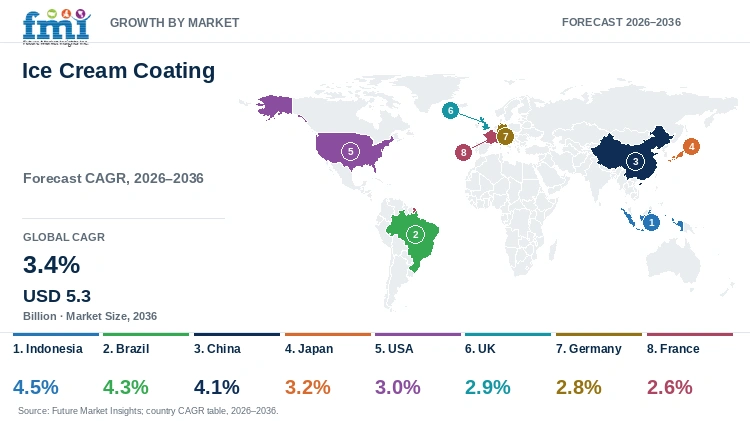
- Top national expansion: Indonesia is projected to lead major novelty markets at a 4.5% CAGR through 2036, supported by local palm kernel oil refining and convenience store freezer growth.
- Broader country progression: Brazil is expected to expand at 4.3% CAGR ahead of China (4.1%), Japan (3.2%), the United States (3.0%), the United Kingdom (2.9%), Germany (2.8%), and France (2.6%).
Market Size & Forecast
Table 1: Market Size and Forecast for the Ice Cream Coating Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 3.7 billion |
| Estimated Market Size in 2026 | USD 3.8 billion |
| Projected Market Size by 2036 | USD 5.3 billion |
| CAGR, 2026 to 2036 | 3.4% |
| Added Value, 2026 to 2036 | USD 1.5 billion |
Industrial dairy kitchens and contract novelty packers have to manage high cocoa prices while keeping freezer line energy use in check. Traditional pure cocoa butter chocolate requires slow, multi-stage temperature control, which holds back line speeds and raises the risk of cracked shells during sub-zero blast freezing. Trade figures from the USDA Foreign Agricultural Service show that U.S. chocolate and cocoa product exports rose 11% from USD 2.41 billion in 2024 to USD 2.67 billion in 2025, led by shipments to Canada (USD 1.51 billion) and Mexico (USD 0.39 billion), as processors adjusted recipes to handle higher cocoa costs[2]. To protect margins, frozen dessert makers are switching to easy-flowing industrial chocolate compounds that keep coating thickness consistent at full production speed.
Novelty Production and Coating-Volume Sizing
Table 2: Novelty Production and Coating-Volume Sizing for the Ice Cream Coating Market (2025, 2026, and 2036)
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 3.7 | 3.8 | 5.3 |
| Dipped novelty volume (billion units) | 94.0 to 102.0 | 97.0 to 106.0 | 134.0 to 146.0 |
| Industrial coating volume (million tonnes) | 1.1 to 1.2 | 1.1 to 1.3 | 1.5 to 1.7 |
| Average coating cost per bar (USD) | 0.03 to 0.04 | 0.03 to 0.04 | 0.04 to 0.05 |
Operational note: Coating-volume ranges apply global dipped novelty production against an average 16.0% to 22.0% coating pick-up weight per bar or cone.
High-speed stick-bar lines need molten coatings to stay fluid at 40 to 45 degrees Celsius so the chocolate drains evenly across frozen cores without leaving pinholes or thick edges at the bottom. Suppliers of chocolate couverture and vegetable fat compounds use sunflower lecithin and plant-based flow modifiers to keep coating weight within a 1.5-gram window per bar.
Per Capita & Dairy Plant Sizing
Table 3: Per Capita and Plant Spending Indicators for the Ice Cream Coating Market (2025, 2026, and 2036)
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Spend per 1,000 people (USD) | 451.2 | 457.8 | 588.9 |
| Annual coating spend per novelty line (USD thousand) | 410.0 to 460.0 | 420.0 to 475.0 | 560.0 to 630.0 |
| Compound vs. real couverture volume share (%) | 68.0% to 72.0% | 69.0% to 73.0% | 73.0% to 77.0% |
Table 4: Industrial Dairy Plant Coating Expenditure Indicators for the Ice Cream Coating Market (2026)
| Metric | Value | Industrial Reference Basis |
|---|---|---|
| Market size, 2026 | USD 3.8 billion | 2026 global demand baseline |
| Commercial ice cream novelty lines | 8,400 lines | Global rotary extrusion and cone line registry |
| Coating spend per novelty line | USD 452.4 thousand | Annualized dipping fat and glaze procurement |
| Extruded stick-bar coating demand, 2026 | USD 2.0 billion | 53.1% novelty format segment allocation |
Preventing shells from shattering when bitten while cutting saturated fat and sugar requires blending liquid vegetable oils with firmer tropical fats, a recipe shift that also supports mini frozen dessert novelties sold in portion-controlled grocery packs.
Analyst Perspective
"Frozen novelty manufacturers require dipping coatings that set in under twenty seconds without cracking during palletized cold-chain shipping. Ingredient suppliers delivering thin, even vegetable fat blends with cocoa-saving flavor systems will win multi-year supply contracts with dairy processors."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the ice cream coating market segmented?
The ice cream coating market is segmented by coating base (cocoa & compound coatings, fruit & sorbet glazes, caramel & nut coatings), lipid system, inclusion texture, novelty format, price tier, and region.
By coating base: Cocoa & Compound Coatings, Fruit & Sorbet Glazes, Caramel & Nut Coatings, and Others.
By lipid system: Lauric Vegetable Oil Compounds, Cocoa Butter Real Couverture, Non-Lauric High-Oleic Blends, and Others.
By inclusion texture: Smooth Gloss Enrobing, Nut & Wafer Inclusions, Double-Dip & Liquid-Core, and Others.
By novelty format: Extruded Stick Bars, Wafer Cones & Discs, Bites & Sandwiches, and Others.
By price tier: Mid-Tier Mainstream Brands, Premium Specialty Artisanal, and Private-Label & Economy.
Why do Cocoa & Compound Coatings lead the coating base category?
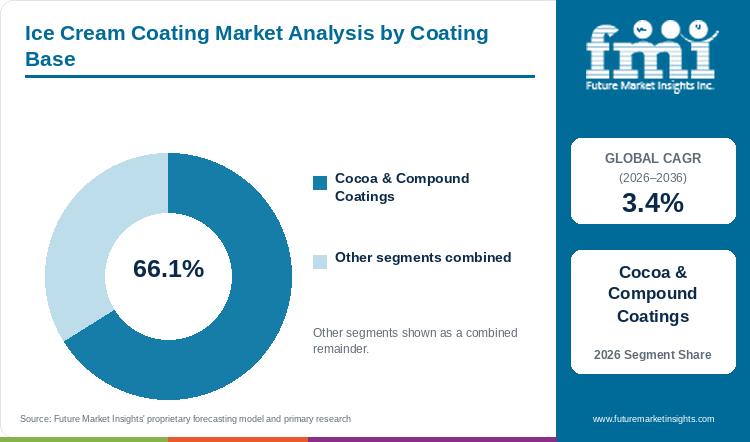
Cocoa & Compound Coatings are projected to capture 66.1% of coating base demand in 2026 because vegetable-fat chocolate compounds set in under twenty seconds without cocoa butter tempering.
Table 5: Coating Base Share for the Ice Cream Coating Market (percentage share), 2026
| Coating Base | Share (2026) |
|---|---|
| Cocoa & Compound Coatings | 66.1% |
| Other Segments Combined | 33.9%* |
| Total | 100.0% |
*Note: Remaining coating base categories sum to 100.0% of 2026 industrial dipping volume.
Table 6: Coating Base Leadership and Market Growth for the Ice Cream Coating Market (2026 to 2036)
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 3.4% |
| Leading Segment | Cocoa & Compound Coatings (66.1%) |
Frozen novelty makers prefer cocoa and compound dipping coatings because blending cocoa powder into vegetable fats gives bars a familiar chocolate taste and shine at roughly half the ingredient cost of pure cocoa butter shells, supporting wide adoption across the ice cream and frozen dessert industry.
- Cocoa & Compound Coatings are projected to secure 66.1% of coating base demand in 2026 by combining fast freezer setting with dependable moisture protection around whipped dairy cores.
- Mixture-design experiments published in Food Chemistry show that partially replacing cocoa butter with palm oil or shea butter extenders lowers coating thickness resistance and boosts chocolate aroma release by 20% to 60% once substitution passes 10%[3].
Why do Lauric Vegetable Oil Compounds define the largest lipid system segment?
Lauric Vegetable Oil Compounds are estimated to secure 58.3% of the lipid system segment in 2026 as coconut and palm kernel fats deliver a crisp snap and fast sub-zero hardening.
Getting a clean snap within seconds of dipping a minus 25 degree Celsius ice cream bar requires fast-melting tropical fats, prompting processors that also buy ice cream premix and stabilizers to specify coconut and palm kernel oil compounds.
- Lauric Vegetable Oil Compounds are estimated to command 58.3% of the lipid system segment in 2026 because coconut and palm kernel fats harden directly into a smooth, glossy crystal structure without tempering machines.
- Research in Crystal Growth & Design confirms that adding 0.1% food-grade phospholipid seeding particles helps chocolate fats lock into stable Form V crystals at 28 degrees Celsius under simple static cooling without mechanical shear or surface cracking[4].
What keeps Smooth Gloss Enrobing ahead by inclusion texture?
Smooth Gloss Enrobing is expected to command 54.7% of inclusion texture demand in 2026 because smooth liquid coatings allow thin, uniform pick-up weights on high-speed dipping lines.
Smooth, nut-free coatings run all day through curtain coaters and dip tanks without clogging pumps or screens, allowing cost-focused brands testing carob-based cocoa replacers to apply thin 12% to 15% shell weights.
- Smooth Gloss Enrobing is expected to hold 54.7% of inclusion texture demand in 2026 because smooth liquid flow keeps shell thickness even and cuts total fat use per bar.
- Puratos Group NV reported through its Cacao-Trace program that it distributed EUR 7.0 million in farmer payouts—EUR 3.2 million in Chocolate Bonus funds and EUR 3.8 million in Quality Premiums—across 24,073 cocoa growers in eight countries while expanding traceable dipping chocolate supply[5].
Why do Extruded Stick Bars lead the novelty format category?
Extruded Stick Bars are forecast to generate 53.1% of novelty format demand in 2026 owing to automated immersion dipping across single-serve and multipack bar lines.
Automated stick-bar lines turn out 18,000 to 30,000 bars per hour and rely on immersion dipping tanks to seal exposed ice cream surfaces right after wire cutting.
- Extruded Stick Bars are forecast to account for 53.1% of novelty format demand in 2026 as single-serve sticks and mini-bar multipacks anchor grocery freezer doors.
- Food Chemistry testing on model chocolate coatings shows that replacing 50% of cocoa butter with soy-protein and carrageenan oil gels cuts saturated fat by more than 20% and raises unsaturated fat by over 25% while keeping shells resistant to fat bloom[6].
What gives Mid-Tier Mainstream Brands the leading position in price tier?
Mid-Tier Mainstream Brands are anticipated to account for 52.7% of price tier demand in 2026 through bulk liquid compound procurement for supermarket multipacks.
Supermarket family multipacks and convenience store single bars make up the bulk of industrial dipping volume and rely on standardized compound coatings to hit everyday retail prices.
- Mid-Tier Mainstream Brands are anticipated to capture 52.7% of price tier demand in 2026 because high-volume dairy plants buy heated liquid bulk tankers rather than boxed chocolate blocks.
- Technical guidance from Fuji Oil Holdings Inc., parent of Blommer Chocolate Company and one of the world's top three suppliers of vegetable fats for chocolate, notes that tailored palm and shea fat blends let mainstream novelty lines adjust drying speed, viscosity, shine, and heat resistance[7].
What are the drivers, restraints, and opportunities in the ice cream coating market?
In the ice cream coating market, high-speed stick-bar automation and cocoa butter replacement drive compound demand, while cocoa bean price volatility and temperature-swing fat bloom restrain margins.
- Driver: High-speed stick-bar and bite-sized novelty lines turn fast-setting compound and couverture coatings into primary moisture barriers.
- Restraint: High cocoa bean prices and surface fat bloom during freezer temperature swings tighten processor margins.
- Opportunity: Double-dipped soft-core shells, pistachio paste glazes, and sugar-free coatings open higher-margin freezer door space.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Dairy plants are upgrading novelty lines to run layered stick bars and bite-sized bonbons that need thinner, faster-draining coatings to trim shell weight by 8% to 12%. Amid volatile cocoa raw material prices, research in Food Chemistry shows that replacing 20% to 30% of cocoa butter with walnut-oil gels stabilized by whey protein and xanthan gum achieves 92% to 95% oil-binding capacity, 85.3% shape retention at 40 degrees Celsius, and 40% lower fat-bloom whiteness after 40 days[8].
Risk Assessment of the Ice Cream Coating Market: Operational and Formulation Friction
Mixing cocoa butter with coconut or palm kernel oils can cause dull gray fat bloom whenever store freezers warm up during door openings and defrost cycles. A study in Food Research International found that adding 8% candelilla plant wax to lauric coconut and palm kernel oil chocolates locks in stable beta-prime crystals that block liquid oil migration during temperature swings[9], helping protect the visual appeal of chocolate inclusions and decorations on dipped bars.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Coating suppliers are rolling out fruit-prep glazes, antioxidant plant extracts, and cell-cultured cocoa butter and cacao alternatives to trim saturated fat and reduce cocoa sourcing risk. Research in Food Science & Nutrition verified that encapsulating functional plant extracts in a 15% maltodextrin and 2% pectin coating improves melting resistance and reduces stickiness in frozen desserts[10].
Ice Cream Coating Market by Country (2026 to 2036)
As per FMI, Indonesia is projected to lead ice cream coating expansion across tracked markets at a 4.5% CAGR from 2026 to 2036, followed by Brazil at 4.3% and China at 4.1%.
Table 7: Country CAGR and Primary Growth Levers for the Ice Cream Coating Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Indonesia | 4.5% | Domestic palm kernel oil refining and convenience store freezer expansion |
| Brazil | 4.3% | Native tropical fat substitution and regional impulse novelty growth |
| China | 4.1% | Inland city cold-chain rollout and multi-textured stick-bar launches |
| Japan | 3.2% | Convenience store seasonal novelty rotation and ultra-thin snap coatings |
| USA | 3.0% | Club-store multipack stick bars and reduced-sugar bite-sized bonbons |
| UK | 2.9% | HFSS portion-size reformulation and private-label mini stick bars |
| Germany | 2.8% | EUDR-certified sustainable cocoa sourcing in discount retail multipacks |
| France | 2.6% | Safety-screened nut-paste glazes and 100% cocoa butter real couverture bars |
Source: Future Market Insights analysis
Indonesia Ice Cream Coating Market Outlook (2026 to 2036)
Unlike cooler Western markets that ship liquid chocolate in heated tankers, Indonesia supports Southeast Asian novelty manufacturing through local palm kernel and coconut oil refineries linked with expanding convenience store freezer networks. A study in Food Chemistry demonstrated that formulating dark chocolates with 5% to 40% tropical mahua oil cocoa butter equivalents keeps coating viscosity steady between 5.6 and 7.9 Pa and prevents fat bloom over 12 weeks of storage[11]. Domestic ice cream coating demand is projected to grow at a leading 4.5% CAGR through 2036 as stick-bar makers add halal-certified compound dipping lines across Java and Sumatra.
Key takeaway: In Indonesia, local palm kernel refining and heat-tolerant compound recipes are projected to drive the fastest national coating growth through 2036.
Brazil Ice Cream Coating Market Outlook (2026 to 2036)
Industrial ice cream coating sales in Brazil are expected to rise at a 4.3% CAGR from 2026 to 2036, supported by year-round warm weather and regional brands replacing costly cocoa butter with native palm fats. Researchers writing in Food Chemistry confirmed that blending Brazilian licuri palm oil and cassava derivatives in gluten- and lactose-free ice cream cones controls moisture absorption and keeps cones crisp[12]. Local novelty plants use domestic palm kernel, licuri, and babassu fats to shield retail stick-bar prices from imported cocoa swings.
Key takeaway: In Brazil, native palm fat substitution and expanding regional novelty chains are expected to sustain 4.3% annual demand growth.
China Ice Cream Coating Market Outlook (2026 to 2036)
In contrast to mature European markets, China's cold-chain expansion into smaller inland cities is speeding up automated stick-bar and wafer-cone production across Inner Mongolia and eastern dairy hubs. AAK AB and Kuala Lumpur Kepong Berhad broke ground in Pasir Gudang, Malaysia on their Nura Specialty Oils and Fats palm fractions plant—scheduled to ramp up in 2028 with full production in 2029—to expand Asian supply of specialty coating fats[13]. China is forecast to record a 4.1% CAGR between 2026 and 2036 as domestic dairy groups launch double-dipped tea, red-bean, and pistachio-coated bars.
Key takeaway: In China, cold-chain rollout into smaller cities and layered novelty launches are forecast to support a 4.1% CAGR.
Japan Ice Cream Coating Market Outlook (2026 to 2036)
Whereas Southeast Asian producers focus on affordable single-layer compounds, Japanese confectionery and dairy makers compete on paper-thin crisp chocolate shells, cone moisture barriers, and multi-layered textures sold across 56,000 convenience stores. Fuji Oil Holdings Inc. reported FY2025 net sales of JPY 370.90 billion in Industrial Chocolate and JPY 271.08 billion in Vegetable Oils and Fats, with business profit rising on steady demand for chocolate vegetable fats and lower cocoa bean costs at Blommer Chocolate Company[14]. Japan is projected to advance at a 3.2% CAGR from 2026 to 2036 as convenience store brands rotate seasonal matcha, white chocolate, and nut-crisp bars.
Key takeaway: In Japan, convenience store seasonal bar rotation and ultra-thin snap coatings are projected to sustain a 3.2% CAGR.
USA Ice Cream Coating Market Outlook (2026 to 2036)
Club-store multipacks and bite-sized frozen bonbons drive United States coating purchases, where dairy co-packers rely on heated liquid tanker deliveries and strict allergen separation. A study in Foods showed that replacing 25% to 60% of cocoa butter with symmetrical mangosteen seed fat slows liquid oil migration and delays surface fat bloom during freezer temperature swings[15]. United States demand is forecast to grow at a 3.0% CAGR through 2036 as national brands expand reduced-sugar shells and roasted almond stick bars.
Key takeaway: In the USA, club-store multipack stick bars and bite-sized bonbons are predicted to anchor a 3.0% CAGR.
UK Ice Cream Coating Market Outlook (2026 to 2036)
What sets the United Kingdom apart from continental Europe is strict government high-fat, salt, and sugar (HFSS) promotional limits as well as intense supermarket private-label competition. Research in Food Science & Nutrition demonstrated that coating guar, locust bean, and xanthan gums onto a carrageenan matrix raises ice cream structural strength by 35% to 40% and delays first melting drip time by more than 25% during dipping and storage[16]. The UK market is estimated to expand at a 2.9% CAGR from 2026 to 2036 as retailers commission smaller portion-controlled stick bars and vegan coconut-oil coatings.
Key takeaway: In the UK, HFSS portion-size rules and supermarket private-label mini bars are estimated to drive a 2.9% CAGR.
Germany Ice Cream Coating Market Outlook (2026 to 2036)
Germany differs from price-led compound markets because discount grocers require strict European Union deforestation-free cocoa traceability and sustainability certification across private-label stick bars and cones. The USDA Foreign Agricultural Service European Union Dairy and Products Annual report estimates EU27 milk deliveries at 153.7 million metric tons in 2026 and 153.3 million metric tons in 2027, prompting dairy processors in Germany to prioritize higher-margin dessert and novelty lines[17]. German ice cream coating sales are projected to grow at a 2.8% CAGR through 2036.
Key takeaway: In Germany, traceable cocoa sourcing and discount supermarket multipack novelties are projected to support a 2.8% CAGR.
France Ice Cream Coating Market Outlook (2026 to 2036)
Artisanal gelato shops and grocery patisserie brands shape French demand, favoring 100% cocoa butter real couverture, caramelized white chocolate, and roasted pistachio or hazelnut paste glazes. An investigation in the Italian Journal of Food Safety evaluating pistachio and hazelnut ice creams at a 10% nut-paste inclusion rate found that 36% of unscreened artisanal pastes risked exceeding EU Regulation 2023/915 mycotoxin limits, reinforcing processor shifts toward tested industrial nut glazes[18]. France is forecast to progress at a 2.6% CAGR between 2026 and 2036 as processors expand verified nut-paste and fruit-sorbet shell lines.
Key takeaway: In France, real cocoa butter couverture and safety-tested nut-paste novelty glazes are forecast to maintain a 2.6% CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the ice cream coating market?
Barry Callebaut AG, Cargill, Incorporated, Puratos Group NV, Fuji Oil Holdings Inc., Cemoi Group, IRCA S.p.A., AAK AB, and Blommer Chocolate Company represent the notable companies in the ice cream coating market.
FMI analysis indicates that the competitive arena divides between global vertically integrated cocoa and industrial chocolate processors, specialty vegetable fat fractionators, and artisanal nut-paste and fruit-glaze formulators.
- Global Industrial Chocolate & Cocoa Leaders: Barry Callebaut AG, Cargill, Incorporated, and Puratos Group NV operate bulk liquid tanker networks and regional application centers serving multinational dairy processors.
- Specialty Vegetable Fat & Compound Innovators: Fuji Oil Holdings Inc., Blommer Chocolate Company, and AAK AB refine lauric and non-lauric fat fractions that control setting speed, shell flexibility, and anti-bloom stability.
- European Couverture & Artisanal Glaze Specialists: Cemoi Group and IRCA S.p.A. supply pistachio, hazelnut, caramel, and fruit-prep dipping coatings as well as single-origin couvertures for premium novelties.
Competitive Benchmarking: Ice Cream Coating Market
Table 8: Competitive Benchmarking for the Ice Cream Coating Market (qualitative capability tiers), 2026
| Company | Coating Portfolio Breadth | Lipid Fractionation Depth | Bulk Liquid Supply Access | Geographic Reach |
|---|---|---|---|---|
| Barry Callebaut AG | High | High | High | High |
| Cargill, Incorporated | High | High | High | High |
| Puratos Group NV | High | Medium | High | High |
| Fuji Oil Holdings Inc. | High | High | High | High |
| Cemoi Group | High | Medium | High | Medium |
| IRCA S.p.A. | High | Medium | Medium | High |
| AAK AB | Medium | High | High | High |
| Blommer Chocolate Company | High | High | High | Medium |
Scoring basis: Capability tiers evaluate documented coating portfolio breadth across compound and real chocolate bases, specialty fat fractionation depth, liquid bulk supply chain access, and regional plant footprint.
Key Developments in the Ice Cream Coating Market
- Barry Callebaut AG reported 9-month fiscal year 2025/26 sales volume of 1,557,239 tonnes and sales revenue of CHF 9,557.1 million (CHF 9.6 billion) in July 2026, with third-quarter volume turning positive at +5.7% and AMEA chocolate volume rising +10.3%[19].
- Research in Food Research International profiling 131 volatile aroma compounds across bulk and fine cocoa roasting and conching showed that controlled fermentation preserves key pyrazines and esters used in European couvertures from producers such as Cemoi Group[20].
- Fuji Oil Holdings Inc. published technical guidance on low-melting-temperature specialty chocolate coatings formulated to melt smoothly in a mouth cooled by minus 20 degree Celsius ice cream[21].
Key Players in the Ice Cream Coating Market
Global Industrial Chocolate & Cocoa Leaders
- Barry Callebaut AG
- Cargill, Incorporated
- Puratos Group NV
Specialty Vegetable Fat & Compound Innovators
- Fuji Oil Holdings Inc.
- Blommer Chocolate Company
- AAK AB
European Couverture & Artisanal Glaze Specialists
- Cemoi Group
- IRCA S.p.A.
Ice Cream Coating Market - Report Scope
Table 9: Report Scope for the Ice Cream Coating Market (coverage fields and definitions)
| Coverage field | Report scope |
|---|---|
| Market breakdown | Coating Base; Lipid System; Inclusion Texture; Novelty Format; Price Tier; Region |
| Quantitative Units | USD Billion |
| Market Definition | Commercial supplier demand for compound chocolate, real couverture, nut-paste, caramel, and fruit-prep coatings applied to frozen novelties |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Indonesia, Brazil, China, Japan, USA, UK, Germany, France, plus regional aggregations |
| Key Companies Covered | Barry Callebaut AG, Cargill, Incorporated, Puratos Group NV, Fuji Oil Holdings Inc., Cemoi Group, IRCA S.p.A., AAK AB, Blommer Chocolate Company |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up novelty line coating reconciliation |
Ice Cream Coating Market - Research Methodology
Table 10: Research Methodology for the Ice Cream Coating Market (research methods and analytical approach)
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with dairy novelty R&D directors, industrial chocolate formulators, and specialty fat procurement managers |
| Secondary Research | Analysis of corporate annual reports, USDA Foreign Agricultural Service trade data, and peer-reviewed lipid crystallization studies |
| Market Sizing and Forecasting | Top-down industrial chocolate and specialty fat balances reconciled against bottom-up extruded bar and cone line pick-up volumes |
| Country Forecasting Model | Country projections weight per-capita novelty consumption, cold-chain retail cabinet growth, and domestic vegetable oil refining capacity |
| Operational Benchmark Traceability | Novelty unit and plant spending indicators in Tables 2, 3, and 4 cross-checked against 16% to 22% coating pick-up norms |
| Data Triangulation and Validation | Demand estimates validated against supplier bulk liquid shipment volumes and trade association production audits |
Ice Cream Coating Market by Segments
Ice Cream Coating Market segmented by Coating Base:
- Cocoa & Compound Coatings
- Fruit & Sorbet Glazes
- Caramel & Nut Coatings
- Others
Ice Cream Coating Market segmented by Lipid System:
- Lauric Vegetable Oil Compounds
- Cocoa Butter Real Couverture
- Non-Lauric High-Oleic Blends
- Others
Ice Cream Coating Market segmented by Inclusion Texture:
- Smooth Gloss Enrobing
- Nut & Wafer Inclusions
- Double-Dip & Liquid-Core
- Others
Ice Cream Coating Market segmented by Novelty Format:
- Extruded Stick Bars
- Wafer Cones & Discs
- Bites & Sandwiches
- Others
Ice Cream Coating Market segmented by Price Tier:
- Mid-Tier Mainstream Brands
- Premium Specialty Artisanal
- Private-Label & Economy
Ice Cream Coating Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
- Israel
Research Sources and Bibliography
- [1] Konar, N., Fidan, M., Atalar, I., Palabiyik, I., Sanli, T., Marasli, S., Gorgulu, A., Sagdic, O., & Toker, O. S. (2026, February 25). Life cycle hotspots in chocolate production: Ingredient formulation, processing technologies, and pathways toward sustainable confectionery systems. Science of the Total Environment, 1018, 181500 (PubMed PMID 41679024).
- [2] USDA Foreign Agricultural Service. (2026, March 12). Chocolate and Cocoa Products 2025 Export Highlights. United States Department of Agriculture.
- [3] Molard, B., Maraval, I., Deuscher, Z., Goli, T., Boulanger, R., & Lecomte, J. (2026, April 30). Effect of palm oil and shea butter addition on chocolate rheology, aroma release and sensory perception: a mixture design of experiment approach. Food Chemistry, 509, 148561 (PubMed PMID 41740385).
- [4] Stobbs, J. A., Ghazani, S. M., Tu, K., Pensini, E., Fameau, A.-L., & Marangoni, A. G. (2025, June 4). Dimyristoylphosphoethanolamine Addition During Chocolate Manufacture Promotes Proper Tempering under Simple Cooling Conditions without Shear. Crystal Growth & Design, 25(12), 4621-4635 (PMCID PMC12186740).
- [5] Puratos Group NV. (2025, November 13). Sharing success through Cacao-Trace: How our Chocolate Bonus brings real impact. Puratos Group NV.
- [6] Zhang, M., Niu, Y., Zhang, S., Li, X., & Ajala, B. T. (2026, October 2). Foam-templated dual-network oleogels based on soybean protein isolate-kappa-carrageenan and glycerol monostearate for partial cocoa butter replacement in a model chocolate. Food Chemistry, 532(Pt 1), 151409 (PubMed PMID 42838010).
- [7] Fuji Oil Holdings Inc. (2026, January 15). Compound Chocolate | Chocolate Happiness | FUJI OIL CO., LTD. Fuji Oil Holdings Inc. (Parent of Blommer Chocolate Company).
- [8] Yang, X., Luan, Y., Yin, L., & Jia, X. (2025, December 15). Walnut oil-based emulsion-templated Oleogels stabilized by whey protein concentrate and xanthan gum as cocoa butter substitutes: Enhancing thermal stability and bloom resistance in chocolate. Food Chemistry, 495(Pt 2), 146410 (PubMed PMID 40987157).
- [9] Fu, Y., Chen, Y., Li, P., Li, C., Wang, Z., & Cao, J. (2025, March 1). Preparation and characterization of lauric acid-rich wax oleogel chocolates: Insights into crystallization behavior, storage stability, and bloom resistance. Food Research International, 204, 115886 (PubMed PMID 39986758).
- [10] Slimani, S., Lamia, K., Akretche-Kelfat, S., Amira, O., & Hesarinejad, M. A. (2025, May 19). Enhanced Antioxidant Properties in Functional Ice Cream Through Encapsulation of Pulsed Electric Field-Assisted Artemisia campestris Extract. Food Science & Nutrition, 13(5), e70306 (PMCID PMC12086377).
- [11] Thilakarathna, R. C. N., Siow, L. F., Tang, T.-K., Cheong, L.-Z., & Lee, Y.-Y. (2025, June 15). Mahua oil fraction: A sustainable and functional 1,3-dipalmitoyl-2-oleoylglycerol (POS)-enriched cocoa butter equivalent for chocolate production. Food Chemistry, 477, 143564 (PubMed PMID 40037047).
- [12] Santos, A. A. S., da Costa, M. C. D. S. A., Costa, S. S., Velloso, T. R., Ribeiro, J. S., Cerqueira, U. M. F. M., Pereira-Filho, E. R., & Dos Santos, E. L. O. (2025, August 30). Use of mixture Design in the Development of gluten- and lactose-free ice cream cones using Licuri (Syagrus coronata (Martius) Beccari) and cassava (Manihot esculenta Crantz) derivatives. Food Chemistry, 484, 144376 (PubMed PMID 40286716).
- [13] AAK AB. (2026, September 1). AAK and KLK break ground for Nura specialty palm fractions plant in Malaysia. AAK AB.
- [14] Fuji Oil Holdings Inc. (2026, May 12). Business Summary | Financial and Performance Overview | Investor Relations | FUJI OIL CO., LTD. Fuji Oil Holdings Inc.
- [15] Hou, X., Chen, Y., Wei, L., & Jin, J. (2025, February 7). Mangosteen Seed Fat: A Typical 1,3-Distearoyl-Sn-2-Linoleoyl-Glycerol-Rich Fat and Its Effects on Delaying Chocolate Fat Bloom. Foods, 14(4), 557 (PMCID PMC11854371).
- [16] Kilinc, M., & Ilkilinc, G. (2026, March 3). The Effect of the Use of Microencapsulated Stabilizers on Textural Rheological and Physicochemical Properties of Ice Cream. Food Science & Nutrition, 14(3), e71570 (PMCID PMC12954641).
- [17] USDA Foreign Agricultural Service. (2026, October 26). European Union: Dairy and Products Annual (Report E42026-0089). United States Department of Agriculture.
- [18] Spinola, F., Forgia, S., Mandarino, S., Marotta, S., Nalbone, L., Giarratana, F., & Giuffrida, A. (2026, May 7). Presence of aflatoxins B and G and ochratoxin A in artisanal dried fruit ice cream produced in the province of Messina, Italy. Italian Journal of Food Safety, 15(2), 13545 (PMCID PMC13189039).
- [19] Barry Callebaut AG. (2026, July 9). Barry Callebaut Group - 9-Month Key Sales Figures, Fiscal Year 2025/26. Barry Callebaut Group.
- [20] de Andrade, A. B., Gubert, R. D. S., Nascimento, M. B., Alves, J. D. C., Mesquita, P. R. R., Shahidi, F., Maciel, L. F., & de Souza, C. O. (2025, December 1). Under and fully fermented fine and bulk cocoa: A comparative study of volatile profile in different stages of bean-to-bar processing. Food Research International, 222(Pt 1), 117743 (PubMed PMID 41267307).
- [21] Fuji Oil Holdings Inc. (2026, January 15). Cold ice cream and melt-in-the-mouth chocolate coatings | Chocolate Happiness | FUJI OIL CO., LTD. Fuji Oil Holdings Inc.
- [22] Cargill, Incorporated. (2026, April 20). Cargill wins two 2026 Edison Awards for advancing the future of food. Cargill Newsroom.
- [23] IRCA S.p.A. (2026, January 26). Welcome to Tastelab Pistachio. IRCA Group.
This bibliography is provided for reader reference and is not exhaustive. The full report draws on additional primary interviews, trade statistics, and proprietary Future Market Insights databases.
This Report Answers
- How large is the ice cream coating market in 2026 and what is forecast for 2036?
- Which novelty automation and cocoa cost pressures support demand for ice cream coatings?
- Why do Cocoa & Compound Coatings lead the coating base category?
- Why do Lauric Vegetable Oil Compounds lead the lipid system category globally?
- How do growth rates differ across Indonesia, Brazil, China, and the USA?
- Which leading companies supply industrial dipping chocolate and specialty coating fats today?
- What limits adoption or supplier switching in the ice cream coating market?
- What should buyers evaluate before purchasing an ice cream coating?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Coating Base, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Coating Base, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Coating Base, 2026 to 2036
- Cocoa & Compound Coatings
- Fruit & Sorbet Glazes
- Caramel & Nut Coatings
- Others
- Y-o-Y Growth Trend Analysis By Coating Base, 2021 to 2025
- Absolute $ Opportunity Analysis By Coating Base, 2026 to 2036
- Global Market Analysis and Forecast, By Lipid System, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Lipid System, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Lipid System, 2026 to 2036
- Lauric Vegetable Oil Compounds
- Cocoa Butter Real Couverture
- Non-Lauric High-Oleic Blends
- Others
- Y-o-Y Growth Trend Analysis By Lipid System, 2021 to 2025
- Absolute $ Opportunity Analysis By Lipid System, 2026 to 2036
- Global Market Analysis and Forecast, By Inclusion Texture, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Inclusion Texture, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Inclusion Texture, 2026 to 2036
- Smooth Gloss Enrobing
- Nut & Wafer Inclusions
- Double-Dip & Liquid-Core
- Others
- Y-o-Y Growth Trend Analysis By Inclusion Texture, 2021 to 2025
- Absolute $ Opportunity Analysis By Inclusion Texture, 2026 to 2036
- Global Market Analysis and Forecast, By Novelty Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Novelty Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Novelty Format, 2026 to 2036
- Extruded Stick Bars
- Wafer Cones & Discs
- Bites & Sandwiches
- Others
- Y-o-Y Growth Trend Analysis By Novelty Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Novelty Format, 2026 to 2036
- Global Market Analysis and Forecast, By Price Tier, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Price Tier, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Price Tier, 2026 to 2036
- Mid-Tier Mainstream Brands
- Premium Specialty Artisanal
- Private-Label & Economy
- Y-o-Y Growth Trend Analysis By Price Tier, 2021 to 2025
- Absolute $ Opportunity Analysis By Price Tier, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- Indonesia
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Coating Base
- By Lipid System
- By Inclusion Texture
- By Novelty Format
- By Price Tier
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Barry Callebaut AG
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Cargill, Incorporated
- Puratos Group NV
- Fuji Oil Holdings Inc.
- Cemoi Group
- IRCA S.p.A.
- AAK AB
- Blommer Chocolate Company
- Barry Callebaut AG
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Coating Base, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Lipid System, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Inclusion Texture, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Novelty Format, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Coating Base, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Lipid System, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Inclusion Texture, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Novelty Format, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Coating Base, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Lipid System, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Inclusion Texture, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Novelty Format, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Coating Base, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Lipid System, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Inclusion Texture, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Novelty Format, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Coating Base, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Lipid System, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Inclusion Texture, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Novelty Format, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Coating Base, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Lipid System, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Inclusion Texture, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Novelty Format, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Coating Base, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Lipid System, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Inclusion Texture, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Novelty Format, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Coating Base, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Lipid System, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Inclusion Texture, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Novelty Format, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Coating Base, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Coating Base, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Coating Base
- Figure 6: Global Market Value Share and BPS Analysis by Lipid System, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Lipid System, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Lipid System
- Figure 9: Global Market Value Share and BPS Analysis by Inclusion Texture, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Inclusion Texture, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Inclusion Texture
- Figure 12: Global Market Value Share and BPS Analysis by Novelty Format, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Novelty Format, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Novelty Format
- Figure 15: Global Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Price Tier
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Coating Base, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Coating Base, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Coating Base
- Figure 32: North America Market Value Share and BPS Analysis by Lipid System, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Lipid System, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Lipid System
- Figure 35: North America Market Value Share and BPS Analysis by Inclusion Texture, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Inclusion Texture, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Inclusion Texture
- Figure 38: North America Market Value Share and BPS Analysis by Novelty Format, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Novelty Format, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Novelty Format
- Figure 41: North America Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Price Tier
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Coating Base, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Coating Base, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Coating Base
- Figure 48: Latin America Market Value Share and BPS Analysis by Lipid System, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Lipid System, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Lipid System
- Figure 51: Latin America Market Value Share and BPS Analysis by Inclusion Texture, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Inclusion Texture, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Inclusion Texture
- Figure 54: Latin America Market Value Share and BPS Analysis by Novelty Format, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Novelty Format, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Novelty Format
- Figure 57: Latin America Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Price Tier
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Coating Base, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Coating Base, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Coating Base
- Figure 64: Western Europe Market Value Share and BPS Analysis by Lipid System, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Lipid System, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Lipid System
- Figure 67: Western Europe Market Value Share and BPS Analysis by Inclusion Texture, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Inclusion Texture, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Inclusion Texture
- Figure 70: Western Europe Market Value Share and BPS Analysis by Novelty Format, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Novelty Format, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Novelty Format
- Figure 73: Western Europe Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Price Tier
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Coating Base, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Coating Base, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Coating Base
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Lipid System, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Lipid System, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Lipid System
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Inclusion Texture, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Inclusion Texture, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Inclusion Texture
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Novelty Format, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Novelty Format, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Novelty Format
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Price Tier
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Coating Base, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Coating Base, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Coating Base
- Figure 96: East Asia Market Value Share and BPS Analysis by Lipid System, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Lipid System, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Lipid System
- Figure 99: East Asia Market Value Share and BPS Analysis by Inclusion Texture, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Inclusion Texture, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Inclusion Texture
- Figure 102: East Asia Market Value Share and BPS Analysis by Novelty Format, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Novelty Format, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Novelty Format
- Figure 105: East Asia Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Price Tier
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Coating Base, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Coating Base, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Coating Base
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Lipid System, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Lipid System, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Lipid System
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Inclusion Texture, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Inclusion Texture, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Inclusion Texture
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Novelty Format, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Novelty Format, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Novelty Format
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Price Tier
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Coating Base, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Coating Base, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Coating Base
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Lipid System, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Lipid System, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Lipid System
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Inclusion Texture, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Inclusion Texture, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Inclusion Texture
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Novelty Format, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Novelty Format, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Novelty Format
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Price Tier
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the ice cream coating market in 2026, and what is forecast for 2036?
According to FMI, global ice cream coating demand is estimated to reach USD 3.8 billion in 2026 from USD 3.7 billion in 2025. Demand is forecast to hit USD 5.3 billion by 2036 as dairy processors expand extruded stick-bar and bite-sized novelty lines.
What is the CAGR for the ice cream coating market from 2026 to 2036?
Future Market Insights projects a 3.4% compound annual growth rate between 2026 and 2036, generating USD 1.5 billion in incremental demand over the ten-year period.
Which coating base segment leads the ice cream coating market?
Cocoa & Compound Coatings are projected to capture 66.1% of coating base demand in 2026 because fast-setting vegetable oil compounds eliminate cocoa butter tempering on high-speed lines.
Which lipid system segment leads the ice cream coating market?
Lauric Vegetable Oil Compounds are estimated to secure 58.3% of the lipid system category in 2026 owing to fast sub-zero hardening and a crisp bite snap.
Which country has a notable growth outlook during the assessment period?
Indonesia is projected to lead national growth at a 4.5% CAGR through 2036, supported by domestic palm kernel oil refining and cold-chain retail expansion.
Who are the key players in the market?
Barry Callebaut AG, Cargill, Incorporated, Puratos Group NV, Fuji Oil Holdings Inc., Cemoi Group, IRCA S.p.A., AAK AB, and Blommer Chocolate Company are the leading suppliers.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
