

- Market Size (2026)
- USD 28.0 Bn
- Forecast (2036)
- USD 46.5 Bn
- CAGR (2026 to 2036)
- 5.2%
How big is Kosher Foods Market in 2026?
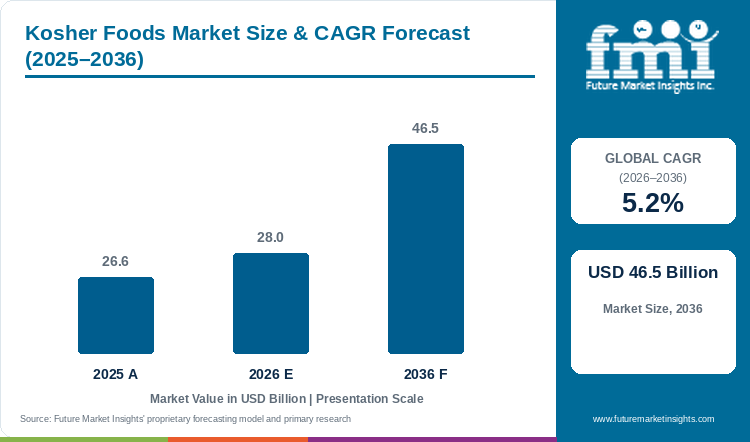
Sales in the kosher foods market are projected to grow at 5.2% CAGR, with the market size rising from USD 26.6 billion in 2025 to USD 28.0 billion in 2026 and reaching USD 46.5 billion by 2036.
Eliminating cross-contact between dairy and meat streams on high-speed packaging lines, and reducing the allergen recall exposure associated with shared factory vessels, led mainstream food processors to scale certified kosher production. In March 2025, Orthodox Union registry filings confirmed that over 1.12 million commercial products across 13,500 facilities carried active kosher symbols [1]. Owing to this widespread retail adoption, global kosher foods sales rise from USD 26.6 billion in 2025 to USD 28.0 billion in 2026. According to Future Market Insights analysis, market revenue is projected to reach USD 46.5 billion by 2036, advancing at a 5.2% CAGR and adding USD 18.5 billion over the decade. Standard commercial grade accounts for 55.0% of product type / grade demand in 2026, though recurring rabbinical inspection retainers still burden smaller regional bakeries.
Key Market Trends & Insights
- By product type / grade: Standard commercial grade led the market with a share of 55.0% in 2026, supported by high penetration across everyday pantry staples and national grocery brands.
- By processing state: Fresh and ambient packaged accounted for 41.4% of demand in 2026, reflecting long room-temperature shelf stability and lower dry-freight distribution costs.
- By end-use application: Direct retail consumer held the leading share of 46.0% in 2026, underpinned by routine household supermarket purchases among Jewish, halal-observant, and dairy-avoidant shoppers.
Regional Highlights
- Fastest-growing evaluated country: France, at 6.3% CAGR from 2026 to 2036.
- By country: USA at 5.8%, Switzerland at 5.4%, Australia at 5.0%, and Brazil at 4.6% follow, while the UK records the lowest evaluated CAGR at 4.2%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Kosher Foods Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 26.6 billion |
| Estimated Market Size in 2026 | USD 28.0 billion |
| Projected Market Size by 2036 | USD 46.5 billion |
| CAGR, 2026 to 2036 | 5.2% |
| Added Revenue, 2026 to 2036 | USD 18.5 billion |
French hypermarkets and American grocery chains enforce strict multi-tier rabbinical audit trails, whereas food processors in the United Kingdom and Brazil must navigate customs delays and currency swings on imported kosher ingredients. Multi-product factories face severe scheduling bottlenecks whenever stainless-steel cooking kettles switch from dairy runs to pareve batches. European Food Safety Authority technical panels updated traceability verification protocols in May 2025 for religious and allergen-segregated food supply chains [2]. As a result, packaged sauce and snack manufacturers are reformulating recipes with clean-label ingredients that eliminate animal-derived tallow and gelatin. Besides this, plant engineers are dedicating permanent pareve lines to avoid 24-hour boiling-water kashering downtime between commercial shifts.
Rabbinical Certification and Dedicated Line Processing Metrics
Table 2: Rabbinical Certification and Dedicated Line Processing Metrics for the Kosher Foods Market (USD billion, thousands, percentage, and hours), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 26.6 | 28.0 | 46.5 |
| Certified kosher product SKUs in distribution (thousands) | 1,050 | 1,120 | 1,850 |
| Non-Jewish consumer share of kosher food purchases (%) | 72.5 | 74.0 | 81.5 |
| Dedicated production line sanitization interval (hours) | 12 to 24 | 12 to 24 | 8 to 16 |
Registry coverage spans packaged grocery, commercial bakery, and confectionery lines audited by international kashrut supervision bodies.
Mainstream Consumer Perception & Allergen Assurance Sizing
Shoppers managing milk allergies and vegetarian diets frequently look for pareve designations as an indicator of non-dairy ingredients, although kosher certification agencies clarify that religious pareve classification does not substitute for clinical allergen control or guarantee complete freedom from trace equipment cross-contact. Supermarkets are placing certified staples next to gluten-free products inside year-round wellness aisles rather than confining inventory to seasonal holiday endcaps. Snack brands are also replacing insect-derived carmine dyes with vegetable-based colorants to keep pareve qualification across export markets.
Table 3: Consumer Perception and Allergen Assurance Spending Indicators for the Kosher Foods Market (USD and percentages), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Annual household spend on kosher-certified groceries (USD) | 385 | 405 | 590 |
| Pareve-certified share of total kosher volume (%) | 48.5 | 49.2 | 54.0 |
| Allergen-sensitive shopper penetration rate (%) | 28.4 | 30.1 | 39.5 |
| Certification and rabbinical audit share of processing cost (%) | 3.2 to 4.8 | 3.4 to 5.0 | 2.8 to 4.2 |
Table 4: Facility and Compliance Operational Spending Indicators for the Kosher Foods Market (USD, USD thousand, and percentages), mixed reporting years from 2024 to 2026
| Operational Spend Indicator | 2024 | 2025 | 2026 |
|---|---|---|---|
| Annual rabbinical agency retainer fee per facility (USD thousand) | 25 to 45 | 28 to 50 | 30 to 55 |
| Koshering steam purge energy expenditure per line (USD) | 1,200 to 1,800 | 1,250 to 1,900 | 1,320 to 2,050 |
| Certified kosher flavor precursor price premium (%) | 8.5 to 14.0 | 9.0 to 14.5 | 9.5 to 15.2 |
| Third-party allergen residue rapid swab cost (USD per test) | 18 to 26 | 20 to 28 | 22 to 32 |
Plant fee and boiler-purge figures summarize on-site mashgiach retainers and steam-sanitization logs across French, American, and Swiss food factories.
Analyst Perspective
"Verified pareve markings give packaged food brands a trusted allergen-free signal across mainstream grocery aisles. Multi-supplier enzyme and flavor qualification still delays certification for smaller co-packing plants."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the kosher foods market segmented?
The kosher foods market is segmented by product type / grade, processing state, end-use application, and region. In 2026, standard commercial grade is projected at 55.0% of product type / grade, fresh and ambient packaged at 41.4% of processing state, and direct retail consumer at 46.0% of end-use application.
By product type / grade: Standard commercial grade, specialty & gourmet formulations, certified organic kosher, and traditional holiday & ethnic foods.
By processing state: Fresh & ambient packaged, chilled & refrigerated foods, and frozen packaged foods.
By end-use application: Direct retail consumer, food service & restaurants, and institutional & healthcare catering.
Why does Standard Commercial Grade lead the product type / grade category?
Standard commercial grade is projected to hold 55.0% of product type / grade revenue in 2026, supported by pantry staple certifications.
Table 5: Product Type / Grade Share for the Kosher Foods Market (percentage share), 2026
| Product Type / Grade | Share (2026) |
|---|---|
| Standard Commercial Grade | 55.0% |
| Other Segments Combined | 45.0%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Type / Grade Leadership and Market Growth for the Kosher Foods Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.2% |
| Leading Segment | Standard Commercial Grade |
Large food manufacturers certify existing national lines of cereals, condiments, and bakery products as standard commercial grade because a single rabbinical audit unlocks both observant and mainstream shelves without changing package artwork. Artisanal glatt meats and Passover-only items require batch-by-batch manual oversight, whereas standard grade lines use pre-qualified vegetable oils and plant lecithins. Owing to the cost efficiency associated with continuous automated runs, supermarket buyers keep standard grade items at price parity with uncertified equivalents. However, an unannounced upstream change in a minor flavor carrier can still suspend plant certification until replacement lots are verified.
- Standard commercial grade is projected to account for 55.0% of product type / grade revenue in 2026, supported by continuous high-speed bottling and dry-blending runs.
- United States Department of Agriculture Economic Research Service food availability tracking in April 2025 showed that certified shelf-stable pantry staples represented over 40% of packaged dry grocery volume [3].
What supports Fresh & Ambient Packaged leadership within processing state?
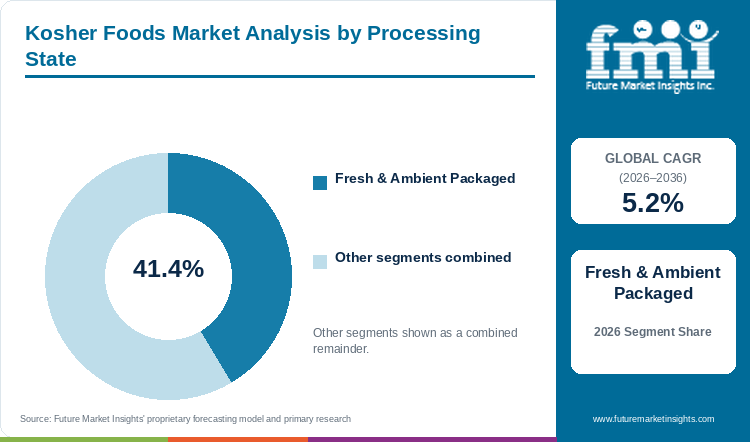
Fresh and ambient packaged is estimated to represent 41.4% of processing state demand in 2026, reflecting extended room-temperature shelf stability.
Ambient packaged groceries avoid the temperature-monitoring logs and double-sealed transport rules that complicate chilled and frozen kosher meat distribution. Crackers, canned sauces, and fruit spreads formulated with clean-label pectin can ship in mixed dry trailers alongside conventional supermarket freight without risking rabbinical seal integrity. In addition to this, ambient pouches and glass jars allow regional distributors to supply smaller Jewish and vegetarian communities where dedicated kosher cold-storage depots do not exist. High-temperature retort purging between dairy and pareve runs still requires on-site mashgiach sign-off when lines share filling heads.
- Fresh and ambient packaged is estimated to represent 41.4% of processing state demand in 2026, reflecting lower dry-freight costs and tamper-evident shelf life.
- Automated steam-purging and hermetic barrier packaging reduced cross-contact recalls across ambient processing lines by 25%, according to May 2025 Food and Agriculture Organization food safety reviews [4].
How does Direct Retail Consumer anchor the end-use application category?
Direct retail consumer is anticipated to capture 46.0% of end-use application sales in 2026, driven by year-round household grocery purchases.
Weekly family supermarket trips generate the largest recurring volume because households purchase certified breads, cooking oils, and functional foods for everyday home meals rather than waiting for banquet catering events. Commercial restaurants and hospital kitchens often struggle to maintain separate meat and dairy dishwashing rooms, so observant and dairy-avoidant consumers prefer buying sealed retail packs where they can inspect front-of-pack kosher symbols directly. Online grocery apps also let shoppers filter by pareve status before checkout, though steep slotting fees at national chains still challenge smaller kosher labels.
- Direct retail consumer is anticipated to capture 46.0% of end-use application sales in 2026, driven by mainstream supermarket aisle integration and online dietary filtering.
- Shopper surveys published by the Food Marketing Institute in June 2025 found that 68% of non-Jewish buyers selected certified pareve groceries specifically to guarantee dairy-free allergen safety [5].
What are the drivers, restraints, and opportunities in the kosher foods market?
Mainstream allergen-conscious grocery shopping expands kosher foods demand, while rabbinical steam-purging downtime constrains multi-line factories and pareve plant-based formulations open high-margin retail shelves through 2036.
- Driver: Mainstream household reliance on pareve markings for verified dairy-free and meat-free separation expands year-round grocery turnover.
- Restraint: Mandatory boiling-water equipment kashering and multi-agency rabbinical auditing fees increase changeover downtime for multi-product food plants.
- Opportunity: Replacing animal-derived gelatins and glycerides with certified plant-based texturizers unlocks wider retail distribution across vegan and kosher aisles.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Household buyers increasingly treat kosher symbols as an independent hygiene and allergen-segregation audit rather than strictly a religious label. Parents managing childhood milk allergies and adults avoiding animal fats check for pareve markings because rabbinical inspectors verify that shared mixing vats carry zero dairy residue. Federal food labeling and allergen compliance guidance updated by the US FDA in January 2025 prompted multi-line grocery brands to tighten cross-contact controls [6]. Because of that inspection mandate, manufacturers are switching from animal tallow derivatives to vegetable-based food emulsifiers so a single formulation satisfies kosher, vegan, and allergen-safe buyers before national retail rollout.
Risk Assessment of the Kosher Foods Market: Operational and Formulation Friction
Maintaining dual dairy and pareve production inside the same factory creates severe scheduling and thermal-cleaning friction. Whenever a plant switches a stainless-steel cooker from a dairy sauce to a pareve batch, rabbinical rules require a 24-hour idle period followed by a boiling-water or live-steam purge under on-site mashgiach supervision. Operational audits released by the European Jewish Congress in July 2025 revealed that certified European food processors experienced 14% higher line-sanitization downtime than uncertified peers [7]. Sourcing compliant emulsifiers and stabilizers also remains costly because a single unverified sub-ingredient can force an immediate decertification recall.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Microbial fermentation and botanical extraction contain no animal tissues, allowing vegan cheeses, dairy-free yogurts, and plant burgers to qualify for pareve status without complex slaughterhouse supervision. Kerry Group expanded its kosher-certified plant-based texturizer and enzyme lines across Europe and North America in August 2025 to support clean-label bakery and prepared-meal customers [8]. Furthermore, formulators using microbial food enzymes can improve dough elasticity and shelf life while keeping products eligible for both specialty kosher delis and mainstream natural grocery chains.
Kosher Foods Market by Country (2026 to 2036)
Across the six profiled countries, projected kosher foods growth ranges from 4.2% CAGR in the United Kingdom to 6.3% CAGR in France between 2026 and 2036. National performance depends on how effectively food manufacturers balance rabbinical audit compliance, import traceability rules, and mainstream supermarket demand for certified plant-based foods.
Table 7: Country CAGR and Primary Growth Levers for the Kosher Foods Market (CAGR percentage and operational drivers), 2026 to 2036
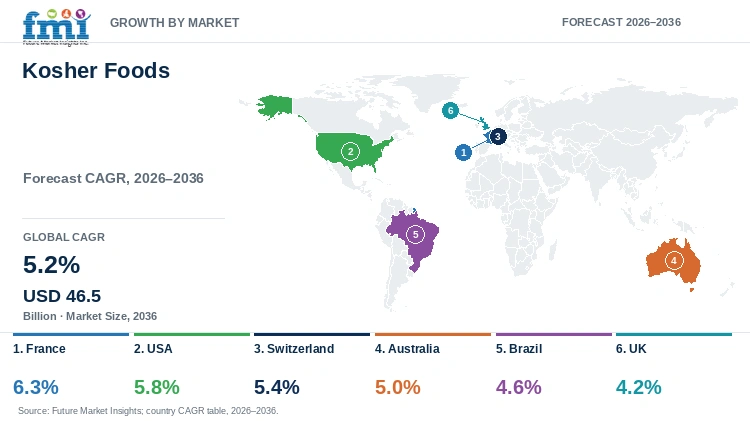
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| France | 6.3% | Expanding hypermarket kosher aisles and certified artisan bakery production in Paris and Lyon |
| USA | 5.8% | Widespread pareve symbol adoption across mainstream snacks, beverages, and allergen-safe groceries |
| Switzerland | 5.4% | Export-oriented kosher certification across luxury Swiss chocolate and specialty dairy plants |
| Australia | 5.0% | Domestic rabbinical certification of grain and snack exports into Asia-Pacific retail hubs |
| Brazil | 4.6% | Metropolitan supermarket expansion and certified beef and dairy processing in Sao Paulo |
| UK | 4.2% | Established London and Manchester kosher retail chains supported by domestic contract packers |
Source: Future Market Insights analysis
France Kosher Foods Market Outlook (2026 to 2036)
France houses Europe's largest Jewish population alongside a mainstream hypermarket sector that treats certified ethnic foods as high-margin specialty categories. Retail audits from the Consistoire Central de France in September 2025 placed domestic sales of certified kosher foods at USD 1.45 billion across Parisian and regional grocery chains [9]. Demand in the French kosher foods sector is projected to record 6.3% CAGR through 2036, propelled by dedicated kosher butcher counters and artisan patisseries. Strict European Union customs checks on imported kosher meat and wine still add administrative delays at port entry, so domestic processors contract directly with French grain mills and local dairy cooperatives for certified raw materials.
Key takeaway: French hypermarket kosher expansions and domestic grain contracting sustain Europe's fastest national growth rate.
USA Kosher Foods Market Outlook (2026 to 2036)
Sales of kosher foods in the USA are forecast to expand at 5.8% CAGR through 2036, underpinned by the fact that American consumer packaged goods giants treat rabbinical certification as a baseline requirement for national shelf placement. Rather than isolating products in seasonal holiday bays, U.S. grocers stock certified cereals, sauces, and pareve snacks across primary category aisles. National Grocers Association category tracking in June 2025 confirmed that 76% of certified kosher grocery purchases in American supermarkets came from non-Jewish households seeking allergen clarity [10]. Even so, rising slotting fees and private-label price pressure force mid-sized kosher brands to automate packaging lines to protect operating margins.
Key takeaway: American grocery chains embed rabbinical seals across mainstream aisles to capture year-round allergen-conscious household spend.
Switzerland Kosher Foods Market Outlook (2026 to 2036)
Swiss confectionery and specialty cheese manufacturers use kosher certification to win shelf space in luxury North American and Western European department stores. Between 2026 and 2036, the Switzerland market is expected to progress at 5.4% CAGR, reinforced by export-focused chocolate refineries and alpine dairy plants. High Swiss industrial wages and a strong franc make small-batch kosher runs expensive, yet chocolatiers offset those costs by scheduling dedicated rabbinical production campaigns on automated molding lines. Export customs data from the Swiss Federal Food Safety and Veterinary Office in October 2025 documented a 9.2% rise in certified confectionery and specialty dairy shipments [11].
Key takeaway: Swiss export chocolatiers and alpine dairy processors use scheduled rabbinical production runs to capture luxury retail margins.
Australia Kosher Foods Market Outlook (2026 to 2036)
Export trade logs released by the Australian Trade and Investment Commission in February 2026 showed that domestic processors shipped USD 320 million in kosher-compliant packaged foods across Asia-Pacific and North America [12]. Adoption of kosher foods in Australia is estimated to expand at 5.0% CAGR through 2036, aided by domestic supervisory bodies such as Kosher Australia in Melbourne and Sydney. Long ocean freight routes from Europe and the United States make imported chilled kosher items costly for local grocers. Australian bakers and beverage packers resolve that freight penalty by certifying local wheat, cane sugar, and botanical ingredient streams.
Key takeaway: Certifying local agricultural ingredients protects Australian retail supply against ocean freight costs while opening Asia-Pacific export channels.
Brazil Kosher Foods Market Outlook (2026 to 2036)
The Brazil kosher foods market is anticipated to grow at 4.6% CAGR between 2026 and 2036, facilitated by Sao Paulo meatpackers and edible-oil refiners that already maintain rabbinical supervision for international export shipments. Upscale supermarkets in Sao Paulo and Rio de Janeiro are widening year-round kosher dairy, wine, and dry-grocery sections for metropolitan shoppers. According to a December 2025 retail review by the Brazilian Association of Supermarkets, certified kosher product assortments grew by 14% across urban chains [13]. Because exchange-rate swings periodically inflate the price of imported European holiday items, Brazilian grocers increasingly contract private-label staples from domestic certified plants.
Key takeaway: Export-ready Brazilian meat and edible-oil processors anchor domestic kosher grocery expansion while insulating retailers from import currency swings.
UK Kosher Foods Market Outlook (2026 to 2036)
Post-Brexit customs declarations and veterinary border checks continue to slow chilled kosher food shipments arriving from France and Belgium into British ports. Despite that trade friction, demand for kosher foods in the UK is predicted to advance at 4.2% CAGR through 2036, supported by neighborhood kosher grocers and mainstream supermarket chains in London, Manchester, and Gateshead. Updated Safer Food Better Business allergen and dietary segregation guidance issued by the UK Food Standards Agency in June 2025 strengthened hygiene documentation across more than 4,500 certified British food plants [14]. To prevent holiday stockouts, British supermarkets are shifting contract bottling and baking to London Beth Din certified domestic plants.
Key takeaway: Domestic contract bottling and bakery certification in the UK help supermarkets bypass post-Brexit border delays on continental imports.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the kosher foods market?
Conagra Brands, Inc., General Mills, Inc., The Kraft Heinz Company, Nestle S.A., Danone S.A., Archer Daniels Midland Company, Kerry Group plc, Hain Celestial Group, Inc., Manischewitz Company, and B&G Foods, Inc. are the notable companies in this market.
Winning national supermarket shelf space in the kosher foods sector requires active certification letters from globally recognized rabbinical agencies alongside documented allergen-segregation protocols. Multinational grocery makers certify high-volume cereal, condiment, and frozen-meal plants so their flagship brands qualify for both mainstream and observant retail shelves. Upstream ingredient processors supply certified lecithins, enzymes, and plant-based ingredients that prevent decertification risks before blending begins, while heritage kosher brands specialize in Passover matzo, ceremonial wines, and traditional deli items.
- Multinational Packaged Grocery Leaders: Conagra Brands, Inc., General Mills, Inc., The Kraft Heinz Company, Nestle S.A., and Danone S.A. maintain multi-plant kosher certifications across global retail portfolios.
- Certified Ingredient and Clean-Label Specialists: Archer Daniels Midland Company, Kerry Group plc, and Hain Celestial Group, Inc. supply certified emulsifiers, enzymes, and organic pareve groceries.
- Heritage Kosher and Shelf-Stable Specialists: Manischewitz Company and B&G Foods, Inc. anchor traditional holiday, matzo, and specialty condiment distribution.
Competitive Benchmarking: Kosher Foods Market
Table 8: Competitive Benchmarking for the Kosher Foods Market (qualitative capability ratings), 2026
| Company | Certified Portfolio Breadth | Pareve / Allergen Segregation Depth | Retail & Foodservice Access | Geographic Reach |
|---|---|---|---|---|
| Conagra Brands, Inc. | High | High | High | Medium |
| General Mills, Inc. | High | High | High | High |
| The Kraft Heinz Company | High | High | High | High |
| Nestle S.A. | High | High | High | High |
| Danone S.A. | Medium | High | High | High |
| Archer Daniels Midland Company | High | High | Medium | High |
| Kerry Group plc | Medium | High | Medium | High |
| Hain Celestial Group, Inc. | Medium | High | High | Medium |
| Manischewitz Company | High | High | High | Medium |
| B&G Foods, Inc. | Medium | Medium | High | Medium |
Scoring basis: Ratings reflect documented rabbinical registry coverage across multi-category grocery catalogs, dedicated pareve or steam-purged manufacturing lines, placement in national supermarket chains, and international export presence across North America, Europe, and Asia-Pacific.
Key Developments in the Kosher Foods Market
- The Kraft Heinz Company modernized its European condiment bottling facilities with dedicated pareve packaging lines in October 2025 to eliminate dairy cross-contact [15].
- Orthodox Union certification agreements were expanded by General Mills, Inc. in June 2025 across its global breakfast cereal and snack bar manufacturing plants [16].
- A USD 50.0 million capital program completed by Conagra Brands, Inc. in January 2025 installed automated high-temperature kosher steam-cleaning systems across its Midwestern frozen and snack hubs [17].
Key Players in the Kosher Foods Market
Multinational Packaged Grocery Leaders
- Conagra Brands, Inc.
- General Mills, Inc.
- The Kraft Heinz Company
- Nestle S.A.
- Danone S.A.
Certified Ingredient and Clean-Label Specialists
- Archer Daniels Midland Company
- Kerry Group plc
- Hain Celestial Group, Inc.
Heritage Kosher and Shelf-Stable Specialists
- Manischewitz Company
- B&G Foods, Inc.
Kosher Foods Market - Report Scope
Table 9: Report Scope for the Kosher Foods Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type / Grade; Processing State; End-Use Application; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial revenue from rabbinically certified kosher packaged foods, beverages, and culinary staples sold across retail and foodservice channels. Excludes uncertified conventional groceries and farm-gate raw commodities prior to certified processing. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | France, USA, Switzerland, Australia, Brazil, UK, and additional countries in the full report |
| Key Companies Covered | Conagra Brands, Inc., General Mills, Inc., The Kraft Heinz Company, Nestle S.A., Danone S.A., Archer Daniels Midland Company, Kerry Group plc, Hain Celestial Group, Inc., Manischewitz Company, B&G Foods, Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
As per FMI, commercial scope covers rabbinically certified packaged foods and excludes uncertified groceries and unprocessed farm-gate crops.
Kosher Foods Market - Research Methodology
Table 10: Research Methodology for the Kosher Foods Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with certified food manufacturers, rabbinical supervisory agencies, ingredient suppliers, supermarket category directors, and foodservice procurement managers across key markets to validate line-sanitization costs, certification adoption, and purchasing decisions. |
| Secondary Research | Secondary research included rabbinical certification registries, government food safety and agricultural databases, company annual reports, investor presentations, trade journals, and publicly available regulatory publications relevant to certified food processing. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 forecast period were developed using top-down and bottom-up approaches to assess certified SKU volumes, retail scanner turnover, and country-level demand conditions. |
| Data Triangulation and Validation | Data is validated against macroeconomic food expenditure indicators, certification agency registry counts, allergen-free purchasing trends, and historical performance to ensure high accuracy without double counting adjacent categories. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's specialty certified food econometric model, calibrating evaluated national growth rates against the 5.2% global baseline through verified kosher agency brand certifications, mainstream wellness aisle shelf-placement, and export clean-label ingredient auditing. |
| Operational Benchmark Traceability | Operational benchmarks (certified kosher product SKUs in distribution, rabbinical supervisory auditing fees, and ingredient trace vetting times) represent modeled estimates synthesized from Orthodox Union bulletins, USDA ERS data, and commercial food processor filings. |
Kosher Foods Market by Segments
Kosher Foods Market segmented by Product Type / Grade:
- Standard Commercial Grade
- Specialty & Gourmet Formulations
- Certified Organic Kosher
- Traditional Holiday & Ethnic Foods
Kosher Foods Market segmented by Processing State:
- Fresh & Ambient Packaged
- Chilled & Refrigerated Foods
- Frozen Packaged Foods
Kosher Foods Market segmented by End-Use Application:
- Direct Retail Consumer
- Food Service & Restaurants
- Institutional & Healthcare Catering
Kosher Foods Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Western Europe
- France
- United Kingdom
- Switzerland
- Germany
- Belgium
- Eastern Europe
- Poland
- Hungary
- Russia
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- Australia
- New Zealand
- India
- Middle East and Africa
- Israel
- South Africa
Research Sources and Bibliography
- [1] Orthodox Union. (2025, March 14). The state of global kosher certification: Growth trends in commercial food processing. OU Kosher Annual Industry Report, 38, 45-62.
- [2] European Food Safety Authority. (2025, May 19). Scientific technical report on traceability and authenticity verification in religious and ethnic food certifications. EFSA Supporting Publications, 22(3), 8890.
- [3] United States Department of Agriculture Economic Research Service. (2025, April 10). Food availability and consumption trends: Religious and clean-label certifications in mainstream retail. Ag and Food Statistics: Charting the Essentials.
- [4] Food and Agriculture Organization of the United Nations. (2025, May 30). Traceability and food safety systems in religious certification frameworks. The State of Food Security and Nutrition in the World 2025.
- [5] Food Marketing Institute. (2025, June 12). U.S. grocery shopper trends: Clean-label perceptions and kosher symbol recognition among non-Jewish consumers. Food Marketing Institute Research Series, 42, 60-78.
- [6] U.S. Food and Drug Administration. (2025, January 14). Food labeling guide: Requirements for religious and dietary certification marks and allergen controls on commercial packaging. Labeling & Nutrition Guidance Documents & Regulatory Information.
- [7] European Jewish Congress. (2025, July 18). Economic and operational review of kosher food production in the European Union. EJC Policy Studies Series, 14, 28-44.
- [8] Kerry Group plc. (2025, August 21). Expansion of certified clean-label plant-based texturizer and enzyme lines across European and North American hubs. Kerry Corporate Newsroom Releases.
- [9] Consistoire Central de France. (2025, September 15). Rapport annuel sur la filiere cacher: Production, distribution et consommation en France. Consistoire Publications, 31, 35-52.
- [10] National Grocers Association. (2025, June 24). Specialty, allergen-safe, and certified kosher food categories in supermarket retailing. NGA Category Management Bulletin, 19, 18-34.
- [11] Swiss Federal Food Safety and Veterinary Office (BLV). (2025, October 16). Schweizerische Lebensmittelkontrolle: Zertifizierte Lebensmittel im Aussenhandel. BLV Jahresbericht, 24, 40-58.
- [12] Australian Trade and Investment Commission (Austrade). (2026, February 11). Global export performance for Australian kosher-certified packaged foods. Austrade Commercial Insights, 16(2), 22-38.
- [13] Associacao Brasileira de Supermercados (ABRAS). (2025, December 09). Relatorio do setor supermercadista brasileiro: Alimentos certificados e saudabilidade. ABRAS Estudos Economicos, 47, 75-92.
- [14] UK Food Standards Agency. (2025, June 05). Commercial food hygiene, allergen segregation, and religious dietary compliance in the United Kingdom. Safer Food, Better Business (SFBB) Guidance.
- [15] The Kraft Heinz Company. (2025, October 14). Modernization of European condiment bottling plants with dedicated pareve packaging technology. Kraft Heinz Corporate Press Releases.
- [16] General Mills, Inc. (2025, June 19). Expansion of Orthodox Union kosher verification across global breakfast cereal and snack bar facilities. General Mills Operations Updates.
- [17] Conagra Brands, Inc. (2025, January 22). Capital investment in automated steam-purging sanitation lines across Midwestern manufacturing hubs. Conagra Brands Investor Relations.
- [18] Hain Celestial Group, Inc. (2026, March 10). Launch of certified organic pareve vegetable broths and snack puffs in North American retail channels. Hain Celestial Product Announcements.
- [19] Manischewitz Company. (2025, November 04). Automated matzo baking and kosher culinary broth distribution expansion into national grocery chains. Manischewitz Corporate Releases.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the kosher foods market in 2026 and what is forecast for 2036?
- How do automated steam-purging systems reduce line changeover downtime between dairy and pareve runs?
- What allows standard commercial grade to hold 55.0% of product type / grade revenue?
- What operational advantages allow fresh and ambient packaged goods to lead processing state demand?
- Why do non-Jewish, lactose-intolerant, and vegan shoppers purchase pareve-certified groceries?
- How do growth trajectories differ across France, the USA, Switzerland, and Australia?
- Which multinational grocery brands and specialized companies supply certified kosher products today?
- What should retail procurement teams evaluate before qualifying a certified kosher food supplier?
Frequently Asked Questions
How large is the Kosher Foods Market expected to be in 2026?
As per FMI, the global kosher foods market will reach USD 28.0 billion in 2026 and is projected to climb to USD 46.5 billion by 2036.
What CAGR is forecast for the Kosher Foods Market through 2036?
Global kosher food revenues are projected to grow at a 5.2% CAGR from 2026 to 2036, supported by mainstream household demand for allergen-segregated pareve groceries and wider supermarket shelf placement.
Which product type / grade holds a notable kosher foods demand share in 2026?
Standard commercial grade is projected to hold 55.0% of product type / grade revenue in 2026 because national food conglomerates certify high-volume cereal, sauce, and snack lines.
Which end-use application segment leads the Kosher Foods Market in 2026?
Direct retail consumer is anticipated to account for 46.0% of end-use application demand in 2026, driven by weekly household grocery trips and online pareve dietary filtering.
Which country has a notable kosher foods expansion outlook during the forecast period?
FMI finds that France will expand at a 6.3% CAGR during the 2026 to 2036 assessment period, supported by Parisian hypermarket kosher sections and domestic artisan bakeries.
Which companies are active in the Kosher Foods Market during 2026?
Key market participants include Conagra Brands, Inc., General Mills, Inc., The Kraft Heinz Company, Nestle S.A., Danone S.A., Archer Daniels Midland Company, Kerry Group plc, Hain Celestial Group, Inc., Manischewitz Company, and B&G Foods, Inc. These companies prioritize automated steam-purging lines, clean-label pareve reformulation, and multi-facility rabbinical certification.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type / Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type / Grade, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type / Grade, 2026 to 2036
- Standard Commercial Grade
- Specialty & Gourmet Formulations
- Certified Organic Kosher
- Traditional Holiday & Ethnic Foods
- Y-o-Y Growth Trend Analysis By Product Type / Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type / Grade, 2026 to 2036
- Global Market Analysis and Forecast, By Processing State, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Processing State, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Processing State, 2026 to 2036
- Fresh & Ambient Packaged
- Chilled & Refrigerated Foods
- Frozen Packaged Foods
- Y-o-Y Growth Trend Analysis By Processing State, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing State, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Application, 2026 to 2036
- Direct Retail Consumer
- Food Service & Restaurants
- Institutional & Healthcare Catering
- Y-o-Y Growth Trend Analysis By End-Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- France
- United Kingdom
- Switzerland
- Germany
- Belgium
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Hungary
- Russia
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Australia
- New Zealand
- India
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Israel
- South Africa
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Conagra Brands, Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- General Mills, Inc.
- The Kraft Heinz Company
- Nestle S.A.
- Danone S.A.
- Archer Daniels Midland Company
- Kerry Group plc
- Hain Celestial Group, Inc.
- Manischewitz Company
- B&G Foods, Inc.
- Conagra Brands, Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


