
- Market Size (2026)
- USD 1.6 Bn
- Forecast (2036)
- USD 3.1 Bn
- CAGR (2026 to 2036)
- 6.8%
How big is Halal Food Market in 2026?
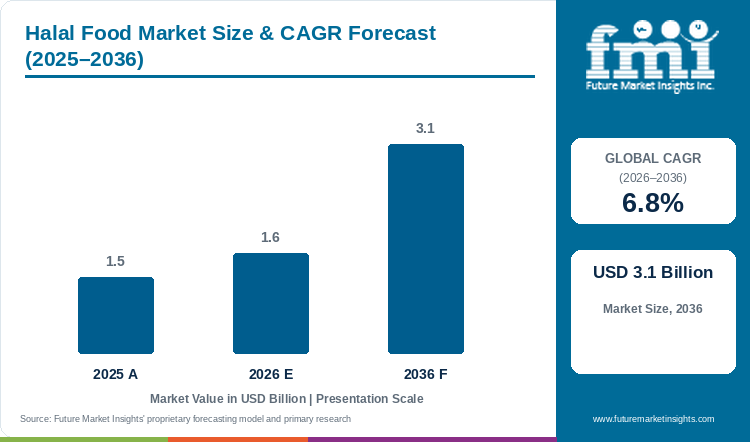
Global halal food sales revenue is projected to grow at a 6.8% CAGR, with market valuation rising from USD 1.5 billion in 2025 to USD 1.6 billion in 2026 and attaining USD 3.1 billion by 2036.
Widespread urbanization and cross-border retail expansion have resulted in higher purchasing standards among multicultural grocery shoppers; however, fragmented slaughterhouse oversight has created a pressing need for verified halal supply chains. Global halal food sales rise from USD 1.5 billion in 2025 to USD 1.6 billion in 2026 and are projected to attain USD 3.1 billion by 2036 at a 6.8% CAGR, creating USD 1.5 billion in incremental opportunity as per FMI. Updated halal red-meat export integrity rules issued by the Australian Department of Agriculture, Fisheries and Forestry in February 2025 tightened abattoir carcass segregation audits. Within product type / grade, Standard Commercial Grade captures 53.9% share in 2026 as processors source certified halal ingredients to keep everyday grocery prices accessible.
Key Market Trends & Insights
- By product type / grade: Standard Commercial Grade accounted for 53.9% of demand in 2026, underpinned by industrial poultry and beef packers running accredited single-specification slaughter lines for mainstream supermarkets.
- By processing state: Fresh / Ambient Packaged represented 40.3% of revenue in 2026, as family kitchens pair freshly butchered red meat cuts with ambient basmati rice and cooking spices.
- By end-use application: With a 44.9% share in 2026, Direct Retail Consumer Consumption led the category as national hypermarket chains expanded dedicated halal chilled bays.
Regional Highlights
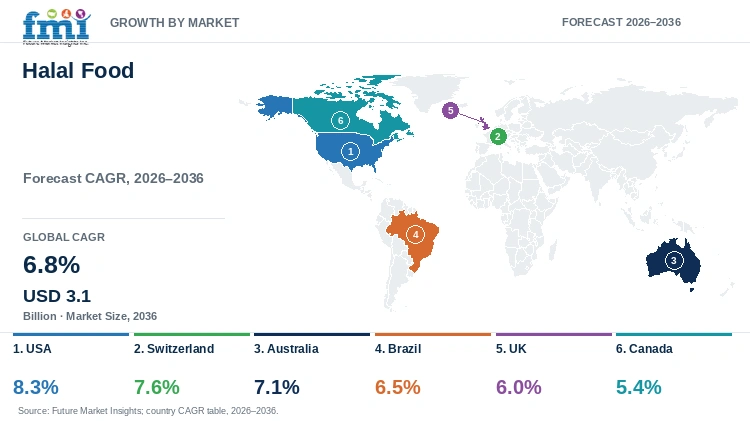
- Fastest-growing evaluated country: The USA, at 8.3% CAGR from 2026 to 2036.
- By country: Switzerland at 7.6%, Australia at 7.1%, Brazil at 6.5%, and the UK at 6.0% follow, while Canada records the lowest evaluated CAGR at 5.4%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Halal Food Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 1.5 billion |
| Estimated Market Size in 2026 | USD 1.6 billion |
| Projected Market Size by 2036 | USD 3.1 billion |
| CAGR, 2026 to 2036 | 6.8% |
| Added Revenue, 2026 to 2036 | USD 1.5 billion |
Meat exporters shipping poultry and beef into Gulf Cooperation Council ports, Southeast Asian retail chains, and Western hypermarkets must maintain separate washdown shifts and non-porcine enzyme documentation across every plant. Retail food packages carrying a halal claim in Canada are required to display the full legal name of the certifying body under May 2025 Canadian Food Inspection Agency method-of-production enforcement. Because customs inspectors reject consignments with incomplete slaughter logs, multinational food manufacturers are replacing batch paper certificates with scannable QR-code lot tracking and dedicated halal processing rooms.
Certified Slaughter Throughput and Trade Sizing
Table 2: Certified Slaughter Throughput and Cold-Chain Trade Indicators for the Halal Food Market (USD billion, million tonnes, and percentage), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 1.5 | 1.6 | 3.1 |
| Certified poultry and red meat export volume (million tonnes) | 4.2 to 4.7 | 4.5 to 5.0 | 7.8 to 8.6 |
| Dedicated halal cold-chain container share (%) | 36.0 to 39.5 | 38.0 to 41.5 | 54.0 to 58.5 |
| Average certification and segregation audit cost per tonne (USD) | 18.5 to 22.0 | 19.0 to 23.0 | 24.5 to 29.0 |
Slaughter tonnage, bonded reefer container share, and per-tonne audit fees measure cross-border halal meat, dairy, and ambient grocery shipments moving through accredited export abattoirs.
Per Capita & Certified Establishment Indicators
Supermarket category managers now allocate permanent refrigerated bays to halal proteins because observant Muslim households and ethical shoppers both look for verified slaughter hygiene and gelatin-free ingredient labels. Maintaining uninterrupted halal status inside a multi-product plant demands physical separation from porcine derivatives across receiving docks, grinders, and chillers. Export meat packers shipping chilled cuts across ocean corridors rely on vacuum skin films and protective meat packaging to prevent purge and preserve red muscle color during transit.
Table 3: Per Capita and Household Spending Indicators for the Halal Food Market (billion people and USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Market spend per capita (USD) | 0.18 | 0.19 | 0.35 |
| Market spend per 1,000 people (USD) | 182.3 | 192.8 | 346.4 |
| Annual spend per certified retail grocery aisle (USD) | 4,200 to 4,850 | 4,480 to 5,150 | 7,600 to 8,750 |
Table 4: Channel & Application Revenue Allocation for the Halal Food Market (USD billion and percentage share), 2026
| Metric | Value | Operational Scope |
|---|---|---|
| Market size, 2026 | USD 1.6 billion | Global in-scope halal food valuation |
| Direct retail consumer consumption revenue, 2026 | USD 0.72 billion | 44.9% end-use application share |
| Food service & hospitality revenue, 2026 | USD 0.52 billion | 32.7% end-use application share |
| Commercial food manufacturing plants revenue, 2026 | USD 0.36 billion | 22.4% end-use application share |
Analyst Perspective
"Unified halal emulsifier lists and microbial-rennet dairy lines enable food processors to supply ethnic grocers and national hypermarkets from a single facility. Divergent national stunning rules and segregated reefer fees still compel exporters to qualify every destination market separately."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the halal food market segmented?
The halal food market is segmented by product type / grade, processing state, end-use application, and region. In 2026, standard commercial grade is projected at 53.9%, fresh / ambient packaged at 40.3%, and direct retail consumer consumption at 44.9%.
By product type / grade: Standard Commercial Grade, Organic & Clean-Label Variant, and Premium Specialty Formulation.
By processing state: Fresh / Ambient Packaged, Frozen & Chilled, and Dehydrated & Dry Packaged.
By end-use application: Direct Retail Consumer Consumption, Food Service & Hospitality, and Commercial Food Manufacturing Plants.
Buyers and certification boards evaluate this market across three primary commercial axes and seven geographic regions from 2026 to 2036. Product Type / Grade separates everyday standard commercial grade meats and seasonings from organic clean-label lines and fortified specialty products. Processing State covers physical preservation across fresh and ambient packaged groceries, frozen and chilled items, and dehydrated shelf-stable packs. End-Use Application distinguishes household supermarket retail from food service hospitality venues and industrial food plants.
Why does Standard Commercial Grade lead the product type / grade category?
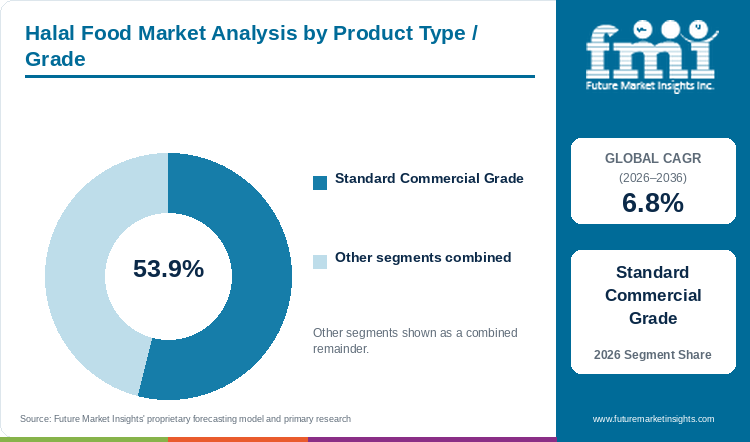
With an estimated 53.9% share in 2026, standard commercial grade leads product type / grade, underpinned by high-volume poultry throughput.
Table 5: Product Type / Grade Share for the Halal Food Market (percentage share), 2026
| Product Type / Grade | Share (2026) |
|---|---|
| Standard Commercial Grade | 53.9% |
| Other Segments Combined | 46.1%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Type / Grade Leadership and Market Growth for the Halal Food Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.8% |
| Leading Segment | Standard Commercial Grade |
Industrial poultry abattoirs, beef deboning plants, and dry grocery blenders run continuous single-specification halal shifts that keep unit costs competitive with conventional grocery items. Supermarket chains and institutional kitchens rely on standard commercial cuts and microbial-enzyme dairy inputs such as compliant halal cheese to stock everyday family meal staples without price premiums. Harmonized OIC/SMIIC and JAKIM emulsifier registries also let factories qualify bulk vegetable oils and seasonings across multiple export destinations. Certified pasture-fed feed requirements keep Organic & Clean-Label Variant (26.8%) and Premium Specialty Formulation (19.3%) priced for higher-income urban shoppers.
- Standard commercial grade is projected to account for 53.9% of product type / grade revenue in 2026, underpinned by high-speed abattoir line efficiency and broad supermarket staple availability.
- Updated industrial ingredient guidelines published by the Halal Development Corporation in March 2025 standardized 140 commercial emulsifiers, microbial rennet enzymes, and bovine gelatin alternatives for mass-market food processors.
What keeps Fresh / Ambient Packaged ahead by processing state?
Fresh / ambient packaged is anticipated to contribute 40.3% of processing state sales in 2026, owing to daily butcher counter turnover.
Household cooks strongly prefer freshly chilled lamb, beef, and poultry cuts paired with ambient-sealed rice, lentils, and spice pastes for daily scratch cooking. Meat packers use modified-atmosphere tray sealing to preserve bright red oxymyoglobin color across supermarket chillers without freezing muscle fibers. Multi-line food plants also run shared clean-room sanitation schedules that satisfy both halal auditors and certified kosher foods inspectors on ambient dry-packing lines. Frozen & Chilled items (34.6%) serve working families seeking par-baked flatbreads and battered poultry snacks, while Dehydrated & Dry Packaged goods (25.1%) supply bulk soup and seasoning blenders.
- Fresh / ambient packaged is estimated to represent 40.3% of processing state demand in 2026, owing to strong consumer turnover across supermarket butcher counters and ambient spice aisles.
- Cross-border trade of modified-atmosphere chilled halal meat and ambient culinary staples across OIC member corridors expanded 14.2% in the February 2025 Standards and Metrology Institute for Islamic Countries (SMIIC) trade bulletin.
What gives Direct Retail Consumer Consumption the leading position in end-use application?
Direct retail consumer consumption is set to command 44.9% of end-use application revenue in 2026, reinforced by supermarket aisle expansion.
National hypermarkets, neighborhood ethnic grocers, and online grocery platforms dedicate permanent chilled bays to certified meats, deli slices, and ready-to-cook marinades, making household retail the primary revenue engine. Younger multicultural families check front-of-pack certification logos alongside clean label ingredients declarations to verify that sauces and snacks contain zero alcohol carriers or porcine enzymes. Supermarket private-label halal ranges have narrowed the price gap with conventional grocery items, pulling weekly household food baskets into audited retail chains. Institutional catering in Food Service & Hospitality (32.7%) and industrial ingredient usage in Commercial Food Manufacturing Plants (22.4%) account for the remaining volume.
- Direct retail consumer consumption is projected to hold 44.9% of end-use application revenue in 2026, reinforced by private-label hypermarket expansion and transparent certification labeling.
- Certified packaged halal food sales across mainstream North American supermarket chains rose 14.0% year-on-year in October 2025 according to Islamic Services of America retail tracking.
What are the drivers, restraints, and opportunities in the halal food market?
In the Halal Food Market, multicultural grocery expansion and ethical clean-slaughter assurance will continue to support demand, fragmented national accreditation bodies and segregated cold-chain costs will constrain trade, and convenience ready meals alongside plant-based halal proteins are expected to widen retail sales through 2036.
- Driver: Expanding multicultural urban populations and broader mainstream supermarket shelf allocation for certified clean-slaughter proteins will continue to propel retail and catering volume through 2036.
- Restraint: Divergent national halal certification standards and mandatory physical cold-chain segregation will continue to elevate export audit and freight expenses through 2036.
- Opportunity: Certified chilled ready-to-heat meals, shelf-stable protein pouches, and halal-certified plant-based meat alternatives are expected to capture time-pressed urban households through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Demographic expansion across metropolitan Europe, North America, the Middle East, and Southeast Asia is converting halal certification from a niche ethnic specialty into a baseline retail procurement requirement. Both observant Muslim shoppers and non-Muslim ethical buyers select certified poultry and beef because accredited slaughter audits mandate strict pre-slaughter animal health checks and full blood drainage. Global consumer spending on halal food and beverage products surpassed USD 1.43 trillion across retail and hospitality channels in the May 2025 State of the Global Islamic Economy report. Processors pairing halal verification with certified organic meat claims win premium shelf space when they provide uninterrupted abattoir lot traceability.
Risk Assessment of the Halal Food Market: Operational and Formulation Friction
Lack of universal mutual recognition among national halal accreditation bodies creates recurring compliance bottlenecks for cross-border food exporters. An abattoir exporting poultry and processed foods to Malaysia, Saudi Arabia, Indonesia, and the European Union must host separate on-site audits regarding mechanical stunning parameters, slaughter line speeds, and alcohol-free flavor solvents. Dedicated reefers, segregated port cold rooms, and duplicate certification audits added 14.8% to landed export logistics costs in July 2025 International Islamic Food Processing Association benchmarking. Raw-material vetting mirrors the strict audit protocols seen in certified halal cosmetics, causing smaller regional meat packers to hold back on export expansion.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Time-pressed urban families are shifting away from multi-hour traditional stews toward certified convenience entrees, marinated air-fryer cuts, and protein-fortified snacks. Food manufacturers capture higher gross margins by launching retort-sterilized curries, shelf-stable canned meat packs, and fortified plant-based meat patties that carry verified halal seals on the front label. New product certification applications for frozen ready meals, plant-protein nuggets, and precision-fermented flavorings rose 22% in September 2025 Islamic Food and Nutrition Council of America records. Bioreactor developers investigating cultivated meat production are also consulting Islamic jurists early to establish stem-cell harvesting and serum-free media compliance.
Halal Food Market by Country (2026 to 2036)
Among the six profiled economies, the United States leads expansion at an 8.3% CAGR through 2036, whereas Canada advances at a more gradual 5.4% CAGR. National growth trajectories depend on whether local demand is driven by domestic supermarket aisle expansion, Gulf tourism hospitality, or government-supervised export abattoir programs.
Table 7: Country CAGR and Primary Growth Levers for the Halal Food Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| USA | 8.3% | Mainstream supermarket chilled bay rollouts, university dining halls, and QR-verified frozen entrees |
| Switzerland | 7.6% | High-value Gulf tourism hospitality in Geneva and Zurich alongside certified alpine dairy and confectionery exports |
| Australia | 7.1% | Government-supervised red-meat export abattoir program (AGHMS) serving Southeast Asian and Middle Eastern buyers |
| Brazil | 6.5% | High-capacity automated halal broiler slaughterhouses and cost-competitive grain-fed poultry export contracts |
| UK | 6.0% | Supermarket private-label chilled halal ranges and high-street quick-service restaurant chains |
| Canada | 5.4% | CFIA-enforced certification labeling transparency and expanding metropolitan grocery retail in Ontario and Quebec |
Source: Future Market Insights analysis
USA Halal Food Market Outlook (2026 to 2036)
Affluent suburban household grocery spending, university campus dining mandates, and national club-store distribution propel the United States halal food market without relying on overseas meat exports. In the USA, demand for halal food is predicted to advance at 8.3% CAGR through 2036, supported by national retail chains placing certified grass-fed beef, deli turkey, and frozen saffron-rice entrees into standard supermarket aisles. Steady domestic specialty poultry and beef processing investment across Midwest packing corridors was documented in October 2026 USDA Economic Research Service livestock trade data. Because multiple regional certifiers operate across states, American brands print scannable batch QR codes on film lids to reassure shoppers.
Key takeaway: Club-store and supermarket aisle rollouts alongside campus dining contracts propel the USA to a leading 8.3% CAGR through 2036.
Switzerland Halal Food Market Outlook (2026 to 2036)
Federal animal protection law in Switzerland prohibits domestic slaughter without pre-slaughter stunning, splitting the market between imported fresh halal meats and domestically manufactured halal dairy, infant formula, and confectionery. The Switzerland halal food sector is projected to record 7.6% CAGR during the assessment period, driven by five-star Gulf tourism catering in Geneva, Zurich, and Interlaken alongside global export qualification of Swiss chocolates and milk powders. Certified alpine dairy and artisan chocolate lines qualified for Middle Eastern and European hospitality buyers increased 9.4% in November 2025 Swiss Halal Certification Organization records. High import tariff quotas on chilled beef require Swiss hotel caterers to manage bonded cold-chain deliveries carefully.
Key takeaway: Five-star Gulf tourism hospitality and export-certified alpine dairy and chocolate lines keep Switzerland growing at a 7.6% CAGR through 2036.
Australia Halal Food Market Outlook (2026 to 2036)
Co-regulation between the federal government and Islamic certifying bodies under the Australian Government Authorised Halal Program (AGAHP) gives Australian red-meat exporters direct customs clearance into strict Asian and Middle Eastern ports. Sales of halal food in Australia are forecast to expand at 7.1% CAGR through 2036, underpinned by chilled vacuum-packed lamb and grass-fed beef shipments to Indonesia, Malaysia, and the Gulf states alongside multicultural dining in Sydney and Melbourne. Certified halal sheepmeat and beef shipments rose 8.2% year-on-year in December 2025 Meat & Livestock Australia export records. Long inland road-train distances to coastal container terminals still inflate refrigerated freight bills, prompting packers to automate portside blast-chilling hubs.
Key takeaway: Government-backed AGAHP abattoir oversight and chilled red-meat exports to Southeast Asia and MENA anchor Australia's 7.1% CAGR through 2036.
Brazil Halal Food Market Outlook (2026 to 2036)
Dedicated export slaughterhouses across Parana, Santa Catarina, and Rio Grande do Sul make Brazil the world's largest industrial supplier of halal poultry and beef despite a small domestic Muslim population. The halal food market in Brazil is anticipated to grow at 6.5% CAGR between 2026 and 2036, propelled by integrated soybean-and-corn feed economics and high-speed automated broiler lines. Annual halal-certified poultry exports surpassed 2.18 million metric tons across Gulf and North African importers in January 2026 Brazilian Animal Protein Association (ABPA) statistics. Currency swings and Red Sea container rerouting still create freight cost volatility, pushing Brazilian packers into multi-year supply agreements with Gulf food-security agencies.
Key takeaway: Integrated feed-grain economics and high-speed export broiler abattoirs sustain Brazil's 6.5% CAGR from 2026 to 2036.
UK Halal Food Market Outlook (2026 to 2036)
Major British supermarket banners and high-street fried-chicken and burger franchises treat halal poultry as a core volume line across London, Birmingham, Manchester, and Bradford. By 2036, the UK is projected to grow at 6.0% CAGR, facilitated by dual-certified chilled poultry aisles and second- and third-generation British Muslim consumers demanding gourmet chilled ready meals. Audited UK foodservice and retail private-label product approvals rose 10.3% in February 2026 Halal Food Authority tracking. Debates between stunned and non-stunned certification boards still divide retail buyers, compelling British processors to run clearly segregated batch schedules with explicit front-of-pack stunning disclosures.
Key takeaway: Private-label supermarket chilled bays and urban quick-service poultry chains drive the UK's 6.0% CAGR through 2036.
Canada Halal Food Market Outlook (2026 to 2036)
Rapid skilled-immigrant household formation in the Greater Toronto Area, Montreal, and Calgary pairs with strict federal truth-in-labeling enforcement to shape Canadian halal grocery retail. Halal food adoption across Canada is anticipated to register 5.4% CAGR during the forecast period, supported by national discount grocers expanding frozen halal samosas, marinated chicken breasts, and deli meats. The Canadian Food Inspection Agency updated its national food labeling compliance directory in May 2026 to verify third-party religious certification bodies on domestic and imported meat packages. Long winter highway hauls between Ontario abattoirs and western provinces still raise refrigerated trucking rates, encouraging regional grocers to partner with provincially inspected halal meat plants.
Key takeaway: Metropolitan immigrant grocery demand and strict CFIA certifier-labeling rules keep Canada expanding at a 5.4% CAGR through 2036.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the halal food market?
Nestlé S.A., Cargill, Incorporated, BRF S.A., Al Islami Foods, Midamar Corporation, Kawan Food Berhad, Saffron Road, and Prima Agri-Products Sdn Bhd are the notable companies active in the halal food market.
Retail grocery chains and hospitality buyers source certified products from three distinct supplier groups: global food and agricultural conglomerates operating dedicated halal factories, export-scale poultry and beef slaughterhouses, and frozen convenience meal brands. Nestlé S.A. and Cargill, Incorporated supply certified dairy, culinary seasonings, infant nutrition, edible oils, and functional texturizers across dozens of countries. BRF S.A. (including its Sadia Halal unit), Al Islami Foods, and Midamar Corporation anchor poultry and beef slaughter, cold-chain distribution, and foodservice supply. Kawan Food Berhad, Saffron Road, and Prima Agri-Products Sdn Bhd focus on frozen flatbreads, clean-label chilled entrees, and processed meat products.
- Multinational Halal Food & Ingredient Platforms: Nestlé S.A. and Cargill, Incorporated operate globally audited halal factories for culinary, dairy, and industrial ingredient lines.
- Industrial Halal Meat & Poultry Leaders: BRF S.A., Al Islami Foods, and Midamar Corporation manage accredited abattoirs and international cold-chain meat distribution.
- Frozen Convenience & Clean-Label Specialists: Kawan Food Berhad, Saffron Road, and Prima Agri-Products Sdn Bhd formulate certified frozen meals, parathas, and value-added proteins.
Competitive Benchmarking: Halal Food Market
Table 8: Competitive Benchmarking for the Halal Food Market (qualitative capability ratings), 2026
| Company | Certified Product Breadth | Multi-Agency Accreditation Depth | Cold-Chain & Retail Access | Geographic Reach |
|---|---|---|---|---|
| Nestlé S.A. | High | High | High | High |
| Cargill, Incorporated | High | High | High | High |
| BRF S.A. | High | High | High | High |
| Al Islami Foods | High | High | High | Medium |
| Midamar Corporation | High | High | Medium | Medium |
| Kawan Food Berhad | Medium | High | High | High |
| Saffron Road | Medium | Medium | High | Medium |
| Prima Agri-Products Sdn Bhd | Medium | High | Medium | Medium |
Scoring basis: Matrix evaluations compare documented supplier credentials across four operational dimensions. Certified Product Breadth contrasts multi-category protein, dairy, and pantry portfolios against focused frozen bakery or meal lines. Multi-Agency Accreditation Depth tracks concurrent JAKIM, MUI, SFDA, and SMIIC/IFANCA approvals, while Cold-Chain & Retail Access and Geographic Reach measure supermarket bay placement and cross-border export coverage.
Key Developments in the Halal Food Market
- Six new antibiotic-free, IFANCA-certified frozen halal beef and chicken entree skus were rolled out across North American retail grocers by Midamar Corporation in January 2026.
- Cargill, Incorporated introduced a dedicated portfolio of JAKIM- and SMIIC-compliant plant-based emulsifiers and modified food starches in October 2025 for Southeast Asian and Middle Eastern bakery and dairy processors.
- An automated halal broiler cut-up and individual-quick-freezing line in Parana, Brazil, was commissioned by BRF S.A. in July 2025 to expand poultry shipments to Gulf Cooperation Council retail accounts.
Key Players in the Halal Food Market
Multinational Food and Ingredient Conglomerates
- Nestlé S.A.
- Cargill, Incorporated
Industrial Halal Poultry and Meat Processors
- BRF S.A.
- Al Islami Foods
- Midamar Corporation
Certified Frozen Meal and Value-Added Food Specialists
- Kawan Food Berhad
- Saffron Road
- Prima Agri-Products Sdn Bhd
Halal Food Market - Report Scope
According to FMI, market estimates capture commercially packaged and certified halal food and beverage products across retail, hospitality, and industrial food processing channels, leaving uncertified livestock and non-food halal pharmaceuticals outside scope.
Table 9: Report Scope for the Halal Food Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type / Grade; Processing State; End-Use Application; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial revenue from certified halal-compliant food and beverage products across red meat, poultry, processed foods, dairy, and culinary ingredients audited and certified by recognized Islamic certification bodies. Excludes non-certified mainstream retail food, certified kosher-only items without halal status, and unorganized wet-market livestock trade. Category Allocation Note: Processing states and commercial grades reflect accredited slaughterhouse, cold-chain transport, and packaged food manufacturing auditing tiers. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA, Switzerland, Australia, Brazil, UK, Canada, and additional countries in the full report |
| Key Companies Covered | Nestlé S.A., Cargill, Incorporated, BRF S.A., Al Islami Foods, Midamar Corporation, Kawan Food Berhad, Saffron Road, Prima Agri-Products Sdn Bhd |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Halal Food Market - Research Methodology
Table 10: Research Methodology for the Halal Food Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with halal certification auditors, export abattoir operations directors, retail supermarket category buyers, and food formulation technologists across North America, Europe, Latin America, Middle East, and Asia-Pacific. |
| Secondary Research | Secondary research evaluated federal agricultural export registries (DAFF, USDA ERS, CFIA), OIC/SMIIC and JAKIM certification bulletins, national meat association trade statistics, and corporate annual reports. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 assessment period were developed using top-down and bottom-up models linking certified slaughter tonnage, supermarket shelf allocation, and institutional catering volumes. |
| Data Triangulation and Validation | Estimates were cross-checked against accredited halal export certificates, bonded cold-chain shipping manifests, and company segment disclosures to ensure accuracy without double counting uncertified commodity meats. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's Islamic economy econometric model, calibrating evaluated national growth rates against the 6.8% global baseline through verified Muslim demographic expansion, halal food import audit protocols, and supermarket halal certified door shelf-space. |
| Operational Benchmark Traceability | Operational benchmarks (certified poultry and red meat export volume, abattoir certification audit costs, and dedicated packaging line sanitation turnovers) represent modeled estimates synthesized from Australian DAFF halal red meat data, Canadian CFIA labeling portals, USDA ERS trade tables, and commercial halal agency filings. |
Halal Food Market by Segments
Halal Food Market segmented by Product Type / Grade:
- Standard Commercial Grade
- Organic & Clean-Label Variant
- Premium Specialty Formulation
Halal Food Market segmented by Processing State:
- Fresh / Ambient Packaged
- Frozen & Chilled
- Dehydrated & Dry Packaged
Halal Food Market segmented by End-Use Application:
- Direct Retail Consumer Consumption
- Food Service & Hospitality
- Commercial Food Manufacturing Plants
Halal Food Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- United Kingdom
- Germany
- Switzerland
- France
- Italy
- Spain
- Benelux
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- Saudi Arabia
- UAE
- South Africa
- Turkiye
Research Sources and Bibliography
- [1] Australian Department of Agriculture, Fisheries and Forestry. (2025, February 11). Exporting halal red meat and red meat products from Australia: AGAHP regulatory requirements. Australian Government Department of Agriculture, Fisheries and Forestry.
- [2] Canadian Food Inspection Agency. (2025, May 14). Method of production claims on food labels: Halal claim certification and labeling verification. Government of Canada CFIA Food Labelling.
- [3] Halal Development Corporation (HDC). (2025, March 18). Global halal industry master plan: Commercial emulsifier, enzyme, and gelatin replacement guidelines. HDC Kuala Lumpur Technical Bulletins.
- [4] Standards and Metrology Institute for Islamic Countries (SMIIC). (2025, February 20). Annual halal food trade, modified-atmosphere meat shipping, and OIC standards bulletin. SMIIC Istanbul Publications.
- [5] Islamic Services of America (ISA). (2025, October 16). North American halal retail grocery trends and mainstream supermarket audit survey. ISA Cedar Rapids Industry Reports.
- [6] DinarStandard. (2025, May 22). State of the global Islamic economy report 2025: Halal food and beverage expenditure benchmarks. DinarStandard Dubai Research.
- [7] International Islamic Food Processing Association (IIFPA). (2025, July 19). Supply chain segregation, dedicated reefer logistics, and multi-agency certification cost study. IIFPA Agribusiness Series, 14(2), 65-79.
- [8] Islamic Food and Nutrition Council of America (IFANCA). (2025, September 25). Modern food technology, ready-meal certification, and alternative protein halal assurance. IFANCA Park Ridge Technical Review.
- [9] U.S. Department of Agriculture, Economic Research Service. (2026, October 07). Livestock and meat international trade data: Specialty poultry and beef processing trends. USDA Economic Research Service Livestock Data.
- [10] Swiss Halal Certification Organization. (2025, November 14). Annual certification statistics for Swiss dairy, confectionery, and hospitality suppliers. Halal Certification Basel Reports.
- [11] Meat & Livestock Australia (MLA). (2025, December 18). Global market snapshot: Halal beef and sheepmeat export performance across Southeast Asia and MENA. MLA Sydney Trade Insights.
- [12] Brazilian Animal Protein Association (ABPA). (2026, January 19). Annual poultry and beef export report: Halal slaughterhouse shipments and Middle East trade. ABPA Sao Paulo Statistical Yearbook.
- [13] Halal Food Authority (HFA). (2026, February 12). UK commercial halal retail private-label and quick-service dining audit survey 2026. HFA London Regulatory Publications.
- [14] Canadian Food Inspection Agency. (2026, May 05). Labelling, standards of identity, and grades: Religious dietary claim compliance directory. CFIA Food Labels and Standards Portal.
- [15] Midamar Corporation. (2026, January 20). Expansion of antibiotic-free IFANCA-certified frozen halal beef and poultry entrees across North American grocers. Midamar Corporate Press Room.
- [16] Cargill, Incorporated. (2025, October 23). Launch of JAKIM- and SMIIC-certified plant-based emulsifiers and specialty food starches. Cargill Food Ingredients News.
- [17] BRF S.A. (2025, July 15). Commissioning of automated halal broiler cut-up and IQF freezing line in Parana for Gulf export markets. BRF Investor Relations.
- [18] Nestlé S.A. (2025, March 24). Expansion of dedicated halal culinary seasoning and dairy production lines in Malaysia and Indonesia. Nestlé Corporate Announcements.
- [19] Al Islami Foods. (2025, November 08). Introduction of blockchain QR-traceable chilled and frozen poultry packs across UAE and Saudi hypermarkets. Al Islami Dubai Press Releases.
- [20] Kawan Food Berhad. (2026, February 17). Commissioning of high-speed automated frozen halal flatbread and dim sum line in Pulau Indah, Malaysia. Kawan Food Bursa Filings.
- [21] Saffron Road (American Halal Company, Inc.). (2025, August 14). Nationwide rollout of clean-label protein-fortified halal simmer sauces and artisan bowls. Saffron Road Stamford News.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the halal food market in 2026 and what is forecast for 2036?
- Which multicultural retail and clean-slaughter verification pressures support demand for halal food?
- Why does Standard Commercial Grade lead the product type / grade category?
- Why does Fresh / Ambient Packaged command the largest processing state share globally?
- How do growth rates differ across the USA, Switzerland, Australia, Brazil, the UK, and Canada?
- Which leading meat packers, ingredient suppliers, and frozen meal brands supply the market today?
- What limits cross-border export qualification or supplier switching in the halal food market?
- What should retail and foodservice buyers evaluate before approving a certified halal supplier?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type / Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type / Grade, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type / Grade, 2026 to 2036
- Standard Commercial Grade
- Organic & Clean-Label Variant
- Premium Specialty Formulation
- Y-o-Y Growth Trend Analysis By Product Type / Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type / Grade, 2026 to 2036
- Global Market Analysis and Forecast, By Processing State, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Processing State, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Processing State, 2026 to 2036
- Fresh / Ambient Packaged
- Frozen & Chilled
- Dehydrated & Dry Packaged
- Y-o-Y Growth Trend Analysis By Processing State, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing State, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Application, 2026 to 2036
- Direct Retail Consumer Consumption
- Food Service & Hospitality
- Commercial Food Manufacturing Plants
- Y-o-Y Growth Trend Analysis By End-Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United Kingdom
- Germany
- Switzerland
- France
- Italy
- Spain
- Benelux
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- Saudi Arabia
- UAE
- South Africa
- Turkiye
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Nestlé S.A.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Cargill, Incorporated
- BRF S.A.
- Al Islami Foods
- Midamar Corporation
- Kawan Food Berhad
- Saffron Road
- Prima Agri-Products Sdn Bhd
- Nestlé S.A.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type / Grade
- Figure 6: Global Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Processing State
- Figure 9: Global Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-Use Application
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Product Type / Grade
- Figure 26: North America Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Processing State
- Figure 29: North America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by End-Use Application
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Product Type / Grade
- Figure 36: Latin America Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Processing State
- Figure 39: Latin America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by End-Use Application
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Product Type / Grade
- Figure 46: Western Europe Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Processing State
- Figure 49: Western Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by End-Use Application
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Product Type / Grade
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Processing State
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by End-Use Application
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Product Type / Grade
- Figure 66: East Asia Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Processing State
- Figure 69: East Asia Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by End-Use Application
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Product Type / Grade
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Processing State
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by End-Use Application
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Product Type / Grade
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Processing State
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by End-Use Application
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the Halal Food Market expected to be in 2026?
Global halal food market valuation is estimated to reach USD 1.6 billion in 2026, rising from USD 1.5 billion in 2025. The market is projected to expand further and reach USD 3.1 billion by 2036 as mainstream supermarkets widen dedicated halal chilled bays.
What CAGR is forecast for the Halal Food Market through 2036?
As per FMI, the halal food market is projected to grow at a 6.8% CAGR from 2026 to 2036. Growth is supported by automated export abattoirs, QR-code lot traceability, and expanding multicultural retail grocery demand.
Which product type / grade segment holds a notable halal food demand share in 2026?
Standard Commercial Grade is projected to hold 53.9% of product type / grade demand in 2026. The segment benefits from high-speed ritual slaughter throughput, competitive unit pricing, and microbial-rennet dairy and pantry standardization.
Which end-use application segment holds a notable halal food share in 2026?
Direct Retail Consumer Consumption is estimated to account for 44.9% of end-use application demand in 2026. Demand is supported by private-label hypermarket ranges, clear front-of-pack certification seals, and home meal preparation.
Which country has a notable halal food expansion outlook during the forecast period?
FMI finds that the USA is projected to expand at an 8.3% CAGR during the 2026 to 2036 assessment period. Growth is supported by club-store and supermarket aisle expansion alongside university and healthcare halal dining programs.
Which companies are active in the Halal Food Market during 2026?
Notable active companies include Nestlé S.A., Cargill, Incorporated, BRF S.A., Al Islami Foods, Midamar Corporation, Kawan Food Berhad, Saffron Road, and Prima Agri-Products Sdn Bhd. These companies focus on multi-agency certification, segregated cold-chain logistics, and convenience ready meals.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
