
- Market Size (2026)
- USD 198.0 Bn
- Forecast (2036)
- USD 389.5 Bn
- CAGR (2026 to 2036)
- 7.0%
How big is Fortified Foods Market in 2026?
With a valuation of USD 185.0 billion in 2025 and moving to USD 198.0 billion in 2026, the fortified foods market is positioned to attain USD 389.5 billion by 2036, exhibiting a CAGR of 7.0%.
The global fortified foods market was valued at USD 185.0 billion in 2025 and is estimated to reach USD 198.0 billion in 2026. The market is projected to reach USD 389.5 billion by 2036, expanding at a compound annual growth rate (CAGR) of 7.0% between 2026 and 2036. Fortified dairy and plant milks are anticipated to hold 36.5% of 2026 base food matrix demand, given that homogenized dairy and oat beverage emulsions carry fat-soluble vitamin D3, vitamin A palmitate and tricalcium phosphate without sediment settling. FMI survey and formulation tracking reflects that product demand is shifting from voluntary marketing claims toward statutory public-health enrichment and multi-nutrient daily meal replacements. Demand for micronutrient-enriched staples is supported by global deficiency intervention programs, with the World Health Organization reporting in September 2026 that iron, folate and vitamin A deficiencies remain major global causes of anemia [1]. That finished-food value creation separates the broader sector from synthetic folic acid fortificants advancing at a 4.6% CAGR, since bulk vitamin raw materials face price competition while branded dairy, cereal and clinical beverages capture retail margin premiums. Global food groups are acquiring high-growth functional brands to capture that consumer shift, as Danone completed its acquisition of nutritionally complete food company Huel in September 2026 to expand its micronutrient-fortified meal portfolio [2]. Dairy processors and cereal makers retain supermarket shelf space when microencapsulated mineral blends eliminate metallic off-flavors, and brands verifying bioavailability across everyday diets will lead volume growth through 2036.
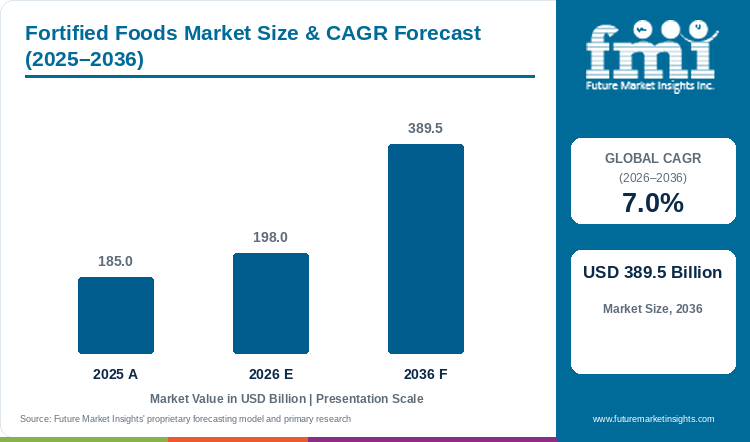
Key Market Trends & Insights
- By base food matrix: Fortified Dairy and Plant Milks are projected to hold an estimated 36.5% share in 2026 since daily household milk and plant beverage consumption ensures high micronutrient compliance.
- By micronutrient fortificant: Vitamins A D E and B-Complex are anticipated to represent 44.0% in 2026 as national flour, oil and dairy laws mandate folic acid, riboflavin and vitamin D enrichment.
- By target cohort: General Adults and Health Enthusiasts are expected to account for 58.0% in 2026 given that working adults steadily substitute fortified yogurts, bars, and cereals for standalone pills.
- By fortification technology: Dry Premix Blending is forecast to secure 47.5% in 2026 owing to low-cost ribbon-blender integration into flour mills, cereal extruders, and powdered beverage plants.
- By distribution channel: Supermarkets and Hypermarkets are estimated to command 53.5% in 2026 through high-turn center-store cereal, cooking oil, and chilled dairy merchandising.
Regional Highlights
- Top national expansion: India leads national growth projections at an 8.7% CAGR through 2036 under the government's INR 17,082 crore universal fortified rice mandate and FSSAI +F dairy and edible oil scaling.
- Broader country progression: Brazil tracks at an 8.2% CAGR ahead of Mexico at 7.8% and the United States at 7.3%, while the United Kingdom advances at a 5.9% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Fortified Foods Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 185.0 billion |
| Estimated Market Size in 2026 | USD 198.0 billion |
| Projected Market Size by 2036 | USD 389.5 billion |
| CAGR, 2026 to 2036 | 7.0% |
| Added Revenue, 2026 to 2036 | USD 191.5 billion |
Large-scale staple food processors and multinational CPG brands rely on standardized vitamin and mineral dosing to close population-wide nutritional deficits without requiring consumers to alter their eating habits. Policy and value-chain research published in Frontiers in Nutrition in February 2026 documented that micronutrient deficiencies affect more than 2 billion people and confirmed that statutory industrial food fortification across cereal and dairy value chains delivers high benefit-to-cost public health returns [3]. Accordingly, flour mills, edible oil refiners and dairy co-packers integrate automated micro-dosers directly into continuous processing lines.
Fortified Food Tonnage & Premix Overages Sizing
Table 2: Fortified Food Volume and Premix Dosing Sizing for the Fortified Foods Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 185.0 | 198.0 | 389.5 |
| Commercially fortified staple & packaged food volume (million MT) | 295.0 to 315.0 | 312.0 to 334.0 | 540.0 to 585.0 |
| Active vitamin & mineral premix consumption (thousand MT) | 410.0 to 445.0 | 438.0 to 475.0 | 790.0 to 860.0 |
| Average micronutrient fortification cost per metric ton of food (USD) | 1.8 to 4.5 | 1.9 to 4.7 | 2.4 to 5.8 |
Operational note: Premix inclusion ranges account for 10% to 35% thermal and oxidative vitamin overages required to guarantee label-claim potency at the end of ambient retail shelf life.
National governments and multilateral nutrition alliances are tightening compliance audits on commercial mills and food processors to ensure fortified staples actually reach retail shelves at statutory nutrient levels. As per the Global Alliance for Improved Nutrition in its March 2025 Paris Nutrition for Growth assessment, global large-scale fortification programs target reaching over 1.2 billion consumers with adequately fortified staples equipped with micronutrient fortifying agents [4]. Stricter regulatory enforcement compels mid-sized grain and oil processors to replace manual scoop dosing with loss-in-weight gravimetric feeders.
Caloric Affordability & Household Fortified Spend
Table 3: Global Nutritional Reach and Per Capita Fortified Food Indicators (USD and operational metrics), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global population reached by fortified staples (billion) | 4.6 | 4.8 | 6.4 |
| Annual fortified food expenditure per consumer reached (USD) | 40.2 | 41.3 | 60.9 |
| Countries enforcing mandatory grain or salt/oil fortification | 142 countries | 145 countries | 165+ countries |
| Encapsulated & chelated bioavailable fortificant share (%) | 34.0% to 38.0% | 36.0% to 40.0% | 52.0% to 57.0% |
Table 4: Matrix Allocation and Public Mandate Benchmarks for the Fortified Foods Market (USD billion and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 198.0 billion | 2026 global revenue baseline |
| Fortified Dairy & Plant Milks revenue, 2026 | USD 72.3 billion | 36.5% base food matrix allocation |
| Vitamins A, D, E & B-Complex matrix revenue, 2026 | USD 87.1 billion | 44.0% micronutrient fortificant allocation |
| Supermarkets & Hypermarkets channel revenue, 2026 | USD 105.9 billion | 53.5% distribution channel allocation |
Macroeconomic income gains across emerging markets directly govern how quickly low-income households transition from unbranded loose commodities to packaged, micronutrient-fortified staples. As per the USDA Economic Research Service in its August 2026 Global Food Assessment covering 83 countries, the share of the assessed population unable to afford 2,100 calories per day is projected to drop from 19.5% (884.4 million people) in 2026 to 11.4% by 2036 [5]. Higher household food purchasing power accelerates commercial adoption of packaged milk, enriched flour, and cooking oils formulated with chelated mineral fortification.
Analyst Perspective
"Food manufacturers no longer treat vitamin and mineral enrichment as a simple label compliance box; they engineer encapsulated multi-nutrient matrices that survive high-heat UHT pasteurization and extrusion without metallic aftertastes. Suppliers that solve iron and omega-3 oxidation inside plant milks and everyday grains will capture long-term CPG reformulation contracts."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the fortified foods market segmented?
The fortified foods market is segmented by base food matrix, micronutrient fortificant, target cohort, fortification technology, and distribution channel. In 2026, Fortified Dairy and Plant Milks are projected at 36.5%, Vitamins A D E and B-Complex at 44.0%, General Adults and Health Enthusiasts at 58.0%, Dry Premix Blending at 47.5%, and Supermarkets and Hypermarkets at 53.5%.
By base food matrix: Fortified Dairy and Plant Milks, Fortified Breakfast Cereals and Grains, Fortified Infant Nutrition and Baby Food, Fortified Edible Oils and Fats, and Fortified Beverages.
By micronutrient fortificant: Vitamins A D E and B-Complex, Minerals Calcium Iron Zinc and Iodine, Omega-3 Fatty Acids and Probiotics, and Protein and Amino Acid Isolates.
By target cohort: General Adults and Health Enthusiasts, Infants Toddlers and Children, Pregnant and Lactating Women, and Geriatric and Senior Nutrition.
By fortification technology: Dry Premix Blending, Microencapsulation and Spray Drying, Liquid Emulsion Dosing, and Extrusion and Kernel Reconstitution.
By distribution channel: Supermarkets and Hypermarkets, Pharmacies and Clinical Dispensaries, Institutional and Public Nutrition Programs, and Direct-to-Consumer and Online Retail.
Why do Fortified Dairy and Plant Milks lead the base food matrix category?
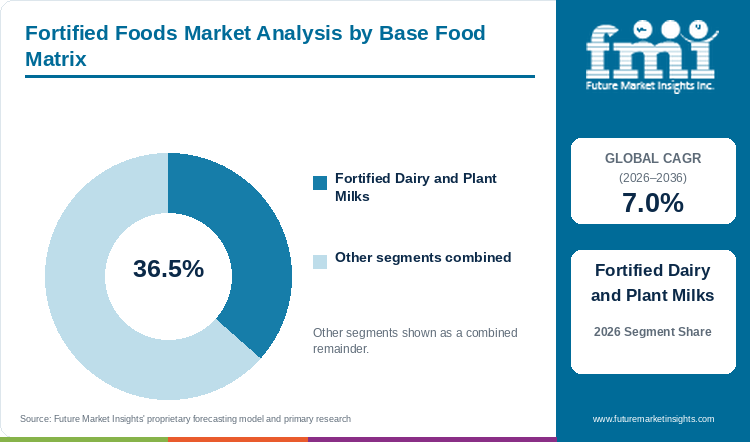
Fortified Dairy and Plant Milks hold an estimated 36.5% of base food matrix demand in 2026, anchored by mandatory milk vitamin D standards and calcium-fortified plant beverage adoption.
Table 5: Base Food Matrix Share for the Fortified Foods Market (percentage share), 2026
| Base Food Matrix | Share (2026) |
|---|---|
| Fortified Dairy and Plant Milks | 36.5% |
| Other Segments Combined | 63.5%* |
| Total | 100.0% |
*Note: Remaining base food matrix categories account for the balance of 2026 global fortified foods demand.
Table 6: Base Food Matrix Leadership and Market Growth for the Fortified Foods Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.0% |
| Leading Segment | Fortified Dairy and Plant Milks |
Liquid dairy milk, fermented yogurts and plant-based oat or almond beverages serve as the premier commercial vehicle for calcium, vitamin D3 and vitamin B12 delivery. Dairy and beverage formulators apply calibrated vitamin nutrition emulsions during homogenization so fat-soluble vitamins remain suspended, although mineral sedimentation in low-viscosity plant milks requires hydrocolloid stabilization.
- Within the base food matrix segment, Fortified Dairy and Plant Milks are projected to account for a leading 36.5% share in 2026, driven by mandatory milk vitamin D standards and plant-beverage nutritional parity claims.
- Clinical meta-analysis findings published in Nutrients in November 2025 confirmed that consuming vitamin D-fortified dairy products significantly raises serum 25-hydroxyvitamin D concentrations compared with unfortified controls [6].
What sustains Vitamins A D E and B-Complex leadership in fortificants?
Vitamins A D E and B-Complex represent an estimated 44.0% of the micronutrient fortificant category in 2026, supported by statutory folic acid, riboflavin, and vitamin A and D enrichment laws.
Fat-soluble vitamins A, D and E paired with water-soluble B-complex vitamins such as folic acid, riboflavin and vitamin B12 anchor global fortification demand. Over 90 countries mandate their inclusion in milled wheat flour, maize meal and liquid milk. Efficacy research published in Nutrients in December 2024 demonstrated that vitamin D3 food fortification offers strong population serum 25(OH)D improvements and public-health returns at minimal per-serving ingredient cost [7]. Formulators must still apply antioxidant tocopherols and single-serve micronutrient powders to prevent UV and thermal vitamin degradation during baking.
- In 2026, Vitamins A D E and B-Complex are anticipated to capture 44.0% of global micronutrient fortificant demand, reflecting statutory grain and dairy enrichment laws.
- Over the 2026 to 2036 window, demand for methylated folate (5-MTHF) and vegan algal vitamin D3 will expand as clean-label cereal and beverage brands upgrade from standard synthetic vitamers.
How do General Adults and Health Enthusiasts lead the target cohort category?
General Adults and Health Enthusiasts account for a projected 58.0% of target cohort demand in 2026, driven by daily consumption of functional cereals, yogurts, and nutritional drinks.
Working-age adults and proactive wellness shoppers represent the largest commercial buyer pool for functional breakfast cereals, protein-and-vitamin-enriched yogurts and immunity-positioned beverages. While pediatric formulas rely on infant nutritional premixes under strict clinical guidelines, adult consumers purchase fortified everyday groceries to combat fatigue, support bone density and avoid pill fatigue.
- By target cohort, General Adults and Health Enthusiasts are estimated to reach 58.0% of total category share in 2026 as everyday functional groceries replace standalone dietary supplements.
- Workplace nutritional screening published in Nutrients in October 2026 across 793 adult employees confirmed that regular vitamin D intake is associated with significantly higher target serum 25(OH)D status while 70.2% of deficient adults remained undiagnosed [8].
Why does Dry Premix Blending lead the fortification technology category?
Dry Premix Blending secures an anticipated 47.5% of fortification technology demand in 2026, supported by economical ribbon-blender dosing across flour mills and cereal plants.
Dry ribbon and paddle blending of free-flowing vitamin-and-mineral premixes with carrier maltodextrin or starch remains the most economical dosing method for wheat flour, breakfast cereals, and powdered milk. Review research published in Frontiers in Sustainable Food Systems in September 2026 examined how bioactive compounds and processed plant by-products fortify staple food matrices while addressing stability and sensory hurdles [9]. Even so, particle-size density mismatches between heavy iron salts and light vitamin powders require careful anti-caking conditioning to prevent batch segregation.
- Operational simplicity and low capital expenditure place Dry Premix Blending on course to hold an estimated 47.5% share of the fortification technology category in 2026.
- Adoption of microencapsulated and spray-dried lipid coatings will grow faster through 2036 as manufacturers mask reactive iron, zinc, and marine omega-3 ingredients in wet dairy and beverage lines.
What gives Supermarkets and Hypermarkets the leading position in distribution?
Supermarkets and Hypermarkets command an estimated 53.5% of distribution channel share in 2026, anchored by high-frequency household grocery replenishment of milk, bread, and cereal.
Mainstream supermarkets and hypermarkets control household replenishment of fortified liquid milk, enriched bread and vitamin-enriched breakfast cereals. Retailers leverage eye-level shelf placement and private-label nutritional callouts to drive weekly basket turns, although rapid growth in direct-to-consumer subscription nutrition powders and pharmacy clinical drinks creates cross-channel competition.
- With a projected 53.5% share of the distribution channel segment in 2026, Supermarkets and Hypermarkets remain the primary commercial outlet for fortified family staples.
- Corporate sales disclosures reinforce this retail channel momentum, with Nestlé reporting 4.0% third-quarter 2026 organic sales growth and 2.8% real internal growth in October 2026 while agreeing to divest its standalone mainstream supplement brands to focus on core food and beverage nutrition [10].
What are the drivers, restraints, and opportunities in the fortified foods market?
In the fortified foods market, statutory staple enrichment laws and adult functional nutrition demand are projected to drive growth, while metallic mineral off-flavors and upper intake ceilings restrain over-dosing and microencapsulated plant-matrix fortificants create new demand avenues.
- Driver: Statutory government mandates requiring iron, folic acid and vitamin A or D enrichment in milled grains, rice and milk generate guaranteed baseline demand.
- Restraint: Organoleptic lipid oxidation, metallic mineral off-flavors, and strict EFSA and FDA tolerable upper intake ceilings restrain aggressive over-fortification in commercial foods.
- Opportunity: Microencapsulating ferric pyrophosphate, algal DHA omega-3s, and heat-stable probiotics into plant-based dairy and extruded rice kernels opens clean-label functional premiums.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
National public-health mandates targeting iron-deficiency anemia and neural tube defects are converting staple grain, rice and edible oil processors into mandatory buyers of micronutrient premixes. When ministries of health enforce statutory enrichment across public food distribution and commercial retail mills, fortification volumes scale independently of discretionary consumer spending. Dietary modeling published in Maternal & Child Nutrition in August 2026 demonstrated that fortifying Indian rice, wheat flour and salt using iron premixes reduces anemia prevalence among women of reproductive age from 52.6% to between 45.1% and 47.6% even under intermediate coverage [11]. Combined with staple mandates, consumer demand for marine and algal omega-3 ingredients in dairy and infant lines further expands processor procurement.
Risk Assessment of the Fortified Foods Market: Operational and Formulation Friction
Sensory defects caused by reactive transition metals and strict regulatory ceilings on cumulative micronutrient intake represent the primary barriers restraining higher fortification levels in commercial foods. Uncoated ferrous sulfate catalyzes lipid peroxidation in cereal grains and turns polyphenol-rich beverages dark, while excessive fat-soluble vitamin overages risk crossing statutory safety thresholds. The European Food Safety Authority documented in its May 2024 Tolerable Upper Intake Level summary report that strict daily upper limits govern preformed vitamin A, vitamin D (100 micrograms/day for adults), iron and folate across fortified foods [12]. Processors must therefore invest in spray-dried nutrient microencapsulation and precision analytical assay testing to avoid regulatory recalls.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Ingredient formulators and food brands can capture superior margins by engineering complementary nutrient pairs that overcome the low bioavailability of plant-based and early-life diets. Non-heme iron and zinc in plant matrices suffer poor intestinal absorption due to phytic acid chelation unless paired with ascorbic acid, phytase enzymes or chelated amino acid complexes. A March 2025 nutritional review in Frontiers in Nutrition confirmed that micronutrient fortification of staple and complementary foods with iron, iodine and vitamins improves health outcomes in the first 1,000 days of life [13]. Combinations of chelated minerals and stabilized vitamin A palmitate in shelf-stable UHT milks and extruded snacks create high-margin retail differentiation.
Fortified Foods Market by Country (2026 to 2036)
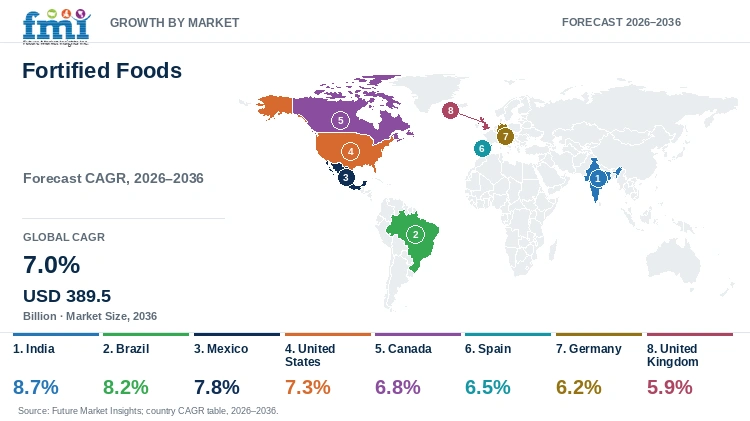
FMI country modeling indicates that India leads fortified foods expansion at an 8.7% CAGR through 2036, while the United Kingdom advances at a 5.9% CAGR. National growth trajectories reflect statutory staple fortification laws, public school and safety-net procurement programs, and retail consumer adoption of vitamin-enriched dairy and plant beverages.
Table 7: Country CAGR and Primary Growth Levers for the Fortified Foods Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| India | 8.7% | INR 17,082 crore universal fortified rice scheme to 2028 and FSSAI +F dairy/oil scaling |
| Brazil | 8.2% | Mandatory ANVISA iron/folic acid flour rules and vitamin-enriched UHT dairy demand |
| Mexico | 7.8% | NOM-247 cereal flour fortification and functional dairy expansion across modern retail |
| United States | 7.3% | FDA enriched grain and corn masa standards plus adult protein-and-vitamin groceries |
| Canada | 6.8% | Health Canada expanded vitamin D fortification in milk, yogurt, and plant beverages |
| Spain | 6.5% | High household penetration of calcium- and omega-3-fortified UHT milk bricks |
| Germany | 6.2% | Vitamin B12- and calcium-fortified oat/soy beverages and iodized bakery salt |
| United Kingdom | 5.9% | Mandatory folic acid fortification of non-wholemeal wheat flour from December 2026 |
Source: Future Market Insights analysis
India Fortified Foods Market Outlook (2026 to 2036)
Demand for fortified foods in India is projected to expand at a leading 8.7% CAGR between 2026 and 2036, driven by the world's largest statutory rice, edible oil and milk fortification network. What distinguishes India from Western retail-led markets is the union government's direct procurement of extruded Fortified Rice Kernels enriched with iron, folic acid and vitamin B12 combined with FSSAI +F logo adoption by commercial dairy cooperatives. On August 21, 2025, the Press Information Bureau announced that the Indian Government extended the universal supply of fortified rice across all government schemes until December 2028 with a financial outlay of INR 17,082 crore [14]. Humid monsoon storage conditions still require strict moisture packaging for extruded kernels.
Key takeaway: In India, the INR 17,082 crore government fortified rice continuation through 2028 and commercial +F dairy and oil scaling are projected to drive a leading 8.7% CAGR.
Brazil Fortified Foods Market Outlook (2026 to 2036)
Brazil's packaged dairy, grain milling, and functional beverage industries are anticipated to generate an 8.2% CAGR in fortified foods demand through 2036. Brazilian growth outpaces mature North American and European averages because ANVISA RDC 150 mandates iron and folic acid enrichment across all domestic wheat and corn flours while urban shoppers actively purchase calcium-and-vitamin-D-enriched UHT milk and fermented dairy drinks. As per a December 2025 USDA Foreign Agricultural Service Dairy and Products Annual report from Brasilia, Brazil's domestic dairy processing industry channels almost its entire fluid milk and powdered dairy output into domestic retail and institutional nutrition programs [15]. Front-of-pack high-sugar and saturated-fat magnifying-glass warnings compel brands to reformulate sweetened fortified drinks.
Key takeaway: In Brazil, mandatory ANVISA flour fortification and strong urban demand for vitamin-enriched UHT dairy and functional beverages are anticipated to sustain an 8.2% CAGR.
Mexico Fortified Foods Market Outlook (2026 to 2036)
In Mexico, fortified foods sales are forecast to advance at a 7.8% CAGR from 2026 to 2036 across industrial corn masa and wheat flour mills, Liconsa social milk programs and modern supermarket chains. Mexican demand differs from purely voluntary markets because Official Mexican Standard NOM-247-SSA1 requires restoration and fortification of cereal flours with iron, zinc, folic acid and B vitamins while warning-octagon labeling laws push cereal and dairy brands to confirm positive micronutrient density. A USDA Foreign Agricultural Service Exporter Guide for Mexico published in July 2025 confirmed that modern supermarket and club-store formats continue expanding consumer-oriented dairy and enriched grocery lines nationwide [16]. Cold-chain gaps in rural southern states still favor ambient UHT formats.
Key takeaway: In Mexico, statutory NOM-247 flour enrichment and functional UHT dairy expansion across modern retail chains are forecast to support a 7.8% CAGR.
United States Fortified Foods Market Outlook (2026 to 2036)
The United States fortified foods market is estimated to progress at a 7.3% CAGR between 2026 and 2036, anchored by federal enriched grain standards, voluntary corn masa folic acid fortification and widespread vitamin A and D dairy enrichment. Compared with state-subsidized developing markets, American growth is driven by adult consumers trading up to protein- and fiber-fortified breakfast cereals, Greek yogurts and hydration beverages. Regulatory guidance maintained by the U.S. Food and Drug Administration under 21 CFR 172.345 permits folic acid addition at up to 0.7 milligrams per pound of corn masa flour to prevent neural tube defects [17]. Consumer scrutiny of ultra-processed food additives requires clean-label vitamin sourcing.
Key takeaway: In the United States, FDA enriched grain and corn masa standards combined with retail demand for protein-and-vitamin functional foods are estimated to drive a 7.3% CAGR.
Canada Fortified Foods Market Outlook (2026 to 2036)
National demand for fortified foods in Canada is projected to grow at a 6.8% CAGR over the 2026 to 2036 forecast period as processors implement updated federal vitamin D levels and Supplemented Foods regulations. Canada stands out from international peers because high northern latitudes limit winter cutaneous sunlight synthesis, prompting Health Canada to double mandatory vitamin D levels in cow's milk and margarine by December 31, 2025 while permitting matching vitamin D levels in fortified plant-based beverages [18]. Canadian cereal and beverage manufacturers must also comply with strict bilingual Supplemented Food Caution Identifiers when micronutrient doses exceed baseline thresholds.
Key takeaway: In Canada, Health Canada's doubled vitamin D fortification policy for milk, margarine and plant beverages is projected to anchor a 6.8% CAGR through 2036.
Spain Fortified Foods Market Outlook (2026 to 2036)
Spain's fortified foods sector is slated to expand at a 6.5% CAGR from 2026 to 2036, led by high household penetration of calcium-, vitamin D- and omega-3-enriched UHT semi-skimmed milk and pediatric dairy formulas. Spanish consumption patterns differ from northern Europe because domestic shoppers strongly favor ambient UHT functional milk bricks enriched with heart-health and bone-health nutrients sold through Mercadona and Carrefour supermarkets. As per the USDA Foreign Agricultural Service in June 2026, EU27 fluid milk consumption was forecast at 23.1 million metric tons in 2026 as milk alternatives and value-added dairy lines gained share [19]. Lower national birth rates temper infant formula volume growth, shifting brand focus toward senior bone and cardiovascular nutrition.
Key takeaway: In Spain, widespread household consumption of calcium- and omega-3-enriched UHT dairy bricks and senior nutrition lines is slated to sustain a 6.5% CAGR.
Germany Fortified Foods Market Outlook (2026 to 2036)
Sales of fortified foods in Germany are predicted to advance at a 6.2% CAGR between 2026 and 2036, shaped by surging retail conversion toward calcium-, iodine- and vitamin B12-fortified oat and soy milks combined with iodized bakery salt. German regulatory dynamics are more conservative than Anglo-Saxon markets because the German Federal Institute for Risk Assessment (BfR) enforces strict maximum addition recommendations for vitamins and trace minerals in foods. In December 2025, the BfR issued an updated opinion proposing maximum iodine addition levels of 100 micrograms per daily serving in supplements (150 micrograms for pregnant women) and controlled food iodization [20]. Strict organic Bio-label rules prohibiting synthetic vitamin fortification in organic plant drinks remain a local restraint.
Key takeaway: In Germany, rapid retail adoption of vitamin B12- and calcium-fortified plant beverages paired with iodized food standards is predicted to support a 6.2% CAGR.
United Kingdom Fortified Foods Market Outlook (2026 to 2036)
The United Kingdom fortified foods market is expected to register a 5.9% CAGR from 2026 to 2036 as statutory flour enrichment rules take effect combined with supermarket functional cereal and dairy lines. British market growth receives a regulatory boost from the Bread and Flour Regulations amendment requiring mandatory folic acid fortification of non-wholemeal wheat flour from December 2026, as analyzed in Nutrients in May 2026 [21]. UK grocery retailers also actively promote vitamin D-enriched mushrooms, breakfast cereals and yogurts following Scientific Advisory Committee on Nutrition reviews, though ongoing HFSS promotional restrictions force cereal makers to cut sugar while fortifying with fiber and iron.
Key takeaway: In the United Kingdom, mandatory folic acid fortification of non-wholemeal wheat flour effective December 2026 and retail vitamin D initiatives are expected to drive a 5.9% CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the fortified foods market?
Nestlé S.A., Danone S.A., General Mills Inc., Abbott Laboratories, WK Kellogg Co, Unilever PLC, Arla Foods amba, Royal FrieslandCampina N.V., Mondelēz International Inc., and PepsiCo Inc. are the notable companies in the fortified foods market.
Commercial leadership across the fortified foods landscape spans diversified global nutrition and dairy conglomerates, specialized clinical and pediatric nutrition manufacturers and fortified breakfast cereal and snack leaders. Nestlé, Danone and Unilever scale micronutrient-fortified dairy, plant beverages and culinary bouillons with Arla and FrieslandCampina. Abbott anchors clinical and infant nutrition, while General Mills, WK Kellogg and PepsiCo lead enriched cereals and functional snacks with Mondelēz.
- Global Dairy and Multi-Category Fortified Food Leaders: Nestlé, Danone and Unilever manufacture vitamin-and-mineral-fortified dairy, plant beverages and culinary cubes with Arla Foods and FrieslandCampina.
- Clinical, Pediatric and Medical Nutrition Specialists: Abbott Laboratories formulates scientifically validated infant formulas, pediatric growth drinks and geriatric oral nutritional liquids with chelated minerals and HMOs.
- Fortified Breakfast Cereal, Grain and Snack Formulators: General Mills, WK Kellogg and Mondelēz produce iron- and B-vitamin-enriched cereals and snacks. PepsiCo also supplies fortified oats and hydration lines.
Competitive Benchmarking: Fortified Foods Market
Table 8: Competitive Benchmarking for the Fortified Foods Market (qualitative capability ratings), 2026
| Company | Micronutrient Bioavailability R&D | Matrix Diversity | Public-Health & Retail Reach | Geographic Reach |
|---|---|---|---|---|
| Nestlé S.A. | High | High | High | Global presence in 180+ countries; fortified dairy, infant nutrition, and Maggi bouillon |
| Danone S.A. | High | High | High | Global dairy, plant-based Alpro/Silk, medical nutrition, and September 2026 Huel acquisition |
| General Mills Inc. | Medium | High | High | North American and global whole-grain and vitamin-mineral fortified breakfast cereals |
| Abbott Laboratories | High | Medium | High | Global pediatric Similac/PediaSure and adult Ensure clinical nutrition leadership |
| WK Kellogg Co | Medium | Medium | High | North American fortified ready-to-eat cereals; launched fiber/vitamin lines at FNCE 2026 |
| Unilever PLC | High | Medium | High | Global Nutrition and Horlicks/Knorr micronutrient-fortified beverages and culinary cubes |
| Arla Foods amba | High | Medium | High | European, Middle Eastern, and African vitamin D and calcium-enriched dairy and whey ingredients |
| Royal FrieslandCampina N.V. | High | Medium | High | Global dairy cooperative supplying fortified Dutch Lady milk and pediatric ingredients |
| Mondelēz International Inc. | Medium | Medium | High | Global biscuits, Belvita fortified breakfast biscuits, and portion-controlled snack bars |
| PepsiCo Inc. | Medium | High | High | Global Quaker fortified oats, functional hydration beverages, and enriched grain snacks |
Evaluation basis: Micronutrient Bioavailability R&D evaluates published clinical and formulation capability in chelated minerals, microencapsulation and vitamin stability. Matrix Diversity rates breadth across dairy, cereal and beverage formats, while Public-Health & Retail Reach measures distribution across mainstream supermarkets and institutional fortification programs.
Key Developments in the Fortified Foods Market
- Unilever PLC reported third-quarter 2026 underlying sales growth of 5.2% with 2.9% volume growth on October 28, 2026, supported by double-digit emerging-market expansion in Latin America and high-single-digit growth in Asia Pacific Africa [22].
- Abbott Laboratories announced third-quarter 2026 financial results on October 21, 2026 with reported sales growth of 14.5% and comparable sales growth of 7.0%, supported by the U.S. rollout of whole-milk Similac 360 Total Care liquid formula [23].
- WK Kellogg Co unveiled new nutrient-dense fortified cereals featuring fiber, protein and single-digit added sugar at the Food & Nutrition Conference & Expo (FNCE) on October 20, 2026 [24].
Key Players in the Fortified Foods Market
Global Dairy and Multi-Category Fortified Food Leaders
- Nestlé S.A.
- Danone S.A.
- Unilever PLC
- Arla Foods amba
Clinical, Pediatric, and Dairy Ingredient Specialists
- Abbott Laboratories
- Royal FrieslandCampina N.V.
- Fortified Breakfast Cereal, Grain, and Snack Formulators
- General Mills Inc.
Fortified Grain, Oat, and Baked Snack Innovators
- WK Kellogg Co
- Mondelēz International Inc.
Fortified Foods Market - Report Scope
Table 9: Report Scope for the Fortified Foods Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Base Food Matrix; Micronutrient Fortificant; Target Cohort; Fortification Technology; Distribution Channel |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial retail, foodservice, and institutional revenue from packaged foods and beverages deliberately enriched or fortified with vitamins, minerals, omega-3 fatty acids, probiotics, or protein/amino acid isolates. Category Scope Note: Excludes unfortified natural whole foods, standalone dietary supplement pills/capsules, and animal feed premixes. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | India, Brazil, Mexico, United States, Canada, Spain, Germany, United Kingdom, and additional countries in the full report |
| Key Companies Covered | Nestlé S.A., Danone S.A., General Mills Inc., Abbott Laboratories, WK Kellogg Co, Unilever PLC, Arla Foods amba, Royal FrieslandCampina N.V., Mondelēz International Inc., PepsiCo Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Fortified Foods Market - Research Methodology
Table 10: Research Methodology for the Fortified Foods Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with CPG food fortification R&D directors, vitamin-and-mineral premix formulators, dairy cooperative quality managers, and public-nutrition procurement officials to validate overage dosing and encapsulation costs. |
| Secondary Research | Analysis of WHO and FAO micronutrient guidelines, FDA 21 CFR enrichment standards, EFSA upper intake opinions, PIB India fortified rice releases, Health Canada fortification dockets, and corporate filings. |
| Market Sizing and Forecasting | Top-down parent packaged dairy, cereal, and staple grain baselines reconciled against bottom-up fortified food tonnage (312M to 334M MT in 2026) and active premix inclusion rates from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight statutory flour, rice, oil, and milk fortification laws, public safety-net distribution budgets, and retail functional food penetration across eight national markets. |
| Operational Benchmark Traceability | Fortified tonnage, population reach, and matrix allocation indicators in Tables 2, 3, and 4 trace to WHO deficiency registries, GAIN Paris 2025 tracking reports, USDA ERS Global Food Assessment 2026-36, and FSSAI standards. |
| Data Triangulation and Validation | Revenue estimates isolate finished packaged foods and beverages carrying verified added micronutrient levels while strictly excluding standalone vitamin tablets and unfortified bulk commodities. |
Fortified Foods Market by Segments
Fortified Foods Market segmented by Base Food Matrix:
- Fortified Dairy and Plant Milks
- Fortified Breakfast Cereals and Grains
- Fortified Infant Nutrition and Baby Food
- Fortified Edible Oils and Fats
Fortified Foods Market segmented by Micronutrient Fortificant:
- Vitamins A D E and B-Complex
- Minerals Calcium Iron Zinc and Iodine
- Omega-3 Fatty Acids and Probiotics
- Protein and Amino Acid Isolates
Fortified Foods Market segmented by Target Cohort:
- General Adults and Health Enthusiasts
- Infants Toddlers and Children
- Pregnant and Lactating Women
- Geriatric and Senior Nutrition
- Clinical and Sports Recovery Patients
Fortified Foods Market segmented by Fortification Technology:
- Dry Premix Blending
- Microencapsulation and Spray Drying
- Liquid Emulsion Dosing
- Extrusion and Kernel Reconstitution
Fortified Foods Market segmented by Distribution Channel:
- Supermarkets and Hypermarkets
- Pharmacies and Clinical Dispensaries
- Institutional and Public Nutrition Programs
- Direct-to-Consumer and Online Retail
Fortified Foods Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] World Health Organization. (2026, September 17). Micronutrients. . World Health Organization Health Topics.
- [2] Danone S.A. (2026, September 4). Danone Completes Its Acquisition of Huel, Extending Its Portfolio in Functional and Micronutrient-Fortified Nutrition. Danone Corporate Press Releases.
- [3] Osendarp, S., & Mkambula, P. (2026, February 18). The Role of Policy on Fortification in Food Processing and Value Addition Across Staple Matrices. Frontiers in Nutrition, 13, 1765596.
- [4] Global Alliance for Improved Nutrition. (2025, March 28). Nutrition for Growth Paris 2025: Tracking Commitments to Large-Scale Food Fortification. GAIN Policy Publications.
- [5] Zereyesus, Y. A., & Cardell, L. (2026, August 26). Global Food Assessment, 2026-36. . U.S. Department of Agriculture, Economic Research Service Report GFA-37.
- [6] Cashman, K. D., & Kiely, M. (2025, November 29). Is Vitamin D Fortification of Dairy Products Effective for Improving Population 25-Hydroxyvitamin D Status?. Nutrients (PMCID PMC12694000).
- [7] Grant, W. B., Wimalawansa, S. J., Pludowski, P., & Cheng, R. Z. (2024, December 14). The Impact and Efficacy of Vitamin D Fortification. . Nutrients, 16(24), 4322.
- [8] Kmieć, P., & Sworczak, K. (2026, October 31). Vitamin D Supplement Use Is Associated with Better Status. . Nutrients, 18(21), 3611.
- [9] Khalangre, A., Jayarajan, S., & Mirza, A. (2026, September 22). Food fortification using fruit-processing by-products and their derived bioactive compounds: opportunities, challenges, and future perspectives. . Frontiers in Sustainable Food Systems, 10, 1877575.
- [10] Nestlé S.A. (2026, October 22). Third-quarter and nine-month 2026 sales. . Nestlé Global Media Releases.
- [11] Swaminathan, S., & Ghosh, S. (2026, August 24). Quantifying the Potential Impact of Food Fortification on Iron Intake and Anemia Prevalence Under FSSAI Standards. Maternal & Child Nutrition (PMCID PMC13501248).
- [12] European Food Safety Authority. (2024, May 20). Overview on Tolerable Upper Intake Levels as Derived by the Scientific Committee on Food and the EFSA Panel on Nutrition. EFSA Technical Summary Report.
- [13] Saran, R., Kasar, J., Jha, M., Sahu, J. K., Babu, S. S., & Mutreja, A. (2025, March 3). Building blocks of life: improving nutrition and health outcomes through fortification and breastfeeding in the first 1000 days of a child's life. . Frontiers in Nutrition, 12, 1517247 (PMCID PMC11912564).
- [14] Press Information Bureau, Government of India. (2025, August 21). Fortified Rice Scheme Extended to 2028 with Rs 17,082 Crore Government Backing. . Ministry of Consumer Affairs, Food & Public Distribution.
- [15] USDA Foreign Agricultural Service. (2025, December 17). Brazil: Dairy and Products Annual. . U.S. Department of Agriculture GAIN Report BR2025-0042.
- [16] USDA Foreign Agricultural Service. (2025, July 3). Mexico: Exporter Guide Annual. . U.S. Department of Agriculture GAIN Report MX2025-0031.
- [17] U.S. Food and Drug Administration. (2024, June 3). Fortifying Corn Masa Flour Products with Folic Acid. . U.S. Department of Health and Human Services.
- [18] Health Canada. (2025, September 3). Fortified foods: Canada's approach to fortification. . Government of Canada.
- [19] USDA Foreign Agricultural Service. (2026, June 5). European Union: Dairy and Products Semi-annual. . U.S. Department of Agriculture GAIN Report E42026-0043.
- [20] German Federal Institute for Risk Assessment (BfR). (2025, December 19). Update (2025): maximum levels proposed for iodine in foods including food supplements. . Bundesinstitut für Risikobewertung Opinion.
- [21] Wald, N. J., & Morris, J. K. (2026, May 30). Reassessing Mandatory Folic Acid Fortification for Neural Tube Defect Prevention. . Nutrients, 18(11), 1758 (PMCID PMC13259054).
- [22] Unilever PLC. (2026, October 28). Continued strong performance in the third quarter. . Unilever Media Relations.
- [23] Abbott Laboratories. (2026, October 21). Abbott Reports Third-Quarter 2026 Results and Reaffirms Full-Year EPS Guidance. . Abbott MediaRoom.
- [24] WK Kellogg Co. (2026, October 20). WK Kellogg Co Showcases New Cereals at FNCE 2026. . WK Kellogg Co Newsroom.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the fortified foods market in 2026 and what is forecast for 2036?
- Which statutory flour, rice, and dairy enrichment mandates drive global demand for fortified foods?
- Why do Fortified Dairy and Plant Milks lead the base food matrix category?
- Why do Vitamins A D E and B-Complex lead the micronutrient fortificant category globally?
- How do growth rates differ across India, Brazil, Mexico and the United States?
- Which leading companies supply fortified dairy and infant nutrition versus enriched breakfast cereals?
- What sensory oxidation hurdles and upper intake ceilings restrain over-fortification in commercial foods?
- What should food processors evaluate when selecting dry premixes versus microencapsulated fortificants?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Base Food Matrix, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Base Food Matrix, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Base Food Matrix, 2026 to 2036
- Fortified Dairy and Plant Milks
- Fortified Breakfast Cereals and Grains
- Fortified Infant Nutrition and Baby Food
- Fortified Edible Oils and Fats
- Y-o-Y Growth Trend Analysis By Base Food Matrix, 2021 to 2025
- Absolute $ Opportunity Analysis By Base Food Matrix, 2026 to 2036
- Global Market Analysis and Forecast, By Micronutrient Fortificant, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Micronutrient Fortificant, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Micronutrient Fortificant, 2026 to 2036
- Vitamins A D E and B-Complex
- Minerals Calcium Iron Zinc and Iodine
- Omega-3 Fatty Acids and Probiotics
- Protein and Amino Acid Isolates
- Y-o-Y Growth Trend Analysis By Micronutrient Fortificant, 2021 to 2025
- Absolute $ Opportunity Analysis By Micronutrient Fortificant, 2026 to 2036
- Global Market Analysis and Forecast, By Target Cohort, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Target Cohort, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Target Cohort, 2026 to 2036
- General Adults and Health Enthusiasts
- Infants Toddlers and Children
- Pregnant and Lactating Women
- Geriatric and Senior Nutrition
- Clinical and Sports Recovery Patients
- Y-o-Y Growth Trend Analysis By Target Cohort, 2021 to 2025
- Absolute $ Opportunity Analysis By Target Cohort, 2026 to 2036
- Global Market Analysis and Forecast, By Fortification Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Fortification Technology, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Fortification Technology, 2026 to 2036
- Dry Premix Blending
- Microencapsulation and Spray Drying
- Liquid Emulsion Dosing
- Extrusion and Kernel Reconstitution
- Y-o-Y Growth Trend Analysis By Fortification Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By Fortification Technology, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Supermarkets and Hypermarkets
- Pharmacies and Clinical Dispensaries
- Institutional and Public Nutrition Programs
- Direct-to-Consumer and Online Retail
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Base Food Matrix
- By Micronutrient Fortificant
- By Target Cohort
- By Fortification Technology
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Nestlé S.A.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Danone S.A.
- General Mills Inc.
- Abbott Laboratories
- WK Kellogg Co
- Unilever PLC
- Arla Foods amba
- Royal FrieslandCampina N.V.
- Mondelēz International Inc.
- PepsiCo Inc.
- Fortified Breakfast Cereal, Grain, and Snack Formulators
- Nestlé S.A.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Base Food Matrix, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Micronutrient Fortificant, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Target Cohort, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Fortification Technology, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Base Food Matrix, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Micronutrient Fortificant, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Target Cohort, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Fortification Technology, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Base Food Matrix, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Micronutrient Fortificant, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Target Cohort, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Fortification Technology, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Base Food Matrix, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Micronutrient Fortificant, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Target Cohort, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Fortification Technology, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Base Food Matrix, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Micronutrient Fortificant, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Target Cohort, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Fortification Technology, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Base Food Matrix, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Micronutrient Fortificant, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Target Cohort, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Fortification Technology, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Base Food Matrix, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Micronutrient Fortificant, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Target Cohort, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Fortification Technology, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Base Food Matrix, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Micronutrient Fortificant, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Target Cohort, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Fortification Technology, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Base Food Matrix, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Base Food Matrix, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Base Food Matrix
- Figure 6: Global Market Value Share and BPS Analysis by Micronutrient Fortificant, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Micronutrient Fortificant, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Micronutrient Fortificant
- Figure 9: Global Market Value Share and BPS Analysis by Target Cohort, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Target Cohort, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Target Cohort
- Figure 12: Global Market Value Share and BPS Analysis by Fortification Technology, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Fortification Technology, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Fortification Technology
- Figure 15: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Distribution Channel
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Base Food Matrix, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Base Food Matrix, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Base Food Matrix
- Figure 32: North America Market Value Share and BPS Analysis by Micronutrient Fortificant, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Micronutrient Fortificant, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Micronutrient Fortificant
- Figure 35: North America Market Value Share and BPS Analysis by Target Cohort, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Target Cohort, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Target Cohort
- Figure 38: North America Market Value Share and BPS Analysis by Fortification Technology, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Fortification Technology, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Fortification Technology
- Figure 41: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Distribution Channel
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Base Food Matrix, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Base Food Matrix, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Base Food Matrix
- Figure 48: Latin America Market Value Share and BPS Analysis by Micronutrient Fortificant, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Micronutrient Fortificant, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Micronutrient Fortificant
- Figure 51: Latin America Market Value Share and BPS Analysis by Target Cohort, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Target Cohort, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Target Cohort
- Figure 54: Latin America Market Value Share and BPS Analysis by Fortification Technology, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Fortification Technology, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Fortification Technology
- Figure 57: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Base Food Matrix, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Base Food Matrix, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Base Food Matrix
- Figure 64: Western Europe Market Value Share and BPS Analysis by Micronutrient Fortificant, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Micronutrient Fortificant, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Micronutrient Fortificant
- Figure 67: Western Europe Market Value Share and BPS Analysis by Target Cohort, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Target Cohort, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Target Cohort
- Figure 70: Western Europe Market Value Share and BPS Analysis by Fortification Technology, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Fortification Technology, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Fortification Technology
- Figure 73: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Base Food Matrix, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Base Food Matrix, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Base Food Matrix
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Micronutrient Fortificant, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Micronutrient Fortificant, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Micronutrient Fortificant
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Target Cohort, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Target Cohort, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Target Cohort
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Fortification Technology, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Fortification Technology, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Fortification Technology
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Base Food Matrix, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Base Food Matrix, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Base Food Matrix
- Figure 96: East Asia Market Value Share and BPS Analysis by Micronutrient Fortificant, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Micronutrient Fortificant, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Micronutrient Fortificant
- Figure 99: East Asia Market Value Share and BPS Analysis by Target Cohort, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Target Cohort, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Target Cohort
- Figure 102: East Asia Market Value Share and BPS Analysis by Fortification Technology, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Fortification Technology, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Fortification Technology
- Figure 105: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Base Food Matrix, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Base Food Matrix, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Base Food Matrix
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Micronutrient Fortificant, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Micronutrient Fortificant, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Micronutrient Fortificant
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Target Cohort, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Target Cohort, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Target Cohort
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Fortification Technology, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Fortification Technology, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Fortification Technology
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Base Food Matrix, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Base Food Matrix, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Base Food Matrix
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Micronutrient Fortificant, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Micronutrient Fortificant, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Micronutrient Fortificant
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Target Cohort, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Target Cohort, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Target Cohort
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Fortification Technology, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Fortification Technology, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Fortification Technology
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the fortified foods market in 2026, and what is forecast for 2036?
FMI estimates that the global fortified foods market stood at USD 185.0 billion in 2025 and reaches USD 198.0 billion in 2026, advancing to USD 389.5 billion by 2036.
What is the CAGR for the fortified foods market from 2026 to 2036?
The fortified foods sector is projected to expand at a 7.0% CAGR over the 2026 to 2036 forecast window, adding USD 191.5 billion in incremental revenue across retail and public-nutrition channels.
Which base food matrix segment leads the fortified foods market?
Fortified Dairy and Plant Milks are anticipated to hold 36.5% of base food matrix demand in 2026 since homogenized dairy and plant beverages disperse fat-soluble vitamins A and D effectively.
Which micronutrient fortificant segment leads the fortified foods market?
Vitamins A D E and B-Complex are projected to represent 44.0% of the micronutrient fortificant category in 2026 owing to mandatory flour, oil, and milk enrichment laws.
Which country has a notable growth outlook during the assessment period?
India leads national expansion projections at an 8.7% CAGR through 2036, supported by the universal government fortified rice scheme and FSSAI +F dairy and oil adoption.
Who are the key players in the market?
Nestlé, Danone and Abbott lead fortified dairy and clinical nutrition. General Mills, WK Kellogg and Unilever anchor enriched cereals and culinary staples. Arla, FrieslandCampina and Mondelēz also hold major shares with PepsiCo.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
