
- Market Size (2026)
- USD 3.0 Bn
- Forecast (2036)
- USD 4.2 Bn
- CAGR (2026 to 2036)
- 3.3%
How big is Polyethylene Terephthalate Glycol (PETG) Market in 2026?
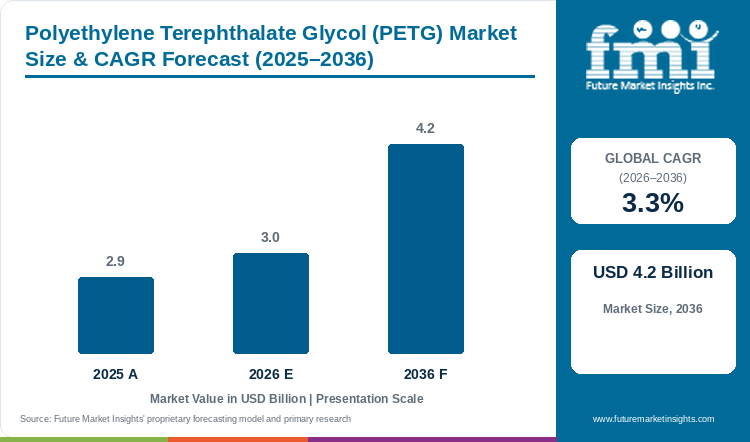
Sales of PETG will grow at a CAGR of 3.3% from 2026 to 2036. Market size was USD 2.94 billion in 2025 and is projected to reach USD 3.04 billion in 2026 and USD 4.21 billion by 2036.
PETG market size stood at USD 2.94 billion in 2025, is estimated at USD 3.04 billion in 2026 and is projected to reach USD 4.21 billion by 2036, a CAGR of 3.3% from 2026 to 2036, according to FMI.
Adoption of dual-site supply is the main trend shaping demand. Selenis bought the copolyester production assets of Polisan Hellas in Greece for installation in Portugal, and Selenis is targeting specialty copolyester capacity of more than 200,000 metric tons a year across Portugal, Italy, Tunisia and the US by 2028, following the installation of the Polisan Hellas assets in Portugal [1]. Selenis plans to qualify key grades at more than one plant, so converters can source the same specification from different sites[1].
The new continuous line will take high-volume grades, with batch lines kept for specialty and custom formulations[1]. Shrink sleeve PETG moves to the line first, followed by film and sheet and medical packaging under the Selcare range[1].
Demand for recycled-content grades is an opportunity, and Selenis develops grades with up to 50% recycled content[1]. Freight and plant disruption risks will keep converters asking for second-site supply. Price competition in standard sheet is the challenge. Suppliers with dual-site supply and medical grades will hold repeat orders through a slow growth pace of 3.3%, FMI projects.
Key Market Trends & Insights
- By product type, extruded grade led with 40% of sales in 2026, ahead of injection molding grade at 35% and blow molding grade at 25%.
- By application, containers and packaging accounted for 45% of sales in 2026, ahead of tools, jigs, fixtures, equipment and machinery at 22% and prototypes at 20%.
- By end use, food and beverage led with 36% of sales in 2026, ahead of medical at 27% and cosmetics at 22%. Eastman names shrink packaging and heavy-gauge sheet in specialty plastics among the focus areas of the company.[2]
Regional Highlights
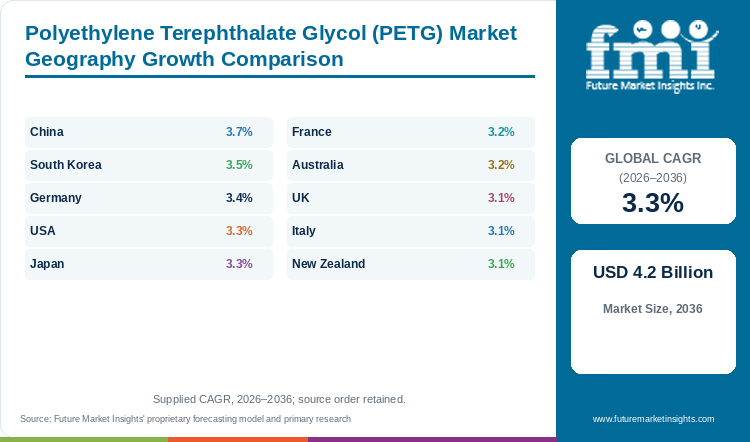
- Fastest-growing profiled country: China (3.7% CAGR, 2026 to 2036).
- By country: South Korea (3.5%) and Germany (3.4%) follow, with the USA and Japan at 3.3%, France and Australia at 3.2%, and the UK, Italy and New Zealand recording the lowest profiled CAGR at 3.1%.
- SK Chemicals reported standalone sales of KRW 479.1 billion for the second quarter of 2026, up 24.8% from a year earlier.[3]
Market Size & Forecast
Table 1: Market Size and Forecast for the PETG Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 2.94 billion |
| Estimated Market Size in 2026 | USD 3.04 billion |
| Projected Market Size by 2036 | USD 4.21 billion |
| CAGR, 2026 to 2036 | 3.3% |
| Added Revenue, 2026 to 2036 | USD 1.17 billion |
| Market Expansion Multiple | 1.4x |
PETG market size is projected to add USD 1.17 billion between 2026 and 2036, a 1.4x expansion on the 2026 base. FMI links the build to clear containers, blister packs and clamshells for pharma, cosmetics, food and electronics, and to medical uses such as IV containers and diagnostic trays. The adjacent polyethylene terephthalate market carries a 3.2% CAGR from 2025 to 2035 in the FMI report, close to the PETG pace. Eastman reported in January 2026 that specialty plastics sales volume/mix was relatively flat in 2025, as growth from innovation offset a weak consumer durables market.[2] Ethylene glycol and purified terephthalic acid prices follow crude oil, and that link remains the stated restraint on producer margins.
Capacity Additions and Utilisation Indicators
Published PETG-only tonnage is scarce, so company filings and trade reports carry the capacity analysis. Eastman called asset utilization a headwind of about USD 100 million in 2025 against 2024, with a significant amount in Advanced Materials, and guided to substantially higher capacity utilization in 2026.[2] In the second quarter of 2026, Advanced Materials sales revenue rose 5% on 4% higher volume/mix, yet EBIT decreased as lower asset utilization and higher variable compensation expense more than offset the gains.[4] Selenis is adding a continuous line, and SK Chemicals reported the highest quarterly standalone sales since the 2017 spin-off.[1][3] Business scope and reporting periods differ across the four sources, so the comparison is directional.
Table 2: Capacity and Utilisation Indicators for the PETG Market (tons, currency and percentage), mixed reporting years from 2025 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Selenis, September 2026 | Polisan Hellas copolyester assets moved to Portugal; shrink sleeve PETG is the first grade on the continuous line | Film and sheet PETG follow on the same line. | [1] |
| Selenis specialty copolyester capacity | 200,000 metric tons a year across Portugal, Italy, Tunisia and the US | The total spans four countries. | [1] |
| Eastman asset utilization, 2025 | About a USD 100 million headwind against 2024, with a significant amount in Advanced Materials | Underfilled plants weighed on segment earnings. | [2] |
| Eastman 2026 outlook | Substantially higher capacity utilization guided for Advanced Materials | Fuller plants are the 2026 plan. | [2] |
| Eastman Advanced Materials, second quarter 2026 | Sales revenue up 5% on 4% higher volume/mix; EBIT lower on lower asset utilization | Volume growth and lower utilization appeared in the same quarter. | [4] |
| Eastman Advanced Materials, third quarter 2026 | EBIT expected higher on improved price-cost and asset utilization | Utilization is expected to improve in the third quarter. | [4] |
| SK Chemicals Shantou site | Shuye facility in China has the potential to produce 70,000 tons of r-BHET a year | Recycled feedstock capacity is next to copolyester production. | [5] |
| SK Chemicals, second quarter 2026 | Standalone sales of KRW 479.1 billion, up 24.8%; Green Chemicals drove growth on stable demand | Demand held up in the Korean producer base. | [3] |
| Clariant Adsorbents & Additives, second quarter 2026 | Sales up 5.3% in local currency; additives grew on pricing and volume | Additive suppliers to compounders reported growth. | [6] |
Analyst Perspective
“Utilisation will decide PETG supply choices through 2036, since a 3.3% CAGR adds only USD 1.17 billion in ten years. Producers with filled sheet, film and shrink sleeve lines and credible recycled-content grades will hold the strongest position.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the Polyethylene Terephthalate Glycol (PETG) Market segmented?
The PETG market is segmented into product type, application, and end use, and region. In 2026, extruded grade holds 40% of product type sales, containers and packaging hold 45% of application sales and food and beverage holds 36% of end use sales.
By product type: extruded grade, injection molding grade, and blow molding grade.
By application: prototypes, containers and packaging, tools, jigs, fixtures, equipment and machinery, and others.
By end use: food and beverage, cosmetics, medical, and others.
By region: North America, Latin America, Europe, Middle East and Africa, East Asia, and South Asia and the Pacific.
Why does extruded grade lead product type sales?
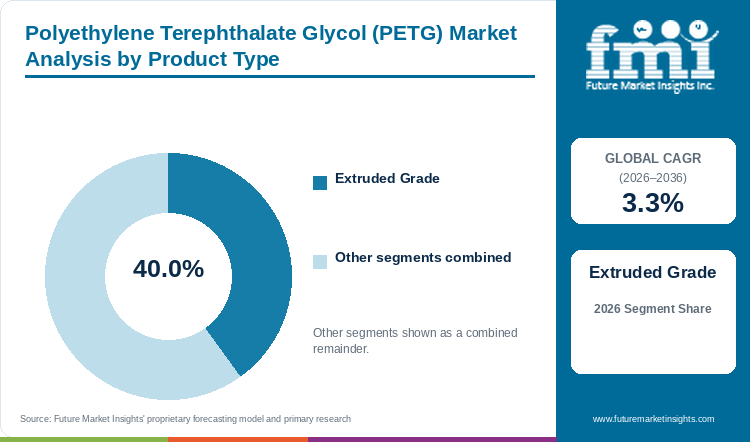
Extruded grade accounts for 40% of product type sales in 2026, ahead of injection molding grade at 35% and blow molding grade at 25%.
Table 3: Product Type Share for the PETG Market (percentage share), 2026
| Product Type | Estimated Share (2026) |
|---|---|
| Extruded Grade | 40% |
| Injection Molding Grade | 35% |
| Blow Molding Grade | 25% |
| Total | 100.0% |
Table 4: Product Type Leadership and Market Growth for the PETG Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 3.3% |
| Leading Segment | Extruded Grade |
Extruded grade leads because sheet and film lines supply the packaging formats that buyers order in the largest quantities. In the FMI split, the grade holds 40% of sales in 2026, and injection molding grade holds 35%. Eastman named shrink packaging and heavy-gauge sheet in specialty plastics as focus areas in January 2026 comments.[2] Recycling opens a second route, since the recycled PET packaging market is projected at a 7% CAGR from 2026 to 2036. Acrylic and polycarbonate still compete for clear rigid uses in cost-conscious regions.
- Sheet and film lines feed blister packs, clamshells and clear containers.
- Eastman reported that Advanced Materials sales revenue rose 5% in the second quarter of 2026 on 4% higher volume/mix.[4]
Why do containers and packaging lead demand by application?
Containers and packaging account for 45% of application sales in 2026, ahead of tools, jigs, fixtures, equipment and machinery at 22% and prototypes at 20%.
Table 5: Application Share for the PETG Market (percentage share), 2026
| Application | Estimated Share (2026) |
|---|---|
| Prototypes | 20% |
| Containers and Packaging | 45% |
| Tools, Jigs, Fixtures, Equipment and Machinery | 22% |
| Others | 13% |
| Total | 100.0% |
Adoption of PETG in containers and packaging is led by pharma, cosmetics, food and electronics buyers, per FMI. Selenis said the first continuous-line grade is shrink sleeve PETG, followed by PETG for film and sheet, including thermoformed and rigid packaging.[1] The plastic packaging market is listed at USD 410.7 billion in 2025, so PETG packaging is a small slice of a large pool. Tools, jigs, fixtures, equipment and machinery and other uses share the balance of application sales. Sheet and film lines are the first to receive new continuous capacity.
- Pharma, cosmetics, food and electronics buyers order clear containers, blister packs and clamshells.
- Selenis supplies medical packaging through the Selcare brand.[1]
Why does food and beverage lead end use sales?
Food and beverage accounts for 36% of end use sales in 2026, ahead of medical at 27% and cosmetics at 22%.
Table 6: End Use Share for the PETG Market (percentage share), 2026
| End Use | Estimated Share (2026) |
|---|---|
| Food and Beverage | 36% |
| Cosmetics | 22% |
| Medical | 27% |
| Others | 15% |
| Total | 100.0% |
Food contact brings approvals into the buying decision. SK Chemicals executive vice president Kim Hyun-suk said in an interview published in August 2025 that the company has received safety certifications from accredited agencies for products that touch food, with the US Food and Drug Administration named as one of them.[5] Medical uses add IV containers, diagnostic trays and face shields, and sterilisation and chemical resistance count for each. Cosmetics buyers use copolyester widely in packaging, the same article notes.[5] Each end use asks for separate approvals, so a grade switch takes time.
- Medical uses include IV containers, diagnostic trays, face shields and surgical components.
- Copolyester is widely used in cosmetics packaging, household items and home appliances, The Korea Times reported.[5]
What are the drivers, restraints, and opportunities in the Polyethylene Terephthalate Glycol (PETG) Market?
In the PETG market, packaging, healthcare and 3D printing use drive sales, raw material swings and a concentrated supplier base constrain supply, and recycled and bio-based grades open the principal commercial opportunity.
- Driver: Clear packaging, sterilisable medical parts and 3D printing grades support sales, and continuous lines add sheet and film supply.
- Restraint: Ethylene glycol and purified terephthalic acid prices follow crude oil, and substitutes press on cost-conscious buyers.
- Opportunity: Closed-loop recycling, bio-based grades and substitution of polycarbonate open new volume.
Continuous Lines Add Sheet and Film Supply
Packaging converters gain a new source of sheet and film grades as Selenis moves copolyester assets from Greece to Portugal. The company said in September 2026 that shrink sleeve PETG is the first grade for the continuous line.[1] Grades for film and sheet, including thermoformed and rigid packaging, follow.[1] Selenis also supplies PETG and PCTG resin to filament producers for 3D printing through Mimesis, which links packaging supply to printer-grade demand.[1] Converters weigh the new source against the long-standing positions of Eastman and SK Chemicals.
Utilisation and Raw Material Costs Limit Margins
Eastman reported that price-cost was stable in Advanced Materials in the second quarter of 2026 as increases in specialty plastics were made to mitigate higher raw material and distribution costs.[4] Asset utilization had been about a USD 100 million headwind in 2025 against 2024.[2] The acrylic resin market offers a clear-plastic alternative for cost-conscious buyers, and the PETG report lists acrylic, polycarbonate and polystyrene as the substitutes. Producer shutdowns or capacity limits can tighten supply quickly in a market with few large suppliers.
Recycled and Depolymerised Grades Open New Supply
Depolymerisation produces r-BHET, a key copolyester material, and SK Chemicals said in an August 2025 interview that the Shuye facility in China has the potential to produce 70,000 tons of r-BHET a year.[5] Eastman reported that the Kingsport methanolysis plant exceeded 75% capacity utilization for the remainder of 2025 after minor equipment modifications completed in October 2025 that increased reliability and overall capacity.[2] PETG can replace polycarbonate with comparable optical properties, which places the grade near the engineering plastic market listed at USD 165.4 billion in 2025. Closed-loop grades give brand owners a route to recycled content without a change of resin family.
Which country CAGRs are profiled in the Polyethylene Terephthalate Glycol (PETG) Market?
Table 7: Country CAGR Comparison for the PETG Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| China | 3.7% |
| South Korea | 3.5% |
| Germany | 3.4% |
| USA | 3.3% |
| Japan | 3.3% |
| France | 3.2% |
| Australia | 3.2% |
| UK | 3.1% |
| Italy | 3.1% |
| New Zealand | 3.1% |
How do country-level CAGRs compare in the PETG market?
Growth across the ten profiled countries stays in a narrow band, shaped by packaging mix and recycling policy. As per the FMI country analysis, China leads at 3.7% CAGR from 2026 to 2036, followed by South Korea at 3.5% and Germany at 3.4%. The USA and Japan are projected at 3.3%, France and Australia at 3.2%, and the UK, Italy and New Zealand at 3.1%. Packaging policy and producer capacity differ across all ten.
- China pairs consumer goods and electronics packaging with foreign-owned recycling capacity at Shantou.
- South Korea links export capacity to SK Chemicals, which reported the highest standalone quarterly sales since 2017.
- Germany combines medical technology and point-of-sale display use with closed-loop production projects.
- The USA follows Eastman as the producer works to refill plants after a weak 2025 for utilization.
- Japan ties clear display use to sustainable engineering plastics from Mitsubishi Chemical and Toray Industries.
- France steers PETG toward cosmetic, medical and personal care packaging under single-use plastics policy.
- Australia moves food packaging toward recyclable thermoplastics under circular economy goals.
- The UK ties pharma packaging and retail displays to the plastic packaging tax.
- Italy links thermoforming and medical device demand to a domestic specialty copolyester site.
- New Zealand centres growth on health and personal care packaging.
Full report country CAGRs cover: North America; Latin America; Europe; Middle East and Africa; East Asia; South Asia and the Pacific.
Country-wise Analysis
China PETG Market Outlook (2026 to 2036)
Consumer goods, electronics packaging and healthcare products drive the 3.7% CAGR projected for China from 2026 to 2036, the highest of the ten profiled countries. SK Chemicals acquired the Shuye facility in China in 2023 and set up SK Shantou, and Kim Hyun-suk said in August 2025 that the site has the potential to produce 70,000 tons of r-BHET a year.[5] Yisheng Petrochemical and China Resources Chemical are expanding PET and PETG lines. Government policy for biodegradable and recyclable materials supports demand, and substitution of PVC and polycarbonate is expected.
Key takeaway: China combines domestic PETG lines with foreign-owned recycled feedstock capacity, so buyers can source local resin built on recycled input.
South Korea PETG Market Outlook (2026 to 2036)
SK Chemicals reported standalone sales of KRW 479.1 billion for the second quarter of 2026, up 24.8%, with Green Chemicals driving growth on stable demand.[3] The company plans to expand sales of high value-added products in the second half.[3] The Korea Times describes SK Chemicals and Eastman as holding a duopoly in the global copolyester market.[5] Electronics packaging, medical disposables and 3D printing drive Korean demand. SK Chemicals and Lotte Chemical are raising capacity for export. South Korea is projected to grow at a CAGR of 3.5% from 2026 to 2036.
Key takeaway: Korean PETG outlook follows decisions at one or two producers, and export orders are the swing factor.
Germany PETG Market Outlook (2026 to 2036)
German packaging and medical technology sectors have adopted PETG for processability, toughness and transparency, with point-of-sale displays and diagnostic trays as common uses. BASF SE and KlöcknerPentaplast pursue closed-loop production. Public authorities support polymer research and sustainability initiatives, which suits converters that want recycled content. Germany is projected at a CAGR of 3.4% from 2026 to 2036, the highest among the four profiled European countries.
Key takeaway: German growth of 3.4% leads Europe in the profiled set, and closed-loop projects at converters decide the share that reaches new resin.
USA PETG Market Outlook (2026 to 2036)
Eastman reported in January 2026 that asset utilization was a headwind of about USD 100 million in 2025 against 2024, and guided to substantially higher capacity utilization in 2026.[2] On 30 July 2026 the company reported that Advanced Materials sales revenue rose 5% in the second quarter on 4% higher volume/mix.[4] The report names Eastman Chemical Company and Tekni-Plex Inc. as investing in recyclable and bio-based grades. Medical parts, food packaging material and 3D printing material support the 3.3% CAGR projected for the USA from 2026 to 2036.
Key takeaway: US supply starts from a lead producer that is refilling existing plants, so buyers look first at contract coverage.
Japan PETG Market Outlook (2026 to 2036)
Chemical resistance and optical clarity make PETG a solution for point-of-purchase displays in Japan. Mitsubishi Chemical and Toray Industries focus on sustainable engineering plastics, and customer support for environmentally friendly manufacturing and green packaging policies backs long-term demand. Japan is projected at a CAGR of 3.3% from 2026 to 2036, level with the USA.
Key takeaway: Display retail and green packaging policy set the pace in Japan, and sustainable grades from Mitsubishi Chemical and Toray Industries are the supply to watch.
France PETG Market Outlook (2026 to 2036)
National policies against one-time-use plastics and for biocompatible alternatives act as growth factors for PETG containers and sheets in cosmetic, medical and personal care packaging in France. Selenis and local converters are investing in food-grade and flame-resistant PETG technologies. France is projected at a CAGR of 3.2% from 2026 to 2036.
Key takeaway: France ties PETG demand to cosmetics and medical packaging, so single-use plastics policy shapes grade choice.
Australia PETG Market Outlook (2026 to 2036)
Stricter import conditions on virgin plastics and circular economy goals push Australian buyers toward recyclable thermoplastics. Food packaging, consumer goods packaging and display uses are rising, and Australia is projected at a CAGR of 3.2% from 2026 to 2036.
Key takeaway: Recycled-content supply sets the pace at which Australian food packaging buyers switch to PETG.
UK PETG Market Outlook (2026 to 2036)
The government plastic packaging tax and environmental objectives are expected to stimulate demand for low-carbon recyclable PETG in the UK. Quinn Packaging and Distrupol invest in EU-sourced REACH-compliant materials, and pharma packaging and green retail display systems fuel growth. The UK is projected at a CAGR of 3.1% from 2026 to 2036 by FMI, the lowest tier of the profiled table.
Key takeaway: UK buyers weigh the tax treatment of recycled content when choosing PETG sheet for pharma and retail displays.
Italy PETG Market Outlook (2026 to 2036)
Selenis operates specialty copolyester sites in Portugal, Italy, Tunisia and the US, and total capacity will reach 200,000 metric tons a year.[1] Lati Industria Termoplastici and MAIP Group are Italian players enhancing product lines. Consumer packaging, medical devices and industrial thermoforming drive demand, and public policy on circular product design and plastic recyclability supports steady absorption. Italy is projected at a CAGR of 3.1% from 2026 to 2036.
Key takeaway: Italy pairs thermoforming demand with a domestic specialty copolyester site, so local sourcing is open to converters.
New Zealand PETG Market Outlook (2026 to 2036)
Health and personal care packaging drive PETG growth in New Zealand, and government waste-reduction programmes that promote plastic substitutes sustain demand. Converters and traders rely more on environmentally sound resin sources. New Zealand is projected at a CAGR of 3.1% from 2026 to 2036, level with the UK and Italy.
Key takeaway: New Zealand is in the lowest CAGR tier, and resin sourcing choices by converters and traders carry the outlook.
Who are the notable companies in the Polyethylene Terephthalate Glycol (PETG) Market?
Eastman Chemical Company, SK Chemicals, Celanese Corporation, Daicel Corporation, Clariant Ltd, SM Kunststofftechnologie GmbH, Integrated Packaging Films Inc., Preferred Plastics, Inc., Industrial Plastics Belgium (IPB NV), and Shandong Shenghe Plastic Ltd are notable companies profiled in this market.
Eastman Chemical Company leads the PETG market at 22% to 26%, followed by SK Chemicals at 15% to 19%, Celanese Corporation at 10% to 14%, Daicel Corporation at 7% to 11%. Other players together hold 20% to 30%. The Korea Times describes Eastman and SK Chemicals as holding a duopoly in the global copolyester market.[5] Eastman expects higher third-quarter EBIT in Advanced Materials on improved price-cost and asset utilization, SK Chemicals reported the highest quarterly standalone sales since the 2017 spin-off, and Clariant reported additives growth in the second quarter of 2026.[4][3][6] Selenis is adding continuous capacity in Portugal.[1]
- Leading producers by share: Eastman Chemical Company, SK Chemicals, Celanese Corporation, Daicel Corporation, and Clariant Ltd.
- Other key players: SM Kunststofftechnologie GmbH, Integrated Packaging Films Inc., Preferred Plastics, Inc., Industrial Plastics Belgium (IPB NV), and Shandong Shenghe Plastic Ltd.
- Regional producers and converters: Tekni-Plex, Quinn Packaging, Distrupol, Selenis, BASF SE, KlöcknerPentaplast, LatiIndustriaTermoplastici, MAIP Group, Lotte Chemical, Mitsubishi Chemical, Toray Industries, Yisheng Petrochemical, China Resources Chemical, Plaspak Group, and Visy Industries.
- Companies with recent capacity or results news: Eastman Chemical Company, SK Chemicals, Selenis, and Clariant Ltd.
Competitive Benchmarking: PETG Market
Table 8: Competitive Benchmarking for the PETG Market (qualitative documentation ratings), 2026
| Company | Capacity | PETG Grades | Activity | Disclosure |
|---|---|---|---|---|
| Eastman | High | Medium | High | High |
| SK Chemicals | Medium | Medium | High | High |
| Selenis | High | High | High | Medium |
| Clariant | Low | Low | Medium | High |
High indicates wider documentation in company filings and releases, Medium indicates limited documentation, and Low indicates less direct documentation. Ratings do not indicate product quality, market share or company rank.
Key Developments in the PETG Market
- In September 2026, Selenis bought the copolyester production assets of Polisan Hellas in Greece for installation in Portugal, with shrink sleeve PETG the first grade for the continuous line.[1]
- In August 2026, SK Chemicals reported second-quarter standalone sales of KRW 479.1 billion, up 24.8%, and plans to expand sales of high value-added products in the second half.[3]
- In July 2026, Eastman reported that Advanced Materials sales revenue rose 5% in the second quarter on 4% higher volume/mix.[4]
- In July 2026, Clariant reported that Adsorbents & Additives sales rose 5.3% in local currency in the second quarter, with additives growing on pricing and volume.[6]
- In January 2026, Eastman guided to substantially higher capacity utilization in 2026 after asset utilization cost about USD 100 million in 2025.[2]
Key Players in the PETG Market
Leading Share-range Companies
- Eastman Chemical Company
- SK Chemicals
- Celanese Corporation
- Daicel Corporation
- Clariant Ltd
Other Key Players
- SM Kunststofftechnologie GmbH
- Integrated Packaging Films Inc.
- Preferred Plastics, Inc.
- Industrial Plastics Belgium (IPB NV)
- Shandong Shenghe Plastic Ltd
Producers Active in 2025 and 2026
- Selenis
Polyethylene Terephthalate Glycol (PETG) Market - Report Scope
Table 9: Report Scope for the PETG Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; application; end use; region |
| Quantitative units | USD billion |
| Market definition | Polyethylene terephthalate glycol (PETG) market covering extruded, injection molding and blow molding grades, tracked by application and end use in food and beverage, cosmetics, medical and other uses. |
| Regions covered | North America; Latin America; Europe; Middle East and Africa; East Asia; South Asia and the Pacific |
| Countries covered | China; South Korea; Germany; USA; Japan; France; Australia; UK; Italy; New Zealand |
| Key companies profiled | Eastman Chemical Company, SK Chemicals, Celanese Corporation, Daicel Corporation, Clariant Ltd, SM Kunststofftechnologie GmbH, Integrated Packaging Films Inc., Preferred Plastics, Inc., Industrial Plastics Belgium (IPB NV), Shandong Shenghe Plastic Ltd |
| Forecast period | 2026 to 2036 |
PETG Market - Research Methodology
Table 10: Research Methodology for the PETG Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Capacity and company facts come from company filings, press releases and trade press dated May 2025 or later. |
| Desk Research | Desk research covers company results, official press releases and trade press on copolyester and PETG capacity, utilization and recycled feedstock. |
| Market Sizing and Forecasting | Sizing starts from the 2025 base of USD 2.94 billion and the 3.3% CAGR. |
| Data Validation | Capacity, utilization and feedstock figures are matched across producer results and trade interviews before use. |
PETG Market by Segments
PETG Market segmented by Product Type:
- Extruded Grade
- Injection Molding Grade
- Blow Molding Grade
PETG Market segmented by Application:
- Prototypes
- Containers and Packaging
- Tools, Jigs, Fixtures, Equipment and Machinery
- Others
PETG Market segmented by End Use:
- Food and Beverage
- Cosmetics
- Medical
- Others
PETG Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Middle East and Africa
- GCC Countries
- South Africa
- East Asia
- China
- Japan
- South Korea
- South Asia and the Pacific
- India
- Australia
- New Zealand
Research Sources and Bibliography
- [1] Milana Nikolova, Packaging Insights. (2026, September 24). Selenis expands copolyester capacity with Polisan Hellas asset acquisition. https://www.packaginginsights.com/news/selenis-expands-copolyester-production.html
- [2] Eastman Chemical Company. (2026, January 29). Eastman Q4 and FY 2025 Prepared Comments. https://s29.q4cdn.com/397220757/files/doc_financials/2025/q4/Eastman-Q4-and-FY-2025-Prepared-Comments-FINAL.pdf
- [3] Asia Economy. (2026, August 14). SK Chemicals Reports Q2 Operating Profit of 31.9 Billion Won... Sales Up 24.8%. https://view.asiae.co.kr/en/article/2026081407432212950
- [4] Eastman Chemical Company (Business Wire). (2026, July 30). Eastman Announces Second-Quarter 2026 Financial Results. https://www.businesswire.com/news/home/20260730556159/en/
- [5] The Korea Times. (2025, August 3). [INTERVIEW] SK Chemicals bets on plastic recycling to overcome industry downturn. https://www.koreatimes.co.kr/amp/business/tech-science/20250803/sk-chemicals-bets-on-plastic-recycling-to-overcome-industry-downturn
- [6] Clariant. (2026, July 31). Clariant delivers continued strong results in volatile operating environment. https://www.clariant.com/Corporate/News/2026/07/Clariant-delivers-continued-strong-results-in-volatile-operating-environment--Court-dismisses-Shells
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the PETG market during 2026?
- What market size is projected by 2036?
- Which product type and application hold notable share?
- Which end use holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Extruded Grade
- Injection Molding Grade
- Blow Molding Grade
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Prototypes
- Containers and Packaging
- Tools, Jigs, Fixtures, Equipment and Machinery
- Others
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Food and Beverage
- Cosmetics
- Medical
- Others
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Europe
- Middle East and Africa
- East Asia
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Application
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By End Use
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- By Product Type
- By Application
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By End Use
- Key Takeaways
- Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- By Product Type
- By Application
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By End Use
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- By Product Type
- By Application
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By End Use
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- South Asia and the Pacific
- India
- Australia
- New Zealand
- By Product Type
- By Application
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By End Use
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By End Use
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Application
- By End Use
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Eastman
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- SK Chemicals
- Selenis
- Clariant
- Eastman Chemical Company
- Celanese Corporation
- Daicel Corporation
- Clariant Ltd
- SM Kunststofftechnologie GmbH
- Integrated Packaging Films Inc.
- Preferred Plastics, Inc.
- Industrial Plastics Belgium (IPB NV)
- Shandong Shenghe Plastic Ltd
- Eastman
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 13: Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 15: Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 16: Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 17: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Middle East and Africa Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 19: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 20: Middle East and Africa Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by End Use, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type
- Figure 6: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Application
- Figure 9: Global Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End Use
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 21: North America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 22: North America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 23: North America Market Attractiveness Analysis by Product Type
- Figure 24: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 25: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 26: North America Market Attractiveness Analysis by Application
- Figure 27: North America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 28: North America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 29: North America Market Attractiveness Analysis by End Use
- Figure 30: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 31: Latin America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 32: Latin America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 33: Latin America Market Attractiveness Analysis by Product Type
- Figure 34: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 35: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 36: Latin America Market Attractiveness Analysis by Application
- Figure 37: Latin America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 38: Latin America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 39: Latin America Market Attractiveness Analysis by End Use
- Figure 40: Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 41: Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 42: Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 43: Europe Market Attractiveness Analysis by Product Type
- Figure 44: Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 45: Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 46: Europe Market Attractiveness Analysis by Application
- Figure 47: Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 48: Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 49: Europe Market Attractiveness Analysis by End Use
- Figure 50: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 51: Middle East and Africa Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 52: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 53: Middle East and Africa Market Attractiveness Analysis by Product Type
- Figure 54: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 55: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 56: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 57: Middle East and Africa Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 58: Middle East and Africa Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 59: Middle East and Africa Market Attractiveness Analysis by End Use
- Figure 60: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: East Asia Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 62: East Asia Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 63: East Asia Market Attractiveness Analysis by Product Type
- Figure 64: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 65: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 66: East Asia Market Attractiveness Analysis by Application
- Figure 67: East Asia Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 68: East Asia Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 69: East Asia Market Attractiveness Analysis by End Use
- Figure 70: Global Market - Tier Structure Analysis
- Figure 71: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the PETG market expected in 2026?
Market size is projected to reach USD 3.04 billion in 2026 and USD 4.21 billion by 2036, as per Future Market Insights. Market size was USD 2.94 billion in 2025.
What CAGR is projected for the PETG market through 2036?
As per FMI analysis, sales of PETG will grow at a CAGR of 3.3% from 2026 to 2036. Packaging, healthcare and 3D printing use support the outlook.
Which product type and application hold notable market shares in 2026?
Extruded grade accounts for 40% of product type sales in 2026, and injection molding grade accounts for 35%. Containers and packaging hold 45% of application sales, and prototypes hold 20%.
Which end use holds a notable market share in 2026?
Food and beverage accounts for 36% of end use sales in 2026. Cosmetics, medical and other uses make up the balance.
Which country has a notable expansion outlook through 2036?
China is projected to record the fastest growth at 3.7% CAGR from 2026 to 2036, according to FMI. South Korea follows at 3.5% CAGR.
Who are the key companies in the PETG market?
Notable companies include Eastman Chemical Company, SK Chemicals, Celanese Corporation, Daicel Corporation, Clariant Ltd, SM Kunststofftechnologie GmbH, Integrated Packaging Films Inc., Preferred Plastics, Inc., Industrial Plastics Belgium (IPB NV), and Shandong Shenghe Plastic Ltd.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
