
- Market Size (2026)
- USD 1.3 Bn
- Forecast (2036)
- USD 1.9 Bn
- CAGR (2026 to 2036)
- 3.8%
How big is Port Wine Market in 2026?
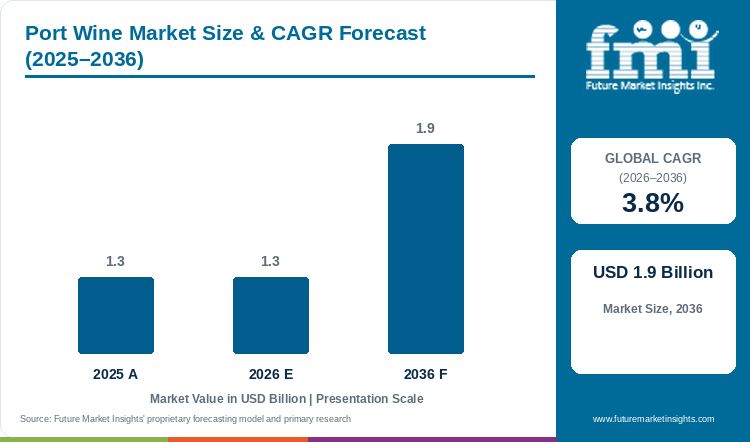
Sales in the port wine market are projected to grow at 3.8% CAGR, with the market size rising from USD 1.3 billion in 2025 to USD 1.3 billion in 2026 and reaching USD 1.9 billion by 2036.
Stemming from the popularity of barrel-aged digestifs and lower-bitterness aperitif cocktail bases, hospitality buyers and specialty wine merchants are widening their Douro valley allocations. Port wine is produced by arresting grape must fermentation with neutral grape spirit, which retains natural residual berry sugar while raising alcohol strength to nineteen or twenty percent for long wood-cask stability. According to FMI, global port wine market value stands at USD 1.3 billion in 2025 and reaches USD 1.3 billion in 2026, before advancing at a 3.8% CAGR to reach USD 1.9 billion by 2036 and generating USD 0.6 billion in added revenue. In May 2026, the International Organisation of Vine and Wine reported that global wine production stood at 225.8 million hectoliters in 2025 while specialized European export hubs sustained high-value fortified wine shipments. Standard classic formulation holds 35.3% of product type / variety sales in 2026 because blended ruby and tawny bottles give supermarkets a reliable entry point. Evaluated country growth spans 3.0% CAGR in Germany to 4.6% in Japan, although rising alcohol excise duties and slower spirit consumption among younger adults restrain bulk volume expansion.
Key Market Trends & Insights
- By product type / variety: Standard classic formulation led with 35.3% share in 2026, driven by steady off-trade demand for multi-vintage ruby and tawny blends during holiday gifting.
- By packaging format: Glass bottles (750ml) accounted for 53.2% in 2026, owing to cellar aging traditions and inert dark-glass protection against ultraviolet light.
- By distribution channel: Off-trade retail supermarkets held 43.8% in 2026, as curated wine aisle displays and fourth-quarter gift cartons generate recurring household purchases.
- By price tier: Mass market / mainstream represented 41.1% in 2026, supported by competitive retail pricing for everyday culinary reductions and casual home pouring.
Regional Highlights
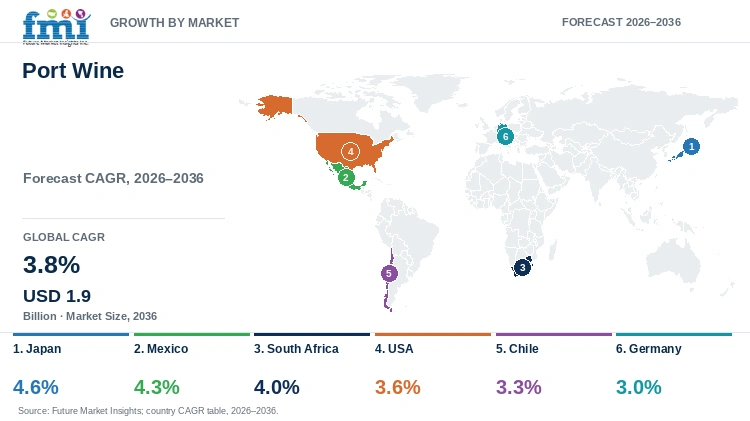
- Fastest-growing evaluated country: Japan, at 4.6% CAGR from 2026 to 2036.
- By country: Mexico at 4.3%, South Africa at 4.0%, and the USA at 3.6% follow, while Germany records the lowest evaluated CAGR at 3.0%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Port Wine Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 1.3 billion |
| Estimated Market Size in 2026 | USD 1.3 billion |
| Projected Market Size by 2036 | USD 1.9 billion |
| CAGR, 2026 to 2036 | 3.8% |
| Added Revenue, 2026 to 2036 | USD 0.6 billion |
Country demand conditions differ as Douro vineyard fortification quotas and national alcohol tax brackets shape how much aged stock reaches each import market. FMI research indicates that estate shippers must balance annual wood-cask evaporation losses against immediate retail cash flow when allocating neutral grape spirit across harvest lots. In February 2025, the Instituto dos Vinhos do Douro e do Porto updated its regulatory production circular governing beneficio fortification authorizations and cellar inventory verification across the demarcated Douro region. Because open 750ml bottles oxidize within weeks at home, producers are also adopting smaller wine packaging formats and chilled white port aperitif serves that fit urban bar programs.
Barrel Maturation and Cellar Cask Sizing
Table 2: Barrel Maturation and Cellar Cask Sizing for the Port Wine Market (USD billion and units), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 1.3 | 1.3 | 1.9 |
| Fortified wine production volume (million liters) | 78.0 to 82.5 | 78.0 to 82.5 | 114.0 to 120.5 |
| Maturing oak cask inventory (thousand oak pipes) | 156.0 to 165.0 | 156.0 to 165.0 | 228.0 to 241.0 |
| Wholesale realization per 9-liter case (USD) | 150.0 to 162.0 | 150.0 to 162.0 | 195.0 to 210.0 |
Per Capita Consumption and Retail Channel Sizing
Aged port wine has gained steady placement in fine dining programs and collector cellars because oxidative barrel aging develops dried fig, walnut, and caramel notes that standard table wines cannot replicate. Managing cellar allocations requires balancing young ruby bottling runs with multi-decade tawny reserves. Surging interest in estate vineyard visits and wine tourism across northern Portugal converts tasting-room visitors into recurring direct-to-consumer case buyers. Specialty wine shops and licensed restaurants represent central revenue channels for age-indicated bottles.
Table 3: Per Capita and Fine Wine Spending Indicators for the Port Wine Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD) | 0.16 | 0.16 | 0.21 |
| Spend per 1,000 people (USD) | 158.0 | 156.6 | 212.3 |
| Wine collector household annual spend (USD) | 68.0 to 76.0 | 68.0 to 76.0 | 108.0 to 120.0 |
Table 4: Facility & Institutional Channel Sizing Indicators for the Port Wine Market (USD and percentages), mixed reporting years from 2023 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 1.3 billion | Report value |
| Licensed fine dining restaurants and wine bars worldwide | 125 thousand | 2024 hospitality census |
| Average annual revenue per licensed establishment | USD 10,400.0 | Commercial average |
| Off-trade supermarket and retail store revenue, 2026 | USD 0.57 billion | 43.8% share |
Analyst Perspective
"Douro estates are revitalizing aged port categories by positioning dry white ports for aperitif cocktails and single-quinta tawnies for dining lists. High excise duties on twenty-percent ABV wines and slow cask turnover still challenge working capital for smaller family quintas."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Port Wine Market segmented?
The port wine market is segmented by product type / variety, packaging format, distribution channel, and price tier. In 2026, Standard Classic Formulation is projected at 35.3%, glass bottles (750ml) at 53.2%, off-trade at 43.8%, and mass market / mainstream at 41.1%.
By product type / variety: Standard classic formulation, premium craft and artisanal, flavored / infused variant, and low-alcohol / zero-ABV line.
By packaging format: Glass bottles (750ml), aluminum cans and single-serve, and bag-in-box and draught kegs.
By distribution channel: Off-trade (retail supermarkets and liquor stores), on-trade (bars, pubs and restaurants), and direct-to-consumer e-commerce.
By price tier: Mass market / mainstream, premium tier, and super-premium and luxury vintage.
Why does Standard Classic Formulation lead the product type / variety category?
Standard classic formulation is expected to hold 35.3% of product type / variety demand in 2026, supported by ruby blending.
Table 5: Product Type / Variety Share for the Port Wine Market (percentage share), 2026
| Product Type / Variety | Share (2026) |
|---|---|
| Standard Classic Formulation | 35.3% |
| Other Segments Combined | 64.7%* |
| Total | 100.0% |
Table 6: Product Type / Variety Leadership and Market Growth for the Port Wine Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 3.8% |
| Leading Segment | Standard Classic Formulation |
Wine importers and supermarket chain buyers rely on standard classic formulations because three-year aged ruby and tawny blends maintain consistent berry aroma and sweetness across large bottling runs. Master blenders draw from multiple Douro sub-regions to buffer vintage weather variation, which gives broader commercial wine distributors predictable shelf pricing without single-vineyard bottle rationing. Whereas declared vintage bottles require decades of sediment decanting, filtered standard blends pour cleanly straight from the bottle in casual restaurants and home dining rooms. Still, rising grape spirit distillation costs require blenders to manage tank maturation schedules carefully through 2036.
- Standard classic formulation accounts for 35.3% of product type / variety revenue in 2026 because multi-harvest blending guarantees uniform taste and approachable retail pricing.
- In March 2025, Instituto da Vinha e do Vinho export registries confirmed that standard ruby and tawny blends represented 61.4% of certified Portuguese fortified shipment volume.
Why do Glass Bottles (750ml) define the largest packaging format?
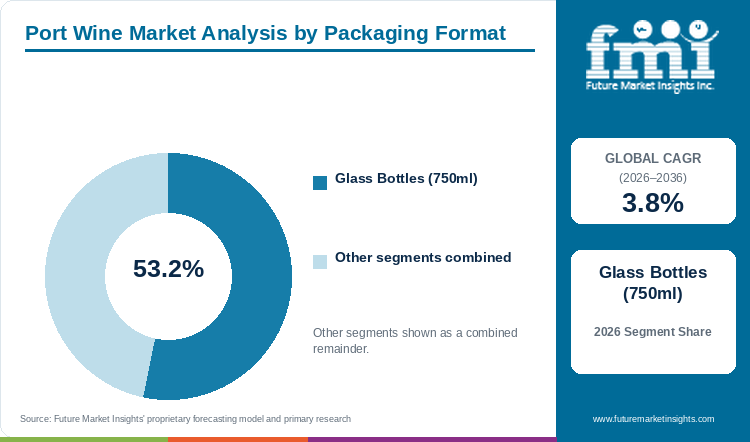
Glass bottles (750ml) are estimated to represent 53.2% of the packaging format category in 2026, underpinned by oxygen-barrier cellar preservation.
Heavyweight 750ml glass bottles remain the primary vessel for port wine because high-proof fortified wines often sit in merchant cellars and domestic cabinets for years after bottling. Thick amber and dark-green glass blocks ultraviolet wavelengths that degrade anthocyanin colour compounds in unfiltered crusted and vintage releases. While bag-in-box and aluminum formats serve high-turnover bar pouring, collectors and duty-free shoppers associate embossed glass bottles and natural cork stoppers with Douro estate authenticity across premium alcoholic beverages packaging lines. Rising container furnace energy bills, however, are pushing glassmakers to reduce bottle weight without weakening internal pressure resistance.
- Glass bottles (750ml) are forecast to maintain 53.2% of packaging format demand in 2026, linked to zero gas permeability and traditional gift presentation.
- In April 2025, the European Container Glass Federation reported that dark-tinted lightweight wine bottles reduced glass furnace carbon intensity by 14.0% while retaining full UV-barrier protection.
What keeps Off-Trade ahead by distribution channel?
Within distribution channel, off-trade retail supermarkets are projected to capture 43.8% share in 2026, driven by seasonal holiday gift merchandising.
Supermarket chains and specialist liquor stores generate the largest share of port wine turnover because household purchasing peaks sharply during autumn and winter festive holidays. Grocery category managers allocate prominent endcap space to wooden gift boxes, cheese-pairing twin packs, and private-label reserve tawnies alongside other fermented beverages from October through December. Unlike on-trade restaurants where by-the-glass markups exceed three hundred percent, off-trade supermarkets let consumers buy aged ten-year tawnies at accessible shelf prices. Outside the fourth quarter, however, retailers require promotional price support and smaller bottle formats to prevent slow summer stock rotation.
- Off-trade accounts for 43.8% of distribution channel sales in 2026, enabled by nationwide grocery cold-weather promotions and bundled holiday gift cartons.
- In May 2025, the Wine and Spirit Trade Association reported that off-trade grocery and specialist wine shops captured 58.2% of annual fortified wine volume in the United Kingdom.
What gives Mass Market / Mainstream the leading position in price tier?
With an estimated 41.1% share in 2026, mass market / mainstream leads price tier sales, owing to everyday culinary affordability.
Mainstream price tiers anchor category volume because culinary kitchens, neighbourhood bistros, and casual home drinkers purchase entry-level ruby and white ports for both sauce reductions and evening pouring. High-volume shippers blend mechanically harvested grapes from lower-altitude Baixo Corgo and Cima Corgo parcels, keeping ex-cellar costs low enough to compete with standard aperitifs and tonic wine offerings on grocery shelves. Although single-quinta vintage bottles carry wider gross margins, mainstream lines keep bottling halls running at steady utilization throughout the year. Retailers still scrutinize entry-level bottle pricing closely whenever duty hikes take effect.
- Mass market / mainstream represents 41.1% of price tier revenue in 2026, reinforced by everyday home cooking use and broad supermarket shelf distribution.
- In June 2026, Symington Family Estates expanded international supermarket distribution of its mainstream Cockburn Fine Ruby expression across 3,200 European and North American grocery stores.
What are the drivers, restraints, and opportunities in the Port Wine Market?
In the Port Wine Market, protected appellation heritage and aged tawny gifting support demand, alcohol excise duties and moderation trends constrain volume, and ready-to-drink white port spritzes expand casual bar consumption through 2036.
- Driver: Protected Douro appellation status and rising consumer preference for age-indicated 10- and 20-year tawnies will continue to support premium bottle realizations through 2036.
- Restraint: Alcohol-strength excise duty escalations above 18% ABV and moderation among younger legal-age drinkers will continue to limit bulk volume growth through 2036.
- Opportunity: Formulating dry white and pink port expressions in single-serve cans and low-ABV aperitif spritzes is expected to open outdoor hospitality occasions through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Strict geographical indication rules and centuries-old wood maturation reserves give Douro port producers a defensible moat against generic fortified competitors. Hospitality buyers and fine wine collectors increasingly trade up from basic ruby blends to age-indicated ten-, twenty-, and thirty-year tawnies as well as single-harvest colheitas that display verified bottling dates. FMI data suggests that age-verified bottles generate substantially higher gross margins per liter than unaged bulk shipments. In May 2025, the European Commission Directorate-General for Agriculture and Rural Development confirmed that protected designation of origin wines commanded more than double the average export price of non-GI table wines across European Union customs registries. Sommeliers are also pairing chilled white and tawny ports with savoury charcuterie boards, extending consumption beyond traditional winter after-dinner service before restaurants lock in annual beverage lists.
Risk Assessment of the Port Wine Market: Operational and Formulation Friction
Steep alcohol-by-volume tax tiers and shifting health habits create persistent headwinds for traditional nineteen-to-twenty-percent ABV fortified wines. When governments index beverage excise duties directly to pure alcohol content, a 750ml bottle of port incurs a substantially heavier tax burden than a twelve-percent table wine or low-strength beer. In July 2025, the World Health Organization Regional Office for Europe reported that twenty-one member states had raised or indexed alcohol excise duties on high-strength alcoholic beverages between 2024 and 2025 to curb per-capita ethanol intake. Younger legal-age consumers also hesitate to buy full 750ml bottles of sweet dessert wine for small households. Lowering alcohol content below eighteen percent without forfeiting statutory Port appellation status remains legally restricted under Douro wine law, which delays low-ABV product launches.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Port shippers are capturing daytime terrace and cocktail lounge traffic by repackaging crisp dry white and rosé ports into single-serve 200ml bottles and 250ml aluminum cans mixed with tonic water. Single-serve packaging eliminates the oxidation waste of an unfinished 750ml bottle and lowers the entry price for solo shoppers experimenting with fortified aperitifs. In May 2025, a research study in the American Journal of Enology and Viticulture demonstrated that controlled micro-oxygenation and cold tartrate stabilization preserve primary muscat and floral esters in white fortified wines packaged in lined aluminum formats. Expanding alongside canned wine and botanical fruit wine spritzers lets Douro lodges win summer festival, airline, and hotel minibar listings once converters validate internal can liner integrity.
Port Wine Market by Country (2026 to 2036)
As per FMI, Japan represents the fastest-growing port wine market among the evaluated economies, recording a 4.6% CAGR from 2026 to 2036, while Germany posts the lowest expansion at 3.0% CAGR. Across all evaluated countries, commercial performance depends on how importers navigate ABV-linked excise tariffs, position aged tawnies in fine dining, and introduce refreshing white port serves.
Table 7: Country CAGR and Primary Growth Levers for the Port Wine Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Japan | 4.6% | High-end cocktail lounge mixology and department store demand for aged vintage tawnies |
| Mexico | 4.3% | Upscale gastronomic tourism and specialty liquor retail expansion across metropolitan hubs |
| South Africa | 4.0% | Domestic Cape Vintage winemaking heritage and cellar-door estate tourism growth |
| USA | 3.6% | Fourth-quarter holiday gift carton retail scale and urban white port cocktail adoption |
| Chile | 3.3% | Sommelier-led fine dining pairings and collector interest in imported European vintages |
| Germany | 3.0% | Established winter holiday consumption and specialist wine merchant demand for colheitas |
Source: Future Market Insights analysis
Japan Port Wine Market Outlook (2026 to 2036)
Bartenders in Tokyo, Osaka, and Kyoto are driving specialty fortified wine orders by using aged tawny and dry white ports as low-acidity modifiers in precision craft cocktails. Demand for port wine in Japan is predicted to advance at a 4.6% CAGR through 2036, supported by luxury gift-box sales in department stores such as Isetan and Takashimaya. In September 2025, Japan’s National Tax Agency reported that taxable imports of high-value European grape wines and fortified specialties rose 6.4% in fiscal 2024 as inbound hospitality spending recovered. Humid summer storage conditions and compact apartment kitchens still discourage Japanese households from storing full 750ml bottles. Importers consequently supply 375ml half-bottles and age-dated gift tubes that fit domestic gifting customs.
Key takeaway: In Japan, precision cocktail bar adoption and department-store luxury gifting sustain the fastest country growth rate for age-indicated port wines.
Mexico Port Wine Market Outlook (2026 to 2036)
The Mexico port wine sector is projected to record a 4.3% CAGR during the 2026 to 2036 assessment period, propelled by upscale resort hospitality in Cancún and Los Cabos alongside fine dining growth in Mexico City. Sommeliers increasingly pair ten-year tawny ports with mole negro and artisanal dark chocolate desserts. In July 2025, the Consejo Mexicano Vitivinícola reported that imported European specialty and fortified wine sales across Mexican hospitality venues expanded 7.8% over the preceding twelve months. However, ad-valorem IEPS alcohol taxes on beverages exceeding fourteen percent ABV raise landed shelf prices for imported vintage bottles. European shippers mitigate tariff pressure by supplying mid-tier reserve rubies through specialist chains such as La Europea and training resort beverage staff on by-the-glass preservation.
Key takeaway: In Mexico, resort gastronomy and specialist liquor retail expansion drive strong commercial uptake despite value-based alcohol tax hurdles.
South Africa Port Wine Market Outlook (2026 to 2036)
South Africa stands apart from pure import markets because Western Cape estates in Calitzdorp and Stellenbosch cultivate traditional Portuguese cultivars including Touriga Nacional, Tinta Barocca, and Souzão to produce domestic fortified styles. Sales in South Africa are forecast to expand at a 4.0% CAGR through 2036, underpinned by cellar-door tourism and competitive domestic pricing. In August 2025, South African Wine Industry Information and Systems documented that certified Cape Vintage and Cape Tawny fortified stocks accounted for 4.2 million liters of domestic cellar inventory. Strict European Union Bilateral Trade Agreement rules prohibit South African wineries from printing the word Port on domestic or export labels. Producers overcome this naming barrier by promoting the statutory Cape Port Producers Association classifications across wine competitions and retail shelves.
Key takeaway: In South Africa, indigenous Touriga Nacional plantings and established Cape Vintage classifications anchor resilient domestic and tourist demand.
USA Port Wine Market Outlook (2026 to 2036)
Between 2026 and 2036, the USA port wine market is expected to progress at a 3.6% CAGR, anchored by nationwide multistate liquor superstores and high-margin steakhouse dessert menus. American retail demand remains heavily concentrated between Thanksgiving and New Year’s Eve, when warehouse clubs and chains such as Total Wine & More stock multi-bottle gift packs. In June 2026, the U.S. Alcohol and Tobacco Tax and Trade Bureau reported that tax-paid withdrawals and imports of dessert and fortified wines over 16% ABV reached 11.8 million wine gallons in calendar year 2025. Three-tier state distribution rules and slower millennial purchasing of sweet after-dinner drinks still cap off-season velocity. Shippers counter seasonal dips by marketing canned white port spritzes and 375ml tawny bottles for year-round entertaining.
Key takeaway: In the USA, fourth-quarter superstore gifting and steakhouse by-the-glass programs provide the largest national revenue base while RTD spritzes address seasonal lulls.
Chile Port Wine Market Outlook (2026 to 2036)
Chilean fine wine collectors and hotel beverage directors in Santiago and Valparaíso are broadening their cellar lists beyond domestic Cabernet Sauvignon to include imported Douro colheitas and late-bottled vintages. Adoption of port wine in Chile is estimated to expand at a 3.3% CAGR through 2036, aided by European free-trade tariff preferences on bottled Portuguese appellations. In November 2025, Chile’s Servicio Agrícola y Ganadero and Wines of Chile noted that specialty imported wine registrations rose 5.1% in 2025 as urban wine boutiques expanded. Abundant domestic production of late-harvest dessert wines and pisco, combined with local boutique investments in wine processing equipment, creates stiff price competition in mass grocery aisles. Portuguese exporters focus on private wine clubs and culinary schools to secure premium placement.
Key takeaway: In Chile, duty-free European trade access and sommelier-curated wine clubs support steady demand for imported Douro age-dated ports.
Germany Port Wine Market Outlook (2026 to 2036)
Centuries of Hanseatic merchant trade and winter holiday traditions make Germany a mature, volume-stable European destination for Douro shippers, with the market projected to grow at a 3.0% CAGR from 2026 to 2036. German consumers purchase ruby and tawny ports heavily during Advent for both fireside drinking and festive baking. In December 2025, the Deutsches Weininstitut reported that specialist wine merchants (Weinfachhandel) increased average bottle realizations on imported fortified wines by 4.2% during the 2025 autumn-winter quarter despite flat grocery discount volume. Aggressive private-label price discounting by German hard discounters compresses margins on basic ruby blends. Historic Douro houses protect profitability by supplying certified organic ports and single-harvest colheitas exclusively to independent wine shops and gourmet department stores.
Key takeaway: In Germany, specialist wine merchant sales of certified organic and colheita ports offset intense price competition in discount supermarket aisles.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Port Wine Market?
Pernod Ricard SA, Suntory Holdings Limited, Symington Family Estates, and The Fladgate Partnership are the significant market players in this market.
As per the analysis from FMI, competition across the port wine industry divides into three operational groups based on vineyard ownership and distribution model. Family-owned Douro port houses control Grade-A schist-terrace quintas and hold millions of liters of aging wood-cask inventory in Vila Nova de Gaia, giving them command over vintage and age-indicated tawny categories. Multinational spirits and wine conglomerates use duty-free and hotel distribution networks to place fortified brands across international markets. Beverage brewers and RTD platform operators focus on canned wine spritzers and low-alcohol mixer formats. Retail buyers qualify suppliers on appellation certification, aged reserve continuity, and packaging innovation.
- Historic Port Lodges and Estate Families: Symington Family Estates and The Fladgate Partnership own classified Douro Valley vineyards and multi-decade tawny aging lodges.
- Global Premium Beverage Conglomerates: Pernod Ricard SA and Suntory Holdings Limited distribute fortified and fine wine labels across global hospitality channels.
Competitive Benchmarking: Port Wine Market
Table 8: Competitive Benchmarking for the Port Wine Market (qualitative capability ratings), 2026
| Company | Heritage Vineyard Breadth | Cask Aging Stock Depth | Global Hospitality Access | Geographic Reach |
|---|---|---|---|---|
| Pernod Ricard SA | High | High | High | High |
| Suntory Holdings Limited | High | High | High | High |
| Symington Family Estates | High | High | High | High |
| The Fladgate Partnership | High | High | High | High |
Key Developments in the Port Wine Market
- In April 2026, Symington Family Estates declared their 2024 Vintage Ports across Dow’s, Graham’s, Warre’s, Cockburn’s, Smith Woodhouse, and Quinta do Vesúvio — the first classic Vintage Port declaration from the family since 2017. The declaration covers nine expressions in total and reflects what the family’s head winemaker described as the most elegant Douro vintage in nearly a decade [1].
- In April 2026, Fladgate Family Wines (The Fladgate Partnership) declared 2024 Vintage Ports from Taylor’s, Fonseca, and Croft — the smallest release in the group’s history and the first tri-house declaration in seven years. The collection is anchored by Taylor’s Sentinels, a Pinhão Valley single-quinta blend introduced after the 2022 harvest, targeting ultra-premium on-trade and collector allocation channels [2].
- In July 2026, Taylor’s Port unveiled a redesigned bottle with a reduced environmental footprint, to be progressively introduced across its full range from July 2026 onward. The new bottle retains the house’s signature design elements while cutting material weight in line with The Fladgate Partnership’s sustainability commitments [3].
Key Players in the Port Wine Market
Historic Port Lodges and Estate Families
- Symington Family Estates
- The Fladgate Partnership
Global Premium Beverage Conglomerates
- Pernod Ricard SA
- Suntory Holdings Limited
Port Wine Market - Report Scope
Table 9: Report Scope for the Port Wine Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type / Variety; Packaging Format; Distribution Channel; Price Tier; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes producer and shipper wholesale revenue from certified port wines, fortified Cape/regional equivalents, and port-based ready-to-drink formats sold within the listed segmentation. Excludes unfortified table wines, culinary vinegar, and bulk neutral grape spirits sold outside the named market. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Japan, Mexico, South Africa, USA, Chile, Germany, and additional countries in the full report |
| Key Companies Covered | Pernod Ricard SA, Suntory Holdings Limited, Symington Family Estates, The Fladgate Partnership |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Port Wine Market - Research Methodology
Table 10: Research Methodology for the Port Wine Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with Douro estate master blenders, cellar masters, monopoly and retail wine buyers, hospitality sommeliers, and beverage trade directors to validate blend pricing, cask inventory turnover, and channel demand. |
| Secondary Research | Secondary research synthesized Instituto dos Vinhos do Douro e do Porto (IVDP) harvest and fortification declarations, OIV trade statistics, customs excise registries, corporate annual filings, and technical enology literature. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 period were developed using top-down and bottom-up material-balance models reconciling certified Douro grape must fortification quotas against bottled export shipments and retail realizations. |
| Data Triangulation and Validation | Data is validated against vineyard yield registries, maturing oak pipe inventories, country alcohol excise databases, and historical shipment trends to ensure arithmetic accuracy without double counting unfortified wine categories. |
Port Wine Market by Segments
Port Wine Market segmented by Product Type / Variety:
- Standard Classic Formulation
- Premium Craft & Artisanal
- Flavored / Infused Variant
- Low-Alcohol / Zero-ABV Line
Port Wine Market segmented by Packaging Format:
- Glass Bottles (750ml)
- Aluminum Cans & Single-Serve
- Bag-in-Box & Draught Kegs
Port Wine Market segmented by Distribution Channel:
- Off-Trade (Retail Supermarkets & Liquor Stores)
- On-Trade (Bars, Pubs & Restaurants)
- Direct-to-Consumer E-Commerce
Port Wine Market segmented by Price Tier:
- Mass Market / Mainstream
- Premium Tier
- Super-Premium & Luxury Vintage
Port Wine Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Portugal
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Israel
- Turkiye
Research Sources and Bibliography
- [1] International Organisation of Vine and Wine. (2026, May 16). State of the world wine sector in 2025: Production, consumption, and international trade flows. OIV Statistical Publications.
- [2] Instituto dos Vinhos do Douro e do Porto. (2025, February 22). Technical specifications, beneficio fortification quotas, and aging regulations for Douro fortified wines. IVDP Regulatory Monograph.
- [3] Instituto da Vinha e do Vinho. (2025, March 26). Portuguese wine export audit: Certified volume shipments by category and destination country. Sistema de Informacao da Vinha e do Vinho (SIVV).
- [4] European Container Glass Federation (FEVE). (2025, April 20). Packaging sustainability, furnace decarbonization, and UV barrier integrity in wine bottling. FEVE Environmental Technical Monograph, 2025-04.
- [5] Wine and Spirit Trade Association. (2025, May 15). Fortified and dessert wine retail performance in modern off-trade supermarket channels. WSTA Market Report, 2025-05.
- [6] Symington Family Estates. (2026, June 16). International grocery retail distribution expansion for mainstream ruby port portfolio. Symington Corporate Press Releases.
- [7] European Commission Directorate-General for Agriculture and Rural Development. (2025, May 14). Economic value and export price premiums of European Union Geographical Indications in the wine sector. DG AGRI Agricultural Market Briefs, 2025(2), 18-34.
- [8] World Health Organization Regional Office for Europe. (2025, July 19). Alcohol excise tax indexing and ABV threshold policy review across European member states. WHO European Alcohol Policy Series, 2025-07.
- [9] American Journal of Enology and Viticulture. (2025, May 12). Influence of micro-oxygenation and tartrate stabilization on white fortified wines in single-serve aluminum formats. AJEV Research Articles, 76(2), 114-129.
- [10] National Tax Agency of Japan. (2025, September 20). Annual liquor taxation report: Imported European wine and fortified specialty consumption trends. NTA Statistical Publication, 2025-09.
- [11] Consejo Mexicano Vitivinicola (CMV). (2025, July 28). Gastronomic tourism and imported specialty fortified wine consumption across Mexican hospitality venues. CMV Industry Bulletin, 2025-07.
- [12] South African Wine Industry Information and Systems (SAWIS). (2025, August 24). Certified Cape Vintage and fortified wine cellar inventory statistics. SAWIS Annual Statistical Review, 2025-08.
- [13] Alcohol and Tobacco Tax and Trade Bureau. (2026, June 29). Wine statistical release: Tax-paid withdrawals and imports of dessert and fortified wines over 16% ABV. U.S. Department of the Treasury TTB Wine Statistics.
- [14] Servicio Agricola y Ganadero & Wines of Chile. (2025, November 28). Domestic fine wine retail and imported European specialty beverage registration overview. Wines of Chile Sector Review, 2025-11.
- [15] Deutsches Weininstitut (DWI). (2025, December 14). Consumer spending on imported dessert and fortified wines in German specialist wine trade. DWI Statistical Bulletin, 2025-12.
- [16] Symington Family Estates. (2026, March 24). Commissioning of LEED-certified low-impact Quinta do Ataide winery in the Douro Superior. Viticultural Engineering Releases.
- [17] The Fladgate Partnership. (2026, January 20). Commercial rollout of Taylor Fladgate Chip Dry & Tonic in recyclable aluminum cans across European retail. Fladgate Product Launch Releases.
- [18] Suntory Holdings Limited. (2025, August 22). Luxury hospitality allocation expansion for aged tawny ports across Japanese five-star hotel lounges. Suntory Corporate Media Updates.
- [19] Pernod Ricard SA. (2026, April 20). Digital cellar tracking and heritage aperitif portfolio modernization in European fortified wines. Pernod Ricard Corporate Whitepapers.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the port wine market in 2026 and what is forecast for 2036?
- Which hospitality and mixology trends support demand for port wine?
- Why does Standard Classic Formulation lead the product type / variety category?
- Why do glass bottles (750ml) lead the packaging format category globally?
- How do growth rates differ across Japan, Mexico, South Africa, the USA, Chile, and Germany?
- Which leading companies supply certified Douro port and fortified wine categories today?
- What limits volume adoption or low-ABV reformulation in the port wine market?
- What should retail and hospitality wine buyers evaluate before purchasing port wine lines?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type / Variety, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type / Variety, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type / Variety, 2026 to 2036
- Standard Classic Formulation
- Premium Craft & Artisanal
- Flavored / Infused Variant
- Low-Alcohol / Zero-ABV Line
- Y-o-Y Growth Trend Analysis By Product Type / Variety, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type / Variety, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Glass Bottles (750ml)
- Aluminum Cans & Single-Serve
- Bag-in-Box & Draught Kegs
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Off-Trade (Retail Supermarkets & Liquor Stores)
- On-Trade (Bars, Pubs & Restaurants)
- Direct-to-Consumer E-Commerce
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Price Tier, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Price Tier, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Price Tier, 2026 to 2036
- Mass Market / Mainstream
- Premium Tier
- Super-Premium & Luxury Vintage
- Y-o-Y Growth Trend Analysis By Price Tier, 2021 to 2025
- Absolute $ Opportunity Analysis By Price Tier, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Portugal
- Nordics
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Israel
- Turkiye
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Pernod Ricard SA
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Suntory Holdings Limited
- Symington Family Estates
- The Fladgate Partnership
- Pernod Ricard SA
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type / Variety, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Product Type / Variety, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Product Type / Variety, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Billion) Forecast by Product Type / Variety, 2021 to 2036
- Table 18: Western Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Billion) Forecast by Product Type / Variety, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 26: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Billion) Forecast by Product Type / Variety, 2021 to 2036
- Table 28: East Asia Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 29: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 30: East Asia Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type / Variety, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Billion) Forecast by Product Type / Variety, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type / Variety, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type / Variety, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type / Variety
- Figure 6: Global Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Packaging Format
- Figure 9: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Distribution Channel
- Figure 12: Global Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Price Tier
- Figure 15: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Product Type / Variety, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Product Type / Variety, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Product Type / Variety
- Figure 29: North America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Packaging Format
- Figure 32: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Distribution Channel
- Figure 35: North America Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Price Tier
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Product Type / Variety, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Product Type / Variety, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Product Type / Variety
- Figure 42: Latin America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Packaging Format
- Figure 45: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 48: Latin America Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Price Tier
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Product Type / Variety, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Product Type / Variety, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Product Type / Variety
- Figure 55: Western Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by Packaging Format
- Figure 58: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 61: Western Europe Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Price Tier
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Product Type / Variety, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Product Type / Variety, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Product Type / Variety
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by Packaging Format
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by Price Tier
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Product Type / Variety, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Product Type / Variety, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Product Type / Variety
- Figure 81: East Asia Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by Packaging Format
- Figure 84: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 87: East Asia Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by Price Tier
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by Product Type / Variety, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type / Variety, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by Product Type / Variety
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by Packaging Format
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by Price Tier
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by Product Type / Variety, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type / Variety, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by Product Type / Variety
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by Packaging Format
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by Price Tier
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Port Wine Market in 2026, and what is forecast for 2036?
The global port wine market is estimated to reach USD 1.3 billion in 2026. Industry revenue is projected to expand further and reach USD 1.9 billion by 2036.
What is the CAGR for the Port Wine Market from 2026 to 2036?
As per FMI, the port wine market is projected to grow at a 3.8% CAGR from 2026 to 2036. Expansion is supported by trade-up into age-indicated tawny ports and white port aperitif mixology.
Which product variety segment holds a notable port wine demand share in 2026?
Standard Classic Formulation is projected to hold 35.3% of product type / variety demand in 2026. The segment benefits from consistent multi-vintage ruby and tawny flavour profiles and approachable supermarket shelf pricing.
Which packaging segment holds a notable port wine share in 2026?
Glass bottles (750ml) are estimated to account for 53.2% of packaging format demand in 2026. Demand is underpinned by zero oxygen permeability, UV light protection, and traditional gift box presentation.
Which country has a notable port wine expansion outlook during the forecast period?
FMI finds that Japan is projected to expand at a 4.6% CAGR during the 2026 to 2036 assessment period. Growth is supported by craft cocktail bar adoption and high department-store demand for aged vintages.
Which companies are active in the Port Wine Market during 2026?
Notable companies active in the market include Pernod Ricard SA, Constellation Brands, Inc., Keurig Dr Pepper Inc., Suntory Holdings Limited, Molson Coors Beverage Company, Anheuser-Busch InBev, Symington Family Estates, and The Fladgate Partnership. These participants focus on sustainable Douro viticulture, multi-decade oak pipe aging, and convenient ready-to-drink spritz formats.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
