
- Market Size (2026)
- USD 218.9 Mn
- Forecast (2036)
- USD 1185.1 Mn
- CAGR (2026 to 2036)
- 18.4%
How big is Portable Monitor Market in 2026?
The global portable monitor market is estimated at USD 184.9 million in 2025 and is expected to reach USD 218.9 million in 2026. By 2036, the market is projected to reach USD 1,185.1 million, expanding at a CAGR of 18.4% from 2026. Above 20-inch screens will hold the largest share of screen size sales in 2026, at 38.8%, as per FMI analysis.
In April 2025, hybrid work in the United States was holding steady, which keeps a second screen in many laptop bags. According to the Bureau of Labor Statistics, 20.8% of private industry workers teleworked that month, against 20.4% a year earlier. Consequently, display brands have a steady pool of mobile workers who replace a second screen every few years. Demand for portable monitors also rises with handheld gaming, as players want a larger picture at home or on the road. Sales of compact screens have a large console base to draw on. Recent figures confirm this, as Nintendo sold 17.37 million Switch 2 consoles between April and December 2025. Adoption of single-cable screens is growing as laptop makers sell displays that also charge the notebook. Evidence of this comes from Lenovo, which listed the ThinkVision L16a in September 2026, a 16-inch portable monitor with two USB-C ports and up to 65 W of power delivery. FMI analysis expects laptop brands to turn such screens into an easy add-on at the point of sale.
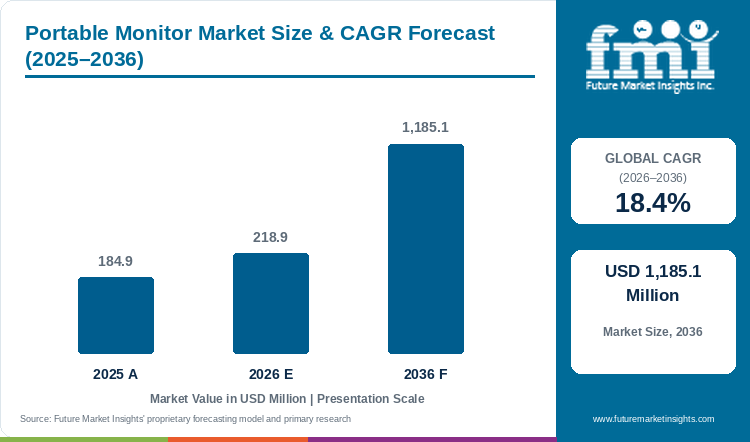
Table 1: Portable Monitor Market Size and Forecast (USD million), 2025 to 2036
| Market size and forecast | Value |
|---|---|
| 2025 market size | USD 184.9 million |
| Estimated market size in 2026 | USD 218.9 million |
| Projected market size by 2036 | USD 1,185.1 million |
| CAGR (2026 to 2036) | 18.4% |
| Added sales, 2026 to 2036 | USD 966.2 million |
Key Market Trends & Insights
- By screen size: Above 20-inch screens are estimated at 38.8% of 2026 sales, as home users pick the largest panel that still packs flat into a bag.
- By screen type: At 68.5% of screen type sales in 2026, LED-backlit panels lead the category, since thin edge-lit designs keep weight down and run on USB power alone.
- By connectivity type: One USB-C cable can carry video, data and power from the host device, so USB connections are likely to account for 57.4% of connectivity sales in 2026.
Regional Highlights
- Fastest-growing country: China is set to grow fastest, at 23.6% a year from 2026 to 2036, as local laptop and gaming brands bundle USB-C screens.
- Growth across other countries: India is set to expand at 21.3%, with the United Kingdom at 19.6% and the United States at 18.9%. South Korea is projected at 18.6%, as local brands get early access to new panels. Germany is likely to grow at 17.4% as more staff return to offices, and Japan is slowest at 16.8%, since many buyers there already own a portable screen.
The panel sets the minimum cost of every portable display, and the large Korean panel makers are shifting output away from mid-sized LCD. Supply of mid-sized LCD is falling, as LG Display reported third-quarter 2026 sales of KRW 6,277 billion, 10% lower than a year earlier, reflecting lower shipments of mid-sized LCD products. Fewer mid-sized LCD panels from Korean fabs leave portable monitor brands more reliant on Taiwanese and Chinese suppliers for 14-inch to 18-inch glass. On the Taiwanese side, AUO Corporation reported March 2026 consolidated sales of NT$26.02 billion, up 26.9% from February and 0.6% from March 2025. Flat year-on-year sales at AUO point to steady panel availability, so component costs stay predictable for brands planning 2026 launches.
Most portable displays are sold as an add-on to a new notebook, so orders move in step with the laptop cycle. Sales of notebooks are rising fast, as Lenovo reported first-quarter 2026/27 Group sales of US$26.9 billion, up 43%, and Intelligent Devices Group sales of US$17.1 billion, up 27%. Faster notebook sales widen the pool of buyers offered a matching portable screen at checkout. In addition, Lenovo global PC market share reached 24.2%, and AI PC share increased to 25.1%. Laptop volume is concentrated in a few brands, which gives those brands more say over which portable monitors reach corporate buyers. As a result, independent accessory makers face a higher bar in enterprise tenders.
Regulation is steering the cable side of the category toward USB-C, and use of a single connector is spreading. Adoption of USB-C charging extends to laptops from 28 April 2026 under EU common charger rules, the European Commission said in December 2024. A USB-C port on every new laptop sold in the EU removes the adapter that older HDMI-only portable screens needed, which favours single-cable designs. The Commission also expects the rules to save consumers about €250 million a year on unnecessary charger purchases. With fewer chargers and adapters to carry, buyers have more reason to choose displays that draw power and signal from one port. Product launches point the same way, and the Lenovo ThinkVision L16a pairs a 1,920 x 1,200 IPS panel with two USB-C ports. Dual ports let one cable feed both laptop and display, so a portable screen becomes usable at a hot desk with a single wall socket.
Table 2: Supporting Industry Indicators for the Portable Monitor Market, 2024 to 2026
| Indicator | Data point | Why it matters | Source |
|---|---|---|---|
| Private sector telework, United States | 20.8% of private industry workers teleworked in April 2025, against 20.4% a year earlier. | A steady remote-work base keeps second-screen purchases recurring. | |
| Federal telework, United States | 18.2% of federal government workers teleworked in April 2025, down from 31.3%. | Office return in the public sector shrinks one group of home-office buyers. | |
| Remote work, European Union | 8.8% of EU employees worked from home in 2025, with Finland at 20.5% and Ireland at 19.2%. | A lower European remote-work base points to office and travel use cases. | |
| Handheld console sales | Nintendo sold 17.37 million Switch 2 units from April to December 2025. | A larger console base widens gaming use of portable screens. | |
| Laptop maker sales | Lenovo Intelligent Devices Group sales reached US$17.1 billion in the quarter to June 2026, up 27%. | Notebook sales set the attach base for portable displays. | |
| PC market position | Lenovo global PC share reached 24.2%, and AI PC share reached 25.1%. | A few laptop brands control the bundle offered to corporate buyers. | |
| Panel maker sales, Korea | LG Display third-quarter 2026 sales fell 10% to KRW 6,277 billion on lower mid-sized LCD shipments. | Less mid-sized LCD output shifts sourcing toward other panel makers. | |
| Panel maker sales, Taiwan | AUO March 2026 consolidated sales reached NT$26.02 billion, up 0.6% year on year. | Stable panel sales point to steady supply for portable screens. | |
| Charger regulation | EU USB-C charging rules extend to laptops from 28 April 2026. | A common port favours single-cable portable displays. | |
| Product launch | Lenovo listed the 16-inch ThinkVision L16a in September 2026 with two USB-C ports and up to 65 W power delivery. | Pass-through charging reduces setup friction for buyers. |
Demand Intensity Analysis
Key drivers of the portable monitor market include laptop sales, and laptop sales also offer the closest outside benchmark, as nearly every portable monitor connects to a notebook. Lenovo reported Intelligent Devices Group sales of US$17.1 billion for the quarter to June 2026. Measured against that one quarter, the 2026 portable monitor estimate of USD 218.9 million is only about 1.3% of Lenovo device sales. Scope differs sharply, since the Lenovo figure covers PCs, tablets, smartphones and accessories from one company over three months. Even so, the small ratio shows that portable monitors remain a niche accessory, which leaves room for attach rates to rise as more laptops ship with USB-C video output.
Console volumes give a second reference point, given that gamers form the other large buyer group. Nintendo sold 17.37 million Switch 2 units between April and December 2025. Set against the 2025 market estimate of USD 184.9 million, that console volume equals about USD 10.6 of portable monitor sales per Switch 2 unit sold. Above 20-inch screens, at 38.8% of 2026 sales or about USD 84.9 million, equal roughly USD 4.9 per console. Only a small share of console owners buy a separate screen, so the comparison points to a large pool of unconverted gaming users.
Growth assumptions look demanding when set against the US labour data on remote work. The US private industry telework rate rose only from 20.4% to 20.8% over the year to April 2025, an increase of 0.4 percentage points. An 18.4% CAGR through 2036 therefore depends on more units per remote worker, larger screen sizes and better panels, as the number of remote workers alone barely changes. Lenovo device sales grew 27% in one quarter, which shows that the laptop channel can carry that mix shift. Suppliers with bundling deals therefore stand to gain most from the forecast.
Table 3: Demand Intensity Metrics for the Portable Monitor Market, 2025 and 2026 Data Against 2025 and 2026 Market Values
| Demand intensity metric | Value | Basis |
|---|---|---|
| Lenovo Intelligent Devices Group sales, quarter to June 2026 | US$17.1 billion | Lenovo Group, first-quarter 2026/27 results |
| 2026 market value as a share of one quarter of Lenovo device sales | About 1.3% | Calculated from Lenovo Group results and the 2026 market value |
| Nintendo Switch 2 units sold, April to December 2025 | 17.37 million | Nintendo, third-quarter fiscal 2026 explanatory material |
| Market value per Switch 2 unit sold | About USD 10.6 | Calculated from Nintendo unit sales and the 2025 market value |
| Above 20-inch segment value per Switch 2 unit sold | About USD 4.9 | Calculated from Nintendo unit sales and the 2026 segment value |
| US private industry telework rate, April 2025 | 20.8% | U.S. Bureau of Labor Statistics, Current Population Survey |
| Change in US private industry telework rate over one year | 0.4 percentage points | Calculated from Bureau of Labor Statistics rates for April 2024 and April 2025 |
| EU employees working from home, 2025 | 8.8% | Eurostat figures reported by Romania Insider |
Analyst Perspective
“Portable monitors are moving from a gadget bought by travellers to a standard item in the hybrid work kit, and the single USB-C cable is the reason. The brands that sell the laptop are best placed to sell the second screen, so I expect bundling deals to decide share more than panel specifications. Specialists will hold the gaming and creative niches, in which colour, refresh rate and size still matter to buyers.”
- Sudip saha, Principal Consultant, Future Market Insights.
How is the portable monitor market segmented?
The market is segmented into screen size, screen type, connectivity type, and region. Above 20-inch screens are expected to lead screen size with 38.8% share in 2026, and LED panels lead screen type with an estimated 68.5%.
By screen size: under 14 inch, 14 to 20 inch, and above 20 inch.
By screen type: LED and LCD.
By connectivity type: USB, HDMI, and VGA.
By region: home, office and travel buyers across North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do above 20-inch screens lead portable monitor sales by screen size?
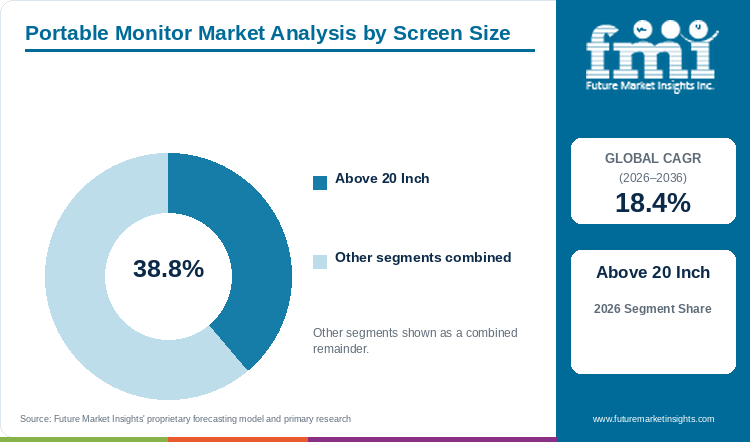
Above 20-inch screens are expected to lead screen size sales with 38.8% share in 2026, ahead of 14 to 20 inch screens at an estimated 35.6%.
Table 4: Screen Size Share for the Portable Monitor Market (percentage share), 2026
| Screen Size | Estimated Share (2026) |
|---|---|
| Above 20 Inch | 38.8% |
| 14 to 20 Inch | 35.6% |
| Under 14 Inch | 25.6% |
| Total | 100.0% |
Table 5: Screen Size Leadership and Market Growth for the Portable Monitor Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 18.4% |
| Leading Segment | Above 20 Inch |
Buyers who use a portable screen as the main display at home want desktop-class size without a fixed stand, so FMI places above 20-inch units at 38.8% of 2026 sales. The 14 to 20 inch band, at an estimated 35.6%, suits travellers who pair a 15-inch or 16-inch laptop with a screen of matching height. Under 14 inch models, near 25.6%, serve handheld consoles and phones, for which weight counts more than area. Panel supply shapes this mix, and LG Display reported lower shipments of mid-sized LCD products in the third quarter of 2026. Tighter mid-sized supply from Korea pushes brands toward larger glass from other fabs, which supports the upper size band. Larger screens are likely to keep the lead through 2036, as home offices settle into permanent two-screen setups.
- Folding-stand 21.5-inch and 24-inch displays, plus large touch models for creative work, make up the above 20-inch group.
- Gaming buyers favour bigger screens for living-room play, and Nintendo sold 17.37 million Switch 2 consoles from April to December 2025. A wider console base adds docked and travel players who want a larger picture than the handheld offers.
Why do LED panels lead portable monitor sales by screen type?
LED panels are expected to lead screen type sales with 68.5% share in 2026, ahead of LCD panels at an estimated 31.5%.
Table 6: Screen Type Share for the Portable Monitor Market (percentage share), 2026
| Screen Type | Estimated Share (2026) |
|---|---|
| LED | 68.5% |
| LCD | 31.5% |
| Total | 100.0% |
Popularity of thin LED-backlit designs comes from low power draw and a weight close to a tablet, so LED panels are estimated at 68.5% of 2026 screen type sales in the FMI breakdown. Conventional LCD units, at about 31.5%, compete on price in entry models sold through online marketplaces. Panel makers are moving output toward OLED and other premium screens. LG Display said third-quarter 2026 sales rose 12% from the prior quarter on higher shipments of large-sized and mobile OLED products. More OLED and premium LED capacity gives portable brands better, lighter panels. OLED demand is growing across devices, and the OLED display market is forecast to expand by 20.1% a year from 2026 to 2036. LED models will hold the lead, as battery-powered laptops cannot spare much power for a second screen.
- Edge-lit LED, mini-LED and OLED-based portable screens make up the LED group.
- Panel sourcing in Taiwan remains steady, as AUO reported March 2026 consolidated sales of NT$26.02 billion, up 0.6% year on year. Stable panel output keeps LED portable screens available at predictable cost through 2026 launch cycles.
Why do USB connections lead portable monitor sales by connectivity type?
USB designs that need only one cable are expected to take 57.4% of connectivity type sales in 2026, ahead of HDMI at an estimated 34.2% and legacy VGA ports at 8.4%.
Table 7: Connectivity Type Share for the Portable Monitor Market (percentage share), 2026
| Connectivity Type | Estimated Share (2026) |
|---|---|
| USB | 57.4% |
| HDMI | 34.2% |
| VGA | 8.4% |
| Total | 100.0% |
A single USB-C link carries video, data and power, so FMI estimates USB connections at 57.4% of 2026 connectivity sales, the largest group by a wide margin. HDMI, at about 34.2%, remains the default for consoles and older laptops, and VGA, near 8.4%, survives in legacy industrial and point-of-sale setups. Regulation strengthens the USB lead, as from 28 April 2026 EU common charger rules extend USB-C charging to laptops, the European Commission said. Every new EU laptop with a USB-C port becomes a ready host for a single-cable display. In line with this, the USB Type C market is forecast to grow at a 15.4% CAGR between 2025 and 2035. Docks and hubs still bridge older ports, with the docking station market set to expand at a 6.1% CAGR over 2025 to 2035. USB will widen the gap through 2036, as HDMI-only laptops leave service.
- USB-C with DisplayPort Alt Mode, USB-C with power pass-through and USB-A DisplayLink models make up the USB group.
- Laptop makers now design screens around dual USB-C ports, and Lenovo listed the ThinkVision L16a with two USB-C ports in September 2026. Two ports let the display pass power to the laptop, which removes a second charger from the desk.
What are the drivers, restraints, and opportunities in the portable monitor market?
Hybrid work and handheld gaming keep adding buyers who want a second screen on the move. Office return policies and panel price swings hold back some orders, and a common USB-C port on laptops opens room for single-cable displays.
- Driver: Office staff who split the week between home and the office carry a light second screen, and gamers add a larger display to handheld consoles.
- Restraint: Return-to-office policies cut the home-office pool in some sectors, and swings in panel supply can raise unit costs for smaller brands.
- Opportunity: A single USB-C port on new laptops makes one-cable displays easy to sell as a bundle with each notebook.
Hybrid Work and Handheld Gaming Expand the Buyer Pool
Every worker who no longer works at one fixed desk is a potential buyer, and hybrid schedules drive most first purchases. Use of home offices stays steady, as the share of US private industry workers who teleworked reached 20.8% in April 2025, according to the Bureau of Labor Statistics. A stable remote-work base keeps replacement cycles regular, as each worker who upgrades a laptop tends to refresh the second screen too. Remote work in Europe is lower, as 8.8% of EU employees worked from home in 2025, with Finland at 20.5%. Lower European rates point suppliers toward office hot desks and business travel. Keyboards show the same accessory pull, with the computer keyboard market expected to grow at a 3.6% CAGR between 2025 and 2035. Hybrid work will remain the largest source of new buyers through 2036.
Office Return and Panel Swings Restrain Orders
Producers of portable displays lose some public sector demand as agencies call staff back to offices. Federal telework in the United States fell to 18.2% in April 2025, from 31.3% a year earlier. Fewer home-office days cut the need for a travel screen among public sector staff and contractors. Panel supply adds a second risk, as LG Display sales fell 10% year on year in the third quarter of 2026 on lower mid-sized LCD shipments. Smaller brands without long-term panel contracts face higher unit costs when mid-sized output shrinks, so price competition favours brands with scale.
USB-C Laptops Open Bundling Room
Laptop bundles increasingly decide growth of the portable monitor market, since a matching screen offered at checkout converts far better than a separate accessory search. Buyers of notebooks are returning, as Lenovo reported Intelligent Devices Group sales of US$17.1 billion in the quarter to June 2026, up 27%. Rising notebook volume gives laptop brands more chances to attach a second screen. Gaming laptops add a premium version of the same bundle, with the gaming laptop market projected to grow at a 4.2% CAGR from 2025 to 2035. EU charger rules also make USB-C standard on new laptops from April 2026. Brands that pair laptops and screens under one warranty will win a larger share of corporate refresh budgets.
Which country CAGRs are profiled in the portable monitor market?
Table 8: Country CAGR Comparison for the Portable Monitor Market (CAGR percentage), 2026 to 2036
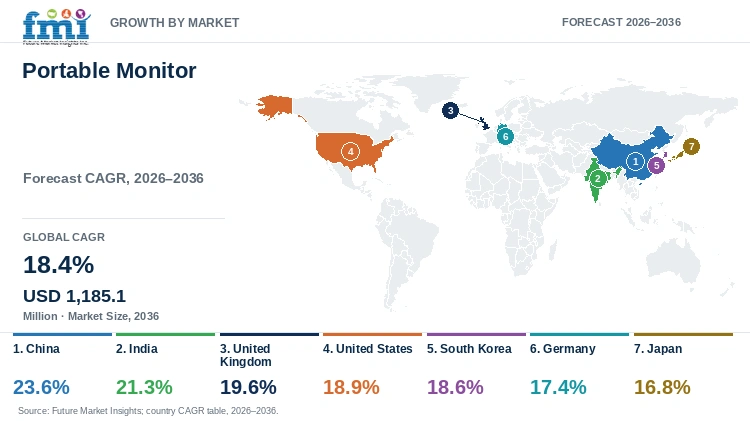
| Country | CAGR |
|---|---|
| China | 23.6% |
| India | 21.3% |
| United Kingdom | 19.6% |
| United States | 18.9% |
| South Korea | 18.6% |
| Germany | 17.4% |
| Japan | 16.8% |
How do country-level CAGRs compare in the portable monitor market?
China leads the FMI country table at 23.6%, 5.2 points above the 18.4% global rate, as local laptop, tablet and console brands sell screens through large online marketplaces. India is next at 21.3%, and the United Kingdom, at 19.6%, also runs ahead of the global pace. Rates for the United States (18.9%) and South Korea (18.6%) land close to the 18.4% average. Germany, at 17.4%, and Japan, at 16.8%, fall below the global rate, as office return and a mature accessory base slow new purchases. The 6.8-point gap between China and Japan shows that emerging laptop markets add buyers faster than mature remote-work markets.
- In China, domestic laptop brands sell portable screens in the same online listing as the notebook, which lowers the purchase barrier and gives local panel suppliers steady orders.
- Rising laptop ownership among students and IT staff in India creates first-time second-screen buyers, so low-cost USB-C models will find the widest audience there.
- British hybrid workers split time between home and city offices, and that pattern keeps demand for light travel screens above the global pace.
- Remote work in the United States has settled at a stable rate, which shifts orders toward replacement and premium sizes over first purchases.
- Korean panel makers are reshaping LCD output, so South Korean brands gain early access to OLED and premium panels for local portable screens.
- German offices have called more staff back, which slows home-office demand and steers suppliers toward business travel and engineering users.
- Japan has a mature accessory base and high console ownership, so growth depends on gaming and replacement buyers more than on new office users.
Full report country CAGRs cover: seven profiled rates ranging from 16.8% in Japan to 23.6% in China, with other standard countries listed in the regional tables.
Country-wise Analysis
China Portable Monitor Market Outlook (2026 to 2036)
Chinese laptop brands are gaining global scale and use that reach to sell accessories at home. Lenovo global PC market share reached 24.2% in the quarter to June 2026. A large domestic laptop maker can place a matching portable screen in front of each notebook buyer, which builds volume for local display suppliers. Sales of portable monitors in China will grow at a 23.6% CAGR, the highest in the profiled set, as online bundles reach smaller cities.
Key takeaway: Chinese buyers will purchase most portable screens together with a new laptop or console on large online marketplaces, which keeps China ahead of every other country.
India Portable Monitor Market Outlook (2026 to 2036)
India adds young IT and services workers each year, and many of them work across home and office on a single laptop. Price-sensitive buyers favour 15-inch and 16-inch USB-C screens sold online, which keeps entry prices low. Demand for portable monitors in India is forecast to grow at a 21.3% CAGR, well above the global rate, as first-time buyers enter the category.
Key takeaway: Students and IT workers in India buying a second screen for the first time will choose low-cost USB-C models sold online.
United Kingdom Portable Monitor Market Outlook (2026 to 2036)
British employers have settled on hybrid schedules, and staff commonly carry a laptop between home and a shared desk in the office. A travel screen gives these workers a two-screen setup in both places without a second fixed monitor. The United Kingdom is projected to grow at a 19.6% CAGR, above the global pace, as hybrid schedules spread to mid-sized firms.
Key takeaway: British office staff who move between home and shared desks will keep buying light travel screens, so the United Kingdom grows faster than average.
United States Portable Monitor Market Outlook (2026 to 2036)
Remote work in the United States has stabilised after the post-pandemic shifts. In April 2025, 20.8% of private industry workers teleworked, against 20.4% a year earlier. A steady base of remote workers turns the US market toward replacement, larger screens and gaming use. Portable monitor sales in the United States will grow at an 18.9% CAGR, slightly above the global rate, with premium sizes gaining.
Key takeaway: Most American buyers already own a portable screen, so US sales will come mainly from replacements and from upgrades to larger premium models.
South Korea Portable Monitor Market Outlook (2026 to 2036)
South Korea hosts major panel production, which gives local brands short supply lines. LG Display reported third-quarter 2026 sales of KRW 6,277 billion as output shifted toward OLED. Local brands gain early access to premium panels, which supports high-specification portable screens for gaming and design work. South Korea is likely to grow at an 18.6% CAGR, close to the global pace, as premium models replace basic LCD units.
Key takeaway: Sales of premium portable screens in South Korea will benefit from local panel makers, which give Korean brands early access to OLED and high-end panels.
Germany Portable Monitor Market Outlook (2026 to 2036)
German employers have brought more staff back to the office, so new demand comes mainly from engineers, sales staff and business travellers. EU charger rules extend USB-C charging to laptops from 28 April 2026, according to the European Commission. A common port on new German laptops favours one-cable screens, and FMI projects Germany at a 17.4% CAGR, below the global rate.
Key takeaway: German sales will come mostly from business travellers and buyers of new USB-C laptops, though the return to offices keeps growth below the global rate.
Japan Portable Monitor Market Outlook (2026 to 2036)
Console gaming is a large hobby in Japan, and handheld play keeps compact screens in demand. Nintendo sold 17.37 million Switch 2 units between April and December 2025. Each docked or travelling player is a candidate for a second screen, which adds steady demand for compact models. A mature accessory base still slows new purchases, and FMI forecasts Japan at a 16.8% CAGR, the lowest in the table.
Key takeaway: Japanese gamers will keep buying compact screens for handheld consoles, but most office users already own one, so growth stays below average.
Who are the notable companies in the portable monitor market?
Ten companies are profiled across laptop brands, display makers and portable specialists. Lenovo, Dell, HP, Acer and ASUS sell laptops, LG Electronics, ViewSonic and AOC make displays, and Gaems and GeChic focus on gaming and travel screens.
Laptop brands, display specialists and portable-screen niche players compete for the same buyer, and the laptop brands hold the strongest channel. Lenovo reported Intelligent Devices Group sales of US$17.1 billion in the quarter to June 2026, up 27%. Scale in notebooks gives Lenovo, Dell, HP, Acer and ASUS a direct route to attach portable screens in corporate refresh deals. Display specialists such as LG Electronics, ViewSonic and AOC compete on panel range and price, and Gaems and GeChic focus on gaming and travel niches. Bundling strength is likely to decide share among the laptop brands through 2036.
- Laptop and PC brands that bundle screens with notebook refresh deals: Lenovo, Dell, HP, Acer and ASUS.
- Display specialists selling on panel range and price: LG Electronics, ViewSonic and AOC.
- Portable and gaming specialists designing for consoles and travel: Gaems and GeChic.
Competitive Benchmarking: Portable Monitor Market
Table 9: Competitive Benchmarking for the Portable Monitor Market (qualitative ratings), 2026
| Company | Laptop Bundling | Panel Range | Gaming Focus | Recent Activity |
|---|---|---|---|---|
| Lenovo | High | Medium | Medium | High |
| ASUS | High | High | High | Medium |
| Dell | High | Medium | Low | Medium |
| HP | High | Medium | Low | Medium |
| LG Electronics | Low | High | Medium | Medium |
| ViewSonic | Low | High | Medium | Low |
| GeChic | Low | Medium | Medium | Low |
Ratings compare the companies on laptop bundling, panel range, gaming focus and recent activity.
Key Developments in the Portable Monitor Market
- Lenovo listed the 16-inch ThinkVision L16a with two USB-C ports and up to 65 W power delivery in September 2026. Dual-port pass-through charging makes the screen an easy add-on in laptop refresh deals.
- Third-quarter 2026 sales at LG Display fell 10% to KRW 6,277 billion on lower mid-sized LCD shipments, the company said on 22 October 2026. Less mid-sized LCD output pushes portable brands toward other panel sources.
- In August 2026, Lenovo reported Intelligent Devices Group sales of US$17.1 billion for the June quarter, up 27%. Faster notebook sales widen the attach base for portable displays.
- AUO Corporation reported March 2026 consolidated sales of NT$26.02 billion in April 2026, up 0.6% year on year. Steady panel sales point to stable supply for 14-inch to 18-inch screens.
- Nintendo reported in February 2026 that Switch 2 sales reached 17.37 million units for April to December 2025. A fast-growing console base adds gaming buyers for compact screens.
- On 28 December 2024, the European Commission confirmed that USB-C charging rules extend to laptops from 28 April 2026. One connector across devices strengthens the case for single-cable portable display designs.
Key Players in the Portable Monitor Market
Laptop and PC Brands
- Lenovo
- Dell
- HP
- Acer
- ASUS
Display Specialists
- LG Electronics
- ViewSonic
- AOC
Portable and Gaming Specialists
- Gaems
- GeChic
Portable Monitor Market - Report Scope
Table 10: Report Scope for the Portable Monitor Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Screen size; screen type; connectivity type; region |
| Quantitative units | USD million |
| Market definition | Lightweight external displays powered and fed by a laptop, tablet, phone or console through USB, HDMI or VGA, used as a second screen for work, gaming and travel. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | China; India; United Kingdom; United States; South Korea; Germany; Japan |
| Key companies profiled | ASUS, Lenovo, Dell, HP, Acer, LG Electronics, ViewSonic, AOC, Gaems, GeChic |
| Forecast period | 2026 to 2036 |
Portable Monitor Market - Research Methodology
Table 11: Research Methodology for the Portable Monitor Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Company results, industry associations, government statistics and trade publications. |
| Desk Research | Screen sizes, panel technologies, connectivity standards, hybrid work patterns and gaming device sales. |
| Market Sizing | Market value is built from unit demand and average selling prices across screen sizes and regions. |
| Data Validation | Figures are cross-checked across company, industry and government sources. |
Portable Monitor Market by Segments
Portable Monitor Market segmented by Screen Size:
- Under 14 Inch
- 14 to 20 Inch
- Above 20 Inch
Portable Monitor Market segmented by Screen Type:
- LED
- LCD
Portable Monitor Market segmented by Connectivity Type:
- USB
- HDMI
- VGA
Portable Monitor Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Bureau of Labor Statistics. (2025, May 23). Telework rate down for federal government workers in April 2025. https://www.bls.gov/opub/ted/2025/telework-rate-down-for-federal-government-workers-in-april-2025.htm
- [2] Nintendo Co., Ltd. (2026, February 3). Financial Results Explanatory Material, 3rd Quarter of Fiscal Year Ending March 2026. https://www.nintendo.co.jp/ir/pdf/2026/260203_2e.pdf
- [3] Notebookcheck. (2026, September 15). Lenovo launches new portable monitor globally with dual USB-C and slim design. https://www.notebookcheck.net/Lenovo-launches-new-portable-monitor-globally-with-dual-USB-C-and-slim-design.1399120.0.html
- [4] LG Display. (2026, October 22). LG Display Reports Third Quarter 2026 Results. https://www.sec.gov/Archives/edgar/data/0001290109/000119312526428336/26.q3_er.htm
- [5] AUO Corporation. (2026, April 9). AUO Corporation Reports March 2026 Consolidated Revenue. https://auo.com/ja-JP/News_Archive/detail/news_MonthlySales_20260409
- [6] Lenovo Group. (2026, August 13). Lenovo Delivers Strongest Quarter in Group History: Hybrid AI Strategy Powers Growth Momentum. https://news.lenovo.com/pressroom/press-releases/q1-fy-2026-27/
- [7] European Commission. (2024, December 28). EU common charger rules: power all your devices with a single charger. https://commission.europa.eu/news-and-media/news/eu-common-charger-rules-power-all-your-devices-single-charger-2024-12-28_en
- [8] Romania Insider. (2026, June 15). Eurostat: Only 1.3% of employees in Romania worked from home in 2025. https://www.romania-insider.com/eurostat-employees-romania-worked-home-2025
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the portable monitor market during 2026?
- What market size is projected by 2036?
- Which screen size holds notable share?
- Which screen type holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Screen Size, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Screen Size, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Screen Size, 2026 to 2036
- Under 14 Inch
- 14 to 20 Inch
- Above 20 Inch
- Y-o-Y Growth Trend Analysis By Screen Size, 2021 to 2025
- Absolute $ Opportunity Analysis By Screen Size, 2026 to 2036
- Global Market Analysis and Forecast, By Screen Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Screen Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Screen Type, 2026 to 2036
- LED
- LCD
- Y-o-Y Growth Trend Analysis By Screen Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Screen Type, 2026 to 2036
- Global Market Analysis and Forecast, By Connectivity Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Connectivity Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Connectivity Type, 2026 to 2036
- USB
- HDMI
- VGA
- Y-o-Y Growth Trend Analysis By Connectivity Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Connectivity Type, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Screen Size
- By Screen Type
- By Connectivity Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Screen Size
- By Screen Type
- By Connectivity Type
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Screen Size
- By Screen Type
- By Connectivity Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Screen Size
- By Screen Type
- By Connectivity Type
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Screen Size
- By Screen Type
- By Connectivity Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Screen Size
- By Screen Type
- By Connectivity Type
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Screen Size
- By Screen Type
- By Connectivity Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Screen Size
- By Screen Type
- By Connectivity Type
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Screen Size
- By Screen Type
- By Connectivity Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Screen Size
- By Screen Type
- By Connectivity Type
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Screen Size
- By Screen Type
- By Connectivity Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Screen Size
- By Screen Type
- By Connectivity Type
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Screen Size
- By Screen Type
- By Connectivity Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Screen Size
- By Screen Type
- By Connectivity Type
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Screen Size
- By Screen Type
- By Connectivity Type
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Screen Size
- By Screen Type
- By Connectivity Type
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Screen Size
- By Screen Type
- By Connectivity Type
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Screen Size
- By Screen Type
- By Connectivity Type
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Screen Size
- By Screen Type
- By Connectivity Type
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Screen Size
- By Screen Type
- By Connectivity Type
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Screen Size
- By Screen Type
- By Connectivity Type
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Screen Size
- By Screen Type
- By Connectivity Type
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Screen Size
- By Screen Type
- By Connectivity Type
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Screen Size
- By Screen Type
- By Connectivity Type
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Screen Size
- By Screen Type
- By Connectivity Type
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Screen Size
- By Screen Type
- By Connectivity Type
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Screen Size
- By Screen Type
- By Connectivity Type
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Screen Size
- By Screen Type
- By Connectivity Type
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Screen Size
- By Screen Type
- By Connectivity Type
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Screen Size
- By Screen Type
- By Connectivity Type
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Screen Size
- By Screen Type
- By Connectivity Type
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Screen Size
- By Screen Type
- By Connectivity Type
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Screen Size
- By Screen Type
- By Connectivity Type
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Screen Size
- By Screen Type
- By Connectivity Type
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Screen Size
- By Screen Type
- By Connectivity Type
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Lenovo
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- ASUS
- Dell
- HP
- LG Electronics
- ViewSonic
- GeChic
- Acer
- AOC
- Gaems
- Lenovo
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Screen Size, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Screen Type, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by Connectivity Type, 2021 to 2036
- Table 5: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Million) Forecast by Screen Size, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Screen Type, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by Connectivity Type, 2021 to 2036
- Table 9: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Million) Forecast by Screen Size, 2021 to 2036
- Table 11: Latin America Market Value (USD Million) Forecast by Screen Type, 2021 to 2036
- Table 12: Latin America Market Value (USD Million) Forecast by Connectivity Type, 2021 to 2036
- Table 13: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Million) Forecast by Screen Size, 2021 to 2036
- Table 15: Western Europe Market Value (USD Million) Forecast by Screen Type, 2021 to 2036
- Table 16: Western Europe Market Value (USD Million) Forecast by Connectivity Type, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Million) Forecast by Screen Size, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Million) Forecast by Screen Type, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Million) Forecast by Connectivity Type, 2021 to 2036
- Table 21: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Million) Forecast by Screen Size, 2021 to 2036
- Table 23: East Asia Market Value (USD Million) Forecast by Screen Type, 2021 to 2036
- Table 24: East Asia Market Value (USD Million) Forecast by Connectivity Type, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Million) Forecast by Screen Size, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Million) Forecast by Screen Type, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Million) Forecast by Connectivity Type, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Million) Forecast by Screen Size, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Million) Forecast by Screen Type, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Million) Forecast by Connectivity Type, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Screen Size, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Screen Size, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Screen Size
- Figure 6: Global Market Value Share and BPS Analysis by Screen Type, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Screen Type, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Screen Type
- Figure 9: Global Market Value Share and BPS Analysis by Connectivity Type, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Connectivity Type, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Connectivity Type
- Figure 12: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Screen Size, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Screen Size, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Screen Size
- Figure 26: North America Market Value Share and BPS Analysis by Screen Type, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Screen Type, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Screen Type
- Figure 29: North America Market Value Share and BPS Analysis by Connectivity Type, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Connectivity Type, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Connectivity Type
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Screen Size, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Screen Size, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Screen Size
- Figure 36: Latin America Market Value Share and BPS Analysis by Screen Type, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Screen Type, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Screen Type
- Figure 39: Latin America Market Value Share and BPS Analysis by Connectivity Type, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Connectivity Type, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Connectivity Type
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Screen Size, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Screen Size, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Screen Size
- Figure 46: Western Europe Market Value Share and BPS Analysis by Screen Type, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Screen Type, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Screen Type
- Figure 49: Western Europe Market Value Share and BPS Analysis by Connectivity Type, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Connectivity Type, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Connectivity Type
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Screen Size, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Screen Size, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Screen Size
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Screen Type, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Screen Type, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Screen Type
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Connectivity Type, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Connectivity Type, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Connectivity Type
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Screen Size, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Screen Size, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Screen Size
- Figure 66: East Asia Market Value Share and BPS Analysis by Screen Type, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Screen Type, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Screen Type
- Figure 69: East Asia Market Value Share and BPS Analysis by Connectivity Type, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Connectivity Type, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Connectivity Type
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Screen Size, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Screen Size, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Screen Size
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Screen Type, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Screen Type, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Screen Type
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Connectivity Type, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Connectivity Type, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Connectivity Type
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Screen Size, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Screen Size, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Screen Size
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Screen Type, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Screen Type, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Screen Type
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by Connectivity Type, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by Connectivity Type, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by Connectivity Type
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the portable monitor market expected in 2026?
FMI puts 2026 portable monitor sales at USD 218.9 million, against USD 184.9 million in 2025. Hybrid workers keep adding a light second screen to the laptop bag.
What CAGR is projected for the portable monitor market through 2036?
An 18.4% CAGR is projected for portable monitor sales, taking them to USD 1,185.1 million by 2036, since USB-C laptops make single-cable screens easy to bundle.
Which screen size holds a notable market share in 2026?
Above 20-inch screens are expected to hold 38.8% of 2026 sales, given that home users want desktop-class size without a fixed stand.
Which screen type holds a notable market share in 2026?
LED panels are likely to account for 68.5% of screen type sales, as thin backlights keep weight and power draw low.
Which country has a notable expansion outlook through 2036?
China has the highest rate in the FMI country table, at a 23.6% CAGR, as laptop brands sell matching screens through online marketplaces.
Who are the key companies in the portable monitor market?
Lenovo, Dell, HP, Acer and ASUS lead through laptop bundles. LG Electronics, ViewSonic and AOC compete on panel range, and Gaems and GeChic serve gaming and travel niches with compact designs.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
