
- Market Size (2026)
- USD 42.0 Bn
- Forecast (2036)
- USD 101.3 Bn
- CAGR (2026 to 2036)
- 9.2%
How big is Semiconductor Packaging Market in 2026?
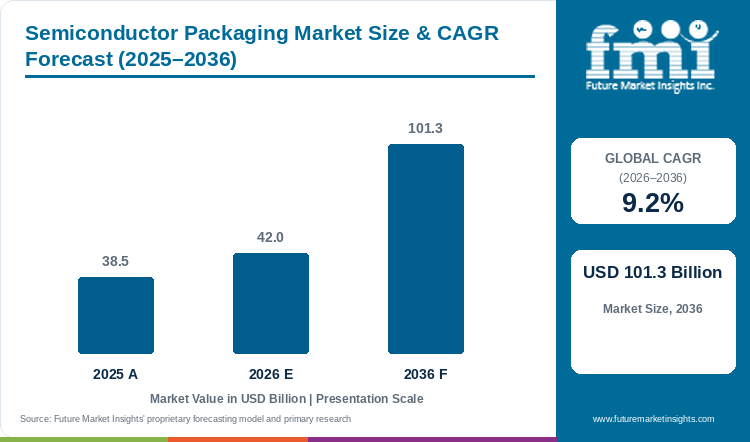
Sales in the semiconductor packaging market are projected to grow at 9.2% CAGR, with the market size rising from USD 38.5 billion in 2025 to USD 42.0 billion in 2026 and reaching USD 101.3 billion by 2036.
Shrinking transistor geometries across monolithic silicon have forced chipmakers to shift performance scaling toward heterogeneous assembly. According to Future Market Insights analysis, the global semiconductor packaging market stands at USD 38.5 billion in 2025 and rises to USD 42.0 billion in 2026. Valuation is projected to reach USD 101.3 billion by 2036 at a 9.2% CAGR, generating USD 59.3 billion in added revenue. In April 2026, SEMI reported that global semiconductor equipment billings climbed 15% to USD 135.1 billion in 2025 on back-end investment [1]. Rigid containers & bottles hold 54.2% share in 2026 as matrix trays protect advanced packaging architectures. Country CAGRs span 7.4% in Italy to 11.2% in Chile, though substrate shortages persist.
Key Market Trends & Insights
- By packaging format: Rigid containers & bottles led with 54.2% share in 2026, supported by anti-static JEDEC matrix trays and moisture-barrier wafer enclosures that prevent lead deformation.
- By material substrate: Recycled paperboard accounted for 44.3% in 2026, driven by static-dissipative secondary cartons and conductive fiber carrier inserts replacing single-use plastics.
- By end-use sector: Food & beverage held 32.7% in 2026, underpinned by packaged optical sensors and programmable control silicon installed across high-speed bottling and inspection lines.
Regional Highlights
- Fastest-growing evaluated country: Chile, at 11.2% CAGR from 2026 to 2036.
- By country: Germany at 10.3%, Portugal at 9.6%, and the USA at 8.8% follow, while Italy records the lowest evaluated CAGR at 7.4%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Semiconductor Packaging Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 38.5 billion |
| Estimated Market Size in 2026 | USD 42.0 billion |
| Projected Market Size by 2036 | USD 101.3 billion |
| CAGR, 2026 to 2036 | 9.2% |
| Added Revenue, 2026 to 2036 | USD 59.3 billion |
Country demand conditions differ as assembly houses confront uneven substrate supply and strict moisture-control rules across regional foundry clusters. FMI research indicates that outsourced assembly and test vendors face severe warpage tolerances when stacking multi-die processors. In January 2025, the U.S. Department of Commerce and NIST finalized USD 1.4 billion in CHIPS National Advanced Packaging Manufacturing Program awards to scale domestic substrate and chiplet piloting capacity [2]. Owing to the advantages associated with localized substrate supply, packaging plants are expanding fan-out wafer level packaging lines while qualifying conductive transport trays that protect bare dies between wafer foundries and final test facilities.
Packaged-Unit and Interconnect-Density Sizing
Table 2: Packaged-Unit and Interconnect-Density Sizing for the Semiconductor Packaging Market (USD billion and unit ranges), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 38.5 | 42.0 | 101.3 |
| Packaged semiconductor units (billion) | 320.0 to 345.0 | 345.0 to 372.0 | 690.0 to 760.0 |
| Advanced packaging wafer starts (million) | 12.5 to 13.5 | 13.5 to 14.6 | 30.0 to 33.5 |
| Spend per assembly site (USD million) | 68.0 to 75.0 | 74.0 to 82.0 | 165.0 to 185.0 |
Operational note: Unit ranges reflect global semiconductor shipment volumes across packaged device categories. Wafer starts reflect advanced interconnect adoption across compute and automotive silicon. Figures represent operational scenario ranges for capacity planning rather than metered fab totals.
Per Capita and Assembly-Site Sizing
High-density interconnect assemblies have gained strong traction across artificial intelligence servers and automotive power modules as device makers balance compute output with thermal control. Rising pin counts convert back-end assembly into recurring procurement of wafer level packaging carriers and static-dissipative shipping trays. In February 2025, JEDEC updated J-STD-033 handling standards governing moisture-sensitive surface-mount packages during baking and dry-bagged transit [3]. Consequently, foundries audit carrier outgassing and dimensional tolerances before approving supplier lots.
Table 3: Per Capita and Assembly-Site Spending Indicators for the Semiconductor Packaging Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Spend per capita (USD) | 4.7 | 5.1 | 11.3 |
| Spend per 1,000 people (USD) | 4,695.1 | 5,060.2 | 11,255.6 |
| Spend per assembly site (USD million) | 74.0 to 82.0 | 78.0 to 87.0 | 150.0 to 168.0 |
Table 4: Assembly-Site and Foundry Spending Indicators for the Semiconductor Packaging Market (USD and percentages), mixed reporting years from 2025 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 42.0 billion | Report value |
| Assembly and test sites worldwide | 480 | 2025 industry estimate |
| Market spend per assembly site | USD 87.5 million | Site allocation ratio |
| Food & beverage end-use revenue, 2026 | USD 13.7 billion | 32.7% share |
Analyst Perspective
"Advanced chiplet interconnects and static-dissipative carrier trays allow assembly houses to raise compute density across artificial intelligence servers. Substrate warpage and moisture sensitivity still require strict cleanroom validation before foundries approve high-volume production."
- Rahul Pandita, Principal Consultant, Future Market Insights.
How is the semiconductor packaging market segmented?
The semiconductor packaging market is segmented by packaging format, material substrate, and end-use sector. In 2026, rigid containers & bottles are projected at 54.2%, recycled paperboard at 44.3%, and food & beverage at 32.7%.
By packaging format: Rigid containers & bottles, flexible wraps & bags, and secondary bulk packaging.
By material substrate: Recycled paperboard, thermoplastic polymers, sustainable plant fibers, and specialty alloys.
By end-use sector: Food & beverage, pharmaceuticals & healthcare, personal care & homecare, and industrial manufacturing.
Why do Rigid Containers & Bottles lead the packaging format category?
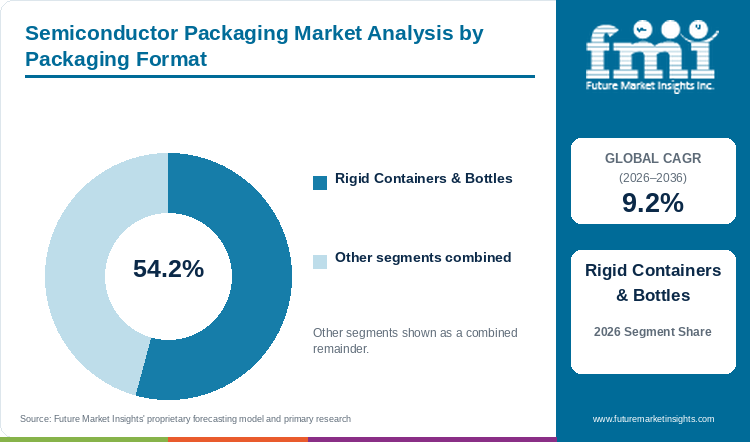
Rigid containers & bottles are projected to hold 54.2% of packaging format demand in 2026, supported by JEDEC matrix protection.
Table 5: Packaging Format Share for the Semiconductor Packaging Market (percentage share), 2026
| Packaging Format | Share (2026) |
|---|---|
| Rigid Containers & Bottles | 54.2% |
| Other Segments Combined | 45.8%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Packaging Format Leadership and Market Growth for the Semiconductor Packaging Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 9.2% |
| Leading Segment | Rigid Containers & Bottles |
Delicate silicon dies and fine-pitch ball grid arrays require rigid structural carriers during transport between wafer foundries and surface-mount assembly lines. High-precision thermoformed polycarbonate matrix trays hold microchips in indexed pockets so robotic pick-and-place nozzles can feed circuit boards without bending solder bumps. Owing to the advantages associated with dimensional stiffness, rigid containers & bottles outperform flexible wraps & bags at 29.5% share and secondary bulk packaging at 16.3%. In addition to this, carbon-loaded polymer trays integrate electrostatic discharge packaging properties that prevent triboelectric charging. However, issues such as tray warpage during high-temperature baking still require strict dimensional inspection before reuse.
- Rigid containers & bottles account for 54.2% of packaging format demand in 2026, underpinned by dimensional stability and robotic surface-mount feeder alignment.
- In June 2025, Entegris expanded production of 300-millimeter front-opening unified pods and conductive matrix trays at its Colorado Springs manufacturing facility to support domestic wafer fabs [4].
What maintains Recycled Paperboard as the leading material substrate?
Recycled paperboard is estimated to represent 44.3% of material substrate volume in 2026, driven by static-dissipative secondary carton conversion.
Outsourced assembly houses and electronics brands are replacing virgin petroleum plastics in secondary component shipping with conductive recycled paperboard cartons. Treated with carbon-based dissipative coatings, recycled fiberboard provides Faraday-cage shielding around tape-and-reel carriers while remaining repulpable in municipal recycling streams. Because outer reel boxes and intermediate shippers represent high tonnage across global logistics corridors, recycled paperboard leads thermoplastic polymers at 33.5%, sustainable plant fibers at 15.4%, and specialty alloys at 6.8%. Besides this, consumer electronics packaging buyers mandate fiber-based secondary boxes to lower Scope 3 emissions. However, humidity fluctuations during sea freight can weaken fiber compression strength unless moisture-barrier liners are applied.
- Recycled paperboard commands 44.3% of material substrate volume in 2026, reflecting corporate plastic-elimination mandates and municipal repulpability.
- In September 2025, the EOS/ESD Association updated ANSI/ESD S541 packaging standards defining surface resistance thresholds for static-dissipative fiberboard outer cartons used in microelectronics logistics [5].
Why does Food & Beverage lead end-use sector demand?
Food & beverage sectors are anticipated to capture 32.7% of end-use sector demand in 2026, owing to automated processing sensor integration.
Automated food and beverage processing plants and cold-chain logistics networks consume large volumes of packaged sensor, microcontroller, and radio-frequency identification silicon. High-speed bottling lines, optical sorting machines, and refrigerated transport pallets rely on hermetically packaged microchips that withstand washdown moisture and thermal cycling. As a result, food & beverage accounts for 32.7% of end-use sector demand in 2026, ahead of pharmaceuticals & healthcare at 28.9%, personal care & homecare at 22.6%, and industrial manufacturing at 15.8%. Furthermore, with the use of industrial electronics packaging, sensor makers protect motor drives and vision modules from caustic cleaning agents. Unit price sensitivity in pallet-level RFID tags still limits premium ceramic substrates.
- Food & beverage represents 32.7% of end-use sector revenue in 2026, reinforced by high-volume deployment of optical inspection sensors and cold-chain RFID microchips.
- In October 2025, GS1 US and food logistics operators documented that automated RFID sensor inlays reduced perishable distribution temperature excursions across commercial cold chains [6].
What are the drivers, restraints, and opportunities in the semiconductor packaging market?
In the semiconductor packaging market, artificial intelligence chiplet integration will continue to propel demand, thermal dissipation limits and substrate bottlenecks will constrain qualification, and glass-core substrates are expected to unlock high-density interconnect scaling through 2036.
- Driver:Generative artificial intelligence server deployments and automotive power modules compel foundries to expand multi-die packaging and protective carrier procurement.
- Restraint:Extreme thermal flux across stacked compute dies and build-up film substrate shortages induce warpage defects and extend qualification cycles.
- Opportunity:Transitioning toward glass-core substrates and co-packaged optical interconnects enables higher pin density while lowering data transmission power.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Escalating capital expenditure on artificial intelligence data centers and electric vehicle power inverters is compelling chipmakers to adopt multi-die assemblies. Training large neural networks requires linking central logic dies to high-bandwidth memory stacks through thousands of fine-pitch micro-bumps inside 2.5D and 3D IC packaging. FMI data suggests that heterogeneous integration is converting back-end packaging from a low-margin assembly step into the primary determinant of processor yield. In December 2025, World Semiconductor Trade Statistics reported that global semiconductor market valuation was on track to approach USD 1.0 trillion in 2026 on surging logic and memory shipments [7]. Consequently, assembly contractors must qualify zero-defect conductive carriers before hyperscale customers approve volume production.
Risk Assessment of the Semiconductor Packaging Market: Operational and Formulation Friction
Severe thermal power density and organic substrate warpage represent the primary technical bottlenecks restricting advanced package yields. When multiple compute and memory chiplets sit inside a single molded module, heat flux exceeds 100 watts per square centimeter and creates mismatched thermal expansion between silicon and copper traces. In May 2025, research published in IEEE Transactions on Components, Packaging and Manufacturing Technology demonstrated that curing shrinkage in epoxy molding compounds induces micro-crack delamination across large fan-out interposers [8]. Without high-conductivity thermal interface materials and tight coplanarity control, assembly plants face elevated scrap rates. Furthermore, long lead times for fine-line build-up films delay new accelerator rollouts.
Commercial Opportunity Analysis: Substrate Differentiation and High-Density Formats
Replacing conventional organic build-up cores with engineered glass substrates offers packaging vendors a major commercial avenue for next-generation artificial intelligence processors. Glass cores provide superior dimensional flatness and thermal stability, allowing lithography tools to pattern ultra-dense through-glass vias without substrate distortion across large multi-chip modules. In April 2025, the National Institute of Standards and Technology published metrology frameworks addressing sub-micron defect inspection in 2.5D and 3D heterogeneous integration [9]. In addition to this, suppliers developing advanced semiconductor packaging substrates are pairing glass interposers with closed-loop conductive JEDEC tray recycling programs. Vendors that master laser via drilling and low-outgassing carrier molding will capture long-term foundry contracts.
Semiconductor Packaging Market by Country (2026 to 2036)
As per FMI, Chile represents the fastest-growing semiconductor packaging market among the six evaluated countries, at an 11.2% CAGR from 2026 to 2036, while Italy records the slowest expansion at 7.4% CAGR. Across all six covered economies, commercial performance depends on how effectively packaging suppliers secure high-purity copper and substrate materials, qualify cleanroom assembly lines under national semiconductor incentives, and prevent electrostatic damage during cross-border wafer transit.
Table 7: Country CAGR and Primary Growth Levers for the Semiconductor Packaging Market (CAGR percentage and operational drivers), 2026 to 2036
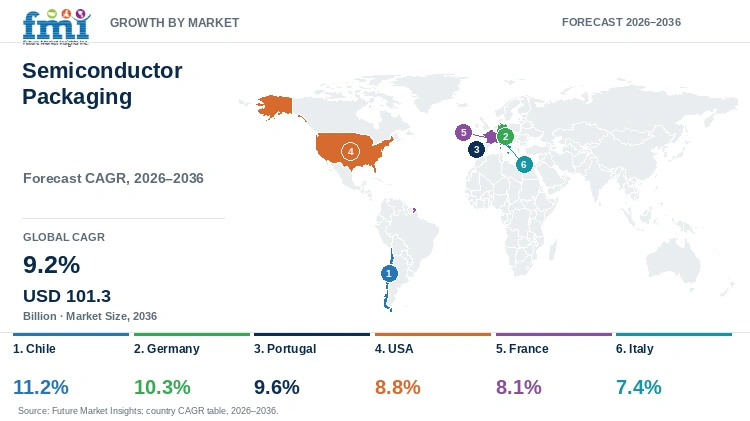
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Chile | 11.2% | High-purity refined copper cathode and lithium supply for semiconductor leadframes and bonding wires |
| Germany | 10.3% | Silicon Saxony cleanroom fab expansions and automotive power microcontroller packaging demand |
| Portugal | 9.6% | European outsourced semiconductor assembly and test clustering and EU Chips Act co-investment |
| USA | 8.8% | CHIPS Act advanced packaging awards and hyperscale AI processor heterogeneous integration |
| France | 8.1% | Grenoble FD-SOI and RF microelectronics research hubs and aerospace hermetic packaging |
| Italy | 7.4% | Catania and Agrate Brianza silicon carbide power discrete packaging for electric vehicles |
Source: Future Market Insights analysis
Chile Semiconductor Packaging Market Outlook (2026 to 2036)
Upstream mineral processing of high-purity copper cathodes and battery-grade lithium positions Chile at the center of raw material supply for semiconductor leadframes and bonding wires. Consequently, the Chilean market is projected to expand at a leading 11.2% CAGR from 2026 to 2036. In January 2026, the Chilean Copper Commission reported that national copper production reached 5.5 million metric tons in 2025, supporting export refining corridors for electronics metallurgy [10]. However, the absence of domestic wafer fabrication cleanrooms means local value capture faces high energy tariffs and smelter modernization delays. Material processors overcome this hurdle by partnering with Asian and North American packaging houses to supply pre-refined copper foil and sealed moisture-barrier export drums.
Key takeaway:In Chile, upstream refining of semiconductor-grade copper cathodes and moisture-sealed export packaging sustain the fastest growth rate among evaluated economies.
Germany Semiconductor Packaging Market Outlook (2026 to 2036)
Between 2026 and 2036, the Germany semiconductor packaging market is expected to progress at a 10.3% CAGR, anchored by automotive microcontroller and radar transceiver assembly across Dresden's Silicon Saxony cluster. In October 2025, the European Commission marked a major European Chips Act milestone as new Dresden wafer and packaging investments advanced toward cleanroom commissioning [11]. Unlike consumer-electronics hubs in East Asia, German packaging demand centers on zero-defect automotive power modules and industrial automation sensors for domestic vehicle makers. High industrial electricity prices and strict PFAS chemical phase-out proposals in Europe still pressure substrate molding costs. Local suppliers mitigate these expenses by automating closed-loop JEDEC matrix tray washing and deploying halogen-free encapsulation resins.
Key takeaway:In Germany, Silicon Saxony foundry investments and zero-defect automotive power module standards drive sustained demand for automated cleanroom packaging.
Portugal Semiconductor Packaging Market Outlook (2026 to 2036)
European automotive and industrial chipmakers increasingly rely on Portugal as their primary nearshore outsourced semiconductor assembly and test hub. Demand across the Portugal semiconductor packaging sector is forecast to rise at a 9.6% CAGR through 2036. In February 2026, Portuguese investment agency AICEP and regional microelectronics partners documented expanded cleanroom wafer bumping and system-in-package capacity in Vila do Conde [12]. This coastal cluster allows European semiconductor buyers to bypass Asian airfreight bottlenecks when packaging MEMS sensors and power management chips. A limited domestic pool of specialized packaging substrate engineers still constrains rapid line scaling, prompting facilities to deploy automated optical inspection and standardized robotic tray feeders.
Key takeaway:In Portugal, nearshore European OSAT cleanroom clustering in Vila do Conde and EU Chips Act co-funding support rapid back-end assembly growth.
USA Semiconductor Packaging Market Outlook (2026 to 2036)
Evaluated at USD 13.4 billion in 2026, the United States semiconductor packaging market is anticipated to grow at an 8.8% CAGR between 2026 and 2036. Fabless artificial intelligence chip architects including Nvidia, AMD, and Apple generate immense domestic demand for 2.5D interposers and high-bandwidth memory stacking. In July 2026, the Semiconductor Industry Association reported that global semiconductor sales reached a record USD 795.6 billion in 2025, with U.S.-headquartered companies generating USD 425.0 billion in revenue [13]. Despite generous federal CHIPS Act co-funding, domestic back-end facilities confront high cleanroom construction costs and dependence on Asian organic substrate imports. American OSAT plants address this gap by automating wafer-level panel lines and qualifying domestic glass-core substrate pilots.
Key takeaway:In the USA, federal CHIPS Act packaging grants and hyperscale AI chiplet architectures anchor high-value domestic assembly investment.
France Semiconductor Packaging Market Outlook (2026 to 2036)
Specialized radio-frequency modules, imaging sensors, and aerospace microelectronics centered in the Grenoble-Isère corridor differentiate France from commodity consumer packaging markets. Valued at USD 1.9 billion in 2026, the French market is predicted to advance at an 8.1% CAGR through 2036. In March 2026, CEA-Leti and French industrial partners advanced their heterogeneous integration and FD-SOI pilot line in Grenoble under the European Chips Act framework [14]. French defense and aviation primes require hermetic ceramic enclosures and radiation-hardened assemblies capable of surviving severe mechanical vibration. Stringent multi-year defense qualification audits slow initial supplier onboarding, so packaging vendors provide pre-validated hermetic cavity packages and traceable anti-static transport reels.
Key takeaway:In France, Grenoble's FD-SOI research ecosystem and defense demand for hermetic ceramic packages sustain high-margin specialty growth.
Italy Semiconductor Packaging Market Outlook (2026 to 2036)
Wide-bandgap silicon carbide power modules and automotive discrete semiconductors in Catania and Agrate Brianza form the backbone of packaging demand in Italy. Sales in the Italian market are forecast to expand at a 7.4% CAGR from 2026 to 2036. In May 2025, the European Commission and the Italian Ministry of Enterprises authorized a EUR 5.0 billion integrated silicon carbide campus in Catania covering wafer fabrication and power module packaging [15]. Packaging high-voltage traction inverters requires copper-clip bonding and silver sintering rather than conventional gold wire bonds. Slowing European electric vehicle registration growth and high regional energy costs still temper short-term volume, prompting Italian plants to export packaged SiC modules to industrial solar and rail customers.
Key takeaway:In Italy, vertically integrated silicon carbide power module manufacturing in Catania and Agrate Brianza supports steady automotive and industrial demand.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the semiconductor packaging market?
Smurfit Westrock plc, Sealed Air Corporation, Ball Corporation, Crown Holdings, Inc., Silgan Holdings Inc., Huhtamaki Oyj, Mondi plc, and Sonoco Products Company are the significant market players in this market.
According to FMI, the competitive environment divides between static-dissipative paperboard converters, cleanroom ESD barrier specialists, and precision metal and rigid container manufacturers serving microelectronics logistics. Sustainable paperboard converters including Smurfit Westrock plc, Mondi plc, Huhtamaki Oyj, and Sonoco Products Company manufacture recyclable conductive folding cartons and molded fiber trays. Protective packaging suppliers such as Sealed Air Corporation engineer low-outgassing vacuum moisture barrier pouches and anti-static cushioning for wafers using flip chip interconnects. Precision container manufacturers including Silgan Holdings Inc., Ball Corporation, and Crown Holdings, Inc. supply electromagnetic shielding cans and rigid transit housings. Procurement teams evaluate suppliers on surface resistivity stability, ionic cleanliness, and global fab delivery reach.
- Static-Dissipative Paperboard & Fiber Converters: Smurfit Westrock plc, Mondi plc, Huhtamaki Oyj, and Sonoco Products Company supply conductive corrugated shippers and molded fiber component trays.
- Protective ESD Shielding & Moisture Barrier Specialists: Sealed Air Corporation engineers anti-static air cushioning, conductive foam pads, and hermetic foil barrier bags for moisture-sensitive devices.
- Precision Metal & Rigid Container Manufacturers: Silgan Holdings Inc., Ball Corporation, and Crown Holdings, Inc. deliver electromagnetic shielding enclosures and durable transit carriers.
Competitive Benchmarking: Semiconductor Packaging Market
Table 8: Competitive Benchmarking for the Semiconductor Packaging Market (qualitative capability ratings), 2026
| Company | Static-Dissipative Paperboard Technology | Cleanroom-Grade Packaging Sourcing | Hermetic Moisture Vapor Barrier Shielding | Geographic Reach |
|---|---|---|---|---|
| Smurfit Westrock plc | High | High | High | High |
| Sealed Air Corporation | High | High | High | High |
| Mondi plc | High | High | Medium | High |
| Huhtamaki Oyj | High | High | Medium | High |
| Sonoco Products Company | High | Medium | Medium | Medium |
| Silgan Holdings Inc. | Medium | Medium | High | Medium |
| Ball Corporation | Low | Low | High | High |
| Crown Holdings, Inc. | Low | Low | High | High |
Scoring basis: Static-Dissipative Paperboard Technology is High when documented product lines include carbon-coated or dissipative fiberboard carriers across multiple resistance ranges, and Medium when narrower. Cleanroom-Grade Packaging Sourcing is High when certified low-particulate converting lines are core, and Medium when less extensive. Hermetic Moisture Vapor Barrier Shielding is High when multi-layer metalized or rigid barrier enclosures are documented, and Medium when concentrated. High Geographic Reach indicates multi-region converting presence, and Medium indicates regional concentration. Low is reserved for documented portfolio specialization outside that axis.
Key Developments in the Semiconductor Packaging Market
- In January 2026, Huhtamaki Oyj partnered with European microelectronics assemblers to commercialize precision molded-fiber component carrier trays compatible with automated pick-and-place feeders [16].
- In November 2025, Mondi plc introduced an unbleached conductive kraft paper wrap treated with bio-based static-dissipative coatings to replace plastic anti-static bubble films in electronics transit [17].
- In August 2025, Sealed Air Corporation launched an ESD-shielding vacuum moisture barrier bag line featuring ultra-low outgassing polymer sealants for artificial intelligence processor shipping [18].
- In May 2025, Smurfit Westrock plc completed a USD 38.0 million cleanroom converting expansion dedicated to static-dissipative corrugated master shippers for semiconductor foundries [19].
Key Players in the Semiconductor Packaging Market
Static-Dissipative Paperboard and Fiber Converters
- Smurfit Westrock plc
- Mondi plc
- Huhtamaki Oyj
- Sonoco Products Company
Protective ESD Shielding and Barrier Packaging Specialists
- Sealed Air Corporation
Precision Metal and Rigid Container Manufacturers
- Silgan Holdings Inc.
- Ball Corporation
- Crown Holdings, Inc.
Semiconductor Packaging Market - Report Scope
Table 9: Report Scope for the Semiconductor Packaging Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Packaging Format; Material Substrate; End-Use Sector; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes supplier revenue from semiconductor packaging assemblies, protective carrier formats, and in-scope substrate materials sold within the listed segmentation. Excludes revenue from bare silicon wafer fabrication and downstream finished electronics outside the named market. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Chile, Germany, Portugal, USA, France, Italy, and additional countries in the full report |
| Key Companies Covered | Smurfit Westrock plc, Sealed Air Corporation, Ball Corporation, Crown Holdings, Inc., Silgan Holdings Inc., Huhtamaki Oyj, Mondi plc, Sonoco Products Company |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Semiconductor Packaging Market - Research Methodology
Table 10: Research Methodology for the Semiconductor Packaging Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with back-end packaging directors, OSAT operations managers, ESD materials engineers, cleanroom logistics specialists, and procurement leads across the value chain to validate packaging format adoption, substrate qualification, and pricing trends. |
| Secondary Research | Secondary research included company annual reports, investor presentations, SEMI equipment billing databases, JEDEC and EOS/ESD standards, IEEE technical proceedings, government CHIPS Act disclosures, and product literature relevant to the market. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 forecast period were developed using top-down wafer fab and assembly correlation modeling combined with bottom-up unit throughput and carrier procurement aggregation. |
| Data Triangulation and Validation | Data is validated against semiconductor shipment indicators, capital expenditure filings, substrate capacity additions, and historical growth trends to ensure accuracy without double counting adjacent categories. |
Semiconductor Packaging Market by Segments
Semiconductor Packaging Market segmented by Packaging Format:
- Rigid Containers & Bottles
- Flexible Wraps & Bags
- Secondary Bulk Packaging
Semiconductor Packaging Market segmented by Material Substrate:
- Recycled Paperboard
- Thermoplastic Polymers
- Sustainable Plant Fibers
- Specialty Alloys
Semiconductor Packaging Market segmented by End-Use Sector:
- Food & Beverage
- Pharmaceuticals & Healthcare
- Personal Care & Homecare
- Industrial Manufacturing
Semiconductor Packaging Market by Region
- North America
- United States
- Canada
- Mexico
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Portugal
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] SEMI (Semiconductor Equipment and Materials International). (2026, April 7). Global semiconductor equipment billings reached USD 135.1 billion in 2025. SEMI Industry Market Data Reports.
- [2] National Institute of Standards and Technology (NIST). (2025, January 16). U.S. Department of Commerce announces USD 1.4 billion in final awards for CHIPS National Advanced Packaging Manufacturing Program. U.S. Department of Commerce CHIPS R&D Office.
- [3] JEDEC Solid State Technology Association. (2025, February 14). IPC/JEDEC J-STD-033: Standard for handling, packing, shipping, and use of moisture/reflow sensitive surface mount devices. JEDEC Engineering Standards.
- [4] Entegris, Inc. (2025, June 18). Expansion of 300-millimeter wafer carrier and conductive matrix tray manufacturing in Colorado Springs. Entegris Corporate Releases.
- [5] EOS/ESD Association, Inc. (2025, September 10). ANSI/ESD S541: Packaging materials for ESD sensitive items and dissipative fiberboard testing. Electrostatic Discharge Standards Series.
- [6] GS1 US. (2025, October 22). Deployment of UHF RFID sensor inlays for automated perishable food cold-chain tracking. Supply Chain Visibility Technical Bulletins.
- [7] World Semiconductor Trade Statistics (WSTS). (2025, December 2). Global semiconductor market approaches USD 1 trillion in 2026: Autumn 2025 market forecast. WSTS Semiconductor Forecast Releases.
- [8] Chen, Y., & Kim, H. (2025, May 19). Thermomechanical warpage characterization of epoxy mold compounds in ultra-dense fan-out wafer-level packaging. IEEE Transactions on Components, Packaging and Manufacturing Technology, 15(5), 812-824.
- [9] National Institute of Standards and Technology (NIST). (2025, April 15). Metrology challenges and through-glass via inspection in 2.5D and 3D microelectronics heterogeneous integration. NIST CHIPS Metrology Program Reports.
- [10] Chilean Copper Commission (Cochilco). (2026, January 20). Refined copper cathode production and high-purity electronics metallurgy export review. Ministry of Mining of Chile Statistical Bulletins.
- [11] European Commission. (2025, October 13). Milestone in strengthening Europe's semiconductor manufacturing capacity under the European Chips Act. Directorate-General for Communications Networks, Content and Technology.
- [12] Agência para o Investimento e Comércio Externo de Portugal (AICEP). (2026, February 11). European OSAT cleanroom capacity expansion and wafer-level packaging investments in Vila do Conde. Government of Portugal Industrial Reviews.
- [13] Semiconductor Industry Association (SIA). (2026, July 10). 2026 State of the U.S. Semiconductor Industry: Historic growth and CHIPS Act packaging investments. SIA Annual Industry Reports.
- [14] CEA-Leti & Ministry of the Economy and Finance. (2026, March 18). Grenoble FD-SOI and 3D heterogeneous integration pilot line progress report. French Microelectronics Research Bulletins.
- [15] Ministry of Enterprises and Made in Italy (MIMIT). (2025, May 28). Authorization of the EUR 5.0 billion Catania silicon carbide power semiconductor manufacturing and packaging campus. Italian Government Industrial Decrees.
- [16] Huhtamaki Oyj. (2026, January 15). Commercialization of precision molded-fiber component carrier trays for automated surface-mount assembly. Huhtamaki Corporate Releases.
- [17] Mondi plc. (2025, November 12). Launch of unbleached conductive kraft paper wrap with bio-based static-dissipative coatings for electronics. Mondi Product Announcements.
- [18] Sealed Air Corporation. (2025, August 19). Introduction of low-outgassing ESD-shielding vacuum moisture barrier bags for advanced AI processors. Sealed Air Technical Dossiers.
- [19] Smurfit Westrock plc. (2025, May 14). Completion of USD 38.0 million cleanroom converting expansion for static-dissipative microelectronics shippers. Smurfit Westrock Investor News.
- [20] ASE Technology Holding Co., Ltd. (2026, January 22). Completion of advanced 3D chiplet packaging and VIPack heterogeneous integration cleanroom facility in Kaohsiung. ASE Corporate Press Room.
- [21] Amkor Technology, Inc. (2025, October 27). Commencement of high-volume advanced system-in-package production at Bac Ninh facility in Vietnam. Amkor Investor Relations.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the semiconductor packaging market in 2026 and what is forecast for 2036?
- Which compute and assembly pressures support demand for semiconductor packaging?
- Why do Rigid Containers & Bottles lead the packaging format category?
- Why does Recycled Paperboard lead the material substrate category globally?
- How do growth rates differ across Chile, Germany, Portugal, and the USA?
- Which leading companies supply relevant carrier, barrier, and OSAT packaging categories today?
- What limits adoption or supplier switching in the semiconductor packaging market?
- What should buyers evaluate before qualifying a semiconductor packaging supplier?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Rigid Containers & Bottles
- Flexible Wraps & Bags
- Secondary Bulk Packaging
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Material Substrate, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material Substrate, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material Substrate, 2026 to 2036
- Recycled Paperboard
- Thermoplastic Polymers
- Sustainable Plant Fibers
- Specialty Alloys
- Y-o-Y Growth Trend Analysis By Material Substrate, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Substrate, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Sector, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Sector, 2026 to 2036
- Food & Beverage
- Pharmaceuticals & Healthcare
- Personal Care & Homecare
- Industrial Manufacturing
- Y-o-Y Growth Trend Analysis By End-Use Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- Mexico
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Portugal
- Benelux
- Nordics
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Portugal
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Smurfit Westrock plc
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Sealed Air Corporation
- Mondi plc
- Huhtamaki Oyj
- Sonoco Products Company
- Silgan Holdings Inc.
- Ball Corporation
- Crown Holdings, Inc.
- Smurfit Westrock plc
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Packaging Format
- Figure 6: Global Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Material Substrate
- Figure 9: Global Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-Use Sector
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Packaging Format
- Figure 26: North America Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Material Substrate
- Figure 29: North America Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by End-Use Sector
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Packaging Format
- Figure 36: Latin America Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Material Substrate
- Figure 39: Latin America Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by End-Use Sector
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Packaging Format
- Figure 46: Western Europe Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Material Substrate
- Figure 49: Western Europe Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by End-Use Sector
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Packaging Format
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Material Substrate
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by End-Use Sector
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Packaging Format
- Figure 66: East Asia Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Material Substrate
- Figure 69: East Asia Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by End-Use Sector
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Packaging Format
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Material Substrate
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by End-Use Sector
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Packaging Format
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Material Substrate
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by End-Use Sector
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the semiconductor packaging market in 2026, and what is forecast for 2036?
Global semiconductor packaging sales are estimated to reach USD 42.0 billion in 2026. Revenue is projected to climb to USD 101.3 billion by 2036, supported by multi-die processor assembly and cleanroom carrier demand.
What is the CAGR for the semiconductor packaging market from 2026 to 2036?
As per FMI, the semiconductor packaging market is projected to expand at a 9.2% CAGR from 2026 to 2036. Growth is underpinned by artificial intelligence accelerator packaging and automotive power module integration.
Which packaging format segment leads the semiconductor packaging market in 2026?
Rigid containers & bottles are projected to hold 54.2% of packaging format demand in 2026. The segment benefits from dimensional stiffness in JEDEC matrix trays and compatibility with automated pick-and-place equipment.
Which material substrate segment holds the largest share in 2026?
Recycled paperboard is estimated to account for 44.3% of material substrate volume in 2026. Demand is supported by static-dissipative folding cartons and corporate mandates to eliminate virgin plastics in secondary electronics shipping.
Which country has a notable expansion outlook during the forecast period?
FMI finds that Chile is projected to register an 11.2% CAGR between 2026 and 2036. Growth is supported by domestic refining of high-purity copper cathodes used in semiconductor leadframes and bonding wires.
Who are the key players active in the semiconductor packaging market?
Notable participants include Smurfit Westrock plc, Sealed Air Corporation, Ball Corporation, Crown Holdings, Inc., Silgan Holdings Inc., Huhtamaki Oyj, Mondi plc, and Sonoco Products Company, alongside OSAT leaders ASE Technology Holding Co., Amkor Technology, Inc., and JCET Group.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
