

- Market Size (2026)
- USD 25.5 Bn
- Forecast (2036)
- USD 40.4 Bn
- CAGR (2026 to 2036)
- 4.7%
How big is the semiconductor wafer market in 2026?
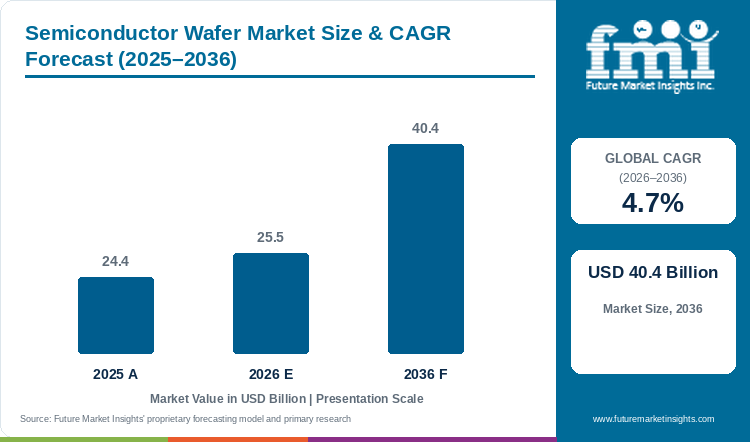
Demand is projected to expand at 4.7% CAGR from 2026 to 2036. Market value rises from USD 24.35 billion in 2025 to USD 25.5 billion in 2026 and USD 40.4 billion by 2036. [1]
The semiconductor wafer market is estimated at USD 25.5 billion in 2026 and projected to reach USD 40.4 billion by 2036, with a CAGR of 4.7% over the forecast period. [1] Demand depends on the devices that semiconductor manufacturers intend to produce, because the substrate needs to meet material, surface and quality requirements within the process. Data center GPU development provides one source of advanced device activity, while consumer and industrial electronics retain different production requirements. SEMI reported that silicon wafer shipments increased in 2025 while revenue declined, showing why volume and commercial value can move differently within a defined industry measure. [2] SUMCO documents polished and epitaxial wafer products, and GlobalWafers’ US facility opening illustrates investment in additional regional supply. [3][4] Buyers consequently consider qualification and dependable delivery alongside available capacity, since a wafer must fit the manufacturing process before it can support usable output. The outlook covers several nodes and applications, with advanced designs and established device processes contributing different purchasing needs. Suppliers can address growth through consistent products and suitable capacity without assuming that every customer requires the same substrate or process arrangement.
Key Market Trends and Insights
- Wafer buyers need consistent material and surface quality within the intended device process, making qualification and dependable delivery important alongside available production capacity. [3]
- Industry shipment and revenue measures can move differently, with SEMI’s 2025 results illustrating why wafer volume should be considered separately from commercial value. [2]
- Regional capacity investment adds supply options, while customers still need to qualify products and assess how the available substrates fit their manufacturing requirements. [4]
Regional Highlights
- US supply has gained a new 300mm facility through GlobalWafers America, giving domestic customers an additional source to assess within their qualification and procurement processes. [4]
- Japanese wafer suppliers serve global semiconductor production through products with different material and surface requirements, illustrating the role of established manufacturing capabilities. [3]
- The UK strategy emphasizes design, compound semiconductors and research, providing a different industrial context from an assumption that every country follows the same fabrication model. [5]
Market Size and Forecast
Table 1: Value outlook for the semiconductor wafer market
| Metric | Value |
|---|---|
| 2025 market value | USD 24.35 billion [1] |
| 2026 market value | USD 25.5 billion [1] |
| 2036 market value | USD 40.4 billion [1] |
| CAGR 2026 to 2036 | 4.7% [1] |
| Revenue increase 2026 to 2036 | USD 14.9 billion [1] |
| Market expansion 2026 to 2036 | 1.58 times [1] |
Growth across 2026 to 2036 is expected to reflect the mixture of advanced and established device processes, with suppliers matching products and capacity to customer requirements. Analog to digital converter production illustrates a device category with needs that can differ from leading-edge computing, so node coverage should not be treated as a uniform purchasing specification. Buyers need dependable quality and delivery across this range, while regional investment influences the supply options available for qualification and continuing manufacturing. [1][2][3]
Why do shipment growth and wafer revenue need separate interpretation?
SEMI’s 2025 silicon wafer results show higher shipped area alongside lower revenue, indicating that the commercial value of supply does not follow volume automatically. Product documentation also identifies different wafer types, while regional investment changes the locations from which customers can obtain qualified material. These sources support a purchasing assessment that considers product fit, quality and supply continuity together rather than using shipped area alone to describe market value. [2][3][4]
Table 2: Industry evidence relevant to the semiconductor wafer market
| Indicator | Data point or observation | Market relevance | Source |
|---|---|---|---|
| Silicon wafer shipments | SEMI reports 12,973 million square inches shipped in 2025, up 5.8%. | Shipment volume is a distinct industry measure. | [2] |
| Silicon wafer revenue | SEMI reports 2025 revenue of USD 11.4 billion, down 1.2%. | Commercial value can differ from shipment growth. | [2] |
| Regional capacity | GlobalWafers America opened its 300mm US facility in May 2025. | New supply still needs to fit customer qualification requirements. | [4] |
Analyst Perspective
"The key factors of competition are innovation, wafer-size, process node, and factory efficiency. Suppliers need to connect those capabilities with the requirements of the intended device process, because consistent material quality and dependable production support determine how effectively customers can use the wafers." [1]
— Sudip Saha, Principal Consultant for Technology, FMI
How is the semiconductor wafer market segmented?
The market is segmented by Process Node, Application, and Region.
By process node, the market covers 3nm, 5 nm, 7 nm, 8 nm, 10 nm, 16 nm, 20 nm, 28 nm, 40 nm, other nodes. By application, the market covers automotive, consumer electronics, industrial manufacturing, telecommunications, other applications.
Why does the 3nm segment lead demand within the process node category?
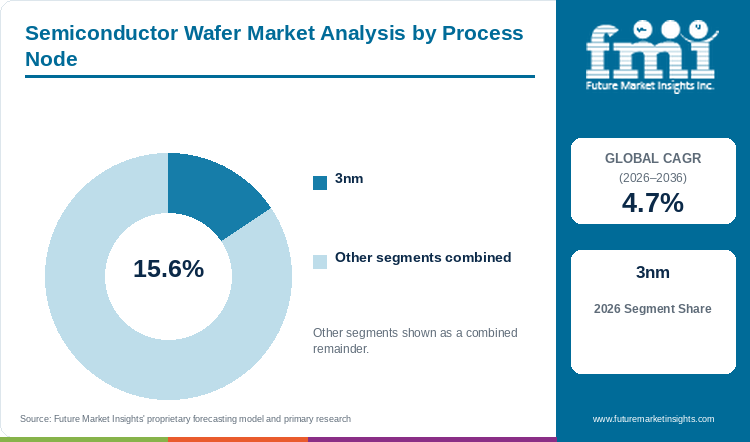
The 3nm segment accounts for 15.6% of process node demand in 2026. [1]
The 3nm category reflects device processes serving advanced performance and efficiency requirements, giving it a leading position within the report’s node-based market coverage. Its share is estimated at 15.6% in 2026. [1] Wafer suppliers still need to provide material that fits the customer’s manufacturing process, with qualification and surface quality influencing whether the substrate can be used dependably. SUMCO’s product documentation describes different wafer types and the importance of manufacturing quality, while industry shipment data gives a separate view of overall material demand. [2][3] The node’s leading share therefore connects with the devices being produced rather than a uniform specification for all wafers. Established processes retain roles in other applications, with product choice determined by the customer’s actual design and fabrication requirements.
- The 3nm segment is estimated to account for 15.6% of demand by process node in 2026, reflecting its role within advanced device manufacturing. [1]
- Customers need qualified substrates that fit the intended process, while established nodes retain useful roles for applications with different device and manufacturing requirements. [1][3]
Table 3: Leading process node share in 2026
| Segment | Share of demand |
|---|---|
| 3nm | 15.6% [1] |
| Other process node segments | 84.4% [1] |
| Total | 100.0% |
Why does the Consumer electronics segment lead demand within the application category?
The Consumer electronics segment accounts for 41.0% of application demand in 2026. [1]
Consumer electronics create demand for semiconductors across several device functions, making the application category a broad source of wafer purchasing rather than one uniform fabrication requirement. Its estimated 41.0% share of application demand in 2026 reflects this breadth within the covered market. [1] Different products use devices with their own performance, power and material needs, so wafer suppliers must support the processes that customers actually operate. Polished and epitaxial products illustrate distinct substrate arrangements, while dependable quality remains important across both advanced and established designs. [3] Consumer electronics leadership consequently relates to the range of devices produced, with supply planning and qualification linking material demand to usable semiconductor output. Other applications retain different requirements even when they purchase from the same upstream supplier base.
- The Consumer electronics segment is estimated to represent 41.0% of application demand in 2026, reflecting semiconductor use across a broad range of electronic device functions. [1]
- Substrate choice depends on the intended device process and qualification requirements, because consumer products do not all require the same material or manufacturing arrangement. [3]
What are the drivers, restraints, and opportunities in the semiconductor wafer market?
Driver
Semiconductor devices require substrates that fit their production process, connecting wafer demand with the introduction and continuing manufacture of electronic products. Cloud computing contributes one source of advanced device requirements, while consumer and industrial applications use a broader range of processes. Growth is supported by new output and dependable replacement supply, with qualified products and suitable capacity helping manufacturers maintain usable production rather than simply obtain additional material without a clear fit to the intended process. [1][2][3]
Restraint
Qualification and manufacturing consistency can constrain the ability to use new supply, because available capacity does not automatically make a wafer suitable for every customer’s process. Commercial conditions also differ from shipment growth, as SEMI’s 2025 results show higher shipped area alongside lower revenue. Buyers and suppliers consequently need to consider product mix, quality and delivery requirements together, while investments in additional capacity remain exposed to the actual device demand and the time required to establish dependable production relationships. [2][3][4]
Opportunity
Regional supply investment can create additional sourcing options when products meet customer qualification requirements, while specialized substrates offer another route to address different device processes. Manufacturing execution systems sit further downstream in the production environment, where material consistency needs to connect with dependable output. The opportunity for wafer suppliers lies in qualified products and usable capacity across advanced and established requirements, supported by clear delivery arrangements and a continuing understanding of the customer’s process rather than capacity expansion alone. [1][3][4]
Which country CAGRs are profiled in the semiconductor wafer market?
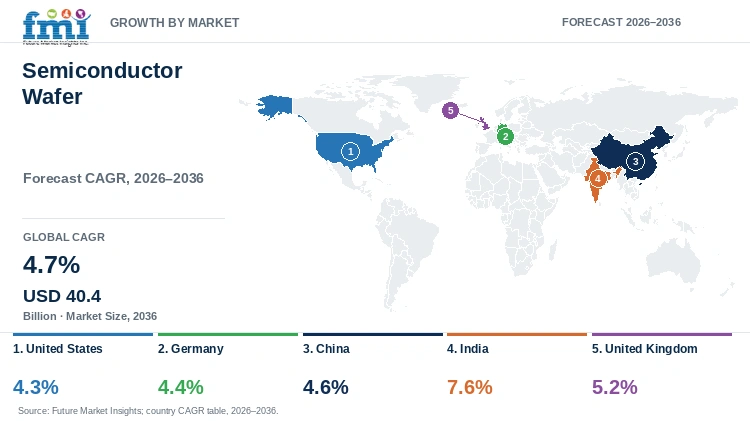
Table 4: Country CAGR comparison for the semiconductor wafer market
| Country or market | CAGR 2026 to 2036 |
|---|---|
| United States | 4.3% [1] |
| Germany | 4.4% [1] |
| China | 4.6% [1] |
| India | 7.6% [1] |
| United Kingdom | 5.2% [1] |
Country-wise Analysis
United States
GlobalWafers America opened its 300mm facility in Texas in May 2025, giving the US semiconductor supply environment an additional domestic manufacturing location. [4] Customers still need to assess qualification and product fit, because the location of capacity does not establish that every wafer meets every device process. The practical purchasing discussion therefore combines supply continuity with material and surface requirements, while new regional options can affect the sourcing arrangements manufacturers consider. The United States market is projected to expand at a CAGR of 4.3% from 2026 to 2036, within the report’s wafer revenue coverage. [1] Suppliers need dependable products and delivery alongside capacity, allowing customers to connect qualified material with usable output across the electronic devices they intend to manufacture. [3]
Germany
German wafer demand is assessed within a manufacturing environment that serves industrial, automotive and other electronic requirements, making the intended device process central to product selection. [1] Buyers need to distinguish advanced performance requirements from applications that retain established processes, because the substrate’s material and surface conditions must fit the actual fabrication task. Product documentation describes several wafer types, while industry shipment figures provide a separate measure of overall material movement. [2][3] Germany’s market is projected to grow at a CAGR of 4.4% from 2026 to 2036, with commercial demand tied to qualified products and dependable supply. The purchasing value rests on usable semiconductor output, so available capacity is assessed alongside manufacturing consistency and the delivery arrangements required to maintain production over time. [1]
China
Consumer electronics and industrial development form part of China’s wafer demand context in the report, connecting material purchasing with the production of devices used across different electronic functions. [1] Manufacturers need a substrate that fits the intended process, while qualification and dependable delivery influence whether additional supply can support usable output. The range of polished and epitaxial products illustrates why a wafer cannot be compared solely through its size or the amount shipped. [3] China’s market is projected to expand at a CAGR of 4.6% from 2026 to 2036, with demand shaped by advanced and established device requirements. Suppliers can address this outlook through consistent manufacturing quality and capacity matched to customer needs, while shipment growth and commercial revenue remain separate measures of the industry’s condition. [2]
India
India’s wafer outlook places procurement within an expanding semiconductor requirement, where manufacturers need to connect available material with the qualification and operating conditions of the intended device process. [1] New purchasing relationships can require careful assessment of quality and delivery, because a production plan needs dependable supply before it can translate capacity into usable output. Suppliers provide different wafer types for different requirements, making technical fit as important as the amount of material available. [3] The Indian market is projected to grow at a CAGR of 7.6% from 2026 to 2036, with demand assessed across the applications and nodes covered by the report. The opportunity rests on qualified products and suitable supply arrangements that can support manufacturing requirements as customers introduce or expand semiconductor production. [1]
United Kingdom
The UK National Semiconductor Strategy emphasizes intellectual property and design, compound semiconductors and research, giving its industrial priorities a different shape from a model centered solely on large-scale silicon fabrication. [5] Wafer demand in this environment still depends on the material and process required for a particular device, with qualification and access to suitable supply connecting development work with manufacturing. The United Kingdom market is projected to expand at a CAGR of 5.2% from 2026 to 2036, within the report’s defined wafer coverage. [1] Customers need to distinguish substrate types and application requirements when assessing supply, while the broader strategy highlights the role of design and research in the semiconductor value chain rather than treating every activity as an identical production requirement. [3]
Who are the notable companies in the semiconductor wafer market?
Shin-Etsu Chemical; SUMCO; GlobalWafers; Siltronic; SK Siltron
Competitive Benchmarking
Wafer suppliers compete through product quality, qualification and the capacity to deliver material suitable for a customer’s semiconductor process. SUMCO’s portfolio illustrates differences between substrate types, while GlobalWafers’ regional investment adds a separate dimension to supply planning. [3][4] Buyers therefore compare the usable product and delivery arrangement alongside capacity, with commercial value influenced by mix and industry conditions rather than shipped area alone. The representative participants serve related material requirements without making every product interchangeable across nodes and applications. [2]
Table 5: Competitive positioning for the semiconductor wafer market
| Company | Positioning | Evidence or purchasing distinction |
|---|---|---|
| Shin-Etsu Chemical | Semiconductor silicon wafer supply | Produces silicon substrates for semiconductor manufacturing. [1] |
| SUMCO | Polished and epitaxial wafer products | Documents product types and manufacturing quality requirements. [3] |
| GlobalWafers | Regional semiconductor wafer manufacturing | Opened its 300mm GlobalWafers America facility in 2025. [4] |
| Siltronic | Semiconductor silicon wafers | Supplies substrates used within semiconductor device production. [1] |
| SK Siltron | Semiconductor substrate manufacturing | Provides wafer products for semiconductor production requirements. [1] |
Key Developments in the Semiconductor Wafer Market
- SEMI’s February 2026 release reports higher silicon wafer shipments but lower revenue in 2025, demonstrating different movements in volume and commercial value within its defined industry measure. [2]
- GlobalWafers America officially opened its 300mm Texas facility in May 2025, adding a regional manufacturing location that customers can assess within their qualification and sourcing requirements. [4]
- The UK’s National Semiconductor Strategy identifies design, compound semiconductors and research as areas of focus, providing a distinct policy context for the country’s semiconductor value chain. [5]
Key Players in the Semiconductor Wafer Market
- Shin-Etsu Chemical
- SUMCO
- GlobalWafers
- Siltronic
- SK Siltron
Semiconductor Wafer Market Report Scope
Table 6: Report coverage for the semiconductor wafer market
| Attribute | Coverage |
|---|---|
| Market | Semiconductor Wafer Market |
| Base year | 2026 |
| Historical reference | 2025 |
| Forecast period | 2026 to 2036 |
| Currency and units | USD billion |
| Segmentation | Process Node, Application |
| Geographical coverage | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East & Africa |
| Country profiles | United States, Germany, China, India, United Kingdom |
| Competition | Representative participants, product positioning and purchasing distinctions |
Semiconductor Wafer Market Research Methodology
Table 7: Research methods for the semiconductor wafer market
| Method | Approach |
|---|---|
| Market definition | The study defines semiconductor wafer revenue within the stated product, service and application coverage, retaining the distinction between market sales and adjacent economic activity. |
| Desk research | Public FMI research, official institutional publications, technical documentation and company disclosures provide the evidence for market conditions and participant positioning. |
| Segmentation | Demand is organized by process node, application, with leading segment shares assessed separately within each category rather than added across categories. |
| Country assessment | The country outlook considers adoption conditions, purchasing practices, local deployment requirements and the operating constraints relevant to each profiled market. |
| Forecast assessment | The 2026 to 2036 outlook considers demand formation, replacement cycles, supplier capacity and the commercial conditions described in the market analysis. |
| Competitive comparison | Representative companies are compared by their stated offerings and role in the value chain, without treating every participant as an interchangeable supplier. |
Semiconductor Wafer Market by Segments
Semiconductor Wafer Market segmented by Process Node:
- 3nm
- 5nm
- 7nm
- 8nm
- 10nm
- 16nm
- 20nm
- 28nm
- 40nm
- other nodes
Semiconductor Wafer Market segmented by Application:
- automotive
- consumer electronics
- industrial manufacturing
- telecommunications
- other applications
Semiconductor Wafer Market by Region
North America
- USA
- Canada
- Mexico
Latin America
- Brazil
- Chile
- Rest of Latin America
Western Europe
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
Eastern Europe
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
East Asia
- China
- Japan
- South Korea
South Asia and Pacific
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
Middle East & Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Turkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
Research Sources and Bibliography
- [1] Future Market Insights. Accessed 14 October 2026. Semiconductor Wafer Market
- [2] SEMI. Accessed 14 October 2026. 2025 silicon wafer results
- [3] SUMCO. Accessed 14 October 2026. Wafer product lineup
- [4] GlobalWafers. Accessed 14 October 2026. GlobalWafers America opening
- [5] UK Department for Science Innovation and Technology. Accessed 14 October 2026. National Semiconductor Strategy
This Report Answers
- How big is the semiconductor wafer market in 2026?
- What is the market forecast for 2036?
- Which segment leads demand in 2026?
- Which countries are profiled in the market outlook?
- Which companies are covered in the competitive analysis?
Frequently Asked Questions
How big is the semiconductor wafer market in 2026?
The market is estimated at USD 25.50 billion in 2026, within the defined product and service coverage. [1]
What is the market forecast for 2036?
Market revenue is projected to reach USD 40.40 billion by 2036, representing a CAGR of 4.7% from 2026 to 2036. [1]
Which segment leads demand in 2026?
The 3nm segment is estimated to hold a 15.6% share within the process node category in 2026, with demand shaped by the purchasing conditions described in the segment analysis. [1]
Which countries are profiled in the market outlook?
The country outlook profiles United States, Germany, China, India, United Kingdom, with a separate 2026 to 2036 CAGR and discussion of local purchasing conditions for each market. [1]
Which companies are covered in the competitive analysis?
Representative participants include Shin-Etsu Chemical, SUMCO, GlobalWafers, Siltronic, SK Siltron, whose offerings and value-chain roles are compared within the market coverage. [1]
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Process Node, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Process Node, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Process Node, 2026 to 2036
- 3nm
- 5nm
- 7nm
- 8nm
- 10nm
- 16nm
- 20nm
- 28nm
- 40nm
- other nodes
- Y-o-Y Growth Trend Analysis By Process Node, 2021 to 2025
- Absolute $ Opportunity Analysis By Process Node, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- automotive
- consumer electronics
- industrial manufacturing
- telecommunications
- other applications
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- Mexico
- By Process Node
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Process Node
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Chile
- Rest of Latin America
- By Process Node
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Process Node
- By Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Process Node
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Process Node
- By Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Process Node
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Process Node
- By Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Process Node
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Process Node
- By Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Process Node
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Process Node
- By Application
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Turkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Process Node
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Process Node
- By Application
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Process Node
- By Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Process Node
- By Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Process Node
- By Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Process Node
- By Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Process Node
- By Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Process Node
- By Application
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Process Node
- By Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Process Node
- By Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Process Node
- By Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Process Node
- By Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Process Node
- By Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Process Node
- By Application
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Process Node
- By Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Process Node
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Process Node
- By Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Process Node
- By Application
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Process Node
- By Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Process Node
- By Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Process Node
- By Application
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Process Node
- By Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Process Node
- By Application
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Process Node
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Shin-Etsu Chemical
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- SUMCO
- GlobalWafers
- Siltronic
- SK Siltron
- Shin-Etsu Chemical
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


