
- Market Size (2026)
- USD 1.3 Bn
- Forecast (2036)
- USD 2.6 Bn
- CAGR (2026 to 2036)
- 7.2%
How big is Smart Pump Market in 2026?
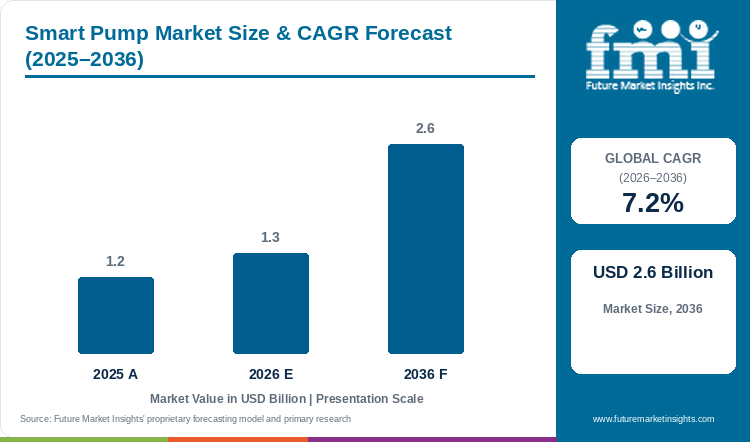
Assessed at USD 1.2 billion in 2025 and progressing to USD 1.3 billion in 2026, the smart pump market valuation is on course to reach USD 2.6 billion by 2036, supported by a forecast-period CAGR of 7.2%.
The global smart pump market reached USD 1.2 billion in 2025 and is projected to climb to USD 1.3 billion in 2026. Evaluation by Future Market Insights shows that the market valuation is on track to attain USD 2.6 billion by 2036, growing at a 7.2% CAGR from 2026 to 2036 and generating USD 1.3 billion in additional market value. The 7.2% growth rate in smart pumps is noticeably faster than the 4.8% CAGR seen across conventional industrial centrifugal pumps, as municipal water utilities and chemical plants shift procurement away from fixed-speed units toward inverter-driven pumps that automatically adjust flow and cut electricity bills. Centrifugal smart pumps are estimated to account for 69.2% of pump type demand in 2026 because variable-speed impeller control prevents throttling energy loss in continuous water and HVAC circulation loops. Increasing investments in municipal sewage treatment and water-reuse infrastructure are propelling the adoption of sensor-integrated pumping systems. According to Eurostat, in June 2026, wastewater treatment accounted for the largest 37.7% share of total European Union environmental protection capital investments recorded in 2025, directly increasing utility tenders for automated lift-station and dosing pumps [1]. Even so, high upfront cost of implementation and strict operational-technology network security audits restrict rapid retrofits in smaller utilities, leaving electricity payback within 24 to 36 months as the main factor deciding buyer adoption.
Key Market Trends & Insights
- By pump type: Centrifugal smart pumps are projected to capture 69.2% in 2026 because dynamic impeller speed modulation cuts booster station power draw.
- By component: Variable frequency drive integrated pumps are estimated to command 54.8% in 2026 as plant engineers specify factory-wired motor-drive packages.
- By end-use industry: Water and wastewater treatment is expected to concentrate 37.8% in 2026 owing to statutory sewage overflow and phosphorus removal mandates.
- By contract structure: Multi-year frame and service-level agreements are forecast to generate 54.5% in 2026 supported by guaranteed uptime and remote telemetry clauses.
- By sales channel: Direct OEM and EPC turnkey contracts are anticipated to account for 57.5% in 2026 while greenfield capacity and new installations hold 54.5% by project lifecycle stage.
Regional Highlights
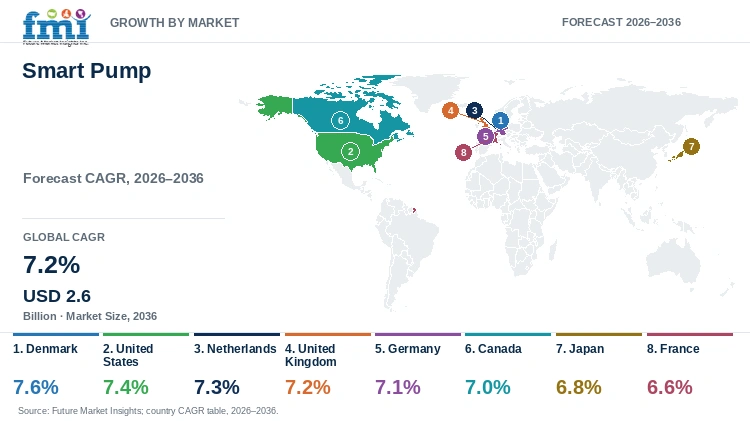
- Top national expansion: Denmark is projected to lead primary industrial markets at a 7.6% CAGR through 2036 driven by domestic smart circulator manufacturing and district heating networks.
- Broader country progression: The United States is expected to expand at 7.4% CAGR ahead of the Netherlands at 7.3% and the United Kingdom at 7.2%, while Germany, Canada, Japan, and France advance between 7.1% and 6.6%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Smart Pump Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 1.2 billion |
| Estimated Market Size in 2026 | USD 1.3 billion |
| Projected Market Size by 2036 | USD 2.6 billion |
| CAGR, 2026 to 2036 | 7.2% |
| Added Market Value, 2026 to 2036 | USD 1.3 billion |
Rising industrial power tariffs and unscheduled pump breakdowns are pushing water utilities and process plants to replace conventional fixed-speed motors with intelligent pumping systems. When a standard pump runs at full speed against a partially closed control valve during low-flow hours, electricity is wasted and excess pipe pressure causes mechanical seal leaks. According to a June 2026 control study published in Scientific Reports (PMC13139366), running a pump at constant motor speed consumes 68% of electrical energy across variable flow loads, whereas combining variable frequency drives with fault-tolerant level, speed, and pressure sensors prevents plant shutdowns [2]. Because of these savings, utility managers are upgrading municipal water pumps to self-regulating smart skids.
Installed Utility-Base and Pump-Unit Sizing
Table 2: Installed-Base and Unit-Requirement Sizing for the Smart Pump Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 1.2 | 1.3 | 2.6 |
| Active industrial & utility pump stations (thousand) | 410 to 450 | 430 to 475 | 720 to 790 |
| Annual smart pump units deployed (thousand) | 340 to 380 | 365 to 410 | 710 to 785 |
| Average system spend per smart pump unit (USD) | 3,150 to 3,520 | 3,170 to 3,560 | 3,310 to 3,660 |
Operational note: Installed-base ranges apply municipal drinking-water, wastewater, commercial HVAC, and process-industry pumping stations against verified factory shipments of VFD-integrated and sensor-equipped pump skids.
Expansion of commercial office retrofits, hospitals, and district heating grids is driving strong demand for electronically controlled wet-rotor circulators and pressure-boosting sets. In multi-story buildings, heating and cooling demand changes throughout the day as room thermostats open and close zone valves. Installing low-horsepower centrifugal water pumps with built-in proportional-pressure software allows building operators to cut HVAC pump electricity use by up to half while eliminating pipe noise and water-hammer damage.
Per Capita & Utility Facility Sizing
Table 3: Per Capita and Facility Spending Indicators for the Smart Pump Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Spend per 1,000 people (USD) | 146.3 | 156.6 | 288.9 |
| Annual spend per municipal or industrial station (USD) | 2,670 to 2,930 | 2,740 to 3,020 | 3,290 to 3,610 |
| Multi-year frame contract share (%) | 52.0% to 55.0% | 53.0% to 56.0% | 58.0% to 62.0% |
Table 4: Utility & Plant Procurement Indicators for the Smart Pump Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 1.3 billion | 2026 global market valuation baseline |
| Water utilities & process plants globally | 450,000 | Global municipal water, HVAC, and chemical plant registry |
| Market spend per facility | USD 2,889 | Annualized smart pump and sensor procurement |
| Water & wastewater share, 2026 | 37.8% | Leading end-use industry allocation |
Automation of chemical, pharmaceutical, and water-treatment dosing lines is also boosting the adoption of digital metering and positive-displacement smart pumps. Manual calibration of coagulant, chlorine, or solvent feed pumps often results in chemical overdosing or batch quality failures when raw water turbidity or process flow changes. To remove human error from industrial processes, plant engineers pair digital flow controllers with chemical metering pumps that automatically adjust stroke frequency and send smartphone or SCADA alerts if suction lines clog or run dry.
Analyst Perspective
"Industrial and municipal buyers evaluate smart pumps on kilowatt-hours saved per cubic meter pumped and verified avoidance of dry-run or cavitation seal failure. Manufacturers that pre-mount variable frequency drives and Bluetooth vibration accelerometers directly on the motor housing are capturing multi-year frame agreements ahead of bare-shaft pump suppliers."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the smart pump market segmented?
The smart pump market is segmented by pump type, component, end-use industry, contract structure, sales and procurement channel, and project lifecycle stage. In 2026, centrifugal smart pumps are projected at 69.2%, variable frequency drive integrated pumps at 54.8%, water and wastewater treatment at 37.8%, multi-year frame and service-level agreements at 54.5%, direct OEM and EPC turnkey contracts at 57.5%, and greenfield capacity and new installations at 54.5%.
By pump type: Centrifugal smart pumps and positive displacement smart pumps.
By component: Variable frequency drive integrated pumps, digital pump controllers, and IIoT vibration and cavitation sensors.
By end-use industry: Water and wastewater treatment, building HVAC hydronics, chemical and petrochemical processing, and oil, gas, and power generation.
By contract structure: Multi-year frame and service-level agreements, and spot equipment and project-specific capex.
By sales and lifecycle channel: Direct OEM and EPC turnkey contracts (57.5%), authorized industrial distributors and system integrators (42.5%), greenfield capacity and new installations (54.5%), and brownfield retrofit, upgrade, and MRO replacement (45.5%).
Why do Centrifugal Smart Pumps lead the pump type category?
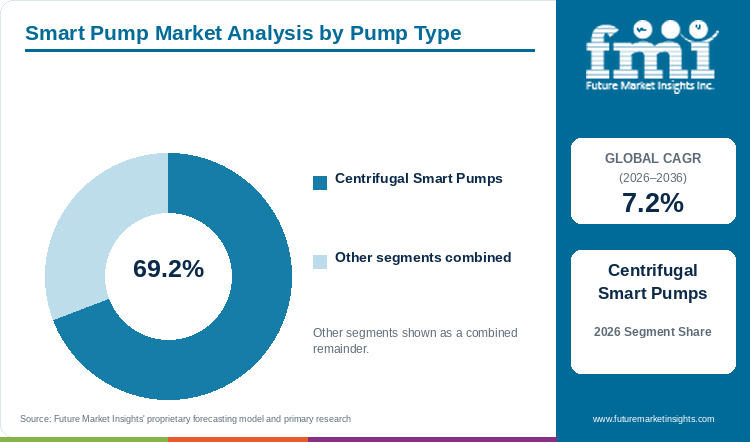
Centrifugal smart pumps are projected to capture 69.2% of pump type demand in 2026, supported by high-volume affinity-law energy savings.
Table 5: Pump Type Share for the Smart Pump Market (percentage share), 2026
| Pump Type | Share (2026) |
|---|---|
| Centrifugal Smart Pumps | 69.2% |
| Positive Displacement Smart Pumps | 30.8%* |
| Total | 100.0% |
*Note: Pump type categories sum to 100.0% of 2026 smart pump demand.
Table 6: Pump Type Leadership and Market Growth for the Smart Pump Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.2% |
| Leading Segment | Centrifugal Smart Pumps |
Demand projections compiled by Future Market Insights show that centrifugal smart pumps account for the largest share because municipal water intake, building cooling loops, and factory washdown lines move large volumes of low-viscosity water under variable daily demand. Under pump affinity laws, slowing a centrifugal impeller by just 20% reduces motor electricity consumption by nearly 50%. Adding onboard pressure and suction sensors to self-priming centrifugal pumps also stops the motor automatically if the intake pipe runs dry.
- Centrifugal smart pumps are projected to secure 69.2% of the pump type category in 2026 by delivering variable-flow efficiency across municipal water and commercial HVAC networks.
- According to an August 2025 fluid-mechanics study published in Micromachines (PMC12388805), fitting a pre-pressurizing inducer onto a high-speed centrifugal pump raises design head by 0.8 meters, improves hydraulic efficiency by 1.5%, and prevents cavitation damage [3].
Why do Variable Frequency Drive Integrated Pumps define the largest component segment?
Variable frequency drive integrated pumps are estimated to secure 54.8% of the component category in 2026, driven by plug-and-pump motor speed regulation.
Segment assessment by Future Market Insights indicates that buyers prefer variable frequency drive integrated pumps because mounting the inverter directly on the motor housing eliminates the cost of buying a separate wall-mounted control cabinet and running shielded cables. Plant maintenance crews can install a factory-wired VFD pump in hours without hiring external PLC programmers. Integrated drives also protect multistage electric submersible pumps against voltage spikes and motor overheating.
- Variable frequency drive integrated pumps are estimated to command 54.8% of the component segment in 2026 as facility managers prioritize single-unit installation and harmonic filtering.
- Per a January 2025 motor-drive study in Scientific Reports (PMC11775130), brushless DC and switched reluctance pump drives reach motor efficiencies of 91.9% and 94.6% respectively, whereas unoptimized inverter harmonics can lower induction motor efficiency by over 30% [4].
What keeps Water and Wastewater Treatment ahead by end-use industry?
Water and wastewater treatment is expected to command 37.8% of end-use industry volume in 2026 through continuous municipal lift-station and aeration upgrades.
Water and wastewater treatment utilities represent the largest end-use industry because pumping stations run 24 hours a day and account for up to 40% of a municipal water authority's total electricity bill. In addition to power savings, sewage utilities face heavy environmental fines when wet-well ragging or pump clogs cause raw sewage overflows during rainstorms. Utilities pair automated anti-clogging reversal controllers with high-head submersible pumps to keep municipal lift stations running without manual cleanouts.
- Water and wastewater treatment is expected to hold 37.8% of end-use industry demand in 2026 since environmental regulators penalize raw sewage spills and excessive abstraction.
- According to the UK Department for Environment, Food and Rural Affairs Wastewater Environment Act delivery plan updated in December 2025, water company phosphorus-reduction treatment plants across England maintain historical permit compliance above 99% over the 2025 to 2030 investment cycle [5].
Why do Multi-Year Frame and Service-Level Agreements lead the contract structure category?
Multi-year frame and service-level agreements are forecast to account for 54.5% of contract structure demand in 2026, owing to guaranteed efficiency and predictive maintenance clauses.
Industry tracking by Future Market Insights reveals that multi-year frame and service-level agreements generate the majority of contract value because utilities and chemical plants lack in-house vibration analysts to interpret pump sensor data. Under a three-to-five-year SLA, the pump manufacturer monitors cloud vibration and temperature alerts remotely and dispatches replacement mechanical seals and bearings before a breakdown occurs.
- Multi-year frame and service-level agreements are forecast to account for 54.5% of contract structure demand in 2026 as plant operators outsource vibration diagnostics to pump OEMs.
- In March 2026, KSB SE & Co. KGaA reported 2.9% order intake growth and 2.3% sales expansion for fiscal 2025 as its KSB SupremeServ aftermarket and digital service business generated one-third of group turnover [6].
What gives Direct OEM and EPC Turnkey Contracts and Greenfield Installations the leading channel and lifecycle positions?
Direct OEM and EPC turnkey contracts are anticipated to account for 57.5% of sales channel demand in 2026, while greenfield capacity and new installations hold 54.5% of project lifecycle demand.
Direct procurement through OEMs and EPC turnkey contractors leads the channel mix because new desalination plants, semiconductor ultrapure water fabs, and municipal treatment works require custom-engineered pump skids pre-tested to match central SCADA networks. Greenfield projects account for 54.5% of demand since specifying smart VFD pumps during new plant construction avoids the piping and electrical panel re-wiring required in brownfield retrofits.
- Direct OEM and EPC turnkey contracts capture 57.5% of channel demand and greenfield installations hold 54.5% of lifecycle demand in 2026 given that new utility plants standardize on connected skids.
- In February 2026, Flowserve Corporation reported fourth-quarter 2025 bookings of USD 1.2 billion including 10% aftermarket growth as EPC turnkey and energy-transition pump orders expanded [7].
What are the drivers, restraints, and opportunities in the smart pump market?
In the smart pump market, the key driver is industrial water-reuse and HVAC efficiency regulation, the key restraint is operational-technology cybersecurity qualification, and the key opportunity is wireless cavitation telemetry.
- Driver: Rising industrial electricity prices and mandatory municipal wastewater nutrient-removal upgrades compel facilities to adopt VFD-integrated smart pumps.
- Restraint: High initial capital cost over standard fixed-speed induction pumps and strict operational-technology firewall audits slow adoption in smaller utilities.
- Opportunity: Retrofitting wireless Bluetooth vibration and acoustic cavitation sensors onto existing slurry, chemical, and water pumps expands recurring cloud diagnostics revenue.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Increasing industrial water-reuse mandates and rising factory electricity bills are the primary factors driving demand for smart pumps across semiconductor, chemical, and food processing plants. Instead of discharging process rinse water and cooling tower blowdown into municipal sewers, factories are installing closed-loop membrane filtration skids that require automated pressure-regulated pumps paired with precision peristaltic pumps for chemical dosing. Market analysis from Future Market Insights points to government funding as a major driver, with the U.S. Department of Energy and the National Alliance for Water Innovation issuing a USD 12 million solicitation in July 2026 to fund industrial water-reuse projects across U.S. factories [8]. Plant managers are signing multi-year contracts for connected pump skids.
Risk Assessment of the Smart Pump Market: Operational and Formulation Friction
High initial purchase prices compared with basic fixed-speed pumps, impeller cavitation damage during off-design flows, and strict industrial cybersecurity rules are the main factors restraining market adoption. When a centrifugal pump runs below 80% or above 120% of its Best Efficiency Point, collapsing vapor bubbles pit the metal impeller and shake the shaft bearings. According to a January 2026 computational fluid dynamics study in Scientific Reports (PMID 41521196), impeller outlet velocity drops from 5.0 m/s to 3.0 m/s under low-flow cavitation while axial backflow climbs from 2.0 m/s to 7.0 m/s [9]. In biotech and food plants where sanitary diaphragm pumps operate, IT security teams also block cloud pump gateways that lack encrypted firmware.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Retrofitting wireless vibration, temperature, and cavitation sensors onto existing industrial and municipal pumps is creating strong aftermarket growth opportunities for pump manufacturers. In mining slurry lines and liquefied gas terminals where cryogenic transfer pumps run continuously, an unexpected bearing seizure or seal failure halts plant output and causes heavy financial losses. According to a 2026 experimental study in Data in Brief (PMC13251777), fitting slurry pumps with Bluetooth wireless triaxial accelerometers and pressure sensors enables real-time condition monitoring under abrasive duty cycles [10]. By offering clamp-on wireless sensor pods that connect to mobile apps and plant dashboards, manufacturers convert older installed pump bases into recurring software subscriptions.
Smart Pump Market by Country (2026 to 2036)
Country-level evaluation by Future Market Insights indicates that Denmark represents the fastest-growing market at a 7.6% CAGR from 2026 to 2036, while France records a 6.6% CAGR over the same period. Across all eight evaluated economies, growth is driven by municipal wastewater treatment investments, district heating automation, and industrial motor efficiency standards.
Table 7: Country CAGR and Primary Growth Levers for the Smart Pump Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Denmark | 7.6% | District heating network automation and domestic smart circulator R&D leadership |
| United States | 7.4% | EPA municipal sewage conveyance upgrades and DOE industrial water-reuse programs |
| Netherlands | 7.3% | Polder water-level pump automation and tertiary nitrogen-removal wastewater retrofits |
| United Kingdom | 7.2% | AMP8 water utility investment cycle and statutory phosphorus-reduction mandates |
| Germany | 7.1% | Commercial HVAC hydronic renovation and chemical process digital twin integration |
| Canada | 7.0% | Municipal sewage lift-station modernization and cold-climate industrial water recycling |
| Japan | 6.8% | Semiconductor ultrapure water fab buildouts and aging municipal booster station automation |
| France | 6.6% | Municipal drinking-water leak reduction mandates and nuclear power cooling upgrades |
Source: Future Market Insights analysis
Denmark Smart Pump Market Outlook (2026 to 2036)
Nationwide automation of district heating networks and strong domestic research and development make Denmark the fastest-growing smart pump market at a projected 7.6% CAGR through 2036. Danish municipal heating and water utilities across Copenhagen, Aarhus, and Odense use variable-speed booster pumps with built-in differential-pressure sensors to lower network water temperatures and cut heat loss. For instance, in August 2025, Grundfos Holding A/S reported 5.1% organic sales growth in the first half of 2025 and a 12.2% operating profit margin before special items on expanding sales of connected commercial building and water utility pumps [11]. Because basic circulator penetration is already high in Denmark, buyers focus on upgrading to cloud-linked multi-pump control systems.
Key takeaway: In Denmark, nationwide district-heating automation and Grundfos smart pump innovation are projected to anchor a 7.6% CAGR through 2036.
United States Smart Pump Market Outlook (2026 to 2036)
Federal municipal sewage pump-station rehabilitation and industrial water-reuse investments are projected to drive the United States smart pump market at a 7.4% CAGR through 2036. Municipal water authorities operating under federal consent decrees are replacing fixed-speed sewage lift stations with SCADA-connected submersible smart pumps that prevent wet-well overflows during storms. For instance, in September 2026, the U.S. Environmental Protection Agency reported that Phase 2 construction under the Border Water Infrastructure Program began with rehabilitation of the Matadero and Laureles II pump stations and more than 3,400 meters of sewer conveyance lines [12]. Fragmented municipal bidding rules across local water districts still lengthen sales cycles for new suppliers.
Key takeaway: In the United States, federal municipal sewage pump-station rehabilitation and industrial water-reuse grants are projected to sustain a 7.4% CAGR through 2036.
Netherlands Smart Pump Market Outlook (2026 to 2036)
Automated polder water-level management and strict municipal nitrogen- and phosphorus-removal rules are estimated to propel the Netherlands smart pump market at a 7.3% CAGR from 2026 to 2036. Regional Dutch water boards rely on sensor-controlled pumping stations that automatically adjust discharge rates based on rainfall radar, canal water levels, and North Sea tide cycles. According to the European Commission and European Environment Agency country profile updated in June 2026, 99.6% of the urban wastewater load in the Netherlands is treated in tertiary removal plants [13]. Because regional electricity grids in the Netherlands face peak-hour congestion, water boards require smart VFD pumps with load-shifting software that runs heavy pumping during high solar and wind generation hours.
Key takeaway: In the Netherlands, automated polder drainage stations and tertiary wastewater treatment retrofits are estimated to drive a 7.3% CAGR through 2036.
United Kingdom Smart Pump Market Outlook (2026 to 2036)
Mandatory wastewater treatment and storm-overflow monitoring investments under the 2025 to 2030 Asset Management Period 8 (AMP8) regulatory cycle are anticipated to drive United Kingdom smart pump demand at a 7.2% CAGR through 2036. Water utilities in England and Wales face strict fines if unmonitored sewage pumps clog or spill untreated effluent into rivers. According to a May 2026 reliability optimization study in Scientific Reports (PMC13319237), installing parallel redundant centrifugal pumping systems with automated switchover prevents municipal water supply outages during peak demand [14]. To meet regulatory uptime targets, UK water companies are buying self-cleaning VFD wastewater pumps and automated chemical-dosing skids under five-year utility framework agreements.
Key takeaway: In the United Kingdom, statutory AMP8 wastewater treatment investments and storm-overflow telemetry mandates are anticipated to drive a 7.2% CAGR.
Germany Smart Pump Market Outlook (2026 to 2036)
Commercial building heating renovations and chemical industry predictive maintenance programs are forecast to expand the German smart pump market at a 7.1% CAGR from 2026 to 2036. High industrial electricity rates and federal building energy laws compel German property owners and factory engineers to replace older fixed-speed heating and cooling pumps with IE5 permanent-magnet smart circulators. In July 2025, Dortmund-based Wilo SE published its annual sustainability and financial report detailing expanded deployments of connected hydronic circulators and digital water utility pumps across European retrofit projects [15]. Although slower new apartment construction tempers residential orders, strong commercial and chemical plant energy-saving retrofits sustain German demand.
Key takeaway: In Germany, commercial building heating renovations and chemical plant predictive maintenance are forecast to drive a 7.1% annual growth pace.
Canada Smart Pump Market Outlook (2026 to 2036)
Upgrades to municipal drinking-water and sewage lift stations across Ontario, Quebec, and British Columbia and industrial water recycling in western resource provinces are slated to support a 7.0% CAGR in Canada through 2036. Sub-zero winter ground frost causes frequent cast-iron water-main breaks unless municipal booster stations use variable-speed smart pumps to smooth out night-time pressure spikes. According to Statistics Canada's Municipal Wastewater Systems report in June 2026, Canadian municipal utilities treated over 6,100 million cubic meters of wastewater annually while modernizing secondary and tertiary treatment plants [16]. Short outdoor construction seasons in northern municipalities also favor pre-assembled, factory-tested smart pump skids.
Key takeaway: In Canada, municipal wastewater lift-station upgrades and pressure-modulated water distribution skids are slated to support a 7.0% CAGR through 2036.
Japan Smart Pump Market Outlook (2026 to 2036)
Semiconductor foundry ultrapure-water buildouts in Kyushu and Hokkaido and automated monitoring of aging municipal waterworks are estimated to drive the Japanese smart pump market at a 6.8% CAGR through 2036. Because municipal water bureaus face retirements of experienced maintenance technicians, utilities install cloud-connected booster pumps that report bearing vibration and seal wear remotely from unmanned stations. According to a May 2026 study in Scientific Reports (PMC13357540) on Field-Oriented Control and Maximum Power Point Tracking in induction motor pumping systems, decoupling flux and torque reaches 99.6% tracking efficiency while removing unstable torque ripple [17]. Strict municipal technical standards in Japan favor domestic manufacturers with local service depots.
Key takeaway: In Japan, semiconductor fab ultrapure water investments and municipal telemetry upgrades are estimated to support a 6.8% CAGR through 2036.
France Smart Pump Market Outlook (2026 to 2036)
National municipal drinking-water leak-reduction targets and industrial wastewater treatment upgrades are projected to support a 6.6% CAGR in the French smart pump market through 2036. Under France's national water-sobriety plan, municipal water syndicates are installing pressure-modulated smart booster pumps and acoustic leak sensors to cut distribution pipe losses across urban and rural communes. In October 2026, the European Commission highlighted the LIFE4FARMS smart sensor-monitored wastewater treatment project that cuts nitrogen pollution by 70% and pharmaceutical residues by 80% [18]. Multi-stage budget approvals among smaller French municipal water syndicates still lengthen tender timelines for full-network retrofits.
Key takeaway: In France, municipal distribution pressure modulation and industrial effluent treatment investments are projected to sustain a 6.6% CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the smart pump market?
Grundfos Holding A/S, Xylem Inc., KSB SE & Co. KGaA, Wilo SE, Sulzer Ltd., Flowserve Corporation, ITT Inc., and Ebara Corporation are the notable companies in the smart pump market.
Competitive tracking by Future Market Insights shows that the smart pump market is moderately consolidated among European smart circulator and water pump manufacturers, North American digital water technology groups, and industrial process-pump specialists. Leading vendors combine IE5 permanent-magnet motors, integrated variable frequency drives, and wireless vibration sensors to win multi-year utility and plant service agreements.
- Smart Circulator & Building Hydronics Leaders: Grundfos Holding A/S and Wilo SE lead in electronically commutated wet-rotor circulators, booster sets, and district heating pump automation.
- Digital Municipal Water & Wastewater Platforms: Xylem Inc., KSB SE & Co. KGaA, and Sulzer Ltd. supply sensor-integrated submersible sewage pumps, digital twins, and utility treatment systems.
- Industrial Process & Petrochemical Flow Specialists: Flowserve Corporation, ITT Inc., and Ebara Corporation deliver IIoT-monitored chemical, refinery, and semiconductor process pumps.
Competitive Benchmarking: Smart Pump Market
Table 8: Competitive Benchmarking for the Smart Pump Market (qualitative capability ratings), 2026
| Company | Integrated VFD & Motor Breadth | IIoT Cavitation & Vibration Telemetry | Utility & EPC Turnkey Access | Geographic Reach |
|---|---|---|---|---|
| Grundfos Holding A/S | High | High | High | High |
| Xylem Inc. | High | High | High | High |
| KSB SE & Co. KGaA | High | High | High | High |
| Wilo SE | High | Medium | High | High |
| Sulzer Ltd. | Medium | High | High | High |
| Flowserve Corporation | Medium | High | High | High |
| ITT Inc. | Medium | High | High | High |
| Ebara Corporation | High | Medium | High | High |
Scoring basis: Capability tiers evaluate factory-mounted IE5 permanent-magnet motor and VFD options, onboard vibration and cavitation diagnostics, and multi-protocol SCADA integration. Access and geographic scores reflect verified municipal utility frame contracts and global EPC pre-qualification.
Key Developments in the Smart Pump Market
- In July 2026, Sulzer Ltd. reported that its first-half 2026 operational EBITDA margin expanded to 15.5% supported by strong municipal water and industrial flow division execution [19].
- In February 2026, Xylem Inc. reported fourth-quarter 2025 revenue of USD 2.4 billion and full-year 2025 revenue of USD 9.0 billion, supported by digital water utility and smart pumping orders [20].
- In February 2026, Ebara Corporation reported 11.2% consolidated revenue growth for fiscal 2025 across its building service, energy, and precision semiconductor fluid machinery divisions [21].
Key Players in the Smart Pump Market
Smart Hydronics and Water Circulation Platforms
- Grundfos Holding A/S
- Wilo SE
- Ebara Corporation
Digital Municipal Water and Wastewater Leaders
- Xylem Inc.
- KSB SE & Co. KGaA
- Sulzer Ltd.
Industrial Process and Severe-Service Flow Specialists
- Flowserve Corporation
- ITT Inc.
Smart Pump Market - Report Scope
Table 9: Report Scope for the Smart Pump Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Pump Type; Component; End-Use Industry; Contract Structure; Sales and Procurement Channel; Project Lifecycle Stage |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial manufacturer valuation from centrifugal and positive-displacement smart pumps equipped with integrated variable frequency drives, digital controllers, or IIoT condition-monitoring sensors. Category Scope Note: Excludes bare-shaft fixed-speed pumps sold without electronic drives or telemetry sensors and medical infusion pumps. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Denmark, United States, Netherlands, United Kingdom, Germany, Canada, Japan, France, and additional countries in the full report |
| Key Companies Covered | Grundfos Holding A/S, Xylem Inc., KSB SE & Co. KGaA, Wilo SE, Sulzer Ltd., Flowserve Corporation, ITT Inc., Ebara Corporation |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Smart Pump Market - Research Methodology
Table 10: Research Methodology for the Smart Pump Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with municipal water utility chief engineers, EPC fluid-handling leads, and industrial plant reliability managers to validate VFD attach rates and SLA contract pricing. |
| Secondary Research | Analysis of corporate annual reports (Grundfos, Xylem, KSB, Wilo, Sulzer, Flowserve, ITT, Ebara), Eurostat environmental investment releases, U.S. EPA and DOE water program filings, and peer-reviewed pump engineering studies. |
| Market Sizing and Forecasting | Top-down intelligent flow-control shipment models reconciled against bottom-up station installations and VFD/sensor retrofit volumes from 2026 to 2036. |
| Country Forecasting Model | Econometric national projections weight municipal wastewater capex (such as UK AMP8 and EU urban wastewater directives), industrial electricity tariffs, and semiconductor/chemical buildouts. |
| Operational Benchmark Traceability | Station-pool and facility spending indicators in Tables 2, 3, and 4 trace to Eurostat environmental investment records, DEFRA phosphorus plans, and PMC pump efficiency studies. |
| Data Triangulation and Validation | Demand estimates are cross-checked against manufacturer flow-division revenues and utility procurement disclosures without double counting standalone control valves or medical infusion devices. |
Smart Pump Market by Segments
Smart Pump Market segmented by Pump Type:
- Centrifugal Smart Pumps
- Positive Displacement Smart Pumps
- Radial & Mixed-Flow Smart Units
- Rotary & Reciprocating Smart Dosing
Smart Pump Market segmented by Component:
- Variable Frequency Drive Integrated Pumps
- Digital Pump Controllers
- IIoT Vibration and Cavitation Sensors
Smart Pump Market segmented by End-Use Industry:
- Water and Wastewater Treatment
- Building HVAC Hydronics
- Chemical and Petrochemical Processing
Smart Pump Market segmented by Contract Structure:
- Multi-Year Frame and Service-Level Agreements
- Spot Equipment and Project-Specific Capex
- Performance-Guaranteed Energy Contracts
- Predictive Diagnostics Subscriptions
Smart Pump Market segmented by Channel & Lifecycle:
- Direct OEM and EPC Turnkey Contracts
- Authorized Industrial Distributors
- Greenfield Capacity Installations
- Brownfield Retrofit and MRO
- System Integrators
Smart Pump Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Eurostat. (2026, June 24). Wastewater drives investments in environmental protection. European Commission Eurostat.
- [2] Irfan, M., et al. (2026, June 3). Design of a fault-tolerant control system for a centrifugal pump-based level control system for sensor faults. Scientific Reports (PubMed PMID 41857174, PMCID PMC13139366).
- [3] Zhou, X., et al. (2025, August 19). Influence of the Inducer on the Performance of a Miniature High-Speed Centrifugal Pump. Micromachines, 16(8), 952 (PubMed PMID 40872459, PMCID PMC12388805).
- [4] Kumar, R., et al. (2025, January 28). Comparative analysis of brushless DC and switched reluctance motors for off-grid water pumping applications. Scientific Reports (PMCID PMC11775130).
- [5] Department for Environment, Food and Rural Affairs. (2025, December 1). Wastewater Environment Act target delivery plan (2025 to 2030 investment cycle). GOV.UK.
- [6] KSB SE & Co. KGaA. (2026, March 26). Annual General Meeting 2026 and Financial Year 2025 Results. KSB Investor Relations.
- [7] Flowserve Corporation. (2026, February 5). Flowserve Corporation Reports Fourth Quarter and Full Year 2025 Results. Flowserve Corporation Investor Relations.
- [8] U.S. Department of Energy. (2026, July 28). National Alliance for Water Innovation Seeks Proposals for Industrial Water Reuse (USD 12 Million RFP). U.S. Department of Energy.
- [9] Fang, M., et al. (2026, January 11). Numerical prediction of cavitation performance of a prototype pump as turbine based on CFD. Scientific Reports, 16(1), 4035 (PubMed PMID 41521196, PMCID PMC12855978).
- [10] More, S. R., et al. (2026, April 15). Design, development and testing of a digitally instrumented slurry pump test rig for real-time condition monitoring. Data in Brief (PMCID PMC13251777).
- [11] Grundfos Holding A/S. (2025, August 21). Grundfos is experiencing strong growth in key markets. Grundfos Media.
- [12] U.S. Environmental Protection Agency. (2026, September 30). EPA Tijuana Sewage Crisis Quarterly Update: Phase 2 Border Water Infrastructure Program and Pump Station Rehabilitation. U.S. Environmental Protection Agency.
- [13] European Commission & European Environment Agency. (2026, June 16). Netherlands Country Profile on Urban Waste Water Treatment. Water Information System for Europe (WISE).
- [14] Sharma, A., et al. (2026, May 12). Enhancing sustainability through reliability optimization of redundant centrifugal pumping systems in state water supply networks. Scientific Reports (PMCID PMC13319237).
- [15] Wilo SE. (2025, July 2). Wilo Group Annual Report: Connected Hydronic and Water Pumping Solutions. Wilo SE.
- [16] Statistics Canada. (2026, June 30). The Daily: Municipal wastewater systems in Canada. Statistics Canada.
- [17] Hassan, T., et al. (2026, May 20). Performance analysis of MPPT techniques in a PV-powered water pumping system with Field-Oriented Control. Scientific Reports (PMCID PMC13357540).
- [18] European Commission. (2026, October 18). New LIFE Project Summaries: Smart Sensor-Monitored Wastewater Treatment (LIFE4FARMS). European Commission Press Corner.
- [19] Sulzer Ltd. (2026, July 24). Sulzer Midyear Report 2026: Financial Review. Sulzer Investor Relations.
- [20] Xylem Inc. (2026, February 10). Xylem Reports Fourth Quarter and Full Year 2025 Results. Xylem Inc. Newsroom.
- [21] Ebara Corporation. (2026, February 13). Consolidated Financial Results for the Fiscal Year Ended December 31, 2025. Ebara Corporation Investor Relations.
- [22] Sulzer Ltd. (2026, February 26). Sulzer Annual Report 2025: Business and Financial Review. Sulzer Investor Relations.
- [23] ITT Inc. (2026, February 5). ITT Reports Fourth Quarter and Full Year 2025 Financial Results. ITT Inc. Investor Relations.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the smart pump market in 2026 and what is forecast for 2036?
- Which utility electricity and wastewater compliance pressures support demand for smart pumps?
- Why do Centrifugal Smart Pumps lead the pump type category?
- Why do Variable Frequency Drive Integrated Pumps lead the component category globally?
- How do growth rates differ across Denmark, the United States, the Netherlands, and the UK?
- Which leading companies supply intelligent pumping and telemetry systems today?
- What limits adoption or delays brownfield retrofits in the smart pump market?
- What should utility and plant buyers evaluate before purchasing a smart pump?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Pump Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Pump Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Pump Type, 2026 to 2036
- Centrifugal Smart Pumps
- Positive Displacement Smart Pumps
- Radial & Mixed-Flow Smart Units
- Rotary & Reciprocating Smart Dosing
- Y-o-Y Growth Trend Analysis By Pump Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Pump Type, 2026 to 2036
- Global Market Analysis and Forecast, By Component, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Component, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Component, 2026 to 2036
- Variable Frequency Drive Integrated Pumps
- Digital Pump Controllers
- IIoT Vibration and Cavitation Sensors
- Y-o-Y Growth Trend Analysis By Component, 2021 to 2025
- Absolute $ Opportunity Analysis By Component, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Industry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Industry, 2026 to 2036
- Water and Wastewater Treatment
- Building HVAC Hydronics
- Chemical and Petrochemical Processing
- Y-o-Y Growth Trend Analysis By End-Use Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Contract Structure, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Contract Structure, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Contract Structure, 2026 to 2036
- Multi-Year Frame and Service-Level Agreements
- Spot Equipment and Project-Specific Capex
- Performance-Guaranteed Energy Contracts
- Predictive Diagnostics Subscriptions
- Y-o-Y Growth Trend Analysis By Contract Structure, 2021 to 2025
- Absolute $ Opportunity Analysis By Contract Structure, 2026 to 2036
- Global Market Analysis and Forecast, By Channel & Lifecycle, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Channel & Lifecycle, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Channel & Lifecycle, 2026 to 2036
- Direct OEM and EPC Turnkey Contracts
- Authorized Industrial Distributors
- Greenfield Capacity Installations
- Brownfield Retrofit and MRO
- System Integrators
- Y-o-Y Growth Trend Analysis By Channel & Lifecycle, 2021 to 2025
- Absolute $ Opportunity Analysis By Channel & Lifecycle, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- By Country
- Market Attractiveness Analysis
- By Country
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- By Country
- Market Attractiveness Analysis
- By Country
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- By Country
- Market Attractiveness Analysis
- By Country
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- By Country
- Market Attractiveness Analysis
- By Country
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- By Country
- Market Attractiveness Analysis
- By Country
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- By Country
- Market Attractiveness Analysis
- By Country
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- By Country
- Market Attractiveness Analysis
- By Country
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- Denmark
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- Netherlands
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Pump Type
- By Component
- By End-Use Industry
- By Contract Structure
- By Channel & Lifecycle
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Grundfos Holding A/S
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Xylem Inc.
- KSB SE & Co. KGaA
- Wilo SE
- Sulzer Ltd.
- Flowserve Corporation
- ITT Inc.
- Ebara Corporation
- Grundfos Holding A/S
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Pump Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Component, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Contract Structure, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Channel & Lifecycle, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Pump Type, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Component, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Contract Structure, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Channel & Lifecycle, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Pump Type, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Component, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Contract Structure, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Channel & Lifecycle, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Pump Type, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Component, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Contract Structure, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Channel & Lifecycle, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Pump Type, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Component, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Contract Structure, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Channel & Lifecycle, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Pump Type, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Component, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Contract Structure, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Channel & Lifecycle, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Pump Type, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Component, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Contract Structure, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Channel & Lifecycle, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Pump Type, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Component, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Contract Structure, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Channel & Lifecycle, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Pump Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Pump Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Pump Type
- Figure 6: Global Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Component
- Figure 9: Global Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-Use Industry
- Figure 12: Global Market Value Share and BPS Analysis by Contract Structure, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Contract Structure, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Contract Structure
- Figure 15: Global Market Value Share and BPS Analysis by Channel & Lifecycle, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Channel & Lifecycle, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Channel & Lifecycle
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Pump Type, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Pump Type, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Pump Type
- Figure 32: North America Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Component
- Figure 35: North America Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by End-Use Industry
- Figure 38: North America Market Value Share and BPS Analysis by Contract Structure, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Contract Structure, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Contract Structure
- Figure 41: North America Market Value Share and BPS Analysis by Channel & Lifecycle, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Channel & Lifecycle, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Channel & Lifecycle
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Pump Type, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Pump Type, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Pump Type
- Figure 48: Latin America Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Component
- Figure 51: Latin America Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by End-Use Industry
- Figure 54: Latin America Market Value Share and BPS Analysis by Contract Structure, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Contract Structure, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Contract Structure
- Figure 57: Latin America Market Value Share and BPS Analysis by Channel & Lifecycle, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Channel & Lifecycle, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Channel & Lifecycle
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Pump Type, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Pump Type, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Pump Type
- Figure 64: Western Europe Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Component
- Figure 67: Western Europe Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by End-Use Industry
- Figure 70: Western Europe Market Value Share and BPS Analysis by Contract Structure, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Contract Structure, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Contract Structure
- Figure 73: Western Europe Market Value Share and BPS Analysis by Channel & Lifecycle, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Channel & Lifecycle, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Channel & Lifecycle
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Pump Type, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Pump Type, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Pump Type
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Component
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by End-Use Industry
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Contract Structure, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Contract Structure, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Contract Structure
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Channel & Lifecycle, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Channel & Lifecycle, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Channel & Lifecycle
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Pump Type, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Pump Type, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Pump Type
- Figure 96: East Asia Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Component
- Figure 99: East Asia Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by End-Use Industry
- Figure 102: East Asia Market Value Share and BPS Analysis by Contract Structure, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Contract Structure, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Contract Structure
- Figure 105: East Asia Market Value Share and BPS Analysis by Channel & Lifecycle, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Channel & Lifecycle, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Channel & Lifecycle
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Pump Type, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Pump Type, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Pump Type
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Component
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by End-Use Industry
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Contract Structure, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Contract Structure, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Contract Structure
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Channel & Lifecycle, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Channel & Lifecycle, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Channel & Lifecycle
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Pump Type, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Pump Type, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Pump Type
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Component
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by End-Use Industry
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Contract Structure, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Contract Structure, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Contract Structure
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Channel & Lifecycle, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Channel & Lifecycle, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Channel & Lifecycle
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the smart pump market in 2026, and what is forecast for 2036?
Research compiled by Future Market Insights estimates that the global smart pump market value will reach USD 1.3 billion in 2026 from USD 1.2 billion in 2025. The market valuation is forecast to reach USD 2.6 billion by 2036 as water utilities and industrial plants automate fluid handling.
What is the CAGR for the smart pump market from 2026 to 2036?
Forecast modeling by Future Market Insights projects a 7.2% compound annual growth rate between 2026 and 2036, generating an estimated USD 1.3 billion increase in added market value across greenfield and brownfield channels.
Which pump type segment leads the smart pump market?
Centrifugal smart pumps are projected to capture 69.2% of pump type demand in 2026 because dynamic speed modulation delivers substantial affinity-law electricity savings across water and HVAC loops.
Which component segment leads the smart pump market?
Variable frequency drive integrated pumps are estimated to secure 54.8% of the component category in 2026 as buyers specify factory-wired motor-inverter packages that simplify installation.
Which country has a notable growth outlook during the assessment period?
Denmark is projected to lead primary industrial markets at a 7.6% CAGR through 2036, supported by automated district-heating networks and domestic smart pump manufacturing.
Who are the key players in the market?
Grundfos Holding A/S, Xylem Inc., KSB SE & Co. KGaA, Wilo SE, Sulzer Ltd., Flowserve Corporation, ITT Inc., and Ebara Corporation lead commercial supply across municipal, HVAC, and process-industry channels.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
