

- Market Size (2026)
- USD 344.1 Mn
- Forecast (2036)
- USD 977.0 Mn
- CAGR (2026 to 2036)
- 11.0%
How big is Smart Insole Market in 2026?
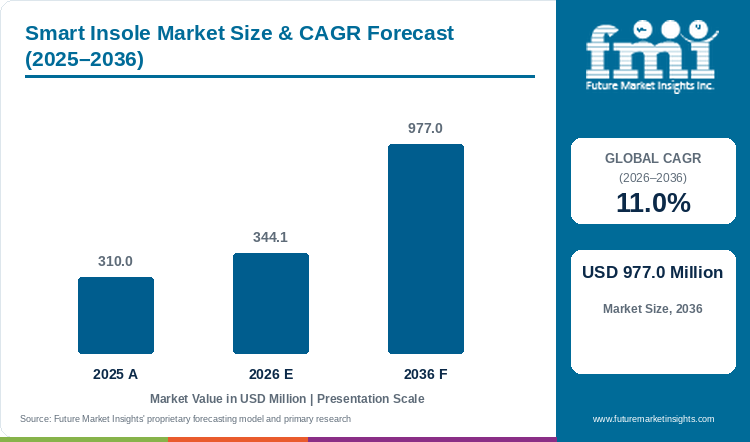
The smart insole market is estimated at USD 310.0 million in 2025 and is expected to reach USD 344.1 million in 2026. The market is projected to grow at an 11.0% CAGR and reach USD 977.0 million by 2036.
Sales of smart insoles are estimated at USD 310.0 million in 2025 and are forecast to grow at an 11.0% CAGR through 2036, rising from USD 344.1 million in 2026 to USD 977.0 million by 2036. US foot care budgets are moving from treating diabetic wounds toward preventing them, and plantar pressure tracking is central to prevention. CMS finalised a single Medicare payment of about $127.28 for skin substitutes from 1 January 2026, after Part B skin substitute payments passed $10 billion in 2024.[1] A lower wound-care payment makes an early pressure alert the cheaper route for podiatry clinics, so pressure-mapping insoles gain a clinical buyer with a cost case.
Court-sport and running buyers form the hottest cell of the buyer map, paying out of pocket and buying quickly, and sports and fitness is forecast to hold 38% of 2026 application sales. SFIA counted about 24.3 million US pickleball players in 2025, up 22.8%, with 4.5 million newcomers in the year.[2] Healthcare and rehabilitation forms a warm cell at roughly 32%, slowed by reimbursement rules and clinical sign-off, and industrial crews near 9% stay cool with occasional bulk orders. Suppliers selling direct through apps and web stores reach the hot sports cell fastest, and clinic sales need payer evidence and longer pilots before volumes build.
Key Market Trends & Insights
- Pressure-mapping models lead product sales at an estimated 41% in 2026, with heated insoles near 27%. Moticon added new gait outcome parameters such as clearance to ReGo in March 2026.[3]
- Consumer preference for phone pairing gives Bluetooth-connected insoles about 46% of 2026 technology sales by estimate.
- Online stores are estimated to hold 44% of channel sales in 2026, as app-led brands ship direct to buyers.
- Sports and fitness buyers are expected to hold roughly 38% of 2026 application sales, and healthcare and rehabilitation about 32%. SFIA counted 27.3 million US tennis players and 24.3 million pickleball players in 2025.[2]
Regional Highlights
- Chinese buyers give smart insoles the top profiled CAGR, 13.0% from 2026 to 2036.
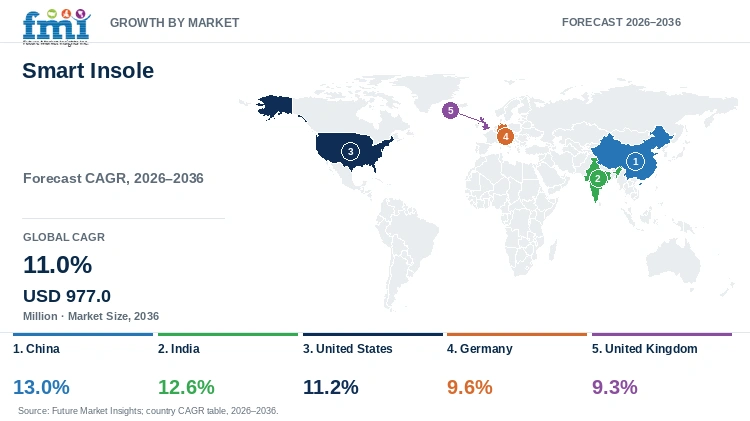
- India (12.6%) also grows above the 11.0% global CAGR, the United States (11.2%) stays near the global figure, and Germany (9.6%) and the United Kingdom (9.3%) grow below the global rate.
- China's GB 25038-2024 footwear standard reaches the end of the transition period on 1 December 2026.[4]
Market Size & Forecast
Table 1: Market Size and Forecast for the Smart Insole Market (USD million and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 310.0 million |
| Estimated Market Size in 2026 | USD 344.1 million |
| Projected Market Size by 2036 | USD 977.0 million |
| CAGR, 2026 to 2036 | 11.0% |
| Added Revenue, 2026 to 2036 | USD 632.9 million |
| Market Expansion Multiple | 2.8x |
Orders for smart insoles peak with sports seasons and clinic budget cycles. The USTA put 2025 play occasions above 616 million, with 14.5 million core players.[5] Core players play 10 or more times, so a gait or load tracker gives them data across a full season. Smart shoes with built-in sensors chase the same buyer. Growth of the smart shoe market at a 19.4% CAGR from 2026 to 2036 runs well ahead of insoles, so shoe brands will press insole makers on price. FMI expects the market to add USD 632.9 million between 2026 and 2036, a 2.8x expansion. Footwear chemical bans in Europe weigh on the USD 632.9 million addition, starting with the French ban on PFAS-containing footwear from 1 January 2026.[4]
Gait Data in Clinics and Courts
Clinics and research labs use pressure insoles to measure gait during rehabilitation, as FMI's assessment shows. Moticon's ReGo release of March 2026 added clearance and other gait test parameters and improved gait line calculation and spatial estimation.[3] Moticon's OpenGo software release of July 2026 added the import of ReGo raw data files.[6] Clinicians can now move patient data from rehabilitation tests into research software, which supports repeat orders from hospitals and universities.
Medicare payment changes are reaching diabetic foot care budgets in the United States. CMS set a single skin substitute payment rate of about $127.28 from 1 January 2026, after Part B payments for skin substitutes rose from $252 million in 2019 to over $10 billion in 2024.[1] Podiatrists and wound clinics will look for prevention tools that flag high plantar pressure before a wound opens, and pressure-mapping insoles fit that role.
Table 2: Clinical, Sports and Rule Indicators for the Smart Insole Market (dates, counts and payments), 2025 to 2027
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| CMS skin substitute rate, 2026 | About $127.28 | Wound-prevention budgets in the United States | [1] |
| Part B skin substitute payments, 2019 to 2024 | $252 million to over $10 billion | Diabetic foot cost pressure | [1] |
| Moticon ReGo release, March 2026 | New gait outcome parameters | Rehabilitation testing | [3] |
| US tennis core players, 2025 | 14.5 million | Season-long load tracking | [5] |
| US pickleball players, 2025 | 24.3 million, up 22.8% | Court-sport insole buyers | [2] |
| France PFAS footwear ban | From 1 January 2026 | Material choice for insoles | [4] |
| Denmark PFAS footwear ban | From 1 July 2026 | Material choice for sales in the EU | [4] |
Analyst Perspective
“My first regional pick is the United States. Medicare Part B payments for skin substitutes rose from $252 million in 2019 to over $10 billion in 2024, and CMS has now moved them to a single rate of about $127.28. I expect podiatrists to fund pressure-alert insoles that help patients avoid the wounds those products treat, and China will follow with the fastest profiled growth, at 13.0%.”
- Rahul Pandita, Principal Consultant, Future Market Insights.
How is the smart insole market segmented?
Smart insoles are segmented by product type, technology, sales channel, application and region. Pressure-mapping insoles lead product type at an estimated 41%, Bluetooth-connected designs lead technology at about 46% and online stores lead channels at an estimated 44% in 2026.
By product type: pressure-mapping insoles, GPS-enabled insoles, heated insoles, and others.
By technology: Bluetooth-connected, wireless charging, AI-integrated, and sensor-based.
By sales channel: supermarkets/hypermarkets, specialty stores, online, pharmacies/drug stores, and others.
By application: sports & fitness, healthcare & rehabilitation, daily wear, and industrial use.
By region: Insole buyers in Eastern Europe, East Asia (China), South Asia and Pacific (India), North America (the United States), Western Europe (Germany and the United Kingdom), Latin America, and Middle East and Africa.
Why do pressure-mapping insoles lead smart insole product sales?
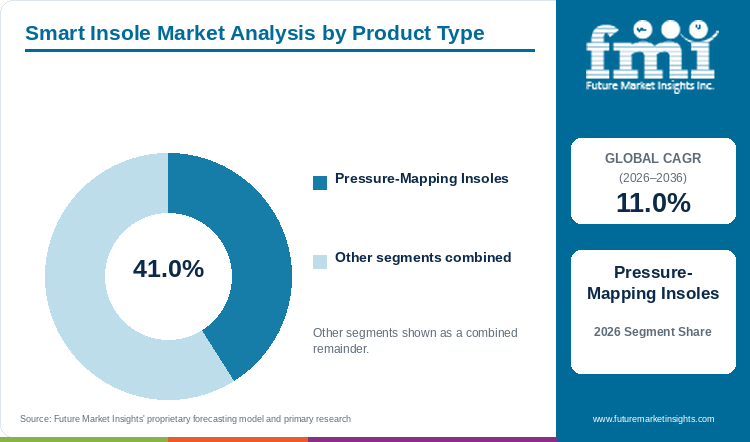
Pressure-mapping insoles lead product type with an estimated 41% share in 2026, heated insoles hold about 27% and GPS-enabled models roughly 14%.
Table 3: Product Type Share for the Smart Insole Market (percentage share), 2026
| Product Type | Estimated Share (2026) |
|---|---|
| Pressure-Mapping Insoles | 41% |
| Heated Insoles | 27% |
| Others | 18% |
| GPS-Enabled Insoles | 14% |
| Total | 100.0% |
Table 4: Product Leadership and Market Growth for the Smart Insole Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 11.0% |
| Leading Segment | Pressure-Mapping Insoles |
Pressure-mapping insoles are expected to lead with 41% share in 2026, because coaches, clinicians and runners all want the same measurement, the load under each part of the foot. Heated insoles hold about 27% (estimated), sold to outdoor workers, hunters and skiers, so sales fall outside winter. GPS-enabled insoles hold near 14% by estimate, aimed at families tracking older relatives, a narrow buyer group. Others, about 18% (estimated), include step counters and vibration insoles for balance training. Moticon improved gait line calculation and spatial estimation in the March 2026 ReGo release.[3] Clinics choosing between a heated insole and a measuring one will keep buying pressure maps, since only measurement feeds a treatment plan.
- Pressure-mapping buyers include running coaches, gait labs, physiotherapists and diabetic foot clinics.
- Clearance joined the gait outcome parameters in Moticon's March 2026 ReGo release.[3]
What keeps Bluetooth-connected insoles ahead in smart insole technology sales?
Bluetooth-connected insoles lead technology with about 46% share in 2026 by estimate, and sensor-based loggers hold about 28%.
Table 5: Technology Share for the Smart Insole Market (percentage share), 2026
| Technology | Estimated Share (2026) |
|---|---|
| Bluetooth-Connected | 46% |
| Sensor-Based | 28% |
| AI-Integrated | 15% |
| Wireless Charging | 11% |
| Total | 100.0% |
Bluetooth-connected insoles are projected to lead with 46% share in 2026, since phone pairing is the default for consumer buyers. Sensor-based loggers that store data on the insole hold about 28% (estimated), bought by labs that need raw data files, and Moticon's July 2026 OpenGo release added raw data import from ReGo.[6] AI-integrated models hold near 15% by estimate, priced above most consumer budgets. Wireless charging, about 11% (estimated), adds cost and bulk to a thin insole. Phone-linked fitness gear is growing across categories, and the smart fitness market is projected to grow at a 12.4% CAGR from 2026 to 2036, which keeps app-connected insoles in the same digital ecosystem as watches and trackers.
- Bluetooth-connected models pair with phone apps for running, gait and comfort tracking.
- On 2 February 2026, STMicroelectronics completed the purchase of NXP's MEMS sensors business.[7]
Why do online stores lead smart insole channel sales?
Online stores lead channel sales with an estimated 44% share in 2026, specialty stores hold about 24% and pharmacies roughly 15%.
Table 6: Sales Channel Share for the Smart Insole Market (percentage share), 2026
| Sales Channel | Estimated Share (2026) |
|---|---|
| Online | 44% |
| Specialty Stores | 24% |
| Pharmacies/Drug Stores | 15% |
| Supermarkets/Hypermarkets | 9% |
| Others | 8% |
| Total | 100.0% |
Online stores will lead with 44% share in 2026. App-led insole brands sell direct through web stores and marketplaces. Specialty running and sports stores hold about 24% (estimated), helped by in-store gait checks. Pharmacies and drug stores hold near 15% by estimate, selling heated and comfort-tech insoles beside foot care. Supermarkets and hypermarkets hold roughly 9% (estimated), and other channels such as clinics and employers about 8%. Skechers sells through about 5,300 Skechers retail stores and in about 180 countries and territories, which shows how far comfort footwear reaches through physical shelves.[8] Online share will stay ahead as subscription apps tie the insole to a monthly fee.
- Online sales run through brand web stores, marketplaces and app subscriptions.
- Skechers, ranked the second largest US footwear brand by units in August 2026, also sells through about 5,300 own stores.[8]
Why do sports and fitness uses lead smart insole applications?
Sports and fitness uses lead application with about 38% share in 2026 by estimate, with healthcare and rehabilitation close behind at roughly 32%.
Table 7: Application Share for the Smart Insole Market (percentage share), 2026
| Application | Estimated Share (2026) |
|---|---|
| Sports & Fitness | 38% |
| Healthcare & Rehabilitation | 32% |
| Daily Wear | 21% |
| Industrial Use | 9% |
| Total | 100.0% |
Sports and fitness is estimated to lead with 38% share in 2026. Athletes pay out of pocket and buy quickly. SFIA found gains in seven of the eight racquet sports tracked in 2025, with 4.5 million newcomers to pickleball alone.[2] Healthcare and rehabilitation follows at roughly 32% (estimated), slowed by reimbursement rules and clinical sign-off before purchase. Clinical gait and injury work also feeds sports medicine. At a 6.0% CAGR from 2026 to 2036 for the sports medicine market, rehabilitation clinics will keep adding insole tests to physiotherapy plans. Daily wear holds about 21% (estimated), held back by price against foam inserts. Industrial use holds near 9% by estimate. With the work shoes market projected at a 4.5% CAGR from 2026 to 2036, heated and fatigue-tracking insoles will reach factory and warehouse crews through work-boot dealers.
- Sports buyers include runners, court-sport players, gym members and team coaches.
- In 2025, 1.1 million more women played tennis in the United States than in 2024, the USTA said in February 2026.[5]
What are the drivers, restraints, and opportunities in the smart insole market?
Growth in court sports and running brings new buyers for sensor insoles who want load and stride data. PFAS bans on footwear raise material costs, and payer pressure on diabetic foot wounds opens a prevention channel in podiatry.
- Driver: Court-sport and running newcomers want load, step and stride data to avoid injury, which brings sensor insoles into the kit of recreational players.
- Restraint: PFAS bans on footwear force insole makers to replace coated foams and fabrics and test each material batch, raising unit costs for brands selling into Europe.
- Opportunity: Lower payments for skin substitutes push podiatry clinics toward preventing diabetic foot wounds, opening demand for pressure-alert insoles among patients with past ulcers.
Court Sports and Running Add Sensor Buyers
Adoption of smart insoles is growing with court-sport participation in the United States. The USTA counted 4.9 million first-time tennis players and 20.7 million retained players in 2025.[5] Pickleball added about 4.5 million new players in the same year.[2] FMI predicts that sales of smart insoles will rise at an 11.0% CAGR from 2026 to 2036. Court-sport players will buy load and step data first, and runners will follow with stride metrics. Runners choosing running shoes after a gait test want stride data on each run.
PFAS Footwear Bans Raise Material Costs
Insole makers selling in Europe face PFAS limits on foams, fabrics and coatings. France banned PFAS-containing footwear from 1 January 2026, and an EU-wide PFAS restriction may enter into force between 2026 and 2027.[4] California's AB 1817 limit on organic fluorine in textile articles, including footwear, drops to 50 ppm from 1 January 2027.[4] Brands will switch to PFAS-free top layers and test every material batch.
Wound Prevention Budgets Open a Clinical Channel
Medicare's single skin substitute rate from January 2026 moves attention from treating diabetic foot wounds to preventing them, and this shift opens a new phase of market expansion for smart insoles in podiatry clinics. CMS also finalised the use of hospital outpatient data for some remote monitoring services.[1] Podiatry practices will trial pressure-alert insoles for patients with past ulcers, and insole makers will seek payer coverage for those programmes.
Which country CAGRs are profiled in the smart insole market?
Table 8: Country CAGR Comparison for the Smart Insole Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| China | 13.0% |
| India | 12.6% |
| United States | 11.2% |
| Germany | 9.6% |
| United Kingdom | 9.3% |
How do country-level CAGRs compare in the smart insole market?
Chinese footwear brands face the end of the GB 25038-2024 transition on 1 December 2026, with limits on hexavalent chromium, dimethyl fumarate and four phthalates.[4] Against an 11.0% global CAGR, the profiled countries range from 9.3% to 13.0% from 2026 to 2036, with China at 13.0%, India at 12.6%, the United States at 11.2%, Germany at 9.6% and the United Kingdom at 9.3%, FMI's report shows. Online launches by Chinese and Indian brands put both countries above the global rate, and the United States stays close to the global figure. German and British sellers grow below the global rate, as EU PFAS limits and UK REACH Entry 72 files add testing cost to each model. Footwear standards matter most in China, sports participation in India, Medicare budgets in the United States, PFAS rules in Germany and REACH carry-over in the United Kingdom.
- China requires material documentation under GB 25038-2024.
- India adds sports insole buyers through cricket, running and gym culture.
- Buying in the United States follows the rise of court sports and wound-care budgets.
- German buyers face EU PFAS limits on insole materials.
- British sellers still follow REACH Annex XVII Entry 72 limits on 33 CMR substances.
Full report country CAGRs cover: China in East Asia, India in South Asia and Pacific, the United States in North America, Germany and the United Kingdom in Western Europe, and regional tables for Latin America, Eastern Europe, and Middle East and Africa.
Country-wise Analysis
China Smart Insole Market Outlook (2026 to 2036)
Sales of smart insoles in China are projected to grow at a 13.0% CAGR from 2026 to 2036, the top profiled rate, FMI's report shows. GB 25038-2024 came into effect on 1 June 2025 and limits hexavalent chromium in leather and fur to 10 mg/kg or less.[4] Xiaomi, H+ Technology and Bojin sell into China's online channel, and makers will add material test files to every new model.
Key takeaway: Material documentation is now the entry ticket for Chinese insole launches.
India Smart Insole Market Outlook (2026 to 2036)
In India, smart insoles are likely to grow at a 12.6% CAGR from 2026 to 2036, FMI predicts. Neomotion, XyberMed and Stridalyzer sell gait and running insoles to Indian runners and clinics, and online marketplaces will carry most first purchases.
Key takeaway: Online launches by local brands will drive growth in India.
United States Smart Insole Market Outlook (2026 to 2036)
Medicare budgets and court sports both feed demand in the United States. CMS cut skin substitute payments to a single rate of about $127.28 from 1 January 2026.[1] US tennis reached 27.3 million players in 2025.[5] FMI projects the United States at an 11.2% CAGR from 2026 to 2036, and Digitsole, Dr. Scholl's and Orpyx compete for American buyers.
Key takeaway: Court-sport players and wound-prevention programmes split sales in the United States.
Germany Smart Insole Market Outlook (2026 to 2036)
ECHA's scientific committees are expected to issue final opinions on the EU-wide PFAS restriction in 2026.[4] FMI expects smart insole sales in Germany to rise at a 9.6% CAGR from 2026 to 2036. Currex, Sidas and FeetMe will sell PFAS-free models to German running stores and orthopaedic shops.
Key takeaway: PFAS-free materials will be a German listing condition.
United Kingdom Smart Insole Market Outlook (2026 to 2036)
At 9.3% from 2026 to 2036, the United Kingdom is likely to see the lowest profiled CAGR for smart insoles. REACH Annex XVII Entry 72, which restricts 33 CMR substances, still applies in the United Kingdom.[4] Moticon, ARION and RunScribe sell gait insoles to British clubs and clinics, and sellers will keep EU and UK material files aligned.
Key takeaway: UK sellers keep one material file for both EU and British shelves.
Who are the notable companies in the smart insole market?
Digitsole, Sidas, Moticon, Plantiga, RunScribe, FeetMe, Sensoria, Walk With Path, Orpyx Medical Technologies, Dr. Scholl's, ARION, Currex, Neomotion, XyberMed, Stridalyzer, Xiaomi, H+ Technology and Bojin are the profiled companies.
Sports-insole specialists, clinical gait firms and consumer electronics brands compete for smart insole buyers. Moticon issued ReGo and OpenGo software releases in March and July 2026, adding gait parameters and raw data import.[3][6] Digitsole is strengthening AI features, battery life and healthcare uses, Sidas is adding real-time analytics to sports insoles and Plantiga is expanding AI motion tracking for rehabilitation and clinical use. Xiaomi, H+ Technology and Bojin sell connected insoles in China.
- Sports and performance insoles: Digitsole, Sidas, Plantiga, RunScribe, ARION, Currex, and Stridalyzer.
- Clinical and mobility insoles: Moticon, Orpyx Medical Technologies, FeetMe, Walk With Path, Sensoria, Neomotion, and XyberMed.
- Consumer and comfort brands: Dr. Scholl's, Xiaomi, H+ Technology, and Bojin.
Competitive Benchmarking: Smart Insole Market
Table 9: Competitive Benchmarking for the Smart Insole Market (qualitative documentation ratings), 2026
| Company | Pressure Mapping | Clinical Use | Software Platform | Recency |
|---|---|---|---|---|
| Moticon | High | High | High | High |
| Digitsole | Medium | Medium | Medium | Low |
| Orpyx Medical Technologies | High | High | Medium | Low |
| Plantiga | Medium | Medium | Medium | Low |
| Xiaomi | Low | Low | Medium | Low |
Benchmark grades follow the depth of dated product and software releases for each firm, with no link to market share.
Key Developments in the Smart Insole Market
- In August 2026, Skechers said the brand had become the second largest footwear brand in units sold in the United States.[8]
- In July 2026, Moticon released OpenGo software with ReGo raw data import.[6]
- In April 2026, SFIA data showed 24.3 million US pickleball players for 2025.[2]
- In March 2026, Moticon added gait outcome parameters such as clearance to ReGo.[3]
- In March 2026, Eurofins set out 2026 footwear compliance dates, including Denmark's PFAS ban from 1 July.[4]
- In February 2026, STMicroelectronics closed the purchase of NXP's MEMS sensors business.[7]
- In February 2026, the USTA reported 27.3 million US tennis players for 2025.[5]
- In October 2025, CMS finalised a single skin substitute payment rate for 2026.[1]
Key Players in the Smart Insole Market
Sports and Performance Insoles
- Digitsole
- Sidas
- Plantiga
- RunScribe
- ARION
- Currex
- Stridalyzer
Clinical and Mobility Insoles
- Moticon
- Orpyx Medical Technologies
- FeetMe
- Walk With Path
- Sensoria
- Neomotion
- XyberMed
Consumer and Comfort Brands
- Dr. Scholl's
- Xiaomi
- H+ Technology
- Bojin
Smart Insole Market - Report Scope
Table 10: Report Scope for the Smart Insole Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; technology; sales channel; application; region |
| Quantitative units | USD million |
| Market definition | Shoe insoles with sensors, heating elements, GPS or wireless links that measure, track or adjust conditions under the foot. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | Digitsole, Sidas, Moticon, Plantiga, RunScribe, FeetMe, Sensoria, Walk With Path, Orpyx Medical Technologies, Dr. Scholl's, ARION, Currex, Neomotion, XyberMed, Stridalyzer, Xiaomi, H+ Technology, Bojin |
| Forecast period | 2026 to 2036 |
Smart Insole Market - Research Methodology
Table 11: Research Methodology for the Smart Insole Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Medicare rules, company releases, footwear compliance notes and sports participation reports dated May 2025 or later. |
| Desk Research | Gait software releases, PFAS and footwear chemical rules, wound-care payments and court-sport participation. |
| Market Sizing and Forecasting | Sizing starts from USD 310.0 million in 2025 and the 11.0% CAGR from 2026 to 2036. |
| Data Validation | Rule dates and payment figures were matched to the CMS and compliance releases. |
Smart Insole Market by Segments
Smart Insole Market segmented by Product Type:
- Pressure-Mapping Insoles
- GPS-Enabled Insoles
- Heated Insoles
- Others
Smart Insole Market segmented by Technology:
- Bluetooth-Connected
- Wireless Charging
- AI-Integrated
- Sensor-Based
Smart Insole Market segmented by Sales Channel:
- Supermarkets/Hypermarkets
- Specialty Stores
- Online
- Pharmacies/Drug Stores
- Others
Smart Insole Market segmented by Application:
- Sports & Fitness
- Healthcare & Rehabilitation
- Daily Wear
- Industrial Use
Smart Insole Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Centers for Medicare & Medicaid Services. (2025, October 31). Calendar Year (CY) 2026 Medicare Physician Fee Schedule Final Rule (CMS-1832-F). https://www.cms.gov/newsroom/fact-sheets/calendar-year-cy-2026-medicare-physician-fee-schedule-final-rule-cms-1832-f
- [2] Pickleball.com. (2026, April 4). SFIA report confirms over 24 million Americans playing pickleball. https://pickleball.com/news/sfia-report-confirms-over-24-million-americans-playing-pickleball
- [3] Moticon. (2026, March). ReGo Release Note - #1 2026. https://moticon.com/news/rego-release-note-1-2026
- [4] Eurofins Softlines & Leather. (2026, March 18). Footwear regulatory updates 2026: Compliance timelines brands must know. https://www.eurofins.com/textile-leather/articles/footwear-regulatory-updates-2026-compliance-timelines-brands-must-know/
- [5] United States Tennis Association. (2026, February 18). Tennis participation continues to surge with six consecutive years of growth, reaching 27.3 million players in 2025. https://www.usta.com/en/home/stay-current/national/tennis-participation-continues-to-surge-with-six-consecutive-yea.html
- [6] Moticon. (2026, July). OpenGo Release Note - #1 2026. https://moticon.com/news/opengo-release-note-1-2026
- [7] STMicroelectronics N.V. (2026, February 2). STMicroelectronics expands sensors capabilities with closing of acquisition of NXP's MEMS business (Form 6-K). https://www.sec.gov/Archives/edgar/data/932787/000093278726000005/st_nxpmemsclosingxprxfinal.htm
- [8] Skechers U.S.A., Inc. (via FDRA). (2026, August 26). Skechers Is Now the #2 Footwear Brand in the United States. https://fdra.org/latest-news/skechers-is-now-the-2-footwear-brand-in-the-united-states/
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the smart insole market during 2026?
- What market size is projected by 2036?
- Which product type holds notable share?
- Which technology holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the smart insole market expected in 2026?
Insole buyers will pay about USD 344.1 million in 2026, a figure FMI sees growing to USD 977.0 million by 2036. The 2025 base was USD 310.0 million.
What CAGR is projected for the smart insole market through 2036?
An 11.0% CAGR is forecast from 2026 to 2036. Court-sport participation and wound-prevention budgets in podiatry clinics drive the outlook.
Which product type holds a notable market share in 2026?
Pressure-mapping insoles are expected to lead with 41% share in 2026. Heated insoles rank second at about 27%.
Which technology holds a notable market share in 2026?
Bluetooth-connected designs are projected to lead with 46% share in 2026. Sensor-based loggers follow near 28%.
Which country has a notable expansion outlook through 2036?
Smart insole sales in China are anticipated to outpace the other four profiled countries, at a 13.0% CAGR through 2036 on FMI figures. India follows at 12.6%.
Who are the key companies in the smart insole market?
Key companies include Moticon, Digitsole, Sidas, Plantiga, RunScribe, FeetMe and Orpyx Medical Technologies. Dr. Scholl's, Xiaomi and H+ Technology compete in consumer and comfort lines.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Pressure-Mapping Insoles
- GPS-Enabled Insoles
- Heated Insoles
- Others
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Technology, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Technology, 2026 to 2036
- Bluetooth-Connected
- Wireless Charging
- AI-Integrated
- Sensor-Based
- Y-o-Y Growth Trend Analysis By Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By Technology, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Supermarkets/Hypermarkets
- Specialty Stores
- Online
- Pharmacies/Drug Stores
- Others
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Application, 2026 to 2036
- Sports & Fitness
- Healthcare & Rehabilitation
- Daily Wear
- Industrial Use
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Technology
- By Sales Channel
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Technology
- By Sales Channel
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Technology
- By Sales Channel
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Technology
- By Sales Channel
- By Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Technology
- By Sales Channel
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Technology
- By Sales Channel
- By Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Technology
- By Sales Channel
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Technology
- By Sales Channel
- By Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Technology
- By Sales Channel
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Technology
- By Sales Channel
- By Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Technology
- By Sales Channel
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Technology
- By Sales Channel
- By Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Technology
- By Sales Channel
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Technology
- By Sales Channel
- By Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Technology
- By Sales Channel
- By Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Technology
- By Sales Channel
- By Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Technology
- By Sales Channel
- By Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Technology
- By Sales Channel
- By Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Technology
- By Sales Channel
- By Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Technology
- By Sales Channel
- By Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Technology
- By Sales Channel
- By Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Technology
- By Sales Channel
- By Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Technology
- By Sales Channel
- By Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Technology
- By Sales Channel
- By Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Technology
- By Sales Channel
- By Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Technology
- By Sales Channel
- By Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Technology
- By Sales Channel
- By Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Technology
- By Sales Channel
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Technology
- By Sales Channel
- By Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Technology
- By Sales Channel
- By Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Technology
- By Sales Channel
- By Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Technology
- By Sales Channel
- By Application
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Technology
- By Sales Channel
- By Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Technology
- By Sales Channel
- By Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Technology
- By Sales Channel
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Moticon
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Digitsole
- Orpyx Medical Technologies
- Plantiga
- Xiaomi
- Sidas
- RunScribe
- ARION
- Currex
- Stridalyzer
- FeetMe
- Walk With Path
- Sensoria
- Neomotion
- XyberMed
- Dr. Scholl's
- H+ Technology
- Bojin
- Moticon
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


